Author: Mei Ling Tan

  • Miniso Launches First Overseas Super Miniso Store in Canada

    Miniso Launches First Overseas Super Miniso Store in Canada

    Miniso opened its first overseas Super Miniso store on October 10 at Square One Shopping Centre in Mississauga, Ontario. The location spans 1,000 square metres.

    Shelves carry more than 5,000 intellectual property-driven stock keeping units. Categories span character merchandise, beauty, travel accessories and everyday lifestyle products.

    This debut brings the full Naruto collection and Stitch Hit Snooze range to Canada for the first time. Upcoming product drops feature Demon Hunter, Chiikawa, Mofusand and Marvel. Miniso will also roll out its proprietary character IP, YOYO, and more than 100 Hello Kitty and Friends products.

    Inside the 1,000-Square-Metre Format

    The Super Miniso concept departs from the chain’s traditional small-footprint layout. Utility shelving gives way to character-themed shows and experiential floor zones built directly into commodity aisles.

    Floor plans blur the line between discretionary collectibles and regular consumable household goods. High-margin licensed items sit in front-of-store lifestyle displays rather than back corners. The strategy targets higher basket sizes.

    The IP Economics of Variety Retail

    For Chinese value retailers operating abroad, licensed character merchandise is the primary lever to lift gross margins. Generic stationery and plastic organizers yield low ticket averages. Co-branded anime and Disney items command higher price points with minimal extra production costs, helping shed the discount dollar-store label.

    Risk lies in inventory turnover and licensing commitments. Securing regional rights for Japanese anime franchises and Western entertainment properties demands minimum guarantee payments that only large-format, high-footfall sites can support. If footfall drops or trends shift quickly, slow-moving licensed stock ties up working capital faster than basic household sundries.

    A Four-Store Canadian Cluster

    Mississauga represents phase one of a Canadian expansion running through October and November 2026. Four themed large-format stores will open across the country in that two-month window.

    Three locations in Mississauga, Winnipeg and Montreal will adopt the Super Miniso balance of curated lifestyle goods and IP collections. A fourth site in Toronto will debut the Miniso Land format. That entertainment-focused concept drops basic lifestyle items in favor of an immersive character park environment.

    West Edmonton Footprint and Next Openings

    Miniso tested large-scale Canadian demand in November 2025 with a 1,000-square-metre store at West Edmonton Mall. Featuring 5,000 IP lines, the opening set a single-day sales record for its North American operations. The chain followed that in April 2026 with a dedicated Hello Kitty and Friends pop-up in Toronto.

    Next up are store rollouts across the three remaining Canadian sites through November 2026, alongside initial sales performance data from the Toronto Miniso Land launch.
  • Bukalapak Will Not Rely on Gaming Revenue for Long-Term Growth

    Bukalapak Will Not Rely on Gaming Revenue for Long-Term Growth

    Bukalapak confirmed in Jakarta this week that digital gaming transactions will not define the group’s corporate future despite generating the largest share of current revenue.

    The stance signals a structural boundary for the Indonesian commerce platform as it balances high-volume digital entertainment sales against broader merchant ecosystems ahead of upcoming quarterly filings.

    Where the Revenue Concentrates

    Gaming services and digital top-ups have become the platform’s primary sales engine following shifts across its core marketplace operations. User demand for in-game currencies and virtual goods created immediate transaction volume across urban and tier-two Indonesian markets.

    Management maintains that relying on digital entertainment leaves the wider enterprise exposed to developer fee changes and regulatory pressure on microtransactions. The platform is keeping its core retail infrastructure focused on physical merchants and supply chain integration.

    The Merchant Ecosystem Balance

    Mitra Bukalapak, the group’s offline-to-online network serving neighbourhood kiosks, remains central to its merchant distribution network across Indonesian provinces. Diverting investment entirely into virtual gaming goods would detach the company from the physical supply chains that separate regional commerce platforms from purely digital app stores.

    Rival platforms across Southeast Asia have confronted the same dilemma. Gaming transactions deliver swift cash flow, yet physical retail distribution builds defensive customer loyalty across small business networks.

    Shifting Away From Pure Marketplace Competition

    Bukalapak retreated from head-to-head capital burn against regional marketplace giants several years ago to concentrate on specialized commerce categories and offline kiosks. That pivot helped stem operating losses and created room for digital gaming services to expand quickly inside the platform.

    The resulting revenue concentration now presents its own operational hazard. Rebalancing the revenue mix requires expanding higher-margin merchant financial services and wholesale supplies to traditional store owners.

    What to Watch Next

    Investors tracking the company on the Indonesia Stock Exchange will monitor segment contribution figures in upcoming quarterly filings. The immediate test is whether physical retail distribution and small merchant services can expand fast enough to match gaming transaction growth.

  • Bitcoin Trades at $83,408 as Crypto Markets Track Asia Trading Moves

    Bitcoin Trades at $83,408 as Crypto Markets Track Asia Trading Moves

    Bitcoin held steady at $83,408.20 on October 13, 2026, gaining $19.57 over the previous morning as trading volumes remained subdued across major digital asset desks.

    The benchmark cryptocurrency is down 27.64 per cent from $115,278.48 a year earlier, representing a value loss of roughly $31,870 per token despite an 7.95 per cent rebound over the past month from $77,261.09.

    Total market capitalisation for Bitcoin stands at $1.33 trillion, maintaining its dominant position over alternative tokens. Second-ranked Ethereum fell 1.97 per cent over twenty-four hours to $2,503.64, extending a 41.02 per cent drop from $4,245.28 recorded twelve months prior and fixing its valuation at approximately $233 billion. Tether followed with a $183 billion market cap at $0.99, while cross-border settlement token XRP traded at $1.35.

    Exchange expansion across North Asian hubs

    Retail and institutional trading activity across Asia-Pacific remains central to digital currency liquidity as platforms seek formal integration with regional equity markets. Binance is weighing plans to offer traditional stock trading access to customers in key Asian jurisdictions, including Hong Kong and South Korea. Connecting digital asset wallets to local equities provides centralized exchanges with a direct route to capture cross-asset retail trading flow.

    Brokerages and consumer finance platforms across Hong Kong and Seoul face renewed competition if major crypto venues succeed in securing regulatory approvals for equity products. Traditional securities brokers have spent years defending their fee structures against zero-commission retail apps. A unified interface combining spot crypto, exchange-traded funds and local equities threatens to erode brokerage commission pools across East Asia.

    Balance sheet purchases and corporate exposure

    Corporate treasury allocations have resumed on a targeted scale following sharp drawdowns from record highs. Strategy completed a $21 million purchase of Bitcoin as corporate buying activity showed signs of renewed momentum. Such transactions provide price support, though treasury adoption outside specialized balance sheet operators remains limited to select consumer brands and technology firms.

    Merchant payment adoption continues among high-ticket retail brands such as Ferrari and Tesla, yet everyday consumer transactions across Asian retail checkouts remain dominated by local fiat digital wallets. Crypto volatility makes inventory pricing difficult for retailers operating on thin margins. For department stores and supermarket operators, processing volatile tokens directly creates currency exposure that standard payment gateway conversions cannot fully eliminate.

    Retracing the October 2025 record peak

    Current price levels reflect a prolonged correction from historic highs set in late 2025. Bitcoin established an all-time record of $126,198.07 on October 6, 2025, before dropping roughly 30 per cent into the close of that calendar year. Ethereum experienced an identical trajectory, peaking near $5,000 in August 2025 before losing half its valuation over the subsequent fourteen months.

    Early stages of the cryptocurrency market saw transactions such as developer Laszlo Hanyecz exchanging 10,000 Bitcoins for two pizzas in 2010, an allocation valued today at more than $668 million. Long-term appreciation exceeds 15,000 per cent over the past decade, yet steep cyclical contractions continue to challenge institutional risk models and consumer holding appetite.

    Regulatory filings and automated order flow

    Trading desks are turning toward automated infrastructure to manage market shifts. Developer teams across the crypto sector are deploying artificial intelligence agents capable of executing autonomous trades, shifting volume away from manual retail orders toward programmatic systems. These tools operate continuously across global venues, tightening spreads during Asian daytime hours.

    Regulatory scrutiny over exchange asset segregation and cross-border token transfers remains the primary hurdle for wider banking integration across Asia. Licensing authorities in Hong Kong continue to review platform permissions, while financial watchdogs in Seoul maintain strict compliance rules on investor identity checks and domestic bank linkages. Market participants are monitoring whether Binance submits formal filing documents for stock trading services in either jurisdiction before the end of the fourth quarter.

  • Hong Kong to Host 21 APEC Economies for 2026 Finance Ministers’ Meeting

    Hong Kong to Host 21 APEC Economies for 2026 Finance Ministers’ Meeting

    Hong Kong will stage the Asia-Pacific Economic Cooperation (APEC) 2026 Finance Ministers’ Meeting for the first time from October 20 to 21, hosting delegates from 21 member economies.

    Gathering at the Hong Kong Convention and Exhibition Centre, finance ministers and leading financial institution representatives will meet as part of the wider APEC China 2026 event hosted by the Ministry of Finance, with Financial Secretary Paul Chan Mo-po highlighting the city’s role as a regional connector.

    Trade exposure and direct investment flows

    Total foreign direct investment inflows into APEC economies reached an estimated US$956.3 billion in 2024, with more than US$126 billion flowing into Hong Kong, while member economies collectively accounted for 62 per cent of global gross domestic product in 2021, or US$67.7 trillion.

    Financial Secretary Paul Chan Mo-po noted that the ministerial sessions will center on four core tracks: fiscal policy, digital infrastructure funding, inclusive finance, and talent development. The agenda also covers small-business financing and productivity measures across member markets.

    Capital deployment across regional supply chains

    For cross-border operators and retail conglomerates, the ministerial agenda directly touches liquidity and transaction friction. Supply chain realignment across Asia has forced corporate treasurers to diversify trade settlements and manage currency volatility across multiple jurisdictions. Hong Kong is using the talks to position its debt markets and clearing systems as the primary conduit for those reconfigured trade corridors.

    Commercial banks face tighter regulatory scrutiny across regional corridors, making common standards on digital infrastructure financing a practical priority for lenders. If delegates align on cross-border payment platforms and green bond standards, regional retail chains and consumer goods suppliers could see lower borrowing spreads for sustainability linked projects.

    Green debt issuance and capital market rankings

    Green and sustainable debt issuance in Hong Kong exceeded US$76 billion in 2025, with approximately US$38 billion arranged as green and sustainable bonds. That pool of capital gives commercial developers and infrastructure operators access to institutional funds seeking low-carbon transition assets.

    Andrew Weir, vice-chairman of the Hong Kong Financial Services Development Council, pointed to the city’s concentration of advisory and legal firms as a structural advantage during periods of market friction. “It’s a great opportunity to clarify any areas of potential misunderstanding or clarify areas of collaboration which need deeper engagement,” Weir said.

    Strategic policy rollout before October summit

    The October summit follows the release of the Hong Kong government’s five-year economic blueprint in September. That development strategy prioritizes offshore yuan liquidity, deeper capital market links with the mainland, and expanded wealth management infrastructure. The Global Financial Centres Index ranked Hong Kong third worldwide behind New York and London in the same month.

    Finance ministers and central bank representatives will convene on October 20 to finalize joint policy recommendations on digital trade infrastructure and multilateral green funding mechanisms.

  • Broekman Logistics Highlights Middle Corridor for Europe-Asia Project Cargo

    Broekman Logistics Highlights Middle Corridor for Europe-Asia Project Cargo

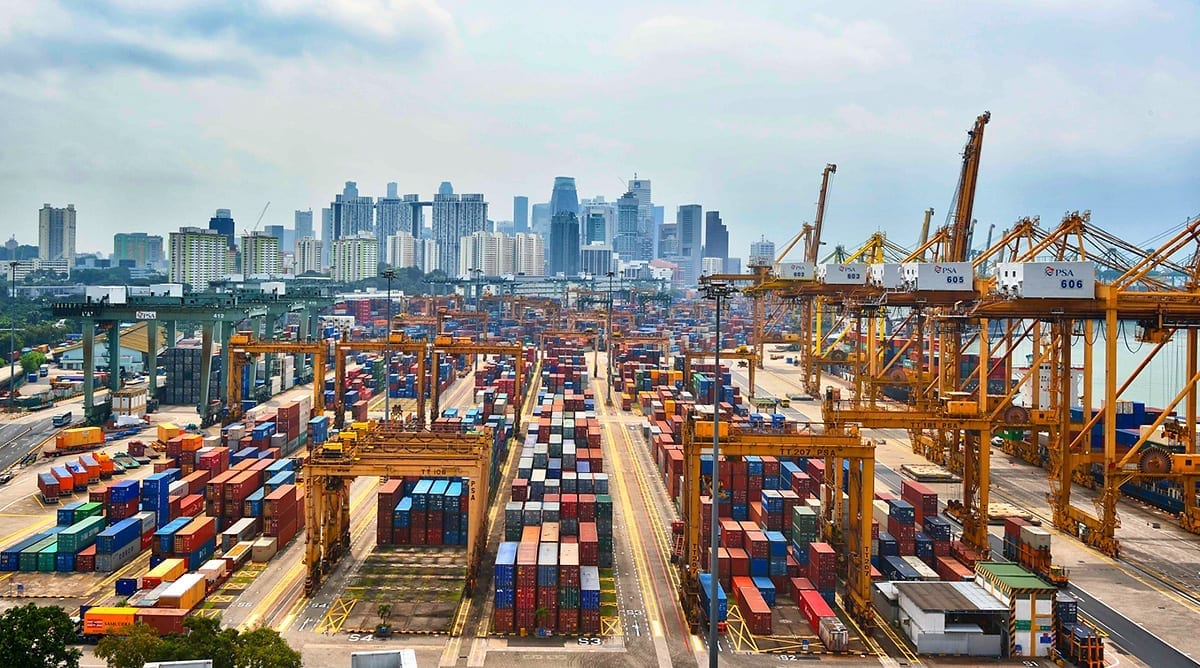
    On 13 October 2026, Broekman Logistics highlighted the growing strategic importance of the Middle Corridor as European and Asian shippers seek alternative transport routes for project cargo, industrial equipment and high-value freight.

    The Netherlands-based logistics company said continued investment in rail infrastructure, ports and terminals along the Trans Caspian route is improving connectivity and creating new options to reduce dependence on established maritime corridors.

    Multimodal Links Across the Caspian Sea

    Running through Turkey, Georgia and Azerbaijan, the corridor crosses the Caspian Sea to reach Kazakhstan, Turkmenistan and Uzbekistan. Shippers combine short-sea shipping, rail freight and road haulage to bypass maritime bottlenecks and geopolitical flashpoints.

    Moving breakbulk cargo across the route requires coordination across multiple rail gauges, seaports and customs jurisdictions. Broekman Logistics focuses on synchronised route surveys, transit permits and heavy-lift transfers at Caspian terminal interchanges.

    Transit Coordination and Gateway Roles

    Turkey serves as the western anchor for the corridor, feeding European traffic through rail and highway links toward the South Caucasus. Turkish ports handle transshipment for landlocked Central Asian destinations that lack direct maritime access.

    Route selection depends on physical constraints along the way. Axle-load limits, bridge clearances, rail tunnel dimensions and Caspian port crane capacities dictate whether oversized equipment can move intact or requires disassembly before crossing inland borders.

    Operational Bottlenecks for Project Cargo

    Terminal upgrades along the Trans-Caspian line have expanded container handling, yet breakbulk cargo faces different operating realities. Transporting industrial machinery requires dedicated roll-on/roll-off vessel capacity and heavy-lift handling gear, which remain limited across Caspian Sea crossings.

    Customs alignment across five transit countries is the primary variable for schedule reliability. For equipment suppliers and engineering contractors, single-point delays at rail-to-ship transfer points can disrupt installation timelines at Central Asian mining and energy developments.

    Border Clearances and Caspian Vessel Capacity

    Infrastructure authorities along the corridor have invested in rail sidings and port berths across Baku, Aktau and Kuryk to improve transfer speeds. These terminal projects aim to establish predictable transit intervals for industrial shippers evaluating overland options against long-haul sea routes.

    Commercial viability for heavy freight now rests on the delivery of scheduled Caspian ferry slots and standardised customs transit documentation across Kazakh and Azerbaijani border points.

  • Foreign Staff Exceed 110,000 Across Japan Top Three Convenience Chains

    Foreign Staff Exceed 110,000 Across Japan Top Three Convenience Chains

    Japan’s three largest convenience store chains employed more than 110,000 foreign workers in 2025, leaning on overseas labor to staff cash registers and stock shelves.

    The cohort represents nearly 14 percent of the 800,000 part-time workers operating networks run by Seven & i Holdings’ 7-Eleven, Lawson, and FamilyMart across the country.

    Hiring managers report that recruits from abroad show strong Japanese language capability and high operational competency, helping operators keep stores open around the clock. The influx has become a structural necessity for a network spanning more than 56,000 convenience stores nationwide, where round-the-clock operating models depend on steady frontline staffing.

    Pressure on the 24-hour retail model

    Convenience operators across East Asia face diverging labor realities, but Japan’s demographic contraction presents the sharpest operational test. While regional peers in South Korea and Taiwan have experimented with automated night shifts and unstaffed outlets to trim payroll costs, Japanese chains continue to anchor their customer proposition on high-touch service, bill payments, parcel handoffs, and freshly prepared hot food.

    That service density requires labor that the domestic population cannot supply. FamilyMart alone faced roughly 10,500 vacancies across its 16,400 stores, forcing corporate headquarters and independent franchise owners to widen recruitment pipelines or risk trimming operating hours.

    Sourcing labor across Asia

    Recruits arrive predominantly from Vietnam, Nepal, China, and Myanmar, drawn initially on student and training visas before taking up part-time retail shifts. In Tokyo hubs such as Shinagawa Ward, overseas employees now anchor entire shift rotations, handling everything from inventory deliveries to food service counters.

    Store managers confirm that language training and structured onboarding have kept register errors low despite complex point-of-sale systems that handle utility billing and administrative tasks. The operational reliance on foreign workers shifts supply risk directly onto immigration policy and cross-border recruitment pipelines, leaving franchisees vulnerable if visa quotas tighten or regional currency shifts erode Japanese wage competitiveness.

    Friction at the checkout counter

    Frontline pressure has surfaced in customer interactions across the retail sector. Service surveys show roughly 80 percent of staff report instances of customer harassment, prompting store managers to rethink standard operating procedures.

    Some franchised locations have adjusted staff name badges, substituting generic tags reading STAFF or using alternate names to protect clerks from customer disputes. The friction reflects broader social adjustments as local neighborhoods adapt to a rapidly diversifying frontline service workforce.

    Automation versus headcounts

    The staffing shift follows years of rapid demographic change across Japan. The country’s registered foreign resident population expanded from 2.76 million in 2021 to 3.77 million in 2024, providing the retail and food sectors with vital replacement labor during a period of record-low domestic unemployment.

    Franchise groups must now balance further investments in automated self-checkout kiosks against the ongoing cost of recruiting and training overseas staff. The next operational test comes as major chains review their overnight roster requirements ahead of the 2027 fiscal planning cycle, where store-level wage inflation will determine whether 24-hour operating mandates remain viable across suburban and rural locations.

  • Beximco Plans British and Chinese Deal to Reopen Shuttered Bangladesh Garment Plants

    Beximco Plans British and Chinese Deal to Reopen Shuttered Bangladesh Garment Plants

    Beximco Group is seeking government approval for a foreign leasing deal to reopen its shuttered apparel plants in Gazipur, backed by British and Chinese investors.

    The five-year agreement brings British investment firm Charter HCP and Chinese operator Besting into the industrial park. Factory restarts are targeted for April 2027.

    How the factory leasing structure works

    Under the proposed plan, foreign backers will run Prefix Fashions, a specialized garment unit inside Beximco Industrial Park. Production will focus on outer garments, with export jackets accounting for roughly 90 percent of output. The first phase will restore approximately 2,500 manufacturing jobs.

    Revival Global, the asset manager for the investor group, designed a mechanism to ringfence cash flows and shield operations from Beximco’s domestic liabilities. Export proceeds will flow directly into bank accounts held by secured creditors. This prevents Beximco management from touching operational funds before paying debt obligations and working capital expenses, according to company executives.

    Phased expansion across Gazipur industrial park

    Prefix Fashions is the initial test case for a broader revival strategy. If operations and finances hold up, the consortium plans to reopen the remaining 15 shuttered apparel units in stages.

    A full rollout could rehire more than 30,000 garment workers across the complex. Beximco previously ranked among the largest private sector employers in Bangladesh. It operated vertically integrated facilities spanning spinning, weaving, denim washing and garment assembly before operations stopped.

    Supply chain shifts across South Asia

    Regional apparel sourcing faces severe turbulence. International fashion brands have spent recent months shifting purchase orders across South Asia to avoid production bottlenecks and delivery delays.

    Neighboring production hubs face their own bottlenecks. In India’s knitwear center of Tiruppur, roughly 460 dyeing facilities halted operations in October to protest raw material shortages and dye price spikes of up to 100 percent. The closures disrupted fabric supplies for export houses. Large-scale capacity in Bangladesh offers global buyers a hedge against regional limits, but confidence hinges on whether foreign management can insulate factory floors from political disruption.

    The collapse following political upheaval

    Beximco’s factory network shut down after the political collapse of the Awami League administration in Dhaka. The arrest of Beximco co-founder Salman F. Rahman, private industry adviser to former Prime Minister Sheikh Hasina, froze bank credit lines. That cut off working capital across the conglomerate’s textile, pharmaceutical and ceramics divisions.

    Plant closures in Gazipur displaced roughly 40,000 garment workers, triggering protests over unpaid wages and leaving multi-million-dollar export contracts unfulfilled. Local lenders took possession of assets. Foreign partnership leases remain the only viable route to restart production without direct government bailouts.

    Government regulators and creditor banks are reviewing the lease documentation for Prefix Fashions. State approval will determine whether maintenance teams can enter the Gazipur facility ahead of the planned April 2027 commercial restart.

  • ASML Warns AI Chip Tool Demand Will Outstrip Capacity Through 2028

    ASML Warns AI Chip Tool Demand Will Outstrip Capacity Through 2028

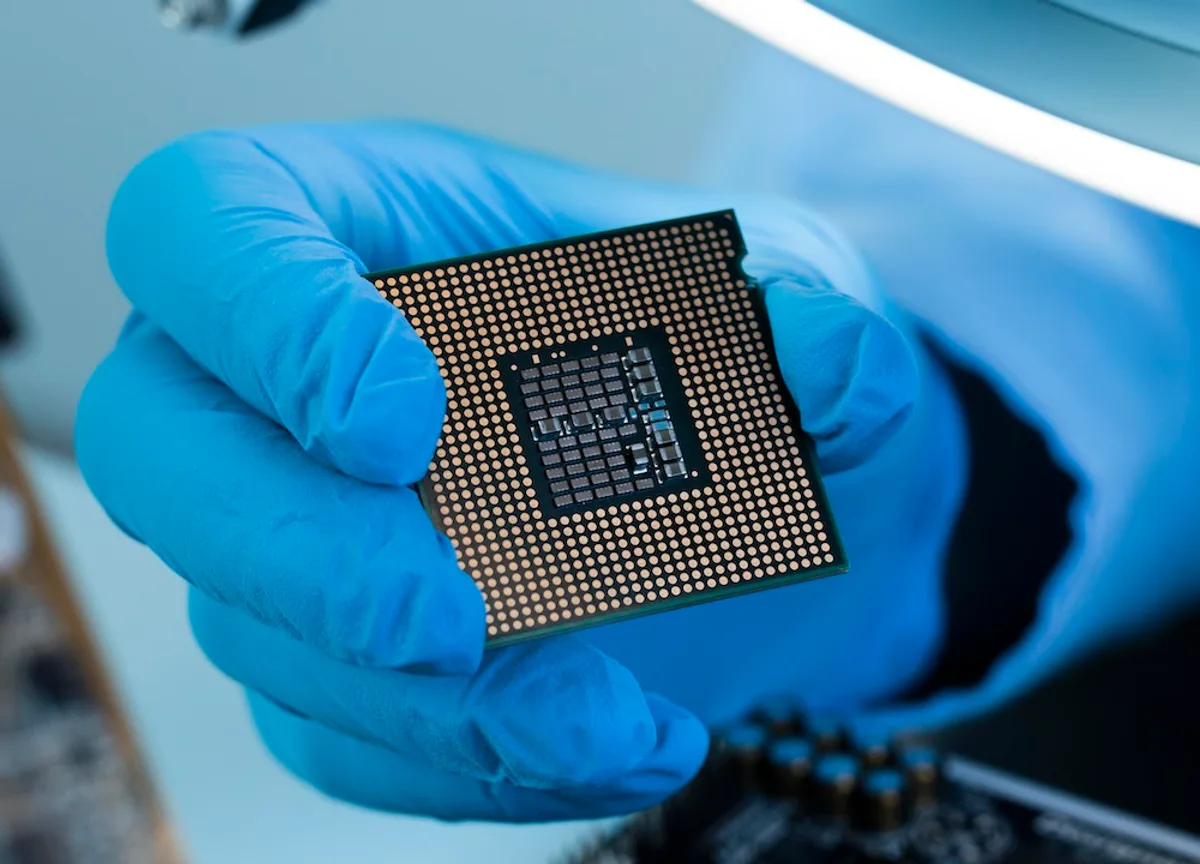
    ASML will fail to satisfy customer demand for its chipmaking machinery in 2027 and 2028 as orders for artificial intelligence hardware exceed manufacturing capacity.

    The Dutch equipment maker projected fourth-quarter sales between €14.2 billion and €15.2 billion, beating average market forecasts of €14.19 billion compiled by LSEG.

    Gross margins for the final quarter are projected at around 57 per cent. Extreme demand for advanced lithography systems has stretched delivery schedules well past normal lead times, pushing commercial negotiations into the next decade.

    Delivery Bottlenecks Hit Advanced Fabs

    Chief executive Christophe Fouquet confirmed that order discussions with key chipmakers now routinely bypass near-term delivery slots. Demand has outpaced every planned production adjustment across the company’s assembly facilities.

    “A lot of our discussions with our customers now are shifting in fact beyond 2027,” CEO Christophe Fouquet said in a statement.

    Fouquet noted that tool buyers are placing firm bookings for 2028 delivery while opening formal negotiations for 2029 and 2030 production slots. Foundries across Asia building capacity for artificial intelligence processors face extended wait times for critical extreme ultraviolet scanners.

    Asian Foundry Expansion Pressures

    For semiconductor manufacturers in Taiwan, South Korea and Japan, machinery shortfalls limit how fast new wafer fabrication plants can ramp output. Tool allocations dictate foundry expansion schedules, consumer hardware production runs and memory delivery timelines.

    The equipment shortage concentrates operational risk among contract chipmakers competing for identical production slots. Commercial foundries that secured earlier delivery positions will hold output advantages over rivals waiting on delayed tool shipments.

    Capacity Expansions Fall Short

    Production limits persist despite aggressive factory investments announced earlier this year. In July, the toolmaker outlined plans to raise equipment output by 30 per cent in 2027 and add another 30 per cent capacity increase in 2028.

    Those production increases will still leave the manufacturer short of customer requirements. Management is reviewing additional manufacturing options to widen assembly bottlenecks before 2028 delivery commitments close.

    Production Timelines to Watch

    Tool buyers now face strict ordering windows to secure production slots for 2029. Equipment allocations and any revision to the planned 30 per cent annual capacity increases will determine delivery timelines for global semiconductor plants.

  • Nio Reaches 500 Battery Swap Stations in Guangdong

    Nio Reaches 500 Battery Swap Stations in Guangdong

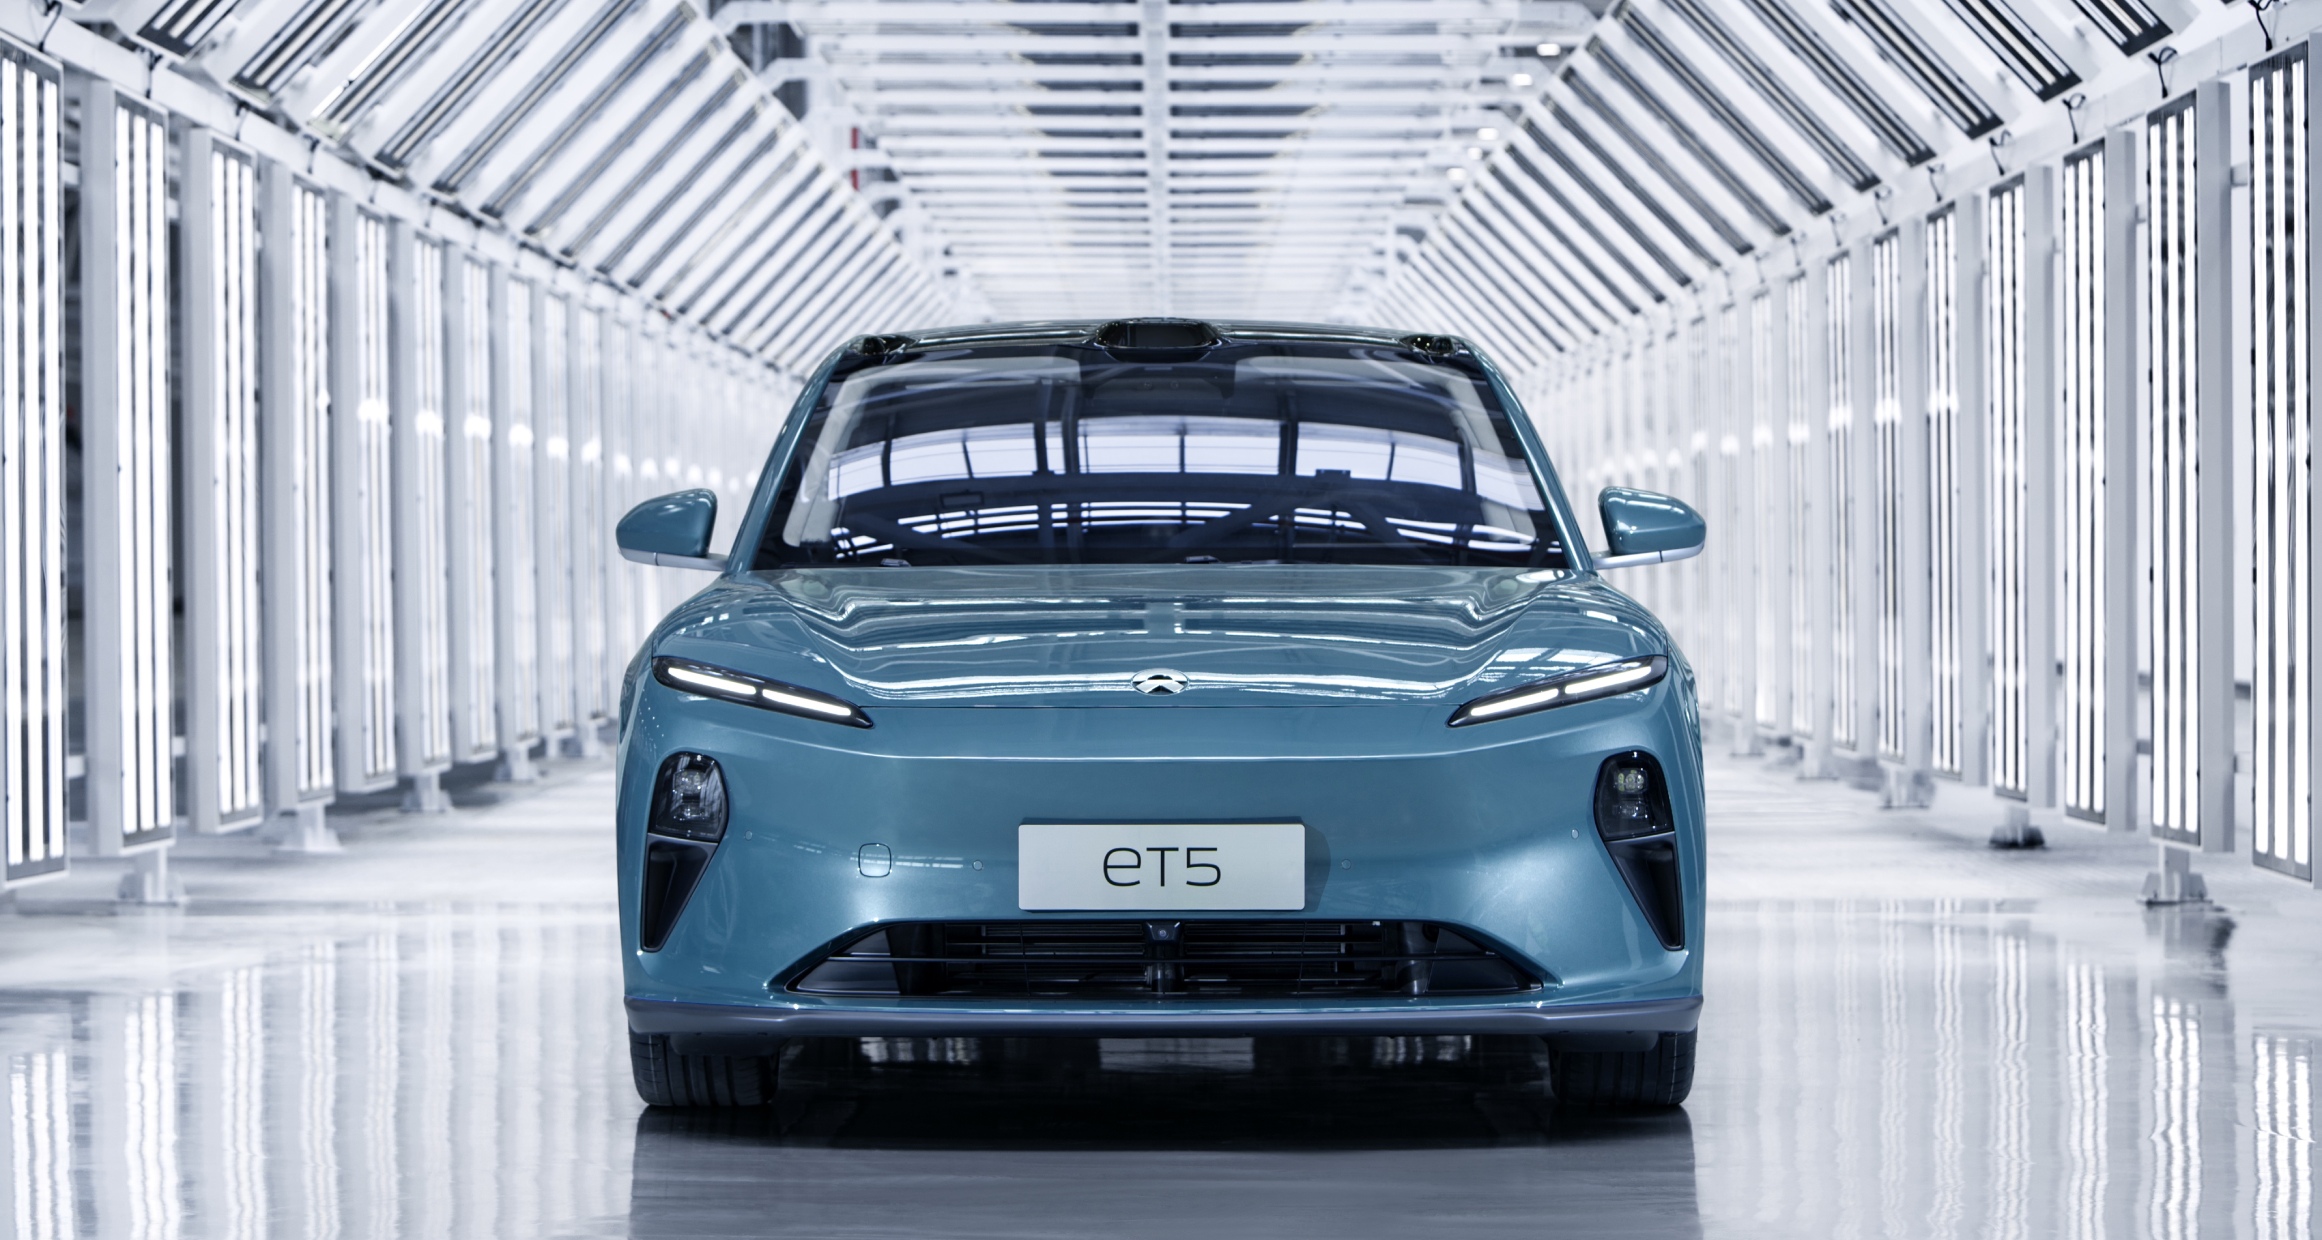
    Nio opened six fifth-generation battery swap stations across Guangdong on Sunday. The launches brought its provincial network to 500 sites, pushing cumulative swaps past 17 million.

    Guangdong generated roughly 13 percent of all battery swaps completed by the company across China. Meanwhile, local vehicle deliveries rose 76.3 percent year-on-year through August.

    Expanding Urban Density Across the Greater Bay Area

    Guangzhou, Shenzhen, Huizhou, Dongguan, Foshan and Zhuhai all added stations simultaneously. Each facility runs on fifth-generation architecture built to cut swap times and handle multiple vehicle platforms.

    Resident numbers in Guangdong reached 129 million in 2025, keeping it China’s largest provincial economy. Nio Power shifted its provincial focus from basic geographic expansion toward tightening urban station density.

    Expressway corridors form a central pillar of that footprint. The company operates 101 swap stations along Guangdong expressways, including the Shenyang-Haikou Expressway, the Beijing-Hong Kong-Macao Expressway and the Pearl River Delta Ring Expressway. Drivers have logged over 3 million swaps along those routes.

    Infrastructure Economics and Competitor Pressures

    Heavy capital spending makes dedicated swap networks costly to build. Still, Nio uses station density to anchor vehicle sales against competitors who rely purely on public plug-in chargers. Price wars remain fierce among electric vehicle makers in southern China, turning operating convenience into a key sales differentiator for premium brands.

    Commercial landlords and transport operators gain recurring high-voltage power demand and steady driver footfall from swap installations. Yet asset utilisation carries real risk. Fixed machinery and battery inventory costs remain high, requiring strong daily turnover to break even.

    County Coverage Foundations

    Station density gained momentum after an early 2025 rollout. Under its Power Up Counties program, Nio Power reached full county-level swap coverage across Guangdong in April 2025, installing 428 stations across all 122 county-level administrative areas.

    Adding 72 stations since that milestone reflects faster installation inside major municipal centres rather than expansion into new regional territories. Nationwide, Nio delivered 262,893 vehicles between January and August, up 57.92 percent from the prior year.

    National Scale Targets

    Across mainland China, Nio operates 9,584 charging and swap stations, a total that includes 4,176 battery swap locations. Highway installations account for 1,073 of those sites, connecting 16 major urban clusters and more than 550 cities.

    National swap volume topped 120 million in August, doubling in six months. Network partners and investors are tracking installation targets for the final four months of the year, alongside integration steps after Geely agreed to take a 30 percent stake in Nio Power.

  • FairPrice Deploys 3,000 Smart Trolleys as Retailers Turn to In-Store Media

    FairPrice Deploys 3,000 Smart Trolleys as Retailers Turn to In-Store Media

    Retailers are expanding into advertising, fintech services, and data monetisation as intensifying competition puts pressure on product margins.

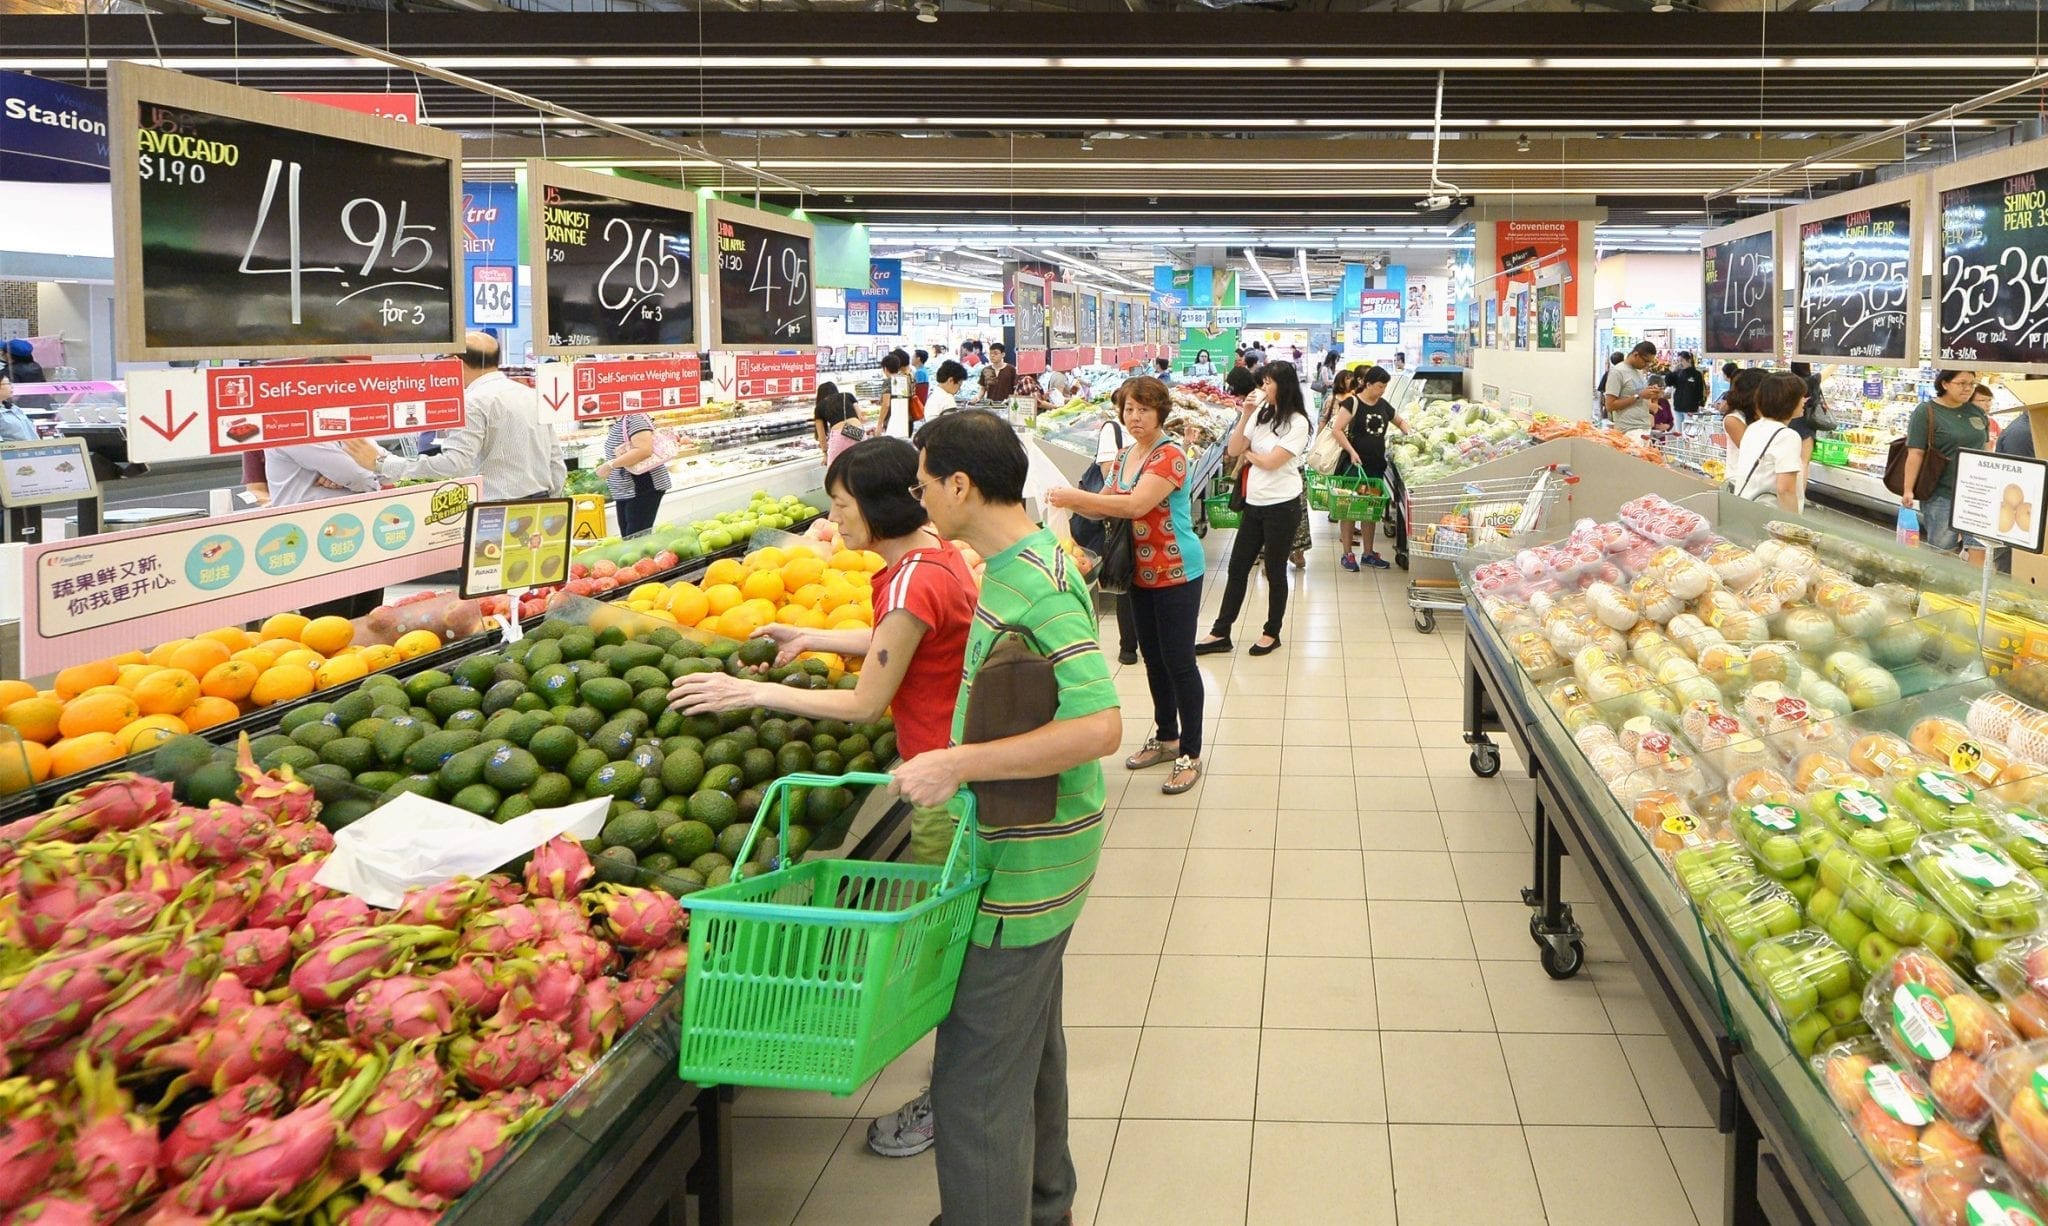
    FairPrice Group has deployed about 3,000 smart trolleys across selected stores ahead of a wider rollout planned for 2027, linking carts to shopper app accounts to personalise ads and offers.

    Speaking at the Retail Asia Summit 2026 in Singapore, Sanjay Singh, senior vice president for the Investor Transformation group at Frost & Sullivan Asia Pacific, said retail media can become a profit engine for physical stores by connecting demand, inventory, payments, and fulfilment.

    Smart Carts and Targeted Health Campaigns

    Grocery operators are using point-of-sale data to sell brand campaigns inside physical aisles. Rajiv Singh, head of the retail media network at FairPrice Group, said an in-store initiative run with Singapore’s Health Promotion Board shifted 12 percent of approximately 500,000 targeted shoppers toward lower-sodium product alternatives. The state health agency is now doubling the budget and scale of the campaign.

    Ad deals are benchmarked on incremental return. The grocer measures exact sales generated per marketing dollar spent. Linking smart shopping trolleys directly to the FairPrice mobile app allows the chain to trigger personalized promotions as shoppers navigate aisles.

    Packaged goods manufacturers gain direct access to verified purchase histories through these retailer-owned networks. Brands pay premiums for verified basket conversions rather than broad digital impressions across open web platforms.

    Extending Sales Windows Beyond the Store

    Duty-free and department store operators are adjusting checkout rules to capture spending outside physical premises. The Shilla Duty Free now allows travelers to purchase merchandise via the iShopChangi platform up to 30 days after their trip, according to Joanne Soh, head of consumer marketing and e-commerce at the travel retailer.

    A wider post-travel purchasing window lets airport retailers recover sales lost to tight flight schedules and carry-on luggage limits. Physical airport storefronts become discovery showrooms backed by centralized domestic delivery.

    Department store operator Metro Singapore is reallocating floor space toward targeted customer problems. Henry Christian, head of loyalty, marketing and partnerships at Metro Singapore, pointed to the retailer’s Sleep Lab concept, launched on World Sleep Day on 15 March. The format evaluates brand participation and customer discussions alongside standard sales volumes.

    Micro Occasions and Quick Commerce Channels

    Food makers are mining retailer transaction data to generate sales outside traditional peak holidays. Kenneth Lau, global digital commerce excellence lead at Mondelēz International, said digital commerce accounts for roughly 41 percent of the company’s sales this year. That channel delivers 61 percent of its total growth.

    In China, Mondelēz partnered with on-demand delivery giant Meituan to target office afternoon tea breaks, tailoring Oreo product selections specifically for immediate local fulfillment. The confectionery group also created an exclusive digital-commerce gift box for its BTS brand collaboration priced at about $15, selling out 20,000 packs on Shopee across Southeast Asia within seven days.

    Furniture retailer Castlery is focusing investments strictly on measurable omni-channel systems. Leah Howatson, general manager for international markets at Castlery, said the company synchronizes online shopping carts with physical store systems so staff can complete purchases started online, while scaling back curated experiential events that failed to deliver adequate return on investment.

    Balancing Capital Outlays Against Ad Revenue

    Retail media networks are creating a split between high-volume grocers and discretionary specialty chains. Supermarket operators control the recurring transaction volume required to justify in-store screens, trolley hardware, and data infrastructure. Discretionary chains lack that visit frequency. They struggle to build ad scale, forcing them to focus on cart synchronization and extended checkout windows instead.

    Physical rollouts still face operational hurdles from hardware maintenance, screen vandalism and basement mobile network dead zones. Retailers that over-invest in in-store hardware without securing long-term brand ad commitments risk adding capital costs without lifting net margins.

    Attention now turns to FairPrice’s planned 2027 fleet expansion for smart carts across its full Singapore footprint, which will test whether ad-supported trolley systems generate sustainable yields across suburban store formats.

  • Hundreds of Woolworths NZ Managers Plan First Strike over Five-Year Pay Freeze

    Hundreds of Woolworths NZ Managers Plan First Strike over Five-Year Pay Freeze

    Hundreds of in-store managers across Woolworths New Zealand are staging their first strike in October 2026 to protest a contract proposal that would freeze wages for up to five years.

    Staff represented by First Union will walk out between 10:30am and 11:30am on Tuesday across store locations nationwide to speak directly with shoppers about the pay dispute.

    Terms of the Proposed Contract

    First Union representative Ross Lampert and union officials state the current remuneration package offered by supermarket management locks store leadership into flat base pay rates. During the one-hour stoppage, participating managers plan to distribute information outside storefronts to explain why they rejected the company offer.

    First Union representative Ross Lampert condemned the proposal during negotiations with the retailer. “The pay offer is a slap in the face for people who run Woolworths’ stores,” Lampert said.

    Operating Pressures in Australasian Grocery

    Supermarket operators across the region face tighter margin scrutiny as store-level overheads climb alongside elevated supply costs. For retail chains, holding management compensation flat is a direct lever to contain operational expenditure, but doing so risks damaging retention across frontline supervisory roles.

    Store managers handle daily stock replenishment, team rostering, shrink control and checkout flows. Industrial friction at this tier creates immediate operational bottlenecks for grocery retailers, particularly during high-traffic morning trading windows.

    Shifting Frontline Labour Dynamics

    Supermarket labour disputes in New Zealand historically centred on hourly floor staff, distribution centre workers and checkout operators rather than salaried or supervisory tier staff. Mid-level retail managers taking collective industrial action reflects growing pressure on supervisory wages as living costs outpace historical salary adjustments.

    Woolworths has been updating its store networks and brand identity across New Zealand while managing cost inflation in freight, sourcing and store operations. The dispute shows that frontline cost controls are meeting organized resistance from the staff running store floors daily.

    Next Steps for Store Negotiations

    Union organizers intend to use the Tuesday morning walkout to gauge customer sentiment and escalate collective bargaining terms with grocery executives. Management and union representatives will monitor participation levels across branches ahead of the next round of contract talks.

  • Ikea Opens Douyin Store in China with 6,500 Products Across 301 Cities

    Ikea Opens Douyin Store in China with 6,500 Products Across 301 Cities

    Ikea opened an official flagship store on ByteDance video platform Douyin on 11 October 2026, offering more than 6,500 home furnishing products across 301 Chinese cities.

    The catalogue covers 179 merchandise categories and links video discovery directly to fulfillment across the mainland.

    Ingka Group, which operates Ikea retail across 32 markets and accounts for 87 per cent of global Ikea retail sales, runs the digital shopfront. The operation runs alongside the retailer’s physical warehouse stores, proprietary mobile app, website, and WeChat mini-programs in China. Orders placed inside Douyin feed into Ikea’s existing national logistics network to handle deliveries across the 301 supported municipalities.

    Channel Shift to Video Commerce

    Global brands in China face a clear migration of shopper traffic away from traditional search-based marketplaces toward algorithmic feed platforms. Douyin has turned short-form video and livestreaming into primary sales drivers for consumer goods, pulling market share from established online storefronts. For furniture retailers, content-driven selling shortens the distance between lifestyle inspiration and immediate checkout.

    Selling flat-pack furniture through social video carries distinct operational demands. Bulky freight logistics and higher assembly-related return rates punish merchants that treat short-video channels as pure promotional feeds. Ikea is betting its localised delivery footprint can absorb the volume without eroding margins through fulfillment delays.

    Lessons for Global Retail Networks

    Parent company Ingka Group intends to export operational insights gathered from Douyin to its broader digital operations. The retailer has introduced digital planning formats such as Ikea Kreativ and artificial intelligence tools for customer assistance in other regions. Douyin provides high-frequency consumer feedback on pricing, product bundles, and live visual merchandising that purely transactional websites rarely generate.

    “Retail is increasingly about being present wherever and whenever people want to meet us, while making those experiences feel like one connected IKEA. What is particularly interesting about new platforms like Douyin E-commerce is the opportunity to learn. They help us understand how inspiration, interaction and commerce are coming closer together, and what that could mean for how we continue to develop the IKEA omnichannel experience.”

    Parag Parekh, chief digital officer at Ikea Retail within Ingka Group, confirmed the company will funnel feedback from Chinese shoppers into digital development programs across other territories.

    Building the Multi-Channel Network

    The Douyin store launch follows a multi-year effort by Ikea China to dismantle its historical reliance on destination suburban big-box stores. The Swedish retailer first opened its official Tmall storefront in 2020 before rolling out bespoke WeChat shopping mini-programs and urban small-format locations across tier-one cities.

    Lydia Song, Ikea China acting chief executive officer, president, and chief sustainability officer, oversees the integration of the video platform into the brand’s local store fleet. The retailer will monitor conversion rates and city-level delivery performance ahead of the upcoming fourth-quarter promotional calendar in China.

  • Baby Bunting Lifts Australasian Sales as Store Upgrades Drive 20% Growth

    Baby Bunting Lifts Australasian Sales as Store Upgrades Drive 20% Growth

    Baby Bunting lifted sales across Australia and New Zealand between August 15 and October 4, driven by a 20 per cent cumulative revenue rise across its newly refurbished locations.

    Australian store sales rose 2 per cent during the period, while New Zealand operations jumped 8.7 per cent following capital investments in redesigned shop floors.

    Store of the Future rollout gathers pace

    The specialty nursery retailer poured $44.5 million into its Store of the Future program during fiscal 2026. Management plans to refurbish or open 120 locations across both markets before the overhaul finishes.

    Seven stores entered fiscal 2027 closed for renovations. The redesign swaps traditional category aisles for activity-based displays organised around nursery setup, feeding, travel and play routines.

    “The new format moves our stores from a category-led layout to an activity-led layout, designed around how parents actually shop, and the results speak for themselves,” Chief Executive Officer Mark Teperson said.

    Divergence between new and old formats

    Older stores without the redesign lagged internal sales targets as broader discretionary retail spending softened. The upgraded footprint carried total revenue higher instead.

    That divide mirrors challenges across specialty retail in Australasia. Big-box specialty chains face higher wage rates, utility bills and cautious consumer budgets, forcing operators to extract higher sales density from existing square metres rather than purely opening new doors.

    Landlords face increased scrutiny over tenant allowances and lease terms. Retailers willing to invest capital into physical experiential formats hold stronger use in lease renegotiations across key suburban homemaker centres.

    Margin targets and consumer headwinds

    The capital expenditure follows a fiscal 2026 recovery after inventory corrections and discount pressures weighed on earnings across the baby goods sector. The company disclosed the early fiscal 2027 figures in an ASX filing ahead of its annual general meeting.

    Teperson told shareholders the executive team is tracking interest rates and cost-of-living pressure on young households ahead of the peak year-end holiday shopping cycle.

    Baby Bunting aims to lift its earnings before interest, tax, depreciation and amortisation margin back above 10 per cent as the network refurbishment scales toward its 120-store target.

  • Singapore Needs Capital Injections Beyond $6.5 Billion EQDP, SGX Chairman Says

    Singapore Needs Capital Injections Beyond $6.5 Billion EQDP, SGX Chairman Says

    Singapore Exchange chairman Koh Boon Hwee said the domestic stock market lacks flow and liquidity, leaving local investors unwilling to take risks on home-grown shares.

    Speaking on the sidelines of the Forbes Global CEO Conference on Oct 8, Koh noted that further capital injections will be needed to sustain demand, even as the government allocates $6.5 billion through the Equity Market Development Programme. However, he warned that state injections are not a natural, lasting flow like pension-backed markets in the US.

    Koh pointed out that younger Singapore investors have an appetite for risk when buying volatile overseas stocks like Tesla and loss-making SpaceX, but local initial public offerings struggle for traction after listing.

    The Exit Route Problem For Growth Firms

    Early-stage venture funding finds solid support in Singapore. Even so, early backers need domestic public markets to absorb later-stage equity. Thin local trading volume forces founders abroad to provide exits for their investors.

    Regional technology leaders repeatedly bypass the local exchange. Shopee parent Sea listed on the New York Stock Exchange in 2017. Ride-hailing group Grab completed a Nasdaq debut in 2021 through a blank-check combination. In October, Singapore-headquartered data centre developer DayOne filed for a Nasdaq initial public offering, continuing the flow of domestic tech assets to the United States.

    Pension Flow Versus Injections

    State-backed interventions do not generate the structural momentum of institutional retirement pools. Equities in the United States draw on multiple independent pension systems. These funds constantly deploy fresh capital across public listings, private equity, and venture funds.

    The 6.5 billion Singapore dollar injection under the EQDP commits capital without creating an automatic mechanism for ongoing demand. Koh noted that the state fund is invested rather than spent. Standalone allocations leave unresolved questions about long-term reinvestment.

    “Our challenge right now is to create something that is circular and sustainable,” said Koh.

    Supply Chain Concentration Risks

    Capital concentration in Singapore tilts heavily toward established lenders, industrial landlords, and real estate investment trusts. These blue-chip counters trade steadily. Their sheer scale makes rapid compound expansion difficult to maintain over decades.

    Backing younger firms offers a route to build consumer-facing companies with proprietary brand equity rather than component suppliers. Tiered supply chains leave component makers vulnerable to sharp order swings. A 5 per cent order cut from a consumer brand can trigger a 15 per cent revenue decline down the manufacturing chain.

    Domestic Valuation Gaps

    A wide gap between private seed financing and public market liquidity leaves founders with few domestic exit options. If the local exchange cannot provide secondary buyers for high-growth enterprises, early venture capital remains locked abroad once portfolio companies exit in New York or Hong Kong.

    The Monetary Authority of Singapore and SGX have reviewed measures to encourage regional listings, while market participants watch DayOne’s pending Nasdaq filing for final pricing terms.

  • Vietnam Cosmetics Stores Reach 574 as Hasaki Leads Expansion

    Vietnam Cosmetics Stores Reach 574 as Hasaki Leads Expansion

    Vietnam’s beauty retail sector recorded 574 stores as of March 2026, up 4.5 percent from 2025 as the pace of store openings moderated after years of rapid growth.

    According to market research firm Q&Me, the physical expansion unfolded alongside rapid digital adoption, with beauty and personal care online sales reaching VND74.4 trillion ($2.83 billion) in 2025.

    Domestic chains take market share

    Hasaki Beauty & Clinic remained the industry’s fastest-growing chain by store openings, adding 52 outlets in a single year to expand its footprint from 172 locations in 2024 to 252 in 2025, with projections to reach 304 stores in 2026.

    Founded in 2016, Hasaki operates an integrated business model combining beauty retail with on-site aesthetic clinics. The retailer raised capital repeatedly to fund network growth, increasing its charter capital to VND350 billion ($13.27 million) in October 2024.

    Co Mem, a domestic brand focused on natural beauty formulas, posted store count growth exceeding 20 percent. The chain is on track to expand from 62 stores in 2025 to 80 locations in 2026 by targeting provincial retail markets beyond Hanoi and Ho Chi Minh City.

    International players slow the pace

    Pan-Asian pharmacy and beauty chains maintained their networks while opening fewer new outlets than local competitors. Guardian is projected to increase its Vietnamese footprint from 125 to 127 stores, while regional rival Watsons maintained steady store counts.

    Smaller multi-brand operators also posted incremental gains. Aeon-backed Glam Beautique is expected to rise from 14 to 16 outlets, and domestic competitor The Gioi SkinFood is projected to increase from 10 to 12 locations.

    Single-brand formats lose ground

    Single-brand cosmetics stores recorded sharp contractions across Vietnamese high streets and shopping centers. Korean beauty chain The Face Shop is projected to shrink its retail presence from 28 stores in 2025 to nine outlets in 2026.

    British retailer The Body Shop also reduced its physical footprint, bringing its store count down to 29 nationwide. Shoppers have shifted spending toward multi-brand formats that offer broader product selections, cross-brand promotions and rapid delivery fulfillment.

    Shifting retail economics

    The divergence between multi-brand store growth and mono-brand closures alters leasing terms for shopping mall operators and streetfront landlords. Landlords in secondary cities now rely on multi-brand beauty chains to anchor personal care floors rather than standalone boutique stores.

    Alibaba International Digital Commerce Group completed the purchase of a minority stake in Hasaki in late 2023. That backing gave the local chain the financial reserves needed to build density across secondary provinces, where lower commercial rents allow larger floorplates.

    Retailers now face the task of sustaining store-level profit margins as physical network growth slows toward single digits. The next milestone for the sector comes at the end of 2026, when Hasaki aims to cross the 300-store mark across Vietnam.