Author: Mei Ling Tan

  • Chinese Automakers Double Paris Car Show Presence with 20 Brands

    Chinese Automakers Double Paris Car Show Presence with 20 Brands

    Around 20 Chinese automotive brands unveiled new models at the Paris car show on Oct 12. They doubled their presence from 2024 to capture European market share.

    Passenger vehicle sales across China fell 20 percent in the first half of 2026. That drop forced domestic manufacturers to accelerate overseas distribution.

    Car manufacturers from China and Europe presented up to 60 new models at the event. Chinese participants included established exporters BYD, Chery, and SAIC’s MG brand, alongside newer entrants such as Aito. State-owned Changan debuted two separate marques, Nevo and Avatr, targeting retail buyers across Western Europe.

    Export pressure mounts as domestic sales drop

    The United States market is largely closed to Chinese automotive imports. That leaves Europe as the central battleground for manufacturers dealing with price competition at home. Chinese car companies have expanded their European market share steadily over the past three years, relying on aggressive retail pricing and rapid model cycles.

    For retailers and dealership groups across Europe, arriving Chinese marques offer wider inventory margins. But they also bring operational volatility. Multi-brand dealership networks in France and Germany face showroom floor adjustments as new brands compete directly against established European volume models.

    Regulatory headwinds and hybrid curbs

    Tightening trade barriers across the European Union now challenge this product rollout. A recent pact between Brussels and Beijing could cut Chinese hybrid vehicle shipments to the bloc by more than half. Detailed implementation mechanisms remain unpublished.

    Those curbs hit hybrid channels directly. Investment bank Jefferies reported in an Oct 11 client note that BYD, Chery, and SAIC’s MG accounted for 90 percent of all Chinese-brand hybrid vehicle sales in the European Union during the first eight months of 2026.

    Local assembly strategies take shape

    Trade friction has pushed Chinese original equipment manufacturers toward European industrial partnerships. The European Union imposed import tariffs on Chinese-assembled fully electric vehicles in October 2024. Meanwhile, policymakers are drafting minimum local-content thresholds under upcoming Made in Europe rules.

    Several groups are responding by moving production directly onto European soil. Geely Auto confirmed in July that it will manufacture electric sport utility vehicles at a Ford Motor plant in Spain. Geely chief executive Alex Nan met partners on Oct 11 in Paris to reinforce joint manufacturing and powertrain ventures with French carmaker Renault.

    Legacy automakers fight back

    European car manufacturers are defending their home territory with competing entry-level models. Stellantis revealed six production vehicles and nine concept cars in Paris. Its push was led by a low-cost electric Citroen 2CV aimed at halting Chinese market share gains.

    Volkswagen chief executive Oliver Blume stated on Oct 11 that European markets require equal operating conditions. He urged foreign manufacturers selling in Europe to generate domestic employment and industrial value.

    Brussels will trigger the next shift when the European Commission releases draft text for its Made in Europe local-content mandate. That measure will define factory sourcing requirements for electric vehicle sales across the bloc.
  • Domino’s CEO Andrew Gregory Takes Control of ANZ as Merrill Pereyra Exits

    Domino’s CEO Andrew Gregory Takes Control of ANZ as Merrill Pereyra Exits

    Domino’s Pizza Enterprises Group CEO and Managing Director Andrew Gregory has taken direct control of the Australia and New Zealand business, effective immediately, to accelerate the company’s reset plan.

    The move follows a mutual agreement for ANZ CEO Merrill Pereyra to leave the business after being appointed to the role earlier this year.

    Pereyra, who holds more than 30 years of quick-service restaurant experience, led a phase focused on reducing costs, paying down debt, strengthening cash flow, and improving franchise partner returns while Domino’s searches for a successor.

    Management shift at the regional unit

    The sudden change puts group-level leadership back into direct line management over the home territory. Regional operations teams will report directly to Gregory while the board conducts an executive search.

    Pereyra previously served as chief executive of Domino’s Pizza Indonesia and held regional leadership roles at McDonald’s across a 30-year industry career. His brief tenure running the Australia and New Zealand business focused on stabilizing unit economics after successive margin squeezes.

    “The reset has established a stronger foundation for the business and remains on track,” chairman Jack Cowin said. “Australia/New Zealand is critical to the Group’s success, and the Board supports Andrew taking direct responsibility to increase the pace of execution while maintaining a clear focus on sustainable, profitable growth for franchise partners.”

    Restructuring and franchisee economics

    The company’s reset plan centers on four financial levers: cutting overhead costs, accelerating debt paydown, lifting free cash flow, and restoring store profitability. Ingredient inflation and higher labor costs strained store margins across Australia and New Zealand over recent trading periods.

    Direct corporate intervention in divisional management signals that the board wants faster cost discipline. Franchisee relations remain the primary operational risk. Store owners need immediate relief on input costs and delivery margins to protect cash returns.

    Quick service restaurant leadership

    Gregory brings extensive quick-service restaurant experience to the operational post, including a previous stint as chief executive of McDonald’s Australia. That background gives group management deep familiarity with franchised supply chains, digital ordering platforms, and local store marketing.

    Fast-food operators across the region face a more cautious consumer base cutting back on discretionary deliveries. Competitors have leaned heavily on price discounts and value bundles. This forces franchisors to balance transaction volume against franchisee gross margins.

    Search for permanent leadership

    Domino’s Pizza Enterprises confirmed the search for a dedicated regional chief executive is underway. The existing divisional leadership team will maintain daily field support and supply logistics during the transition.

    Progress under Gregory will hinge on how quickly store profitability recovers before a new regional chief executive steps in.

  • Oeko-Tex Records 13 Percent Rise in Made in Green Demand

    Oeko-Tex Records 13 Percent Rise in Made in Green Demand

    Oeko-Tex launched its Trust in Every Thread consumer campaign on Oct. 12 after the European Union introduced regulations restricting unverified sustainability claims across apparel and textiles.

    Demand for the group’s Made in Green standard rose 13 percent during its 2025-26 fiscal year.

    At the centre of the campaign is a 35-second film and consumer education drive. It directs shoppers to inspect garment tags and verify claims through digital traceability tools. The European Union’s Empowering Consumers for the Green Transition Directive took effect on Sept. 27. It outlaws sustainability labels lacking backing from public authorities or accredited third-party certification bodies. Private schemes must now maintain publicly accessible criteria, enforce third-party monitoring, and provide mechanisms to suspend non-compliant users.

    Stricter verification rules for textile certification

    Generic environmental buzzwords face outright bans under the new European framework unless backed by verified data. Brands can no longer present a single product characteristic as proof of whole-garment sustainability. Verification systems must also operate independently from scheme owners and commercial clients.

    Standard 100, the core certification from Oeko-Tex, tests raw materials, intermediate goods, and finished items for more than 1,000 harmful chemicals. Criteria cover every component of a finished product, including sewing threads, zippers, and buttons. Limit values undergo mandatory annual reviews. The tightest thresholds apply to baby and toddler clothing up to three years of age.

    Quality control procedures require retesting for 25 percent of all issued certificates each year. The group enforces compliance through unannounced site inspections and factory audits across its global network.

    Supply chain transparency and chemical screening

    The broader Made in Green certification links Standard 100 product testing with facility-level audits under the STeP program. That framework evaluates chemical management, working conditions, and environmental performance inside processing mills and cut-and-sew units. Each certified item carries a dedicated product ID and QR code. Shoppers can use them to track production stages back through the manufacturing chain.

    Rival standards take different approaches. The Global Organic Textile Standard requires a minimum of 70 percent organic fibres, while Bluesign focuses on facility chemical management and specific inputs. Oeko-Tex designed its dual-track testing and facility tracking system to satisfy European regulators demanding end-to-end evidence.

    Garment suppliers and global brands sourcing from manufacturing hubs across Asia face immediate compliance pressure. Exporters operating without accredited third-party verification risk regulatory fines and product suspensions at European ports of entry.

    Governance overhaul and structural separation

    Oeko-Tex revamped its operating structure ahead of the European directive to protect its certification status. In an announcement on Aug. 19, the organization separated standard-setting operations from conformity assessments. The restructuring introduced an independent oversight council and an anonymous whistleblowing platform for reporting compliance breaches.

    Inga Bleyer, head of marketing and communication at Oeko-Tex, outlined the rationale behind the verification drive in an official statement:

    “Trust is not a word you can put on a label. It is built in the places nobody looks: in the button, the zipper, the thread, in the limits we revise every year because the science moves, in a quarter of our certificates we go back and retest.”

    What buyers and suppliers face next

    Chief executive Alfred J. Beerli stated that independent verification remains the only mechanism to safeguard consumer trust under the new regulatory climate. The group’s digital Label Check portal lets retailers and shoppers enter certificate numbers to verify validity in real time.

    European member states must now transpose and enforce national penalties under the directive as customs authorities inspect incoming shipments. Brand compliance audits across autumn and winter retail collections will test how strictly European regulators apply the documentation standards.

  • Former Flipkart Staff Mobilise for Share in Proposed $2 Billion Share Buyback

    Former Flipkart Staff Mobilise for Share in Proposed $2 Billion Share Buyback

    A group of former Flipkart executives has launched a campaign to mobilise up to 30,000 former staff across India. They are demanding inclusion in a proposed $2 billion share buyback.

    The petition started on October 10. It targets parent company Walmart, which refused to guarantee immediate liquidity for vested options held by departed workers.

    Organisers represent alumni from the core marketplace alongside group subsidiaries Myntra, Cleartrip, Shopsy, Super Money and ANS Commerce. They want Walmart to open the upcoming repurchase pool to former staff rather than restricting payouts to current employees.

    Three Demands Put To Bentonville

    This campaign sets out three operational demands for Walmart and Flipkart leadership before the $2 billion deal closes.

    First, the group wants the exercise window for vested stock options extended until a liquidity event takes place. Second, ex-staff seek full participation rights in the buyback on identical terms to current workers, rejecting any nominal allocation. Third, the petition demands a formal corporate liaison to negotiate directly with an elected alumni committee.

    Former employees frame the campaign as an invitation to commercial dialogue rather than a legal dispute. Early staff took pay cuts and career risks during Flipkart’s early growth. In exchange, they received equity that has remained illiquid for over a decade.

    Escalating Pressure After Leadership Letter

    An earlier October 1 letter went directly to Walmart’s board from several former operating leaders. Signatories included Myntra cofounder Mukesh Bansal, former Flipkart group chief financial officer Sanjay Baweja and former chief business officer Ankit Nagori.

    Those executives asked for an exit route for options granted between 10 and 15 years ago. Walmart’s legal counsel responded that former staff would be considered during an eventual initial public offering. Counsel offered neither a timeline nor a binding commitment.

    Alumni pushed back against the stance. Without a filed prospectus and in volatile markets, waiting for a listing creates open-ended holding risk for departed option holders.

    The Valuation Divide In Indian Tech

    For technology operators and private equity backers across Asia, the Flipkart dispute reflects broader friction over long-dated employee equity. Indian tech platforms routinely issued options instead of cash compensation during market-share battles between 2012 and 2020. Listing timelines now stretch from five years to fifteen. Those incentive structures leave buyers with heavy balance sheet overhangs and reputational exposure.

    Walmart ring-fenced previous cash distributions for active staff to protect employee retention in India. In July, Flipkart ran a $50 million liquidity round letting eligible current staff cash out up to 5 percent of their vested options at a $38.2 billion valuation. Excluding alumni while paying current staff deepens the rift between early builders and incoming corporate managers.

    Redomiciling And Listing Uncertainty

    Flipkart cleared a major corporate hurdle in March by moving its corporate domicile from Singapore back to India. The tax restructuring clears a path for a domestic listing. Still, the group has not filed a schedule with market regulators.

    Speaking on the company’s listing road map in a July interview, Flipkart group chief executive officer Kalyan Krishnamurthy said:

    We don’t have any timeline right now and, to be very clear, we never have had any timeline for going public. It’s not a management-only decision that can be made.

    Walmart has not responded publicly to the broader staff petition. Attention now turns to whether the retailer finalises the terms of the $2 billion buyback without an alumni carve-out before the end of the financial quarter.

  • Sega Shifts Strategy from Selling Games to Building Transmedia Ecosystems

    Sega Shifts Strategy from Selling Games to Building Transmedia Ecosystems

    In October 2026, Sega outlined a shift in its commercial strategy toward multi-channel intellectual property ecosystems, moving away from a traditional reliance on packaged video game releases to drive core revenue across consumer markets.

    President Shuji Utsumi confirmed the Tokyo-based entertainment company is deploying films, retail licensing agreements, and direct fandom engagement to anchor franchise values across physical and digital storefronts.

    Building beyond standalone software

    The transmedia push prioritises cross-platform character exposure over single-title release schedules. Film adaptations and character merchandise now serve as primary customer acquisition channels rather than secondary promotional spin-offs, feeding consumer demand directly into software catalogues, physical retail merchandise, and digital brand platforms.

    Executive leadership under Utsumi is aligning internal development studios with external film distributors and consumer product licensees. The operational framework treats each intellectual property portfolio as an enduring franchise ecosystem designed to retain audience spend across multiple entertainment touchpoints.

    The read across for Asian licensing and retail

    For toy manufacturers, apparel licensees, and retail buyers across the Asia-Pacific region, Sega’s multi-channel pivot establishes continuous consumer engagement throughout product life cycles. Traditional video game merchandising relied on volatile spikes during hardware generation launches or standalone sequel debuts, leaving shelf space vulnerable during development lulls.

    A coordinated release calendar spanning theatrical distribution, streaming content, and physical consumer goods reduces operational inventory risks for commercial partners. The challenge for Sega lies in maintaining franchise quality across external licensing partners while protecting brand equity from overexposure in competitive consumer categories.

    Competitive pressure across regional peers

    Japanese entertainment conglomerates are systematically consolidating character portfolios to defend consumer wallet share against Western entertainment groups. Regional rivals such as Bandai Namco have accelerated cross-border licensing expansions across Southeast Asia to insulate balance sheets from domestic demographic contraction.

    Sega’s transmedia rollout establishes the operational benchmark for its upcoming pipeline of legacy properties, with management tracking audience engagement and cross-category licensing conversions as the next multi-platform releases enter international markets.

  • 1MDB in Talks to Settle US$1.83 Billion Lawsuit with Deutsche Bank

    1MDB in Talks to Settle US$1.83 Billion Lawsuit with Deutsche Bank

    1Malaysia Development Berhad is negotiating a settlement with Deutsche Bank Malaysia Berhad over a US$1.83 billion lawsuit filed in Kuala Lumpur. Counsel for the fund confirmed the talks to the Federal Court.

    Legal counsel Datuk Lim Chee Wee disclosed the talks before a three-member Federal Court panel led by Chief Judge of Malaya Datuk Seri Hashim Hamzah. High Court Judicial Commissioner Rihada Rafie will hear the proposed agreement on October 26. Financial terms remain undisclosed.

    Details of the Multi-Billion Dollar Claim

    The state investment vehicle filed the suit on May 7, 2021, targeting seven defendants. It alleged breach of contract, negligence and criminal conspiracy linked to stolen company funds. The original filing named Deutsche Bank (Malaysia) Berhad, Coutts & Co, JP Morgan (Switzerland), Petrosaudi International, Petrosaudi Holdings (Cayman), Tarik Obaid and Patrick Mahony.

    Court filings alleged the defendants assisted in fraudulent transactions that caused heavy capital losses and damaged the fund’s reputation. 1MDB dropped JPMorgan and Coutts & Co from the lawsuit on November 13 last year, narrowing the scope of the case.

    Federal Court Weighs Evidence in White & Case Appeal

    Alongside the Deutsche Bank negotiations, the Federal Court panel addressed 1MDB’s application for leave to appeal a separate ruling involving London law firm White & Case LLP. Chief Judge of Sabah and Sarawak Datuk Seri Azizah Nawawi and Federal Court Judge Datuk Ravinthran N. Paramaguru completed the three-member bench.

    Counsel for White & Case, Datuk Dr Cyrus Das, objected to 1MDB submitting more than 3,000 pages of supplementary documents. Khoo Guan Huat, another counsel for 1MDB, stated that the records were raised during earlier case management. The apex court admitted the documents. It also directed the filing of affidavits and ordered immediate case management to fix a hearing date.

    Jurisdictional Rulings and Institutional Risk

    On August 20, the Court of Appeal overturned a High Court decision that allowed 1MDB’s fraud claim against White & Case to proceed locally. The appellate judges ruled that Malaysian courts lacked jurisdiction over the foreign firm. Filed in 2024, that suit sought US$1.83 billion plus US$33 million in consequential losses from White & Case and Mahony over allegations of assisting PetroSaudi during advisory mandates.

    Jurisdictional disputes have complicated Malaysia’s efforts to pursue international financial intermediaries and legal advisers abroad. For institutional banks and advisory firms in Southeast Asia, negotiated settlements provide legal finality while avoiding protracted discovery across multiple countries.

    Next Steps in the Recovery Proceedings

    Global investigations into billions of dollars siphoned from 1MDB previously spurred asset recovery actions across Malaysia, Singapore, Switzerland and the United States. Settlements with major banks have driven Malaysia’s broader recovery efforts in recent years.

    Judicial Commissioner Rihada Rafie will take up the proposed settlement terms between 1MDB and Deutsche Bank at the Kuala Lumpur High Court on October 26.

  • Chinese Luxury Gold Jeweler Lamchiu Generates 10 Million Yuan on Nanjing Debut

    Chinese Luxury Gold Jeweler Lamchiu Generates 10 Million Yuan on Nanjing Debut

    Lanzhou gold jeweler Lamchiu generated over 10 million yuan during the first day of its soft launch at Nanjing Deji Plaza on Sept. 25.

    It is the third-generation family business’s first retail store outside its home city in northwestern China. The jeweler generated more than 500 million yuan in sales from its sole Lanzhou location in 2025.

    Handmade Production and Delayed Rollouts

    Lamchiu pushed back the Nanjing opening twice from its initial July target to finish handcrafted architectural elements. The basement space in Deji Plaza features handmade Suzhou floor bricks alongside interior walling of Quyang marble and Jingdezhen ceramics. Workers spent twelve months assembling a barrel-vaulted ceiling from mother-of-pearl scales.

    Handcrafted techniques account for more than 90 percent of the brand’s output, spanning filigree, chasing, and fine carving across original designs. Production bottlenecks forced the company to halt order intake twice in 2024. Lamchiu raised retail prices by 10 to 20 percent in 2025 as lead times stretched to twelve months. Customer orders still outpaced workshop capacity.

    Rethinking Expansion Models for Chinese Luxury

    High-end shopping center operators see slow-craft domestic jewelers shifting the leasing equation away from fast-turnover international fashion. Landlords such as Deji Plaza now place domestic fine gold houses including Lamchiu, Laopu Gold, and Junpei directly beside European legacy labels on premium concourses. These brands secure strong sales densities and demand lower marketing allowances from property managers. Affluent domestic shoppers readily place prepaid orders months in advance.

    Institutional investors face clear trade-offs between pricing power and operational scaling. Handcrafted gold items cannot scale on automated manufacturing lines, creating a hard ceiling on quarterly unit volume. The investment thesis hinges on margin retention, bespoke ticket sizes, and cultural resonance among high-net-worth buyers rather than physical footprint growth.

    Cultural Commerce Across Eastern Hubs

    A parallel shift toward low-velocity, heritage-driven commerce is surfacing across eastern Chinese retail districts. In Hangzhou’s Xihu district, municipal developer West Lake Construction Investment Group curated the Liuxia 1129 historical zone around Song Dynasty cultural activities rather than standard retail tenancies. Chinese incense house Kongshan Shi staged a multi-month series of private literati gatherings and tea banquets in the district through autumn, avoiding overt point-of-sale promotions.

    Hangzhou reported a gross domestic product exceeding 2.3 trillion yuan in 2025, yielding a per-capita GDP of approximately $24,000. That regional wealth gives commercial operators room to trade rapid lease turnover for distinctive heritage positioning.

    The most extreme beauty in this world is kindness, and business is the same. Growth and revenue matter, of course. But we are willing to give patience and space, so in choosing tenants we have made the trade-offs we should.

    Capital Follows Heritage Craft

    Venture funds and private equity firms poured capital into heritage-focused luxury operators over the past twelve months. Lamchiu closed a strategic funding round of more than 100 million yuan at the end of 2025 to finance store construction and workshop expansion. Hangzhou-based gold label Baolan secured a Series A round exceeding 100 million yuan led by Challenger Ventures, with backing from Kering and Shunwei Capital.

    Store designs are now underway for Lamchiu’s planned openings in Shanghai and Shenzhen, testing whether bespoke regional flagships can sustain order backlogs as store counts rise.

  • Thailand Plans Foreign Investment Push to Lift Economic Growth to 3%

    Thailand Plans Foreign Investment Push to Lift Economic Growth to 3%

    Thailand plans to lift economic growth to 3 per cent within three years by channeling foreign investment into data centres, semiconductors and electric vehicle manufacturing.

    The target comes after Southeast Asia’s second-largest economy grew at an annual average of just 2.34 per cent over the past five years, trailing the faster recoveries posted by regional neighbours.

    Thai Finance Minister Ekniti Nitithanprapas outlined the investment-led strategy ahead of Bangkok hosting the annual meetings of the International Monetary Fund and the World Bank next week. The government is directing capital incentives toward energy-heavy high-tech sectors while investing in renewable power to support incoming factories and server farms.

    Investment ratio drops after 1997 crisis

    Capital spending across the country has never fully regained the share of economic output it held before the 1997 Asian financial crisis, when Bangkok devalued the baht and sought an IMF bailout.

    “After the financial crisis, our investment-to-GDP has declined to around 22% to 23% at the moment. So that’s why our growth momentum has been so slow,” Ekniti said in an interview.

    Rebuilding that baseline forms the core of the current ministerial agenda, but the fiscal room for state stimulus remains constrained. Thailand’s public debt-to-GDP ratio is approaching the official statutory cap of 70 per cent, limiting direct government spending programmes.

    Central bank divergence and consumer debt

    The Ministry of Finance faces a more cautious assessment from the Bank of Thailand, which estimates the country’s potential growth rate at 2.7 per cent. The central bank projects that reaching even that lower expansion rate will take at least four years of structural adjustment.

    Commercial banks and store operators face immediate drag from elevated household debt levels that curb discretionary consumer spending across retail formats. Weaker tourist arrivals have compounded pressure on urban malls and hospitality venues that rely on foreign footfall to offset sluggish domestic purchases.

    Unresolved bilateral trade negotiations with Washington create further export friction for electronics and component suppliers looking to scale up production runs.

    Tech and electric vehicle supply chains

    Industrial developers across the Eastern Economic Corridor have pivoted land allocations toward clean energy infrastructure to accommodate overseas semiconductor and cloud infrastructure groups. These capital-intensive installations demand stable power supplies that traditional local grids cannot deliver without renewable additions.

    Automotive assemblers in Thailand must also transition established internal combustion engine lines to battery-powered vehicles without forfeiting their established regional export volumes. Japanese automakers that dominated local factory floors for decades now face direct competition from expanding Chinese electric vehicle brands establishing assembly hubs around Rayong and Chonburi.

    Outlook improves after February elections

    Credit rating agencies have recognized signs of political stability following the general elections held in February 2026. Fitch Ratings revised Thailand’s sovereign outlook to stable from negative, citing reduced deflationary pressures and greater policy predictability despite broader global energy shocks.

    External headwinds remain acute as global institutions warn that persistent energy volatility, record public debt loads and surging artificial intelligence capital requirements test emerging market fiscal buffers.

    Delegates gather at the Queen Sirikit National Convention Center next week for the IMF-World Bank meetings, where Thai officials will present their foreign investment roadmap to international lenders and corporate executives.

  • AI Could Offset Asia’s 25% Workforce Loss by 2050, IMF Says

    AI Could Offset Asia’s 25% Workforce Loss by 2050, IMF Says

    Artificial intelligence could help offset Asia’s shrinking workforce as populations age if adoption is scaled evenly across the region, the International Monetary Fund said on Monday.

    IMF Managing Director Kristalina Georgieva said at a book launch during meetings at the Queen Sirikit National Convention Center that AI is projected to lift growth in advanced Asia by 0.5 to 1 percentage point, more than offsetting demographic pressure if productivity is captured.

    The demographic drop in North Asia

    Countries including China, Japan and South Korea could lose nearly 25 percent of their working population between now and 2050, according to findings in the IMF book, though productivity gains from AI could offset that loss.

    IMF Managing Director Kristalina Georgieva presented the findings during the IMF and World Bank annual meetings at the Queen Sirikit National Convention Center. She identified demographics, regional trade integration and artificial intelligence as the three central shifts deciding Asia’s economic trajectory.

    AI is projected to lift up growth in advanced Asia, where the ageing populations are, somewhere between half a percentage and one percentage point… And what is amazing is that if the countries capture productivity and this growth, they will more than offset the demographic pressure

    Divergence between rich and emerging markets

    The gap between mature industrial economies and developing Southeast Asian nations creates an uneven playing field for artificial intelligence rollout. Wealthier hubs possess the computing infrastructure and capital required to automate white-collar tasks and industrial workflows quickly.

    Developing markets face different exposure levels. Krishna Srinivasan, director of the IMF Asia and Pacific department, warned that emerging economies have fewer automated jobs today but also lack the capital to capture software-driven productivity gains without targeted policy support.

    Supply chains and operational exposure

    For consumer goods manufacturers, retailers and logistics operators across Asia, the findings point to immediate operational choices. Supply chain networks that depend on cheap labour in aging hubs must substitute headcount with automated fulfilment, inventory forecasting and automated sorting.

    Retailers in Japan and South Korea already operate with automated store checkouts and robotic warehouse pickers to handle persistent staffing shortages. Expanding those systems into Chinese manufacturing corridors will determine whether factory gate prices stay stable as industrial payrolls shrink.

    Trade barriers and reform timelines

    Technology alone will not solve structural regional slowdowns without cross-border commerce reforms. Lowering non-tariff barriers and deepening trade pacts across Asia would expand regional gross domestic product by approximately 1.8 percent over the long term.

    Srinivasan noted that national workforce training programmes and regulatory reforms can accelerate enterprise adoption of artificial intelligence tools by a decade or more. Asian policymakers now face the task of drafting common digital standards and labour retraining budgets before the projected 2050 workforce contraction reaches its steepest curve.

  • Smart Launches Electric #2 City Car in China at 112,999 Yuan

    Smart Launches Electric #2 City Car in China at 112,999 Yuan

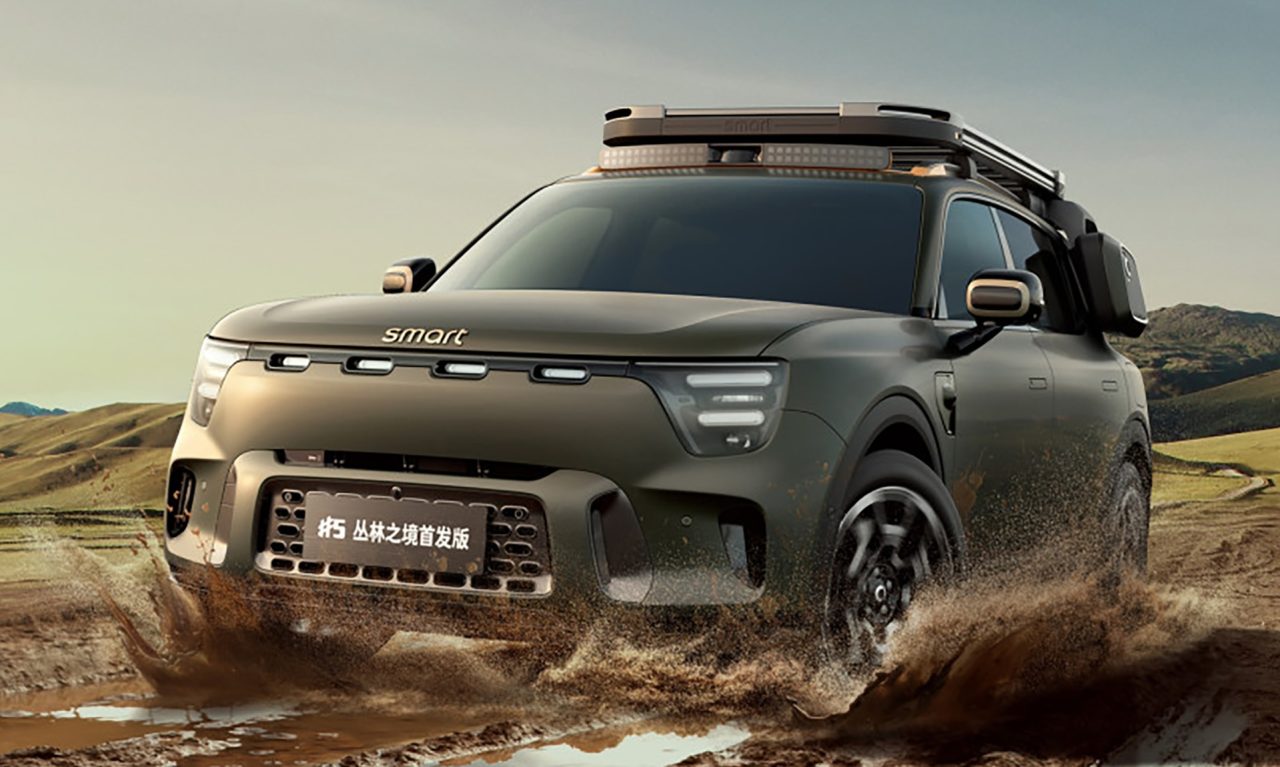
    Smart launched the Smart #2 Couture Edition in China for 112,999 yuan ($16,790). The release revives its signature two-seater city car format as an all-electric model.

    The joint venture between Mercedes-Benz and Geely Auto capped the initial Chinese run at 999 numbered units. That matches a separate 999-unit allocation earmarked for European buyers.

    Deliveries for immediate Chinese orders begin before year-end. Early ordering opens across Europe following the car’s global debut at the Paris Motor Show. European buyers face a pre-order entry price of 19,990 euros ($22,400). Chinese buyers will see pricing for standard Premium variants in November.

    Hardware and Architecture

    Built on Geely’s Electric Compact Architecture, the vehicle uses a platform engineered specifically for ultra-compact urban runabouts. Mercedes-Benz’s global design team handled the styling. They retained the proportions of the original ForTwo while adding LED lighting, flush surfaces and a capsule-patterned grille.

    A 35.8-kilowatt-hour lithium iron phosphate battery pack powers the vehicle, using cells supplied by CATL. It delivers a China Light-Duty Vehicle Test Cycle range of 410 kilometres. European testing targets a combined Worldwide Harmonised Light Vehicles Test Procedure range of 290 kilometres.

    Power comes from a single rear-mounted electric motor driving the rear axle. It produces 60 kilowatts of power and 130 Newton-metres of torque. The chassis pairs MacPherson strut front suspension with a five-link independent rear setup, delivering a tight turning radius of 3.35 metres. European models support 65-kilowatt direct-current fast charging, taking the battery from 10 per cent to 80 per cent in 20 minutes.

    Cabin Layout and Dimensions

    Dimensionally, the vehicle measures between 2,751 and 2,764 millimetres in length, 1,669 millimetres in width and 1,555 millimetres in height, riding on an 1,875-millimetre wheelbase. The exterior pairs matte white paint with a gold roof, gold grille accents and 16-inch alloy wheels. Staggered tyres measure 185/50 at the front and 205/45 at the rear.

    Inside, the cabin features an S-shaped dashboard, bench-style seating, turbine air vents and an infotainment display running the Flyme Link operating system. The car includes Level 2 driver assistance and remote automated parking. At the rear, the split tailgate retains a folding lower section that supports up to 120 kilograms when parked.

    Urban EV Market Strategy

    Smart’s return to the two-seater segment tests whether premium urban minicars can command retail margins in a domestic Chinese market crowded with budget micro-EVs. Geely and Mercedes previously repositioned Smart into mainstream compact crossovers with the #1 and #3 to chase broader sales volume. Bringing back the two-seater at nearly 113,000 yuan requires convincing city drivers to pay a substantial premium over mass-market urban runabouts that sell for half that amount.

    Production handled by Geely’s Zhejiang Haoqing Automobile Manufacturing gives the joint venture a low manufacturing cost base for export shipments to Europe. European urban centres tightly regulate vehicle emissions and parking footprints. That creates clearer commercial demand for micro-footprint electric vehicles than China’s wider highway networks require.

    Production History and Next Steps

    The original petrol-powered Smart ForTwo sold more than two million units globally after its 1998 debut under Daimler ownership. This revival follows an August regulatory filing by China’s Ministry of Industry and Information Technology, which confirmed technical specifications ahead of production clearance.

    Domestic pricing for the mass-volume Smart #2 Premium variant arrives in November, followed by local market rollouts and delivery schedules across European dealer networks.

  • Malaysia Expands RM2,500 Lifestyle Tax Relief to Cover Pet Care and AI

    Malaysia Expands RM2,500 Lifestyle Tax Relief to Cover Pet Care and AI

    Malaysian taxpayers can claim veterinary treatments, shelter adoption fees and artificial intelligence software subscriptions under the RM2,500 lifestyle tax relief starting in the 2027 assessment year.

    The Ministry of Finance detailed the new scope in its Budget 2027 tax measures document released in Kuala Lumpur.

    What Qualifies Under the Expanded Cap

    Veterinary care enters the personal tax framework for the first time. Eligible claims cover vaccination and sterilisation procedures performed by registered clinics. Taxpayers can also claim fees paid to adopt rescued animals from registered shelters, an incentive meant to encourage rehoming over commercial breeding.

    Software subscriptions sit alongside pet costs in the same pool. Taxpayers may claim AI tools used by themselves, their spouses or their children. Officials framed the AI relief as a push to speed up household adoption of digital tools.

    The RM2,500 Basket Stays Fixed

    The deduction ceiling remains fixed at RM2,500 despite the longer list of eligible items. New categories must compete against established ones. Existing items include books, printed newspapers, personal computers, smartphones, tablets and household internet subscriptions, which took effect for the 2024 assessment year.

    Vendors and clinic operators may see limited fiscal upside from the shared cap. Broadband bills and hardware upgrades routinely exhaust the RM2,500 threshold on their own. Pet owners who max out the relief on electronics will gain zero extra tax savings from vet bills.

    Pressure on Municipal Budgets and Shelters

    Local councils face rising animal management costs nationwide. Official records show stray dog complaints in Malaysia climbed from 37,535 in 2024 to 44,231 in 2025. Council teams captured 77,573 dogs in 2025, up from 66,264 the prior year. Rehoming lagged far behind at 20,771 animals.

    Welfare groups lobbied for direct budget funding ahead of the announcement. Persatuan Haiwan Terbiar Malaysia asked for a dedicated RM30 million annual fund to finance nationwide sterilisation and clinic services. Federal officials bypassed that request, relying instead on consumer tax incentives.

    Implementation Rules to Follow

    Direct state funding for stray control shrank over the same timeframe. The Ministry of Housing and Local Government allocated RM130,000 to local authorities for stray campaigns in 2025, down from RM180,000 in 2024. Relying on personal tax deductions shifts the upfront cash burden to pet owners and private clinics.

    Guidelines on documentation and registry verification for veterinary clinics and animal shelters will arrive before the 2027 assessment year begins, according to the Inland Revenue Board.

  • HCLTech Partners with Anthropic to Form Agentic AI Business Unit

    HCLTech Partners with Anthropic to Form Agentic AI Business Unit

    India’s HCLTech signed a partnership with Anthropic on Monday to accelerate enterprise adoption of Agentic AI with a focus on safety, cybersecurity and governance.

    Under the agreement, the country’s third-largest IT services firm will establish a dedicated business unit with a centre of excellence to build Agentic AI solutions.

    Teams at HCLTech will develop industry solutions embedding Anthropic products such as Claude, Cowork and Claude Code, ahead of announcing its second quarter results later in the day.

    Embedding Claude Across Enterprise Software

    HCLSoftware will natively integrate Claude across its commercial enterprise product suite. Rather than offering basic API connectivity, engineers are building domain-specific automation. The goal is running routine business operations with minimal manual oversight.

    Target sectors include banking, healthcare, telecommunications, and industrial manufacturing. By baking safety guardrails and governance controls directly into the foundational layer, the partnership aims to bypass compliance hurdles that delay enterprise rollouts across regulated Asian markets.

    The Pivot Away From Headcount-Driven Services

    Indian IT exporters face structural pressure to replace billing models tied to engineering headcount with high-margin software orchestration. Global clients no longer buy generic digital transformation consulting at past volumes. They demand operational automation that delivers measurable productivity cuts within two to three quarters.

    By tethering its software division directly to frontier foundation models, the company seeks recurring software licensing and specialized integration fees. The strategy risks cannibalising traditional maintenance billings if client systems require fewer engineers to operate. Yet letting rival systems integrators capture model orchestration poses a far greater threat to long-term margins.

    Sovereign Infrastructure and Platform Expansion

    Building an enterprise model footprint requires significant capital alongside technical integration. Clients in highly regulated jurisdictions increasingly demand data isolation and strict compliance before handing critical records to third-party model providers.

    Strategic positioning allows the group to address sovereign computing demands while maintaining access to leading global foundation models. The Anthropic alliance covers multinational accounts requiring complex frontier capabilities. Meanwhile, domestic holdings provide local infrastructure for clients bound by strict national data residency mandates.

    Building the Foundation Layer

    This partnership follows a series of structured AI investments by the Bengaluru-based group over the past four months. On October 8, 2026, it unveiled a suite of 20 Industry AI Solutions for corporate implementations across financial services, telecom, and industrial manufacturing.

    Earlier capital allocations laid the groundwork in June 2026, when HCLTech invested $150 million for a 10 percent equity stake in domestic firm Sarvam AI to build out sovereign infrastructure.

    Second-quarter financial earnings arrive later today. Management faces immediate investor scrutiny over client adoption metrics for the Claude software suite and the capital expenditure needed to scale the dedicated AI unit.

  • Japan Drops Reflation Label as Currency Friction with Washington Mounts

    Japan Drops Reflation Label as Currency Friction with Washington Mounts

    Japan abandoned its decade-long reflation doctrine this week. The government pledged fiscal discipline after currency depreciation pushed the yen to 164 against the US dollar.

    Prime Minister Sanae Takaichi told parliament that 2026 begins a period of responsible fiscal management. The statement formally disavowed the easy-money playbook championed by former leader Shinzo Abe.

    During parliamentary debates on Oct 8, Takaichi rejected the reflationary tag and laid out plans to steer domestic capital into higher-productivity sectors. That pivot followed a tense Sept 22 meeting in New York with US President Donald Trump. Trump complained that a cheap yen penalises American exporters. US Treasury Secretary Scott Bessent increased pressure shortly after, explicitly telling Tokyo to halt its reflation policies.

    Exchange Rate Pressures and Import Costs

    Tokyo spent more than 27 trillion yen on direct foreign exchange interventions in 2026 alone to defend the currency. In July, Japanese and American authorities conducted a joint yen-buying operation, their first coordinated market intervention since the 1998 Asian financial crisis. The gains faded quickly. The interest rate gap between Tokyo and global central banks remained wide.

    For retailers and consumer goods distributors across Japan, prolonged currency weakness has inflated wholesale import costs for food, energy and raw inputs. Core consumer inflation in Tokyo reached 2.7 percent year on year in September. That eroded household discretionary spending despite nominal wage growth. Retail margins on imported apparel, processed foods and electronics have tightened, forcing store chains to lift shelf prices.

    Fiscal Realities and Consumption Taxes

    Regional supply chains and consumer brands face higher borrowing costs as the Bank of Japan normalises monetary policy. Japanese conglomerates that benefited from cheap overseas earnings translation now confront shifting trade calculations. Import-reliant domestic operators stand to gain relief if the yen steadies. Still, rising debt-servicing costs present clear balance-sheet risks across the corporate sector.

    Public finances leave little room for error. Japan’s gross government debt sits near 200 percent of gross domestic product. Takaichi told lawmakers not to worry about funding gaps, yet her administration plans a two-year cut to the food consumption tax. That tax cut will erase an estimated 10 trillion yen in annual state revenue.

    Shifting Away From Easy Money

    Central bank officials raised Japan’s benchmark interest rate to 1.25 percent in mid-September, lifting borrowing costs to their highest point in 31 years. Meeting records revealed pushback from government representatives. That resistance triggered fresh yen sales before Takaichi moved to reset her administration’s messaging in parliament.

    Washington has considerable political use, particularly when exchange rates become linked to trade negotiations and the broader bilateral relationship.

    Trade friction between Tokyo and Washington has deep precedent, extending from the 1985 Plaza Accord to bilateral investment pacts where Japanese groups committed 550 billion dollars to American projects. The current dispute directly links currency valuations to bilateral trade balance metrics.

    Targeting High-Tech Industrial Investments

    Takaichi is directing state support toward industrial modernization rather than monetary stimulus. Tokyo intends to channel combined public and private capital into 17 designated sectors. These include artificial intelligence, semiconductor fabrication and commercial shipbuilding.

    The administration plans to finalise its Growth Strategy Implementation Plan before the end of December. The document will establish investment milestones toward a 370 trillion yen capital deployment target by 2040.

  • Vietjet Launches Maiden Hanoi-Prague Flight on Airbus A330

    Vietjet Launches Maiden Hanoi-Prague Flight on Airbus A330

    Vietjet operated its first flight outside Asia-Pacific on Oct. 10, flying an Airbus A330 from Hanoi to Prague via Almaty in Kazakhstan.

    The maiden service to the Czech Republic expands the Vietnamese budget carrier’s network beyond Asia-Pacific, tapping a growing but underserved market.

    Routing through Central Asia

    Passengers received souvenirs on the flight as the airline pressed ahead with European routes despite challenges from Middle East conflict and fuel shortages.

    A technical stop in Almaty gives the airline operational flexibility while airspace closures and regional conflicts complicate direct Asia-Europe flight paths. In Prague, the route taps into one of Europe’s largest Vietnamese diaspora communities. That base helps fill seats alongside outward tourism from Vietnam.

    Fleet deployment and long-haul competition

    Twin-aisle Airbus A330 aircraft are now flying routes that traditional flag carriers often overlook. Vietnam Airlines and Singapore Airlines focus on primary hubs such as London, Paris and Frankfurt. Vietjet is targeting secondary European gateways where budget competition is scarce.

    Long-haul discount flights run on thin margins. Fuel volatility and landing fees in Central Asia lift per-seat costs well above regional point-to-point routes. That dynamic puts pressure on seat occupancy and ancillary sales across both legs.

    In-flight upgrades and regional units

    Beyond new routes, the airline is overhauling onboard products across its fleet. A recent deal with Starlink will bring free in-flight Wi-Fi to passengers. The upgrade aligns cabin services with long-haul international standards.

    Regional affiliate Vietjet Thailand is separately working to double revenue by 2028 through fleet additions and network expansion. Meanwhile, the European expansion tests whether a Southeast Asian low-cost model can turn a profit on intercontinental segments without full-service feeder networks.

    Next European destinations

    Planners are evaluating more European destinations to link with Hanoi and Ho Chi Minh City as additional widebodies arrive. Prague’s commercial performance over its first winter season will dictate how fast the carrier commits planes to other European cities.

  • Mekong Tourism Operators Cut Wet-Season Rates by up to 50 per Cent

    Mekong Tourism Operators Cut Wet-Season Rates by up to 50 per Cent

    Mekong region tourism operators and state agencies are overhauling wet-season packages, discounting travel prices by up to 50 per cent to eliminate the traditional monsoon revenue slump.

    Hotels and cruise lines across Vietnam, Cambodia and Myanmar have sharply reduced tariffs between May and October to capture budget-focused millennial and Gen Z travellers, according to Hanoi Tourism Association Vice Chairman Nguyen Tien Dat.

    In Vietnam, boutique accommodation in Hoi An that commands US$90 a night in February drops to US$35 in October. Cruise operators in Halong Bay have rolled out 40 per cent price cuts during the same window. The pricing strategy aims to smooth out hospitality revenue cycles by filling inventory that traditionally sat empty through months of heavy rainfall.

    Discounting to Fill Rooms

    Price drops of 30 to 50 per cent across transport, lodging and guided tours are altering cash-flow dynamics for independent operators. Lower room yields reduce unit margins, yet maintaining baseline occupancy covers fixed property overheads and keeps service staff employed through the low season.

    In Myanmar, domestic demand has absorbed capacity in secondary destinations. Hotels in Hpa-an, the capital of Kayin State, reached full occupancy during the monsoon as regional travellers booked nature and landscape excursions.

    Restructuring Urban and Cultural Products

    Destination managers are substituting weather-exposed outdoor activities with indoor, urban and heritage experiences. Coastal hubs that rely on swimming and beach recreation during dry months are pivoting to culinary tours, craft villages, museum trails and wellness centers.

    Quang Ninh province in northern Vietnam is marketing evening entertainment and temple sites alongside mountain circuits. Further south, Da Nang is redirecting visitors away from beaches toward integrated resorts and city entertainment venues when coastal conditions deteriorate.

    Hanoi Tourism Association Vice Chairman Nguyen Tien Dat outlined the shift in product design for rainy periods. “A rainy day is an opportunity for museum visits, heritage tours, culinary experiences, wellness, art or craft villages, while a beach itinerary can be replaced with a city tour, nature excursion, and community-based cultural activities,” he said.

    Community Spending and Operational Margins

    Shifting visitor traffic into rural communities spreads consumer spending directly to local suppliers. Guesthouse operators, craft producers, traditional performers, and transport rental vendors secure steady cash flow rather than enduring half-year income droughts.

    For retail and hospitality investors, year-round operating models lower customer acquisition costs by reducing the need for aggressive marketing campaigns ahead of peak periods. The commercial risk rests on weather volatility, as sudden flooding or extended transport disruptions can trigger last-minute cancellations that promotional pricing cannot offset.

    Greener Models and Target Travelers

    Regional authorities are coupling the off-season push with sustainability mandates aimed at younger demographic cohorts. Tourism accounts for 7.3 per cent of global greenhouse gas emissions, according to data from the World Travel and Tourism Council, creating pressure on regional governments to balance volume growth with lower-impact travel models.

    Cambodia launched its Coastal Green Season Tourism Event in Kampot province in early October, setting out state plans to market rainforest and river attractions during peak precipitation months.

    Regional tourism boards across Hanoi, Phnom Penh and Yangon are preparing their next round of joint promotional campaigns ahead of the mid-2027 monsoon booking cycle.