Author: Mei Ling Tan

  • Krispy Kreme Japan Launches Limited Fox Doughnuts Across Four Outlets

    Krispy Kreme Japan Launches Limited Fox Doughnuts Across Four Outlets

    Krispy Kreme launched a limited-edition fox doughnut across four store locations in Japan on May 25, testing ultra-concentrated product scarcity.

    The restricted release confines the themed pastry to a tiny fraction of the chain’s national store footprint. Limiting distribution creates immediate localized foot traffic while managing production runs for intricate, hand-finished menu items.

    Targeted Store Allocations

    Restricting specialty bakery products to specific stores allows chain operators to test niche product appeal without burdening nationwide supply chains. In Japan, quick-service dessert operators frequently use regional or store-exclusive runs to drive localized foot traffic and generate organic social engagement without standard advertising spend.

    For retail landlords and station-adjacent retail hubs, hyper-local limited releases direct customer volume directly to specific commercial corridors. The trade-off sits squarely in execution: tight allocations risk customer frustration if inventory sells out too early in the trading day, shifting footfall away from neighboring tenants.

    The Hyper-Local Fast Food Playbook

    Rival confectionery chains across East Asia rely on similar micro-drops to maintain menu novelty against intense convenience store competition. Japanese convenience chains routinely turn over bakery shelves weekly, forcing standalone doughnut operators to create distinct, photogenic items that justify a dedicated store visit.

    Krispy Kreme Japan previously restructured its operations by trimming oversized standalone units and pivoting toward high-efficiency transit kiosks and compact shopping center locations. Concentrating short-run specialty items into selected stores tests how well these distinct formats capture impulsive commuter spending.

    The four selected locations will carry the fox doughnut for a limited period, with store-level sales volumes determining whether the concept rolls into wider regional distribution.

  • FamilyMart Opens Famima Park Azabudai in Tokyo for 45Th Anniversary

    FamilyMart Opens Famima Park Azabudai in Tokyo for 45Th Anniversary

    FamilyMart launched its new concept store, Famima Park Azabudai, in Tokyo last Friday, drawing two-hour queues and purchase limits on exclusive merchandise. The opening marks a fresh design departure for the convenience chain, which operates 16,400 shops across Japan.

    Devised for FamilyMart’s 45th birthday on the fringes of the Azabudai Hills development, the project brings together creative director Nigo, Masamichi Katayama of interior studio Wonderwall, and fashion designer Hiromichi Ochiai.

    Apparel and layout overhaul

    The store layout alters standard convenience floorplans by integrating clothing fitting rooms, dedicated retail staff for garments, and a takeaway window branded Famima Stand. Outside seating borders the pick-up hatch, where staff serve hot food lines including Fami-Chiki boneless fried chicken directly to street pedestrian traffic.

    Merchandise runs from basic consumables to limited-edition selvedge denim jackets and jeans, stocked alongside Ochiai’s Convenience Wear line of packaged socks and basic garments. Staff wear cotton-look striped uniforms instead of traditional synthetic workwear. Structural additions include a planted rooftop garden with an elevated view of a rooftop brand emblem visible to surrounding commercial towers.

    Pressure on traditional margins

    Japan’s convenience store sector comprises roughly 56,000 stores nationwide, leaving operators with limited room for physical network expansion. Saturation in major urban centers forces chains to lift basket sizes rather than rely on opening new front doors. Seven-Eleven, Lawson and FamilyMart face structural margin pressure from rising store-level wage costs and higher utility expenses, making commodity food and beverage sales alone insufficient to maintain franchise returns.

    Pushing higher-margin lifestyle categories into small formats gives FamilyMart an edge in customer acquisition among younger urban shoppers. Apparel and branded lifestyle accessories carry significantly higher gross margins than packaged beverages and chilled bento meals. The risk sits in franchise economics: regular store operators operate inside tight footprints and cannot easily afford dedicated fitting rooms or inventory risk on slow-moving seasonal garments.

    The Convenience Wear trajectory

    The Azabudai launch builds on a multi-year effort to expand non-food lines that began with the nationwide rollout of Convenience Wear in 2021. That basics range has sold more than 30 million pairs of socks, establishing that convenience shoppers will purchase wardrobe staples from refrigerated grocery stores if the price and material quality align. FamilyMart recruited actor Tadanobu Asano as brand ambassador to widen the commercial appeal of its apparel range.

    Executive leadership views format redesign as essential to differentiating the business in mature consumer sectors. Tatsuo Odani, representative director and president of FamilyMart, pointed to the need for long-term structural changes across the company’s operating model.

    “To achieve sustainable growth in the future, transformation and evolution are essential,” he said.

    Store elements head to franchise fleet

    FamilyMart has not committed to rolling out full-scale standalone concept flagships in secondary metropolitan districts. Management confirmed instead that selected interior fixtures, retail displays and merchandise categories trialled at the Azabudai store will be integrated into the broader Japanese store network over coming financial quarters.

    RetailNews Asia will track whether conversion rates and merchandise sales density at the Azabudai flagship prompt FamilyMart to formalise dedicated non-food retail sections across its standard franchise portfolio.

  • Piramal Pharma Opens Microbiology Lab in 85 Million Dollar US Expansion

    Piramal Pharma Opens Microbiology Lab in 85 Million Dollar US Expansion

    Piramal Pharma Solutions has opened a microbiology laboratory at its sterile injectable plant in Lexington, Kentucky. The project advances an 85 million dollar expansion.

    The new space triples testing floor area. It targets a 50 per cent cut in product release turnaround times.

    Regulators cleared routine Good Manufacturing Practice work on September 11, 2026. Conditional approval for the adjoining sterility suite followed soon after. The lab unit forms the first operational phase of the multi-year capital program.

    Boosting Sterility and Cleanroom Capacity

    Engineers reconfigured the Lexington site to handle higher volumes of sterile drug products for clinical and commercial use. The upgrade adds three biosafety cabinets for concurrent testing. It also consolidates all incubation equipment into a single footprint.

    A dedicated Grade C cleanroom suite houses a Grade A sterility testing isolator. That setup replaces a non-classified zone. It doubles testing throughput by running open and closed filtration on multiple batches at once. Built-in sample pass-throughs connect manufacturing suites directly to analytical benches.

    Cutting Release Bottlenecks for Injectables

    Global sterile injectable manufacturing faces capacity crunches, particularly for antibody-drug conjugates, peptides and high-potency small molecules. Bringing microbiology and sterility testing in-house cuts sample transport delays. It also lowers contamination risks.

    Faster batch clearance gives the company an edge over Asian contract development and manufacturing rivals tied strictly to domestic facilities. Shorter release cycles also help pharmaceutical clients. They trim inventory holding costs and speed market access.

    Indian CDMOs Expanding Global Footprints

    Indian contract manufacturers continue to buy and upgrade assets in North America and Europe to stay close to clinical sponsors. Piramal Pharma Limited trades in Mumbai on both the BSE and the National Stock Exchange of India. It runs 17 development and manufacturing sites across India, North America and Europe, alongside hospital generics and consumer healthcare units.

    Through its subsidiary Yapan Bio, the parent company entered complex biologics manufacturing while keeping fill-finish work in Western jurisdictions. Cleanroom and testing capacity in the United States protects contract volume from overseas trade barriers and inspection backlogs.

    Timeline for Full Commercial Operations

    Nathan Richardson, vice president and site head at the Lexington facility, said: “By enhancing sterility testing and microbiological quality capabilities, we are further strengthening our ability to support clients with high quality, reliable, and responsive services throughout the product life cycle.”

    Crews are now installing commercial-scale fill and finish equipment across the remaining space. Piramal expects the full Lexington plant to reach commercial readiness in late 2027.

  • Superfan Spending Boosts Japan Annual Retail Turnover by 2%

    Superfan Spending Boosts Japan Annual Retail Turnover by 2%

    Superfan spending across Japan lifted the country’s annual retail turnover by 2 per cent, according to figures highlighted by Rick Kelsey on BBC Business Daily on 12 November 2025.

    Economists credit the surge to oshikatsu, the dedicated fan culture of spending money and time to support idols through merchandise, concerts, and streaming, with helping pull retail sales out of a long slump.

    How Superfans Drive Everyday Retail

    The practice stems from the Japanese verb osu, meaning to endorse or support, which evolved into a noun during the 2000s across domestic idol and anime communities. Today, the behaviour extends far beyond live entertainment venues into everyday high-street retail, convenience stores and food service.

    Consumers regularly purchase acrylic character stands, plush toys, key chains and branded photo cards designed to be carried and photographed in daily settings. Food and beverage operators capture direct spend through collaboration menus, where cafes offer themed items linked to character birthdays, anniversaries and content releases.

    Retailers also capture revenue through dedicated colour-coded apparel, accessories and travel packages tied to anime pilgrimages, where fans visit real-world locations featured in specific series.

    What the Shift Means for Store Operators

    For department stores, convenience chains and shopping centre landlords across Japan, the commercial impact alters basic merchandising strategy. Conventional retail relies on broad demographic appeal and seasonal discounting, but fan-driven retail operates on high price tolerance and non-negotiable loyalty to specific intellectual property.

    Operators that secure exclusive licensing rights and limited-run character merchandise generate immediate foot traffic without heavy promotional markdowns. The risk sits entirely in inventory timing and intellectual property selection, because secondary-market saturation or sudden shifts in fan interest leave unpartnered stock stranded on store shelves.

    Supply Chains Adapt to Collectibles Demand

    Capsule toy machines and blind-box collectibles have expanded floor space in major transit hubs and suburban malls to monetise this demand. Manufacturers now design goods specifically for social sharing, turning consumer photography into free marketing that drives secondary store visits.

    Domestic retailers increasingly structure product launches around character calendars rather than traditional shopping holidays. This predictable cadence gives suppliers steady manufacturing runs for small-format plastics, novelty textiles and packaged food collaborations throughout the year.

    From Niche Subculture to Economic Driver

    A 2024 academic study tracking linguistic use documented how the term transitioned from subculture slang in the early 2000s into a mainstream commercial category embraced by corporate marketing desks. What began as fan-club subscriptions and physical compact disc sales now spans digital streaming support, interactive virtual creators and cross-category retail licensing.

    Department store groups in Tokyo and Osaka that previously cut floor space for youth apparel have rebuilt those areas into rotating pop-up zones for licensed goods. The strategy mirrors broader structural changes across Asian consumer markets, where experiential and identity-driven purchases consistently outpace generic consumer staples.

    The Next Test for Fan Consumption

    Retail analysts are watching upcoming quarterly sales prints from major Japanese department store operators and convenience chains to determine whether the 2 per cent turnover lift holds against broader inflationary pressures on household budgets. Corporate earnings releases scheduled across the next reporting cycle will show whether licensed collaboration margins continue to outpace traditional retail lines.

  • L’Oréal Unveils 510-Square-Meter Airport Beauty Show at TFWA 2025

    L’Oréal Unveils 510-Square-Meter Airport Beauty Show at TFWA 2025

    L’Oréal Travel Retail Asia Pacific has rolled out retail activations across all four terminals at Singapore Changi Airport in May 2025. The push targets passenger dwell time across its portfolio of 22 luxury beauty brands.

    The campaign includes a 510-square-meter show at the TFWA 2025 exhibition. It tests interactive retail formats for international transit hubs.

    Lounges Target Transit Passengers by Trip Stage

    Organizers divided the exhibition space into three operational zones built around flight schedules and destinations. The first zone features climate-customized misting pods. Beauty advisors use them to pair skincare products with the weather at a traveler’s destination, from tropical humidity to high-altitude cold.

    A second zone delivers 10-minute Lancôme longevity skin repair treatments using cryo-sculpting tools, set beside displays marking the brand’s 90th anniversary. A third area houses destination-themed fragrance bars, silent disco soundscapes, Kérastase scalp analysis, and L’Oréal Men Expert grooming stations.

    More than 90 percent of the structure’s build materials were recycled, upcycled, or 3D-printed.

    Changi Activations Extend to All Terminals and Jewel

    Inside the airport, L’Oréal partnered with The Shilla Duty Free Singapore and Changi Airport Group to place pop-ups directly along passenger pathways. The YSL Beauty Light Club ran across all four terminals and Jewel Changi Airport from April 18 to May 25, 2025.

    That installation used artificial intelligence to match makeup looks to individual travelers. Orders routed directly to iShopChangi, the airport’s digital pre-order platform. The space also featured fragrance discovery booths and cocktail bars.

    Over in Terminal 3 transit, active medical skincare brand SkinCeuticals operated its first worldwide travel retail outpost from April 27 to June 4, 2025. Beauticians from Calvin Chan Aesthetics delivered non-invasive HydraFacial treatments in under 30 minutes, alongside sales of an exclusive Collagen-III Amplifier serum through The Shilla Duty Free.

    Pre-Flight Data Partnerships Link Ride-Hailing to Terminal Sales

    L’Oréal organized the campaign under a five-party model coordinating brand owners, airport authorities, duty-free retailers, airlines, and digital platforms. The network links Changi Airport Group and The Shilla Duty Free with Singapore Airlines KrisFlyer, Grab, Meta, and United Overseas Bank.

    Targeting begins before passengers reach the terminal. Grab users receive promotional offers en route to Changi. Meanwhile, KrisFlyer and Meta channels distribute pre-departure product notices matched to flight itineraries.

    At L’Oréal Travel Retail, we believe in creating beauty experiences that resonate emotionally, culturally, and memorably. The L’Oréal Airport Beauty “Shopper-tainment of the Future” is our vision for what travel beauty can become: immersive, intelligent and unforgettable. As global travel accelerates and the appetite for beauty keeps getting stronger, we are proud to lead the reinvention of the category with world-class partners and future-facing innovations.

    Shifting Focus from Traditional Shelves to Experiential Service

    Asian duty-free operations face shifting economics as domestic e-commerce undercuts standard shelf pricing. Operators now focus on converting airport dwell times, which average up to two hours per passenger, into high-margin service sales rather than relying on volume discounts.

    Allocating floor space to clinical devices, grooming chairs, and cocktail bars represents a calculated trade-off for concessionaires like The Shilla Duty Free. These installations reduce retail stock density per square meter. Still, they capture higher transaction values from experience-seeking travelers who research beauty purchases online before flying.

    Global passenger traffic reached 3.7 billion travelers in 2024, returning volume to pre-pandemic levels across major Asian aviation hubs. That recovery prompted beauty groups to direct capital into experiential flagships across Singapore, Hong Kong, and Incheon.

    Regional attention now turns to how concessionaires adapt these high-service formats to secondary airports across Southeast Asia, where terminal space is tighter and passenger spending profiles differ from Changi.

  • Li Auto Delays European Debut to First Quarter 2027 with Norway and Netherlands Rollout

    Li Auto Delays European Debut to First Quarter 2027 with Norway and Netherlands Rollout

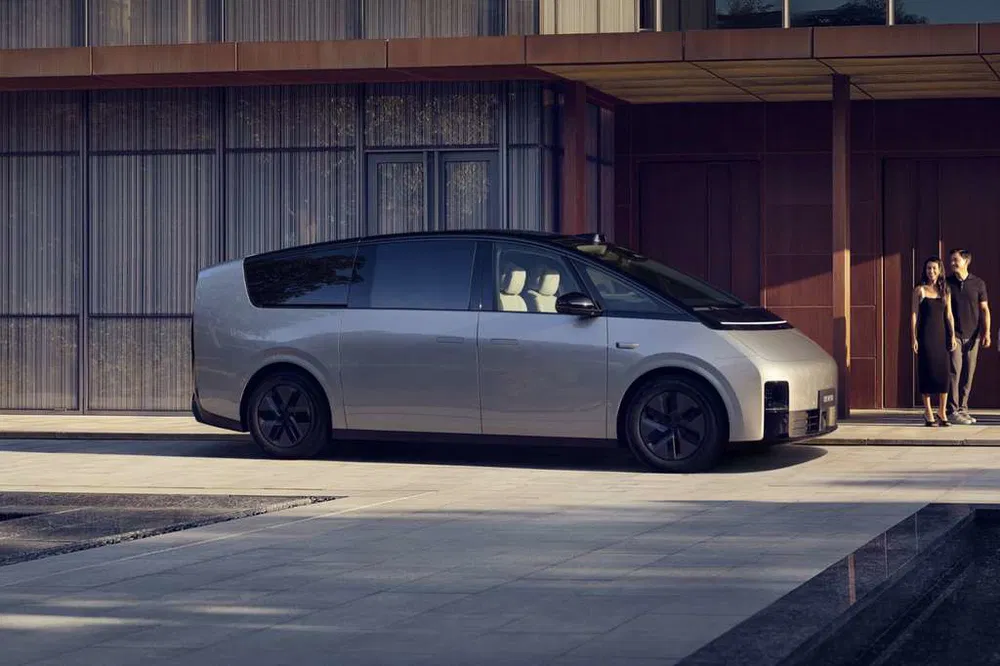
    Li Auto pushed its European market debut to the first quarter of 2027 on Monday. The company revealed the battery-electric Li 6 SUV in Paris ahead of initial sales in Norway and the Netherlands.

    That timeline delays European showroom arrivals from late 2026. Management previously gave a fourth-quarter 2026 target during an August earnings call.

    Benjamin Baum, senior exterior design director at Li Auto, presented the vehicle on October 12 during the opening day of the Paris Motor Show. Known as the i6 in China, the export model carries the shorter Li 6 badge for European buyers. Deliveries will focus first on Norway and the Netherlands before expanding across other European markets. Localized versions of the brand’s extended-range hybrid models will arrive at an unannounced date.

    European Target Selection and Vehicle Architecture

    Norway and the Netherlands serve as proving grounds for Chinese electric carmakers entering Europe. Both countries offer dense charging networks and high EV adoption rates. Li Auto chose pure electric drivetrains for Western Europe while prioritizing extended-range hybrids in Central Asia and the Middle East to match local charging infrastructure. In July, it introduced the L9 extended-range SUV in Kazakhstan and Uzbekistan. That rollout drew technical support from an engineering center established in Munich in January 2025.

    Engineers built the European specification to meet Euro NCAP five-star crash test standards. Formal safety assessments will follow once local market deliveries begin. Under the floor sits a 96 kilowatt-hour fast-charging battery pack. It delivers an operating range of up to 780 kilometers under China Light-Duty Test Cycle standards. Li Auto designs the battery cells internally and outsources cell fabrication to suppliers CALB and Sunwoda, though it builds the completed packs in-house.

    Domestic Pressure Drives Overseas Export Push

    Selling abroad has become a commercial necessity for Chinese carmakers facing brutal price competition and slowing domestic volume growth. Li Auto delivered 31,817 vehicles in September. That was a 6.29 per cent drop from the same month last year and a 15.56 per cent slide from August. Total deliveries across the first nine months of the year reached 293,436 units, down 1.25 per cent compared to the identical period in 2025.

    Rivals like Nio and Xpeng have already built retail distribution channels across Northern Europe. They found that building brand recognition is expensive and sales accumulate slowly. Li Auto must now set up physical showrooms, service centers, and software localization across multiple languages while fighting established European premium marques. CEO Li Xiang stated on Weibo that the company will adapt to local conditions and enter when ready. He pointed to compact vehicle dimensions suited to European urban street layouts.

    Model Refresh Precedes Export Program

    In China, the i6 remains Li Auto’s primary volume driver. Cumulative domestic sales have exceeded 190,000 units since its debut. In August alone, the vehicle accounted for 16,979 deliveries, representing roughly 45 per cent of the manufacturer’s total monthly output. Order books for the initial model generation closed on September 11 to clear assembly lines for an updated 2026 edition.

    Dealerships across China began displaying static models of the refreshed 2026 i6 at 485 locations on October 11. The updated variant adds adaptive beam matrix headlights and twin 150-degree reclining zero-gravity front seats. It also includes a 29-inch panoramic front display, Li Auto’s proprietary Mach M100 driving assistance processor, and Qualcomm Snapdragon silicon.

    Customer test drives and official retail sales for the 2026 i6 begin across China on October 28. Initial customer handovers follow in early November ahead of planned European export shipments.

  • SurfStitch Cuts Annual IT Costs to $400,000 in Marketplace Overhaul

    SurfStitch Cuts Annual IT Costs to $400,000 in Marketplace Overhaul

    In October 2026, ten months into a restructuring led by Olvera Advisors, Australian online retailer SurfStitch has rebuilt its operating model as a curated marketplace, cutting annual fixed IT costs from close to $1.2 million to around $400,000.

    The business now hosts roughly 75 predominantly domestic labels on a variable-cost architecture powered by Shopify and HubSpot, ditching wholesale inventory risk to arrest years of margin erosion.

    Rewriting the commercial terms for brands

    Under the restructured model, participating labels manage their own fulfillment and pricing rules while agreeing to keep core product lines at full price outside scheduled promotional windows. The platform prohibits wholesale inventory dumping, preventing suppliers from using the digital storefront as a discount clearance outlet. Brands must match their own direct-to-consumer digital pricing rather than undercutting the channel.

    Restructuring lead Damien Hodgkinson has limited total seller onboarding to protect vendor visibility. Rather than competing against thousands of merchants on catch-all apparel portals, sellers on the platform retain category focus across surf, outdoor, street and coastal lifestyle lines.

    Building utility to drive repeat visits

    Traffic generation has shifted from discount email blasts to editorial and activity hubs designed to capture search intent. The storefront now operates three recurring services: a daily surf report tracking swell and tide across 100 Australian beaches, a dedicated trail guide for hikers, and a coastal live music directory.

    These utility features funnel organic visitors directly into targeted product categories such as apparel, technical footwear, surfboards, water bottles and electric bikes. Customer browsing history across the guides feeds behavioral profiles, replacing broad discounting campaigns with targeted gear suggestions.

    Shifting wholesale pressure across Asia-Pacific e-commerce

    Pure-play apparel retail across the Asia-Pacific region is colliding with the limits of discount-led customer acquisition. Regional aggregators that built scale on debt and perpetual clearance sales have faced severe margin contraction as performance marketing costs climbed and global labels pulled back inventory allocations. By offloading inventory risk directly to brand partners, marketplace operators shift working capital burdens back upstream.

    The critical vulnerability sits in customer retention. Retraining a legacy database conditioned on clearance coupons to pay full retail price routinely triggers high churn rates. If converted shoppers bypass the marketplace to transact directly on brand websites once discovery happens, take rates will not cover customer acquisition overhead.

    From insolvency proceedings to solvent platform

    Best Markets Group acquired SurfStitch from Alquemie Group in March 2025 before a dispute with a landlord and petitioning creditor Nike forced the business into voluntary administration. Turnaround firm Olvera Advisors took control of the asset, securing creditor approval for a Deed of Company Arrangement before overhauling the underlying software stack and vendor contracts.

    Management plans to expand the product catalogue into winter snowsports next season, with overall transaction volume on the restructured platform serving as the benchmark for sustained solvency.

  • Reliance Consumer and DailyObjects Lead Rs 1,343 Crore Indian Retail Funding

    Reliance Consumer and DailyObjects Lead Rs 1,343 Crore Indian Retail Funding

    Reliance Consumer Products committed over Rs 600 crore to build an integrated food park in West Bengal this week, as Indian retail and consumer investments reached Rs 1,343 crore across sectors.

    Lifestyle tech brand DailyObjects secured Rs 332 crore in Series C capital at a valuation of Rs 1,050 crore. The funds will back its physical expansion across India and entry into overseas markets.

    Funding spanned fast-moving consumer goods, home appliances, kitchen fittings, health wellness brands, gourmet foods, and lab-grown jewellery. The split between manufacturing plants and direct-to-consumer expansion shows investors backing factory capacity alongside retail store rollouts.

    Manufacturing push in West Bengal

    In West Bengal, Reliance Consumer Products secured 30 acres in Haringhata, Nadia district, for its new food and beverage hub. The Rs 600 crore project is the first manufacturing asset owned directly by the Mukesh Ambani-led FMCG unit in eastern India. It manufactures and distributes packaged goods, including revived soda label Campa, across regional markets.

    Direct ownership of regional plants cuts freight costs and feeds stock directly into general trade and quick-commerce dark stores. For suppliers and logistics vendors in eastern India, the Haringhata site concentrates processing, packaging, and bottling in a single corridor rather than splitting work across contract packers.

    Since launching its consumer goods unit, Reliance has acquired legacy regional brands and expanded nationwide distribution. Dedicated production in West Bengal creates a regional base to supply eastern and northeastern retail networks without paying interstate freight fees.

    Tech accessories and store expansion

    DailyObjects raised Rs 332 crore through primary and secondary share sales led by Xponentia Capital Partners, Anicut Capital, and Axiom Asia Private Capital. The accessories brand operates roughly 350 touchpoints across India, including exclusive brand outlets and counters inside Apple Premium Reseller stores.

    Management will use the capital to open 150 standalone stores over five years, step up product design, and enter overseas retail channels. The company sells tech accessories, bags, and desk gear online and through third-party brick-and-mortar networks.

    Domestic accessories brands are shifting capital into company-owned stores to lift order values and secure mall retail space. High-street landlords face steady demand from labels seeking customer engagement outside multi-brand discount portals.

    Kitchen appliances and bathroom fittings

    Smart kitchen brand Beyond Appliances raised Rs 110 crore in a Series B round led by Fireside Ventures, with participation from Dharana Capital. It plans to build a new factory, introduce two appliance lines, and expand distribution from four to 14 cities over the next three years.

    Fittings maker Lorazzo completed a Rs 15 crore round led by Sauce, with follow-on funding from Sprout Venture Partners and backing from Panthera Peak and Alteria Capital. Lorazzo will allocate the proceeds to expand product lines, add staff, and broaden distribution across state wholesale and retail markets.

    Capital also flowed into wellness and functional foods. Health and wellness investor NDude Labs committed roughly Rs 28 crore ($3 million) in Series A funding to US-based brand SuperMush, which sells through Amazon, direct channels, and over 2,000 US stores. In India, actor Varun Dhawan bought an undisclosed stake in biofortified staples brand Better Nutrition and signed on as brand ambassador to support sales on quick-commerce apps and direct-to-consumer websites.

    Food brands and lab-grown jewellery

    Smaller rounds closed across food and beverage to build regional retail footprints. Gourmet pizza operator The Dough Therapy secured Rs 5.25 crore in seed funding at a Rs 35 crore valuation in a round led by Michigan Capital Advisors, formerly known as Melwani Finance, with participation from Equiglobe Investment. Zero-sugar mixer label Sober & Co raised Rs 75 lakh from New Ground Collective investors Sunaina Bhattacharya and Anuj Dhariwal.

    In jewellery, lab-grown diamond label Zinara raised Rs 3.61 crore in pre-seed funding led by Inflection Point Ventures, alongside Nine Jewellery, actor Nikita Dutta, and angel investors. Zinara plans to put the capital into supply chain development, marketing, and hiring.

    Beyond Appliances will focus next on site acquisition and equipment orders for its planned manufacturing facility as it prepares to enter 10 additional cities.
  • Investors Bet on Japan and Australia Rental Housing as Rates Rise

    Investors Bet on Japan and Australia Rental Housing as Rates Rise

    Higher mortgage rates and elevated home prices across Tokyo and Sydney are pushing buyers out of the sales market. Institutional capital is flowing into rental housing instead.

    Australian home values have dropped 5.2 per cent nationally from their March 2026 peak. In Japan, buyers are opting for compact rental units to avoid borrowing costs.

    That split reflects the sharpest monetary tightening cycle across major Asia-Pacific economies in over a decade. Tokyo professionals are turning toward compact apartments with shared amenities, choosing rent over long-term debt as yields shift. Across Australia, the Reserve Bank raised its cash rate from 3.6 per cent to 4.6 per cent over four hikes in February, March, May and September 2026. Borrowing costs now sit at their highest point since 2011.

    Squeezed Borrowers and Dropping Valuations

    Price drops have hit Australia’s major metropolitan centers hardest over the past six months. Sydney values fell 8.6 per cent from their February high. Melbourne prices dropped 7.2 per cent since November.

    Top-tier properties are absorbing the brunt of the downturn. Cotality data shows values in the top quartile across Sydney and Melbourne dropped more than 10 per cent from peak valuations. Seven of Australia’s eight capital cities are recording price declines. Darwin is the lone market where values still rise.

    Household debt has amplified the downturn, standing at roughly 178 per cent of annual disposable income. Most Australian borrowers hold variable-rate loans. That transmits interest rate hikes directly into monthly budgets.

    Tax Overhauls Shake Investor Demand

    Policy changes in Canberra are speeding up the shift away from speculative residential buying. From July 2027, the Australian government will restrict negative gearing deductions strictly to newly constructed dwellings. Buyers will no longer write off rental losses on existing homes against taxable income.

    Federal authorities are also eliminating the 50 per cent capital gains tax discount on investment properties. An indexation system will replace the flat deduction, adjusting initial purchase prices for inflation before calculating taxable profit on a sale.

    Lending data already reflects cooling sentiment among private landlords. Australian Bureau of Statistics figures show lending commitments to property investors fell 8.6 per cent between March and June 2026. That pullback hits a segment of more than 2.2 million individual property owners nationwide.

    Diverging Capital Flows Across the Region

    In Tokyo, institutional operators are scaling up build-to-rent formats and small-footprint units for single-person households in central locations. Shared community spaces help operators preserve net effective rents. Individual unit costs also remain accessible for young tenants.

    Rental housing offers regional real estate funds stable cash generation while residential sales volumes drop. Westpac Banking forecasts Australian home prices will fall 7.3 per cent from peak to trough as tighter credit works through the banking system.

    Developer balance sheets will face pressure across both markets through the rest of the year. Attention now turns to whether the Reserve Bank of Australia holds rates steady at 4.6 per cent, and how quickly private investors recalibrate their portfolios before the July 2027 tax changes take effect.

  • Eztia Expands 10-Degree Cooling Fabric Trials Across Japan

    Eztia Expands 10-Degree Cooling Fabric Trials Across Japan

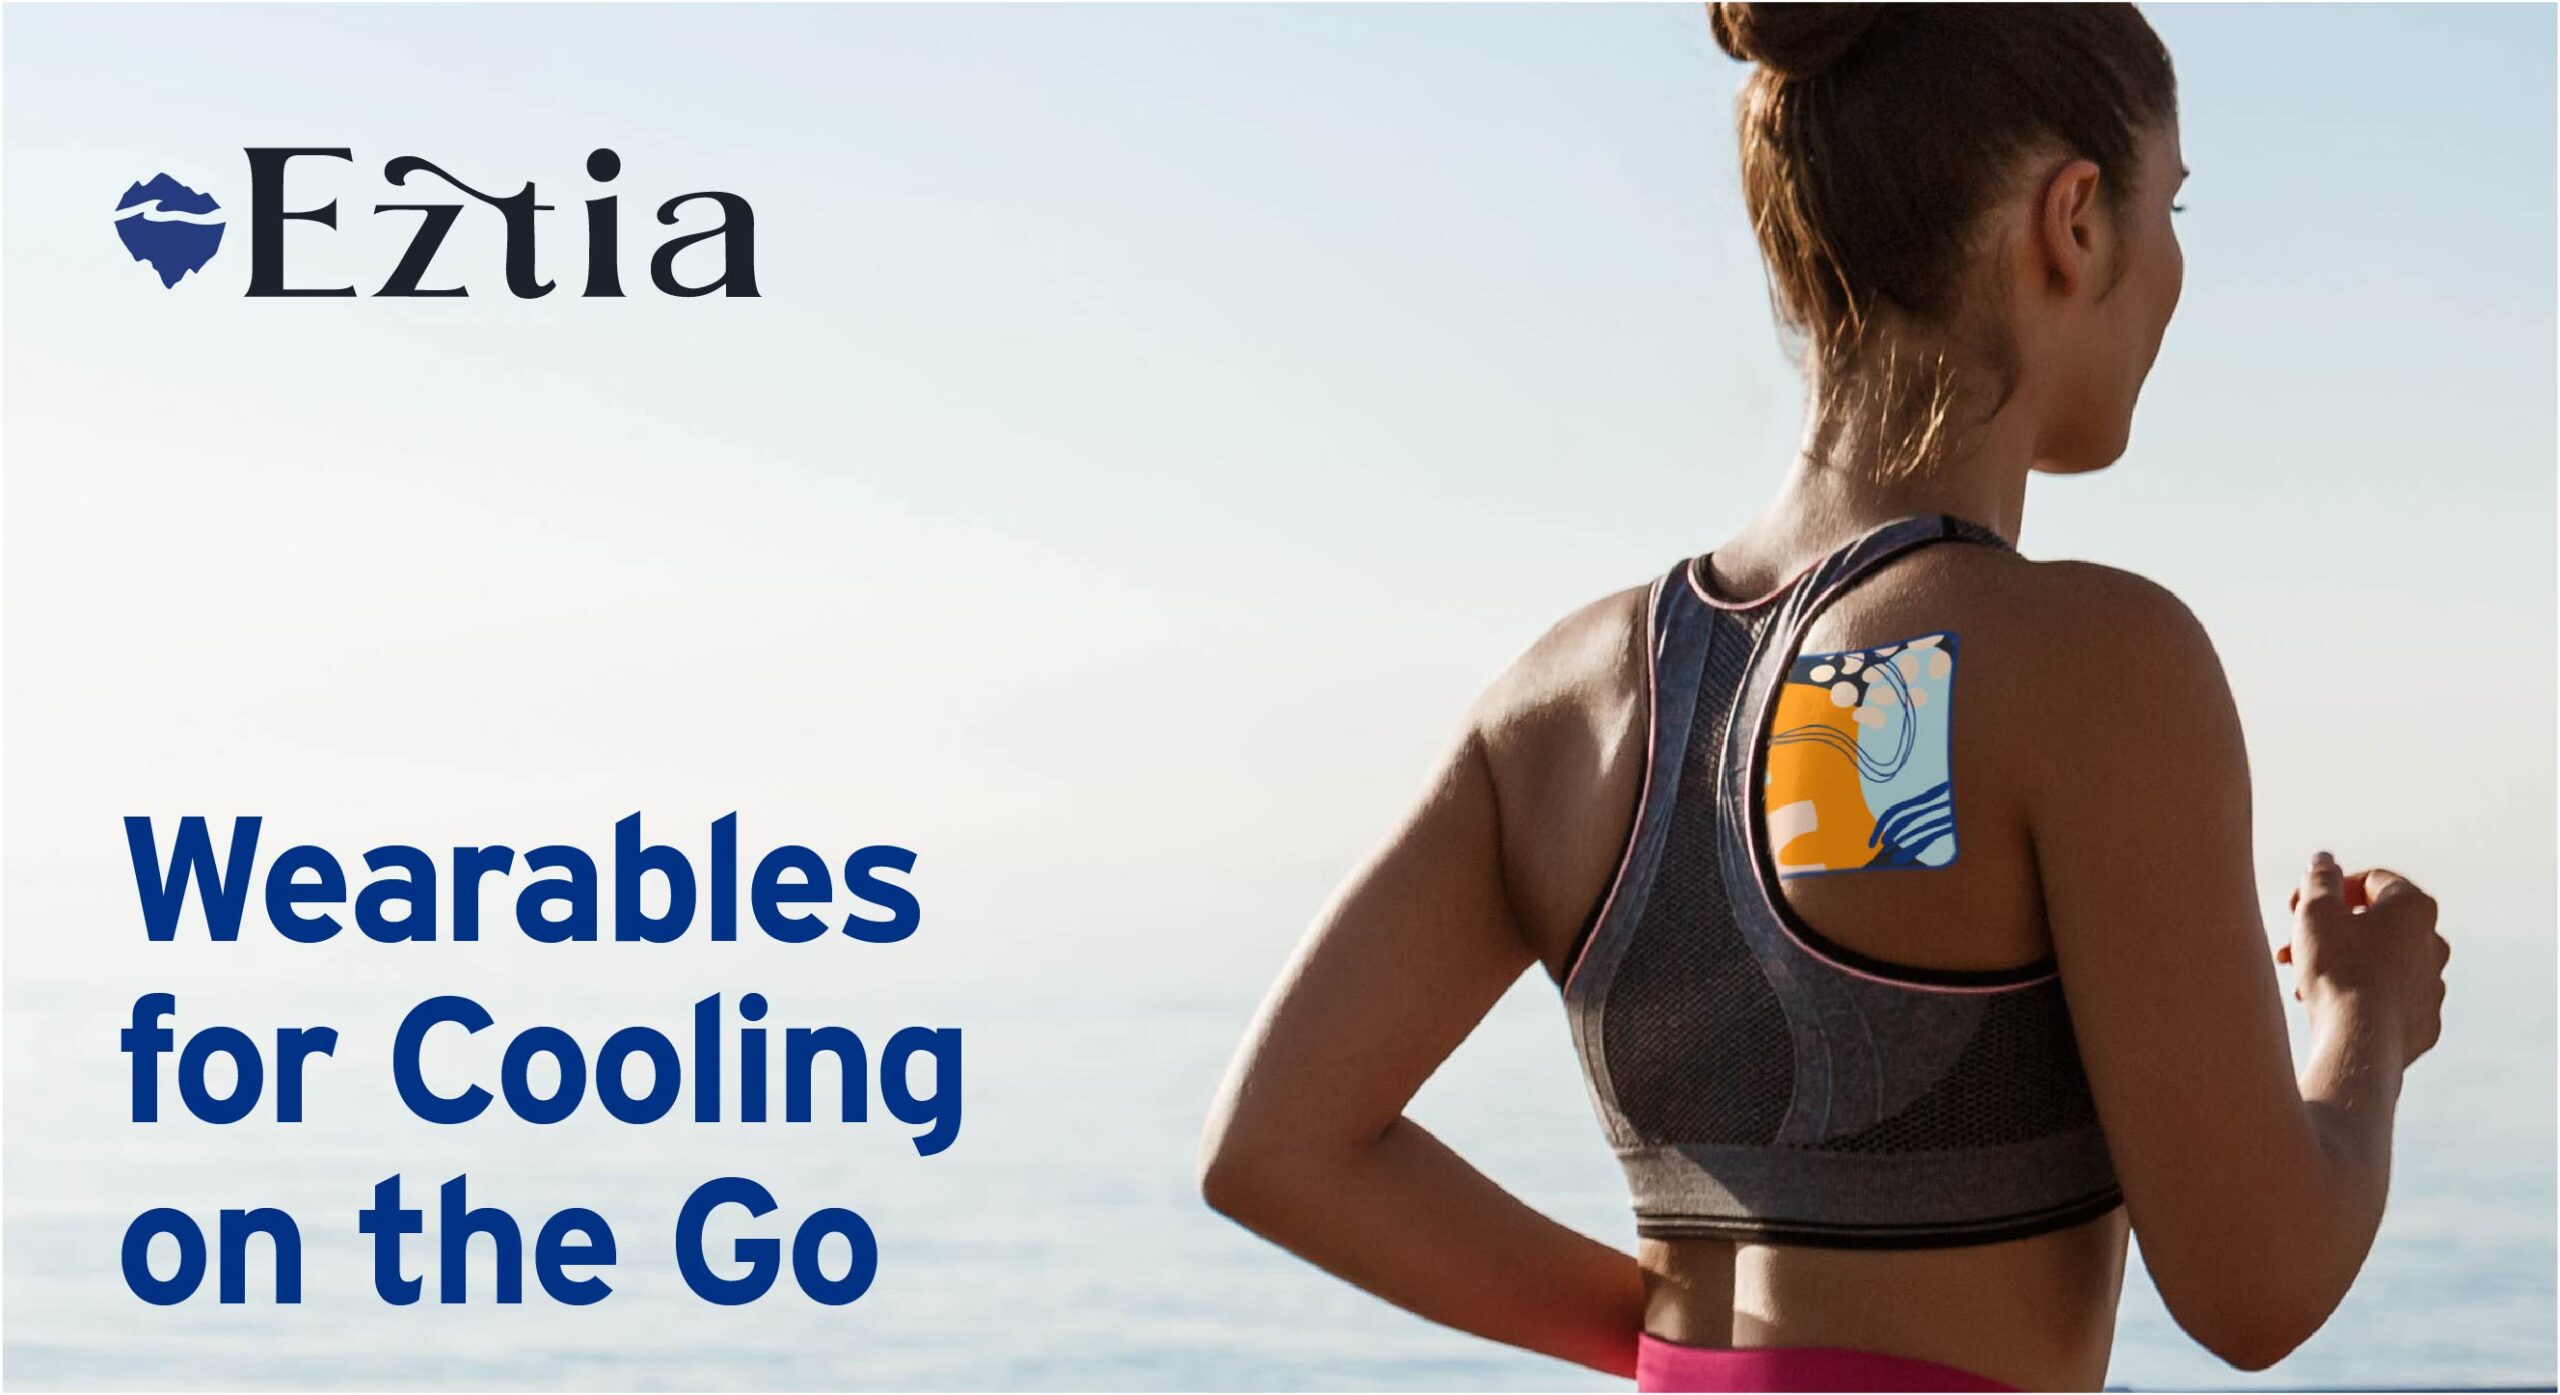
    In October 2026, United States materials startup Eztia Materials expanded commercial testing of its HydraVolt wearable cooling technology across logistics, construction and public safety fleets in Japan and Singapore. The electricity-free fabric lowers skin temperatures by up to 10 degrees Celsius for as long as eight hours using water-activated evaporative cooling.

    Delivery drivers at Yamato Holdings Co. Tested the material as arm covers during regional trials in Hokkaido, while construction group Kajima Corporation integrated the tech into workwear across building sites in Tokyo. The material requires no batteries, recharges through direct exposure to water, and endures standard machine laundering.

    How HydraVolt Integrates With Workwear

    Founded by materials scientist and medical doctor Tiffany Yeh, Eztia manufactures the cooling polymer through a dedicated production base in Taiwan. The company began developing the compound from building and vaccine packaging insulation before adapting it for direct application to commercial textiles.

    Early product iterations relied on detachable cooling patches and shirts with dedicated internal pockets. Eztia has since shifted to direct garment printing, applying the polymer onto apparel without altering the weight or washing requirements of industrial uniforms.

    Corporate Testing and Fleet Deployments

    Cross-border venture capital firm Scrum Ventures backed Eztia to accelerate its field trials across commercial fleets in Japan. Beyond Yamato’s delivery network, regional programs in Hokkaido evaluated the cooling fabric in headwear for elementary school students and performance gear for the Hokkaido Nippon-Ham Fighters baseball club.

    Outside Japan, government agencies in Singapore have deployed HydraVolt garments to equip police and corrections officers operating in equatorial humidity. United States construction contractors have also started running site trials for heavy infrastructure crews.

    Operational Economics for Logistics Fleets

    For parcel delivery carriers and warehouse operators across Asia, chronic heat stress represents a direct drag on workforce retention, route completion times and workplace safety compliance. Battery-powered fan jackets and active thermoelectric vests add bulk, require dedicated charging infrastructure at depots, and increase unit repair costs across large driver networks.

    Passive water-rechargeable polymers remove the electrical failure points that disrupt daily operations during peak summer delivery cycles. The main commercial hurdle rests on whether printed polymers retain their thermal efficiency through hundreds of commercial laundry cycles without degrading, an operational cost metric fleet buyers will scrutinize before committing to systemwide uniform replacements.

    Supply Chain Alignment in Taiwan

    Yeh developed the core polymer designs while completing her medical degree at the University of Pennsylvania, following undergraduate materials science training at the Massachusetts Institute of Technology. The company established its manufacturing line in Taiwan to secure immediate access to regional technical textile suppliers and garment assembly hubs.

    Commercial momentum built following the SusHi Tech Tokyo innovation summit held at Tokyo Big Sight in late April 2026, where Eztia presented its deployment data as a finalist in the venue pitch challenge.

    Next Steps for Regional Rollouts

    Eztia is now working with its initial corporate partners in Japan and Singapore to scale deployment from isolated demonstration sites to broader workforce divisions. Engineering teams in Taiwan continue running multi-cycle wash durability tests to clear full procurement standards for regional parcel carriers ahead of the next peak summer delivery season.

  • Kyochon Chicken Re-Enters Japan with Arai Shoji Partnership

    Kyochon Chicken Re-Enters Japan with Arai Shoji Partnership

    South Korean fast-food chain Kyochon Chicken signed a franchise agreement with Japanese distributor Arai Shoji to re-enter the Japanese dining market. The plan targets a Tokyo opening in the first half of 2027.

    The deal establishes a multi-unit franchise model that grants regional operating rights across Tokyo. It sets up a pipeline for phased expansion into surrounding cities.

    Multi-unit structure replaces single-store bet

    Kyochon F&B signed the memorandum of understanding with Kanagawa-based Arai Shoji on September 29. Under the arrangement, the Japanese trading house will handle regional store operations, site selection, staff training and local marketing. Kyochon oversees sauce formulation and kitchen preparation standards.

    Arai Shoji brings existing supply chain infrastructure to the rollout. Founded in 1920 as an auction and distribution business, the company acquired Korean food importer Ongane Holdings in 2020. It entered direct food service in 2024 by opening a specialty waffle concept. That network gives Kyochon direct access to established wholesale channels for Korean ingredients rather than building a logistics pipeline from scratch.

    We have laid the groundwork for market entry through collaboration with a partner that has strong local distribution networks and a deep understanding of Korean food products.

    Correcting the 2015 Roppongi missteps

    This venture represents Kyochon’s second attempt to establish a permanent presence in Japan. The chain first entered Tokyo in December 2015 with a flagship store in Roppongi alongside local partner Food Planet. That outlet closed in September 2016 after nine months of trading.

    Misaligned pricing and high real estate costs doomed the initial run. The Roppongi outlet priced an 18-piece wing platter at ¥1,800, roughly $11 at the time. That was nearly twice the retail price charged across its domestic South Korean network. Side dishes such as pickled radish, provided complimentary in Korea, were billed at ¥280. Food Planet subsequently ran into financial difficulties and was delisted from the Tokyo market in 2017.

    Domestic saturation forces regional expansion

    South Korean fried chicken chains face severe margin compression and store saturation at home. Domestic franchise territories are densely packed. Operators have limited headroom to add outlets without cannibalising existing franchisees. Moving into neighbouring Asian markets has become an operational necessity for top-tier Korean fast-food operators looking to sustain system-wide sales growth.

    Japan presents substantial structural hurdles despite growing consumer familiarity with Korean dining concepts. Foreign operators face slim margins. Tokyo brings high prime commercial rents, chronic kitchen staffing shortages across metropolitan centres and entrenched competition from domestic karaage chains. Kyochon’s success rests on whether Arai Shoji can price the menu competitively against local convenience chains and specialty chicken shops while absorbing central Tokyo overheads.

    Next steps for the Tokyo pipeline

    Site selection for the initial Tokyo restaurant is currently being finalised ahead of the planned launch in early 2027. Kyochon and Arai Shoji are reviewing locations. Once the flagship opens, the partners will evaluate operational data and store-level margins before committing capital to secondary locations in adjacent prefectures.

  • FairPrice Adapts on Xiaohongshu to Target 3.1 Million Chinese Tourists

    FairPrice Adapts on Xiaohongshu to Target 3.1 Million Chinese Tourists

    FairPrice Group has partnered with agency Prizm Group to overhaul its marketing on Xiaohongshu, shifting resources away from broadcast advertisements toward search-indexed consumer guides.

    The push targets a domestic audience where Chinese residents make up 73.9 per cent of Singapore’s resident population, alongside mainland Chinese visitors who generated S$3.68 billion in tourism receipts during the first nine months of 2025.

    Shifting from Social Feeds to Search Queries

    Xiaohongshu, operated internationally as RedNote, functions across Southeast Asia primarily as a product search engine rather than a passive social feed. Users search the platform for purchasing advice, store guides and product comparisons before transacting in physical outlets or on digital storefronts.

    For retailers, the operational change requires building content around high-frequency search keywords rather than conventional brand campaigns. Agency data from Prizm Group shows that organic saves serve as the primary performance benchmark on the platform, indicating intent to retrieve product information inside a supermarket aisle.

    Localising Terminology for Regional Shoppers

    Campaign assets developed for FairPrice include bilingual grocery guides designed to resolve naming disparities between Southeast Asian and mainland Chinese retail packaging. A visual reference guide for fresh pork cuts mapped regional Singaporean retail labels against terms used by shoppers from mainland China.

    A related campaign targeting office workers with breakfast recipes generated 1,453 organic saves against 1,591 likes, demonstrating higher retention than standard social engagement formats. FairPrice also introduced closed user group chats on the platform to distribute promotional vouchers without diluting standard search feeds.

    Regional Reach Across Southeast Asian Markets

    The platform’s user base extends across neighbouring Malaysia, where the Chinese community accounts for 22.2 per cent of citizens, representing nearly seven million consumers. Xiaohongshu recorded more than 2.5 million active Malaysian users in 2023, establishing the country as the platform’s second-largest user base outside mainland China after Taiwan.

    Retail operators running regional supply chains across the Singapore-Malaysia corridor face three distinct consumer tiers on a single application: local citizens, resident expatriates and incoming tourists. Marketing assets created for domestic Singaporean shoppers frequently fail with mainland tourists due to differences in product nomenclature and payment preferences.

    Search Indexing Over Brand Broadcasts

    Mainland China delivered 3.1 million visitor arrivals to Singapore in 2025, regaining its position as the city-state’s top international travel source. Department of Statistics data indicates that inbound spending from these travellers concentrates heavily in grocery, personal care and specialty food categories.

    Retailers operating physical store networks in the region are now tracking keyword volumes on lifestyle platforms alongside traditional Google search rankings to protect footfall against cross-border e-commerce alternatives.

  • Athleisure and Luxury Lift K11 Musea Tourist Sales by 26% During Golden Week

    Athleisure and Luxury Lift K11 Musea Tourist Sales by 26% During Golden Week

    Tourist spending at Hong Kong’s K11 Musea climbed 26 per cent year on year during National Day Golden Week. New premium fashion and sports apparel tenants drove the gains.

    Footfall at the waterfront complex rose roughly 12 per cent over the holiday period. That set an all-time October record for the property.

    Athletic apparel delivered the sharpest rebound. Spending by loyalty members on athleisure surged 279 per cent compared to the same holiday window last year. US label Alo Yoga helped drive those gains after opening a duplex harbourfront unit in September. Running brand HOKA added its largest Hong Kong specialty store during the third quarter. Chinese outdoor brand KAILAS also introduced its first mountaineering concept shop in the territory.

    Luxury flagships and dining lift basket sizes

    High-end jewellery and watches generated the bulk of high-ticket transactions. The single largest purchase approached HK$2 million. Member sales across international luxury labels rose 75 per cent year on year. Fashion apparel revenue climbed 25 per cent.

    Lower-level openings fueled the luxury surge. Prada launched a new duplex flagship, Miu Miu opened a boutique, and Max Mara unveiled a two-storey concept store.

    Restaurants captured spillover traffic from evening events around Victoria Harbour. An estimated 380,000 people gathered along both sides of the harbour for the 1 October fireworks display. Every harbour-facing restaurant inside the mall was fully booked for dinner. Dine-in revenue across the property rose 10 per cent year on year through the break.

    Tenant reshuffle tests high-density retail

    Spending patterns show how Hong Kong mall operators must reconfigure floors to capture mainland tourist dollars. Inbound travellers have shifted away from mass retail. Instead, they seek experiential dining, technical sportswear and luxury concepts.

    Landlord New World Development Company Limited swapped standard mall units for multi-storey duplexes and outdoor labels to defend market share against Causeway Bay and Central. The real test is whether athletic labels can maintain sales density once opening promotions fade.

    NWD broadens brand overhaul

    Holiday numbers follow a multi-year repositioning campaign across New World Development’s retail portfolio. During the previous financial year, the overall K11 operating segment expanded 9 per cent year on year. K11 Musea posted record full-year retail sales.

    Experiential events ran alongside the retail rollouts. The venue staged an immersive space exhibition called “Fly Me to the Moon: A 380,000 km Journey”. It also ran a gin-pairing dining promotion titled “Taste of GIN-dulgence” across 12 venues in K11 Musea and adjacent K11 Art Mall.

    New World Development plans to open another round of international retail flagships across K11 Musea before the end of the fourth quarter.

  • Seven & I Targets Europe as Fourth Growth Pillar for 7-Eleven

    Seven & I Targets Europe as Fourth Growth Pillar for 7-Eleven

    Seven & I Holdings is looking to Europe for the next phase of 7-Eleven’s global expansion following its exit from India in October 2026.

    According to Nikkei Asia, president and CEO Steve Dacus said the company aims to make Europe its fourth major growth pillar, alongside Japan, North America and Asia.

    The region’s relatively small store network presents an opportunity for the Tokyo-based retail conglomerate to expand its footprint as it reassesses its international growth strategy.

    Building a Fourth Regional Base

    The European push elevates the continent alongside Seven & I’s three core operational strongholds. While 7-Eleven maintains dominant networks across East Asia and North America, its European presence has historically lagged far behind domestic rivals and fuel station operators.

    Expanding across Europe requires tailored franchise models and fresh supply chain infrastructure. Local planning laws and dense urban competition in Western Europe present a very different operating environment than suburban North American forecourts or high-density Asian city centres.

    North American Overhaul and Fuel Dependencies

    The push into Europe coincides with an ongoing operational overhaul across Seven & I’s North American business. Under 7-Eleven Inc. Head Mauricio Leyva, the group has been importing fresh food merchandising and supply chain practices directly from Japan to upgrade standard US convenience formats.

    North American earnings delivered strong overseas profitability during the second quarter, largely lifted by fuel margins. Group net profit fell during the quarter as weak domestic Japanese retail performance outweighed overseas gains.

    Strategic Shifts After India Retreat

    Exiting the Indian retail market closed a difficult chapter for Seven & I’s Asian licensing division. Expanding deep into India required heavy logistical spending without delivering the high-margin packaged food velocity that sustains the chain in markets like Japan, Taiwan and Thailand.

    Redirecting expansion resources into developed European economies shifts the group away from low-margin, high-risk emerging markets toward consumer bases with higher disposable spending power. The risk sits in high European labour costs and entrenched regional supermarket chains already operating compact express formats.

    Next Steps in Overseas Expansion

    Seven & I now faces the task of securing master franchise partners and real estate pipelines across targeted European cities. Investors will watch for specific country entry timelines and capital allocation details in upcoming corporate strategy filings.

  • Pakistan Ad Market Shifts to Influencers as Social Media Reaches 80 Million Users

    Pakistan Ad Market Shifts to Influencers as Social Media Reaches 80 Million Users

    Pakistan’s advertising market is shifting toward content creators as of October 2026, with the country recording around 80 million adult social-media user identities.

    TikTok alone has an advertising reach approaching 80 million adults, while YouTube reaches around 54 million and Instagram reaches approximately 22 million.

    Individual creators are amassing major audiences, including Jannat Mirza with over 25 million TikTok followers, Hania Aamir with over 20 million Instagram followers, Ducky Bhai with over 10 million YouTube subscribers, and Rajab Butt with around 9 million.

    Performance Models Replace Flat Sponsorship Fees

    Commercial deals are shifting from flat fees to direct affiliate commissions. Smaller creators take free merchandise or modest cash retainers, while top celebrities still charge premium rates. Retail brands now deploy trackable discount codes and custom referral links.

    A merchant offering unique promo codes across 100 creator accounts can measure exact conversions within days. That turns endorsements into direct sales channels. For consumer startups and domestic cosmetic lines, performance deals offer instant distribution without the steep upfront costs of television runs.

    Niche Conversion Challenges Follower Scale

    Relevance now matters more than raw follower totals in campaign planning. A specialised account with 50,000 motorcycle enthusiasts regularly delivers higher conversion rates for vehicle parts suppliers than a general entertainment channel with five million subscribers.

    This mirrors digital commerce across Southeast Asia and China, where live-stream selling ties demonstrations straight to payment and fulfilment. Pakistan holds the same ingredients: expanding smartphone adoption, digital payment rails and a young urban population accustomed to mobile buying.

    Metrics Move Toward Acquisition and Retention

    Rapid growth has brought friction over audience authenticity and transparency. Brands face risks from synthetic engagement, bought follower counts and unclear commercial disclosures. These hazards run highest in regulated sectors like consumer health and financial services.

    Marketing teams now evaluate creator deals against customer acquisition costs, basket sizes and repeat order rates instead of vanity impressions. That demand is fueling dedicated talent management agencies, affiliate platforms and analytics firms across Karachi and Lahore.

    Traditional Media Monopolies Recede

    Billboards, print ads and television commercials still draw institutional budgets, but legacy networks no longer control consumer reach. Independent creators now build audiences larger than broadcast stations from home setups.

    Budgets will track verified checkouts as consumer brands watch whether creator live streams deliver steady sales through upcoming festive shopping cycles.