Author: Mei Ling Tan

  • Novo Nordisk Introduces Higher-Dose Semaglutide in Thailand

    Novo Nordisk Introduces Higher-Dose Semaglutide in Thailand

    Novo Nordisk Pharma Thailand introduced a higher-dose semaglutide option on October 7. The treatment addresses type 2 diabetes and linked cardiovascular risks across the country.

    It targets an expanding patient base. Diabetes prevalence in Thailand climbed to 10.6 per cent in 2025, up from 9.5 per cent in the 2020 national survey.

    The Danish drugmaker presented the formulation to more than 500 Thai medical practitioners at an industry gathering. The therapy targets cardiovascular-kidney-metabolic syndrome. That condition links heart disease, renal impairment, and obesity in diabetes patients.

    Expanding Treatment Beyond Glycaemic Control

    Cardiovascular disease is the leading cause of death among Thai type 2 diabetes patients. Chronic kidney disease also affects up to 40 per cent of diagnosed patients. Diabetes remains the primary driver of end-stage renal failure nationwide.

    Doctors gain an extra clinical tool for weight management and organ protection alongside blood glucose reduction. Most Thai adults with type 2 diabetes are overweight or obese. This compounds their health risks.

    Distribution runs through state hospital tenders, private hospital networks, and licensed retail pharmacies across the Kingdom. The company has operated locally for more than four decades, supplying metabolic and chronic disease therapies through all three channels.

    Commercial Stakes in Southeast Asian Healthcare

    Demand for advanced glucagon-like peptide-1 receptor agonists has surged across Southeast Asia. Lifestyle illnesses now place heavy pressure on state healthcare funds. In Thailand, universal health coverage schemes face rising long-term costs from dialysis and acute cardiac interventions.

    Drug suppliers compete directly for formulary spots in private hospital groups and government procurement lists. Higher dosage strengths help manufacturers preserve revenue per patient. They also defend market share against emerging biosimilars and rival GLP-1 therapies entering Asian markets.

    Premium chronic therapies provide healthcare operators and pharmacy chains with steady prescription volumes. Affordability and public reimbursement access remain the main hurdles. Because of those limits, high-dose therapies rely largely on private payers and self-funded patients.

    Four Decades of Thai Market Presence

    Novo Nordisk established its formal presence in Thailand more than 40 years ago. It built distribution relationships with public teaching hospitals and private medical groups, later rolling out baseline semaglutide formulations across Southeast Asia after global clearances.

    Novo has been at the forefront of diabetes care for more than a century, and we recognise that type 2 diabetes is one of the most pressing public health challenges of our time. In Thailand, it is closely linked to CKM syndrome, conditions that place an enormous burden on families and on the Thai healthcare system.

    Next year, the pharmaceutical producer will hold clinical symposiums across provincial medical hubs. These sessions will train specialists on prescribing protocols for the higher dosage.
  • Tokyo Financial Exchange Launches BOJ Overnight Rate Futures After Benchmark Hits 1.25%

    Tokyo Financial Exchange Launches BOJ Overnight Rate Futures After Benchmark Hits 1.25%

    Tokyo Financial Exchange will introduce a futures contract tied to the Bank of Japan’s overnight call rate this month. The contract targets traders hedging volatility between policy meetings. Last month, the central bank lifted its benchmark rate to a 31-year high of 1.25 percent. That was its second increase this year.

    Faster rate adjustments broke the central bank’s previous pattern of six-month pauses between increases. The new contract allows financial institutions and corporate treasuries to hedge specific policy meeting outcomes. They no longer have to rely on wider quarterly averages.

    Plunging Activity in Three-Month TONA

    Trading in the exchange’s existing three-month Tokyo Overnight Average Rate (TONA) futures failed to match market needs during recent policy shifts. Volume in that contract fell nearly 50 percent in September compared to the same month a year earlier, the exchange reported.

    Market participants faced mismatch risks under the three-month design when pricing rate hikes scheduled weeks apart. “Interest rate moves have become more active lately, and there is an increase in demand for derivatives trading,” said Ryosuke Seo, a director in the wholesale business department at the Tokyo Financial Exchange.

    Exchange Competition Against Swaps Desk

    Both Tokyo Financial Exchange and Osaka Exchange, a unit of Japan Exchange Group, launched three-month TONA contracts in 2023 ahead of the central bank’s exit from negative interest rates. Neither venue took decisive liquidity away from private dealer networks.

    Over-the-counter overnight index swaps remain the primary competition because they allow customized maturities matched directly to meeting dates. Notional volume in yen overnight index swaps extending out past 30 years reached a record high last month, according to Japan Securities Clearing Corp data.

    Implications for Commercial Borrowers

    For Japanese businesses and regional corporate treasuries, listed meeting-date futures provide a transparent pricing mechanism for short-term borrowing costs. Commercial real estate borrowers, consumer lenders, and retail supply chain financiers in Tokyo have seen debt servicing expenses climb as rates advanced from negative territory to 1.25 percent.

    An active exchange-traded contract reduces reliance on bespoke bank swaps. Those private swaps often carry higher bid-ask spreads for smaller institutional participants. Tokyo Financial Exchange must now build adequate clearing volume before the next central bank tightening cycle takes hold.

    Context of the Policy Tightening Cycle

    This launch follows monetary tightening steps across 2024 and 2026 that dismantled over a decade of ultra-loose policy. The Bank of Japan exited negative interest rates in 2024. That shift altered domestic yield curves and prompted financial institutions to seek shorter-duration hedging tools.

    Traders and money-market desks now look to the central bank’s December meeting. Consensus estimates point to a third rate hike that would push Japan’s benchmark lending rate above 1.25 percent before year-end.

  • Wpay Processes over 1.55 Billion Transactions Annually Across ANZ

    Wpay Processes over 1.55 Billion Transactions Annually Across ANZ

    Australian payment provider Wpay processed over 1.55 billion transactions across Australia and New Zealand in October 2026. Merchants are overhauling disconnected point-of-sale and digital payment networks.

    Enterprise store operators face heavy pressure to link in-store payment terminals with online checkout engines. Software stacks across Australasian retail chains remain fragmented. This setup causes operational friction. Store staff cannot view cross-channel customer histories or process instant returns.

    Rebuilding Cross-Channel Checkout Systems

    Payment architectures across the region remain divided between legacy physical registers and digital gateways. When these systems run on separate databases, customer records fracture. Data splits across store registers, mobile apps, and e-commerce websites.

    Retailers are fixing this split by adopting universal identifiers, including Payment Account Reference codes and payment tokens. These network identifiers track shoppers across physical card taps and in-app transactions. They protect customer privacy by concealing raw card numbers. Operators also link these tokens directly to loyalty programs and gift card balances. That delivers accurate data on basket size and repeat visits.

    This engineering shift changes daily store operations. Integrated systems allow partial and multiple payment captures against a single authorization code. This step prevents payment failures during split shipments and deferred fulfillment orders. Shoppers who buy online can receive immediate terminal refunds in physical stores directly back to their cards. Store staff can also push refunds to original online payment methods.

    Integrating AI Agents into Payment Rails

    Beyond traditional point-of-sale hardware and mobile applications, Australian retail networks are preparing infrastructure for automated agentic commerce. Autonomous artificial intelligence agents are entering consumer markets. These bots search product catalogues, negotiate pricing, and execute transactions directly on behalf of shoppers.

    Non-human buyers demand structural changes to transactional payment architecture. Automated purchasing requires programmable, permissioned authorization protocols and hard spending limits to avoid erroneous transactions. Heavy bot traffic also demands multi-gateway routing engines. Fraud detection must operate at machine speed.

    Modern payment platforms treat automated agents as an integrated retail channel. They direct machine sales through the same settlement, inventory, and reporting databases used by physical cash registers. This safeguards supply chains against double-booking stock. It also prevents errors in daily cash reconciliations.

    Network Resilience and Offline Store Infrastructure

    Store chains in regional Australia and New Zealand face recurring telecommunications disruptions that threaten register uptime. Register downtime leads to lost sales. It also triggers long checkout queues during peak trading periods.

    To keep lanes open, retailers are installing payment terminals equipped with local store-and-forward offline processing alongside automated 4G cellular failover connections. When primary fixed-line connections drop, registers continue logging and clearing card taps locally. Normal synchronization resumes once data links restore.

    Back-end reporting tools aggregate physical register receipts and digital gateway feeds into one central balance sheet. This direct integration eliminates the need for manual end-of-day register reconciliation across regional store footprints.

    What Enterprise Retailers Face Next

    The operational divide between single-channel terminals and unified commerce platforms will drive retail technology spending across Australasia through 2027. Retailers that delay system overhauls will struggle to support combined click-and-collect fulfillment, split shipments, and cross-channel loyalty redemption.

    Technology directors now face the task of upgrading legacy enterprise systems without disrupting live checkout lanes. Artificial intelligence buying services are entering digital marketplaces. Store operators will need payment gateways capable of authorizing automated machine transactions while maintaining strict fraud thresholds.

  • Mars Study Projects AI-Driven Retail to Reach 788 Billion Dollars by 2035

    Mars Study Projects AI-Driven Retail to Reach 788 Billion Dollars by 2035

    Automated AI agents will handle everyday consumer purchases over the next decade. At the same time, global retail will shift toward experiential spaces, according to research from Mars, Kantar and Synthesis.

    Researchers analysed more than 180,000 data signals across four continents. The goal was to evaluate how consumer purchasing habits and retail platforms will operate through 2035.

    The report identifies three primary shifts: algorithmic purchasing automation, granular personal curation, and experiential physical and digital storefronts. Intelligent software assistants will handle recurring household restocking. As a result, physical shops must transform from functional transaction points into entertainment and community destinations.

    Automated repeat purchases and agentic commerce

    Software agents now manage routine consumer replenishment without manual order placement. They process purchase histories, individual preferences and live inventory levels in real time. Artificial intelligence referrals to e-commerce brands jumped 752 per cent year on year during the 2025 holiday shopping season, according to data from BrightEdge. The firm projects that AI-driven commerce transactions will expand to $788 billion globally by 2035.

    This dynamic splits retail into two separate tracks. Basic household necessities and staple groceries move into frictionless background fulfilment. Meanwhile, discretionary shopping becomes an intentional activity centred on product discovery.

    Balancing personal curation with data governance

    Consumer expectations for customised digital interactions continue to climb across retail categories. Research from TransUnion shows that 39 per cent of consumers now expect personalised online shopping experiences.

    Tailored product recommendations require retail platforms to process deeper customer data streams. That requirement raises compliance demands around customer consent, data storage and cross-border consumer protection standards across international operating territories.

    Physical stores pivot to entertainment

    Physical stores and digital platforms are responding to automated replenishment by turning shopping trips into sensory destinations. Experiential brand venues recorded 15.3 per cent year on year growth, according to tracking data from Emarketer.

    Online channels follow a similar path toward active engagement. Emarketer figures show that 22 per cent of United States digital buyers already purchase products directly through livestream broadcasts.

    Snacking brands confront disappearing impulse buys

    Background replenishment threatens traditional impulse-driven consumer packaged goods categories. Packaged food manufacturers built their distribution models around checkout aisles, end-cap displays and point-of-sale visibility in convenience stores and supermarkets. When automated algorithms reorder groceries based on historical basket data, unprompted impulse sales drop sharply.

    Brand owners now need direct interactive touchpoints to introduce new items before algorithms lock shoppers into rigid consumption loops. Regional supermarket operators must redesign floor layouts away from dense shelving and toward dedicated sampling zones and interactive kiosks.

    Retail chains started testing automated inventory reordering and cashierless checkout networks in late 2025. Consumer packaged goods manufacturers now face the 2026 holiday retail cycle as the next test of whether interactive digital activations can defend impulse purchase volumes against automated buying agents.

  • Microsoft Secures Approval for $902M Western Sydney Data Centre

    Microsoft Secures Approval for $902M Western Sydney Data Centre

    Microsoft won New South Wales government approval for an A$1.3 billion ($901.9 million) data centre in western Sydney on 1 October. The five-storey facility in Huntingwood will deliver 96 megawatts of IT capacity across 40 data halls.

    State planners signed off on the project three days after Goodman Group abandoned plans for an A$798 million facility on Sydney’s north shore following neighborhood protests. Industrial corridors and suburban fringes continue to drift apart as cloud infrastructure expands across Australia.

    Power Caps and Grid Conditions

    The development consent caps total power consumption at 140 megawatts. Before operations begin, state authorities require Microsoft to match all electricity demand with additional, firmed renewable supply. This power must come through power purchase agreements for generation within New South Wales.

    First-year carbon dioxide equivalent emissions are projected at 1,326 kilotonnes, driven largely by operational electricity draw. Onsite backup systems include 46 diesel generators holding up to 1.5 million litres of fuel, alongside 158,763 kilograms of lithium-ion batteries. Cooling will rely on 36 rooftop evaporative cooling towers drawing approximately 3.9 megalitres of water daily.

    Federal Biodiversity Clearance

    Planning consent gives Microsoft no immediate path to break ground. The company must still secure federal environmental sign-off under the Environment Protection and Biodiversity Conservation Act.

    Clearing the site requires removing 0.33 hectares of a conservation area containing critically endangered woodland and potential wildlife habitats. Construction will take 24 months once federal approvals land. It will generate 250 construction jobs and 74 permanent operational positions.

    Site Selection Shifts West

    Securing the Huntingwood site required extensive negotiations with Blacktown City Council over building bulk, drainage, and landscaping before reaching a formal planning agreement in September 2025. The proposal attracted only a single public objection. Residential properties sit 90 metres away.

    Goodman faced a harsher reception at its proposed Project Mars site in Lane Cove West. Homes stood 20 metres away, with a primary school within 160 metres. That proposal drew 374 public submissions, with only nine in support, before Goodman withdrew it on 28 September.

    The policy environment for large data centres had evolved significantly since planning started, Goodman head of planning Guy Smith told the planning department.

    Hyperscalers and real estate developers in Sydney are concentrating capital in western industrial clusters to avoid urban friction. Huntingwood borders Eastern Creek, where Goodman has filed plans for a 500-megawatt, A$5 billion campus. Nearby in Minchinbury, Starwood, Doma, and Telstra InfraCo are building a 62-megawatt facility.

    National Standards on the Horizon

    Engineering consultancy Lehr Consultants International lodged Microsoft’s initial application in 2023 without naming the end user. The project ties into Microsoft’s October 2023 commitment to invest A$5 billion over two years to expand Australian cloud and computing infrastructure.

    State planners also approved Stockland’s A$630.4 million Road 1 Data Centre in Macquarie Park on the same day, permitting a 34.3-megawatt IT load alongside future residential towers. Developers now face tighter rules. Victoria is proposing mandatory 150-metre buffer zones from homes, while the Australian federal government prepares national data centre legislation for introduction in early 2027.

  • DNB Secures $1.27 Billion Islamic Facility for Malaysia 5G Network

    DNB Secures $1.27 Billion Islamic Facility for Malaysia 5G Network

    Digital Nasional Berhad secured MYR 5.2 billion ($1.27 billion) in syndicated Islamic term financing. The facility funds the next stage of Malaysia’s national 5G deployment.

    The package refinances an existing Government Guarantee Revolving Credit Facility that expired on September 29, 2026. This shifts the wholesale operator away from direct sovereign debt backing.

    Refinancing state debt

    Maybank Investment Bank led the syndicate as mandated lead arranger, bookrunner, and coordinator. Joint mandated lead arrangers were AmInvestment Bank, CIMB Islamic Bank, RHB Islamic Bank, and United Overseas Bank (Malaysia). AmInvestment Bank also served as financial adviser to DNB.

    This long-term package ranks among the largest syndicated debt deals arranged for an unlisted Malaysian business. It provides independent capital to maintain infrastructure operations as the country prepares to licence a competing second 5G wholesale network.

    Ownership changes among carriers

    Proceeds prepare the ground for the Ministry of Finance Incorporated to surrender its ordinary equity. MOF Inc. Holds a 31.18 percent stake in DNB and plans to exit early in the fourth quarter of 2026. It will keep a special share to retain veto power over strategic national decisions.

    Three commercial mobile network operators, CelcomDigi, Maxis, and YTL Communications, each hold 22.94 percent stakes after injecting MYR 202 million ($49.45 million) apiece in May. Once the finance ministry transfers its ordinary holding, those three carriers will become equal shareholders in the business.

    Commercial impact and competitive risk

    For enterprise customers and mobile subscribers, private ownership removes the risk of sudden policy reversals tied to government budgets. Joint control forces the three competing retail operators to fund capital expenditure directly rather than rely on state guarantees.

    Commercial risk now shifts to network economics under Malaysia’s planned dual-network structure. When the telecommunications regulator awards the second 5G network, DNB must defend its wholesale traffic volumes against a rival system. The debt facility secures critical operating runway for that contest.

    Spectrum boost and network specs

    DNB expanded its active spectrum assets alongside the financing deal. The carrier activated an extra 100 MHz in the 3.3 GHz to 3.4 GHz band. Paired with its original 3.4 GHz to 3.5 GHz assignment, it now has 200 MHz of contiguous mid-band spectrum.

    All 240 MHz of DNB’s spectrum holdings converted into formal spectrum assignments on October 1, 2026, following approval from the Malaysian Communications and Multimedia Commission. The operator will direct the additional capacity into Massive MIMO, carrier aggregation, 5G-Advanced, and automated traffic management across metropolitan nodes.

    What happens next

    Next up is the formal completion of MOF Inc.’s equity exit before the end of the fourth quarter of 2026. Attention will then turn to how CelcomDigi, Maxis, and YTL Communications balance their board representation and whether any of the three seek access to Malaysia’s second 5G consortium.

  • Chagee Adds Live Calorie Calculator to Mobile App in Thailand

    Chagee Adds Live Calorie Calculator to Mobile App in Thailand

    CHAGEE launched an in-app calorie calculator across Thailand on 5 October 2026. The tool gives beverage buyers real-time nutritional breakdowns for custom recipes starting from 4 calories per cup.

    It calculates instant shifts in calories, sugar, fat, protein, carbohydrates and caffeine. Values adjust whenever a customer changes cup sizes, switches between hot and iced preparations, or adjusts sugar levels.

    Real-time nutritional tracking in the ordering flow

    Customers access the tool directly inside the CHAGEE App by tapping the Calorie Calculator icon, picking a beverage category, and opening individual product specifications. The interface updates the total nutritional payload as options change before checkout. This removes guesswork from sweetened or dairy-based beverages.

    The release accompanies the chain’s “Sip Better, Feel Better” marketing push in the Thai market. Lowest-calorie options highlighted on the platform include Da Hong Pao, Osmanthus Green and Peach Oolong brewed teas starting at 4 calories. Milk tea options, including BO-YA Jasmine Green, Osmanthus Oolong and Da Hong Pao, start at 119 calories.

    “At CHAGEE, wellbeing is at the heart. That is why we are committed to providing transparent nutritional information. The ‘Calorie Calculator’ is more than just a tool that displays what is in your cup. It gives people the freedom to customize and choose beverages that best suit their individual needs and preferences, making every sip enjoyable while promoting their wellbeing every day.”

    Store promotions tied to athletic activity

    Alongside the digital rollout, CHAGEE Thailand introduced a physical activity promotion running from 5 to 11 October 2026. Customers receive tiered purchase incentives by showing recorded running or walking activity from smartwatches or tracking apps at store counters.

    A verified 5-kilometre log qualifies for a free drink size upgrade. A 10-kilometre distance yields a THB 30 discount, and a 15-kilometre log unlocks a buy-one-get-one voucher. The promotion applies across the network except at CHAGEE Mahanakhon 74 and Don Mueang Airport branches, with redemptions capped at three vouchers per person through the app.

    Pressure shifts across Southeast Asian tea retail

    Tea chains across Southeast Asia face stricter scrutiny over sugar content and caloric density. Regional regulators are examining beverage labelling standards while consumer habits change. Digital ingredient transparency allows premium tea operators to defend ticket sizes. It also counters perceptions that commercial milk tea is entirely indulgent.

    For mall landlords and competing beverage franchises, embedding health metrics directly into proprietary ordering apps shifts footfall toward operators with robust digital ecosystems. Brands lacking unified digital ordering and dynamic recipe databases face higher barriers in retaining health-oriented consumers.

    Expansion beyond regional milk tea benchmarks

    This Thai app update follows regional product variations across Southeast Asia, including brand collaborations and seasonal market entries in Malaysia and Indonesia. Building functional digital tools into the ordering loop deepens customer lock-in within the loyalty program.

    Under the broader promotional schedule running through 15 October 2026, CHAGEE is distributing double loyalty points on Mondays. The company is also offering 30 per cent discounts on second drinks within curated low-calorie bundles, and allowing CHA Members to redeem accumulated points for fitness and Pilates sessions.

  • Three Seized Sentosa Cove Waterfront Bungalows Listed for $30 Million

    Three Seized Sentosa Cove Waterfront Bungalows Listed for $30 Million

    Three waterfront bungalows in Sentosa Cove are up for sale via expression of interest with combined guide prices of S$38.48 million ($30 million). Authorities seized the properties during Singapore’s S$3 billion money laundering crackdown.

    List Sotheby’s International Realty is handling the sales. All three homes include private yacht berths. A separate 1,741-square-metre vacant plot in the same waterfront district is also on the market for S$23.65 million.

    Breakdown of the Sentosa listings

    Two adjoining bungalows at 38 and 40 Ocean Drive occupy a combined 1,468 square metres. Registered to Lin Baoying, the joint parcel carries a guide price of S$22.8 million. Bids close on Oct. 29.

    A third residence at 13 Pearl Island covers 879.6 square metres across two storeys. Registered to Zhang Ruijin, the detached house features marble flooring, five en-suite bedrooms, an entertainment suite, a wine cellar, a private swimming pool, and a home lift. The guide price is S$15.68 million, with submissions closing on Oct. 15 at 3pm.

    Nearby at 143 and 145 Cove Drive, an amalgamated 99-year leasehold site spans 18,740 square feet with an asking price of S$23.65 million. Su Haijin is the registered owner of the plot, which previously held two bungalows. Bids for that land parcel close on Nov. 12 at 3pm.

    Legal title and asset liquidation terms

    Singapore Land Authority records show the convicted individuals remain registered titleholders. However, statutory enforcement orders have stripped their rights to deal with or transfer the properties. Sale proceeds will go directly into the Government’s Consolidated Fund.

    The expression of interest process lets receivers test buyer demand confidentially without committing to public reserve auctions. Bidders lodge formal offers before designated deadlines. That gives liquidators room to negotiate transaction terms lot by lot.

    Sentosa pricing drag tests market appetite

    Sentosa Cove enters the sale under prolonged pricing pressure. Villa values fell roughly 11 per cent across the residential enclave during the decade ending in 2025. Many secondary transactions remain underwater.

    Demand has stayed selective because of high maintenance fees, 99-year lease terms, and steep stamp duties on foreign buyers. Luxury buyers in Singapore consistently prefer mainland freehold parcels over island leaseholds. Releasing several waterfront assets at once will establish a clear clearing price for Sentosa Cove landed property.

    The wider asset recovery schedule

    Sales follow the August 2023 police sweep that snared 10 foreign nationals. Both Zhang and Lin received 15-month prison sentences after pleading guilty to money laundering and forgery charges. Courts ordered Su to forfeit over S$165 million in assets.

    Deloitte is coordinating the phased sale of more than 80 forfeited property assets and 1,000 luxury goods through mid-2027. Real estate disposals have started slowly. A late September auction cleared four of 26 listed condominiums for S$16.28 million. Luxury goods moved faster, generating more than $6 million across two digital auctions in late September.

    Attention now turns to Oct. 15, when bids close for the Pearl Island villa, followed two weeks later by the deadline for the Ocean Drive residences.

  • Hermitage Capital Deploys over 200 Million Dollars in Physical AI Pivot

    Hermitage Capital Deploys over 200 Million Dollars in Physical AI Pivot

    Hong Kong private equity firm Hermitage Capital has deployed more than US$200 million into artificial intelligence and robotics. The capital shift directs money toward hardware and automation.

    This drawdown forms part of a three-year, US$500 million global tech allocation programme announced in 2025. The money comes from the firm’s wider US$1.5 billion asset base.

    Hermitage manages a portfolio split evenly between China and overseas markets, primarily the United States. About 80 per cent of its capital base is held in US dollars, with the remainder in renminbi. Backers include Asian family offices, regional institutions, and investors in Britain and Canada. Sean Xiang Yuqiu, a former JPMorgan Chase banker who founded the firm in 2017, runs the fund across offices in Hong Kong and New York.

    Shifting from foundation models to physical automation

    Capital is shifting away from early bets on large language models to secure positions in robotics, self-improving software and specialized silicon. Recent portfolio additions include US humanoid robot builder 1X, automated research platform Recursive Superintelligence, and Chinese robotics chip designer D-Robotics.

    The investment thesis targets growth beyond pure software layers. “Foundation models were the sector to bet heavily on in 2023 and 2024,” Xiang said. “Physical AI is the sector to bet heavily on now.”

    That repositioning follows sharp price corrections across public robotics equities in mainland China. Unitree Robotics dropped roughly 60 per cent from its peak after listing on Shanghai’s Star Market in August 2026. The drop forced private investors to price unproven manufacturing schedules more carefully.

    Balancing US deals with Chinese hardware supply chains

    Deal origination and research are split between two distinct ecosystems. The New York outpost, initially established to raise Western capital for Chinese deals, now screens and executes direct investments in American technology companies.

    Growth-stage positions range from series B through series D rounds. The fund participated in 13 funding rounds for cross-border payments company Airwallex since 2019, five rounds for autonomous driving developer Horizon Robotics, and three rounds for graphics processor maker MetaX Integrated Circuits.

    Public market liquidity has returned selectively for these bets. Horizon Robotics listed in Hong Kong in October 2024. MetaX completed its initial public offering on Shanghai’s Star Market in December 2025.

    Investor preference shifts toward single-deal vehicles

    Asian family offices backing the firm are demanding direct control over their exposure. Rather than committing blind capital to traditional 10-year fund vehicles, wealth managers increasingly funnel money through single-deal special purpose vehicles with explicit entry pricing and shorter exit schedules.

    Internal risk management rules tightened following setbacks in early 2021 solid-state battery bets, where mass production missed planned milestones. The fund now limits initial check sizes in frontier hardware. Larger follow-on tranches wait until companies deliver working production lines and commercial shipments.

    For technology operators and corporate suppliers across Asia, the deployment shows venture backing has moved past general-purpose chatbots. Private capital now concentrates on robotics components, industrial sensors, and dedicated semiconductor designs that tie directly into domestic manufacturing lines.

    Hong Kong capital markets build fundraising momentum

    Regional financing has grown increasingly active as technology companies tap public markets for capital-intensive artificial intelligence buildouts. Hong Kong equity sales reached a record US$47.5 billion in the third quarter of 2026. That lifted total proceeds in the city above US$92 billion for the year.

    Heavy follow-on share sales, debt instruments and secondary listings drove that volume as Chinese chipmakers and platform groups raced to fund processing capacity and server infrastructure.

    Hermitage plans to deploy the remaining US$300 million of its frontier tech allocation by 2028, tracking milestone completions and production yields across active hardware investments.

  • Cin Cin Targets Stores in New York and Miami as US Demand Grows

    Cin Cin Targets Stores in New York and Miami as US Demand Grows

    Australian resortwear label Cin Cin is preparing to open standalone stores in the United States, targeting New York and Miami in October 2026 to capture its largest online buying demographic.

    The brand, founded by Louise Lazarus and Geo Moriarty, manufactures its retro-styled swimwear and apparel lines in Bali, Indonesia, where both founders are based and where the company operates physical storefronts.

    Bali manufacturing footprint

    Lazarus and Moriarty built the label around 1970s bohemian prints and saturated palettes, placing product development and garment production directly in Indonesia. Operating local stores in Bali gave the business an immediate testing ground with international holidaymakers before scaling wholesale and direct-to-consumer digital channels overseas.

    Direct control over Indonesian workshop capacity allows the company to turn around seasonal collections faster than competitors who outsource offshore without an on-the-ground presence. Keeping operations in Southeast Asia while selling into high-spending Western markets maintains strong unit economics for premium resortwear.

    The direct-to-consumer export corridor

    Cin Cin follows a proven path carved by Australian apparel exporters, including Monday Swimwear, PE Nation and Silk Laundry, that built international volume by pivoting early toward US shoppers. North American consumers continue to show heavy demand for southern-hemisphere lifestyle branding, particularly in coastal and warm-weather metropolitan hubs.

    Maintaining that momentum requires transition from pure-play e-commerce and multi-brand stockists into owned brick-and-mortar units. High freight rates and cross-border return friction frequently cap international digital growth, making localized storefronts essential to defend margins.

    “Our dream would be to open in New York or Miami, as our largest customer bases are there.”

    Margin pressures in physical expansion

    Leasing prime retail space in Manhattan or South Beach carries high fixed overheads and substantial upfront fit-out commitments. For independent resort labels, winter trading in non-sunbelt cities presents cash-flow risks that require disciplined inventory management across contrasting hemispheres.

    Retail property landlords in both New York and Miami are demanding solid balance sheets and proven trading histories from foreign direct-to-consumer entrants. Cin Cin will need to balance the costs of long-term commercial leases against seasonal wholesale partnerships with department stores and specialty boutiques.

    Next steps in retail rollout

    The label previously prioritized building out its retail base across tourist hubs in Bali alongside global e-commerce fulfillment. That dual structure generated the cash reserves needed to finance initial overseas market research and site scouting.

    Cin Cin is now reviewing retail real estate options and wholesale distribution schedules across North America for upcoming seasonal drops, with site selection in Florida and New York serving as the benchmark for its physical rollout.

  • SingPost Trials Digital Stamps from 62 Cents for Domestic Mail

    SingPost Trials Digital Stamps from 62 Cents for Domestic Mail

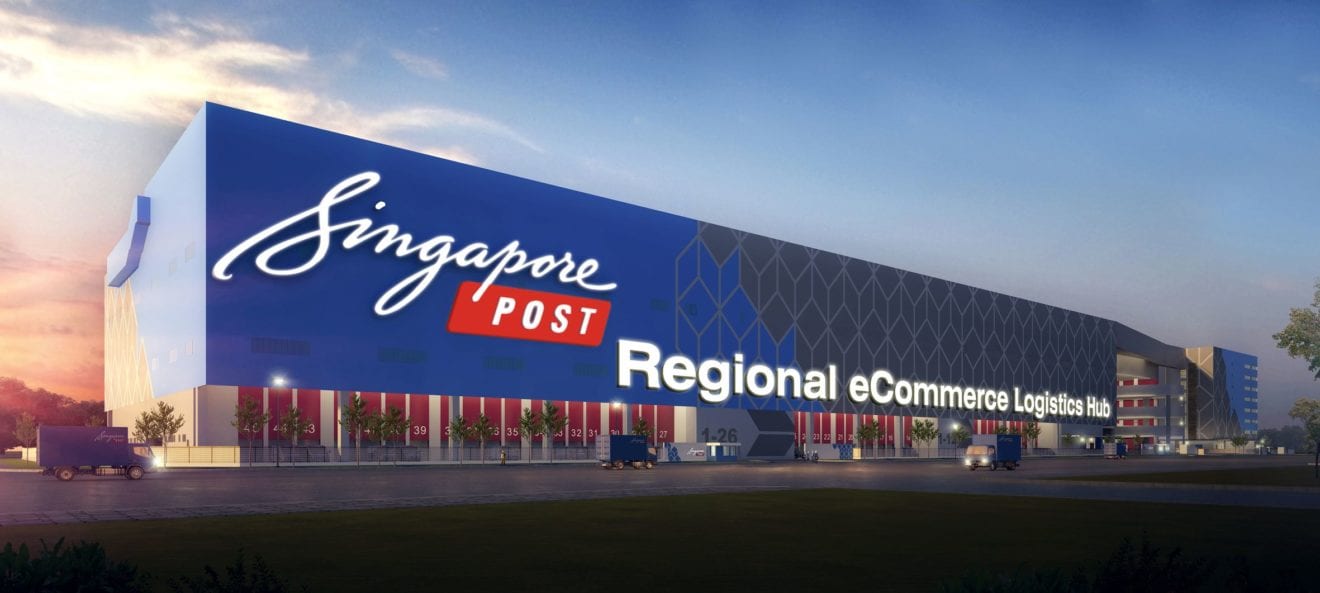
    Singapore Post launched a public trial for digital stamps on Oct 8, allowing consumers across Singapore to send domestic mail using unique codes purchased through its mobile app.

    Postage costs 62 cents for standard regular mail and 90 cents for standard large envelopes, sold in minimum purchases of five stamps valid for 24 months. Users no longer need physical stamps or labels.

    How the digital code system works

    Buyers purchase stamps in the app and write the generated alphanumeric code on the top-right corner of standard envelopes or postcards. They can drop the mail into any street posting box, post office counter, or residential letterbox return slot.

    For the trial running until April 6, 2027, SingPost is discounting five-stamp regular sets to $1 from $3.10. Five-stamp sets for large mail cost $1.50 during the promotional window. Accounts are limited to one discounted purchase each.

    Sorting automation and optical recognition

    Handling handwritten codes shifts operational pressure onto sorting centers. The trial tests optical character recognition scanners on live mail volumes. SingPost will calibrate sorting accuracy across different handwriting styles.

    Gan Heng, head of customer experience at SingPost, said:

    “Digital stamps remove that barrier entirely.”

    Digital postage applies strictly to domestic basic mail, including letters, postcards, and printed paper items. Alongside the scanning trial, SingPost added collectible digital graphics to the app. Users unlock commemorative designs, such as a 61st National Day theme and a Fullerton Building graphic, every 15 purchases.

    Network adjustments across residential hubs

    This trial links with the operator’s residential collection rollout completed in September. Dubbed SingPost@MyBlock, that project converted letterbox return slots across more than 20,000 residential buildings into collection points for outbound letters and small parcels.

    Postal operators across the Asia-Pacific region face declining letter volumes as corporate billing and consumer correspondence move online. SingPost cuts the overhead of running stamp vending machines and retail counter queues by digitising postage, while keeping its collection network active.

    Next steps in the rollout

    Neighborhood infrastructure expanded after first-quarter operating profit rose 55.2 per cent to $4.1 million on cost cuts in core delivery units. Connecting app payments to automated sorting machinery forms the next stage of the overhaul.

    A four-day public show at SingPost Centre in Paya Lebar runs through Oct 11 to demonstrate the scanning workflows. The trial will gather consumer feedback through the mobile application until the test period closes on April 6, 2027.

  • CloudHQ Plans to Shrink Tokyo Shopping Mall for Data Centres

    CloudHQ Plans to Shrink Tokyo Shopping Mall for Data Centres

    CloudHQ has proposed rebuilding the struggling BigHop Garden Mall Inzai in Greater Tokyo, shrinking its retail footprint to 13,345 square metres to make room for two data centres.

    The Washington DC-based developer presented the plan, named Project Asahi, to the Inzai City Council on 29 September, seeking an exemption from local development restrictions near commuter rail stations.

    Under the proposal, CloudHQ plans to reduce the 13-hectare property beside Inzai-Makinohara Station on the Hokuso Line into a smaller retail row facing the station, paired with a 6,235-square-metre public park and 8,450 square metres reserved for non-data centre commercial uses and offices. Revenue generated from the server facilities would fund the capital expenditure needed to overhaul the remaining shops.

    Cutting shop space to save the asset

    BigHop opened in 2007 after construction by Takenaka Corporation, but the asset has suffered from stagnant tenant revenue and looming capital expenditure requirements. CloudHQ told city officials that the mall’s sales have stayed flat, trailing the 3.4 per cent growth recorded across comparable Kanto shopping centres in municipalities with fewer than 150,000 residents during 2025.

    Rising expenses for labour, purchasing, and consumables have compressed retailer margins, removing room for rent increases. The developer noted that the mall’s existing rental income cannot cover major equipment renewals scheduled over the next five years. Soundings conducted in 2025 with Japanese trading houses, contractors, institutional asset managers, and foreign developers yielded zero interest in acquiring or backing the site as a standalone shopping destination.

    Of the remaining land on the 13-hectare parcel, roughly half will host two data centres and electrical infrastructure, while the other half will be retained for future development. CloudHQ Japan operates the property and aims to finish the phased reconstruction by the mid-2030s.

    Station-front opposition and council rules

    Securing municipal approval remains the primary hurdle for the project. In August 2025, Inzai’s city council passed a 19-0 resolution barring future data centres from zones immediately surrounding its three railway stations, reserving those plots for civic services, retail outlets, and pedestrian traffic.

    Local sentiment against digital infrastructure in station districts runs high. A city consultation held in April 2025 showed that 90.5 per cent of data centre submissions, representing 114 out of 126 responses, opposed server halls near transit hubs. Legal disputes have already surfaced nearby, with ten residents filing a lawsuit in Chiba District Court in March to cancel building clearance for an Inzai Five TMK project backed by Mitsui & Co near Chiba New Town Chuo Station.

    To defuse community pushback, CloudHQ pledged to build the public park and civic facilities before constructing the data halls. The developer also offered to provide local school scholarships and technical classes to broaden community benefits beyond municipal property tax receipts.

    The shifting economics of suburban retail

    Converting underperforming suburban retail into digital infrastructure represents a hard-nosed pivot for operators trapped in low-yielding regional assets. Japanese suburban malls built during the mid-2000s face structural challenges from an ageing population, online commerce, and escalating utility and refurbishment bills that conventional retail leases cannot cover.

    Replacing low-margin retail space with long-term server capacity provides a guaranteed cash flow that traditional consumer tenants no longer deliver. However, the model risks creating dead zones around railway nodes if municipal councils allow industrial-scale server blocks to displace foot traffic. For retail landlords across suburban Japan, the Inzai case illustrates how hyperscale compute demand is outbidding conventional retail real estate for grid connections and physical land.

    Institutional money in Inzai’s digital hub

    The BigHop parcel already accommodates digital infrastructure. Stack Infrastructure previously built a data centre on a former mall parking lot at the southwest corner of the site as part of its 36-megawatt Inzai campus.

    Institutional investors continue to funnel capital into Inzai due to its seismic stability, proximity to central Tokyo, and robust electrical and fibre connections. In 2025, Keppel DC REIT and Keppel Ltd acquired a Colt data centre in Inzai leased to Microsoft for 707 million Singapore dollars, followed by a 190 billion yen deal to buy a 90 per cent interest in two facilities from an Equinix and GIC joint venture. Digital Realty brought its campus capacity in the city to nearly 100 megawatts in April, joining operators including Google, AWS, AirTrunk, and STT GDC.

    CloudHQ, founded in 2016 by Hossein Fateh and managing over 5 gigawatts globally, previously partnered with ESR on a 2 billion dollar, 130-megawatt campus in Osaka. Public briefing sessions with Inzai residents run through 11 October, setting up the council’s formal review of the zoning exemption.

  • AllHome and AllDay Cut Store Counts to 34 and 13 Outlets

    AllHome and AllDay Cut Store Counts to 34 and 13 Outlets

    Villar-owned retail companies AllHome and AllDay confirmed store network contractions on Wednesday, October 7, following financial losses and stiff retail competition.

    Separate disclosures to the Philippine Stock Exchange show home improvement chain AllHome cut its store count to 34 as of September 29, 2026, down 26 percent from 47 at the end of 2025. Grocery operator AllDay Marts reduced its network by 50 percent over the same period, dropping from 26 locations to 13.

    Network shrinkage across home and grocery formats

    The retrenchment represents a steep reversal for two retail chains that expanded aggressively across Villar residential developments over the past decade. AllHome operated 72 outlets at its peak across 2023 and 2024, after starting with just four branches in 2013 and listing on the local bourse in 2019. Its current 34 locations include large mall-based, large free-standing, and small specialty outlets.

    AllDay opened its first grocery branch in late 2016 and expanded to 40 supermarkets by 2024. The current fleet of 13 stores leaves the grocery operator with less than a third of its peak footprint. The company told the exchange it will reorient remaining operations toward smaller mini-mart formats to lower overhead and protect liquidity.

    Earnings collapse and anchor space turnover

    Financial results explain the sudden retreat from large-format retail. AllHome posted a net loss of 36.4 million pesos for the first nine months of 2025, swinging from a net profit of 384 million pesos during the prior-year period. AllDay saw full-year 2024 net profit decline 27 percent to 268 million pesos as revenue fell 9.2 percent to 9.25 billion pesos, citing intense competition in low-performing catchment areas.

    Mall landlords within the group are already reallocating space to outside operators. The Philippine Stock Exchange questioned both companies after reports surfaced that Gokongwei Group brand Shopwise will take over the anchor space previously occupied by AllHome at Vista Mall in Santa Rosa City, Laguna. Inventory clearance sales across Cavite, Laguna, Mandaluyong, Taguig, and Pampanga preceded the closures, with promotional markdowns reaching 75 percent.

    Rethinking township retail integration

    The contraction exposes structural limits in relying on captive housing developments for retail foot traffic. The Villar group built more than 500,000 residential units nationwide and positioned its retail chains as natural amenities for those master-planned subdivisions. While property integration gave AllHome and AllDay fast access to commercial land, it insulated both brands from direct competitive pressure only temporarily.

    Rival operators with stronger supplier terms, deeper private-label assortments, and more efficient logistics chains have consistently pressured independent township stores. When housing construction slowed and consumer spending tightened, foot traffic inside standalone township malls failed to generate the volumes required to support big-box home depots and premium supermarkets. Handing anchor tenancy to external chains such as Shopwise indicates that property management now prioritizes stable rental yield over internal ecosystem synergy.

    Leadership departures and operating reset

    Management instability accompanied the downturn well before the latest round of store shutdowns. The shared president and chief operating officer of AllHome and AllDay resigned in September 2025 as earnings began to deteriorate. That executive exit followed earlier public statements from chairman Manny Villar and former AllValue president Camille Villar celebrating record sales figures from the post-pandemic reopening.

    Both companies now face the task of defending their remaining assets while containing operating debt. AllDay is adjusting store layouts to focus on working capital optimization, cash conservation, and smaller-format convenience retailing. Investors and suppliers will monitor third-quarter 2026 financial statements and upcoming lease filings to see whether the network consolidation stabilizes operating margins or triggers further asset impairments.

  • Nippan Group Confirms Book Sales to US AI Firm Anthropic

    Nippan Group Confirms Book Sales to US AI Firm Anthropic

    Nippan Group Holdings has confirmed that it sold books to US artificial intelligence firm Anthropic, sources familiar with the matter said on Wednesday, October 7, 2026.

    The Japanese book wholesaler confirmed the sale in a letter addressed to the Japan Book Publishers Association, an industry group.

    Nippan Group did not disclose how many books were sold or the total purchase amount.

    The Paper Trail in Project Panama

    Filings in a US copyright lawsuit brought the commercial relationship to light. Internal records submitted in court identified a deal with an entity listed as Nippan Japan under Project Panama, an initiative to purchase and digitise print volumes across international markets.

    Briefings to trade representatives omitted the volume of books supplied and the financial value of the transaction. The industry association then circulated the wholesaler’s written statement to approximately 380 domestic publishing houses.

    Publishers Face Downstream Copyright Exposure

    The disclosure shifts a dispute over AI scraping from digital web crawlers directly into physical supply chains. Wholesalers in Japan sit between content creators and readers. Bulk sales of catalog backlists can channel proprietary print into training clusters without separate licenses from authors.

    Publishing houses in Tokyo now face an audit problem across their distribution channels. Standard export contracts may allow unmonitored mass digitisation under foreign fair-use or research clauses. When that happens, domestic rights holders lose the ability to negotiate commercial data fees for models that eventually compete in their home market.

    Scrutiny Mounts Over Model Inputs

    Developers have pursued physical procurement to source high-grade, non-English training text absent from public web archives. Japanese print media holds dense, structured vocabularies. General web scrapers struggle to harvest this material cleanly from behind paywalls and regional access controls.

    Across Japan, financial institutions and systems integrators are rolling proprietary models into operational software. These commercial integrations rely on stable copyright foundations. Contested bulk purchases of print stock leave those foundations vulnerable.

    Publishers Demand Commercial Clearances

    Nippan Group told member firms of the publishing association that it will respond directly to corporate inquiries from copyright owners affected by the shipments. Industry groups in Tokyo are now reviewing whether standard distributor contracts provide sufficient controls over secondary usage by corporate technology buyers.

  • Payra Port Adds 5 Cargo-Handling Machines at First Terminal

    Payra Port Adds 5 Cargo-Handling Machines at First Terminal

    Payra Port has added five modern cargo- and container-handling machines to the fleet of its first terminal in Kalapara, Patuakhali.

    Rear Admiral Syed Saiful Islam, chairman of the Payra Port Authority, said the new cranes bring the 650-metre multipurpose berth to full operational capacity while speeding up cargo handling and reducing ship turnaround times.

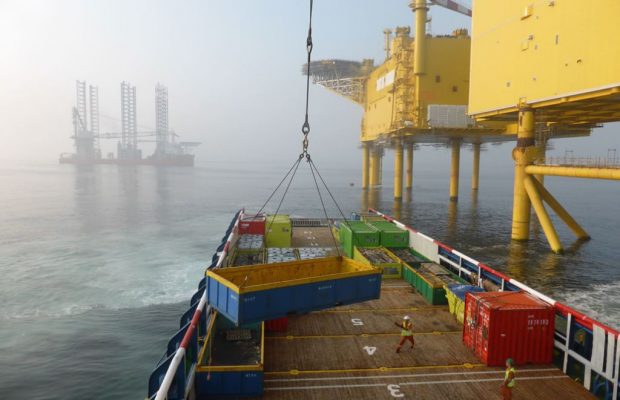
    The equipment arrived around 9 am today aboard the mother vessel Fan Zhou-6, marking the resumption of direct mother-vessel operations at the terminal jetty after nearly two years. Manufactured in China by Nanjing Port and Harbour Machinery Co and Xuzhou Construction Machinery Group, the shipment includes two 80-tonne ship-to-shore cranes, two 40-tonne rubber-tyred gantry cranes, and one 80-tonne mobile harbour crane.

    Equipment Specifications and Yard Roles

    Operations divide between vessel discharge and container yard management. Two ship-to-shore units will lift containers directly off arriving vessels. Rubber-tyred gantry cranes will transfer boxes to haulage trailers and manage yard stacking, according to Azizur Rahman, deputy director of the port’s traffic department.

    Bulk cargo and flexible lifting tasks will run through the 80-tonne mobile harbour crane. Port authorities designed this mix to eliminate discharge bottlenecks and reduce vessel laytime across the multipurpose berth.

    Chinese Machinery Shipment

    The delivery vessel completed a 19-day sea transit from Pingtan Port in China, departing on September 18 before docking directly at the terminal jetty. Captain SM Sharifur Rahman, harbour master at Payra Port, confirmed the 170-metre vessel arrived with an operating draft of approximately six metres.

    Direct berthing by a mother vessel of this length bypasses outer-anchorage lightering. That step often adds handling fees and transhipment delays for importers moving project cargo into Bangladesh.

    Multipurpose Berth and Vehicle Yard

    New crane installations complement landside storage infrastructure built to handle roll-on, roll-off operations and finished consumer goods. Rear Admiral Syed Saiful Islam, chairman of the Payra Port Authority, said a dedicated yard for imported vehicles is ready for service alongside the berth.

    Adding vehicle processing capacity allows the southern port to compete for finished automotive imports that traditionally enter Bangladesh through congested terminals at Chattogram and Mongla.

    Rabnabad Channel Dredging Targets

    Terminal efficiency now depends on maintaining water depth along the Rabnabad Channel. While smaller mother vessels can navigate the six-metre draft, deeper-draft container ships require consistent maintenance dredging to access the jetty without tidal restrictions.

    “Maintaining navigability will allow larger mother vessels to berth directly at the jetty,” he said.

    Direct calls at the terminal were previously limited to bulk mineral shipments. The port hosted the MV Zain on May 15, 2024, carrying 50,500 tonnes of stone, followed by the MV Da Hong-16 on November 1, 2024, with 48,511 tonnes of stone.

    Trial operations for the ship-to-shore cranes are now being scheduled as dredging programmes continue along the approach fairway.