Author: Mei Ling Tan

  • Australian Retail Spending Growth Slows to 4.9 per Cent Ahead of Peak Season

    Australian Retail Spending Growth Slows to 4.9 per Cent Ahead of Peak Season

    Australian retail spending grew 4.9 per cent in the year to September, slowing from 5.6 per cent in August as households cut back under persistent mortgage and living costs.

    Total retail trade reached $39.91 billion over the 12-month period, according to figures released by the Australian Retail Council. The drop in momentum comes just weeks before the critical Black Friday and Christmas trading window, which traditionally delivers the bulk of annual discretionary margins.

    Spending Splits Across Categories

    Pockets of non-discretionary and experiential spending held up while general merchandise stalled. Other retailing, covering pharmacies and cosmetics, climbed 8.1 per cent over the year, while cafes, restaurants, and takeaway food services rose 7.4 per cent.

    Discretionary categories showed sharp deceleration. Department stores and large online retailers recorded turnover growth of just 1.7 per cent, pointing to volume contraction once accounting for higher operating costs. Food retail turnover increased 3.3 per cent, running almost flat against the 3.2 per cent jump in food and non-alcoholic beverage prices measured in the September Consumer Price Index. The figure indicates that grocery growth reflected higher shelf prices rather than larger baskets.

    Margin Squeeze Ahead of Black Friday

    Weakening sentiment is already bleeding into register receipts across major shopping precincts. Consumer confidence fell sharply in September and slid again in October, leaving households with little appetite for full-price holiday shopping.

    The Reserve Bank of Australia compounded the pressure by lifting interest rates and downgrading its broader consumption forecasts. Central bank projections now anticipate consumption growth of 1.4 per cent for the years ending December and June, trimmed from an earlier 1.6 per cent forecast.

    “This weaker outlook, combined with yesterday’s interest rate increase, comes at a particularly difficult time for retailers, with Black Friday sales and the crucial Christmas trading period fast approaching,” said ARC chief economist Glenn Fahey.

    Price Restraint Limits Turnover Value

    Merchants face severe margin pressure as they discount stock to stimulate foot traffic. Clothing and footwear prices rose by just 0.4 per cent over the past year, while household equipment, furnishings, and services increased 0.8 per cent. Both categories trailed headline inflation of 4.3 per cent by a wide margin, demonstrating that stores swallowed cost increases rather than passing them on to shoppers.

    For regional supply chains and Asian consumer goods exporters exposed to the Australian market, these figures point to cautious reordering. Importers and local retail groups are keeping inventories tight to avoid forced clearance events in January.

    Attention now turns to preliminary November promotional volumes, where merchants will test whether heavy discounting can shake loose household savings before Christmas.
  • Nio Adds ES8 Special Edition in Guangzhou as Overall Deliveries Slip

    Nio Adds ES8 Special Edition in Guangzhou as Overall Deliveries Slip

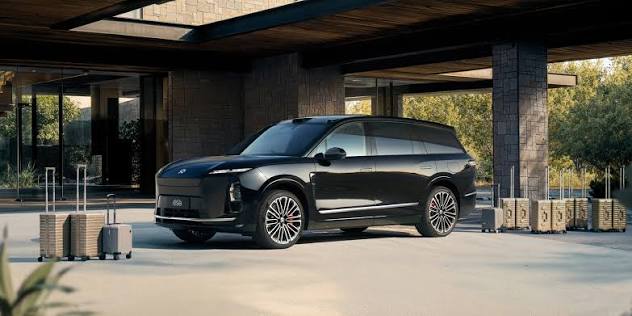
    Nio will introduce a special edition of its third-generation ES8 sport utility vehicle at the Guangzhou Auto Show on November 27, leaning on a model that drove half its brand sales in September.

    The current variant retails between 382,800 yuan ($57,010) and 446,800 yuan with a battery pack, or from 274,800 yuan under the company’s battery subscription service.

    Trade reports indicate the special edition will focus on visual tweaks and dedicated exterior colors rather than structural powertrain revisions. Technical specifications and final showroom pricing remain unannounced ahead of the exhibition opening at the Canton Fair Complex.

    Carrying the Core Brand

    The third-generation ES8 has delivered 160,000 units since customer handovers started on September 21, 2025. It took 33 days to log the final 10,000 units in that run, crossing the threshold on October 23.

    Volume peaked early in the year, hitting 17,658 units in January before settling into a steady pace through late summer. Deliveries reached 10,546 vehicles in September, accounting for 49.5 per cent of all cars sold under the main Nio badge.

    Showrooms currently stock five variants across five-, six-, and seven-seat cabin layouts. A five-seat configuration joined the lineup in July, followed by an optional package in September that bundled 22-inch forged wheels and gold-painted brake calipers.

    Delivery Run Breaks Under Pressure

    Product adjustments at the top of the catalogue arrive as group-level volume contracts across Chinese showrooms. Nio Inc delivered 34,246 vehicles across all its nameplates in October, falling 15.2 per cent from a year earlier and ending 31 straight months of annual expansion.

    Deliveries for the flagship Nio badge stood at 18,125 vehicles during the month, up 5.7 per cent year-on-year but down 15.0 per cent from September. Volume shortfalls at the mass-market Onvo division wiped out gains recorded by the primary marque and the smaller Firefly brand.

    That pressure leaves retail networks leaning heavily on top-tier metal to protect dealer cash flows and average selling prices. In September, the ES8 and the newer ES9 SUV combined to generate 85.6 per cent of all deliveries booked by the core brand.

    Defending High-Ticket Margins

    Automakers in China routinely deploy cosmetic packages late in a vehicle’s second year to defend pricing floors without rewriting list prices. Premium buyers respond to distinctive trim lines, allowing manufacturers to hold transaction values steady while rivals discount older stock.

    For Nio, the risk sits in product concentration. Squeezing incremental volume out of a single large chassis works only while wealthy urban households keep buying; it does nothing to fix showroom traffic across the broader, cheaper model lines.

    Showroom teams also face internal overlap. The ES9 delivered 7,706 units in September, carving out 36.2 per cent of brand volume and competing for the same multi-car family budgets that supported the ES8 throughout late 2025.

    A Crowded Trade in Guangzhou

    Nio claimed first place in retail sales for China’s large SUV category over the first ten months of the year, though it withheld specific October figures for the vehicle. The nameplate logged 10,705 units in November 2025 and 22,276 in December 2025, setting a high hurdle for year-end comparisons.

    Trade attention now turns to the Canton Fair Complex, where regional operators will gauge whether cosmetic trims can reverse the October slide. Guangzhou Auto Show runs through December 6, when order intake figures will show whether buyers still pay full price for the platform.

  • Bubs Revenue Drops 9.8% to $23.1M as Asian Market Delays Bite

    Bubs Revenue Drops 9.8% to $23.1M as Asian Market Delays Bite

    Bubs Australia booked a 9.8 per cent drop in quarterly net revenue to $23.1 million for the three months to September 30, hit by currency swings and stalled export markets across Asia.

    The Victoria-based infant formula producer burned through $6.0 million in operating cash during the period, leaving it with $13.4 million in available liquidity to fund inventory and marketing.

    Foreign Exchange Pressures Erode US Gains

    Revenue in the United States, Bubs’ largest regional market, dropped 8.9 per cent to $15.3 million. Management blamed foreign currency translation for the headline decline, which masked diverging retail channels across North America.

    Brick-and-mortar scan sales held up across major retailers. Sales through Walmart and Target grew strongly as distribution widened to more than 12,000 stores across all 50 states, but lower sales volumes on Amazon blunted those physical retail gains.

    Delays in Singapore and Vietnam Hit Regional Books

    Trading beyond the Pacific showed acute regional friction. Revenue from the Rest of the World division plunged 36 per cent to $1.2 million as planned market re-entries into Singapore and Vietnam ran into operational delays.

    China provided a modest buffer. Revenue from mainland buyers crept up to $2.6 million, giving the company small volume gains in an import market where rival dairy labels have written down excess inventory.

    The Tradeoff Behind America’s Permanent Authorisation

    Bubs gained permanent US Food and Drug Administration authorisation in September for three infant formula lines. That clears regulatory uncertainty that lingered after emergency pandemic-era supply waivers expired, giving the business a permanent footing against incumbent American brands.

    Yet chasing US market share carries clear capital risks for Asia-Pacific consumer operators. Supplying 12,000 North American storefronts locks up operating cash in long shipping lanes, and physical shelf space cannot cover the drop when digital orders on platforms like Amazon slip. Diverting corporate attention to satisfy Western regulators has clearly left flank markets in Southeast Asia vulnerable, stalling recovery timelines in key consumer hubs such as Vietnam.

    From Daigou Crash to Big Box Retail

    The quarterly slide traces the longer remaking of Bubs from an Australian domestic exporter into a Western big-box supplier. When cross-border daigou channels into China dried up, the business pivoted its goat milk and dairy infant nutrition inventory toward North American shortages.

    That strategy broadened its retailer network, but the margin profile now depends on continuous physical sell-through across massive US chains while local sales in Australia face lingering household budget pressures.

    Executive attention now turns to inventory replenishment and the commercial rollout of relaunched distribution runs in Vietnam, with full-year liquidity levels tied directly to how quickly Southeast Asian trade recovers.

  • Visy Produces First Glass Bottles at Yatala Recycling Plant

    Visy Produces First Glass Bottles at Yatala Recycling Plant

    Packaging company Visy has produced the first glass bottles at its new glass recycling and manufacturing facility in Yatala, Queensland, four years after construction began.

    Once fully operational, the plant will manufacture up to 1 billion glass bottles and jars annually, incorporating an average of 70 per cent recycled content.

    Visy CEO Mark De Wit noted the milestone following the start of commissioning of the site’s first of two oxygen-fuelled furnaces, which are designed to consume less energy than traditional facilities.

    Cutting Energy on the Furnace Line

    Engineers at the south Brisbane site started operations using the first of two oxygen-fuelled furnaces. Visy intends to bring the second furnace online as commissioning advances across the site.

    Conventional furnaces burn fuel using ambient air, which introduces unwanted atmospheric nitrogen into the heating chamber. Visy instead feeds concentrated oxygen into the combustion zone to trim nitrogen volumes and raise thermal efficiency.

    Incoming cullet undergoes pre-heating before entering the main melt zone. Lifting recycled glass temperatures ahead of melting cuts the thermal lift required from the burners, driving lower fuel use per tonne of finished glass.

    Clustering Supply Beside Big Brewers

    Putting glass production directly into Yatala links sorting, melting, forming, and packing inside an existing manufacturing cluster. The new site stands next to Visy’s established cardboard box factory and beverage can plant.

    Logistics dictate glass economics. The Yatala ovens sit roughly two kilometres from Asahi Beverages’ Yatala brewery and about 30 minutes by road from Lion’s XXXX brewery in Milton, removing cross-state container freight from local supply chains.

    The capital expenditure relies on long-term supply agreements. Asahi Beverages holds a foundational partnership on the site, alongside contracted volume commitments with Lion, Bundaberg, and Coca-Cola.

    Local Cullet and Container Scheme Feedstock

    Recycled container supply underpins the commercial rationale. The facility is engineered to process up to 200,000 tonnes of recovered Queensland glass each year, drawing heavily from regional container deposit collection points.

    For beverage manufacturers across Asia-Pacific, packaging remains a severe emissions liability. Securing commercial volumes with 70 percent recycled cullet gives regional bottlers an immediate mechanism to strip scope 3 emissions without changing primary bottle designs.

    The operational risk now centres on cullet purity and feedstock continuity. Contaminated recovered glass creates production defects and furnace downtime, forcing Visy to maintain tight control over sorting operations as intake scales toward the 200,000-tonne ceiling.

    Four Years of Build Lead to Commercial Output

    Construction crews broke ground on the Yatala development nearly four years ago, supporting roughly 600 construction roles during the installation of the heavy furnaces and forming machinery.

    The manufacturing complex will sustain approximately 200 permanent operational jobs once both production lines run at capacity, according to company projections.

    Visy now faces the commissioning of the second oxygen-fuelled furnace, which will lift production to the full 1-billion-unit target.

  • Black Milk Enters Voluntary Administration After 17 Years

    Black Milk Enters Voluntary Administration After 17 Years

    Brisbane-founded fashion brand Black Milk has entered voluntary administration 17 years after its launch, appointing Apex Advisory to oversee operations and explore a potential sale.

    Co-founder Linda Lillis confirmed that trading remains uninterrupted and all staff stay in place while administrators review the business.

    Established in 2009 by Linda Lillis and the late James Lillis, the online-first label grew around a devoted fanbase known as ‘Sharkies’ before mounting costs forced a restructuring.

    “Voluntary administration gives the business an opportunity to explore what comes next,” she added. “We don’t yet know what the outcome of that process will be, and I don’t want to make promises about something that is now in the hands of the administrators.”

    “What I can say is that entering administration does [not necessarily mean the end of Black Milk](https://insideretail.com.au/careers/blackmilks-ceo-on-the-importance-of-being-prepared-diligent-and-measured-202512), and we very much hope it isn’t.”

    The company said it is exploring a potential sale.

    Earlier this year, Black Milk faced backlash from its community when it closed the last of its manufacturing operations in Australia, offshoring the process to China and moving on from its ‘Made in Australia’ label.

    “Over the past few years, BlackMilk has undertaken significant change to respond to a very different retail environment and build a more sustainable business,” Lillis said. “The team has worked incredibly hard and made meaningful progress, but the combination of a challenging consumer environment, rising costs and increasingly complex global trading conditions has continued to place pressure on the business.”

    Lillis asked customers to respect Black Milk employees’ privacy. “They are processing this news themselves while continuing to pack your orders, answer your emails, and look after our customers,” she added. “The people behind Black Milk care deeply about this business, and they are facing uncertainty too.”

  • ChaHalo to Open Columbus Store in December Following Cleveland Launch

    ChaHalo to Open Columbus Store in December Following Cleveland Launch

    Chinese tea brand ChaHalo will open a storefront in Columbus in mid-December this year, marking its latest expansion into Central Ohio. Founded in Xi’an in 2016, the chain currently runs more than 1,000 stores in China alongside overseas outposts in the United Kingdom, Australia, and North America.

    The Columbus location follows an earlier retail announcement for a storefront in Cleveland. The company confirmed the expansion on Instagram, stating: “Hey Columbus! Something exciting is brewing! ChaHalo is coming to town, and we can’t wait to meet you.”

    ChaHalo disclosed via its Columbus storefront account that the new shop will be situated “near the Ohio State University,” though a specific street address was not provided. Known for pairing traditional Chinese teas and brewing methods with contemporary flavors, the group is now preparing the site for shoppers ahead of the holiday season.

    Midwestern college town strategy

    Entering Columbus exposes ChaHalo directly to a dense student demographic with high beverage consumption rates and an existing familiarity with Asian drink concepts. University corridors in the United States offer compact trade areas where young consumers generate steady weekday footfall, lowering the customer acquisition spend typical of suburban strip mall entries. The brand relies on strong visual merchandising and familiar tea pairings to draw domestic students while retaining overseas Chinese consumers who already know the chain.

    For independent beverage operators in Ohio, the arrival introduces competition backed by a massive domestic supply chain. Operators with hundreds of locations in China negotiate raw tea, dairy, and packaging contracts at volumes single-unit American businesses cannot match. The core risk for the brand sits in localized operating expenses, where US labor rates and real estate fit-out costs run substantially higher than in secondary Chinese cities.

    The march across Western markets

    Chinese tea chains have steadily accelerated outward expansion over recent years as home metropolitan markets hit saturation. ChaHalo started in Xi’an in 2016, building scale across regional domestic hubs before looking beyond mainland borders. Its cross-border expansion has pushed units into the United Kingdom and Australia, testing operating formulas against strict local health codes and fragmented supplier networks.

    The Columbus location follows an earlier retail commitment in northern Ohio, where the company announced plans for a Cleveland storefront. ChaHalo enters a competitive US drinks market where Asian beverage chains increasingly treat tertiary cities as viable expansion territory rather than relying solely on coastal hubs like New York or Los Angeles.

    Opening timeline and rollout

    The business expects to finish fitting out the Columbus space ahead of its planned launch in mid-December this year. Store staffing and local ingredient sourcing will determine opening speeds across both planned Ohio sites as ChaHalo tests Midwestern consumer retention.

  • Indian Telecom Carriers Face 5G Speeds Squeeze as Data Traffic Surges

    Indian Telecom Carriers Face 5G Speeds Squeeze as Data Traffic Surges

    Mobile subscribers in India are consuming an average of 31.1 gigabytes of cellular data each month, driving monthly mobile network traffic to 27.6 exabytes and squeezing real-world 5G connection speeds across major commercial centres.

    Monthly 5G volume climbed 70 per cent year over year to 12.9 exabytes, now accounting for 46.8 per cent of all cellular data traffic in the country, according to Nokia’s Mobile Broadband India Traffic Index 2026. Network capacity is falling behind that appetite. Even as carrier icons display 5G service on phone screens, users face sluggish response times and reduced throughput across shopping centres, transport hubs and high-density housing developments.

    Traffic Surges Overwhelm Local Cells

    Radio cells in major urban corridors now handle simultaneous demand for video streaming, cloud gaming, digital retail checkouts and video conferencing. When thousands of handsets connect to a single base station, available radio spectrum splits across those devices, causing local throughput to fall sharply regardless of advertised network capabilities.

    The Telecom Regulatory Authority of India reported that total wireless mobile data consumption reached 84,424 petabytes during the April to June quarter of 2026. That represents an 8.30 per cent quarter-on-quarter increase from 77,953 petabytes. Average monthly wireless data usage per subscriber rose 6.32 per cent to 28.39 gigabytes over the same period.

    Reliance Jio reported in its October 2026 financial disclosures that its user base included roughly 300 million 5G customers out of 542 million total connections. Individual monthly data usage on Jio’s network reached 44.2 gigabytes per subscriber, up from 38.7 gigabytes twelve months earlier. Handling that traffic volume demands constant radio densification and high-capacity backhaul lines.

    The Backhaul Bottleneck and Indoor Walls

    Carrier deployments show rapid physical additions, but transmission feeds from base stations to core networks frequently fall short. Fixed wireless access services have intensified that strain. Home broadband products such as Reliance Jio’s JioAirFiber and Bharti Airtel’s Xstream AirFiber now generate more than 25 per cent of all 5G data traffic in India, locking heavy continuous data streams onto cellular masts.

    Physical structural barriers compound the problem. High-frequency 5G radio signals, particularly mid-band 3.3 GHz frequencies, struggle to penetrate concrete walls, metallic cladding and coated window glass in indoor commercial venues. When indoor signal strength falls, base stations downgrade customer devices to more robust but slower transmission modulations, cutting download rates.

    Regulator drive tests conducted in July 2026 across Kolkata, Howrah and Hooghly logged 122 poor-signal samples for Airtel, 181 for Jio, 401 for Vodafone Idea and 3,904 for state-run BSNL across roughly 65,000 samples per operator along 309.7 kilometres of roadways and hotspots. Cellular operators rely on hardware vendors like Ericsson, Nokia, Samsung Networks and Mavenir for carrier aggregation and active antenna arrays, but equipment on towers cannot bypass missing fibre lines.

    Operator Speeds and Consumer Grievances

    Performance gaps between operators remain wide in field measurements. Testing conducted by nPerf across real users between April 2025 and March 2026 showed Bharti Airtel leading average download performance at 113.81 megabits per second, with an upload rate of 16.84 Mbps and latency of 58.98 milliseconds. Reliance Jio recorded 94.22 Mbps down, 8.97 Mbps up and latency of 62.09 milliseconds.

    Vodafone Idea trailed with average download speeds of 75.80 Mbps, higher upload speeds of 14.51 Mbps and elevated latency of 111.60 milliseconds. BSNL delivered 15.11 Mbps down and 5.45 Mbps up, reflecting its reliance on an indigenous 4G network deployed with TCS, Tejas Networks and C-DOT. State filings showed BSNL operated 95,511 active 4G sites out of 97,672 installed units as of January 15, 2026.

    Capital Allocation and Network Expansion

    Private operators have pursued diverging technical strategies to maintain performance. Reliance Jio built its standalone 5G network from the outset, whereas Bharti Airtel expanded via non-standalone 5G configurations while adding infrastructure. Airtel deployed more than 2,900 new 5G sites across Punjab, Haryana, Himachal Pradesh and Jammu and Kashmir over 12 months, covering 77 districts, alongside 2,750 sites in Gujarat.

    Vodafone Idea is executing a phased catch-up strategy. After servicing 43 cities across 17 priority circles, the company mapped out an expansion in March 2026 targeting 90 additional cities to reach 133 municipal markets. Network equipment suppliers including Nokia, Ericsson and Samsung have secured rollout contracts to modernize Vi’s physical gear, but spectrum density in residential districts remains thin.

    Retailers and mobile commerce operators rely directly on cellular network stability at the point of sale. Digital payments, dynamic in-store inventory tracking and rapid logistics fulfillment require low-latency cell handoffs that degraded 5G connections fail to deliver during peak foot-traffic hours. The pressure now shifts to municipal fibre approvals and small-cell indoor installations.

    The next major performance test will come as Vodafone Idea works to operationalize its expanded 133-city footprint.

  • Awinic Plans Controlling Stake in Yutai Semiconductor as Profit Drops 61%

    Awinic Plans Controlling Stake in Yutai Semiconductor as Profit Drops 61%

    Awinic Technologies suspended trading of its shares and convertible bonds on November 10 as it plans to buy a controlling stake in Yutai Semiconductor through shares and cash.

    The chip designer holds nearly CNY 3.783 billion in cash-like reserves, giving it the balance sheet capacity to fund a transaction that may constitute a major asset restructuring.

    Awinic plans to issue new shares, pay cash, and raise matching funds to secure all or part of the target business. Trading will halt for no more than 10 trading days. The four initial selling partnerships named in company filings are Shanghai Yubo, Shanghai Jinweili, Shanghai Yitiai, and Shanghai Yuzong. Together, Shanghai Yubo and Shanghai Jinweili hold a combined 38.43 percent of Yutai. No formal agreement is signed, and the final valuation and transaction ratio remain unset.

    The Sticking Point at SG Micro

    The deal immediately runs into an awkward structural problem. SG Micro, a direct competitor in analog chips, sits on Yutai’s register as the second-largest shareholder with a 25.95 percent holding. That stake gives SG Micro the use to either block a clean sweep or demand terms that alter the economics of the buyout. Awinic cannot absorb Yutai cleanly without addressing whether its chief domestic rival exits or stays embedded in the cap table.

    For hardware suppliers and brand procurement teams, consolidation among domestic analog suppliers reduces bargaining use. Phone makers and consumer gadget assemblers often rely on fragmented domestic chip shops to keep component costs low. If Awinic absorbs Yutai’s catalogue, buyers face a more consolidated supplier base across low-voltage and medium-voltage power lines. Competitors will watch whether SG Micro tenders its stock or uses its minority position to slow the integration.

    Balance Sheet Buffer Against Dropping Profits

    Awinic needs product diversification because its core consumer electronics business is stalling. In the first three quarters of 2026, the company posted revenue of CNY 2.117 billion, down 2.75 percent from the previous year. Net profit attributable to shareholders plunged 61.08 percent to CNY 107 million, while operating cash flow dropped 93.18 percent to CNY 22.66 million. Tight memory chip supply held back production schedules at smartphone factories, while mature-process foundry capacity squeezed gross margins.

    Cash reserves provide the only real protection for the buyer. Awinic entered October with CNY 703 million in monetary funds and CNY 3.08 billion in trading financial assets. Paying part of the acquisition in cash prevents excessive equity dilution at a time when Awinic’s valuation multiple is depressed by falling earnings. Issuing too much stock when net profit excluding non-recurring items fell 87.53 percent would trigger resistance from institutional investors.

    A Tortuous Path to Liquidity

    Yutai has tried and failed to reach the public markets twice before. SG Micro originally purchased 28.7 percent of the business for CNY 115 million in December 2018, before launching a CNY 1.07 billion bid for the remaining 71.3 percent in late 2019 that collapsed in October 2020. Yutai then filed for an independent listing on the STAR Market in 2022 to raise CNY 750 million for research and industrialization facilities, but the application stalled before tutoring restarted in 2023 without an outcome.

    Founded in November 2017 in Nantong by former Maxim Integrated designers, Yutai sells more than 500 power management products across 10 categories, including DC-DC converters, battery management chips, and interface protection circuits. Backers across four funding rounds include Transsion Holdings, SK Hynix Semiconductor (China), SMIC Capital, Longcheer Technology, and Leishi Investment. Its parts sell into smart meters, routers, power banks, and security cameras, giving Awinic a path beyond saturated smartphone sockets.

    Regulators and investors are now waiting for the restructuring framework before trading resumes at the end of the 10-day halt.

  • Swire Cuts Taikoo Place Office Rents 14 Percent

    Swire Cuts Taikoo Place Office Rents 14 Percent

    Swire Properties signed office leases at an average 14 percent discount to expiring rents across Taikoo Place, excluding its newest tower, in the first nine months of 2026, failing to catch Central’s rebound.

    The negative rental reversions covered 934,991 square feet of new and renewed tenancies through September, according to the developer’s quarterly operating statement released on Thursday.

    Occupancy across the established Quarry Bay portfolio edged up to 90 percent from 89 percent at the end of 2025. Two Taikoo Place, the one-million-square-foot tower opened in September 2022, remained stuck at 80 percent occupancy at the end of September. That figure was unchanged from June, though higher than the 73 percent recorded at the end of last year.

    Discounts Spread Across Island Portfolios

    Price cuts were not isolated to Hong Kong East. At Pacific Place in Admiralty, on the edge of Central, Swire recorded negative rental reversions of 12 percent through September, even as occupancy rose to 97 percent from 96 percent at year-end. In leasing terms, rental reversions track the rate difference between incoming leases and expired contracts rather than prevailing headline rates.

    Within Taikoo Place, One Island East and One Taikoo Place together logged negative reversions of 13 percent, with occupancy rising to 92 percent from 91 percent at the end of 2025. Other established towers across the Quarry Bay hub booked average reversions of negative 14 percent, with occupancy moving up a point to 89 percent.

    The landlord secured major commitments during the period, including a 200,000-square-foot renewal by BNP Paribas and a renewal and expansion to 83,000 square feet by Prudential Hong Kong. FWD also committed to 330,000 square feet for ten years. None of those deals prevented contract values from resetting lower.

    Central Pulls Divergent District Numbers

    The pricing drag highlights a sharp geographic split across Hong Kong commercial property. Across the city, Grade A office rents rose 0.7 percent in September from August, driven by a 1.6 percent increase in Central, based on JLL data. Citywide vacancy fell for a fifth straight month to 12.4 percent, the lowest level recorded since May 2023.

    Vacancy in Central fell to 7.2 percent in September from 7.8 percent in August. In Hong Kong East, vacancy widened to 14.3 percent from 14.1 percent.

    Agency figures from Knight Frank show Central net effective rents jumped 22.4 percent year on year in the third quarter. Quarry Bay rents dropped 4.4 percent over the same period, despite inching up 0.2 percent from the second quarter. The gap leaves decentralized landlords exposed to prolonged cash-flow drag while core financial district blocks take the initial tenant recovery.

    Retail Cash Flow Offsets Corporate Leases

    Swire found financial ballast in consumer spending. Across mainland China, tenant sales at Beijing’s Taikoo Li Sanlitun surged 59.8 percent year on year in the first nine months, reaching 100 percent occupancy. Sales at Shanghai’s HKRI Taikoo Hui climbed 52.6 percent, with occupancy at 97 percent.

    Taikoo Li Chengdu recorded an 11.3 percent sales gain, while Taikoo Li Qiantan in Shanghai rose 10.2 percent. Both developments stood at 98 percent occupancy at the end of September.

    Hong Kong retail assets also held firm. Pacific Place tenant sales grew 14.8 percent over the nine months, Citygate Outlets rose 14 percent, and Cityplaza gained 2.3 percent. All three shopping centres maintained 100 percent occupancy.

    Capital Recycling and Redevelopment Timeline

    Consumer gains are steering Swire toward Chinese public investment markets. The developer is actively reviewing domestic real estate investment trusts to unlock cash from mainland properties, with no specific seed assets or public listing timetable determined yet.

    Work also continues on its home turf. Swire and Chinachem Group have detailed a plan to build a 27-storey office tower by combining Swire’s Sea View Building and Hoi Wan Building sites with the adjacent Chinachem Exchange Square. The 35,000-square-foot combined site will support 500,000 square feet of gross floor area, including a retail podium, subject to planning approval.

    Swire and Chinachem scheduled construction to begin in 2027, with completion targeted for 2032. On the mainland, Swire secured an occupation permit for Phase A of CDF Taikoo Li Sanya in August and for the west parcel of Taikoo Place Beijing in September.

  • Indian Banks Lift Credit Loss Estimates as Bond Yields Complicate Transition

    Indian Banks Lift Credit Loss Estimates as Bond Yields Complicate Transition

    Indian banks are raising their expected credit loss estimates and bracing for investment book adjustments before a regulatory shift to forward-looking accounting takes effect on April 1, 2027.

    Canara Bank widened its estimated one-time transition requirement to between 12,000 crore and 15,000 crore rupees, up from an earlier range of 12,000 crore to 13,000 crore rupees calculated in July. Central Bank of India added roughly 500 crore rupees to its credit loss provisioning tally, while Bandhan Bank revised its one-time assessment to 2,200 crore rupees.

    The overhaul replaces the current incurred-loss provisioning model with an expected credit loss framework that forces institutions to account for potential loan defaults before repayments actually slip. Lenders must also mark their held-to-maturity investment portfolios to fair market value on March 31, 2027, absorbing the balance sheet difference through equity reserves.

    Yield Swings Strain Treasury Portfolios

    Government paper yields climbed steadily across the four months leading into late October, driving up paper losses for treasury desks holding large sovereign debt books. India’s benchmark 10-year government bond yield rose from about 6.75 per cent at the end of June to 7.18 per cent by late September, before touching nearly 7.50 per cent in late October. A 25-basis-point increase in the Reserve Bank of India repo rate, local currency weakness, firm crude oil costs and tight domestic cash liquidity drove the debt market selloff.

    Yields eased back to roughly 7.32 per cent on Monday following a pullback in global oil prices. Even with that rally, benchmark yields sat about 57 basis points above late-June marks, keeping portfolio markdowns elevated across state and private balance sheets.

    Lenders Detail Provisioning Gaps

    State-owned and private institutions face uneven hits depending on overdue balances and treasury allocations. Central Bank of India lifted its projected credit loss provision to a band of 5,000 crore to 5,500 crore rupees, compared with 4,500 crore to 5,000 crore rupees projected in July. The bank has already parked 1,525 crore rupees as an advance buffer against the shift.

    Indian Bank calculated its expected credit loss provision at approximately 3,500 crore rupees and has set aside 2,500 crore rupees so far. The lender has not disclosed the mark-to-market impact of its held-to-maturity securities.

    Bandhan Bank’s 2,200 crore rupee estimate represents a sharp increase from an initial 1,250 crore rupee estimate compiled several quarters earlier. Management calculated the latest sum on its loan book as of March 2026, though recoveries in overdue retail and microfinance accounts could lower the final balance before implementation.

    Private Lenders Measure Capital Buffers

    Large private institutions project a narrower capital hit relative to their total balance sheets. Kotak Mahindra Bank calculated its one-time credit loss transition requirement at less than 2 per cent of net worth. Federal Bank expects its transition cost to fall between 1.5 per cent and 2 per cent of net worth.

    Canara Bank faces an additional balance sheet drag from debt markets outside its loan provision line. Managing director and chief executive Brajesh Kumar Singh confirmed the scale of that exposure during the bank’s September quarter earnings review.

    “HTM will be also mark-to-market. So that will affect us by ₹2,000-3,000 crore,”

    Singh said.

    Capital Allocation Shifts Across Commercial Credit

    For corporate borrowers, retail chains and institutional investors across Asia, the revised accounting timeline changes how Indian lenders price risk and deploy balance-sheet capacity over the next two fiscal years. Stricter provisioning rules penalize delayed stress recognition, which forces credit committees to demand wider spreads or tighter collateral from mid-tier retail operators and commercial landlords seeking term loans. Banks absorbing large mark-to-market hits on sovereign holdings will also have less surplus capital to support aggressive corporate credit expansion.

    The transition introduces friction between public sector lenders and private peers. State-backed banks carry heavier concentrations of sovereign paper and legacy assets, requiring larger equity set-asides than private institutions that entered the cycle with lower portfolio durations and stronger net-worth coverage.

    The Reserve Bank of India laid the groundwork for the expected credit loss framework following global adoption of IFRS 9 standards, giving lenders time to build internal default probability models. Banks have spent recent quarters modeling historical recovery rates and setting aside voluntary buffers during periods of strong net interest income.

    Attention now turns to March 31, 2027, when lenders must take their final held-to-maturity fair-value readings against prevailing bond yields before opening their books under the new credit loss regime the following morning.

  • Karachi Port Lifts Cargo Traffic to 19.3 Million Tonnes

    Karachi Port Lifts Cargo Traffic to 19.3 Million Tonnes

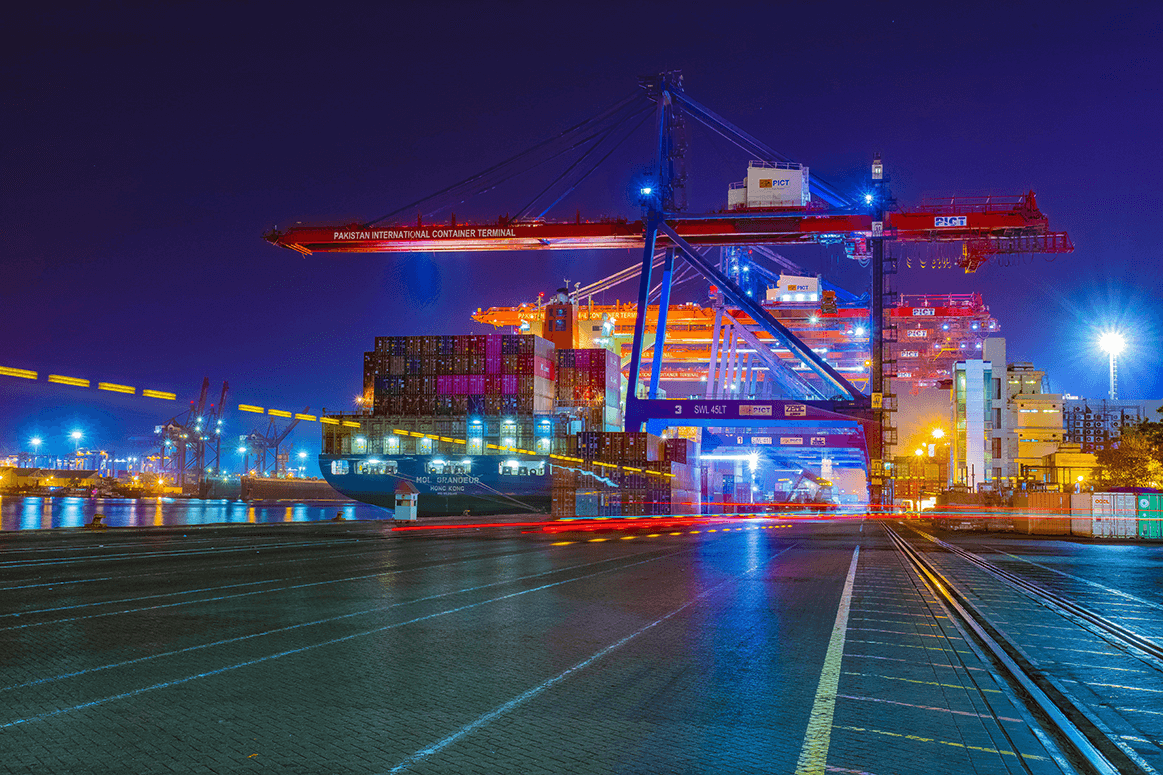
    Karachi Port handled 19.286 million tonnes of cargo between July and October 2026, lifting throughput 3.8 per cent as shipping lines rerouted vessels away from Middle East disruptions.

    Total ship calls climbed 13.7 per cent to 764 vessels during the four-month window, up from 672 calls a year earlier.

    Export cargo rose 10.5 per cent, while dry bulk volumes jumped 26.1 per cent across the same period. The gains follow fiscal year 2025-26, when terminal operators processed an all-time peak of 55.438 million tonnes, handled 2.749 million 20-foot equivalent units and berthed more than 2,100 vessels.

    Fee Cuts and Free Storage

    Commercial incentives drove the shift. Federal authorities rolled out a unified transshipment framework in August 2026 that lowered wet cargo vessel tariffs by 20 to 80 per cent and gave shippers 14 days of free terminal storage at Karachi Port Trust facilities.

    Port Qasim Authority waived wharfage completely and expanded free storage to between 7 and 21 days. Terminal concessions followed quickly.

    Four private container handlers, Karachi International Container Terminal, South Asia Pakistan Terminal, Karachi Gateway Terminal Limited and Qasim International Container Terminal, reduced terminal handling charges by up to 25 per cent.

    Customs agencies also opened the gates to off-dock transshipment, sea-to-air cargo transfers, around-the-clock physical checks and pre-arrival paperwork to clear quayside bottlenecks.

    Direct European and Gulf Links

    Global carriers responded by adding direct tonnage. Mediterranean Shipping Company opened a weekly direct European loop called Premium IPAK through Karachi Gateway Terminal Limited in October 2026.

    A dedicated feeder run connects Karachi directly to Khor Fakkan in the United Arab Emirates. These links bypass congested regional transfer hubs and cut transit days for consumer goods entering and leaving South Asia.

    Connectivity scores tracked the added routes. Karachi Port gained 30 spots to place 69th on the Container Port Performance Index for 2025, while its Port Liner Shipping Connectivity score climbed from 309 in the first quarter of 2026 to 357 in the third quarter.

    The Logistics Bottleneck Outside the Gate

    Terminal efficiency alone does not protect supply chains if cargo stalls on city streets. Retailers and manufacturers moving freight into northern Pakistan face crumbling municipal roadways between terminal gates and national transport corridors.

    Karachi Port Trust delivers 12 billion rupees annually in federal taxes and 5 billion rupees to Sindh province, while provincial authorities collect 160 billion rupees through the Sindh Infrastructure Development Cess on seaborne goods. Yet freight corridors linking maritime docks to inland distribution hubs remain heavily congested, inflating drayage fees and stretching inventory holding costs for importers.

    The maritime trust wants provincial administrators to allocate 50 per cent of provincial cess receipts straight into access road repairs. Without quick road fixes, transit gains made at berths evaporate once containers clear the main gates.

    Reforms After Red Sea Shifts

    Government initiatives began taking shape in March 2025 with targeted tariff reductions and cargo discounts designed to draw mainline vessels skipping high-risk waterways. The country later climbed to 34th place on the global Liner Shipping Connectivity Index, up from 35th.

    Long-stay auction containers were shifted out of primary yards to secondary off-dock facilities, clearing physical ground for transshipment boxes. The country also secured removal from Lloyd’s war-risk list, lowering marine insurance surcharges for commercial fleet owners.

    Contractors will finish capital dredging across the main Karachi Port navigation channel by December 2026 to clear access for deeper-draft mother vessels. Commercial managers are also tendering 250 acres for fresh terminal buildouts alongside 140 acres earmarked for an integrated marine commercial district.

  • Goldfield & Banks Opens First Standalone Boutique in Sydney’s Strand Arcade

    Goldfield & Banks Opens First Standalone Boutique in Sydney’s Strand Arcade

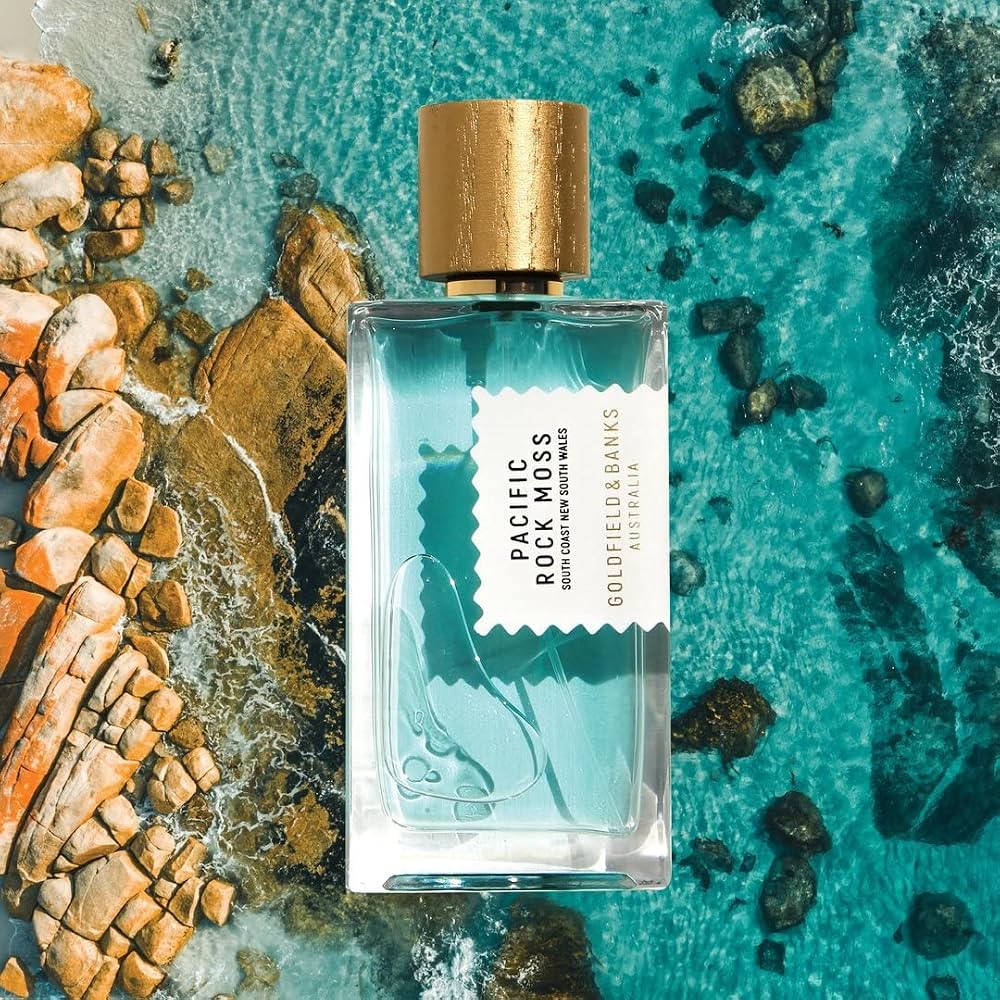
    Goldfield & Banks will open its first flagship boutique in Sydney’s Strand Arcade this December, establishing dedicated brick-and-mortar retail after expanding wholesale distribution across more than 80 countries.

    Founded in Sydney in 2016, the luxury fragrance house enters physical direct-to-consumer store operations on its tenth anniversary, after relying primarily on wholesale distribution through department stores including Harrods, Selfridges and Saks.

    The Strand Arcade Deployment

    The boutique will show the brand’s full fragrance portfolio within a physical format designed alongside Australian interior designer Brahman Perera. The company partnered with its domestic distributor, Prestige Brands Australia, to execute the retail rollout.

    Founder Dimitri Weber said the upcoming opening in Sydney is a “dream come true”.

    “To now have a permanent home in the Strand Arcade, one of Sydney’s most iconic destinations, feels very special. It’s a celebration of everything we’ve achieved over the past decade and an exciting new chapter.”

    The design plan departs from standard department store concessions by deploying native materials, light treatments and tailored display formats. Weber structured the boutique to function as an immersive brand destination rather than a transactional counter.

    Wholesale Transition to Owned Retail

    Niche fragrance brands across Asia-Pacific face rising wholesale customer acquisition costs and tighter shelf allocations in major department store channels. Shifting from multibrand stockists to single-brand boutiques gives independent perfumers direct access to shopper transaction data, higher gross margins per bottle, and complete pricing control.

    For arcade landlords in mature central business districts, boutique perfumeries provide reliable sales densities across compact square footage. Fragrance purchases carry high average order values and minimal stock space requirements compared to apparel tenants.

    Retail Footprint and Distribution Lineage

    Weber started Goldfield & Banks around botanical ingredients native to Australia, directing early distribution into overseas luxury channels before consolidating domestic footprint. The international export track built brand equity in department stores, generating inbound demand from international travellers returning to Sydney.

    Prestige Brands Australia will support the operational handling of the Strand Arcade location as the brand tests standalone retail economics. The store opening in December tests whether independent domestic luxury labels can sustain prime shopping arcade leases on dedicated fragrance sales alone.

  • Givaudan Targets GLP-1 Consumer Spending Shift Toward Beauty

    Givaudan Targets GLP-1 Consumer Spending Shift Toward Beauty

    Givaudan is revamping product development across its beauty and fragrance divisions as weight loss treatments reshape consumer budgets, tracked by 15 generic semaglutide brands entering India since patent expirations began. The ingredient supplier found adult adoption of GLP-1 therapies in the US climbed from 3 per cent in 2024 to 11 per cent in 2026, triggering direct reallocation of discretionary spending.

    Data compiled by the manufacturer from a NielsenIQ Homescan panel revealed American households using the medications increased spending on fine fragrances by 97 per cent while cutting grocery budgets. In Brazil, 47 per cent of buyers reported trimming other expenses specifically to finance treatment doses, signaling a widespread behavioral reallocation away from food toward personal grooming, sports, and travel.

    India Generics Drive Rapid Market Expansion

    Price reductions and the loss of patent exclusivity in markets such as India have dismantled entry barriers for metabolic therapies. The introduction of 15 domestic brands following patent expiries expanded regional supply rapidly, lowering therapy costs and broadening usage beyond narrow clinical segments.

    Lower retail prices combined with the development of oral alternatives to subcutaneous injections are speeding up adoption across emerging economies. For personal care brands operating in Asia, this shift alters the customer base faster than anticipated. Product developers must adjust formulas for consumers managing the physiological consequences of rapid weight reduction.

    Formulations Adapt to Side Effects

    Patients experience specific physiological issues that prompt new topical requirements, notably loss of facial volume, loose skin, barrier dryness, temporary hair thinning, and bad breath. Consumers navigating these side effects prioritize demonstrable performance over brand prestige, checking active concentrations and clinical validation closely.

    Buyers demand formulas that combine medical-grade efficacy with sensory textures. Frédéric Merlin, manager of the Givaudan Digital Factory in Paris, stated: “Faced with these very real concerns, consumers are becoming more demanding: they seek out the right actives, compare concentrations, and check the evidence behind efficacy claims. But they are unwilling to choose between performance and pleasure. They expect visible results, sensorial textures, and an enjoyable experience. Whereas a brand’s reputation may once have been enough to win them over, it is now the efficacy promise, backed by evidence, that makes the difference.”

    Scent Profiles Reflect Appetite Changes

    Social listening data gathered by Givaudan identified two dominant fragrance profiles among treatment users: gourmand compositions and crisp, fresh notes. Appetite suppression does not eliminate interest in rich food-inspired aromas, although nausea risks create sharp aversions to heavy notes, requiring finer calibration by perfumers.

    Energy dips and sleep disruptions linked to these therapies have opened room for functional scents. Givaudan is deploying its patented MoodScentz and DreamScentz platforms, pitching neuro-olfactive formulations that stimulate alertness in the morning or support disrupted sleep cycles at night.

    Digital Factory Tests Commercial Concepts

    The company developed an exhibition format called The New Desire at its Paris Digital Factory, built around an artificial intelligence persona named Nathalie to model shifting habits. Brand teams examine over 120 global product rollouts and generate concept packaging tested against simulated consumer feedback.

    Corporate clients have booked repeat sessions at the facility, prompting an operational extension of the program. Fast-moving consumer goods suppliers across the Asia-Pacific region now face parallel realignments on retail shelves: packaged food volumes face headwinds, while functional personal care and premium fragrances capture liberated wallet share.

    Givaudan plans to publish its next wave of field research on GLP-1 olfactory preferences before the end of 2026.

  • Songzio and Egonlab Debut Military-Inspired Collection Online

    Songzio and Egonlab Debut Military-Inspired Collection Online

    South Korean fashion house Songzio launched a collaborative apparel collection with Paris-based label Egonlab online on Monday, drawing on historical French military silhouettes across outerwear and tailoring.

    The capsule, titled “The Art of Dark Poetry,” follows about eight months of the teams working together, after finding common ground in the Paris design scene.

    Physical retail rollouts accompany the digital release. Songzio hosts an opening presentation at its Seoul flagship store on Wednesday, followed by a European retail show scheduled for Dec. 3 at its boutique in the Marais district of Paris.

    Sculptural Tailoring and Military Reworks

    The collection focuses on structured forms, contrasting Songzio’s architectural garment construction with Egonlab’s romantic detailing. Garments feature exaggerated shoulder padding, cinched waists, lengthened officer coats, and wider cavalry jackets.

    Traditional military uniform fixtures appear throughout the line in shifted placements. Rather than designating status or rank on shoulders and chests, elements such as frogging, soutache embroidery, braids, and decorative cord work sit across trouser legs and outer seams.

    Songzio creative director and chief executive officer Jay Song explained the creative tension behind the project.

    “Rather than compromising those identities, we wanted to challenge one another and create something that neither house could have achieved independently,” he said.

    Cross-Border Retail Positioning

    For South Korean luxury houses, collaborative releases with European independent labels serve as a vehicle to test customer demand outside domestic department stores. Songzio has run dedicated runway shows on the official Paris calendar while preserving its flagship footprint in Seoul.

    Independent labels face elevated production costs when combining bespoke tailoring components like soutache braiding with low-volume runs. By coordinating simultaneous launches across domestic and European company stores, both brands split developmental exposure while pooling customer bases across two distinct high-end shopping hubs.

    Building Presence in the Marais

    The Paris flagship in the Marais has served as Songzio’s primary distribution beachhead in continental Europe. That physical footprint anchors the French leg of the collaboration, giving the Korean house direct commercial access to Parisian foot traffic during the winter retail corridor.

    Egonlab gains reciprocal physical visibility inside the Korean capital, where local shoppers drive high sales volumes for imported independent menswear. The joint effort tests whether avant-garde design crossover can convert into sustained international wholesale interest.

    Attention shifts to in-store sell-through rates at the Seoul flagship on Wednesday before retail inventory reaches the Marais location on Dec. 3.

  • Bill Wavish Rescues Cue Clothing After 31 Store Closures

    Bill Wavish Rescues Cue Clothing After 31 Store Closures

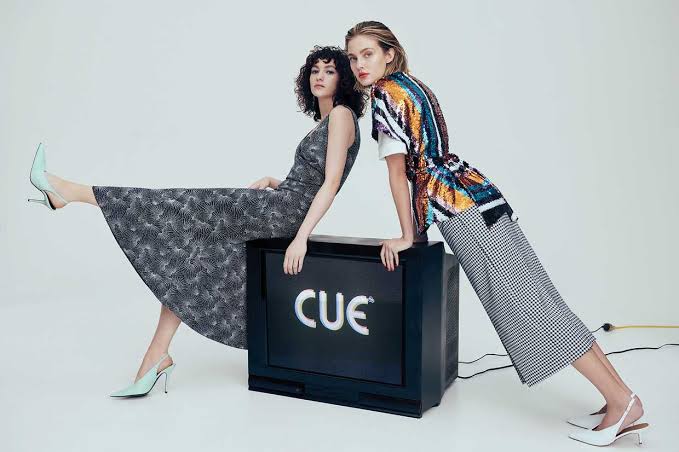
    Former Myer executive chairman Bill Wavish has acquired collapsed Australian fashion retailer Cue Clothing Co, pulling the 60-year-old apparel group out of receivership after administrators shut down more than half of its retail network.

    The purchase gives the veteran retail leader control of both the Cue label and sister brand Veronika Maine, concluding an insolvency process that reduced the business from 51 retail locations to just 20 doors.

    Investment firm Hilco Capital placed the business into administration and receivership in September after a one-month sales campaign failed to secure a buyer, leaving receivers from FTI Consulting to manage operations amid “insufficient sales”.

    How the Receivership Unfolded

    Hilco Capital initiated the insolvency proceedings after private sale efforts stalled. Receivers from FTI Consulting took charge of the operating business as customer traffic softened and sales failed to cover overheads.

    The company suffered severe executive departures during Hilco Capital’s one-month sales campaign, losing both its chief executive officer and chief financial officer. FTI Consulting kept the registers running at a rump of viable locations while looking for bidders with the balance sheet to take on long leases.

    Store closures came swiftly. In mid-October, receivers confirmed the shuttering of 26 locations across the country, cutting lease obligations and staff rosters to stop operating losses while negotiations continued.

    Rival Bidders and Family Ties

    Wavish, who led department store chain Myer as executive chairman ahead of its listing on the Australian Securities Exchange, stepped in to beat competing interest from fashion brand operator Brand Collective. Justin Levis, son of Cue founder Rod Levis, had also pursued the assets during the bidding process.

    The transaction returns the company to an executive closely connected to its originators. Wavish is a long-standing personal friend of Rod Levis, who started the fashion group six decades ago and built it into an anchor apparel tenant across prime Australian shopping strips and department store concessions.

    Turnaround duties now fall directly on Wavish, whose background spans department store merchandise overhauls and grocery operations. Reviving the label will require stocking floors that consumers abandoned for cheaper online imports and premium specialty brands.

    What the Balance Sheet Carries

    Cue produced top-line gains in the financial year prior to its collapse, but the margin was too thin to survive modern rental structures. Revenue rose from $98 million in fiscal 2024 to $103.2 million in fiscal 2025.

    Net losses narrowed from $14.1 million down to $5.1 million over the same period. That operating improvement proved too slow when rising store wages, softer discretionary foot traffic, and mounting finance charges squeezed liquidity at the end of winter.

    For shopping centre landlords and apparel suppliers throughout the region, the deal stops an outright liquidation. A network of 20 profitable doors offers a cleaner base for wholesale partners and garment makers than the legacy network, which carried too many underperforming leases signed before post-pandemic office patterns altered corporate workwear demand.

    The Preceding Collapse

    Hilco Capital’s ownership ended abruptly when it became clear the label could not fund its working capital requirements into the spring selling season. The private equity backer pulled support after internal cost cuts failed to outpace declining sales volumes.

    Trade creditors and property groups watched the rapid wind-down over September and October as administrators cut non-performing concessions and standalone shops. Without immediate scale, regional apparel labels have struggled to match the sourcing power and digital logistics of global fast-fashion platforms.

    Formal transfer of the trading entity and any restructured lease terms between Wavish and shopping centre landlords across the remaining 20 doors will determine how quickly fresh inventory reaches store shelves for the summer season.