Category: Automotive

Retail News Asia is committed to providing both local and global retailers with the latest Auto and Car news throughout the Asian market. This on a daily base.

  • Xpeng Consolidates 4 Product Lines into 2 to Cut R&D Costs

    Xpeng Consolidates 4 Product Lines into 2 to Cut R&D Costs

    Xpeng has consolidated its four product lines into two to focus research and development resources and reduce costs, media outlet 36Kr reported on Monday.

    The Chinese electric vehicle maker merged its I and F product lines into the G line, leaving only the G and D lines in place.

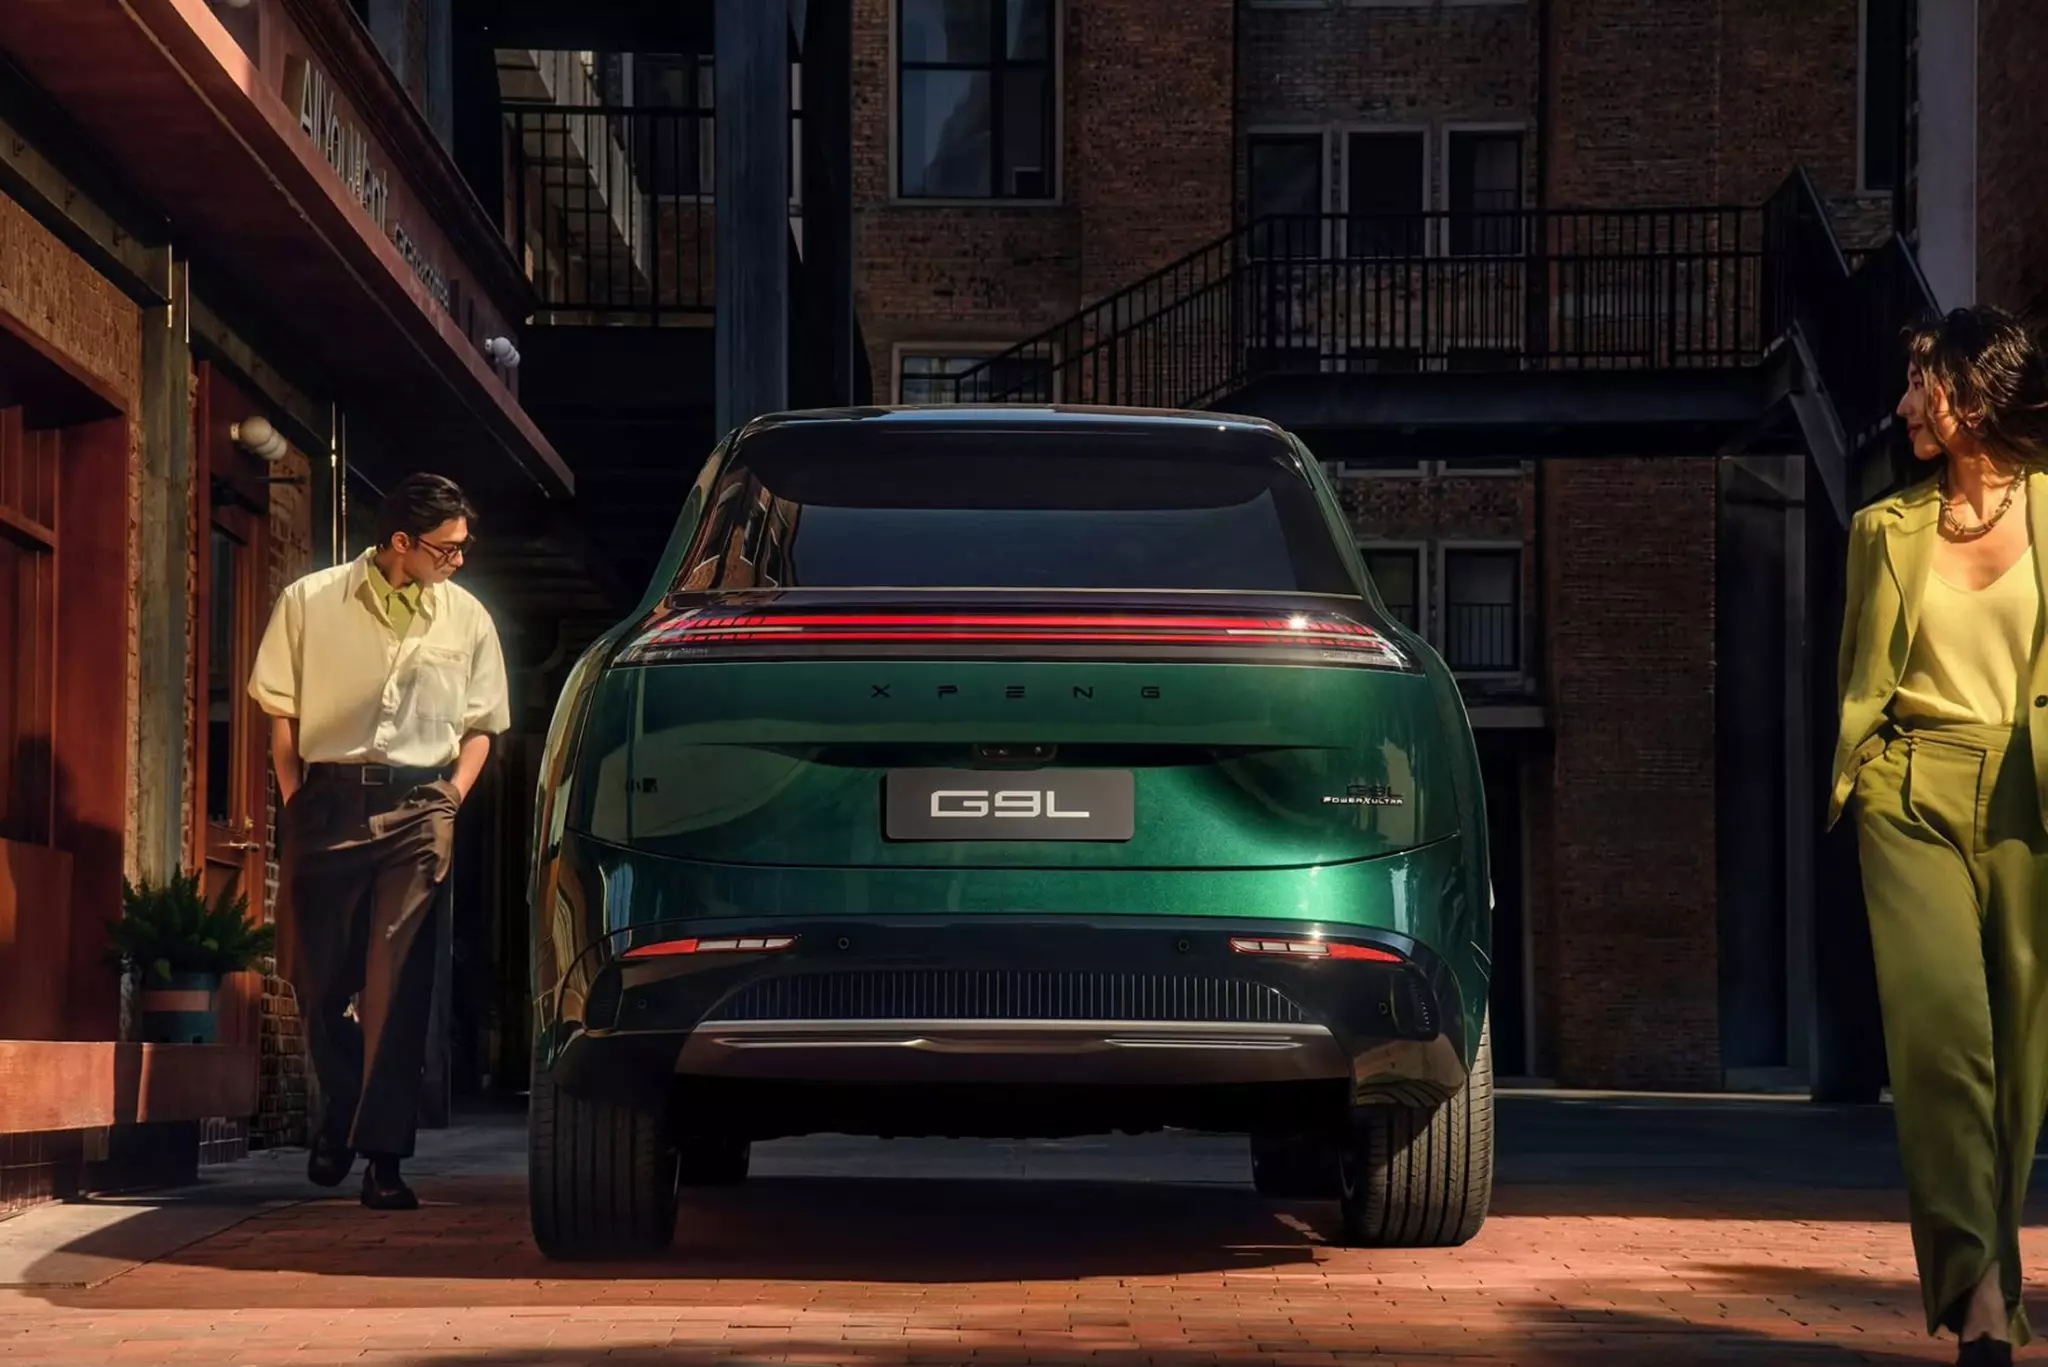
    Following the restructuring, the Mona series remains under the D line, while large SUVs including the GX and G9L and P-series sedans fall under the G line. The former head of the F line now oversees product definition for the G line, while the former head of the I line shifted to overseeing overseas affairs.

    Reining in Development Overlap

    Engineering teams previously built vehicles across separate tracks that competed for the same laboratory testing slots, supplier contracts, and software integration cycles. Merging the lines eliminates duplicate vehicle architectures and limits internal pricing clashes between sedans and crossovers that share identical wheelbases.

    For automotive component suppliers across the Pearl River Delta, fewer product lines mean consolidated purchase orders and standardized component tooling. Investors have pushed for tighter capital controls as Chinese electric vehicle makers face aggressive domestic price cutting and slowing volume gains across the mid-market bracket.

    R&D Outpaces Delivery Growth

    Development costs rose 32.1 per cent year on year to 2.91 billion yuan ($431.8 million) in the second quarter, driven by autonomous driving software, foundation AI models, and platform engineering. Vehicle deliveries in the same quarter stood at 103,295 units, up 0.1 per cent from the previous year.

    Second-quarter net loss widened to 1.34 billion yuan from 480 million yuan a year earlier, though it improved from the 1.78 billion yuan loss recorded in the first quarter. Vehicle gross margin reached 12.1 per cent, down from 14.3 per cent a year earlier due to production changeovers, while overall company gross margin stood at 20.7 per cent with support from technical service revenue.

    Model Cadence Across Two Tracks

    The restructuring aligns vehicle programs ahead of several fourth-quarter rollouts designed to lift monthly volumes. Xpeng introduced its G9L five-seat SUV on September 17 to complement its six-seat GX, targeting family buyers who previously looked at rival offerings from Li Auto and Nio.

    Volume pressure now rests heavily on the Mona product unit. Deliveries of the Mona M03 sedan began in July, while the Mona L05 crossover enters the Chinese market before the end of the year.

    Factory Commitments and Fourth-Quarter Targets

    Management is targeting monthly deliveries above 60,000 units in the fourth quarter, a 53 per cent jump from the 39,107 vehicles handed over to customers in August. Reaching that pace requires the Guangzhou and Zhaoqing assembly plants to operate near full capacity through December.

    Parallel investments in non-automotive hardware remain active. Xpeng commissioned its Iron humanoid robot manufacturing line earlier in September, targeting commercial deployment across its retail showrooms by the end of 2026 before starting customer deliveries in 2027.
  • BYD Pushes European Production as Sales Reach 4.27 Million Units

    BYD Pushes European Production as Sales Reach 4.27 Million Units

    BYD delivered 4.27 million new energy vehicles last year, expanding its European footprint. The surge steps up competitive pressure on German automakers across their core regional markets.

    Total sales for 2024 rose 41 percent over the previous year. That growth gives the Shenzhen-based automaker added scale as it builds its first European assembly facility.

    Bypassing Tariffs in Hungary

    Construction is underway on a passenger car plant in Szeged, Hungary. Vehicles assembled there will be built inside the European Union rather than shipped from Chinese ports.

    Local assembly lets the carmaker bypass additional tariffs the European Commission imposed on battery electric vehicles imported from China. The Commission determined in 2024 that Chinese state subsidies harmed European producers, introducing penalties to offset pricing differences.

    The Szeged plant will create thousands of local jobs and source components through regional supply chains, establishing a domestic European operating base.

    Pressure on German Brands

    German automotive groups face mounting headwinds across their volume and luxury segments. Volkswagen, BMW and Mercedes-Benz built their global market presence on engineering standards and brand prestige, supported by specialist badges including Audi and Porsche.

    Sluggish domestic economic growth, persistent inflation and supply chain friction now squeeze profit margins across German operations. Lower production costs and rapid development cycles from Chinese competitors directly challenge those legacy advantages.

    Pricing pressure in electric passenger cars leaves legacy European manufacturers with narrow operating margins. Chinese competitors produce battery packs and vehicle software internally, cutting component costs below what German supply networks currently deliver.

    Policy and Market Headwinds

    Trade barriers alone offer limited protection for European carmakers once overseas competitors start manufacturing inside the trade bloc. European manufacturers must match competitive vehicle prices while investing heavily in software architecture and battery chemistry.

    The European Commission outlined these structural vulnerabilities in its 2025 automotive action plan. The report warned that European automakers risk falling behind international rivals in battery development, vehicle software systems and autonomous driving platforms.

    Brussels now pairs import duties with domestic manufacturing incentives. Factory investments by Chinese firms inside the trade bloc weaken that intended barrier.

    Expansion from 2022 Entry

    BYD formally entered the European passenger car market in 2022 before committing capital to the Hungarian production site. Economists compare the broader shift to the manufacturing trade integration seen after China joined the World Trade Organization in December 2001.

    German automakers must now defend market share across both electric sedans and compact sport utility vehicles as local assembly begins. The decisive metric will be the production start date at the Szeged plant and the final retail pricing of its Hungary-built models.

  • Geely Buys 30 per Cent Stake in Nio Power for 16 Billion Yuan Valuation

    Geely Buys 30 per Cent Stake in Nio Power for 16 Billion Yuan Valuation

    Geely Holding Group will acquire a 30 per cent stake in Nio Power by injecting its commercial battery swap unit and 640 million yuan in cash. The transaction values Nio Inc’s energy arm at roughly 16 billion yuan ($2.37 billion) on a post-money basis.

    Nio China will retain management control of the subsidiary with a 63.6 per cent holding upon closing, according to a filing submitted to the Hong Kong Stock Exchange. Wuhan Guangchuang Emerging Technology Phase I Venture Capital Fund Partnership, which injected capital in May 2024, will hold the remaining 6.4 per cent.

    Terms of the capital tie-up

    Under the definitive agreement, Geely transfers the entire equity interest in its fleet battery swap operator, Yiyi Power, alongside 640 million yuan ($94.8 million) in cash to subscribe for new shares in Nio Power. The cash and operational assets consolidate Geely’s commercial mobility swap business directly into Nio’s broader infrastructure network.

    Geely’s ultimate equity percentage remains subject to post-closing adjustments tied to operational milestones. If performance falls short of agreed metrics, the holding will decrease, though contracts specify a floor of 20 per cent.

    Geely also secured an option to inject a further 640 million yuan in cash. Exercising that option would increase Geely’s stake to 34 per cent and dilute Nio China’s holding to 60 per cent, provided it is executed within two years of closing or prior to any subsequent financing round.

    Cross-investing in charging networks

    The transaction includes a reciprocal capital link on the fast-charging side. Nio China agreed to subscribe in cash for newly issued equity in Geely’s Zhejiang Haohan Energy Technology, securing a 10 per cent stake upon completion.

    Haohan Energy will allocate the proceeds to purchase selected charging assets directly from Nio. The companies did not disclose the cash consideration for the Haohan shares, which remains subject to regulatory review and closing approvals.

    Both operators plan to bridge their charging hardware and apps across mainland China to increase station utilisation. Combining these operations links two of the country’s most active proprietary charging operators behind a common access layer.

    Commercial fleet and consumer standards

    Absorbing Yiyi Power hands Nio Power immediate scale in commercial mobility fleets, a sector where high daily mileage makes rapid turnaround critical. Passenger car standardisation presents a tougher road. Geely agreed to develop consumer EV models compatible with Nio swap stations, but Nio noted in its exchange filing that passenger vehicle integration plans remain preliminary and require further negotiations.

    For hardware suppliers and energy grid operators, consolidating these two proprietary swap architectures reduces the risk of stranded assets in China’s secondary cities. Standardised battery packs and shared stations lower per-site capital expenditure, shifting competitive pressure directly onto rival automakers relying solely on ultra-fast plug-in chargers.

    Earlier agreements and buildout targets

    Cooperation between the two groups began in November 2023 with an initial battery swap pact, followed by an interoperability agreement for EV charging points signed in March 2024. Nio Power was established in Wuhan in May 2017 as a wholly owned entity before bringing in outside funds through a 1.5 billion yuan round from Wuhan Guangchuang in 2024.

    The combined business now faces aggressive infrastructure deadlines. Nio Power aims to run 10,000 battery swap stations across China by 2030, projecting annual electricity demand through its footprint will exceed 10 billion kilowatt-hours. Geely is building toward a network of more than 22,000 charging stations and 100,000 charging connectors before the end of 2027.

  • US and China Agree to $30 Billion Tariff Relief as Chinese EVs Eye Entry

    US and China Agree to $30 Billion Tariff Relief as Chinese EVs Eye Entry

    Chinese electric vehicle makers plan to enter the United States market despite bilateral trade talks in Washington on Thursday and Friday concluding without a breakthrough agreement on automotive import access.

    High vehicle prices and sustained inflation in the American domestic market keep Chinese automakers focused on entry routes even after negotiators limited bilateral tariff relief to 30 billion dollars of non-sensitive goods for each country.

    Export Volumes Drive Overseas Push

    Automakers in China are accelerating their export strategies as domestic competition reaches a consolidation point. BYD set a target of 2 million overseas sales in 2026, building on vehicle sales momentum across Brazil and Europe.

    Rising vehicle retail prices and fuel expenses in North America provide commercial incentives for Chinese manufacturers. Smaller players are also gaining global scale, with Zhejiang-based Leapmotor surpassing the global sales volumes of legacy Japanese automakers Subaru and Mitsubishi Motors.

    Competitive Shift Across Asian Automakers

    For Asian automotive supply chains, the push toward Western markets represents a permanent structural realignment. Japanese carmakers are already altering production schedules and supplier networks to counter Chinese pricing and manufacturing speed.

    Suzuki plans to halve vehicle development cycles to match Chinese design timetables, while Honda committed nearly 2.5 billion dollars to construct a dedicated hybrid vehicle assembly plant in the United States. Traditional tier-one components suppliers in Japan face margin pressure as Toyota expands extended-range electric vehicle production using Chinese facilities and local supply bases.

    Bilateral Talks and Tariff Boundaries

    The latest diplomatic meetings in Washington between United States and Chinese leaders established selective tariff relief covering 30 billion dollars of goods on each side. The bilateral framework excluded automotive imports, leaving existing trade barriers and tech scrutiny in place.

    Commercial transport startups are testing alternative international regulatory pathways in parallel. Autonomous delivery developer Neolix launched robovan trials in Belgium to build European commercial logistics operations ahead of broader international rollouts.

    Manufacturing Targets to Watch

    Market attention turns to full-year delivery reports to verify whether BYD can hit its 2 million export vehicle threshold by December 2026.

  • Chinese Automakers Launch Five-Minute EV Fast Charging

    Chinese Automakers Launch Five-Minute EV Fast Charging

    Chinese electric vehicle makers have introduced ultrafast charging systems this week that replenish passenger car batteries in five minutes, cutting charging times to rival standard petrol pump stops.

    The engineering milestone targets range anxiety directly as automakers deploy high-voltage platforms across new production models to secure domestic market dominance.

    High Voltage Platforms Hit Dealerships

    Domestic manufacturers showed the updated charging architecture across production models, including the Geely Galaxy E8, at the Auto China exhibition in Beijing. The vehicle architecture relies on high-voltage electrical systems that handle higher current loads without overheating battery cells.

    Accelerated charging speeds require dedicated station hardware capable of delivering high power outputs safely. Automakers are pairing vehicle releases with dedicated charging infrastructure investments across tier-one cities in China to guarantee headline charging speeds for retail buyers.

    Infrastructure Demands and Grid Integration

    Deploying five-minute charging shifts operational pressure from vehicle powertrains to urban electrical distribution networks. Fleet operators, commercial landlords, and charging networks must install industrial-grade battery energy storage systems at stations to buffer the grid against sudden spikes in electrical demand.

    For retail and property operators hosting charging points, five-minute turnaround times dramatically increase station throughput and customer turnover. Shorter dwell times change how commercial landlords monetize driver visits, shifting retail strategy from long-stay amenities to high-frequency grab-and-go formats.

    Regional Competitive Pressure

    Legacy foreign automakers face renewed margin pressure across Asian markets as Chinese brands commercialize battery breakthroughs faster. European and Japanese competitors selling into China continue to rely on longer 15-to-30-minute fast-charging cycles on mainstream consumer lines.

    The technology gap threatens foreign brand equity in Southeast Asia and Latin America, where Chinese original equipment manufacturers are expanding retail dealership footprints. Buyers in export markets increasingly treat charging speed as a primary purchasing criterion alongside upfront sticker price.

    Manufacturing Milestones

    Chinese battery suppliers spent recent development cycles optimizing cell chemistry and thermal management systems to handle continuous high-current inputs. The commercialization of five-minute charging marks the transition of advanced silicon-carbon anodes and liquid-cooling designs from laboratory test benches to high-volume assembly lines.

    Vehicle brands are integrating these platforms across entry-level and premium product lines rather than restricting ultrafast charging to low-volume halo vehicles. The broader rollout lowers component unit costs across suppliers in the domestic supply chain.

    Commercial focus now turns to highway network operators as charging infrastructure providers work to deploy compatible multi-megawatt public dispensers along national transit corridors.

  • CharIN Tests 1,000 kW Megawatt Charging Systems at 2026 Testival

    CharIN Tests 1,000 kW Megawatt Charging Systems at 2026 Testival

    Global charging alliance CharIN stepped up interoperability testing for heavy-duty electric trucks and passenger vehicles as hardware communication failures continue to disrupt high-power charging deployments in 2026.

    Live trials using Phoenix Contact systems delivering up to 720 kW revealed persistent connection handshaking delays between vehicle software and chargers, proving that standardisation on paper has outpaced field implementation.

    The tests evaluated the Megawatt Charging System, known as MCS, alongside the second-generation ISO 15118-20 communication protocol. Commercial vehicle demonstrations verified throughput capacity of up to 1,000 kW on the Mercedes-Benz eActros 600, 750 kW on the MAN eTGX, and 700 kW on the Volvo FH Aero Electric. CharIN, which has coordinated MCS specifications across 120 member companies since 2018, confirmed that physical socket standards remain governed under IEC TS 63379 specifications.

    Protocols Advance Faster Than Hardware

    Software standardisation moved forward following the release of the ISO 15118-20 Amendment 1 update in July 2026. That revision incorporated MCS services, grid-tied alternating-current distributed energy resource applications, and updated TLS 1.3 cryptographic security protocols. Yet physical trials revealed ongoing mechanical locking and inlet alignment faults across multiple hardware vendors.

    Michael Keller, chief technology officer of CharIN, stated during the trials: “Without 100% interoperability, the customer has no guarantee of a successful charging process when they arrive at an unfamiliar charging station.”

    Vehicle-to-grid capabilities showed wider compliance variations during system trials. Out of 23 direct-current test systems evaluated for bidirectional energy flow, 13 handled European grid feedback specifications, while only seven out of 11 alternating-current systems functioned under simulated grid conditions. CharIN confirmed that automated energy management and bidirectional communication channels require extensive local certification before utility networks permit commercial power exports.

    Implications for Asian Logistics Hubs

    For fleet managers and warehouse operators across Asia-Pacific logistics corridors, the lack of plug-and-play uniformity introduces direct capital risk. Port operators and long-haul logistics fleets in markets like South Korea, China, and Australia cannot afford failed charging handshakes during tight freight turnaround windows. Purchasing megawatt-rated dispensers does not guarantee scheduled power delivery if proprietary truck control units reject public charger firmware.

    RetailNews Asia notes that retail distribution centers face secondary property planning bottlenecks alongside vehicle testing. Megawatt-level charging requires dedicated onsite battery buffering, dynamic load balancing, and restructured depot layouts to accommodate non-standard charging port positions. Operators building high-voltage freight hubs must design facilities around shifting cable lengths, cooling hardware, and transformer lead times rather than vehicle specifications alone.

    Grid Constraints Dictate Rollout Timelines

    Distribution network operators also struggle to process high-capacity grid hookups at the pace demanded by fleet operators. German electrical industry body ZVEI pointed out that local substation headroom and administrative approvals form the primary constraint on fast-charging hubs. In response, regulators such as the Federal Network Agency began publishing regional utility connection timelines to expose connection bottlenecks.

    Municipal public transport operators have already hit these limits during depot conversions. Local authorities in districts like Lippe reported that while over 50 percent of municipal bus fleets are now electrified, expanding depot connections requires balancing local rooftop solar arrays against uncoordinated central energy directives.

    Regional Testing Heads to South Korea

    Standardisation efforts previously focused primarily on light passenger vehicles before shifting toward megawatt-class haulage at trials in Arnhem earlier this year. Those earlier Dutch sessions validated basic bidirectional direct-current flows but left connector durability and automated communication handshakes unresolved for mass-production trucks.

    Testing now moves to the Korea Electrotechnology Research Institute in Ansan-si on October 12, 2026. Industry participants, including GridWiz, VertexCom Technology, and GENIS Korea, will test HomePlug GreenPHY validation workflows and ISO 15118-20 interfaces against Asia-Pacific grid codes.

  • Mazda Adds Hesai LiDAR to Updated EZ-60 in China Starting at 113,900 Yuan

    Mazda Adds Hesai LiDAR to Updated EZ-60 in China Starting at 113,900 Yuan

    Changan Mazda launched its updated 2027 EZ-60 electric SUV in China on Saturday. Pricing starts at 113,900 yuan ($16,880) across four new LiDAR-equipped variants.

    The roof-mounted sensor package sits on upper trims, lifting the top of the nine-model range to 172,900 yuan before a promotional 6,000 yuan discount across all configurations. The baseline official guide price holds steady at 119,900 yuan. That matches the entry level from the model’s debut.

    Buyers pay a 12,000 yuan premium for the LiDAR options. The extended-range electric vehicle (EREV) Pro LiDAR variant costs 151,900 yuan, while the battery electric (BEV) Max LiDAR edition tops the lineup at 172,900 yuan. Dimensions stay unchanged. The SUV measures 4,850 mm long, 1,935 mm wide, and 1,620 mm tall on a 2,902 mm wheelbase.

    Sensor Package and Driver Assistance Architecture

    A single Hesai ATX LiDAR mounted on the roof line drives the driver assistance suite. The optical unit delivers a detection range of 200 meters. It works alongside three millimeter-wave radars, 11 high-definition cameras, and 12 ultrasonic sensors to scan forward past 250 meters.

    Software runs on an end-to-end architecture that handles highway navigation assistance between 0 and 130 km/h. Urban navigation assist operates between 0 and 80 km/h. Automated parking supports more than 300 bay geometries. Features like memory parking will arrive via over-the-air updates alongside 25 active safety functions.

    Powertrain Options and Battery Capacities

    Powertrains carry over unchanged. EREV trims pair a 70 kW 1.5-liter range extender with a rear electric drive motor producing 190 kW (255 hp) and 290 Nm of torque. A 31.73-kWh battery pack provides 200 kilometers of pure electric driving range under the CLTC cycle.

    Pure electric trims use a 77.94-kWh lithium iron phosphate pack with the same 190 kW rear-wheel-drive motor. That setup delivers a CLTC driving range of 600 kilometers per charge.

    Joint-Venture Rivalry in China’s Electric Market

    Legacy joint ventures face intense pricing pressure in China as domestic automakers make semi-autonomous driving standard in mass-market brackets. International brands have largely avoided putting LiDAR on mid-tier models to protect profit margins. That left their products exposed against high-specification Chinese rivals.

    Putting Hesai LiDAR and end-to-end software below 180,000 yuan takes direct aim at rivals like the Buick Electra E7 and the Nissan NX8. Japanese and American joint ventures need this equipment bundling to protect showroom share in China’s tier-two and tier-three cities.

    Global Export Track and Deployment Plans

    The EZ-60 anchors Mazda’s electrification export program developed with Changan Automobile. It serves as the production base for the CX-6e, which debuted at the Brussels Motor Show in January. Retail shipments to European distributors are already underway.

    Changan Mazda launched the original EZ-60 on September 26, 2025, bringing this refresh 12 months into the lifecycle. Other Japanese carmakers are also expanding electrified lineups in China. Nissan recently updated its N7 sedan, and Toyota plans to introduce localized extended-range models in April 2027.

    Deliveries of the LiDAR-equipped EZ-60 trims begin at dealerships across China next month. The 6,000 yuan launch subsidy will run through the initial intake window.

  • Suzuki Aims to Halve Vehicle Development Time by 2030

    Suzuki Aims to Halve Vehicle Development Time by 2030

    Suzuki Motor will cut its new vehicle development time in half by around 2030 from fiscal 2020 levels, speeding up model rollouts across Asian markets.

    The Japanese carmaker is targeting a 30 per cent improvement in development efficiency alongside a 50 per cent boost to production efficiency over the same period.

    Faster turnaround for key markets

    Shrinking development cycles will allow the manufacturer to refresh its compact passenger car lineup faster. Shorter lead times reduce capital tied up in vehicle design programs while giving engineering teams quicker responses to shifting regional safety standards, emissions regulations, and consumer preferences.

    Automakers across the region face sharper competition from domestic and regional rivals capable of bringing new platforms to market on compressed schedules. By targeting a 30 per cent gain in engineering efficiency, Suzuki intends to defend its volume positions in key Asian passenger car segments without inflating research overhead.

    Expanding Indian manufacturing capacity

    India serves as the central pillar of the group’s manufacturing footprint and retail sales volume. Suzuki confirmed plans to expand its annual production capacity in the country to between 4 million and 4.99 million vehicles by the 2030 financial year or later.

    Scaling output in India to nearly 5 million units yearly requires severe factory floor optimization. The targeted 50 per cent increase in production efficiency is designed to extract higher unit volume from existing and planned assembly lines, controlling per-unit manufacturing costs as output scales.

    Operational shifts across assembly plants

    Reaching these targets requires overhaul across tooling, component sourcing, and plant automation. Improving assembly efficiency by half within the decade means standardizing modular architectures and trimming build hours per chassis across global sites.

    Suppliers in Suzuki’s tier-one network will need to align with tighter delivery cycles and faster part validation schedules. Compressing vehicle gestation from fiscal 2020 baselines transfers operational pressure directly down the supply chain, requiring parts vendors to validate components on shorter development tracks.

    Market response in Tokyo

    Shares in Suzuki Motor rose 0.9 per cent on Friday following the announcement in Tokyo. The benchmark Nikkei index finished the session 1.1 per cent higher.

    Investor attention now turns to the capital expenditure plan required to lift Indian capacity to the 4.99 million vehicle threshold by fiscal 2030.

  • Beijing Auto Show Sets March 2027 Dates for First Odd-Year Exhibition

    Beijing Auto Show Sets March 2027 Dates for First Odd-Year Exhibition

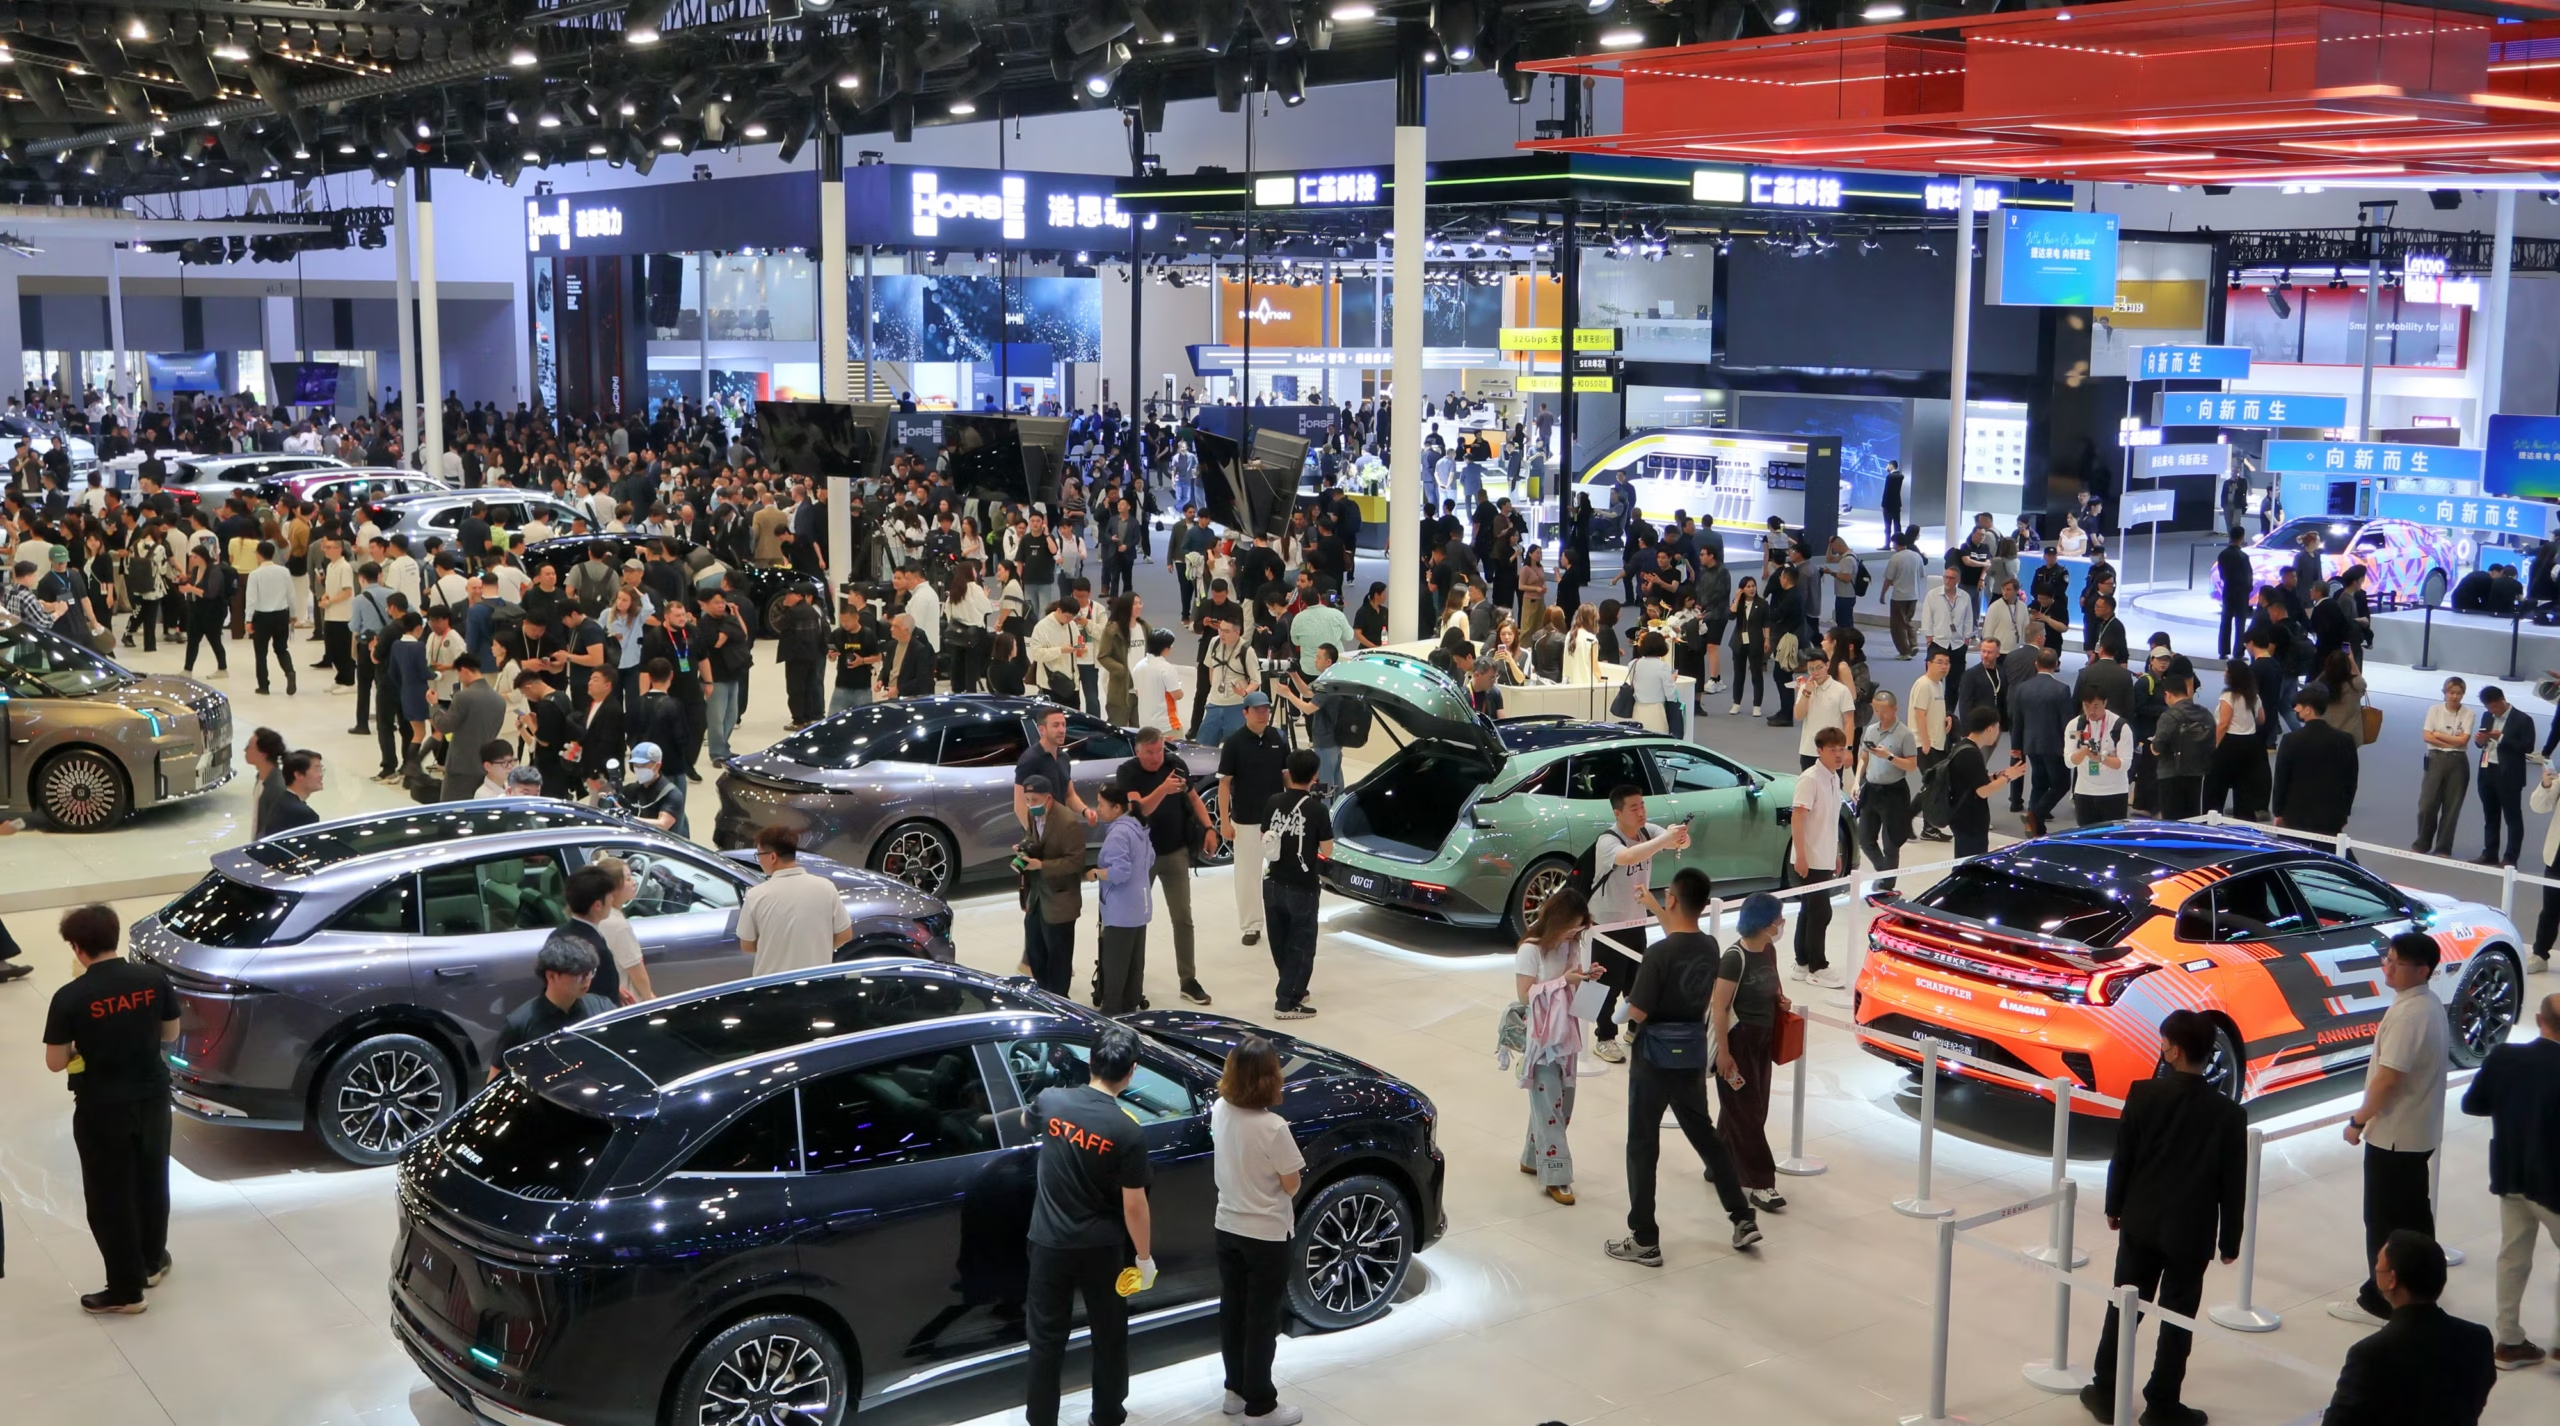
    Organizers have scheduled the next Beijing Auto Show for March 27 to April 5, 2027. The event introduces an odd-year specialized format focused on smart vehicle manufacturing.

    The 10-day event follows a 2026 exhibition that drew 1.28 million visitors. That show filled 380,000 square meters of floor space in the capital.

    Officially named the 2027 Beijing International New-Quality Automotive and Future Smart Mobility Exhibition, the show will use two venues: the China International Exhibition Center Shunyi New Venue and the Capital International Exhibition Convention Center. Media days run on March 27 and 28. Trade days follow on March 29 and 30, before public entry opens from March 31 to April 5. A dedicated auto parts section will operate for four days from March 27 to March 30.

    Schedules and venue allocation

    This schedule runs the Beijing show in an odd-numbered year for the first time since its 1990 debut. It follows months of talks between the Shanghai Council for the Promotion of International Trade and the automotive branch of the China Council for the Promotion of International Trade. Both bodies agreed on September 7 to keep their alternating system for comprehensive vehicle exhibitions. Under that deal, full-scale passenger car shows stay in Beijing during even years and Shanghai during odd years.

    To avoid overlapping with Shanghai’s gathering, Beijing will operate as a specialized trade exhibition in 2027. Exhibits will concentrate on smart manufacturing, digital production lines, artificial intelligence software, smart mobility services, and industrial robotics alongside traditional new energy vehicles.

    Technology race drives exhibition demand

    Automakers in China face compressing model lifecycles and rapid tech shifts. These changes demand more frequent commercial exposure. More than 100 domestic passenger car brands compete inside mainland China, forcing manufacturers to shorten product refresh cycles to keep dealer inventories moving.

    Hardware advances have pushed vehicle launches beyond annual cycles. Domestic suppliers have speeded up the deployment of ultrafast charging technology. Manufacturers including Geely, BYD, and CATL are rolling out systems designed to complete battery charging within five minutes. Meanwhile, factory automation and AI integration have become core commercial selling points alongside vehicle range and chassis design.

    “The real challenge is whether the battery can accept that level of current quickly and repeatedly without overheating, excessive degradation or internal bottlenecks,” said Chris Liu, a Shanghai-based senior analyst at Omdia.

    Export focus and commercial matchmaking

    Organizers will also target export procurement on the show floor as domestic brands look overseas to offset slowing passenger vehicle deliveries at home. They plan to host dedicated matchmaking sessions between Chinese carmakers and foreign dealership groups, component distributors, and regional fleet operators.

    During the April 2026 Beijing show, brands presented 1,451 vehicles across more than 1,000 booths. That lineup included 181 product debuts and 71 concept cars. The 2027 edition aims to convert foot traffic into export supply agreements by prioritizing international procurement delegations.

    Shanghai prepares expanded 2027 floor plan

    Shanghai’s auto show will open less than three weeks after the Beijing event concludes. Its comprehensive exhibition runs from April 23 to May 2, 2027, at the National Exhibition and Convention Center. The event spans 400,000 square meters and includes a specialized area for embodied artificial intelligence.

    Car brands must now split capital expenditures and marketing budgets across two major events within a five-week window in northern and eastern China. Floor space allocations and overseas buyer registrations for the Shunyi exhibition halls will open in early 2027.

  • BYD Teases Shark Pickup China Launch After Selling 29,997 Units Overseas

    BYD Teases Shark Pickup China Launch After Selling 29,997 Units Overseas

    BYD began promoting the domestic launch of its Shark plug-in hybrid pickup truck on September 24, after selling 29,997 units across international markets in the first eight months of 2026.

    The carmaker released official promotional images across its social media channels under the slogan “The overseas champion returns,” assigning the model to its specialized Fang Cheng Bao sub-brand. The campaign follows two years of sales abroad, reversing the standard practice among Chinese vehicle manufacturers of establishing domestic volume before attempting foreign distribution.

    Export track record and platform specifications

    Overseas deliveries of the Shark reached 4,300 units in August alone. BYD first introduced the pickup in Mexico in May 2024, followed by rollouts in Australia, Brazil, Cambodia and Pakistan.

    Built on the company’s off-road dual-mode platform, the truck pairs a 1.5-litre turbocharged petrol engine with two electric motors. Regulatory filings published by the Ministry of Industry and Information Technology in July show peak motor outputs of 170 kW at the front axle and 150 kW at the rear. The vehicle uses lithium iron phosphate packs produced by BYD’s battery manufacturing division, FinDreams Battery.

    Dimensions submitted to regulators match the export specification. The body measures 5,457 mm in length, 1,971 mm in width and 1,925 mm in height, riding on a 3,260 mm wheelbase.

    The domestic utility vehicle landscape

    Entering the domestic pickup segment pits BYD directly against Great Wall Motor, the long-standing market leader in Chinese commercial haulers, and Geely Auto’s electric utility brand Radar. Retail buyers in China have historically treated pickups as commercial workhorses rather than lifestyle vehicles, constrained by municipal traffic bans that restrict light trucks from entering major downtown cores.

    Those regulatory limits keep the overall category small relative to passenger cars. Chinese buyers purchased 455,000 pickup trucks between January and August 2026, according to figures from the China Passenger Car Association. By comparison, total retail passenger car volume reached 11.7 million units over the same eight months, of which 7.78 million were plug-in hybrids or pure battery-electric models.

    Electrification trends in commercial light trucks

    New energy pickups remain a small slice of commercial sales, but demand is expanding faster than the wider commercial truck market. Electrified pickup sales climbed 18 per cent year on year to 62,000 units through August. Commercial fleet buyers and municipal contractors in regional provinces have adopted plug-in models to cut operational fuel costs and comply with local emissions caps.

    Assigning the Shark to Fang Cheng Bao indicates BYD intends to market the truck to private off-road enthusiasts rather than commercial fleet buyers alone. Fang Cheng Bao general manager Xiong Tianbo confirmed the model’s inclusion in the brand portfolio earlier this year, aiming to broaden a lineup that previously focused on rugged sport utility vehicles.

    Regulatory steps and launch timeline

    The consumer promotional push marks the final marketing stage before open sales begin. Li Yunfei, general manager of branding and public relations at BYD, first outlined plans for a Chinese release in October 2025, followed by the formal MIIT filing three months ago.

    Dealership distribution timelines and domestic retail pricing remain unannounced. The Ministry of Industry and Information Technology has yet to release battery capacity and pure electric driving range figures for the localized configuration.

  • GAC and Huawei Joint Brand Aistaland Launches GX7 SUV from 229,900 Yuan

    GAC and Huawei Joint Brand Aistaland Launches GX7 SUV from 229,900 Yuan

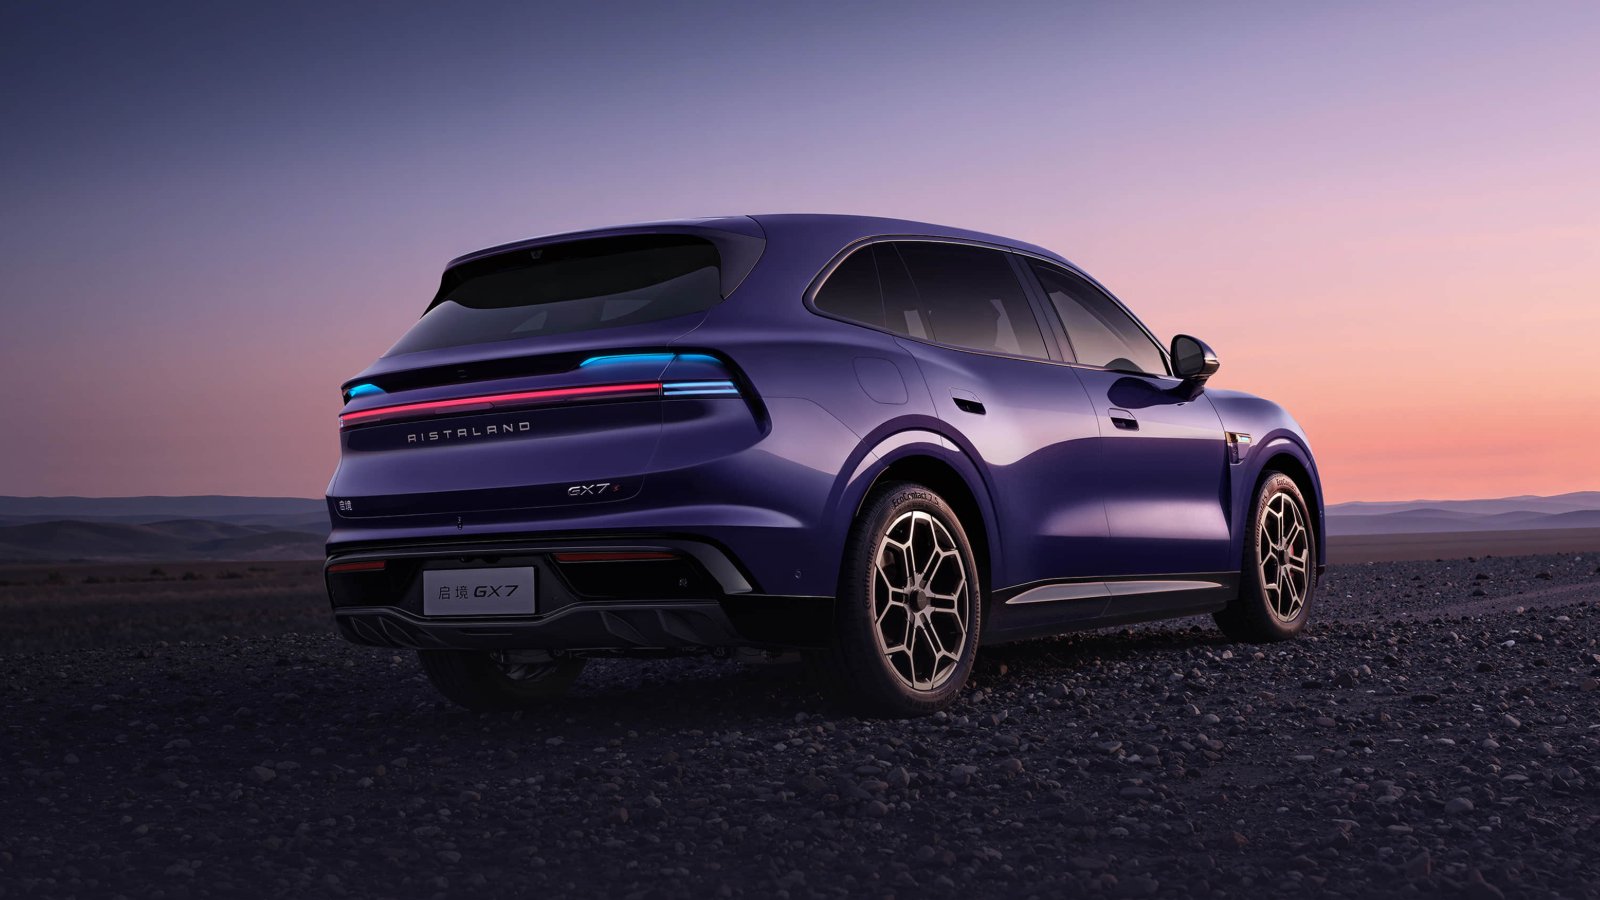
    Aistaland rolled out its second production vehicle on September 23 in Guangzhou. The carmaker priced the GX7 extended-range SUV at an introductory 229,900 yuan ($34,060) to fight sluggish brand sales.

    That promotional price sits 20,000 yuan below the pre-sales floor opened on September 4. Buyers also get a 10,000 yuan payment rebate and an optional 8,000 yuan trade-in subsidy.

    Standard sticker prices for the five-seat SUV span 239,900 yuan to 301,900 yuan across three variants. With the launch promotion, the base rear-wheel-drive Ultra sells for 229,900 yuan. The dual-motor all-wheel-drive version costs 249,900 yuan, and the tri-motor flagship tops the lineup at 291,900 yuan. Applying the trade-in allowance drops the entry point to 221,900 yuan.

    Pricing and Powertrain Variants

    Every GX7 variant runs on a 1.5-litre turbocharged petrol range extender paired with electric drivetrains. The single-motor Ultra delivers 200 kW (268 hp). It reaches 100 km/h in 7.6 seconds. Stepping up to the dual-motor model raises output to 340 kW and cuts the sprint time to 4.9 seconds. The range-topping tri-motor model produces 550 kW, hitting 100 km/h in 3.9 seconds.

    Contemporary Amperex Technology Co. Ltd. Supplies the battery systems. Buyers choose between a 52 kWh lithium iron phosphate pack and a 67 kWh ternary lithium pack. Pure electric range on China’s light-duty vehicle test cycle covers 325 km to 385 km. Total combined range reaches between 1,500 km and 1,580 km.

    Fast replenishment separates the flagship from entry variants. The tri-motor version adopts an 800-volt electrical architecture supporting 5C charging speeds, taking the battery from 30 per cent to 80 per cent in 10 minutes. The other two models require 15 minutes for the same charge.

    Autonomous Driving Architecture and Cabin Tech

    Driver-assist hardware forms the core marketing proposition for the new model. The GX7 is among the earliest vehicles fitted with Huawei’s Qiankun ADS 5 driver-assistance suite. That system relies on 38 sensor points and four LiDAR units, including an 896-channel dual-optical-path system. Aistaland built the vehicle with hardware redundancies across eight operational systems, power supply, braking, steering, computing, perception, communications, positioning, and user interaction, to support Level 3 autonomous driving requirements.

    Inside, the cabin draws heavily on Huawei software. The setup integrates the HarmonySpace 6 operating system, dual 15.6-inch console screens, an 88-inch augmented-reality head-up display, and a 21-speaker proprietary sound system. The rear seats fold into a flat bed in 20 seconds. That mechanism supports 12 layout adjustments inside a body that spans 5,099 mm in length, 2,006 mm in width, and 1,750 mm in height on a 3,070 mm wheelbase.

    Crowded Field in Family Extended-Range SUVs

    Targeting the full-size five-seat SUV segment shifts Aistaland directly into China’s most contested vehicle category. Extended-range models continue to take market share from pure battery-electric rivals because family buyers want road-trip reliability without charging station queues during holiday travel. The GX7 goes head-to-head with Li Auto’s Li L6, the Seres-built Aito M7, and Xiaomi’s upcoming YU7.

    Retail distribution and brand overlap present clear commercial risks. Huawei already supplies intelligent cockpit and driving systems across multiple automotive partnerships, including the Harmony Intelligent Mobility Alliance network. Because Aistaland operates under a separate bilateral structure, GAC must handle vehicle assembly and showroom footfall alone while pitching the GX7 against Huawei-equipped rivals in identical price bands.

    Reversing the GT7 Sales Slide

    GAC and Huawei based their collaborative team in Guangzhou to speed up product launches after signing their co-development pact. The joint venture introduced its debut vehicle, the GT7 shooting brake, on June 26 with a starting tag of 209,900 yuan. Deliveries peaked at 2,658 units in July. They dropped 58.62 per cent to 1,100 units in August, exposing limited demand for wagon body styles.

    Factory lines in Guangdong have now shifted production capacity to the higher-volume SUV platform. Deliveries for the three GX7 trims start across national dealership networks before the close of September, making fourth-quarter sales the decisive trial for the joint venture.

  • Leapmotor Overtakes Subaru and Mitsubishi Motors in Global Sales

    Leapmotor Overtakes Subaru and Mitsubishi Motors in Global Sales

    Chinese electric vehicle startup Leapmotor surpassed Subaru and Mitsubishi Motors in global quarterly deliveries for the first time between April and June. Strong domestic sales in China drove the shift. An accelerating rollout across European dealerships also lifted volume.

    The Hangzhou-based manufacturer built momentum on budget battery-electric models and extended-range powertrains. Those lower prices unlocked retail demand in mainland tier-three cities. They also found buyers in price-sensitive European export markets.

    Shift in Global Volume

    Overtaking two established Japanese automakers shifts the competitive baseline for entry-level passenger cars. Subaru and Mitsubishi built multi-decade international sales networks through independent franchised dealers. Their slower battery-electric transition left budget segments exposed to cheaper Chinese rivals.

    Leapmotor entered European showrooms by pricing compact electric models against legacy petrol hatchbacks. That approach bypassed the premium segment. European and Japanese marques still hold stronger brand loyalty in that higher tier.

    Pressure on Traditional Dealerships

    Across Europe and Asia, independent auto retailers and multi-brand dealer groups must now adjust inventory allocation. Dealerships facing sluggish demand for internal combustion models are handing floor space to Chinese brands. These vehicles deliver higher unit turnover, though dealer margins are tighter.

    Component vendors and regional distributors tied exclusively to mid-tier Japanese manufacturers face direct exposure. As sales volume drifts toward Chinese electric platforms, legacy suppliers face shrinking factory orders unless they win contracts on dual-fuel and battery architectures.

    Export Trajectory

    Behind the quarterly milestone are two years of factory scaling and targeted export homologation by Leapmotor. The company previously relied almost entirely on mainland China registrations before opening European distribution channels.

    Delivery numbers through the second half of the year will test the expansion as European trade policy and regional import tariffs take effect.

  • Sunwoda Unveils 15C Flash Battery to Challenge BYD in Fast Charging

    Sunwoda Unveils 15C Flash Battery to Challenge BYD in Fast Charging

    Sunwoda Electric Vehicle Battery unveiled a 15C flash charging system in Zaozhuang on September 17 that charges an electric vehicle from 10 to 97 per cent in nine minutes.

    The system matches the benchmark room-temperature charging speed established by market leader BYD. It also comes with a company commitment to deploy 10,000 megawatt charging stations by the end of 2027.

    Charging Performance and Cold Weather Specs

    At room temperature, the battery charges from 10 to 70 per cent in five minutes. That adds 100 kilometres of driving range in 60 seconds. Total driving range exceeds 700 kilometres on a full charge.

    Cold weather tests show the pack charges from 10 to 97 per cent in 15 minutes at minus 20 degrees Celsius. Sunwoda attached a warranty covering 10 years or 300,000 kilometres to non-commercial vehicles with unlimited ultrafast charging cycles, targeting buyer anxiety over high-current cell degradation.

    Hardware Architecture and Grid Storage

    Hardware diagnostics rely on proprietary cell sensors, an energy domain controller and a cloud monitoring engine. Sunwoda stated the platform identifies more than 20 separate failure modes between two and 10 days before a breakdown. Its detection rate reaches 99.77 per cent.

    On the grid side, the company introduced an integrated platform that bundles solar generation, stationary battery storage, liquid-cooled charging posts and megawatt-scale dispensers. The multi-brand terminal design allows third-party automakers to access the high-voltage stalls under commercial sharing agreements.

    The Race for Megawatt Infrastructure

    China’s EV power race has shifted from laboratory power ratings to physical network footprint. BYD crossed its 10,000th flash charging station milestone on August 28. It maintains a target of 20,000 operational stations by the end of 2026.

    Other domestic manufacturers are pushing similar power thresholds. Dongfeng introduced a prototype 1,500-kilowatt charger on July 29, matching BYD’s peak terminal rate. FAW Hongqi posted July laboratory results showing a 10-to-70 per cent charge in three minutes and 41 seconds with battery partner CNET. In Hong Kong, Xpeng energised its first one-megawatt X-Energy stall with 400 kilowatt-hours of local storage on September 15.

    Commercial Rollout and Factory Timelines

    Sunwoda EVB faces a crowded manufacturing landscape. CATL and BYD command more than 60 per cent of China’s domestic vehicle battery volume. Total battery installations across the country grew 26.3 per cent year-on-year in August, but second-tier cell makers must prove station economics to justify high capital spending on utility-scale grid connections.

    Initial announcements omitted capital expenditure figures, manufacturing site allocations, commercial vehicle partnerships and the first production passenger car chosen for the 15C pack. Filings with the Ministry of Industry and Information Technology will soon show which automaker integrates the hardware first ahead of the 2027 station rollout target.

  • Chery Delivan Targets 100 UK Dealerships for Electric Van Expansion

    Chery Delivan Targets 100 UK Dealerships for Electric Van Expansion

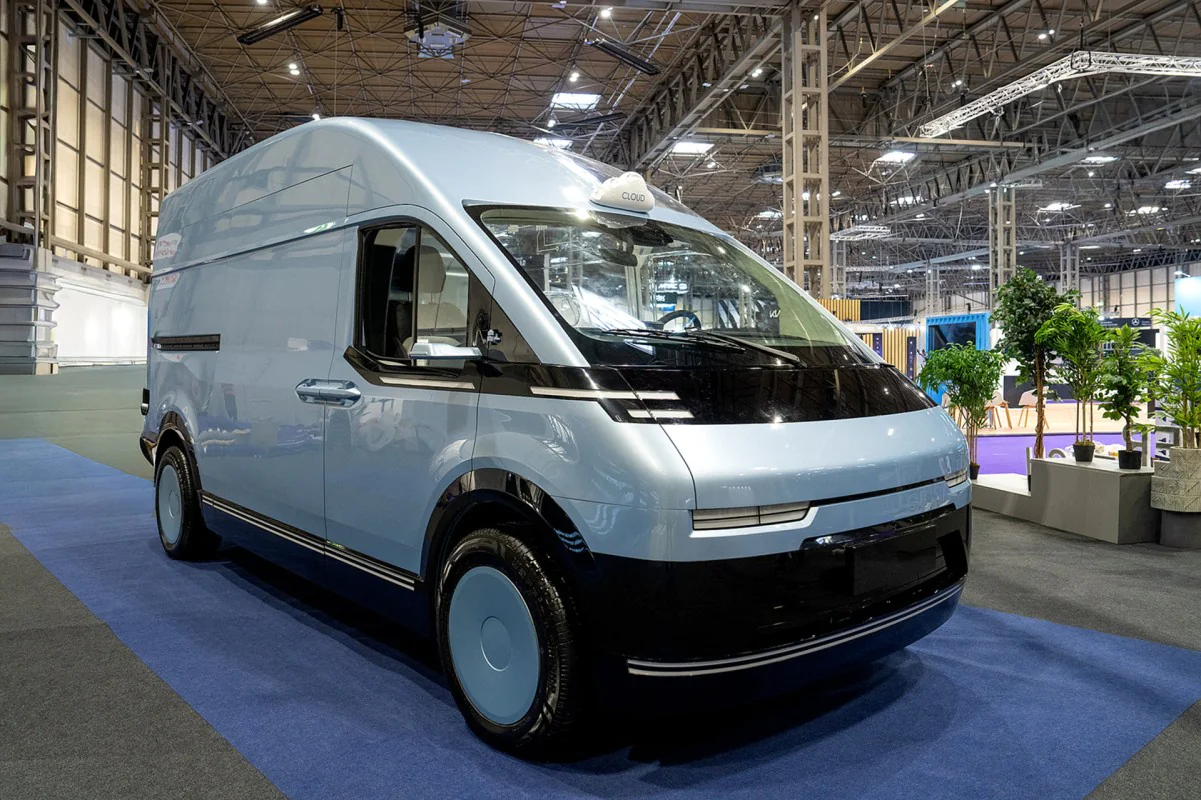
    Chery Commercial Vehicle brand Delivan plans to establish more than 100 UK dealership sites over the next five years to sell electric delivery vans.

    The Chinese automotive group unveiled its production van range at the IAA Transportation show in Hanover, preparing for commercial deliveries in 2027 across Britain, Germany, France, Spain, Italy and the Nordic region.

    Hardware specifications and conversions

    Delivan built its launch lineup on a single electric architecture, offering battery capacities between 50.4 kilowatt-hours and 97.4 kilowatt-hours. The vehicles deliver up to 426 kilometres of WLTP combined range with speed capped at 100 kilometres per hour, while direct-current fast charging takes the battery from 15 percent to 80 percent in roughly 22 minutes.

    The range includes the L1H1 panel van with a 1,400-kilogram payload, the larger L2H3 panel van offering 11.6 cubic metres of cargo capacity, and the L3 chassis cab supporting payloads up to 2,120 kilograms. Both panel vans carry a 2,500-kilogram towing rating. Delivan also displayed four specialist conversion bodies developed with European bodybuilders: a crew van, a refrigerated box, an integrated tool storage layout and a three-way tipper.

    Fleet software and uptime service

    Commercial operations will run on a package the company calls its 1+3 proposition, combining vehicle hardware with three digital support layers. Delivan I handles telematics, route efficiency and real-time energy usage tracking, while Delivan PRO links operators to an uptime centre for predictive maintenance and remote diagnostics. Delivan X oversees third-party vehicle conversions and bodybuilder certifications.

    Software integration has become a primary sales mechanism for Chinese commercial vehicle exporters targeting overseas corporate buyers. Fleets evaluate total cost of ownership through vehicle availability and software integration rather than purchase price alone. Delivan is attempting to bypass typical import friction by embedding diagnostics and bodybuilding approvals directly into European fleet workflows.

    Dealership network strategy

    Distribution in Britain will combine franchised car retailers with dedicated commercial vehicle centres. Chery plans to convert selected existing passenger-car showrooms to carry Delivan while appointing independent commercial vehicle specialists to cover high-density logistics corridors.

    Establishing physical workshops and rapid parts supply presents the main execution hurdle for new commercial vehicle brands in Europe. Delivery companies cannot absorb prolonged vehicle downtime. While Chinese electric passenger cars rely heavily on direct retail or light dealer agreements, light commercial vehicles require round-the-clock maintenance agreements and guaranteed replacement turnarounds to win institutional fleet tenders.

    European expansion timeline

    Delivan initiated its Western European rollout in April at the Commercial Vehicle Show in Birmingham, where Chery first introduced the commercial sub-brand. The company subsequently established regional operating headquarters and technical teams in the UK and Germany to adjust suspension, cargo packaging and cab ergonomics for local delivery routes.

    “Using real-time connected-vehicle data, our in-house smart system applies AI to connect the entire operational chain, from individual vehicles to fleet management,” said Yueqiong Gong, vice president of Chery Holding Group and general manager of Chery Commercial Vehicle.

    Chery will finalize its initial UK dealer appointments over the coming months before opening order books ahead of customer deliveries in 2027.
  • Islamabad Police Deploys 50 BYD Atto 2 Electric SUVs for Capital Patrol

    Islamabad Police Deploys 50 BYD Atto 2 Electric SUVs for Capital Patrol

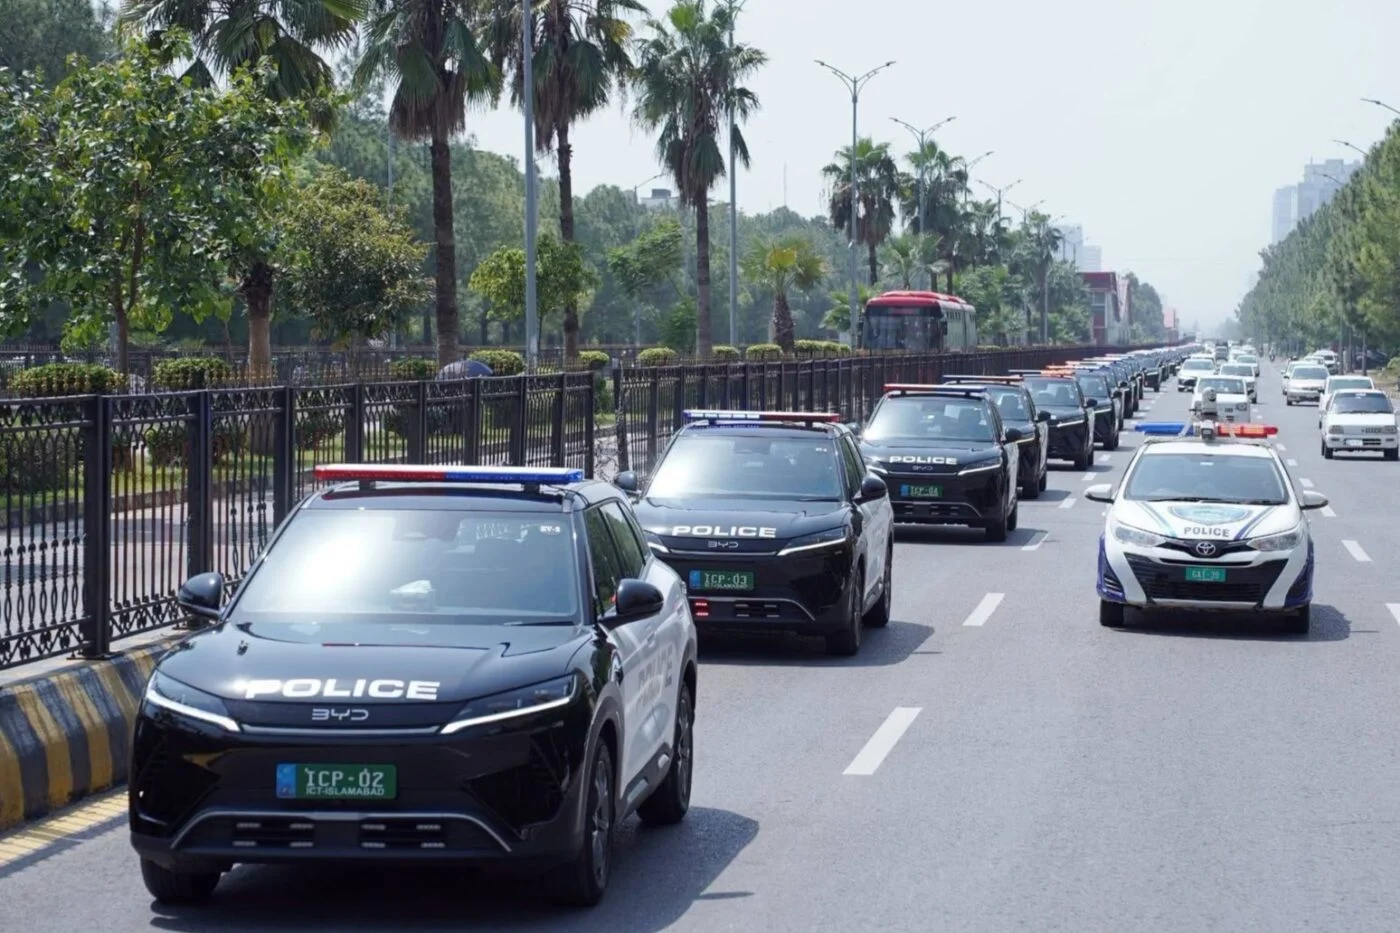
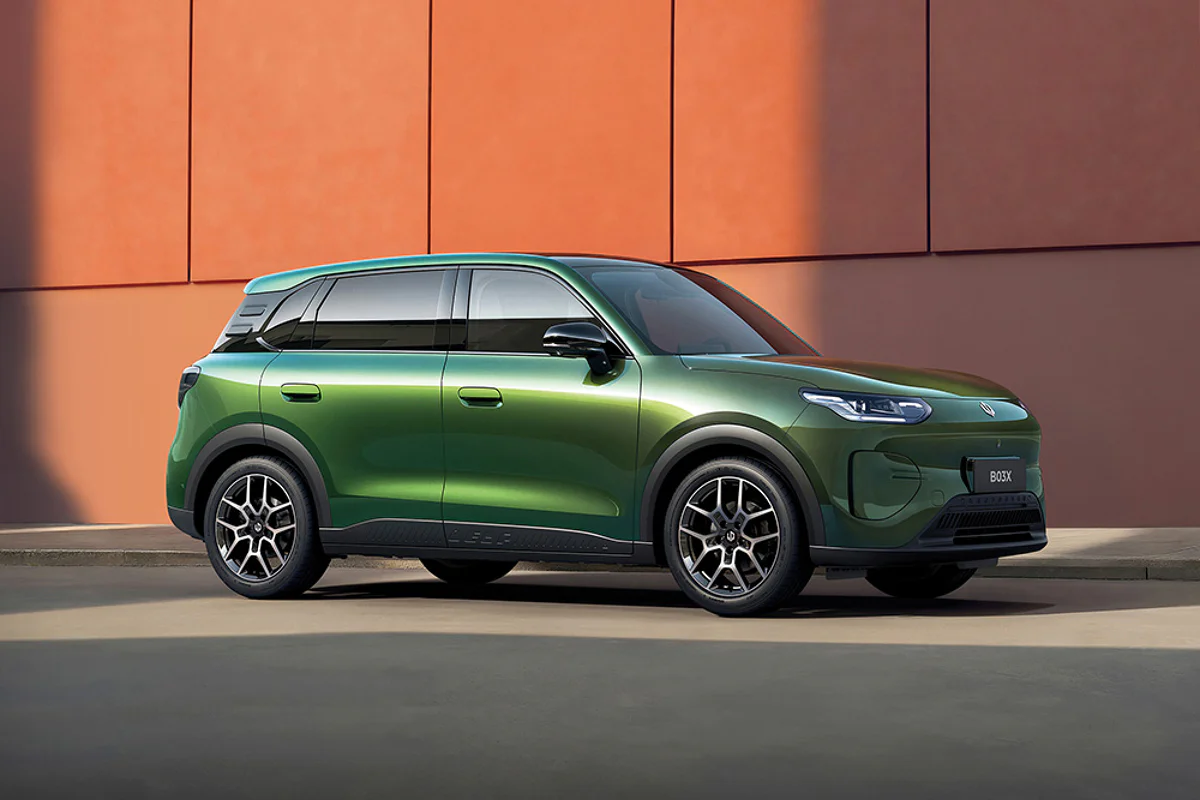
    Islamabad police deployed 50 BYD Atto 2 electric sport utility vehicles across the Pakistani capital, establishing a dedicated 200-officer patrol unit. The fleet cost 7.29 million Pakistani rupees per vehicle and will cut monthly municipal fuel spending by roughly 34 million rupees.

    Pakistani Prime Minister Shehbaz Sharif transferred the vehicle keys on 8 September to Federal Minister for Interior Mohsin Naqvi and Inspector General of Islamabad Police Syed Ali Nasir Rizvi. The rollout equips the newly formed Capital Patrol force to handle urban surveillance and emergency calls.

    Fleet deployment and financial return

    Municipal calculations indicate the monthly fuel savings will recover the capital outlay for each vehicle in ten and a half months. Lower operational expenses allow the department to reallocate budget lines from fuel procurement to frontline equipment and maintenance.

    Police leadership expects the electric fleet to improve urban response times across Islamabad. Rapid torque delivery from electric powertrains and reduced maintenance downtime give city patrols higher daily availability than aging internal combustion units.

    Powertrain and battery specifications

    The deployed Atto 2 models run on a single powertrain configuration. A front-mounted permanent magnet synchronous motor generates 130 kW of power and 290 Nm of torque, allowing acceleration from zero to 100 kilometres per hour in 7.9 seconds.

    Energy storage relies on a 45.12 kWh lithium iron phosphate battery pack. The system delivers an operating range of up to 380 kilometres under NEDC testing standards, and fast charging restores battery capacity from 30 per cent to 80 per cent in 30 minutes.

    Local assembly plans in Sindh

    The municipal procurement aligns with BYD’s manufacturing roadmap in Pakistan through its local partner, Mega Motor Company. Mega Motor, an associate of power producer Hub Power Company, is building a vehicle assembly plant in Gharo, Sindh.

    Establishing domestic production enables the Chinese automaker to lower import tariffs and compete aggressively against traditional Japanese vehicle assemblers that dominate Pakistan’s passenger market. Fleet deals with government agencies provide stable initial volumes while retail distribution develops.

    Commercial network expansion

    Mega Motor plans to complete construction of the Gharo assembly facility by the end of 2026. The Atto 2 serves as the primary candidate for initial local assembly lines once production begins.

    Watch the rollout of charging infrastructure along capital patrol routes and the completion timeline for the Sindh factory ahead of the late 2026 manufacturing target.