Category: E-Tailing

Retail News Asia is committed to providing both local and global retailers with the latest E-Commerce & Etail news throughout the Asian market. This on a daily base.

  • Taiwan Plans Ban on Auto-Renewing Subscriptions with Fines up to NT$50 Million

    Taiwan Plans Ban on Auto-Renewing Subscriptions with Fines up to NT$50 Million

    Taiwan will ban automatic subscription renewals for digital services and require explicit user consent, the Executive Yuan announced in Taipei.

    Companies that conceal renewal terms face fines of up to NT$50 million ($1.57 million) per violation under proposed regulatory amendments. The cabinet said service providers must scrap pre-ticked consent boxes and allow customers to manually confirm any recurring payment schedule through a clearly labeled checkbox.

    Contract Rules and Cancellation Parity

    The Ministry of Digital Affairs will amend the Mandatory and Prohibited Clauses for Standard Contracts in Online Retail Transactions to enforce the ban. Under the updated framework, platforms must clearly disclose subscription durations, recurring fee structures and cancellation procedures before a customer signs up.

    Ending a recurring plan must become as simple as starting one. Regulators will require businesses to build cancellation workflows that match the ease of their sign-up funnels. Platforms must also send a separate advance notice to users before any scheduled renewal charge goes through.

    Under Article 42 of the Fair Trade Act, initial concealment of subscription terms carries fines between NT$50,000 and NT$25 million ($1,570 to $784,831). Operators that fail to fix non-compliant interfaces before a set deadline face recurring penalties ranging from NT$100,000 to NT$50 million for each infraction.

    Targeting Dark Patterns in Digital Commerce

    Scrutiny over subscription traps has sharpened across Asia-Pacific markets as streaming, software and direct-to-consumer apps shift revenue models toward recurring billing. Regulators across the region are cracking down on deceptive user interface designs, commonly known as dark patterns, that lock shoppers into recurring payments with hidden clauses and overseas corporate registrations.

    Taiwanese consumer protection rules will also void hidden terms entirely. Under Article 12 of the Enforcement Rules of the Consumer Protection Act, clauses presented in ways that are difficult to detect or understand will not legally bind the subscriber.

    The policy overhaul follows legislative questioning by Chinese Nationalist Party (KMT) lawmaker Liao Hsien-hsiang, who highlighted user financial losses tied to overseas digital providers. The cabinet is working against a one-month timeline to formalize the regulatory draft and submit the revised contract provisions.
  • More Japanese Merchants Leave Rakuten Marketplace over Drone Logistics Alliance

    More Japanese Merchants Leave Rakuten Marketplace over Drone Logistics Alliance

    Japanese merchants are leaving Rakuten Group’s e-commerce marketplace following the company’s latest drone logistics alliance. Seller departures have increased as platform operators adjust delivery requirements across the domestic network.

    Merchant relations on the platform face renewed strain over fulfillment and distribution integration. Store operators running storefronts on Rakuten Ichiba must balance rising platform costs against competing fulfillment channels.

    Merchant Friction Over Delivery Strategy

    The marketplace has pushed deeper into automated logistics and aerial transport to solve driver shortages in regional Japan. That shift requires store owners to adapt packaging, inventory management and dispatch schedules to automated logistics hubs.

    Sellers unwilling or unable to meet those fulfillment rules are closing their accounts. For smaller Japanese brands, direct-to-consumer websites and rival channels now offer cheaper operational alternatives.

    Pressure Across Japanese E-Commerce

    Competition among Japan’s digital marketplaces has tightened sharply. Amazon Japan and LY Corporation’s Yahoo Shopping continue to court independent merchants with flexible shipping terms and lower platform fees. Rakuten has spent heavily to defend its merchant base, yet policy shifts around shipping rates and fulfillment standards historically triggered seller pushback across the country.

    Merchant retention numbers for the current quarter will show how many storefronts follow through on closing their marketplace accounts.

  • JD.com and Sino Land Win $2.1B Northern Metropolis Hub in Hong Kong

    JD.com and Sino Land Win $2.1B Northern Metropolis Hub in Hong Kong

    A consortium led by JD.com and Sino Land won the tender for an 11-hectare Northern Metropolis development site in Hong Kong with expected total investment of HK$16.8 billion ($2.1 billion). The group beat Henderson Land Development with a HK$1.03 billion land bid evaluated under a two-envelope system.

    Hong Kong authorities awarded the 50-year grant for three residential parcels and a dedicated technology park site in the Hung Shui Kiu-Ha Tsuen New Development Area. The residential plots will yield more than 3,000 homes, while the tech site provides 50,950 square metres of gross floor area.

    Logistics hub and residential split

    Four mainland developers joined JD.com and Sino Land in the winning group: China Overseas Land & Investment, China Merchants Land, China Resources Land (Overseas) and CTG Investment. The government weighted non-price technical criteria at 70 percent and price at 30 percent, assessing anchor tenant commitments, development speed and employment generation.

    Sino Land and its partners will construct an intelligent logistics centre on the commercial parcel, with JD serving as the anchor tenant. The tender conditions require the consortium to bring at least 15,300 square metres of gross floor area into operation within 55 months. The group must also complete site formation works for three government plots intended for public facilities.

    Expanding footprint across Hong Kong

    The land tender cements a fast physical build-out by Beijing-based JD across Hong Kong assets. The group bought grocery chain Kai Bo Food Supermarket last August to gain direct neighbourhood retail access. In December, it agreed to buy a 50 percent stake in Central’s China Construction Bank Tower from Lai Sun for HK$3.5 billion to house its local headquarters, followed by a HK$750 million purchase of the Silka Seaview Hotel in Kowloon for student accommodation.

    By securing industrial land directly adjacent to the mainland border, Chinese e-commerce operators are shifting from leasing third-party warehouses in the territory to developing dedicated automated cross-border fulfilment infrastructure. The project now enters detailed planning, with the 55-month countdown starting for delivery of the first automated supply chain space.

  • Brandpay Logs 65 Million Impressions Turning Retail Shoppers into Ad Channels

    Brandpay Logs 65 Million Impressions Turning Retail Shoppers into Ad Channels

    Australian retail technology platform Brandpay has logged 65 million organic impressions across 250 brands by turning regular shoppers into measurable advertising channels. The platform generated an average 4.2 times return on reward spend across 12,894 pieces of customer content.

    Instead of hiring professional creators, the system pays shoppers in store credit when they post authentic social media content about products they bought. That credit circulates back through existing checkout systems, encouraging repeat transactions.

    Micro audiences and store credits

    Brandpay co-founder and chief executive Dr Mike Haywood said the model distributes reach across regular buyers rather than concentrating budgets on a handful of high-profile influencers. More than 80 per cent of rewarded participants have between 100 and 5,000 followers.

    The mechanics produce measurable cost advantages over standard digital ad inventory. Brandpay reported an average cost per mille of $2.48 and a cost per click of $2.62 across its network.

    A brand’s own content describes itself. A customer’s content is evidence.

    RetailNews Asia has tracked a sharp regional pivot away from high-fee influencer contracts across Asia-Pacific e-commerce operators, as rising customer acquisition costs on major ad platforms force merchants to monetize their existing customer bases.

    Measuring return on reward spend

    Shoppers rewarded under the program return to buy twice as frequently as non-rewarded customers. The resulting data allows merchants to test specific reward tiers against basket size increases.

    Brandpay is now testing automated reward calibrations to determine how different credit amounts influence basket size and repurchase frequency across retail categories.

  • Dingdong Lifts Second Quarter Profit to $40 Million Ahead of Meituan Deal

    Dingdong Lifts Second Quarter Profit to $40 Million Ahead of Meituan Deal

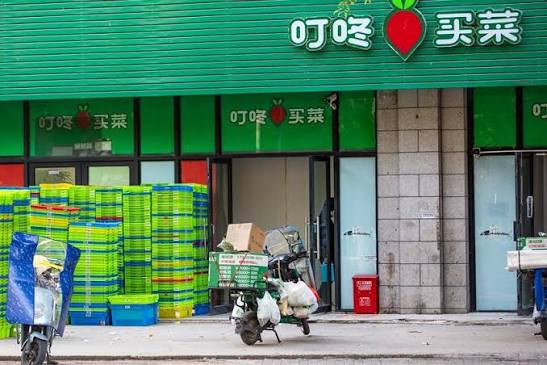
    Dingdong boosted second-quarter net income by 153 per cent to $40 million, lifted by higher domestic order frequency and an accounting adjustment on assets designated for sale.

    Revenue rose 8.6 per cent to $956.1 million for the three-month period, while gross merchandise value increased 11.8 per cent to $1.07 billion.

    Accounting Shift Drives China Earnings

    Net profit from operations in China surged 155 per cent. That increase stemmed primarily from the cessation of depreciation and amortisation charges on long-lived assets classified as held for sale under US GAAP rules. Overseas operations moved in the opposite direction, with net losses widening 166 per cent despite a 36.2 per cent rise in international revenue.

    The divergent performance comes as Dingdong prepares to hand over its domestic operations. In February, the grocer agreed to divest its China business to on-demand delivery giant Meituan. That transaction remains pending regulatory and closing conditions.

    Summer Peak Drives Daily Volumes

    Chief executive Song Wang credited higher order frequency among loyal members for driving the gains. Dingdong has now recorded non-GAAP profit across 15 consecutive quarters, alongside 10 straight quarters of year-over-year revenue expansion and positive GAAP net income.

    Trading accelerated further as the platform entered its summer peak in July. Monthly gross merchandise value hit a record high, with single-day sales exceeding RMB 100 million multiple times during the month.

    China’s instant-grocery sector has shifted decisively toward consolidation after years of heavy cash burn, forcing independent warehouse networks to integrate into larger delivery ecosystems or redirect resources abroad. Dingdong’s run of GAAP profitability shows the frontline warehouse model can deliver positive margins once promotional subsidies recede.

    Market attention now centers on the completion date for the Meituan transaction, which will determine how quickly Dingdong pivots its core focus toward international expansion.

  • Online Merchants Face Rising Fraud Rates as AI Tools Lower Attack Costs

    Online Merchants Face Rising Fraud Rates as AI Tools Lower Attack Costs

    Retailers face rising fraud losses as bad actors deploy low-cost artificial intelligence tools at scale, according to global payment processor Worldpay. A survey of 1,466 payment specialists across major markets including Australia shows fraud as a percentage of merchant revenue is climbing.

    The shift leaves digital store operators fighting automated attacks at checkout while trying to prevent unnecessary transaction rejections that destroy legitimate sales. Traditional card-not-present theft remains common, but pressure is shifting rapidly towards bot-driven credential stuffing, account takeovers, and refund abuse.

    The Cost of False Declines

    Rejecting good customer transactions out of caution carries a steep penalty. When checkout software incorrectly blocks a legitimate shopper, merchants lose both the immediate basket and the customer acquisition cost spent bringing that buyer through the sales funnel.

    Colin Baines, vice president of commercial and country manager at Worldpay, said false declines act as a silent drag on merchant margins. Using risk-based authentication backed by device intelligence and behavioral analytics allows retailers to challenge suspicious orders without adding friction to trusted buyers.

    Optimizing payment routing improves conversion. Implementing network tokenization, managing card credentials across their lifecycle, and configuring soft-decline retry schedules give merchants measurable lifts in completed orders across domestic card networks.

    Cross-Border Payment Routing

    Cross-border expansion introduces friction when checkouts fail to support local acquiring banks or domestic payment preferences. Presenting buyers with unfamiliar currencies, foreign checkout flows, or rigid 3D Secure rules increases cart abandonment.

    For retailers trading across Asia-Pacific markets, pairing stored network tokens with domestic acquiring infrastructure lifts card acceptance rates and cuts interchange processing expenses. Baines said store operators must treat payment routing and compliance as active components of their commercial strategy rather than administrative checkout settings.

  • Kogan Group Gross Sales Pass $1 Billion as Core E-Commerce Offsets Mighty Ape Loss

    Kogan Group Gross Sales Pass $1 Billion as Core E-Commerce Offsets Mighty Ape Loss

    Kogan Group lifted annual gross sales past $1 billion in the year ended June 30, driven by double-digit expansion across its core Australian e-commerce platform.

    Group revenue rose 5 per cent to $510 million, while statutory net profit after tax reached $11.2 million. The result masked a sharp divergence between the company’s flagship Australian portal and its struggling New Zealand subsidiary.

    The main Kogan.com business expanded gross sales and revenue by 16 per cent during the period, delivering $16.3 million in net profit. Management credited internal automation and AI-driven processes with lowering operational expenses, freeing cash to reinvest in customer marketing while defending profit margins.

    Restructuring the New Zealand Arm

    Mighty Ape remained a drag on bottom-line earnings, posting a $5.1 million net loss. Gross sales at the Auckland-headquartered online retailer fell 14 per cent, while annual revenue dropped 30 per cent as the group dismantled unprofitable operations.

    To stem the losses, management halved inventory from $21 million to $10 million and shuttered its Christchurch fulfillment center. Those reductions lowered quarterly fixed operating costs from $4.9 million to $3.4 million, pushing Mighty Ape into positive adjusted EBITDA in the fourth quarter.

    Higher-margin digital services cushioned the hardware contraction. Paid subscriptions via Primate, marketplace commissions, and the Mighty Mobile telecommunications service all expanded their share of the subsidiary’s total top line.

    Marketplace Shift Across Australasia

    The split performance mirrors a broader transformation across Australasian e-commerce, where pure-play retailers have moved away from holding heavy direct inventory to rely on third-party marketplace commissions and automated logistics. RetailNews Asia has tracked similar inventory purges at competing digital platforms seeking to protect gross margins against stubborn freight and handling costs.

    Group management confirmed it will maintain strict capital discipline across both divisions entering fiscal 2027, with full-year performance hinging on whether Mighty Ape can convert its fourth-quarter operating stability into sustained annual profit.

  • TikTok Shop Tracks Toward US$100 Billion in Global GMV by 2026

    TikTok Shop Tracks Toward US$100 Billion in Global GMV by 2026

    TikTok Shop is on track to surpass US$100 billion in global gross merchandise volume in 2026 as its social commerce format expands across Asia and Western markets.

    The projected milestone reflects steep annual transaction volume growth, driven by aggressive merchant acquisition in Southeast Asia and rapid adoption in the United States.

    Challenging Incumbents Across Southeast Asia

    ByteDance built TikTok Shop around short-form video feeds and live shopping broadcasts, funneling consumer traffic directly into merchant checkout flows. In Southeast Asia, the platform has eaten into market share held by Sea Group’s Shopee and Alibaba’s Lazada, particularly in Indonesia, Thailand, and Vietnam.

    Cross-border competition has intensified as PDD Holdings’ Temu and fast-fashion platform Shein push discount goods into the same consumer segments. TikTok Shop countered by integrating local logistics partnerships and offering subsidized shipping to lock in high-frequency buyers.

    Global Footprint and Platform Competition

    Western market expansion provides the second engine behind the US$100 billion trajectory. After scaling up operations in the United Kingdom and the United States, ByteDance began preparing localized rollouts in continental Europe and Latin America to diversify revenue away from single-market regulatory risks.

    RetailNews Asia notes that conventional marketplace apps rely primarily on search intent, while TikTok generates spontaneous purchases by inserting checkout prompts into entertainment feeds. That structural difference forced Shopee and Lazada to invest heavily in their own live streaming hubs to defend market share.

    The key metric to track heading into 2026 will be TikTok Shop’s take rate, as ByteDance lifts seller commission fees to convert platform volume into operating profit.

  • Alibaba Net Profit Plunges 75 per Cent on Heavy AI Infrastructure Spending

    Alibaba Net Profit Plunges 75 per Cent on Heavy AI Infrastructure Spending

    Alibaba Group reported a 75 per cent plunge in quarterly net profit to June as capital expenditure on artificial intelligence surged. Group revenue rose 9 per cent to 268.95 billion yuan, matching market forecasts while cloud computing gains offset slowing domestic commerce.

    Capital spending climbed 75 per cent year on year to 67.68 billion yuan in the three months to June 30. The Hangzhou-based group has already deployed half of its 380 billion yuan AI investment budget scheduled through 2029, buying server processors and expanding data centres to handle surging enterprise demand.

    Surging Compute Costs and In-House Silicon

    Chief executive Eddie Wu said the company expects to break even on its AI-related capital expenditure within three years at current gross margins. Revenue from AI cloud and compute services jumped 45 per cent to 48.44 billion yuan during the quarter, with annual recurring revenue from AI model-as-a-service exceeding 16 billion yuan.

    To rein in hardware expenses, Alibaba is replacing commercially procured processors with silicon built by its in-house chip division, T-head. The proprietary semiconductors are now running across clustered server racks for both model training and inference workloads, which management expects will widen operating margins as deployment expands.

    The margin squeeze mirrors the heavy infrastructure spending across Asia’s technology sector, where hyperscalers and platform operators are absorbing massive upfront costs before enterprise software monetization matures. Alibaba is defending its cloud dominance against domestic rivals Tencent and Baidu, while simultaneously backing frontier model developers such as Moonshot to anchor future compute traffic to its ecosystem.

    Reorganisation and Core Retail Headwinds

    Adjusted earnings per American Depositary Share fell to 8.52 yuan, trailing the 10.53 yuan consensus tracked by LSEG. Softer consumer demand in mainland China continues to weigh on the core marketplace division, prompting chief financial officer Toby Xu to highlight macroeconomic friction across domestic online shopping.

    Wu now leads the dedicated Alibaba Token Hub following an internal restructuring that split operations into four divisions: e-commerce, AI cloud and compute, model applications, and other businesses. Affiliate Ant Group recorded a 1 per cent rise in quarterly profit as it tests AI shopping assistants and digital health tools.

    Management is targeting overall profitability for the group’s quick-commerce unit by fiscal 2029, while tracking a three-year payback window on its current infrastructure outlays.

  • Tokopedia and TikTok Shop Lift Indonesian Merchant Sales 51 per Cent

    Tokopedia and TikTok Shop Lift Indonesian Merchant Sales 51 per Cent

    Tokopedia and TikTok Shop drove a 51 per cent increase in sales of Indonesian local products during the first half of 2026. The combined marketplace moved nearly 700 million items over the period.

    Gross merchandise value for the joint #BeliLokal initiative climbed 14 per cent during the six months. Merchant participation rose 50 per cent compared with the first half of 2025.

    Expanding beyond Java

    Agency Bukacerita created an Independence Day campaign named Pahlawan Beli Lokal for the platform. It promotes domestic makers of fashion, packaged food, automotive goods, and electronics. The campaign runs on social feeds and a dedicated web hub, featuring regional brands like Malang snack producer Apelicious and cosmetics brand Facetology.

    According to internal survey data from TikTok Shop, 72 per cent of participating sellers gained new customers through discovery commerce tools. Another 67 per cent used the channel to launch new product lines. Live shopping sessions, affiliate tie-ups, and short videos generated most of those initial sales.

    ByteDance and GoTo are working to satisfy Indonesian regulators following the state-mandated merger of TikTok Shop and Tokopedia. Both operators face stiff competition from Shopee and direct-from-factory platforms in Southeast Asia’s largest consumer market. Alignment with local merchants remains critical for their political and commercial standing.

    Training and registration push

    The platforms have turned the promotional campaign into a permanent merchant onboarding track. More than 4,800 micro, small, and medium enterprises, creators, and affiliates have completed training modules. These sessions cover intellectual property rules, live selling, and official business registration numbers.

    Most participating merchants operate outside Greater Jakarta. Half of the training workshops took place outside Java to tap production hubs across the outer islands.

    “In the spirit of Independence Day, we want to continue strengthening collaboration with the government, creators, partners, and the community through #BeliLokal so that more local businesses can move up a class, build more competitive businesses, and grow sustainably,” said Stephanie Susilo, executive director of Tokopedia and TikTok Shop Indonesia.

    Plans are underway to expand regional onboarding workshops into secondary cities across Sumatra and Sulawesi through the fourth quarter.

  • India Quick Commerce Discounts Ease to 20% as Rivals Add Dark Stores

    India Quick Commerce Discounts Ease to 20% as Rivals Add Dark Stores

    Average discounts across India’s quick-commerce platforms have dropped to between 19 and 20 per cent, cooling from early-year peaks as operators focus on unit economics. The pull-back comes even as larger e-commerce rivals prepare to roll out up to 1,500 new dark stores over the next 12 to 18 months, according to research by UBS.

    Price discounting reached its height in early 2026 when Amazon Now raised discount rates from 26 per cent in November 2025 to 57 per cent two months later. Competitors responded in kind. Flipkart Minutes and incumbent platforms increased promotional discounts by 200 to 300 basis points across key retail categories before the pricing war settled over the past four months.

    Dark Store Land Grab

    The total addressable market for quick commerce across India is projected to reach $59 billion by FY30, upgraded by UBS from an earlier forecast of $34 billion. Quick-commerce networks now operate across more than 100 towns and are expected to capture roughly half of all incremental growth in online retail across the country.

    Network footprints are widening beyond standard grocery lines. Dark stores increasingly handle consumer electronics, personal care, and apparel, directly competing with traditional parcel delivery networks. To contest this volume, conventional e-commerce groups are setting up 400 to 600 micro-warehouses each, with plans to scale their combined networks to between 1,200 and 1,500 facilities.

    Unit Economics and Margins

    Incumbents enter this new round of competition with substantial cash reserves. Blinkit and Swiggy’s Instamart hold roughly Rs 18,000 crore each on their balance sheets, while Zepto holds about Rs 7,000 crore. Blinkit posted positive adjusted EBITDA margins in the first quarter alongside rapid net order value growth. Instamart reached contribution-margin break-even in May, lifting its sequential quarterly margin by 160 basis points to negative 0.2 per cent. Zepto cut promotional pricing and removed more than four million unprofitable customer accounts before restarting growth spending in July.

    Across Asia’s instant-delivery markets, platforms in South Korea and Southeast Asia experienced a similar shift once order density matured: headline subsidies gave way to monetisation through merchant advertising, platform fees, and branded marketing tie-ups. In India, UBS reduced its steady-state operating margin forecast for the sector by 250 to 300 basis points, reflecting the lower margins found in non-grocery merchandise and higher fulfilment costs outside top-tier metros.

    Attention now shifts to food-delivery user activation, where platforms report that more than 70 per cent of accounts transact less than once a month. Zomato and Swiggy are rolling out smaller basket sizes, tighter delivery radiuses, and reduced restaurant commissions to draw those dormant accounts into regular ordering cycles.

  • Alibaba and ByteDance Divest from Gaming and Retail to Fuel AI Ambitions

    Alibaba and ByteDance Divest from Gaming and Retail to Fuel AI Ambitions

    Alibaba Group Holding and ByteDance are restructuring their business portfolios, selling off non-core assets in gaming and retail to private equity firms. This strategic shift aims to re-focus substantial resources and investment into the burgeoning field of artificial intelligence, as competition in the AI sector intensifies across Asia.

    Strategic Divestment For AI Focus

    The move sees Alibaba Group Holding in the process of selling Lingxi Games, its video game unit, to a private equity fund. This divestment reflects a broader trend among leading Chinese technology firms to streamline operations and concentrate capital on high-growth, strategic areas like AI. The decision comes as these companies face mounting pressure to innovate and secure a leading position in the global AI race.

    For retailers and consumer brands in Asia, this reorientation by tech giants like Alibaba has significant implications. Alibaba’s strong presence in e-commerce means that resources diverted to AI are likely to enhance capabilities in areas such as personalised recommendations, supply chain optimisation, and customer service automation. Similarly, ByteDance’s TikTok, a major platform for consumer engagement, could see advanced AI integration impacting everything from content delivery to advertising effectiveness.

    Implications For Asia’s Retail And Tech Sectors

    The decision by Alibaba and ByteDance signals a clear prioritisation of AI development over other business segments, including those with direct ties to consumer spending like gaming and certain retail operations. While the full scope of ByteDance’s retail divestments is not detailed, Alibaba’s move with Lingxi Games indicates a willingness to shed assets to fund core strategic initiatives. This aligns with broader market trends where technology companies are doubling down on AI infrastructure and research, viewing it as the next frontier for competitive advantage.

    This redirection of investment could lead to more sophisticated AI tools and platforms becoming available for businesses, potentially driving efficiency and innovation within the retail and consumer sectors. RetailNews Asia has observed similar strategic realignments across the region, where companies are either investing heavily in AI or partnering with AI specialists to stay competitive in an increasingly tech-driven market.

  • US Billionaires Boost Baidu Bets Amid AI Surge, Pull Back from Alibaba and JD.com

    US Billionaires Boost Baidu Bets Amid AI Surge, Pull Back from Alibaba and JD.com

    Major US investors are rebalancing their portfolios in Chinese technology stocks, with a notable shift towards Baidu as artificial intelligence capabilities expand. Stanley Druckenmiller, through his Duquesne Family Office, re-entered the US-listed Chinese market by acquiring 88,200 Baidu American depositary receipts (ADRs) during the second quarter. This purchase, valued at approximately US$10.1 million, marks his firm’s first investment in such companies since exiting Alibaba Group Holding in late 2023.

    Similarly, David Tepper’s Appaloosa Management nearly doubled its investment in Baidu, increasing its holdings to 1.3 million ADRs, worth about US$148 million. This move contrasts with the hedge fund’s earlier stance in late 2024, when Tepper indicated a broad increase in China exposure.

    Shifting Focus To AI Innovations

    Baidu, traditionally known for its dominant search engine, has aggressively pivoted to artificial intelligence. The company’s strategic focus now includes its Ernie large language models, cloud computing services, and autonomous driving technology. This emphasis on AI appears to be a key driver for the renewed investor interest from Wall Street billionaires.

    The increased investment in Baidu coincides with a reduction in other Chinese internet holdings for some investors. Appaloosa Management, for instance, cut its Alibaba stake by 42 percent and completely divested from JD.com and PDD Holdings. These adjustments reflect a selective approach to the Chinese tech sector, prioritizing companies with strong AI growth narratives.

    Implications For Asia’s Tech Market

    These investment shifts by influential global investors underscore the growing significance of AI capabilities in determining value within Asia’s technology sector. As Baidu strengthens its AI ecosystem, including efforts in large language models and autonomous vehicles, it could reshape competitive dynamics, especially in cloud services and advanced consumer tech, areas RetailNews Asia actively tracks across the region. Such movements by prominent investment figures often signal broader trends that impact market sentiment and strategic directions for companies operating in Asia-Pacific’s fast-evolving digital economy.

  • Shein’s Hong Kong IPO Slashes Valuation to $25 Billion amid E-commerce Regulatory Challenges

    Shein’s Hong Kong IPO Slashes Valuation to $25 Billion amid E-commerce Regulatory Challenges

    Online fast-fashion retailer Shein is expected to have a company valuation of roughly $25 billion in its upcoming Hong Kong initial public offering (IPO), a significant decrease from its earlier valuation of approximately $100 billion four years ago. This change comes amid a slowdown in the company’s growth.

    Sources familiar with the situation have indicated that the current valuation of Shein, a company that made its name selling affordable clothing such as $5 dresses and $10 jeans, potentially lies between $25 billion and $28 billion. This represents a decrease from the initially projected valuation of $30 billion to $40 billion earlier this month.

    The Impact of Market Changes

    This reduction in valuation can be attributed to significant shifts in Shein’s most prominent markets, including an increased crackdown on e-commerce platforms selling inexpensive Chinese-manufactured goods. This has negatively affected the company’s growth prospects.

    Shein, which was established in China in 2012 and now sells to customers in approximately 160 countries, is poised to launch its eagerly-anticipated IPO this week.

    The company is reportedly planning to issue up to 8% of its total shares in the IPO. Should the company be valued at $25 billion, this would equate to an offering size of up to $2 billion.

    Economic Factors and Valuation

    Shein’s net income in 2025 stood at $2.06 billion, indicating that a $25 billion valuation would result in investors valuing the company at around 12 times its earnings.

    However, several factors have led to a decrease in Shein’s valuation. Slower growth, increased trade costs, tighter regulatory scrutiny, and heightened competition have all contributed to a decrease in investor appetite for the company.

    Shein’s net revenue saw a growth rate of 41.1% in 2023 and 20.7% in 2024. However, growth slowed dramatically to just 8% last year, resulting in total revenue of $41.8 billion. In the first quarter of this year, revenue growth was a mere 1.1% due to the impact of US customs duties and tariffs implemented in May last year.

    Questions & Answers

    What is the expected valuation of Shein in its upcoming Hong Kong IPO?
    The expected valuation of Shein in its upcoming Hong Kong IPO is around $25 billion.

    What factors have contributed to a decrease in Shein’s valuation?
    Factors such as slower growth, higher trade costs, increased regulatory scrutiny, and intensified competition have contributed to a decreased valuation.

    What was Shein’s net income in 2025, and what does this mean for its valuation?
    Shein’s net income in 2025 was $2.06 billion. If the company is valued at $25 billion, this would mean investors value Shein at around 12 times its earnings.

  • JD.com Forecasts Rise in Home Appliance Sales in H2 Despite First Revenue Drop in Over a Decade

    JD.com Forecasts Rise in Home Appliance Sales in H2 Despite First Revenue Drop in Over a Decade

    JD.com, a prominent marketplace for consumer electronics in China, forecasted an uptick in home-appliance sales for the second half of the year during their recently held quarterly review. This projection was made despite their first reported decrease in quarterly income in over a decade.

    The CEO of the company, Sandy Xu, addressed the downturn in revenue from electronic and home appliances during a conference call with analysts. She attributed the decline to an elevated comparison base from the previous year and escalated raw material costs. However, she noted that there was a resurgence in momentum entering into June.

    Expectations for Growth

    As she peered into the coming months, Xu expressed her confidence in the potential growth of the consumer electronics category, even as its continually rising prices may continue to impact consumer demand adversely. She postulated that this growth will be “meaningful” and is partly due to the easing of the challenging year-on-year comparison.

    However, the impact of these predictions was somewhat dampened as US-listed shares of the company saw a decrease of 3.5 per cent in trading during the GMT 1342 time slot.

    The Uphill Task of Rejuvenating Consumer Spending

    Despite the setbacks, JD.com exceeded estimated quarterly revenue projections, with the annual 618 shopping festival playing a significant role. The festival, one of the country’s largest online retail events, ran for more days than previous years, offering retailers and brands additional time to vie for consumer spending via deep discounts and promotional campaigns.

    However, total revenues still saw a dip of 2.9 per cent, settling at 346.4 billion yuan (US$51.37 billion) in the quarter ending in June. This underlines the ongoing struggle to rejuvenate consumer spending in China. This struggle is exacerbated by consumer apprehension concerning job security and the prolonged downturn in China’s property sector, which has weakened consumer confidence.

    The company reported a net profit for the quarter of 7.1 billion yuan, a notable improvement compared to last year’s 6.2 billion yuan in the same period. The non-GAAP net profit for the quarter was 8.9 billion yuan, showing an impressive 20 per cent increase from the second quarter of 2025.

    Questions & Answers

    What factors were attributed to the recent dip in JD.com’s revenues?
    The decline in revenues was attributed to an elevated comparison base from the previous year and increased raw material costs.

    What is the company’s projection for the second half of the year?
    JD.com predicts an increase in home-appliance sales during the second half of the year.

    How does JD.com plan to rejuvenate consumer spending?
    One strategy is through extended online retail events like the annual 618 shopping festival which offers deep discounts and promotional campaigns to consumers.