Category: Finance

Retail News Asia is committed to providing both local and global retailers with the latest Finance news throughout the Asian market. This on a daily base.

  • Maybank widens presence in Laos with second Vientiane branch

    Maybank widens presence in Laos with second Vientiane branch

    Malayan Banking Bhd (Maybank) has expanded its network in Laos with a second branch in the capital Vientiane, thus establishing a greater presence in one of the fastest expanding economies in Asean.

    The branch, located in the commercial district of Nongduang, offers a full spectrum of banking services, and aims to serve the needs of the local community as well as customers from across the region having trade and investment links in the country.

    The new branch was officially launched by Bank of the Lao PDR (central bank) deputy governor Vathana Dalaloy at an event hosted by Maybank chairman Tan Sri Megat Zaharuddin Megat Mohd Nor.

    Maybank international CEO Pollie Sim said the opening of the Nongduang branch will strengthen Maybank’s presence in Indochina and enhance its ability to meet the banking needs of customers, particularly the growing investor base into the country.

    “Laos is among the strongest performing economies in the region, with steady economic growth of around 8.5% for the past four years and is anticipated to achieve 7.5% real gross domestic product growth on average from 2016 to 2020, according to the government’s eighth development plan.”

    Sim said the first Maybank branch in Vientiane, which was opened in 2012, has experienced encouraging growth with loans and deposits rising at an annual average of 46% and 78% respectively over the last two years.

    “We anticipate that the opening of this second branch will further boost our franchise in the country and lift our loans and deposits growth to over 70% and 100% respectively by end of 2016,” she added.

    Services offered by the two Maybank branches in Laos include retail and business banking, foreign exchange, remittances, treasury as well as ATMs. The retail offerings include mortgages and personal loans while business banking services include term financing and trade financing.

    The two branches have a paid-up capital of LAK200 billion (about RM100 million) a staff strength of 30 in total.
  • Malaysia among first in world with Retail Workbench iPad app, said Standard Chartered

    Malaysia among first in world with Retail Workbench iPad app, said Standard Chartered

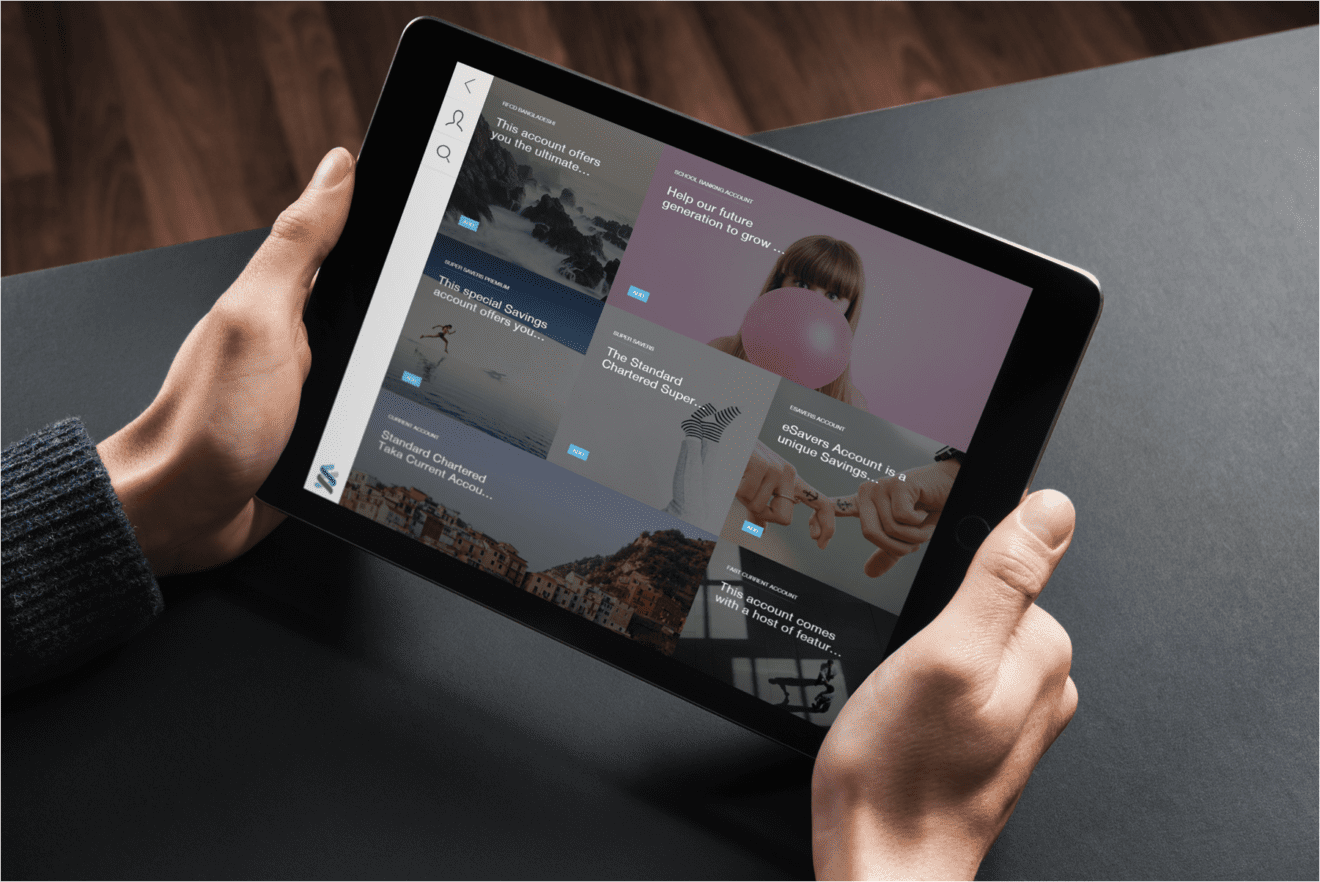
    Malaysia is one of the first six markets to go live with Retail Workbench, a digital tablet-based sales-and-service tool, according to Standard Chartered Bank, which globally launch of its Retail Workbench,

    The iPad tool is also live in India, the UAE, Bangladesh, Nigeria and Kenya, said Aaron Loo, country head, Retail Banking, Standard Chartered Bank Malaysia.

    “Banking should be easy and convenient – that’s what the Retail Workbench is all about,” said Loo, adding that the application is integrated with the Bank’s back-end infrastructure, which will allow sales staff to open an account for a client in any location. Banking services such as loan approvals and credit card issuance will be fast, simple and completely paperless.

    “We are harnessing technology to make banking a seamless experience for both clients and staff. Going paperless fits into the increasingly mobile lifestyle of our clients while improving cost efficiency and productivity by freeing up staff’s time to focus on what really matters, which is serving the client,” he said.

    In addition, Loo said the ‘the bank on an iPad: Retail Workbench’ also puts a set of current and savings account, credit card and personal loan products on one mobile platform – along with product information and marketing brochures – so sales staff can answer questions and respond to client needs in person, at any location.

    He said that with this fully digital device, we can process client requests from anywhere, with the data moving straight through to the Bank’s back-end operations in near real-time. Previously, sales staff could visit clients in person but the paperwork had to be manually entered into the Bank’s systems back at the branch or Bank’s premises.
     

    Aaron Loo - Standard Chartered Malaysia 

    Photo – Aaron Loo, Country Head, Retail Banking, Standard Chartered Bank Malaysia

    This means that clients only need to give their personal data to the bank once to create a profile that can be used for future purchases. Sales staff use the iPad’s built-in camera to securely snap a picture of identity documents so there is no need to fill out multiple forms and no missing data.

    Loo said Retail Workbench has already revolutionised the banking industry in Korea when it was launched in 2014, cutting account opening time in the digitally advanced country to five minutes and credit card issuance to less than half an hour. It has since won numerous industry awards for innovation and outstanding client service.

    Due to differences in local infrastructure, turnaround times and other features of Retail Workbench will vary across the seven markets following the global launch, he added.

    A statement added that Standard Chartered will successively add capabilities and enhance performance in each market over the coming months and equip more sales teams with the device. By the end of 2017, Retail Workbench will be in the hands of staff in 18 markets across Asia, Africa and the Middle East.

     Digitising banking

    The statement added that this global launch marked “a milestone in Standard Chartered’s strategy of using digital technology to deliver a better banking experience to clients. The Bank last year announced it will invest US$1.5bn in technology over three years. Standard Chartered was named the World’s Best Consumer Digital Bank in 2015 by Global Finance magazine and also won Best Consumer Digital Bank in Malaysia in 2010, 2014 and 2015.”

    Standard Chartered Bank, a member of the Standard Chartered Group was established in Malaysia in 1875 and incorporated as Standard Chartered Bank Malaysia Berhad in 1984. Standard Chartered employs close to 7,000 employees in all its Malaysian operations.


  • HSBC Gets Approval for Credit Card Operations in China

    HSBC Gets Approval for Credit Card Operations in China

    HSBC Holdings efforts to scale up its retail and wealth management business in China got a major boost with the U.K.-based company receiving permission to start a credit card business in China’s $1 trillion market.

    The approval from the Chinese authorities came after Peter Wong, Asia-Pacific Chief Executive Officer at HSBC, announced in a weekend interview that HSBC ended its joint venture with Bank of Communications Co. However, Wong believes that there are several other avenues of collaboration with Bank of Communications and that the two companies share healthy business terms.

    HSBC intends to maintain its stake of around 19% in the Chinese lender, Wong said on Saturday in an interview on the sidelines of China’s annual congress of lawmakers in Beijing.

    However, Wong did not specify when HSBC won regulators’ approval or provide details on how the business will be moved forward.

    The move makes HSBC the third foreign credit-card issuing company after Citigroup Inc. (C – Analyst Report) and The Bank of East Asia, Limited (BKEAY – Snapshot Report) to get approval to operate solo on the mainland. The permission to start credit card operations in the country would facilitate HSBC’s plan to expand China footprint.

    At its June 2015 Investor Day conference, HSBC unveiled plans to make increased investments in the under-penetrated Asian markets, with particular focus on China. Notably, the company continues to perceive China as an “engine of growth” and hence, intends to capitalize on Hong Kong’s high-quality customer base, where the market has grown over 13% in the past two years. Also, an ageing Chinese population is undeniably driving the demand for retirement and protection products in the country.

    More importantly, HSBC believes that building operations in its most-profitable Asian business will help it offset the negative impact from soaring expenses. Moreover, aided by such investments, the company estimates growth in pre-tax profits to outpace that in risk-weighted assets or RWAs, thereby enhancing its return on RWAs.

    Though Chief Executive Officer Stuart Gulliver’s plan seemed to suffer due to falling commodity prices, a slowing Chinese economy and a pretax loss in the fourth quarter, an independent credit card division in China would help HSBC expand the client base for its retail bank and enhance HSBC’s access to a rapidly growing market.

    According to a Bloomberg report, getting approved for its own operation in China “is a meaningful step for HSBC as it gives the bank the autonomy to run the business,” said Chen Xingyu, a Shanghai-based analyst at Phillip Securities Research. “Since the Pearl River Delta is HSBC’s focus, having its own credit-card business can help the bank expand in the region.”

    “There’s still strong demand for credit cards in China’s first-tier cities, but the business is getting saturated in some areas,” said Chen at Phillip Securities. “That’s why the potential in smaller cities is even bigger.”

    Though the Chinese economy is currently showing signs of weakness, we believe the country will resume its strength, given a sturdy performance history as well as efforts by its government to boost growth. This, in turn, will support HSBC’s prospects in the country.

  • Bank of Korea likely to keep policy rate on hold tomorrow

    Bank of Korea likely to keep policy rate on hold tomorrow

    The Bank of Korea is likely to keep its policy rate unchanged at 1.5% during its upcoming meeting. The meeting will mainly focus on the weakness in January’s activity data. Also, there is a higher probability for another cut in GDP forecasts during the April meeting. But, t he rebounding sentiments in global financial markets and February’s macroeconomic data will help the cautious stance of a majority of the MPC members.

    The February’s monetary policy meeting’s minutes showed central bank policymakers’ reluctance regarding further rate cuts, in spite of further decline in the outlook of growth. All members had agreed that there were growing threats on the downside for growth, but only one member had voted for a rate cut.  The other members didn’t support a cut in interest rate because of the usual worries regarding financial stability, the requirement to secure the room for policy actions, the lack of further downside threats for inflation and the expected diminishing marginal impacts of additional easing actions.

    January’s activity data indicated broad weakening of growth momentum. The drop in manufacturing production was expected given the considerable decline in January exports. However, the contraction of retail sales and services production was a major concern because consumption was the main over GDP growth driver in H2 2015.

    As facility investment did not strengthen in December, it was only construction activity that kept its strength amongst the different activity indices. However, strength in February’s exports alleviated worries regarding growth. The renewed tax cut on autos will stimulate consumption as the retail sales contraction in January was mainly due to auto sales after the termination of tax cut in December. A considerable rise in February’s headline inflation to 1.3% supports most of the MPC members’ views that the central bank’s current inflation forecast is appropriate.

    The Bank of Korea is unlikely to change its policy rate throughout 2016. The unwillingness of MPC members regarding additional easing implies that the central bank is expected to keep rate unchanged even if the GDP forecast is revised downwardly from the current estimate of 3%.

    Also, BoK’s projection of potential growth in 2017 might be as low as 2.8%. Considerable surprises on the downside in growth, which can lead to a sizable reduction in the GDP growth forecast to a level of about 2% or below is expected to be a precondition for a further cut in interest rate.

    © EconoTimes 2015. All rights reserved. The EconoTimes content received through this service is the intellectual property of EconoTimes or its third party suppliers. Republication or redistribution of content provided by EconoTimes is expressly prohibited without the prior written consent of EconoTimes, except for personal and non-commercial use. Neither EconoTimes nor its third party suppliers shall be liable for any errors, omissions or delays in content, or for any actions taken in reliance thereon.

  • SM Investments Corporation wins two Anvil Awards for its Annual and ESG Reports

    SM Investments Corporation wins two Anvil Awards for its Annual and ESG Reports

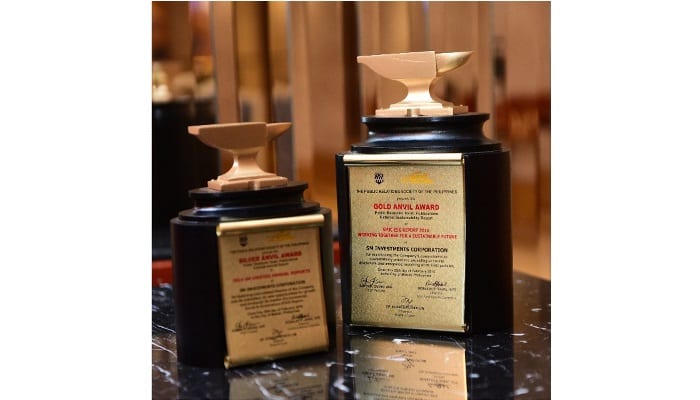
    SM’s first 2014 ESG report with the theme, “Working Together for a Sustainable Future”, earned a Gold Anvil Award for manifesting the company’s commitment to sustainability practices and for providing accurate disclosure and integrated reporting of its ESG policies. It is a group-wide report highlighting good governance, social development and environmental consciousness of SM companies such as SM Retail, SM Prime Holdings, and BDO Unibank. SM recognizes that adhering to ESG global best practices is a journey as global guidelines and the needs of SM’s stakeholders continue to evolve.

    The 2014 Unified Annual Reports bagged a Silver Anvil Award for featuring inter-related themes of the company and its subsidiary on new opportunities for growth.

    The 2014 Unified Annual Reports consist of the Annual Report of SM with the theme, “Pursuing New Opportunities for Growth” and that of SM Prime Holdings, Inc. that carried the theme, “Building New Opportunities for Growth”.

    Dubbed as the “Oscars” of the public relations industry in the Philippines, the Anvil is presented to the outstanding public relations tools and programs that have met the high standards set for each category.  PR practitioners, industry communications specialists, academicians and business persons attended the event.

  • 2016 China Fixed-Asset Investment Growth Target at Around 10.5%

    China’s economic planning agency said Saturday that it aims to realize around 10.5% growth in fixed-asset investment this year.

    Beijing had set a 15% growth target for fixed-asset investment in 2015, but actual growth came in slower at 10% as the world’s second-largest economy lost momentum.

    The National Development and Reform Commission also said it expected retail sales to increase by 11% in 2016, compared with a target of 13% in 2015. Last year, China’s retail sales rose 10.7% from a year earlier.

    China attracted $126.27 billion in foreign direct investment in 2015, up 6.4% from a year earlier, and it reported $ 118.02 billion overseas direct investment last year, up 14.7% year-over-year.

  • Indonesia to reopen banking transactions with Iran

    Indonesia to reopen banking transactions with Iran

    Indonesia said it is open to resume banking transactions with Iran following the lifting of economic sanctions against Iran.

    “Banking relations, an obstacle we are facing, will soon be resumed,” President Joko Widodo said after receiving Irans Foreign Minister Mohammad Javad Zarif on the sidelines of the 5th Organization of Islamic Cooperation Extraordinary Summit on Palestine and Al Quds here on Monday.

    The President said economic and investment cooperation between the two countries had been hindered because banking transactions were closed due to the imposition of economic sanctions against Iran.

    He said Indonesian banking authorities had agreed to follow up on the cooperation plan.

    “The chairman of the Financial Service Authority (OJK) said just now that the banking transactions would soon be resumed to develop and strengthen economic relations between the two countries,” he said.

    Bank Indonesia (the Central Bank) and OJK would discuss the mechanism for cooperation with Iranian banking officials.

    Due to the imposition of economic sanctions several years ago, Iranian banks were unable to conduct transactions with overseas banks.

    Since Irans nuclear program came to be known in 2002, the United Nations, the European Union, the US and several other countries had imposed economic sanctions on Iran.

    After these sanctions were revoked, the flow of trade to and from Iran is expected to become easier.

  • ANZ wealth chief Joyce Phillips leaves after restructure

    ANZ wealth chief Joyce Phillips leaves after restructure

    ANZ Bank’s wealth chief, Joyce Phillips, is departing the banking giant following a restructure of the $67 billion institution’s wealth management arm.

    Chief executive Shayne Elliott said the group was simplifying its approach to wealth management, which includes the bank’s insurance, superannuation and investments products.

    As a result of the changes, Ms Phillips, who led ANZ’s wealth, marketing and innovation divisions, will leave.

    ANZ Bank's wealth chief, Joyce Phillips, is departing the banking giant following a restructure of the $67 billion ...ANZ Bank’s wealth chief, Joyce Phillips
    “The simplified approach also provides the opportunity to focus on improving returns and capital efficiency from our insurance, superannuation and investments product business given higher regulatory capital requirements,” Mr Elliott said.

    The moves, foreshadowed by Street Talk, comes after ANZ appointed Google’s Australian boss, Maile Carnegie, to the newly created position of group executive for digital banking.

    Reporting to Mr Elliott, Ms Carnegie will have responsibility for digital projects, innovation and “strategic relationships” with the fintech sector that is seeking to challenge the power of the big four banks.

    Mr Elliott said the wealth division had achieved a “significant amount” under Ms Phillips’ watch since it was formed in 2012.

    ANZ’s global wealth arm posted a net profit of $601 million during the last financial year – an 11 per cent increase from 2014. The division contributed less than 10 per cent of ANZ’s profits.

    In an internal company interview, Mr Elliott said the bank wanted to “really maximise” the 10 per cent of group capital that was currently locked in the wealth division.

    “It is going to be material in the terms of the impact on the wealth business but for shareholders, given that it’s only 10 per cent, it will be a good thing but it’s unlikely that it’s going to be a dramatic outcome for shareholders,” he said.

    The restructure will see wealth effectively move into ANZ’s retail business. ANZ’s private bank division will report to Fred Ohlsson, group executive Australia and ANZ Financial Planning will transition to be part of the retail distribution arm.

    The group’s New Zealand wealth business will fall into the expanded retail, business banking and wealth division.

    Wealth in Asia will join Retail Asia, while the group’s remaining insurance, superannuation and investments activities in Australia will be rebranded Australia Wealth. Alexis George, ANZ’s managing director of insurance, will head the business and report to Mr Elliott.

    Sources said the break-up of the wealth division could be seen as a precursor to a potential sale in the next 12 months.

    ANZ has looked at stepping up a process of divestments. Last year, the bank sold its Esanda dealer finance unit to Macquarie Group for $8.2 billion. It is also reviewing its non-controlling interests in Asia.

    ANZ shares have fallen 35 per cent in the past 12 months to $23.07, compared with the 17 per cent fall of the benchmark S&P/ASX200.

  • China court jails 24 people over $1.5-bln financial fraud

    China court jails 24 people over $1.5-bln financial fraud


    A court in southern China has jailed 24 people for fraudulently raising nearly 10 billion yuan ($1.5 billion) in one of the country’s biggest financial scams, the official Xinhua news agency said.

    The group was convicted of illegally raising funds during the decade to 2012 from more than 230,000 investors, mainly senior citizens who put in their life savings, it said, citing the court.

    Guangdong Bangjia Leasing Co set up four firms in the southern province and many branches and subsidiaries across China, luring retail investors to buy memberships and fund nonexistent loans by promising returns of as much as 47 percent.

    The case spotlights growing risks in a loosely regulated wealth management products industry, which lures millions of unsophisticated retail investors to high-yield products offered by opaque online finance firms and privately run exchanges.

    In February, authorities arrested 21 officials of Ezubao, once China’s biggest peer-to-peer lending platform, which collected $7.6 billion in less than two years from more than 900,000 investors.

    Ezubao used savvy marketing, authorities said, to fund “a complete Ponzi scheme”, that used investor funds to support a lavish lifestyle for company executives.

    Last year, hundreds of angry investors also hit the streets in Beijing and Shanghai after losing $6 billion from the Fanya Metals Exchange, which offered investment products promising an annual return of up to 14 percent.

    The Guangzhou Intermediate People’s Court on Monday sentenced the main suspect in the Guangdong fraud, Jiang Hongwei, to life in prison, while the others received terms ranging from 3 years to 14 years, Xinhua said.

    The court has frozen and seized their assets, including 127 vehicles and 43 villas, but prosecutors said few victims might get their money back, since Jiang had squandered millions on luxuries, the agency added.

    Some older investors who lost money in the Guangdong fraud said they were attracted by its fancy branding.

    “Their grand exhibition occupied six halls,” Xinhua quoted one elderly woman from Jiangsu province as saying.

    “After attending it, I felt assured and decided to invest 700,000 yuan,” she added. “It was all the savings my husband and I had.”

    ($1=6.5397 Chinese yuan)


  • SGX proposes 10% minimum retail tranche for mainboard IPOs

    SGX proposes 10% minimum retail tranche for mainboard IPOs

    The Singapore Exchange is proposing that mainboard companies allocate to retail investors a minimum 10 per cent of shares in their initial public offers (IPOs), up to a maximum of $100 million.

    Between 2010 and last year, market debutantes on average set aside only 8 per cent of their IPO shares for retail investors, the SGX said.

    But over the same period, 90 per cent of IPOs received applications for their public subscription tranches amounting to greater than 10 per cent of the total offer size.

    “SGX’s proposal for a minimum 10 per cent retail allocation for shares of mainboard IPOs is aimed at giving individuals more investing opportunities in the Singapore equities market,” said chief executive Loh Boon Chye.

    “While market conditions may have been uncertain of late, this initiative is for the long term and is part of overall enhancements to the Singapore stock market.”

    This is the second time that the bourse operator has suggested introducing a minimum IPO allocation for retail investors. The first time it did so was in in 2012, when it proposed a 5 per cent retail allocation.

    Yesterday’s proposal is a recalibrated one that takes into account the feedback the SGX received from the 2012 consultation and data from IPOs launched between 2010 and 2015, it said.

  • Mandiri’s profit up 2.3 percent to Rp20.3 trillion in 2015

    Mandiri’s profit up 2.3 percent to Rp20.3 trillion in 2015

    State lender Bank Mandiri posted a net profit of Rp20.3 trillion last year, up 2.3 percent from Rp19.8 trillion a year earlier.

    The profit grew by one-digit percentage as the bank allocated most of its funds for reserves, Bank Mandiri President Director Budi Gunadi Sadikin said in a public statement here on Tuesday.
    The bank saw its reserve fund rising significantly at the end of 2015 to Rp12.04 trillion from Rp5.5 trillion in the same period of 2014.

    “Admittedly, part (of our income) was put in reserves to protect the bank from risks of non-performing loans (NPL),” he said. With the improving economic condition, he believed the banks profit will increase in 2016, but refused to divulge the target set for profit growth. The bank saw its fee-based income hitting a record high of 23.7 percent or Rp18.6 trillion, and operating income growing 18 percent to Rp67.1 trillion. The amount of credits extended last year grew by 12.4 percent to Rp595.5 trillion, while its consolidated net interest margin (including that of its sharia unit) rose by 0.11 percent to 6.08 percent.

    The net ratio of NPLs stood at 0.9 percent last year. As of December 31, 2015, the banks assets reached Rp910.1 trillion, up 6.4 percent from Rp855 trillion the previous year.

  • StanChart still profitable in Singapore

    StanChart still profitable in Singapore

    Singapore remained one of the few bright spots for Standard Chartered last year amid huge losses elsewhere.

    Profit before tax in Singapore was US$567 million (S$796 million) in the 12 months to Dec 31, down 33.4 per cent year-on-year but still the second best country performance.

    Hong Kong’s profit contribution was top, at US$1.49 billion, but still down 17.9 per cent compared with a year ago. In China, profit pared 45.3 per cent year-on-year to US$88 million, according to the group’s results released overnight.

    Elsewhere, signs that StanChart was struggling amid global headwinds were more apparent.

    In India, it suffered a loss before tax of US$981 million, a huge reversal from 2014’s profit of US$561 million. Its losses in Britain widened from 2014’s US$154 million to US$1.41 billion last year.

    The banking group reported a total loss before tax of US$1.52 billion, down from a US$4.24 billion profit in 2014.

    Group chief executive Bill Winters warned of a choppy outlook, noting in the annual report: “The economic and geopolitical backdrop for the group clearly deteriorated over 2015 and has not improved into 2016.”

    But StanChart’s business in Singapore, where it employs about 7,000 people, presents a rosier picture.

    “The bank in Singapore remained profitable in 2015. We saw a double-digit year-on-year growth in retail deposits and bancassurance, achieved a substantial increase in wealth management market penetration and grew our priority banking client base,” Singapore chief executive Judy Hsu said in a statement yesterday.

    She added: “We also maintained positive business momentum in financial markets, driven by a significant increase in foreign currency volume and revenues, and improved on the quality and interest margins of transaction banking’s cash income business.

    “Singapore is a core market for the bank and plays a significant role as a hub for our global business and as a gateway to Asean… and we will continue to invest in the growth of our Singapore franchise across retail, private banking, commercial and institutional clients.”

    Ms Hsu’s comments came amid concerns about how global banks are faring in Singapore. In November, StanChart moved to cut 15,000 jobs globally, including an unspecified number of positions here.

    Uncertainty yet looms at the bank, which is undergoing “accountability reviews” targeting around 150 current and former employees globally. The reviews have led to some layoffs and the move to claw back past year bonuses.

    A Singapore spokesman declined to comment on whether any staff here was affected by the reviews, adding: “The accountability reviews are still ongoing and more actions, including the reduction or cancellation of prior year incentive awards, are likely.”

  • HSBC, Standard Chartered Caught Between ‘Brexit’ and China

    HSBC, Standard Chartered Caught Between ‘Brexit’ and China

    Two big U.K. banks’ shares tanked over the past couple of days, and unlike the British pound, they’re not weakening because of the so-called “Brexit” referendum — although that certainly doesn’t help.

    Instead, their fall may have a lot to do with the market and economic turmoil that has been taking place in China.

    The London-listed shares of emerging markets-focused bank Standard Chartered (SCBFF) fell by 10% at one point on Tuesday morning after it reported its first annual loss in more than 25 years.

    The bank reported a loss before tax of $1.5 billion last year, in sharp contrast to 2014’s profit of $4.2 billion.

    On Monday, HSBC’s (HSBC) shares fell in an otherwise rising market after the bank, which is the biggest in Europe and one of the biggest in the world by assets, reported a loss of $858 million before tax in the fourth quarter of last year, vs. a profit of $1.7 billion in the fourth quarter of 2014.

    HSBC, which is doing a lot of business in Asia and was even thinking of moving its headquarters there before deciding earlier this year to remain in London, eked out a 1% increase in pretax profit for full 2015 to $18.87 billion, but its adjusted loan impairment charges were up 17% at $3.7 billion over the period.

    The weak results of the two banks chime with rising investor worries about the exposure of U.K. banks to Asia, and particularly China, at a time when European banks have been making investors nervous again.

    Richard Barnes, senior director at Standard and Poor’s credit rating agency, received many questions about the risk of European banks’ exposure to Asia last week during an analyst call, and said the region was important particularly for HSBC and Standard Chartered.

    However, “we’ve seen European banks generally retrenching from a number of regions in the world including Asia … banks are trying to reduce exposure,” Barnes said, adding that, in China, “banks look again at their exposure to state-owned enterprises and are focusing on the ones that are likely to be supported by the government in a downturn.”

    HSBC has been deeply involved in the liberalization and deepening of China’s capital markets, having successfully negotiated a majority stake in a new, nationally licensed securities joint-venture in the mainland. HSBC Group Chairman Douglas Flint acknowledged in a statement on Monday that “China’s slower economic growth will undoubtedly contribute to a bumpier financial environment,” but he added that the country “is still expected to be the largest contributor to global growth as its economy transitions to higher added value manufacturing and services and becomes more consumer-driven.”

    He said this transition is driving the bank’s focus on the Pearl River Delta as a priority growth opportunity, as the area is a concentration of high-tech, research-focused and digital businesses.

    HSBC’s exposure to mainland China is around $143 billion, according to its annual report; of these, $135 billion are loans to other banks or non-bank financial institutions, sovereign and corporate loans, while $8 billion are loans to retail clients.

    China is perhaps even more important for Standard Chartered and has helped reduce the bank’s loss over the past year. Its Greater China business showed a pre-tax profit of $1.37 billion last year, compared to a loss of $1.33 billion in its European operations. In terms of exposure to China, Standard Chartered listed $77.67 billion in loans to customers in the country.

    The two banks would normally be sheltered from fears over their exposure to China by their presence in one of the strongest financial centers in the world, London. But with uncertainty in the U.K. rising because of the referendum on EU membership, expect a few particularly volatile months ahead for HSBC and Standard Chartered.

  • MasterCard says Australian retail sales ‘worrisome’

    MasterCard says Australian retail sales ‘worrisome’

    MasterCard’s Sarah Quinlan says a cooling property market is hitting retail sales. Australian retail sales will rise in 2016, but slowing wages growth and a cooling property market here and in China is dampening growth. That’s the prediction based on MasterCard’s first monthly analysis of millions of card payments made on card terminals.

    It began tracking retail sales in Australia last year based on all transactions at terminals and claims this gives more accurate data than that provided by the Bureau of Statistics, which relies on surveys.

    MasterCard’s first monthly survey of payments in Australia predicts retail spend will drop further. Photo: Jim Rice

    Sarah Quinlan, MasterCard’s New York-based senior vice-president of market insights, said retail sales year-on-year in Australia grew 3.2 per cent in value in January compared to a year earlier.

    Year-on-year sales growth in January 2015 was running at about 6 per cent.

    She said growth at the moment is due to inflation because of a depreciating Australian dollar and the trend down is being driven by real wages growth declining. This has been reinforced by house prices cooling because regulators have capped investor lending.

    A big slowdown in spending by Chinese tourists and investors is the other main factor which is hitting all countries.

    “You could have absolutely predicted the real estate outcome,” she said. “There’s two things I watch in spending; I watch consumer confidence and wage growth.”

    MasterCard's first monthly survey of payments in Australia predicts retail spend will drop further.

    Growth due to importing inflation

    In the US, she said, wage growth has been poor, but consumer confidence is higher than in Australia now.

    “They are absolutely confident they are going to hold their job now or they can find a job if they want to switch. It is the opposite of what’s happening here,” Ms Quinlan said.

    “While you still have a positive growth rate in your spending in Australia, it is of a worrisome nature because it is more due to importing inflation due to a 35 per cent drop in the Australian dollar [versus the US dollar] since 2012.”

    The pullback of Chinese money, she said, is due to a property bubble there and numerous senior officials being hit with corruption allegations.

    “We can tie exactly back to the day back in August 2013 that [politician] Bo Xilai was arrested for corruption and there’ve been 100,000 people arrested for corruption subsequently. So they are just not showing their wealth now,” she added.

    “And this debt bubble up there is huge right now, it makes ours pale by comparison. By our calculations around 75 per cent of the economy in China is owned by state-owned enterprises. So the state has been running this huge bubble.”

    As well as Australia, MasterCard produces a monthly report called SpendingPulse based on 160 million transactions per hour on its network for the US, Japan, Canada, Brazil, Hong Kong and Britain.

  • Is Xinqi Asset another Ezubao?

    Is Xinqi Asset another Ezubao?

    An asset management company backed by property projects has defaulted on wealth management products worth 1.9 billion yuan (HK$2.27 billion), affecting more than 5,000 retail investors across mainland China and triggering more concerns about its property and financial markets.

    Xinqi Asset held a meeting to discuss solutions with its investors in Shanghai on Wednesday, sources said. Retail investors have been unable to redeem their investments and earnings since Sunday.

    A final solution has not been confirmed. It remains unknown whether other assets managed by Xinqi are safe. An earlier company statement said assets under management stood at around 4 billion yuan. Shanghai police have been taking complaints from investors and looking into the matter.

    More defaults and scandals have been exposed in the mainland’s thriving wealth management business in recent months as the economy slows down, revealing scams in the innovative and less regulated sector. Late last year, the mainland’s largest peer to peer lending company, Ezubao, defaulted on HK$59 billion owed to more than 900,000 investors across the mainland. Xinhua said 95 per cent of the projects on the platform were fake.

    Xinqi Asset sold wealth management products to individual investors, with the investments put into commercial and residential development in second-tier cities including such as Xian and Zhengzhou, and promised annual interest rates as high as 15.6 per cent, according to its official website and documents about its products.

    Worse still, there is no specific regulator overseeing these companies

    The wealth management products issued by Xinqi Asset were used to finance big property developers.

    Xinqi would buy properties under development from the developers, and then transfer ownership to retail investors. Investors would be repaid with their capital and earnings after the project was finished and the developer bought back the properties.

    Xinqi Asset lists mainland China’s leading property developer, Greenland, as a partner on its official website.

    Greenland denied raising funds through Xinqi Asset as early as September, although it did sell some property units to it.

    “It seems Xinqi Asset has been using offline selling, rather than online selling to promote its products, which makes it different from the popular peer to peer lending companies,” said Abner An, an independent financial commentator in Beijing. “However, China’s offline asset management companies have even bigger problems with lack of transparency in capital flow.

    “Worse still, there is no specific regulator overseeing these companies. It is crucial to find out the capital flow under Xinqi Asset. It is possible that their investments in property are eroded by sluggish selling in second-tier cities. But the problem will be bigger if the money is embezzled to do other high-yield investment.”

    Calls to Xinqi’s headquarters in Zhengzhou, Henan province on Thursday, failed to reach management.

    Xinqi Asset, registered in Xian, Shaanxi province, has registered capital of 200 million yuan.