Category: Finance

Retail News Asia is committed to providing both local and global retailers with the latest Finance news throughout the Asian market. This on a daily base.

  • Cathay Capital Invests In Chinese Furnishing Retailer ABS

    Cathay Capital Invests In Chinese Furnishing Retailer ABS

    Sino-Europe private equity firm Cathay Capital has made an undisclosed investment in Chinese home furnishing product retailer ABS through its Sino French SME Fund, says a company announcement.

    “ABS stands out among the numerous other domestic home furnishing companies in China because it has established an innovative data-based development model and an omni-channel retail system,” says Cai Mingpo, president of Cathay Capital.

    The private equity firm says it plans to leverage its home furnishing industry resources in China and France to assist ABS’ cross-border development.

    Founded in 2009, ABS has developed from a tele and catalogue selling model to an omni-channel and direct sale model with the integration of an online retailing mall, offline brand stores and mobile apps.

  • TransferWise partners with Pay Gate to bring money transfer services to Korea

    TransferWise partners with Pay Gate to bring money transfer services to Korea

    TransferWise, the P2P international money transfer platform, has opened up transfers to South Korea.

    Until recently, banks and brokers were the only option for consumers needing to send money to the country. But now, thanks to recent changes in regulation, TransferWise has partnered with local firm, PayGate, to bring better, fairer international money transfer to South Korea.Instead of sending the money in Korean Won, banks and brokers send customers’ money in GBP or USD for example, and the receiving bank makes the conversion. This leaves consumers paying two rounds of fees and maybe even two rounds of conversion – and usually they haven’t even been told they’re being charged in this way. But TransferWise sends the money in Korean Won, which means no receiving bank mark-up. The process is also completely transparent. TransferWise charges 1.5% for transfers with a delivery time of the same or next day.

    Taavet Hinrikus, CEO and co-founder of TransferWise, said:
    “Until recently, there was no alternative to banks and brokers when people wanted to send money to South Korea. We’ve heard from consumers that the process was slow and outrageously expensive so we’re hugely excited to launch the route on TransferWise. It’s going to make a huge difference to the seven million Koreans living, working and studying overseas.

    “The steps that the government in South Korea is taking to open up the financial services sector is good news for consumers. There will be more choice and better, fairer services to choose from.”

    So Yeong Park, CEO and co-founder of PayGate, said:
    “It is so glad that we now can serve customers with our 18 years of diverse experience as a Payment Service Provider, for them to make much cheaper, faster, and safer international money transfers to Korea.

    “For the last few years PayGate has been working hard to grow the Korean Fintech Industry and our recent partnership with TransferWise is the result of these efforts. Customers in Korea will see how this alternative finance can positively affect their daily lives.”

    People use TransferWise to transfer more than £500 million globally every month, saving themselves more than £22 million a month in unfair fees and charges.

  • Maybank to grow Singapore retail SME loan portfolio by 40% this year

    Maybank to grow Singapore retail SME loan portfolio by 40% this year

    Maybank is planning to “aggressively expand” its retail small and medium enterprises (RSME) financing across Singapore and the region, it said on Monday.

    The bank will be lending money to more businesses with revenues of up to $20 million, termed “retail SMEs” because they have simpler financing needs akin to those of retail or consumer banking.

    The move follows the implementation of its RSME model in Malaysia, which has seen a compounded annual growth rate (CAGR) of more than 30 per cent in loans since it was fully rolled out in 2013.

    Maybank Singapore said it expects to grow its total RSME loan portfolio by 40 per cent this year.

    In the two years since the RSME business was officially launched here, SME loans have increased by more than 50 per cent and deposits have risen by almost 25 per cent, according to Mr Choong Wai Hong, head of community financial services (CFS) for Maybank Singapore.

    “Our RSME business was a newly created segment which we identified as having great potential in 2011,” said Mr Lim Hong Tat, chief executive of Maybank Singapore.

    Mr Lim added that Maybank will be focusing on building its RSME portfolio regionally as the formation of the Asean Economic Community has resulted in countries placing increasing emphasis on smaller firms. “Asean economies are powered by the SME segment, which generates about 50 per cent of employment and some 40 per cent of GDP on average,” he added.

    “The SME industry itself is growing by between 8 and 28 per cent CAGR in these markets and presents an untapped potential for growth.”

    Maybank has introduced its RSME model in Indonesia, the Philippines, Cambodia, Laos and Brunei.

    The bank also has online capabilities to help small business owners improve their productivity in areas such as payroll, collections and payments. Maybank intends to devise more innovative financing solutions to help business owners manage uncertainties around their cash flow.

    “As the only bank with a presence in all 10 Asean countries, we are well-poised to help more small businesses capitalise on new opportunities to grow their business locally and access new markets in the region,” Mr Choong said.

  • Japan’s biggest bank sees crucial role for Philippines

    Japan’s biggest bank sees crucial role for Philippines

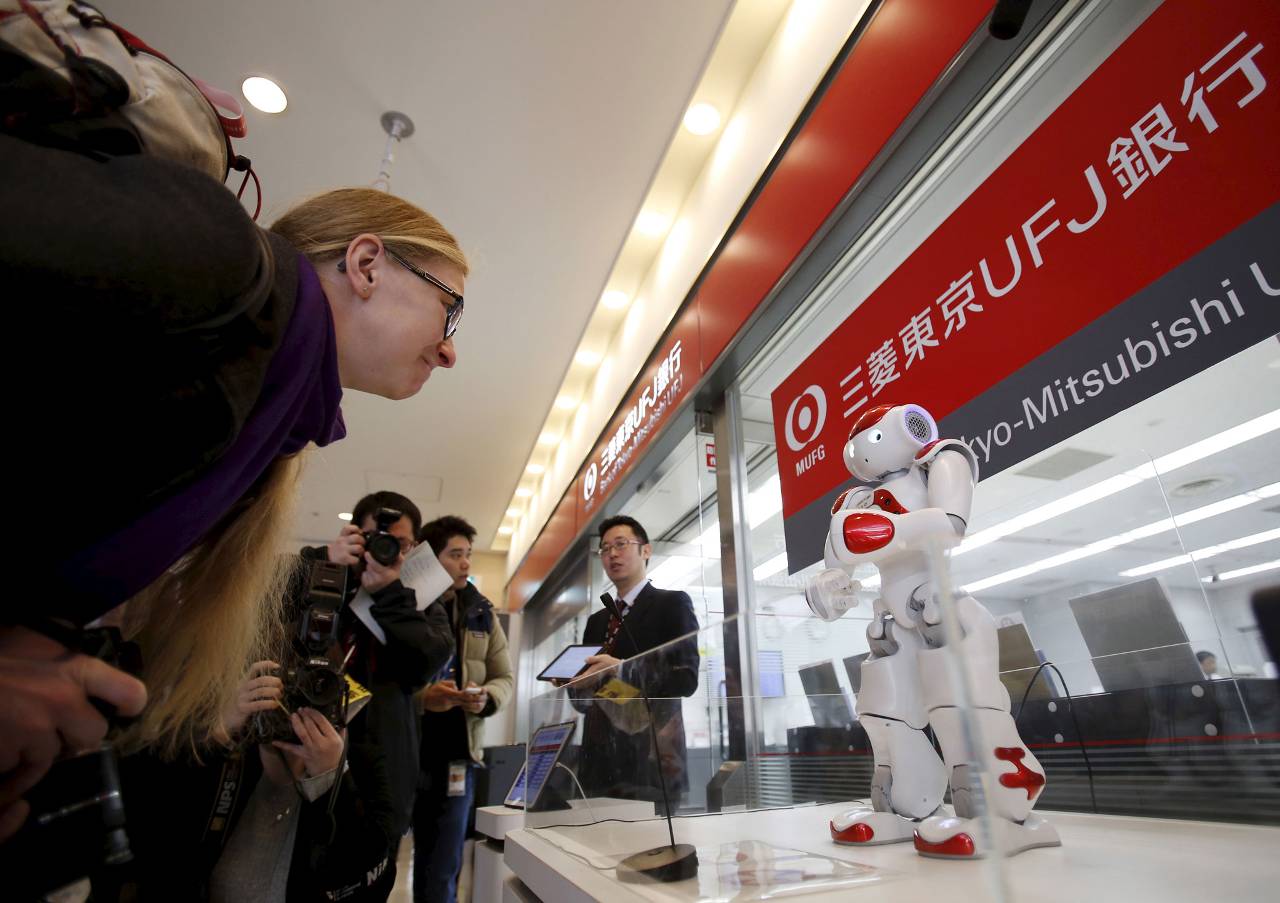
    Japan’s biggest lender Bank of Tokyo-Mitsubishi UFJ said the Philippine market plays a crucial role in its goal to become Asia’s Tier 1 financial institution.

    BTMU, which recently bought a 20-percent stake in the Philippines’ Security Bank Corp., said it envisions surpassing three of the biggest banks in Asia (HSBC, Citibank and Standard Chartered Bank) by 2020.

    “The Philippines is one of the most important markets for the bank because the economy is strongly performing, and many Japanese companies have been advancing in the Philippines,” Go Watanabe, BTMU chief executive officer in Asia and Oceania Region, told reporters in a roundtable discussion on Tuesday.

    “The Philippines is the missing part of BTMU. That is why we have decided to have a strategic alliance with Security Bank,” he added.

    Watanabe said its P36.9-billion investment in the local lender, which is also the biggest capital infusion to date in the Philippine financial market, is part of BTMU’s strategy to identify the right partners in high growth markets and to deepen its presence in organic communities.

    He said that with the partnership BTMU could now provide its strong base of Japanese customers with retail banking services using the local network of Security Bank.

    With BTMU’s diverse global network, it can also provide global corporates and Filipino companies with services such as project and trade financing, he added.

    For his part, BTMU General Manager Tadahiro Miyamoto, said that with the large consumer market in the Philippines, many Japanese firms are showing interest in expanding operations into the country.

    Potential for auto industry
    “There are many companies interested in the Philippine market. One is the retail segment such as food and apparels, but currently, probably the most interested segment is automotive,” he said.

    Miyamoto added that if the Comprehensive Automotive Resurgence Strategy (CARS) program of the government becomes successful, there are potentially many Japanese manufacturers and suppliers that would be producing car parts in the Philippines, which would create even more investment opportunities for the sector.

    Despite this, Watanabe said that encouraging more manufacturing firms to do business in the country is a bit challenging because of the lack of incentives and persistent gaps in infrastructure and power generation.

    “The challenge for the Philippines is how to encourage overseas companies, especially manufacturing, to invest in this country. In that respect, BTMU is willing to support the country to encourage them to invest more in the Philippines,” he said.

    “More than 100 million population is a good big market. If the government will think about good incentives, I think it will be a good chance for the Philippines to increase the entry of foreign direct investments, not only from Japan but also from other countries,” he added.

    Meanwhile, Miyamoto said improvement in other areas such as infrastructure, and the cost and reliability of electricity are also needed.

    “There are a lot of projects going on. We hope that those will be realized soon so that there will be more general support for Japanese companies to invest more here,” he said.

    Interested in PPP
    In this regard, Watanabe said the public-private partnership program (PPP) of the government, particularly in infrastructure, is necessary for the country.

    “Japanese companies are showing strong interest in participating in the PPP. BTMU as the best project finance bank, together with good peso liquidity from Security Bank, means our team is the best team to support the PPP and encourage Japanese customers to participate in the PPP. This will be very beneficial to this country,” he said.

    At present, Miyamoto said BTMU has no PPP investment yet, but the bank has been looking to participate in projects included in the pipeline.

    One particular project that the BTMU is interested in is the Clark Green City, which includes access and inter-city roads, a railway system, a mixed-use residential and commercial block, business district, industrial estates, schools and centers, government offices, and other facilities that would make up a major city.

    At full development, the city is estimated to accommodate some 1.12 million residents and 800,000 workers.

    “It is a very good project. It creates a lot of positivity for the Philippines and we will see what we can do,” Miyamoto said.

    Another project that can be considered by BTMU is the North-South Railways Project, Watanabe added.
  • HSBC expanding retail banking business in China’s Guangdong province

    HSBC expanding retail banking business in China’s Guangdong province

    HSBC, the largest bank in Europe and Hong Kong, is planning to expand its retail banking business in China’s Guangdong province in the coming years, with credit cards. securities trading and residential mortgage business in the pipeline, said Asia-Pacific chief executive Peter Wong Tung-shun.

    Wong was in Guangzhou on Wednesday morning with group chief executive Stuart Gulliver and Greater China head Helen Wong to co-host the launch ceremony of HSBC Express, the bank’s first train sponsorship programme. Under the sponsorship deal, 11 out of 22 trains between Guangzhou and Shenzhen will be named HSBC Express.

    “These trains are for mass commute. The programme aims to bring the image of HSBC to the public as we are expanding retail banking in Guangdong, which would provide huge opportunities for HSBC in the coming years,” Gulliver told the South China Morning Post at the launch ceremony.

    “While Hong Kong has 8 million customers, there are over 50 million Cantonese speakers in Guangdong province. HSBC is very strong in retail banking in Hong Kong, which is a big part of our business. Retail banking would be our important business thrust in Guangdong in the years ahead,” he said.

    HSBC now has 64 outlets in Guangdong, accounting for a third of its 177 outlets in China. The lender has traditionally focused on corporate banking in China but Gulliver said the growing wealth in Guangdong makes it the ideal place for retail banking. “On its own, the Guangdong economy is the 16th largest in the world. The middle classes are growing, and so is the demand for retail business services,” Gulliver said.

    Wong told the Post that retail expansion would include launching HSBC credit cards, which received regulatory approval last year but the launch date is yet to be confirmed.

    Securities trading is also in the pipeline. The bank has set up a joint venture with the Qianhai authorities, becoming the first foreign firm to hold a majority stake, of 51 per cent, in a securities joint venture trading stocks for customers from Qianhai special economic zone. It is to commence operation sometime this year.

    Wong said resident mortgage business is anther retail segment in demand, adding that the bank would also like to go into other types of wealth management businesses.

    “When people get wealthy, they like to buy homes. HSBC can offer mortgage and other wealth management services for these customers in Guangdong,” Wong said. “HSBC has a long history in both Hong Kong and Guangdong. We have been in Hong Kong for 150 years and set up our first office in Guangzhou in 1909. We financed Kowloon and Guangzhou railway in the old days. We are here for the long term,” Wong said.

    Gulliver said that with the many train and bridge projects linking Hong Kong with Guangdong, the interconnection between the two would be huge in the future. This is transforming the area from a low-end manufacturing centre into a high-end technology area led by Shenzhen, providing huge opportunities for HSBC.

  • OCBC launches banking app for Apple Watch

    OCBC launches banking app for Apple Watch

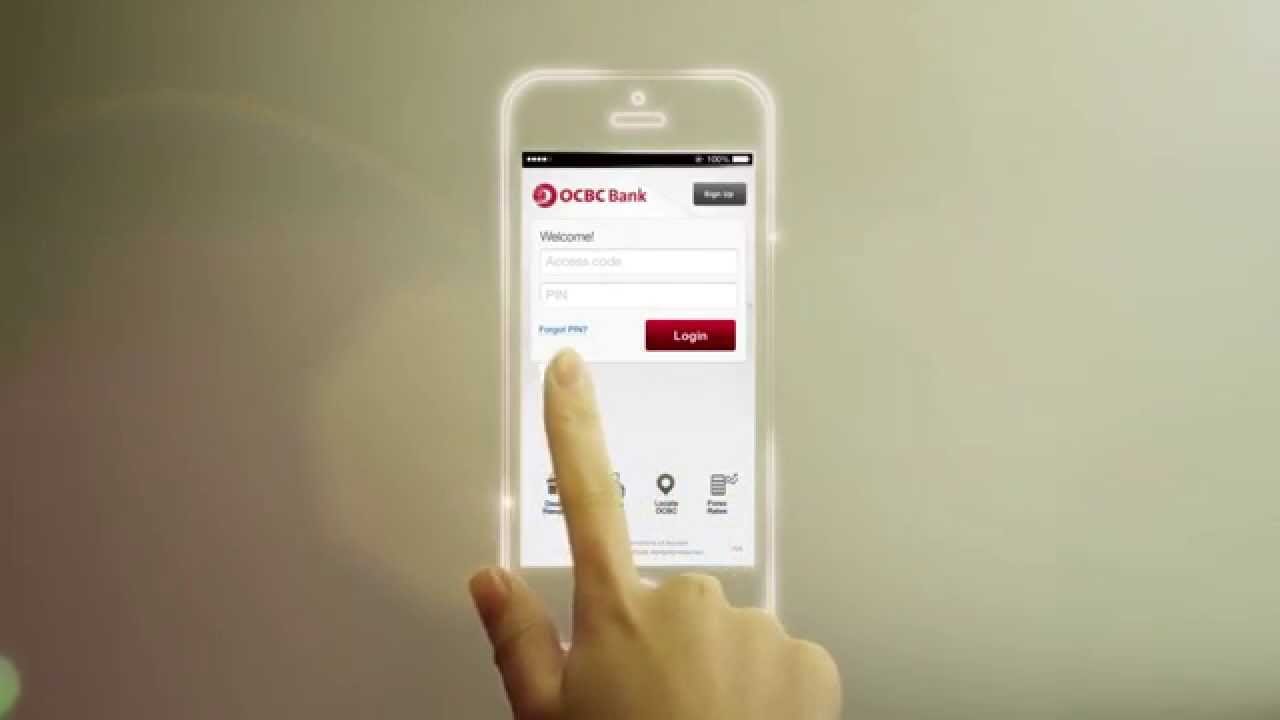
    Singapore’s OCBC Bank has launched a new mobile banking app designed for the Apple Watch.

    With the app, users can have instant access to their personal banking information, including the full list of their balances – bank accounts, cards and investments, recent transactions, and the location of the nearest OCBC Bank branch or ATM, on their Apple Watch.

    Customers must first perform a one-time activation on their OCBC iPhone mobile banking app before using the Apple Watch app. Once activated, account information and recent transactions can be viewed on Apple Watch, without the need to login to mobile banking.

    This service is available for customers using mobile devices such as iPhone 5, iPhone 5S, iPhone 6, iPhone 6 Plus, iPhone 6S or iPhone 6S Plus operating on iOS 9 and Apple Watch devices running on WatchOS2.

    The service can only be activated on a single pair of Apple Watch and iPhone devices at one time and all account numbers displayed on the watch are partially masked with only the last four digits revealed. No information is stored on the phone or watch and for security purposes, customers can choose to set a passcode on their Apple Watch.

    Market intelligence firm IDC estimates the worldwide wearable device market will reach a total of 111.1 million units shipped in 2016, a strong 44.4% increase from the 80 million units shipped in 2015. By 2019, the five-year compound annual growth rate (CAGR) of wearable devices would be 28%, with Apple smart watch devices taking the lion’s share of the market.

    “Smartwatches represent the next generation of personal mobile devices, and our Apple Watch app will offer the convenience, security and choice that customers demand when it comes to everyday banking on-the-go,” said Aditya Gupta, OCBC Bank’s Singapore head of e-business, said.

    “We are confident the Apple Watch app will be a big hit with our fast-growing number of customers who are mobile and digitally-savvy.”

  • HSBC Going Solo in China Credit Cards Gives Boost to Expansion

    HSBC Going Solo in China Credit Cards Gives Boost to Expansion

    HSBC Holdings Plc winning approval to start a credit-card business in China’s $1 trillion market offers Chief Executive Officer Stuart Gulliver added flexibility in his push into the nation’s retail banking and wealth-management industries.

    The approval from Chinese authorities came as HSBC ended a card venture with Bank of Communications Co., the bank’s Asia-Pacific head Peter Wong said in a weekend interview, paving the way for the U.K. company to join Citigroup Inc. and Bank of East Asia Ltd. as the only foreign credit-card issuers on the mainland. Wong didn’t say when HSBC won the nod from regulators, or provide any specifics on how the business will be rolled out.

    Gulliver’s Asian ambitions have been dealt a setback by crashing commodity prices, a slowing Chinese economy and a pretax loss in the fourth quarter. An independent card unit in China would improve HSBC’s access to a fast-growing market that had 449 million cards on issue as of September and allow the bank to find new clients for its retail bank.

    Getting approved for its own operation in China “is a meaningful step for HSBC as it gives the bank the autonomy to run the business,” said Chen Xingyu, a Shanghai-based analyst at Phillip Securities Research. “Since the Pearl River Delta is HSBC’s focus, having its own credit-card business can help the bank expand in the region.”

    Credit-card offerings can act as a springboard for drawing customers to other parts of the business such as private banking, Chen said. HSBC is getting a license for a planned brokerage venture with Shenzhen Qianhai Financial Holdings Co.

    The Pearl River Delta, located to the north of Hong Kong and centered around the city of Guangzhou, is home to more than 40 million people. HSBC plans to add 4,000 jobs in that area as the bank shifts about $100 billion of investment to Asia in an effort to expand retail banking and wealth management. The bank will slow the pace of thathiring amid China’s economic downturn, but HSBC won’t alter its strategy, Gulliver said last month.

    Good Relations

    While the bank has ended its card venture with Bank of Communications, HSBC intends to maintain its roughly 19 percent stake in the Chinese lender, Asia-Pacific Chief Executive Officer Wong said Saturday in an interview on the sidelines of China’s annual congress of lawmakers in Beijing.

    “We still have a lot of other initiatives” with Bank of Communications, Wong said. “We have a very good relationship.”

    HSBC’s card offerings would compete with its old venture partner, which had 40 million domestic cards as of June, while Industrial & Commercial Bank of China Ltd. had 108 million, according to their 2015 interim reports.

    The London-based company has been working with Bank of Communications, China’s fifth-largest lender by assets, since 2004 on businesses including credit cards. The Chinese bank announced the establishment of the credit-card venture — with 2.5 billion yuan of capital — in an October 2009 statement to Hong Kong’s stock exchange.

    HSBC shares in Hong Kong fell 0.3 percent on Tuesday to HK$49.50 as of 1:31 p.m. local time, compared with the benchmark Hang Seng Index’s 0.8 percent loss. The bank’s stock dropped 20 percent this year.

    The number of Chinese credit cards in circulation at the end of the third quarter had nearly doubled to 449 million since 2010, central bank data show. That total is about the same as the combined populations of the U.S. and Japan. The outstanding balance on those cards was 6.7 trillion yuan, up 26 percent from a year earlier, according to the People’s Bank of China data.

  • BNI, Indonesia’s Leading Bank, Adopts e-Learning to Improve Credit Performance

    BNI, Indonesia’s Leading Bank, Adopts e-Learning to Improve Credit Performance

    Omega Performance, a TwentyEighty company, and BNI, Indonesia’s fourth largest bank, teamed up to create a robust e-Learning platform to improve the bank’s quality of assets aimed at reducing its credit risk. By focusing on training and developing its loan officers, BNI has found a solution to reduce the percentage of its nonperforming loans (NPLs).

    Risk management is one of the top threats facing Indonesian banks in today’s economic climate. BNI had shown improvement year over year regarding its NPLs, but leaders of the bank wanted to do even better.

    BNI’s strategy to reduce the burden on its financial system was to manage its operational risks by investing in technology and its people through a systematic training system for its loan approval processes. The best way to do this was to supplement its in-house training model with an e-Learning platform from Omega Performance. Training employees using a technologically advanced platform ensures consistent learning opportunities are available to all credit officers and it encourages knowledge sharing within the bank.

    “A few years ago, I personally evaluated the content Omega Performance offered in terms of credit training, and I was highly impressed with the quality of the material,” said Putu B. Kresna, head of the organizational learning division at BNI. “After that experience, we have been successfully working together ever since.”

    Since it was established in 1946, BNI has grown and developed into a national bank with sustainable financial performance and millions of customers worldwide. The bank relies on its wide-ranging service network, comprising of 1,585 domestic outlets and nine overseas branches in Singapore, Hong Kong, Japan, Korea, the United Kingdom and the United States.

    In addition to seeing improvement on its NPLs, BNI senior managers saw instant results in the change in employee perception towards training. It’s clear that BNI employees are seeing great value in being trained by a partner that understands the banking credit culture like Omega Performance.

    Omega Performance has been able to get BNI’s most experienced credit officers to buy into the e-Learning platform. Using a blended approach that includes online self-study, facilitator-led interactive workshops, skills application labs and a Train-the-Trainer style of learning has laid a strong foundation for training at BNI. Omega Performance is providing training platforms to help BNI in consumer lending, business lending fundamentals, financial accountability for lenders, commercial loans to business and minimizing problem loans.

    “We are pleased that BNI has chosen Omega Performance as its trusted learning partner to help the bank make continuous improvements in its NPL ratio by using our blended credit training solutions,” said Gil Madrid, business development director at Omega Performance. “By elevating the competency and risk management skills of its bankers to international standards, BNI has taken an invaluable and progressive step to fulfill its vision of creating and sustaining a strong credit culture at the bank.”

  • Malaysia Airports partners with Union Pay to boost Chinese spend

    Malaysia Airports partners with Union Pay to boost Chinese spend

    The Commercial Division of Malaysia Airports Holdings Berhad is collaborating with UnionPay International to boost Chinese tourist spending at its airports.

    The move is said to be in line with Malaysia Airports’ Commercial Division’s new strategic direction which calls for a targeted passenger focus. According to Malaysia Airports Holding Senior General Manager Commercial Services Berhad Mohammad Nazli Abdul Aziz, the collaboration also fits in with the significant growth of Chinese passenger traffic.

    Air China, Shanghai Airlines and Spring Airlines were the latest to join the fleet of Chinese airlines flying to Kuala Lumpur and Kota Kinabalu in 2015. Together they connect Malaysia to more than 17 key cities located throughout China.


    “According to statistics obtained from Tourism Malaysia, on average, a Chinese tourist spends approximately MYR3,300 (US$847). If Tourism Malaysia achieves its target Chinese tourist arrivals of over 2 million for 2016, this will translate to more than MYR6.7billion (US$1.72 billion) in tourist receipts. Capturing a fraction of that will contribute positively to our revenue. UnionPay is a fast-growing global payment brand.

    Partnering UnionPay International will allow us to tap into the Chinese tourists.”Nazli said: “The Chinese tourists market is a priority for us given their volume and strong spending power. Last year, total passenger movement between Malaysia and China stood at approximately 5.54 million, the second highest for Malaysia Airports. Much of it is boosted by the fact that we currently have 12 airlines connecting Malaysia to over 17 destinations in China. We expect the Chinese tourists market to increase even further with the visa-waiver programme.

    To further boost tourist spending, Malaysia Airports has signed several new brands at its international gateways. Among the local brands are Noodlelicious, Sofia Iman, Killiney Kopitiam, and Upin & Ipin Café. New international brands include Michael Kors, Pedro, Montblanc and Barry Smith.

    The partnership between Malaysia Airports Holdings Berhad and UnionPay includes the ‘Be Rewarded When You Spend Campaign’, of which the launch coincided with the prize presentation ceremony to mark the conclusion of Malaysia Airports’ Indulge & Explore Campaign.

    UnionPay International Southeast Asia General Manager Wenhui Yang said: “We are pleased to partner Malaysia Airports for the “Be Rewarded When You Spend” campaign. Malaysia Airports is one of the biggest players in Malaysia’s tourism and hospitality industry, our collaboration is in line with our efforts to bring greater value and more exciting privileges to our customers, wherever they go.”

    Foo Yit Kin from Kota Bahru, who claimed the Grand Prize in the Indulge & Explore Campaign, won a six-day trip to participate in a Panda Experience Programme in China.According to data recorded by Malaysia Airports’ recently-concluded Indulge & Explore Campaign, Chinese tourists were among the top three airport spenders. For the three-month duration of the campaign, which ran from 7 December 2015 to 6 March 2016, Chinese tourists spent an estimated MYR1.65million (US$425,000) at KLIA/klia2 combined. On the whole, the campaign saw a +7% increase over the previous year’s initiative.

    In addition to the Grand Prize won by Foo, the Indulge & Explore Campaign also awarded 13 weekly prizes, including Lovina Dolphin trips to Bali and New Leaf Detox programmes in Koh Samui, Thailand. The 13 weekly prize winners were selected throughout the campaign period, with each weekly prize winner also entered to win the Grand Prize.

    According to Malaysia Airports, more than 43,500 travellers from 164 countries partook in the Indulge & Explore Campaign, with top participation from Malaysians followed closely by Chinese tourists.


    Malaysia Airports’ Indulge & Explore Campaign, which was supported by MasterCard, provided the opportunity for shoppers to double their entries when they used their MasterCard.Nazli added: “The Indulge Campaign is an important component of our overall commercial strategy. It underscores our drive towards providing passengers and visitors with the total airport experience. 2016 will see us doing even more to drive the message home.”

    MasterCard Group Country Manager Indonesia, Malaysia and Brunei and Group Head Islamic Payments and Southeast Asia Safdar Khan said: “MasterCard understands that Malaysians love to travel and for many of them, shopping is an integral part of their trip. According to our latest Consumer Purchasing Priorities Survey, nine in ten Malaysians intend to travel in the next year and shopping is among their top three activities when travelling.”

    He added: “Together with Malaysia Airports, we are delighted to have delivered unique travel experiences in conjunction with the Indulge & Explore Campaign over the past decade. We look to continue offering exciting benefits and exclusive rewards to MasterCard cardholders at every step of their journey.”

  • CIMB expects more conducive economy for consumer banking in 2H2016

    CIMB expects more conducive economy for consumer banking in 2H2016

    Collaboration between CIMB and Tesco Stores (Malaysia) Sdn Bhd today, the group’s CEO of group consumer banking Renzo Viegas told pressmen that while the current marketplace remains tough for business, the mass affluent community will still continue to invest.

    “It’s a tough environment, so loan growth will be slower than last year for sure (in terms of) investment products, people are really concerned about the global economy and the Malaysian economy; (there are) a lot of volatility, so people are holding back their investment decisions, but the mass affluent customers will still invest, so the second half should pick up a bit,” he said.

    “(In the) second half (of 2016), the whole economy environment should improve to become more stable and predictable; investment by consumers should also grow, and therefore our wealth management would also do well,” he added.

    On the other hand, Viegas said CIMB is also monitoring its credit quality closely, to avoid any deterioration in the group’s consumer portfolio.

    “All in all, there will still be slower growth, and we are watching the credit quality. So far, there is no deterioration to our credit quality in consumer portfolio. But there are still challenges, and there are still going to [be] opportunities like the launch today,” he said.

    Viegas said the partnership will allow CIMB to benefit from Tesco Malaysia’s three million weekly customers, by the increased accessibility to other products offer by the bank.

    “In the next two years, we hope we can garner half a million new card customers,” he added.

    Earlier at the launching ceremony today, CIMB’s CEO Tengku Zafrul Aziz announced an exclusive five-year strategic partnership with Tesco Stores (Malaysia) Sdn Bhd to come out with the new card services.

    The collaboration will also see CIMB set up its consumer banking kiosks at 38 Tesco stores nationwide. Tesco Malaysia currently operates 55 stores, with about 8,000 employees.

    Zafrul said the partnership between CIMB and Tesco Malaysia represents a winning formula in delivering value to both companies’ customers.

    “Being able to bring our vast suite of products through a seamless and paperless process to Tesco stores, make for a truly compelling value proposition to customers, both current and new. We genuinely believe that this partnership is the start of many great things ahead,” he said.

    The new CIMB Tesco MasterCard members will enjoy an annual fee waiver. From April 1, 2016 to March 31, 2017, one Tesco Clubcard point will be awarded for every RM2 spent on CIMB Tesco MasterCard at other retail outlets.

    Tesco Malaysia CEO, Paul Ritchie, also commented that the partnership, which had taken a year to materialise, is the form of bringing the best of two companies to enhance customers’ shopping trip.

    “With Tesco’s variety in range at fantastic promotions and good prices, and CIMB’s strengths in the financial and banking sector, together we will be able to reward our customers and create value to earn their long-term loyalty,” he said.

  • Standard Chartered opens Singapore innovation lab

    Standard Chartered opens Singapore innovation lab

    Standard Chartered Bank has opened a new innovation lab in Singapore to explore the use of emerging technologies and data sciences in support of the bank’s digital transformation strategy.

    The ‘eXellerator’ builds upon Standard Chartered’s established technology outpost in Silicon Valley, SC Studios, and is the bank’s first dedicated space for innovation in Asia, located at the heart of its main office building at Marina Bay Financial Centre.Anju Patwardhan, Standard Chartered’s global chief innovation officer, says: “This is where we can tap the depth of knowledge and talent, as well as work with local universities and research organisations, to help drive the bank’s innovation agenda.”

    The bank has secured the support of the Monetary Authority of Singapore (MAS) in establishing the facility. MAS has been actively encouraging the development of a ‘Smart Financial Centre’, in line with country’s ‘Smart Nation’ plan, and recently appointed a ‘chief fintech officer’, Sopnendu Mohanty, to co-ordinate its efforts.

    Says Mohanty: “The financial sector is an integral part of Singapore’s ambition to be a Smart Nation. A Smart Financial Centre with an open architecture and collaborative fintech community will promote innovation, application of technology advancements and talent development in financial services.”

    Standard Chartered has already laid the groundwork for the new lab through a multi-year collaboration agreement with A*Star’s Institute for Infocomm Research (I2R) – Singapore’s national information and communications technology research institute – to jointly work on data science research and experimentation by tapping the Institute’s network of data scientists and software engineers.

    It has also partnered with DBS Bank and Singapore’s Infocomm Development Authority (IDA) to successfully complete a proof of concept (PoC) on the application of distributed ledger technology in trade finance invoicing with the objective of reducing risk around duplicate invoice financing for banks while preserving client confidentiality.

  • HSBC sets sights on Vietnam

    HSBC sets sights on Vietnam

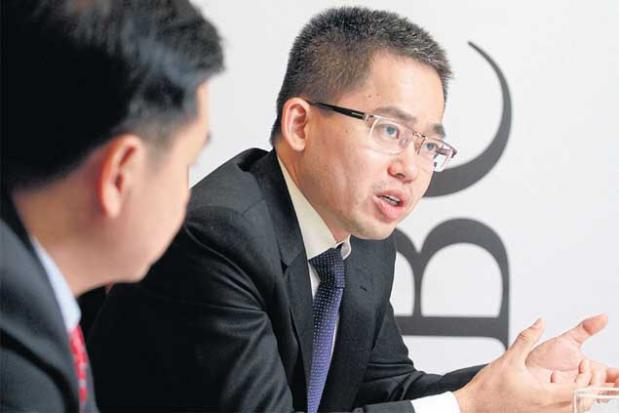
    HSBC Bank (Vietnam) chief executive Pham Hong Hai (right) and Kelvin Tan, chief executive of HSBC Thailand, say HSBC aims to capitalise on its presence in seven of the 10 Asean countries.

    HSBC seeks to offer a better integrated regional service with the increase of cross-border investment following the formation of the  Asean Economic Community (AEC).

    The bank in particular is looking at Vietnam, where investment is set to surge under government policies to attract foreign investment.

    Kelvin Tan, chief executive of HSBC Thailand, said the company aimed to capitalise on its presence in seven of the 10 Asean member countries. Only Myanmar, Cambodia and Laos do not have branches of HSBC.

    “We made it very clear to our investors since last year that Asean will be one of our main focuses to help HSBC’s future growth,” said Mr Tan.

    HSBC will also focus on the Pearl River Delta, which consists of Hong Kong and Guangzhou, China.

    Mr Tan said the company will enhance the connectivity between its subsidiaries in each country to serve customers better and expand business.

    “We add value to our services by offering well-connected financial services in this region.”

    When a Thai customer expresses an interest in investing in another country in which HSBC operates, the bank will refer the customer to the office in that country, which can provide local information for doing business.

    Many HSBC customers have already expanded their businesses in other countries, especially Vietnam, to tap into a bigger market as well as take advantage of low labour costs, he said. Thai investors should benefit from the cheaper labour by setting up production bases there and using Thailand as their regional headquarters, which is the policy that the Thai government is promoting.

    “Thailand is in a very strategic location for logistics and air transport so pushing the RHQ concept is a step in the right direction, but the government will also have to include stakeholders as part for this development,” said Mr Tan.

    Pham Hong Hai, chief executive of HSBC Bank (Vietnam), said Vietnam had attracted heavy investment from Asean countries over the past few years as well as from other Asian countries such as South Korea, Japan, Taiwan and China.

    Vietnam’s low labour costs and political stability are the major draws that attract a huge amount of foreign direct investment, he said. Given the low wage rate for unskilled labour, the country has attracted a lot of labour-intensive industries.

    “Cambodia, Laos and Myanmar also have cheap labour, but Vietnam has the added positive factors of political stability and good infrastructure,” said Mr Pham.

    He said the low wage rate would last for about five years.

    However, one problem that has emerged in Vietnam is a shortage of workers at management level. Mr Pham said he expected the AEC integration to attract more white-collar workers to the country.

    He said Vietnam’s ruling party just elected a new central committee, which is expected to maintain the current policies to strengthen the country’s economy.

    The policies that will be continued include privatisation of state enterprises, modernising the banking sector, enhancing the effectiveness of fiscal policy and improving the business environment, he added.

    Vietnam’s state enterprises contribute 35% of GDP. The government is due to allow private firms to gradually own bigger stakes in the enterprises in order to enhance their effectiveness.

    The government is improving Vietnam’s business environment by passing new laws that will shorten the time required to start a new business and also to obtain a licence, Mr Pham said. There there are a lot of opportunities in businesses such as logistics, retail and manufacturing, which are growing quickly.

    “When the manufacturing sector grows it is always followed by logistics services to support the industries,” he said. “We also see that the retail sector’s growing fast with Thai companies such as Central and TCC Group investing in Vietnam.”

    He said with a population of 90 million, with young people forming a large proportion, Vietnam’s demographic make-up offers great opportunities for retail businesses to benefit from their purchasing power, which will grow significantly.

  • BNI Set to Penetrate ASEAN Market

    BNI Set to Penetrate ASEAN Market

    Bank Negara Indonesia (BNI) president director Achmad Baiquni said that state-owned lender BNI would expand its business in other Southeast Asian countries, in addition to Myanmar.

    “There are some countries targeted by BNI, but we can’t reveal them yet, because it’s too early,” Baiquni told us during a tree-planting event at kilometer 59 of the Jakarta-Cikampek toll road on Saturday, March 26, 2016.

    Baiquni added that the expansion plan would be executed based on existing business potentials. Myanmar was selected since other state-owned companies were expanding their business in the country.

    “We have to follow our customers,” Baiquini explained.

    Baiquni admitted that BNI had looked into the business potential in Myanmar. He also expected that the expansion plan would be realized this year.

    BNI and Bank Mandiri are preparing to expand their businesses in the ASEAN market prior to Financial Services Authority’s agreement signings with Central Bank of Myanmar and Bank Negara Malaysia.

  • UnionPay now in Thailand

    UnionPay now in Thailand

    While the company’s success up to now has relied on the huge domestic home market in China – which accounts for 99 per cent of all UP credit cards issued – this could be about to change. UnionPay is setting its sights on global expansion and intriguingly Thailand is the catalyst which will help make this happen. Over the past few years several landmark decisions about ATM/debit cards have been made by the Bank of Thailand (BOT) and the Thai Bankers’ Association (TBA), and these are beginning to be implemented this year.

    To combat the growing incidence of ATM and debit-card fraud, the BOT decided that all new ATM/debit cards in Thailand must carry secure embedded chips, a mandate which comes into force this May. Significantly, the BOT and TBA adopted UnionPay’s chip technology as the standard for all of Thailand’s debit cards, the first country outside of China to do so.

    This will mean a mass transformation of Thailand’s 50-million strong debit-card market, as currently few debit cards have embedded chips and they are mainly used as ATM cards and not for retail transactions. Most cards will, therefore, need to be replaced and to support this UnionPay has joined with Bangkok Bank to establish the Thai Payment Network (TPN). Other leading Thai banks are also expected to become shareholders in this joint venture company.

    Thai banks and other financial service providers will produce the new cards under the TPN and TPN-UnionPay brands, which will be locally issued and processed in line with BOT policy.

    China UnionPay chairman Ge Huayong said that the launch of TPN in Thailand has great significance and he cited four major reasons for this. It is a new breakthrough in the development of technical standards in China’s financial sector, it represents a model for China’s policy of Going Global, it lays a solid foundation for large-scale acceptance and issuance of UnionPay cards in other local markets, and it will help UnionPay develop a business-expansion model which can be replicated which will accelerate the roll-out of its global business.

    Ge Huayong also added that it ties in with China’s “One Belt, One Road” international expansion strategy as UP plans to develop similar payment infrastructure in other countries along the Belt and Road.

    Meanwhile, in another major development China UnionPay last month signed a memorandum of understanding with Visa to collaborate on payments security, innovation and financial inclusion.

    Visa CEO Charlie Scharf said the two card giants would work together to develop innovations in digital payments and broaden the access of financial services to a wider population.

    All these developments fit well with the Thai government’s digital payments strategy and should ensure that Thailand is at the forefront of using new technology in the payments industry.

    The benefits include helping our businesses keep up-to-date with modern technology while ensuring the public has easy and convenient access to financial services.

  • Maldives laments HSBC retail banking loss

    Maldives laments HSBC retail banking loss

    Maldives central bank on Thursday lamented the decision by Banking giant Hong Kong and Shanghai Banking Corporation (HSBC) to cease retail banking in the Maldives from April.

    Speaking at the parliamentary finance committee governor Azeema Adam insisted that the Maldives Monetary Authority (MMA) does not wish HSBC to cease retail banking services in the Maldives but said the country still needed the bank’s other services.

    Male branch of HSBC had decided to cease retail banking operations from April 28 and is now informing its customers.

    An official from the Maldives Monetary Authority (MMA) also confirmed the plans by HSBC’s Male branch to shift to corporate-only operations. The official, however, did not give details.

    HSBC was not available for comment.

    HSBC operates in Maldives as a trading desk of the HSBC branch in Sri Lanka.

    The governor however, pointed out that HSBC’s decision was not limited to the Maldives.

    “Every bank has its own standards. Certain services that they offer. Instead of forcing something on them we look to find out how it could prosper as a business. We put in a lot of effort to bring HSBC to the Maldives,” Azeema explained.

    “Even when they [HSBC] first came they had sought to serve high net worth customers and individuals. We had given them the operating license knowing that all those years ago.”

    Azeema also revealed that several challenges had prompted the bank to adopt cost cutting measures.

    “It’s not something we also want. But if we look at the services provided by the banks in Maldives, HSBC is the third largest bank in the country. In terms of deposit size and loan size,” she continued.

    HSBC is the second highest banking profit tax payer in the Maldives, she added.

    An account in HSBC has to be opened with an initial deposit of MVR 50,000; the highest initial deposit required of any bank that operates in Maldives. The bank also pays the lowest deposit interest rate at 1 – 1.75 percent. Deposit interest rate on US Dollar accounts is 0.10 percent.

    As the bank charges a high amount in fees, the bank mainly hosts Maldivian businesses.

    In May 2014, complaints mounted over the bank’s decision to close down accounts held by many small and medium businesses citing administrative reasons. The businesses had complained that the move was made without prior notice.

    The decision by one of the biggest banks in the world comes a week after it was revealed that the Maldives had lost a major international banker.

    President Abdulla Yameen Abdul Gayoom told residents of Gaafu Dhaal atoll Gadhdhoo on February 15 that one of the major correspondent banks had dropped Maldives from its client list, while another one is considering a similar move. The reason, according to the president, is false claims made about Maldives, including threats posed by home-grown jihadists.

    “When we make such claims without considering the repercussions, it’s the people of Maldives that has to suffer,” he said, after inaugurating a project to establish a clean water system in the island.

    The president did not identify the bank that had dropped the Maldives. Haveeru, however, understands that US-based JPMorgan Chase had terminated its dealings with Maldivian banks in 2013.

    A correspondent bank is a financial institution that provides services on behalf of another, equal or unequal, financial institution. It can conduct business transactions, accept deposits and gather documents on behalf of the other financial institution.