Category: Finance

Retail News Asia is committed to providing both local and global retailers with the latest Finance news throughout the Asian market. This on a daily base.

  • BRI records net profit of Rp25.2 trillion

    BRI records net profit of Rp25.2 trillion

    PT Bank Rakyat Indonesia Tbk. made a net profit of Rp25.2 trillion in 2015, representing a 4.5 percent growth from Rp24.2 trillion it made in the previous year.

    “The growth is driven by an increase in the interest income that reached Rp82.2 trillion, reflecting a growth of 13.5 percent from the previous year,” the state-owned lenders president director, Asmawi Syam, said here on Wednesday.

    The banks non-interest income reached Rp14.2 trillion, up 21.4 percent from the previous years figure, taking the total income of the lender to Rp96.4 trillion, 14.6 percent above the previous figure.

    Outstanding loans distributed by Bank BRI till 2015-end reached Rp558.4 trillion, reflecting a growth of 13.9 percent year-on-year compared to the same period of the previous year. These loans were given across all business sectors.

    Credits to the micro-sector, which is the core business area of the bank, grew by 16.8 percent year-on-year to reach Rp178.9 trillion with the number of customers increasing to 7.8 million from 7.3 million, year-on-year.

    “Credit growth in the micro-sector was driven by the re-launch of a smallholder credit program (KUR) by the government in the middle of August 2015,” he said.

    Since its launch on August 18 2015, Bank BRI has extended Rp16.2 trillion in credits to more than 920,000 businessmen across the country through the KUR program.

    Credits to non-state-owned companies in the corporate segment grew 31.5 percent year-on-year to Rp75.1 trillion while credit to the consumer segment grew 9.8 percent to Rp88.5 trillion.

    Credits to state-owned companies were up 9.6 percent to Rp81.2 trillion and to small commercial and medium businesses rose 7.5 percent to Rp134.7 trillion.

  • Moody’s continues to review for downgrade ratings of Standard Chartered Bank Korea

    Moody’s continues to review for downgrade ratings of Standard Chartered Bank Korea

    Moody’s expects to conclude the review in March 2016, after incorporating SCB’s efforts to turn around SCBK’s performance, as well as the detailed results of SCBK’s parent, Standard Chartered Bank’s (SCB, FC deposits Aa2 rating under review for downgrade, BCA a2 rating under review for downgrade) performance for 2015.

    These results will be available in late February.

    Moody’s had originally placed the long-term ratings of SCBK on review on 9 November 2015. Please refer to “Moody’s reviews for downgrade Standard Chartered Bank Korea’s ratings” published on 9 November 2015.

    Moody’s notes that SCB is restructuring its poorly performing Korean retail and commercial banking businesses, introducing some uncertainty as to the future of SCBK’s operations.

    The ratings review of SCBK will consider whether: (1) these initiatives have the potential to change SCBK’s stand-alone credit profile, as expressed by its BCA; and/or (2) to change the strategic importance of SCBK to SCB and therefore potentially to affect the strength of support from SCB.

    The following ratings are on review for downgrade:

    – Local- and foreign-currency long-term deposit ratings of A1

    – Foreign currency senior unsecured MTN rating of (P)A1

    – Local- and foreign-currency short-term deposit ratings of P-1

    – Foreign currency commercial paper and other short-term ratings of P-1/(P)P-1

    – Long-term and short-term counterparty risk assessment of A1(cr) and P-1(cr)

    – BCA of baa2, and adjusted BCA of a3

    The principal methodology used in these ratings/analysis was Banks published in January 2016. Please see the Ratings Methodologies page on www.moodys.com for a copy of this methodology.

    SCBK is headquartered in Seoul, with total assets of KRW61.7 trillion or USD54 billion as of June 2015.

  • Goodbaby China aims to deliver $161m HK IPO

    Goodbaby China aims to deliver $161m HK IPO

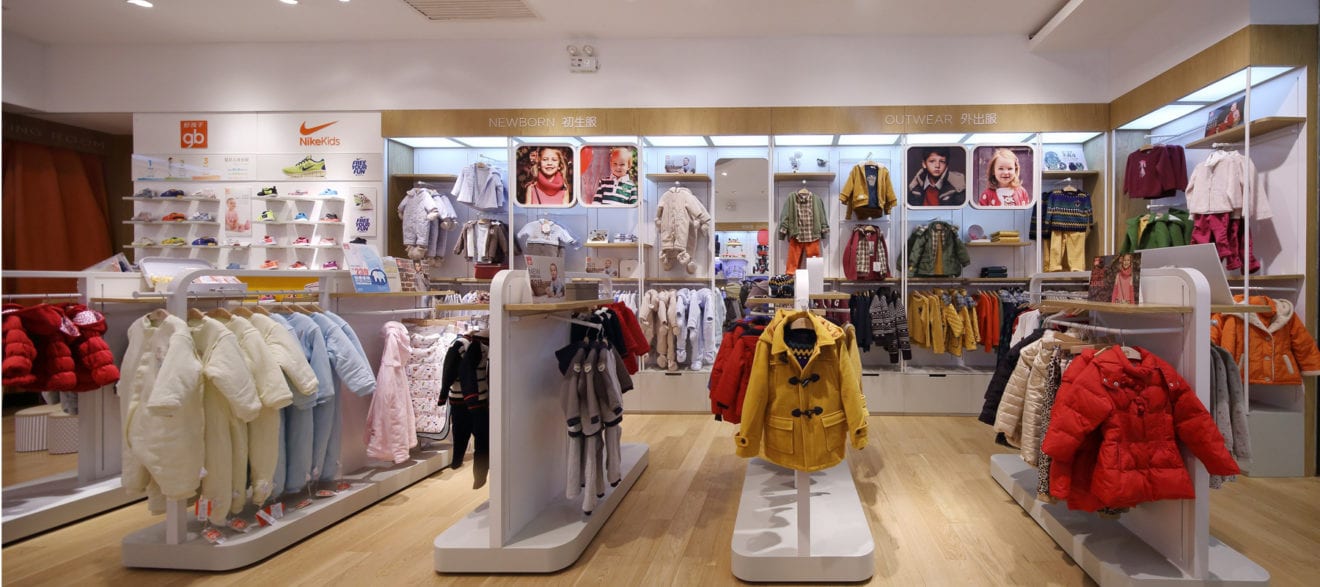
    Goodbaby China broke the equity capital markets silence on Tuesday by launching Hong Kong’s first initial public offering in almost two weeks.

    Braving choppy market conditions, the Chinese maternity, baby, and children’s products seller hopes to raise as much as HK$1.25 billion ($161 million) by wooing investors with a positive tale of growth.

    With global stock markets faring poorly as fears of an economic slowdown gather steam amid a slump in oil prices, conditions are hardly favourable for primary share sales, not least in Hong Kong and mainland China. The Hang Seng index fell another 2.5% on Tuesday, extending its losses so far in 2016 to almost 14% as shares in Shanghai and Shenzhen tumbled another 6.5% to 7%.

    But bankers familiar with the transaction hope the underlying quality of Goodbaby China plus an appealing valuation will help to counter sluggish market sentiment and support the IPO.

    Goodbaby China is scheduled to take orders until February 2 and aims to list on February 12, the second day after the Chinese New Year break. It is the first IPO in Hong Kong for which marketing has begun within the 2016 calendar year and would be the first since Virscend Education listed on January 13.

    Indicative deal terms include the sale of 333.3 million shares at a price range of HK$2.68 to HK$3.76 per share. The company is selling 25% of its enlarged share capital through the IPO with an option to increase the deal size by 15% depending on subscription levels.

    Based on these terms Goodbaby China could raise between $115 million to $161 million on a pre-shoe basis and up to $185 million if the upsize option is fully exercised.

    By Hong Kong standards that is not a large trade; the territory was the world’s largest IPO fundraising hub last year, raising a total of $33.7 billion. So Goodbaby China’s offering is less likely to be undermined by broader market sentiment, assuming the company and its representatives can pitch a good equity story during the bookbuilding process.

    Initial readings are encouraging. Goodbaby China, which is China’s largest multi-channel retailer of children’s products, according to its prospectus, ticks some of the hottest investment boxes in China as it stands to benefit from China’s new two-child policy, increased consumption, and the boom in e-commerce.

    Goodbaby China sells maternity, baby, and children’s products both under its own brands and third-party brands. It operates in the downstream of the value chain and is independent to Goodbaby International, the Hong Kong-listed manufacturer of children’s products.

    The company was formed through a spinoff from Goodbaby International in 2010.

    Moving online

    Like other consumer retailers, Goodbaby China is in the midst of transforming into an online and offline retailer through the introduction of internet and mobile sales platforms.

    It appears to have executed the transformation well with a significant portion of its growing sales shifting to online platforms.

    According to the company’s prospectus, online sales as a percentage of revenue grew from 5.2% in 2012 to 22.4% in the first 10 months of last year. During this same period, Goodbaby China’s revenue and net profit grew at a compound annual growth rate of 11.75% and 14.5%, respectively.

    One of the company’s strengths is the extensive strategic partnerships it has entered into with international brands like Nike, Adidas, Reebok, and Puma. Sales of third-party brand products have become a key sales component for the company, accounting for around 35% to 40% of its total revenue in the last four years.

    Goodbaby China’s multi-channel retail sales model and its focus on children’s products make it difficult to benchmark against individual listed companies. So for comparison purposes, syndicate analysts are using a basket that comprises Chinese offline retailers Anta Sports and Cosmo Lady and online retailer Jumei International.

    One source familiar with the matter told FinanceAsia that the indicative price range for Goodbaby China’s IPO equates to about 9.5 times to 13.3 times estimated 2016 earnings, based on the syndicate consensus. That is a significant discount to the trio of reference companies, which are much bigger in terms of their market capitalisation but trade at around 18 times forecast 2016 earnings.

    The company intends to continue expanding both online and offline sales model, with the proceeds of the IPO allocated fairly evenly between the two.

    Approximately 30% of the proceeds will be deployed for expanding self-operated stores, while another 25% will be used for potential acquisitions of new businesses and technologies. The company also plans to use 22% of the proceeds to improve its supply chain management and IT infrastructure, according to its prospectus.

    Morgan Stanley is the sole sponsor of the IPO and also a joint bookrunner with BOC International.

  • Korea to release online price index

    Korea to release online price index

    South Korea plans to unveil a new index tracing online retail prices this year by using big data from private sector to reflect actual economic sentiment, according to Statistics Korea on Tuesday.

    The state-run agency plans to release an online price index that will complement the consumer price index by the end of this year, the agency reported in its 2016 plan to President Park Geun-hye.

    To develop the new indicator, Statistics Korea is currently collecting price data from six major online shopping malls and discount store chains — E-Mart, Homeplus, Lotte Mart, Lotte Supermarket, 11st and Interpark.

    “The online price index will be calculated based on the prices of a sample of representative items being sold online,” an official at the agency said.

    He added that the index will show the average price change on a daily basis unlike the consumer price index which shows monthly data.


  • Hong Kong feels squeeze of slowing China, rising rates

    Hong Kong feels squeeze of slowing China, rising rates

    AS a premier Asian financial center parked at the doorstep of one of the fastest-growing economies on the planet, Hong Kong has long lived a charmed life.

    The former British colony’s Western-style legal and regulatory system made it a magnet for global investors interested in buying listed Chinese stocks on the Hong Kong Stock Exchange.

    Its banks, insurance companies, ports and cargo carriers have made a nice living off their powerful neighbor. An added bonus: Since 2008, low global interest rates in the post-financial crisis era have powered a property market that has kept the $300-billion economy humming.

    Yet, now China’s economy is decelerating and just turned in its weakest full-year economic growth since 1990. Global investors are no longer gravitating to Hong Kong—they’re scrambling for the exits.

    The Hang Seng Index has slumped 13 percent so far this year. Housing prices have fallen 8 percent from their September peak and are poised to drop as much as 30 percent this year, according to Bocom International Holdings Co. analyst Alfred Lau.

    The Hong Kong dollar peg is under pressure and short-term interest rates have spiked. Exports are falling and big-spending Chinese tourists are staying away.

    “Hong Kong is facing a wave of pressure,” said Kevin Lai, chief economist for Asia excluding Japan at Daiwa Capital Markets in Hong Kong, who likens the growing storm to the market gyrations of the Asian financial crisis. “The situation right now is potentially worse” than the regional turmoil in 1997 and 1998.

    Lai is particularly concerned about the rapid credit expansion over the past five years, as Chinese companies rushed to borrow in Hong Kong, leaving the city’s banks “massively leveraged and exposed.” Daiwa estimates that $237 billion in broad inflows has poured into Hong Kong since 2005.

    Capital flows accelerating

    For Hong Kong, the worst-case scenario could play out like this: A sustained dive in the Hang Seng Index and heavy downward pressure on the local dollar triggers a massive departure of capital, squeezing liquidity in the banking system and driving up interest rates. That, in turn, sparks a speculative attack on the local dollar peg, forcing the Hong Kong Monetary Authority to defend it by spending its foreign-currency reserves. Or abandon the peg altogether.

    Capital flows out of Hong Kong appear to be accelerating. The Hong Kong dollar has traded at the lower side of its trading range against the US dollar, and recently touched a seven-and-a-half year low versus the greenback. Local interest rates have also surged: The three-month Hong Kong Interbank Offered Rate (Hibor) has jumped 30 basis points to 0.697 since the end of last year, exceeding the London Interbank Offered Rate on January 20.

    A sustained spike in Hibor could push mortgage rates higher, further hurting housing affordability, Morgan Stanley analysts led by Derrick Y. Kam wrote in a note. The bank said it cut its price targets for Hong Kong property stocks by an average of 17 percent.

    While global investors can quickly withdraw money from this Westernized financial center, local banks and investors face a tougher time pulling their cash out of the mainland economy.

    “It could take a matter of seconds for the rest of the world to draw money out from Hong Kong—but it would be a lot more difficult for Hong Kong to do the same from China,” Lai said.

    If the US Federal Reserve (the Fed), which raised rates last December for the first time in almost a decade, pushes up rates again as expected later in the year, it could pull the rug out from housing prices that have surged more than 350 percent from their low in 2003. To maintain its peg with the US dollar, Hong Kong must match interest-rate hikes by the Fed, increasing borrowing costs to homeowners.

    “The property market in Hong Kong is going to go down the tubes when eventually the Americans will continue to increase interest rates,” said Andrew Freris, CEO of Ecognosis Advisory, a Hong Kong-based economic and financial consultancy.

    Meantime, Hong Kong developers with significant yuan-denominated cash holdings face greater currency risks from the yuan’s increasing volatility, according to Bloomberg Intelligence.

    Retailers paying heavily

    Hong Kong retailers are also paying heavily because of Hong Kong’s peg.

    The city is losing its luster as a shopper’s paradise for mainlanders, who are instead flocking to Japan and South Korea in search of better bargains for Louis Vuitton handbags and Patek Philippe watches, thanks to those countries’ weaker currencies.

    Retail sales fell 3.1 percent in the first 11 months of 2015, with jewelry, watches and clocks, especially hard hit with a 15.4-percent decline. There have been other disappointments, too. The Shanghai-Hong Kong Stock Connect, a program allowing individual investors on either side of the border to invest in each other’s stock markets hasn’t delivered the boost to Hong Kong shares its architects had envisioned.

    Since its launch in November 2014, Chinese buyers have only reached the 10.5 billion yuan daily buying quota on two days, and total ownership has never reached the 250-billion yuan limit.

    That said, Hong Kong does have a track record of weathering market storms, and its bourse isn’t the only one suffering losses. The MSCI Asia Pacific Index is down 10 percent this year as oil’s slide and concerns over China’s economic outlook dents shares around the world.

    The city also has deep resources to respond to any attack. During the 1997-1998 Asian financial crisis, the Hong Kong Monetary Authority spent HK$120 billion buying up Hong Kong stocks, and successfully defending the dollar against speculators.

    In 2003 after the severe acute respiratory syndrome virus epidemic leveled the economy, Beijing created a free-trade deal with Hong Kong through the Closer Economic Partnership Agreement that gave its businesses a leg up over rivals in China. Easing of travel restrictions unleashed a flood of Chinese visitors and buoyed retail sales.

    Hong Kong’s $358.8 billion in foreign exchange reserves as of the end of December and a budget surplus give local authorities room to maneuver.  “The speculators right now want to make Hong Kong just like 1998,” said Banny Lam, cohead of research at the Agricultural Bank of China International Securities Ltd. in Hong Kong.

    Lam reckons that a key difference between now and the Asian financial crisis is that the system is flush with interbank liquidity, which means the speculators will be proven wrong.

    Yet, even if Hong Kong can pull through the current market turmoil, it faces bigger challenges ahead. David Dodwell, executive director of the Hong Kong Asia-Pacific Economic Cooperation Trade Policy Group, says that going forward the city has to move beyond its position as the gateway to China by having its banks and professional services help Chinese companies establish their global operations using the city as their base.

    “For me, the litmus test is the flow of headquarters to Hong Kong,” Dodwell said.
  • Indonesia’s central bank forecasted 4.8% economic growth in 2015

    Indonesia’s central bank forecasted 4.8% economic growth in 2015

    Bank Indonesia (BI), Indonesias central bank, had estimated the economy to grow by 4.8 percent in 2015, slightly higher than the Finance Ministrys forecast of 4.74 percent.

    “The central bank had estimated a 4.8 percent growth throughout 2015,” BIs Deputy Governor, Perry Warjiyo, stated here on Friday.

    Despite last years economic growth being far from the revised budget assumption of 5.7 percent in 2015, the economy is believed to grow at a better pace in 2016, Perry affirmed.

    “This year, the economy could grow at 5.2 percent,” remarked Perry.

    Domestic economic growth is being supported by several factors, such as the global economic growth, which is believed to improve though not that strongly.

    Besides this, the government has implemented the fiscal stimulus in the first quarter of 2016 in addition to BI relaxing the macroprudential policy to boost liquidity, thereby helping banks in lending.

    “And finally, of course, yesterday, the central bank had given a signal of monetary easing by scaling down the BI rate by 25 basis points, which will give a positive perception to the business community to buy government securities,” Perry remarked.

    Currently, the BI rate is at the level of 7.25 percent, with the deposit facility rate at 5.25 percent and lending facility rate at 7.75 percent.

  • ADB offers new loan scheme to Indonesia

    ADB offers new loan scheme to Indonesia

    The Asian Development Bank (ADB) has offered a new loan scheme to the Indonesian government, and currently, both parties are still reviewing the potential financing that can be availed through it.

    Development Financing Deputy of the Indonesian National Development Planning Agency (Bappenas) Wismana Adi Suryabrata stated that the newly offered scheme is different from the earlier three schemes of result-based lending, direct lending, and conventional loans.

    “They are offering the loan based on the need to fund projects in the state budget. So, it is not similar to procurement, but when the project is completed and there is still a shortage of funding, then they can cover it,” Wismana explained here on Friday.

    Wismana noted that the loan scheme is directly based on the matrix of infrastructure projects in the state budget, and it is a new scheme that has not yet been offered to other multilateral or bilateral financing institutions and partners.

    Indonesia will benefit from the governments criteria for the projects under this new scheme. Moreover, the government has received assurance for additional sources of funding if there is a shortage of funds to finance any government infrastructure projects.

    “This new scheme is only for infrastructure projects,” Wismana stated while referring to the ADB, which is also expanding its role to finance social and environmental projects.

    However, the Indonesian government and ADB are still formulating other provisions in this new scheme, Wismana added.

    Currently, the ADB is offering a lending rate of 1.2 percent, with a five-year grace period and a repayment tenor of 20 years.

    Previously, the ADB had increased the loan limit to Indonesia in 2014, when it had disbursed funding worth US$710 million.

    The loan was then increased to US$1.5 billion.

    In 2016, the ADB has committed to lend US$2 billion to Indonesia.

  • BNI Syairah resolved to attract more investors

    BNI Syairah resolved to attract more investors

    State-owned Bank BNI Syariah is determined to attract more strategic investors this year as part of its efforts to increase capital, according to its President Director Dinno Indiano.

    The Bank BNI Syariah has opened itself to investors over the past three years.

    “This year we will make even more intensive efforts to lobby for investors. After all, we have the confidence, supported by good performance over the past three years,” Dinno told a press conference in Jakarta on Tuesday.

    Earlier, President Director of Bank BNI, Achmad Baiquin, said the state-owned bank was exploring the possibility of cooperating with strategic investors to support the BNI Syariah business. Bank BNI Syariah is a subsidiary of Bank BNI.

    Bank BNI was willing to sell 20 percent or more of the stake of its subsidiary to strategic investors. Yet, Bank BNI will remain the majority holder of the Bank BNI Syariah stake.

    Last week, Bank BNI said it was optimistic that its Peoples Business Credit (KUR) would increase rapidly in 2016 after the interest rate on the credit scheme was cut to 9 percent per year.

    Achmad Baiquni said in a statement that between August 2015 till 2015-end, the publicly traded state lender had already disbursed more than Rp3 trillion in KUR.

    Baiquni said this amount is predicted to surge to more than Rp10 trillion in 2016 .

    KUR disbursement by BNI was made symbolically at the Glenmore sugar factory in Banyuwangi, East Java, on Wednesday in the presence of the Minister for State Enterprises Rini Soemarno and Achmad Baiquni.

    Baiquini said the KUR funneled by BNI in 2015 represented an increase of 70 percent from 2014.

    In 2015, there were more than 12,200 KUR recipients all over Indonesia. In East Java alone, BNI funneled Rp476.5 billion in KUR to 2,022 clients, including micro businesses, retailers and workers.

    In East Java, KURs are offered to labor intensive and productive sectors such as processing industry, agriculture and trade.

    There is a potential KUR market in East Java, and it may attract sugar farmers under the coordination of state plantation company, PT Perkebunan Nusantara (PTPN).

    BNI is optimistic that there would be more KUR users in 2016 because of the cut in interest rate and improved economy.

  • Should We Worry About The Hong Kong Dollar?

    Should We Worry About The Hong Kong Dollar?

    Winter is coming to Hong Kong. The Hong Kong dollar breached its 2007 low today, down to as low as 7.8226, just haircuts away from the 7.85 level that would prompt the Hong Kong Monetary Authority to intervene.
    After China decoupled its loosely pegged yuan from the dollar last August, we Hong Kong residents are understandably worried Hong Kong may de-peg its currency as well.

    But really, rather than the Hong Kong dollar, we should worry about the Hong Kong economy instead.

    First of all, it is highly unlikely Hong Kong would want to rock the boat even though Hong Kong’s economy is more closely tied to China (and so should its monetary policy be). After all, this is the government that lets its citizens kidnapped across the border without consequences.

    Second, HKMA has enough gun power to defend its currency when it comes to it. Hong Kong’s foreign reserve is currently at $359 billion, which covers 1.75 times its monetary base. See my last week’s blog for Credit Suisse‘s commentary on the possibility of Hong Kong de-pegging.

    But what this means is that Hong Kong has to raise its interest rates to compensate for the Hong Kong dollar outflow, estimated to be around 300 billion Hong Kong dollars, or $38 billion. This certainly is not good news for the Hong Kong economy, especially when it is already in the downturn. In 2015, Hong Kong retail sales, a growth engine in recent years, is expected to slump over 5%, even worse than the SARs epidemic in 2003.

    Hong Kong investors are catching up to reality today, sending the Hang Seng Index down 3.1% a new 40-month low. No surprise, Hong Kong property developers tumbled today. Cheung Kong Property fell 5.6%, Wheelock dropped 4.8%, Wharf Holding was down 3.7%.

    Year-to-date, the iShares China Large-Cap ETF (FXI) fell 13.5%, the iShares MSCI China ETF (MCHI) fell 13.4%, the iShares MSCI Hong Kong ETF (EWH) was down 10%.

  • China quarter feeblest since ’09

    China quarter feeblest since ’09

    China’s economy slowed in December, capping the weakest quarter of growth since the 2009 global recession, as the Communist leadership grapples with a transition to consumer-led expansion.

    Industrial production, retail sales and fixed-asset investment all slowed at the end of the year, while gross domestic product rose 6.8 percent in the fourth quarter from a year earlier. Full-year growth of 6.9 percent, the least since 1990, was near the government’s target of about 7 percent.

    Policymakers must weigh the need for further monetary easing with the risk it would spur more weakness in the yuan and additional capital outflows. Arguing against major stimulus: A rise in services, which became more than half of the economy for the first time, cushioned the slowdown and underpinned employment.

    “2016 will be another challenging year as the old capital-intensive, highly levered industrial sector continues to be placed under severe strain,” said Kenneth Courtis, former Asia vice chairman at Goldman Sachs Group Inc. and now chairman of Starfort Holdings. “But we remain constructive on the outlook for the period ahead,” he said, citing steady job gains and retail sales that are rising faster than GDP.

    Industrial production posted one of the weakest gains in the past quarter century, increasing 5.9 percent in December from a year earlier, compared with a 6 percent median estimate of analysts and November’s 6.2 percent.

    Retail sales increased 11.1 percent from a year earlier, compared with the 11.3 percent projected by economists. Fixed-asset investment excluding rural areas expanded 10 percent last year, the slowest pace since 2000.

    The Shanghai Composite Index closed 3.2 percent higher as the data fueled speculation of increased stimulus and industrial shares rallied on prospects of state-fund buying.

    In an update to its annual outlook published Tuesday, the International Monetary Fund left its estimate for China’s growth this year unchanged at 6.3 percent even as it lowered the global projection to 3.4 percent. The fund said risks to the global outlook remain tilted to the downside, with the world facing three big adjustments: the emerging-market slowdown, China’s shift to growth driven less by exports and manufacturing, and the Federal Reserve’s gradual exit from ultra-low interest rates.

    China’s top leadership has signaled in recent months it may allow some additional slowness as officials tackle delicate tasks such as reducing excess capacity, but nothing that could threaten President Xi Jinping’s goal of at least 6.5 percent growth through 2020. The world’s second-largest economy will slow to 6.5 percent this year and 6.3 percent next year, according to the median of economist estimates.

    Reaching the official 6.5 percent target “is fast becoming a challenge,” Shen Jianguang, chief Asia economist at Mizuho Securities Asia Ltd. in Hong Kong, said in a note.

    China’s economy is going through a “tough transition to make, but critical if growth is to be sustainable,” former Fed Chairman Ben Bernanke said at a forum Tuesday in Hong Kong. “You have to have a transition to more services if you want to keep the economy growing and providing jobs.”

    China’s economy is growing at two speeds, with old rust-belt industries from steel to coal and cement in decline while consumption, services and technology do better. Services accounted for 50.5 percent of output last year.

    The policy response to last year’s slowdown included accelerated monetary easing with six interest-rate cuts since late 2014 and increased fiscal spending. Through market turbulence, the central bank forged ahead with interest-rate liberalization by removing a cap on deposit rates and won the IMF’s approval for the yuan to enter its Special Drawing Rights basket of reserve currencies.

    This year, attention is likely to turn more to a new focus on supply-side tactics such as cutting excess industrial capacity and labor in state enterprises, lowering taxes and increasing productivity.

    Information for this article was contributed by Xiaoqing Pi, Ailing Tan, Jeff Kearns, Enda Curran and Christopher Anstey of Bloomberg News.

    Business on 01/20/2016

  • Indonesia to speed up EU CEPA negotiation

    Indonesia to speed up EU CEPA negotiation

    Indonesia will speed up negotiations on the Indonesia-European Union (EU) Comprehensive Economic Partnership Agreement (CEPA), aiming to have an agreement with the EU come into effect within two years.

    The two parties had discussed the implementation of the CEPA in a meeting with EU trade ministers during the World Economic Forum (WEF) in Davos last week, Trade Minister Thomas Lembong said.

    “It has been decided in a Cabinet meeting that we will have a trade agreement with the EU. We must start it immediately because the President gave us two years to complete the agreement,” Thomas said in Jakarta on Tuesday.

    In contrast to the discussion of trade agreements in the Trans Pacific Partnership (TTP), which still required time for assessment to solve the challenges, Thomas underlined that there were no special constraints on the Indonesia-EU CEPA discussion.

    The planned Indonesia-EU CEPA has been stagnant since 2013. Vietnam, which started free trade agreement negotiations with the 28-member trading bloc in the same year reached an agreement in August last year.

    The EU CEPA covers issues of trade and business, including the reduction of trade barriers and liberalization of government procurement. The two points are also included in the TPP framework.

    Aside from the two agreements, Thomas continued, the ministry also held meetings with trade ministers from several countries to discuss bilateral trade agreements.

    “We are exploring bilateral trade agreements with Australia. Also with the EFTA [European Free Trade Association] which consists of Norway, Switzerland, Iceland and Liechtenstein,” Thomas said.

  • Malaysian banks in Indonesia to gain from BI rate cut

    Malaysian banks in Indonesia to gain from BI rate cut

    The interest rate cut by Bank Indonesia (BI) last week and further anticipated rate cuts in that country could be a game changer for Malaysian banks in Indonesia as they could see an uplift in their loan growth and earnings amid a challenging economic environment following weaker commodity prices and slower economic growth.

    Malayan Banking Bhd (Maybank) and CIMB Group Holdings Bhd’s units had been bogged down by provisions due to pressure on their asset quality but this scenario is set to change amid signs of further rate cuts by the Indonesian central bank.

    Maybank operates in Indonesia via PT Bank Maybank Indonesia Tbk and has about 80% shareholding in Maybank Indonesia Tbk while CIMB Group has 97.94% stake in PT Bank CIMB Niaga Tbk.

    CIMB Group chief executive Tengku Datuk Seri Zafrul Aziz, via an e-mail, told StarBiz the move to cut interest rates by BI would see further uplift in CIMB Niaga’s loan growth this year.

    “BI is adopting a growth strategy for its 2016 monetary policy. As such, we believe there will be further interest rate cuts this year. We expect CIMB Niaga earnings to improve this year on the back of sustained net interest income, improved non-interest income as well as lower loan provisions,” he said.

    He said the group was still positive on the longer-term growth and opportunities in Indonesia and were placing added focus on the consumer and small-medium enterprise (SME) segments in a bid to boost earnings growth.

    “With the government’s economic policy packages that aim to boost the economic growth in Indonesia, we are cautiously optimistic of our business growth there.

    “On the direction of the gross non-performing loans (NPL) of the industry, it is highly dependent on the macroeconomic shifts from commodity prices, the currency and consumer consumption. For CIMB Niaga, we expect gross NPLs to gradually reduce, going forward, from the high of 2015,” Zafrul added.

    For the third quarter ended Sept 30, 2015, CIMB Niaga’s gross NPL ratio improved to 3.17% compared with 3.35% in the same period a year ago as a result of sales of asset to an affiliated company of CIMB Group. Its loan loss coverage during the period increased to 120.96% from 82.89% a year ago.

    The group’s Indonesian arm posted a net profit of 442 billion rupiah (RM137.4mil) for the third quarter. Comparatively, it recorded 93 billion rupiah a quarter ago.

    The bank kept its position as Indonesia’s fifth largest bank by assets, with total assets standing at 244.29 trillion rupiah, representing a 7.3% increase year-on-year.

    Total gross loans rose 7.2% year-on-year to 178.89 trillion rupiah, driven largely by growth in corporate loans, consumer loans and in micro small-medium enterprise banking, while commercial loans remained flat.

    BI, on Jan 14, announced a 25-basis-point cut in its benchmark policy rate to 7.25% in a bid to lift an economy growing at its slowest rate in six years.

    Zafrul said CIMB Niaga would follow suit with the rate reduction and also make adjustments to its lending interest rate accordingly as the cost of funds would be correspondingly lower.

    He said the banking group has also identified a few key priorities for CIMB Niaga this year. These include looking at ways to optimise its SME franchise, further developing its treasury and market capabilities and growing the consumer banking business while focusing efforts to increase CASA (current account/savings account), improve asset quality and continuing with its stringent cost management initiatives.

    Additionally, Zafrul said CIMB Niaga would play a more active role as the leading digital bank in Indonesia with the support of a new core banking infrastructure.

    Meanwhile, despite weakening asset quality, Maybank Indonesia’s net profit for the nine months ended Sept 30, 2015 increased by 70.7% to 592 billion rupiah (RM187.1mil) from 347 billion rupiah a year ago. Its gross NPL stood at 4.34% in the third quarter from 2.55% last year. The bank posted loans growth of 6.6% to 111.5 trillion rupiah in the nine months from 104.6 trillion rupiah in the same period in 2014.

    On the loan growth for CIMB Niaga and Maybank Indonesia as a result of the interest rate cut, Malaysian Rating Corp Bhd head of banking Sharidan Salleh said: “During the nine months of last year, the two banks’ loans grew by about 7% year-on-year. We expect the banks’ loan growth could be higher in 2016 at about 9%-10% in tandem with the expected higher GDP growth at 5.3% in 2016 from 4.73% in 2015.

    “The economic growth is expected to be supported by Indonesian government-driven infrastructure projects. However, banks’ profits from Indonesian operations could be pressured by provisions and compressed margin. Given the current challenges in the economy, we expect the asset quality of these banks would remain under pressure in 2016.”

    UOB Kay Hian analyst Alexander Margaronis said that based on historical data, significant loan growth in Indonesia might take three quarters to pick up after the first rate hike.

    Furthermore, he said the relationship between time-deposit (TD) rate cuts to BI reference rate cut was 1:1 in the short term with no lag time.

    “As we expect further BI rate cuts down the road, cost of funds could come down further as time deposit rates decrease. This should keep the industry’s net interest margin relatively stable or even higher.

    “In the last major round of rate cuts by the BI (2009-2013), BI reference rates came down by a total of 350 basis points (bps) versus TD rates declining by about 500 bps whereas lending rates came down by about 300 bps,” Margaronis noted.

  • Thai Central says keen to bid for Casino’s units in Thailand, Vietnam

    Thai Central says keen to bid for Casino’s units in Thailand, Vietnam

    Thailand’s largest retail conglomerate Central Group is keen to bid for Casino Group’s Thai and Vietnam operations, a company executive said.

    Casino owns 58.6 percent of Big C Supercenter Pcl, which has a total a market value of $5.5 billion. Casino said last week it was keen to sell this stake after announcing it would sell its Vietnam unit in the first quarter.

    “We are interested in both Big C in Thailand and Vietnam,” Prin Chirathivat, deputy chief executive officer told Reuters.

    “If the prices are not too expensive, we will be keen to bid,” Prin said adding his family, the Chirathivats, has a combined 25 percent stake in Big C. Central has been actively looking to buy assets overseas as it wants to expand into Southeast Asia and Europe.


  • China on track for a more sustainable economic expansion

    China on track for a more sustainable economic expansion

    Investors world-over fear that China could record another worse-than-expected slowdown this year. Over the past two decades, annual GDP growth in China has averaged around an impressive 10 percent, underpinned mostly by investments, as well as exports. The IMF expects China to account for almost 18 per cent of world economic activity in 2016. Hence a bump in China’s economy can definitely not be ignored. A drop in China’s growth rate from an expansion of more than 10 per cent in 2010 to 6.3 per cent expected this year could directly knock-off about 0.75 percentage points off the global growth rate.

    The recent week’s turmoil in China has hit both stocks and currency markets, sending shock-waves through global financial markets. Stock indexes around the world have seen massive sell-offs, global markets have fallen by 7.1% since January 1st, their worst ever start to a year. The instability brings back to light China’s stock market crash and a surprise Yuan devaluation by Beijing in August 2015 which sparked a global rout, and wiped out trillions of U.S. dollars in value from Chinese equities.

    Some of China’s leading economic indicators, such as its manufacturing index and factory output, are indeed slowing. This is a rational slowdown which would deliver a healthier and more sustainable growth path. The emerging markets and the rest of the world may just have to the deal with the “new normal” of global growth as the Asian giant seeks a slower, but more sustainable, economic expansion.

    Markets will keep focus on China data-deluge, including the GDP, industrial production and retail sales due tomorrow. Expectations are for data to remain weak. Barclays forecasts Q4 GDP growth data to have slowed further to 6.6 % y/y (consensus: 6.9%) from 6.9% in Q3. Industrial production is likely to have moderated, (Barclays: +5.9%y/y; consensus: 6.0%), retail sales (+11%y/y) and fixed asset investment (+10.1%y/y).

    PBoC has strongly signaled a desire for near-term stability by keeping its USD/CNY fixings stable at about 6.56 over the past week. On Monday, the PBoC said they will start implementing RRR to some banks involved in the offshore yuan market, in a move that seemed intended to soak up additional liquidity. The spot market opened at 6.5800 per dollar on Monday and was trading at 6.5792 in early trade, 48 pips below the previous close and 0.31 percent away from the midpoint, which was set at 6.559. The offshore yuan was trading -0.18 percent away from the onshore spot at 6.591 per dollar, firmer than the previous day’s close of 6.6165.


  • Jakarta index closes higher on Friday

    Jakarta index closes higher on Friday

    The Jakarta composite index (JCI) closed 42.61 points higher on Friday on selective buying by market players.

    The index of the Indonesian Stock Exchange rose 0.96 percent to 4,456.74 points with index of 45 blue chips up 1.48 percent to 779.31 points.

    Selective buying of big capitalization shares pushed up the JCI slightly, HD Capital analyst Yuganur Wijanarko said.

    “In addition, share prices in foreign markets generally rose on oil prices being on the increase lately , prompting market players on the domestic market to buy shares< he said.

    The price of WTI on Friday afternoon rose 4.3 percent to S$30.80 per barrel and Brent pri9ce was up 5.09 percent to US$30.74 dollar.

    Satisfaction expressed by the Capital Investment Coordinating Board (BKPM) with the achievement in direct investment to Rp545.4 trillion in 2015 gave positive sentiment to the market.

    In 2016, BKPM set growth target at 9.3 percent for direct investment to Rp594.8 trillion .

    There were 213,493 transactions in the market on Friday with 4.07 billion shares valued at Rp5.25 trillion changing hands .

    Regional markets such as Hang Seng, Nikkei and Straits Times recorded gain in index.

    Meanwhile the national currency rupiah closed stronger trading at 13,834 per U.S. dollar gaining from the previous level of 13,906 per dollar.

    “Rising trend of oil prices propped up the currencies of emerging countries ,” financial market observer from Bank Himpunan Saudara, Rully Nova, said.