Blog

  • Soilbuild bags US$9.4m Myanmar contract

    Soilbuild bags US$9.4m Myanmar contract

    It’s for a shopping center’s addition, alteration works. Soilbuild Construction has nabbed a build and design contract worth about US$9.4m, or $13.4m.

    According to the company’s media release, as Soilbuild’s second contract in Myanmar, the US$9.4m deal is for the addition and alteration works of St. John Shopping Center in Yangon. It was awarded by a joint venture between two reputable companies in Myanmar, which have activities in retail and real estate development.

    The work for St. John Shopping Center is expected to begin in the first quarter of 2016, and is to be completed within 8.5 months from the commencement.

    Soilbuild notes that this project is not expected to materially impact the company’s net tangible assets and earnings per share for FY16.

  • Singapore supermarket lost $120000 on trolleys

    Singapore supermarket lost $120000 on trolleys

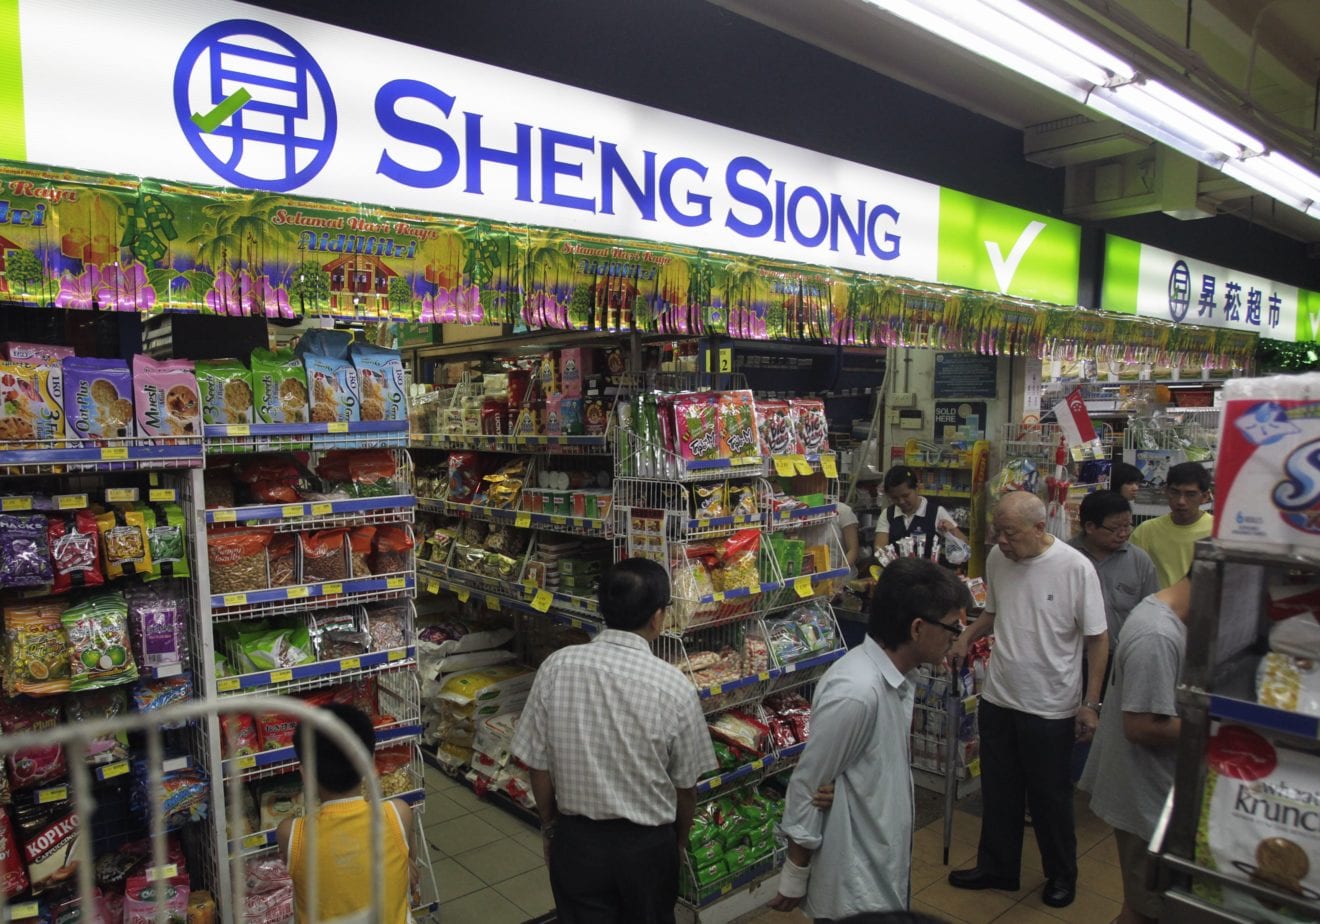
    The third largest chain of supermarkets in Singapore Sheng Siong loses 90 metal trolleys and 180 plastic ones over its outlets each month.  That interprets into a stunning $120,000 loss on just trolleys. Furthermore, this supermarket chain is not the only one. In the previous two years, NTUC FairPrice lost around 1,000 trolleys every year over more than 90 stores they operate in.

    The grocery store chain said it spends around $150,000 every year on repairing, supplanting and recovering abandoned trolleys. Sheng Siong said a few clients do return the trolleys, however not promptly, after use.  Be that as it may, in 2012, NTUC FairPrice lost just around 800 trolleys crosswise over more than 80 stores, proposing an ascent in the quantity of unreturned trolleys when contrasted to 2014 and 2015.

    For the supermarkets, store workers recover the trolleys from adjacent housing estates, asphalts and taxi stands now and then. Clients are required to store a one-dollar coin into the metal trolley when they acquire one from Sheng Siong general store, yet plastic ones don’t require any store. Similarly, NTUC FairPrice grocery stores’ trolleys require a deposite of either a one-dollar coin from the old coin series or a 50-penny coin from the new coin series. In spite of the series of un returned trolleys, Sheng Siong has not yet made any police reports in this regard.

  • India And Southeast Asia Could Be The ‘New China’ For Apple

    India And Southeast Asia Could Be The ‘New China’ For Apple

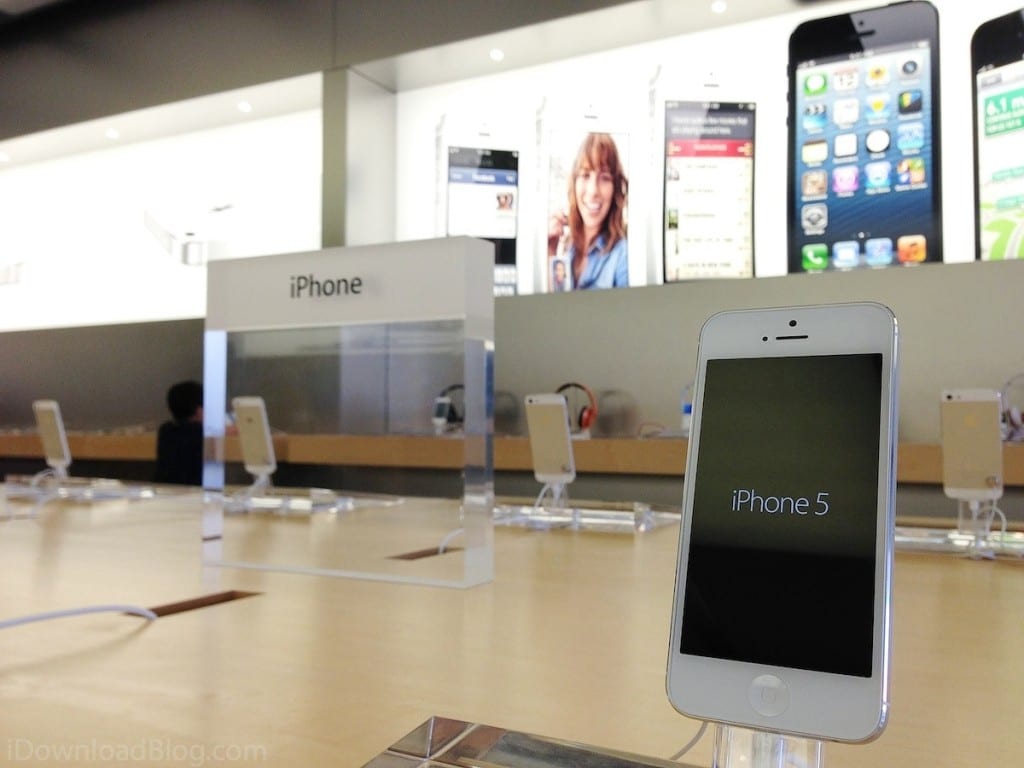
    I first wrote about the potential of Asia for Apple in September 2014. My article, titled “Asian Growth sends strong bull message for Apple” met with a lot of critical comments that the Apple brand would never catch on in China. The people were too poor, the local competition was too strong, the political and legal hurdles were an insurmountable barrier, etc. Of course, such critics have been proved very wrong. In the company’s 2012 annual report, China was not even listed as a specific operating segment. China is now second behind the US in terms of operating income. Now everyone writes articles about how vital China is to the company.

    Apple’s Q1 2016 results showed the importance of international sales (66% of revenue) to Apple, and specifically the importance of Asia.

    The Americas: revenue decline of 4% to US$29.3 billion.

    Europe: revenue increase of 4% to US$17.9 billion.

    Japan: revenue decline of 12% to US$4.8 billion.

    Asia-Pacific: revenue increase of 4% to US$5.4 billion.

    Greater China: revenue increase of 14% to US$18.4 billion (and + 47% sequentially).

    India specifically, and Asia in general, now offer the same future potential for Apple as did China. Indeed, Asia is already realizing that potential for the company.

    India

    Of course, India is not exactly the same challenge as was China, but the similarities are very apparent. Again, the naysayers state the people are too poor, the local competition is too strong, and the political and legal hurdles (including rampant corruption at every level of society) are insurmountable. For the same reason this was a false argument in regard to China, it is a false argument in regard to India.

    China’s economic growth is indeed slowing. However, consumer demand is strong as China transitions from an industrial economy to a consumer-driven one. Apple will continue to grow there, but more slowly than the 84% growth in revenue it enjoyed last year. Despite all the talk of gloom and doom, in Q1 2016 iPhone unit sales in China did increase by 19%. Mac sales increased 27% year-on-year as the Apple “ecosystem” increasingly embeds itself in the country.

    The country forecast by the IMF to have the fastest growth of any major economy this year is India, at 7.5%.

    Of course India has the negative of a much lower GDP per head than China or of many other Asian countries. The IMF assesses Chinese GDP per head in 2015 at US$8,280. For India it has a figure of US$1,688. What this misses out though is the incredible wealth inequality in India. The middle class there is growing fast and has a strong culture of showing off brand affordability. General estimates are that by 2025 the country will have over 500 million people who can be called “middle class.” As Tim Cook commented in the Q1 2016 conference call, the median age of the country is only 27, the kind of demographic that economists love.

    As my October 2015 article pointed out, India is forecast to have 314 million mobile users by 2017, which would be the second-highest total of any country.

    Retail in India

    Despite the headlining and highly-paid Angela Ahrendts coming on board, Apple has been slow to ramp up its retail presence in Asia. Only about 10% of Apple’s worldwide total of stores are in Asia and Australia. Only in China has the pace of new stores been quickened. In total, 26 new stores are planned for China this year, doubling their current number. The latest of these, the 33rd, opened in Qingdao this week. Apple targets to have 40 stores open in China by the middle of this year. This still compares poorly with the 53 retail stores, for instance, in California alone.

    In India, retail could be vital for success. So far Apple has been handling the retail market in India through sub-distributors, but this has put their brand image in the hands of often not very competent third parties. Historically, retail has been difficult for foreign companies in India, but the Modi Government is relaxing the rules.

    Previously, single-brand retailers which were foreign-owned had to source 30% of their product locally. Additionally, there were heavy restrictions on the use by such companies of e-commerce. With these restrictions being loosened, in mid-January, Apple filed an application to open the first real Apple Store in the country. Just as Tim Cook personally led the political dance to get Apple established in China, so he has reportedly met twice with Indian Prime Minister Modi in the past six months.

    The India Market

    Almost identically to when Apple entered the China market, the smartphone market in India is dominated at present by Samsung (OTC:SSNLF) and by local manufacturers. We all know what happened in China when that was the case a couple of years ago.

    IDC estimates that in the third quarter of 2015, Samsung had 24% of the market and Lenovo held second place among imported phones. Apart from them, it was local manufacturers such as Micromax, Lava and Intex. This is ripe for Apple to follow their China strategy. That means supplying current new models to the wealthier middle-classes and their older models at a strongly discounted price to those who cannot afford the current model. Apple is already doing this in fact. As an example, the 6S originally sold for 62,000 rupees, while the 5S price was cut in early December to 24,999 rupees. This put it in a similar price bracket to the Samsung “A” and “E” series phones. Now the 16GB 6S has been further reduced to 48,499 rupees.

    Up to March 2015, Apple increased sales by 44% to over US$1 billion. It is expected that this figure will double in the year to March 2016. In Q1 2016, revenue increased 38% (or 48% in constant currency terms). iPhone unit sales increased 76%.

    Sales are growing from a small base, but retail expansion and a new concentration on India by Tim Cook should see sales take off in the next couple of years. An accelerated planned roll-out of 4G in India, just as we saw in China, will also help the company’s expansion. Interestingly in the Q1 2016 conference call, Tim Cook made specific reference to rising 4G penetration in China as a boost to Apple sales. No doubt the same is equally true of India.

    He also stressed the importance of emerging markets in general and LTE penetration to the future. He commented:

    “If you go outside of China into the other emerging markets, our share is much lower and the LTE penetration is so low…. it indicates to me that there is still a lot of people, a tremendous number of people in the world, that will buy smartphones.”

    The GDP per head differential with China will mean that India takes longer to reach the stratospheric sales figures we saw in China. Equally, the Apple ecosystem is not as strong in India and it will take time for iTunes and the App Store to become a way of life there.

    One potentially very bullish factor for Apple is the fact that their biggest manufacturing partner, Foxconn, has applied for manufacturing approvals in the country. This has led to obvious speculation that iPhones will be manufactured in the country, with all the myriad advantages that would bring. Foxconn is proposing to have 20 facilities operating in India by 2020 at an investment cost of US$5 billion.

    Elsewhere in Asia

    China may have a population of 1.4 billion and India 1.25 billion, but elsewhere in Asia the sheer mass of the addressable market is substantial. Figures of population of other Asian countries for 2015 and World Bank details of GDP per capita for 2014 illustrate the often-overlooked potential in Asia outside of China and India. In the Q4 2015 conference call, the company had stated that revenue increased 27% in that period for this region.

    There are over 1.8 billion people in Asia outside the behemoths of China and India. This potential is reinforced by the fact that these countries have the demographics that economists look for. That is to say, young growing populations with improving educational levels in countries with strong growth rates. This group of countries alone far exceeds the populations of US or of Western Europe.

    Below, I summarize just a few of the Asian countries where Apple’s footprint has grown strongly.

    Japan (population 127 million and GDP per capita of US$36,194) is the market in the world where the Apple ecosystem is generally considered at its strongest. In the Q4 2015 conference call, Apple had stated that Japan revenue increased 9%, not bad for a mature market. However in Q1 2016, revenue declined 12%, although in constant currency terms it was a decline of only 4%. This is still of some concern for Apple, and the figures seem to reinforce market rumors that the iPhone 6 and 6S were not so well received there in what is already a mature market for Apple.

    Indonesia (population 255 million and GDP per capita of US$3,491) and the Philippines (population 101 million and GDP per capita of US$2,872) are both seeing Apple sales grow strongly. Both have very young populations and the Philippines was the strongest growing economy in Asia last year. Apple is planning to invest in R & D facilities in Indonesia following new government regulations to come into effect in 2017. These will require overseas suppliers to include 30% of import value in their products from either local manufacturing or from software input. Official figures show that Indonesia imported US$5 billion worth of mobile phones in 2015. The real figure would be higher as it does not include parallel imports through Singapore.

    In Korea (population 49 million and GDP per capita of US$27,970), Apple has made significant inroads. This is despite Korea being the home market of the formerly all-powerful Samsung. At the Q1 2016 conference call, it was reported that iPhone sales increased 45% there.

    Thailand (population 67 million and GDP per capita of US$5,977) and Malaysia (population 30 million and GDP per capita of US$11,307) are seeing significant growth for Apple. Exact growth rates have not though been released by Apple.

    Vietnam (population 93 million and GDP per capita of 2,052) is an interesting study. The country was a long-time foe of the US and has a low GDP per capita of US$2,052. Yet, Apple opened a subsidiary there in October last year on the back of sales that had tripled in the first half of 2015. This will allow them to open their own store and sell directly to Vietnamese consumers. There are a startling 124 million cellphone subscribers in the country which shows the fast development in the country.

    Singapore (population of 5.6 million and GDP per head of US$56,284) will be seeing its first Apple store opening in 2016. With a GDP per capita higher than the US and a large re-export business, this is a strong market for the company. Apple Pay will be launched here in 2016. The other Asian destinations for Apple Pay this year will be China and Hong Kong.

    Different commentators may argue as to what extent these countries can have a substantial effect on Apple’s bottom line. There seems little doubt to me as to the strongly accretive effect on the company in the medium to long term.

    For 2016, the ADB (Asian Development Bank) has forecast GDP growth of 7.3% for South Asia, 4.9% for S-E Asia and 6.7% for China. Though lower than in some previous years, this is a lot stronger than likely growth rates in developed countries and will further narrow the gap between the two.

    Conclusion

    It should be only a matter of time before China is the single biggest market for Apple in terms of revenue. As Tim Cook said on the earnings call, the company is “maintaining our investment plans for China.”

    It is probably only a matter of time and demographics before the rest of Asia is Apple’s third biggest market in terms of revenue. This makes it false to argue that growth for the iPhone and other Apple products is limited because of the company’s high market share in its mature markets. Short term, currency fluctuations somewhat tempered Apple’s still healthy growth in the region, but that will not be a continuing long-term issue.

    These immature markets signify that Apple has very significant growth opportunities for years to come, as Tim Cook pointed out. The company may have been somewhat slow to roll out its retail footprint around Asia, but this now seems to be on the way. At the Q1 2016 results call, it was revealed that the company has US$215.7 billion in cash. US$200 billion of this is stashed off-shore. Retail expansion in Asia could well be the best use Apple has for a portion of this huge cash pile. This will help set up Apple’s long-term continuing growth in the region.
  • Toyota Thailand industry auto sales seen down 10 pct in 2016

    Toyota Thailand industry auto sales seen down 10 pct in 2016

    Thailand’s total domestic car sales are expected at 720,000 in 2016, down 10 percent from 2015, Toyota Motor Corp’s Thai unit said on Thursday.

    Toyota, which commands about a third of the Thai market, sees a 9.8 percent fall from 2015 in its annual automotive sales in the Southeast Asian nation to 240,000 in 2016, it said at a news conference.

    Kyoichi Tanada, president of the Toyota Thai unit, said the reason for the fall in both domestic car sales and Toyota’s own car sales were a weak global economy and a new Thai excise tax which would increase the retail prices of vehicles in 2016.


  • Hong Kong bets on Chinese demand to drive property market

    Hong Kong bets on Chinese demand to drive property market

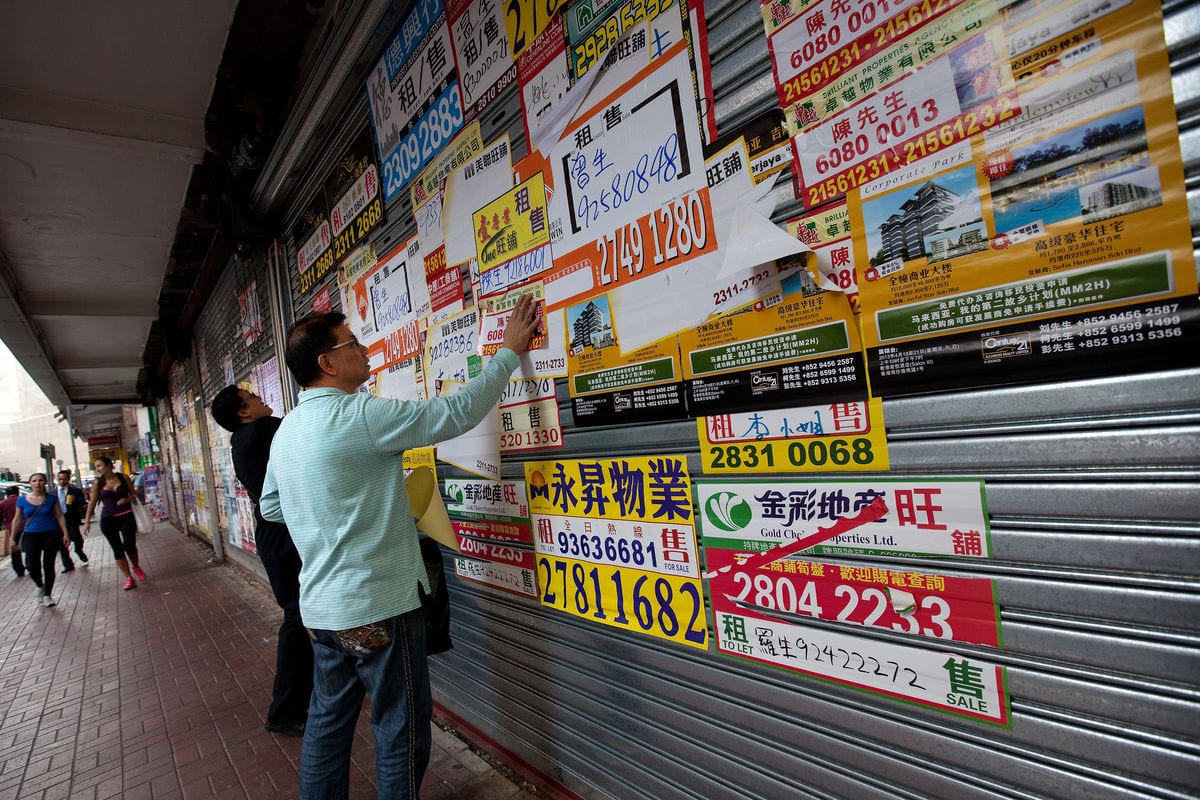
    Mainland China’s influence continues to grow across the four core sectors of the Hong Kong property market, according to the latest research from JLL.

    Demand for office space is increasingly being underpinned by mainland corporates, while a persistent slowdown in inbound tourism from China has put a large dent in retail sales growth of late.

    Cross-border trade remains the lynchpin of the city’s warehouse sector, while mainland participation in the residential market is slowly transitioning from a buyer to that of a developer.

    Office market

    New mainland policy initiatives, including the development of the offshore renminbi market, the expansion of CEPA and the roll-out of the Stock-Connect Pilot Programme, have played a leading role in driving demand for Hong Kong office space.

    In 2015, mainland Chinese firms were among the most active in the market, accounting for about 36 per cent of all new leasing transactions in Central. Their share of new lettings in the Grade A office market has doubled over the past five years and today accounts for about 21 per cent of all floor space leased in Central.

    Denis Ma, Head of Research at JLL, said, “With China’s economy starting to slow and its financial markets showing increased volatility, there is growing concern whether demand from the mainland will be sustained. But looking ahead we remain confident that mainland companies will continue to play a pivotal role in the short- and long-term growth of the city’s office market.

    “Government policies will play a large part in growth and help to attract more foreign companies to establish or grow operations in Hong Kong. We estimate that up to 28 per cent or 7 million sq ft of the tenant base in the Central Grade A office market will be mainland corporates by 2021.”

    Retail market

    Hong Kong’s retail sector flourished at the same time mainland tourist arrivals increased three-fold between 2006 and 2015, accounting for more than three quarters of all tourist arrivals last year.

    Latest figures show mainland tourists spent an estimated HKD 178 billion on shopping in Hong Kong last year, accounting for about a third of all retail sales and spending an average of HKD 3,900 per visit. Despite the growth of mainland arrivals slowing since their peak in 2014, some of the causes that have led to a retail sales slump of late can be reversed through policy changes.

    “If the restrictions placed on multi-entry visas were eased and the Individual Visit Scheme (IVS) programme was expanded as proposed in 2012, up to HKD 21 billion in sales could be added to Hong Kong’s retail market. But the type of tourists would likely be more focused on mass market goods rather than luxury items,” said Mr Ma.

    Industrial market

    Since China’s economy has slowed, Hong Kong’s logistics market has shown signs of vulnerability. In 2015, trade with China retreated for the first time since the Global Financial Crisis, dropping 1 per cent y-o-y through the first 11 months. With external trade accounting for about 70 per cent of all warehousing demand in the city, the slowdown has led to an easing of new warehousing demand.

    But as Pearl River Delta (PRD) industries move up the value chain, they have increasingly turned to Hong Kong’s logistics market to move their goods, taking advantage of the higher quality provisions and security offered by warehouse in the city.

    Other positives for the sector include the completion of new infrastructure that will bring the Western PRD within a 3-hour commute of Hong Kong and permit cargo flowing from the Western PRD to be moved through export facilities at Hong Kong International Airport (HKIA) and the Kwai Chung Container Port.

    Mr Ma said, “According to HKIA Master Plan 2030, cargo handled by HKIA will increase at an average of 4.2 per cent per year, with the bulk of growth being driven by the movement of goods in and out of mainland China.

    “Based on our estimates, the increase in cargo volumes at HKIA translates to about 300,000 sq ft of additional warehousing demand per year. Hong Kong’s status as a key logistics and trading hub will further be cemented by the ‘One Belt, One Road’ policy initiative, while the demand for warehouse will increase.”

    Residential market

    Mainland homebuyers had accounted for as much as 40 per cent of all sales in individual projects in the primary market before retreating to 10 per cent in 2015, largely as a result of the government’s stiff Buyer’s Stamp Duty introduced in 2012.

    Today, attention has shifted to the growing participation of mainland developers. Mainland developers have bid on over half of all residential land sales tendered by the government in 2015, winning about a quarter of awarded tenders and elbowing aside local developers that had long enjoyed an entrenched position.

    They are also setting new benchmarks for the market. The bid prices of mainland developers exceeded market expectations in 73 out of 100 instances between 2013 and 2015, compared with 59 out of 100 for local developers.

    Mr Ma said, “We expect mainland developers will continue to expand in the city. Hong Kong’s traditional developers are still expected to dominate the market but will face increasing competition in acquiring residential plots from a larger pool of bidders.

    “Based on JLL’s supply forecasts, residential units built by mainland developers will account for up to 8 per cent of the overall private housing supply between 2016 and 2019, with the majority delivered in the New Territories (56 per cent) and Kowloon (35 per cent).

    “With around 119,000 new households expected to be formed between 2016 and 2019, about one in ten new families opting for primary homes in the private market could end up living in properties developed by mainland developers.

    “Whether mainland developers are able to grow their business in the city to a point where they can influence market direction remains to be seen and will be dependent on the response to the first wave of their units that come to the market.”

  • Drone Giant DJI Opens Flagship Store In South Korea

    Drone Giant DJI Opens Flagship Store In South Korea

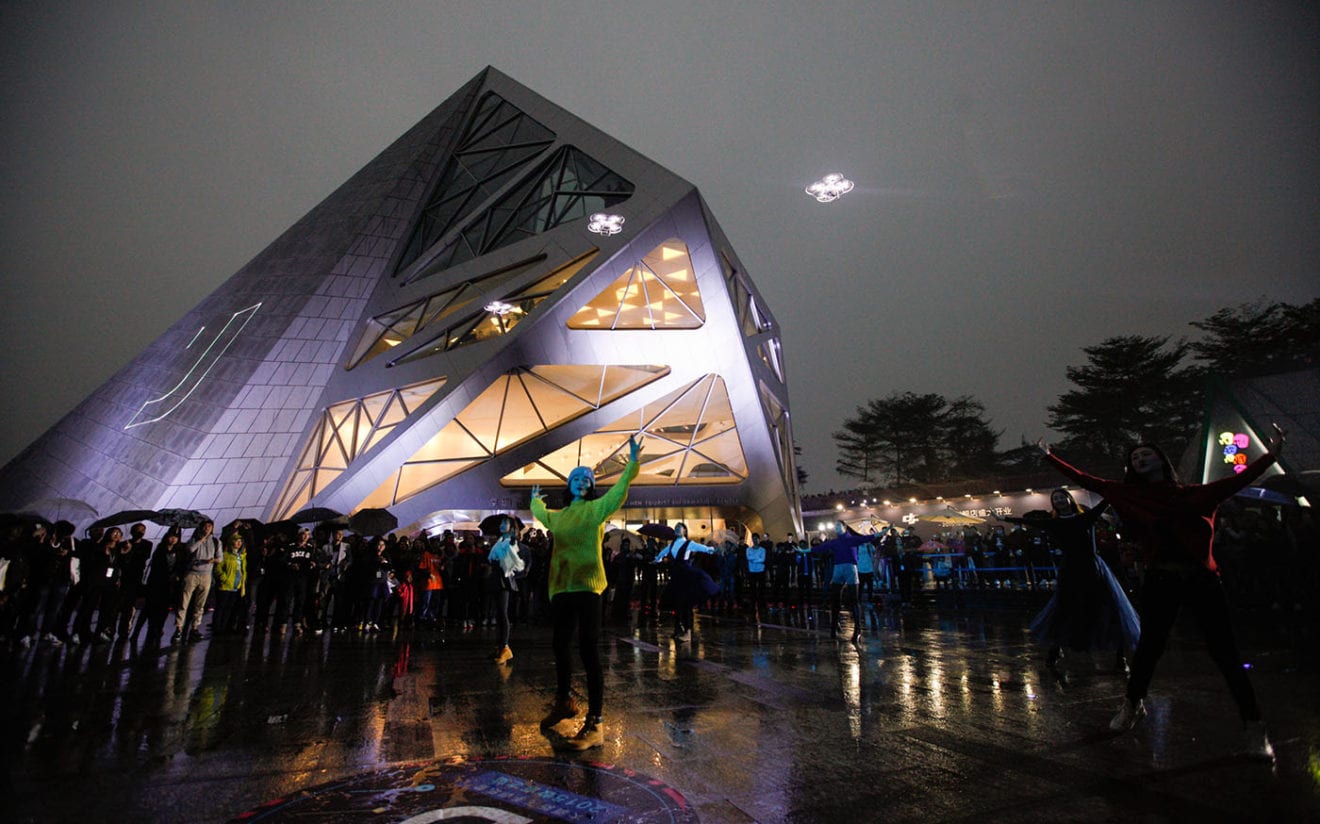
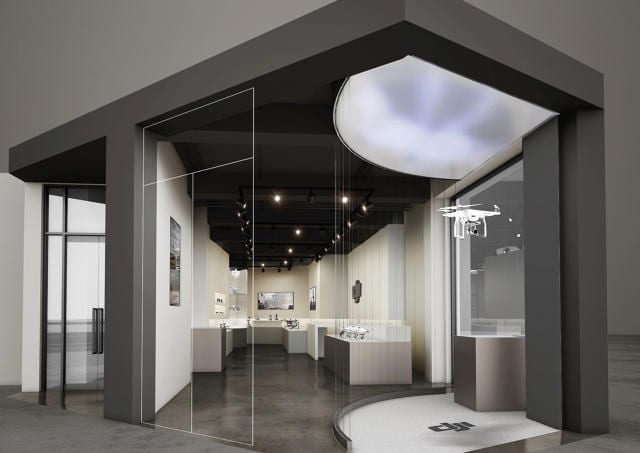
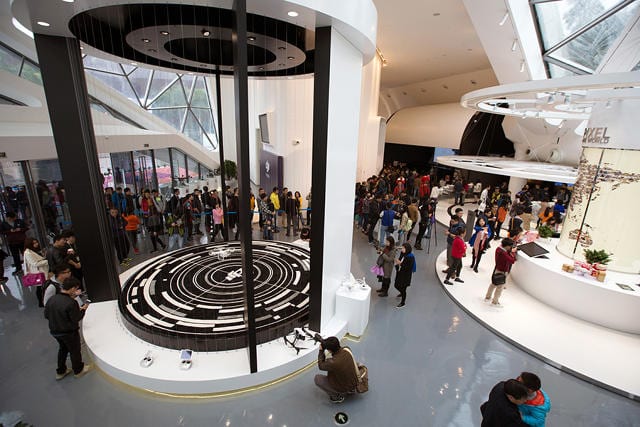
    The Seoul store will open in March. It features five stories and 9,364 square feet showcasing the entirety of DJI’s consumer products. That includes its line of Phantom drones, as well as its Inspire, Matrice, and Spreading Wing drones. Also on display will be DJI’s aerial cameras and its Osmo handheld camera. The store has a theater offering visitors films and other visual content shot using DJI gear, as well as an “experience zone” where DJI pilots will perform demos of the company’s drones.

    A DJI spokesperson said the company has no list of future retail locations. “For us, getting the retail experience right is far more important than the rapid opening of retail stores,” the spokesperson said. “For now, we’ve selected two locations—Shenzhen and Seoul—where we see both opportunity to grow and to offer a hands-on, immersive experience for customers.”

    DJI store in Shenzhen, China

    DJI currently has a 70% share of the global consumer drone market, the company said, with the United States its largest market, followed by Europe.

    In the United States, the federal government now requires owners of most consumer drones to register them or face potentially substantial fines or even imprisonment. As of earlier this month, more than 180,000 people had signed up.

  • Thailand Plans to Boost Northeastern Economy

    Thailand Plans to Boost Northeastern Economy

    Thailand’s northeastern economy, among the poorest in the country, is looking to expand trade with neighboring Laos and business in the Greater Mekong Subregion (GMS) as it recovers from a two-year recession.

    The downturn was triggered by an end of populist programs heralded by the former government of Yingluck Shinawatra. The May 2014 coup ended her almost three year administration and brought an end to programs led by a rice price pledging scheme.

    Under the program, farmers were paid at rates some 50 percent above the global market before the effort collapsed, costing Thai taxpayers more than $14 billion and leaving farmers across the region deeply in debt.

    While the good times lasted, funds triggered a boom in retail and commercial investment and spending. Major department stores sprang up in towns such as Ubon Ratchathani and Udon Thani.

    A rice farmer collects snails and cleans the rice field near Udon Thani, Thailand, Sep. 15, 2015.

    A rice farmer collects snails and cleans the rice field near Udon Thani, Thailand, Sep. 15, 2015.

    But now retailers report sluggish sales and the Thai central bank warns of growing indebtedness among farmers as rice prices fall to their lowest in six years.

    Agriculture accounts for some 20 percent of the region’s economy, followed by trade. Household incomes in the Northeast are the lowest in Thailand, at close to $550 a month, well short of the nearly $1,200 earned per month in the Bangkok region.

    Border trade

    But Athikarn Ringcharoen, president of the Chamber of Commerce in Amnat Charoen province, bordering Laos, said the local economy was starting to pick up although still below levels of two years ago.

    Athikarn said government policy support and increased cross border trade with Laos, was helping the recovery. He added that despite the poor state of the global economy, the provincial outlook was “OK”.

    Infrastructure spending is also set to come to the aid of the region.

    Athikarn said plans to upgrade a Royal Thai Airforce airstrip to a regional airport less than 30 kilometers from Amnat Charoen town were also welcome.

    Long term infrastructure set to benefit the region includes the $10 billion China-Thai 870 kilometer rail-line from Nong Khai, bordering with Laos, to Bangkok. On the horizon is the Japan-Thailand rail-line from Tak province, bordering Myanmar, to Mukdahan, bordering Laos.

    Ubon Ratchathani University political scientist, Titipol Phakdeewanich, said cross border trade ties have helped eased the downturn.

    “Many businesses are now more open to customers from Laos. If you go to different malls – they have signs in Lao [language] and when the market is more connected – to some extent – it helps to provide a cushion to the local economy. So the local economy in the area I don’t think it’s entirely dependent on the global market,” said Phakdeewanich.

    Government spending

    The military government’s economic czar, Deputy Prime Minister Somkid Jatusripitak, has announced spending of over $970 million in projects directed to 70,000 villages nationwide.

    Analysts say the program mirrors similar initiatives under previous governments of so-called “village funds” to boost rural consumption.

    The Federation of Thai Industries, while welcoming the programs, say more measures are needed to ensure growth is sustained.

    The Federation warns the rural sector remains vulnerable to falling commodity prices that may impact some 30 million people in the farm sector – almost half the national population.

  • Singapore investors buy record US$26.3b of overseas properties in 2015

    Singapore investors buy record US$26.3b of overseas properties in 2015

    Singapore-based investors purchased a record US$26.31 billion (S$37.83 billion) in overseas real estate in 2015, up 49 per cent from US$17.63 billion in 2014, going by preliminary data compiled by real-estate data and analytics firm Real Capital Analytics (RCA) as at Jan 12.

    The increase reflects Singapore investors’ strategy of targeting the world’s most liquid markets to diversify and grow their portfolios in the low-interest-rate environment.

    Last year’s record level of deals was boosted by big-ticket purchases by heavyweights such as GIC and Global Logistic Properties (GLP); however, mid-sized and smaller property purchases were also made by Singapore developers and family offices increasingly turning overseas in the face of a dour outlook for real estate at home, with the imposition of property cooling measures.

    RCA’s numbers may be updated as more transactions come to light.

    Globally, Singapore ranked as the fourth-largest cross-border property investor in 2015, the same as in 2014.

    US buyers were the most active in 2015, pouring US$58.74 billion in capital outside their borders; they were followed by their counterparts in Canada (US$32.17 billion) and Hong Kong (US$31.44 billion). China was in fifth position, at US$23.35 billion.

    Marc Giuffrida, executive director of global capital markets (Asia) at CBRE, said it was not surprising that Singapore-based investors emerged the fourth largest cross-border investors of real estate: “Singapore is a relatively small country, but has a relatively large wealth pool to invest – not just sovereign wealth, but corporates, families and private wealth. So there are only so many opportunities for them to put that money to work in Singapore.”

    The overseas property investment brigade from Singapore last year was led by bigwigs GIC, GLP, Temasek Holdings, Mapletree, ARA Asset Management Group and Ascendas Real Estate Investment Trust.

    RCA’s database covers only transactions above US$10 million in various asset classes, including development sites, office, industrial, retail, apartment, hotel and serviced apartments.

    The US$26.31 billion that Singapore investors ploughed into overseas real estate last year was six times the US$4.24 billion figure for 2009, when central banks embarked on the first round of quantitative easing, noted Petra Blazkova, senior director of analytics for the Asia-Pacific at RCA.

    The firm’s analysis also showed that the US$26.31 billion comprised 126 completed transactions, compared with 139 deals in 2014 and 26 in 2009. RCA also noted that there were 68 Singapore-based investors active overseas in 2015, almost double the 33 five years ago.

    Ms Blazkova said: “As more Singaporean investors look abroad to diversify a growing pool of domestic wealth, they have been drawn to offshore opportunities in real-estate markets that offer stable fundamentals, regulatory support and market transparency.”

    Historically, Singapore investors have been interested in the familiar Chinese property market. It was the top destination for Singaporean capital, attracting about US$25.87 billion of investment from 2009 to 2015. The next most popular destination was the US, which drew US$20.29 billion from the island-state’s investors during the same period, followed by Australia (US$15.35 billion), the UK (US$10.80 billion) and Japan (nearly US$7.1 billion).

    For 2015 itself, the US was the top investment destination for Singapore investors in search of overseas property; the US$14.76 billion they invested there was boosted by mega acquisitions by the likes of GIC and GLP in the industrial property sector. This resulted in industrial property being the most sought-after property class overseas among Singapore investors, drawing US$13.92 billion last year.

    A joint venture between GLP and GIC purchased Blackstone’s Indcor portfolio of 117 million sq ft across the US for slightly over US$8 billion; GLP also paid US$4.52 billion for a portfolio of industrial properties in the US which it acquired from Industrial Income Trust.

    In Australia, Ascendas Real Estate Investment Trust picked up a portfolio of 26 logistics properties for A$1.01 billion from GIC and Frasers Property Australia.

    Office and retail property remained popular among Singapore investors; they bought US$5.45 billion worth of office property and US$3.15 billion in retail property overseas last year.

    Of note was GIC’s purchase of a US retail portfolio comprising five malls from Macerich, said RCA.

    While Singapore’s overseas property investments have expanded over the past few years, the inflow of foreign capital into the Singapore property market remained stable at US$3.51 billion last year. This was in line with most of the previous years, with the exception of 2014, when the figure fell to US$1.22 billion.

    Ms Blazkova said: “Chinese investors maintained their lead as the largest source of foreign capital investing in Singapore property, accounting for US$1.03 billion of properties and development sites purchased in 2015.

    “That said, one of the largest sales of Singapore property to a foreign entity also took place in 2015, when a development site in Paya Lebar was acquired for total of US$1.28 billion by a joint venture between Abu Dhabi’s sovereign wealth fund Abu Dhabi Investment Authority and the Australian developer Lend Lease.”

    Apart from this transaction, China’s MCC (China Metallurgical) and Hao Yuan Investment group were the most active foreign investors in Singapore’s real estate market last year.

    Ms Blazkova noted that between 2011 and last year, the preferred route for foreign investors looking to access real estate in Singapore was by purchasing a development site. During the period, they picked up almost US$8 billion of development sites, accounting for 58 per cent of inward investment into Singapore real estate.

    Market watchers said this is partly due to the ease and transparency of the tender process when it comes to buying land at state tenders as well as a dearth of completed investment-grade properties available for sale, as most owners are long-term holders. Moreover, profit margins from property development are typically higher than rental yields.

    Mr Giuffrida of CBRE highlighted a recent trend of more transactions in the lower price bracket of, say, below US$100 million. This segment is starting to attract keen interest from smaller developers, family offices and private wealth on the lookout for opportunities, particularly for yield plays.

    For this year, he predicts two key trends for global cross-border property investments:

    The first is heightened interest in smaller-ticket deals from Asian investors, including Singaporean investors. The second trend is that more investors will move outside core locations. “In the Australian context, if they were previously looking at downtown CBD office buildings, now they are prepared to look at city-fringe locations.

    “In Europe, they might have previously focused on Central London office buildings, development sites and hotels; now they are looking at regional UK and branching into continental Europe.”

    Greg Hyland, head of capital markets, Singapore at JLL, said: “London is still a very important market, but there is an element of caution because of price appreciation; so investors may see better value in continental Europe – for example, Germany, Portugal, Italy, Spain and France.”

  • Philippines leader welcomes Japan’s Emperor as ties blossom

    Philippines leader welcomes Japan’s Emperor as ties blossom

    Philippines President Benigno Aquino III gave a red-carpet welcome to Japan’s Emperor Akihito on Wednesday in a sign of blossoming ties between the two nations, both mired in territorial disputes with China, while further moving past painful memories of Japan’s World War II aggression.

    Mr. Aquino and Emperor Akihito held talks at Manila’s Malacanang presidential palace, where Philippines and Japanese flags were displayed side by side and Filipino troops fired cannons in a traditional salute.

    Mr. Aquino is to host a state banquet later for Emperor Akihito, whose visit marks 60 years of diplomatic relations between the two nations.

    Mr. Aquino and Emperor Akihito briefly discussed robust sales of Japanese-made cars that have contributed to Manila’s heavy traffic and the entry of Japanese retail store Uniqlo, presidential spokesman Herminio Coloma Jr. said.

    Emperor Akihito, a revered symbol of Japanese unity who plays no political role in his country, does not plan to discuss contentious security issues such as the territorial disputes or demands for an apology by Filipino women who accuse Japan’s wartime army of forcing them into sexual slavery, according to the Emperor’s press secretary, Hatsuhisa Takashima.

    During the meeting with Mr. Aquino, “there was no mention of the war,” he told reporters.

    But Mr. Takashima said it was well known to Mr. Aquino that the Emperor had earlier expressed his “profound remorse for the loss of lives of many Filipinos” during the war and that “the Japanese people must remember the agony and difficulty suffered, experienced by Filipino people.

    Asked if an apology could put an ending to the issue of wartime sex slaves, Mr. Takashima said it was not the Emperor’s role to address individual subjects related to the war, but that Emperor Akihito “always mentions the necessity of peace and the stability of the international relations as well as [to] never forget the war and never forget the victims of the war.”

    Relations between Japan and the Philippines have improved dramatically in the seven decades since the war, with Japan becoming a major trading partner and aid donor for the Philippines. Emperor Akihito’s visit is seen as a strong sign of a further deepening of ties as the countries, both close American allies, confront China over long-contested maritime territories.

    Japan’s Self-Defence Forces have staged joint search and rescue exercises with the Philippine Navy near the disputed South China Sea and are providing the Philippines with coast guard patrol boats.

    Still, six elderly Filipino women led a protest outside the presidential palace Wednesday asking the Japanese government to formally apologiSe and compensate them and other sex slaves abused by Japanese forces during the war. They carried placards reading, “No to rising Japanese militarism.”

    “Emperor Akihito’s foreign trips conveying a pacifist message are important because they ease concerns over perceptions that Japanese political leaders are trying to flex the country’s military muscles once again,” said Richard Heydarian, a political science professor at Manila’s De La Salle University.

    “We should forgive but we should not forget the past. That will also help Japan,” Mr. Heydarian said.

    Emperor Akihito is to pay his respects at memorials for both Philippine and Japanese war dead during his visit, which ends Saturday.

  • A bigger shoe may yet drop for Apple stock

    A bigger shoe may yet drop for Apple stock

    As analysts and investors eye prospects for Apple stock, many are drilling down on the company’s sales and earnings prospects in China, its biggest overseas market.

    On Wednesday, the company’s stock was down as much as 5 percent, a day after the tech giant reported disappointing sales of the iPhone and the slowest year-over-year growth ever for the blockbuster device. That news raised a red flag, since those sales account for two-thirds of Apple’s total revenue.

    In response, Apple CEO Tim Cook remained confident on the outlook for China. He noted that Chinese incomes are rising and their savings rate is among the highest on the planet. China’s consumers sent retail sales up 11 percent year-over-year in December — not very ruffled, for now, by the nation’s market turmoil.

    The question, for Apple, is whether that confidence can last: Cook noted in a conference call after Apple’s earnings announcement Tuesday that sales in Greater China, especially Hong Kong, began to “soften” in January. But for now, China’s consumers are the reason why Apple execs rattled off a list of eight nations and regions they were worried about, from Canada to Turkey, without mentioning China.

    “Young urban Chinese elites have savings, so they can afford it,” said Todd Lee, senior director of economic consulting firm IHS Global Insight.

    The damage was less for the simple reason that China’s consumers are relatively flush, even as the nation’s investment and export sectors are enduring shocks. Their savings rate is about 38.5 percent of income, and average per capita disposable income rose 7.4 percent in 2015, even as China’s financial markets whipsawed throughout the second half of the year.

    That’s also a reason why expectations are fairly high for the Jan. 28 report from Chinese e-commerce giant Alibaba, which RBC Capital Markets analyst Mark Mahaney said will boost adjusted profit per share by 31 percent. Consensus estimates are lower, calling for a 25 percent gain.

    Apple said its overall profit for the first quarter of its 2016 fiscal year rose 1.9 percent, to $18.4 billion, or $3.28 per share, from $18 billion and $3.06 a share last year. (The 7.2 percent gain in per-share earnings reflects stock buybacks that reduced Apple’s share count.)

    Sales rose 1.7 percent, to $75.9 billion, but would have been up 8 percent if the value of the world’s different currencies had stayed the same as last year, Apple said. “The difference is about the size of an average Fortune 500 company,” Cook said.

    iPhones’ average price was reduced by $49, to $691, by the rise in the U.S. dollar, which makes each sale in local currency abroad less valuable to U.S.-based shareholders. Currency is also the reason for about a third of the drop in revenue that Apple projected for the March quarter.

    By contrast, Apple’s Brazil sales fell because of a 40 percent drop in the Brazilian real that required Apple to raise iPhone prices there, dragging overall sales in the Americas 1 percent lower. Japan was down 12 percent, sales in Russia were hurt by the collapsing price of oil and the ruble, and the falling euro combined with Russia’s woes to turn an 18 percent European sales gain in constant currency into only a 4 percent as-reported gain. Apple now gets two-thirds of its revenue from outside the U.S.

    “Major currencies, such as the Canadian dollar, Australian dollar, Mexican peso and Turkish lira have declined 20 percent or more,” Cook said, adding that “$100 of Apple’s non-U.S. dollar revenue in Q4 of 2014 translated to only $85 last quarter due to the weakening currencies in our international markets.”

    Analysts had expected Apple to earn $3.23 a share on $76.6 billion in revenue.

    Shares of Apple rose modestly after the earnings were announced, then sagged as Cook and other executives talked on the post-earnings conference call with analysts. Having closed at $99.99, they slumped under $95 on Wednesday morning. The stock was above $120 as recently as November.

    “[The] negative reaction after hours reflect[ed] … a huge shift in tone as AAPL sounded more susceptible to China macro versus 90 days ago,” RBC Capital Markets analyst Amit Daryanani wrote.

    Apple’s relatively strong China performance isn’t an anomaly or tied to any Asian enthusiasm for a quintessentially American brand. China’s retail sales gains all last year were nearly five times the rate in the United States, where consumer spending has also been growing faster than the economy as a whole. According to Moody’s Analytics, China’s retail sales were up by double digits in every month of 2015.

    According to Lee of IHS Global Insight, China’s consumers have increased their spending at a fairly predictable pace in recent years, behaving much the same way when the investment side of the economy is growing faster than 10 percent as they are now, with overall growth reported at just under 7 percent in official statistics. Investors have openly questioned whether the official statistics exaggerate the health of China’s economy.

    The price of an iPhone is still stiff for Chinese consumers who make an average income of about $10,000 per three-person household, Lee said. But the average income of the top 20 percent of the population is about $23,000, making them the primary target of Apple’s continued push into China. And consumers in China still have enough savings to keep consuming — though that could change if markets there keep gyrating, he said.

    “It depends on the severity and the type of the slowdown,” Lee said. A slow, steady decline in growth wouldn’t be likely to spook consumers, but “if there’s a banking crisis that crushes the economy, all bets are off.”

    Not all bets. Long-term prospects are bullish enough that Apple isn’t planning to pull back on investing heavily in China, Cook said.

    “The middle class in China was less than 50 million people in 2010, and by 2020 it’s projected to be about half a billion,” he said.

    But in a possible sign that even Apple is hedging its bet on China, Cook’s quickly changed the topic to India — which has a younger population and lower smartphone penetration than China, and where Apple boosted sales 38 percent.

    “India is incredibly exciting,” Cook said. “It’s quickly becoming the fastest-growing BRIC country.”

  • Kingsdown Vietnam opens first store

    Kingsdown Vietnam opens first store

    American bedding producer Kingsdown has opened its first branded retail showroom in Vietnam, in Ho Chi Minh City, heralding a push into Asia.

    The company has also announced it plans to open more than 100 branded showrooms in Asia within the next 12 months.

    Based in Mebane, North Carolina, Kingsdown claims to be the largest independent, employee-owned mattress manufacturer in the US. The Kingsdown Vietnam showroom carries bedding and furniture products made by long-time licensee Far East Foam.

    “We have enjoyed a fantastic reception in Asia over the past few years with its growing middle and upper classes,” says Kingsdown president/CEO Frank Hood.

    “As wealth spreads throughout the region, it made sense to expand our presence with our good partner Far East Foam. American products are held in high regard in this region.”

    Kingsdown entered the Chinese market with its My Side and BedMatch brands in 2012, and following “significant” growth is set to open 46 more branded retail stores across the mainland. These Kingsdown stores will sell its popular collections, as well as products specifically designed and developed for the Chinese marketplace, the company says.

  • Thailand Lingerie Sales Rise As Temperatures Fall

    Thailand Lingerie Sales Rise As Temperatures Fall

    WearYouWant, Thailand’s leading online fashion marketplace and beauty platform reports that far from adding on extra layers to guard against the sudden chilly weather, Thais could be doing the opposite – staying indoors more and wearing less!  With temperatures dropping the site has seen a sudden rise in lingerie traffic and sale in Thailand.

    It seems that instead of digging out an old sweater or cardigan, the cold weather is inspiring more cuddle-time with couples. Of course Thailand’s/Bangkok’s fashion conscious want to look great whether they are stepping out and about or snuggling up with a loved one at home…in their underwear.

    WearYouWant recorded a 70% increase in the sales of lingerie since the temperature plunged early this week.

    There are no doubt many who are hoping that the cold-blast continues for a little longer yet.  Many others are also now realizing that their undergarments need an upgrade and are logging on to WearYouWant to get their lingerie delivered straight to their door so they do not have to go out in the cold!

    WearYouWant’s CEO, Julien Chalté, finds the development amusing.

    “We cannot state whether this is related to the weather or not, but it is not difficult to imagine that the chilly temperatures may encourage certain indoor activities for which the lingerie would certainly be useful,” says the CEO with a smile.

  • Starbucks Asia performance concerns

    Starbucks Asia performance concerns

    Starbucks’ latest overall figures look impressive- but this first set of results of its new fiscal year show a marked polarisation in performance around the globe.

    In the Americas, the company’s largest market, sales and profits powered ahead. However, the same cannot be said of both Europe and China, where the results were far more subdued.

    Turning first to China and Asia Pacific, at first glance the results do not look too bad, with revenues up by a very solid 32 per cent. However, most of this increase is attributable to incremental revenues from the acquisition of Starbucks Japan early in the last fiscal year.

    A significant 885 net new store openings across the region also helped to boost top line growth.

    Despite this there are two areas for concern. The first is underlying sales growth, which at 5 per cent has come in below expectations; the concern is that some of this is related to a general slowdown in China which, if part of a longer term trend, could harm company earnings.

    The second is the margin position which has deteriorated because of higher wage costs and the change of ownership of the Japanese operation.

    Turning to the Americas: Despite having been accused of “declaring war on Christmas”,  Starbucks’ results showed much more holiday cheer than its generic red cups. Across the region revenue rose by a very respectable 11 per cent, underpinned by 9 per cent comparable growth.

    Operating income also rose by 14 per cent. Tweaks to the menu which saw the inclusion of some more expensive drinks options and an enhanced range of food helped to drive up average ticket across the period.

    The American results were particularly impressive given the warmer weather across most of the holiday period. That this did not deplete sales underscores the habitual nature of Starbucks and its importance as a small indulgence for many of its regular customers. This loyalty has, in our view, been further strengthen by strong take-up of the mobile app which encourages and stimulates regular buying.

    Within Europe and the wider EMEA region, the net addition of 79 stores did little to bolster overall revenue which declined by 6 per cent on a year-over-year basis. Admittedly much of this was related to unfavorable exchange rates but some is also attributable to weak underlying sales growth at existing shops. The impact on profits has been negative, something further exacerbated by the shift to developing more licensed stores which operate at a lower margin than company-owned outlets.

    Looking ahead, initiatives such as the evening sale of alcoholic beverages and an enhanced food menu, will help to further drive productivity in US stores.

    However, Starbucks will need to work harder to ensure that these gains are not diminished by the deteriorating environment in Asia and the lackluster performance in Europe.

  • Jetro helping convenience stores

    Jetro helping convenience stores

    Four major convenience store chains in Japan are teaming up with a government-related body to work on expanding their businesses overseas.

    FamilyMart, Lawson, Ministop and 7-Eleven Japan have formed a council with the Japan External Trade Organization (Jetro) to accelerate their establishment of branches overseas after the Trans-Pacific Partnership (TPP) goes into effect, reports the Sankei Shimbun.

    With the TPP easing restrictions on foreign distributors entering into the markets of partner countries such as Vietnam and Malaysia, the convenience stores hope to devise a system that will enable them to sell Japanese processed food products and commodities in overseas markets.

    Jetro’s task will be to work with foreign governments to resolve problems and collect relevant retail information. It will also help the convenience store chains find partner companies in Asian countries.

  • Pos Indonesia eyes eCommerce boom

    Pos Indonesia eyes eCommerce boom

    Indonesia’s national postal service, Pos Indonesia, is mulling a spin-off its logistics arm in 2019 an IPO to capitalise on the online shopping boom.

    Pos Indonesia is aiming for Rp 11 trillion ($796 million) in revenue within the next two years, according to its director of technology and financial services, Indyruwani Asikin Natanegara. One third of this would come from its logistics arm, Pos Logistik Indonesia.

    This would more than double Pos Indonesia’s estimated revenue of about Rp 4 trillion last year, and be a nearly eightfold increase (about Rp 500 billion) for Pos Logistik Indonesia.

    Established four years ago, Pos Logistik Indonesia may make its trading debut before its holding company. It is something Pos Indonesia has been discussing for three years. With a network of 4367 offices and more than 28,000 agents, Pos Indonesia has established ties with such eCommerce companies as MatahariMall and Zalora Indonesia, in providing pickup and delivery services.

    Pos Logistik Indonesia’s business solutions director Yan Hendry Jauwena says the idea is to provide logistics for eCommerce companies. It has formed a partnership with Singapore-based technology firm Anchanto, which will be offering its services for warehousing and inventory, processing orders and delivery.