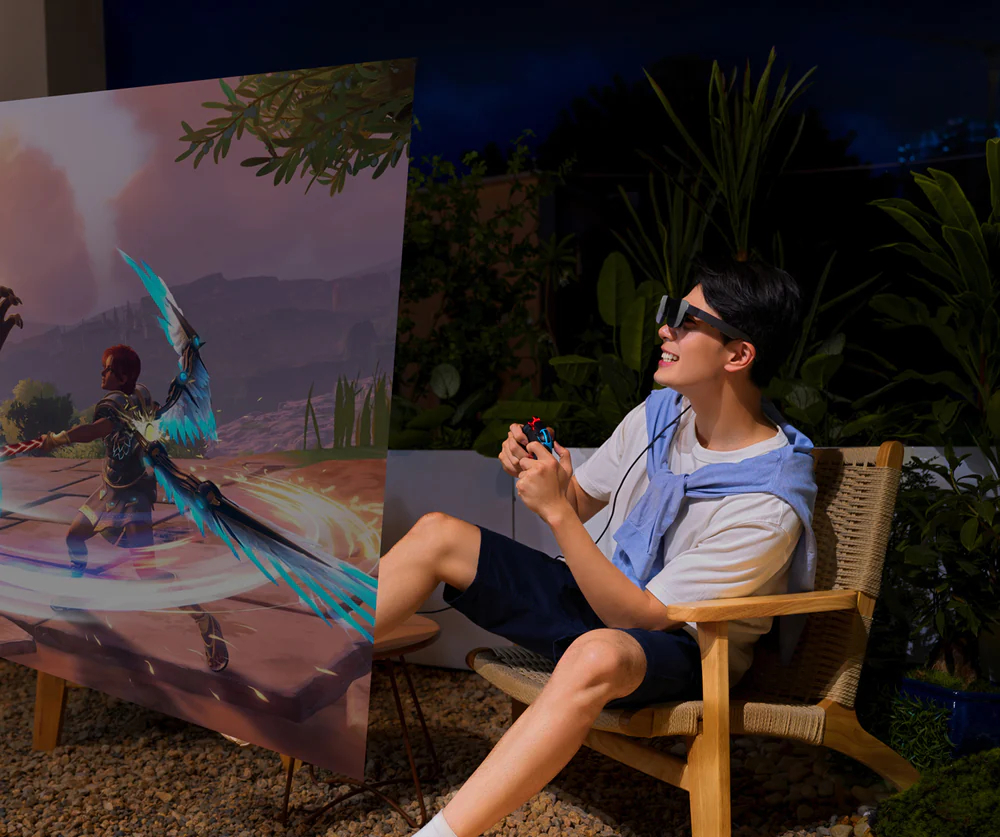
Blog

  • QIC Opens 6,842-Square-Metre Racquet Club at Robina Town Centre

    QIC Opens 6,842-Square-Metre Racquet Club at Robina Town Centre

    QIC Real Estate opened a 6,842-square-metre Racquet Club venue at Robina Town Centre on the Gold Coast in September 2026, adding 13 courts to the shopping complex.

    Built outdoors, the project features seven padel courts, six pickleball courts, athlete recovery facilities and a clubhouse food and beverage venue.

    Landlords pivot to social sports

    The project gives major retail space to racquet sports over traditional specialty stores or standard entertainment anchors. Sally Harding, head of alternative income at QIC, noted the shift in asset management: “Some of the most exciting opportunities in our portfolio come from looking at land in new ways; not just where the next store goes but how we create places that get people active and connected.”

    Retail landlords across Asia-Pacific face structural shifts in department store footprints and apparel tenancies. Turning outdoor land and rooftops into sports hubs drives footfall during weekday evenings and weekend mornings. Conventional mall traffic softens during those periods. The risk lies in operational intensity: leisure operators need steady community engagement to justify square footage that produces lower base rent per square metre than luxury or specialty retail tenancies.

    Alternative income and regional footprint

    Founded in Sydney in 2023, Racquet Club previously built permanent facilities in Sydney and Canberra alongside temporary pop-ups. The Gold Coast venue serves as the company’s third permanent Australian location and its second-largest site to date.

    Robina Town Centre celebrated its 30th anniversary in April 2026. That milestone followed a 2024 institutional marketing partnership between QIC, the Australian Sports Commission and the Australian Institute of Sport to lift on-site sports participation.

    Clubhouse launch schedule

    Court bookings at the Robina venue are active now. The adjoining clubhouse food and beverage operation opens before the end of September 2026.
  • Bidgely Shows Energy AI for 50 Million Homes at Enlit Asia 2026

    Bidgely Shows Energy AI for 50 Million Homes at Enlit Asia 2026

    Bidgely will present its energy artificial intelligence solutions alongside regional energy leaders at Enlit Asia 2026, scheduled for 22 to 24 September in BSD City, Jakarta.

    Headquartered in Los Altos, California, the company serves over 50 million homes globally and holds more than 19 foundational patents powering its UtilityAI platform.

    Bidgely and its vice president for EMEA and APAC, Nipun Jain, will demonstrate how smart meter data analytics can be deployed directly or across cloud ecosystems such as AWS, Microsoft Azure, Snowflake, and Databricks.

    Targeting Southeast Asian Power Loss

    Power distributors across Southeast Asia face heavy revenue leakage from non-technical losses, primarily unmetered taps, meter tampering, and unrecorded commercial consumption. Traditional auditing relies on manual inspections across sprawling municipal feeder lines. It is a slow, expensive field process that leaves billions in lost revenue on distribution balances. Algorithmic anomaly detection cuts those inspections down to verified problem sites. That gives state-backed utilities in Indonesia, Malaysia, and the Philippines a faster return on their smart meter outlays.

    Commercial property owners and industrial operators across the region will feel this operational shift directly. As utilities adopt granular meter-level intelligence, billing discrepancies become faster to audit and harder to contest. For enterprise consumers, appliance-level breakdown data clarifies peak-demand surcharges. Regional distributors also gain direct data to use when negotiating tariff structures and demand-response targets.

    Cloud Platforms and Grid Strains

    Growth across ASEAN follows Bidgely’s addition of regional executive teams in July 2026 and technical roadshows across North America and Europe earlier in the year. Rapid deployment of advanced metering systems across key ASEAN markets has generated vast troves of interval data. Local power authorities rarely process this information beyond standard monthly invoicing.

    At Enlit Asia, we are showing how energy leaders are extracting value from this AMI data with AI/ML based big-data analytics, which turn interval data into concrete outcomes that remove bill shock, eliminate non-technical losses and build a resilient grid for the future.

    Technical Sessions in Jakarta

    Nipun Jain, vice president for EMEA and APAC at Bidgely, leads the regional delegation. Technical sessions scheduled for 22 and 23 September focus on feeder-level forecasting, battery asset visibility, and active grid layer management for distribution networks facing new consumer demand spikes.

  • Lululemon Appoints Heidi O’Neill as CEO After Comparable Sales Drop Nine per Cent

    Lululemon Appoints Heidi O’Neill as CEO After Comparable Sales Drop Nine per Cent

    Former Nike executive Heidi O’Neill took charge of Lululemon on September 8 after second-quarter comparable sales dropped nine per cent.

    Net revenue fell four per cent year over year. In the United States, comparable store sales sank 12 per cent.

    The Vancouver-based activewear company lowered its full-year financial outlook and scaled back its physical retail pipeline. Lululemon now plans to open 35 net new stores in 2026, down from an earlier target of 40. It will also trim its operational pop-up fleet to about 40 locations, down from 65 at the end of last year.

    Slowing Demand Hits Global Expansion

    For landlords and retail operators across Asia and the Pacific, the pullback signals that premium athleisure no longer guarantees footfall. Rapid international sales growth previously cushioned softening retail demand in North America. That buffer eroded in the second quarter when international comparable sales slipped into decline.

    Fast-growing rivals such as Vuori and Alo Yoga continue to capture shelf space and customer loyalty across key metropolitan hubs. Lululemon must defend high price points without the product novelty that originally justified them. That leaves franchise partners and department store landlords facing softer conversion rates.

    Product Fatigue and Pricing Pressure

    Expansion into non-core lifestyle categories failed to resonate with shoppers looking for technical performance. High price tags compounded the problem as consumers rejected premium pricing on basic assortments.

    “The reason they are is that Lululemon has gone firmly off the boil,” said Neil Saunders, managing director at GlobalData.

    O’Neill’s operational task centres on rebuilding the product engine rather than relying on discounts. Americas revenue slipped three per cent in the first quarter, then dropped eight per cent in the second quarter. Core customer fatigue is accelerating.

    Targets for the Turnaround

    Momentum has slowed over several quarters. The brand built its original market dominance on proprietary yoga fabrics and studio ambassador networks. Aggressive international scaling then diluted its product focus and slowed its development cycles.

    Investors and retail property operators are tracking O’Neill’s initial 90-day operating review and the third-quarter earnings release. Progress against the revised 35-store opening plan will show whether core product fixes can stabilise full-price sales.

  • SingLand to Shut Marina Square for 360,000-Sqm Mixed-Use Rebuild

    SingLand to Shut Marina Square for 360,000-Sqm Mixed-Use Rebuild

    Singapore Land Group will close Marina Square on March 31 to redevelop the 40-year-old complex into a 360,000-square-metre mixed-use property.

    The project replaces the standalone shopping centre with three towers housing 204 luxury apartments, 13,000 square metres of office space, a 304-key hotel, and a four-storey retail hub by 2031.

    The Rebuild Plan for Marina Bay

    SingLand plans to build a 49-storey residential tower alongside an eight-floor office block and hospitality facilities. The revamped four-storey retail podium will pivot toward food and beverage outlets, pet-friendly public spaces, padel courts, a botanic loop, and covered pedestrian bridges linking directly to NS Square.

    Master planning is led by PLP Architecture alongside local firm DP Architects. The current building was designed in the 1980s as an inward-facing structure focused on department stores, a bowling alley, and cinemas, cutting off foot traffic from the surrounding waterfront district that grew around it over four decades.

    Why Single-Use Retail Boxes Are Disappearing

    The overhaul reflects a broader structural change across Asian retail hubs. Standalone malls in central business districts face direct pressure from decentralised suburban retail, with more than 50 town centres across Singapore now offering duplicate tenant mixes within residential estates.

    Landlords are responding by stacking residential and commercial towers directly above retail space to engineer built-in foot traffic. The same dynamic drives major mixed-use precinct investments across the region, including IconSiam and One Bangkok in Thailand, Omotesando Hills in Tokyo, and Taikoo Li in Shanghai.

    Planning Incentives and Anchor Store Decline

    Urban planners in Singapore are actively encouraging commercial landlords to retire single-use retail boxes. SingLand is tapping the Urban Redevelopment Authority’s Strategic Development Incentive Scheme, which grants higher gross plot ratios and flexible land-use rezonings for developers adding residential and hotel components to older commercial sites. Similar transformations are underway at Union Square on Havelock Road and Tanglin Shopping Centre near Orchard Road.

    When Marina Square opened in 1986, its 59,000 square metres of retail floor area made it Southeast Asia’s largest shopping complex. That legacy retail model relied on sprawling department store anchors, an arrangement that has broken down following the collapse or scaling back of operators such as Robinsons, John Little, and Metro.

    Tenants face a final trading date of March 31 before demolition crews take over the site ahead of the 2031 handover.

  • Geely Hosts CCC Digital Key Trials in Ningbo as China Penetration Hits 58%

    Geely Hosts CCC Digital Key Trials in Ningbo as China Penetration Hits 58%

    Geely Holding Group opened the Car Connectivity Consortium Plugfest in Ningbo on September 7, 2026, testing cross-device vehicle access specifications across global hardware makers.

    Digital keys reached 13.3 million passenger vehicles in China in 2025, taking factory installation rates to 58.1 per cent, according to ResearchInChina.

    The four-day event runs through September 10, bringing engineers from Apple, Volkswagen Group China, Leapmotor, and the China Academy of Information and Communications Technology together to validate CCC Digital Key Version 3 and Version 4 implementations. Testing focuses on Bluetooth Low Energy, Near Field Communications, remote keyless systems, and relay-server architectures built for Chinese mobile platforms.

    Standardizing Access Across Mobile Ecosystems

    Hardware and vehicle makers face a fragmented user base where device compatibility dictates owner satisfaction. Chinese electric vehicle makers built proprietary smartphone-to-car links early to differentiate their cabins, but scaling across export markets requires uniform global protocols. Aligning with CCC protocols reduces development friction for Chinese auto exporters targeting Europe and Southeast Asia, where multi-brand phone compatibility is mandatory.

    The technical risk sits in the handoff between mobile operating systems and vehicle transceivers. Proprietary app-based keys often suffer from background process throttling and latency on Android devices. Standardized Near Field Communication and Ultra-Wideband protocols shift authentication directly to device secure elements, eliminating reliance on third-party companion apps.

    Regional Expansion and Certification Pipeline

    Earlier in 2026, the consortium certified its first batch of Chinese vehicles across Geely brands including Volvo, Polestar, Zeekr, Lynk & Co, Smart, and Lotus, alongside standalone approvals for Nio and Xpeng. Regional momentum extended into India with Mahindra & Mahindra and South Korea through Hyundai Motor Company.

    Testing in Ningbo directly addresses local technical conditions, including cross-platform key sharing via relay servers. Test equipment suppliers including Comprion, Dekra, and Ellisys are running validation benches for Bluetooth sniffing and updated NFC test suites alongside software provider GosuncnWelink.

    “As digital key adoption grows, a common global standard is essential to ensuring interoperability across vehicles and devices,” said Alysia Johnson, President of the Car Connectivity Consortium.

    Testing China-Specific Architecture

    Participating laboratories are using authorized IDL hardware and Comprion validation software to check device compatibility against published automotive test cases before production rollouts. These trials will establish the technical criteria for the next round of device-to-car certifications across Asian component supply chains.

    Engineering teams conclude the Ningbo trials on September 10, 2026, with the validated test cases feeding into updated consortium validation tools as China’s passenger car digital key penetration passes 60 per cent before year-end.

  • NIQ and Similarweb Partner to Launch AI Commerce Measurement in Q4 2026

    NIQ and Similarweb Partner to Launch AI Commerce Measurement in Q4 2026

    NIQ and Similarweb are collaborating on an Agentic Commerce Measurement solution to help brands, retailers and technology platforms track purchases made through artificial intelligence, with an initial version scheduled for Q4 2026.

    The collaboration combines NIQ’s product intelligence, consumer behavior data and retail sales measurement with Similarweb’s digital signals across generative AI platforms. Together, the two New York Stock Exchange-listed companies will connect AI discovery to measured sales outcomes.

    Five tracking pillars

    The planned solution will initially focus on 5 areas across the buying journey: consumer intent, agentic shelf visibility, product content readiness, AI-driven traffic and AI-driven conversion into verified omnichannel purchases.

    Initial monitoring will cover major generative tools including ChatGPT, Gemini, Google AI Mode, Perplexity and Claude. These analytics feed directly into NIQ’s Commerce Intelligence ecosystem, which links brand product catalogs with enterprise retail operations.

    AI is becoming a new commerce channel, and NIQ intends to make it measurable. Our clients want to know where AI is already influencing their business, how quickly that influence is growing and what they should do about it.

    The shift to agentic checkouts

    Protocols such as Google’s Universal Commerce Protocol and OpenAI’s Agentic Commerce Protocol prompted the project. Both frameworks allow autonomous software agents to research, evaluate and purchase merchandise inside a single chat window without redirecting the shopper to a traditional storefront.

    For consumer brands and multi-brand merchants, automated shopping removes the classic digital shelf where banner placements and search bidding drove conversion. Brands drop out of the basket entirely if an AI agent filters options down to two choices based on structured technical metadata they lack.

    Catalog hygiene and algorithmic bias pose immediate hurdles for suppliers. A brand cannot buy sponsored placement inside an autonomous agent if the underlying Large Language Model cannot parse the product description or confirm inventory in real time.

    Platform coverage and next stages

    Integration relies on NIQ’s existing enterprise analytics tools, Optiq and ConnectAI, which feed commercial data directly into corporate workflow software. Similarweb previously built out dedicated digital footprint tools to capture referral traffic from generative artificial intelligence search portals.

    NIQ and Similarweb plan to reveal initial product categories and regional test markets ahead of the fourth-quarter rollout in 2026.

  • Foreign Tech Investors Pay up to US$15,000 for Access to Chinese Factory Floors

    Foreign Tech Investors Pay up to US$15,000 for Access to Chinese Factory Floors

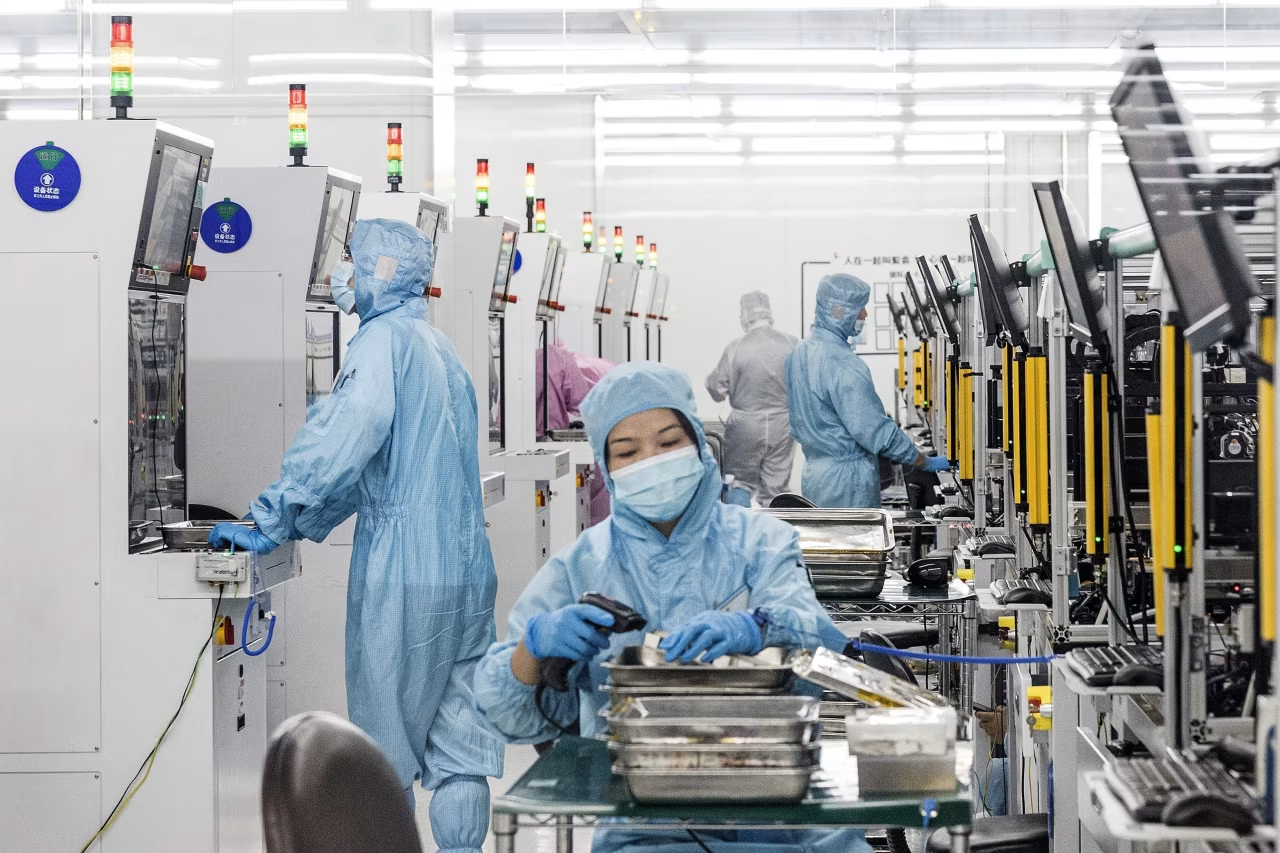
    Foreign investors and tech executives are paying up to US$15,000 each to tour Chinese manufacturing plants. The visits cover robotics, electric vehicle and artificial intelligence facilities across five industrial hubs.

    Western and regional boardrooms face pressure to see if Chinese automation has pulled ahead of global rivals. These paid delegations offer a direct look at mainland hardware supply chains.

    Programmes span Beijing, Shenzhen, Shanghai, Hangzhou and Hefei. Shanghai-based data research firm Baiguan charges up to US$15,000 for a five-day itinerary. Around half its participants come from Southeast Asia. Tech tour agency Glopen reported a 50 per cent jump in enquiries during 2026, mostly from European and Singaporean clients. It now operates more than 100 single-day corporate visits every month. Tech Buzz China founder Rui Ma has organised 11 delegations since 2019, including an April tour through three cities focusing on robotics.

    The Business Behind Factory Tourism

    State backing has turned industrial site visits into commercial business across the mainland. Beijing has designated more than 140 demonstration sites for industrial tourism. The sector generated US$17.8 billion last year and is projected to reach 300 billion yuan (US$44.6 billion) by 2029.

    Public rates for individual factory visits usually run around US$60, but premium access commands steep markups. Xiaomi’s electric vehicle assembly plant in Beijing has recorded more than 250,000 visitors since March 2024. Entry slots from Xiaomi’s official lottery system have been scalped on secondary platforms for up to 2,000 yuan (US$300), despite company rules barring transfers.

    Institutional investors have quietly joined the circuit. US firms Dimension, Capital Group and Thrive Capital have all sent representatives to inspect mainland production setups. European corporate delegations have also toured sites to study state-backed technology coordination.

    Hardware Dependence and Supply Realities

    Consumer hardware and robotics brands see that physical supply chains remain tethered to southern China. Geopolitical posturing has not changed that reality. Western developers still depend on mainland ecosystems for sensors, battery cells, structural frames and precision actuators. Replicating those supplier clusters outside the Pearl River Delta remains slow and capital intensive.

    Visitors risk mistaking demonstration speed for total commercial dominance. Non-Chinese technology firms still hold most global market share, high-margin software profits and core intellectual property. In sectors like autonomous robotaxis, Chinese domestic deployment continues to move cautiously. Regulators remain concerned about urban transport employment.

    Shenzhen Emerges as the Focal Point

    Years of infrastructure spending transformed Shenzhen from a contract assembly zone into an integrated hardware design centre. The current tour rush builds on that base. Foreign visitor arrivals in Shenzhen jumped 70 per cent last year and rose another 30 per cent in the first quarter. Total entries topped 5 million through August.

    Founders use 10-day visa-free entry policies to test prototypes directly with component suppliers. Local operators have opened communal hacker houses for visiting robotics and AI engineers. Informal network groups coordinate factory access across Shenzhen and Silicon Valley.

    Next up is the Asia-Pacific Economic Cooperation forum in November, which Shenzhen will host. Municipal officials plan to show automated assembly plants and urban drone networks to pitch the city’s hardware infrastructure to visiting regional trade delegations.

  • Petrobangla Halves Net Worth Requirement to $50 Million for Spot LNG Suppliers

    Petrobangla Halves Net Worth Requirement to $50 Million for Spot LNG Suppliers

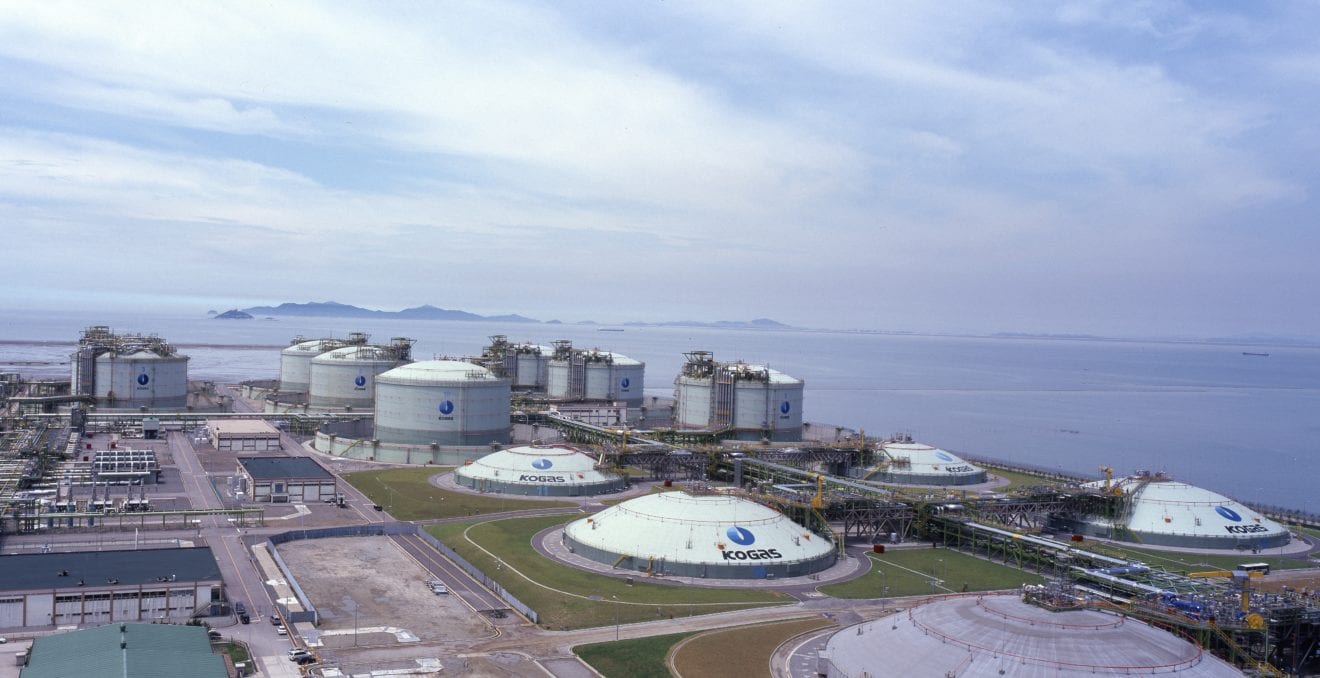
    Petrobangla has slashed its financial and experience thresholds for spot liquefied natural gas suppliers, halving the required net worth to $50 million to ease severe national fuel shortages.

    The state-run energy company now demands just one completed supply contract with no minimum cargo volume, dropping a previous rule requiring 0.5 million tonnes delivered across two separate years.

    Lower barriers for commodity traders

    Under the revised criteria issued on August 29, Petrobangla eliminated requirements for suppliers to own or charter an LNG vessel, prove experience with floating storage and regasification units, or guarantee lean gas containing at least 91 percent methane. Applicants no longer need to verify an absence of failed cargo deliveries over the past five years or limit their arbitration losses to three awards. For joint ventures, the lead partner must cover 75 percent of the $50 million financial capacity, while partners supply the remaining 25 percent.

    “We are looking for more participants in the spot market,” Petrobangla Director for operations and mines Md Shoyeb said.

    Pressure on industrial output

    For industrial manufacturers and export supply chains across South Asia, reliable gas flow dictates factory uptime and power tariffs. Bangladesh faced severe disruption in August when average gas deliveries dropped to 2,235 million cubic feet per day against official demand of 3,860 million cubic feet per day, the lowest August supply figure in a decade. Terminal outages and global supply bottlenecks forced emergency spot purchases at more than $28 per million British thermal units, up sharply from historical norms of $10 to $12 per MMBtu.

    Lowering entry barriers allows smaller trading houses without dedicated fleets to bid against established multinational commodity merchants. The tradeoff sits squarely in operational risk: by waiving past delivery guarantees and vessel charter proofs, Petrobangla accepts higher exposure to cargo defaults and scheduling failures when spot vessel availability tightens.

    Procurement shift since 2024

    The revised criteria follow a governance overhaul that suspended the Quick Enhancement of Electricity and Energy Supply Act, which previously allowed direct, non-tender contracts. The interim administration shifted spot purchases under the Public Procurement Rules 2025, expanding the active spot tender roster to 30 companies from an earlier pool where purchases were concentrated among five suppliers.

    Applications for the new supplier pool close on September 15.

  • Siam Center Adds Three New Concepts in Three Weeks to Anchor Local Brands

    Siam Center Adds Three New Concepts in Three Weeks to Anchor Local Brands

    Siam Piwat opened three concept stores across fashion, beauty and wellness at Bangkok’s Siam Center over three weeks. The openings add local labels alongside Italian apparel brand Subdued.

    Among them is domestic apparel maker Maison Keeps, which opened its largest flagship to date on the first floor on September 4.

    The brand started in 2017 as an officewear line called Keeps. During pandemic lockdowns, it shifted into durable everyday basics for young adults and children. Earlier, on August 17, nail artist Grace Kantima Banjobdee opened Kantima House on the first floor. Her salon is styled like a living room and takes bookings through Line and Instagram. Local fragrance house 3rd Sense opened its first physical counter near the first-floor escalator on August 26. The brand sells scents themed around four energy paths, featuring artwork by Thai painter Juart Woraset.

    Local flagships and first-floor concepts

    These domestic labels join Italian Gen Z fashion retailer Subdued, which entered Thailand on Siam Center’s ground floor in July. Securing space requires tenants to follow Siam Piwat’s exclusivity mandate. The mall operator requires multi-branch brands to reserve a fixed share of their inventory exclusively for Siam Center. This keeps tenants from simply replicating standard mall assortments.

    That policy turns the venue into an incubator rather than a volume driver. By demanding bespoke stock allocations and custom store designs, the landlord trades standard chain rollouts for distinct merchandising. The goal is keeping foot traffic from migrating to larger neighbouring complexes.

    Exclusivity rules test tenant margins

    For independent labels like Maison Keeps and 3rd Sense, physical retail drives up overhead through staffing, fit-outs and custom production runs. Yet a ground- or first-floor lease in the Siam interchange district provides high footfall. It draws younger domestic shoppers and regional tourists that digital channels cannot match.

    Inventory management poses the main challenge. Carrying dedicated stock for a single branch ties up working capital. Smaller designers must maintain fast sell-through rates to justify prime-district rents against rivals in less restrictive centres.

    Competing along the Rama 1 corridor

    Siam Piwat also operates Siam Discovery and Iconsiam, and holds a stake in Siam Paragon. It has spent years positioning Siam Center against retail rivals Central Pattana and The Mall Group. Competition along Rama 1 Road and Ploenchit Road is tight as operators chase discretionary spend.

    Just over a kilometre to the east, Central Pattana’s renovated Central Chidlom department store is hosting its Time and Treasures luxury watch exhibition. The show runs from September 2 to October 11, displaying limited pieces priced up to US$15,000.

  • EU Warns Pakistan That GSP Plus Benefits Cannot Be Taken for Granted

    EU Warns Pakistan That GSP Plus Benefits Cannot Be Taken for Granted

    The European Union has warned Pakistan that trade preferences under the Generalised Scheme of Preferences Plus cannot be taken for granted as the current framework expires at the end of this year.

    EU Ambassador Raimundas Karoblis told Dawn that Islamabad must address compliance issues under 27 international conventions before reapplying for the successor regime ahead of the Dec 31, 2028 transition deadline.

    Tariff Exposure for Apparel Suppliers

    European buyers take roughly 28 per cent of Pakistan’s total exports. Nearly 90 per cent of those shipments qualify for duty relief under the Generalised Scheme of Preferences Plus framework, known as GSP Plus.

    Textile and apparel factories generate between 70 per cent and 76 per cent of sales to the European market. Leather goods, processed foods, and beverages also rely on zero-tariff access. Without it, local producers struggle against rivals in South and Southeast Asia.

    Pakistan has held GSP Plus status since 2014. The current regulation expires at the end of this year, but existing beneficiaries receive a transition window running until December 31, 2028. European officials stress that the transition does not guarantee automatic inclusion in the next cycle.

    The situation is not certain. And, of course, GSP+ preferences cannot be taken for granted.

    New Benchmarks and Regional Competition

    For European fashion brands and sourcing heads, losing preferential tariffs on Pakistani cotton and knitwear would shift costs overnight. Standard tariffs would add immediate import duties on garments. That would wipe out margins against competitors in Bangladesh, India, and Vietnam.

    Brussels has stripped trade perks before. Sri Lanka lost its GSP Plus standing in 2010 over human rights issues, forcing clothing exporters there to renegotiate pricing across European retail accounts. Pakistan faces partial or full suspension during the transition window if regulators find compliance failures.

    Stricter Conditions for Islamabad

    A European Commission review covering the 2023 to 2025 period cited compliance problems in Pakistan, noting regression on forced labour, judicial independence, and civil rights. Outgoing Foreign Office spokesperson Tahir Andrabi stated that the report understates the country’s reform progress across international treaties.

    The successor framework expands qualifying criteria from 27 international conventions to 32. Islamabad has ratified the five additional treaties. Still, European monitors require a detailed action plan with verified metrics before granting approval under the new system.

    Formal European Commission monitoring reviews will run ahead of the December 31, 2028 transition deadline. Those findings will determine whether Pakistani garment manufacturers retain zero-tariff access to European ports.

  • Jonathan Waecker Completes First Year as Michael Hill CEO

    Jonathan Waecker Completes First Year as Michael Hill CEO

    Jonathan Waecker marked his first 12 months as chief executive of jeweller Michael Hill on August 27. His arrival followed an international search and a sombre period for the retailer.

    Former chief executive Daniel Bracken died unexpectedly in February 2025, followed by founder Sir Michael Hill in July.

    Leadership Transition at the Jeweller

    Waecker took charge of the retail network just weeks after Sir Michael died. The double loss forced the company to manage executive succession and institutional continuity at the same time.

    Directors turned to Waecker to execute long-term strategy while protecting brand equity across the store fleet. Maintaining operational discipline during senior turnover remains the board’s primary focus.

    “I’ve approached it with enormous respect for what Sir Michael and Lady Christine built,” Waecker said. “There’s so much magic in this brand and its history.”

    Succession After Twin Losses

    Retail chains facing sudden leadership gaps often risk strategic drift. Michael Hill countered that threat by moving rapidly through a global search to fill the vacancy left by Bracken.

    Executive stability gives regional landlords and investors clear assurance on leasing commitments and store funding. Sector rivals continue to fight for discretionary spend, leaving management little room for operational disruption.

    Stewardship Across Core Markets

    Before Waecker took charge in August 2025, the group relied on Bracken to direct brand elevation and store network refinements. Losing both the operational chief and the founder within five months tested governance across the business.

    Attention now turns to annual trading performance and network expansion targets across the brand’s core markets.

  • Singapore Retail Sales Growth Slows to 1.5% in July as Luxury Holds Firm

    Singapore Retail Sales Growth Slows to 1.5% in July as Luxury Holds Firm

    Singapore retail sales excluding motor vehicles rose 1.5 per cent year-on-year in July to SG$3.7 billion (US$2.9 billion), slowing from a 4.1 per cent gain in June.

    Official Department of Statistics data released on Monday showed shoppers pared back daily supermarket and fuel spending while sustaining double-digit increases on high-end discretionary items. Online transactions generated 18.3 per cent of total retail turnover during the month.

    Discretionary Spend Defies Inflation

    Recreational goods rose 13.9 per cent year-on-year, propelled by sports equipment purchases. Turnover for watches and jewellery climbed 11.1 per cent over the same period, giving both categories three consecutive months of double-digit expansion.

    Everyday retail categories faced a sharper contraction. Fuel receipts dropped 1.1 per cent in July after an 8.0 per cent expansion in June, reflecting a mid-year drop in pump prices before crude costs picked up again heading into late third-quarter trading. Supermarkets, convenience stores, mini-marts, and food and alcohol retailers all posted annual revenue declines.

    Right now, this is a market where retailers serving the masses are struggling, while those attracting the wealthy thrive.

    Josh Gilbert, lead analyst for Apac at Etoro, noted that households have adjusted their budgets around elevated living expenses by cutting routine spending to protect big-ticket purchases.

    Department Stores Squeezed

    Department stores suffered their sixth contraction in seven months. The persistent slide exposes structural problems for general merchandise retailers competing against specialized mono-brand stores on one side and cross-border e-commerce platforms on the other.

    Landlords across central shopping corridors face an increasingly split tenant base. Prime retail space dedicated to athleisure, fitness gear, and hard luxury continues to deliver higher sales densities, while suburban grocery anchors and legacy multi-brand floors yield lower turnover rents.

    Distortions and the Next Baseline

    Part of the drag on staple retail reflects a high comparative base from July 2025, when households spent state-issued SG60 vouchers across neighborhood stores and supermarkets.

    August retail numbers will reveal whether renewed oil price volatility and the complete runoff of previous fiscal stimulus further weaken food receipts, ahead of fourth-quarter lease renegotiations across major shopping mall portfolios.

  • Tetra Pak Names Michael Wu Managing Director for Oceania Operations

    Tetra Pak Names Michael Wu Managing Director for Oceania Operations

    Tetra Pak appointed Michael Wu as managing director of its Oceania business, taking charge of operations across Australia and New Zealand effective September 1.

    Wu brings 18 years of executive experience across the Swiss-Swedish packaging giant, stepping into the role after serving as market operations quality and sustainability director.

    Leadership Track Across Southeast Asian Markets

    Before his latest global role, Wu led Tetra Pak businesses across Malaysia, Singapore, the Philippines and Indonesia. His appointment shifts an executive with deep Southeast Asian operating experience into the mature Oceania dairy, beverage and liquid food packaging market.

    Food manufacturers across Australia and New Zealand face tight regulatory mandates on packaging circularity and emissions reductions. Placing a former quality and sustainability lead in charge of Oceania reflects packaging producers aligning commercial leadership directly with compliance demands from major supermarket chains and brand owners.

    Shifting Packaging Demands in Oceania

    For beverage processors and dairy co-operatives in the region, processing and packaging machinery upgrades require heavy capital expenditure. Wu inherits client relationships across Australia and New Zealand where processors are balancing automation investments against shifting retail carton consumption.

    Competition from alternative barrier packaging and local carton converters adds pressure on supply agreements. Tetra Pak has relied on integrated equipment and service contracts across Australasia to protect its volume footprint against cheaper imported carton blanks and plastic formats.

    Regional Supply Chain Realities

    Wu oversaw rapid packaging volume growth across Southeast Asian beverage markets before his transition into global sustainability and operations quality management. That background gives him direct insight into regional raw material flows and converting plant efficiency.

    His immediate focus turns to commercial execution across key Oceania accounts as dairy and beverage brand owners finalise processing equipment budgets for the coming operating cycle.

  • TCL Affiliate RayNeo Launches GT and iO Smart Glasses Across 40 Markets

    TCL Affiliate RayNeo Launches GT and iO Smart Glasses Across 40 Markets

    RayNeo launched its GT Series and iO smart glasses across 40 retail markets on September 4, 2026. Pricing ranges from US$329 to US$549.

    The Chinese hardware maker held a 23.7 per cent global market share in the first quarter of 2026. That made it the world’s largest consumer augmented reality vendor.

    Hardware Pricing and Regional Distribution

    Sales started immediately through Amazon and the company’s direct web store. Distribution spans 40 countries and territories, including Singapore, Malaysia, Thailand, Vietnam, Japan, Australia, New Zealand, Saudi Arabia, the United Arab Emirates, the United States, Canada, Mexico, the United Kingdom and the European Union.

    Products fall into two distinct hardware tiers. The 33-gram RayNeo iO operates as a heads-up display for navigation, teleprompting, live translation and voice recording summaries. It costs US$499 with a standard case, or US$549 with a charging case bundle. For entertainment, the RayNeo GT retails at US$329, and the GT Max costs US$429. Both GT models feature audio co-tuned with Danish specialist Bang & Olufsen. They also support Dolby Vision playback when paired with the companion RayNeo Pocket TV Pro accessory.

    Competitive Shift in Consumer Wearables

    For electronics retailers and distributors in Southeast Asia, the rollout signals a shift from crowdfunding campaigns to volume consumer retail. At an entry price of US$329, the TCL-backed company takes direct aim at portable monitors and external displays rather than bulky mixed-reality headsets.

    Hardware margins in this segment stay tight. That puts pressure on companion accessories, such as the Pocket TV Pro and optical prescription inserts, to generate operating profit. Ecosystem lock-in presents the main commercial risk. Smart glasses still rely heavily on external host processing and content partnerships to attract buyers beyond early adopters.

    From Domestic Lead to Global Retail Footprint

    RayNeo built up to the Berlin release with several hardware announcements earlier in 2026. It debuted eSIM-enabled glasses at CES in January and introduced the Air 4 Pro at Mobile World Congress in March. Tracking databases from IDC, RUNTO, CINNO Research and AVC all ranked the company first for shipments in China.

    Demonstrations and executive interviews run through September 8 at Hall 21A at IFA 2026 in Berlin. Buyers can access introductory promotional discounts of US$30 during this opening sales window.

  • Australian Grocery Baskets Rise 8.5% as Shoppers Trade Down

    Australian Grocery Baskets Rise 8.5% as Shoppers Trade Down

    Australian households face an 8.5 per cent jump in standard grocery costs, pushing four-person families to spend an average of $245 weekly at supermarket checkouts. That identical basket of goods climbed to $232 in July 2026 from $214 in March 2025, according to tracking data from consumer research firm Canstar.

    Overall household grocery spending rose two per cent year on year from an average of $240 per week, held down only because shoppers are actively ditching premium items and buying cheaper alternatives. Research from ANZ Institutional shows consumers are managing higher food costs by swapping beef for chicken, picking private-label staples like pasta and canned tomatoes, and structuring purchases around promotional cycles.

    Trading down to private labels

    Price scrutiny has altered basket composition across major supermarket chains. Canstar survey data indicates 40 per cent of shoppers cut back on discretionary treats and snacks, while 38 per cent spend extra time evaluating unit pricing on shelves. Another 30 per cent target marked-down stock, and 25 per cent now buy supermarket home brands instead of proprietary labels.

    The shift demonstrates how consumer adaptation blunts headline shelf inflation. Families who alter their purchasing baskets shield their weekly budgets, while those maintaining rigid preferences for items like fresh beef, dairy and convenience foods absorb the full weight of cumulative price gains.

    “Food inflation doesn’t just change prices; it changes habits,” said Matthew Mann, director of research and analysis at ANZ Institutional.

    Margin squeeze for national brands

    For packaged goods manufacturers and tier-one food brands, this behavioral pivot threatens market share in key dry-grocery and dairy categories. Major supermarket operators in Australia continue to expand their private-label ranges, securing margin while offering entry-level price points that squeeze branded suppliers off shelf space.

    Suppliers unable to fund trade promotions or justify premium pricing risk permanent volume losses as private-label loyalty solidifies. The margin pressure sits heavily on domestic food processors, who must navigate higher logistical and ingredient costs without full pricing power at the retail negotiating table.

    Tracking the checkout shift

    Cost pressures built steadily through 2025 before escalating into mid-2026, compounded by wider supply chain friction and energy costs. University of Sydney retail researcher Lisa Asher noted that real wage growth has failed to keep pace with cumulative food cost increases over that window.

    The key metric for Australian retail suppliers through the final quarter of 2026 is volume recovery in branded meat and snack categories as promotional discounting deepens.