Blog

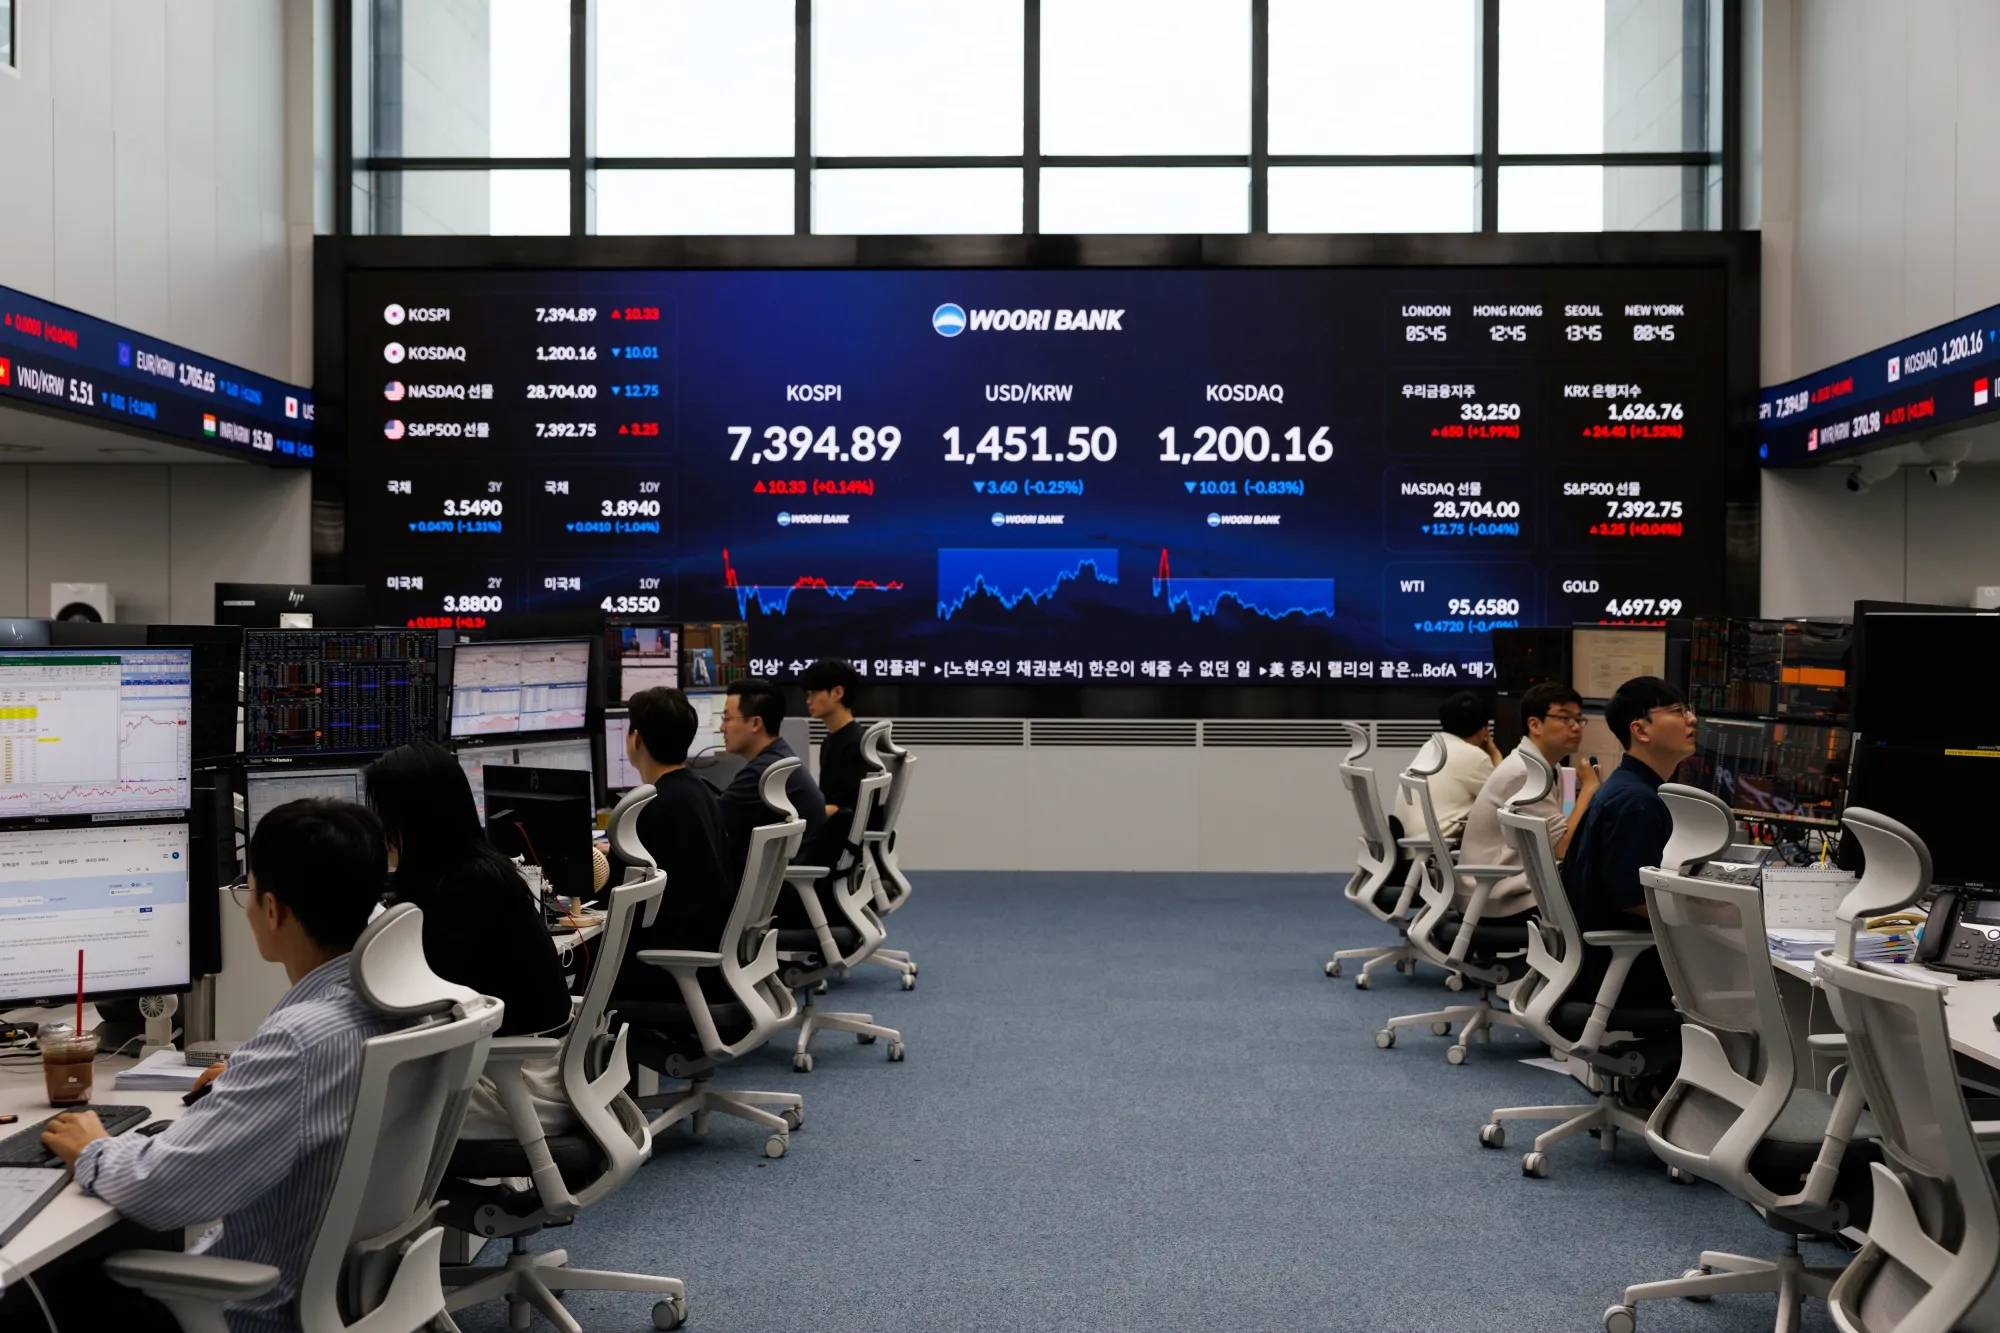
  • Tokyo Stock Exchange Delistings Set for Record High in 2026

    Tokyo Stock Exchange Delistings Set for Record High in 2026

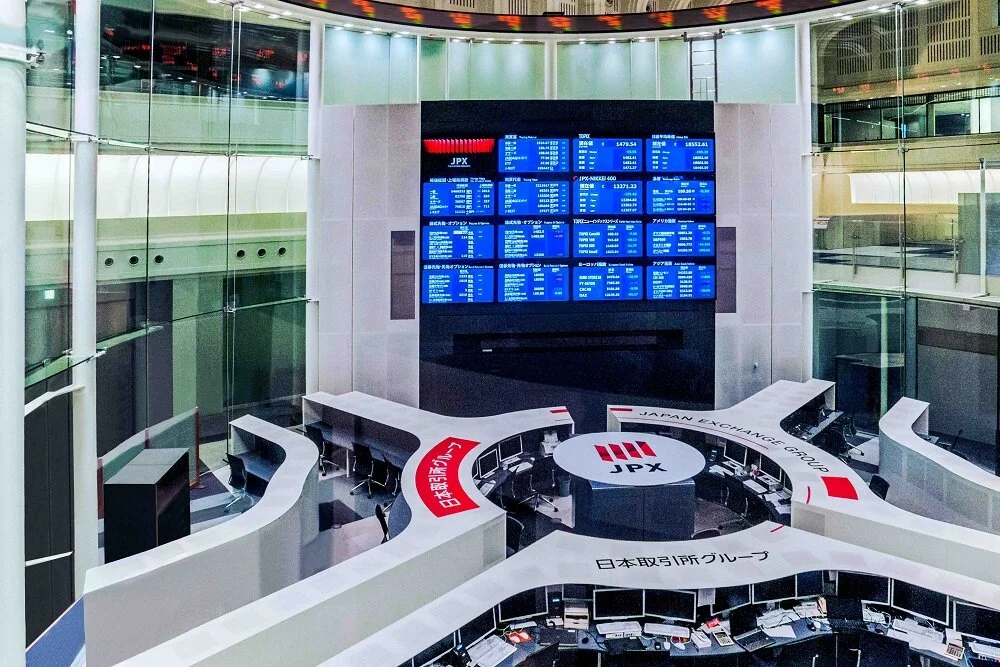
    A record number of companies will delist from the Tokyo Stock Exchange in 2026, marking the third consecutive year of peak departures from Japan’s main equity market.

    Departures stem from corporate buyouts alongside investment funds seeking to take firms private, combined with companies failing to satisfy stricter listing criteria across exchange segments.

    Tougher Criteria Squeeze Growth Names

    Stricter compliance thresholds have forced underperforming issuers to evaluate their public status. On the Tokyo Growth market, a majority of listed equities sit below required market capitalisation cutoffs as regulatory deadlines approach. Companies unable to reverse their valuations or generate sufficient trading liquidity face mandatory removal.

    At the same time, maintaining a listing carries heavier burdens. Rising domestic interest rates have increased the cost of capital for corporate borrowers, while Japan now ranks second globally in shareholder activism campaigns. Management teams face direct pressure from institutional investors to improve capital efficiency, leading smaller operators to conclude that public market scrutiny outweighs the benefits of an equity quote.

    Private Capital and Shifting Exits

    Private equity sponsors have moved quickly to absorb listed targets. Founders and management teams are teaming up with domestic and global buyout funds to execute management buyouts, taking operating businesses private to restructure away from quarterly earnings demands.

    For consumer, retail, and technology operators across Asia, this turnover alters how expansion capital is secured. Public equity is no longer an automatic default for mid-tier Japanese businesses. Instead, unlisted status gives boards latitude to cut unprofitable units, absorb logistics cost increases, and realign supply chains without continuous market valuation hits.

    New Channels for Unlisted Shares

    Japanese regulators have adjusted market infrastructure to accommodate this shift away from traditional public listings. Authorities greenlit a dedicated trading platform for unlisted shares, providing secondary liquidity for private companies and venture-backed entities that choose to bypass or exit the main exchange.

    The current delisting volume builds on two prior years of record departures following the Tokyo Stock Exchange’s comprehensive market restructuring in 2022. That overhaul replaced legacy trading sections with Prime, Standard, and Growth boards, setting concrete governance and liquidity minimums.

    Attention now turns to upcoming compliance deadlines for Growth market issuers sitting below capitalisation cutoffs, which will dictate the final delisting count before year-end.
  • Miniso Starts Global Pop-Up Tour with Lisa Featuring 70 Products

    Miniso Starts Global Pop-Up Tour with Lisa Featuring 70 Products

    Miniso opened a global pop-up tour in Bangkok on September 1 with K-pop star Lisa. The rollout introduces more than 70 co-branded products across Asia and the Americas. It follows a 22.4 per cent jump in first-half revenue as the retailer expands its international store network.

    The lineup spans apparel, bags, blind boxes and lifestyle accessories. Central to the range is the YoYo x Lisa Collection Vinyl Plush Surprise Box series. That line pairs the artist’s brand directly with Miniso’s proprietary character IP, YoYo.

    Tour Schedule and Asian Locations

    Bangkok’s IconSiam shopping complex hosted the debut before the tour heads to East Asia. The next activation opens at Omotesando Hills in Tokyo, running from September 11 to October 5.

    Three flagship pop-up locations in Beijing, Shanghai and Shenzhen will open simultaneously on September 12. Jakarta hosts the final Southeast Asian stop in October.

    Beyond Traditional Licensing

    Merchandise strategy is shifting across the business. Instead of relying purely on third-party entertainment licenses, the chain couples its proprietary IP with celebrity partnerships. The approach aims to lift average selling prices and drive foot traffic into physical stores.

    For mall operators and rivals, the push raises competition for temporary space. Pop-up formats let Miniso test local demand and build shopper volume in prime retail corridors without immediate long-term lease commitments.

    Americas Rollout Follows Revenue Gains

    Financial results reported last month showed a 22.4 per cent revenue increase for the first half. Growth was driven by performance across mainland China and international markets.

    Overseas expansion follows the Asian run, with pop-up locations opening across the United States and Mexico in November.

  • Mecca Opens 285-Square-Metre Store at Sydney International Airport

    Mecca Opens 285-Square-Metre Store at Sydney International Airport

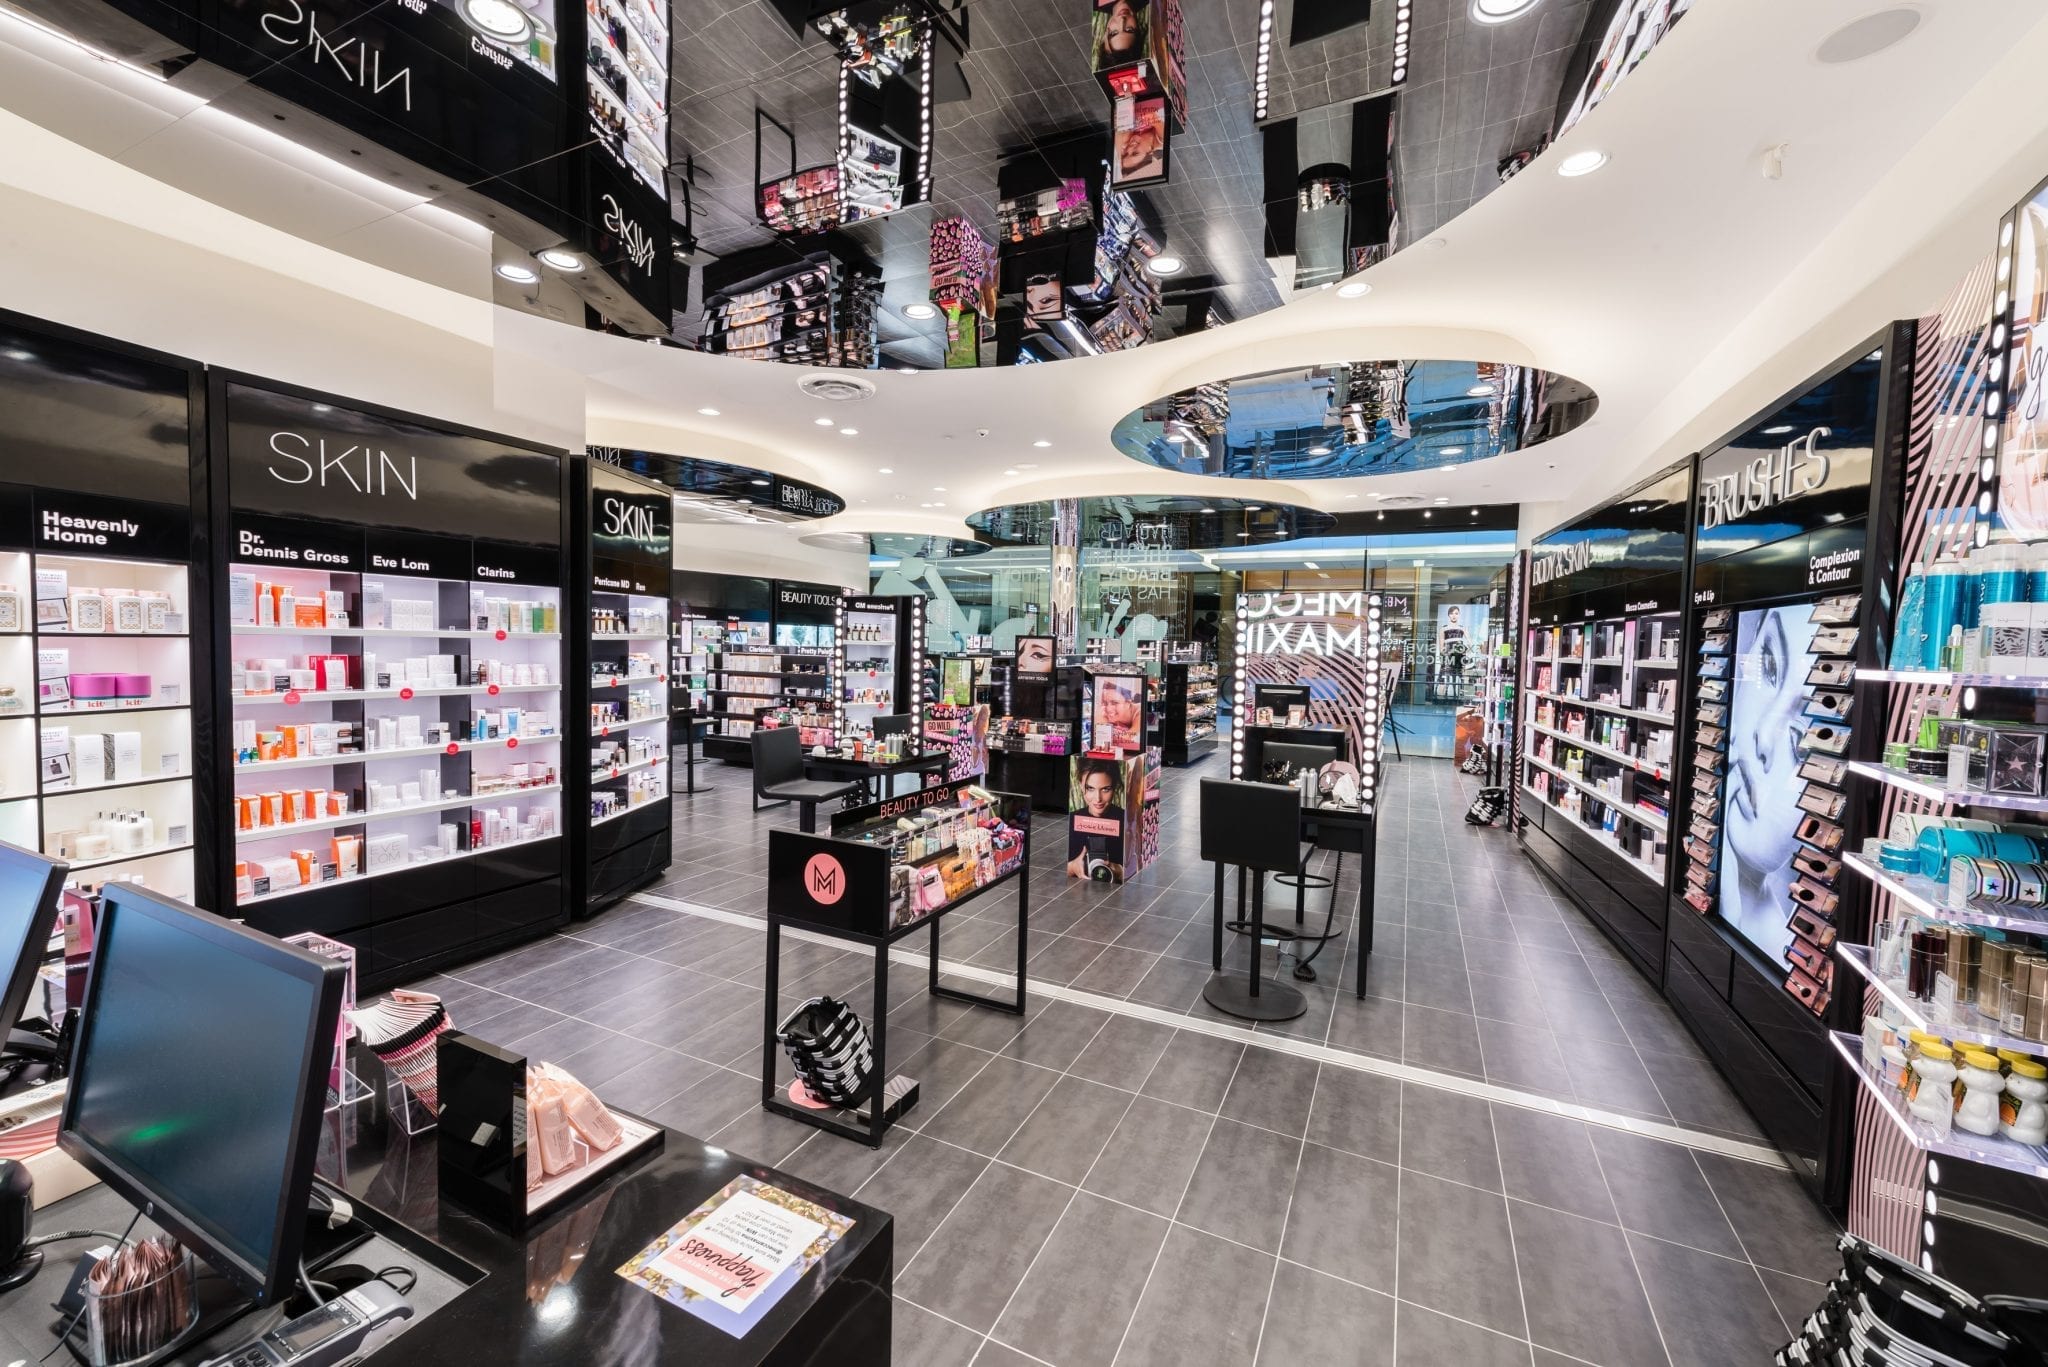
    In September 2026, Mecca opened a 285-square-metre retail space in Sydney’s T1 International terminal, marking the Australian beauty brand’s first international airport store.

    The footprint sits inside the Heinemann Tax and Duty Free concession, trading standard duty-free product walls for interactive service stations and dedicated brand zones. That footprint is roughly half the size of a standard Mecca high-street flagship, forcing the retailer to compress its inventory into high-velocity skincare, cosmetics, and travel exclusives.

    Shifting airport beauty from transaction to service

    Airport beauty retail across Asia-Pacific has historically relied on branded island counters, multi-buy discounts, and quick transactions before boarding gates call. Operators like Shilla, Lotte, and Heinemann have traditionally built duty-free concessions around volume and liquor-tobacco margins rather than high-touch advisory services.

    Mecca is testing whether hands-on consultations, application stations, and curated indie labels can extract higher basket values from outbound passengers who have cleared customs with dwell time to spare. The risk falls on staffing costs and turnaround speed: consultative beauty takes ten to twenty minutes per shopper, a cadence that clashes directly with flight departure windows.

    Heinemann’s concession strategy in Sydney

    For Heinemann, integrating a domestic specialty powerhouse allows the German travel retailer to defend sales against competing downtown duty-free stores and suburban flagship locations. Domestic travelers familiar with the Mecca brand loyalty ecosystem get an immediate reason to spend before departure rather than waiting for overseas destinations.

    Sydney Airport restructured its T1 luxury and retail precincts over recent years to capture higher average spends from returning international traffic, particularly routes across East Asia and North America. Adding specialized domestic operators inside wholesale duty-free concessions gives landlords a blueprint to raise sales per square metre without carving out independent tenancy leases.

    The travel retail rollout pipeline

    The Sydney terminal opening establishes the operating template Mecca needs before negotiating similar airside locations in Melbourne, Brisbane, or Auckland. The immediate metric to monitor is sales productivity per square metre against Heinemann’s conventional multi-brand cosmetic floorplates during peak morning departure banks.

  • Gentle Monster Parent Iicombined Appoints Renaud Divisia as Europe GM

    Gentle Monster Parent Iicombined Appoints Renaud Divisia as Europe GM

    In September 2026, Seoul-based Gentle Monster parent Iicombined appointed Renaud Divisia as general manager of Europe to lead its regional expansion.

    Divisia previously served as general manager of Puig Korea and international director of Byredo, following several years at LVMH’s Dior Parfums in leadership roles across Europe and the Middle East.

    In his new role, Divisia oversees organisation, retail expansion, and commercial strategy across Europe, where the South Korean group first launched in 2018.

    Expanding Beyond the London Beachhead

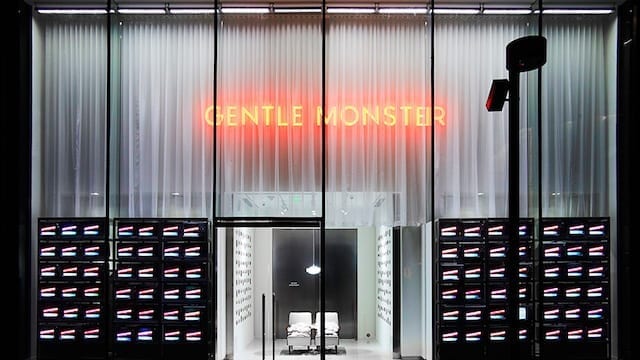
    Iicombined entered Europe in 2018 with a Gentle Monster store in London’s West End. Standalone locations in Paris and Milan followed. Those openings tested European appetite for the brand’s gallery-style retail spaces in competitive fashion capitals.

    Europe demands a different commercial model than Asia. In Asian markets, Gentle Monster built scale through experiential flagships that rotate art installations every few months. European high streets present steeper prime rents in cities like Paris and Milan. These locations require tighter retail economics and established wholesale accounts alongside mono-brand real estate.

    Bringing in a leader with roots in European luxury fragrance and cosmetics gives Iicombined a structure capable of handling multi-brand rollouts. The company cannot rely solely on the eyewear playbook that drove its early international visibility.

    Managing a Multi-Brand Portfolio

    Founded in 2011, Iicombined has expanded well beyond eyewear into a broader lifestyle business. Its wider portfolio includes fragrance and skincare brand Tamburins, bakery cafe concept Nudake, headwear label Atiissu and kitchenware brand Nuflaat.

    Tamburins gives the group a second growth vehicle with direct appeal to European department stores and specialty beauty retailers. Fragrance brands scale faster than luxury eyewear. Replenishment cycles are shorter, and distribution networks through multi-brand retail are already built.

    Operational risks remain across fragmented European real estate markets. Opening high-cost flagships in London or Paris requires major capital. Western European luxury consumers also demand sustained brand heritage rather than rapid trend turnover.

    Capital Backing and the Next Phase

    Private equity firm ZWC Partners invested in Iicombined earlier this year to finance global expansion. That capital targets growth across Asia alongside deeper penetration into Europe and North America.

    Divisia must now decide how to expand the wider portfolio. His immediate challenge is whether to introduce Tamburins and Nudake into existing flagships or secure dedicated real estate across prime retail streets in France, Italy and the United Kingdom.

  • Okada Manila and Dior Lead Philippine Customer Service Rankings

    Okada Manila and Dior Lead Philippine Customer Service Rankings

    Okada Manila topped a Philippine customer service study across 78 categories with a score of 96.87, leading a field led by luxury hospitality and global retail brands.

    Grand Hyatt Manila followed in second place at 95.57, while French fashion house Dior ranked third overall at 95.12. The benchmark, compiled by data portal Statista and the Philippine Daily Inquirer, evaluated both physical and digital operations using more than 90,000 customer reviews collected between February and April 2025.

    How the scores were calculated

    Researchers weighted the final scores equally between a respondent’s likelihood to recommend a brand and five direct performance metrics. Those five criteria, each carrying a 10 percent weighting, covered accessibility, customer focus, quality of communication, professional competence and range of services.

    Participants evaluated companies they had transacted with, visited or researched over the previous three years. The survey spanned five broad sectors: brick-and-mortar stores, online retailers, digital services, hospitality and general consumer services.

    Top performers across retail and hospitality

    Homegrown luxury furniture maker Philux placed fourth with a score of 94.88 in the home goods retail division. Shangri-La Hotels took fifth at 94.81, followed by serviced apartment operator Ascott at 94.41.

    Consumer technology and fast-moving retail also secured spots in the upper tier. LG Electronics Philippines led online home goods with 94.33, while bakery chain Red Ribbon scored 93.5 in the restaurant and leisure bracket. Japanese apparel giant Uniqlo took the final two spots in the top ten, scoring 93.38 for its physical stores and 93.30 for its Philippine e-commerce operation.

    The strong showing of physical flagships alongside digital channels mirrors a broader shift across Southeast Asian retail, where omnichannel consistency dictates customer loyalty. Premium hospitality operators and luxury apparel labels continue to command the highest marks because their operating models justify higher floor staffing and dedicated post-purchase support.

    Statista and local partners plan to track category shifts through the next evaluation cycle, where rising store automation and digital checkouts face direct consumer assessment.

  • Indian Appliance Makers Swap Copper for Aluminium to Defend Shrinking Margins

    Indian Appliance Makers Swap Copper for Aluminium to Defend Shrinking Margins

    Electronics and appliance manufacturers across India are replacing copper with aluminium and expanding domestic component sourcing after input inflation squeezed industry operating margins into single digits.

    Producers have already raised retail prices on air conditioners, refrigerators, and washing machines by 10 to 12 percent across three rounds since January, while absorbing an additional 7 to 10 percent to protect sales volumes.

    Value Engineering and Sourcing Shifts

    Surging copper prices, which rose roughly 45 percent year on year, have forced appliance brands to redesign motors, connecting pipes, and coils. Replacing copper with aluminium, steel, or alternative alloys saves between 2 and 6 percent of final manufacturing costs. Strong buying from artificial intelligence data centres and electric vehicle producers has tied up global copper output months in advance.

    Memory component prices have also doubled or tripled on heavy AI infrastructure demand, driving price hikes of 20 to 40 percent on smartphones, laptops, and televisions. Indian consumer electronics manufacturers import between 30 and 40 percent of their inputs, leaving factory gates exposed to higher freight rates and currency depreciation.

    Supply chain snarls have caused direct revenue losses. Crompton Greaves Consumer Electricals missed out on nearly Rs 200 crore in sales during the previous quarter because of material shortages. At contract manufacturer PG Electroplast, the cost to build 500,000 air conditioners climbed from Rs 700 crore last year to Rs 940 crore.

    Local Manufacturing Expansion

    Brands are countering these cost pressures by shifting away from overseas suppliers. LG Electronics India now sources a key moulding resin domestically after importing its entire requirement until March, while engineering teams adjust product designs to trim material volume per unit. Voltas and Bajaj Electricals have rolled out similar value engineering programs across their appliance lineups.

    Cost restructuring of this scale reflects a broader defensive pivot across Asian consumer hardware manufacturing. When consumer demand resists further retail price hikes, brands must either cut bill-of-materials costs or surrender volume in price-sensitive suburban and rural markets.

    PG Electroplast plans to commission domestic production of air conditioner compressors between December and January, alongside a separate manufacturing line with an annual capacity of two million units.

  • 87% Of Australians Have AI Privacy Concerns, Report Finds

    87% Of Australians Have AI Privacy Concerns, Report Finds

    Eighty-seven per cent of Australians have concerns about privacy for artificial intelligence, according to Australian Retail Council research discussed at an industry roundtable in September 2026.

    The findings, highlighted by Diebold Nixdorf, show that only 5 per cent of Australians say they trust AI companies, presenting a live commercial risk for retailers integrating automation into everyday operations.

    Senior retail leaders at the gathering noted that while the technology for age verification, customer service, and loss prevention is ready, customer trust remains the primary barrier to adoption across Australian stores.

    Designing privacy into the checkout lane

    Automated age verification and theft detection represent the front line of store deployment. In international grocery markets, automated systems now approve most age-restricted purchases at self-checkout within seconds by processing visual data locally without retaining personal files.

    Hardware suppliers argue that keeping customer records off retail servers prevents chains from becoming targets for regulatory scrutiny. Similarly, loss prevention algorithms in newer self-checkouts prompt shoppers to scan missed items before store staff intervene, reducing confrontation at the register.

    Operating standards across store networks

    Supermarket operators across the Asia-Pacific region have accelerated camera-assisted checkout rollouts over the past three years to curb inventory shrink. Australian grocers that run uncoordinated systems across point-of-sale, payments, and security cameras risk alienating shoppers if privacy safeguards vary between store departments.

    For regional retail executives, deploying store AI without clear boundaries creates legal and operational liabilities. While Asian retailers in markets such as Singapore and Japan have integrated automated kiosks with high public compliance, Australian consumers push back when surveillance feels unchecked.

    Industry proposals for shared rules

    The push toward automation follows earlier disputes between major Australian supermarket chains and privacy regulators over facial recognition testing in retail aisles. Industry participants at the roundtable raised support for a retail-specific AI code of practice to set standard data retention limits across the sector.

    Diebold Nixdorf published the findings alongside its research report on self-service systems in Australia. Retailers now weigh whether to adopt voluntary operating rules or wait for formal regulatory guidelines on customer data capture at the till.

  • Laifen Adds Curling Iron and Smart Mirror to Challenge Dyson

    Laifen Adds Curling Iron and Smart Mirror to Challenge Dyson

    Personal care device maker Laifen launched three new hardware products on September 1, expanding beyond hair dryers. Its global household footprint now tops 30 million units across 60 countries.

    The lineup includes the Swift 4 high-speed dryer, the AutoCurl curling iron, and the Glowy vanity mirror. The rollout pushes the Shenzhen-founded hardware maker directly into multi-category personal care tech.

    Motor tech and sensor additions

    Positive and negative ion emitters in the Swift 4 dryer generate 470 million ions. A dedicated nozzle infuses bottled hair treatments directly into the airflow. It sells in platinum, titanium, and burgundy finishes through the company’s direct digital storefronts.

    The AutoCurl curling iron uses a micro-servo motor that detects rotational resistance in real time to stop snagging. An automated chamber feeds hair strands in either direction. This eliminates manual switching between left and right barrels.

    Bathroom fixtures mark the next hardware expansion with the Glowy Vanity Mirror, which goes on sale September 4. The 8.5-inch unit embeds a 24 GHz radar sensor. It activates full-spectrum LED illumination when a user steps in front of the glass and saves lighting preferences to internal memory.

    Hardware playbook outside China

    Laifen built its initial commercial success across Asia by undercutting Dyson on price while matching brushless motor speeds. Extending that playbook into curling wands and smart mirrors brings new competition. The brand now faces legacy salon suppliers and beauty gadget makers with entrenched shelf space in Western department stores.

    That shift exposes the business to different replacement cycles. Hair dryers are daily essentials with high purchase frequency. Lit vanity mirrors and curlers face slower replacement rates and tighter specialty demand. Margins will depend on whether direct online buyers buy into the broader three-piece routine.

    From motor engineering to retail shelves

    Founded in 2019, Laifen established its manufacturing base on proprietary brushless motors. It holds over 600 patents. The company broadened its catalog in May 2025 with the Wave Special electric toothbrush, followed by physical distribution expansion into US warehouse chain Costco in July 2026.

    Laifen will show all three devices at its first brand media presentation in New York City on September 17. Retail distribution agreements for brick-and-mortar storefronts are scheduled for presentation at the event.

  • Hims Enters Australia with Pilot Rebrand in $1 Billion Global Push

    Hims Enters Australia with Pilot Rebrand in $1 Billion Global Push

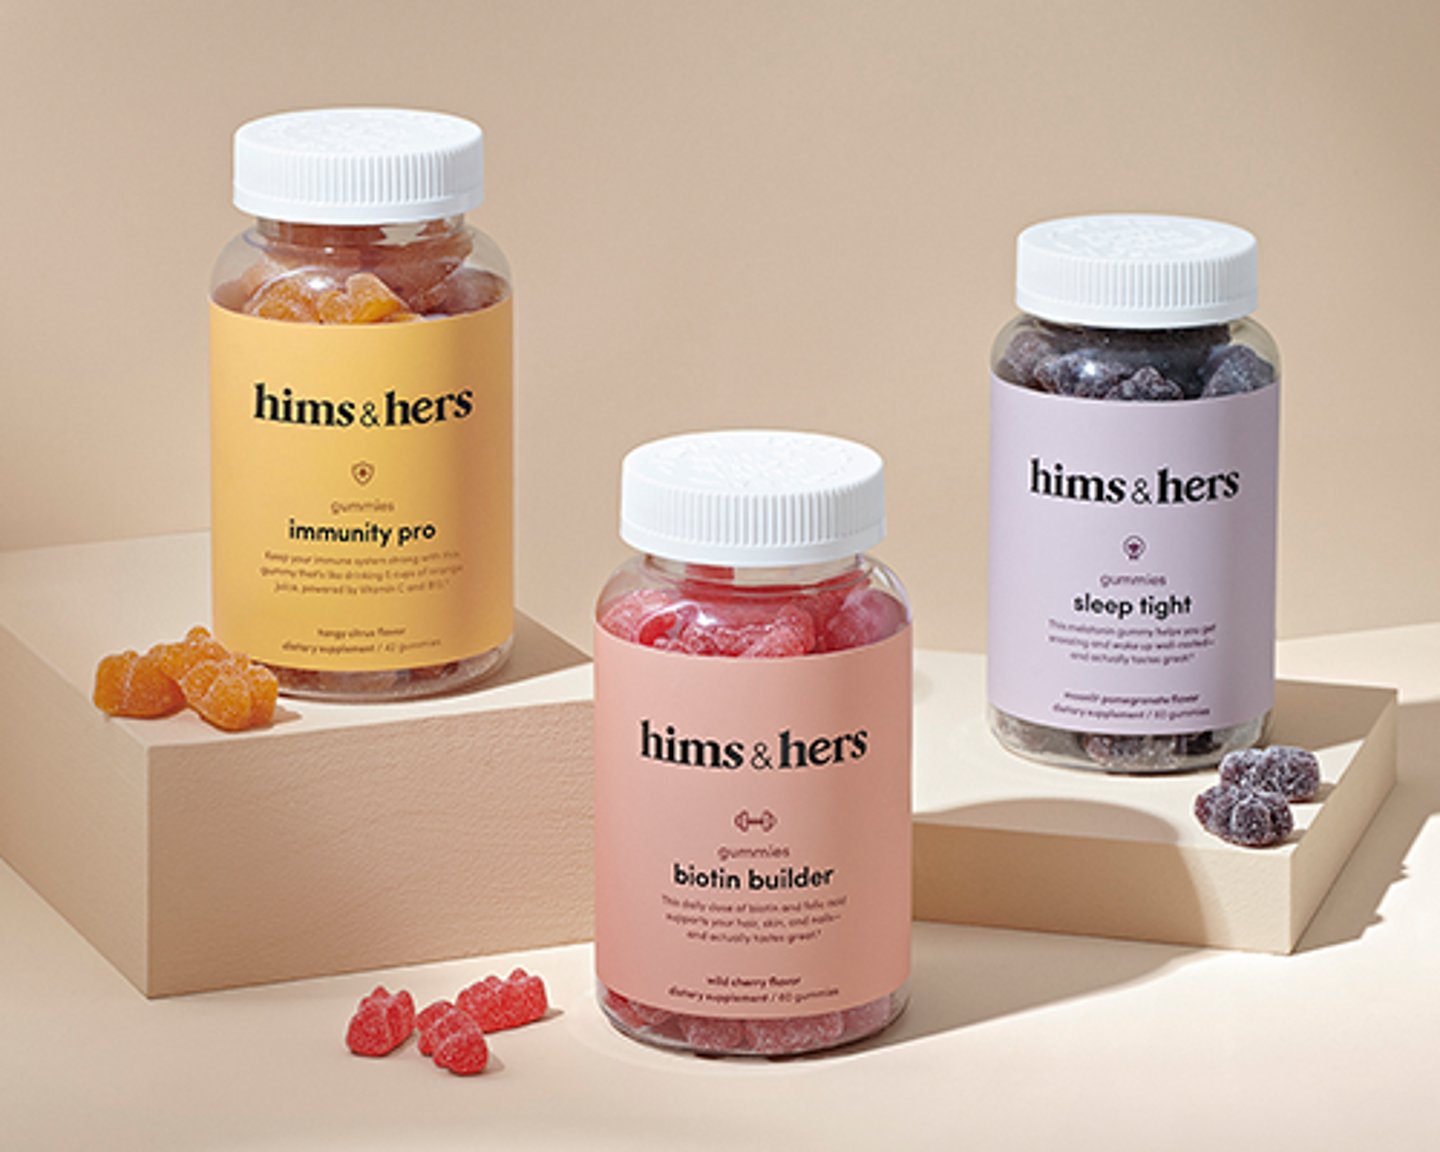
    Hims & Hers Health has launched operations in Australia by rebranding local men’s clinic Pilot, setting its sights on a 1 billion dollar international annual revenue target within three years.

    The transition gives the New York-listed group immediate access to a domestic telehealth market projected to reach 2.56 billion dollars by 2034. It also establishes the company’s first operating foothold in the Asia-Pacific region following its takeover of Sydney-based parent Eucalyptus earlier this year.

    How the Transition Operates

    Existing Pilot patients will transfer directly to the Hims platform, keeping their current treatment plans and practitioner links. Roughly 30 percent of the platform’s patient base lives in regional and rural Australia, where physical clinic access remains thin and appointment wait times run long.

    Former Eucalyptus chief executive Tim Doyle leads the international division as senior vice president, running Australian operations alongside country general manager Gus Wood. Dr Matt Vickers serves as chief medical officer for the local entity to oversee clinical governance and domestic regulatory standards.

    Pilot proved that Australian men want a different model of healthcare: one that is proactive, personal, and built around their lives.

    The Read Across for Digital Health

    Consolidating Eucalyptus under the core Hims identity shows how direct-to-consumer health brands are moving away from multi-brand regional stables toward single global flags. Maintaining separate platforms in every territory drives up customer acquisition costs and fragments marketing spend. By putting its primary brand on Australian screens, Hims can funnel global brand marketing and technology infrastructure straight into a market with high average revenue per user.

    The risk lies in consumer attachment and regulatory scrutiny. Digital health platforms in Australia face strict advertising rules around prescription treatments and compounding pharmacies, alongside tight supervision from medical boards. Pilot built significant local recognition, and erasing the name risks alienating repeat customers if the migration disrupts prescription delivery or doctor consultations.

    The Steps That Led Here

    Hims & Hers completed its buyout of Eucalyptus earlier this year, securing established patient networks in Australia and the United Kingdom. Eucalyptus had originally built discrete vertical brands including Pilot for men, Kin for fertility, and Software for dermatology, proving out direct-to-door medicine across Australasia before selling to the San Francisco operator.

    Market watchers will track whether Hims rebrands the remaining Eucalyptus product lines across women’s health and dermatology, and whether Australian patient numbers keep the company on course for its 1 billion dollar international revenue goal by 2029.

  • South Korean Retail Traders Amass Billions in US Used ETF’s

    South Korean Retail Traders Amass Billions in US Used ETF’s

    South Korean retail investors poured an estimated $10 billion into US used exchange-traded funds during the first half of the year. The buying gave them dominant stakes in several high-risk products. Korea Securities Depository filings show domestic accounts held $5.24 billion in the Direxion Daily Semiconductor Bull 3X Shares alone. That equals 27 per cent of the fund’s $19.3 billion market capitalisation.

    This concentration spreads well past semiconductor tracking. Korean buyers hold 38.8 per cent of the Direxion Daily TSLA Bull 2X Shares and 37.6 per cent of the Direxion Daily MSCI South Korea Bull 3X Shares, alongside 20.9 per cent of the ProShares Ultra QQQ. Net buying of the semiconductor fund reached $2.43 billion this year. That outstripped demand for standard index trackers by a factor of 1.5.

    Regulatory Caps at Home Drive Outflows

    Financial regulators in Seoul prompted the overseas shift by imposing minimum deposit rules and volume ceilings on domestic single-stock used products. The restrictions failed to cool risk appetite. Capital flowed straight to US exchanges, where investors access uncapped daily use across individual equities, semiconductor benchmarks, and international country indices.

    Total Korean equity holdings in the US stand at $112 billion. That is barely 0.2 per cent of total American market capitalization. In specialized used derivatives, however, concentrated buying turned Seoul day traders into the dominant liquidity provider.

    Past retail surges across East Asia followed a similar pattern. Tighter domestic margin rules in markets like Hong Kong and Tokyo pushed speculative volumes into offshore derivatives whenever local platforms restricted margin access.

    Night Trading Halts Force Blind Orders

    Heavy order flow disrupted execution infrastructure on September 1. Alternative trading system Blue Ocean ATS suspended daytime trading for 18 securities, including the top semiconductor and Korea bull funds. The platform acted under the US Securities and Exchange Commission Fair Access Rule. That rule triggers extra regulatory burdens when an alternative venue handles 5 per cent or more of a single security’s volume over four out of six months.

    Local brokerages including Samsung Securities and Toss Securities routed daylight orders to alternative platforms MOON and Bruce to keep order lines open. These backup venues do not deliver real-time quote feeds. Clients had to enter limit orders without viewing bid and ask spreads.

    Blue Ocean reviews trading volumes monthly to determine when the 18 suspended securities can return to its platform. Meanwhile, brokerage houses in Seoul are building backup order-routing networks to prepare for further liquidity limits.

  • Solum Expands Electronic Shelf Labels Across Australian Retailers

    Solum Expands Electronic Shelf Labels Across Australian Retailers

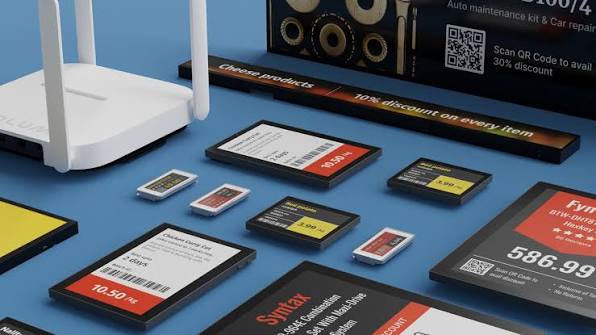
    Retail technology provider SOLUM has expanded its electronic shelf label network across Australia. The deployment covers rollouts with appliance chain Bing Lee and The Natural Grocery Company.

    Bing Lee is extending digital price tags across multiple consumer electronics stores. The chain aims to eliminate paper ticketing and curb pricing discrepancies on shop floors.

    Centralised Pricing at Scale

    The system connects in-store tags directly to a central management platform. Store managers can push real-time price updates and promotions instantly. Staff no longer need to replace physical shelf tags manually.

    Across its grocery aisles, The Natural Grocery Company has deployed the same digital setup. Freeing employees from manual repricing shifts floor labor toward customer service. It also cuts paper waste from recurring promotional cycles.

    “For The Natural Grocery Company, our ESL solution supports real-time pricing, rapid promotional updates, and greater pricing accuracy,” said Paul Kyriakos, General Manager at SOLUM Australia.

    Automation on Shop Floors

    Australian retailers face elevated labor costs and high operational overheads. Automated shelf-edge tools have become an operational priority across electronics and food retail. Supermarket operators and specialty chains across the Asia-Pacific region have accelerated similar rollouts to compete with dynamic pricing used online.

    SOLUM plans to roll out additional digital store infrastructure across retail partners in Australia and the wider Oceania region.

  • ESR Kendall Square Sells Pyeongtaek Warehouse to Samsung SRA for $253 Million

    ESR Kendall Square Sells Pyeongtaek Warehouse to Samsung SRA for $253 Million

    ESR Kendall Square sold Pyeongtaek Logistics Park to a Samsung SRA Asset Management vehicle backed by South Korea’s National Pension Service for KRW 343 billion ($252.6 million). The transaction closed on 1 September at KRW 1.8 million per square metre of gross floor area.

    The deal transfers one of South Korea’s largest modern sheds from foreign pension backing to domestic institutional ownership. ESR built the 2023-vintage facility with capital from Canada Pension Plan Investment Board and Dutch asset manager APG. Samsung SRA funded the acquisition through a KRW 400 billion core fund that drew KRW 250 billion from the National Pension Service alongside capital from Samsung-affiliated insurers.

    Hub for Port and E-Commerce

    Pyeongtaek Logistics Park spans 190,000 square metres across a 165,827-square-metre site in the Poseung district of the Gyeonggi Free Economic Zone. E-commerce platform SSG.com pre-leased the entire ambient facility in late 2021 before ground broke.

    Located three kilometres from Pyeongtaek Port, the property features direct ramp access to every floor, high ceilings, South Korea’s largest single-floor warehouse footprint, and 10 megawatts of power capacity. Logistics inventory in Pyeongtaek expanded more than 1.7-fold between 2022 and mid-2025 as third-party logistics firms and end-users absorbed space near regional automotive and electronics clusters.

    Capital Flows Shift Domestic

    Institutional buyers are moving on cash-flowing assets in South Korea as new warehouse construction drops sharply from post-pandemic peaks. Overseas capital accounted for more than 60 percent of industrial trades in 2025, but Korean managers with long-term domestic mandates are now securing completed, fully leased assets as supply eases and ambient rents start to climb.

    Greater Seoul logistics net absorption rose 42 percent to 164,000 square metres in the second quarter, while nominal rents reached $7.65 per square metre per month. Investors are tracking second-half completions, which fell to one-third of their year-earlier level, to test how quickly remaining vacancies tighten across the capital region.

  • DSG Consumer Partners Buys Singapore Wellness Brand Bback

    DSG Consumer Partners Buys Singapore Wellness Brand Bback

    DSG Consumer Partners has acquired Singapore recovery and wellness brand bback from Evo Commerce, taking control of a business distributed across more than 400 retail outlets.

    The venture capital firm completed the buyout alongside Saket Gore, the former Asia Pacific chief executive of Himalaya Wellness, who steps in as bback’s chief executive.

    Retail footprint and executive shift

    Bback started as an alcohol recovery brand before adding hydration and liver wellness formulations to its catalogue. In Singapore, the brand sells through pharmacy chains Guardian and Watsons as well as online platforms. The companies did not disclose financial terms of the transaction.

    Under the new ownership structure, bback plans to broaden its product line beyond hangover remedies into a wider range of daily recovery and functional health items. Singapore will remain the brand’s primary market in the near term.

    Consolidation in regional consumer health

    Consumer health and functional wellness labels in Southeast Asia face increasing pressure to move beyond direct-to-consumer online sales into established pharmacy chains and convenience store networks. Scaling those physical footprints requires professional operating leadership and deeper supply chain funding.

    The immediate milestone to watch is bback’s rollout of its expanded wellness formulations across its existing 400 retail points of sale in Singapore under Gore’s management.

  • Chinasquad Expands Global Cross-Border Sales with Curated Chinese Fashion

    Chinasquad Expands Global Cross-Border Sales with Curated Chinese Fashion

    Chinasquad is scaling international distribution for domestic apparel designers, offering direct deliveries across global markets with a free shipping threshold set at $99.

    The platform has accumulated more than 7,200 verified customer reviews while targeting shoppers seeking curated streetwear, statement dresses, and modern Hanfu-inspired collections.

    To address cross-border fulfillment friction, the operator provides optional DHL Express transport with delivery times between two and four days. Returns operate on a 14-day window supported by a checkout protection add-on that covers return handling and exchanges across multiple international territories.

    Sizing Standards and Cross-Border Logistics

    Cross-border apparel exporters from China routinely face high return rates tied to sizing discrepancies. Chinasquad produces its inventory to Asian sizing specifications, advising international buyers to size up on fitted garments and evaluate flat measurements across shoulders, bust, and waist. Flat garment measurements published on the site account for manual variations between one and three centimetres.

    Discounts on the storefront reach up to 90 percent on clearance lines. The merchandising mix focuses on structured trousers, outerwear, and dresses that emphasize tailored cuts rather than disposable basics.

    The Shift Toward Niche Chinese Aesthetics

    Direct-to-consumer fashion exporters in China are shifting away from pure low-cost volume to focus on distinctive regional aesthetics, including contemporary interpretations of traditional Hanfu tailoring. While mass-market players compete primarily on bottom-tier pricing, specialised curators seek higher basket sizes by pairing distinctive cuts with express air freight.

    Customer service operations and global return intake remain centred on managing cross-border garment fits as the platform tests overseas appetite for contemporary Chinese designer labels.

  • Philip Morris Tops $11 Billion in Net Revenue as Smoke-Free Sales Hit 42 Percent

    Philip Morris Tops $11 Billion in Net Revenue as Smoke-Free Sales Hit 42 Percent

    Philip Morris International generated more than $11 billion in net revenues during the second quarter of 2026. Higher international sales of heated tobacco and oral nicotine alternatives drove the total.

    Organic top-line growth reached close to 8 percent. That lifted the smoke-free category to 42 percent of total group net revenues across the first six months of the year.

    Operating income climbed 11 percent on an organic basis. In currency-neutral terms, adjusted diluted earnings per share rose 14 percent, or 15 percent in dollar terms. IQOS heated tobacco systems and VEEV vapes led non-combustible volume gains abroad. Meanwhile, the conventional cigarette unit held gross profit growth through higher pricing and steady category share. In the oral nicotine business, ZYN shipments rose 2 percent year on year to 2.9 billion pouches, helped by early distribution of the new ZYN ULTRA variant.

    Portfolio shift across retail channels

    Convenience retailers and travel hubs across Asia-Pacific and Europe now face a permanent rebalancing of shelf space. In Japan and South Korea, heated tobacco adoption outpaces traditional smoking in major cities. Tobacco fixtures there function increasingly like consumer electronics displays. Retailers with early distribution deals for IQOS consumables continue to capture higher basket values from repeat device and heatstick purchases. Traditional corner shops reliant solely on combustible cigarette cartons face shrinking margins.

    Across Southeast Asia, the transition creates immediate inventory complications for convenience store operators. Regional regulators take fragmented stances on reduced-risk products, ranging from outright bans to regulated imports. Retailers in open markets must tie up working capital in multi-brand hardware alongside conventional packs. That creates inventory turnover risks if consumer adoption lags manufacturer targets.

    Pricing power and regional performance

    Cash flow from conventional cigarettes continues to fund smoke-free production facilities and clinical testing. Higher prices in emerging markets offset volume declines in mature combustible territories, keeping category margins steady. Group CFO Emmanuel Babeau pointed to sequential gains in the United States after a slow start to the year, alongside momentum across wider international markets.

    We reported close to plus 8% organic top line growth, reaching over $11 billion in quarterly net revenues for the first time.

    Transition timeline and next targets

    Full-year 2025 performance set the foundation for the latest quarter. Smoke-free alternatives reached 109 commercial markets worldwide that year, topping 50 percent of total net revenues in 27 national territories. The company counted more than 43 million legal-age consumers using its reduced-risk lines by late 2025, broadening out from early adoption hubs in Japan and select European test cities.

    Management presents its next strategy update at the Barclays Global Consumer Conference on September 8, 2026, where commercial execution figures for the ZYN portfolio expansion will face investor scrutiny.