Tag: Banking

  • Silverlake Axis buys retail banking software firm SunGard Ambit for $12m

    Silverlake Axis buys retail banking software firm SunGard Ambit for $12m

    Singapore-listed Silverlake Axis has reached a deal to buy local firm SunGard Ambit (Singapore) Pte. Ltd. (previously known as System Access Limited) for $12 million.

    Silverlake, that provides digital economy solutions and services, told the Singapore exchange that the deal will enable it to expand its suite of software and services as well as deepen and broaden its customer relationships and geographical presence.

    On an immediate basis, the deal is expected to contribute about 15 per cent to the revenue of the enlarged Silverlake Axis Group, the company said.

    The acquisition will also enable it to add over 50 new customers to its current base of over 150 customers, extending its geographical reach to Eastern Europe, Middle East, South Asia while at the same time creating a stronger market leadership in South East Asia, it added.

    The deal will see Silverlake Axis acquire 100 percent of SAS from SunGard Asia Pacific Inc.

    “SAS brings a complementary retail banking portfolio of software and service solutions to the group’s strengths in delivering financial technology innovation to our customers. In particular, the SAS Retail Banking Product Portfolio positions Silverlake Axis for mid-tier customers while offering a broader variety of tiered deployment options from a technology and a pricing perspective. These products can be deployed on open digital platforms thereby making it possible for Silverlake Axis to address the needs of customers from mid-tier to large enterprises,” its regulatory filing said.

    Dr Raymond Kwong, Silverlake Axis chief executive and group managing director, said : “The group is constantly on the lookout for complementary software businesses to expand our suite of business enterprise software solutions. Through this acquisition, the combined and complementary multi-platform core, channels, card and payment solutions will enable us to deepen our customer solution implementation and support capabilities.”


  • Floating bank brings services to remote islands

    Floating bank brings services to remote islands

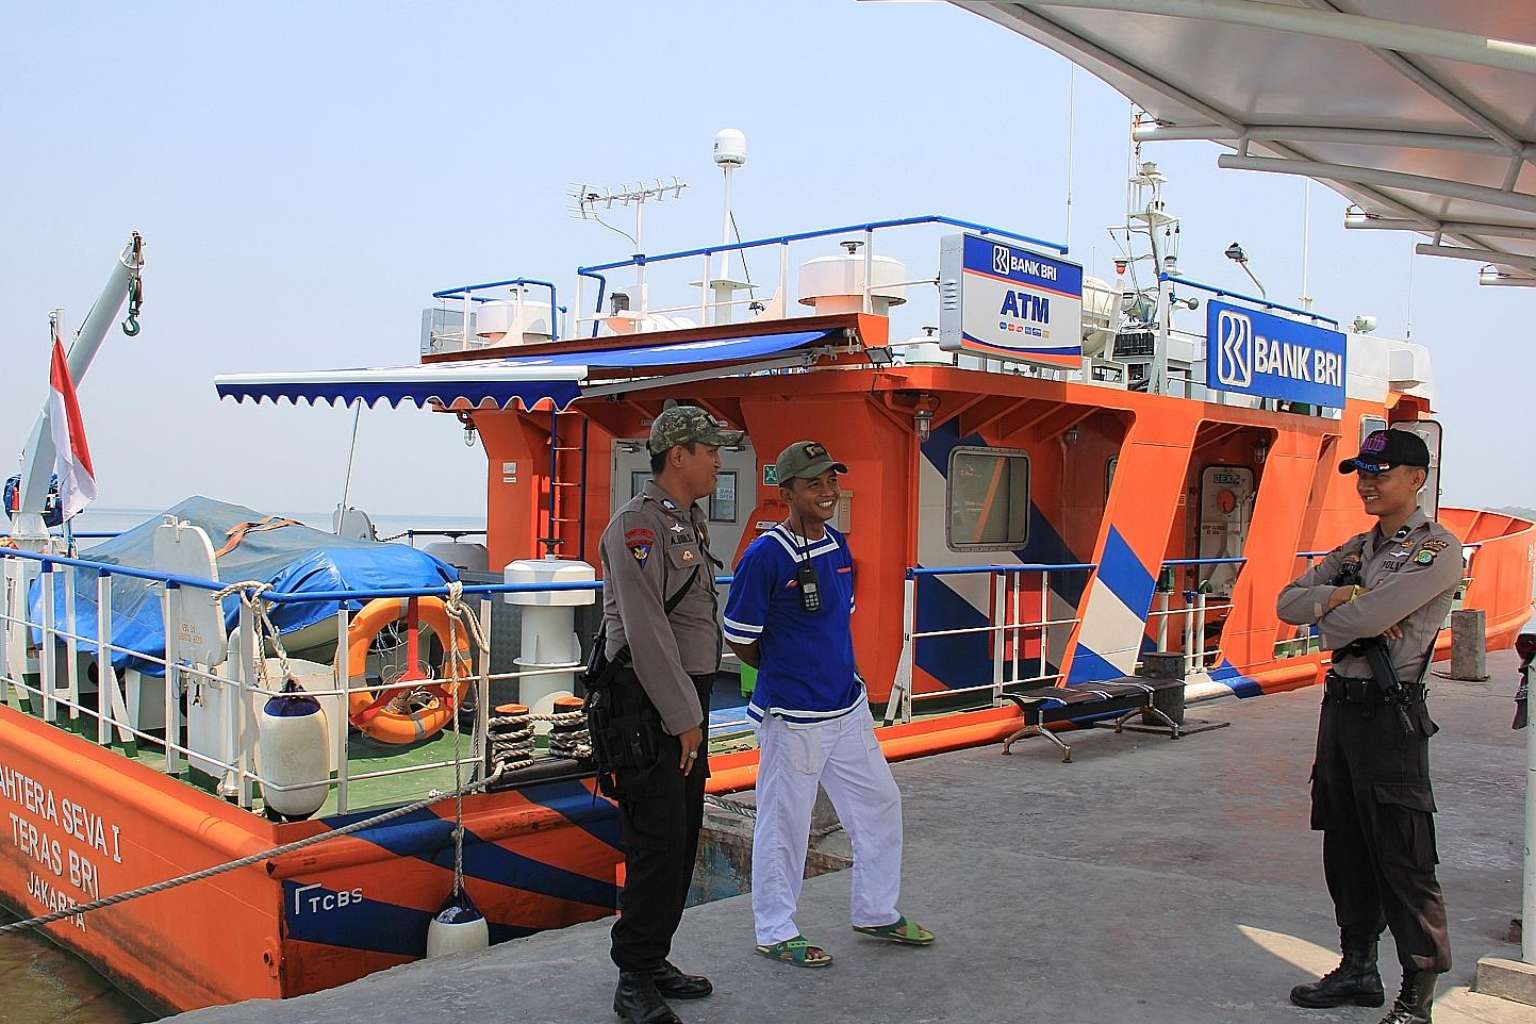
    An Indonesian bank has transformed a boat into a mobile bank outlet, providing services to residents living on remote islands of the sprawling archipelago. Officially launched in August by President Joko Widodo, the service is the first of its kind in the south east Asia nation, and is hoping to make banking services more accessible to people living on the country’s many sparsely populated islands.

    The service offered by Bank Rakyat Indonesia (BRI) is in a trial period and currently serving five islands in the Thousand Islands regency, a chain of islands off the coast of the capital Jakarta. The boat takes off every Monday from Jakarta to visit five islands, one each day, and returns on Friday.

    Equipped with three service desks and an ATM, the boat allows islanders, who used to have to travel to Jakarta, a one-stop shop for services such as personal banking and loans. One resident on Pramuka Island, which is about a two-hour boat ride from Jakarta, said it used to take days to complete her business transactions.

    “It takes one day go to the [main]land, and another day to return, and it takes about two to three days if we need to go to the bank. Although this service is provided once in a week, it helps a lot,” said Hudreya.

    Since the arrival of the boat bank, more local businesses have been given small loans to expand – an important change on the islands that mainly rely on the tourism industry. Ferdinand Tahamata, an assistant manager for the bank who has overlooked the operation, said the ultimate goal of the programme is to provide all residents with a bank account and the funds they need.

    Tahamata, the assistant manager of the Micro-business Department at the BRI Jelamber branch in Jakarta, said: “We’ll continue the operation until we think we’ve garnered enough support from the people, which means everyone on the island has a bank account and can gain access to the capital they need, then we’ll establish a branch on the thousand island regency to serve the people here. Then our boat can move on to other parts, like eastern Indonesia, or the other islands.”

  • HSBC to rebrand Britsh retail operation as HSBC UK..

    HSBC to rebrand Britsh retail operation as HSBC UK..

    The bank, which is based in Britain and has operations in 73 countries, announced in June that it would rebrand its UK business – and fuelled speculation it could potentially sell them off – as a result of the rules that require high street banking to be ringfenced from investment banking.

    HSBC announces today that the name of its UK ring-fenced bank will be HSBC UK.

    It was not immediately clear whether the red and white logo that HSBC uses across its global operations, and which features on airbridges at Heathrow airport, will remain part of its UK facias.

    “Adding “UK” [will] distinguish the ring-fenced bank from the non-ring-fenced bank”, it helpfully pointed out.

    The famous old Midland Bank name will NOT be revived on the high street after finance giant HSBC decided against restoring the brand.

    Feedback indicated that the HSBC brand represents strength and connectivity, supporting the domestic and global ambitions of our customers.

    The news comes just days after HSBC became the latest UK bank to be affected by a processing error which temporarily affected payments to customers.

    However, a person close to the bank said the decision about the branding of its ring-fenced operation should not lead investors to draw conclusions about the outcome of the domicile review.

    But in a statement this morning, HSBC said that after a “consultation process with retail, private and commercial banking customers, as well as customer-facing staff” (we wonder how much that cost), it had chose to opt for HSBC UK.

    But the business was bought by HSBC in 1992 and branches were re-named in 1999.

    It has been hit by the banking levy introduced since the financial crisis – seen as a key reason why HSBC is considering relocating away from London and possibly back to Hong Kong where it originated.

    While HSBC’s bill from the Bank Levy will reduce over time, the impact on its overall tax burden remains unclear because of a new Corporation Tax surcharge that the Chancellor has also chose to implement on banks which make profits of more than £25m.

  • Banks, insurers to face new rules when selling at malls, public places

    Banks, insurers to face new rules when selling at malls, public places

    As financial institutions (FI) jostle to get a bigger share of the consumer dollar by sending their salespeople to hawk everything from credit cards to insurance and investment products at shopping malls, MRT stations and other public places, the Monetary Authority of Singapore (MAS) has stepped in to minimise the risks to consumers from such aggressive marketing tactics.

    In a consultation paper released today (July 23), the financial regulator proposes `Market Conduct Guidelines’ setting out safeguards that FIs — including banks, non-bank credit card and charge card licensees, insurance companies, capital markets and financial advisers — are required to implement while marketing their products and services at retail outlets and public places.

    “These proposals seek to strike a balance between allowing FIs flexibility with their marketing and distribution activities, while safeguarding consumers’ interests when they purchase financial products at retailers and public places,” said Mr Lee Boon Ngiap, assistant managing director of capital markets at the MAS.

    He emphasised that the regulator does recognise the importance of such marketing initiatives as a part of the FIs’ business models. The proliferation of such practises could lead to problems including harassment of consumers, confusion over the roles of the FI and the retailer, enticing consumers to purchase unsuitable products, buying financial products in an unconducive environment and mishandling of monies collected, the MAS said.

    Under the proposals, FIs will have to notify the MAS of their marketing and distribution activities at retailers and public places on a quarterly basis so that the regulator is able to monitor the situation more closely and tailor its supervisory approach accordingly.

    The MAS also proposed that the board and senior management of FIs be accountable for ensuring proper controls over their marketing campaigns at such places. FIs are also expected to call back customers roped in at public places before or within the free-look or cooling-off period to ensure they have understood the insurance and investment schemes they purchased. FIs must regularly conduct mystery shopping and site visits to ensure that their representatives adhere to the required standards and guidelines.

    The proposals complement existing rules and practises, and ensure consistency and alignment of standards across the financial industry, the MAS said, referring to existing guidelines that most FIs already have in place.

    Mr Antony Eldridge, financial services leader at business consultancy PwC Singapore said: “Given innovations in marketing and distribution techniques used by FIs, these proposals should not be unexpected. In fact, the proposals should also help to protect FIs in Singapore from getting caught in the kind of hugely costly scandals that have hit a number of overseas institutions.”

    Mr Rajan Raju, head of retail clients at Standard Chartered Bank Singa­pore, said: “The initiative is about responsible selling, treating customers fairly, and ensuring a robust process for the marketing of financial products and services. Treating customers fairly remains a key priority for us at Standard Chartered.”

    The Life Insurance Association of Singapore said its members are aligned with the MAS in safeguarding consumers’ interests. The implementation of numerous initiatives such as compareFIRST, balanced scorecard and Direct Purchase Insurance products are some examples of the industry’s efforts to ensure that consumers are well-informed and given flexibility in managing their portfolios to meet their protection, savings and investment needs, LIA added.

    The public consultation will close on Aug 24.

  • Indonesia’s Bank Mandiri partners ASCO, Tunas for multifinance biz JV

    Indonesia’s Bank Mandiri partners ASCO, Tunas for multifinance biz JV

    PT Bank Mandiri Tbk (BMRI), the largest bank by assets in Indonesia, is planning to tap the growing automotive credit market through a joint venture (JV) with a multifinance firm PT Mandiri Utama Finance (MUF).

    The bank plans to collaborate with automotive distribution company ASCO Automotive and Tunas Group for establishing the JV company. In the new JV, Bank Mandiri will hold 51 per cent, while US ASCO will hold 37 per cent stake and Tunas Group 12 per cent.

    MUF expects the new JV firm to begin operations in September.

    MUF was established in January 2015 as a leasing sub unit of Bank Mandiri, which has 10 subsidiaries, including Syariah lender PT Bank Syariah Mandiri (BSM), securities firm PT Mandiri Sekuritas and life insurer firm PT AXA Mandiri Financial Services.

    Hery Gunadi, Consumer Banking Director for the bank told that Bank Mandiri intends to capture market share of 30 per cent by 2018. Currently, the bank has around 10 per cent market share in the multi finance sector.

    MUF plans to open between five and eight branches (Jakarta, Bandung and Surabaya) in the second half of this year.

    Meanwhile, Mandiri Tunas Finance will provide financing for car, heavy equipment and motorcycles, while Mandiri Utama Finance will focus on new and used car and motorcycle financing, said Gunadi.

    President Director and CEO Group of Bank Mandiri, Budi Gunadi Sadikin added that the potential market for automotive credit could reach Rp200 trillion ($14.93 billion) this year with estimated car sales around 1 million units and motorcycle 8 million units.

    “There are a lot of multifinance firms that are encountering funding difficulties. This creates opportunities for us to enter (the financing) business. At present, income contribution from multifinance business, on average grows, by around 31 per cent per annum; and it is the third largest income contribution from subsidiaries after AXA Mandiri and Bank Syariah Mandiri,” he said.

    ASCO Automotive and Tunas Group are among largest automotive distributors in the country. ASCO Automotive, previously called Adira Mobil, was jointly established by former CEO of PT Astra International Tbk (ASII) Teddy P Rahmat and former CEO of financing firm PT Adira Finance TbkStanley Setia Atmadja in 1989.

    Tunas Group was established by businessman Anton Setiawan in early 1970s. In 1980, he establishedPT Tunas Ridean Tbk (TURI) as holding company of Tunas Group and listed the firm in 1995. In 2009, Bank Mandiri acquired 51 per cent shares of PT Tunas Financindo Sarana, a subsidiary of Tunas Group and later changed the company’s name to PT Mandiri Tunas Finance (MTF).

  • Identifying Asia’s regional bank champions

    Identifying Asia’s regional bank champions

    Bank of China is seen as the strongest challenger for Asian leadership

    A swelling population, exponential economic growth and broad financial development are transforming Asia ex-Japan into a global finance hub.

    It is the opportunity to service retail and wealthy clients in Asia that has fired banks’ ambitions to extend their regional networks and boost their distribution power.

    But the odds are stacked against them. They have nowhere near the scale of the international players Citi, HSBC and Standard Chartered. This trio has resources, customer networks and relationships acquired from a century of operations in Asia.

    Asian banks, on the other hand, face constraints in their ability to expand cross-border, including fierce domestic competition and national protectionism.

    Nevertheless, they have become increasingly vocal about their regional ambitions, centred around expanding their wealth management businesses.

    Our leading contenders come from China, Malaysia and Singapore. Hong Kong banks appear content to focus on Greater China, where they will seek to be facilitators of trade flows rather than competitors in regional distribution.

    “From a geographical standpoint, the footprint of the Singaporean banks is wider,” said Michael Wu, senior equity analyst at Morningstar. “They might be in a better position to access Asia.”

    Bank of China is seen as the strongest challenger for Asian leadership. It has the balance sheet and is willing to suffer in the short term to expand, notes CLSA.

    BOC has a network of 11,514 offices, although 10,693 are onshore. Overseas, it has 628 offices in Hong Kong, Macau, Taiwan and in 37 other countries.

    It was first to offer private banking onshore in 2007 and now manages Rmb720 billion ($116 billion) for 74,000 private banking customers, with more than 7,000 wealth management centres and 34 private banking hubs. It has private banking operations in Singapore and Hong Kong and has ambitions to grow in Asia, including Australia, where it opened a branch in 2010.

    Singapore’s largest lender, DBS, has 280 branches across 15 markets in Asia. But Singapore and Hong Kong remain its major markets, despite its attempts for regional leadership. As CLSA points out, its operations in the growth markets of China, India and Indonesia have remained sub-scale.

    DBS is building wealth management/private banking operations. Its private banking business was bolstered by its $220 billion acquisition of Société Générale’s private banking business in Asia last October, boosting its AUM 22% to S$133 billion ($97.4 billion) as of December 2014. DBS’s total wealth management AUM stood at S$141 billion and its private bank AUM at S$95 billion.

    Maybank was a late-comer to private banking, but has been building a solid Asean network. Its regional operation only started 18 months ago, with Singapore as its hub. But it has been hiring aggressively and expanding its proposition, including launching a discretionary portfolio management service.

    Steven Seow, Asia head of wealth management at Mercer, pointed out that Maybank has succeeded in converting long-time Asian corporate banking entrepreneurs to its wealth management business. In terms of private banking assets, Maybank has S$6 billion in overall AUM, having added S$2 billion in new assets over the past year.

    Historically OCBC has focused on Southeast Asia. It has a strong position in Singapore and is one of the largest foreign banks in Malaysia, providing conventional and Islamic finance. Last year it acquired Wing Hang Bank in Hong Kong for $5 billion.

    That increased OCBC’s branches in Greater China from 25 to 120 and deepened its operations in the Pearl River Delta, although it paid a high premium given Wing Hang’s operations in Hong Kong and China were marginal.

    In private banking and wealth management, OCBC’s 2009 acquisition of ING Private Banking (renamed Bank of Singapore) for $1.46 billion has given it the scale to compete with DBS and global banks. The acquisition trebled its private banking AUM to $23 billion.

    As of March this year that AUM had since doubled to $51 billion. It enjoyed 15% year-on-year growth in wealth management income in 2014.

    Among Singaporean banks, UOB’s focus is on Southeast Asia, with universal banking operations in Malaysia, Thailand and Indonesia. But outside of Singapore its strength in Malaysia – it has the largest foreign bank network in the country with 45 branches – is not replicated in Thailand and Indonesia.

    Without the help of an international acquisition, UOB has invested in building its wealth management and private banking capabilities out of Singapore.

    It saw the combined AUM of wealth management and private banking grow 67% to S$80 billion in the four years to 2014, during which time the profit contribution of wealth management doubled to 47%.

    But while it has plans to offer private banking outside of Singapore, its current proposition is acknowledged as behind city-state peers DBS and OCBC.

    The full article appears in the July 2015 edition of AsianInvestor magazine
  • ICBC Singapore launches USD/SGD dual currency card

    ICBC Singapore launches USD/SGD dual currency card

    Industrial and Commercial Bank of China (ICBC) Singapore has launched a US dollar and Singapore dollar dual currency credit card as it seeks to expand its retail banking presence here.

    The ICBC Visa USD/SGD dual currency credit card will have zero administrative fees for all US dollar transactions, the bank said in a press release on Monday. This would ease “additional costs that customers tend to bear, which can be as high as 2.5 per cent”, ICBC Singapore’s general manager Zhang Weiwu added in the statement.

    It is “the first dual currency card in Singapore to combine both USD and SGD customer accounts in one credit card”.

    Credit card providers typically charge an administrative fee for currency conversions on credit card purchases made in foreign currencies. This fee is usually a percentage of the transaction cost, and depends on the rate set by the bank and by the credit card network, such as Visa or MasterCard. This fee is usually not explicitly given in the cardholder’s monthly statement.

    Banks in Singapore have rolled out a few new credit cards since the start of the year in a bid to grow their slice of the market, where growth momentum is slowing. OCBC, which has set its sights on 30 per cent growth in card spending this year, launched its Voyage air miles card in March targeted at high net worth and affluent customers. ANZ also launched in March a credit card that lets cardholders choose what rebates they get.

    ICBC Singapore, designated as the yuan clearing bank here, also came up with Singapore’s first yuan and Sing dollar dual currency credit card in 2011 – the RMB(renminbi)/SGD UnionPay dual currency credit card.

    On the launch of its latest credit card, the bank said that its promotion incentives include “cashbacks on every new application and activation, and additional rewards for online applicants”. It has retail branches in Raffles Place, Orchard, Chinatown, Paya Lebar and Jurong East.

  • HSBC aims to be the leading international bank in Singapore

    HSBC aims to be the leading international bank in Singapore

    As HSBC moves to reduce costs and reverse declining profits, it says Singapore will remain one of the group’s priority markets in its pivot to Asia.

    The banking giant says it plans to cut about 50,000 jobs, sell its operations in Brazil and Turkey, and have a return on equity of more than 10 per cent by 2017.

    In its Tuesday investor update for 2015, HSBC also outlines a strategy to increase its presence in South-east Asia and China’s Pearl River Delta within the next 10 years.

    The bank notes that Singapore is a leading financial centre in Asia. HSBC aims to “become the leading international financial services provider in Singapore” in the long term, with emphasis on Financial Institutions Group (FIG) clients and large regional and global corporates. It will locally incorporate the retail business here, focus on the affluent segment and expand its private banking business to capture cross-border wealth flows.

    HSBC was one of the seven banks named by the Monetary Authority of Singapore last month as being “systemically important”, but has yet to locally incorporate its retail operations as required under the additional supervisory measures.

    The bank’s Asean strategy recognises the significant growth in loans and advances in the region between 2009 and 2014. HSBC saw this rise by 15 per cent in Singapore, reaching US$32 billion last year. This is more than twice the amount in Malaysia, and compares relatively well with mainland China, which had US$38 billion.

    Hong Kong loans and advances grew 17 per cent to reach US$214 billion.

    HSBC is among the top five banks in Singapore, based on market share in deposits and loans and advances to customers, with a loan market share of 3.6 per cent. In the past year, it opened two local branches in a bid to boost its retail business, bringing the total count to 11.

    HSBC would have to compete with other banking leaders, including DBS and Standard Chartered, as it also aspires to be one of the top five banks in South-east Asia.

    The bank highlighted its “unique position” in Asean, noting that it is the world’s third fastest-growing trade zone, and home to a large emerging middle class and some of the fastest-growing cities. HSBC has more than 180 branches in Singapore, Malaysia and Indonesia combined, and sees itself as one of the “leading foreign banks” in these priority markets.

    The bank expects “significant growth opportunity” in South-east Asia, with wealth creation to grow 3.6 times by 2030.

  • Zooming in on market niches lets Maybank flourish

    Zooming in on market niches lets Maybank flourish

    Navigating Singapore’s crowded banking landscape is not easy, and Maybank’s retail banking unit says it needs to be nimble by zooming in on market niches.

    The bank last month launched a Maybank Save Up programme tailored for young workers in Singapore after noticing that many are increasingly keen on financial planning.

    And, noting that young children are often neglected by lenders, it launched last September the Maybank Family Plus programme to encourage parents to help kids save.

    Maybank is also focusing on long-term relationships and on catering to customers’ needs at every stage of their lives.

    “I think (Singapore) is probably one of the most highly- banked markets, even for retail,” said Mr Choong Wai Hong, the bank’s head of community financial services. “But that said, I find the Singaporean consumers, the account holders, they are quite savvy.”

    In an interview with The Straits Times on Thursday, he said consumers are often willing to snap up new products and services. “Their sensitivity to change, to go for a product, is quite high. So if you can find the right market niche for them, the willingness to move is quite high”.

    What Maybank does in Singapore is closely-watched by rival lenders as it is one of the very few foreign banks with a large retail presence here.

    Its three entities in Singapore – Maybank, Maybank Kim Eng brokerage and Etiqa Insurance – employ 2,400 staff.

    Singapore’s central bank last month named Maybank one of the inaugural seven “domestic systemically important banks” in the Republic.

    The seven each has a significant impact on the financial system’s stability and proper functioning of the broader economy, the Monetary Authority of Singapore said.

    The three domestic lenders in the list are DBS Bank, OCBC Bank and United Overseas Bank. And apart from Maybank, the other foreign banks are Citibank, Standard Chartered and HSBC.

    Maybank has 22 full-service branches in Singapore – the largest for a foreign bank here, but nowhere near the hundreds of branches operated by the three local lenders.

    It is sometimes known as the “time deposit bank”, owing to its competitive retail deposit rates. Mr Choong said Maybank has 10 per cent to 11 per cent share of the time deposit market in Singapore.

    Its other strength is in the vehicle loan market where it has a 22 per cent market share.

    The Maybank group in Singapore last week reported profit before tax for the first quarter of $93.75 million, down from $110.9 million a year earlier.

    Asked about its retail lending profile, Mr Choong said the major segments are about 45 per cent in mortgages, 18 per cent in auto loans, 22 per cent in retail small and medium enterprises and commercial loans. Other consumer loans make up the other 15 per cent.

    Maybank, he said, has an advantage that other foreign banks here might not have – the group offers the full spectrum of services including retail banking, Maybank Kim Eng brokerage, Etiqa Insurance and Maybank Private Wealth.


  • Singapore to remove distinction between international and domestic banking

    Singapore to remove distinction between international and domestic banking

    The Monetary Authority of Singapore (MAS) plans to change accounting rules that split domestic and offshore banking into separate ‘units’. 03 Jul 2015

    Since 1968, banks have had to separate operations into domestic banking units (DBSs) and Asian current units (ACUs). Domestic operations, which are predominantly denominated in Singapore dollars, are accounted for through a bank’s DBU, while offshore operations, which are entirely denominated in foreign currency, are accounted for through the ACU.

    However, global regulatory developments over the past five years have created a situation where the split system is no longer useful, Singapore’s minister of finance Tharman Shanmugaratnam said.

    The initial aim of the divide was to safeguard domestic financial stability, Tharman said.

    “For example, MAS imposed liquidity requirements on banks’ Singapore dollar liabilities – that is, only within the DBU. In addition, DBU activities were subject to large exposure and equity investment limits,” he said.

    The divide also made it easier to offer incentives to encourage offshore banking activities out of Singapore, Tharman said, but focusing incentives in the ACU.

    “The DBU- ACU divide served us well for decades, but has been losing its relevance,” Tharman said.

    “Since 2004, our development incentives have no longer been based on the domestic versus offshore distinction, and the divide between domestic and offshore banking has in practice become increasingly porous,” he said.

    In addition, global regulatory changes have meant that banks’ offshore activities are now subject to rules that are broadly similar to those governing DBUs in Singapore. These rules have increased the amount and quality of capital and the liquidity buffers that banks need, Tharman said.

    “These global regulatory reforms have put all banks on a sounder footing. It has also reduced the relevance of MAS rules that distinguish between offshore and domestic banking activities of foreign banks, since home regulators will now be requiring their banks to meet enhanced standards on a group-wide basis,” he said.

    Changes to MAS’s own regulations have also made the divide less relevant, Tharman said.

    All banks in Singapore will have to meet liquidity requirements across the entirety of their operations by January 2016, while banks that are designated as ‘domestic systematically important banks’ will be subject to extra measures on both domestic and offshore business, he said.

    In addition, Tharman said, “where a foreign bank branch has significant retail presence in Singapore, it will also be required to locally incorporate its retail operations. The subsidiary will be subject to the same suite of regulation as the local banks, and the same supervisory regime aimed at minimising risks to local depositors”.

    MAS will therefore remove the divide from banking regulations, and details will be released in a consultation paper by August, Tharman said.

    “There is no rush. We will implement the changes in close consultation with the banking community, and phase them in over time,” he said.

  • Citigroup combines retail banking and mortgage operations

    Citigroup combines retail banking and mortgage operations

    Citigroup Inc (C.N) will combine its retail banking and mortgage operations under Jonathan Larsen, according to an internal memo seen by Reuters, in the second senior promotion for a veteran of the bank’s Asian franchise this year.

    The U.S. bank’s Asia Pacific chief Stephen Bird in April became the global head of Citi’s consumer bank, in a move seen by analysts as rewarding the U.S. lender’s strategy in the region.

    Larsen, currently global head of retail banking, previously ran Citi’s Singapore unit and spearheaded the lender’s push in credit cards in Asia. Citi’s Asian franchise now has 12 of the lender’s 24 consumer banking markets globally, and contributes a fifth of global profits.

    “Citi Asia is a sign of where Citigroup as a whole potentially can go,” CLSA analyst Mike Mayo said in a research note prior to the announcements. The lender’s strategy in the region has been to move from targeting the mass market to richer ‘mass affluent’ customers, Mayo wrote.

    The appointments this week of Larsen and Bird, who oversaw that push in Asia to trim low-profit customers and target wealthier clients, signals Citi’s intention to pursue the strategy globally.

    In a separate memo also seen by Reuters on Thursday, Citi named Anand Selvakesari as head of consumer banking for Asia, a position Larsen has been holding since 2009.

    A Citi spokesman confirmed the contents of the memos.

    Fabio Fontainha, the head of consumer banking in Brazil, will assume additional responsibility for consumer banking in Latin America.

  • Indonesian FinTech start-ups raise stakes for banks

    Indonesian FinTech start-ups raise stakes for banks

    A string of innovative financial products from Indonesian start-ups are circumventing the traditional payment and investment system, helping to broaden financial inclusion and challenging the established banks.

    Indonesia’s tech-savvy youth have already given rise to pioneering start-ups with social and religious missions and the so-called FinTech industry is set to disrupt traditional banks by offering everything from Bitcoin remittances to mobile pawn shops and retail lending platforms.x

    New alternatives

    With a large swath of the population still unbanked – in part due to the country’s challenging geography – new technologies in banking, transactions and payments offer significant growth potential, with banks under increasing pressure to respond to the trend.

    Banks and regulators in Asia are at difficult levels of understanding of the sector, explained Mohit Mehrotra, an executive director at Deloitte Consulting. “Asia has a huge potential for FinTechs. Countries like India and Indonesia, with their low financial services penetration and large unbanked and underserved populations, are perfect breeding grounds with several white spaces for FinTechs to play an important role,” he told local media in May.

    But collaboration with the FinTech sector is also an option and represents a potential source of growth, particularly for larger banks. “Big banks, by nature of their legacy set-ups, find it increasingly difficult for forging new digital-enabled business models that FinTechs specialise in,” said Mehrota.

    This is starting to be acknowledged by the big banks. Jamie Dimon, chairman of JPMorgan Chase & Co, in a letter to shareholders in May warned there were “hundreds of start-ups with a lot of brains and money” working on various alternatives to traditional banking services.

    Rapid rise

    With Indonesia’s demographic trends favouring smaller and more flexible solutions, start-ups are set to gain a competitive advantage over established banks in areas such as mobile payments and crowd funding, which are increasingly popular in the new web-based financial services field.

    Regional investors have been quick to spot the trend. On June 1, Japan-based venture capital firm CyberAgent Ventures announced a new $50m fund for South-east Asian start-ups, with more than half of the new fund’s activity directed towards the Indonesian market. The firm has predominantly focused on series A Indonesian start-ups until now, but the new fund will open the doors to tech start-ups in the seed, series A and series B stages.

    “We are very bullish, especially on Indonesia,” Steven Vanada told regional media. “It doesn’t only have to be in consumer business or e-commerce… We’re keeping our eyes on other sectors too,” he added.

    Such moves will likely draw interest towards firms like Blossom, a product targeting the global Muslim community. Based out of south Jakarta, the firm brings together Bitcoin, microfinance and Islamic finance, the latter of which is increasingly popular in Indonesia.

    The company’s model involves collecting money from global investors for entrepreneurs who want to start a small business. Blossom does not give the funds to business owners directly, but works through an intermediary or a local microfinance institution. After a 12-month investment cycle, Blossom collects profits from the microfinance institutions and distributes them to the investors.

    Bitcoin rise

    Due to Indonesia’s large underbanked population, Bitcoin is expected to gain significant traction as consumers bypass banks and other financial institutions. World Bank inclusion data from 2014 put the percentage of people above 15 years of age in Indonesia with a financial account at 36%, up from 20% in 2011 and the percentage with a loan from a financial institution at 13%. This compares poorly with regional peers with more than two-thirds of the population in East Asia and the Pacific having an account.

    Artabit, a US and Indonesian start-up, is tapping into the market by combining payment solutions using the Bitcoin network. One use of its products is for remittance services. Hong Kong-based Bitspark recently joined forces with Artabit to provide a remittance service for Indonesian workers in Hong Kong who want to send money back home.

    But despite the huge potential for digital payments in countries such as Indonesia, some industry participants say that infrastructure is still lacking. “Given the size of Indonesia, it may take some time before digital payments are widely used for retail e-commerce because the required infrastructure will have to be in place first,” said Raj Dharmodaran, MasterCard Asia Pacific’s group head for emerging payments.

    He also highlighted the importance of having a regulatory framework that supports the growth of digital payments, saying that a country should have globally standardised regulations conducive to the growth of digital payments.

    For now, the Indonesia government is maintaining a strict stand against the digital currency. The central bank does not recognise Bitcoin as a legal form of currency and has warned people to use it at their own risk. However, the Indonesian public are beginning to embrace the technology and related services as new FinTech start-ups help to make them more accessible and easier to use.

  • Citizen Card to facilitate online shopping in Myanmar

    Citizen Card to facilitate online shopping in Myanmar

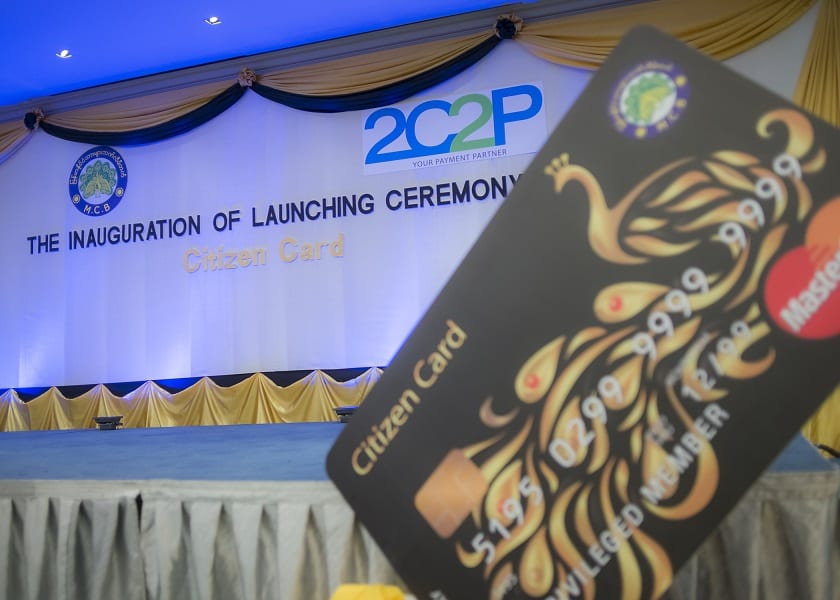
    A citizen card launched by payment services provider 2C2P and Myanmar Citizens Bank is expected to support e-commerce in Myanmar.

    The reloadable prepaid card is accepted by MasterCard merchants and comes with an optional smartphone application that allows cardholders to manage transactions in real time.

    “Targeted at the retail, and travel and tourism sectors, Citizen Card will facilitate both physical and online shopping. It will also be of use to Myanmar tourists when they travel overseas, as consumers can enjoy special benefits and privileges at destinations such as Thailand and Singapore, with a number of partner merchants in the airline, food and beverage and hospitality sectors,” said.

    Initially, supply of the Citizen Card will be limited to 5,000 units but plans are underway for options to roll out more within the year.

    According to McKinsey & Co, Myanmar is expected to quadruple the size of its economy from USD45 billion to over USD200 billion by 2030, with per capita GDP rising from USD1,300 in 2010 to USD5,100 by 2030.

    “Building on this momentum, we are pleased to partner with 2C2P and launch MCB’s very first prepaid card, which will help support the imminent growth in Myanmar e-commerce,” said U Myint Win, Managing Director of Myanmar Citizens Bank.

    2C2P has also introduced in Myanmar iACCEPT, a mobile point-of-sales system with Visa, MasterCard, Myanmar Citizens Bank and Myanmar Hotels International. In July, 2C2P partnered with Creative Web Studios, a Yangon-based e-commerce solutions provider, working to drive financial inclusion and develop Myanmar’s contactless payment infrastructure.

  • Australian shoppers flock to the Boxing Day sales despite poor sentiment

    Australian shoppers flock to the Boxing Day sales despite poor sentiment

    Retailers in Australia were delighted by a strong turnout of shoppers on Boxing Day, giving analysts further reason to suspect a turnaround in consumer sentiment.

    Myer executive general manager stores, Tony Sutton, said the crowd through the doors at the Melbourne Bourke Street store at 5am looked like its biggest in a decade.

    Accounting firm BDO reported that spending in the week before Christmas was up 13 percent on 2013. BDO national retail lead partner Simon Scalzo said the last few weeks of December had seen a shift in consumer sentiment and now more people were willing to spend.

  • Christmas shopping: Consumer anxiety falls in time for retail season

    Christmas shopping: Consumer anxiety falls in time for retail season

    Consumers in Australia are less anxious than at any time in the past 18 months amid signs of a robust finale to the Christmas shopping season.

    The National Australia Bank’s consumer anxiety index, released on Tuesday, has fallen for a second straight quarter to its lowest mark since mid-2013. It also revealed households have increased spending on non-essentials.

    New spending data pointed to solid retail spending growth in December, despite the hit to consumer confidence caused by last week’s siege in Martin Place. Commonwealth Bank figures, released on Tuesday, show the volume of debit and credit card transactions made in stores across Australia in the first three weeks of December was 10.7 percent higher than the same period last year. The total value of transactions was five per cent higher in that period.