Tag: beauty

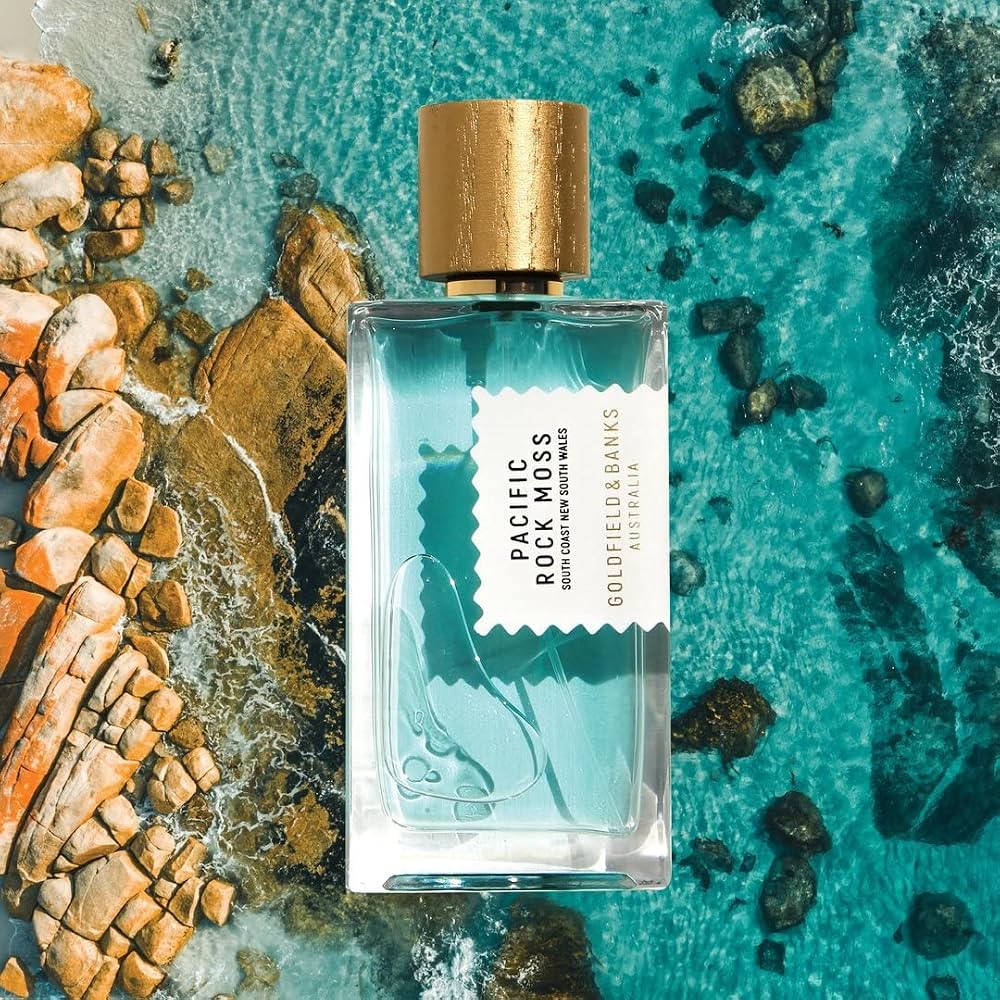
  • Goldfield & Banks Opens First Standalone Boutique in Sydney’s Strand Arcade

    Goldfield & Banks Opens First Standalone Boutique in Sydney’s Strand Arcade

    Goldfield & Banks will open its first flagship boutique in Sydney’s Strand Arcade this December, establishing dedicated brick-and-mortar retail after expanding wholesale distribution across more than 80 countries.

    Founded in Sydney in 2016, the luxury fragrance house enters physical direct-to-consumer store operations on its tenth anniversary, after relying primarily on wholesale distribution through department stores including Harrods, Selfridges and Saks.

    The Strand Arcade Deployment

    The boutique will show the brand’s full fragrance portfolio within a physical format designed alongside Australian interior designer Brahman Perera. The company partnered with its domestic distributor, Prestige Brands Australia, to execute the retail rollout.

    Founder Dimitri Weber said the upcoming opening in Sydney is a “dream come true”.

    “To now have a permanent home in the Strand Arcade, one of Sydney’s most iconic destinations, feels very special. It’s a celebration of everything we’ve achieved over the past decade and an exciting new chapter.”

    The design plan departs from standard department store concessions by deploying native materials, light treatments and tailored display formats. Weber structured the boutique to function as an immersive brand destination rather than a transactional counter.

    Wholesale Transition to Owned Retail

    Niche fragrance brands across Asia-Pacific face rising wholesale customer acquisition costs and tighter shelf allocations in major department store channels. Shifting from multibrand stockists to single-brand boutiques gives independent perfumers direct access to shopper transaction data, higher gross margins per bottle, and complete pricing control.

    For arcade landlords in mature central business districts, boutique perfumeries provide reliable sales densities across compact square footage. Fragrance purchases carry high average order values and minimal stock space requirements compared to apparel tenants.

    Retail Footprint and Distribution Lineage

    Weber started Goldfield & Banks around botanical ingredients native to Australia, directing early distribution into overseas luxury channels before consolidating domestic footprint. The international export track built brand equity in department stores, generating inbound demand from international travellers returning to Sydney.

    Prestige Brands Australia will support the operational handling of the Strand Arcade location as the brand tests standalone retail economics. The store opening in December tests whether independent domestic luxury labels can sustain prime shopping arcade leases on dedicated fragrance sales alone.
  • Givaudan Targets GLP-1 Consumer Spending Shift Toward Beauty

    Givaudan Targets GLP-1 Consumer Spending Shift Toward Beauty

    Givaudan is revamping product development across its beauty and fragrance divisions as weight loss treatments reshape consumer budgets, tracked by 15 generic semaglutide brands entering India since patent expirations began. The ingredient supplier found adult adoption of GLP-1 therapies in the US climbed from 3 per cent in 2024 to 11 per cent in 2026, triggering direct reallocation of discretionary spending.

    Data compiled by the manufacturer from a NielsenIQ Homescan panel revealed American households using the medications increased spending on fine fragrances by 97 per cent while cutting grocery budgets. In Brazil, 47 per cent of buyers reported trimming other expenses specifically to finance treatment doses, signaling a widespread behavioral reallocation away from food toward personal grooming, sports, and travel.

    India Generics Drive Rapid Market Expansion

    Price reductions and the loss of patent exclusivity in markets such as India have dismantled entry barriers for metabolic therapies. The introduction of 15 domestic brands following patent expiries expanded regional supply rapidly, lowering therapy costs and broadening usage beyond narrow clinical segments.

    Lower retail prices combined with the development of oral alternatives to subcutaneous injections are speeding up adoption across emerging economies. For personal care brands operating in Asia, this shift alters the customer base faster than anticipated. Product developers must adjust formulas for consumers managing the physiological consequences of rapid weight reduction.

    Formulations Adapt to Side Effects

    Patients experience specific physiological issues that prompt new topical requirements, notably loss of facial volume, loose skin, barrier dryness, temporary hair thinning, and bad breath. Consumers navigating these side effects prioritize demonstrable performance over brand prestige, checking active concentrations and clinical validation closely.

    Buyers demand formulas that combine medical-grade efficacy with sensory textures. Frédéric Merlin, manager of the Givaudan Digital Factory in Paris, stated: “Faced with these very real concerns, consumers are becoming more demanding: they seek out the right actives, compare concentrations, and check the evidence behind efficacy claims. But they are unwilling to choose between performance and pleasure. They expect visible results, sensorial textures, and an enjoyable experience. Whereas a brand’s reputation may once have been enough to win them over, it is now the efficacy promise, backed by evidence, that makes the difference.”

    Scent Profiles Reflect Appetite Changes

    Social listening data gathered by Givaudan identified two dominant fragrance profiles among treatment users: gourmand compositions and crisp, fresh notes. Appetite suppression does not eliminate interest in rich food-inspired aromas, although nausea risks create sharp aversions to heavy notes, requiring finer calibration by perfumers.

    Energy dips and sleep disruptions linked to these therapies have opened room for functional scents. Givaudan is deploying its patented MoodScentz and DreamScentz platforms, pitching neuro-olfactive formulations that stimulate alertness in the morning or support disrupted sleep cycles at night.

    Digital Factory Tests Commercial Concepts

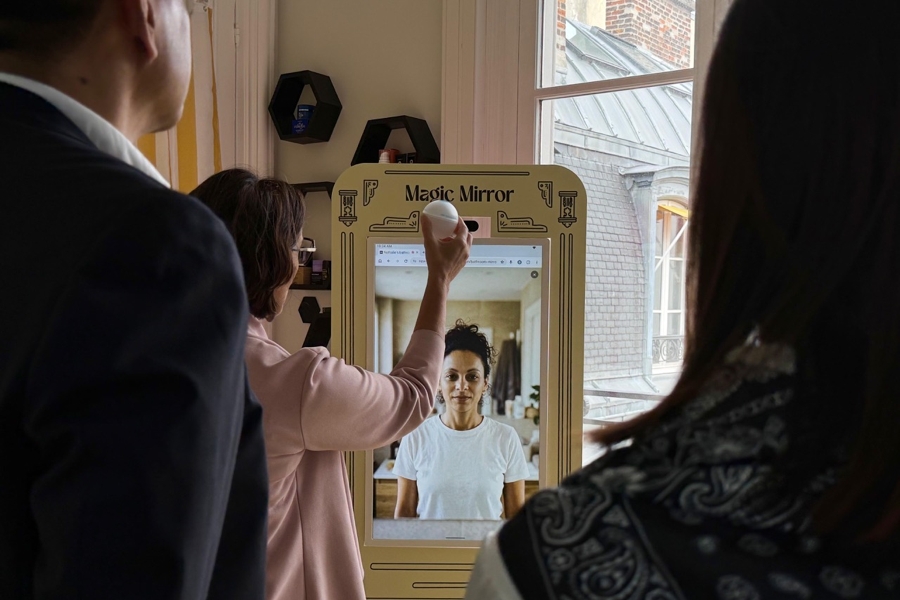
    The company developed an exhibition format called The New Desire at its Paris Digital Factory, built around an artificial intelligence persona named Nathalie to model shifting habits. Brand teams examine over 120 global product rollouts and generate concept packaging tested against simulated consumer feedback.

    Corporate clients have booked repeat sessions at the facility, prompting an operational extension of the program. Fast-moving consumer goods suppliers across the Asia-Pacific region now face parallel realignments on retail shelves: packaged food volumes face headwinds, while functional personal care and premium fragrances capture liberated wallet share.

    Givaudan plans to publish its next wave of field research on GLP-1 olfactory preferences before the end of 2026.

  • ELF Beauty Raises Outlook as Q2 Net Sales Climb 51% to US$520.8 Million

    ELF Beauty Raises Outlook as Q2 Net Sales Climb 51% to US$520.8 Million

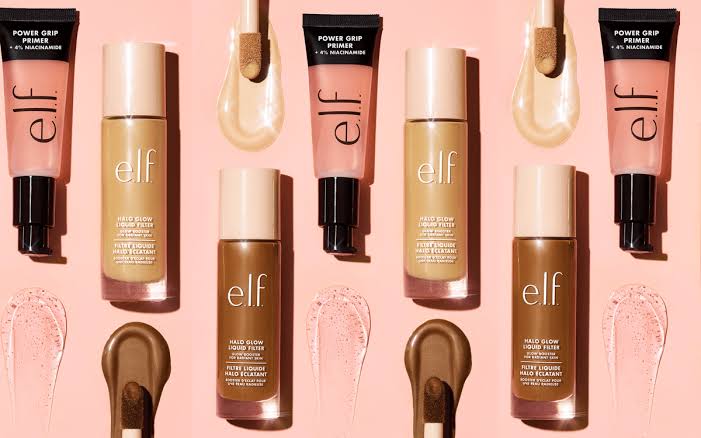
    ELF Beauty has raised its full-year outlook following a strong second quarter ended September 30, driven by organic momentum and expansion from Hailey Bieber’s brand Rhode.

    Net sales advanced 51 per cent year-on-year to US$520.8 million (A$755.9 million) during the three-month period. Over the same quarter, net income climbed to about US$30 million (A$43.5 million), up from just under US$3 million (A$4.4 million) a year earlier.

    The company now projects full-year net sales to increase between 22 per cent and 24 per cent, compared with an earlier projection of 18 per cent to 20 per cent. It lifted adjusted EBITDA expectations to a band of US$421 million to US$427 million, while adjusted diluted earnings per share are projected at US$3.82 to US$3.86.

    Wholesale Pipeline Drives International Volume

    International sales advanced 165 per cent during the period, lifted by initial stocking shipments for Rhode’s retail debut across European Sephora doors. Domestic net sales inside the United States rose 25 per cent.

    Organic revenue across the group climbed roughly 35 per cent. Rhode added 16 percentage points to total top-line growth during the final four weeks before e.l.f. Reached the one-year anniversary of the buyout on August 5, after which the brand rolled into organic calculations.

    Volume contributed 31 percentage points of overall company growth, while price adjustments and product assortment added 20 percentage points. Gross margin widened 160 basis points to 71 per cent, supported by a 30-basis-point lift from tariff refunds.

    Adjusted EBITDA rose 86 per cent to US$123 million. Adjusted net income reached US$73 million, translating to US$1.21 per diluted share compared with US$0.68 a year ago.

    Margin Pressures and Retail Channel Costs

    The financial payoff from rapid retail placement will narrow over the next two quarters. Management warned that adjusted EBITDA margins will settle in the low teens through the second half of the fiscal year.

    Operating costs are climbing as the group funds marketing programs alongside physical build-outs for Rhode across specialty beauty retailers. Price competition in mass retail also limits pricing flexibility, prompting leadership to redirect tariff recoveries toward shelf pricing and promotional spending.

    For retail buyers and department store operators across Asia-Pacific, Rhode’s rollout shows the operational strain of backing viral social brands. The group faces immediate working-capital demands to support store stock levels without dragging down profitability.

    Execution risks now sit inside inventory control. Retailers carrying colour cosmetics face tighter sell-through windows, meaning any plateau in consumer demand leaves distributor channels burdened with excessive inventory.

    Annualising Regional Expansions

    Second-half performance faces harder annual comparisons after heavy channel rollouts during the prior fiscal cycle. That base includes Rhode’s introduction into MECCA doors across Australia and New Zealand, alongside e.l.f. Shelf expansions at Ulta Beauty, German drugstore chain dm, and Naturium’s rollout across Walmart counters.

    Second-half net sales growth will moderate to between 7 per cent and 10 per cent, with third-quarter gains running ahead of that rate and fourth-quarter growth dropping below it.

    The company expects full-year organic sales growth of 9 per cent to 11 per cent, revised upward from earlier guidance of 6 per cent to 7 per cent. Digital and marketing investments absorbed 21 per cent of second-quarter net sales, lower than budget allocations due to campaign timing shifts.

    Attention turns to retail reorder patterns across overseas doors when e.l.f. Beauty reports third-quarter financial figures.

  • Touchland Enters Sephora Australia with 13 Products

    Touchland Enters Sephora Australia with 13 Products

    Touchland entered Australia on October 28, rolling out 13 products across Sephora stores nationwide and online.

    The partnership gives the US brand its first local retail presence in the country, following years of domestic shoppers purchasing its mist sanitizers while traveling overseas.

    Expanding personal care shelves

    Founded in 2018, the US-based brand built its profile around fragrance-led formulations and slim, pocket-sized packaging. The Australian debut focuses on its Power Mist range, placing the sanitizer lineup directly into Sephora’s physical footprint and digital storefront.

    Personal care items in beauty retail have steadily migrated from checkout add-ons into dedicated shelf categories. By securing prime space inside Sephora, Touchland bypasses mass-market pharmacy shelves where utility sanitizers dominate on price rather than branding.

    The premium hygiene play

    The Australian rollout tests whether local consumers will pay beauty-counter premiums for hand hygiene in an inflationary retail climate. For Sephora, stocking the brand expands impulse personal care assortment with products that carry established social media recognition.

    Department stores and specialty beauty chains across Asia-Pacific face tighter consumer discretionary budgets, forcing retailers to rely on lower-ticket basket builders. Touchland gives the retailer a recognized entry-level item that drives foot traffic without demanding high capital outlay from shoppers.

    Retail distribution across markets

    Before securing domestic distribution, Touchland relied on outbound Australian travelers buying inventory abroad. Brand tracking and cross-border demand indicated an addressable audience long before domestic stock arrived on local shelves.

    The initial deployment across Australian retail establishes a southern anchor for the brand in the broader Asia-Pacific region. Inventory performance across Sephora’s network over the final quarter will show whether consumer demand sustains beyond initial launch traffic.

  • Hourglass Enters Australian Travel Retail at Sydney Airport Terminal 1

    Hourglass Enters Australian Travel Retail at Sydney Airport Terminal 1

    Hourglass Cosmetics opened its first Australian airport counter inside Sydney Airport Terminal 1 International Departures, partnering with duty-free operator Heinemann.

    The debut marks the luxury beauty label’s first travel retail presence nationwide, following its initial domestic launch in February through Sephora Australia and local e-commerce.

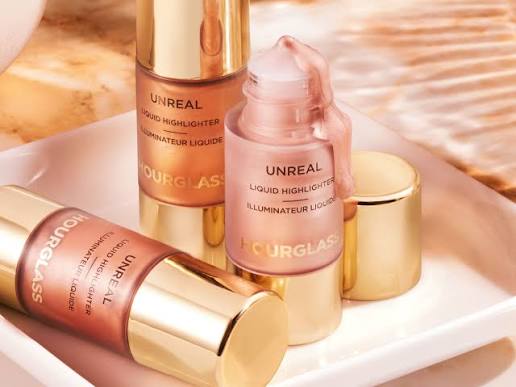
    Featuring 1 dedicated location at Terminal 1, the counter shows complexion, colour, and finishing lines including Vanish Airbrush Concealer, Veil Hydrating Skin Tint, and Unlocked Instant Extensions Mascara alongside Ambient Lighting Edit Unlocked palettes.

    Terminal 1 Footprint and Service Formats

    Travellers passing through the terminal can access personalised consultations and beauty artistry services before flights. Formats include Signature Glow and Amplified Eyes looks, accompanied by a bespoke Lip Wardrobe experience.

    “Opening our first counter in Australian travel retail is a proud moment for Hourglass,” said Ai San Beaumont, regional GM Apac and head of global travel retail, Hourglass.

    “Travel brings people, cultures, and experiences together, and we’re delighted to be part of that at Sydney Airport. With Heinemann and Sydney Airport, we look forward to introducing travellers to our vegan and cruelty-free formulas, from on-the-go essentials like Vanish Airbrush Concealer to curated gifting with Ambient Lighting Edit Unlocked palettes.”

    Travel Retail Strategy and Asian Traffic Flows

    Airport concessions operate under distinct retail dynamics compared with downtown counters, requiring strong sales productivity and high turnover during compressed pre-flight dwell windows.

    Sydney Airport channels steady outbound passenger volumes, where Heinemann uses premium beauty to capture international travel spend.

    Concession operations present both distinct reach and commercial pressure: high airport tenant overheads demand efficient basket conversion and solid margins to outperform traditional domestic retail channels.

    Building Out Australian Distribution

    The Sydney Airport counter extends the brand’s local footprint established earlier in the year. Hourglass initially debuted in Australia in February via its dedicated online portal and Sephora Australia retail doors.

    Terminal 1 departures now serves as the brand’s sole travel retail window in the country. The partnership tests whether premium service concepts such as live skin consultations can pull transaction conversion in high-turnover duty-free concourses as flight frequencies expand.

  • Proya Opens 450 Square Metre Research Lab in Paris Suburb

    Proya Opens 450 Square Metre Research Lab in Paris Suburb

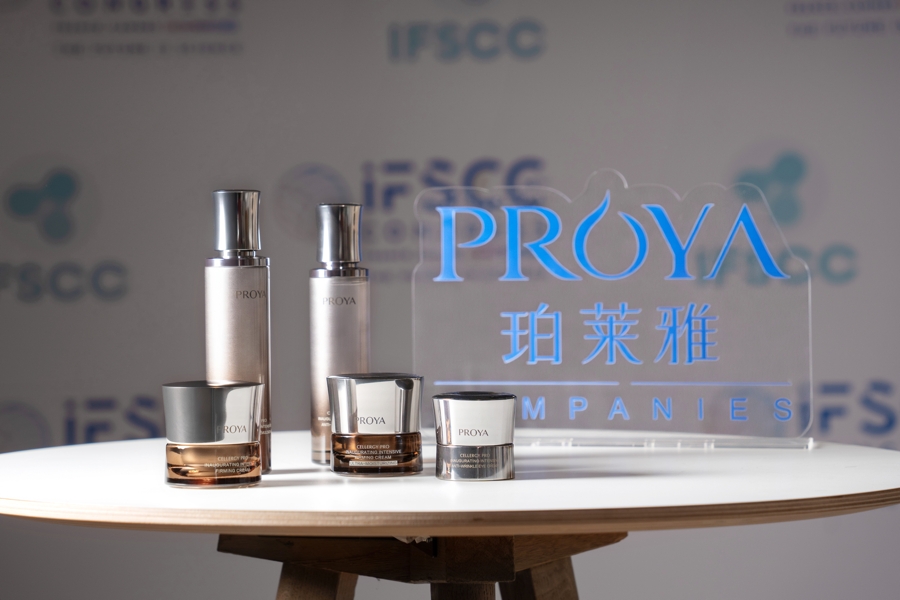
    China’s Proya Cosmetics opened a 450-square-metre research and development laboratory in Suresnes near Paris on October 13, 2026, putting seven researchers and 76 scientific instruments into service outside its domestic manufacturing base.

    The suburban Paris site links directly into formulation work at the Hangzhou-based group’s primary development hub in Longwu, feeding European biochemical research into its mass-market skincare pipelines in Asia.

    Technical operations at the French facility focus on skin biology, longevity mechanisms, biotechnology and sustainable ingredient processes. The scientific staff coordinates testing with Proya’s existing Hangzhou facility, which oversees core chemical formulations and consumer safety data, alongside a dedicated Shanghai site that handles scalp microbiome research and haircare lines.

    Targeting Active Ingredients in France

    European cosmetic science gives Chinese personal-care groups access to specialised ingredient supply chains that remain difficult to replicate domestically. Western groups like L’Oréal and Puig continue to defend their pricing power in Greater China through clinical skincare claims, forcing local brand owners to back their mass products with verifiable dermatological research rather than pure digital marketing spend.

    Setting up shop in Suresnes allows the Hangzhou company to collaborate directly with European biotechnology suppliers and academic testing houses. The facility serves as an operational extension of the broader European Innovation Centre that the group founded in France in 2024, converting regional partner agreements into physical bench testing.

    “This Europe Innovation Center Laboratory connects the European and Chinese ecosystems to draw on combined strengths and create new innovation capabilities through the interaction of scientific, cultural and consumer perspectives,” said Hou Juncheng, Founder and Chairman of Proya Cosmetics.

    Shifting Beyond Fast Digital Marketing

    Chinese beauty brands built their initial scale on quick domestic supply chains and heavy promotion across Douyin and Tmall. That model is hitting its limits as domestic consumer spending tightens and shoppers demand clinical validation before paying higher price tags for anti-ageing creams.

    By establishing physical research assets in France, Proya takes direct aim at premium international rivals that have long used European heritage to defend market share across tier-one Chinese cities. The risk for the Hangzhou group lies in execution. A team of seven researchers is a modest footprint against the thousands employed across multinational technical centres, meaning the lab must produce distinct ingredient discoveries quickly to justify the overseas overhead.

    Building Out Domestic and Foreign Hubs

    The Paris opening follows two years of corporate infrastructure work in Europe. Proya established its European Innovation Centre in France in 2024 to scout partnerships, then showed its initial collaborative work at the Cosmetics 360 trade exhibition in Paris immediately following the Suresnes opening.

    Work completed at the Suresnes laboratory will feed raw materials into clinical verification trials across Proya’s Shanghai and Hangzhou networks.

  • Gen Z Shoppers Drive Twofold Surge in Korean Beauty Orders on Myntra

    Gen Z Shoppers Drive Twofold Surge in Korean Beauty Orders on Myntra

    Gen Z shoppers accounted for 55 per cent of Myntra’s beauty growth over the past year, driving a 200 per cent surge in Korean beauty orders and a 78 per cent increase in men’s skincare.

    Spend per customer within the 14-to-29 age bracket climbed 1.2 times year on year, while repeat purchases among these buyers rose roughly 70 per cent, according to data from the Bengaluru-based e-commerce platform.

    The findings, drawn from order data between August 2025 and August 2026, show younger consumers allocating 75 per cent more of their personal care wallet to beauty compared with millennial shoppers. Beauty and personal care now accounts for approximately one in every five units shipped across the marketplace. Myntra expects Gen Z to generate more than half of its beauty customer base over the next three years.

    Active Ingredients and Smaller Regimens

    Younger shoppers are consolidating their daily routines while demanding clinical formulations. Around 80 per cent of Gen Z buyers limit their daily regimen to three products, and 30 per cent buy only one or two items per order. Sales of ingredient-focused derma products climbed 75 per cent, led by targeted searches for active ingredients including Centella asiatica, copper peptides, azelaic acid and panthenol.

    Sun protection has shifted into a year-round staple rather than a seasonal purchase. Orders for sun protection products rose 60 per cent year on year among younger shoppers. Searches for sunscreen sprays increased 80 per cent, ingredient-led formulations rose 70 per cent, and tinted sunscreen varieties climbed 60 per cent, with consumers favouring gel-based and fragrance-free textures.

    Haircare orders reflect a similar turn toward treatments over basic cleansing. Demand for hair masks jumped 110 per cent, outpacing conditioners at 59 per cent growth. Searches for scalp serums rose 50 per cent, dry shampoo searches gained 68 per cent, and styling appliances grew 55 per cent.

    Regional Demand and Premium Sample Formats

    Tier II and tier III cities now generate half of all Gen Z beauty purchases on the platform and account for half of total international brand orders. Urban centres such as Ludhiana, Patna, Bhopal, Indore, Guwahati, Surat, Varanasi and Imphal are driving category expansion. The northeastern states recorded particularly strong volume in masstige and prestige makeup, alongside rising appetite for gourmand fragrances in smaller cities.

    Entry into prestige brands is increasingly happening through travel and trial sizes. Approximately 53 per cent of luxury makeup transactions include a miniature format, representing 14 per cent of all luxury units sold. Prestige labels including M.A.C, Kayali, Smashbox and Salvatore Ferragamo now secure more than half of their new customer acquisitions through mini formats.

    Men’s grooming has expanded beyond basic shaving supplies. Total men’s grooming orders climbed 70 per cent so far in fiscal 2026, while fragrance purchases rose 50 per cent. Among Gen Z men, fragrance demand increased 60 per cent, with bundled gift sets up 125 per cent.

    Catalogue Scale and Fast Fulfilment

    To capture demand, Myntra added more than 30 Korean brands over the past 12 months, taking its K-Beauty catalogue past 1,000 stock keeping units across 90 labels. Platform searches for Korean skincare and cosmetics rose more than 300 per cent over the same period.

    Direct-to-consumer brands are also taking market share. The platform’s domestic portfolio covers 700 dedicated D2C brands and 3,000 emerging labels, with the segment growing 68 per cent in the current fiscal year. Gen Z shoppers proved 25 per cent more likely to purchase an indigenous or D2C product than older demographics.

    Speed of delivery is becoming a decisive channel differentiator. The marketplace’s quick-commerce arm, M-Now, stocks roughly 600 beauty brands, including 107 foreign labels. The rapid delivery service recorded its peak order value at Rs 61,750, with beauty volumes concentrating heavily between 11 am and 2 pm.

    Room for Market Growth

    India’s overall beauty and personal care market is projected to expand from $23 billion to $40 billion over the medium term. Annual per-capita spending on beauty in India stands at approximately $15, compared with $38 in China and $383 in the United States.

    For multi-brand retailers and beauty platforms, the immediate battle lies in capturing younger consumers outside the major metropolitan areas before regional retail chains or dedicated beauty specialists establish physical footprints there. Brand discovery has largely shifted to social channels, where Myntra maintains an active roster of 82,000 beauty creators and saw user-generated content increase 40 per cent year on year.

    Myntra is targeting M-Now to fulfill more than 50 per cent of total beauty order volume in cities where the rapid delivery service currently operates.

  • Marketplaces Surpass Specialist Beauty Retailers in Australia as Online Market Nears $2.2B

    Marketplaces Surpass Specialist Beauty Retailers in Australia as Online Market Nears $2.2B

    Marketplaces outpaced Australia’s leading beauty chains online for the first time in late 2025, taking e-commerce sales past the combined total of Mecca, Sephora, Adore Beauty and Chemist Warehouse.

    The shift comes as Australia’s online beauty and personal care market heads toward 47 per cent growth to reach $2.2 billion by 2030, according to Pattern’s State of Beauty & Personal Care in Australian Ecommerce report.

    Amazon Expands Category Grip

    Online marketplaces generated roughly $200 million in Australian beauty sales during the fourth quarter of last year. That total cleared the $199.3 million recorded by Mecca, Sephora, Adore Beauty and Chemist Warehouse combined.

    Amazon drove much of the advance. Its local beauty and personal care turnover rose by $66.7 million year on year, lifting the marketplace operator to a 19.9 per cent share of Australia’s total online beauty spend.

    Shopper intent points to further gains. Pattern found 71 per cent of Australian digital beauty shoppers plan to purchase products on Amazon over the next twelve months, while 43 per cent say they will switch to an alternative brand if their first choice is out of stock.

    Consumers aren’t thinking about a brand’s distribution strategy. They simply expect beauty products to be available through the channels they use, and they’re willing to switch brands for that convenience.

    Fragmented Social Discovery Funnels

    Discovery patterns are pulling shoppers away from traditional storefront browsing. Nearly half of surveyed beauty shoppers reported buying items based on creator recommendations, compared to just 15 per cent across non-beauty retail sectors.

    Instagram and Facebook each shaped purchase intent for 47 per cent of beauty shoppers, followed closely by YouTube and TikTok. Yet discovering an item on social networks rarely results in a direct in-app checkout.

    Instead, 39 per cent of buyers who spot products on social feeds complete their transactions on standalone retailer or brand websites. Another 32 per cent head directly to Amazon to finish the order.

    Algorithmic Search and AI Assistants

    Artificial intelligence assistants are now actively routing consumer purchase paths. The data shows 38 per cent of Australian beauty shoppers use AI tools more frequently than they did last year to search for products online.

    Roughly 27 per cent of consumers have relied on ChatGPT or comparable conversational tools to research or buy cosmetics, and 55 per cent express confidence in AI-generated product advice. Global beauty conglomerates are taking notice: Estée Lauder Companies recently partnered with marketing startup Profound to optimize brand visibility across generative platforms including ChatGPT and Google Gemini.

    What the Shift Means for Specialty Retail

    For dedicated beauty retailers, the loss of market share to general merchandise marketplaces threatens the high-margin basket sizes that have long supported domestic store networks. Department stores and specialty chains can no longer rely on exclusive supplier arrangements to protect digital footfall when marketplace logistics offer faster shipping and lower barriers to checkout.

    Brand owners face an equally sharp operational trade-off. Direct-to-consumer storefronts carry heavier customer-acquisition costs as search engines and social platforms shift toward algorithmic discovery, forcing brands to list on Amazon or risk losing sales to competing formulations.

    The critical metric for retailers heading into 2027 will be whether specialist chains can defend their remaining 80 per cent market share as marketplace volume accelerates toward the $2.2 billion category ceiling.

  • Chinese Beauty Accessory Sales Surge Across the United States

    Chinese Beauty Accessory Sales Surge Across the United States

    Sales of Chinese-made beauty accessories are surging across the United States in 2026, according to exporter Joe Wu, as wigs and nails ride a social media boom.

    The export growth comes this week amid a presidential summit shadowed by trade friction over high-profile Chinese shipments of cars and batteries.

    Export hubs in central China

    Production is concentrated in central Chinese hubs like Xuchang, supplying US consumers with pre-bleached straight hair wigs, wavy clipped extensions and coffin-shaped nails.

    “This market is growing,” said Joe Wu, an exporter based in Xuchang. Suppliers in the region are managing steady order books from overseas buyers despite shifting trade patterns in broader commerce.

    Consumer trade outside strategic disputes

    The acceleration in non-strategic consumer goods runs alongside political scrutiny over high-profile Chinese exports such as electric vehicles and industrial batteries. Beauty accessories remain largely separate from those high-level trade disputes.

    Cross-border merchants rely on rapid production cycles to match viral online styling trends. Low tooling costs and deep supply ecosystems allow workshops to switch styles within days.

    Supply chain agility for digital retail

    Online retail platforms continue to compress the timeline between cosmetic trend cycles and factory output. Fast fulfillment models give specialized producers a direct route to Western consumers seeking affordable personal care accessories.

    For independent exporters, small-batch logistics provide steady cash flow while avoiding the inventory risks carried by larger consumer electronics or automotive components.

    Order volumes heading into peak season

    Production facilities in central China are maintaining high output schedules to meet American retail restocking deadlines. Factory managers are tracking platform shipping costs and digital advertising conversion rates closely as seasonal demand builds.

  • Maison Margiela Fragrances Opens First Store at AEON Mall Phnom Penh

    Maison Margiela Fragrances Opens First Store at AEON Mall Phnom Penh

    Maison Margiela Fragrances has opened its first standalone boutique in Cambodia at AEON Mall Phnom Penh this week. The space debuts the brand’s complete Replica perfume collection in the capital.

    It gives the brand a direct retail presence in the country. International beauty houses previously reached local shoppers only through multi-brand counters and cross-border grey channels.

    Replica Portfolio in Phnom Penh

    Inside, the boutique stocks personal scents, scented candles, home diffusers, and bath items. Customers can also use on-site customisation services, including personalised cotton pouch labels and bespoke bottle tags.

    Store staff provide fragrance consultations based on memory-driven scent profiles. That setup mirrors the format used in Bangkok, Singapore, and Seoul flagships.

    Shifting Luxury Footprints in Indochina

    Global beauty groups are testing frontier markets across Southeast Asia as tier-one capitals mature. Rapid shopping centre growth in Phnom Penh over the past five years has provided the climate-controlled, managed floor space needed for direct investments.

    Securing standalone niche fragrance boutiques helps mall operators like AEON lift tenant quality and raise basket values. High-margin fragrance concessions also generate resilient revenue per square metre compared to standard apparel retail.

    Regional Retail Rollout

    L’Oreal’s luxury division, which holds the Maison Margiela beauty licence, has expanded standalone boutiques across Southeast Asia since 2022. The brand opened locations in Thailand, Malaysia, and Vietnam before entering Cambodia.

    Distributors in Phnom Penh previously focused on designer lines from Chanel, Dior, and Gucci. The arrival of dedicated niche fragrance stores reflects shifting demand among younger Cambodian consumers toward artisanal perfumery.

    Store Operations and Next Steps

    Trading on the ground floor, the store is now open seven days a week. Retailers in the capital will watch whether parent operators follow this debut with satellite counters in AEON Mall Sen Sok City or downtown department stores over the next fiscal year.

  • Salon Lane Opens 675-Square-Metre Melbourne Duplex in Victorian Expansion

    Salon Lane Opens 675-Square-Metre Melbourne Duplex in Victorian Expansion

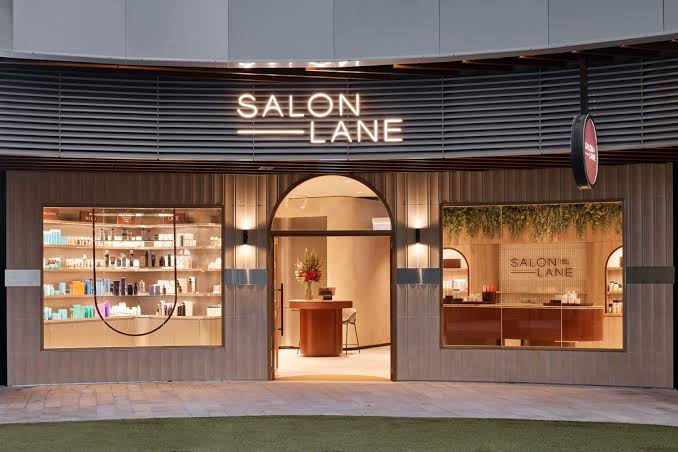
    Salon Lane will open a 675-square-metre duplex at Richmond Square in Melbourne in February. The launch expands the shared salon operator into Victoria.

    Up to 50 independent practitioners will work out of the two-level facility. They cover hair, aesthetics, skin, brows, lashes, wellness and nail care. It is the company’s sixth location nationally.

    Inside the Richmond Square Layout

    The space holds 21 private studios and 14 open workstations alongside specialized service stations. Architecture firm X+O designed the interior layout. The design brings an artistic visual identity tailored to Melbourne’s retail corridor.

    Customer amenities include a dedicated wash lounge, nail and colour stations, a client lounge with a coffee bar, and an on-site retail store. Independent beauty professionals get access to a private member lounge and back-of-house infrastructure. They run autonomous businesses under one roof.

    The Shared Real Estate Model

    Co-working salon hubs alter conventional retail leasing by gathering independent operators into a single anchor tenancy. For commercial landlords, this structure lowers vacancy risk. It replaces individual small-lease negotiations with a single master tenant.

    Commercial pressure falls directly on workstation utilization and tenant retention. Independent practitioners must generate steady foot traffic to cover recurring station costs. At the same time, the operator relies on full occupancy across private suites and open chairs to protect margins.

    Expanding From East Coast Hubs

    Salon Lane built its footprint across five locations in Sydney and Brisbane before committing to Melbourne. This expansion tests whether the shared-space beauty model can duplicate its northern East Coast momentum in a competitive personal care market.

    Doors open at Richmond Square in February for the initial intake of 50 independent operators.

  • Estée Lauder Partners with Profound to Track Brands Across Generative AI

    Estée Lauder Partners with Profound to Track Brands Across Generative AI

    The Estée Lauder Companies has partnered with AI marketing platform Profound to monitor and optimize how its beauty portfolio appears across generative artificial intelligence platforms.

    Earlier this summer, industry leaders highlighted a new visibility battle for beauty brands as consumers increasingly consult 2 leading AI assistants, ChatGPT and Gemini, for product comparisons and personalized beauty advice.

    Through the collaboration, Estée Lauder gains a consolidated view of how its brands are represented across major AI engines worldwide, deploying Profound’s tools to ensure conversational recommendations align with product positioning.

    Tracking Generative Engine Optimization

    Retail marketing is shifting rapidly from search engine optimization to generative engine optimization. Traditional search engines return ranked links based on keywords, indexing and paid placements. Conversational models work differently. They synthesize answers from training data and live retrieval, producing direct recommendations without standard search results.

    Profound co-founder and chief executive James Cadwallader noted that brand owners must actively monitor how algorithmic systems describe their products to shoppers. The software scans model outputs across regions to flag inaccurate claims, missing product lines and unapproved comparisons.

    “The way people discover beauty is being rewritten in real time, and we intend to shape that shift rather than reacting to it,” said Aude Gandon, global chief digital and marketing officer at The Estée Lauder Companies.

    Shifting Digital Spend From Keyword Search

    Beauty conglomerates face higher customer acquisition costs across standard digital channels as retail media networks fragment and search traffic slows. Deploying optimization software lets brand managers identify which datasets feed recommendation models.

    That transition creates operational friction for teams accustomed to bidding on static keywords. Generative models update retrieval patterns frequently. As a result, visibility is harder to predict and measure across regional variations in product nomenclature.

    Dynvibe chief executive Anne-Cécile Guillemot characterized the rise of conversational discovery tools as a new visibility battle for consumer brands. She noted that companies must rebuild how they structure product data and publish ingredient documentation.

    Monitoring Brand Accuracy Across Platforms

    Estée Lauder will direct its portfolio teams to standardize product attributes, clinical claims and application guidance across databases that large language models crawl. The initiative covers the group’s global stable of skincare, makeup, fragrance and hair care labels.

    Consumer adoption of generative search interfaces has spread across North America, Europe and Asia over the past two years. Beauty remains one of the most queried retail categories on conversational platforms. Shoppers frequently seek advice on complex ingredient combinations and personalized skin routines.

    Looking ahead, the two companies will integrate regional language queries into the monitoring platform as AI engines expand local conversational capabilities.

  • Unilever Cuts Beauty Formulation Time to Two Days Using Artificial Intelligence

    Unilever Cuts Beauty Formulation Time to Two Days Using Artificial Intelligence

    Unilever cut product formulation cycles from six days to as little as 24 hours across its beauty division. The shift followed the deployment of predictive artificial intelligence tools across 4,500 research staff.

    The business arm generated EUR 12.8 billion in 2025. That accounted for one-quarter of the consumer goods giant’s global turnover across brands including Pond’s, Dove, Vaseline, Dermalogica and Nutrafol.

    Concept-to-brief design timelines have shrunk to a few days, and scientific claims generation is 75 per cent faster, the group said. In-house systems mine external retail, social media and search data across more than 1,000 sources every month. This tracks beauty trends 60 per cent faster than traditional market research methods.

    Accelerating Lab Work to Shelf

    Products built on these algorithmic models are already selling across mass retail channels. Pond’s Skin Institute Hydra Miracle line uses the company’s Cera-Hyamino formula. It emerged after machine learning models processed 30 terabytes of microbiome data to identify ingredient pairings. A recent Dove hair damage range drew on algorithmic analysis of 100,000 structural hair data points.

    Scientists at the division also cross-reference 150,000 internal research documents accumulated over several decades. Virtual cohorts simulate test outcomes across 2,500 digital subjects before physical trials begin. To embed the workflow, the company ran internal AI training programs for more than 40,000 employees worldwide.

    Today, AI plays a role across the entire innovation journey: from understanding emerging consumer needs to scientific discovery and product validation.

    Compressing Mass Market Timelines

    Speed matters in Asian beauty aisles. Agile domestic brands in China, South Korea and Southeast Asia regularly take new personal care concepts from idea to retail checkout in under four months. Legacy multinationals traditionally operated on multi-year development cycles. That left them flat-footed when ingredient fads or application formats caught fire on social platforms.

    Linking live social sentiment directly to formulation labs is Unilever’s strategy to close that speed gap. The company used that mechanism for its Vaseline Originals expansion, turning viral social media beauty hacks into packaged products sold via TikTok Live, including specialized jelly primers and brow cosmetics. The operational risk shifts downstream. Accelerating formulation does little if contract packaging and regional supply chains cannot scale production at the same pace.

    The Multi-Year Data Pivot

    This deployment builds on multi-year investments in consumer data infrastructure and algorithmic ingredient modeling. Unilever reorganized its corporate structure into five category-focused business groups in 2022, isolating Beauty & Wellbeing to give it dedicated research budgets and faster commercial clearance.

    Competitors like L’Oreal and Procter & Gamble have made parallel investments in skin diagnostics and automated chemistry labs across the region. The race now turns on whether predictive formulation translates into durable repeat purchases or merely floods store shelves with short-lived trend products.

    Unilever is currently testing predictive digital twin models and agentic software across its R&D pipeline. The next slate of AI-designed skincare lines is scheduled for regional retail distribution through 2027.

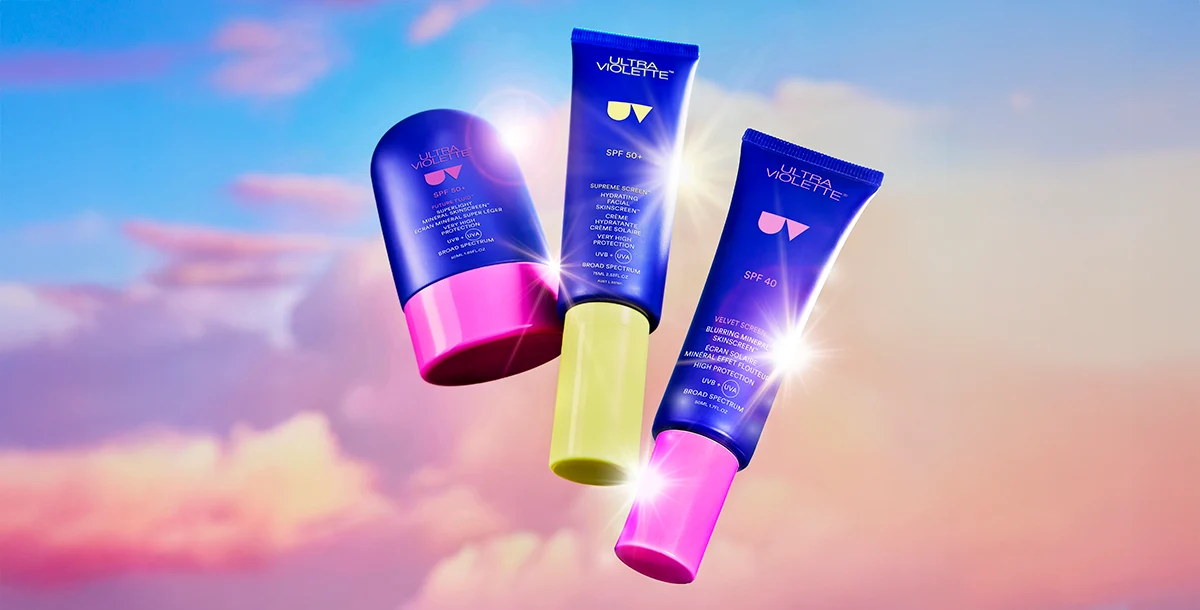
  • Ultra Violette Sues Wild Child Laboratories over SPF 4 Sunscreen

    Ultra Violette Sues Wild Child Laboratories over SPF 4 Sunscreen

    Sunscreen brand Ultra Violette is suing contract manufacturer Wild Child Laboratories following the recall of its SPF50+ sunscreen product, Lean Screen, last year. Testing by consumer advocacy organisation Choice previously found the product had an SPF of only four.

    The dispute centres on a base formula produced by Wild Child Laboratories that was also used by nearly 20 sunscreens from other brands.

    Shared Formulations Create Systemic Risk

    Contract manufacturing lets independent beauty brands scale without building their own factories. When a shared base formula fails laboratory verification, liability cascades across dozens of retail brands. Beauty labels in high-UV Asia-Pacific markets cannot rely on supplier certifications alone. They need rigorous third-party batch testing.

    Retailers stocking private-label and independent suncare lines now face scrutiny over supplier auditing and shelf compliance. The litigation puts direct financial and reputational pressure on third-party laboratories. It forces brand founders to reassess contract terms, indemnity clauses and quality-control oversight at every stage.

    The Timeline Leading to Legal Action

    Legal action follows the recall of Ultra Violette’s Lean Screen sunscreen last year after advocacy group Choice published independent efficacy tests. Those evaluations showed the mineral formula failed mandatory Australian standards for SPF50+ claims. Retailers pulled stock from shelves immediately.

    What to Watch in Court Filings

    Proceedings will examine the manufacturing warranties and testing protocols Wild Child Laboratories maintained during commercial production runs. The case will determine liability for recall expenses, testing costs and brand damages, creating a precedent for contract manufacturing accountability across the regional cosmetics industry.

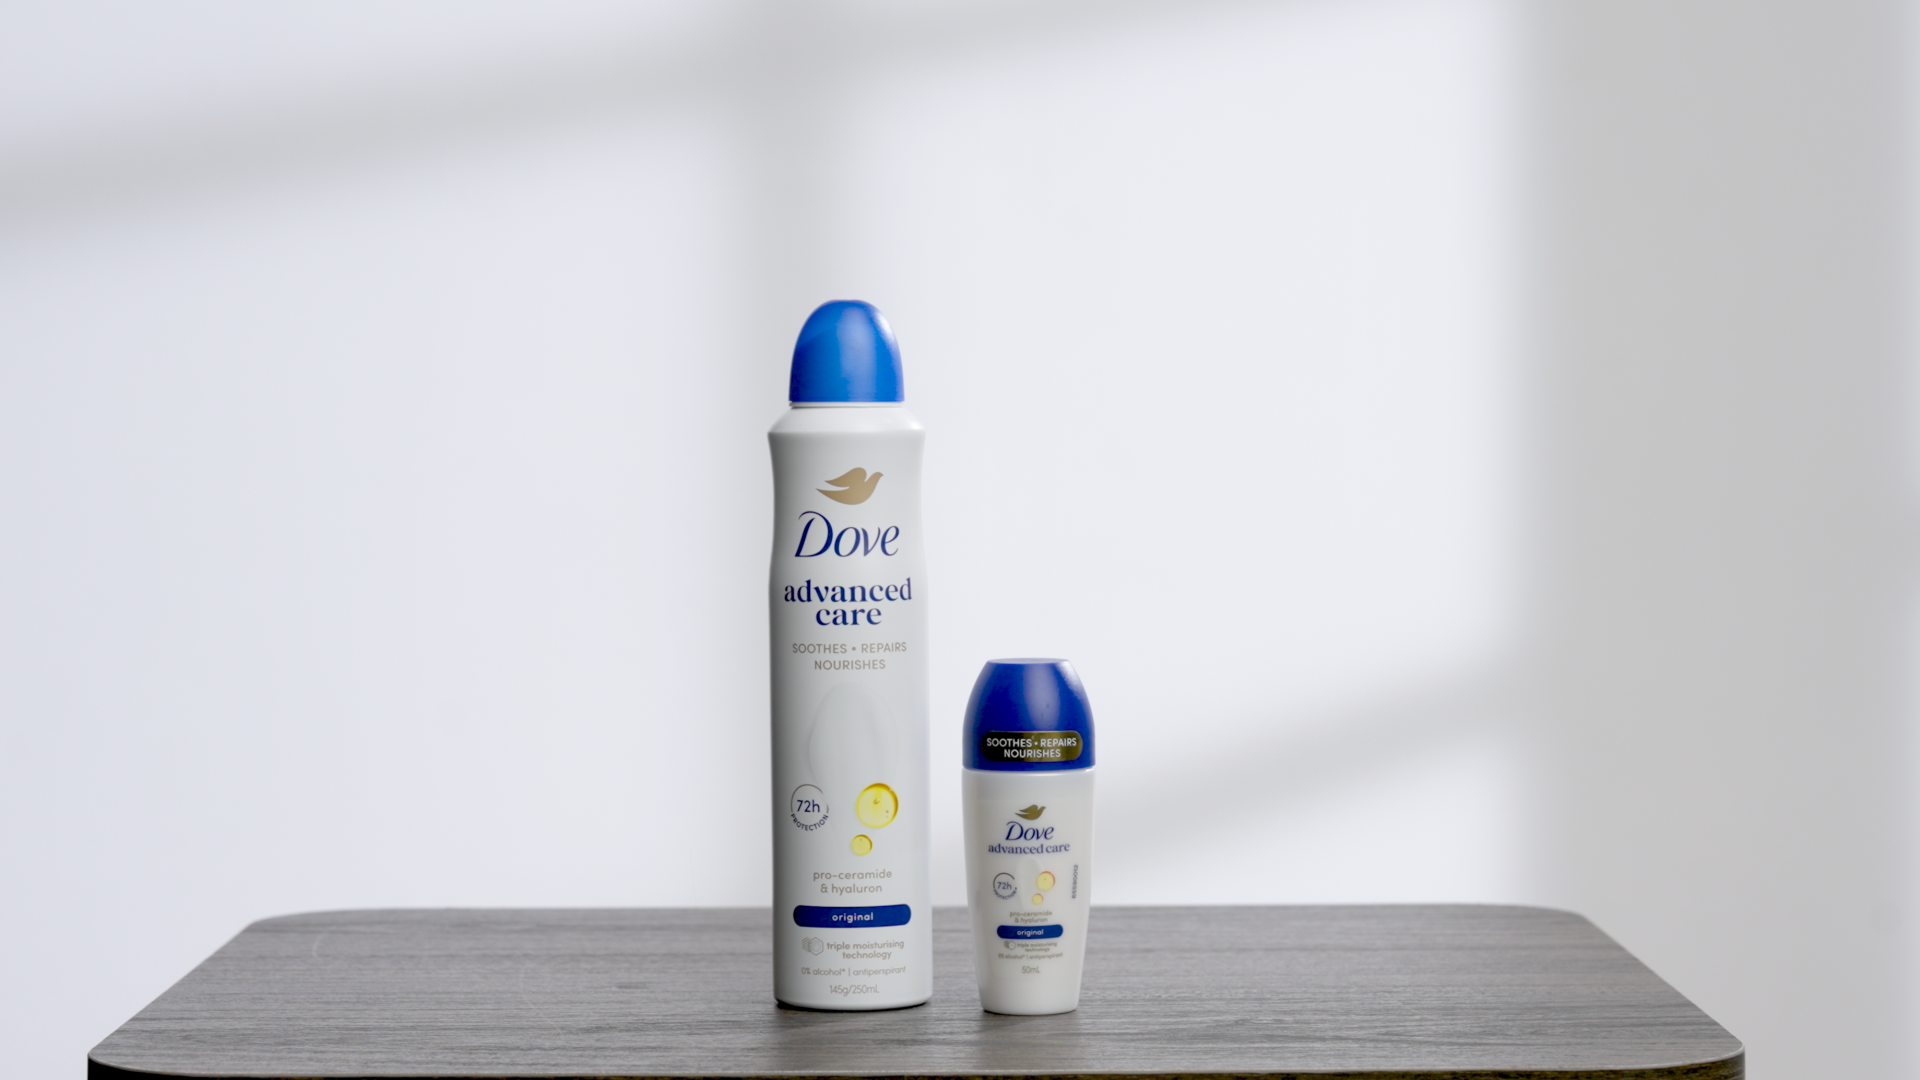
  • Dove Expands Advanced Care Deodorant Range to Six Scents in Australia

    Dove Expands Advanced Care Deodorant Range to Six Scents in Australia

    Dove upgraded its Advanced Care deodorant lineup in Australia in September 2026, adding active skincare ingredients across six distinct fragrance varieties.

    The revamp introduces pro-ceramide serum and hyaluronic acid directly into the brand’s mass-market underarm portfolio, featuring an exclusive scent for independent retailer IGA.

    Skincare Ingredients Enter Daily Deodorants

    Formulations across the refreshed line now blend barrier-repair ingredients typically reserved for facial serums. Pro-ceramide serum works alongside hyaluronic acid to hydrate skin, targeting irritation caused by daily shaving and friction.

    The range spans six fragrances: Original, Pomegranate & Lemon Verbena, Acai Berry & Waterlily, Coconut & Jasmine Flower, Passionfruit & Lemongrass, and Apple & White Tea.

    Retail Distribution and Exclusive Variants

    Supermarket distribution splits the lineup across major national grocers and independent operators. The Apple & White Tea variant sells exclusively through independent IGA stores across the country.

    Channel-exclusive scents give independent operators a defensive shield against major supermarket chains. Tier-one grocers take the core five variants, while IGA uses the exclusive fragrance to drive foot traffic into its personal care aisles.

    Shifting Formulations on Supermarket Shelves

    Personal care manufacturers across the region continue migrating premium skincare ingredients down into high-volume grocery categories. Adding active hydrators allows everyday consumer brands to protect shelf space against specialty pharmacy competitors.

    Retail buyers are watching whether functional skincare claims can lift basket values in basic grocery aisles as shoppers manage everyday household budgets.