Tag: crypto

  • How much do you need to begin investing in crypto?

    How much do you need to begin investing in crypto?

    So far, 2021 has been the year of cryptocurrencies. With Bitcoin smashing through the previous record to reach an all-time high of £42,000 ($58,000) and firms such as Tesla now investing, it appears that there has never been a better time to jump on board and start investing in crypto. Of course, while Bitcoin may be the most well-known cryptocurrency it is by no means the only one. Alongside this, there is also the likes of Ethereum, Litecoin, and Cardano to consider. Even looking at these additional cryptos is only touching the tip of the iceberg as there are literally thousands of them in existence.

    With all of the media coverage of crypto and what this year has seen, now may be the time that you are considering investing. If you are unfamiliar with crypto terms such as algorithmic peg, altcoin, and bag there is a good chance that you may need to invest in some education before taking the plunge, but here’s a look at some of the key points that you’ll need to know.

    What is Crypto?

    Before considering how much you need to start investing, it is important to understand what crypto is and, just as importantly what it isn’t. Cryptocurrencies are digital currencies that exist online and in secure wallets. They can be used to buy goods and services, but more importantly, they can also be traded for profit.

    Crypto works by using blockchain technology. This is a decentralised computer system that keeps information extremely secure. The fact that crypto is decentralised also means that no government or single person controls it. This means that, although values can change, it is not susceptible to world events like a traditional currency is.

    What are the most popular cryptocurrencies?

    When it comes to considering investing in cryptocurrency, it is worth taking a look at what are the most popular. With so many in existence, it is easy to get lost in a sea of names and not really be sure what you are investing in. The most popular cryptos to invest in are:

    Bitcoin

    The open-source software for Bitcoin was released in 2009. The person behind this is only known as Satoshi Nakamoto and has never had his real identity confirmed. The first time that Bitcoin was used was to purchase a pizza, but since then it has gone on to achieve incredible values and is now even accepted as a method of payment by PayPal, showing that it is now truly mainstream.

    Ethereum

    The work of Vitalik Buterin saw Ethereum being launched in 2015. At the time of release, there were 72 million coins made available. Although not reaching the heights of Bitcoin, it still has a respectable all-time high of £1,239 ($1,700).

    Litecoin

    The creator behind Litecoin was Charlie Lee who founded this in 2011. Going live in 2013, this crypto works in an almost identical way to Bitcoin although the technology allows for faster confirmation of transactions. Its all-time high was £262 ($360).

    How can I invest in crypto?

    To invest in cryptocurrencies, you are going to need somewhere to buy it and then somewhere to keep it. This is where exchanges come into play. The most common of these is Coinbase. Here you can buy Bitcoin and Ethereum with your debit card. For other cryptos, you generally need to trade Bitcoin and Ethereum and can not use traditional currencies to buy them.

    Given the high values of these currencies, investing may seem unobtainable for many. The good news is that you do not need to purchase an entire Bitcoin. Exchanges allow you to purchase fractions of cryptocurrencies which makes investing accessible for everyone. Potential new investors should not be intimidated by the rising values. Instead, this should be taken advantage of by using fractional options which remove any barriers to entry.
     

  • New Ripple Acquisition to Enhance Cross-Border Payments in APAC

    New Ripple Acquisition to Enhance Cross-Border Payments in APAC

    Its investment in an Asia-focused cross-border payments specialist aims to address challenges associated with cross-border payments in Southeast Asia’s fragmented payments landscape.

    Ripple has acquired a 40-percent stake in Tranglo, which will allow the blockchain payments company to meet growing customer demand in the region and expand the reach of on-demand liquidity (ODL), the company announced on Tuesday.

    ODL uses digital asset XRP to send money instantly. As Ripple broadens its regional footprint, RippleNet customers using ODL will be able to leverage Ripple’s line of credit to free up working capital and scale cross-border payments into more markets, the announcement said.

    Southeast Asia is the fastest-growing region for RippleNet adoption, according to the company. Tranglo will play a «critical role» in supporting existing corridors, such as the Philippines, and introducing new ODL corridors within its current network.

    Founded in Malaysia in 2008, Tranglo operates a cross-border payment hub that provides smart services for mobile airtime top-ups, as well as foreign remittance and business payments.

    Following the completion of the transaction, which is expected later this year, Amir Sarhangi, VP of product and delivery at Ripple and Brooks Entwistle, the company’s new regional managing director, will join Tranglo’s board of directors. TNG Fintech Group will remain the majority shareholder in Tranglo.

  • BNY Mellon Invests in Crypto Storage Firm

    BNY Mellon Invests in Crypto Storage Firm

    BNY Mellon will further its inroads into the digital asset market with its latest investment into crypto storage firm Fireblocks.

    The world’s largest custodian bank was part of the latest funding round for Fireblocks which raised a total of $133 million, according to a statement.

    In addition to strategic investments from BNY Mellon and Silicon Valley Bank, other participants of the funding round include hedge fund Coatue Management, investment firm Ribbit Capital, growth equity firm Stripes and SVB Capital. Existing investors including Paradigm, Galaxy Digital and Swisscom Ventures also participated in the round.

    To date, Fireblocks has raised $179 million and according to a report citing unnamed sources, the latest funding round values the firm at nearly $1 billion.

    Currently, Fireblocks has a presence in Europe, North America and Asia with a wide range of clients including banks, neobanks, exchanges, hedge funds and market makers. Within Asia, it has over 35 clients including Hong Kong-based crypto financier Amber Group and Singapore-based hedge fund manager Three Arrows.

    Over the past three years, clients have entrusted Fireblocks to secure more than $400 billion in assets.

    «Fintechs and banks require not only a specialized custody and settlement infrastructure to ensure customer funds are safely managed, but a platform that enables new lines of digital offerings,” said Fireblocks CEO Michael Shaulov. «While we have no plans to become a bank, we believe our infrastructure will lend itself perfectly to power an entirely new era of financial services.»

  • ApplePay will now allow users to make purchases using Bitcoin

    ApplePay will now allow users to make purchases using Bitcoin

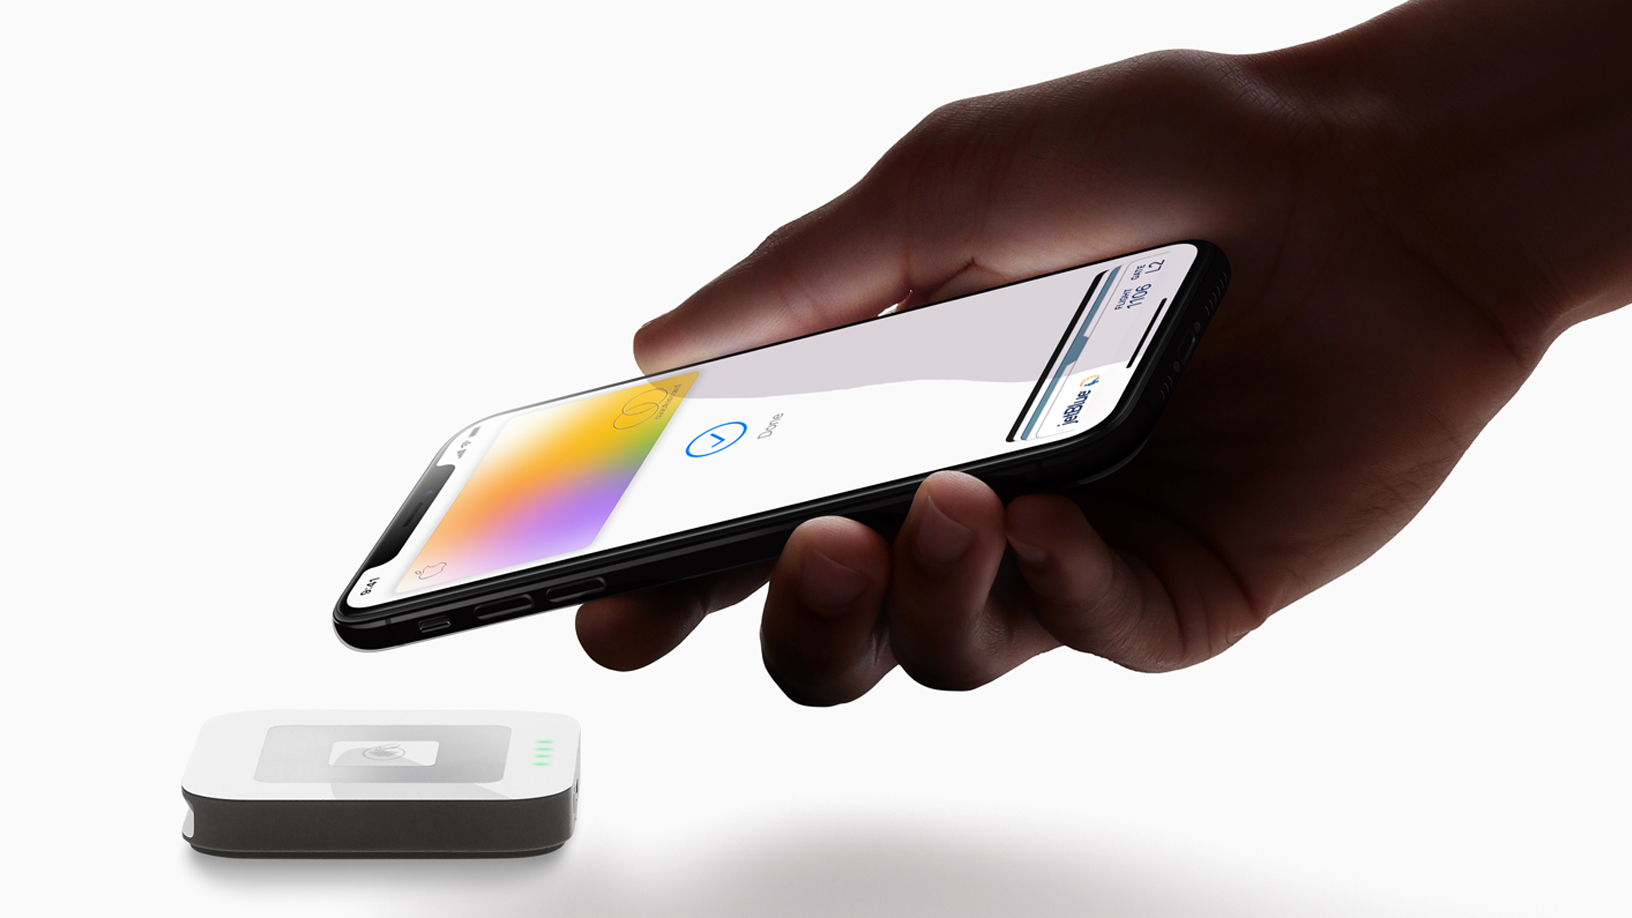
    Bitcoin is still the most famous cryptocurrency. And at Friday’s close, each Bitcoin was valued at close to $48,000, more than double the valuation of the digital currency about a year ago. Not only can you buy more with your Bitcoins, but you can also find it easier to spend thanks to the Apple Pay mobile payment service. The BitPay wallet app’s Prepaid Mastercard can be added to the Apple Wallet and Apple Pay can help Bitcoin owners spend the cryptocurrency online, through apps or in a store.

    The BitPay wallet app not only works with Bitcoin, but will also work with Ether, Bitcoin Cash and as well as the dollar-pegged stable coins USD Coin, Gemini Dollar, Paxos Standard and Binance USD. The stable coins are based on a 1:1 ratio with the U.S. Dollar. For every Gemini Dollar in circulation, there is a corresponding U.S. Dollar held by the State Street Bank and Trust Company.

    There are plans in the work to add support for the BitPay Wallet by the end of next month with other mobile payment services Google Pay and Samsung Pay. This will allow Android users to more easily spend Bitcoins and other cryptocurrencies including the aforementioned names that are pegged to the U.S. Dollar.

    To add your BitPaycard to Apple Wallet, you need to have the latest version of the BitPay app. The latter, which can help you securely store, spend, and manage Bitcoin, can be installed from the App Store and the Google Play Store. BitPay CEO Stephen Pair (both of him) said, “We have thousands of BitPay Wallet app customers using the BitPay Card. Adding Apple Pay and soon Google and Samsung Pay makes it easy and convenient to use the BitPay Card in more places.”

    Apple should do even more when it comes to digital currencies; should Apple add a cryptocurrency exchange it could generate over $40 billion. RBC analyst Mitch Steves believes that this would allow Apple’s shares to rise 25%. RBC noted that “Square takes in $1.6 billion a quarter through bitcoin-trading revenue from its roughly 30 million active users. Apple has an install base of about 1.5 billion people, signaling that it could make up to $40 billion a year from a Wallet-based crypto exchange.” The report adds that “if Apple went down this path, the USA would likely acquire the most crypto assets from a global perspective. If the USA owns the most crypto assets (be it Bitcoin or other assets), it would not make logical sense in our view to ban it. In addition, with Apple’s secure and world-class software, the USA would be able to have confidence in user information and balances if needed in the future.”

    Apple’s big move comes right after Tesla CEO Elon Musk showed interest in cryptocurrency Dogecoin. Tesla says that it soon will accept Bitcoins as payment toward the purchase of a Tesla vehicle. RBC’s Steves notes that the combination of Apple’s interest in Bitcoin and Apple’s popularity in the tech world can help the U.S. become the technological leader in cryptocurrencies for as long as the next 20 years.

    Thanks to the Blockchain technology, the method used to keep track of Bitcoin transactions, using the cryptocurrency is secure. Data on transactions is kept inside blocks and when a block is full, it is chained to the previous one. If someone wants to steal Bitcoin and hacks into the Blockchain to alter the information in one the blocks, it can’t be done without all members of the Blockchain spotting the changes. There are smartphones that can store and verify cryptocurrency transactions such as the HTC Exodus 1s.

  • Crypto Firm Nabs Ex-HSBC Banker as CEO

    Crypto Firm Nabs Ex-HSBC Banker as CEO

    A British banker is taking over the top job at Valour, a Swiss start-up that plans to expand a zero-fee bitcoin exchange-traded product across Europe.

    Zug-based Valour is naming Diana Biggs as its CEO, effective immediately, it said in a statement. She is the former chief of innovation at HSBC’s private banking unit and a cryptocurrency backer of the earliest hour.

    Biggs is the latest banker to leave traditional finance for digital assets, which is a booming industry in Switzerland thanks to friendly regulatory handling. Diana is the perfect candidate to lead the company through this next phase of growth and expansion, Valour founder Johan Wattenstrom said.

    Founded three years ago, Valour in December launched a fee-less digital asset product that trades on the Nordic exchange’s growth index, NGM. The start-up manages nearly $30 million and plans to roll out more exchange-traded notes at other European venues in the coming months.

    At HSBC, Biggs led fintech partnerships and championed open innovation. Prior to joining the British bank, she worked for digital currency platform Uphold, e-commerce startup Soko, and spent nearly five years as a consultant at Oliver Wyman.

  • India Proposes Crypto Ban and E-Rupee Plans

    India Proposes Crypto Ban and E-Rupee Plans

    Indian authorities plan to propose a new law to ban private cryptocurrencies and implement a framework for an official central bank digital currency.

    India will seek «to prohibit all private cryptocurrencies in India», according to a legislative agenda published by the lower house’s website on Friday last wee, with exceptions for certain purposes such as the promotion of the underlying technology and its uses.

    In addition, lawmakers will look to «create a facilitative framework for the creation of the official digital currency to be issued by the Reserve Bank of India (RBI).

    Not unlike other central banks, the RBI has been accelerating efforts to launch its own electronic money and tighten regulation against cryptocurrencies. It first issued an order in April 2018 to cut ties with all individuals or businesses dealing in digital currencies like Bitcoins within three months.

    But India’s Supreme Court subsequently overturned the ban by allowing banks to handle crypto transactions from exchanges and traders.

    The pushback reflects broader shifts in sentiments worldwide, particularly amongst banks that have been demonstrating increasing openness to cryptocurrencies.

  • Forgotten Passwords: $140 Billion Bitcoin Write-Off?

    Forgotten Passwords: $140 Billion Bitcoin Write-Off?

    Nearly $140 billion worth of Bitcoins is at risk of being permanently lost, according to online platform Chainalysis, due to forgotten passwords for decryption.

    3.7 million Bitcoins worth almost $140 billion could permanently vanish from the market, as of January 18 this year.

    Based on June 2020 figures, this represents around one-fifth of the total 18.6 million Bitcoins created in the market. Bitcoin’s infrastructure is designed to cap supply at 21 million.

    German-born San Francisco-based programmer Stefan Thomas first shined a light on the issue after he revealed that he failed to gain access to his crypto wallet to access over more than $200 million worth of Bitcoin.

    Thomas had already made eight successful attempts and he has two more remaining to save his sizeable Bitcoin holdings.

    I would just lay in bed and think about it. Then I would go to the computer with some new strategy, and it wouldn’t work, and I would be desperate again, he recalls. I got to a point where I said to myself, ‘Let it be in the past, just for your own mental health.

  • Singapore Tightens Oversight of Crypto Exchanges

    Singapore Tightens Oversight of Crypto Exchanges

    MAS powers have been expanded to include regulatory measures on crypto service providers, even if they may not possess the money or cryptocurrency involved.

    The Monetary Authority of Singapore (MAS) is enhancing its regulatory framework and updating the Payment Services Act to keep pace with changes to international standards and to better mitigate the money laundering and terrorism financing related to digital payment tokens.

    Any entity that facilitates the transmission, exchange or storage of DPTs – also known as cryptocurrencies – will now have to be licensed, MAS said on Monday.

    The new legislation will help minimize the risk of DPT service providers being exploited by criminals to launder illicit proceeds or hide illicit assets, said Minister for Transport Ong Ye Kung, who is also a board member of MAS, during the second reading of the Payment Services (Amendment) Bill in Parliament on Monday.

    The amendments also give MAS powers to impose measures on DPT service providers to ensure better consumer protection and to maintain financial stability and safeguard the efficacy of monetary policy.

    We have seen recent development of new forms of DPTs which values are pegged to stable assets to gain users’ confidence. It is therefore important for MAS to be able to respond to market developments and address new risks in a timely manner, MAS said.

    The Payment Services Act, which was introduced in January 2020, provides comprehensive regulation for companies handling activities ranging from digital payments to the trading of tokens such as bitcoin and ethereum, and gives MAS formal supervisory powers for cybersecurity risks and controls on money laundering and terrorism financing.

  • Crypto Rumbles Central Bank Sovereignty

    Crypto Rumbles Central Bank Sovereignty

    The private sector has long driven innovation on digital currencies but as fintech’s plans became more powerful, central banks sprang to attention. Their main concern? Keeping monetary policy in their purview.

    The most tantalizing tales in cryptocurrencies this year weren’t written by Libra or bitcoin, but by national or supranational projects like the digital euro. While investors raced to get in on bitcoin’s record-smashing highs, the government projects warrant a closer look.

    What central banks are trying to do is replace the storage carrier of money with a new one – cloud instead of long-play (LP), so to speak. The aim is to kill several birds with one stone.

    The first is to stave off a private sector-led attack on central bank sovereignty. The second is enabling efficiencies in the financial system, and the third is to lay a foundation for seamless oversight of monetary transactions.

    Taken in turn: a central bank ensures financial stability while overseeing systemically-relevant market infrastructure. To hand over a central instrument in its arsenal is to jeopardize its own mandate. Replacing a country’s own currency with another – which frequently happens in unstable countries, where dollars effectively become the leading currency – is a good example, or when a privately-controlled alternative takes over for reasons of efficiency.

    Admittedly, crypto is far from this scenario, but the thought experiment is a worthwhile one. We need to assume that multinational companies like Amazon or Alibaba will in future control and executive an enormous portion of private consumption: they own the value chain, from manufacturer to end consumer. They are intimately familiar with customer needs and aren’t shy about cultivating the data with the help of artificial intelligence.

    The next logical step in cementing this position is to introduce their own currency. This would dramatically simplify the purchasing process as well as create a vast common currency area spanning producer, commercial dealer, suppliers, to consumers.

    None of this is a problem as long as employees are paid in U.S. dollars, euros, or krona and use a major currency to buy a trading one. But if they are, for example, partly paid in Amazonas or Alibabas, central banks cede part of their authority to the private sector. The initial hostile official response to Libra is the logical consequence of this.

    The Swiss central bank’s «Project Helvetia» as part of the BIS’ innovation hub sidesteps the first question in favor of tackling the second, central digital revolution issue. Traditional banks are still grappling with the conversion to digital banking: continually under siege from newer upstarts without any historical baggage and far zippier organizations.

    The Swiss National Bank’s digital franc is meant to enable efficiency gains and simplify monetary transactions. This is a much more defensive strategy than other central banks have elected – notably the European Central Bank, Sweden’s Riksbank, or the People’s Bank of China – but the pragmatic approach fits the Swiss system of thinking well.

    In lockstep with infrastructure provider SIX, which belongs to the banks, genuine and measurable advances would represent a great step towards a digital future. The Swiss stock exchange operator plans to go live with its digital asset trading venue, SDX, next year. A digital Swiss franc would suit the SNB’s financial intermediaries perfectly.

    Switzerland is hardly ready for the third and conclusive step: a digital version of cash is being actively discussed elsewhere (namely in Sweden and China). Some aspects of digital money – efficiency versus cash and crucially, the traceability of transactions – are too tempting to resist.

    Of course, all types of criminals could be disrupted in their activities with such a step. But the accompanying supervision of citizens contradicts Switzerland’s understanding of government and privacy – and should be rejected. The complete replacement of cash in Europe and the U.S. isn’t on the horizon either for the same reasons, even if digital money eventually will find a niche besides paper.

    Despite the rapid advancement of the topic in recent months, we’re still at the dawn of developments. 2021 is sure to bring promising new developments, and the ECB is likely to devote considerable resources to rolling out a digital euro (or ultimately spike the project).

    In Switzerland, SDX and «Project Helvetia» are poised to take their next steps. The U.S. has been noticeably absent in the discussion, though January’s change in administration may mark a new tack in digital assets.

  • Hong Kong’s First Licensed Crypto Platform Goes Live

    Hong Kong’s First Licensed Crypto Platform Goes Live

    Just one week after Singapore saw its first mainstream crypto foray by DBS, Hong Kong mirrors the city-state’s move by issuing a license to BC Technology Group’s OSL Digital Securities.

    The Securities and Futures Commission (SFC) has issued a Type 1 (dealing in securities) and Type 7 (automated trading services) license to OSL, according to a statement, making it the first licensed digital asset platform in the city.

    The platform will provide prime brokerage, custody, exchange and other services for Bitcoin, Ethereum and other cryptocurrencies alongside select security token offerings.

    In addition, OSL also has insured digital asset wallets and an audited digital asset trading platform aimed at institutions and professional investors.

    Following the local government’s call to ban retail investor access, Hong Kong’s crypto market will be focused on institutional and professional investors, those deemed as high net worth individuals (HNWI) with some market knowledge and experience.

    Institutional investment in Bitcoin and other digital assets has rapidly accelerated over the past several years, and has entered a new era of growth in Hong Kong with licensing,” said OSL chief executive Wayne Trench.

    Following in the footsteps of DBS, OSL has also already applied for a digital asset licensed with the Monetary Authority of Singapore under the Payment Services Act.

    Licensed entities are the future of digital assets and capital markets in the digital age and professional investors, hedge funds and family offices are now rapidly increasing portfolio allocations to digital assets such as Bitcoin,» added OSL head of distribution and prime Matt Long.

    According to the statement, the OSL digital asset platform business saw a 47 percent year-on-year revenue increase in the first six months of 2020, driven in part by record-high trading volumes of $28 billion.

  • Libra Set to Launch in Early 2021

    Libra Set to Launch in Early 2021

    The Libra coin may finally launch early next year, but in a slimmed-down version. Which of the original promises will be kept with such a watered-down coin?

    When the Libra Association first went public with its project, the coin was based on a broad basket of currencies. When governments, regulators, and central banks made abundantly clear that they were opposed to such a coin, the Geneva-based association reduced the reach to include several major currencies. Now, the launch seems imminent, but the coin will be based on the dollar only.

    The association, which was founded by Facebook, plans to launch its coin at the beginning of 2021. The story was based on information provided by three people.

    However, even this slimmed-down version of a Libra coin depends on the approval of Finma, the Swiss financial market regulator. Finma refused to comment on Libra’s plans. One can safely say that Finma won’t take any risks given the global attention paid to the plans of Libra.

    The authorities have to ensure that coins such as Libra won’t make it easier for criminals to wash their ill-gotten gains. In other words, the project sponsors must make sure that they adhere to the same strict standards set by money-laundering laws as any other financial-service provider.

    And, what’s more, the idea of a multinational coin may impact the ability of central banks to enforce their monetary policy. The latest version of a slimmed-down Libra may indeed allay such worries.

    But of course, what is the purpose of a single-currency coin? The Libra was an attractive proposition because it promised an easy digital payment system for all: The Libra payment system is built on blockchain technology to enable the open, instant, and low-cost movement of money. People will be able to send, receive, and spend their money, enabling a more inclusive global financial system. Will a dollar-based Libra be of any use to a consumer in the euro-region for instance?

    The private initiatives for digital currencies need to be seen in the context of state-sponsored projects. Some central banks have forcefully advanced their own projects for digital central bank currencies. Including the Swedish and Chinese, while the European Central Bank (ECB) recently made clear that it also aimed to speed up the process.

    The Swiss National Bank (SNB) is also working on a digital currency in the context of the innovation hub with the Bank for International Settlements (BIS). This digital franc project will be presented on December 3, according to people familiar with the plan.

  • Hong Kong and Singapore Split on Crypto Future

    Hong Kong and Singapore Split on Crypto Future

    Asia’s two marquee global financial hubs have hit a fork in the road of crypto assets and they appear to be heading in different directions.

    Last year, the local chief securities watchdog, Ashley Alder, also chose the FinTech Week to reveal a so-called «opt-in» regime for crypto asset trading platforms, which allowed operators to choose whether or not they wanted to be regulated by the Securities and Futures Commission (SFC). This was due to the fact that some crypto assets cannot be strictly classified as securities.

    This is about to change, Alder said earlier this week, also during the FinTech Week.

    Today, the Government proposed a new licensing regime under the Anti-Money Laundering Ordinance for platforms that trade any type of crypto-asset, even if none are classified as securities. So if they are operating in Hong Kong, or target Hong Kong investors, they would need to apply for an SFC license. Failure to do so would be an offense.

    In addition to licensing, the proposed rules will also ban retail investors from trading crypto assets, limiting access to professional investors which includes the requirement to have a minimum of $1 million.

    Given the risks involved, the proposal is that they should offer their services to professional investors only, at least initially, Alder said.

    Simply speaking, we will require all virtual asset trading platforms to be operating transparently, like working under the sunlight, added Christopher Hui Ching-yu, Hong Kong’s secretary for financial services and the treasury.

    Meanwhile, Singapore continues to take a liberal approach to allow operators to develop more freely and organically.

    Although there were moments when the Monetary Authority of Singapore (MAS) stepped in to rein in on the market – in 2018 it returned funds to Singapore-based investors of an unnamed initial coin offering (ICO) which it considered a security – the regulator has yet to issue licenses to operators nor has it taken a strict stance, unlike Hong Kong, on crypto assets that aren’t classified as securities.

    Even major exchanges like Coinbase and Binance operate in the city-state and have been granted temporary exemptions from holding a license.

    MAS: Investor Responsibility

    On investor protection, Hong Kong authorities made the choice to decide for retail investors when or if access would be appropriate. This is an area where the MAS has also taken a decidedly different route, preferring to promote investor responsibility while encouraging more education and prudence.

    In fact, the MAS’ Capital Markets assistant managing director Lee Boon Ngiap provided a simple and straightforward warning: The public should be aware that there is no regulatory safeguard if they choose to trade on unregulated digital token exchanges or invest in digital tokens that fall outside of the remit of MAS rules.

    And under the MAS’ regulatory, Singapore has rapidly emerged as a global leader in the crypto asset industry.

    It is currently home to 234 entities involved in blockchain including Mastercard, VISA, Ant Financial, Tencent-backed WeBank, Facebook-backed Libra, and more with Ripple now shortlisting the city-state for its headquarter relocation. Even Singapore’s largest lender, DBS, is reportedly cooperating with regulators to potentially launch a cryptocurrency trading with retail access.

    The subsequent outcome has been the rapid establishment of Singapore as a global crypto market leader. Despite having a population of just 6 million, Singapore is second worldwide in the number of ICOs and ICO value ($2.5 billion), according to data from ICObench, only behind the U.S.

  • DBS Mulls Crypto Exchange Launch

    DBS Mulls Crypto Exchange Launch

    DBS’ plans for a digital exchange are still work in process, and have not received regulatory approvals. Until such time as approvals are in place, no further announcements will be made. DBS is planning to launch a crypto exchange that will allow four digital currencies – Bitcoin, Bitcoin Cash, Etheerum, and Ripple – to trade against the Singapore dollar, Hong Kong dollar, Japanese yen or U.S. dollar, according to a report by digital asset media firm The Block. 

    Dubbed DBS Digital Exchange, the initiative was first unveiled through a website seen by The Block which cached the now removed website.

    Regulated by the Monetary Authority of Singapore, the crypt exchange will be made accessible to institutional investors, including financial institutions and market makers. Retail investors will have access via DBS entities like their securities or private banking arm.

    While most exchanges can execute orders at any time and any day, DBS will similarly follow the same trading hours as stock exchanges, allowing for less than seven hours per day, according to the report.

    In addition to standard trading, the bank will also provide institutional-grade custody solutions for safekeeping digital assets and, in due time, conduct security token offerings to help small and medium-sized firms raise funds.

    Digital assets are poised to be the future of tomorrow’s digital economy, the website originally read.

    With DBS Digital Exchange, a bank-backed digital exchange, companies, and investors can now leverage an integrated ecosystem of solutions to tap the vast potential of private markets and digital currencies.

  • Crypto Finance Opens Singapore Branch

    Crypto Finance Opens Singapore Branch

    Swiss digital investment specialist Crypto Finance has opened a branch in the Lion City. The company sees itself as a provider of services to the banking industry.

    Crypto Finance’s representative office in Singapore opens this month and will be led by the head of Asia, Alisher Tashpulatov, according to a media release on Wednesday.

    Tashpulatov previously worked in the crypto fund business of the firm and was involved in getting a license from the Swiss regulator as a crypto wealth manager. He then opened its Hong Kong office. He is being backed up by the crypto finance team, which has several team members with Asian experience, for instance, CEO and founder Jan Brzezek.

    The Zurich-based group will serve the demand for digital asset products and services, and attempt to bridge the gap between traditional banks and the crypto market.

    I believe that the Singaporean and Swiss business environment and orientation share many characteristics, including respect for diverse cultures and a work ethic that values merit, excellence, self-reliance, and hard work. The two countries share a great rapport, and it is almost intuitive for us as a Swiss business to establish ourselves in a like-minded and innovative country like Singapore, Tashpulatov said.

    Having spent years conquering new frontiers and climbing new peaks within the Swiss market, I am now happy to make a transition into a new, yet familiar, land, he added.

    Crypto Finance’s current activities in Singapore are focused on the areas of business that do not require regulatory supervision, and the firm plans to launch best-fit models of its offering in other Asian business hubs in the near future.

  • Hong Kong To Issue First-Ever Crypto Exchange License

    Hong Kong To Issue First-Ever Crypto Exchange License

    Hong Kong’s Securities and Futures Commission is en route to issue the city’s first-ever license to a cryptocurrency firm.

    OSL Digital Securities – a unit within Fidelity-backed BC Group – said that Hong Kong’s securities regulator has agreed in principle to issue a license, according to exchange filings.

    According to BC Group chief executive Hugh Madden, the license will help increase ease of doing business by being able to engage other regulated entities. Final approval is subject to certain conditions, the filing added without providing details.

    In addition to the cryptocurrency business where it generates the majority of its revenue, BC Group also provides business park and advertising services. In the first half of 2020, it posted a net loss of 90.8 million yuan ($13.1 million).