Tag: Fashion

  • LVMH and Prada Shares Trade at Deep Discount to Zara and H&M

    LVMH and Prada Shares Trade at Deep Discount to Zara and H&M

    Shares in luxury powerhouses LVMH and Prada traded at an unusually deep valuation discount to fast-fashion retailers Zara and H&M in October 2026. Investors hesitated to buy the dip amid growing concern that the luxury sector’s strongest growth period has passed.

    The valuation gap marks a sharp reversal after trends that made high-end luxury groups a standout investment over the past 20 years began fading. Top fashion houses are increasingly exposed as demand cools across broader consumer segments, leaving them reliant on a narrow group of ultrawealthy spenders.

    Valuation gap widens

    Stock multiples for top luxury names historically commanded a heavy premium over mass apparel operators. That pricing power built on high gross margins, tight inventory control, and reliable price increases on leather goods and apparel.

    Equity markets have flipped that relationship. Fast-fashion groups Inditex, which owns Zara, and H&M now trade at higher comparative multiples than both Paris-listed LVMH and Hong Kong-listed Prada.

    Fast fashion takes market momentum

    Mass-market retailers have defended turnover by turning inventory quickly and adjusting collections within weeks. Zara and H&M adjusted prices more conservatively while capturing spend from middle-income households managing tighter budgets.

    Luxury brands took the opposite path over the last four years. Aggressive price increases on core handbags and accessories pushed aspirational shoppers out of the market entirely.

    Squeeze on aspirational spenders

    Department stores and flagship retail malls across Asia report softer footfall in premium corridors as middle-class consumers cut discretionary purchases. The pullback leaves luxury groups reliant on top-tier VIP clients who buy haute couture and high jewelry.

    That customer base is too narrow to sustain the double-digit revenue growth rates equity investors came to expect. Mall operators in major retail hubs are already reassessing space allocations as mass-market and sports labels post steadier sales densities.

    Earnings reports to watch

    The downturn follows consecutive years of record revenues across European luxury houses between 2021 and 2023. Those gains unraveled as post-lockdown shopping splurges faded and mainland consumer sentiment turned cautious.

    Market watchers are tracking upcoming third-quarter revenue updates from LVMH and quarterly trading figures from Prada to gauge whether holiday order books show any signs of stabilization.
  • Asia-Pacific Expands Market Share in Netherlands Apparel Imports

    Asia-Pacific Expands Market Share in Netherlands Apparel Imports

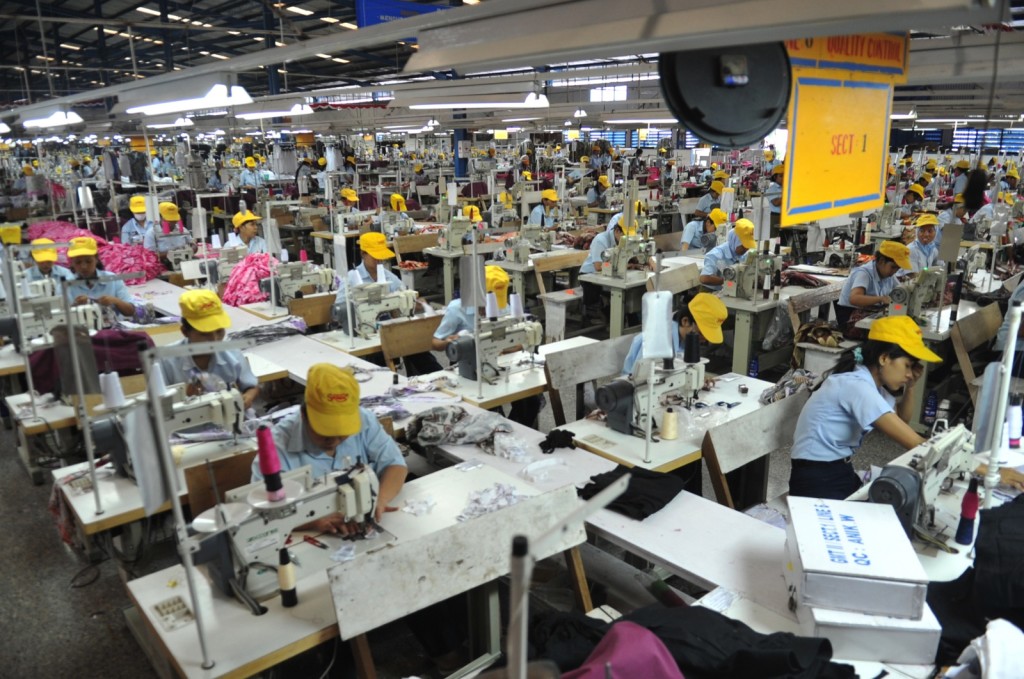
    Asia-Pacific manufacturers captured a larger share of the Netherlands’ apparel imports during the first seven months of 2026, outperforming European suppliers despite falling overall trade values.

    Sourcing intelligence data from TexPro shows Asian suppliers retained the top position in Dutch garment procurement between January and July 2026, extending a multi-year market share gain over regional European competitors.

    Europe held the second-largest share of Dutch clothing procurement over the same period. While European regional shipments also edged higher in percentage terms, the wider multi-year shift continues to favour Asian manufacturing hubs across South and Southeast Asia.

    Cotton and Trouser Shipments Anchor Volume

    Cotton garments remained the largest product category by value entering Dutch ports during the seven-month period. Trousers and shorts led specific product categories, confirming that core high-volume basic lines continue to dominate retail order books.

    European fashion buyers have concentrated purchase orders into core everyday categories rather than expanding speculative fashion inventory. For Asian fabric mills and garment factories, volume resilience in woven and knit trousers provides steady production runs even when retailer demand softens in value terms.

    Pressure on European Garment Sourcing

    The steady shift toward Asia-Pacific production highlights cost advantages that nearshore European suppliers struggle to match under current retail pricing pressures. Dutch retailers and cross-border e-commerce hubs operating out of Amsterdam and Rotterdam continue to route base volume through Asian supply chains.

    Nearshore suppliers in Southern and Eastern Europe retain speed advantages for short-cycle replenishment. However, Asian producers have steadily upgraded logistics links and compliance standards, narrowing the operational gap for standard seasonal collections.

    Shifting Trade Policy and Regional Flow

    The import pattern across the Netherlands reflects wider European retail adjustments ahead of prospective changes to low-value parcel duties across the European Union. Similar procurement shifts toward Asian production hubs have appeared in neighbouring markets including Austria.

    For Asian apparel associations in markets such as Bangladesh, Vietnam, India, and China, maintaining Dutch market share provides critical stability. The Netherlands acts as a primary logistics gateway for re-exporting fashion goods into Germany, Belgium, and Northern Europe.

    Order Books for the Final Quarter

    Garment exporters across Asia now face the critical fourth-quarter delivery window for winter stock and preliminary manufacturing runs for spring 2027 collections.

    Trade desks will track Dutch full-year customs filings and European retail sell-through rates through December to gauge whether Asian volume gains translate into margin recovery for supplier factories.

  • Fashion Leaders from over 60 Countries Gather in Moscow for BRICS+ Summit

    Fashion Leaders from over 60 Countries Gather in Moscow for BRICS+ Summit

    Fashion industry leaders from more than 60 countries gathered in Moscow on Sept. 28 for the BRICS+ Fashion Summit. They sought direct trade links across emerging consumer markets.

    The event ran through Sept. 30 alongside Moscow Fashion Week, bringing delegations from across Asia, Africa, and the Arab world.

    Building South-South Trade Channels

    Delegates focused on commercial ties between regional production hubs and consumer markets across Asia and the Middle East. Talks covered cross-border logistics, textile supply chains, and retail distribution networks that bypass traditional Western wholesale channels.

    For Asian apparel manufacturers and brand owners, the summit offered an alternative path into non-Western markets. Operators face shifting global trade patterns. They also contend with higher tariffs in mature markets and changing consumer demand in traditional export destinations.

    Shifting Market Focus

    The gathering reflects a wider pivot toward emerging market alliances. Chinese cashmere producer Erdos and Indian jewellery retailers preparing for initial public offerings are targeting regional market depth rather than relying on European or North American partners.

    European luxury groups face their own headwinds. Kering reported a 39 per cent decline in first-half recurring operating income to €969 million. Brands such as Saint Laurent are lifting select prices to protect margins against trade friction and tariff pressures.

    Next Steps for Regional Brands

    Domestic apparel sectors across Asia and partner markets want higher-value retail positioning. Broadening bilateral distribution agreements allows manufacturers to retain higher margins than contract manufacturing affords.

    Participating delegations will review bilateral trade arrangements and regional retail partnerships before the close of the current fashion market season.

  • China Luxury Malls Expand Footprint Despite Retail Gloom

    China Luxury Malls Expand Footprint Despite Retail Gloom

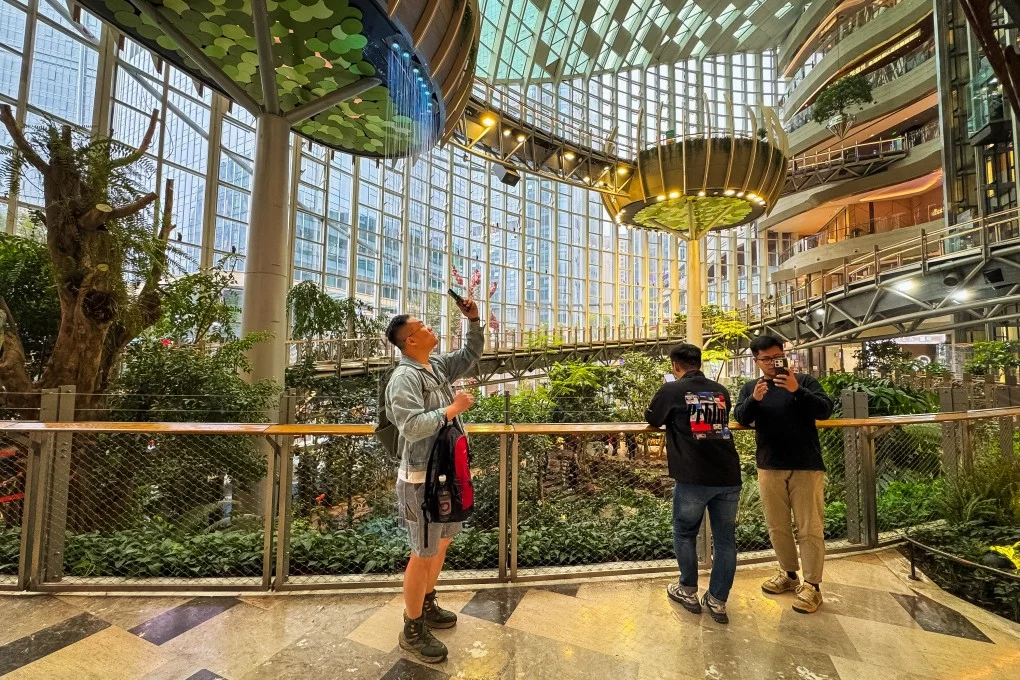
    Luxury mall operators across China are pressing ahead with major retail expansion projects this week despite persistent weakness across the broader consumer economy, Nikkei Asia reported. High-end property developers are securing footprint commitments from top global fashion and jewelry houses across primary commercial centers.

    The physical expansion push comes as top-tier landlords separate their performance from standard mass-market department stores. Premium commercial destinations continue to attract long-term brand commitments because affluent shoppers maintain higher discretionary budgets than middle-market consumers.

    Bifurcation across commercial real estate

    Commercial leasing data across mainland tier-one and tier-two cities shows a sharp split between mass retail centers and destination luxury complexes. While mid-market shopping centers struggle with tenant turnover and rent concessions, prime luxury properties maintain tight occupancy rates and multi-year waiting lists for prime ground-floor frontages.

    Global luxury houses require expansive multi-level flagships with dedicated VIP lounges, private salons, and custom architectural facades to serve high-net-worth clients. Operators of luxury centers are reconfiguring existing floor plans and building new wings to meet these spatial specifications.

    Brand strategy shifts in mainland centers

    International fashion groups are consolidating their retail networks rather than retreating from mainland China. Brands are closing underperforming satellite boutiques in secondary malls to concentrate capital and inventory into larger experiential flagships inside leading luxury complexes.

    For mall landlords, securing anchor flagships from premier European luxury houses guarantees footfall from top-tier spenders. It also allows developers to command premium rental yields on adjacent specialty dining, lifestyle, and beauty spaces.

    Landlord competition and regional exposure

    Competition among high-end landlords is intensifying across regional hubs beyond Shanghai and Beijing. Commercial developers are competing aggressively to bring exclusive boutique concepts and direct-operated flagships to regional centers such as Chengdu, Shenzhen, and Hangzhou.

    The execution risk rests on whether local high-end consumption can absorb the expanded commercial floor space without diluting sales density per square meter. Landlords that overcommit capital to new luxury builds in saturated micro-districts face longer lease-up schedules if brand partners limit their capital expenditure.

    Pipeline targets across major markets

    Earlier retail cycles established luxury retail hubs around historical downtown commercial districts. The current construction cycle focuses on mixed-use commercial developments that combine luxury retail with prime office towers, cultural spaces, and five-star hospitality.

    Commercial developers have scheduled their new luxury mall openings and phased retail extensions through the next several operating quarters. Occupancy rates, flagship delivery schedules, and initial tenant sales productivity across these new developments will determine whether landlords maintain their current expansion pace.

  • Valley Eyewear Receives 7 Formal Offers in Liquidation Sale

    Valley Eyewear Receives 7 Formal Offers in Liquidation Sale

    Sunglasses brand Valley Eyewear has received seven formal written offers after entering liquidation in mid-August following a legal battle between its owners.

    The Gold Coast-based business drew 120 registrations of interest and 72 executed confidentiality agreements from prospective purchasers across Australia, New Zealand, Asia, and the US.

    Global distribution draws turnaround buyers

    Federal Court-appointed liquidators James Robba and Jason Bettles of Worrells led the sale campaign, confirming that the outcome is expected to deliver a return to creditors.

    Founded in 2011 by Michael Crawley, Tenielle Crawley, and Matthew Grippo, the independent label expanded beyond its domestic base to stock products in more than 100 wholesale accounts across 20 countries. That international wholesale footprint proved the primary draw for offshore distributors seeking established design assets without the overhead of company-owned retail storefronts.

    Cross-border interest in premium accessories

    Regional retail operators face tight consumer spending in discretionary fashion, yet niche eyewear assets continue to attract trade buyers looking to consolidate wholesale relationships. A buyer acquiring the label out of liquidation avoids legacy shareholder liabilities while gaining established shelf space across independent boutiques in Asia and Australasia.

    For retail stockists and wholesale partners, the outcome determines whether product shipments and seasonal range deliveries resume under new ownership or splinter across regional licensing agreements. The risk for prospective buyers sits in reviving brand momentum and preserving design credibility after months of courtroom paralysis among the original creators.

    There was considerable interest from prospective purchasers throughout the campaign, which culminated in multiple competitive offers being submitted for our consideration.

    Shareholder deadlock forced liquidation

    The sale follows a protracted legal battle among the three co-founders that culminated in Australia’s Federal Court placing the business into liquidation in mid-August 2026. The court mandated an urgent sale process to preserve asset value before wholesale distribution channels eroded.

    Worrells confirmed that the volume and pricing of the seven competing offers are expected to generate sufficient proceeds to deliver a financial return to unsecured creditors.

    Finalising the asset transaction

    Robba and Bettles are currently assessing the seven formal submissions to select a preferred bidder and execute definitive asset purchase agreements. Creditors will receive a formal report detailing the winning offer, transaction terms, and estimated dividend distribution timetable once contracts are exchanged.

  • Musinsa Helps 15 Korean Fashion Brands Enter China via Shanghai Pop-Up

    Musinsa Helps 15 Korean Fashion Brands Enter China via Shanghai Pop-Up

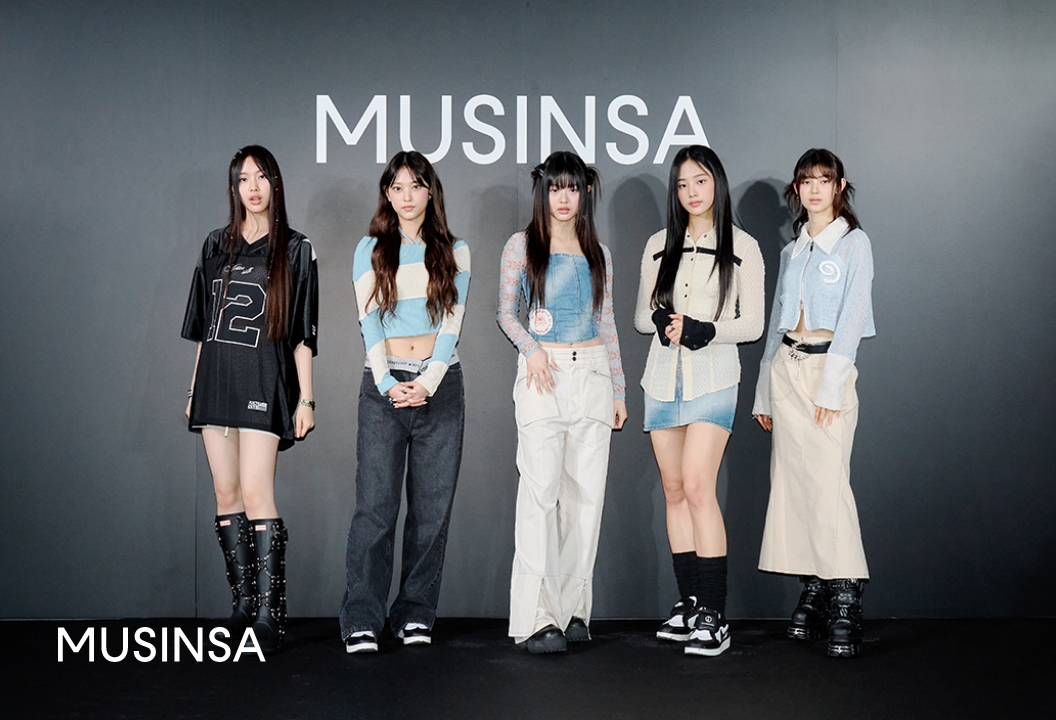
    South Korean fashion platform Musinsa is helping 15 domestic apparel brands enter China through a dedicated pop-up store at Shanghai’s Jing An Kerry Centre. The temporary retail space drew more than 10,000 visitors between Aug. 21 and Sept. 21.

    Running through Nov. 30 on Nanjing West Road, the initiative covers product certification and in-store sales operations. Backed by South Korea’s Ministry of Trade, Industry and Energy alongside the Korea Trade-Investment Promotion Agency, the project aims to reduce costs and hurdles for small and midsize brands entering the market.

    State backing and regulatory clearance

    Participating labels include Lookast, Lebah, Tillaidie, and RSSC. Musinsa selected brands based on local demand and consumer preferences, assisting them with Chinese product standards required for local distribution and managing on-site sales.

    Small apparel exporters face steep barriers in mainland China, where localized testing, labeling rules, and import certifications routinely stall foreign market debuts. Handling store staffing and inventory management centrally removes upfront capital expenditure for the labels, letting them test mainland consumer appetite without signing long-term commercial leases.

    Testing demand on Nanjing West Road

    Securing prime frontage at Jing An Kerry Centre places these emerging Korean names beside established global luxury flagships. The high-traffic shopping corridor gives independent streetwear and contemporary labels immediate exposure to Shanghai’s core fashion demographic.

    Foot traffic numbers indicate solid curiosity, but footfall does not guarantee recurring wholesale orders. Chinese consumer spending across mid-tier fashion remains selective, and domestic Chinese streetwear brands have taken market share by responding to local trends faster than overseas competitors.

    The platform approach across Asian markets

    Musinsa’s export model shifts financial risk away from single designers and turns the platform into a consolidated distributor. The company is replicating this physical playbook across the region, pairing its domestic roster with localized retail partners, as seen in Southeast Asia where its Musinsa Standard private label partnered with ACx Retail to enter the Philippines.

    For commercial landlords, the arrangement provides a rotating roster of trending Korean brands without the lease default risks tied to single-label tenants. For the fashion brands, the structure caps downside exposure while testing whether Chinese shoppers will buy beyond short-term novelty.

    Anfu Road pipeline and next steps

    The Kerry Centre project builds on Musinsa’s permanent footprint in Shanghai. The company opened a flagship retail space on Anfu Road in December, which serves as a dedicated launchpad for Korean apparel labels seeking Chinese distribution.

    That location has already hosted individual pop-ups for brands including Ronron, Sculptor, and Stand Oil. Accessories label Find Kapoor starts a monthlong residency at the Anfu Road store on Oct. 30, while the Jing An Kerry Centre multi-brand show runs until Nov. 30.

  • H&M Shrinks Asian Footprint to 886 Stores as Regional Sales Edge up 4 per Cent

    H&M Shrinks Asian Footprint to 886 Stores as Regional Sales Edge up 4 per Cent

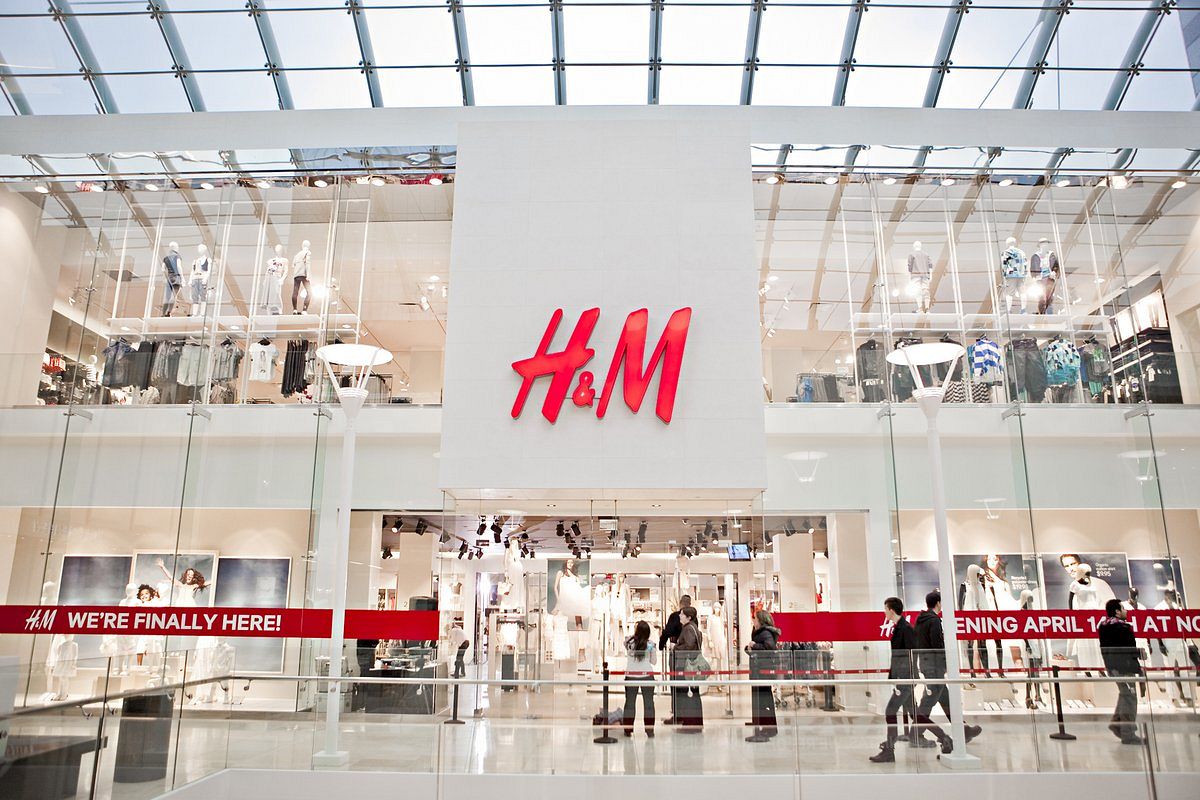
    H&M Group closed 54 stores across Asia, Oceania and Africa over nine months to August. That trimmed its regional footprint to 886 locations. Regional sales for the quarter still rose 4 per cent.

    Group-wide revenue for the three months to August 31 reached SEK 57.2 billion ($5.8 billion). That was an increase of just 1 per cent in local currencies, as a stronger Swedish krona erased top-line gains.

    Operating profit climbed 23 per cent to SEK 6.04 billion, beating market forecasts of SEK 5.14 billion. The operating margin widened to 10.6 per cent from 8.6 per cent a year earlier. One-off refunds from US tariff payments accounted for 1.6 percentage points of that margin increase. The company confirmed those credits will not repeat in coming quarters.

    Pruning the Asian Store Network

    Physical retail space continues to shrink across Asia, Oceania and Africa. The regional network stood at 940 locations in November 2025 before net closures reduced the tally to 886 by the end of the third fiscal quarter.

    Management has paired store closures with selective rollouts for higher-margin labels. The group introduced COS to India in October 2025. It is betting affluent urban shoppers will back premium concepts as core H&M outlets leave marginal shopping centres.

    “We are able to get product from having a first rough idea to the customer in six weeks, and when we talk about shortening the lead times, it is about increasing the share that we buy in that way,” said chief executive Daniel Erver.

    Online transactions now generate more than 30 per cent of total sales. That growth has accelerated the push to refit existing flagships. The company has modernised a fifth of its 4,000 global stores rather than adding floor space.

    Rival Pace and Regional Margins

    H&M faces pressure from both ends of the fashion market in Asia. Zara owner Inditex reported a 9 per cent sales increase in constant currency in August, outpacing H&M through rapid stock turnover.

    Discount competitor Shein continues to capture budget market share across Southeast Asia and East Asia, squeezing the middle price bracket where H&M operates. Landlords in tier-two Asian malls face falling footfall. That drop leaves retailers with less bargaining power over fixed leases unless their sales density improves.

    Shifting logistics hubs has added further friction. A warehouse closure in Belgium disrupted stock flows into international distribution channels earlier this year. Transport bottlenecks in the Middle East compounded those freight delays.

    Decarbonising the Manufacturing Base

    Supply chain costs remain exposed to rising energy expenses across South Asia. Fuel price hikes in Bangladesh, a major manufacturing centre for the group, prompted H&M to push suppliers toward renewable power.

    Direct suppliers must complete the phaseout of coal-fired boilers by the end of 2026. This energy shift targets long-term operational resilience as regional fossil fuel tariffs fluctuate.

    European logistics operations are also expanding through 2027 with new facilities. These hubs aim to shorten shipping cycles and improve product availability across digital channels.

    The Next Trading Targets

    Recent store closures follow a difficult 2025 fiscal year. H&M shuttered a net 105 stores across Asia, Oceania and Africa during that period, driving a 7 per cent reported revenue drop in Swedish krona terms.

    Early autumn trading shows little acceleration. September sales are projected to grow 1 per cent in local currencies, matching the flat trajectory of the third quarter.

    Investors and retail partners are watching the fourth-quarter gross margin to see if shorter lead times can protect full-price sales without discounting once temporary tariff credits vanish.

  • Hermès Reopens Renovated Store at Taikoo Li in Chengdu

    Hermès Reopens Renovated Store at Taikoo Li in Chengdu

    Hermès reopened its retail store in Chengdu, located in China’s Sichuan province, on September 28, 2026, following a renovation.

    Situated in the Taikoo Li open-air mall, the store first opened in 2014.

    According to the company, the redesigned space reimagines the region’s architecture and cultural heritage through a contemporary lens, featuring dark timber, matte-finish metal, enamelled ceramic in amber tones, and tall windows veiled with bamboo screens and curtains.

    Architectural overhaul at Taikoo Li

    The redesign updates a flagship that anchors one of western China’s highest-grossing commercial developments. Luxury labels in Chengdu have steadily shifted focus toward expanding and retrofitting established premier doors rather than pursuing raw floorplate expansion across secondary properties.

    Regional textures and craft references align the boutique with a broader global strategy of giving individual flagships distinct local identities. For high-spending regional shoppers, tailored physical store environments remain the primary point of contact for leather goods, ready-to-wear lines and bespoke collections.

    Western China luxury demand

    Chengdu serves as the principal luxury capital for inland and southwestern China, drawing top-tier consumer spending from Sichuan, Yunnan and Guizhou provinces. Competition among European fashion houses for prime positioning at Taikoo Li remains intense as landlords curate tenant mixes to retain ultra-high-net-worth client traffic.

    Upgrading the 2014 location preserves Hermès’s standing against rival flagship boutiques from Chanel, Louis Vuitton and Dior. The investment protects market share in a provincial capital where retail footfall and high-ticket sales consistently rival levels recorded in Shanghai and Beijing.

    Network investment across China

    This completed renovation follows a three-year cycle of store expansions and refurbishments executed by Hermès across greater China. The Paris-based fashion house opened its initial mainland boutique in 1997 and spent the next three decades building a tightly controlled network of directly operated flagships in key commercial hubs.

    Hermès continues to review and modernise its legacy stores across mainland retail hubs, with further provincial flagship enhancements planned as commercial lease renewals approach across the national network.

  • LVMH Stock Falls 40 per Cent as Asia Demand Slows

    LVMH Stock Falls 40 per Cent as Asia Demand Slows

    LVMH Moët Hennessy shares have dropped 40 per cent year to date, touching six-year lows. Luxury demand weakened across key consumer markets in Asia and the United States.

    The sell-off erased 11 per cent of the French group’s market value in September alone. Shoppers pulled back across mainland China and western retail hubs.

    Valuation drops below historical averages

    LVMH now trades at a forward non-GAAP price-to-earnings multiple of 15.8 times. Its five-year historical average sits at 22.4 times.

    Valuation multiples compressed across the sector as high interest rates, inflation and geopolitical tensions cut into discretionary budgets. Institutional buyers have stayed cautious about near-term revenue trajectories.

    Asia ex-Japan pressure mounts

    The United States and Asia ex-Japan together generate nearly 54 per cent of total revenue for the Paris-based conglomerate. Weakness across both territories leaves the group exposed to broader retrenchment.

    Chinese shoppers spent less on high-end leather goods, spirits and watches over recent quarters. Foot traffic in tier-one city flagship stores slowed down. Regional travel retail failed to fill the gap.

    Operating margins face structural shift

    For department store operators and prime landlords across Asia, the valuation slide signals leaner wholesale orders and tougher lease renegotiations. Luxury houses spent three years opening stores and raising prices across Shanghai, Hong Kong and Singapore.

    That pricing power has hit a ceiling. Group brands now face tough inventory decisions, particularly in fashion, leather goods and cognac segments where excess stock demands discounting or production cuts.

    Slowing momentum across core divisions

    Growth rates across the sector slowed early this year after record post-pandemic sales volumes. Consumer sentiment worsened rather than stabilized as property and labor market pressures persisted in mainland China.

    Investors are tracking whether the group can protect gross margins without heavy promotional discounting in regional department stores. Third-quarter organic revenue from Asia ex-Japan will be the critical figure when the next quarterly results arrive.

  • Chanel Acquires France’s Oldest Shirtmaker Charvet

    Chanel Acquires France’s Oldest Shirtmaker Charvet

    French luxury fashion house Chanel acquired France’s oldest shirtmaker Charvet in July. Sibling co-directors Jean-Claude and Anne-Marie Colban continue to lead the heritage brand from its long-standing boutique on Place Vendôme in Paris, offering classic tailored shirts and ties.

    The move comes alongside milestone anniversaries and executive transitions across independent fashion labels. British brand YMC is celebrating 30 years since its first collection, with creative director Sage Toda-Nation directing design alongside co-founder Jimmy Collins after joining in 2024 following the death of co-founder Fraser Moss.

    Wholesale Networks and Direct Market Entry

    In retail, South London store Suntosons launched in 2025 under founder Keita Hiraoka, formerly of Beams Japan and Trunk, while in Southeast Asia, former Mall Group executives founded retail venue Friend Friend in summer 2025 inside Bangkok’s Emporium shopping mall.

    South Korean fashion exports have gained commercial traction across Tokyo and Shanghai, helped by consumer demand for unisex silhouettes and neutral palettes. Direct market entry allows brand owners to retain higher gross margins compared to pure wholesale distribution, which often discounts unsold seasonal inventory through third-party stockists.

    Mass Market Scale and Regional Supply Chains

    At the top of the market by volume, Fast Retailing’s Uniqlo is projecting annual sales of 3.9 trillion yen, equivalent to 20.8 billion euros, keeping pace with global fast-fashion operators Inditex and H&M Group. The Japanese retailer is using functional outerwear, including padded blousons with checked linings, to anchor seasonal volume across its Asian store network.

    Independent designers across the region are also integrating domestic textile manufacturing into global wholesale networks. Seoul-based designer Jiyong Kim, an LVMH Prize semi-finalist in 2024 who trained at Louis Vuitton and Lemaire, supplies Dover Street Market in Singapore and Paris, 10 Corso Como in Seoul, and GR8 in Tokyo with sun-weathered and light-responsive fabrics.

    Repurposing Mall Real Estate in Southeast Asia

    Retail formats in Southeast Asia are shifting space away from conventional department store layouts toward multi-use commercial hubs. In Bangkok, retail venture Friend Friend opened inside a converted car park at The Mall Group’s Emporium shopping complex at 622 Sukhumvit Road.

    Former Mall Group executives Suchada Peanpiriya, Worapun Sinakhom and Tanchanok Thitisaksakul established the venue in 2025, mixing workshops, food service and lifestyle merchandise. The floor plan stocks local ceramics from Bangkok’s Aoon Pottery alongside Sekisaka tableware from Japan and Kent hairbrushes from Britain, demonstrating how mall operators are converting underutilised square footage to drive foot traffic.

    Niche Manufacturing and Technical Commuter Lines

    Specialist Asian apparel makers are targeting functional categories to build export niches. In Japan’s Tokai region, Gifu-based commuter brand Ketta developed cycle-ready formalwear, adding cuff fasteners to suit trousers to prevent gear snags during urban commutes.

    Cross-border production partnerships are supporting this technical shift. Japanese label Comoli paired with Italian outerwear house Ten C, overseen by Federico Melchioli, to manufacture a nine-piece black collection blending Japanese flannel with humidity-responsive jersey textiles. In South London, former Beams Japan buyer Keita Hiraoka founded appointment-only showroom Suntosons in 2025, contracting garment factories in Japan to produce heavyweight denim fatigue jackets for European buyers.

    Commercial landlords and multi-brand buyers across Shanghai and Tokyo are now reviewing autumn order books as Recto finalises its opening retail locations in both territories.

  • Global Luxury Set to Grow 2 to 5 Percent as Burberry and Kering Reset

    Global Luxury Set to Grow 2 to 5 Percent as Burberry and Kering Reset

    Global luxury spending is set to grow between 2 percent and 5 percent this year following a three-year malaise, according to Boston Consulting Group data presented at an executive roundtable last Thursday.

    The projected rebound is driven by an 8 percent increase in North America and a 2 percent to 3 percent recovery in China, while Middle East sales are expected to drop by double digits.

    Executives from Burberry and Kering told the gathering that brands are overhauling strategies and price points, as a BCG survey of 12,000 luxury shoppers revealed that 70 percent have avoided purchases due to price increases.

    Shifting Price Points and Product Lines

    Burberry is running a turnaround plan called Burberry Forward, focused on brand identity, client engagement, core merchandise, and store distribution. Laura Dubin-Wander, Americas president for the brand, said it is refocusing on heritage outerwear and accessible entry products. To draw new shoppers, the house set up dedicated trench coat areas, scarf bars, and displays for $400 polo shirts.

    Its store network is also under review. The company plans to downsize or exit unproductive sites while adding pop-ups in affluent resort towns and growing its womenswear athleisure range. On the marketing side, it added American athletes like Carmelo Anthony to build wider recognition.

    Across Asia-Pacific, landlords and department stores must rebalance their floor space. Retailers that gave prime ground-floor square footage to high-priced ready-to-wear collections now see lower sales densities. Operators in hubs like Shanghai, Tokyo, and Singapore are shifting space toward beauty counters, eyewear concessions, and fragrance boutiques where sales volumes hold up.

    Brand margins are shifting as sales move from runway lines to entry-level accessories. Labels must sell far more low-ticket units to offset slowing ready-to-wear purchases. That puts direct pressure on boutique staffing and stock management.

    Price Sensitivity Bites Top Spenders

    Affordability concerns now reach well beyond entry-level shoppers, according to an annual survey of 12,000 luxury consumers by BCG and Altagamma. Roughly 70 percent of respondents walked away from a planned purchase at least once due to a price increase. Most redirected that money into luxury cosmetics and skincare.

    Kering is splitting its commercial strategy to handle this divide between wealthy clients and aspirational buyers. Ewa Abrams, Americas president at Kering, said top-tier clients expect private, personalized service. Aspirational shoppers, by contrast, respond to cultural partnerships in entry categories such as eyewear and fragrances.

    It’s important to stimulate them with the right product categories such as eyewear or fragrance.

    Channel Synergies and Technology Steps

    A shared operational platform now runs across the French group’s houses, including Gucci, Saint Laurent, Balenciaga, and Bottega Veneta. The setup streamlines administration. It also uses artificial intelligence to accelerate commercial decisions.

    Social commerce is another testing ground. Tim Chai, head of product strategy at TikTok Shop, said digital luxury consumers favor unpolished, direct brand communication over rigid corporate campaigns. Burberry adopted fast-paced video clips to show British heritage to younger online shoppers.

    Customer discovery is increasingly driven by artificial intelligence. The BCG survey found 90 percent of luxury shoppers use AI tools daily or weekly to find products, compare prices, and get recommendations. Those shoppers also trust AI comparison tools more than traditional social media influencers.

    Regional Exposure and China Trajectory

    Recent restructuring follows a painful financial stretch across the European luxury sector. London-listed Burberry posted full-year revenue of $2.42 billion and net income of $21 million, leaving an operating margin of 0.87 percent. Paris-based Kering generated trailing twelve-month revenue of 14.46 billion euros and recorded a net loss of 322 million euros as demand slowed in key Asian shopping cities.

    Investors will get their next check on November 12, 2026, when Burberry reports interim results. Those numbers will show whether lower price points and store cuts can stop margin erosion.

  • Gucci Shifts Sneaker Manufacturing to China in Break with Tradition

    Gucci Shifts Sneaker Manufacturing to China in Break with Tradition

    Gucci has begun manufacturing new sneaker models in China this season, departing from its longstanding practice of producing all footwear within Italy.

    The move by parent group Kering marks the first time the luxury house has placed assembly of select athletic footwear lines directly into Chinese manufacturing hubs, targeting supply chain efficiency and regional technical capabilities.

    Shifting the European Production Model

    European luxury houses have historically defended the ‘Made in Italy’ label as a core pricing pillar. Gucci’s pivot to Chinese production lines reflects the technical dominance Asian facilities hold over complex athletic shoe construction. Technical footwear demands specialised tooling, bonding agents, and synthetic mesh engineering that Italian artisan workshops rarely handle at volume.

    Kering, Gucci’s parent group, faces pressure to improve margins while defending market share in mainland China. Producing sneakers closer to Asian supply networks cuts shipping times and lowers unit assembly costs on high-turnover casual lines.

    Brand Equity and Consumer Perception

    Consumer reaction across Asia will test how rigid luxury buyers remain regarding country-of-origin labels. Chinese luxury consumers increasingly prioritise product quality, technical execution, and brand relevance over traditional European manufacturing stamps. Younger buyers who purchase luxury streetwear sneakers evaluate comfort and silhouette ahead of heritage claims.

    Other luxury competitors will watch the rollout closely. If Gucci maintains its retail price points without consumer backlash, rival houses will accelerate their own offshore manufacturing plans for technical categories. If shoppers resist, Gucci risks diluting the prestige that supports its footwear margins.

    Supply Chain Realignment

    Sourcing sneaker production in China shortens logistics cycles between Asian factories and regional flagship stores. Direct domestic distribution lowers tariffs and inventory lead times across key East Asian markets.

    Italy will retain production for Gucci’s formal leather shoes, handbags, and core ready-to-wear collections. Segmenting technical streetwear from traditional leather goods allows the brand to split its manufacturing strategy without abandoning its Tuscan heritage entirely.

    The Road Ahead for Footwear Lines

    Gucci plans to distribute the first Chinese-assembled sneaker models across global wholesale and retail channels over the coming season. Sell-through rates across department stores and flagship boutiques will dictate whether Kering expands Asian production into additional accessory categories.

  • Dr. Martens Launches Global Brand Campaign to Reverse Two Years of Revenue Declines

    Dr. Martens Launches Global Brand Campaign to Reverse Two Years of Revenue Declines

    Dr. Martens will launch a global brand campaign on September 24 to reverse two straight years of declining sales and an 83.3 per cent drop in its share price.

    Annual revenue fell 8.2 per cent to £787.6 million in fiscal 2025. Over the same period, earnings before interest, tax, depreciation and amortisation dropped 40.8 per cent to £117 million.

    This marketing push anchors the Levers for Growth turnaround plan, which followed an operational restructuring completed in 2024. Chief brand officer Carla Murphy is leading the creative repositioning around the slogan “What makes your sole bounce?” Chief executive Ije Nwokorie recruited Murphy from Adidas in July 2025. The media rollout combines out-of-home displays, social video formats and cultural events featuring American actress Chloë Sevigny, Japanese comedian Naomi Watanabe and British musician Jordan Stephens.

    Shifting from wholesale exposure

    Consumer purchase frequency is the primary target. Sales have bottlenecked partly because the brand’s classic air-cushioned boots simply last too long. Footwear operators across the Asia-Pacific region and North America also face softer discretionary spending. Euromonitor projects slow volume growth across global footwear and apparel through 2030. For department stores and wholesale partners, the shift toward direct storytelling and category extensions will decide whether floor space yields repeat foot traffic or stagnant stock.

    Rivals in casual and heritage footwear rely heavily on rapid fashion collaborations to keep unit velocity high. Dr. Martens tested this approach during London Fashion Week with capsule partnerships alongside Chopova Lowena, Labrum and Goyagoma to elevate design credentials above basic workwear utility. That strategy carries commercial risks. The brand could alienate core subcultural buyers while chasing broader casual spend against athletic giants with vastly larger marketing budgets.

    Financial pressure mounts

    Steep contractions across major geographic divisions forced the new marketing drive. Fiscal 2024 revenue declined 9.8 per cent year-on-year to £877.1 million, driven by weaker wholesale ordering in the United States. EBITDA fell 19 per cent, sliding from £245 million to £197.5 million.

    “Brands don’t shape communities; communities shape themselves,” said Murphy.

    Management must now prove whether higher marketing expenditure can stabilise direct-to-consumer order books ahead of the winter trading quarter and the next fiscal reporting period.

  • Brand Collective Buys Glue Store, the Dom and Running Bare

    Brand Collective Buys Glue Store, the Dom and Running Bare

    Brand Collective bought youth fashion chain Glue Store, online outlet The Dom and activewear label Running Bare to expand its Australian retail footprint.

    The deal adds three distressed apparel brands to a portfolio of more than 30 operating labels owned by billionaire Larry Kestelman.

    Under the terms, Brand Collective acquired Glue Store’s intellectual property and customer database from footwear operator Accent Group. Accent shuttered the streetwear chain in mid-June after an 8.4 million dollar loss and multiple store closures. The new owner plans to reopen physical stores targeting Gen Z and millennial shoppers. It will also upgrade the brand’s digital sales platform.

    Building a Discount Marketplace Unit

    The transaction also includes The Dom. That online factory outlet platform folded in April following cash constraints. Brand Collective will use its digital marketplace infrastructure to anchor a broader clearance portal selling apparel, footwear and accessories.

    Running Bare enters the fold after six months out of business. Brand Collective plans a digital overhaul for the activewear label while keeping its design identity intact.

    These acquisitions demonstrate Brand Collective’s ongoing evolution and innovation as a business. Brand Collective has considerable experience in taking brands to new levels of success, and we see enormous potential across all three.

    Picking Through Distressed Inventory

    Buying dormant brand assets allows multi-brand groups to secure established customer databases without taking on legacy lease liabilities. Accent Group offloaded Glue Store after less than five years of ownership. High mall rents and promotional pressure had eroded youth streetwear margins.

    Similar pressures hit Running Bare and The Dom as discretionary fashion spending slowed across Australian metropolitan centers. Folding all three into a single back-end operating unit cuts warehousing, marketing and digital fulfillment costs across the combined group.

    Shifting Channel Exposure

    The strategy mirrors consolidation seen across regional department stores and specialty apparel groups chasing online volume. Traditional storefronts have struggled against direct-to-consumer labels. Discount marketplaces offer an alternative route to clear excess inventory.

    For shopping center landlords, the planned revival of physical Glue Store outlets offers replacement tenancy in youth-focused retail precincts. Those locations lost foot traffic following Accent Group’s June exit.

    Operational Integration Ahead

    Accent Group walked away from Glue Store after restructuring costs failed to stem operating losses across mall locations. The divestment allows Accent to refocus capital entirely on its core footwear chains.

    Chief executive David Thomas said Brand Collective will announce rollout timelines and opening locations for the revitalised brands over the coming months.

  • Bangladesh Garment Factory Cooling Costs Recovered Within Four Years

    Bangladesh Garment Factory Cooling Costs Recovered Within Four Years

    Investments in cooling systems across Bangladesh garment factories pay back capital costs within four years, according to a study released on Sunday. Temperature data collected over a six-month period across eight manufacturing facilities in Dhaka showed that indoor heat stress erased an average of 4.1 per cent of annual factory revenue.

    Researchers at Cornell University’s Global Labor Institute found that physical modifications, including reflective roof paint, overhead insulation, and airflow ventilation, are commercially viable. Factory temperatures regularly climbed higher than outdoor readings, with the heaviest thermal load concentrated in pressing, ironing, and finishing lines.

    The Math on Shop Floor Cooling

    Jason Judd, executive director of the Global Labor Institute, noted that suppliers considering heat mitigation have struggled to weigh upfront spending against operational savings. Over the past year, apparel brands have sought verified payback timetables while discussing mitigation costs, emissions targets, and alternative energy sources with manufacturers.

    Apparel brands have spent years negotiating greenhouse gas targets and energy efficiency standards with suppliers. Adding physical climate adaptation to commercial contracts changes the financial equation. It shifts the focus from pure regulatory compliance to protecting factory throughput.

    Buyer Pricing and Cost Sharing

    Paying for factory retrofits creates friction between Asian garment manufacturers and Western fashion labels. Factory operators run on thin unit margins. They hesitate to fund facility upgrades without long-term order commitments or higher purchasing prices from international buyers.

    A heat resilience toolkit from the American Apparel and Footwear Association recommends that global brands co-fund factory modifications when direct commercial returns fall short of total setup costs. Nate Herman, executive vice president at the trade group, stated that brands must help protect workers across manufacturing networks as extreme heat events become frequent.

    Regional Export Exposure

    Earlier trade assessments showed severe climate risks across Asian manufacturing hubs. Heat stress and seasonal flooding threaten to wipe out $65 billion in combined apparel export earnings across Bangladesh, Cambodia, Pakistan, and Vietnam by 2030 if industrial zones fail to adapt physical infrastructure.

    Suppliers in Dhaka and regional production belts face a clear timeline to integrate cooling into capex plans. Retail buyers and factory operators will test the financial returns of these ventilation and insulation upgrades as contract pricing rounds open for upcoming production cycles.