Tag: FinTech

  • Macau Police Uncover 33,000 Fake Sites as Android Trojans Hit Wallets

    Macau Police Uncover 33,000 Fake Sites as Android Trojans Hit Wallets

    Malware syndicates across Southeast Asia are deploying fraudulent gambling applications to intercept digital wallet transactions, targeting systems run by Malaysian payment networks Touch ‘n Go and DuitNow. Instead of processing transactions through secure banking rails, malicious overlays draw counterfeit payment interfaces directly over mobile screens to capture personal identification numbers.

    The scale of the threat infrastructure emerged when INTERPOL concluded Operation Synergia III in March, taking down 45,000 malicious IP addresses and servers worldwide. Within that total, police in Macau alone uncovered more than 33,000 fraudulent websites operating as fake casino platforms and spoofed portals designed to harvest personal and financial credentials.

    Recent security investigations demonstrate how threat groups use localized mobile tools to penetrate devices across the region. In October, cybersecurity firm ThreatFabric documented Hirudo, an Android trojan that triggers a purchase before projecting an interface carrying counterfeit Malaysian bank and wallet branding.

    Spoofing Local Checkout Interfaces

    ThreatFabric documented a trojan called Hirudo, which operates by initiating a transaction and generating a transparent graphical overlay across the phone screen. The counterfeit screen replicates the checkout branding of major Malaysian banks and electronic wallet providers, intercepting the user’s personal identification number before presenting a falsified success notification.

    The mechanics exploit payment habits developed in regional commerce. Malaysian shoppers expect deposit screens to show Touch ‘n Go or DuitNow interfaces, rather than standard payment cards. In a review of PIN-approved e-wallet casino payments, a Malaysian comparison site that deposited with two local wallets at each operator found Touch ‘n Go accepted at all ten it listed and DuitNow at eight. Genuine transactions process verification inside the standalone payment app, with the merchant receiving merely a reference code.

    Hirudo alters that structure entirely. The malicious package renders the credential entry form within the host program itself. When a transaction completes, the software sends a forged confirmation notice back to the lure interface, even though no legitimate funds transfer occurred through the wallet system.

    Surveillance Disguised as Consumer Tools

    Technical analyses reveal identical delivery models elsewhere in Southeast Asia. Security firm PT ITSEC Asia dissected an Android application named Gacor Max, distributed across Indonesia via direct messaging campaigns that routed users to spoofed Google Play storefronts. The name borrows Indonesian slang for a slot machine paying out cash.

    The code requested immediate access to phone states, cameras, and local media storage before reaching any interactive interface. Devices running the package maintained persistent background wake locks, keeping the malware operational while freezing on an emulator loading screen. Similarly, threat monitors at Infoblox traced a fraudulent program named Universe Browser, circulated across regional gaming sites by a group tracked as Vault Viper. While marketed as a privacy platform, the software redirects web traffic through external servers in China and executes background payloads.

    The Proliferation of Interface Overlays

    Interface overlays have become standard infrastructure for financial malware operating across regional digital ecosystems. Group-IB documented RemControl, an Android banking threat that projects full-screen replicas of legitimate banking apps over consumer software. Related tracking of ToxicPanda revealed fake login interfaces designed for 349 financial institutions operating in 16 markets.

    For mobile commerce operators, these intrusions undermine user confidence at checkout. Digital wallets rely on end-to-end user confirmation, directing customers never to share one-time passwords or input credentials outside designated application boundaries. When third-party apps simulate checkout dialogues, the security perimeter established between merchants and payment gateways breaks down on the local client device.

    The current malware expansion builds on structural distribution networks uncovered during INTERPOL’s Operation Synergia III, which dismantled cross-border cyber infrastructure earlier this year. As regional mobile wallet adoption accelerates across consumer services, threat groups continue shifting away from general phishing links toward targeted, localized mobile payloads disguised as consumer entertainment software.
  • Credit Saison Partners with ADB on Small Business Loans Across Asia

    Credit Saison Partners with ADB on Small Business Loans Across Asia

    Credit Saison has agreed to partner with the Asian Development Bank to expand commercial lending facilities for small and midsize enterprises across developing Asian markets. The Tokyo-based financial services provider plans to take lending models developed through its Indian subsidiary and roll them out into additional regional economies to establish new recurring revenue.

    Multilateral backing provides the Japanese consumer credit group with institutional balance-sheet support as it steps beyond its saturated domestic market. The Asian Development Bank previously participated in a syndicated loan facility announced by Credit Saison’s Indian operating arm in May, establishing the groundwork for a broader regional agreement.

    The partnership targets small business credit across emerging economies, pairing private Japanese capital with multilateral developmental resources as regional non-bank lending activity gathers pace.

    Exporting the Indian Credit Blueprint

    Credit Saison built its offshore corporate lending thesis in India, using automated underwriting systems and local balance-sheet partnerships to service smaller enterprise borrowers. Traditional retail banks often bypass these firms due to patchy documentation and high origination costs. By systematising risk assessment in India, the company created an origination structure that it now intends to replicate across neighbouring frontiers.

    Teaming up with an international development lender shifts the cost profile of cross-border enterprise funding. The Asian Development Bank brings concessional capital structures and local currency syndication capabilities, which insulate private credit providers from foreign exchange swings and sudden offshore liquidity contractions. For small commercial suppliers, merchant distributors and independent retail operators, the entry of Japanese non-bank lenders provides an alternative to restrictive domestic banking collateral rules.

    Balance Sheet Pressures Drive Outbound Expansion

    Consumer credit operators in Tokyo face structural headwinds at home, where an ageing population and stagnant real wages curb revolving credit demand. Credit Saison responded by aggressively diversifying outside Japan, chasing higher-yield commercial books in emerging consumer markets. Extending working capital to supply chain operators and storefront businesses offers margins that domestic credit cards can no longer generate.

    The central risk sits in credit cycle management across disparate legal jurisdictions. India’s digital public infrastructure, including unified digital IDs and corporate tax registries, gave non-bank financiers reliable verification pipelines that do not exist uniformly across other developing Asian economies. Transferring credit risk algorithms to markets with weaker creditor protections or higher non-performing loan ratios will test whether Indian recovery rates can be duplicated.

    Deepening Multilateral Ties

    The formal collaboration follows months of closer financial links between both institutions. In May, the Asian Development Bank took a direct role in a syndicated debt package for Credit Saison’s Indian operations, confirming its appetite for the company’s balance sheet.

    Credit Saison is currently mapping targeted jurisdictions across developing Asia for the roll-out of joint financing structures with the development bank, with capital deployment volumes and local regulatory filings in initial secondary markets serving as the operational benchmark for the expansion.

  • Thai Virtual Bank Clicx Taps Thought Machine Ahead of up to 3 Licensees

    Thai Virtual Bank Clicx Taps Thought Machine Ahead of up to 3 Licensees

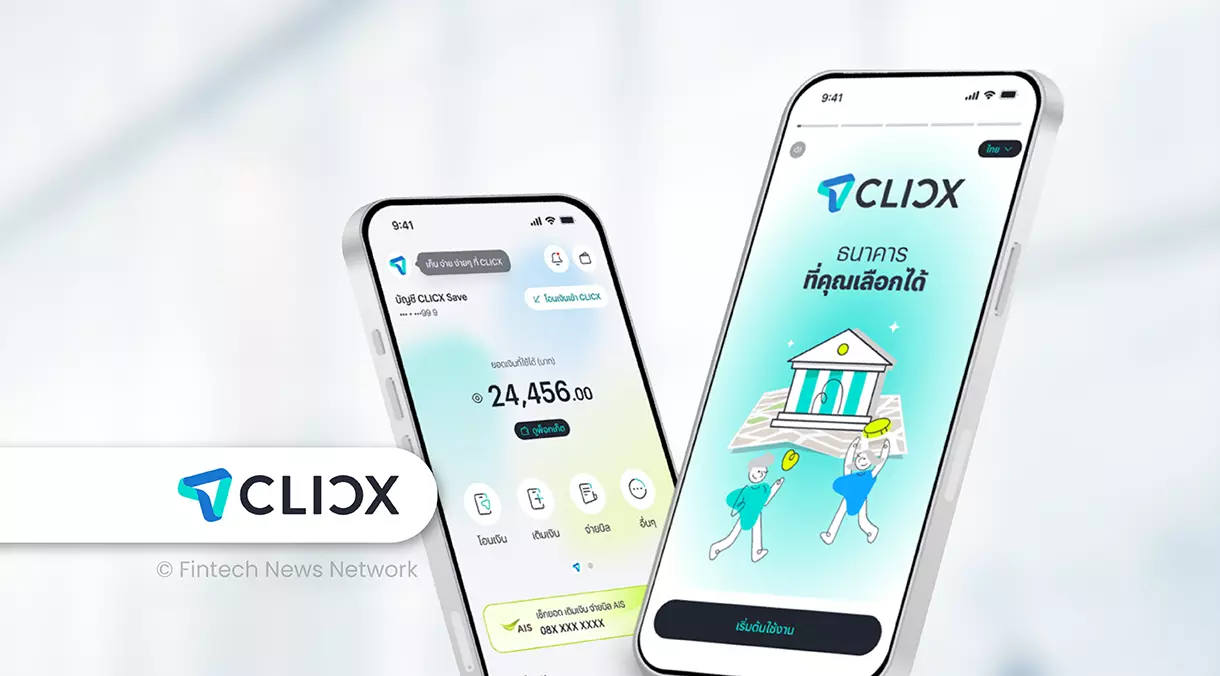
    Thai virtual bank Clicx chose London software vendor Thought Machine on November 3 to run its core banking engine, clearing its infrastructure setup ahead of rival licence holders.

    The consortium, owned by state-controlled lender Krungthai Bank, mobile carrier Advanced Info Service, and fuel and convenience retailer PTT Oil and Retail Business, is the first entrant to claim full operational readiness under the central bank schedule.

    Clicx runs on Vault Core, a cloud system that separates ledger code from product rules. Instead of waiting on an outside vendor to modify backend code when rolling out credit products, the bank can adjust interest rate schedules and repayment periods directly. The bank targets nano-loans and digital personal credit at freelancers, daily wage earners, and mom-and-pop vendors who lack standard salary slips. Risk assessment relies on customer-consented behavioural records pulled from AIS mobile accounts, OR petrol stations, retail cash registers, and Krungthai payment networks.

    How Real-Time Data Replaces Collateral

    Virtual banks routinely promise financial inclusion, but uncollateralised micro-lending often collapses under high non-performing loans when underwriting relies on static quarterly statements. By feeding real-time merchant settlement receipts and telco top-up histories into its ledger, Clicx tries to calculate cash flow before a borrower misses a payment. If a roadside stall owner buys fuel and stock each morning through OR channels and accepts digital payments via Krungthai, the transaction frequency acts as the credit score.

    That cross-ecosystem architecture brings operational friction. Merging customer profiles across three massive consumer databases requires strict compliance under Thailand’s Personal Data Protection Act, which governs explicit user consent, data correction, and deletion. Any technical glitch in how consent tags migrate across corporate systems can halt automated loan approvals at the point of sale.

    The Tech Stack Behind the Build

    Traditional lenders typically buy monolithic cores where a single product update takes months of regression testing. Vault Core operates differently by treating every account balance and transaction as an event-driven ledger entry, leaving the commercial logic in isolated microservices.

    Wannasit Chaiphinan, CTO of Clicx, said: “We selected Vault Core because we needed a core banking platform that gives our team the flexibility to develop products around our customers’ needs. Its cloud-native architecture separates product logic from the underlying core infrastructure, allowing us to configure, test and refine products in-house with less dependence on vendor-led changes.”

    For vendor Thought Machine, the contract adds Thailand to a regional footprint that includes client banks in Singapore, Malaysia, Vietnam, and the Philippines. The British tech firm recently crossed $100 million in annual recurring revenue with positive free cash flow, following a 57 per cent annual revenue gain.

    Pressure on Traditional Branch Networks

    The consortium model poses a clear threat to brick-and-mortar retail banking branches across suburban Thailand. While incumbent commercial banks pay commercial rents and staff teller counters to process small-business loans, Clicx uses the nationwide physical footprint of OR petrol stations and AIS customer service centres as passive marketing conduits.

    Retail merchants who already purchase stock inside the OR retail ecosystem gain an incentive to keep their working capital accounts within the same network. Traditional mid-tier lenders must either compress their loan origination margins or watch self-employed borrowers migrate to platform-native digital lines of credit.

    Consortium Timeline and Licensing Steps

    The Bank of Thailand published its roster of successful virtual bank applicants on June 19, 2025, capping the initial framework at up to three operating licences. Regulatory guidelines required winning consortia to establish secure IT systems, risk controls, and capital cushions before receiving final clearance to open customer accounts.

    The next concrete hurdle sits with the central bank inspectors, who must complete technical audits of the Vault Core integration and data privacy protocols before Clicx can formally accept public deposits and disburse its first commercial loans.

  • Kakao Swings to Net Profit of KRW 526 Billion

    Kakao Swings to Net Profit of KRW 526 Billion

    Kakao Corp lifted annual operating profit by 48 per cent to KRW 732 billion in 2025 as full-year revenue reached KRW 8.1 trillion, pulling the company out of a previous net loss.

    The platform operator closed the year with a net profit of KRW 526 billion, recovering from a KRW 162 billion deficit in 2024.

    Core messaging network KakaoTalk held 49 million monthly active users in South Korea at the close of the period, securing 97 per cent market share among domestic chat applications and reaching roughly 95 per cent of the national population. Total platform segment revenue rose 17 per cent to KRW 1.22 trillion. Within that unit, business messaging and advertising layer Talk Biz delivered KRW 627 billion, up 13 per cent year-on-year. Commerce operations brought in KRW 253 billion, an 8 per cent rise, supported by KRW 10 trillion in annual commerce gross merchandise value recorded in 2024.

    Offline checkout growth drives fintech gains

    Kakao Pay accumulated more than 42 million registered users and 23 million monthly active users through late 2025. Total payment volume climbed 12 per cent year-on-year to KRW 47 trillion in the third quarter of 2025, driven by a 46 per cent jump in offline checkout volume across physical retail merchants. Quarterly revenue at the payments arm rose 28 per cent, while average transaction frequency reached 75 transactions per user in the third quarter, representing a 43 per cent gain.

    Other operating units retained domestic dominance while pruning unprofitable digital ventures. Kakao Mobility maintained a 90 per cent share of the local ride-hailing sector with 9.2 million monthly active users on Kakao T, while rolling out cross-border transit booking service k.ride across 12 overseas markets. Banking arm Kakao Bank counted more than 24 million customers across its digital-only system, with the parent holding a 27 per cent stake. Kakao Entertainment closed its overseas web novel site Radish in late 2025 to focus resources on its primary platform Tapas and its controlling stake in K-pop label SM Entertainment, which Kakao acquired in 2023.

    Rivals challenge core local dominance

    Competition across consumer touchpoints in Seoul is intensifying from cross-town rival Naver and international players. Naver built its base on web search and e-commerce shopping directories, matching Kakao Pay directly in checkout processing while both groups target cross-border retail expenditure from outbound Korean travellers. Naver also paired with Uber to challenge the transport sector. That joint offensive lifted Uber’s share of ride bookings in Seoul to between 7 and 8 per cent, up from 3 to 4 per cent within a single year.

    Global search providers pose an additional threat to domestic retail footfall mapping. South Korean regulators cleared Google to roll out direct navigation features, dismantling historical data localisation curbs that previously shielded Kakao Map and Naver Map from overseas platforms. This shift exposes an interface that Korean retailers and food service outlets have used as a primary customer discovery channel.

    Legal clearances protect neobank stake

    The financial turnaround follows a disruptive corporate crisis that peaked in July 2024 with the arrest of company founder Kim Beom-su. State prosecutors charged Kim with manipulating SM Entertainment stock prices during a competitive bidding contest against entertainment agency HYBE, keeping him in custody for 100 days. A conviction risked triggering South Korean banking regulations that could have forced Kakao to sell down its 27 per cent holding in Kakao Bank.

    The Seoul Southern District Court acquitted Kim, Kakao Corp, and Kakao Entertainment of all charges in October 2025, ruling that the transaction did not constitute market manipulation. The decision removed the immediate operational threat to the digital banking unit, though prosecutors have filed an appeal to contest the ruling.

    Regulatory pressure remains elevated as antitrust officials examine concentration rules across digital marketplaces, transport, and app store ecosystems. To defend engagement, Kakao scheduled the consumer rollout of its proactive artificial intelligence assistant Kanana on iOS and Android devices, integrating conversational task management and commercial bookings straight into KakaoTalk chat threads.

  • Peppermint Bizmoto Partners with HaveIt to Power Transport Payments

    Peppermint Bizmoto Partners with HaveIt to Power Transport Payments

    Peppermint Bizmoto, the company operating the bizmoto e-wallet, has agreed to provide the payment processing infrastructure for HaveIt’s transport and consumer services ecosystem. Announced in November 2026, the deal links Peppermint directly to HaveIt’s passenger-matching mobility arm, Ride It.

    Peppermint secured its electronic money issuer licence from the Bangko Sentral ng Pilipinas in 2022, enabling it to issue digital wallets through the bizmoto app. Integrating its payment rails allows HaveIt to support passenger transactions while directing resources toward scaling its transport services.

    Neither party revealed a launch timeline or confirmed the specific payment methods passenger accounts will support. Integration will route consumer payments and transport bookings through the bizmoto infrastructure, letting HaveIt offload payment compliance while scaling its passenger fleet.

    Rider Economics and Transport Competition

    For HaveIt, running a transport network company without proprietary payment plumbing removes a heavy regulatory burden. Building an in-house clearing engine in the Philippines requires dedicated central bank clearances, capital reserves and continuous anti-money laundering compliance. Outsourcing the settlement layer to Peppermint hands HaveIt a ready-made digital wallet architecture without the overhead of maintaining an e-money issuer licence.

    Ride-hailing margins in Southeast Asia hinge on transaction friction. Platforms that force drivers and riders to jump through disconnected payment channels bleed market share to unified operators. Supplying direct digital payment rails across Ride It gives HaveIt a fighting chance to retain drivers who demand fast daily fare settlements.

    Merchant Rails and Sari-Sari Integration

    Peppermint brings more than consumer wallets to the arrangement. Its parent company, Peppermint Innovation, trades on the Australian Securities Exchange, while Peppermint Bizmoto received an electronic money issuer licence from the Bangko Sentral ng Pilipinas in 2022. By 2025, the operator established direct connectivity to InstaPay for real-time fund transfers across domestic commercial banks and competing digital wallets.

    Crucially for transport networks operating in dense urban centres, Peppermint also holds a central bank merchant acquisition licence. That clearance allows it to sign up neighborhood sari-sari stores to take QR Ph payments through bizmoto. Tying driver payouts into that neighborhood network creates an immediate cash-in, cash-out ecosystem on the ground.

    Building Transaction Scale Against Market Giants

    Independent e-wallets in the Philippines face extreme consolidation pressures. Dominant players control the vast majority of consumer wallet volume and consumer lending books across the archipelago. Smaller balance sheets cannot easily outspend those market leaders on consumer acquisition incentives.

    Peppermint’s play relies on embedded utility rather than standalone consumer marketing. Securing closed-loop transport platforms like HaveIt generates recurring transaction flow from daily commuters. Every daily ride booked through Ride It represents repeatable transaction volume running over Peppermint’s processing rails.

    What Operators Are Watching Next

    The immediate operational challenge sits in fare settlement mechanics. Transport network operators must settle cash balances with thousands of independent riders while managing digital transaction disputes and platform commissions. Speed of driver cashouts often decides which platform drivers keep switched on during peak commuting hours.

    Neither partner has released a firm launch date for the live wallet integration on the Ride It application, which will reveal the supported payment instruments and whether riders can tap QR Ph rails on day one.

  • 3 Southeast Asian Central Banks Partner on Cross-Border Digital Money Initiative

    3 Southeast Asian Central Banks Partner on Cross-Border Digital Money Initiative

    Central banks in Singapore, Malaysia and Thailand have formed a cross-border digital money partnership to standardise commercial acceptance and settlement across the three jurisdictions.

    The Monetary Authority of Singapore led the rollout of the initiative, operating under the name BLOOM, which stands for Borderless, Liquid, Open, Online, Multi-currency.

    Announced last Friday, the central banks of Malaysia and Thailand entered the programme as official policymaker participants alongside Singapore’s monetary authority. Commercial banks, merchant payment networks and financial technology providers across all 3 markets will work directly with the regulators to establish standard operating practices for multi-currency transactions.

    Setting Terms for Regional Digital Settlement

    Work under the framework focuses on defining how distinct forms of digital money can clear, settle and exchange without institutional friction across borders. Participating teams will address three concrete tracks: cross-border acceptance and settlement mechanisms, technical interoperability between domestic payment systems, and programmable transaction controls.

    Implications for Cross-Border Merchants

    For cross-border retailers and online marketplace platforms operating across the Singapore-Malaysia-Thailand corridor, disparate clearing mechanisms create structural working capital delays. Wholesale clearing channels often demand days to convert and settle local balances.

    By establishing common protocols for programmable and digital currencies, central banks are testing ways to bypass fragmented correspondent banking relationships. The operational risk sits in technical compliance, where commercial operators must adapt their checkout infrastructure to central bank specifications while managing distinct domestic regulatory requirements across each border.

    The Trajectory of Southeast Asian Payments

    The BLOOM framework builds on existing cross-border links established across the region over recent years. While those early retail integrations connected consumer smartphone apps for tourist spending, they relied on conventional commercial bank rails behind the scenes.

    BLOOM shifts the focus from consumer front-ends to the core settlement layer, evaluating programmable digital tokens to automate settlement conditions directly. The test phase will determine operational guidelines, with the participating regulators due to outline technical specifications and initial private-sector pilot results in upcoming joint releases.

  • Salesforce Finds No Vulnerability in AU Small Finance Bank Leak

    Salesforce Finds No Vulnerability in AU Small Finance Bank Leak

    Salesforce found no platform security vulnerabilities following a suspected customer data leak at India’s AU Small Finance Bank, the enterprise software company said on Saturday.

    AU Small Finance Bank opened an internal inquiry after extortion outfit ScarlettGroup claimed on Thursday to possess vehicle loan files hosted on external software.

    The lender confirmed that core banking infrastructure remains unaffected, isolating the inquiry to third-party software while branch operations continue normally across the domestic network.

    Disputed Access to Vehicle Loan Records

    Threat intelligence platform Hackmanac reported that ScarlettGroup threatened to leak sensitive records taken from the bank’s perimeter. The claimed haul covers customer identity paperwork including PAN and Aadhaar records, signed loan contracts, credit bureau evaluations, bank statements, and staff credentials.

    Salesforce maintains that the software platform itself shows no technical failure. The company stated that it does not discuss individual client deployments as a matter of policy, though technical teams are assisting the lender during the review.

    Verification of the stolen dataset remains unresolved. Threat actors frequently publicise sample files to force negotiations before corporate defenders assess whether the exposed folders came from active systems, older backups, or third-party brokers.

    Consumer Credit Exposure

    Vehicle financing represents one of the most document-heavy consumer lending categories in India. Lenders assemble physical identity proof, income validation, and collateral records for every vehicle financed on the road.

    A confirmed release of identity documents creates direct exposure for borrowers through identity fraud and fake account openings. For consumer retail finance desks, third-party software integrations represent an operational weak point because corporate security teams hold less visibility over vendor-managed environments.

    Lenders across the market increasingly deploy third-party cloud tools to speed up credit checks and field sales. That architectural shift cuts credit approval times at car dealerships, but it scatters applicant personal data beyond internal bank servers.

    Institutional Warning Over Financial Threats

    Indian authorities have stepped up scrutiny on digital finance infrastructure following recent breach reports across major retail lenders. Commercial institutions including State Bank of India and ICICI Bank faced suspected digital incidents during recent security reviews.

    Prime Minister Narendra Modi addressed the exposure on October 25, warning that cyber intrusions target financial system stability. The warning came during the launch of the Reserve Bank of India’s Rs 169-crore data facility and cybersecurity institute in Bhubaneswar.

    The central bank has pushed commercial lenders to run frequent perimeter tests and review vendor risk governance. Bank boards face stricter compliance requirements when consumer identity documents sit on hosted third-party services.

    Outstanding Verification by Security Teams

    Investigators from AU Small Finance Bank and external response teams continue examining server logs to establish how files were pulled from the system. The scope of customer accounts exposed during the incident remains unconfirmed by the lender.

  • Stricter Bank Underwriting Shifts Credit to Fintech Lenders

    Stricter Bank Underwriting Shifts Credit to Fintech Lenders

    Stricter bank approval standards are steering younger borrowers toward buy now, pay later (BNPL) services, microloans and digital lenders, according to a report from MoneyHero.

    Inflation-driven repayment concerns prompted banks to tighten underwriting and collections, AB Capital Securities noted in an October 2026 commentary. Meanwhile, fintech platforms are deploying alternative data to reach underserved customers.

    A July reopening of online lending licenses by the Securities and Exchange Commission (SEC) could accelerate this migration as more digital competitors enter the market.

    Alternative Screening Fills Bank Deficit

    Digital finance providers rely on alternative data points, including e-commerce transactions and mobile wallet activity, to approve shoppers bypassed by established lenders. Traditional credit bureaus cover only a minority of the population, leaving retail merchants dependent on app-based checkout credit to maintain consumer ticket sizes.

    Smaller transaction sizes typical of buy now, pay later services protect initial loan performance. However, repeat checkout usage by debt-laden shoppers facing persistent inflation creates hidden credit concentrations across unregulated platforms.

    Licensing Reopening Accelerates Platform Entry

    Platform competition intensified after the Securities and Exchange Commission reopened online lending license applications in July. The end of the regulatory moratorium brings fresh capital into mobile instalment lending, multiplying financing options at online and physical retail checkouts.

    The expansion presents operational friction for merchants managing multiple checkout payment integrations. Retailers gaining top-line volume through digital loans risk margin erosion if platforms raise processing charges to cover rising portfolio delinquencies.

    Underwriting Quality Replaces Volume Growth

    Vehicle dealership loan approvals have slowed alongside stricter bank reviews, showing early stress in high-ticket consumer debt. That slowdown confirms that household balance sheets are weakening, even as point-of-sale microloans maintain high headline volume.

    Bank credit screening historically protected established institutions during inflation spikes, while pure-play consumer credit apps absorb higher credit loss rates. The current divergence tests whether algorithm-driven microloans can maintain repayment rates without conventional collateral or documented payroll income.

    The Timeline to Watch

    Consumer platform operators are positioning portfolios ahead of anticipated capital market deadlines. Digital finance operator Maya targets an initial public offering in 2027, making portfolio quality and loan book yields critical metrics for private investors over the coming quarters.

    The immediate metric to monitor will be early delinquency rates across fintech balance sheets through the next quarterly reporting round, which will show whether alternative underwriting can outlast prolonged consumer price pressures.

  • Binance Pursues Malaysia Licence Following Five-Year Regulatory Ban

    Binance Pursues Malaysia Licence Following Five-Year Regulatory Ban

    Binance opened talks with Malaysian regulators to secure a domestic operating licence, aiming to reverse a five-year market shutout triggered by an enforcement ban in July 2021.

    The exchange engaged the Securities Commission Malaysia and Bank Negara Malaysia across a ten-month dialogue to establish a compliant business model. Domestic regulators previously blocked access to the platform’s mobile applications and domain names after finding it operated an illegal exchange. That enforcement package banned local marketing campaigns and cut consumer access to official community channels.

    The discussions unfold alongside broader industry fallout after Binance suffered a record US$6.3 billion security breach this week, forcing the platform to halt withdrawals and pledge full reimbursement for customer losses.

    Ten Months of Direct Regulatory Engagement

    The dialogue between the exchange and domestic authorities focuses on establishing an onshore corporate structure. Malaysian digital asset rules require exchange operators to win registered market operator status before taking local retail deposits. The company declined to detail the specific licence category requested during the ongoing filings.

    Earlier regulatory actions created a difficult starting point. The Securities Commission removed Binance from its public Investor Alert List earlier in 2024 before reversing course and re-listing the exchange in October without a stated rationale. Central bank officials maintain strict oversight on ringgit-denominated conversions to prevent unauthorized capital flows across regional borders.

    Cross-Border Peer-to-Peer Scrutiny

    Scrutiny over currency controls escalated when Malaysian lawmaker Lim Guan Eng sent a formal inquiry to the Securities Commission in September. The complaint asked officials to examine whether traders used foreign-currency listings on peer-to-peer markets to move ringgit outside approved channels. His office released that correspondence publicly on October 31.

    Management pushed back against allegations of systemic exchange violations while adjusting product availability. The platform confirmed it disabled a Papua New Guinea kina trading board that users unofficially tied to ringgit pricing, acting directly on regulatory feedback. It categorized a separate Romanian leu trade as a single unauthorized posting by a foreign account.

    Competitive Shift Across Southeast Asian Exchanges

    Securing licensed access in Malaysia would change how retail fintechs and onshore exchanges compete for digital asset volumes in Southeast Asia. Domestic operators run under tight capital mandates, serving a conservative retail market that values local deposit insurance and ringgit bank rails. An approved Binance presence would bring institutional liquidity directly into a market that previously pushed crypto investors toward offshore channels.

    Operating risk remains elevated following technical vulnerabilities across international infrastructure. Binance suspended withdrawals and committed to covering client funds after suffering a US$6.3 billion security breach, the largest recorded theft in the sector. Malaysian regulators scrutinize platform solvency and custody tools closely, meaning any security failure abroad reduces the probability of a swift domestic licence grant.

    Past Enforcement Actions and Unresolved Hurdles

    The path back to Malaysia follows half a decade of regulatory friction. The Securities Commission ordered the exchange to halt domestic operations in July 2021 after finding it solicited retail investors without registration. That order shuttered local customer service groups on Telegram and halted web marketing targeting domestic users.

    Decisions now rest with the Securities Commission and Bank Negara Malaysia on whether the platform meets custody and capital requirements. The primary metric to track is whether the Securities Commission issues an agreement in principle or removes the operator from its active alert directory.

  • Bank of Thailand Proposes Strict One-to-One Reserves for Baht Stablecoins

    Bank of Thailand Proposes Strict One-to-One Reserves for Baht Stablecoins

    The Bank of Thailand proposed draft rules requiring baht-denominated stablecoin issuers to back tokens 1:1 with bank deposits and prohibited them from paying interest to holders.

    Redemptions must clear within one business day under the central bank’s consultation paper, stripping out speculative yield features to force issuers into functioning strictly as payment tools.

    Cash Reserves and Redemption Rules

    Under the initial phase of the framework, issuers must place all reserve assets in commercial bank accounts. The central bank stated that each issued token requires a full baht counterpart on deposit to guarantee liquidity when users exit to fiat currency.

    Later stages could permit issuers to diversify backing into other high-quality liquid assets such as short-dated government securities. For now, capital remains locked exclusively in standard accounts.

    Holders will receive zero yield. The paper bars issuers from providing direct or indirect incentives, interest payments, or returns calculated against holding duration or token balances.

    The role of the digital payment tool should be clearly distinguished from financial products that offer returns on holdings. The restriction aims to ensure that THB stablecoins function as a means of payment rather than a savings or investment product, the consultation paper stated.

    Licensing Under the Finance Ministry

    The central bank recommended that Thailand’s Ministry of Finance formally designate token issuers and custodial wallet operators as payment service businesses. That designation pulls every participant directly beneath central bank supervision before they can launch commercial services.

    Regulators also want the legal authority to cap the total number of licensed issuers operating in Thailand. Fragmented liquidity across dozens of corporate tokens would weaken settlement stability and leave merchant gateways juggling incompatible digital currencies.

    Wallet providers and token operators must install anti-money laundering controls alongside know-your-customer and know-your-merchant checks. Systems must flag suspicious flows and maintain cyber safeguards equivalent to retail banking networks.

    Automated Settlements and Retail Reality

    Commercial banks and payment aggregators already run PromptPay across Thailand, processing high-volume consumer payments at near-zero fees. A baht stablecoin does not exist to replace that daily point-of-sale infrastructure.

    The central bank pointed instead toward programmable commerce built on distributed ledgers. Smart contracts could automate escrow payments, releasing merchant disbursements only after a freight carrier confirms final delivery of goods.

    For enterprise treasuries, programmable tokens eliminate multi-day corporate settlement delays without taking on foreign-exchange volatility. Yet by banning interest, regulators have eliminated the primary mechanism decentralized finance protocols use to attract commercial liquidity.

    What to Watch Next

    Thailand is choosing a defensive stance that protects retail deposits rather than testing financial engineering.

    The policy document follows years of steady payments modernization in Thailand, moving from paper cash to QR codes under state supervision. Permitting private corporate tokens without strict balance sheet anchors would reverse that consumer protection stance.

    The Bank of Thailand is now gathering public industry feedback on the consultation paper before submitting formal statutory recommendations to the Ministry of Finance.

  • Southeast Asian Startups Face Capital Shortage as Investment Shifts to US and China

    Southeast Asian Startups Face Capital Shortage as Investment Shifts to US and China

    Southeast Asian startups face an acute capital shortage as venture funding shifts toward technology markets in China and the U.S. Investors pulled back after the pandemic as capital costs rose, leaving regional operators struggling to expand beyond domestic borders.

    The downturn hits businesses that attracted capital during the early 2020s, when young populations, rapid economic growth, and wider mobile phone use initially drew international funds.

    Global Capital Diverts to Artificial Intelligence

    Venture capital allocations redirected sharply toward artificial intelligence in the U.S. And China, while governance scandals in Indonesia and opaque legal systems compounded the regional retreat.

    Higher global capital costs compounded the contraction. Investors who once funded multi-market rollouts across the region now demand immediate cash flow generation and tighter overhead controls from portfolio companies.

    Regulatory Friction and Market Limits

    Structural barriers inside regional economies limit cross-border scaling for young firms. Founders and investors point to opaque bureaucracy, restrictive legal frameworks, and persistent friction in attracting foreign entrepreneurial talent as recurring obstacles across key markets.

    Regional fragmentation forces businesses to navigate distinct regulatory regimes in each country. That friction prevents local software, retail tech, and platform businesses from reaching the scale required to appeal to global investor syndicates.

    Governance Concerns Dampen Investor Appetite

    High-profile corporate governance scandals, particularly in Indonesia, damaged institutional confidence across the regional startup ecosystem. Due diligence processes lengthened substantially as international funds reassessed risk premiums across Southeast Asian growth assets.

    The current retreat follows an aggressive capital influx during the early 2020s. Cheap capital, young populations, fast-growing national economies, and accelerating smartphone adoption drove heavy valuations across regional platforms during that cycle.

    Scrutiny Centers on Near-Term Profitability

    Venture funds operating in the region are conditioning fresh financing rounds on unit-level profitability rather than top-line transaction volume. Early-stage and growth-stage companies face compressed valuations as they adjust burn rates to survive extended funding gaps.

    Founders across Southeast Asia now face the task of securing bridge rounds and domestic capital before existing cash reserves run out.

  • GCash Allocates 60% of IPO Cash to Challenge Informal Lenders

    GCash Allocates 60% of IPO Cash to Challenge Informal Lenders

    GCash operator Mynt will deploy 60 percent of its primary IPO proceeds into consumer lending, targeting the informal loan market across the Philippines.

    The digital wallet counts 41.5 million monthly active users, but only 7.5 million borrow through its platform. Converting the remaining 34 million registered users into active credit customers forms the central growth pitch to equity investors ahead of listing.

    Mynt runs its credit operations through Fuse Financing, offering micro-credit products like GLoan Sakto for sums as low as 100 pesos and Borrow Load for 20 pesos. More than 90 percent of the user base falls within the lower C2DE socio-economic brackets, where daily cash flow needs mirror sachet retail buying habits. Frost & Sullivan data compiled for the listing shows roughly 40 percent of borrowing Filipino adults relied on informal credit in 2025, including unregulated 5-6 money lenders who demand 20 percent nominal interest rates on short-term advances.

    Sachet credit replaces street lenders

    Digital wallets across Southeast Asia have shifted from simple payment rails to balance-sheet lending to offset margin compression on transfers and merchant settlements. Singapore-based Grab, Indonesia’s GoTo and regional digital banks all pursued similar transitions, yet few command the domestic user dominance GCash holds in its home market. By pushing loan sizes down to 100 pesos, Fuse Financing mirrors the Philippine retail distribution model of selling daily goods in small packets.

    This micro-lending model shifts customer acquisition costs almost to zero because borrowers already transact on the core app. Traditional Philippine banks struggle to service sub-1,000-peso tickets profitably due to branch overheads and manual underwriting costs. GCash automates that screening using its proprietary GScore credit assessment and an automated voice bot called GINA to manage collection calls.

    Rising share of digital lending revenue

    Lending generated 28.52 billion pesos in 2025 after expanding at a two-year compound annual rate of 67.1 percent. That performance lifted credit from 35.8 percent of adjusted revenue in 2025 to 41.8 percent during the first half of 2026. Payments generated 50.34 billion pesos, or 63.2 percent of 2025 revenue, but lending expansion now drives top-line momentum as total loan assets hit 70.5 billion pesos in June 2026.

    “There’s money in serving them,”

    Mynt president and chief executive Martha Sazon told investors at an October 6 briefing, pointing to unbanked consumer segments as the primary engine for the next growth cycle.

    Credit loss provisions and default risks

    Rapid loan book expansion brings balance sheet volatility. The company booked 12.62 billion pesos in provisions for credit losses in 2025, absorbing 44.3 percent of its lending revenue that year. First-half 2026 provisions reached another 7.93 billion pesos.

    Non-performing loans stood at 4.9 percent in June 2026, falling from 7.5 percent in 2025 and 9.2 percent in 2023. Fuse Financing chief executive Tony Isidro told brokers he remains comfortable holding delinquent loans within single-digit bands while migrating borrowers away from informal street lenders. Managing those defaults will dictate whether lending remains an earnings generator or becomes a capital drag as net income growth slowed to 7.3 percent year-on-year in the first half of 2026.

    Premium valuation on the trading floor

    The company priced its initial public offering at 6.60 pesos per share, implying an equity valuation of roughly 442 billion pesos. That prices Mynt at 25.7 times its 2025 net earnings, commanding a premium over global peers such as PayPal and Brazil’s Nu Holdings. Institutional demand oversubscribed the offer during the retail bookbuild.

    Market participants will test that valuation when shares begin secondary trading on Tuesday, October 20 under the ticker symbol GCASH.

  • Philippine Cash on Delivery Share to Stay Above 20 Percent Through 2027

    Philippine Cash on Delivery Share to Stay Above 20 Percent Through 2027

    Cash on delivery will account for more than 20 percent of Philippine e-commerce transactions through 2027. That keeps the country as Southeast Asia’s most cash-reliant online shopping market, according to payments gateway Xendit.

    Physical cash currently represents 23 percent of online transaction value on Xendit’s Philippine platform. That figure outstrips all five other Southeast Asian markets surveyed in its joint report with market research firm Cube.

    Across Southeast Asia, cash on delivery is projected to fall below 25 percent of total e-commerce gross merchandise value next year. The Philippines will remain the only major regional market where paper currency holds over a fifth of checkouts.

    Cash Holds 23 Percent Share

    A persistent unbanked population, limited formal credit, and fear of delivery fraud slow the shift away from cash. In a survey of 6,000 online shoppers across six regional markets, including 1,000 in the Philippines, 12 percent of Filipino buyers said nothing would convince them to stop using cash on delivery. That group is double the size seen in neighboring countries.

    Shopper habits are shifting at the margin. About 33 percent of surveyed Philippine consumers reported using cash on delivery less frequently than a year ago. Discounts and cashback offers prompt them to try digital alternatives. Long-term retention still requires fast refunds and fraud protections.

    “Looking ahead, across the whole Southeast Asia, COD payments will actually fall below 25 percent of all e-commerce payments, but the Philippines will still probably be one of the fewer markets that are going to be above 20 percent,” said Ina Gatan, head of go-to-market at Xendit Philippines.

    QR Ph and Bank Transfers Surge 198 Percent

    Account-to-account payments are capturing what physical cash loses. Transaction volume settled via QR codes and direct bank transfers increased 198 percent between January 2025 and April 2026 across Xendit’s merchant network.

    National payment rails QR Ph and InstaPay drove the surge. QR Ph alone processed roughly 13 percent of total Philippine e-commerce value on the platform during the period. The standard lets merchant QR codes take payments across competing banking apps and digital wallets without custom point-of-sale setups.

    Digital wallets grew by 3 percent over the same 16-month timeframe. E-wallets already dominate Philippine digital checkouts. That leaves little room for rapid percentage gains compared to account-linked instant clearing schemes.

    Cross-Border Retail Lags Regional Neighbors

    Reliance on cash creates an operational barrier for international merchants selling into the country. Cross-border purchases represented only 9 percent of total Philippine online retail volume in 2026. Only Indonesia recorded a lower share at 6 percent.

    Higher digital adoption elsewhere fuels international orders. Cross-border sales accounted for 19 percent of online retail in Singapore, 15 percent in Thailand, 14 percent in Vietnam, and 12 percent in Malaysia. Foreign sellers rarely accept cash on delivery because of return logistics risks. That shuts uncarded Philippine consumers out of international storefronts.

    Southeast Asian cross-border e-commerce is projected to expand between 11 and 19 percent annually through 2030, assuming regional instant payment linkages and customs procedures improve. Merchants relying purely on upfront card or wallet payments will miss a fifth of Philippine demand until alternative rails provide instant buyer protection.

    Roadblocks to Digital Settlement

    Handling cash on delivery imposes heavy costs on logistics providers and retailers. Couriers face higher failed-delivery rates, delayed settlement cycles of up to seven days, and cash-handling risks that drive up freight rates across the archipelago.

    Couriers and platforms have introduced OTP verification at delivery and partial advance deposits to curb return rates. Even so, Valerie Cai, head of marketing at Xendit, estimated that bringing the Philippine cash-on-delivery ratio below 20 percent will require several years of sustained infrastructure rollouts.

    Total Southeast Asian e-commerce merchandise value reached $197 billion in 2025, up from $3 billion in 2012, with Cube forecasting the market to pass $400 billion by 2031. The pace of payment digitization across the Philippine archipelago will determine how much of that regional growth turns into merchant profit rather than delivery losses.

  • Philippine Fraud Cases Stall as 71 Percent of Online Scam Victims Never Report Losses

    Philippine Fraud Cases Stall as 71 Percent of Online Scam Victims Never Report Losses

    Philippine cybercrime prosecutors face widespread case abandonment. More than 70 percent of scam victims fail to report financial losses or decline to testify in court. Law enforcement officials revealed the bottleneck at an anti-scam forum hosted by the Bangko Sentral ng Pilipinas on October 12.

    A 2026 Global Anti-Scam Alliance survey of 1,160 Filipino adults showed that 15 percent suffered direct financial losses from fraud. Only 29 percent reported the incidents to authorities. Complainants who file reports frequently abandon proceedings before trials start.

    Prosecution Hurdles in Digital Fraud Cases

    Investigators routinely prepare filings only to have victims withdraw cooperation, said Department of Justice Office of Cybercrime Assistant Director Chris Jark Ace Maño. Without victim participation, prosecutors cannot establish legal damage. They cannot secure fraud convictions under Philippine evidentiary rules.

    Even after successful raids on illicit call centers and fraud rings, state attorneys often must downgrade charges to human trafficking, according to National Bureau of Investigation Financial Intelligence Unit Chief Minerva Sobreviga-Retanal. Courts require the aggrieved party to appear as witnesses to sustain criminal deceit charges.

    Tracing illicit funds requires immediate intervention before capital leaves traditional banking rails. Sobreviga-Retanal warned that victims waste crucial hours when they try to investigate fraud independently. That delay allows proceeds to move through virtual asset channels and cryptocurrency wallets within milliseconds.

    Rising Losses Across Younger Demographics

    Demographic shifts complicate defense across digital retail channels. Cybercrime Investigation and Coordinating Center Executive Director Renato Paraiso noted that digital fraud no longer affects older consumers alone. Gen Z, Millennials, and Gen Alpha users fall victim at increasing rates due to overconfidence on digital platforms.

    Senior executives face the same exposure on unverified marketplaces. Google Philippines Country Manager Prep Palacios disclosed at the forum that she lost PHP 90,000 to a rogue online merchant who vanished immediately after collecting payment.

    “I’m a tech executive, and I was still fooled,” she told the same forum.

    Impact on Digital Commerce and Payment Gateways

    Low reporting rates obscure the genuine scale of merchant fraud for Southeast Asian e-commerce marketplaces and digital wallet operators. Unreported losses prevent payment gateways from blacklisting suspect accounts. Fraudulent merchant profiles then stay active across peer-to-peer selling channels.

    Platform operators face stricter compliance expectations from regional central banks as fraud schemes evolve from simple phishing to social commerce diversion. Marketplaces that fail to enforce escrow settlement mechanisms leave buyers vulnerable to off-platform payment requests.

    A lack of victim follow-through also reduces legal deterrents for syndicates operating out of domestic hubs. When criminal operators evade fraud convictions, they frequently re-establish operations under new corporate identities within weeks.

    Regulatory Pressure on Merchant Verification

    The Bangko Sentral ng Pilipinas continues to press financial institutions for faster account-freezing protocols to intercept disputed transfers before conversion into digital assets. Regional banks have tightened real-time transaction screening. Still, consumer reluctance to participate in court cases leaves systemic fraud networks intact.

    Enforcement agencies are now assessing streamlined digital reporting mechanisms to reduce court appearance burdens for defrauded buyers. The central bank plans to review inter-agency transaction dispute frameworks before the close of the current fiscal quarter.

  • Bukalapak Posts IDR 821 Billion Half-Year Loss on Investment Decline

    Bukalapak Posts IDR 821 Billion Half-Year Loss on Investment Decline

    PT Bukalapak.com Tbk reported a net loss of IDR 821 billion for the first half of 2026 in Jakarta, dragged down by an IDR 1.74 trillion investment loss.

    The result followed a loss of IDR 426 billion in the first quarter and a further shortfall of IDR 395 billion in the second quarter. Top-line performance moved in the opposite direction, with revenue rising nearly 30 percent year on year to IDR 3.99 trillion across the six-month period.

    Gaming Carries Top-Line Growth

    Gaming generated IDR 3.48 trillion during the half, making up 87.31 percent of total revenue. The division delivered an operating profit of IDR 76.3 billion, anchoring the company’s core earnings.

    Online-to-offline operations brought in IDR 326 billion in revenue and generated an operating profit of IDR 10.45 billion. Retail revenue contributed IDR 139 billion, while investment income added IDR 44.4 billion and corporate revenue stood at IDR 1.83 billion.

    Investment Portfolio Weighs on Corporate Segment

    Losses in non-core units offset the gains made by gaming and merchant networks. The corporate division posted the steepest deficit at IDR 885 billion, primarily reflecting the IDR 1.74 trillion drop in the value of its investment holdings.

    Financial statements showed a net cash outflow of IDR 2.32 trillion from investing activities during the half. Bukalapak directed IDR 3.07 trillion toward additional investments and allocated IDR 70 billion in capital injections to associated entities.

    Shift Away From Marketplace Operations

    Bukalapak exited its traditional e-commerce marketplace in early 2025. That decision eliminated the heavy merchant subsidies and logistics spending that weighed on cash flow for years, reorienting the business toward digital item distribution and treasury management.

    The pivot leaves the Emtek Group-backed company operating more like an asset allocator with a digital entertainment distribution engine than a conventional shopping platform. While gaming provides cash generation, corporate earnings remain exposed to public equity valuations and mark-to-market adjustments.

    Digital Banking Exposure and Market Pressure

    Much of that valuation pressure stems from listed holdings acquired during the tech boom. Bukalapak has held an 11.49 percent equity stake in PT Allo Bank Indonesia Tbk since January 2022, when the digital lender traded above IDR 5,000 per share.

    Shares in the digital bank have fallen to IDR 900 each, dropping almost 40 percent since the start of 2026. Investors will watch whether the board adjusts its marketable securities portfolio before third-quarter financial results are filed later this year.