Tag: FinTech

  • Samsung to take eight C-Lab start-ups to CES

    Samsung to take eight C-Lab start-ups to CES

    Samsung Electronics will introduce eight in-house artificial intelligence (AI) start-ups at the Consumer Electronics Show (CES) 2019 to take place next month in Los Angeles, the company said Wednesday. All eight start-ups are under Samsung’s C-Lab, an in-house incubating program that allows employees to embark on a one-year project to realize a business idea. Samsung will organize an independent booth to present their products and services at the four-day exhibition scheduled to take off on Jan. 9.

    All eight of the projects use AI as a core part of their business.

    For example, the mobile app SnailSound uses AI technology to remove background noise and provide clear human voices in a tailored way based on the app’s test results of the user’s hearing abilities.

    Another app called Medeo uses AI to select the best shots in a video while it is being shot.

    Prismit is an AI-based news app that shows news articles of the same topic automatically aligned in the form of a timeline.

    The list also includes Girin Monitor Stand, which helps to correct posture while sitting in front of computer screens, and the Alight desk light, which adjusts light in the best way to enhance one’s concentration.

    The Perfume Blender suggests the best perfume recipe based on a user’s preferences and also comes with a device to make the personalized perfume.

    As well as the eight in-house start-ups that are currently working under Samsung’s C-Lab, eight groups that have already graduated from the scheme will take part in CES 2019 to set up booths of their own.

    Among them, three have earned awards from this year’s CES. Since the program’s launch in 2012, C-Lab has produced 36 spin-offs that now conduct business as start-ups outside of Samsung.

  • First Binance Blockchain Week Set for Singapore Next Month

    First Binance Blockchain Week Set for Singapore Next Month

    About 2,000 people from around the world are expected to attend the inaugural Binance Blockchain Week in Singapore on Jan. 19-22. The conference, which will take place at the Sands Expo and Convention Centre in Marina Bay Sands, is presented by Binance, the world’s leading cryptocurrency exchange.

    The high-profile event will serve as a platform to bring together regulators, investors, academics, entrepreneurs and technologists to discuss the current blockchain ecosystem and encourage sustainable growth in the industry.

    Binance Blockchain Week will feature more than 70 speakers, including thought leaders, top executives, academics and heads of state in a productive, yet exciting program filled with keynote speeches, panel discussions, fireside chats and exclusive networking events.

    Confirmed speakers include Changpeng Zhao, the founder and chief executive of Binance; Genping Liu, partner at Vertex Ventures; Justin Chow, head of business development, Asia at Cumberland; and Sonia Bashir Kabir, managing director of Microsoft Bangladesh, Myanmar, Nepal, Bhutan and Laos.

    “We are thrilled to host the first ever Binance Blockchain Week in Singapore, the finance and technology hub of Asia. Gathering the most notable players and thought leaders in blockchain, this will be a defining event. We look forward to many thought-provoking discussions and debates on how we can further work together to move the industry forward,” Zhao said.

    There will also be an expo featuring more than 50 booths for sponsors to showcase the best blockchain and cryptocurrency technologies.

    Secure Asset Funds for Users Hackathon

    The inaugural Binance SAFU Hackathon, which aims to seek innovative blockchain solutions to secure crypto assets, will take place at the offices of PricewaterhouseCoopers Singapore in Marina One East Tower on Jan. 19-20.

    The panel of judges includes PwC, blockchain accelerator program Tribe Accelerator and Binance Labs. Participants will have the opportunity to receive mentorships from senior leaders at companies such as the Ethereum Foundation, Primitive Ventures, Earn.com, Binance Labs and IDEO CoLab.

    Individuals and teams interested in participating in the event can submit their applications between Dec. 10 and Jan. 6.

    Twenty developer teams will be selected via pre-hackathons and direct registration on the event website. Pre-hackathons will be held around the world between December and early January.

    Only winning teams will qualify for free passes to the final SAFU Hackathon in Singapore.

    The teams winning the final will share a prize pool of $100,000 in Binance Coin (BNB) courtesy of Binance.

    For more information, check out the Binance Blockchain Week Facebook page or the cryptocurrency exchange’s Twitter profile.

  • Bukalapak Joins Hands With Tanamduit to Sell Mutual Funds Online

    Bukalapak Joins Hands With Tanamduit to Sell Mutual Funds Online

    E-commerce platform Bukalapak has partnered with online investment platform Tanamduit to introduce mutual fund products to first-time retail investors. The partnership will see local asset management firms Bahana TCW Investment Management, Batavia Prosperindo Asset Management and Sucorinvest Asset Management offer five new investment products, ranging from equity to fixed-income funds, on Bukalapak’s mutual funds platform BukaReksa.

    At its launch in January 2017, BukaReksa only featured money market fund products offered by CIMB Principal Asset Management and Mandiri Manajemen Investasi.

    But to capture a larger market, Bukalapak joined hands with finance marketplace Bareksa in December 2017, adding four more asset management firms, Kresna Asset Management, Syailendra Capital, Ciptadana Asset Management and BNP Paribas Investment Partners, to the platform

    BukaReksa now features nine asset management firms offering 21 investment products, compared with Bareksa, which has 31 asset management firms offering 160 investment products.

    “We hope our partnership with Tanamduit can boost financial literacy and investment in the country,” said Destya Danang Pradityo, head of payment and financial services at Bukalapak.

    Through the BukaReksa platform, customers can invest from as little as Rp 100,000 to Rp 1.5 million ($7-$104) in mutual funds.

    Destya said BukaReksa has at least 120,000 registered customers, with around half of them active investors from across the archipelago.

    “We believe online investment will become part of our lifestyles. Our collaboration with Bukalapak forms part of our mission to educate people on the benefits of investing,” said Muhammad Hanif, business development director at Tanamduit.

    With rapid technological development and the growth in online transactions, e-commerce players see opportunities to provide various services, including financial and investment products. This has seen the emergence of fintech startups offering mutual fund investment has been a trend over the past three years.

    Aside from Bukalapak, other online marketplaces also joined hands with Bareksa, such as Tokopedia, which in April this year launched Tokopedia Reksadana, offering mutual funds through local asset management firm Syailendra Capital.

    Another fintech startup, Invisee, has also been offering mutual fund products online in partnership with various asset management firms since last year.

    According to Halim Haryono, deputy director of investment supervision and development at the Financial Services Authority (OJK), the number of people investing in mutual funds increased 16.25 percent year-on-year to about 930,000 by October this year, due to the rise of online mutual fund marketplaces.

    Only about 400,000 people invested in mutual funds in 2016, Halim said.

  • Vietnamese government will share risks with startups, PM assures

    Vietnamese government will share risks with startups, PM assures

    The Vietnamese government is willing to make changes in regulations to facilitate timely funding of startups, Prime Minister Nguyen Xuan Phuc said. Addressing at the Youth Startups Forum 2018 in Hanoi on Thursday, he acknowledged the challenges that Vietnamese startups have highlighted, saying that it is the task of authorities to find a breakthrough solution for creative entrepreneurs to start and run a business.

    He asked the Ministry of Planning and Investment, the Ministry of Science and Technology, the Ministry of Finance and the State Bank of Vietnam to create more favorable conditions for startups by making changes in the legal framework.

    “We need a breakthrough innovation in policies from government bodies to help startups succeed with their ideas,” he told the forum, which attracted 300 entrepreneurs from across the country.

    The government is willing to share a part of the risks with startups, the PM added.

    He asked relevant ministries and other agencies to report in detail next month on the solutions they have identified for the problems that industry insiders have highlighted.

    Vietnam has seen an increasing number of startups in recent years. The country’s speed of startup development ranks third among ASEAN members. But regulatory obstructions are hindering their ability to attract funds they need to establish themselves and thrive in the market, entrepreneurs said at the forum.

    Thach Le Anh, founder of Vietnam Silicon Valley, a government-backed organization aiming to stimulate the growth of startups, said that angel investors are reluctant to invest due to a lack of incentives in tax and policies. Angel investors are people who inject money into a new business in the early stage.

    The early financial support is crucial for a startup to succeed, Anh said.

    Nguyen Manh Dung, a representative of the investment fund CyberAgent Veuntures in Vietnam, also said that many investors want to invest in Vietnam’s startups, as larger markets like the U.S., Japan and China require bigger capital and fewer opportunities.

    Investors are also reluctant about later stage investments, when profits can be extracted, because of slow administration procedures, he said.

    Disbursement procedures in Vietnam could take from six months to a year while the very nature of startups is that they need to act fast, he added.

    Dung also said that divestment was one the main concerns that investors have.

    “These challenges take opportunities away from startups,” he said.

    Dam Quang Thang, CEO of AgriTech Village, a company which assists local startups in agriculture, said that although startups often use new technological solutions, they have to go through a traditional testing method, which is more time consuming than it should be.

    A representative of Vietinbank, Vietnam’s fourth-biggest listed bank by market capitalization, said tight bidding procedures and long financial checks were preventing the bank from investing in a tech startup.

    “Startups struggle to sell their products to investors as they have to go through the traditional process. There must be a better way for them to sell their new solutions,” the representative said.

    Last year, Vietnamese startups received $300 million in investments in 92 different deals, according to startup accelerator program Topica Founder Institute (TFI).

  • Momo becomes first Vietnamese Fintech 100 firm

    Momo becomes first Vietnamese Fintech 100 firm

    Vietnam’s mobile, electronic wallet and payment application Momo is among the top 100 innovative fintech companies in the world. This is the first time a Vietnamese firm has broken into this special group, positioned 84th. Momo is also in the “Emerging 50” category, which includes newer companies that are at the forefront of innovative technologies and practices.

    Its products help customers in Vietnam make nationwide cash transfers, pay more than 100 types of bills, recharge mobile phone accounts, settle personal loans, and purchase services like software licenses and online game cards, airline and movie tickets, etc.

    The company’s payment system partners with 24 domestic banks and foreign payment networks, including JCB, MasterCard, and Visa.

    A judging panel comprised of senior partners from H2 Ventures and KPMG decided the final composition of the Fintech100 list.

    H2 Ventures is a global thought leader in fintech venture capital investment while KPMG is a global network of independent member firms offering audit, tax and advisory services.

    Companies were ranked based on total capital raised, rate of capital raising, location and degree of sub-industry disruption and the judging panel’s subjective rating of the degree of product, service, customer experience, and business model innovation.

    Other newcomers to the list include Argentina, Bahrain, Colombia, Czech Republic, Indonesia, Jordan, Malaysia, Myanmar, United Arab Emirates, and Thailand.

    Leading the ranking this year are China’s Ant Financial, the world’s largest third-party payments platform, JD Finance, a digital technology company and Singapore’s ride hailing firm Grab.

  • Touché forms strategic partnership with Seed into the Middle East market

    Touché forms strategic partnership with Seed into the Middle East market

    Singapore-based technology company Touché has signed a Cooperation Agreement with SEED Group as their local sponsors and partners, to expand the reach of the world’s first fingerprint biometric-based payment and loyalty management solution to the Middle East. Based in Dubai, United Arab Emirates (UAE), SEED Group is a diversified group of companies owned and chaired by The Private Office of Sheikh Saeed bin Ahmed Al Maktoum. It establishes strategic partnerships with organisations in various sectors and accelerates their presence within the Middle East.

    Through this agreement, Touché hopes to leverage the local expertise of SEED Group to reach potential target customers, bringing personalised and seamless experiences to more merchants and consumers in the region.

    This marks a key milestone for Touché in the Middle East, which also received the Commercial License to engage commercial trade activity in the UAE. Issued by the Department of Economic Development in Dubai, the licensing enables Touché to perform business activities and introduce its solution in a compliant manner, further cementing Touché’s commitment towards the region.

    Developed in Singapore, with offices in Barcelona, Tokyo and now Dubai, Touché provides both an elegant and innovative device and a robust software solution that delivers highly secure, convenient and personalised point-of-sale transaction services using fingerprint biometrics or recurring cards.

    Touché’s solution also connects and manages loyalty programmes, and points and discounts are instantly applied for qualifying customers at the point of interaction without the need for vouchers or membership cards. This provides the customers a unique experience. Its data analytics component enables merchants to access historical and predictive purchasing habits and buying patterns of customers, creating bespoke, personalised, offers and recommendations for them.

    “We are delighted that such a high calibre and impressive organisation as SEED Group will be supporting Touché in redefining point-of-sale transactions in the Middle East. The partnership, together with our incorporation in the UAE with our trading license, will bring a new dimension to personalisation in the region, where customers can enjoy unique in-store experiences,” said Sahba Saint-Claire, Chief Executive Officer and Co-Founder, Touché.

    “The Middle East is well prepared to enter a new age of digitalisation and push the boundary in digital payment customer experience. We believe that Touché could serve as a key differentiator to transform the growing payment scene and offer a more secure, convenient and efficient payment and loyalty management solution for consumers,” said Hisham Al Gurg, CEO of SEED Group and of The Private Office of Sheikh Saeed bin Ahmed Al Maktoum.

    The partnership between Touché and SEED Group is supported by Enterprise Singapore, which as part of its mandate, champions internationalisation of Singapore companies. Enterprise Singapore has provided great assistance to Touché through facilitating introductions to potential partners and clients in its target markets, including the Middle East.

  • Mastercard Takes HongKong’s Education Sector into New Milestone

    Mastercard Takes HongKong’s Education Sector into New Milestone

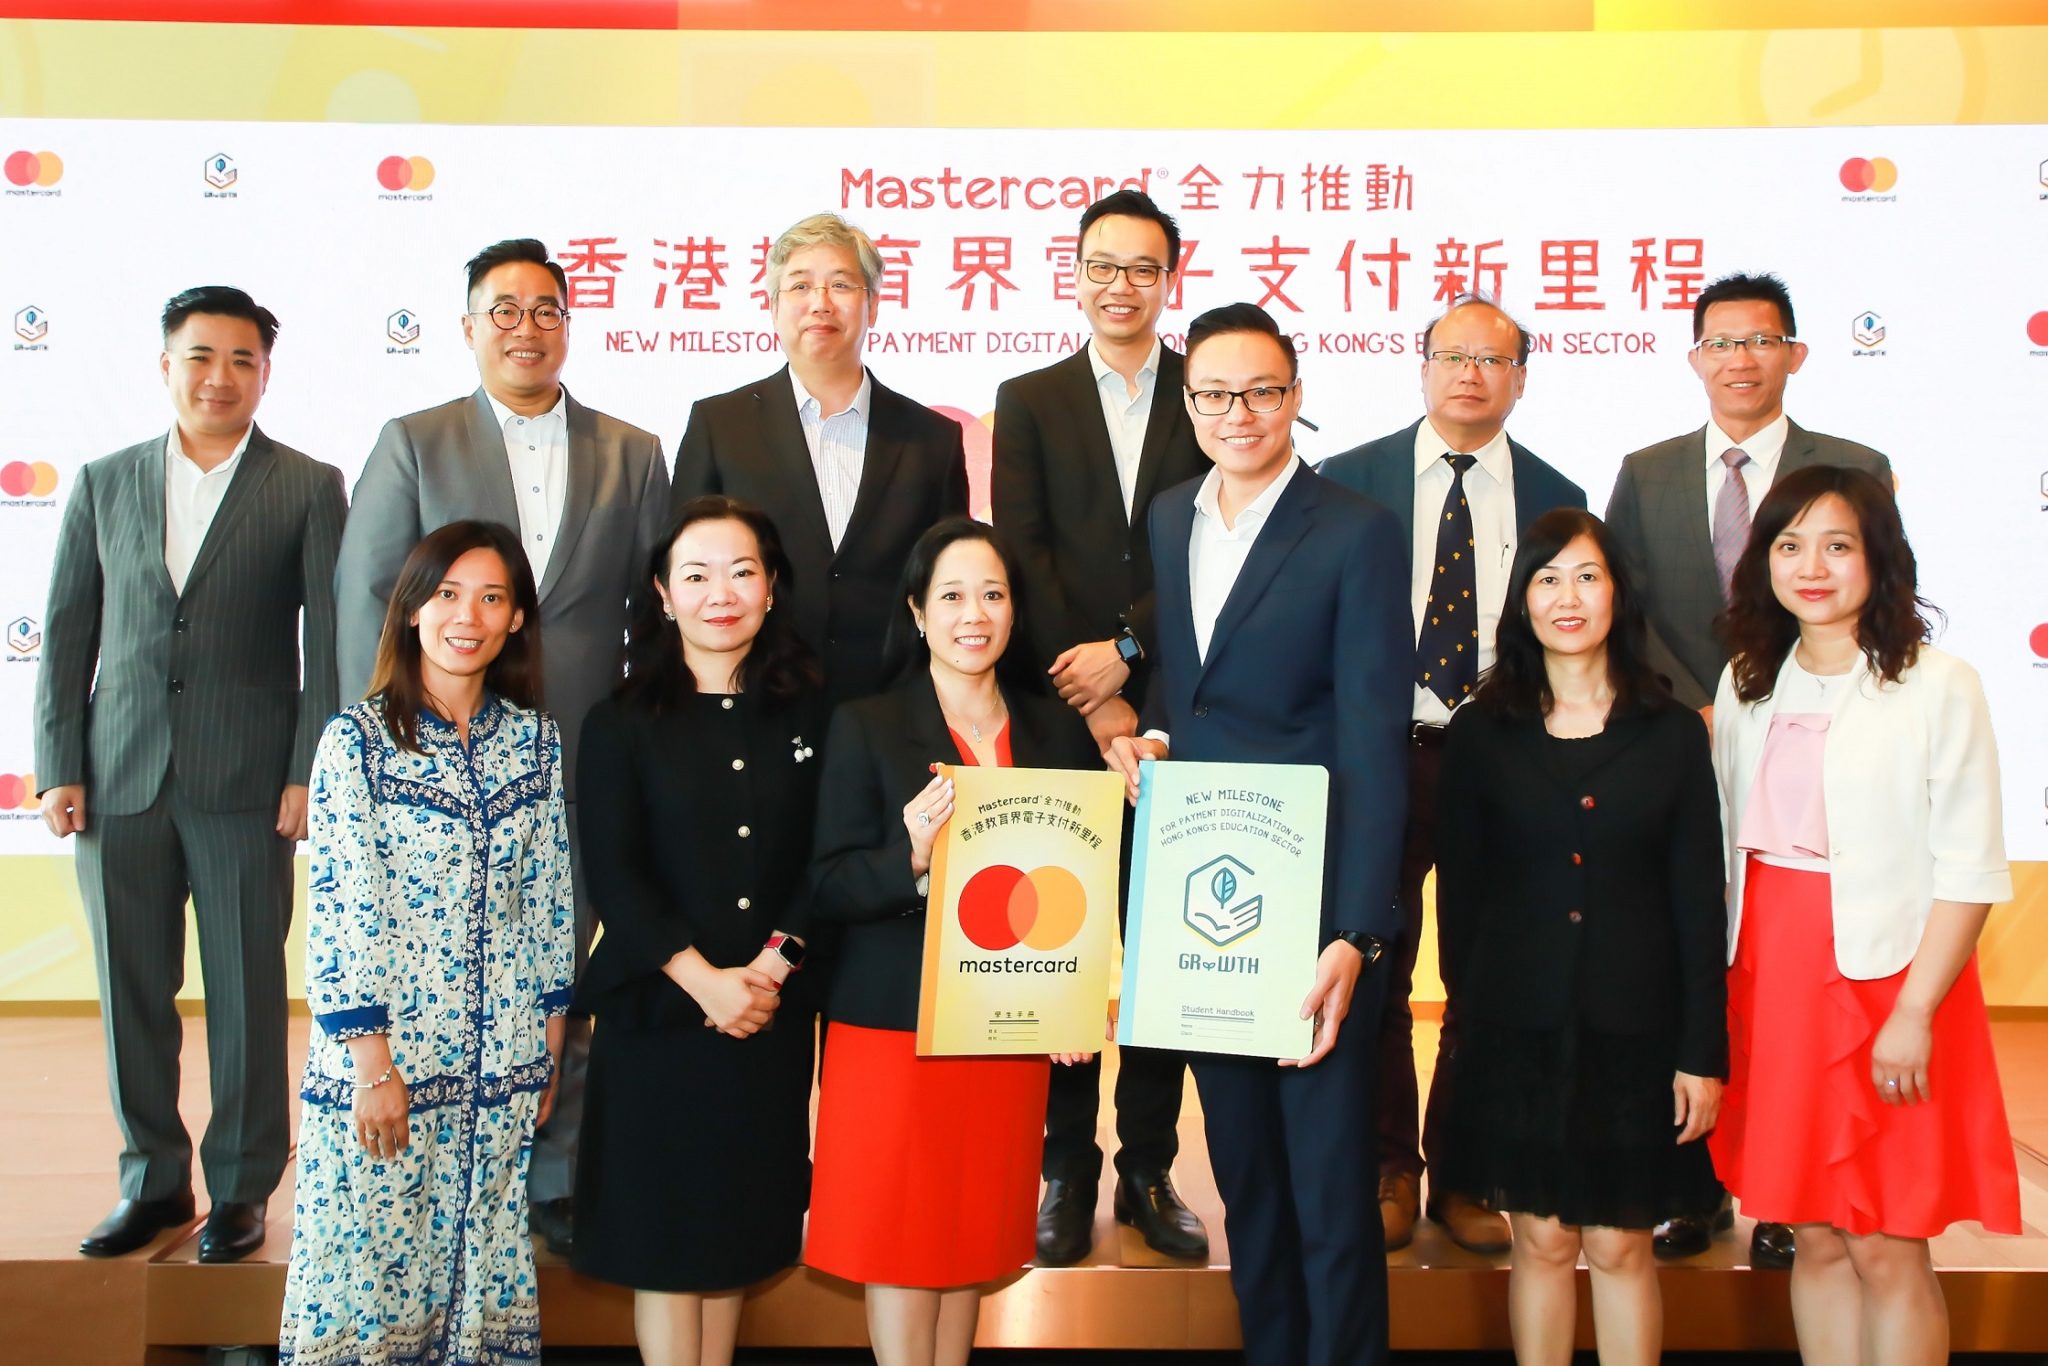
    Mastercard is bringing cashless payments to Hong Kong’s education sector through a seamless FinTech and EduTech platform, which enables the city’s first-ever integrated education app with multiple in-app digital payments.

    Through an exclusive partnership with local education app developer GRWTH, Mastercard will bring hassle-free, fast, safe, and convenient cashless payments experience to schools and parents. The enhanced app integrates digital payments, account reconciliation, student profiles, home-school communication, as well as school administration into one single platform.

    The partnership addresses the pain points faced by parents in daily school payments situations, such as spending a lot of time preparing cash or issuing checks, keeping track of expenses that are often paid in small amounts, and students missing out opportunities to join school activities due to losing cash or checks. All school expenses can be settled via the in-app digital payments function, thereby eliminating the need to deal with cumbersome cash or checks. Parents can also easily track their school payments anytime, anywhere, giving them greater peace of mind.

    Schools also benefit from saving massive administrative time and costs that come with handling the complex payment procedures. Teachers can also save time spent during class manually collecting payments from students. The app offers an exclusive backend reconciliation system, which provides a direct and convenient way to keep track of payments. This includes simplifying reconciliation procedures via transaction categorization and real-time transaction tracking as well as report generation. It relieves the pressure for schools in handling school expenses, allowing more quality teaching time.

    “We are proud to partner with Mastercard to attain our goal of enriching the life of our children through technology. GRWTH links up students, school administrators and parents and provide them with powerful and innovative tools for better home-school communication and organization,” said Adam Chan, co-founder and CEO, GRWTH. “By connecting the education, finance and technology sectors, we aspire to push forward the development of digital payments in Hong Kong.”

    “We are excited to turn a new chapter for the Hong Kong education sector. By bringing together EduTech and FinTech, Mastercard aspires to alleviate the pressure of handling large amounts of cash and checks for schools and parents, not only by providing them with fast, safe and convenient cashless payments experiences but also by helping them devote more time and energy into students’ growth and development,” said Helena Chen, managing director, Hong Kong and Macau, Mastercard. “Through Mastercard’s technology, we can truly lay the foundations for the future of our next generation, and push forward the development of Hong Kong as a smart city.”

    As the exclusive partner, Mastercard provides a one-click, secure digital payments solution. Parents simply need to store their Mastercard card details only once to enjoy the seamless, one-click experience for all future payments. To provide even more convenience, the new in-app payments service is not only available for Mastercard credit and debit cardholders, but also to Mastercard prepaid cardholders. With the world’s fastest and most reliable global payments network, Mastercard cardholders can enjoy the same robust, multi-layered security protections that comes with paying with a Mastercard.

    GRWTH has recently launched the service to 10 schools in Hong Kong as part of a pilot program* and plans to gradually expand the service to all kindergartens, primary and secondary schools in Hong Kong. “Our school aspires to bring changes to the education sector by leveraging technology and innovation. We are excited to be one of the 10 pilot schools to introduce a cashless payments option for parents,” said Chu Tsz Wing, chief principal, St. Hilary’s Primary School & VNSAA ST. HILARY’S SCHOOL.

    Apart from its in-app payment function, the GRWTH app includes tools for home-school communication and school administration, and will soon integrate the ability to pay vendors such as extra-curricular activities and school service providers, allowing parents to make instant and direct payment. The “GRWTH Community” is made up of over 100 NGOs and commercial organizations in Hong Kong. Parents can choose personalized extracurricular activities for their children based on the multi-intelligence analysis function in the app’s talent pool. The GRWTH app is available for free download via Apple App Store and Google Play Store.

    *The 10 pilot schools are:

     Buddhist Lim Kim Tian Memorial Primary School

     Buddhist Wing Yan School

     ELCHK Ma On Shan Lutheran Primary School

     Fung Kai No.1 Primary School

     Gloria Creative Kindergarten and Gloria Creative Kindergarten (Sheung Shui)

     Lok Sin Tong Leung Wong Wai Fong Memorial School

     N.T.W.J.W.A. LTD. Leung Sing Tak Primary School

     St. Edward’s Catholic Primary School

     St. Hilary’s Primary School and VNSAA ST. HILARY’S SCHOOL

     The ELCHK Wo Che Lutheran School
  • Temasek Foundation and Indonesia To Develop Fintech Talents

    Temasek Foundation and Indonesia To Develop Fintech Talents

    Temasek Foundation International (TF INTL) and Ngee Ann Polytechnic (NP) has partnered with Indonesia’s Ministry of Research, Technology and Higher Education (MoRTHE) on Wednesday to deliver a new programme that encourages an exchange of knowledge among academia, industry partners and regulators in the financial technology (FinTech) sphere.

    «The digital economy is disrupting work and indeed, lives. This means that educators need to collaborate to reinvent and update their skills to keep pace with industry developments,» said Benedict Cheong, chief executive of TF INTL in a press statement.

    Educators To Benefit

    This programme will enable educators from Indonesia and Singapore to exchange knowledge and develop new ways to train aspiring youths in financial technology, Cheong said.

    «We hope to develop lecturers with high performance and good understanding in Financial Technology, to supply talent who can compete in the industry’s 4.0 era. This MoU will give a lot of benefits to Indonesia’s Higher Education, especially in universities and polytechnics in Indonesia,» said Ir. Paristiyanti Nurwardani, director of learning of MoRTHE.

    Commitment

    TF INTL has committed a grant of about S$523,000 for this cross-border programme, which will include experiential learning through lab crawls, hackathons, seminars and workshops.

    The course participants will get to visit and network with FinTech developers and users to gain fresh insights into the emerging field, as well as take part in challenges that will inspire innovative applications for the financial sector.

    Collaboration

    Over the next three years, the three parties will collaborate to implement a FinTech learning programme for higher education providers in Indonesia.  Some 180 academic leaders and faculty from Indonesian tertiary institutions will work towards developing FinTech curriculum and capability.

    The programme will span over two runs, ending in 2020. The institutions confirmed for the first run include: Institute Teknologi Bandung (ITB), Politeknik Negeri Jakarta (PNJ), Universitas Indonesia (UI), Universitas Pendidikan Indonesia (UPI), Universitas Padjadjaran (UNPAD) and Univeristas Airlingga (UNAIR).

  • Indonesian fintech startup Moka raises $24M

    Indonesian fintech startup Moka raises $24M

    Indonesia’s Moka, a startup that helps SMEs and retailers manage payment and other business operations, has pulled in a $24 million Series B round for growth.

    The investment is led by Sequoia India and Southeast Asia — which recently announced a new $695 million fund — with participation from new backers SoftBank Ventures Korea, EDBI — the corporate investment arm of Singapore’s Economic Development Board — and EV Growth, the later stage fund from Moka seed investor East Ventures. Existing investors Mandiri Capital, Convergence and Fenox also put into the round.

    The deal takes Moka  to $27.9 million raised to date.

    Moka was started four years ago primarily as a point-of-sale (POS) terminal with some basic business functionality. Today, it claims to work with 12,500 retailers in Indonesia and its services include sales reports, inventory management, table management, loyalty programs, and more. Its primary areas of focus are retailers in the F&B, apparel and services industries. It charges upwards of IDR 249,000 ($17) per month for its basic service and claims to be close to $1 billion in annual transaction volume from its retail partners.

    That’s the company’s core offering, a mobile app that turns any Android  or iOS device into a point-of-sale terminal, but CEO and co-founder Haryanto Tanjo — who started the firm with CTO Grady Laksmono — said it harbors larger goals.

    “Our vision is to be a platform, we want to be an ecosystem,” he told TechCrunch in an interview.

    That’s where much of this new capital will be invested.

    Tanjo said the company is opening its platform up to third-party providers, who can use it to reach merchants with services such as accounting, payroll, HR and more. The focus is initially on local services that cater to SMEs in Indonesia, but as Moka targets larger enterprises as clients, he said that it will integrate larger, global solutions, too.

    Moka offers services beyond point-of-sale, but the core offering is turning any smart device into a cash machine

    Moka itself is expanding its capabilities on the payment side.

    Indonesia, the world’s fourth largest country based on population and Southeast Asia’s largest economy, is in the midst of a fintech revolution with numerous companies pioneering mobile-based wallet services aimed at ending the country’s fixation on cash-based transactions. That’s mean that there are a plethora of options available today. Tanjo said Moka is working to support them all in order to help its merchants grow their businesses and consumers to have easier lives.

    There are so many wallets here in Indonesia,” he said. “There are more than 10 right now and maybe in the next few months there’ll be 15-20, we want to be the platform that works with all of them.”

    Already it works with the likes of OVO, T-Cash and Akulaku, and e-wallets including DANA and Kredivo. The startup is also working in another area of fintech: loans.

    As an extension of its platform, it has tied up with SME loan companies who can reach out to Moka businesses using its platform. With the merchant’s consent, Moka can provide business data — including revenue, profit, etc — to help provide data to assess a loan application. That’s important because the process is particularly challenging in Southeast Asia, where few organized credit checking facilities exist — it makes sense that Moka — which has built its business around encouraging business growth and management — uses the information it has access to help its partners.

    Tanjo said the company takes an undisclosed cut of the loan in cases where it has successfully connected the two parties. He said that he doesn’t expect that to initially become a major revenue stream, but over time he anticipates it will help its customer base grow and become a more important source of income for the startup.

    Sequoia India has some experience in POS startups having backed Pine Labs in India, which recently landed a big $125 million round from PayPal and Singapore sovereign fund Temasek. Still, there are plenty of local players across various markets in Southeast Asia, including StoreHub, which is backed by Temasek subsidiary Vertex Ventures, and Malaysia’s SoftSpace.

    While those two competitors have established a presence in multiple markets in Southeast Asia, Tanjo — the Moka CEO — said there are no plans to venture overseas for at least the next 12 months.

    “We’re still scratching the service,” he said. “So it doesn’t make sense to expand too soon.”

  • Higher Risk Still Means Higher Interest in Fintech Lending

    Higher Risk Still Means Higher Interest in Fintech Lending

    For platforms that boast superior debtor risk assessments and aim to compete with conventional banks, online peer-to-peer lending services have so far fell short of their promises.

    These services currently offer annual interest rates of 19 percent on average to their clients, most of which are small and medium enterprises. However, the Indonesia’s Financial Services Authority (OJK) says this is still too high to attract more borrowers that generally do not qualify for bank loans.

    In comparison, conventional banks offer SMEs loans at interest rates of up 10 percent, or 7 percent with the state subsidy. Ajisatria Sulaeman, director of the Association of Financial Technology (Aftech), said borrowers using peer-to-peer services are often those who do not meet banks’ requirements.

    It means there are risks that those banks do not want to take, hence the higher interest to adjust to the higher risk, Ajisatria said. While it is easy for peer-to-peer services to obtain potential borrowers’ behavior data on social media and through the use of services such as technology startup Go-Jek, it is still costly to verify.

    “Without data from the civil registry, how can we make sure that they use their own identity numbers and not those of others?” Ajisatria said.

    “So data from the Directorate General of Population and Civil Registration and the Financial Information Service System are still very important. With that, we can ensure that borrowers are not fraudulent,” Ajisatria said on Thursday.

    Some peer-to-peer lenders even resort back to conventional credit scoring services, such as Pefindo, but this comes at additional costs, which are passed on to borrowers in the form of higher interest rates.

    “The focus is on how we can easily identify borrowers, especially those with good intentions,” Ajisatria said.

    He said peer-to-peer platforms will be in a better position to assess loan risks if they have easy access to the population registry data. The number of bad loans can be reduced, which in turn, will allow peer-to-peer lenders to charge lower interest rates.

    Sluggish lending by banks over the past few years has seen Indonesia’s financial regulator welcome peer-to-peer platforms, which usually disburse small loans to micro, small and medium businesses that banks often consider high risk.

    Loan growth has dropped to below 10 percent over the past two years from 20 percent previously, central bank data shows. Chatib Basri, a former finance minister, said in March that a climate of healthy competition and a growing number of online lending firms could help to reduce high interest rates.

    “This approach can be made by multiplying the firms in the market segment, which will certainly cause interest rates to decline,” said Chatib, who just became an advisor to peer-to-peer lender ModalKu.

    Indonesia currently has 66 registered peer-to-peer lending firms, which have paid out Rp 7.8 trillion ($525 million) in loans as of July this year, compared with just Rp 247 billion by December 2016, according to the OJK.

    These firms serve to connect more than 250,000 individual lenders to 1.85 million borrowers. OJK deputy commissioner Sukarela Batunanggar said the financial regulator until now still has no intention to cap interest rates and limit the size of loans these financial technology firms can offer. Aftech, which was established in 2015 and now consists of 152 fintech startups offering various services, ranging from lending, insurance and investment, plans to issue a standard on fintech interest rates soon, but it is currently still finalizing the amount.

    Economic Contribution

    According to a study conducted by Aftech and the Institute for Development of Economics and Finance (Indef), fintech lending firms have contributed Rp 26 trillion to Indonesia’s gross domestic product since the OJK issued a regulation on such services in 2016.

    Indonesia’s nominal gross domestic product was Rp 13,558 trillion at the 2017 exchange rate, according to the Central Statistics Agency (BPS).

    “While this is relatively small, there is still hidden potential on fintech platforms, as until now, it has not reached those in need of loans across the country,” Indef economist Bhima Adinegara said.

    The presence of peer-to-peer lending firms has resulted in the creation of 215,433 jobs since 2016, with total wages amounting to around Rp 4.6 trillion.

    “The government must use this potential to increase financial inclusion by issuing easier regulations to expand the sector further, so it can contribute more to the Indonesian economy,” Bhima said.

  • Decision time for Malaysia’s fintech regulators

    Decision time for Malaysia’s fintech regulators

    Just as Kuala Lumpur hosted the opening of what claims to be the “largest blockchain centre in Asia,” a newly published report has urged the Malaysian government to hone and relax the regulations covering blockchain technology.

    The 242-page report, entitled “Tailoring Malaysian blockchain regulations for the new digital economy”, was published yesterday by the University of Malaya’s Faculty of Law.

    While it aims to be a “starting point to synthesize some of the [existing] legal viewpoints into collective practical solutions which will benefit Malaysia,” it also calls on the country’s central bank and securities commission to work together to define and provide better clarity, especially in regard to crypto-related taxation.

    The legality of crypto-currency trading in Malaysia remains somewhat unclear, as it is not formally illegal but remains unregulated. Report project director Nur Husna Zakaria said the current government stance was “promising” because, as yet, “none of the regulators in Malaysia has banned any transaction related to blockchain,” but she urged all government stakeholders to work alongside the country’s blockchain community to “ensure whatever regulation is [put] in place … is comprehensive.”

    According to the Malaysia’s Sun Daily, the country’s Inland Revenue Board is now studying the country’s crypto-currency market but has given no timeline on the release of any guidelines or legislation.

    The University of Malaya report was published the day after international technology developer NEM Foundation opened its new Southeast Asian HQ in Kuala Lumpur. The 11,000-square-foot facility, that NEM claims is the biggest blockchain-focussed facility in Asia, will act as a learning centre, incubator and accelerator for blockchain related startups.

    The centre aims to serve as an R&D facility for NEM related developers, business users and crypto exchanges and already Appsolutely Inc, a crypto-based rewards and loyalty business from the Philippines, has based its regional operations at the NEM centre, as has Indonesian crypto retail startup Pundi X and Singaporean mobile settlement solution Dragonfly Fintech.

    Singapore-based NEM, that gained global notoriety after its own digital token was at the centre of a $530 million hack in January 2018, announced earlier this month that it had devoted $40 million to an on-going global expansion program. NEM says $5 million of this fund has been allocated to support blockchain companies based at the new Kuala Lumpur centre.


  • Korea’s first Internet bank struggling to raise capital

    Korea’s first Internet bank struggling to raise capital

    K-Bank, the country’s first Internet-only bank, is struggling to raise the capital it needs to expand as profits remain elusive amid increasing costs, sources directly involved with the issue said.

    “K-Bank recently asked local private equity funds (PEFs) to participate in an additional rights offer because it wants to raise its capital to 500 billion won ($455 million) by the end of the year. However, investors have concerns about the bank’s future profitability given its weak growth in consumer loans and growing policy threats,” a local PEF source said.

    “It’s highly unlikely the bank can achieve its goal. One reason is it has too many shareholders. This can create additional administrative costs, which I believe is not good for K-Bank as it has to address many challenges as quickly as possible,” said the source.

    After a delay of one month, K-Bank’s shareholders approved in June a plan to raise 150 billion won via a rights offer. The bank was in discussions with new investors and PEFs to raise up to 300 billion won in an additional shares sale.

    Korea Telecom (KT), the country’s dominant fixed-line operator, is the largest shareholder of K-Bank with 18.01 percent, followed by Woori Bank with 12.97 percent, NH Investment with 10.10 percent, Hanwha Life with 8.13 percent, GS Retail with 8 percent, KG Inicis with 6.57 percent, Danal with 6.57 percent and 13 others owning the rest, according to the bank.

    New “digital banks” are widely expected to have an impact on its performance particularly by poaching customers and eroding margins across its retail segments.

    Consumers and industry watchers see evidence of these trends and some say they are happening faster than expected. A key question is services differentiation that haven’t been extensively explored because Internet banks charge lending rates comparable to existing banks, which offer mobile banking services 24 hours a day.

    “My question is how well K-Bank is positioned in terms of product differentiation. Differentiation will make its services much more attractive by contrasting its uniqueness with other competing services and products. K-Bank made an impressive start, however, it has to respond to lots of questions from shareholders and investors if it wants to attract more,” said another PEF source.

    K-Bank reported an 83.8 billion won net loss last year, according to data from the Korea Federation of Banks. The bank, which began operating in April of last year, has extended about 1.95 trillion won in loans as of May this year. But it reported an 8.6 billion won loss by exempting customers from commission fees to win more users.

    The PEF sources have asked the financial regulators to ease rules that bar non-financial companies from owning more than 10 percent of a bank.

    “This regulation limits the growth of internet-only banks. If the rule is eased, then the bank’s largest shareholder KT has no legal issues in participating in a large-scale share sale,” said the second source, adding it will be tough for K-Bank to change the industry dynamics and resolve?the broader industry’s woes.

  • Vietnamese startups pour $129 million into financial tech scene

    Vietnamese startups pour $129 million into financial tech scene

    Widespread smartphone usage, increased consumer spending and a low unemployment rate have spurred investment. Vietnamese startups have invested $129 million into financial technologies, with investors saying the country has high potential for tech development, a conference in Hanoi heard last week.

    Vietnam is one of the best markets for financial technologies given its widespread smartphone usage, increased consumer spending and low unemployment rate, Varun Mittal, Ernst & Young’s ASEAN FinTech head, said at the conference.

    FinTech (financial technologies) are technological innovations created to support or enable banking and financial services such as AI-powered trading.

    “Foreign investors are interested in and even willing to buy FinTech from Vietnam due to the country’s markets being attractive for FinTech development,” Mittal said.

    The company said there are almost 80 FinTech firms currently operating in Vietnam, with about 47 percent specializing in payment services. This is partly due to the fact that most Vietnamese people still conduct transactions in cash.

    Mittal also said that several banks want to collaborate with FinTech firms to develop digital banking software instead of developing the software themselves, citing lower costs.

    Korea-based financial group Keb Hana’s chairman Kim Jung Tai said that the group is working with a Vietnamese bank on the development of FinTech during a meeting with Vietnam’s Deputy PM Vuong Dinh Hue in Hanoi back in January.

    However, obstacles still remain. Vietnam’s financial services country leader for Ernst & Young, Nguyen Thuy Duong, said the Southeast Asian nation does not yet have an official policy regarding cooperation between banks and FinTech firms. The fact that many FinTech companies are just fledgling startups with limited capital, workforces and experience doesn’t help either.

    Duong added that the State Bank of Vietnam is working on developing a legal framework to experiment with FinTech before applying it on a larger scale.

  • Payments and lending dominate Indonesia’s Fintech scene

    Payments and lending dominate Indonesia’s Fintech scene

    Payment and lending focused Fintech startup companies dominate the overall Indonesia Fintech landscape in terms of maturity level, according to IDC Financial Insights.

    This was followed by marketplace, wealth management, company solution and accounting based software providers.

    “The collaboration between Fintech and traditional institutions (banks) becomes mandatory for now and in the future. There are several Indonesia banks that have done collaboration actions either in [the] operation aspect or through investment funds. We believe that speed to dominate the market is the key to win for Fintech especially in payments category,” said Handojo Triyanto, Senior Research Manager, IDC Financial Insights.

    “In the future Indonesia Fintech market will have consolidations by collaboration, mergers and acquisitions between the players. It has already happened as Go Jek (Go Pay) acquired Midtrans, Kartuku, and Mapan. The driver is the need to penetrate consumer market as soon as possible… not only to grab higher market share, but also to attract more investors.”

  • Fintech transforming B2B money transfer market

    Fintech transforming B2B money transfer market

    The cross-border B2B money transfer market is ripe for disruption, as new technologies and legislative changes redefine traditional banking practices across the globe, according to Juniper Research.

    Cross-border B2B transactions will exceed $218 trillion by 2022, up from $150 trillion in 2018, the company predicts.

    Disrupting traditional cross-border B2B transactions

    B2B Money Transfer: Cross-border Market Opportunities 2018-2022 Research author Lauren Foye explained: ‘While traditional banks still facilitate the vast bulk of B2B cross-border transactions, new technologies, such as virtual accounts, eInvoicing, and blockchain technology will aid in driving businesses to solutions which provide savings in time, efficiencies, and transparency’.

    The proportion of cross-border B2B transfer values facilitated by newer Fintech start-ups and disruptive technologies, will grow from 7.5% in 2017; equating to $10.4 trillion, to reach 13.3% or $29 trillion by 2022. This will occur as more businesses utilize these efficient and transparent methods in a notoriously cloudy industry.

    Juniper cited activities by Visa and Mastercard as beacons in this space. In addition to offering its own Visa B2B Connect’ service which utilizes blockchain-based Chain Core, Visa has partnered with Fintech start-up ‘Billtrust’ to provide virtual cards for B2B transactions. Likewise, Mastercard is working with Optal, to offer virtual accounts to businesses.

    Opportunity to lead innovation charge

    Juniper believes that banks are well placed to benefit from the opportunity posed in B2B transfers. For instance, legislative changes such as PSD2 in Europe, serve as a perfect opportunity to partner with Fintechs to deliver innovative services to companies; lest institutions fall behind and see Fintechs ultimately out maneuver them.