Tag: FinTech

  • AI Adoption Hits 71% Among Emerging Market Venture Firms but Core Integration Lags

    AI Adoption Hits 71% Among Emerging Market Venture Firms but Core Integration Lags

    Artificial intelligence adoption among venture capital and private equity-backed firms jumped to 71 per cent this year in Bangkok, up from 39 per cent a year earlier.

    The headline surge conceals narrow implementation, with only 17 per cent of surveyed companies embedding artificial intelligence into their core business operations.

    Data released by the International Finance Corporation at the IMF-World Bank Annual Meetings shows that more than half of adopting businesses still restrict deployments to isolated operational functions. The survey sampled 1,600 private equity and venture capital firms to evaluate how early-stage and portfolio enterprises deploy automated tools. Improved productivity ranked as the primary driver, cited by 54 per cent of respondents, yet operational bottlenecks persist across developing markets.

    Skills Shortages and Local Integration Bottlenecks

    Human capital constraints remain the primary hurdle to enterprise rollouts across emerging regions. More than 40 per cent of non-adopters identified acute skills shortages as their primary barrier, while broader institutional capacity deficits continue to stall deployments outside basic software tools.

    Enterprise operators in Southeast Asia and South Asia frequently encounter tools designed for Western data sets and cost structures. Without local tuning, generic generative platforms fail to handle regional dialects, local commercial registries, and fragmented banking APIs. The practical value for regional businesses depends on engineering lightweight, localized models rather than purchasing expensive enterprise subscriptions that internal teams cannot maintain.

    Cross-Border Payments and Merchant Infrastructure

    Fintech operators are focusing on targeted agents to resolve transaction delays for small and medium-sized enterprises. Cross-border payments and remittance channels across developing corridors remain plagued by settlement delays and excessive processing fees.

    Adeola Adewede, founder and chief executive of fintech platform Kredete, stated that autonomous AI agents configured for local language context and cost structures can transact on behalf of regional merchants across borders, lowering operating costs and speeding liquidity cycles.

    Medical Imaging and Regulatory Clearance

    Healthcare deployment demonstrates a similar pattern of targeted edge utility versus administrative obstruction. In India, medical imaging platform CARPL has deployed portable X-ray units powered by laptop-based AI models to screen populations for tuberculosis and breast cancer.

    CARPL founder and chief executive Vidur Mahajan noted that the platform maintains an ecosystem of more than 300 imaging applications for hospitals. However, ambiguous medical software regulations across emerging markets delay rollouts, prompting industry calls for regulators to streamline domestic approvals for diagnostic algorithms already certified in developed economies.

    On-Device Intelligence and Hardware Integration

    Hardware providers argue that long-term productivity gains require local processing rather than continuous cloud connections. Running machine learning models directly on laptops, vehicles, and connected hardware eliminates latency and lowers connectivity costs for small businesses.

    Veerabhan Kheterpal, co-founder and chief executive of semiconductor IP licensing company Quadric, noted that building intelligence directly onto devices allows systems to generate customized software adjustments in real time, expanding operational capacity for small enterprise operators.

    Commercial focus now shifts to whether portfolio companies can convert functional experiments into revenue-generating workflows before early investment capital runs dry.
  • DuitNow Caps Singapore Cross-Border Fund Transfers at RM3,000 a Day

    DuitNow Caps Singapore Cross-Border Fund Transfers at RM3,000 a Day

    Malaysian merchants processing cross-border remittances through the national DuitNow payment network face an outbound ceiling of RM3,000 a day for fund transfers to Singapore as of October 2026.

    Domestic business transfers across the same network clear up to RM10 million per transaction, highlighting the gap between local retail payment rails and regional settlement links.

    Operated by Payments Network Malaysia, known as PayNet, the retail payments platform functions under the primary ownership of Bank Negara Malaysia alongside commercial lenders. The infrastructure connects commercial banks and non-bank e-wallets into a single interoperable clearing system. Retailers and suppliers send and receive funds using proxy identifiers including mobile numbers, identity card records and verified Business Registration Numbers issued by the Companies Commission of Malaysia.

    Domestic Transfer Limits and Merchant Fees

    Consumer transactions clear up to RM50,000 per transfer through commercial banking applications, with transfers up to RM5,000 processed without consumer transaction charges. Above that threshold, financial institutions may levy a 50 sen fee, though individual retail banks retain discretion to waive the charge. Commercial users maintain higher headroom, clearing up to RM10 million per transaction subject to institutional credit and fraud underwriting terms.

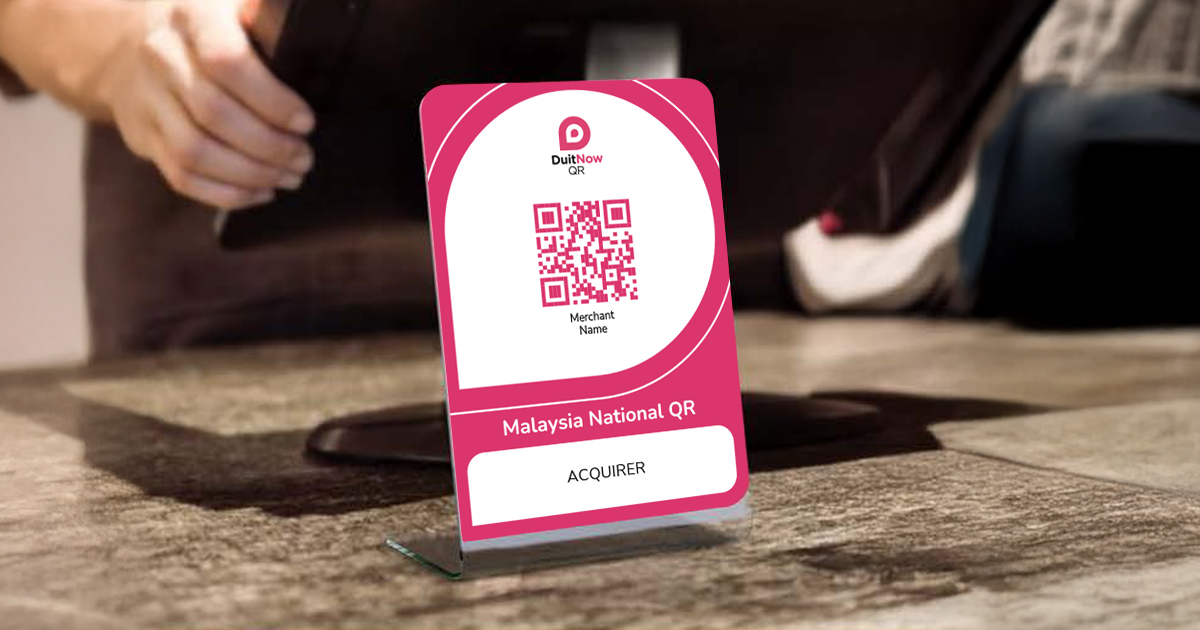
    Point-of-sale retail payments operate through unified QR standards. Merchants deploy a single static or dynamic QR code that accepts clearing requests from all domestic mobile banking applications and licensed e-wallets. Consumer payments remain fee-free at retail counters, while merchant discount rates apply to retail enterprises depending on their merchant acquirer contract.

    E-commerce checkout integrations route directly through DuitNow Online Banking and Wallets, bypassing traditional payment card rails. The direct routing pulls cleared funds directly from buyer accounts without requiring debit card credentials. For recurring invoicing, the network deploys AutoDebit protocols that clear utility billings, subscriptions and recurring wholesale invoices under pre-authorised value limits without recurring manual approvals.

    Regional Settlement Links and Currency Controls

    Inbound cross-border retail acceptance currently covers visiting consumers from six Asian economies: China, Indonesia, Singapore, Thailand, South Korea and Cambodia. Tourists and business travellers scan local merchant QR codes using their domestic banking apps. Settlements convert automatically, crediting Malaysian merchant bank accounts exclusively in Malaysian ringgit.

    Merchants cannot hold foreign currency balances directly inside the DuitNow clearing architecture. Exchange rates for incoming tourist QR spending are determined by the originating overseas payment application at the point of interaction. This leaves cross-border sellers exposed to conversion markups set by foreign issuing institutions.

    Outbound commercial transactions across the border face structural barriers. While the bilateral corridor with Singapore enables retail peer-to-peer transfers, the daily cap of RM3,000 or S$1,000 restricts corporate trade settlement. Companies paying overseas manufacturers, regional software vendors or inventory partners require separate international clearing rails or multi-currency corporate banking accounts.

    Payment Rail Fragmentation Across Retail Chains

    Retail chains across Southeast Asia are weighing single-currency domestic payment rails against cross-border fintech platforms. The local DuitNow architecture eliminates domestic card processing interchange fees, yet fails to provide working capital accounts in trade currencies such as the US dollar.

    Cross-border procurement teams that purchase stock from Mainland China or regional suppliers cannot use PayNet rails to settle trade invoices. The limitation forces operators to run dual payment workflows: national QR and real-time bank transfers for domestic store sales, and cross-border platforms such as WorldFirst or SWIFT wire transfers for import settlement. For high-volume retail chains, maintaining dual clearing mechanisms adds operational reconciliation costs and exposure to retail foreign exchange spreads.

    The operational split gives pure-play international corporate treasury providers an opening against state-backed retail clearing systems. Commercial banks capture high spreads on foreign exchange wire transfers, driving online sellers and cross-border merchants toward multi-currency accounts that issue local clearing details in overseas markets.

    Building the Regional Payment Network

    PayNet developed DuitNow to consolidate a fragmented mobile payment sector where competing digital wallet operators deployed incompatible proprietary QR codes. The central bank intervened to mandate standardisation, creating a shared national QR code and central proxy registry.

    The central bank expanded the domestic retail clearing platform through bilateral central bank linkages, starting with Thailand and Indonesia before connecting Singapore PayNow. The bilateral linkages aim to reduce regional reliance on traditional card networks and correspondent banking systems for micro-transactions and tourism spending.

    Bank Negara Malaysia and regional central banks continue testing multilateral clearing arrangements across ASEAN economies, with broader business settlement ceilings remaining the key requirement for commercial supply chain operators.

  • Bitcoin Trades at $83,408 as Crypto Markets Track Asia Trading Moves

    Bitcoin Trades at $83,408 as Crypto Markets Track Asia Trading Moves

    Bitcoin held steady at $83,408.20 on October 13, 2026, gaining $19.57 over the previous morning as trading volumes remained subdued across major digital asset desks.

    The benchmark cryptocurrency is down 27.64 per cent from $115,278.48 a year earlier, representing a value loss of roughly $31,870 per token despite an 7.95 per cent rebound over the past month from $77,261.09.

    Total market capitalisation for Bitcoin stands at $1.33 trillion, maintaining its dominant position over alternative tokens. Second-ranked Ethereum fell 1.97 per cent over twenty-four hours to $2,503.64, extending a 41.02 per cent drop from $4,245.28 recorded twelve months prior and fixing its valuation at approximately $233 billion. Tether followed with a $183 billion market cap at $0.99, while cross-border settlement token XRP traded at $1.35.

    Exchange expansion across North Asian hubs

    Retail and institutional trading activity across Asia-Pacific remains central to digital currency liquidity as platforms seek formal integration with regional equity markets. Binance is weighing plans to offer traditional stock trading access to customers in key Asian jurisdictions, including Hong Kong and South Korea. Connecting digital asset wallets to local equities provides centralized exchanges with a direct route to capture cross-asset retail trading flow.

    Brokerages and consumer finance platforms across Hong Kong and Seoul face renewed competition if major crypto venues succeed in securing regulatory approvals for equity products. Traditional securities brokers have spent years defending their fee structures against zero-commission retail apps. A unified interface combining spot crypto, exchange-traded funds and local equities threatens to erode brokerage commission pools across East Asia.

    Balance sheet purchases and corporate exposure

    Corporate treasury allocations have resumed on a targeted scale following sharp drawdowns from record highs. Strategy completed a $21 million purchase of Bitcoin as corporate buying activity showed signs of renewed momentum. Such transactions provide price support, though treasury adoption outside specialized balance sheet operators remains limited to select consumer brands and technology firms.

    Merchant payment adoption continues among high-ticket retail brands such as Ferrari and Tesla, yet everyday consumer transactions across Asian retail checkouts remain dominated by local fiat digital wallets. Crypto volatility makes inventory pricing difficult for retailers operating on thin margins. For department stores and supermarket operators, processing volatile tokens directly creates currency exposure that standard payment gateway conversions cannot fully eliminate.

    Retracing the October 2025 record peak

    Current price levels reflect a prolonged correction from historic highs set in late 2025. Bitcoin established an all-time record of $126,198.07 on October 6, 2025, before dropping roughly 30 per cent into the close of that calendar year. Ethereum experienced an identical trajectory, peaking near $5,000 in August 2025 before losing half its valuation over the subsequent fourteen months.

    Early stages of the cryptocurrency market saw transactions such as developer Laszlo Hanyecz exchanging 10,000 Bitcoins for two pizzas in 2010, an allocation valued today at more than $668 million. Long-term appreciation exceeds 15,000 per cent over the past decade, yet steep cyclical contractions continue to challenge institutional risk models and consumer holding appetite.

    Regulatory filings and automated order flow

    Trading desks are turning toward automated infrastructure to manage market shifts. Developer teams across the crypto sector are deploying artificial intelligence agents capable of executing autonomous trades, shifting volume away from manual retail orders toward programmatic systems. These tools operate continuously across global venues, tightening spreads during Asian daytime hours.

    Regulatory scrutiny over exchange asset segregation and cross-border token transfers remains the primary hurdle for wider banking integration across Asia. Licensing authorities in Hong Kong continue to review platform permissions, while financial watchdogs in Seoul maintain strict compliance rules on investor identity checks and domestic bank linkages. Market participants are monitoring whether Binance submits formal filing documents for stock trading services in either jurisdiction before the end of the fourth quarter.

  • Bukalapak Captures 584 Million Dollars Across Ten Private Funding Rounds

    Bukalapak Captures 584 Million Dollars Across Ten Private Funding Rounds

    Indonesian e-commerce operator Bukalapak accumulated 584 million dollars across 10 private financing rounds before leaning into financial services and merchant digitisation in Jakarta.

    Institutional backing from 26 corporate and venture investors financed the marketplace through six late-stage rounds, three early-stage rounds and a single seed injection.

    Capital allocations peaked during a Series G sequence between late 2020 and April 2021. Microsoft led the platform’s largest single transaction with a 234 million dollar round on April 14, 2021, drawing capital from Singapore sovereign wealth fund GIC, media conglomerate Emtek, SC Ventures, South Korea’s Naver, Mandiri Capital Indonesia, BRI Ventures and Bank Rakyat Indonesia.

    The Capital Structure Behind Series G

    The final private funding push followed a 200 million dollar tranche led by Standard Chartered in January 2021 and an initial 100 million dollar Microsoft-led commitment in November 2020. The trio of late-stage injections provided Bukalapak with balance sheet stability to build out merchant banking integrations and enterprise services across secondary Indonesian cities.

    Strategic investors dominated the share register over financial venture firms. State lenders Bank Rakyat Indonesia and Bank Mandiri entered through their corporate venture arms to link offline retail kiosks, known locally as warungs, directly into banking and payment networks.

    Valuation Milestones and Early Backers

    Bukalapak achieved unicorn status in November 2017 following a Series C round backed by GIC and Ant Group that valued the business at 1 billion dollars. Subsequent rounds pushed that valuation upward, reaching 1.2 billion dollars in January 2019 after a 50 million dollar Series D round led by Naver and Mirae Asset Global Investments, with participation from Ant Group and Endeavor Catalyst.

    Valuation numbers peaked in private markets at 2.5 billion dollars in October 2019 during a Series F round led by South Korea’s Shinhan Financial Group alongside Emtek. Early development had relied on smaller regional funds, beginning with an undisclosed seed round from Batavia Incubator in July 2011 and early venture rounds from Japan’s Strive, 500 Global, Aucfan, IREP and KMK Online between 2012 and 2015.

    Shifting Focus From Consumer Marketplaces

    Competition in Southeast Asian e-commerce forced Bukalapak to pivot away from direct consumer subsidies against rivals Shopee and Lazada. The platform redirected capital into Mitra Bukalapak, supplying fast-moving consumer goods and digital billing terminals to neighborhood mom-and-pop stores that represent the bulk of Indonesia’s retail economy.

    Specialist digital investment platforms such as Ajaib, which raised 515 million dollars across six rounds including a 270 million dollar Series C to reach a 1 billion dollar valuation, increased competition for consumer retail savings. Bukalapak countered by integrating investment products and micro-insurance distribution directly into its offline agent network.

    Investor Networks and Next Operational Targets

    Global funds continue to monitor Southeast Asian digital retail assets as broader ecosystem funding recovers. Endeavor Catalyst closed its 320 million dollar Fund V to back growth-stage operators across emerging markets, maintaining a portfolio that includes Bukalapak alongside automotive platform Carsome and fintech group Advance Intelligence.

    Management attention now centers on widening transaction margins across offline retail fulfillment lines and preserving cash reserves as digital commerce platforms navigate tighter lending conditions across Southeast Asia.

  • Bukalapak Extends Positive EBITDA Streak in Q2 Despite First-Half Net Loss

    Bukalapak Extends Positive EBITDA Streak in Q2 Despite First-Half Net Loss

    Bukalapak extended its run of positive adjusted EBITDA through the second quarter, maintaining operating profitability across core business units despite reporting a net loss for the first half.

    The Indonesian tech group balanced tighter operational spending across its marketplace and merchant network against bottom-line pressures that kept first-half net earnings in negative territory.

    Operating Discipline Across Units

    Second-quarter performance showed steady cost control across business segments. Management kept overhead tight while protecting revenue from offline-to-online merchant partners and specialized online commerce categories.

    Operating expenses fell in key administrative and marketing lines. That disciplined spending allowed adjusted earnings before interest, taxes, depreciation, and amortization to stay positive for consecutive reporting periods.

    Shifting Focus to Core Margins

    Merchant solutions and offline partner services formed the primary engine for the operating result. The company focused resources on profitable transactions rather than subsidizing top-line gross merchandise value across low-margin consumer retail categories.

    For investors, the divergence between positive EBITDA and a statutory net loss points directly to non-operating factors. Net results reflect mark-to-market adjustments on investments and financial assets rather than everyday cash burn from core commercial units.

    Regional Platform Competition

    Across Southeast Asia, online marketplaces have abandoned customer acquisition subsidies to protect cash reserves. Bukalapak took that step earlier than its regional peers, pivoting away from direct competition in mass consumer e-commerce to protect its balance sheet.

    Competitors across Indonesia continue to face intense margin pressure from social commerce platforms and fast-delivery networks. By prioritizing specialized commerce niches and physical kiosk networks, the group avoided the heavy promotional spending draining rival platforms.

    Balance Sheet and Next Steps

    Earlier quarters established the foundation for this operating run as leadership cut peripheral projects and reduced headcounts. The first-half figures confirm that core operations can run without burning operating capital, even as accounting valuations weigh on statutory net income.

    Attention now turns to the third-quarter earnings release, where sustained adjusted EBITDA and narrowing bottom-line losses will determine whether full-year operational targets stay on schedule.

  • ShopeePay Adds Zurich Life Insurance in Malaysia Starting at RM500

    ShopeePay Adds Zurich Life Insurance in Malaysia Starting at RM500

    In October 2026, Zurich Life Insurance Malaysia Berhad partnered with ShopeePay Malaysia to sell life insurance directly through the e-wallet app, with entry premiums starting at RM500.

    The two-year single-premium product is named the Zurich Savings & Protection Plan. It offers guaranteed cash payouts every six months. Customers receive full principal protection at maturity, along with 105 per cent of the premium paid for life and disability coverage.

    Expanding Digital Wallet Distribution

    This agreement makes ShopeePay the first digital distribution platform partner for Zurich’s life insurance division in Malaysia. It builds on an existing relationship. The platform already distributes products for Zurich General Insurance Malaysia Berhad and Zurich General Takaful Malaysia Berhad.

    Users purchase policies inside the ShopeePay mobile app under the insurance tab by selecting the endowment category. Both companies plan to lower the minimum entry premium from RM500 to RM100 to widen user adoption.

    Targeting First-Time Insurance Buyers

    Tapping an established checkout ecosystem bypasses traditional agency channels and their higher acquisition costs. Insurers across Southeast Asia bundle life protection into short-duration endowment products for a clear reason. They want to convert younger, digital-native consumers who avoid long-term premium commitments.

    For ShopeePay, the rollout creates a high-margin financial service stream within its payments ecosystem. The move mirrors regional super-apps that are diversifying beyond payment processing and micro-lending into wealth and insurance distribution.

    Building Out Embedded Finance

    Intense competition for transaction volume across Southeast Asia is pushing digital wallets to embed stickier financial products. Short-term endowment policies create recurring platform engagement. Every six months, guaranteed cashback payouts return directly into user accounts.

    Operational risks remain if claim fulfillment or cash-out requests create friction inside a third-party app. To prevent that, Zurich and ShopeePay rely on digital underwriting infrastructure called Zurich Edge to process claims and manage policy administration.

    Next Steps For Islamic Products

    Earlier rollouts between the two companies introduced digital critical illness coverage on Shopee platforms. Benefits distributed under the program remain protected by Perbadanan Insurans Deposit Malaysia up to statutory limits.

    Looking ahead, Zurich Malaysia will broaden the lineup in 2027 by introducing Syariah-compliant family takaful products across ShopeePay. Both firms are also preparing to lower the entry threshold for the current savings plan to RM100.

  • Wpay Processes over 1.55 Billion Transactions Annually Across ANZ

    Wpay Processes over 1.55 Billion Transactions Annually Across ANZ

    Australian payment provider Wpay processed over 1.55 billion transactions across Australia and New Zealand in October 2026. Merchants are overhauling disconnected point-of-sale and digital payment networks.

    Enterprise store operators face heavy pressure to link in-store payment terminals with online checkout engines. Software stacks across Australasian retail chains remain fragmented. This setup causes operational friction. Store staff cannot view cross-channel customer histories or process instant returns.

    Rebuilding Cross-Channel Checkout Systems

    Payment architectures across the region remain divided between legacy physical registers and digital gateways. When these systems run on separate databases, customer records fracture. Data splits across store registers, mobile apps, and e-commerce websites.

    Retailers are fixing this split by adopting universal identifiers, including Payment Account Reference codes and payment tokens. These network identifiers track shoppers across physical card taps and in-app transactions. They protect customer privacy by concealing raw card numbers. Operators also link these tokens directly to loyalty programs and gift card balances. That delivers accurate data on basket size and repeat visits.

    This engineering shift changes daily store operations. Integrated systems allow partial and multiple payment captures against a single authorization code. This step prevents payment failures during split shipments and deferred fulfillment orders. Shoppers who buy online can receive immediate terminal refunds in physical stores directly back to their cards. Store staff can also push refunds to original online payment methods.

    Integrating AI Agents into Payment Rails

    Beyond traditional point-of-sale hardware and mobile applications, Australian retail networks are preparing infrastructure for automated agentic commerce. Autonomous artificial intelligence agents are entering consumer markets. These bots search product catalogues, negotiate pricing, and execute transactions directly on behalf of shoppers.

    Non-human buyers demand structural changes to transactional payment architecture. Automated purchasing requires programmable, permissioned authorization protocols and hard spending limits to avoid erroneous transactions. Heavy bot traffic also demands multi-gateway routing engines. Fraud detection must operate at machine speed.

    Modern payment platforms treat automated agents as an integrated retail channel. They direct machine sales through the same settlement, inventory, and reporting databases used by physical cash registers. This safeguards supply chains against double-booking stock. It also prevents errors in daily cash reconciliations.

    Network Resilience and Offline Store Infrastructure

    Store chains in regional Australia and New Zealand face recurring telecommunications disruptions that threaten register uptime. Register downtime leads to lost sales. It also triggers long checkout queues during peak trading periods.

    To keep lanes open, retailers are installing payment terminals equipped with local store-and-forward offline processing alongside automated 4G cellular failover connections. When primary fixed-line connections drop, registers continue logging and clearing card taps locally. Normal synchronization resumes once data links restore.

    Back-end reporting tools aggregate physical register receipts and digital gateway feeds into one central balance sheet. This direct integration eliminates the need for manual end-of-day register reconciliation across regional store footprints.

    What Enterprise Retailers Face Next

    The operational divide between single-channel terminals and unified commerce platforms will drive retail technology spending across Australasia through 2027. Retailers that delay system overhauls will struggle to support combined click-and-collect fulfillment, split shipments, and cross-channel loyalty redemption.

    Technology directors now face the task of upgrading legacy enterprise systems without disrupting live checkout lanes. Artificial intelligence buying services are entering digital marketplaces. Store operators will need payment gateways capable of authorizing automated machine transactions while maintaining strict fraud thresholds.

  • MSB Unifies Retail and Enterprise Banking on Single Platform

    MSB Unifies Retail and Enterprise Banking on Single Platform

    Vietnam Maritime Commercial Joint Stock Bank merged its retail and enterprise banking channels onto a single architecture built by Backbase and SmartOSC this week. The deployment removes the traditional technical divide between consumer accounts and corporate treasury services across the bank’s digital channels.

    Running both divisions on 1 unified engagement engine allows MSB to manage customer journeys from a central system. Branch staff, retail depositors and commercial clients now access shared service modules rather than independent software stacks.

    Architecture and Integration Scope

    Amsterdam-headquartered Backbase supplied the core engagement banking software layer, while Hanoi-based digital enabler SmartOSC managed local system integration and custom development. The project ties directly into MSB’s core transactional databases, consolidating mobile applications, web portals and assisted service touchpoints.

    Standardising the front-end layer cuts the software maintenance overhead created by operating two separate digital platforms. It also gives the bank a single interface to roll out payment features, credit applications and onboarding tools across both business units simultaneously.

    Regional Shifts in Digital Infrastructure

    Lenders across Southeast Asia spent a decade buying standalone retail mobile systems while maintaining older, custom-built corporate cash management portals. Maintaining these separate tracks doubled maintenance costs and delayed feature updates for mid-tier commercial clients whose owners expect consumer-grade mobile interfaces.

    Combining consumer and business engines shifts the engineering workload from platform maintenance to application programming interface management. For software vendors, the contract confirms how mid-sized commercial banks in Vietnam increasingly prefer packaged engagement layers over proprietary in-house builds.

    Operating Pressures in Vietnamese Banking

    Vietnamese commercial lenders face tightening margin pressure as competition over digital deposits and transaction fee income intensifies. MSB’s previous digital updates focused on individual consumer onboarding and merchant acquiring channels, which operated largely independently from its small and medium enterprise servicing pipelines.

    Consolidating those operations resolves data fragmentation between private consumer accounts and small commercial accounts, where business owners frequently bridge personal and business finances through one institution.

    Next Integration Targets

    The primary execution risk shifts to back-end stability as commercial volumes migrate onto the shared front-end framework. Corporate accounts require complex approval matrices, bulk payroll capabilities and custom payment permissions that place different operational loads on an engagement platform than retail shopping transactions.

    MSB and its integration partners will complete the migration in phases, transitioning legacy commercial clients to the new environment while tracking platform latency, API throughput and cross-service onboarding metrics over the coming quarters.

  • Ethereum Holds Near $2,700 as Futures Open Interest Hits $33.69 Billion

    Ethereum Holds Near $2,700 as Futures Open Interest Hits $33.69 Billion

    Ethereum held near $2,702 on Oct. 4 as cryptocurrency derivatives open interest reached $33.69 billion across global exchanges.

    The asset gained less than 1 percent over 24 hours, maintaining a narrow range after closing at $2,687 on Oct. 3 and $2,668 on Oct. 2.

    Trading volume in Ethereum futures hit roughly $25.04 billion in a 24-hour window. Market data tracked by CoinGlass showed elevated use across derivatives venues, leaving positioning exposed to sharp liquidation cascades if spot prices break key support or resistance thresholds.

    use Expands While Bearish Bets Surface

    Large proprietary trading desks and individual accounts took opposing positions as volatility compressed. Market trackers recorded a single short position worth approximately $61 million opened against the token, carrying an estimated liquidation price near $3,010.

    Spot pricing gained 7.1 percent over the trailing 30-day period. That month-long recovery established a higher base following late-September turbulence, yet price action stalled below broader technical breakout targets.

    Retail and institutional market participants face conflicting technical indicators. Some chart analysts point to a rising wedge pattern that risks a pullback toward $2,400 if lower support fails, while bullish desks target an initial push toward $3,000 before challenging higher boundaries.

    Exchange Inventories Show Mixed Capital Flows

    On-chain exchange reserves reflect conflicting behavior rather than sustained accumulation. CryptoQuant recorded a daily netflow of 17,492 ETH moving into centralized exchange wallets, adding to available liquid supply.

    Tracked exchange balances stood at roughly 14.66 million ETH across global platforms. That aggregate total follows a volatile September where single-day spikes altered balance totals, including an inflow of 709,400 ETH to Binance on Sept. 17 alongside isolated whale withdrawals exceeding 5,000 ETH from major venues.

    These opposing movements indicate portfolio repositioning and collateral management across venues rather than outright long-term treasury accumulation by Asian institutions.

    Testnet Roadmap Sets Immediate Technical Catalyst

    Protocol developers are shifting focus to core network upgrades rather than short-term market fluctuations. The Ethereum Foundation confirmed that the Glamsterdam upgrade will activate on the Sepolia testnet on Oct. 6 at 13:53:36 UTC.

    The software update integrates enshrined proposer-builder separation, block-level access lists, and revised gas accounting mechanisms. Mainnet deployment dates remain unconfirmed pending the results of the Sepolia trial run.

    For crypto treasury desks and digital asset funds across the Asia-Pacific region, operational stability across testnets takes precedence before allocating fresh spot capital to the ecosystem.

    Support Thresholds Define Immediate Trading Ranges

    Price action over recent weeks shows spot markets consolidating within a tighter band after absorbing initial September selling. Ethereum cleared its late-September lows, yet overall market dominance remained steady near 11 percent while Bitcoin held 57.39 percent of aggregate digital asset market capitalization.

    Traders are watching the $2,400 support level to gauge whether the current recovery holds or unwinds into used liquidations. A sustained break above the $3,000 mark remains necessary to force short liquidations and confirm a broader trend reversal.

  • GCash Prices Record Philippine IPO at 6.60 Pesos per Share

    GCash Prices Record Philippine IPO at 6.60 Pesos per Share

    GCash priced its initial public offering at 6.60 Philippine pesos per share on October 2. The deal is the largest stock market listing in Philippine history.

    The price fixes terms for institutional and retail investors after months of preparation by the country’s dominant digital payments operator. Trading schedules and final share allocations follow.

    Setting the valuation benchmark

    Setting the final price concludes the bookbuilding phase with domestic and foreign institutional funds. The 6.60-peso level anchors the platform’s public debut on the local bourse.

    Market participants watched the offering as a key test of equity appetite in Manila. It establishes the platform as the benchmark technology asset on the Philippine Stock Exchange.

    Fintech expansion across consumer channels

    Proceeds will fund financial service distribution, digital lending, and transaction processing infrastructure across the archipelago. The platform has expanded beyond peer-to-peer transfers into credit lines, micro-insurance, wealth management, and merchant payments.

    Competition across Southeast Asian digital payments has shifted from user acquisition toward merchant monetisation and lending margins. Philippine consumers rely on digital wallets for utility settlements, offline retail payments, and e-commerce transactions. That gives large ecosystem operators steady transaction volumes.

    Implications for Philippine capital markets

    Liquidity from the record transaction flows into a domestic exchange that recorded muted listing volumes over recent quarters. A successful listing by a marquee technology firm reopens the domestic market to large private equity exits and institutional portfolio reallocations.

    Regional equity investors will track post-listing liquidity closely. Sustained trading activity could encourage other venture-backed technology operators in Southeast Asia to explore primary domestic listings rather than dual-class foreign debuts in the United States.

    Next steps for trading and allocations

    Retail offering periods and institutional book settlements begin after the formal price confirmation. Bourse officials and underwriters will monitor opening-day price stability and institutional secondary market participation once shares begin unrestricted trading.

  • Ping an Bank Approves AI Rules After Deploying over 450 Use Cases

    Ping an Bank Approves AI Rules After Deploying over 450 Use Cases

    Ping An Bank has approved internal management rules for artificial intelligence, becoming the first listed Chinese lender to formally adopt an AI governance framework.

    The Shenzhen-listed lender announced the board-approved measures in a filing on Wednesday, following a push by regulators for banks to strengthen oversight of AI use.

    Board oversight and risk tiers

    By the end of June, the bank had rolled out more than 450 large-model AI use cases across marketing, investment advice, compliance and risk control, according to its interim report.

    Operational AI risks are classified into distinct tiers and folded into the bank’s enterprise risk-management system. While the lender confirmed the board approval in a regulatory filing, it has not published the full text of the rules.

    Scale of deployment across lenders

    All 42 A-share listed commercial banks in mainland China referenced AI deployments in their interim financial reports this year. Several other listed lenders are preparing matching compliance rules to meet state regulatory requirements.

    Across the region, formalising AI governance shifts the technology from experimental pilots to audited core infrastructure. The operational risk lies in compliance execution. Internal oversight mechanisms must keep pace with rapid deployment without choking automated workflow efficiency.

    Hong Kong sandbox and cross-border testing

    Regulators in neighbouring Hong Kong are pushing financial firms to adopt autonomous systems while maintaining cross-border compliance standards. In March, financial authorities expanded a supervised generative AI sandbox to include securities brokerages, insurance underwriters and pension funds. The program first launched for retail banks in 2024.

    Financial Secretary Paul Chan Mo-po stated that Hong Kong provides a testing environment for model training, data security and cross-border financial data flows under common law standards. Gary Ng, senior economist for Asia-Pacific at Natixis, noted that the city operates as “a perfect place to test and apply the standards of different jurisdictions in an increasingly fragmented world”.

    Regulatory requirements and earlier steps

    The governance measures implement binding guidelines issued in June by the National Financial Regulatory Administration. Those rules require mainland commercial banks and licensed insurers to assume direct institutional liability for autonomous systems. They also mandate board-level supervision of algorithm deployment.

    International financial groups are running similar integration programs across Asia and Europe. HSBC launched its HSBCnio corporate data platform in late September to connect institutional accounts directly to client AI tools. Barclays expanded its automated software engineering tools across retail and wholesale units.

    Attention now turns to the remaining A-share lenders as third-quarter disclosures approach. Those filings will show which state-owned and joint-stock commercial banks follow Ping An Bank in publishing board-approved AI governance structures.

  • Apple Pay Enters India with Axis Bank in 16.3 Million Card Rollout

    Apple Pay Enters India with Axis Bank in 16.3 Million Card Rollout

    Apple Pay launched in India on Wednesday through an exclusive initial partnership with Axis Bank. The rollout enters the world’s most populous consumer market.

    Axis Bank is India’s fourth-largest credit card issuer. It held 16.3 million cards outstanding out of 124 million nationwide as of August, according to central bank data.

    How the Axis Bank Rollout Works

    The private lender, India’s third-largest, is the first domestic institution to support the payment service. Cardholders can link eligible Visa and Mastercard credit cards through the Axis Bank mobile app or directly inside Apple Wallet.

    Transactions operate across physical retail checkouts, mobile apps, and online merchant portals using iPhone, Apple Watch, and iPad hardware. The service enables contactless checkout without a physical card PIN or a one-time password. Instead, it authenticates charges through Face ID, Touch ID, or a device passcode.

    Domestic cards issued on India’s homegrown RuPay payment network remain excluded from the service at launch.

    India is home to a dynamic and digitally savvy population that continues to embrace a cashless future while expecting the highest standards of security and privacy, and we’re so excited to bring Apple Pay to users in India today.

    The Battle Against UPI Dominance

    Entering India puts Apple directly up against the Unified Payments Interface. The domestic real-time bank settlement architecture processes 84 per cent of digital transaction volumes. According to a 2025 International Monetary Fund report, the protocol ranks as the world’s largest retail fast-payment network by transaction volume.

    For retailers and consumer brands across India, adding Apple Pay provides a direct checkout route for premium smartphone owners. These shoppers frequently transact on credit rather than direct bank debit. The system shifts point-of-sale interaction toward tap-and-pay hardware readers, bypassing the QR-code scanning routines that dominate local merchant counters.

    Merchant Margins and Bank Negotiations

    Commercial terms have slowed broader adoption among top Indian credit issuers. Apple held talks with larger domestic rivals HDFC Bank and ICICI Bank. It has not agreed commercial terms with either institution.

    Interchange fee sharing and integration expenses remain the central tension in a market where UPI merchant transactions carry minimal processing costs. Axis Bank took the opening position to attract affluent device owners. In doing so, it accepted Apple’s ecosystem rules to secure an early advantage in premium card acquisition.

    Next Steps for Indian Card Expansion

    India was one of the last major global economies without local wallet support after earlier rollouts across East Asia and Southeast Asia. The launch coincides with Apple’s widening retail footprint in Mumbai and New Delhi, where direct store openings have accelerated hardware sales.

    Attention now turns to whether HDFC Bank and ICICI Bank resolve fee discussions to link their respective card portfolios. A deal with both lenders would open Apple Pay to more than half of India’s total credit card base.

  • Indonesia Cyber Attacks Inflict US$6.2 Billion in Losses This Year

    Indonesia Cyber Attacks Inflict US$6.2 Billion in Losses This Year

    Cyber attacks caused an estimated US$6.2 billion in financial damage across Indonesia during 2026, Bank Indonesia Governor Destry Damayanti announced in Jakarta on Thursday.

    Central bank officials linked the losses directly to automated tools and artificial intelligence. These technologies multiply payment fraud, scam operations, and data theft across consumer networks.

    Surging Risks in Digital Payments

    Destry urged government ministries and commercial agencies to tighten payment security standards and enforce direct consumer protections. The central bank holds the statutory mandate to supervise and develop the country’s payment infrastructure.

    Digital networks expand domestic economic output. Still, the governor warned that interconnected systems leave merchant acquiring channels and retail banking endpoints exposed to automated intrusion. Joint security literacy programs with the Financial Services Authority are planned to train consumers and retail operators.

    ISP Group Pushes Security Bill

    Backing the central bank’s warning, the Indonesian Internet Service Providers Association (APJII) demanded swift passage of the Cyber Security and Resilience Bill. Commercial internet providers require uniform technical standards and legal clarity to defend national digital infrastructure against automated threats, according to APJII Chair Muhammad Arif.

    “Indonesian service providers need legal certainty to grow, not disruptive regulations,” said Arif.

    Monitoring data from APJII tracked 246.4 million connections to dangerous IP addresses between June 13 and August 28, 2026. A separate three-day network scan by the association recorded roughly 68 million distinct cyber attack events targeting domestic routes.

    Direct Pressures on Retail and Finance

    For retail merchants, digital lenders, and e-commerce platforms operating across Southeast Asia’s largest market, these financial losses raise basic operating costs. Acceptance of QR codes and instant transfer rails expanded rapidly over the past three years. Back-end defense budgets frequently lagged that growth.

    Platforms now face higher chargeback rates, elevated verification costs, and direct liability when account credentials leak. Operators that fail to upgrade transaction authentication face friction at checkout. Financial institutions risk regulatory penalties if compromised channels disrupt daily settlement flows.

    Escalating Breach Scale Since 2025

    The US$6.2 billion tally reflects climbing attack sophistication following major infrastructure breaches over the previous eighteen months. Regional lender Bank DKI suffered repeated network intrusions that produced over US$15 million in irregular transactions, showing how attackers breach core accounting ledgers.

    Parliamentary debate on the Cyber Security and Resilience Bill now enters committee reviews. Enterprise software providers and payment processors are tracking whether mandatory incident-reporting rules will carry statutory fines before the legislative session closes.

  • Bank Indonesia Issues 32,457 Domestic Credit Cards in First Month

    Bank Indonesia Issues 32,457 Domestic Credit Cards in First Month

    Indonesian commercial lenders issued and activated 32,457 domestic credit cards in the first four weeks following the system’s retail debut. The figures, confirmed by Bank Indonesia Governor Destry Damayanti in Jakarta on September 24, 2026, track adoption since the retail tier went live on August 17.

    Total spending across the new network reached Rp18.7 billion over 38,800 transactions. Average ticket size stood at Rp482,000, pointing to everyday retail purchases rather than high-value consumer financing.

    Transaction Volume and Merchant Spend

    The card, known locally as Kartu Kredit Indonesia (KKI), operates in its first phase as a virtual credit line linked directly to the national QRIS standard. Shoppers scan standard merchant QR codes at checkouts, drawing down an unsecured credit balance through their standard mobile banking application rather than a deposit account.

    Bank Indonesia Deputy Governor Filianingsih Hendarta reported that nearly 8,000 individual cardholders have executed live purchases across the initial network. The difference between issued cards and active spenders highlights the early onboarding curve as retail customers set up digital limits inside existing mobile banking apps.

    Bank Distribution and Market Share

    Private lender PT Bank Central Asia accounts for the bulk of early issuance, logging roughly 28,000 cardholders during the opening month. State-owned PT Bank Rakyat Indonesia and private lender PT Bank Permata follow at a distance, each recording around 1,500 active users.

    Five other payment service providers make up the initial implementation cohort: Bank Mandiri, Bank Negara Indonesia, CIMB Niaga, Bank Mega, and Bank Syariah Indonesia. For retail merchants across tier-one cities, the domestic scheme reduces dependence on foreign card networks while plugging directly into existing QR checkout hardware and printed counter placards.

    Sharia Options and Technical Integration

    Participating lenders are structuring distinct product variants to capture specific consumer segments. Bank Syariah Indonesia is developing Sharia-compliant financing structures to offer non-interest credit lines over the central switch.

    Local retailers benefit from standardized merchant discount rates tied to the domestic clearing infrastructure. By channelling unsecured revolving credit through QRIS rails, physical merchants avoid procuring separate point-of-sale terminals to accept credit payments from everyday shoppers.

    E-Commerce and Physical Card Rollout

    The central bank launched the KKI framework initially for government procurement before expanding the architecture to retail consumers on August 17, 2026. The shift forms part of a broader push to retain domestic transaction fees inside the national clearing ecosystem while expanding consumer credit access outside traditional cardholder demographics.

    Bank Indonesia is executing the consumer rollout across three distinct phases. The current phase covers QRIS-linked digital cards inside banking applications. Phase two will expand the network to online e-commerce checkout gateways, while the third phase will introduce physical cards for merchants without digital scanning terminals.

  • DBS Expands Avaloq Wealth Tech Alliance to Target SGD 1 Trillion Assets

    DBS Expands Avaloq Wealth Tech Alliance to Target SGD 1 Trillion Assets

    DBS Bank signed a memorandum of understanding with wealthtech vendor Avaloq to expand platform deployment across Asia. The lender is targeting SGD 1 trillion in retail and wealth assets.

    The agreement extends an 18-year technology alliance. It supports the Singapore-based bank’s goal of reaching S$1 trillion (USD 781 billion) in assets under management by 2030.

    Scaling Assets to One Trillion Dollars

    Under the memorandum, DBS and Avaloq will evaluate broader deployment of the Avaloq core platform across the bank’s international markets and retail lines. The work includes adapting software architecture to local regulatory requirements across the region.

    Both companies plan to jointly build digital tools, execution workflows, and operating models for advisers. DBS will also run capability exchanges and training programmes with Avaloq to teach front-line and back-office staff to use automated and artificial-intelligence-enabled tools.

    “Avaloq has been a critical enabler for our wealth management operations for the past 18 years,” said Shee Tse Koon, group executive and head of consumer banking and wealth management at DBS. “By deepening capabilities across the wealth continuum, we can give our advisers greater capacity for the judgment that matters and help more customers put their money to work.”

    Software to Bridge Adviser Shortages

    Wealth managers across Asia face a persistent shortage of licensed human advisers as private capital expands in financial hubs. Industry figures indicate that seven in 10 regional investors currently use a dedicated wealth adviser. Meanwhile, more than 40 per cent of self-directed investors want one assigned to them.

    Automating portfolio construction, compliance checks, and back-office trade processing allows relationship managers to handle larger client books without inflating headcount. DBS is betting software scalability bridges that advisory shortfall faster than direct hiring. Rival institutions continue to bid up compensation packages for experienced bankers in Singapore and Hong Kong.

    Cross-Border Wealth Infrastructure

    The Avaloq deal builds on recent distribution partnerships designed to capture wealth flows across East Asia. In July, DBS established a wealth management alliance with South Korea’s Samsung Securities. That tie-up linked domestic capital markets access in Seoul with the bank’s regional advisory infrastructure.

    Integrating third-party platforms with proprietary banking engines creates operational complexity, especially when synchronising risk rules and multi-currency product suites across jurisdictions. Avaloq is widely deployed among European and Asian private banks. It provides the core transactional layer DBS relies on to process high-net-worth and mass-affluent accounts.

    Operational Execution Targets

    Technical collaboration will focus on three areas: enterprise growth, co-innovation of advisory products, and talent development across technology teams.

    DBS has set 2030 as the firm deadline to reach its SGD 1 trillion asset target. The initial rollout of platform enhancements under the agreement will launch across key Asian franchises over the coming financial year.