Tag: luxury retail

  • Southeast Asian Luxury Tourist Influx Projected to Drop 38 Percent

    Southeast Asian Luxury Tourist Influx Projected to Drop 38 Percent

    Southeast Asian luxury boutiques face an abrupt end to a decade of passive tourist spending, with luxury tourism growth projected to decline by up to 38 percent following maritime route closures in the Strait of Hormuz and global geopolitical disruption. Flagship stores across Jakarta, Bangkok, Singapore, and Kuala Lumpur must now rely entirely on domestic consumers to absorb regional inventories, according to projections from the UN Tourism and Retail Asia Economic Outlook.

    A joint study by Harvard Business Review and Deloitte reveals that execution failures on the sales floor account for up to 72 percent of in-store purchase cancellations, driven by unproactive staff and poor customer experience rather than a lack of buying interest. To stop this revenue leakage, boutique operators are turning to artificial intelligence tools, including Nimbly Echo from Nimbly AI, to monitor floor interactions and audit service quality.

    The shift follows years of unearned footfall that left store teams ill-prepared for domestic clienteling, with research showing that more than 85 percent of boutique visitors enter with specific purchase intent, while price resistance accounts for less than 5 percent of abandoned sales.

    The Conversion Gap on the Sales Floor

    Data shows that shoppers entering luxury stores arrive ready to spend. Harvard Business Review retail behavioural research indicates that more than 85 per cent of boutique visitors enter with specific purchase intent or targeted collection interest, while shoppers without buying intent account for roughly 6 per cent. An Econsultancy study shows price friction causes fewer than 5 per cent of abandoned luxury transactions.

    Instead, transactions collapse because boutique personnel fail to engage visitors. Operational data gathered through Nimbly AI’s conversation tracking tool, Nimbly Echo, shows staff proactively recommend products in only 40.9 per cent of interactions. Store associates demonstrate or explain new collections to just 14.0 per cent of visitors, despite data showing positive shopper response rates reach 52.9 per cent when staff present products directly.

    Inventory friction deepens the drop-off. When requested stock is missing from display shelves, 83.9 per cent of store associates fail to suggest alternative items available in the boutique. The Shopper Dismissal and Luxury Retail Service Gap Study found that 73 per cent of VIP consumers report encountering cold treatment or neglect on their initial visit, prompting permanent customer churn. Globally, poor customer service costs the luxury sector up to $1.7 trillion, according to data from IHL Group.

    Pivoting from Point of Sale to Experience Centres

    Luxury operators in Southeast Asia are reworking their retail spaces to focus on long-term client relationships rather than quick tourist transactions. A study from Bain and Company indicates that personalised clienteling focused on brand heritage can lift customer lifetime value in luxury retail by 3.5 times. Retaining local VIP clients also costs up to five times less than acquiring new shoppers in a depressed tourist market, according to Deloitte.

    The operational shift requires luxury brands to discard traditional store auditing tools. Overhead door sensors track staff, cleaners and security guards indiscriminately, skewing conversion ratios. Standard checkout point-of-sale registers record paid purchases but capture nothing about the 70 per cent of buyers who leave without purchasing. Periodic mystery shopper visits offer only staged snapshots during quiet periods rather than daily performance under floor pressure.

    Deploying Conversation Intelligence in Stores

    To audit customer interaction, retail groups are rolling out retail-contextual artificial intelligence tools such as Nimbly Echo. The software evaluates spoken dialogue on the shop floor to measure service tone and warmth against luxury brand standards. It also logs verbal objections and stock requests, giving inventory planners direct visibility into unfulfilled local demand.

    Store managers use interaction data to test sales scripts and guide associate coaching. The technology replaces manual walkarounds with automated alerts on floor performance, letting regional directors benchmark store execution across multiple Southeast Asian markets.

    The Bottom-Line Hurdle for Retail AI

    For store operators and landlords, this shift exposes a major commercial divide: technology that tracks service performance must prove it can lift net revenue. Luxury brands across Asia previously spent capital on digital floor displays and clienteling apps that produced operational records but failed to stem floor leakage. If conversation intelligence merely flags unhelpful associates without lifting conversion per square metre, finance chiefs will cut the software line.

    Tracking spoken retail conversations also brings execution risks. Associates pushed to follow artificial conversational scripts often deliver mechanical service, the exact opposite of what affluent domestic buyers expect. Landlords holding premium mall leases will monitor whether these monitoring investments protect store sales productivity as tourist traffic remains volatile.

    Shifting Demographics and Financial Pressures

    For nearly a decade, regional luxury outposts generated steady revenues from incoming high-net-worth travellers, requiring little active selling from floor staff. That commercial buffer evaporated as geopolitical unrest disrupted regional airline routes and maritime transit, triggering the 38 per cent decline projected by the UN Tourism and Retail Asia Economic Outlook.

    Financial pressure inside retail groups complicates software adoption. A cross-industry CEO survey by Gartner found that 44 per cent of chief executives struggle to prove measurable financial returns from artificial intelligence deployments. McKinsey’s 2026 State of AI survey revealed that 37 per cent of companies attribute earnings before interest and taxes impact to AI implementations, identical to the previous year’s level. Retailers deploying conversational auditing will face intense scrutiny from finance teams requiring cashable savings rather than soft efficiency metrics.

    Luxury networks across Southeast Asia are now testing whether automated frontline monitoring can lift conversion rates before full-year financial allocations close.
  • Lindt Opens First Southeast Asian Store in Kuala Lumpur with Valiram

    Lindt Opens First Southeast Asian Store in Kuala Lumpur with Valiram

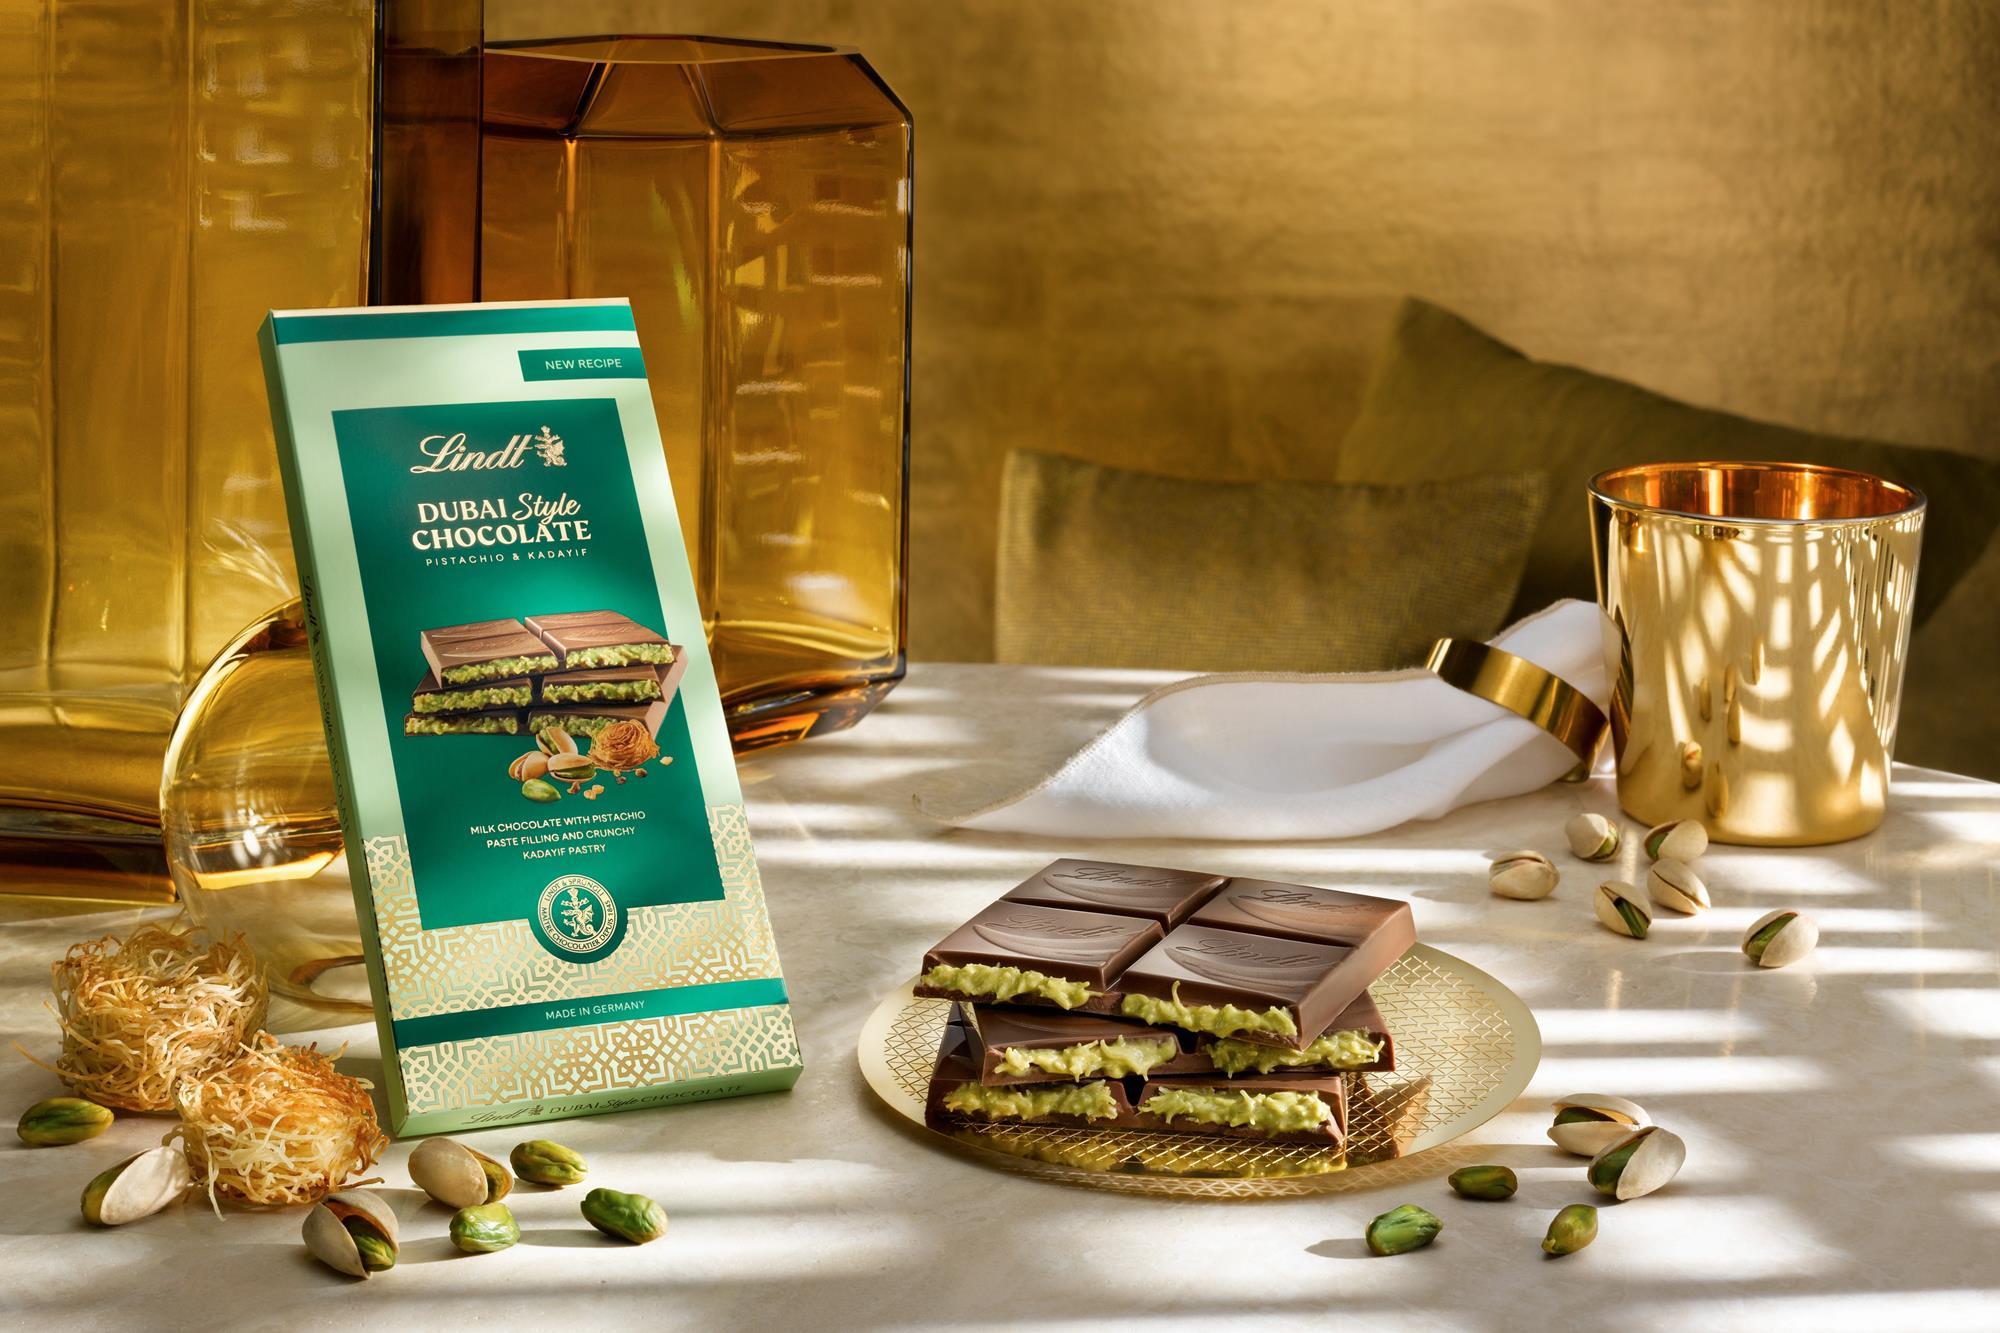
    Swiss chocolatier Lindt opened its first Southeast Asian standalone boutique at Kuala Lumpur’s The Exchange TRX on Friday. The company partnered with luxury distributor Valiram for the launch.

    A dedicated Pick & Mix station inside the flagship stocks 19 Lindor varieties alongside market-exclusive flavours. The installation anchors the brand’s direct retail push across the region.

    Product mix at The Exchange TRX

    Inside, the shop carries Lindt’s full inventory. Lines include the Excellence dark chocolate range, the Extra Creamy milk selection, and the newer wafer lineup.

    With the bulk Pick & Mix fixture, the store replicates the format Lindt runs across European transit hubs and North American city centres. Shoppers choose items by weight instead of buying fixed multipacks. This lifts basket sizes. It also gives the confectionery maker direct control over pricing and display.

    Valiram’s premium confectionery push

    Valiram manages operations on the ground. The Kuala Lumpur-based conglomerate oversees regional networks for international labels across fashion, timepieces, and specialty food.

    Partnering with Valiram gives Lindt immediate access to prime mall space without building local logistics from scratch. Valiram already holds leases in key commercial developments across Malaysia, Singapore, Indonesia, and Thailand. Placing Lindt in The Exchange TRX puts the brand inside Kuala Lumpur’s newest financial district, targeting affluent locals and international travelers alike.

    Direct retail over wholesale distribution

    For decades, European chocolatiers treated Southeast Asia strictly as an import wholesale market. Supermarkets, duty-free airport kiosks, and specialty grocers sold boxed stock through third-party food brokers.

    That model shields margins against tropical heat and supply chain hurdles, but it limits brand control. Supermarkets discount stock, and tight shelf space restricts product range. Standalone boutiques shift the strategy toward experiential shopping. Gifting and seasonal items command higher prices in this format.

    Earlier airport presence paved the path

    Lindt previously relied on airport duty-free counters and travel-retail pop-ups across Southeast Asia. The Malaysian store is its first permanent high-street location in the region.

    Competitors have tested similar models. Godiva built boutique cafes across Asian capitals over the past decade, while Japanese and European artisan producers expanded into major malls. Lindt enters the standalone space focused on packaged volume at lower entry price points than luxury cafe chains.

    Future results at The Exchange TRX will determine how quickly Valiram and Lindt expand into secondary Malaysian markets like Penang, as well as Singapore and Bangkok.

  • Cordova Launches Menswear Ski Line with Japan Retail Push

    Cordova Launches Menswear Ski Line with Japan Retail Push

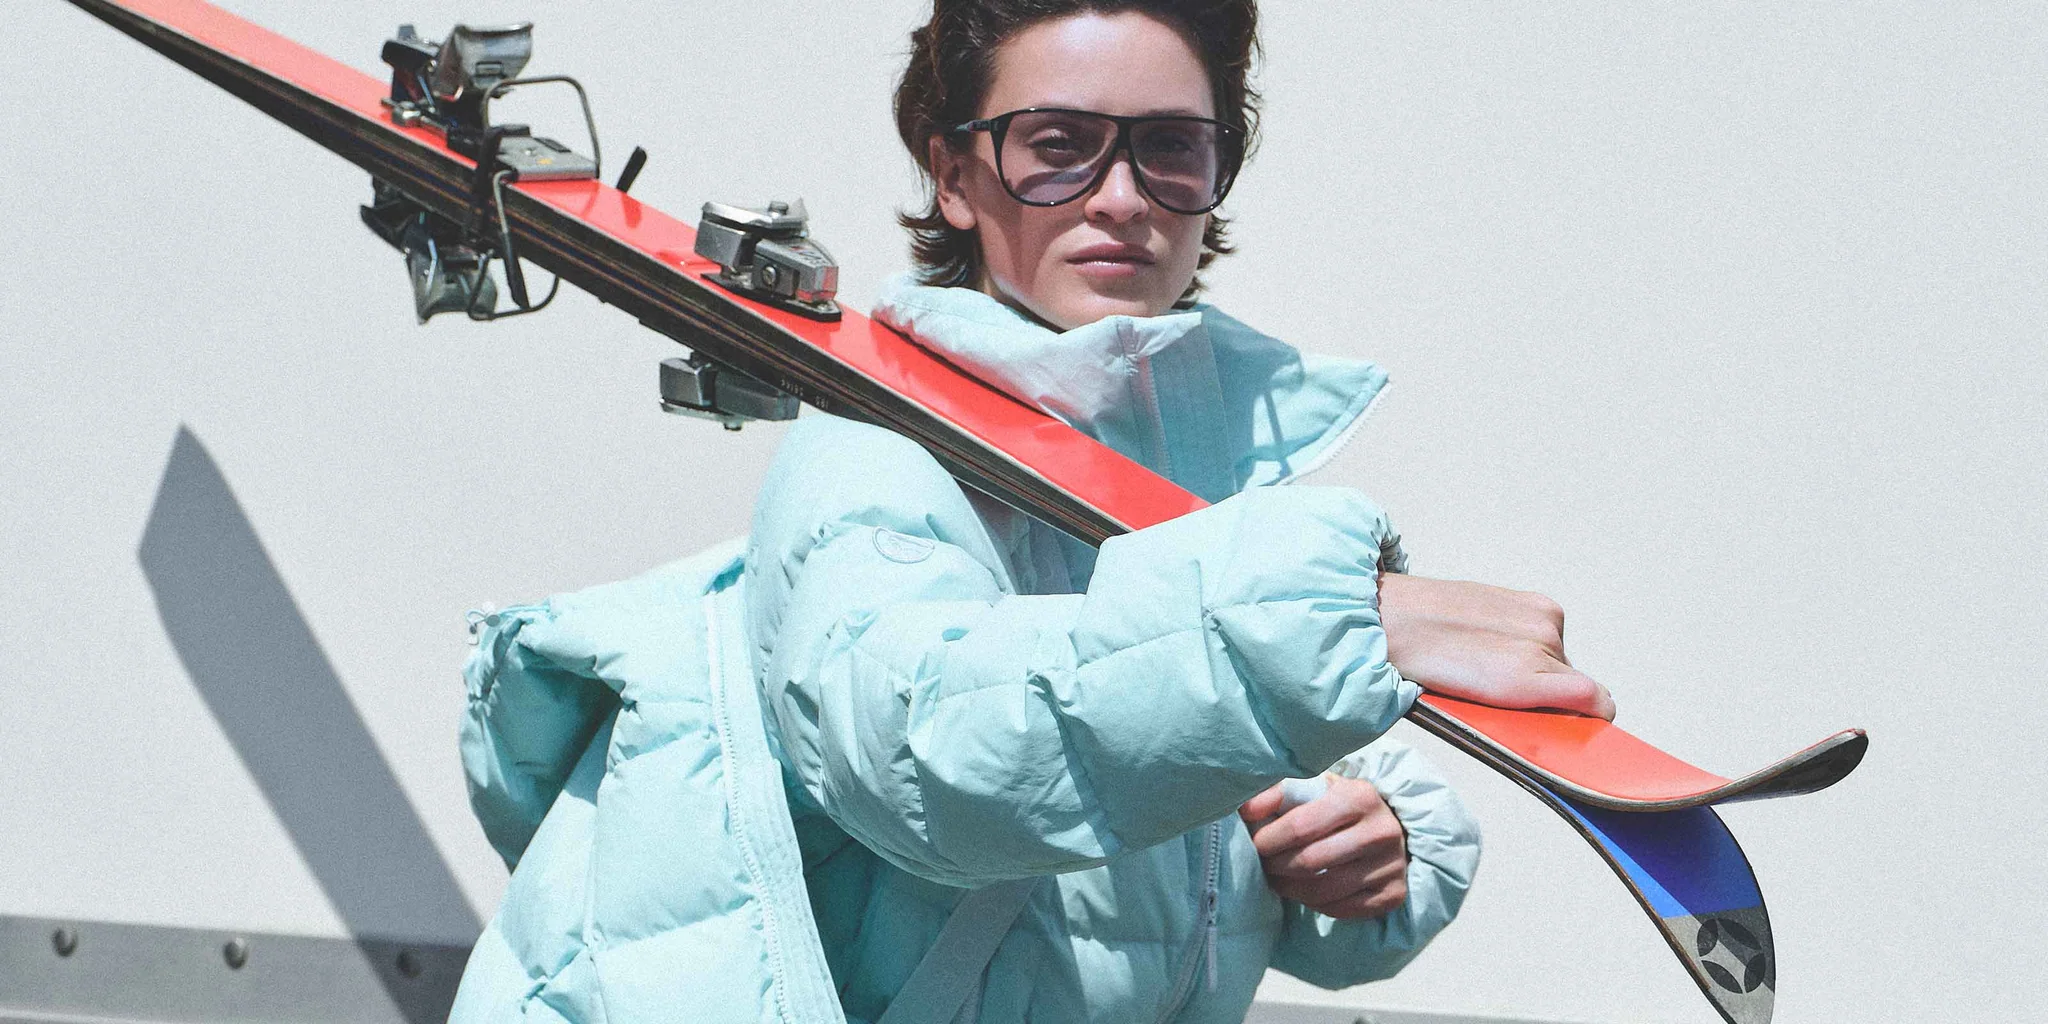
    Cordova launched its debut menswear collection on its tenth anniversary. The release expands the luxury skiwear label into men’s alpine apparel across wholesale partners in Japan, Europe and North America.

    The 21-piece range features nine silhouettes. Prices span from $160 for accessories to $1,980 for full one-piece ski suits.

    Wholesale rollout and Japan distribution

    Jane and Cody Seim founded the business in 2016 as a women’s luxury ski brand. It built sales on tailored one-piece suits through platforms including Net-a-porter, Mytheresa and Moda Operandi. The men’s line is the label’s first category expansion beyond womenswear.

    Physical distribution focuses on specialty boutiques in ski markets including Japan, Aspen, Courcelles and the French Alps. Online sales run exclusively through Browns Farfetch and Forward in the United States ahead of wholesale presentations at the Paris market in January.

    Technical fabrics and pricing tiers

    The collection spans technical ski jackets, trousers, puffers and knitwear. Premium pieces include a waterproof Italian wool ski jacket priced at $1,350 and matching pants for $900. Outerwear puffers retail between $1,000 and $1,400, depending on fabric specifications sourced from European and Japanese textile mills.

    There are unexpected materials in prints and colorways that create an emotional connection and some excitement for men. We felt there was a need in the market and this is the right time to meet that.

    Differentiation in luxury performance outerwear

    Cordova enters a luxury ski segment contested by established European performance houses and fashion conglomerates expanding into winter sports capsules. Moncler, Bogner and Fusalp command significant market share across Asian ski destinations. That presence is strong in northern Japan and mainland China, where winter sports tourism has expanded.

    Tailored silhouettes and retro alpine references from 1960s and 1970s ski culture position the offering away from purely technical shells. For independent luxury labels, the primary challenge is scaling production. They must also secure wholesale floor space against legacy outerwear giants with dedicated mono-brand retail networks.

    Next steps at Paris market

    Initial production began a decade ago with 120 women’s ski suits before securing department store placement with Selfridges and Matches. Output has since expanded globally across premium specialty retailers.

    Wholesale buyers will review the full menswear line during Paris market showroom sessions in January. Those appointments will determine the brand’s door count for the subsequent winter delivery cycle.

  • LVMH, Hermès and Kering Shares Fall up to 40% Since January

    LVMH, Hermès and Kering Shares Fall up to 40% Since January

    Over the past three years, the luxury retail sector has experienced a steady decline following a brief post-pandemic boom, with most major players reporting lower-than-ever sales figures.

    Since January, share prices of LVMH, Hermès and Kering have fallen 40 per cent, 39 per cent and 30 per cent, respectively, while Richemont remains roughly flat.

    Valuations tumble after pandemic highs

    The downturn reflects the Q3 performance of eight key luxury companies, including Burberry, Hermès, Kering, LVMH, Moncler, Prada and Richemont, as major luxury houses struggle with falling demand.

    Third-quarter earnings across eight key players, Burberry, Hermès, Kering, LVMH, Moncler, Prada and Richemont, show softer client appetite. Entry-level and aspirational buyers cut spending sharply. Top-tier jewelry and watch assets held their ground better than leather goods and fashion apparel.

    Richemont holds steady against fashion losses

    Richemont avoided the valuation collapse that hit French fashion and leather houses. Its share price traded roughly unchanged over the period. Steady demand for high jewelry and fine timepieces insulated the group.

    By contrast, fashion-heavy houses such as Kering and LVMH bore the brunt of reduced store traffic. Aspirational buyers drove volume growth for designer accessories and entry-level items during the post-pandemic rebound. They cut discretionary outlays as price hikes collided with tighter household budgets.

    Shift in aspirational demand across core markets

    Retail strategies face a reset after three years of contraction. Luxury groups spent the post-pandemic cycle raising prices on signature handbags and footwear. They wagered that brand equity would protect volume.

    That pricing strategy has hit resistance. Brands dependent on repeat purchases from middle-income aspirational consumers are seeing foot traffic slow. Operators and department store landlords must now adjust inventory intake and floor space allocations.

    Earnings filings show divided sector performance

    The retreat began three years ago when pandemic savings cushions unwound and international travel normalized. Quarterly reports from Paris and Milan have since shown sequential decelerations across core product divisions.

    Investors and retail operators now track upcoming full-year earnings from LVMH, Kering and Richemont. Those reports will show whether inventory adjustments and selective price freezes can stabilize revenue heading into the next fiscal cycle.

  • China Economic Slowdown Weighs on LVMH Luxury Fashion Business

    China Economic Slowdown Weighs on LVMH Luxury Fashion Business

    A broader economic slowdown in China has started weighing on LVMH’s core luxury fashion operations across key Asian retail hubs. Weak consumer confidence in the mainland market is curbing discretionary purchases for top-tier apparel and leather goods.

    Shoppers across tier-one Chinese cities are pulling back on aspirational luxury purchases, hitting store footfall and transaction values. The pullback directly affects revenue momentum across flagship fashion houses within the French conglomerate’s portfolio.

    Slowing Momentum in Mainland Stores

    Department stores and high-end shopping complexes in Shanghai and Beijing report softer traffic among local buyers. Domestic consumers who previously drove double-digit retail gains are deferring non-essential purchases or turning toward alternative spending categories.

    Footfall declines have spread into secondary luxury corridors where premium labels expanded floor space over recent years. Landlords operating high-end properties now face slower turnover across fashion and accessories concessions.

    Regional Shifts in Luxury Spending

    Part of the slowdown reflects Chinese travelers shifting luxury purchases abroad rather than buying in domestic boutiques. Currency differences in markets like Japan continue to divert transaction volume away from mainland counters.

    This spending diversion complicates inventory management for regional operators who stocked high volumes across Chinese city flagships. Operators must balance localized retail expenses against shifting consumer travel flows across East Asia.

    Pressure Across Fashion and Leather Portfolios

    Fashion and leather goods represent the largest profit engine for luxury conglomerates operating in Asia. When demand softens in mainland China, the impact spreads rapidly across broader regional wholesale and retail networks.

    Rival European luxury houses face identical headwinds as middle-class consumers reassess discretionary budgets. Price increases implemented over previous quarters have also met increased resistance from domestic buyers seeking value retention.

    Next Steps for Asian Retail Networks

    Luxury groups are reviewing capital spending on new boutique openings across Greater China. Attention is turning toward clienteling programs and exclusive VIP experiences to retain high-net-worth shoppers while mass-affluent spending remains subdued.

    Retail property owners and brand managers will track consumer footfall data through upcoming holiday travel seasons to gauge whether promotional initiatives can stabilize store volumes across the region.

  • LVMH Fashion Sales Drop 5 Percent in Third Quarter

    LVMH Fashion Sales Drop 5 Percent in Third Quarter

    LVMH posted a 5 percent drop in third-quarter organic sales across its core fashion and leather division. Spending by Chinese shoppers deteriorated sharply.

    Total group revenue rose 1 percent on an organic basis to 18.5 billion euros ($20.7 billion). Market analysts had forecast 1.3 percent growth.

    Fashion and leather goods generate nearly half of group revenue. The unit’s contraction landed well below consensus estimates of a 1.8 percent decline. Flagship labels Louis Vuitton and Dior took the brunt of the downturn. Regional sales across Asia excluding Japan dropped 5 percent over the quarter.

    Chinese Spending Reverses Regionally

    Weakness in mainland China offset gains in other markets, including a 5 percent sales increase in the United States. Chinese consumers generate roughly one-fifth of global luxury purchases. That exposure hit regional department store concessions and flagship boutiques as footfall and basket sizes retreated.

    Recent regulatory pressure in China, including a tax crackdown on wealthy individuals, dampened appetite for high-ticket discretionary purchases. In mainland retail centers, luxury operators report tighter consumer budgets and reduced conversion rates across apparel and leather goods.

    “In the third quarter specifically, Asia was penalised by a sharp macro-led deterioration in Chinese consumer sentiment, with a tangible impact on discretionary expenses.”

    Hard Luxury Loses Momentum

    Slower demand spread into categories that previously showed resilience during broader retail pullbacks. Organic sales growth in the watches and jewellery unit, which includes Bulgari and Tiffany, slowed to 6 percent in the third quarter after posting 9 percent growth during the first half of the year.

    Hard luxury typically attracts shoppers seeking store-of-value assets during economic uncertainty. Slower momentum at Tiffany and Bulgari shows that even affluent shoppers across Greater China are delaying watch and jewellery transactions.

    Mall Landlords and Margin Pressure

    For high-end landlords across Shanghai, Beijing and Hong Kong, falling sales at anchor fashion tenants threaten revenue-share lease terms. Premium malls lean heavily on Louis Vuitton and Dior flagships to generate customer foot traffic. Softer sales volumes reduce landlord yields on turnover rents.

    Rival luxury conglomerates face identical pressure across their regional store networks. European luxury groups have shed roughly 330 billion euros in combined market capitalization this year. Marketing budgets and store renovation schedules across second-tier Asian cities now face immediate scrutiny.

    Three Years of Slower Growth

    The latest trading update extends a three-year luxury demand deceleration across Asia. Following a brief post-pandemic rebound in travel retail, Chinese outbound tourism shifted toward closer regional destinations where luxury price differentials have narrowed.

    LVMH shares fell more than 3 percent in US trading following the update. Investors and retail operators now track whether upcoming fourth-quarter holiday trading and Chinese New Year bookings stabilize inventory levels across luxury flagship networks.

  • Athleisure and Luxury Lift K11 Musea Tourist Sales by 26% During Golden Week

    Athleisure and Luxury Lift K11 Musea Tourist Sales by 26% During Golden Week

    Tourist spending at Hong Kong’s K11 Musea climbed 26 per cent year on year during National Day Golden Week. New premium fashion and sports apparel tenants drove the gains.

    Footfall at the waterfront complex rose roughly 12 per cent over the holiday period. That set an all-time October record for the property.

    Athletic apparel delivered the sharpest rebound. Spending by loyalty members on athleisure surged 279 per cent compared to the same holiday window last year. US label Alo Yoga helped drive those gains after opening a duplex harbourfront unit in September. Running brand HOKA added its largest Hong Kong specialty store during the third quarter. Chinese outdoor brand KAILAS also introduced its first mountaineering concept shop in the territory.

    Luxury flagships and dining lift basket sizes

    High-end jewellery and watches generated the bulk of high-ticket transactions. The single largest purchase approached HK$2 million. Member sales across international luxury labels rose 75 per cent year on year. Fashion apparel revenue climbed 25 per cent.

    Lower-level openings fueled the luxury surge. Prada launched a new duplex flagship, Miu Miu opened a boutique, and Max Mara unveiled a two-storey concept store.

    Restaurants captured spillover traffic from evening events around Victoria Harbour. An estimated 380,000 people gathered along both sides of the harbour for the 1 October fireworks display. Every harbour-facing restaurant inside the mall was fully booked for dinner. Dine-in revenue across the property rose 10 per cent year on year through the break.

    Tenant reshuffle tests high-density retail

    Spending patterns show how Hong Kong mall operators must reconfigure floors to capture mainland tourist dollars. Inbound travellers have shifted away from mass retail. Instead, they seek experiential dining, technical sportswear and luxury concepts.

    Landlord New World Development Company Limited swapped standard mall units for multi-storey duplexes and outdoor labels to defend market share against Causeway Bay and Central. The real test is whether athletic labels can maintain sales density once opening promotions fade.

    NWD broadens brand overhaul

    Holiday numbers follow a multi-year repositioning campaign across New World Development’s retail portfolio. During the previous financial year, the overall K11 operating segment expanded 9 per cent year on year. K11 Musea posted record full-year retail sales.

    Experiential events ran alongside the retail rollouts. The venue staged an immersive space exhibition called “Fly Me to the Moon: A 380,000 km Journey”. It also ran a gin-pairing dining promotion titled “Taste of GIN-dulgence” across 12 venues in K11 Musea and adjacent K11 Art Mall.

    New World Development plans to open another round of international retail flagships across K11 Musea before the end of the fourth quarter.

  • China’s 20% Tax Crackdown Piles Pressure on Luxury Brands

    China’s 20% Tax Crackdown Piles Pressure on Luxury Brands

    China’s 20 per cent tax crackdown on wealthy individuals has become the latest headache for luxury brands ahead of third-quarter financial results. Under Beijing’s new rules, affluent citizens who used offshore trusts to shelter assets have until October 22 to declare and pay years of back taxes, threatening spending in a market that generates roughly a fifth of global luxury purchases.

    Shares in LVMH and Birkin bag maker Hermes are both down about 40 per cent this year near multi-year lows, while Gucci owner Kering has fallen 29 per cent. Summer shopping mall data in mainland China pointed to a sharp deceleration in growth, according to Bernstein analysts.

    Tax Deadlines and Retail Liquidity

    The 20 per cent levy is hitting spending by ultra-high-net-worth individuals, a tier that had previously proved more resilient than middle-class consumers affected by China’s prolonged property downturn. Alexis Bonhomme, head of Shanghai-based luxury consultancy Trinity Asia, noted that some shoppers face short-term liquidity constraints before the compliance window closes.

    “Until the deadline to pay the tax, some people may face liquidity issues”, Bonhomme said. “This doesn’t mean they won’t start buying again, but right now, the mood just isn’t there,” he added.

    Quiet Luxury Pulls Ahead in Mall Aisles

    Two industry sources familiar with third-quarter mall trading in mainland China said overall conditions remained weak, although performance varied widely between brands. Smaller “quiet luxury” labels such as cashmere specialist Brunello Cucinelli and LVMH’s Loro Piana are outperforming more conspicuous brands such as Louis Vuitton and Gucci.

    High-end jewellery remains a bright spot. Brands such as Richemont’s Cartier have benefited as wealthy consumers increasingly favour gold and precious materials, which are viewed as offering more enduring value.

    Global Headwinds Compound Asia Weakness

    The slowdown in China comes as luxury demand softens in the United States, the industry’s largest market. US credit card spending on luxury goods tracked by Citi fell for a third consecutive month in September as consumer confidence weakened ahead of midterm elections.

    Luxury houses are also grappling with fallout from the Iran war. Kering has already warned analysts to expect a further contraction at Gucci, prompting brokerages to cut their stock price targets.

    Earlier Strains and Upcoming Earnings

    The $350 billion luxury sector remains mired in a three-year slowdown after pandemic-era demand weakened. In downtown Beijing, Deng Qi, an exporter of ceramic building components, forecast 20 per cent less luxury spending than in previous years, warning that the offshore tax measures undermine confidence across the broader wealthy demographic.

    Investors will receive their first read on the sector when LVMH reports results on Monday, with analysts forecasting quarterly sales of €18.5 billion ($20.7 billion), up 1 per cent from a year earlier. Kering and Hermes report their quarterly performance on October 22.

  • Lotte Signs Blackpink Jennie as Foreign Spending Drives Record Department Store Profits

    Lotte Signs Blackpink Jennie as Foreign Spending Drives Record Department Store Profits

    Lotte Department Store signed Blackpink singer Jennie for a yearlong campaign. The deal follows foreign shoppers pushing international sales past 1 trillion won for the first time.

    The agreement gives South Korea’s largest department store operator its first brand ambassador in seven years. It covers 31 domestic branches and four outlets in Vietnam and Indonesia.

    Promotions launch in October across central transit hubs, including Incheon Airport and Seoul Station. Shinsegae Department Store counters without a formal contract. The rival chain, which operates 13 locations nationwide, features rookie group Allday Project member Annie on the digital screen outside its Myeong-dong flagship through Oct. 18. She is the daughter of Shinsegae Inc. Chair Chung Yoo-kyung.

    Foreign Footfall Rewrites Merchandising Strategies

    Department store operators across East and Southeast Asia spent years phasing out celebrity-driven advertising in favour of direct luxury brand partnerships. Rising tourist traffic reversed that playbook in Seoul. Floor plans evolved from standard retail halls into cultural destinations for international visitors.

    Foreign visitors spent 14.02 trillion won ($10.5 billion) on credit cards across South Korea from January through August. That represents a 48.5 percent increase from a year earlier, according to the Ministry of Culture, Sports and Tourism. Overseas visitors now generate almost 30 percent of total sales at the Myeong-dong flagships of both Lotte and Shinsegae. That share stood at 15 percent in 2024.

    “By combining our ambassador’s global influence with Lotte Department Store’s brand value, we will widen our reach to customers worldwide,” said Lotte Department Store CEO Jung Hyun-seok.

    Flagship Showdowns in Myeong-dong

    Concentrated tourist demand inside central Seoul creates intense pressure on prime retail real estate. Lotte built a dedicated hall for domestic fashion labels that draws most of its volume from inbound travellers. Shinsegae consolidated K-pop merchandise, packaged snacks, and domestic apparel labels onto a single tourist floor.

    Competition extends directly to the street. Shinsegae uses its building-scale outdoor digital media screen to display cultural and pop music content. Lotte plans to counter with an even larger outdoor display panel on its own building facade in December.

    Surging Operating Profits Across Both Chains

    Record quarterly and half-year earnings followed the spending surge. Lotte generated roughly 640 billion won in sales to overseas shoppers during the first half. Shinsegae collected 580 billion won from the same demographic.

    Second-quarter results set new records. Lotte’s department store division reported revenue of 891.2 billion won, lifting operating profit 84 percent to 119.7 billion won. Shinsegae posted store revenue of 738.5 billion won, up 17.5 percent, while operating profit jumped 53.5 percent to 108.8 billion won.

    First-half tallies confirmed the trend. Lotte expanded six-month operating profit by 54.8 percent to 295.9 billion won on revenue of 1.69 trillion won. Shinsegae grew first-half operating profit 39.7 percent to 249.9 billion won as division revenue reached 1.48 trillion won.

    Southeast Asian Footprint and Year-End Targets

    Across Southeast Asia, the celebrity campaign supports a retail footprint of four department stores in Vietnam and Indonesia. Cross-border brand recognition directly affects footfall in those assets. Korean lifestyle and beauty concepts drive the tenant mix at each location.

    Lotte had not used a single advertising model since actress Shin Min-a fronted its promotions in 2017. Its Myeong-dong flagship alone generated approximately 520 billion won of the retailer’s 1 trillion won in foreign sales this year. The chain focuses on maintaining foreign customer volumes into the final quarter.

    Both department store chains turn next to year-end campaigns for the winter travel season, led by the December opening of Lotte’s expanded media wall in Myeong-dong.

  • Dickson Poon Faces £100M Loss Following Sale of Harvey Nichols

    Dickson Poon Faces £100M Loss Following Sale of Harvey Nichols

    Hong Kong retail tycoon Dickson Poon faces a £100 million loss following the sale of luxury department store chain Harvey Nichols to Frasers Group. Frasers acquired the business out of administration in August in a £43 million deal covering six UK stores, the e-commerce operation and international franchise agreements.

    The transaction ended Poon’s multi-decade ownership of the British luxury institution. The retailer fell into administration after sustained operational challenges and mounting trading headwinds eroded cash reserves.

    Breakup of the Regional UK Network

    Frasers Group has begun reorganising the physical store footprint to align with its broader commercial portfolio. Chief executive Michael Murray confirmed plans to rebrand the Leeds and Bristol Harvey Nichols branches under the Flannels banner. Leeds opened in 1996 on Briggate as the chain’s first outlet outside London, while the Bristol site at Cabot Circus launched in 1998.

    Staff at both regional locations received notice of the rebranding proposals in October. The group will maintain Harvey Nichols department stores in London, Edinburgh and Manchester, keeping the historic name on flagship metropolitan assets while converting regional units to its contemporary streetwear and designer format.

    Consolidation Under Frasers Luxury Division

    The acquisition anchors a newly established £1 billion luxury division inside Frasers Group. The unit integrates Harvey Nichols with Flannels and US retailer The Webster, combining prestige department store operations with multi-brand designer retail.

    Frasers has assembled an extensive stable of premium and heritage names through distressed acquisitions. The group’s portfolio includes Savile Row tailor Gieves & Hawkes, lingerie label Agent Provocateur, House of Fraser, Jack Wills and core sporting retailer Sports Direct.

    Shift in Capital Deployment for Asian Luxury Investors

    Poon’s exit highlights the difficult economics facing Asian high-net-worth investors and holding companies that acquired legacy European department stores. High structural overheads, elevated business rates and shifted tourism spending patterns have compressed margins across traditional multi-brand department stores. Luxury consumers increasingly shop directly through mono-brand flagships or digital platforms, bypassing regional department store concessions.

    For regional operators and real estate landlords, the conversion to Flannels signals a shift in tenant mix. Flannels prioritises younger demographic designer apparel and streetwear over traditional departmental concessions. Landlords that relied on Harvey Nichols to anchor regional luxury catchments now face the test of whether younger-skewing multi-brand formats generate equivalent footfall and consumer spending.

    Earlier Restructuring and Franchise Assets

    Harvey Nichols operated under Poon’s control through periods of rapid international franchise expansion across the Middle East and Asia. The brand built outposts in regional hubs while maintaining its core Knightsbridge presence. Persistent trading pressure across the UK retail sector eventually forced the parent entity into administration earlier this summer before Frasers stepped in with the rescue transaction.

    Attention turns to how Frasers handles the existing Flannels flagship in Leeds, situated inside the former Debenhams building only yards from the Harvey Nichols site on Briggate. Landlords and retail partners await formal lease filings detailing the exact conversion timelines for both Leeds and Bristol.

  • Gen Z Collectors Outspend Older Generations with $347,000 Average Art Outlay

    Gen Z Collectors Outspend Older Generations with $347,000 Average Art Outlay

    Wealthy Gen Z collectors spent an average of $347,000 on fine art in 2025. That outlay topped every older demographic group by more than two to one.

    Spending rose 19 per cent from the previous year. That finding comes from survey data published by Art Basel and UBS, covering 3,100 high-net-worth individuals across 10 major markets.

    Baby Boomers aged 62 to 80 ranked second in spending, followed by Millennials aged 30 to 45. Gen X respondents aged 46 to 61 posted the lowest average outlay at $79,000 per collector. That is less than a quarter of the Gen Z total.

    Family Wealth Powers Million-Dollar Acquisitions

    Inherited capital among younger ultra-wealthy buyers drove the surge, rather than retail enthusiasm. Gen Z buyers made up 9 per cent of the 3,100 collectors polled. Yet they represented nearly half of all buyers who bought artworks priced above $1 million during 2025 and the first half of 2026.

    During the first half of 2026, 13 per cent of Gen Z respondents spent more than $1 million on fine art, against 3 per cent across the wider sample. About 37 per cent of Gen Z respondents reported their wealth came primarily from family sources. Another 40 per cent cited family influence as their entry point into collecting.

    Across the full sample, average fine-art spending rose 13 per cent year on year in 2025 to reach $124,265. Gen Z spending in the first six months of 2026 alone beat their full-year 2025 average.

    Traditional Mediums Retain Buyer Loyalty

    Purchases remain concentrated in classic categories rather than digital assets or non-traditional formats. Painting and sculpture dominate transaction volumes across every surveyed generation.

    “Some aesthetic preferences remain more consistent across generations than is often assumed,” Paul Donovan, chief economist at UBS Global Wealth Management, said in the report.

    Buyer motivations also diverge from institutional tastemakers. Nearly half of all surveyed buyers said an artwork’s rarity and uniqueness carried more weight in purchase decisions than critical acclaim from curators or commercial dealers.

    Digital Discovery and Direct Studio Sourcing

    Younger collectors are altering transactions across primary and secondary channels. Commercial galleries face changing habits as buyers bypass intermediaries to purchase directly from artist studios or independent platforms.

    Artificial intelligence tools are gaining traction in collector research. The proportion of collectors using AI to research potential art purchases rose from 4 per cent in 2024 to 22 per cent in 2026.

    Gallery operators and luxury auction houses must adapt digital-native marketing to clients who favor traditional tastes. Family offices managing intergenerational transfers are directing capital toward blue-chip physical inventory rather than speculative emerging categories.

    Intergenerational Wealth Transfer Shapes Market Baseline

    Survey qualification required respondents to hold at least $1 million in investable liquid assets, excluding primary residences and privately held business equity. This baseline separates the cohort from general retail consumers and highlights the mechanics of wealth preservation.

    Earlier surveys conducted after 2020 pointed to falling transaction counts among older institutional patrons. The latest data shows younger heirs are buying higher-value individual lots, maintaining dollar volume across top-tier international sales.

    Auction houses and private dealing desks now look to late-2026 auction totals to see if direct artist purchases continue to eat into dealer commission revenue.

  • Armani Group Names Stephanie Wen CEO for Greater China

    Armani Group Names Stephanie Wen CEO for Greater China

    Armani Group appointed Stephanie Wen as chief executive officer for Greater China on October 1. The appointment places a veteran apparel distributor in charge of operations across mainland China and Taiwan.

    In her new role, Wen oversees regional business development, retail networks, marketing agencies and commercial partnerships for the Milan-based fashion house.

    Distribution Background at Carnival Industrial

    Wen previously served as vice general manager of Carnival Industrial Corporation, an apparel manufacturer under Taiwan’s Yulon Group. The company acts as a distribution partner for Giorgio Armani. She concurrently ran Carnival’s Giorgio Armani division, managing wholesale and retail distribution for the Italian label before taking direct regional leadership for the parent group.

    That operational background gives Armani direct experience in Greater China garment distribution, local department store concessions, and joint-venture retail management.

    Navigating Greater China Retail Channels

    Western luxury fashion groups continue adjusting their executive structures in Greater China. They face divergent market conditions between top-tier mainland cities and secondary retail hubs. Direct operational control over local distributors allows luxury houses to align boutique rollouts, pricing strategies and inventory allocations without intermediary delays.

    Hiring directly from a local distribution partner lets Armani maintain continuity in partner relationships. It also consolidates oversight under group headquarters in Milan.

    Expanding Brand Presence

    Founded in Milan in 1975, Armani Group operates a brand portfolio spanning Giorgio Armani, Emporio Armani, and Armani Exchange across major Asian metropolitan centres. Unifying mainland China and Taiwan under one leader coordinates retail expansion across premier department stores, duty-free locations, and standalone flagships.

    Wen will now execute store performance reviews and strengthen partner networks across both territories through the final quarter of the year.

  • Indonesia Leads Global Surge in Ultra-Wealthy Population Through 2031

    Indonesia Leads Global Surge in Ultra-Wealthy Population Through 2031

    Indonesia will post the fastest growth in ultra-high-net-worth individuals worldwide over the five years to 2031, expanding its wealthiest cohort by 81.7 percent.

    Data from Knight Frank’s The Wealth Report 2026 shows the country’s population of individuals with a net worth exceeding $30 million will jump from 3,833 in 2026 to 6,966 by 2031.

    Southeast Asia claims four of the top ten spots globally for ultra-wealth expansion. Vietnam ranks fourth worldwide with a projected 59 percent increase, lifting its ultra-rich count from 1,233 individuals in 2026. The Philippines takes ninth place with 48.9 percent growth from a base of 1,910 wealthy residents, while Singapore ranks tenth with an expected 46.4 percent gain.

    Shifting Wealth Concentrations Across the Region

    Singapore maintains the largest absolute pool of wealth in Southeast Asia, housing 7,171 ultra-high-net-worth individuals in 2026. Indonesia holds second place, followed by Thailand with 2,853 individuals, the Philippines with 1,910, Malaysia with 1,566, and Vietnam with 1,233.

    Together, the combined ultra-wealthy population across Indonesia, Vietnam, the Philippines, Singapore, and Thailand will climb from more than 14,000 people in 2026 to over 22,000 by 2031. That pace adds an average of more than four individuals to the $30 million wealth bracket every single day.

    Saudi Arabia and Poland rank second and third globally, each registering projected growth of roughly 63 percent. Australia ranks fifth at 58.5 percent, Sweden sixth at 55.3 percent, the United States seventh at 54.1 percent, and Romania eighth at 49.5 percent.

    Commodities and Digital Platforms Drive Jakarta Liquidity

    Indonesia’s domestic market of more than 280 million consumers provides substantial scale for homegrown commercial enterprises. Rapid expansion across commodity extraction, logistics, and digital financial platforms continues to convert private equity and equity holdings into personal liquidity for founding families.

    For luxury retailers, private wealth managers, and premium real estate developers, this structural shift alters where high-ticket capital originates. Luxury operators have traditionally concentrated flagship retail footprint and private client salons in Singapore. As wealth pools deepen in Jakarta, Manila, and Ho Chi Minh City, commercial landlords in those secondary capitals will capture direct allocations of luxury retail square footage rather than relying solely on outbound tourist spending.

    The operational risk sits in domestic wealth preservation and regulatory shifts. High headline percentage growth rates partly reflect lower starting baselines in developing markets, meaning total addressable purchasing power still trails mature western hubs. Capital controls, local currency volatility, and uneven infrastructure also determine how much of that accumulated balance sheet stays within domestic retail and property assets.

    Billionaire Tallies Tell a Divergent Story

    Billionaire creation patterns diverge from broader wealth expansion. Indonesia does not place in the global top ten for forecast billionaire growth over the five-year forecast window.

    The Philippines leads regional billionaire momentum instead, with its billionaire roster projected to grow 63 percent to 26 individuals by 2031, ranking eighth fastest worldwide. Thailand registers a more modest trajectory, with its ultra-rich population expected to grow 26 percent through 2031 to rank 17th globally.

    Tracking these shifts shows how Southeast Asian manufacturing gains, supply chain relocations, and digital commerce adoption have steadily lifted private balance sheets across developing Asian economies over the past decade.

    Luxury brands and commercial property operators will monitor whether Indonesia reaches its interim milestones toward 6,966 ultra-rich residents as new wealth data releases throughout 2027.

  • Moncler Expands Re/Icons Archive Range into Full Ready-to-Wear Line

    Moncler Expands Re/Icons Archive Range into Full Ready-to-Wear Line

    Moncler expanded its archival Re/Icons project into a full ready-to-wear line priced between 990 and 2,400 euros. An exclusive prelaunch takes place at Tokyo’s Isetan department store.

    The collection introduces complete apparel looks alongside four remastered jacket silhouettes. It widens the scope of a technical heritage program that previously centered on standalone outerwear releases.

    Previews begin during Paris Fashion Week inside Il Rifugio, a renovated private suite within the label’s Champs-Elysees flagship. Paris hosts an initial prelaunch on Thursday. Next comes the dedicated pop-up at Isetan in Tokyo, followed by a prelaunch at the Fifth Avenue flagship in New York on October 14. Global distribution opens October 15 across select Moncler boutiques and the brand’s e-commerce platform.

    Archival silhouettes and ready-to-wear expansion

    Four core models anchor the lineup: the Karakorum, the Verone, the Himalaya and the Tibb gilet. Beyond outerwear, the capsule incorporates windbreakers, T-shirts, pants and skirts. Accessories round out the range with beanies, balaclavas, silk-twill foulards, and titanium and leather sunglasses modeled after vintage climbing goggles.

    Each jacket uses a camaieu dyeing method and carries an interior label reproducing Vittorio Sella’s June 1909 photograph of K2. Pocket attachments feature metal badges styled after vintage alpine souvenir pins. The brand is also issuing an Alpine Diary, blending fictional 1950s expedition journal entries with historical mountain photography set against the 2026 collection imagery.

    The 1954 Karakorum jacket returns in 10-denier micro ripstop. Originally, it was built from raw down-filled cotton for Achille Compagnoni and Lino Lacedelli during the first ascent of K2. The cut includes double snap fastenings, a detachable hood, internal carry straps and a redesigned chest badge. Men’s colorways comprise black, red and petrol-blue, while women’s options come in black and purple.

    Urban iterations and Paninari styling

    Urban references shape the Verone, an 1980s silhouette associated with the Paninari subculture in Milan. The reissue uses lightweight matte micro cotton with a stowable hood and buttoned storm flap. It comes in pastel pink, lilac and black for women, alongside navy, gray and black for men.

    Lionel Terray’s 1950s Makalu expedition gear inspired the Himalaya jacket before its 2009 commercial debut and subsequent evolution into the Maya jacket. Moncler built the new version from a matte cotton-nylon blend with signature sleeve pocketing, offered in off-white, brown, navy, black and pastel pink. Meanwhile, the sleeveless Tibb vest arrives in reversible recycled matte Longue Saison nylon or wool gabardine with boudin quilting across four shades per gender line.

    Asian wholesale and department store positioning

    Securing a dedicated prelaunch floor at Isetan Shinjuku gives Moncler direct access to Tokyo’s high-spending luxury clientele ahead of general distribution. Japanese department stores serve as key testing grounds for European luxury houses validating high-ticket technical capsules before wider Asian rollouts. The Isetan pop-up connects the technical archival narrative directly with Japanese shoppers who prioritize heritage craftsmanship and expedition provenance.

    Category expansion carries risk in ready-to-wear execution. Lightweight layers face competition from established luxury fashion houses that already dominate seasonal wardrobe spend. Moncler relies on its technical credibility and distinct alpine aesthetic to justify prices reaching 2,400 euros, testing whether outerwear loyalists will buy skirts, pants and tailored separates under the same label.

    Heritage project trajectory and cinema tie-in

    Moncler initiated the Re/Icons series in 2023 to commercialize historical milestones from its founding in Monestier-de-Clermont in 1952. Executive chairman Remo Ruffini described the initiative at its inception as an effort that “represents a unique opportunity to celebrate some of our timeless and most iconic styles by remastering, reimagining and reintroducing them to current and new generations of Moncler lovers.”

    Cinema provides the next platform through Bianco, a feature film directed by Daniele Vicari. Actor Alessandro Borghi portrays climber Walter Bonatti in the recreated Karakorum jacket. Be Water Film produced the movie alongside Rai Cinema, The Project Film Club and Tarantula. It heads to Italian cinemas in 2027 through 01 Distribution, while Rai Cinema International Distribution manages global rights ahead of Moncler’s subsequent worldwide retail delivery deadlines.

  • LVMH and Prada Shares Trade at Deep Discount to Zara and H&M

    LVMH and Prada Shares Trade at Deep Discount to Zara and H&M

    Shares in luxury powerhouses LVMH and Prada traded at an unusually deep valuation discount to fast-fashion retailers Zara and H&M in October 2026. Investors hesitated to buy the dip amid growing concern that the luxury sector’s strongest growth period has passed.

    The valuation gap marks a sharp reversal after trends that made high-end luxury groups a standout investment over the past 20 years began fading. Top fashion houses are increasingly exposed as demand cools across broader consumer segments, leaving them reliant on a narrow group of ultrawealthy spenders.

    Valuation gap widens

    Stock multiples for top luxury names historically commanded a heavy premium over mass apparel operators. That pricing power built on high gross margins, tight inventory control, and reliable price increases on leather goods and apparel.

    Equity markets have flipped that relationship. Fast-fashion groups Inditex, which owns Zara, and H&M now trade at higher comparative multiples than both Paris-listed LVMH and Hong Kong-listed Prada.

    Fast fashion takes market momentum

    Mass-market retailers have defended turnover by turning inventory quickly and adjusting collections within weeks. Zara and H&M adjusted prices more conservatively while capturing spend from middle-income households managing tighter budgets.

    Luxury brands took the opposite path over the last four years. Aggressive price increases on core handbags and accessories pushed aspirational shoppers out of the market entirely.

    Squeeze on aspirational spenders

    Department stores and flagship retail malls across Asia report softer footfall in premium corridors as middle-class consumers cut discretionary purchases. The pullback leaves luxury groups reliant on top-tier VIP clients who buy haute couture and high jewelry.

    That customer base is too narrow to sustain the double-digit revenue growth rates equity investors came to expect. Mall operators in major retail hubs are already reassessing space allocations as mass-market and sports labels post steadier sales densities.

    Earnings reports to watch

    The downturn follows consecutive years of record revenues across European luxury houses between 2021 and 2023. Those gains unraveled as post-lockdown shopping splurges faded and mainland consumer sentiment turned cautious.

    Market watchers are tracking upcoming third-quarter revenue updates from LVMH and quarterly trading figures from Prada to gauge whether holiday order books show any signs of stabilization.