Tag: Retailers

  • V-MORE Enters Thailand’s E-Commerce Market With More Than 500 Marketplace Platforms and Merchants

    V-MORE Enters Thailand’s E-Commerce Market With More Than 500 Marketplace Platforms and Merchants

     V-MORE, Asia’s leading e-commerce supply chain management platform, has announced its plans to expand into Thailand. Over the pasts 12 months, the fast-growing one-stop e-commerce platform which has already garnered 500,000 users in the region.  V-MORE aims to recruit new Thai e-commerce merchants as part of its expansion strategy and has rolled out onboarding programs for new merchants and users.

    “We are pursuing a plan of expansion and hope to achieve revenue growth through mass adoption by users and merchants in our ecosystem. Thailand is fast becoming the leading e-commerce market, and we seek to increase our user and merchant base through user incentive programs, brand awareness and marketing programs,” said Sir Eldee Tang, CEO and Founder of Noble Vici Group.

    V-MORE is a one-stop marketplace for high quality products which are value for money. Its unique shop, save and earn program has gained the trust of many online shoppers. Through V-MORE, consumers can shop and be rewarded at over 500 marketplace and shopping sites including leading online brands, hotel and flight booking sites, technology as well as food and beverages merchants. Thai merchants can participate in its e-commerce program and increase their exports to other countries in Asia and beyond.

    According to research, there are more than 57 million internet users in Thailand who are well-versed with digital technologies, mobile and e-commerce. The market is valued at USD 3.5 billion and is expected to generate revenue growth rate of 13.2% annually, reaching USD 5.8 billion by 2022.

    “We look forward to new local merchants to come on board our platform and welcome sellers and buyers to experience the online marketplace for the first time,” Eldee added.

  • RFG totters making its way

    RFG totters making its way

    Retail Food Group remains in danger of collapse as it tests the nerve of its financiers. The multi-brand franchisor has racked up losses of more than half a billion dollars in the past 18 months; its market capitalisation has fallen below $50 million, with its share price dropping to 25¢ last week on the Australian Securities Exchange.

    Directors have been attempting to sell assets in a bid to reduce debt to satisfy bankers and ensure the company can continue to trade.

    The problem is that most of the assets have little value in real terms and, in some instances, carry significant liabilities in respect of store lease commitments, exit costs on unprofitable and unfranchised stores and prospective legal action by disgruntled franchisees.

    The results for the first half of the 2019 financial year would indicate that the entire company is struggling to survive and is facing imminent administration if it cannot quickly conclude a significant asset sale.

    Debt covenants tested

    A waiver of debt covenants by lenders NAB and Westpac expired on December 31 – and are due to be tested by March 31. Without clear indications of the viability of the company on an ongoing basis, lenders are unlikely to hold their nerve.

    Directors of the company have been unable to conclude a deal on any asset sales despite the company reporting the Donut King and QSR Division as discontinued operations in its FY19 first-half results released last week.

    Directors advised investors that negotiations were ongoing but no formal binding agreement had been achieved with a proposed buyer.

  • Retail brand Penshoppe signs deal with Kendall Jenner

    Retail brand Penshoppe signs deal with Kendall Jenner

    Global fashion retail brand Penshoppe has unveiled the latest addition to its roster of international ambassadors – 23-year-old world’s highest-paid supermodel and one of the most followed celebrities on social media, Kendall Jenner.

    The model initially appeared on Penshoppe’s DenimLab campaign in 2015, and is now headlining the brand’s Spring Summer 2019 Campaign with Zayn Malik, Paris Jackson, Nam Joo Hyuk and Sandara Park.

    “As we move from strength to strength, we couldn’t think of a better addition to our growing list of global ambassadors”, said Golden ABC’s VP for brand management Jeff Bascon. “It’s good to have you back, Kendall!”
    Penshoppe has more than 400 locations across Bahrain, Cambodia, Indonesia, Saudi Arabia, Myanmar, Thailand, Vietnam and the Philippines. The brand is available online in Singapore, Malaysia, Hong Kong, Taiwan and Indonesia.

  • Retail slow in January despite Luxury growth

    Retail slow in January despite Luxury growth

    While several retailers have talked about conditions improving since a somewhat dismal holiday trading period, the Australian Bureau of Statistics have released a more muted view of month of January, with retail sales having improved by 0.1 per cent.

    This increase followed a fall of 0.4 per cent over December 2018, and a 0.5 per cent increase in November off the back of successful Black Friday and Cyber Monday sales events.

    “While January hasn’t proved to be a ground-breaking month by any stretch, on the plus side it does indicate that retail is slowly picking itself up and heading in the right direction,” National Retail Association chief executive Dominique Lamb said.

    Department store spending saw a 2.1 per cent decline over the month, while spending on clothing, footwear and personal accessories dipped 0.3 per cent.

    Food retailing and cafes, restaurants and takeaway services saw spending 0.3 per cent higher than the month prior, while ‘other retailing’, which brings together several industries such as pharmaceuticals, books and recreational goods, saw a jump of 0.7 per cent.

    The increase in cafe spending could be indicative of consumers beginning to feel more comfortable spending on ‘little luxuries’, according to Australian Retailers Association executive director Russell Zimmerman.

    “We hope this trend will continue to increase and spill into other retail categories across the retail sector,” Zimmerman said.

    The NRA’s Lamb went on to point to the upcoming Federal Budget, stating the importance that the Government puts a focus on encouraging consumer spending.

    “Measures such as tax cuts, infrastructure spending and initiatives that ease the burden on small businesses can all help improve the economy and assist retail in getting out of this sluggish phase it’s experiencing,” Lamb said.

  • Thailand franchise market ready for further growth

    Thailand franchise market ready for further growth

    Thailand franchise consultancy Gnosis Co expects a healthy market for franchises in the country.

    Gnosis MD Sethaphong Phadungpisuth said more than 50 chains from both local and international brands are exploring the market this year following measures to ease regulations on the part of the Business Development Department.

    “The Thailand franchise market will become more active this year. We expect the overall number of new franchise brands both from abroad and the domestic market that will open their franchise in Thailand this year to increase by 10 per cent to about 630 brands”, he said.

    According to Gnosis, some brands have chosen Thailand as a springboard to other Asean countries, in particular Myanmar and Laos.

    Among those diverse brands set to start operations in Thailand this year include Taco Bell, The Edge Learning Centre, and Singaporean hygiene and disinfection products firm Sureclean. Additionally the number of Taiwanese milk tea chains continues to increase in the territory.

    Franchise business in Thailand is estimated to be valued at THB250-300 billion (US$7.84 billion).

  • Mixed results for Giordano International

    Mixed results for Giordano International

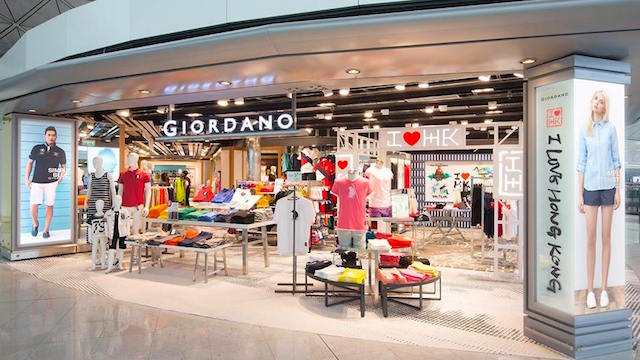
    Hong Kong casual-apparel brand Giordano International has reported a small increase in sales for last year – and a dip in profit. Group-wide sales reached HK$5.509 billion last year, up 1.8 per cent, with same-store sales down a marginal 0.1 per cent. Profit attributable to shareholders fell 4 per cent to $480 million.

    In a stock exchange filing, Giordano International said sales from physical stores achieved a 1.7 per cent growth rate, while online sales – through its own sites and third-party platforms, grew by 1.3 per cent. Wholesale sales to its franchisees grew by 2.6 per cent.

    By category, its best-performing sectors were childrenswear and womenswear, where sales for both rose by 6.9 per cent.

    By geographical market, Giordano International delivered a mixture of results:

    Mainland China: Business was affected by the Sino-US trade dispute and stock-market volatility, which negatively impacted on domestic retail sales. Comp-store sales slipped by 0.9 per cent.

    Hong Kong and Macau: “Well-executed marketing programs, smart promotional activities and stringent cost control all helped achieve double-digit growth amidst complex macroeconomic conditions,” the company reported. “This market experienced a difficult retail landscape caused by an economic slowdown since the third quarter of the year. Severe typhoons and an abnormally warm winter also adversely affected its sales.”

    Taiwan: Sales here rebounded to allow an operating profit increase of 34.9 per cent in the first half of last year, however the full-year change was a mere 2 per cent, due to the uncertainty created by the Sino-US trade dispute.

    Vietnam: Giordano bought out its third-party retail operation in Vietnam and after improved sales and cost controls turned the business around. The market has grown to account for 5.6 per cent of Giordano international’s regional sales and operating profit rose.

    Thailand: Operating profit from Thailand grew by 11.1 per cent, thanks to stable sales growth and an improvement in gross-profit margin.

    Indonesia: In Southeast Asia, Indonesia stood out with a comp-store sales growth of 7 per cent for both Giordano and non-Giordano brands, and operating profit increased by 16 per cent.

    Singapore: Operating profit decreased by 6 per cent as the business was adversely affected by an overall stagnant economy and lower tourist traffic.

    Middle East: With consumers adapting to the newly introduced Value-Added Tax and changes in economic policies, comp-store sales fell by 7.3 per cent in the first quarter of last year. However, in the early weeks of this year, the company saw growth in comp-store sales of 4 per cent, prompting management to conclude that consumers have now adjusted to the tax changes and the retail industry there has stabilised.

    South Korea:  Net profit here increased by 6.7 per cent, attributable to better cost control, closure of non-performing stores and enhanced gross margin. Wholesale sales to South Korea increased by 10.5 per cent.

  • Abercrombie & Fitch sales continue to climb

    Abercrombie & Fitch sales continue to climb

    Abercrombie & Fitch sales rose for the second consecutive year as its restructure and new store format begins to pay off. Comparable sales rose by 3 per cent in the year to February 2, to US$3.6 billion and operating income, after excluding extraordinary items, was $138.6 million compared to $100.8 million last year. However fourth-quarter sales fell by 3 per cent.

    CEO Fran Horowitz said the fashion retailer achieved an improvement in gross profit and reduced operating expenses, resulting in a 77-per-cent improvement in net income.

    “We continue to keep the customer at the centre of everything we do and are excited about the future of our brands. Our transformation initiatives are gaining traction and keeping us on track to deliver our previously disclosed fiscal 2020 targets.”

    Neil Saunders, MD of GlobalData Retail, said while the sales decline during the fourth quarter looks poor on the surface, the dip is a function of a calendar shift and a shorter trading period compared to last year.

    “The comparable Abercrombie & Fitch sales figure, which strips out these negative influences, provides a more balanced assessment of performance and here we believe A&F continues to deliver good growth. The comparable growth rate of 3 per cent is particularly impressive when set against last year’s stellar 9 per cent uplift.”

    He said there was now a clearly evident divergence between the performance of the Abercrombie and Hollister brands. The former posted a 2 per cent decline in comparables with the latter recording an impressive 6 per cent uplift.

    “In our view, Hollister is a brand that is strongly connected to its core customer base, both through impressive marketing and an assortment that is attuned to their needs and tastes. Our own tracking shows that the brand has strong traction and is attracting and converting a core group of shoppers on a regular basis at the same time as adding some new shoppers into the mix. Provided Hollister remains on trend with its range – and we see no reason why this should not be the case – we believe it should continue to perform well as the company moves into its new fiscal year.”

    Saunders said that while Abercrombie’s performance was a little soft this time around, the brand was up against tougher prior year figures.

    “Nevertheless there has clearly been a loss of momentum. Our data show that affinity to the brand, although much improved, is a more tenuous than Hollister. This means that Abercrombie was more exposed to the loss of consumer momentum in the general economy after Thanksgiving and Black Friday.”

    But he said the brand continues to show good potential and there were a number of fashion wins over the period, including good traction in outerwear.

    “Despite the slowdown we remain confident that Abercrombie is on the right track and can improve its numbers as it fine-tunes both marketing and merchandising.”

  • Japan studies regular mandatory closings in the Retail Industry

    Japan studies regular mandatory closings in the Retail Industry

    Large-scale specialty stores such as Daiso and Ikea may be subject to mandatory closings every two weeks as the South Korean government studies the validity of such a regulation.

    Research on the appropriateness of the regulation on large-scale specialty stores will start this month, says the Korea Small Business Institute. It will examine whether the big retailers are hurting small shops, and whether the regular closures are necessary. Requested by the Ministry of SMEs and Startups, the study will determine if the regulation is necessary.

    The restriction on such large-scale specialty stores has become the thorniest issue in the retail industry. Large retail outlets such as E-mart, Home Plus and Lotte Mart are subject to restrictions on working hours following a revision of the Distribution Industry Development Act in 2012, aimed at protecting small shops. Local governments adopted ordinances based on the Act, forcing large retail outlets to close on the second and fourth Sunday of each month.

    However, critics say it is unfair as only retail outlets are subject to the regulation while shopping malls such as Shinsegae Group’s Starfield and specialty shops like Ikea were exempted.

  • Myanmar allows full foreign ownership in Retail Business

    Myanmar allows full foreign ownership in Retail Business

    Foreign companies are now allowed to invest in Myanmar’s retailers and wholesalers, including holding 100% stakes, as the country makes efforts to lift foreign investment amid the Rohingya refugee crisis.

    The Ministry of Commerce announced the change on Friday, explaining that it wants to increase competition in the sectors and promote price stability and technology transfers. The new rule took effect on Wednesday.

    But restrictions still apply. Foreign companies must invest at least $700,000 to take an up to an 80% stake in retailers, and $3 million for anything more. They cannot own minimarkets and convenience stores with floor spaces of 929 sq. meters or less. For wholesalers, the minimums are set at $2 million for up to an 80% stake and $5 million for more.

    The ministry is also letting foreign companies themselves bring their products into Myanmar and sell them instead of going through local importers as in the past. This could encourage automakers and appliance manufacturers to make further inroads here.

    Foreign companies could technically take stakes in Myanmar retailers and wholesalers before if they received the ministry’s approval. But almost none got the green light. Japanese retailer Aeon, one of the handful that did, began operating supermarkets with a local partner in 2016.

    Emerging economies often restrict foreign investment to protect homegrown retailers and wholesalers. It is unusual for a country like Myanmar, with per capita gross domestic product of only $1,200 or so in 2016, to relax the rules so much.

    But de facto civilian leader Aung San Suu Kyi has come under fire for delays in key economic reforms. And human rights abuses against the Rohingya Muslim minority, hundreds of thousands of whom have fled to neighboring Bangladesh, are making American and European businesses uneasy about operating in Myanmar.

    The country approved about $5.7 billion of foreign investment in the 12 months ended March, down for a second straight year. A further decrease could throw a wrench into a development strategy heavily reliant on foreign money.

  • Global Brands expects massive loss this year

    Global Brands expects massive loss this year

    A big swing to a loss is expected by apparel group Global Brands Group Holding for its latest 12 months, to the end of March.

    A preliminary assessment of its accounts indicates a net loss attributable to shareholders of between US$70 million and $75 million.

    This compares to a net profit attributable to shareholders of about $90 million for the previous 12 months.

    Global Brands says the expected loss is primarily the result of one-off impairment charges from the write-off of a receivable arising from a loan made by the company, as well as impairment charges on various intangible assets. Also, a major licence expired during the year. Exceeding $100 million, the impairment charges and receivable write-off were non-cash adjustments.

    The company expects to release its annual results late next month.

  • Hong Kong retail rents about to rise again

    Hong Kong retail rents about to rise again

    Hong Kong retail rents will recover more quickly in Kowloon than on Hong Kong Island according to projections by Colliers analyst Melanie Kotschenreuther.

    Kotschenreuther predicts high-street Kowloon retail rents will rise 5 per cent in Mong Kok this year and 3 per cent in Tsim Sha Tsui, while across the harbour, high-street rents will rise by 2 per cent in both Causeway Bay and Central.

    “Rising retail sales and robust demand for prime locations should contribute to a slight recovery of overall high-street rents this year,” she writes in Collier’s First Quarter Hong Kong Retail analysis.

    “Second- and third-tier high-streets will likely remain under pressure in the first half year.” Next year, however, Colliers expects overall high-street rents to rise by 3 to 5 per cent.

    Kotschenreuther says the decline in high-street retail rents in major districts continued to slow, with average rents edging down 0.3 per cent quarter-on-quarter in the first three months of this year.

    “While some first-tier high-street retail rents, except in Central, have started to regain momentum due to robust demand for prime spots, rents outside first-tier high-streets in popular shopping areas have remained soft. Mong Kok, led by further rental improvements on first-tier Sai Yeung Choi Street South, could continue its positive direction, with overall high-street rents growing 0.9 per cent quarter-on-quarter. In contrast, overall high-street retail rents in Central dropped by another 1.4 per cent quarter-on-quarter in the first three months of this year as rental adjustments, particularly on second and third-tier high streets, continue.”

    She says one of the reasons for this is the large size shop configurations common within the area.

    Malls recovering

    Territory-wide, improved market conditions and rapidly recovering retail sales (up by 15.7 per cent during the first two months of this year) combined with proactive strategies by shopping centre owners will help drive further improvements in mall rents in the year ahead.

    “Malls are being transformed into lifestyle hubs, driven by new demand for excitement. We expect continuing tenant-mix refreshments and extended new dining experiences, paired with a comprehensive entertainment program. Mall operators are stepping up digital customer engagement and launching mobile apps to attract new visitors.”

    She says the financial results of operators of prime malls in major retail districts show a positive development of their tenant sales last year. Wharf’s flagship mall Harbour City in Tsim Sha Tsui and Champion’s Langham Place Mall located in Mong Kok announced year-on-year growth of 9.1 percent and 5.3 per cent, respectively – above Hong Kong’s overall retail sales growth last year of 2.2 per cent.

    “The upturn has extended into this year, with shopping malls enjoying a positive start into the Year of the Dog. Sun Hung Kai Properties announced that foot traffic in 12 of its malls was up 13 per cent and retail sales jumped 16 per cent during the Lunar New Year.”

    She says the appetite for international affordable luxury and lifestyle brands, medicines and cosmetics and new F&B concepts is increasing, which will help strengthen rents.

    Meanwhile, Colliers predicts 1.41 million sqft (131,200sqm) of new retail space to come on stream in core retail districts this year and a further 339,700sqft (31,560sqm) next year, led by Victoria Dockside in Tsim Sha Tsui and H Code in Central this year and at 15 Middle Road in Tsim Sha Tsui next year.

  • Online Giants Carve Out Twin Empires in China’s Age of New Retail

    Online Giants Carve Out Twin Empires in China’s Age of New Retail

    The largest e-commerce players in China have rapidly expanded their scope and reach in recent years through a wave of investments and acquisitions. Alibaba owns two of China’s largest e-commerce platforms, Taobao and TMall, as well as an electronic payments system, AliPay. JD has allied with Tencent, which owns WeChat. Now, a report released by Oliver Wyman, a global consulting firm, analyses how the two players’ ubiquity in mobile payments, deep consumer data and sophisticated logistics capabilities has resulted in a new ‘age of empires’ in China’s retail sector where incumbents must quickly adapt to survive.

    The report, Chinese Grocery’s Age of Empires, reveals the e-commerce giants’ efforts to drive further growth by introducing new shopping formats – dubbed O2O, or online-to-offline. These blend online shopping’s convenience and wealth of information with the social experience and physical contact with products that people enjoy in traditional, brick-and-mortar stores. This is most immediately visible in the online grocery sector, where Alibaba and Tencent/JD are actively pursuing three strategic plays that could together increase their share of grocery shopping from around 10 percent today to around 30 percent over the next five years, by when it could be worth approximately 400 billion renminbi in gross merchandise value.

    “With the grocery sector seeing mobile payment penetration of 35%, the two giants are seeking to maximize their critical advantage of dominance in covering 97% of the overall mobile payment market,” says Richard McKenzie, Partner, Greater China at Oliver Wyman. “Now their investments are rapidly building a wider ecosystem of alliances that will make them ubiquitous through online-to-offline tools and features.”

    Over 460 million people in China regularly shop online, where densely populated cities facilitate home delivery. As a result, China has leapfrogged other markets to take the lead with nearly 10 percent of the population shopping for groceries online, compared to just 3 percent in the United States and 6 percent in the United Kingdom, Europe’s highest rate.

    This rapid change favors the two giant empires, which could make it hard for independent retailers to survive outside of them, evidenced by declining like-for-like sales and margins among China’s traditional supermarkets and convenience stores over the past few years. However, they may yet survive in some form with help from the online giants themselves, leveraging the empires’ logistics networks, rapid delivery services and new software solutions.

    Both empires are building their O2O power through three plays, each of which blends their online capabilities with offline stores in new ways:

    1. Experimentation with own retail formats

    Unlike supermarkets elsewhere that offer online shopping in parallel with a traditional in-store experience, China’s players integrate elements of the two. For example, Alibaba’s Hema stores offer smartphone payment and home delivery within 30 minutes. . Though expensive to set up and with high initial running costs, these stores are only marginally loss making. With further maturity and ramp up, breaking even is within reach. Oliver Wyman believes there is potential for at least 1,000 stores in major cities with total revenues of RMB 200 billion.

    1. Strategic Partnership with Big Box Retailers

    Big-box retailers have tried and failed to launch their own O2O and online shopping services in the past. Amid pressure from the online giants, a flurry of partnerships has seen large retailers aligning themselves with the two tech empires. These show early signs of success as parties combine their different strengths. Examples include Alibaba installing Tmall Supermarket shelves in RT-mart branches, with one-hour home delivery for products on these shelves, while Walmart, which has a strategic partnership with JD, is using its O2O unit JD Daojia as the service platform for over 150 stores to attract online traffic.

    1. Reinvention of the traditional world of “mom and pop” shops

    Traditional stores still account for half the sales of fast-moving consumer goods in China, much of them through the more than 7 million family-run stores that dominate retail outside big cities. Since early 2017, JD and Alibaba have been converting these into franchises, helping them optimize their stock through data-based curation tailored to their neighborhoods. Smartphone-based ordering systems and rapid delivery have also revolutionized procurement. Tmall planned to open 10,000 such franchises in 2017, while JD is aiming for one million by 2021. Alibaba and JD are further likely to dominate the growing market for their ordering systems, a market that could be worth up to RMB 400 billion over the next five years.

    Wai-Chan Chan, Partner, Greater China at Oliver Wyman notes, “China has not only surpassed the US in terms of online grocery penetration but also in terms of the pace of innovation and introduction of value-added services. Customers at a Hema store can pay seamlessly via their mobile phone, have fresh crayfish cooked in-store and delivered to their home within 30 minutes. Players in other markets are still some way behind in matching that offering.”

    As O2O becomes the new normal in retail, the two alliances will act as both players and facilitators of these models. While retailers and brands need to plan the best way to function in a retail world dominated by the two tech empires, identifying opportunities for synergy, it will pose a more serious challenge for some incumbents.

    The new environment will pose serious challenges to independent supermarkets and hypermarkets. Survival will require drastic changes, but this is unlikely under their current set-up. Some leading convenience stores should be able to survive outside these empires in the short term, but they too will come under threat in time from the revival of family-run stores under the franchise networks run by the two giants.

    The tech empires will inevitably influence the shape and future of the supermarket and hypermarket industry. It is crucial for incumbents to find ways to partner or co-exist with them if they are to survive and thrive.
  • Zara Debuts Augmented Reality Retail Experience for Limited Time in Select Stores Worldwide

    Zara Debuts Augmented Reality Retail Experience for Limited Time in Select Stores Worldwide

    Zara will unveil an augmented reality experience running for two weeks in select stores worldwide. The innovative concept superimposes state-of-the-art technology on the retail environment, engaging customers both outside and inside the store to shop and to share like never before.

    This made-to-measure augmented reality is enabled on mobile devices via the Zara AR app. The activation plays out at three different sites: store windows, centrally-located podiums, and atop e-commerce boxes. When smartphones are positioned at the graphic signage, models Léa Julian and Fran Summers seemingly come to life as 7 to 12-second sequences in people’s screen displays. Incredibly realistic and proportioned according to each setting, they naturally pose, move around, and even speak while dressed in the SS18 Zara Studio Collection. All of their looks can be purchased instantly through a single touch on the Zara AR app, as well as in store.

    The experience will be highly visible from the street, with store windows appearing completely empty aside from bold signage encouraging people to access the Zara AR app. Downloading is easy: simply connect to the dedicated Wi-Fi network, or else by QR code, via iTunes and Google Play, or through the link on zara.com or the app. In addition to the shopping feature, a social media sharing feature invites people to take and send photos alongside the holograms, establishing a virtual connection that seems remarkably real. To maximize the limited-time experience, different sequences of new looks will be introduced after the first week.

    Zara Augmented Reality is the conception of Paris-based creative director, Ezra Petronio, who developed this high-quality experience and app with HOLOOH, a French company, in addition to research partner, INRIA (the French National Institute for computer science and applied mathematics). The 12 dynamic sequences were captured as holograms in a 170-square-metre studio involving 68 cameras, among the largest recording systems of its kind in the world. Petronio, who is also the co-founder of Self Service magazine, enhanced Issue 47 (September, 2017) with a shop-able augmented reality component.

    With augmented reality finding more and more real-world applications, the Zara experience demonstrates how innovation, inspiration and additive technology can reimagine conventional retail. Engaging in both the store environment and the app simultaneously, shoppers will discover ease of use alongside their sense of awe. Zara’s global reach brings the advanced renderings to a wide and inclusive public. In a sense, this exciting concept could not have been more natural for the retailer: as the dedicated branding makes clear, augmented reality has been within Z-AR-A all along.

  • Daigou retailer to expand into over 150 pharmacies

    Daigou retailer to expand into over 150 pharmacies

    Daigou retailer AuMake has inked a deal with pharmacy network Chemsave which will see its own branded products distributed through a network of 150 pharmacies across the country.

    The announcement, which follows the listed retailer declaring a trading halt earlier this week, will see Aumake’s own-branded health supplement and honey products distributed initially, prior to further expansion.

    Cross promotional marketing will accompany the products, with AuMake’s recently launched live streaming functionality to move into some Chemsave pharmacies.

    The listed retailer hopes that the partnership will bolster its credibility of its private label range, while Chemsave is looking to increase its exposure to the Chinese market.

    “Aumake is thrilled to have formed this strategic partnership with Chemsave, which is a significant milestone,” Aumake executive chairman Keong Chan said of the deal.

    “This partnership with Chemsave allows us to significantly expand the reach of our products across Australia … this is not simply a distribution agreement but a long-term mutually beneficial strategic alliance.”

    Chemsave CEO Michael Dixon concurred, saying that the Chinese market represents a lucrative opportunity for its network.

    “Over the last year we have had the opportunity otm eet with a number of groups with a view to forming a partnership that will allow us to grow our members’ businesses and increase our presence with the important and influential Chinese consumer,” he said.

    The initial terms of the contract are set out across two years, with an option for a further two-year extension if mutually agreed.

    Aumake shares rose 10 per cent to 27 cents in early Wednesday trading.

  • Time to go to into a retail rehab

    Time to go to into a retail rehab

    Why are retailers failing at such an alarming rate?

    The preconditions for any business to be successful are:

    1. Is there a real market need that I understand?
    2. Do I have access to a product or service address that need?
    3. Am I sufficiently equipped (skills, resources, motivation etc) to address this opportunity in a particular way that provides me with a competitive advantage or at least desirable point of difference?

    Points one and and two are usually not the issue because failure is quick – if the business even succeeds in getting off the ground.

    The root cause of many failures can be found in HOW the retailer chooses to play the arbitrage game of tapping into a supply to meet a need.

    That is, entrepreneurs will pick the way in which business is done (proposition delivered) and attempt to build some differentiation around that that can be defended at a profit.

    Timing: First or faster

    An example would be Zara that aims to bring the latest fashion (from the catwalk to the store) in less than six weeks – and if anecdotal reports are to be believed have done so in a matter of days. Or you can be the Concord. Or the movie house that shows all the premiers.

    Leverage:  Add value, minimise cost

    Someone turns raw meat into patties, someone solves the challenge of distributing fuel to every town in every country. Someone is the cheapest, someone figures out how to make things smell better, work differently, last longer or taste better. We are limited only by our imagination and the possibilities of innovation are endless. Of course, any particular innovation can be made redundant in a flash.

    Change: Adapt, transform, improve

    More than simply adding value, there are opportunities for entrepreneurs to transform products completely. Old tires can become road base. Cars can be turned into supercars or transformed into vehicles for mobility impaired people and clothes can be altered to fit. Wind can be turned into electricity.

    Access: Exclusive or convenient

    Businesses also exist on the premise that access to the product/ service is exclusive or particularly convenient. This is a very typical ‘advantage’ that many smaller retailers rely on, and it is most often also their weakness. E.g. to be the only menswear retailer in Yepoon or the only newsagent in the shopping centre, or maybe even the only convenience store on that particular side of that particular city block leverages ‘access’ as the method of arbitrage.

    Most small, product-oriented retailers tend to rely on the ‘access’ angle to create a POD. Retailers tend to be resellers, so innovation is not a primary focus. The only value-add lies in the bulk-breaking activity. These SME retailers are content to be ‘the only shoe shop’ in the mall as their core proposition.

    In the past this has been a legitimate approach to ‘capitalise’ on an opportunity. There has always been limits as to how far people would travel to gain access to a product, so geography-based retail propositions have been viable since forever.

    But, reliance on this particular approach is the reason why the technological shift in the market is causing serious competitive pressure. And being blind to the change that has occurred is the cause of many retail failures.

    Too many retailers rely on the fact that they are ‘the only’ cafe on the strip, the only menswear retailer in a suburb, the only servo on that street.

    If you merely rely on being the only store in a particular geography, the internet obliterated that point of difference because on the internet, geography hardly matters.

    Everything that is for sale is in every customer’s pocket. And the time delay (caused by delivery requirements) are (a) offset by cost saving and (b) becoming shorter and shorter. In metropolitan areas, many e-commerce providers are providing same-day delivery and food delivery businesses do it in a matter of hours.

    This leaves traditional corner-stores an ever-shrinking market comprising mostly of emergency shoppers or impulse buyers.

    That is why Amazon poses such a threat to retailers – suddenly there is a competitor that it is more convenient and cheaper than your shop on your corner, and you can do very little about it.

    The internet has made geography irrelevant – and if THAT has been the basis of your business, so is the business.

    The only appropriate response is to change your execution. You need pick a different propositional dimension to differentiate.

    The problem is obvious. The solution is obvious. But maybe, like any good rehab program, the starting point is to admit the problem.