Tag: semiconductors

  • Hermitage Capital Deploys over 200 Million Dollars in Physical AI Pivot

    Hermitage Capital Deploys over 200 Million Dollars in Physical AI Pivot

    Hong Kong private equity firm Hermitage Capital has deployed more than US$200 million into artificial intelligence and robotics. The capital shift directs money toward hardware and automation.

    This drawdown forms part of a three-year, US$500 million global tech allocation programme announced in 2025. The money comes from the firm’s wider US$1.5 billion asset base.

    Hermitage manages a portfolio split evenly between China and overseas markets, primarily the United States. About 80 per cent of its capital base is held in US dollars, with the remainder in renminbi. Backers include Asian family offices, regional institutions, and investors in Britain and Canada. Sean Xiang Yuqiu, a former JPMorgan Chase banker who founded the firm in 2017, runs the fund across offices in Hong Kong and New York.

    Shifting from foundation models to physical automation

    Capital is shifting away from early bets on large language models to secure positions in robotics, self-improving software and specialized silicon. Recent portfolio additions include US humanoid robot builder 1X, automated research platform Recursive Superintelligence, and Chinese robotics chip designer D-Robotics.

    The investment thesis targets growth beyond pure software layers. “Foundation models were the sector to bet heavily on in 2023 and 2024,” Xiang said. “Physical AI is the sector to bet heavily on now.”

    That repositioning follows sharp price corrections across public robotics equities in mainland China. Unitree Robotics dropped roughly 60 per cent from its peak after listing on Shanghai’s Star Market in August 2026. The drop forced private investors to price unproven manufacturing schedules more carefully.

    Balancing US deals with Chinese hardware supply chains

    Deal origination and research are split between two distinct ecosystems. The New York outpost, initially established to raise Western capital for Chinese deals, now screens and executes direct investments in American technology companies.

    Growth-stage positions range from series B through series D rounds. The fund participated in 13 funding rounds for cross-border payments company Airwallex since 2019, five rounds for autonomous driving developer Horizon Robotics, and three rounds for graphics processor maker MetaX Integrated Circuits.

    Public market liquidity has returned selectively for these bets. Horizon Robotics listed in Hong Kong in October 2024. MetaX completed its initial public offering on Shanghai’s Star Market in December 2025.

    Investor preference shifts toward single-deal vehicles

    Asian family offices backing the firm are demanding direct control over their exposure. Rather than committing blind capital to traditional 10-year fund vehicles, wealth managers increasingly funnel money through single-deal special purpose vehicles with explicit entry pricing and shorter exit schedules.

    Internal risk management rules tightened following setbacks in early 2021 solid-state battery bets, where mass production missed planned milestones. The fund now limits initial check sizes in frontier hardware. Larger follow-on tranches wait until companies deliver working production lines and commercial shipments.

    For technology operators and corporate suppliers across Asia, the deployment shows venture backing has moved past general-purpose chatbots. Private capital now concentrates on robotics components, industrial sensors, and dedicated semiconductor designs that tie directly into domestic manufacturing lines.

    Hong Kong capital markets build fundraising momentum

    Regional financing has grown increasingly active as technology companies tap public markets for capital-intensive artificial intelligence buildouts. Hong Kong equity sales reached a record US$47.5 billion in the third quarter of 2026. That lifted total proceeds in the city above US$92 billion for the year.

    Heavy follow-on share sales, debt instruments and secondary listings drove that volume as Chinese chipmakers and platform groups raced to fund processing capacity and server infrastructure.

    Hermitage plans to deploy the remaining US$300 million of its frontier tech allocation by 2028, tracking milestone completions and production yields across active hardware investments.
  • Samsung Electro-Mechanics Commits $5 Billion to Vietnam and Korean Substrates

    Samsung Electro-Mechanics Commits $5 Billion to Vietnam and Korean Substrates

    Samsung Electro-Mechanics will invest nearly $5 billion by 2028 in semiconductor substrate manufacturing across facilities in South Korea and Vietnam.

    The capital program targets high-end substrates for artificial intelligence servers and high-performance computing systems. Construction is underway in Thai Nguyen province. Samsung is building a dedicated chip testing and component facility there.

    Targeting AI server demand

    This outlay shifts Samsung’s manufacturing footprint in Southeast Asia toward higher-value component fabrication. Substrates connect bare silicon chips to printed circuit boards. Global capacity remains tight because orders for artificial intelligence hardware are surging.

    Data centres and generative model clusters require dense, multi-layer substrate packages that handle high heat and complex routing. Expanding in Vietnam allows the group to split lines between its South Korean base and lower-cost Southeast Asian hubs.

    Vietnam’s push into advanced packaging

    Hardware assemblers across the region are shifting capital away from standard consumer electronics assembly. They are focusing on advanced packaging, testing, and component fabrication. Other conglomerates are running similar programs, including LG with its $1 billion expansion in northern Vietnam.

    Major packaging and substrate plants anchor supply chains for materials suppliers, equipment vendors, and industrial park operators. Thai Nguyen and surrounding northern industrial corridors have evolved from handset assembly clusters into integrated electronics nodes.

    Upgrading from smartphone assembly

    Vietnam built its initial manufacturing base largely on final-stage assembly of consumer devices and mobile handsets. Samsung has long run major smartphone assembly plants in the country. Producing advanced semiconductor substrates represents a technical upgrade for local operations.

    Equipment installation and facility construction will proceed in phases through 2028. The five-year spending plan secures component capacity as enterprise computing demand outpaces consumer electronics.

    Capacity rollout schedule

    Suppliers must still navigate long equipment lead times and heavy utility demands. Substrate processing requires stable electrical grids and continuous cleanroom operations. These requirements will test regional infrastructure.

    Samsung Electro-Mechanics will ramp capacity across both South Korea and Vietnam over the next four years to meet target deployment deadlines by 2028.

  • Taiwan Indicts Ten over Smuggling NT$360 Million in Controlled Chips

    Taiwan Indicts Ten over Smuggling NT$360 Million in Controlled Chips

    Taiwan prosecutors have indicted 10 tech executives for running illicit procurement rings. The rings smuggled NT$360 million ($11.33 million) worth of export-controlled military chips into China and Hong Kong.

    The New Taipei District Prosecutors’ Office filed aggravated fraud charges against the group. Investigators uncovered three separate networks that falsified ties to the island’s premier defense research institute.

    Forged End-User Certificates and Relabeling

    Chen Chien-hsiung, head of ADWELL Technology, ran the largest operation starting in 2017. Chen and his associates imported semiconductors from the United States, the Philippines, Malaysia, and South Korea. They forged end-user declarations from the National Chungshan Institute of Science and Technology. Those documents falsely certified that the components would remain in Taiwan and would not reach entities under US trade restrictions.

    Once shipments arrived in Taiwan, the group repacked the components. Workers swapped original labels for stickers claiming Taiwan manufacture, then routed the shipments to shell companies in Hong Kong and mainland China. That operation generated roughly NT$120 million in illicit gains. Smuggled hardware included more than 10 types of restricted chips manufactured by Texas Instruments and Analog Devices. These were designed for radar units, electronic warfare systems, antenna arrays, ultrasound equipment, and unmanned aerial vehicles.

    A second network led by Hygge Investment head Lai Chin-lan launched in 2019. Lai used identical document falsification methods to ship US military-specification chips to buyers in Hong Kong. That operation brought in NT$130 million in illegal revenue.

    Yuan Tung-tai, a third operator, ran orders through two Taiwan entities, Hui Chung Telecommunications and ZhanKai Technology. Yuan masked product origins on customs declarations. He exported drone flight-control chips to his own Hong Kong entity for onward sale into mainland China, netting more than NT$100 million.

    Sentencing Demands and Legal Gaps

    Prosecutors seek a 10-year prison sentence for Chen, eight years for Yuan, and six years for Lai. They also requested a six-year sentence for Zkey Technology head Chiang Kun-cheng. Terms of one to three years were requested for six other co-defendants across five supplier entities.

    The indictment lands as regional component distributors face scrutiny over grey-market diversion. Manufacturers and franchised distributors formally block unverified buyers in mainland China. Intermediary brokers still exploit Taiwan’s deep inventory pools and porous transit documentation to reroute critical hardware. For electronics supply chain managers, the case signals immediate tightening of know-your-customer audits and inventory traceability across East Asian logistics hubs.

    Grey-market routing through Hong Kong shell entities presents compliance risks for component manufacturers. Major chipmakers rely on automated compliance screening. Physical relabeling in intermediate free-trade zones bypasses those digital customs filters. Until regional authorities enforce physical lot-tracking across cross-border freight transfers, distributor liability will remain a flashpoint in cross-strait trade enforcement.

    Widening Enforcement Across Regional Tech Hubs

    This case parallels recent international crackdowns on parallel semiconductor pipelines running through Southeast Asia into China. In the United States, federal authorities arrested Earthmade Computer chief executive Greg Lui. Lui allegedly routed more than $300 million in restricted Nvidia A100 and H100 graphics servers to Hangzhou through front operations in Malaysia and Singapore. That operation also relied on falsified purchase orders and shell recipient identities to clear customs.

    Taiwanese investigators note that the National Security Act does not currently classify the smuggling of dual-use electronic components and commercial artificial intelligence hardware as a direct breach of state security law. Prosecutors must instead rely on aggravated fraud and commercial forgery statutes to penalize diversion networks after shipments clear.

    Judicial authorities in Taiwan are preparing evidence submissions for the upcoming trial in the New Taipei District Court. Meanwhile, legislative committees are reviewing proposed amendments to extend statutory national security export controls over dual-use electronics.

  • Qualcomm to Pay Huawei in Multi-Year 5G and Artificial Intelligence Patent Agreement

    Qualcomm to Pay Huawei in Multi-Year 5G and Artificial Intelligence Patent Agreement

    Qualcomm has agreed to pay Huawei Technologies for access to its patents in a multi-year cross-licensing deal covering 5G, computing, and artificial intelligence, the Shenzhen company announced on Monday.

    The agreement makes the San Diego chipmaker a net payer to Huawei for the first time, pushing Huawei’s cumulative intellectual property licensing contract value past $6.9 billion.

    Under the terms of the transaction, Qualcomm will license Huawei’s portfolio and buy specific US patents held by the Chinese group across computing, artificial intelligence, and networking hardware. The deal does not include broader commercial tie-ups or component sales, and both companies must clear regulatory reviews in the United States before closing the asset transfers.

    Reversing the Flow of Licensing Cash

    The financial turnaround marks a sharp shift in the mobile supply chain. Huawei paid Qualcomm for patent access as early as 2001, and paid $1.8 billion in back licensing fees to settle an intellectual property dispute with the US group in 2020. Now the balance of standard-essential communications patents and edge computing IP has forced Qualcomm to write checks back to its Chinese competitor.

    For device makers across Asia, the agreement sets a pricing precedent. Hardware brands that design around Qualcomm chipsets have watched royalty rates climb as 5G and on-device AI architectures mature. A formal licensing pact between the two dominant patent holders removes immediate litigation risks for smartphone assemblers, while confirming that access to Chinese cellular and machine-learning IP will carry direct cash costs.

    Expanding Patent Monetisation Beyond China

    Huawei has spent the past five years building a high-margin licensing arm to recoup capital spent on domestic research and development. The business turned net positive on revenue in 2021 after US export restrictions curtailed Huawei’s handset shipments and blocked its access to American semiconductor fabrication tools.

    That monetization drive has yielded more than 260 patent agreements with global tech firms, including Nokia, Samsung, and Amazon, alongside domestic phone brands Oppo, Vivo, and Xiaomi. Huawei signed a similar multi-year cross-licensing agreement with US personal computer maker HP in August, covering foundational Wi-Fi technologies after resolving earlier disputes.

    The Long Legal Road from 2011

    Huawei collected its first external patent royalty payment in 2011 from Motorola. Over the subsequent decade and a half, the company poured capital into 3GPP wireless standards, optical transmission, and proprietary compute silicon, accumulating extensive patent portfolios in Europe, the US, and mainland China.

    US authorities continue to scrutinize cross-border technology transfers, creating friction for any transaction involving Chinese hardware intellectual property. The current agreement remains subject to Washington’s regulatory clearance, which will test whether standard-essential patent sales and cross-licensing can proceed amid ongoing federal export controls and pending legal trials.

  • Taiwan Banks Ration Credit After US$126 Billion Tech Borrowing Spree

    Taiwan Banks Ration Credit After US$126 Billion Tech Borrowing Spree

    Taiwanese banks extended a record NT$4 trillion, or US$126 billion, in loans during the first seven months of the year. The borrowing surge triggered credit rationing across the island.

    Demand for working capital from suppliers serving Nvidia Corp and Microsoft Corp pushed monthly bank lending to an all-time high of NT$1.04 trillion in July. That upended years of low interest rates.

    Local lenders raised corporate borrowing rates between 50 and 90 basis points. Margins for top-tier syndicated corporate facilities climbed 10 to 20 basis points. Mortgage rates reached almost 3 percent across the island, up from 2.2 percent a year earlier. Tech manufacturers need quick cash to secure semiconductor components, build inventory, and expand production lines for orders linked to Taiwan Semiconductor Manufacturing Co and global artificial intelligence infrastructure programs. Many suppliers now demand loan approvals within two months, cutting a third off the standard 90-day evaluation window.

    Surging Working Capital and Squeezed Margins

    Working capital loans to businesses and individual borrowers rose by NT$823 billion in July alone. That expanded nearly eight times faster than residential mortgage growth. The spike pushed the banking system loan-to-deposit ratio to 72.96 percent, near its historical ceiling of 73.07 percent recorded in 2020. Average liquidity coverage ratios fell to 115.52 percent in July. While still above the statutory 100 percent threshold, it was the sharpest four-month liquidity drop in four years.

    Commercial banks are shifting balance sheets toward higher-yielding corporate facilities and short-term consumer credit lines. Unsecured personal loans yield fatter spreads than residential mortgages, which face central bank cooling measures and property transaction curbs. At the same time, retail depositors accelerated withdrawals to buy listed technology shares. That pulled deposits from regional institutions and tightened wholesale funding conditions.

    Credit Shut Out for Builders and Exporters

    Capital reallocation is starving non-technology businesses of routine working credit. Commercial property developers and homebuilders have seen credit pipelines collapse. At one regional lender, weekly approvals for land acquisition and construction financing dropped from 30 deals to zero. Loan officers instructed developers to halt new submissions entirely.

    Traditional industrial exporters, already dealing with tariff headwinds and sluggish consumer goods demand abroad, face tighter credit terms as bank committees favor electronics manufacturing. Taiwan’s economy expanded 13 percent year on year in the second quarter. The expansion is lopsided. Industrial estates housing advanced packaging and chip fabrication run around the clock, while consumer-facing businesses face rising financing hurdles and slowing real estate sales.

    Offshore Syndication Pullback and Regional Spillover

    Liquidity strains are shifting credit dynamics across Southeast Asia, where Taiwanese commercial banks have long served as anchor lenders for syndicated facilities. Taiwanese institutions are scaling back commitments to offshore transactions across Singapore, Hong Kong, and Vietnam. They are pricing themselves out of lower-margin deals or declining syndication tranches to preserve balance-sheet capacity for domestic tech clients. For regional borrowers who relied on Taipei banks for tight margins, financing costs will rise as Japanese and European lenders step in with higher pricing hurdles.

    Structural risk sits directly on balance sheets overconcentrated in single-sector capital expenditure. Banks are directing most of their incremental loan books into hardware suppliers tied to volatile data-center construction schedules. Any pause in hyperscaler procurement cycles will hit banking asset quality swiftly. Traditional suppliers, service firms, and real estate operators unable to access credit today face balance-sheet stress that could outlast the tech cycle.

    Central Bank Coordination and Regulatory Scrutiny

    The credit squeeze follows months of aggressive capital deployment across the hardware supply chain. Micron Technology accelerated its memory production investments in Taiwan to NT$1.6 trillion by mid-year, concentrating high-bandwidth capacity on the island. Total outstanding residential mortgages still climbed 4.6 percent to reach NT$11.95 trillion in August. Bank appetite for long-term mortgage debt has withered in favor of revolving corporate credit.

    Central bank Governor Yang Chin-long has initiated talks with state-backed lenders, commercial institutions, and Chunghwa Post Co, the postal savings system holding the island’s largest pool of retail deposits. The meetings aim to coordinate liquidity relief for small and medium-sized enterprises. The Financial Supervisory Commission confirmed deposit growth currently tracks overall loan creation without immediate systemic failures, but said it will step up surveillance of bank capital allocations.

    Officials from the central bank will hold follow-up consultations with commercial bank treasurers to review quarterly liquidity ratios and evaluate whether non-technology corporate borrowers face structural lending barriers through the final quarter.

  • Dassault Systèmes Targets India’s Semiconductor Sector to Build Workforce

    Dassault Systèmes Targets India’s Semiconductor Sector to Build Workforce

    Dassault Systèmes is expanding operations in India’s semiconductor sector this week, focusing its investment on technical workforce training and specialized engineering capabilities across the country.

    The initiative directs the French group’s 3D design and simulation tools toward local chip designers, packaging units, and planned fabrication facilities.

    Software role in chip manufacturing

    Industrial software plays a critical role in modern semiconductor development, from electronic design automation to cleanroom facility modeling and equipment maintenance simulation. Dassault Systèmes provides virtual twin technology that lets manufacturers simulate production lines, chemical flows, and thermal dynamics before pouring concrete or installing lithography tools.

    By introducing these systems early to engineering institutions and local design houses, the company aims to embed its platforms into the foundational workflow of domestic chip projects. Training engineers on proprietary software creates long-term commercial lock-in across production pipelines.

    Tackling the talent bottleneck

    India offers an enormous pool of front-end chip design talent but faces a sharp deficit in specialized fabrication and operational manufacturing engineers. Cleanrooms require precise execution, where minor procedural errors result in ruined silicon wafers and millions of dollars in yield loss.

    Workforce training initiatives close this operational gap by exposing technicians and graduate engineers to simulated cleanroom environments. Virtual training reduces the cost of onboarding while cutting the time required to bring new facilities up to global yield standards.

    Competing for engineering capacity

    Global design and automation vendors are competing aggressively for technical talent across Bengaluru, Hyderabad, and the National Capital Region. Established software players have already expanded their Indian technical centers to support worldwide product development and customer deployments.

    For Dassault Systèmes, positioning its toolsets directly inside university curricula and specialized trade centers defends its market presence against established semiconductor software rivals. Suppliers and fab operators that standardize on identical simulation platforms can coordinate buildouts faster with fewer engineering mismatches.

    The road to operational fabs

    India has approved multiple commercial semiconductor projects, including assembly and testing units and commercial fabrication plants backed by international joint ventures. The success of these facilities depends directly on having thousands of certified engineers ready on day one.

    Suppliers, construction partners, and software providers now face the task of synchronizing equipment delivery and digital systems with operational launch schedules across targeted industrial corridors.

  • Asian Stocks Dip 0.2% as US 10-Year Treasury Yield Hits 5.306%

    Asian Stocks Dip 0.2% as US 10-Year Treasury Yield Hits 5.306%

    Asian stocks were subdued on Oct 1 as global bonds remained under pressure, with MSCI’s broadest index of Asia-Pacific shares outside Japan falling 0.2 per cent following a brutal September.

    Blockbuster earnings from AI chipmaker Micron failed to lift market sentiment, while stalling US-Iran peace talks kept oil prices elevated and benchmark US 10-year Treasury yields touched 5.306 per cent.

    Regional equity performance was mixed as South Korea’s KOSPI slipped 0.14 per cent, Japan’s Nikkei gained over 1 per cent on chip shares, and European stock futures fell 0.75 per cent.

    Treasury Yields Test Multi-Decade Highs

    Bond markets ended September with heavy losses after rising energy prices revived inflation concerns across major economies. The United States 30-year Treasury yield traded at 5.634 per cent after touching 5.6517 per cent, a level unseen since June 2002.

    Sustained yields above 5 per cent have weighed on equity valuations and corporate balance sheets. United States federal debt has now crossed the $40 trillion mark, leaving investors focused on debt sustainability and rate velocity. Darren Shames, global head of rates sales at Nomura, noted that the speed of the yield move has drawn intense scrutiny from institutional allocators.

    Currency markets reflected the bond pressure. The United States dollar traded near a two-month peak, while the euro held at $1.1334 after sliding 2.5 per cent through September. In Tokyo, the Japanese yen weakened 0.3 per cent to 157.95 per dollar, even after Bank of Japan summary documents showed several board members favored accelerating the pace of domestic interest rate hikes.

    Chip Earnings and Hardware Valuation Pressure

    Strong quarterly figures from memory maker Micron failed to sustain broader technology gains across Asian exchanges. Hardware and consumer electronics supply chains remain caught between record artificial intelligence infrastructure demand and broader macroeconomic drag.

    Official trade figures from Seoul showed South Korea’s total exports jumped 83.5 per cent year-on-year in September to a record $120.94 billion, led by a 262 per cent surge in semiconductor shipments to $60.3 billion. Computer product shipments surged 435.3 per cent to $7 billion as suppliers fulfilled high-bandwidth memory orders for global computing platforms, including multi-billion supply agreements involving Samsung Electronics, SK hynix, and Nvidia.

    “Micron’s numbers are another strong validation of AI and memory demand, but markets may increasingly be asking whether we are closer to peak memory shortage, even if demand continues to exceed supply,” said Charu Chanana, chief investment strategist at Saxo.

    Energy Pressures and Policy Shifts

    Elevated commodity prices continue to complicate central bank calculations across Asia-Pacific import hubs. Brent crude futures hovered at $98.15 per barrel on October 1, after climbing more than 14 per cent in September to register a third straight month of price gains.

    Diplomatic friction and stalled peace negotiations between the United States and Iran regarding the seven-month conflict in the Middle East have kept shipping risks elevated across crucial energy corridors. Higher bunker and fuel costs are feeding directly into freight rates, hitting import-reliant consumer goods distributors and retailers across Southeast Asia.

    Data released on September 30 showed United States consumer price inflation rose less than expected in August, offering brief relief to equity trading desks. Pricing data from CME FedWatch showed traders assigned a 38 per cent probability to a Federal Reserve rate increase on October 28, down from a 50 per cent probability priced a day earlier.

    What Operators and Investors Face Next

    For retail conglomerates, electronics manufacturers, and commercial property owners across Asia, persistent capital costs are forcing tighter inventory control and reduced reliance on floating-rate debt. Higher discount rates limit speculative store rollouts, prompting operators to favor proven high-density retail corridors over aggressive regional expansion.

    The current market tension follows the Federal Reserve’s September decision to raise borrowing costs for the first time in three years. While New York Fed President John Williams indicated on September 29 that there was no immediate urgency for another policy move, energy market volatility keeps headline inflation risks open.

    All eyes now turn to the Federal Reserve’s rate-setting meeting on October 28, alongside third-quarter earnings releases from Asia’s leading consumer hardware and semiconductor manufacturers as South Korea aims for $1 trillion in annual exports.

  • Trump and Xi Summit in Washington Yields Limited Progress on Tariffs

    Trump and Xi Summit in Washington Yields Limited Progress on Tariffs

    President Donald Trump and Chinese leader Xi Jinping met in Washington last week for a summit that yielded limited progress on tariffs, leaving bilateral relations in what analysts describe as a managed stalemate.

    The limited outcomes showed how far apart Washington and Beijing remain on core economic issues, reinforcing analyst views that China sees little incentive to grant major political concessions ahead of November’s midterm elections.

    Limited Progress on Technology and Supply Chains

    Asia-Pacific supply chains face operations without clear visibility into 2027. Negotiators deferred binding settlements on critical trade disputes. These include China’s export limits on rare earth materials and US trade restrictions on advanced semiconductor shipments.

    Xi arrived in Washington seeking trade predictability as domestic retail spending softens in mainland China. Chinese factory exports have reached record levels globally. Still, falling residential property prices and persistent youth unemployment continue to depress household demand across tier-one and tier-two cities, where homeownership stands near 80 percent.

    Stalemate Over Tech Controls and Taiwan

    Artificial intelligence discussions ended without operational safeguards or a formal bilateral pact. Xi argued during the meetings that advanced computing systems must stay under direct human control. Meanwhile, the White House maintained its broader export controls on cutting-edge processors.

    Geopolitical friction also limited commercial progress. Xi reiterated that American arms sales to Taiwan cross a fundamental red line for Beijing, following a May warning that mishandling the territory could spark direct conflict. The US administration continues to hold a pending 14 billion dollar arms package for the island, using it during negotiations.

    What Operators and Exporters Face Next

    For consumer electronics makers, apparel brands and contract manufacturers across East Asia, the outcome changes little on the ground. Companies that accelerated factory shifts into Southeast Asia to dodge unilateral duties must continue carrying dual-supply chain overhead.

    Retailers sourcing consumer goods through southern Chinese hubs face an immediate cost risk early next year. The three-month extension merely pushes tariff uncertainty past the November US midterm elections without removing the threat of sudden duty hikes.

    January brings the next formal test for cross-border logistics and bilateral commerce, when the current tariff pause expires and working groups resume formal negotiations over market access and tech controls.

  • TSMC Affiliate Vanguard Eyes Second Singapore Plant as First Sells Out

    TSMC Affiliate Vanguard Eyes Second Singapore Plant as First Sells Out

    Taiwan Semiconductor Manufacturing Co. Affiliate Vanguard International Semiconductor inaugurated its first advanced chipmaking plant in Singapore on Monday, with capacity already sold out amid an artificial intelligence infrastructure boom.

    The plant was constructed in less than two years as chipmakers race to meet demand for data center components.

    With the initial site opening completely full, the company is already eyeing expansion and planning a second facility.

    Surging Data Center Component Intake

    Surging demand for AI computing has outstripped regional supply chains. Packaging and wafer fabrication lines filled up before commercial operations even began. Enterprise data center operators are securing long-term component capacity years ahead to avoid hardware bottlenecks.

    For technology equipment suppliers across Southeast Asia, the quick capacity fill guarantees immediate local component availability for server assembly and power management hardware. Device manufacturers that delayed long-term supply agreements now face extended lead times. Available volume is shifting to hyperscalers.

    Singapore Role in Asian Semiconductor Shift

    Foundries are establishing high-specification manufacturing clusters outside Taiwan and mainland China. Southeast Asia has drawn substantial capital expenditure from global semiconductor firms seeking neutral production hubs with established infrastructure and logistics links.

    This investment pairs NXP automotive and industrial silicon expertise with Vanguard manufacturing discipline. The combination insulates downstream consumer electronics and automotive assemblers across the Asia-Pacific region from single-location supply disruptions.

    Fast-Track Construction and Factory Timelines

    Vanguard and NXP broke ground on the initial Singapore site to capture expanding demand for specialty and power management semiconductors. The venture finished construction within twenty-four months to meet rapid AI hardware deployment schedules.

    Earlier expansion programs across the region faced construction delays and tool installation bottlenecks. By contrast, the Singapore project maintained its delivery timetable through streamlined municipal permitting and fast-tracked site preparation.

    Next Steps for the Second Facility

    Planning for the second Singapore plant now hinges on equipment procurement schedules and utility allocations from local authorities. VisionPower must finalize technical specifications for the proposed advanced production lines before committing total capital expenditure numbers.

    Directors on the joint venture board will next review the project to decide on the final construction timeline and the exact process geometry for the second facility.

  • TSMC to Build Five More Packaging Plants at Chiayi Science Park

    TSMC to Build Five More Packaging Plants at Chiayi Science Park

    Taiwan Semiconductor Manufacturing Co plans to build five additional advanced packaging plants at Chiayi Science Park in southwestern Taiwan, following the start of mass production at Phase I in June.

    The project will bring TSMC’s total advanced packaging facilities at the Chiayi site to 10, creating the world’s largest packaging hub for high-performance semiconductor components.

    Taiwan’s National Science and Technology Council has opened a one-month public consultation for Phase II expansion at the park in Taibao City, which local industries view as the launchpad for Phase III development. The planned Phase III zone covers 198.65 hectares, primarily leased from Taiwan Sugar Corp, to support technologies related to artificial intelligence, heterogeneous packaging, silicon photonics, high-speed broadband networks, quantum technology and net zero emissions.

    Scaling Up Advanced Packaging Capacity

    TSMC already operates two advanced packaging lines in Phase I of the Chiayi park, where mass production began in June. Equipment installation is now underway in Phase II. The company intends to complete three packaging facilities in Phase II by 2031, while preliminary site preparation for Phase III has begun.

    Building out Chiayi links the location to existing science parks in Tainan, Kaohsiung and Pingtung County to the south, as well as hubs in Taichung and Hsinchu to the north. Together, the interconnected parks form an integrated manufacturing corridor across western Taiwan designed to keep advanced fabrication close to domestic engineering teams.

    CoWoS Demand From Global Chip Buyers

    Surging orders for chip-on-wafer-on-substrate packaging from Nvidia, Advanced Micro Devices and Apple serve as the primary commercial engine behind the Chiayi project. Advanced packaging binds multiple silicon dies onto a single substrate, giving AI accelerators and mobile processors the memory bandwidth required for high-density computing workloads without relying solely on smaller nanometer lithography.

    For hardware manufacturers and consumer electronics brands, packaging bottlenecks have dictated device delivery schedules for more than two years. Concentrating 10 packaging plants in Chiayi addresses that supply constraint directly, giving key enterprise and consumer hardware clients guaranteed assembly allocations through the end of the decade. The concentration of advanced packaging on the island also raises the operational stakes for global electronics supply chains, which remain heavily dependent on Taiwan’s local power grid, water supplies and regional transport networks.

    Taiwan Infrastructure and Regional Competition

    While TSMC expands fabrication operations overseas in the United States, Japan and Germany, its most advanced packaging processes remain anchored in Taiwan. Packaging clusters require tight proximity to the leading-edge wafer fabs that produce raw silicon slices, making domestic expansion far more cost-effective than duplicating complex multi-die assembly networks abroad.

    Competitors such as Intel and Samsung continue to build out proprietary advanced packaging services to win third-party foundry clients. TSMC’s accelerated buildout in Chiayi prevents rivals from capturing unmet packaging demand from top-tier chip designers who cannot secure sufficient domestic capacity elsewhere.

    What Comes Next in the Planning Process

    Capital spending supports the speed of the expansion. In July, TSMC lifted its full-year capital expenditure forecast to a band between US$60 billion and US$64 billion, up from an earlier estimate of US$52 billion to US$56 billion announced in April. The Ministry of Economic Affairs reports that TSMC operates 19 advanced wafer fabs and packaging plants across Taiwan, with 13 additional facilities under construction in Hsinchu, Taichung, Chiayi, Tainan and Kaohsiung.

    Following the conclusion of the public comment window for the Chiayi expansion, the National Science and Technology Council will complete a formal feasibility study for submission to the Executive Yuan. Once the central government approves the plan, the project will advance to statutory urban planning reviews and environmental impact assessments before Phase III construction contracts are awarded.

  • Thailand Targets $80 Billion in Semiconductor Investment by 2050

    Thailand Targets $80 Billion in Semiconductor Investment by 2050

    Thailand wants $80 billion in semiconductor investment by 2050 to build a domestic chip manufacturing sector, the Board of Investment announced on Thursday.

    Under the national roadmap, officials aim to generate $150 billion in annual revenue. The plan targets 230,000 technical jobs over the next quarter-century.

    Finance Minister Ekniti Nitithanprapas said the government will offer tax incentives, regulatory reforms, workforce training, infrastructure upgrades, and direct research funding to draw foreign chipmakers. The programme rolls out in stages. It starts with packaging and testing before advancing into wafer fabrication and integrated circuit design.

    Targeting Three Priority Technologies

    Bangkok designated photonics, power semiconductors, and sensors as priority subsectors. These categories feed into automotive electronics, industrial machinery, and artificial intelligence hardware. Thailand already maintains substantial export volume in these sectors.

    Local factories currently handle back-end assembly and testing, the lowest-margin link in the value chain. Moving upstream requires heavy capital expenditure. Industrial estates must now build cleanroom utilities from scratch.

    Supply Chain Realities for Southeast Asian Electronics

    For regional manufacturers and automotive supply chains, the roadmap alters the sourcing map across Southeast Asia. Car assemblers in the Eastern Economic Corridor have spent two years dealing with supply bottlenecks for specialised power management chips. Domestic fabrication plants would reduce component lead times for electric vehicle assembly lines and consumer tech exporters operating across ASEAN.

    Competition across the region is stiff. Malaysia holds an established lead in back-end packaging and advanced testing, while Singapore dominates regional wafer fabrication and Vietnam captures substantial front-end assembly investments. Thai officials bet that combining high tax breaks with domestic automotive demand will persuade global foundries to commit billions to local fabrication lines.

    Geopolitical Alignments and Investment Realities

    This policy push follows Prime Minister Anutin Charnvirakul’s July 2026 visit to China. Trade officials there discussed deepening bilateral industrial integration across electric vehicles and electronic hardware. Chinese state-backed industrial groups have expanded rapidly into Thai manufacturing estates, bringing price advantages and technical capacity while raising questions about supply chain concentration.

    The Board of Investment briefly withdrew its initial strategy statement on Thursday morning. It reissued the text without alterations to its headline capital and employment targets. Planners had faced scrutiny over whether the state budget could sustain long-term research subsidies alongside multi-year corporate tax holidays.

    The Timeline for Early Approvals

    State agencies will draft specific tax concession packages and workforce development grants for review by the cabinet. Next quarter, the Board of Investment plans to publish detailed application guidelines for advanced packaging and power semiconductor projects, establishing threshold capital requirements for incoming investors.

  • ADB Lifts Southeast Asia Growth Outlook to 4.7% on Tech Exports

    ADB Lifts Southeast Asia Growth Outlook to 4.7% on Tech Exports

    The Asian Development Bank raised its 2026 economic growth forecast for developing Southeast Asia to 4.7 per cent on Wednesday, up from 4.6 per cent projected in July. Global shipments of semiconductor chips and data center components surged. That demand offset the drag from high energy prices and severe weather.

    Across the wider Asia-Pacific region, the Manila-based lender lifted its 2026 expansion target by 0.1 percentage point to 5.0 per cent. It held the 2027 projection at 5.1 per cent. The revised figures show a widening regional split. Electronics manufacturing hubs are pulling ahead while economies exposed to food inflation and power generation shortfalls lag behind.

    Hardware Demand Lifts Export Leaders

    Vietnam received the sharpest upgrade in the updated Asian Development Outlook. Growth there is now projected at 7.8 per cent for 2026, up from 7.2 per cent. The bank also increased Vietnam’s 2027 forecast to 7.6 per cent, citing strong foreign direct investment and state stimulus programs directed into industrial parks and logistics infrastructure.

    Malaysia gained an upward adjustment as well. The economy will expand 4.9 per cent in 2026, up from the 4.6 per cent estimated in July. Growth should moderate to 4.7 per cent in 2027. Both countries have secured substantial market share in chip packaging, testing, and component fabrication for cloud infrastructure operators.

    Net exports remained resilient, supported by demand for electronics and AI-related products.

    Thailand recorded a modest bump to 2.0 per cent for 2026 from 1.8 per cent, though ADB trimmed its 2027 outlook to 1.9 per cent. Indonesia held steady. Growth there is projected at 5.2 per cent across both years, underpinned by household consumption.

    Energy Costs and Drought Penalise Importers

    Prospects weakened in the Philippines. The lender lowered the country’s 2026 growth target to 3.3 per cent from 3.8 per cent. It also reduced the 2027 forecast to 5.1 per cent from 5.3 per cent. Power sector strains and dry spells continue to weigh on domestic output.

    Geopolitical friction in the Middle East and Eastern Europe has kept fuel import bills high for non-oil producers. In markets like Cambodia and the Philippines, higher utility tariffs flow directly into retail prices. That squeeze curbs discretionary consumer spending and raises cold-chain logistics expenses for supermarket operators.

    What the Divergence Changes for Retail and Supply Chains

    Consumer brands face a shifting landscape where capital expenditure yields the fastest returns. Rising wages in Vietnam and Malaysia bolster middle-income buying power for consumer tech and packaged goods. Mall operators and retail chains are accelerating store openings in secondary cities to match demand.

    Agricultural supply chains face heavier margin pressure across the western Pacific. Parched croplands and high diesel prices increase transport and ingredient costs for food manufacturers. Fast-moving consumer goods suppliers must now renegotiate wholesale contracts across archipelagic supply routes.

    Earlier Forecast Steps and Baseline Trajectory

    The latest revisions follow a July review where regional output held steady against tightening monetary conditions in Western export destinations. In April, the lender had modeled a broader regional recovery. Energy market volatility then intensified through the middle quarters of the year.

    Price pressures have eased across developing Asia, where headline inflation should settle at 2.8 per cent this year. That moderation gives central banks room to adjust interest rates once currency pressures ease against the US dollar.

    The Timeline for El Nino Disruption

    Weather risks represent the primary operational hazard through the coming quarters. ADB expects the current El Nino pattern to intensify through late 2026 and peak around November. That timeline threatens hydroelectric generation and irrigated rice cultivation.

    Agricultural disruptions register in headline economic data with a multi-month lag. The bank expects the sharpest drag from the climate cycle to hit during the first half of 2027. The next baseline revision to regional growth figures arrives in December.

  • South Korea KOSPI Tests 7,100 on Chip Gains Before Pre-Holiday Selling

    South Korea KOSPI Tests 7,100 on Chip Gains Before Pre-Holiday Selling

    South Korea’s benchmark KOSPI broke past 7,100 in early Tuesday trading as semiconductor heavyweights tracked a Wall Street rally before profit-taking trimmed gains ahead of the Chuseok holiday.

    The index opened 1.94 percent higher at 7,153.99, gaining 136.08 points at the opening bell, before retreating to the late 7,020 level as domestic traders liquidated positions ahead of a two-day market closure.

    Semiconductor Heavyweights Drive Early Surge

    Tech issues led the opening advance, tracking overnight strength in the United States where the Philadelphia Semiconductor Index gained 2.06 percent and the tech-heavy Nasdaq Composite reached a record close of 27,244.28. Samsung Electronics advanced as much as 2.80 percent intraday to touch 285,000 won (approximately $210) before paring its advance to around 2 percent. SK Hynix climbed 1.96 percent to reach 1.9 million won (approximately $1,400) in early deals before flattening out.

    Chip-adjacent suppliers and affiliate holdings tracked the initial rally. SK Square rose 4.41 percent, Samsung Electronics preferred shares gained 3.31 percent, and Samsung Electro-Mechanics climbed 2.22 percent. On the junior KOSDAQ board, equipment maker Wonik IPS added 4.68 percent while Simmtech and HPSP gained 2.57 percent and 2.03 percent respectively.

    Retail Debut Sparks Household Goods Rally

    Wise Planet Company delivered the session’s sharpest single-stock move during its KOSDAQ debut. The household goods retailer jumped 230 percent above its initial public offering price of 12,000 won (approximately $8.9) to trade at 29,200 won (approximately $22), reaching an intraday peak gain of 243.33 percent. The listing lifted the broader household goods index by 134.92 percent.

    Other consumer and industrial names showed sharp dispersion. POSCO Future M opened more than 4 percent higher after confirming a 1.1 trillion won (approximately $814.1 million) lithium iron phosphate cathode supply contract with battery maker SK On, but selling pressure pulled the stock into negative territory by midday. Shipping operator KSS Line gained roughly 15 percent following a share buyback disclosure, while cyber-security provider Xgate posted double-digit gains.

    Institutional and Foreign Positioning

    Trading flows fluctuated sharply as domestic retail participants moved into cash. Retail investors on the main board sold a net 366 billion won (approximately $270.9 million) in opening deals, while foreign and institutional desks recorded net purchases of 174 billion won (approximately $128.8 million) and 142.9 billion won (approximately $105.8 million) before shifting volume across the morning session.

    In the foreign exchange market, the South Korean won traded around the early 1,350 won level against the US dollar, opening at 1,349.8 won as dollar conversions from exporters provided currency support.

    Holiday Consolidation Mirrors Previous Session

    Tuesday’s price action repeated the pattern of the prior trading day. On Monday, the KOSPI opened 2.20 percent higher at 7,161.61, reached an intraday high of 7,171.44, and then gave up nearly all its gains to close at 7,017.91, up just 0.15 percent after retail accounts sold a net 1.8886 trillion won (approximately $1.4 billion).

    South Korean financial markets remain closed on Wednesday and Thursday for the Chuseok holiday, leaving domestic bourses scheduled to resume regular trading on Friday, September 26.

  • Taiwan Freezes Electricity Rates at NT$3.78 per Kilowatt-Hour Until December Review

    Taiwan Freezes Electricity Rates at NT$3.78 per Kilowatt-Hour Until December Review

    Taiwan has frozen average electricity tariffs at NT$3.78 per kilowatt-hour through December. The decision rejects a proposed 12.83 percent increase by state utility Taiwan Power Co to curb broader consumer price inflation.

    This is the second consecutive freeze by the Ministry of Economic Affairs electricity price review committee. Any potential rate adjustment now shifts to January at the earliest.

    Taipower requested an increase to NT$4.2675 per kilowatt-hour after absorbing higher generation costs from volatile global energy markets. The government will instead seek a NT$71.1 billion (US$2.24 billion) Cabinet-backed supplementary budget. That funding will cover fuel deficits the utility incurred between March and August.

    Subsidy Request Replaces Proposed Double-Digit Hike

    International crude oil prices swung between $68 and $132 per barrel during recent Middle East escalations, forcing state power suppliers across Asia to absorb steep fuel cost swings. Deputy Minister of Economic Affairs Lai Chien-hsin confirmed the tariff committee chose direct fiscal support over passing generation expenses to commercial users and households.

    The ministry expects Taipower to post a full-year loss of NT$71.1 billion without state intervention. Lawmakers in the Legislative Yuan must still approve the funding. That sign-off is needed to restore balance-sheet working capital and avert sharper tariff hikes in early 2027.

    Split Rates Debated for Advanced Manufacturing

    Committee discussions included proposals to introduce differential pricing for high-load artificial intelligence data centers and advanced semiconductor fabrication facilities. General Chamber of Commerce of the Republic of China chairman Paul Hsu argued against blanket relief. He advocated targeted adjustments on high-tech consumers while protecting small commercial enterprises.

    We hope electricity rates can be frozen for households and small and medium-sized traditional industries, while high-tech industries should see moderate price adjustment.

    Regulators declined to implement split rates during the session, citing the risk to export competitiveness without comprehensive usage data. A specialized working group will now study industry consumption patterns, economic output, and consumer price transmission channels before the December meeting.

    Mounting Deficits at the State Utility

    Taipower accumulated losses exceeding NT$400 billion over recent operating cycles while absorbing global crude oil spikes to protect domestic retail price stability. The utility lost another NT$21.4 billion during the first seven months of the year. That brought cumulative balance-sheet losses to NT$372.2 billion.

    A net profit of NT$76.1 billion in the prior financial year gave the company narrow financial leeway to withstand the immediate freeze, according to Taipower president Kuo Tien-ho.

    What Operators Face Heading into 2027

    For commercial store networks, logistics hubs, and physical retailers across Taiwan, the decision provides short-term visibility on utility overheads during peak fourth-quarter shopping periods. Keeping tariffs below generation costs shifts the strain onto legislative fiscal approvals. If lawmakers trim the requested allocation, operators face a sharp cost cliff.

    Commercial landlords and chain operators must now model utility expense increases into their preliminary 2027 budgets. The ministry will publish full meeting minutes and Taipower cost datasets on October 2. Regulators will then finalize transmission, distribution, and base tariff rates for next year at the third review meeting in December.

  • Subaru to Evaluate Onsemi Platform Offering 4X EV Inverter Power Density

    Subaru to Evaluate Onsemi Platform Offering 4X EV Inverter Power Density

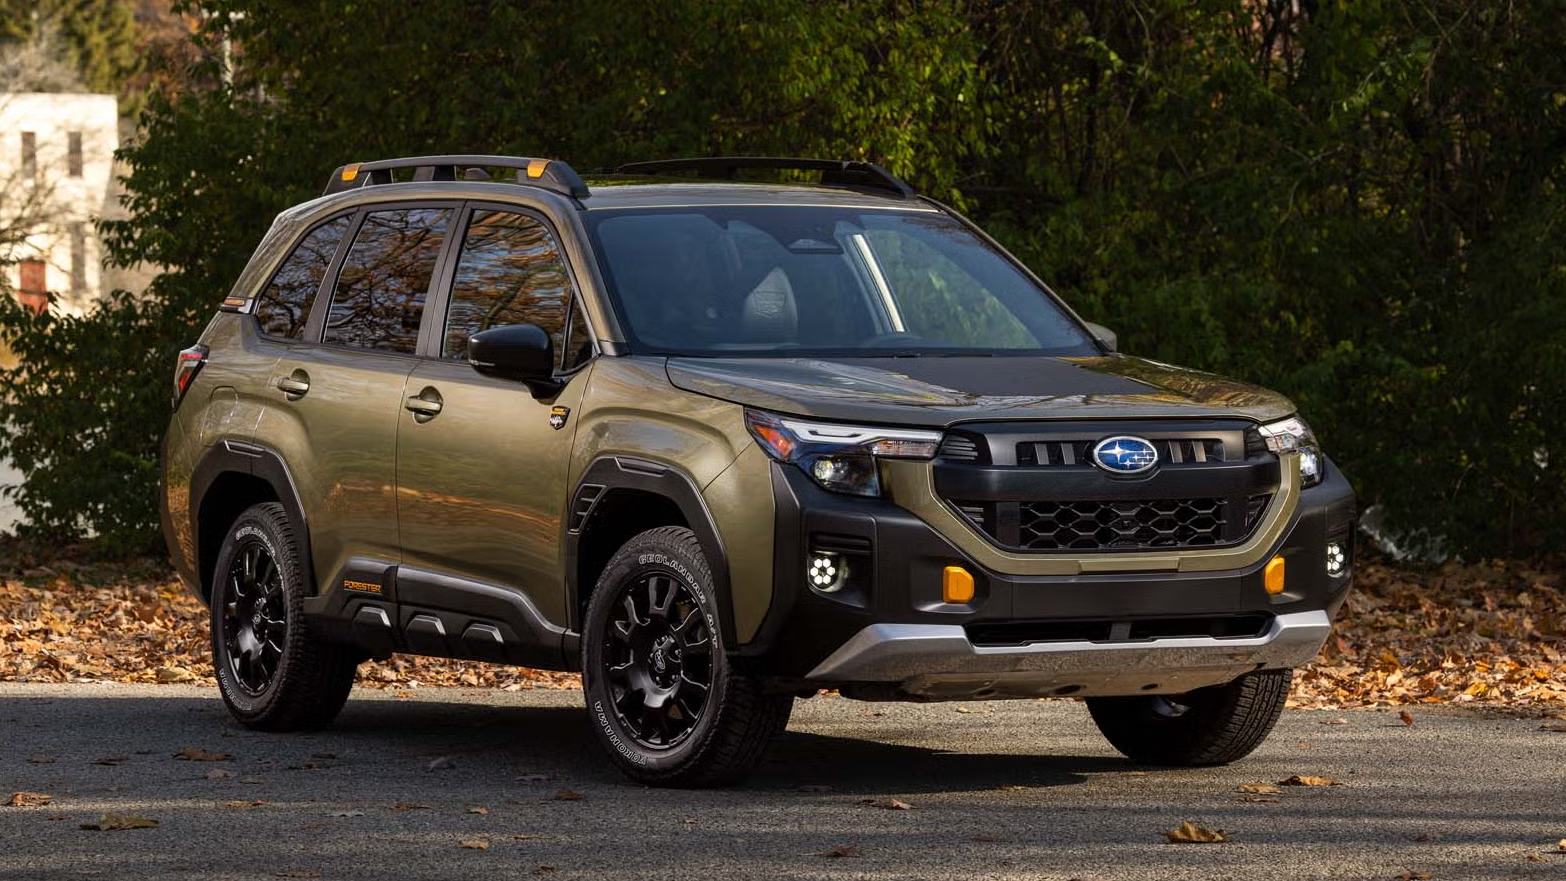
    Subaru has partnered with semiconductor maker Onsemi to evaluate a new power electronics architecture designed to quadruple power density in electric vehicle traction inverters.

    Under the collaboration, the Japanese automaker will receive early access to engineering samples, simulation models and technical expertise later this year to test the system across its future electrified vehicle architectures.

    Wafer-level packaging for vehicle drives

    Named the Embedded Power Platform, the system uses the silicon wafer itself as the package base. This setup combines silicon, silicon carbide and gallium nitride components. It also integrates field-effect transistors, gate drivers and system controllers inside a single module.

    Building components directly on 12-inch wafer production lines eliminates multiple assembly steps. It also cuts parasitic inductance. Lower inductance reduces electrical losses and lets power switches run at higher frequencies without excessive heat.

    Onsemi claims the architecture cuts inverter power losses by up to 15 per cent and shrinks the footprint up to fourfold. Subaru has not committed the hardware to a specific production model yet. Still, the evaluation gives the carmaker a direct look at multi-voltage powertrain integration.

    Standardising power across vehicle lines

    Modular power electronics offer Japanese carmakers a way to cut engineering overhead as they chase global battery-electric rivals. Engineers can scale one base architecture across compact cars, crossovers and commercial platforms instead of designing custom inverters for each vehicle class.

    This strategy shifts component integration risk from the vehicle assembly line to the chip fabrication plant. Automakers get smaller, lighter drive units. However, they face greater dependence on single-source packaging methods that cannot be swapped quickly during supply shortages.

    Industrial and data centre crossover

    Beyond passenger cars, the platform scales into industrial machinery and artificial intelligence data centre power racks. In non-automotive setups, Onsemi claims power density jumps by three to five times. That reduction cuts hardware development timelines to four months in select industrial cases.

    Japanese manufacturers spent the past two years consolidating electric powertrain supply chains to protect operating margins as domestic hybrid sales peak. Subaru previously committed to expanding its electrified lineup through joint projects with Toyota, focusing on shared platform costs and joint battery procurement.

    Initial engineering samples of the platform will ship to Subaru and select artificial intelligence hardware partners before the end of 2026.