Tag: shopee

  • Indonesia Enforces 0.5% Tax Collection on Domestic E-Commerce Sales

    Indonesia Enforces 0.5% Tax Collection on Domestic E-Commerce Sales

    Finance Minister Suahasil Nazara confirmed on Friday that collecting income tax from merchants selling through online platforms is necessary to create fairer competition between digital sellers and conventional brick-and-mortar retailers.

    The policy applies an Article 22 income tax rate of 0.5% on domestic merchants’ sales turnover, governed by Finance Minister Regulation No. 37 of 2025. The Finance Ministry began consolidating transaction revenue data in November 2026, with the first figures scheduled for release in December.

    Under the framework, the government designated four major e-commerce platforms, Shopee, Tokopedia, Lazada and Blibli, to collect, remit and report the levy on behalf of sellers operating across their digital marketplaces.

    Marketplace Tax Collection

    The measure introduces no new levy, shifting collection instead to marketplace operators for income tax that merchants previously handled independently. Individual merchants generating annual turnover of up to Rp 500 million ($27,400) are exempt from marketplace tax collection, provided they fulfill formal criteria, including submitting a declaration of their turnover.

    Suahasil stressed that commercial enterprises across differing distribution channels require comparable treatment under fiscal rules, whether trading across digital storefronts or physical premises.

    “The taxation of e-commerce is intended to improve the level playing field, even though the tax rate for online merchants is lower,” Suahasil told a press conference in Jakarta.

    “The new e-commerce tax policy is beginning to be reflected in consolidated data this November, and the figures will be reported next month,” Suahasil said.

    Separate Tax on Foreign Digital Services

    Suahasil noted that income tax withheld from domestic online traders remains distinct from value-added tax levied on offshore digital goods and services. Cross-border digital transactions, including video streaming platform subscriptions, have yielded Rp 14 trillion ($768.7 million) in VAT revenue.

    Both tax collection tracks reflect state initiatives aimed at strengthening fiscal compliance across the digital economy, encompassing internal merchant sales and cross-border digital services.
  • TikTok Launches Standalone Shopping App in Four Southeast Asian Markets

    TikTok Launches Standalone Shopping App in Four Southeast Asian Markets

    TikTok has launched a standalone TikTok Shop application across four Southeast Asian markets this month, separating its retail operations from its primary social media platform in Singapore, Malaysia, Thailand and the Philippines.

    The dedicated software allows the company to compete more directly with established online marketplaces such as Amazon and Temu while encouraging consumers to complete purchases within its proprietary retail ecosystem.

    Available on iOS and Android, the standalone app offers personalised product recommendations, livestream shopping, short-form product videos and exclusive promotions. The platform also incorporates in-app payments, order tracking and customer support, providing a dedicated ecommerce experience. ByteDance rolled out the software without formal fanfare, testing shopper appetite for an unbundled buying channel.

    Splitting Social Feeds From Retail Checkout

    Separating commerce from browsing addresses a mechanical limitation of social retail. In-feed shopping clutters entertainment feeds and irritates casual viewers, while high-intent buyers want catalogue search tools, order histories and swift order reconciliation rather than algorithmic video streams. A dedicated storefront gives merchants persistent shelf space that does not vanish when an algorithm rotates clips out of circulation.

    The engineering shift alters the operating equation for beauty, fashion and fast-moving consumer brands. Merchandisers gain direct promotional pathways and structured storefront displays, but they lose the effortless discovery of an audience that was not explicitly looking to spend money. Driving repeat app downloads demands heavy capital expenditure, forcing TikTok to fund discount incentives and free delivery to build independent utility.

    Rival Pressures Across Regional Marketplaces

    The unbundled app takes direct aim at incumbent marketplace operators Shopee and Lazada, alongside cross-border discount merchants Shein and Temu. While Amazon retains a narrower footprint in the region, established Asian platforms command entrenched logistics pipelines and deep consumer loyalty. These legacy platforms will not surrender search-driven shopping volume without discounting their own commissions.

    Regional merchants now face fragmented channel management. Maintaining inventory, campaign pricing and creator affiliate links across both the main TikTok social platform and an auxiliary shopping app increases operational complexity for suppliers. Investors face elevated customer acquisition costs as ByteDance attempts to build consumer habits around two separate app icons instead of one.

    Earlier Footprint and Regional Expansion

    Southeast Asia provided the operational launchpad for ByteDance’s commercial ambitions long before TikTok Shop expanded into Western territories. The region delivered more than one trillion video views by 2022, creating the engagement base that allowed the company to pilot live commerce and merchant integrations. Subsequent rollouts in the United States and the United Kingdom yielded substantial transaction gains, with TikTok Shop pacing toward $100 billion of gross merchandise value in 2026 led by U.S. Sales.

    Rivals have answered by fortifying their Asian commerce ties, including external partnerships linking video platforms like YouTube with Asian merchant inventories such as AliExpress. Despite those defensive manoeuvres, ByteDance continues to treat Southeast Asia as an experimental sandbox for product architecture before deploying changes worldwide.

    Next Steps for Market Rollout

    ByteDance has not confirmed release timetables for additional territories, leaving an eventual rollout to Western economies including the United States pending. The immediate test sits in download conversion and monthly active user retention across the four Southeast Asian territories through the final quarter of the year.

  • TikTok Launches Standalone Shopping App in Four Southeast Asian Markets

    TikTok Launches Standalone Shopping App in Four Southeast Asian Markets

    TikTok has launched a standalone TikTok Shop application across four Southeast Asian markets this month, separating its retail operations from its primary social media platform in Singapore, Malaysia, Thailand and the Philippines.

    The dedicated software allows the company to compete more directly with established online marketplaces such as Amazon and Temu while encouraging consumers to complete purchases within its proprietary retail ecosystem.

    Available on iOS and Android, the standalone app offers personalised product recommendations, livestream shopping, short-form product videos and exclusive promotions. The platform also incorporates in-app payments, order tracking and customer support, providing a dedicated ecommerce experience. ByteDance rolled out the software without formal fanfare, testing shopper appetite for an unbundled buying channel.

    Splitting Social Feeds From Retail Checkout

    Separating commerce from browsing addresses a mechanical limitation of social retail. In-feed shopping clutters entertainment feeds and irritates casual viewers, while high-intent buyers want catalogue search tools, order histories and swift order reconciliation rather than algorithmic video streams. A dedicated storefront gives merchants persistent shelf space that does not vanish when an algorithm rotates clips out of circulation.

    The engineering shift alters the operating equation for beauty, fashion and fast-moving consumer brands. Merchandisers gain direct promotional pathways and structured storefront displays, but they lose the effortless discovery of an audience that was not explicitly looking to spend money. Driving repeat app downloads demands heavy capital expenditure, forcing TikTok to fund discount incentives and free delivery to build independent utility.

    Rival Pressures Across Regional Marketplaces

    The unbundled app takes direct aim at incumbent marketplace operators Shopee and Lazada, alongside cross-border discount merchants Shein and Temu. While Amazon retains a narrower footprint in the region, established Asian platforms command entrenched logistics pipelines and deep consumer loyalty. These legacy platforms will not surrender search-driven shopping volume without discounting their own commissions.

    Regional merchants now face fragmented channel management. Maintaining inventory, campaign pricing and creator affiliate links across both the main TikTok social platform and an auxiliary shopping app increases operational complexity for suppliers. Investors face elevated customer acquisition costs as ByteDance attempts to build consumer habits around two separate app icons instead of one.

    Earlier Footprint and Regional Expansion

    Southeast Asia provided the operational launchpad for ByteDance’s commercial ambitions long before TikTok Shop expanded into Western territories. The region delivered more than one trillion video views by 2022, creating the engagement base that allowed the company to pilot live commerce and merchant integrations. Subsequent rollouts in the United States and the United Kingdom yielded substantial transaction gains, with TikTok Shop pacing toward $100 billion of gross merchandise value in 2026 led by U.S. Sales.

    Rivals have answered by fortifying their Asian commerce ties, including external partnerships linking video platforms like YouTube with Asian merchant inventories such as AliExpress. Despite those defensive manoeuvres, ByteDance continues to treat Southeast Asia as an experimental sandbox for product architecture before deploying changes worldwide.

    Next Steps for Market Rollout

    ByteDance has not confirmed release timetables for additional territories, leaving an eventual rollout to Western economies including the United States pending. The immediate test sits in download conversion and monthly active user retention across the four Southeast Asian territories through the final quarter of the year.

  • Temu Joins Philippine Anti-Counterfeiting Pact Across 90 Markets

    Temu Joins Philippine Anti-Counterfeiting Pact Across 90 Markets

    Chinese e-commerce platform Temu has agreed to cooperate with the Philippine government to eliminate counterfeit goods from online marketplaces, signing a memorandum of understanding with the Intellectual Property Office of the Philippines (IPOPHL).

    The voluntary agreement creates a direct mechanism for intellectual property rights holders to report potentially infringing listings and coordinate removals with participating operators.

    Temu, which operates in more than 90 markets globally after entering the Philippines in 2023, joins regional competitors Lazada, Shopee, Zalora and TikTok Shop under the IPOPHL framework following preliminary talks in June.

    How the Takedown System Works

    Under the voluntary framework, rights holders submit suspected knockoffs directly to participating operators. Temu will then coordinate with the regulator and brand owners to verify complaints and take down listings.

    The company enters an arrangement that already binds Lazada, Shopee, Zalora and TikTok Shop. Together, those platforms account for the vast majority of cross-border consumer marketplace volume in the Philippines.

    “E-commerce platforms are a significant driver of consumer activity in the Philippines, making them important partners in protecting buyers and legitimate businesses from counterfeit goods,” IPOPHL Deputy Director General Nathaniel Arevalo said.

    Screening Database and Brand Protection

    Temu built out internal intellectual property controls ahead of the Manila agreement. The platform set up an IP Protection Portal in 2023 and rolled out its Brand Guardian Initiative in 2024, logging regular communication with more than 3,000 rights holders.

    Its backend screening database tracks more than 15,000 brands. That system uses 47 million reference images and 9.5 million keywords to catch infringements before or after products go live.

    Shifting Regulatory Pressure on Low-Cost Marketplaces

    Voluntary pacts give regulators faster takedown use without tying up cases in local courts. For discount platforms relying on direct-from-factory Chinese merchants, policing millions of bargain listings is the price of keeping local market access.

    Signing on brings Temu level with established Southeast Asian rivals on paper. The operational friction sits in enforcement: automatic keyword and image filters often miss rebadged consumer goods, leaving the burden of discovery on local brand owners.

    Timeline Behind the Manila Agreement

    Temu entered the Philippine retail market in 2023, competing directly with regional incumbents on cut-rate apparel, electronics and home goods. Talks with Manila officials gained traction in June during a World Intellectual Property Organization session on digital commerce.

    The next metric to monitor is the volume of formal takedown notices brand owners file through the IPOPHL portal once Temu integrates its notice-and-takedown workflow.

  • TikTok Shop Targets 13.2% Share Across Southeast Asia E-Commerce

    TikTok Shop Targets 13.2% Share Across Southeast Asia E-Commerce

    TikTok Shop is projected to take a 13.2 per cent share of Southeast Asia’s e-commerce market in 2023, upending the hierarchy established by regional incumbents. The platform is tracking toward a gross merchandise value target of US$15 billion this year, according to data from venture builder Momentum Works.

    That volume represents more than a threefold jump from the US$4.4 billion recorded across the region in 2022. The rapid expansion pulls the ByteDance unit into direct parity with Indonesian market leader Tokopedia, which holds an estimated 13.9 per cent share, while closing the gap on Lazada at 17.7 per cent.

    Beauty Baskets Drive Volume Growth

    Personal care and beauty products form the engine of the platform’s regional expansion. The category accounts for 84 per cent of all products sold on TikTok Shop and generates 70 per cent of its total gross merchandise value.

    Merchants and cosmetics brands rely heavily on product bundling strategies across their livestreams to push average order values higher. By pairing skin creams, lip tints and cleansers into discounted kits, sellers generate bulk purchases from viewers watching real-time product demonstrations.

    The concentration in beauty mirrors the early development of social commerce in mainland China, where low-ticket impulse buys established initial buying habits before consumers shifted toward consumer electronics and household goods.

    Shopee Steps Up Indonesian Livestream Battle

    Market leader Shopee still retains the dominant regional footprint with a projected 46.5 per cent market share for 2023. Sea Group is responding directly by diverting resources into its own live shopping features to defend its merchant base in major markets like Indonesia.

    During its 7.7 campaign in Indonesia, Shopee logged a 12-fold increase in transaction volumes through livestreaming channels compared to a standard trading day, Sea Group chief executive Forrest Li told analysts on an earnings call. That spending shift demonstrates how legacy marketplace operators must now pay to defend engagement formats they once treated as optional add-ons.

    For consumer brands and multi-channel retailers across Southeast Asia, the fragmentation of platform market share alters commercial use. Sellers no longer rely entirely on Shopee search placements or Lazada campaign days to clear inventory. Instead, marketing budgets are flowing toward video creator networks, changing merchant acquisition costs and logistics routing across Jakarta.

    Disruption Tests Traditional Network Effects

    Established marketplaces long operated under the assumption that vast merchant catalogs and established logistics routes created insurmountable defenses. The surge of video-led buying breaks that pattern by pulling purchasing directly into entertainment feeds.

    “The bigger narrative is that in ecommerce, where leading players seem to have a network effect and structural advantage, disruption can still happen, and the incumbents should always remain focused and vigilant,” Chen said in a statement.

    Weihan Chen, insights lead at Momentum Works, noted that incumbents face structural pressure regardless of whether TikTok Shop operates as an isolated social platform or a full-scale marketplace operator.

    The threat is particularly sharp in Indonesia, Southeast Asia’s biggest retail economy, where ByteDance has staged extensive offline merchant recruitment drives and creator summits. Having reached scale in beauty, the platform now faces the harder operational test of building delivery networks and merchant infrastructure capable of handling bulkier, higher-value consumer goods without margin erosion.

    Momentum Works is scheduled to release the complete market share dataset across Southeast Asia’s digital commerce sector in an upcoming research report, outlining full-year regional gross merchandise volume tallies.

  • Lazada, Shopee and TikTok Cut Fees to Save Thai SMEs 1.93B Baht

    Lazada, Shopee and TikTok Cut Fees to Save Thai SMEs 1.93B Baht

    Lazada, Shopee and TikTok Shop agreed to roll back gross profit commission fees for Thai small businesses to January 1 levels for six months starting December 1, 2026.

    The temporary reduction runs through May 31, 2027, and is projected to save 1.2 million merchants an estimated 1.93 billion baht in operating costs.

    Wattanasak Sur-iam, director-general of the Department of Internal Trade, stepped in after the three platforms raised merchant commissions three separate times since January 2026. Those rapid hikes gave vendors little time to reprice stock or recalibrate working capital. Under the settlement, the rollback caps Lazada gross profit fees between 7.50 per cent and 11.60 per cent, sets Shopee rates from 8.03 per cent to 13.91 per cent, and pegs TikTok Shop fees at 11.24 per cent to 17.66 per cent depending on the product category. Electronics are excluded from the fee relief.

    Thresholds and Bureaucratic Hurdles for Sellers

    Access to the lower fee schedule comes with rigid revenue ceilings. Individual sole traders must record annual sales below 1.8 million baht, while registered legal corporate entities qualify only if yearly turnover stays at or below 3.5 million baht.

    Relief is not automatic. Sellers must file applications directly with the Department of Business Development, provincial commerce branch offices or local administrative councils to secure the discounted commission tiers.

    That administrative layer creates friction. Thousands of small operators run informal operations across social networks and marketplaces, meaning operators who fail to register through government channels will continue paying post-hike commissions during peak holiday trading.

    Margin Battles Shift from Subsidies to Extraction

    For marketplace operators across Southeast Asia, the fee battle reflects a sharp pivot from subsidised user acquisition to aggressive take-rate monetisation. Platforms spent years burning cash on free shipping vouchers and merchant onboarding bonuses to lock in domestic market share. Now, parent groups want positive free cash flow, and raising commission rates is the fastest lever to pull.

    Thailand has become the sharp edge of this regional pushback. When marketplaces simultaneously raise commissions multiple times in a single calendar year, merchant margins vanish faster than consumer prices can adjust. By enforcing a temporary rollback, state regulators are checking platform pricing power without dismantling the underlying commission models.

    The policy hands independent suppliers temporary margin breathing room. It does not solve the long-term risk for vendors who remain entirely dependent on three dominant digital distribution channels.

    Antitrust Intervention Precedes Statutory Controls

    Regulatory pressure had been building before the commerce ministry stepped into negotiations. The Trade Competition Commission of Thailand previously pushed platforms to freeze gross profit increases for a six-month window from August 27, 2026 to February 27, 2027.

    Supree Thongpetch, chairman of the Thai Small and Medium Enterprises Council, argued the registration mechanism should push informal vendors into formal commercial frameworks to improve transparency. He noted, “The solution lies in finding a balance among all business operators, as we are part of the country’s shared commercial structure.”

    Commerce Minister Suphajee Suthumpun confirmed the relief plan serves only as a stopgap measure. Ministries are reviewing the draft Digital Platform Economy Act, which officials first assembled in 2025, to write permanent statutory controls over platform pricing, business conduct and service benchmarks.

    Permanent Pricing Rules Await February Deadline

    State agencies will continue gathering stakeholder feedback on the draft digital platform legislation until February 27, 2027. Commerce officials plan to present the final assessment framework governing ongoing gross profit fees before the end of February.

  • Southeast Asia AI User Base Hits 243 Million While Subscriptions Lag

    Southeast Asia AI User Base Hits 243 Million While Subscriptions Lag

    Generative artificial intelligence reached 243 million users across Southeast Asia in less than three years, representing 58 per cent of the region’s working population. Direct software subscriptions capture only 1 to 2 per cent of those consumers, shifting the financial return to e-commerce and marketing channels.

    The joint annual e-Conomy SEA report from Google, Temasek and Bain & Company projects the regional digital economy will expand 17 per cent to $368 billion in gross merchandise value this year. The market is tracking toward $1 trillion by 2035.

    Merchant Operations Absorb Infrastructure Costs

    Consumer uptake is outrunning the early curve of mobile internet by four times. Rather than charging monthly fees for software access, digital marketplaces are monetizing the audience through backend conversion gains, targeted search, and automated customer service desks.

    Shopee routed approximately 80 per cent of its customer inquiries through automated AI chatbots. That shift lowered its customer contact costs by 30 per cent year on year. Across the broader retail sector, early case studies track a 10 per cent year-on-year lift in baseline conversion rates and order basket increases reaching 75 per cent.

    About 69 per cent of shoppers now deploy artificial intelligence tools to evaluate complex retail transactions like consumer electronics. In addition, 75 per cent of surveyed users say they are ready to delegate product sourcing and payment execution directly to automated software agents.

    Shifting Margins for Marketplaces and Merchants

    For marketplace operators, the gap between zero subscription income and higher computing overhead creates a clear operational mandate: platforms must extract savings from headcount and advertising yield. Merchant partners shoulder these costs when platforms bake automated tooling fees into standard transaction commissions and marketing auction prices.

    Regional brands face inventory risks if automated comparison agents direct buyer volume entirely to discounting algorithms. Retailers that rely on brand loyalty rather than programmatic price optimization stand to lose checkout shelf space to rival sellers indexed directly into AI buying agents.

    Sector Shifts Across Transport and Media

    Online media revenue, covering digital advertising and streaming formats, is on track to advance 22 per cent to $44 billion this year as ad engines improve conversion rates. The regional ride-hailing and food delivery segment is forecast to gain 15 per cent to $40 billion in gross merchandise value, backed by voice-assisted booking tools.

    Travel bookings are expanding as well, with the online travel market projected to grow 10 per cent to $59 billion in gross merchandise value this year as travelers build itineraries via automated search assistants.

    Consumer confidence in regional software tools is rising alongside adoption. The study found 62 per cent of respondents trust artificial intelligence applications more than they did twelve months earlier, even as overall per-capita usage in Southeast Asia remains at 10 per cent of United States volume.

    Singapore Leads Deployment as Trillion-Dollar Target Looms

    Singapore is among Southeast Asia’s early leaders in AI adoption.

    The immediate marker for digital commerce leaders remains the year-end shopping quarter, where merchants will test whether AI-assisted search traffic sustains the projected run toward the $368 billion regional digital gross merchandise value milestone.

  • Hyundai Glovis Partners with Shopee to Serve 700 Million E-Commerce Users

    Hyundai Glovis Partners with Shopee to Serve 700 Million E-Commerce Users

    Hyundai Glovis began operating an end-to-end logistics partnership with Shopee Korea this month, taking over the complete supply chain for domestic cosmetics brands expanding abroad.

    The agreement links the freight forwarder to Shopee’s customer base of about 700 million users across Southeast Asia, Taiwan and Brazil, packaging international shipping into a single contract.

    Announced on Monday, the collaboration handles cross-border operations as Hyundai Glovis targets raising non-affiliated business to 40 percent of its total revenue by 2030.

    Consolidating the Cross-Border Chain

    Under the arrangement, merchants receive a single service point covering domestic cargo pickup in South Korea, air and ocean line-haul, export-import customs clearance, in-country regulatory filings and destination fulfillment. Previously, cosmetics labels contracted separate logistics handlers for domestic trucking, international freight and destination deliveries. That fragmentation created handoff delays and customs clearance bottlenecks at regional entry ports.

    Cross-border cosmetics exporters regularly encounter divergent health authority approvals across Southeast Asian jurisdictions, where labeling regulations and ingredient clearances vary between markets. Handling domestic regulatory compliance directly allows merchants to avoid third-party agency handoffs that routinely slow inventory onboarding.

    Diversifying Beyond Captive Car Hauling

    For Hyundai Glovis, handling consumer parcel flow serves a long-term commercial balance sheet target. The company wants non-affiliated commercial contracts to generate 40 per cent of its total corporate revenue by 2030.

    Carriers serving South Korean e-commerce have historically struggled with unit economics on low-weight parcel shipments compared to bulk automotive and industrial cargo. Running cross-border beauty logistics shifts Glovis into higher-frequency retail operations, competing against dedicated regional integrators and postal networks. Success depends on whether consolidated freight pricing beats the decentralized local forwarders merchants currently use.

    Export Demand Drives Freight Integration

    South Korean cosmetics manufacturers have leaned harder into direct platform exports as consumer appetite for premium skincare formulas climbed across Southeast Asia and Latin America. Rather than building local retail store footprints or signing sole distributorships, mid-tier beauty labels increasingly use marketplace storefronts to test market appetite before committing physical capital.

    Shopee operates dominant marketplace market shares across Southeast Asia, alongside expanding operations in Brazil. Supplying those territories with consolidated freight infrastructure gives platform sellers predictable delivery timelines against local beauty retail alternatives.

    Next Steps for Latin America

    Initial rollouts focus on South Korean sellers fulfilling consumer orders into Southeast Asian markets. The companies plan to extend the service footprint into Brazil and other Latin American territories once operations across the primary Asian hubs stabilize.

    Execution hinges on Glovis meeting delivery timetables while building non-captive freight volume toward that 2030 target.

  • Shopee and Magalu Form Marketplace Partnership in Brazil

    Shopee and Magalu Form Marketplace Partnership in Brazil

    Singapore-based e-commerce platform Shopee agreed this week to a commercial partnership with Brazilian retailer Magazine Luiza to cross-list inventory on two online marketplaces.

    The agreement allows Magazine Luiza, known as Magalu, to sell its first-party catalog directly through Shopee while integrating Shopee products into its own digital ecosystem.

    Integrating Distribution Networks

    Shopee operates one of the largest marketplace channels in Southeast Asia and has built a substantial local seller network in Brazil. Magalu brings established national warehousing, electronics retail relationships, and durable goods fulfillment across South America.

    By listing core retail lines on Shopee, Magalu gains immediate exposure to Shopee’s high-frequency mobile user base. Shopee secures direct access to Magalu’s consumer appliance inventory and established local distribution channels without taking on independent inventory risk.

    Shifting Marketplace Alliances

    Marketplace tie-ups between major regional operators reflect a broader change in international e-commerce strategy. Rather than competing head-to-head across every category, platforms are pooling traffic and distribution strengths to protect margin profiles.

    For regional operators in Asia and Latin America, cross-platform merchant access lowers customer acquisition costs while defending market share against global rivals. The operational risk rests on technical integration, fulfillment speed, and commission splits between the two platforms.

    Commercial Trajectory

    Shopee entered Brazil as part of Sea Group’s international expansion outside Southeast Asia, shifting over time from cross-border deliveries toward local merchant networks. Magalu has steadily broadened its digital platform to defend its home market position.

    Platform teams are currently integrating merchant catalogs and seller tools ahead of the combined marketplace rollout.

  • DBS Cuts Sea Target as Shopee Spending Weighs on Profit Growth

    DBS Cuts Sea Target as Shopee Spending Weighs on Profit Growth

    DBS cut its target price for Sea Ltd this week after heavier spending at e-commerce unit Shopee curbed near-term earnings growth across Southeast Asia. The downward revision reflects higher costs tied to defending market share against rival marketplaces in key regional markets.

    Shopee has stepped up investments in user subsidies, live-commerce infrastructure, and logistics fulfillment networks. Those operational costs eat directly into consolidated group margins at parent company Sea Ltd, which also operates digital entertainment platform Garena and digital financial services arm Monee.

    Spending Pressures Mount in Southeast Asian E-Commerce

    Competition across Southeast Asian retail platforms remains intense as regional players compete aggressively on pricing, merchant commissions, and delivery speeds. Shopee continues to defend its market leadership by funding merchant incentives and livestream promotions to counter expanding rivals across four regional markets: Indonesia, Vietnam, Thailand, and Malaysia.

    Marketplace spending has risen sharply as operators prioritize transaction volume and buyer retention over immediate margin expansion. For suppliers and consumer brands, this rivalry preserves promotional support and discounted channel fees in the near term. For equity investors, however, elevated operational expenditures delay Sea’s transition toward sustained profitability.

    Balancing Market Share and Bottom-Line Margins

    Sea previously shifted toward aggressive cost rationalization to achieve bottom-line profitability before re-accelerating platform investments to protect user growth. The latest valuation adjustment reflects the drag that recurring promotional campaigns place on overall operating cash flows.

    The central operational risk rests on whether platform spending generates sticky consumer loyalty or merely buys temporary gross merchandise volume. If merchant take rates do not rise sufficiently to offset shipping subsidies and livestream discounts, operating margins will remain under pressure.

    Prior Restructuring and Current Market Realities

    Sea previously trimmed corporate headcount, exited secondary overseas markets in Latin America and Europe, and narrowed operating losses across its non-core divisions. The return to higher investment levels highlights how difficult it is to pull back spending while competitors continue to subsidize platform transactions.

    Investors and market analysts will look closely at Sea’s next quarterly earnings filing for updates on adjusted EBITDA margins, sales and marketing expenses, and average order values across Shopee’s core Southeast Asian territories.

  • ShopeeFood Launches in the Philippines Across Metro Manila

    ShopeeFood Launches in the Philippines Across Metro Manila

    Shopee launched its food delivery service ShopeeFood in the Philippines on September 16. The country is now its fifth market in Southeast Asia.

    The service is starting in Metro Manila. It embeds restaurant ordering straight into the main Shopee app to reach millions of existing e-commerce shoppers.

    Integration inside the main platform

    Instead of releasing a standalone app, the company built food delivery directly into its primary interface. Users can browse menus, track couriers, and complete orders without leaving the core app. The feature links to the ShopeePay digital wallet. It also lets diners spend and earn Shopee Coins on meals.

    Early restaurant partners include McDonald’s, Pizza Hut, Domino’s, Taco Bell, Dairy Queen, Krispy Kreme, and Potato Corner. For now, the rollout covers only selected areas and user groups across the capital region.

    Challenging the delivery duopoly

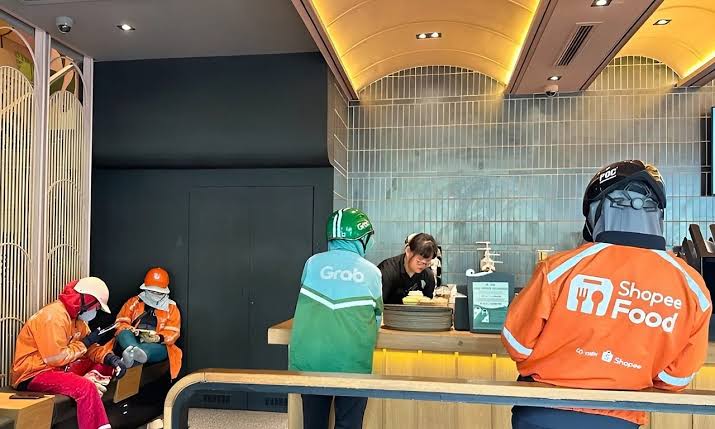
    ShopeeFood enters an urban market long dominated by GrabFood and foodpanda. Housing food delivery inside a high-traffic retail app lowers customer acquisition costs. But moving meals demands tighter dispatch networks and faster rider fulfillment than parcel logistics.

    Restaurant operators gain immediate use on merchant commission fees with a third major delivery platform in play. The real test will be rider retention and delivery speeds during peak lunch and dinner hours, when rivals already run dense fleet networks.

    The regional playbook

    This Philippine debut mirrors the operational strategy Sea Limited used in Indonesia and Vietnam. In those markets, the parent firm tied food delivery to e-commerce to boost daily active users and drive transactions through its digital finance channels.

    Pilot testing began in early September ahead of the official September 16 release. The service will expand to more districts across Metro Manila in the coming weeks before determining rollouts outside the capital.

  • Indonesia Moves E-Commerce Seller Tax Collection Forward to October 1

    Indonesia Moves E-Commerce Seller Tax Collection Forward to October 1

    Indonesia will require major e-commerce platforms to collect income taxes directly from merchant sales starting October 1. The decision pulls the policy forward by one month across a 71 billion dollar digital retail sector.

    Four major marketplaces fall under the mandate: ByteDance-controlled Tokopedia, Sea Limited’s Shopee, Alibaba-backed Lazada and local operator Blibli.

    Tax Collection Brought Forward After Cabinet Switch

    The accelerated rollout follows the removal of former finance minister Purbaya Yudhi Sadewa. President Prabowo Subianto appointed veteran technocrat Suahasil Nazara to lead the ministry in his place. Suahasil becomes Prabowo’s third finance minister in less than two years.

    Tax authorities designated the four platform operators as official withholding agents in July. Platforms were initially scheduled to deduct taxes from seller earnings in August. Implementation was abruptly put on hold.

    Bimo Wijayanto, head of the finance ministry’s tax department, confirmed the October 1 start date to domestic media. Regulatory preparations and technical systems between the state and platforms are complete, he said.

    God willing, we will immediately activate the regulation and implementation. They are ready, we are ready. There’s no drama.

    Reversal of the August Implementation Delay

    This decision unwinds a delay granted on August 5. Purbaya had postponed the withholding rule to November 1 to protect consumer purchasing power and domestic merchants. At the time, the tax office pledged to refund any levies collected prematurely.

    Internal policy friction preceded the leadership change. Prior to his dismissal, Purbaya clashed with senior ministry officials, including Bimo, over the transfer and reassignment of hundreds of department personnel.

    With Suahasil installed at the ministry, the tax office moved quickly. Officials decided to secure digital commerce revenues immediately rather than wait for November.

    Operational Pressure Shifts to Platform Merchants

    Shifting the withholding burden to marketplaces forces hundreds of thousands of independent merchants into direct compliance. Until now, tracking revenue from decentralized digital storefronts relied on self-reporting by shop owners. That system left large volumes of domestic transactions outside the formal tax net.

    For platform operators, the rule demands automated calculations and real-time deductions from merchant payouts. Tokopedia and Shopee process the vast majority of consumer volume in the country. Tokopedia, which combined its Indonesian operations with TikTok Shop and retains GoTo as a minority shareholder, now shares market exposure with Shopee if small vendors migrate sales to unmonitored social channels.

    Gross margins for small merchants selling consumer goods, fashion and electronics will narrow once deductions begin. Established brands operating under corporate tax structures face little disruption. Micro-sellers running on thin markups will have to raise retail prices or absorb the levy.

    Southeast Asia’s Largest Digital Economy

    Indonesia is the central growth engine for digital commerce in Southeast Asia. Industry estimates from Google, Temasek and Bain & Co valued the country’s e-commerce gross merchandise value at 71 billion dollars in 2025. Projections show that figure reaching 140 billion dollars by 2030.

    Tax administrators view expanding digital retail as an essential revenue source for state spending priorities under Prabowo. Traditional retail faces sluggish household demand. Closing tax gaps between physical stores and digital storefronts has become an urgent fiscal target.

    Marketplace platforms are currently issuing technical guidelines and updating seller dashboards ahead of the October 1 launch. Merchant groups will monitor vendor reactions across all four designated portals as automated deductions go live.

  • Taiwan Phishing Losses Hit NT$54.5 Million as Scammers Target Shopee and Momo Users

    Taiwan Phishing Losses Hit NT$54.5 Million as Scammers Target Shopee and Momo Users

    Phishing losses in Taiwan surged to NT$54.51 million ($1.71 million) across 505 cases last month, driven by fake merchant alerts and impersonations of leading online marketplaces. The surge came even as overall telecom and internet fraud dropped 22.3 per cent nationwide to 10,652 cases.

    Data released by the National Police Agency’s Criminal Investigation Bureau shows phishing cases doubled from 253 incidents in the same month last year. Financial damages grew more than fourfold from NT$13.05 million over the same period, even while total nationwide fraud losses fell 35.1 per cent to just over NT$4 billion.

    How Scammers Target Online Shoppers

    Fraud networks are shifting tactics from crude mass outreach to targeted retail spoofs. The bureau identified recurring schemes where scammers pose as customer service agents or merchants from platforms like Shopee and Momo. These messages claim abnormal orders, pending refunds, duplicate billings, or mandatory membership profile updates.

    Victims receive links mimicking official digital storefronts to capture payment credentials and credit card details. Other widespread lures involve bogus telecommunications and transport notices, warning consumers about expiring loyalty points or unpaid parking fees.

    Traps also include fake application portals for international travel documentation, including Thailand’s Digital Arrival Card, the US Electronic System for Travel Authorization, and the UK Electronic Travel Authorization. Links frequently direct targets into private chats on the Line messaging app, where scammers instruct users to scan QR codes, initiate ATM transfers, or authorize cardless cash withdrawals.

    The Operational Risk for Marketplaces

    For marketplace operators in Taiwan, rising phishing volumes threaten brand trust and checkout conversion rates. When attackers clone legitimate merchant workflows, consumers become wary of regular notification channels, SMS reminders, and standard email receipts. That friction hurts cart completion and slows customer adoption of direct digital payment flows.

    Retailers face rising support overheads as their customer service teams deal with disputing victims who believe they interacted with verified platform representatives. The fraud shift shows syndicates are abandoning broad investment tricks in favor of everyday transactional touchpoints, raising pressure on platform operators to harden merchant verification and URL defenses.

    Enforcement Push and Tracking Numbers

    Taiwan authorities previously reported fraud losses topping NT$6 billion for the comparable month last year, prompting joint awareness drives with private sector operators and public figures. Deputy Commissioner Chiu Shao-chou outlined the latest operational numbers alongside actor Harry Chang at a bureau briefing in Taipei, urging shoppers to manually type official URLs instead of following unsolicited message prompts.

    Platform operators and law enforcement are now tracking whether cross-agency link-takedown programs can cut phishing figures back below the 300-case mark in the final quarter.

  • TikTok Shop U.S. Gross Merchandise Value Hits $15.1B

    TikTok Shop U.S. Gross Merchandise Value Hits $15.1B

    TikTok Shop generated US$15.1 billion in gross merchandise value across the United States in 2025, up 68 per cent from the previous year, according to data from Momentum Works.

    The expansion established the platform as a major cross-border sales channel for Chinese manufacturers and domestic sellers, defying regulatory pressure and intense competition from Amazon and Temu. ByteDance built the platform by merging creator live streams and algorithmic product discovery into a direct checkout experience that bypasses traditional search-based retail.

    Expanding Across Core Retail Categories

    Fashion, beauty, and consumer electronics drove the bulk of U.S. Order volumes through short-form video links and creator storefronts. Lower take rates and subsidized shipping helped recruit thousands of merchants who previously depended solely on Amazon Seller Central.

    Supply chain infrastructure handled larger fulfillment runs through partnered logistics networks in California and Texas. The platform shortened delivery windows for local inventory while maintaining discounted direct air-freight routes from hubs in Shenzhen and Yiwu.

    The Content Commerce Blueprint in Asia

    ByteDance perfected this shopping model across Southeast Asia before scaling it westward. Regional content commerce across Southeast Asian markets is on track to reach US$77.9 billion in 2026 as Shopee and Lazada roll out competing live video formats.

    In Indonesia, Vietnam, and Thailand, social video transactions now account for a double-digit share of total online retail spending. Regional logistics networks adjusted their sorting hubs to manage high-volume, low-ticket parcels generated during evening live stream flash sales.

    Competition and Regulatory Targets

    Temu, operated by PDD Holdings, continues to fight for identical budget-conscious consumer dollars with aggressive discount coupons and gamified referrals. Meanwhile, Sea Limited’s Shopee invested heavily in creator incentives across Southeast Asia to defend its core market leadership against ByteDance.

    Merchants face rising advertising costs on the platform as competition for feed placement stiffens. RetailNews Asia tracks whether TikTok Shop can maintain its merchant retention rates through the 2026 holiday shopping cycle while targeting US$20 billion in North American sales.

  • Shopee Expands Local Fulfillment Network Across Southeast Asia and Taiwan

    Shopee Expands Local Fulfillment Network Across Southeast Asia and Taiwan

    Shopee is overhauling its logistics network across Southeast Asia and Taiwan. The push aims to cut transit times and protect delivery margins across its core marketplace.

    The Singapore-based platform, owned by Sea Group, uses a mix of in-house couriers, third-party fulfillment centers, and external delivery networks. These teams process merchant orders across multiple regional hubs.

    How the routing model operates

    Merchants use a split fulfillment model. They either ship directly from their own facilities or hold stock inside platform-managed hubs. Storing fast-moving inventory near dense urban areas cuts transit distance and speeds up dispatch. Automated systems then route each parcel to external couriers or internal fleets based on carrier capacity, pricing, and destination.

    Surges during promotional events like 11.11 and 12.12 test this setup. Shopee handles these spikes by enforcing strict cut-off windows. It also synchronizes warehouse picking schedules with local freight partners.

    Cross-border friction and last-mile costs

    Last-mile transport remains the most expensive link in regional logistics. Island geography in Indonesia and the Philippines creates delivery hurdles. Heavy traffic in capital cities adds further friction, forcing platforms to run separate delivery setups for urban and rural buyers. Cross-border consignments face extra delays from customs clearance and import duties, requiring close coordination with regional freight handlers.

    Marketplace operators across the region face steady pressure to balance speed against parcel subsidies. Moving higher volumes through dedicated fulfillment nodes lowers per-package handling costs. It also helps platforms retain larger brand merchants.

    Sellers are now preparing inventory allocations for year-end shopping campaigns, setting up the network’s next operational test.