Tag: supply chain

  • Thai Chamber of Commerce Urges Raw Material Imports to Defend Food Exports

    Thai Chamber of Commerce Urges Raw Material Imports to Defend Food Exports

    Thailand must permit regulated imports of agricultural raw materials to supply export-oriented factories, the Thai Chamber of Commerce warned this week as persistent domestic shortages squeeze food processing operations.

    Poj Aramwattananont, chairman of the chamber, said the shortfall hinders exports despite the country’s advanced infrastructure in cold storage, sterilisation and canning. “To support the Kitchen of the World, we must enable imports for export-oriented production,” said Mr Poj.

    The bottleneck affects established exports of fresh chicken, processed poultry and tuna, alongside 1 rapidly growing export sector: pet food manufacturing. In addition to raw material deficits, agricultural water management issues continue to limit local supply, preventing domestic production from keeping pace with processing lines.

    Opening Inbound Supply for Export Lines

    Poj proposed setting up regulated import channels specifically for raw agricultural goods destined for re-export after processing, balancing factory demand without depressing domestic farmgate prices.

    Industrial processors operate sterilisation autoclaves and continuous-feed canning lines designed for steady volume. When local farms miss delivery quotas because of seasonal water shortages, these industrial plants run below capacity, driving up the fixed cost per unit on finished export goods.

    Food security has shifted into a top global priority as trade routes face recurring disruption from armed conflicts. Sourcing inputs from outside Thailand allows packaging plants to fulfill overseas retail contracts while domestic agricultural reform remains slow.

    Shifting Formulations to Functional Ingredients

    Visit Limlurcha, vice-chairman of the chamber, said post-pandemic consumption patterns require local processors to shift development toward health, innovation, and environmental criteria.

    Functional ingredients represent the fastest-moving segment of this shift, prompting negotiations between industry groups and the Thai Food and Drug Administration to approve specific ingredient health claims on packaged retail labels.

    Maintaining export margins will also require biological upgrades at the farm gate. Visit said agricultural programs must prioritise targeted plant breeding for disease and pest resistance alongside livestock lines engineered to withstand recurring epidemics.

    Diversifying Culinary Exports Past Staple Dishes

    Restaurateurs and consumer packaged goods brands face similar product concentration risks on retail shelves abroad. Thaniwan Kulmongkol, president of the Thai Restaurant Association, said export campaigns rely too heavily on familiar recipes like pad Thai, leaving regional food styles unmonetised.

    Coordinated marketing through bodies like the Tourism Authority of Thailand could pull lesser-known regional recipes into standard restaurant formats and commercial retort packaging.

    Processing plants already possess the technical equipment to produce shelf-stable regional meals. Without sustained access to raw fish, poultry cuts, and specialised farm inputs, those lines cannot run the production runs necessary to displace cheaper regional competitors.

    The Policy Hurdle Facing Factory Floor Inputs

    Thai agribusiness groups have historically operated behind protective trade walls designed to preserve local farmer margins. The chamber’s call exposes a growing divide between rural agricultural producers and industrial export manufacturers who need cheap, predictable inputs to defend supermarket shelf space.

    If the government grants tariff exemptions or streamlined permits for processing-bound agricultural inputs, factory owners can run their sterilisation and canning operations at planned capacity. If the trade restrictions stay intact, regional processors in neighbouring markets with direct maritime trade access will absorb that volume.

    The Thai Food and Drug Administration continues discussions on labelling rules for functional products, while cabinet review of agricultural import mechanisms remains pending.
  • Malaysia Health Ministry Probes Gardenia Bakeries over Illness Reports

    Malaysia Health Ministry Probes Gardenia Bakeries over Illness Reports

    Malaysia’s Ministry of Health launched an investigation into Gardenia Bakeries (KL) Sdn Bhd this week following consumer complaints linking two core packaged products to food poisoning. Regulators are running laboratory tests on collected samples and preparing follow-up inspections at the company’s production plant to verify compliance with the Food Act 1983.

    The inquiry focuses on Gardenia Original Classic White Bread and Twiggies Choc-A-Lot snack rolls, two staple packaged bakery lines distributed nationwide. Health officials sought a formal explanation from the commercial baker after digital media reports and social postings documented consumers suffering vomiting and diarrhoea.

    In response, Gardenia submitted an internal review indicating zero process deviations or standard operating breaches across its facilities.

    Factory Controls Under Scrutiny

    Gardenia’s internal review concluded that production lines maintained full compliance with food safety controls. The company reported finding no recipe modifications, process deviations or procedural breaches at its plants.

    Ministry investigators noted that product traceability remains constrained because batch numbers and expiry dates submitted by complainants were incomplete. Health officials nevertheless gathered remaining products along with original packaging directly from consumers to conduct microbiological and chemical assays.

    Supply Chain and Retail Exposure

    Packaged bakery goods rely on rapid inventory turns and short shelf-life distribution networks across convenience stores, hypermarkets and petrol stations. Any confirmed contamination or mandatory recall disrupts retailer shelf allocations and exposes FMCG distributors to immediate inventory write-offs.

    Gardenia operates as the dominant industrial baker in the Malaysian retail landscape, commanding substantial market share. For commercial retailers, bread represents high-frequency basket traffic, meaning supplier compliance checks and fast inventory tracking are critical to ringfencing store liability.

    Enforcement Under the Food Act

    Health officials clarified that the manufacturer’s internal review does not constitute a definitive finding. The ministry reiterated that regulatory enforcement steps will follow if laboratory outcomes identify contamination or legal non-compliance.

    Regulators instructed affected consumers to report incidents through the SiSPAA public complaints management system and seek clinical treatment at local health centres. The outcome of the ministry’s laboratory analysis will determine whether health authorities order a formal product recall or issue factory-level sanctions under the Food Act 1983.

  • EU Trade Talks Put Thai Seed Rules and Farm Costs in Focus

    EU Trade Talks Put Thai Seed Rules and Farm Costs in Focus

    Negotiations for a free trade agreement between Thailand and the European Union have brought intellectual property standards for agriculture to the fore, with Brussels proposing alignment under the 1991 International Convention for the Protection of New Varieties of Plants (UPOV 1991).

    Adopting the framework could lift domestic crop production costs by up to 1,000 baht per rai and push consumer prices for rice-based products up by 4%, according to projections cited by Aat Pisanwanich, a lecturer at Rangsit University’s Institute of Economics.

    As of November 2026, Thailand regulates plant varieties under its Plant Varieties Protection Act of 1999 and has taken no formal stance on accession, even as regional trade partners prepare bilateral pacts scheduled for implementation through 2027.

    The Cost Burden on Farm Inputs and Shelf Goods

    Seed procurement represents between 10 per cent and 15 per cent of total crop production costs in Thailand, based on operational metrics from the Thai Seed Trade Association. Shifting to international breeder mandates would alter those balance sheets quickly. Production costs for staple paddy rice would increase by 125 to 500 baht per rai, while feed corn costs would rise by 200 to 800 baht per rai. Industrial sugar cane crops face added outlays between 250 and 1,000 baht per rai, and tapioca expenses would jump by 125 to 500 baht per rai.

    For food manufacturers, feed millers, and grocery distributors, these upstream increases squeeze operating margins along the retail supply chain. The projected 4 per cent consumer price increase on packaged rice and processed grain products comes as food retailers across Southeast Asia work to contain shelf inflation. While commercial seed companies argue that stronger intellectual property laws spur private research and development, commercial buyers face immediate procurement pressure.

    Regional Precedents Across Southeast Asia

    Vietnam provides an operating precedent for what happens when a regional farm exporter signs the agreement. Hanoi acceded to UPOV in 2006 before implementing its bilateral trade pact with the European Union in August 2020. Commercial breeders increased their registered local varieties by 50 per cent following accession. Seed prices for those protected crop lines rose six to eight times above standard open varieties, concentrating input supply among licensed private distributors.

    India took a divergent path by rejecting UPOV membership entirely, relying instead on its domestic protection framework under the World Trade Organization TRIPS agreement to protect farmers alongside commercial breeders. That stance did not block market access: New Delhi concluded its free trade agreement negotiations with the European Union, with formal signing scheduled for 16 December 2026. Meanwhile, Indonesia adopted the 1991 standards with bespoke domestic exemptions as it prepares for its EU trade pact to take effect in January 2027.

    Legislative Conflicts and Breeder Rights

    Commercial seed houses maintain that greater intellectual property protection will not distort open-market retail pricing if variety choice expands. The Thai Seed Trade Association wants the government to amend the 1999 domestic act by clarifying the legal definitions of general domestic plant varieties, preventing companies from claiming existing public germplasm while establishing protection for newly engineered strains. The group also advocates retaining legal allowances for smallholders to save seed supplies across seasons.

    Thidakoon Saenudom, director of the Plant Standard and Certification Division at the Agriculture Department, argued for explicit state backing for public cultivation pipelines. “The government must allocate sufficient funding for plant breeding R&D to ensure that publicly developed varieties remain available as an alternative for farmers.”

    Trade negotiators in Bangkok continue to review the agricultural chapter of the European trade text without taking a formal accession stance. Commercial operators and packaged food brands are tracking the ministerial review of draft exemption clauses, which will establish whether staple cereal grains receive statutory carve-outs before final bilateral ratification schedules are set.

  • Aldi to Reach 150 China Stores by End of 2026

    Aldi to Reach 150 China Stores by End of 2026

    Aldi is doubling its store expansion pace in China to reach 150 outlets nationwide by the close of 2026. The German hard-discount chain expects to launch around 60 locations this year, roughly twice its annual total from earlier years, China chief executive Jacqueline Chen said in an interview published this week.

    Expanding from Shanghai into Jiangsu

    The company operates more than 70 stores in Shanghai and over 50 across the southern region of Jiangsu province. Most locations run on a compact footprint of roughly 1,000 square meters, carrying about 2,000 stock-keeping units. Over 90 percent of those goods are private labels, allowing the retailer to bypass third-party distributors and strip out wholesale markups.

    To support that density, Aldi recently brought online its third major warehouse in East China, located in Nanjing. Supply chain capacity must be built before entering a new market, Chen said, pointing out that the distribution hub will let the company launch regional branches faster while balancing logistics costs, speed and inventory resilience.

    The Psychology of the Ten Yuan Anchor

    Price architecture drives the operational model. Between a quarter and a third of all products on Aldi shelves in China sell for less than CNY10 (USD1.49). Merchandise buyers identify the band between CNY9.90 and CNY12.90 as the critical psychological threshold to secure impulse basket additions, with shopper conversion dropping steeply once single-item pricing crosses CNY13.

    Domestic rivals including Kinglomo, Mart Fresh and Sanjiang Shopping Club are competing aggressively around the same ten-yuan price point. Across Chinese retail, discount formats and membership warehouse clubs remain the sole grocery models gaining share in an otherwise strained consumer environment. Warehouse clubs serve mid-to-high-income households buying in bulk, leaving discount supermarkets to mop up high-frequency foot traffic with low-cost daily necessities.

    Supplier Margins and Format Risk

    Aldi is betting that intense urban density inside the Yangtze River Delta can insulate it from the deflationary price battles hurting conventional hypermarkets. Big-box grocery chains across eastern China have struggled with large physical footprints and costly vendor fees, creating opportunities for smaller neighborhood stores. By leaning on local manufacturing for proprietary labels, the chain protects gross margins that traditional grocers lose to national brand allowances.

    The risk sits in category depth and supplier stickiness. Regional domestic operators have copied the limited-assortment private-label model with faster localized sourcing cycles, while suppliers face shrinking margins under Aldi’s cost-plus purchasing contracts. If identical ten-yuan staple goods saturate local wet markets and convenience chains, retaining customer traffic will require constant product rotation rather than price cuts alone.

    Building Out East China Footprint

    Aldi entered the Chinese mainland market in 2019, initially using cross-border e-commerce before setting up physical neighborhood locations across Shanghai. Over the subsequent five years, it calibrated its assortment from imported European specialty foods toward domestic hard discount, steadily pushing out of Shanghai’s central wards into secondary cities across Jiangsu.

    The immediate benchmark is the completion of the 2026 expansion schedule, which requires delivering the remaining pipeline of the planned 60 openings to hit the 150-store fleet total before the close of December.

  • Only 35 Percent of Gazipur Garment Factories Open on Friday

    Only 35 Percent of Gazipur Garment Factories Open on Friday

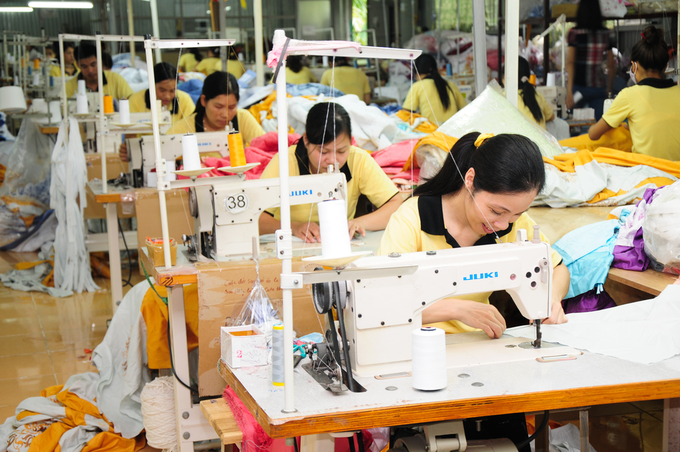
    Garment manufacturers in Gazipur operated only 35 percent of their production facilities on Friday as widespread factory shutdowns sent assembly line workers home across Bangladesh’s core apparel belt.

    Amjad Hossain, superintendent of Gazipur Industrial Police, confirmed the operating rate at 10:00am, leaving roughly two-thirds of the district’s export factories idle along key transport arteries including the Dhaka-Mymensingh Highway.

    Workers emptied out of the Taragachh industrial zone early in the morning after plant managers declared two-day closures. Ananta Garments suspended work at its Taragachh site, directing staff to leave the compound. Matrix Sweater in the Hajipukur area similarly halted operations for two days, citing local tensions.

    Uneven Operations Across the Cluster

    Disruptions remained selective rather than total across the manufacturing cluster. Parkstar Apparels and Parksin Bangladesh kept lines running in Barabari and Gachha, logging standard morning shift arrivals without incident.

    Freight corridors showed little physical obstruction despite the stoppages. Traffic Inspector Tarikul Islam reported clear vehicle movement through the Chandana Chourasta interchange, with commercial freight lanes operating normally throughout the morning.

    Sourcing Risks for International Buyers

    Sourcing directors across Europe and North America face immediate production bottlenecks when Gazipur pauses. The industrial hub accounts for a major share of Bangladesh’s readymade garment exports, serving global mass-market fashion brands that run tight inventory turns.

    When plants declare sudden multi-day shutdowns, delivery schedules for spring collections slip, forcing suppliers to absorb air freight penalties or renegotiate shipment windows. Sourcing desks at global fashion retailers are already monitoring South Asian capacity after months of volatile operating conditions in Dhaka’s satellite hubs.

    Production Continuity in Question

    Factory floors in Gazipur have experienced repeated friction between management and labour over working conditions, wage settlements, and local safety. Industrial police superintendent Amjad Hossain noted that Saturday coincides with a scheduled government holiday, giving operators a natural operational pause.

    A decision on whether garment factories would remain closed on Saturday would be announced this afternoon.

  • Acer Targets 15% Consumer PC Growth in Taiwan Despite Rising Component Costs

    Acer Targets 15% Consumer PC Growth in Taiwan Despite Rising Component Costs

    Acer expects consumer PC shipments in Taiwan to increase by more than 15 percent in 2026, driven by Singles’ Day discount promotions and strong year-end demand.

    The Taipei-based hardware manufacturer matched that run rate through the first 10 months of the year, reporting 15 percent annual volume growth across the local domestic market.

    Rising component prices, particularly for memory and silicon modules, pushed average retail selling prices higher across the sector. Acer Taiwan brand product and marketing manager Wu Ke-chien said revenue growth would outpace unit volume gains as hardware manufacturers pass procurement inflation on to shoppers. The company is maintaining its target for shipment expansion above 15 percent through November and December despite component delivery bottlenecks.

    Component Crunch Reshapes Hardware Margins

    Processors, dynamic random-access memory and solid-state storage expanded to represent about 68 percent of the bill of materials for a 900-dollar mainstream notebook by late 2026, up from 45 percent early last year. Conventional memory contract prices are forecast to rise another 10 to 15 percent in the fourth quarter, while flash storage is projected to increase 15 to 20 percent. Preserving gross margins on comparable consumer hardware under those input cost conditions requires retail list price increases approaching 80 percent.

    Shortages are acute for discrete graphics cards and select mainstream central processors. Acer global headquarters allocates available inventory centrally across world territories, restricting local commercial pipelines. Discrete graphics models generate between 15 and 18 percent of Acer consumer notebook transactions in Taiwan, though company management targets 18 to 20 percent if component allocations improve.

    Assembly Moves Back to Mainland Plants

    Component inflation is forcing Asian electronics brands to reconsider their Southeast Asian manufacturing footprints. Rising memory expenses led brands including Acer, Asus and HP to transfer select consumer laptop assembly back to mainland Chinese facilities from factories in Thailand and Vietnam. The shift unwinds part of the diversified production footprint established across Southeast Asia amid US-China trade tensions.

    Total notebook production outside mainland China is slipping from 24 percent of global volume in 2025 to 21 percent in 2026, with research projections tracking a drop below 20 percent by 2027. Major Taiwanese original design manufacturers like Quanta Computer, Compal Electronics and Inventec are redirecting floor space toward server hardware. Enterprise servers accounted for over 80 percent of Quanta revenue in the second quarter of 2026, freeing PC contract orders for Chinese assemblers such as Luxshare Precision Industry, Huaqin Technology and Longcheer Technology.

    Display Niches and Retail Lineup Expansion

    Consumer demand patterns in retail channels are fragmenting into specialized hardware segments. Alongside artificial intelligence laptops, tablets and ultra-lightweight notebooks introduced for the Singles’ Day retail period, Acer expanded its portable external monitor portfolio with screen sizes between 14 and 23.8 inches. Portable screens secured a 20 percent share of Taiwan’s total external mobile display market, creating an unexpected retail volume driver.

    Securing low-cost silicon remains the deciding factor for regional consumer electronics margins. HP and Dell were qualifying DRAM from Chinese domestic supplier ChangXin Memory Technologies during 2026, while Acer and Asus asked Chinese production partners to source memory for some notebooks.

    Acer reported its strongest second-quarter revenue performance in 13 years earlier in July 2026, followed by a seasonal tablet shipment rebound in September. Full-year local results hinge on whether retail sales volume during the November Singles’ Day promotions and December holiday shopping cycles can hold the targeted 15 percent growth rate against rising shelf tags.

  • Robinsons Retail Expands Network Beyond 4,800 Outlets Across the Philippines

    Robinsons Retail Expands Network Beyond 4,800 Outlets Across the Philippines

    Robinsons Retail Holdings Inc. Now runs over 2,700 branches alongside more than 2,100 franchised pharmacy locations nationwide. Group president and chief executive officer Stanley Co leads the business alongside chair Robina Gokongwei-Pe and director Lance Gokongwei.

    Franchised storefronts under TGP The Generics Pharmacy form the 2,100-door network, while core corporate banners cover food, drugstores, department stores, hardware, appliances and electronics, toys, mass merchandise, beauty, pet retail, lifestyle sneakers and motorcycles.

    The business trace its start to a single Robinsons Department Store launched in Ermita in 1980 by late founder John Gokongwei Jr., who opened the retail location himself after prospective department store tenants declined to lease space in his commercial center.

    Scale Across Formats

    Today the multi-format structure handles volume purchasing across distinct supply chains, from neighborhood pharmaceuticals to shopping mall anchor units.

    Gokongwei-Pe, who entered the business in 1984 as a warehouse receiving clerk, logged 41 years of service alongside James Go at 46 years and Lance Gokongwei at 38 years. Go serves as vice chair, while Lance Gokongwei leads parent conglomerate Gokongwei Group.

    Logistics Realities and Operating Margins

    Running separate formats under one corporate umbrella forces Robinsons Retail to balance differing margin profiles and supply chain complexities. Grocery, pharmacy and mass merchandise demand rapid inventory turnover and tight distribution cycles, whereas fashion, footwear and consumer tech expose working capital to higher holding costs and obsolescence risk.

    Rival operators like SM Retail maintain denser exposure to large-format department stores and hypermarkets, whereas Robinsons has pushed aggressively into franchised medicine counters and neighborhood specialty niches. That pharmacy exposure delivers defensive cash generation when discretionary spending contracts, but franchise networks offer lower revenue per square meter than corporate-owned flagship boxes.

    Early Mechanics at Ermita

    Initial operations relied on basic manual systems and decentralized stock control. At the Ermita depot, manual inventory clerks handled physical receiving and handwritten documentation on carbon paper without automated backup power systems or barcode logistics. The group has since replaced those manual processes with central procurement workflows, integrated vendor management and dedicated inventory tracking across regional distribution hubs.

    Lance Gokongwei began on the department store floor ticketing apparel during the late 1980s before joining executive management. The group recently recognized 85 staff members who have spent 25 years or more with the operating company.

    Next Capital Milestones

    Management attention remains fixed on store expansion density across provincial growth corridors outside Metro Manila, particularly through drugstore additions and community supermarket footprints. Investors will track whether the retail holding firm can lift trading margins across its non-food retail banners as supply chain automation and direct vendor programs roll out nationwide.

  • Bridgestone Pushes Mining Tire Plants to Full Capacity

    Bridgestone Pushes Mining Tire Plants to Full Capacity

    Bridgestone is operating its specialized factories for large mining and construction equipment tires at nearly full capacity in November 2026, prioritizing high-margin lines to capture demand generated by artificial intelligence infrastructure.

    Output at the Tokyo-headquartered manufacturer’s Kitakyushu plant centers on ultralarge units that stand more than twice the height of an average person, built for heavy haulage operations.

    Management is directing industrial bandwidth toward off-the-road equipment servicing suppliers of copper, a critical conductor for data centers. The allocation links factory scheduling directly to capital expenditure across global digital infrastructure, where data facilities and related power equipment continue to drive raw metal extraction.

    Kitakyushu Capacity and Heavy Mining Volumes

    Industrial machinery tires represent one of the highest-margin categories in the global rubber sector. Producing them requires specialized curing presses and custom tooling, which limits how quickly competing manufacturers can match capacity spikes.

    Bridgestone has centered this production run on vehicles that service open-pit mines, where trucks transport hundreds of tons of ore per cycle. The wear rate on these sites requires steady tire replacement schedules, giving suppliers with immediate factory availability an advantage in long-term fleet contracts.

    By prioritizing massive haulage tires over standard industrial lines, the company protects operating margins against persistent raw material inflation. The specialized compound and steel cord formulations used in Kitakyushu command pricing power that consumer vehicle lines lack.

    Equipment Makers Expand US Support

    Equipment builders linked to the same mining corridors are expanding field support at a matching pace. Komatsu is moving to triple the size of its maintenance hub in the United States to handle repair work for mining machinery deployed across North American copper pits.

    The machinery maker raised its profit outlook on construction and mining demand across the Americas, while its finance leadership confirmed plans to increase equipment shipments into the region.

    Japanese heavy equipment suppliers are consolidating sales operations across regional corridors to protect market share. Trading house Itochu reached an agreement to acquire the Taiwan sales unit of Hitachi Construction Machinery, tightening its control over distribution channels as industrial equipment demand rotates across Asian and trans-Pacific logistics routes.

    Rival Pressures Across Automotive Segments

    Bridgestone is managing this mining ramp-up while its core consumer tire business faces low-cost competition across Asia. Japanese competitors are redirecting capital to counter cost-efficient Chinese manufacturing platforms.

    Yokohama Rubber is setting up lower-cost production facilities targeting BYD and other Chinese electric vehicle manufacturers. That strategy seeks volume at narrower margins, contrasting with Bridgestone’s capital allocation toward specialized, high-tonnage mining contracts.

    Bridgestone has simultaneously pursued alternative commercial formats in its home market. The company put its airless tire technology onto public roads in Japan following nearly two decades of technical trials, looking for durability gains in light urban transport while mining lines absorb heavy industrial investment.

    Capital Allocation and Fleet Exposure

    Focusing plant operations on copper extraction exposes Bridgestone to cyclical risks in metals demand. If data center buildouts slow or power grid procurement stalls, mining fleets quickly idle haul trucks and defer replacement orders.

    For now, lead times on heavy earthmover tires remain extended across North America. The immediate operating risk sits in factory flexibility, as running Kitakyushu near ceiling levels leaves little headroom if machinery failures interrupt production lines.

    Bridgestone’s operating balance sheet reflects the pivot toward high-specification industrial components. Maintaining nearly full utilization at Kitakyushu gives the manufacturer pricing use with global mining houses through the next contracting round.

  • DFI Directs over Half Its AI Efforts to Merchandising Across 7,600 Stores

    DFI Directs over Half Its AI Efforts to Merchandising Across 7,600 Stores

    DFI Retail Group is directing more than half of its artificial intelligence work towards business transformation, reinvention and innovation, prioritising merchandising across its network of over 7,600 stores in 12 Asian markets. Speaking at the Retail Asia Summit 2026 in Hong Kong, Stijn Casneuf, data & AI automation director, warned that retailers spreading investments across too many simultaneous use cases risk missing measurable returns.

    “Retailers need to focus on initiatives that deliver tangible value rather than adopt AI simply because it is gaining traction,” Casneuf said. Merchandising receives the largest share of attention because improvements directly influence both revenue and profitability, with remaining resources directed to internal productivity gains.

    DFI launched AI supply chain forecasting around one-and-a-half years ago, blending internal enterprise data with weather metrics and holiday calendars to lift prediction accuracy. Having begun restructuring fragmented data systems a year ago to enable effective scaling, the pan-Asian operator is now recording its first wave of operational benefits.

    Building the AI Control Tower

    To coordinate the roll-out, DFI established an internal AI Control Tower comprising representatives from people and culture, technology and cyber security, finance, corporate communications, legal, and AI. The team assesses proposed initiatives against business priorities, shareholder value, customer trust, and team member impact before evaluating technical fit, security, and legal requirements.

    The Control Tower reports directly to the Management Committee, with updates also provided to the board. Casneuf said this structure helps the company concentrate resources on a prioritised set of high-value projects. “We are also taking a hybrid approach to large language models (LLMs), assessing Chinese and Western models according to the requirements of each application,” he added.

    Fixing the Master Data Floor

    DFI’s AI strategy spans four areas, covering merchandising, customers, and storefront store support centres. On the customer side, the group is exploring how the technology can improve product discovery and shopping journeys across digital channels.

    The group is piloting large language models to generate product descriptions by drawing on enterprise resource planning (ERP) data and predefined market best practices. With millions of stock-keeping units across its banners, commercial and master data teams validate the AI-generated descriptions rather than writing them manually, improving searchability and catalogue discovery.

    The Enterprise Automation Race

    Beyond current workflow pilots, Casneuf indicated that DFI is monitoring longer-term shifts in consumer interaction and autonomous ordering technologies. “Agentic shopping remains at an early stage, but DFI has a clear strategy for how customers could eventually use AI agents to shop through its own platforms,” he said.

    The disciplined deployment model reflects a broader shift among regional mass merchants seeking to extract verifiable financial returns from machine learning rather than maintaining speculative laboratory tests. By grounding deployment in core data restructuring and strict executive oversight, DFI is positioning automated forecasting and automated catalogue administration at the center of its regional operations.

    Early Replenishment Results

    DFI began restructuring data processes a year ago and is now starting to see the first wave of benefits. As the company continues to advance, it expects to unlock even greater value and impact across its 12 regional markets.

    RetailNews Asia will track whether DFI’s agentic shopping pilots move from internal tests into live customer applications during upcoming fiscal periods.

  • 7-Eleven Opens 2000Th Store in Guangdong as DFI Expands Network

    7-Eleven Opens 2000Th Store in Guangdong as DFI Expands Network

    Convenience chain 7-Eleven opened its 2,000th store in China’s Guangdong province. The milestone extends the operator’s footprint across 14 cities in the southern economic hub.

    DFI Retail Group manages the franchise network in Guangdong, where it introduced the brand more than three decades ago. The business set up its initial outlet in Shenzhen in 1992.

    Southern expansion

    Building out a network of 2,000 stores in a single Chinese province required navigating shifting municipal planning rules and fierce competition from domestic convenience operators. DFI concentrated on tier-one and tier-two cities, anchoring its business in dense residential clusters, transit hubs, and commercial office towers.

    The current footprint spans 14 municipalities across Guangdong. Shenzhen continues to hold a high concentration of outlets, providing the scale required to support dedicated cold-chain logistics and daily fresh-food replenishment.

    Fresh food and proprietary brands

    Scale in the convenience sector depends on recurring basket margins rather than packaged dry goods alone. DFI targeted daily foot traffic by building out ready-to-eat hot food counters, bakery selections, and proprietary private-label lines that yield higher margins than third-party inventory.

    Store profitability increasingly leans on these prepared meals and exclusive beverage tie-ups. Fast product turnover helps offset elevated commercial real estate leases in major southern commercial hubs, where convenience stores compete directly with local street stalls and regional chains.

    Rival networks and regional pressure

    Guangdong represents one of the most crowded retail arenas in mainland China. Regional domestic operators run thousands of smaller franchised stores across suburban and residential districts, forcing foreign-backed chains to defend prime central locations.

    Landlords in high-traffic transport nodes hold significant use during lease renewals. Operators that fail to extract strong revenue per square metre face rising operational friction, particularly as utility overheads and local store labour expenses increase across southern metropolitan areas.

    Franchise density across the province

    DFI established its first mainland foothold in Shenzhen during the early phase of southern China’s retail liberalisation in 1992. Over the following decades, the group progressively built a supply-chain apparatus capable of sustaining daily inventory cycles across adjacent manufacturing and consumer centres.

    The provincial network expanded before accelerating sub-tier city penetration. That gradual rollout laid the foundation for the current 14-city coverage map.

    Attention now turns to store density in lower-tier municipalities outside Shenzhen, where DFI faces the operational challenge of matching delivery economics against lower average consumer tickets.

  • BMW Reports 11% Drop in Pretax Profit as Restructuring Hits Margins

    BMW Reports 11% Drop in Pretax Profit as Restructuring Hits Margins

    BMW reported an 11% drop in third-quarter pretax earnings to €2.1 billion ($2.4 billion), warning that restructuring costs will depress its core automotive operating margin to between minus 0.5% and 0.5% this year.

    Chief executive Milan Nedeljkovic announced plans to speed up structural cuts, including 8,000 layoffs in Germany, after issuing the group’s second profit warning in less than five months late on Tuesday.

    Quarterly revenue slid 6% to €30.4 billion as sales in China fell 22% across the first nine months of the year, pressuring core automotive margins down to 3.4% from 5.2% a year earlier.

    Margin Pressure Across Asian Showrooms

    German premium brands face an unprecedented squeeze in China, where aggressive price cuts by domestic electric vehicle manufacturers have eaten away foreign market share. BMW’s operating performance reflects that erosion directly. Excluding the one-off restructuring charges, management expects an underlying margin above 2%, down sharply from its historic operational corridor.

    Rival Mercedes-Benz likewise booked lower earnings for the third quarter. Porsche managed a small rebound after previous model overhaul charges, though it continues to scale down exposure to mainland buyers. Foreign vehicle importers can no longer rely on Chinese dealership networks to generate outsized cash flow to bankroll global operations.

    Factory Reorganisation and Export Reorientation

    Chief executive Milan Nedeljkovic is reorganising the group’s manufacturing footprint to protect returns. BMW plans to localise component supply chains and technical development inside China, turning its mainland assembly lines into an export hub targeting wider Asia-Pacific territories.

    Current developments in our industry call for decisiveness and swift implementation. We will therefore specifically intensify and accelerate structural measures.

    The revised regional framework also introduces tailored product lines elsewhere. The carmaker plans an expanded range of large luxury sport-utility vehicles for US buyers and an entry-level platform designed specifically for Europe.

    The Neue Klasse Rollout

    This revision marks the second profit warning BMW delivered within five months. Operating margins in the core vehicle division had held at 5.2% during the third quarter of last year before aggressive domestic discounts in China wiped out dealer pricing power across Tier 1 and Tier 2 cities.

    The company now relies on its new architecture to stop the slide. Deliveries of the Neue Klasse platform begin in China this month with the retail launch of the electric iX3, setting up a critical test for Nedeljkovic’s long-term margin target of 8% to 10%.

  • Yamato Holdings to Raise Delivery Fees for Major Corporate Clients

    Yamato Holdings to Raise Delivery Fees for Major Corporate Clients

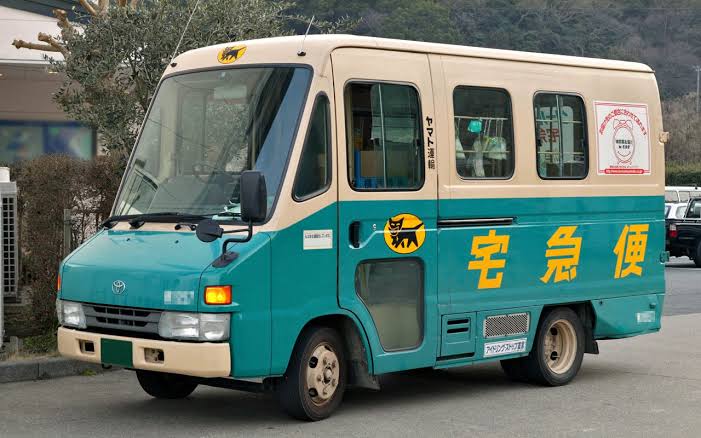
    Japanese parcel carrier Yamato Holdings will negotiate price increases with major corporate clients across Japan as it pivots from chasing delivery volume to shoring up operating profits.

    President Toshiyuki Sakurai told Nikkei that the strategy shift aims to lift slim margins in the group’s core express delivery division by rightsizing operations.

    The move lands as Yamato Holdings targets leaner operations, deploying artificial intelligence tools to optimize parcel routing while trimming network capacity across its domestic terminal base.

    Pruning Delivery Capacity

    Yamato plans to trim its domestic transportation network, deploying artificial intelligence tools to optimize parcel routing across sorting terminals. The carrier handles the bulk of consumer e-commerce drop-offs in Japan, where persistent driver shortages and rising vehicle fuel expenses have squeezed operating returns.

    Passing higher line-haul expenses onto large corporate accounts marks a deliberate break from volume-first carrier contracting. Corporate accounts that secured steep volume discounts during earlier e-commerce surges must now absorb steeper per-box handling fees or reconfigure their dispatch schedules.

    Squeeze on Online Merchants

    For online retailers and marketplace sellers operating across Tokyo and regional hubs, carrier fee increases hit order economics directly. Merchants who built free-shipping tiers around discounted express carrier contracts will either raise minimum checkout thresholds or swallow narrower gross margins.

    Rival carriers face identical wage pressures under tightened domestic overtime rules. When Yamato lifts commercial rates, competitors typically follow rather than absorb discounted volume, preventing merchants from shopping freight accounts across town.

    The Operational Pivot

    Yamato historically expanded depot capacity to absorb peaks from domestic e-commerce platforms. That footprint carried heavy capital outlays and overhead costs when box growth decelerated.

    The company now uses routing algorithms to consolidate regional sorting points, matching truck dispatches to daily manifest volumes rather than running fixed-capacity transport lanes.

    Contract Talks Ahead

    Annual freight negotiations with primary corporate shippers represent the immediate operational hurdle for Sakurai. The company will test its bargaining power when contract renewal rounds open across its largest enterprise accounts.

  • Apple Shares Fall 4% as Rising Memory Costs Threaten Gross Margins

    Apple Shares Fall 4% as Rising Memory Costs Threaten Gross Margins

    Apple shares dropped about 4 per cent in premarket trading on Tuesday, putting the tech giant on track to lose over $170 billion from its $4.94 trillion valuation. The decline followed executive warnings that escalating memory component costs will squeeze profitability.

    Chief Executive John Ternus delivered his first earnings report on Monday, describing the current memory-pricing climate as “unprecedented” and cautioning that cost pressures will extend beyond the quarter ending in December. The company expects gross margins for the period to slip to between 45 per cent and 46 per cent.

    That guidance marks a contraction from the 47.9 per cent gross margin reported for the September quarter, even after factoring in tariff refunds. The cost squeeze comes as Apple exhausts the advantage of earlier, lower-priced memory inventories, leaving fresh hardware manufacturing exposed to higher market rates.

    Component Inventories Diminish

    The hardware manufacturer had managed production costs throughout 2026 by tapping stockpiles of memory purchased under earlier, cheaper contracts. Those reserves are now depleted. Fresh component purchases reflect elevated spot and contract rates, exposing hardware production directly to wholesale price spikes.

    Rising memory bills arrive alongside operational expenses from rolling out generative features across the Siri ecosystem. Apple must now pay more for core memory silicon inside every handset while spending heavily on server infrastructure to process assistant queries. For regional consumer electronics retailers, higher component inputs point toward wholesale price increases across upcoming device cycles.

    Flagship Demand Carries Fourth Quarter

    The margin compression follows a record September quarter for iPhone revenue despite broader consumer spending headwinds. Handset sales reached $57.58 billion, clearing market forecasts of $56.54 billion.

    Apple achieved that total using a staggered device launch that offered only the top-tier 18 Pro models during the final days of its fiscal 2026. The baseline Duo models did not ship during the period. The reliance on premium tiers cushioned top-line numbers, but it narrows the cushion available when factory-gate component bills climb across every tier.

    We see the flagship iPhone as the linchpin of this ecosystem, from which Apple derives pricing power, switching costs, and a network effect

    Valuation Gaps and Supply Chain Risks

    The company enters the holiday quarter trading at nearly 35 times expected 12-month earnings. That multiple sits well above rival tech platforms, with Alphabet trading at 18.23 times and Microsoft at 23.43 times forward earnings. Such a premium leaves little leeway when gross margins contract by two to three percentage points.

    Device vendors across Asia face identical supply crunches, yet Apple commands the balance-sheet scale to secure volume allocation ahead of smaller competitors. If higher retail tags depress consumer upgrade cycles across key Asian markets, hardware revenue will take the brunt of the downturn.

    The immediate indicator remains gross margin execution for the December-ending period, where management must hold the guided 45 per cent floor while absorbing continuous memory cost revisions.

  • Samsung Secures AMD and Nvidia Orders for 2.7 Million-Square-Foot Texas Plant

    Samsung Secures AMD and Nvidia Orders for 2.7 Million-Square-Foot Texas Plant

    Samsung Electronics will dedicate its second semiconductor plant in Taylor, Texas, to manufacturing base dies for high-bandwidth memory chips destined for AMD and Nvidia. Industry sources reported this week that the South Korean company has already booked orders covering the facility’s total planned capacity ahead of ground breaking.

    AMD accounts for the majority of the secured volume at the site, where formal construction is scheduled to begin this month.

    The plant will cover about 2.7 million square feet, roughly 1.5 times the size of Samsung’s first Taylor facility, which holds a supply contract with Tesla, and will deploy an advanced 2-nanometre manufacturing node.

    Plant Footprint and Production Schedules

    Equipment installation will start in February 2029. Commercial mass production will follow in 2030.

    Samsung Electronics declined to comment on the customer allocations and production timelines. The company previously dedicated its initial Taylor plant to automotive and computing contracts, including work for Tesla.

    Pressure on the AI Hardware Chain

    Base dies form the foundation of high-bandwidth memory stacks, acting as the logic layer that links dynamic random-access memory directly to high-performance graphic processing units. Securing dedicated foundry capacity for these components removes a critical choke point for server makers, data platform operators and consumer tech hardware vendors that rely on fast graphic processors.

    Committing the plant entirely to external graphic chip designers locks Samsung into heavy capital deployment years before revenue flows. Cleanroom tools and extreme ultraviolet lithography systems must be ordered and amortised on schedules that leave little room for client order cancellations. The operational risk sits squarely on yield rates: running a 2-nanometre node at scale has challenged every major foundry in Asia, and transferring that production overseas amplifies tooling and labour risks.

    Shifting Rivalries and Customer Locks

    Tesla already anchors work at Samsung’s first Texas site, giving the Korean group an industrial base in North America across autonomous transport and machine-learning processors. Expanding in Texas matches broader attempts by Asian hardware giants to build manufacturing capacity inside the United States, positioning supplies closer to American enterprise buyers.

    The Long Run to 2030

    Heavy site preparation in Taylor now shifts to foundation work this month, with cleanroom completion targeted ahead of the February 2029 tool installation date.

  • Chinese Capital Pours 4.5 Billion Dollars into Vietnam Manufacturing

    Chinese Capital Pours 4.5 Billion Dollars into Vietnam Manufacturing

    Chinese and Hong Kong investors registered 4.5 billion dollars in capital across 1,104 new Vietnamese projects in the first nine months of 2026, targeting industrial supply lines.

    Bilateral trade between China and Vietnam expanded 37.6 per cent year on year to exceed 253 billion dollars during the same nine-month period, following a full-year total of more than 256 billion dollars in 2025.

    Factory Lines Take the Bulk of Inbound Funds

    Manufacturing absorbed 80.61 per cent of the registered capital committed by Chinese groups, placing China fourth among foreign direct investment sources in Vietnam. The figures, presented at the Autumn Economic Forum in Ho Chi Minh City, reveal an accelerating shift from basic merchandise exchange toward deep factory linkages.

    Cross-border commerce now relies on coordinated production networks rather than simple container shipments. Electronics assemblers and industrial component vendors are shifting sub-tier operations directly into Vietnamese industrial parks to retain tariff efficiency while drawing technical oversight from mainland supply hubs.

    Consulate Calls for Direct Process Integration

    Xu Shou, acting consul general of China in Ho Chi Minh City, said the two economies hold complementary industrial structures that demand technical coordination.

    Cooperation between Chinese and Vietnamese businesses has moved beyond traditional trade in goods into a new phase of supply chain coordination, technology exchange, and knowledge sharing

    Xu urged suppliers and downstream manufacturers to align quality control, factory automation, and workforce training. He also pressed for joint ventures in urban rail systems, digital trade infrastructure, and cross-border settlement channels.

    Sourcing Hubs Deepen Downstream Roots

    For consumer brands and contract electronics manufacturers operating across Southeast Asia, these capital commitments reduce the friction of sourcing raw components. Moving intermediate fabrication closer to Vietnamese assembly plants cuts lead times for export-bound goods, but it ties regional factory schedules even tighter to Chinese industrial design and material supplies.

    The operational risk sits squarely in logistics bottlenecks at overland crossing points. Factory operators face acute delays whenever northern border gates back up, which makes physical rail integration and unified technical customs standards the primary gating factor for factory productivity.

    Transport Corridors Form the Next Test

    Hanoi is pushing infrastructure projects to match the incoming industrial volume. Vietnamese Deputy Minister of Finance Nguyen Thi Bich Ngoc met with China’s State Council Research Office in late October, laying out five priority areas that feature the planned Lao Cai-Hanoi-Hai Phong railway line alongside smart border checkpoints.

    Regional conglomerates are building commercial networks around the trade flow. Sunwah Group, through its Sunwah Innovations unit established in 2020, runs business hubs across Ho Chi Minh City, Hanoi, and Da Nang to link early-stage technology and factory partnerships between domestic firms and mainland investors.