Author: Mei Ling Tan

  • Cashless society push will speed smart city development in Malaysia

    Cashless society push will speed smart city development in Malaysia

    Malaysia’s Malaysian Global Innovation & Creativity Centre (MaGIC), smart city enabler Cyberview and Mastercard have signed an agreement to support the Malaysian government’s push towards a cashless society.

    During the recent signing of the memorandum of agreement at the Smart City Expo World Congress in Barcelona, Cyberview’s managing director Dato’ Faris Yahaya said that a cashless society drive would help to strengthen smart city development in Cyberjaya.

    Faris said the agreement is the latest in a series of milestones achieved by Cyberjaya in its continued evolution as a Smart City.

    Recent achievements include the deployment of a city-wide long range (LoRA) network to offer an IoT lab and the establishment of its City Innovation Council (CIC) to allow startups to test out prototypes.

    “Cyberview has spearheaded the continued development of the city under its Smart City and Living Lab initiatives – development pillars designed to increase its operational efficiency, improve the quality of life for the people of Cyberjaya and contribute to growing the local economy,” added Faris.

    “We continue to do this by incorporating technology into every facet of the township through collaboration with our many partners, and this is eminent from our push in transforming Cyberjaya into a cashless city by working hand in hand with MaGIC and Mastercard,” he said.

    Cyberview, MaGIC, Mastercard
    (From left) Carlos J. Menendez, President Enterprise Partnership, MasterCard; Dato’ Faris Yahaya, Managing Director, Cyberview Sdn Bhd; Tan Sri Dr. Mohd Irwan Serigar, Secretary General of Treasury, Ministry of Finance Malaysia; Perry Ong, Country Manager for Malaysia and Brunei, MasterCard and Mr. Ashran bin Dato’ Ghazi, Chief Executive Officer, Malaysian Global Innovation & Creativity Centre (MaGIC) during the Memorandum of Understanding Ceremony at the Smart City Expo World Congress in Barcelona.


    “The reason why we’re doing this is because we understand that payments are the heart of a city’s economic activity – forming the core of every economic flow including salaries, consumer spending, business procurement, and taxes,” said Faris.

    Cashless ecosystem

    This latest agreement lists several initiatives to be rolled out by the partners to develop a cashless ecosystem in Cyberjaya.

    He said some of these include integrating Mastercard’s digital payments service Masterpass to make everyday transactions for consumers faster, simpler and more secure as well as providing city authorities and urban planners actionable data-driven insights into the retail industry and to better inform their marketing campaigns for visitors.

    These activities are in line with the government’s Economic Transformation Programme and Bank Negara Malaysia’s (BNM) vision to transform Malaysia into a cashless society.

    Ashran Dato’ Ghazi, chief executive officer of MaGIC said: “MaGIC will support the Cyberview Smart City initiative in a collaboration with both Cyberview and Mastercard. Through the Corporate Entrepreneurship Responsibility (CER) platform, MaGIC will play a key role to facilitate the partnership between players in the corporate sector like Mastercard and local entrepreneurs to design and build smart city infrastructure, services and solutions in Cyberjaya.”

    Perry Ong, country manager for Malaysia and Brunei of Mastercard, said, “Through the Economic Transformation Program, an electronic payments agenda is embedded through a structural reform known as the Payment Card Reform framework where the payment industry is working together in efforts to broaden market access and to dampen cash transactions. It is imperative that we recognise the great control, transparency and efficiency electronic payments offers to society.”

    Ong added that Mastercard will be providing the horizontal payment construct across all the vertical clusters in the Smart City including urban mobility, lifestyle, finance, health, supply chain and education among others.

    He said this will  ensure an integrated payment ecosystem for a better commerce experience with digital solutions such as “Masterpass,  which helps Malaysians to enjoy simpler, safer and smarter digital payments across any device and channel anywhere  – be it online, in app and in-store with contactless.”

    “By embedding digital payments into our core infrastructure and harnessing the data that electronic payments generate, cities can deliver on their promise to create smarter, more welcoming spaces, and empower their citizens to lead greater, more rewarding lives,” said Cyberview’s Faris.

    He said an AllianceDBS Research report earlier this year projected that the ‘cashless’ system in Malaysia will grow by 15 per cent, five-year compounded annual growth rate (CAGR), as Bank Negara Malaysia (BNM) pushes for reform in the country’s payment system.

    “We will continue to collaboratively work with our numerous ecosystem partners, including MaGIC and Mastercard to enhance the liveability of the city and provide the people of Cyberjaya with everything they will need to improve their lives,” Faris said.

  • Causeway Bay and Tsim Sha Tsui retain allure for retailers in spite of sluggish times

    Causeway Bay and Tsim Sha Tsui retain allure for retailers in spite of sluggish times

    The prime shopping hubs of Causeway Bay and Tsim Sha Tsui, among the most expensive in Hong Kong in terms of rental costs, remain attractive for retailers amid overall sluggishness in the sector.

    Retail rents in Causeway Bay fell 8 per cent in the rental index in the third quarter and 10 per cent in Tsim Sha Tsui, and they are expected to decline further next year, according to a Colliers International report.

    These declines came amid a 19-month drop in retail spending in the city, with overall sales dropping 9.6 per cent year on year in the first nine months of the year.

    Spending in Hong Kong has been depressed by an 8.7 per cent fall in mainland tourist arrivals during the period.

    The retail industry in the city as a whole is undergoing a consolidation as tourist traffic from the mainland continues to thin, pushing down shop rents in the near term, according to David Ji, the head of research for greater China at Knight Frank.

    In Hong Kong, the four major retail districts of Causeway Bay, Central, Tsim Sha Tsui and Mong Kok had all seen rental corrections, said Terence Chan, the head of Hong Kong retail at JLL.

    While Mong Kok has experienced less pressure from the flight of luxury brands, the property consultancy sees a 15 per cent correction for retail rents in the city as a whole this year.

    The decline was likely to bottom out next year with a correction of about 5 to 10 per cent, Chan added.

    He said that among the four major shopping districts, Tsim Sha Tsui would command the highest average rents in terms of gross floor area, at HK$2,000 per square foot per month. It was followed by Central, with an average monthly rent of HK$1,400 per square foot.

    Causeway Bay ranked third with an average of HK$1,200 per square foot.

    Chan said that while overseas brands would continue to focus on these four districts, established ones might seek to diversify their footprint with outlets in secondary areas such as Yuen Long.

    According to Ji, retailers will continue to favour Causeway Bay and Tsim Sha Tsui, but the trend of high-end luxury brands being ­replaced by sports, lifestyle and food and beverage outlets will continue.

    With Adidas leasing the space formerly occupied by a Coach store in Central and footwear outlet Joy & Mario replacing jewellery store Folli Follie in Causeway Bay, rents will inevitably continue to come under downward pressure.

    “We are now facing a ‘new normal’ trend,” Ji said. “It’s safe to say we are not going to see a drastic improvement. If retailers can hold their ground for the better part of next year, then it’s already a good situation.”

  • The rise and rise of property management firms in China

    The rise and rise of property management firms in China

    Virginia Huang has amassed nearly 20 years of top-level commercial real estate industry knowledge, and is the longest serving member of the CBRE team in Beijing.

    After joining the firm in 1997, she is now the firm’s managing director, and head of advisory and transaction services for Greater China

    A specialist, particularly, in the office leasing market, Huang has been involved in some of the Chinese capital’s highest profile transactions, dealing with top-tier Chinese and international developers.

    She shares her thoughts on the sea changes that have happened in China’s commercial real estate landscape, the recent rise in the amount of retail space being converted into offices, and the emergence of Beijing’s decentralised markets.

    What major changes have you seen during your 20 years in the commercial real estate sector?

    When I first entered the industry in the late 1990s, Chinese companies basically wouldn’t use our services. Our customers were primarily foreign corporations whose own corporate real estate teams were small and much more used to outsourcing.

    The traditional perception about CBRE as a company was that we were classy but aloof, dealing only with foreign clients. But we set out to convince people that was not the case, that we were straight forward, humble and down to earth, and that we had and in-depth understanding of Chinese companies and the Chinese market.

    Our domestic client base, as a result, has grown rapidly in the past few years, very much in line with the rise in size and number of many Chinese companies. There has also been a change in mindset, that they increasingly recognise the value of a professional international firm, as many are looking overseas for business.

    How can companies ensure their real estate requirements match their overall growth strategy?

    Many Chinese companies, especially technology firms, have grown so fast that often their property planning procedures has failed to keep pace, even if they do have procedures in place. But the same is often true in many mature multinationals, who might not have clear procedures in place to make these types of decision. It’s a universal problem.

    Chinese firms in this aspect do face a gap, especially when it comes to decision making: who, at what stage should they be involved? Often that is unclear. That fits their early-stage nature. But when start-ups grow larger and larger, as some now do, they will naturally shift to see leasing more as a means to attract and retain talent and improve working efficiency. In that way they would be less likely to compromise quality simply for cost.

    Workplace management should be aligned more with other departments from the start, especially with the top management and the overall strategy of the company. In terms of leasehold or freehold, there is no fixed solution. Each company has to make its workplace strategy in line with its overall strategy.

    A lot of companies have reported that finding good office space in Beijing’s central business district(CBD) is becoming increasingly difficult, and expensive – but many are unwilling to locate to less popular and cheaper sites away from the city centre. How can the problem be solved?

    Contrary to popular perception, there is plenty of supply in Beijing CBD, a lot more in fact than in the city’s Financial Street or Zhongguancun, where an office can be really hard to find.

    Also contrary to perception is that emerging markets, such as Wangjing area, have a high vacancy ratio. The vacancy ratio in Wangjing is low, and rents are not low any more.

    The problem some of these areas have in filling their space is to do with infrastructure

    Office workers in Wangjing, particularly, complain it’s hard to get to by public transport. Services and amenities, such as convenience stores, restaurants and hotels are rare.

    These types of out-of-town areas used to attract tenants with cheap rents and favourable policies. But office owners are becoming increasingly aware they cannot attract firms just by offering generous discounts. They have to do more complete the surrounding amenities, the soft environment of their markets, and more will be willing to move into them.

    With an oversupply of retail space in China, many underperforming malls are being converted into offices. Is there a danger of that too becoming oversupplied if the trend continues?

    There are two types of retail space being converted into offices: complementary retail space in bigger complexes, and whole retail buildings that are underperforming due to their poor location or poor management.

    On the first type, often their small size and flaws in design make them difficult to attract tenants. Ideally owners should be converting the second, third and fourth floors into offices, especially if higher floors are already offices.

    Whole underperforming retail buildings can be more be difficult to convert, because of their design, the position of their escalators, windows and so on. It can also be hard for there types of building to attract traditional tenants such as financial and law firms.

    I don’t think there’s an oversupply issue for now, because the trend is exclusively robust in Beijing. There is an acute supply issue in the capital, because it is nearly impossible to find new office projects in the downtown area because of policy regulations. Demand for offices here continues, unabated.

    If retail property owners invest in converting the lower levels of their buildings into office space, they will be able to earn much higher rents, than if for instance the site was leased as a restaurant. So there is a strong incentives to do so.

  • Vietnamese consumers prefer the ‘Made in Thailand’ label

    More than ever, consumers in Vietnam are looking for the ‘Made in Thailand’ label when purchasing consumer goods, and they’re willing to pay a premium for these products, according to experts.

    The high domestic demand for Thai products, they say, was the driving factor that resulted in the Thai Central Group earlier this year acquiring a controlling interest in 33 Big C Vietnam supercenters (and 10 convenience stores) and later Thai BCJ Group’s purchase of 19 Metro Vietnam superstores.

    The majority of Vietnamese consumers are willing to pay more for many key product categories, from baby food and appliances to electronics and apparel, as long as these goods were produced in Thailand, say the experts, reported Thai News Bureau.

    In each of the key categories, they say, at least 50% of domestic consumers are willing to pay a premium of more than 10%.

    More surprising, however, is the fact that the prices of Thai products are often lower than the prices of Vietnamese products of similar size and quality.

    Vu Dieu Thuan, a customer at Metro Ha Dong, says after careful consideration she chose to buy 5kg of Thai rice at US$4.71 (VND105,000) over Dien Bien rice at US$4.93 (VND110,000) because it tastes better.

    Experts say, many Vietnamese consumers report they regularly choose Thai made products over Vietnamese goods regardless of price on a regular basis.

    An assistant at the Metro in Ho Chi Minh City, points out that customers regularly purchase condensed milk from Thailand, which is US$.27 (VND 6,000) less expensive per can than Vietnamese milk.

    Only Thai clothing items are routinely more expensive than similar items made in Vietnam, says the assistant.

    Experts express the view that Thai products are positioned well in the domestic market. On the one hand they are less expensive than Japanese and Korean products of equivalent quality. On the other hand, they are of much better quality than Chinese products.

    To top it all off, they are aesthetically more appealing than Vietnamese products say the experts, adding that domestic consumers on the whole perceive Thai-made products as being of higher quality than local products. In fact, even when comparing Vietnamese and Thai products of similar price and quality, the majority of domestic consumers would still buy the Thailand-made items, they say.

    Still other experts disagree vehemently and say not so fast. Vu Vinh Phu, president of the Hanoi Supermarket Association, says Thai products are benefiting from better placement in stores like Big C and Metro.In these supercenters, says Mr Phu, the placement of retail products on shelves favors Thai products over Vietnamese products. One commonly used phrase in retail is “eye level is buy level”.Meaning that products positioned at eye level are likely to sell better. Stores like Big C and Metro are putting Thai products at eye level or just below, which is the best location and this explains in part why their sales are better.

    The location of goods within an aisle is also important, says Mr Phu. Vietnamese goods are being placed at the start of an aisle and don’t sell as well as Thai products placed in the center of the aisle. As well items placed at the end of aisles sell better because of higher visibility and Thai products are given these choice locations as well, says the Vietnam Association of Seafood Exporters and Producers (VASEP). The battle between supercenters and their placement of Vietnamese produced goods continues, says VASEP, adding they are urging Big C and Metro to give better visibility and placement to Made-in-Vietnam products.

  • Mazda Unveils the All-New CX-5

    Mazda Unveils the All-New CX-5

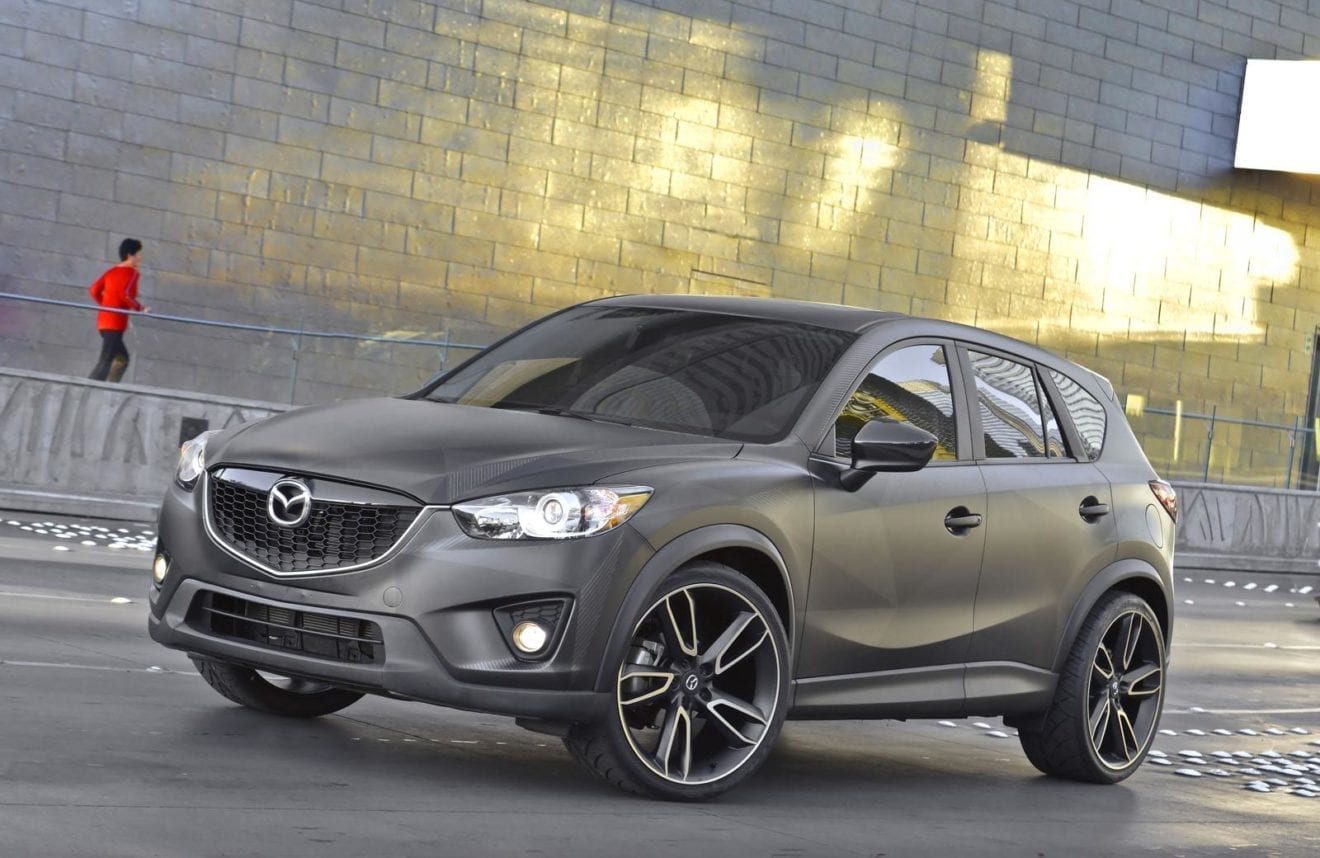
    Mazda Motor Corporation today unveiled the all-new Mazda CX-5 crossover SUV. The fully redesigned model, which refines every element of Mazda’s design and technology to offer new dimensions of driving pleasure, will be launched in Japan in February before being rolled out to global markets.

    The slogan for development of the all-new CX-5 was “an SUV all customers will enjoy,” and Mazda aimed to add a new dimension by offering driving pleasure that everyone on board can enjoy—not just the driver. The model is engineered in line with human sensibilities to deliver responsive performance that conforms to the driver’s expectations. It also prioritizes passenger comfort, with a quiet cabin and pleasant ride feel, and adopts G-Vectoring Control, the first of the SKYACTIV-VEHICLE DYNAMICS vehicle motion control technologies. Designed under the KODO—Soul of Motion design theme, the exterior is both bold and sensual, and the interior has been crafted to give occupants a pleasant feeling. The body color lineup includes the newly developed Soul Red Crystal, which highlights the beauty and quality of Mazda’s KODO designs.

    The powertrain lineup comprises the SKYACTIV-G 2.0 and 2.5 gasoline, and SKYACTIV-D 2.2 diesel engines. All three options offer powerful, linear driving performance and outstanding environmental performance.

    The all-new CX-5 will be on display at the Los Angeles Auto Show, open to the public Nov. 18-27.

    Launched in 2012, the CX-5 was the first new-generation model featuring SKYACTIV technology2 and KODO design. It has since grown into a core model that is sold in over 120 countries and accounts for approximately one quarter of Mazda’s global sales volume.3 It has won around 90 awards worldwide, including 2012-2013 Japan Car of the Year.4

    By providing driving pleasure to everybody who drives or rides in one of its vehicles, Mazda aims to enrich people’s lives and become a brand with which customers feel an emotional connection.

  • New Phuket boutique opens for Furla at Shilla Duty Free

    New Phuket boutique opens for Furla at Shilla Duty Free

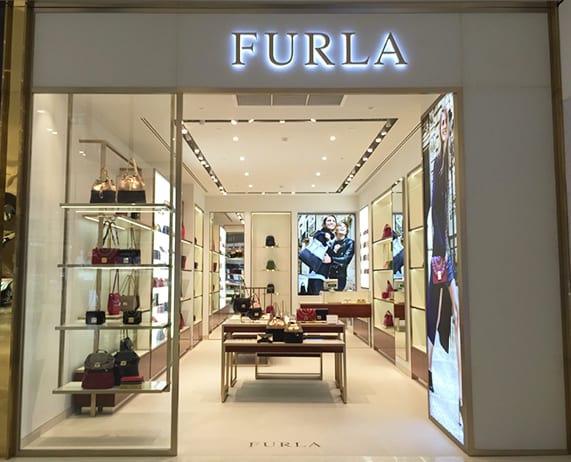
    The new boutique was officially opened last Saturday ^ featuring Furla’s Autumn and Winter 2016 Collection.

    The outlet is well lit and easily browsed with aisle room for customers to browse the wall-mounted leathergoods collections, as light boxes reinforce the brand’s product presentation and lifestyle.

    Gerry Munday, Furla’s Global Travel Retail Director said: “We thank Shilla Duty Free for their continued support of the brand.”

    Furla Phiket November 2016 Shilla
    The new boutique offering at Shilla Duty Free’s downtown store in Phuket.

    BACKGROUND TO PHUKET STORE OPENING

    It is first reported this new downtown duty free store development back in July of this year when Shilla Duty Free joint venture partner GMS Duty Free talked directly with our Asian Correspondent David Hayes.

    GMS Duty Free is the joint venture company formed by Shilla Duty Free with local partners, Gems Gallery Group and The Mall Group, to operate the store.

    The Mall Group is one of Thailand’s leading shopping mall operators with six malls, five of which are in Bangkok and one in northeast Thailand. The Gems Gallery Group is a leading Thai jewellery retailer and wholesaler with four showrooms in Bangkok, Chiang Mai, Pattaya and Phuket.


  • PCCW Global connects to Djibouti Data Center

    PCCW Global connects to Djibouti Data Center

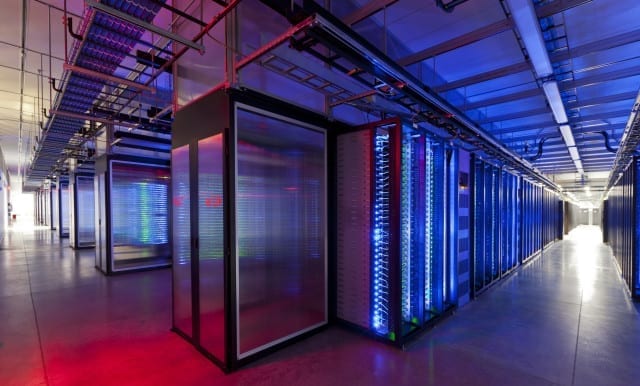
    PCCW Global, the international operating division of Richard Li-owned HKT, has selected Djibouti Data Center (DDC) to facilitate network expansion and the provision of colocation and undersea fiber cable access services in East Africa.

    The Djibouti Data Center has been built to Tier III data center standards and serves as a major meeting point for undersea fiber cable systems including the new Asia-Africa-Europe-1 (AAE-1) submarine cable designed to connect Asia, the Middle East, Africa and Europe.

    The AAE-1 system, of which PCCW Global is a founder consortium member, will employ 100Gbps technology, with a capacity of more than 40 terabits to provide customers with low-latency and direct connectivity around the world.

    The 25,000km-long submarine cable is expected to be ready for service by early 2017, connecting Djibouti with Hong Kong, Vietnam, Cambodia, Malaysia, Singapore, Thailand, Myanmar, India, Pakistan, Oman, UAE, Qatar, Yemen, Saudi Arabia, Egypt, Greece, Italy and France.

    “The addition of AAE-1 to PCCW Global’s existing undersea fiber cable assets in the region will enable us to provide even more robust services, along with lower latency and increased diversity, boosting services levels for our customers,” said Jordick Wong, senior vice president of product and vendor management at PCCW Global.

    Wong said the partnership with DDC is an important element of its wider pan-African development and expansion plans.

    It enables PCCW Global to establish cross-connect and colocation facilities directly adjacent to Djibouti Telecom’s cable landing stations. In addition to supporting AAE-1 in the near future, the DDC provides access to fiber-cable systems such as EIG, EASSy, Aden-Djibouti, and Ethiopia-Djibouti, Wong added.

  • Chinese Ride-Hailing Company Ucar Partners with BitTiger

    Chinese Ride-Hailing Company Ucar Partners with BitTiger

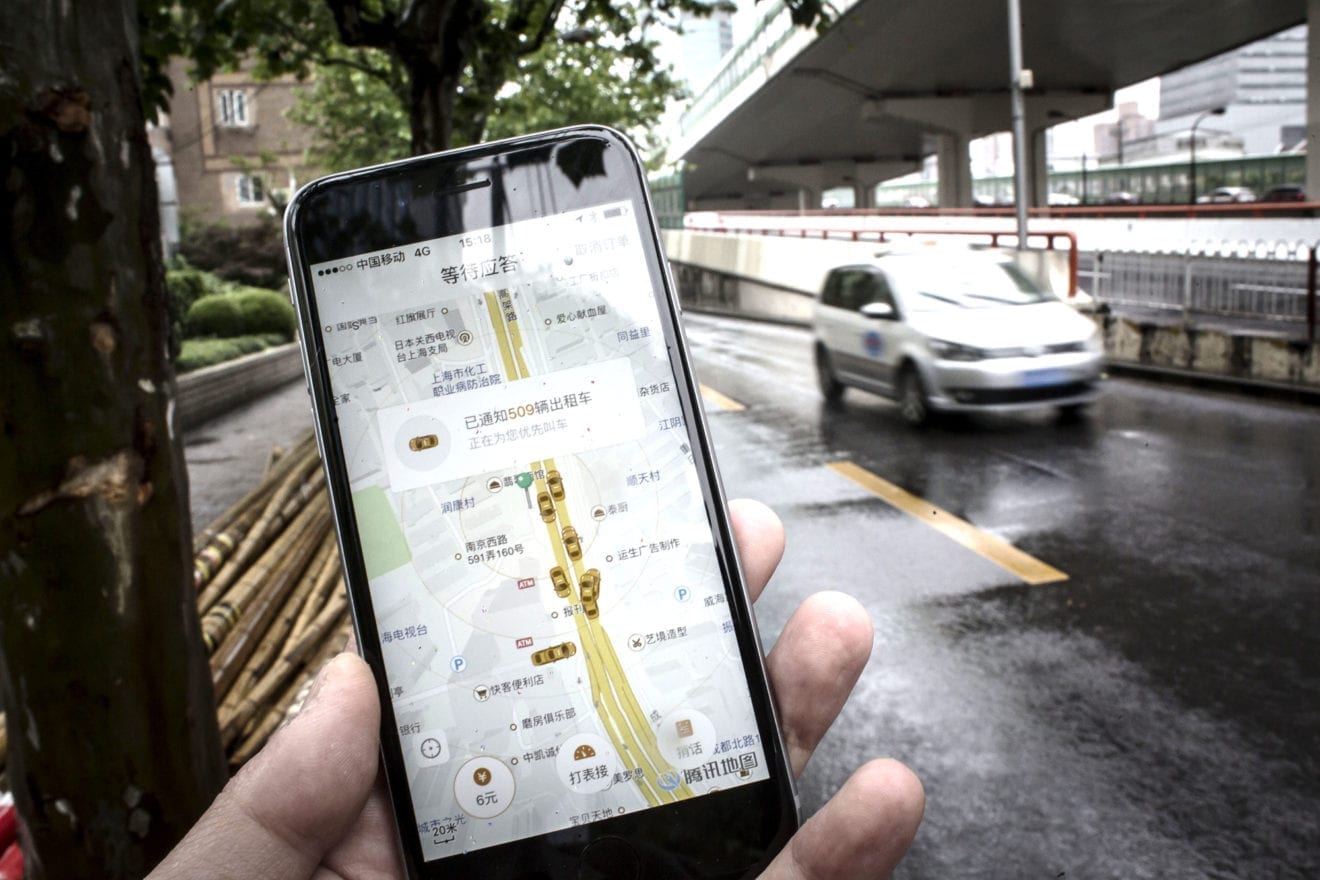
    Ucar, a major player in the Chinese ride-hailing and car rental market, has joined the global race to develop a road ready self-driving car. To compete for the best international talent, Ucar has opened a research outpost in Silicon Valley and partnered with online education platform BitTiger to host a deep-learning coding class and competition that offers winners cash prizes and a chance to interview with the company.

    Ucar (神州专车) booked approximately 15%1 of car chauffeur services in China in 2015, and are backed by Alibaba. They are based in Beijing, China and began aggressively expanding their research center in Silicon Valley last year by hiring experienced engineers from major Bay Area tech companies. The research center is part of a larger trend among Chinese companies, including tech giant Baidu, that are creating research outposts in Silicon Valley to gain a competitive talent advantage over domestic rivals.

    Ucar is responding to the huge market opportunity for self-driving cars in China where crippling traffic jams can keep city streets gridlocked for days2. Principal engineer of the Ucar Silicon Valley based research center, Zhong Hua, explains that Ucar’s self-driving car technology aims to “minimize traffic related deaths, reduce commute times, and make better use of cars left idly parked most of the day,” all goals that would have a big impact in China’s mega-cities.

    BitTiger is a US-based online learning platform for Chinese engineers that gained experience at elite tech companies to share their knowledge with Mandarin-speaking students around the world. These students are eager to gain access to a top education taught by industry experts not otherwise available to those outside of the best university programs.

    The course being launched by Ucar and BitTiger will provide candidates with fundamental knowledge of image recognition and deep learning techniques. Upon completion of the course, students will be challenged to accurately identify pedestrians, cars, and bicycles among images collected by Ucar’s test vehicles. The top three teams that most accurately and consistently identify these target objects will receive cash prizes and an opportunity to interview for a position at the Ucar Silicon Valley research center.

  • CASBAA confab debuts in Macau

    CASBAA confab debuts in Macau

    The CASBAA Convention annual conference debuted in its new venue, Studio City, Macau, marking the 25th anniversary of CASBAA which is dedicated to representing key players from the cable and satellite broadcasting industry under the motto ‘represent, inform, connect’.

    Irwin Gotlieb, the Global Chairman for GroupM, was first to take to that stage to discuss the changing nature, and measurement of viewing behaviors. He also touched upon how the way to reach audiences via the marketing funnel is the same but a granularity of data can now inform decisions for each stage of the funnel. He underscored how media will continue to play a role becoming more targetable, addressable and eventually part of the transaction process.

    Also on the subject of measurement, Ben Reneker of S&P Global Market Intelligence highlighted how machine-driven predictive measurement models are now able to inform strategic decisions on marketing and investment.

    Oliver Wilkinson, managing director for PricewaterhouseCoopers, provided statistics to illustrate that pay TV is not dead, despite what the headlines say, and that it remains a primary form of entertainment.

    Doing deals in China was the topic for Bennett Pozil, EVP of East West Bank, who discussed the migration of content both ways as well as some of the pros and cons of doing business in China.

    Reaching a vast audience through tailored video and gaming content was the topic for Chad Gutstein, CEO of Machinima who highlighted that their most valued content was when viewers felt they had a connection to the creation of it. On a video note, Ricky Ow from Turner International predicted that Machinima’s e-Sports will be as successful as the English Premier League.

    James Schwab, co-president of VICE announced the opening of the company’s first full-service office in Jakarta, Indonesia.  He discussed how their local content policy over digital channels has helped the company grow exponentially over the last few years. The recent move into TV has been important for VICE as it gives them the ability to invest more in content.

    On the second day, Dave Downey, CEO of INVIDI Technologies, illustrated how “addressable” advertising could be used to predict viewing behaviors. Basil Chua, CEO from AsiaMX, talked about the need to understand viewer habits, flagging that they are watching content not devices. Both believed that the advertising formats would result in big wins for operators.

    Intrinsically linked to the advertising discussion is the subject of measurement and Craig Johnson, Nielsen’s media managing director for South East Asia, Pacific and India, highlighted some of the current challenges OTT has presented with measurement, suggesting that viewership on other devices could represent an additional 15% to 20% of media usage that is not accurately measured yet. The introduction of smart-meters could help more accurately chart multi-device viewership and content sources.

    Content from Japan took the spotlight with Eriya Kawachi, director of sales and promotions at Club TV Japan, showcasing some platforms that have been winning in popularity outside of Japan with Club TV. Richard Woo, consultant for WAKUWAKU JAPAN, discussed how Japanese content is well known for its creativity, uniqueness and a certain wackiness.

    Korean content also featured on the agenda with Miles Ki Young Choi, founder and CEO of Bethel Group Media Contents, talking about how interactive content was key to the future, flagging interactive drama as something they were championing. Byeong-Joon Song, CEO Group 8, saw simultaneous distribution as important for Korean content, highlighting difficulties with penetrating the Chinese market and Tom Taehyun Kim, CEO and executive producer at K Production, confirmed that superb storytelling was of course essential for content to have wider appeal.

  • Global 5G subscribers to reach 500m by 2022

    Global 5G subscribers to reach 500m by 2022

    Global 5G subscriptions will grow rapidly once the technology is available, Ericsson has forecast, with the vendor predicting that subscriptions will reach 500 million by 2022.

    North America is expected to lead the way in 5G uptake, with 5G projected to account for 25% of subscriptions in the region by 2022. But APAC will be the second fastest growing region, with 5G accounting for 10% of subscriptions.

    Ericsson’s latest Mobility Report also projects that global mobile subscriptions will grow to 8.9 million, with 90% of these for mobile broadband, and 6.1 billion unique subscribers in 2022.

    As of the third quarter of this year, there were 84 million new mobile subscriptions being added per quarter, for a total of 7.5 billion. India had the most net additions for the third quarter of 15 million, followed by China’s 14 million, Indonesia’s 6 million and Myanmar and the Philippines’ 4 million each.

    By the end of 2016 there will be 3.9 billion smartphone subscriptions worldwide, Ericsson said, with nearly 90% of these registered on WCDMA/HSPA and LE networks. This is expected to grow to 6.8 billion and 95% of subscriptions by 2022.

    The report also shows that mobile video is projected to grow by 50% annually through to 2022 to account for nearly 75% of all mobile data traffic. Increased use of live video streaming to contact friends, family and followers is meanwhile expected to contribute to a 39% annual growth in social media traffic.

    Finally, the report suggests that IoT will account for around 18 billion of the 29 billion connected devices forecast by 2022.

  • AEON Your Cash awards Nissan March to lucky winner

    AEON Your Cash awards Nissan March to lucky winner

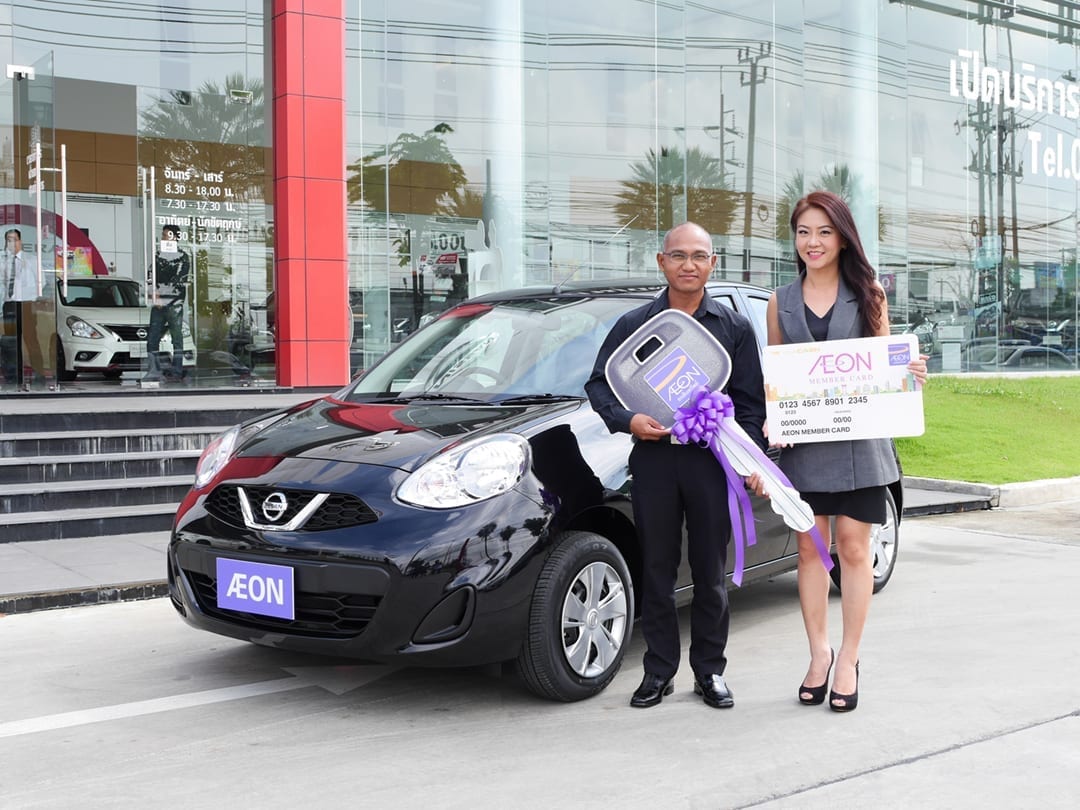
    Saranya Pipoppinyo (right), Vice President Marketing of AEON Thana Sinsap (Thailand) Public Company Limited, hands over keys to a Nissan March, valued at 451,000 baht, to Suthit Saisuwan from Sisaket, the lucky winner of the grand prize from the AEON Promotion Your Cash Car Lucky Draw campaign which had run from July 1 to September 30.

  • Gamified Trading App TradeHero’s Brand Acquired by Ayondo

    Gamified Trading App TradeHero’s Brand Acquired by Ayondo

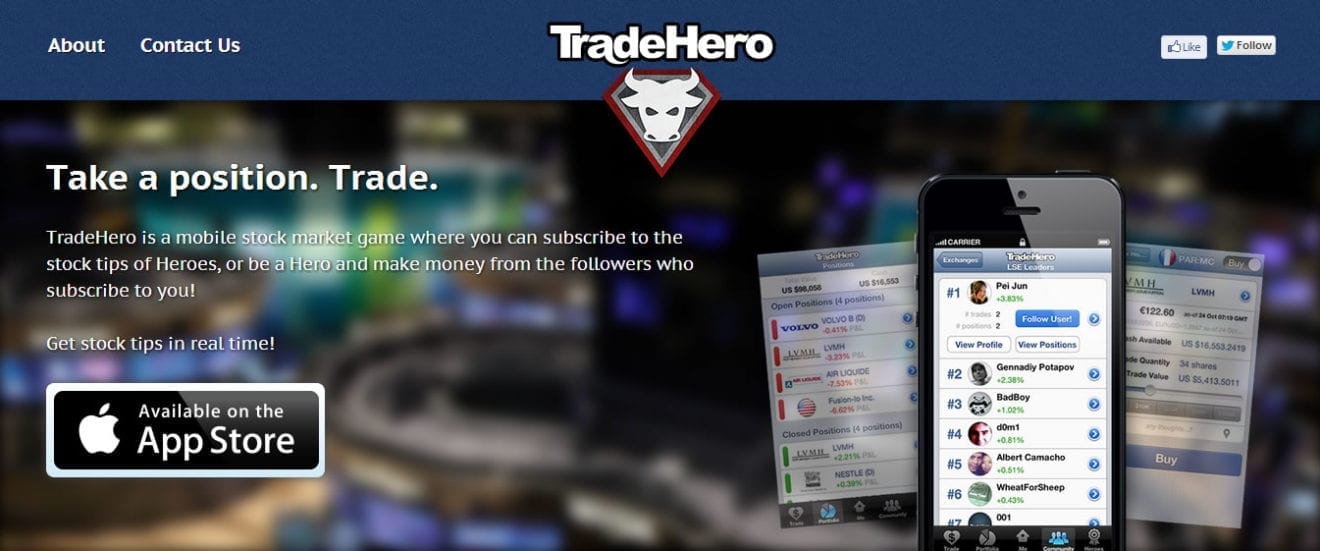
    Ayondo, a social trading technology developer for the financial services industry, has acquired the TradeHero brand, a Singapore-based trading gamification app.

    The acquisition for TradeHero’s brand outside of China and the United States, expands ayondo’s footprint in Singapore nearly a year after it announced a partnership with KGI Fraser Securities Pte Ltd to launch KGI Contrax, a platform for investors to trade Contracts for Difference (CFD).

    Robert Lempka, CEO of the ayondo Group, says: “For ayondo, mobile technology is a big part of the Group’s strategy for expansion and growth. The TradeHero brand is extremely well established in Asia and was the missing piece in our product range. Following Top Traders and taking social trading to the next level, in offering fully automated execution is exactly what is in ayondo’s DNA.”

    Dominic Morris, co-founder of TradeHero and the new Head of Innovation for ayondo Group, adds: “ayondo and TradeHero share the same vision, that is to democratise the world of investing through easy-to-use disruptive technology and knowledge sharing.”

    The team of TradeHero’s mobile technology specialists built the foundation for ayondo’s Singapore based Mobile Lab, where the group’s latest research and development takes place. The group is engaged in advanced negotiations with a SGX-listed company on a Reverse Takeover (RTO) transaction. This could result in ayondo being the first fintech company to be listed on the Singapore Exchange (SGX) and the head office being moved to Asia’s fintech hub.

  • How Nestle plans to grow in travel retail

    How Nestle plans to grow in travel retail

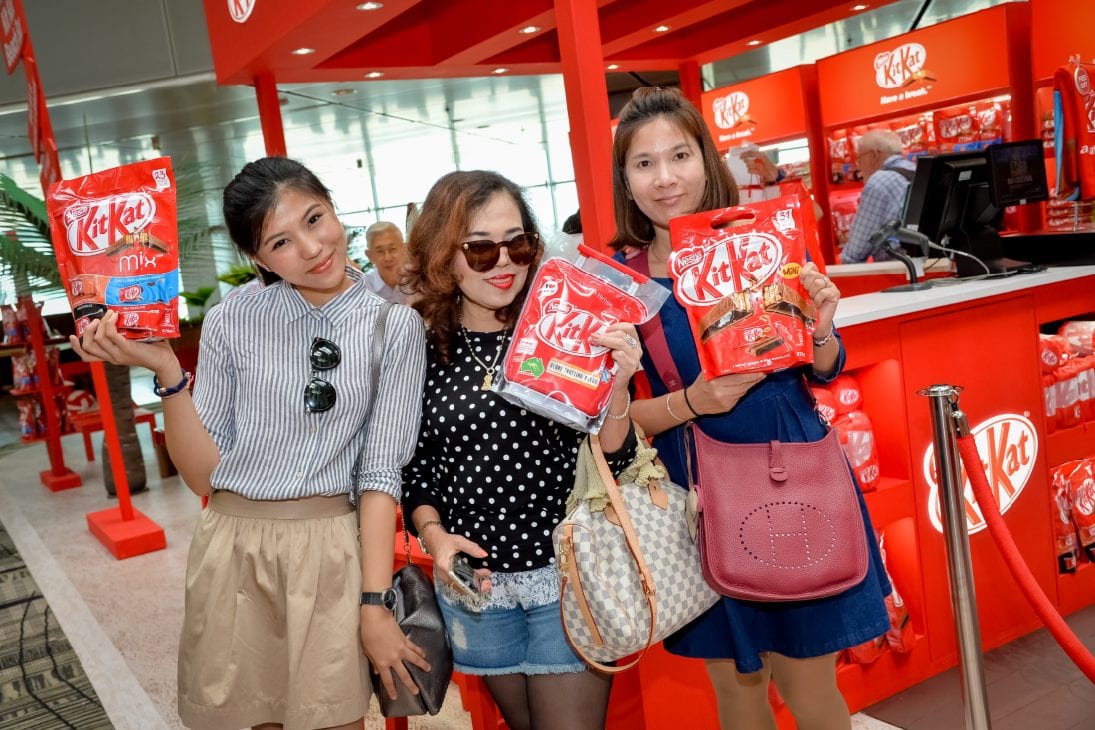
    Nestle’s travel retail unit is a US$100m-plus business, which generates the lion’s share of its revenue from confectionery. Stewart Dryburgh, who heads the company’s travel retail business, says the sector, while a small part of the Nestle empire, presents a strong growth avenue for the group. However, Dryburgh acknowledges it is also a competitive and fast-paced channel and those companies that want to cash in need to navigate some unique challenges. Katy Askew spoke to Dryburgh to find out more.

    Nestle generates more than US$100m in annualised revenues through its dedicated travel retail unit, which has gained market share since the world’s largest food maker set it up in 1999.

    The KitKat maker is aiming to capitalise on the expansion in international travel retail, which it expects to see as air travel continues to grow. “There were roughly 3.45bn individual airport travellers last year. Roughly split 50-50 between domestic and international. And that is projected in the next ten years to basically double to over 7bn by 2025,” Stewart Dryburgh, the general manager of Nestle’s international travel retail unit, stresses.

    However, this expanding consumer base makes the high-traffic sector a highly competitive one in which to operate. “Most people want to play here that is for sure,” Dryburgh says. “You have got at the moment [almost] 3.5bn people travelling through airports every year. And if you take the top 50 airports – the likes of Heathrow, Frankfurt, Singapore, Dubai, JFK – internationally there are 1bn travellers going through those airports every year. So there is a huge audience there in what is a relatively limited number of locations that they are going through.”

    Standing out in this competitive environment – especially because consumers are not expressly travelling though terminals to shop but as part of their journey – is one of the key challenges for companies operating in the sector.

    “That is a perpetual challenge no matter what channel you are in. A brand has to work hard to understand consumers needs and remain relevant. I have worked in big domestic markets like the UK, in emerging markets like India and I have looked after some of Nestle’s biggest brands including KitKat. No matter where you sit it is a challenge. Our challenge in this particular industry is to engage in a way that is relevant to the moment that consumers are experiencing. And that is a journey.”

    Of course, there are different types of journey, Dryburgh continues. This gives rise to two distinct need-states Nestle wants to meet through its travel retail range. “It may be a business journey and if they are heading out they might want to take a gift to somebody who they are going to meet, or they might be heading back and want to take something to their loved ones. You might be going off for a long weekend and you want something more snacking oriented. There is a mix if you come very specifically into the confectionery world of gifting chocolate and consumption chocolate. The whole world of millennial consumer and the emerging middle-class consumer in Asia and LatAm continually creates opportunities for us. Then it is understanding how they can be relevant.”

    Within the travel retail channel, chocolate and confectionery “comfortably” account for 80% of Nestle’s sales, Dryburgh notes. “The main category focus is chocolate and confectionery for the simple reason that is one of the key categories within the [travel retail] industry,” he observes.

    The pressure cooker atmosphere of the channel means that trends born out in travel retail frequently develop ahead of the winder market, Dryburgh suggests. “I think as a whole this industry has done things that have been pushing the envelope. I think the challenge is always to stay ahead because often what you see being executed in this industry at certain premium price points then becomes translated into domestic markets. The continual challenge is to stay ahead of that curve.”

    Dryburgh points to Nestle’s decision to expand its Cailler brand via the travel retail channel as part of a push to internationalise the 200-year-old brand of premium Swiss chocolate.

    “We have been focusing in particular on Cailler as a first instance. It is one of the strategic priorities that has been called out by the organisation. Cailler is the original Swiss chocolate brand. It is the home of chocolate in Switzerland. It dates back to 1819 and Francois-Louis Cailler who set up the company making chocolate in the factory where we are [still] manufacturing at the foot of the Alps.

    “This is an undiscovered diamond that Nestle has been sitting on. I would say, Lindt & Sprungli have done an outstanding job of driving the premium end of Swiss chocolate without a doubt, I take my hat off to what the team from Lindt have done. However, Nestle is sitting on the first and the original Swiss chocolate. It is a strong brand in Switzerland, but we have not done a good job of internationalising it.”

    This year, Nestle kicked off “activations” first in Swiss airports, Geneva and Zurich. The company then piloted the brand in Dubai and Singapore, the “two big hub airports heading east”. Dryburgh says this roll out has gone “extremely well”. Marketing has included virtual reality point of sale activities to communicate the brand’s heritage and build a rapport with consumers.

    Rolling out the brand to travel retail is a “premier example” of how Nestle’s travel retail business works to add value to the industry, Dryburgh says. “The way you add value is giving consumers a reason to buy because they are going to get something they can’t get at home. That is one of the things that people look for when they are travelling, part of the experience.”

    Ultimately, Nestle does plan to broaden Cailler’s base, but the company does not intend to roll the brand out in traditional retail channels. “We are going to go high-end with this particular brand. I think the focus is very much on leveraging the travel retail channel as a spearhead in giving consumers the chance to engage with the brand in the first place and then encouraging them out.”

    While confectionery sales dominate Nestle’s travel retail sales, Dryburgh says the trend-setting nature of the sector and evolving consumer demand mean in the longer term the company is likely to capitalise on opportunities to exploit other categories.

    “You will be aware of Nestle’s journey in the direction of health science, delivering nutrition via food and health benefits via food, which is something that has historically always been part of what food brings you. Over the centuries people have understood the more holistic benefits that food can bring when consumed in the right way. That is also where our company is heading. For the future, [our travel retail business] tends to be far broader than confectionery and it will be far broader than that as consumer needs change with ageing populations. In the short term it is still going to focus on confectionery,” he says.

    Nestle is also taking advantage of some niche opportunities in travel retail that are created by local conditions, Dryburgh continues. For example, the company has developed “interesting” business selling milk powders in the Middle East.

    The company spotted an opportunity to cater to “blue collar workers” who have come from the Indian sub-continent to places like Dubai as part of the city’s construction boom. “These individuals have a once a year trip home and the opportunity to sell them milk powder was a very interesting one… What we discovered along with the airport authority was the opportunity to sell a relatively bulky, relatively heavy product like 2 kgs of milk powder in the airport duty-free store. The reason the consumer wanted to buy it there was because they didn’t have to put it in their checked luggage and they could carry it on the plane. It is a very simple little story but it is a hugely successful business. And that is about understanding your local consumer and local needs. That is something that is relatively unique to the Middle East.”

    While Nestle picks up local opportunities such as this, they are not the “core thread” of the business because it would “create such complexity that it wouldn’t be worth focusing on,” Dryburgh adds.

    Nestle’s focus on international brands, such as KitKat or Cailler, does not mean the company does not tailor its offering to cater to local preferences. “You have to deal with regional taste and you have to understand who is flying where. Often, in the bugger hub airports certain airlines fly through certain terminals… You have to tailor your offering subject to the terminal and the airport. If you have a brand that is a global proposition – like KitKat or Cailler – well that proposition is quite universal it is just a function of how you communicate or engage with consumers around it.”

    Those operating in the travel retail sector face some unique channel-specific challenges. According to Dryburgh, while branded manufacturers still have negotiations around pricing “the environment you work within and also the margin structures” are specific to the channel.

    “This is different because of the nature of the industry. Effectively, the way the industry is set up now, the airport authorities as a general rule of thumb earn around 70% plus of their revenue comes in now from non-aeronautical sources,” Dryburgh explains.

    “The very clever game that the airport authorities play is for the main duty-free store they auction the space off. The retailers come and tender for a five or ten-year contract. But it is a very different world to a domestic supermarket world… retailers either win the tender or they don’t, you are either in or out. That means they have to put a very specific sum of money on the table as a guaranteed payment to the airport on an annualised basis. And therefore they demand extremely high margins from brand owners to be in the stores.

    “The big four categories – tobacco, alcohol, perfumes, cosmetics – they are all offering 80-85% margin that is being earned by the retailer. But the retailer is having to earn that money because they are paying extremely high rental costs to the airport authorities. The airport authorities are the ones making the money, and they are ploughing it back into infrastructure because the whole sector has seen a dramatic growth curve. More people are flying so they have to invest in the infrastructure.”

    Overall, Dryburgh says the underlying growth drivers for travel retail are “extremely positive”. However, the sector does face exposure to “very big peaks and troughs” that track ahead of the economic growth curve.

    “For example, when 9-11 happened people tended to travel a little less and people weren’t shopping. The same when the SARS epidemic hit SE Asia back in 2003. That basically stopped people travelling in Hong Kong, Bangkok, Manilla. The industry collapsed. The Singapore industry collapsed. You can get some significantly negative downturns.

    “You can also get some significantly positive upswings. When the globalisation trend was at its peak you had some more Russians travelling, more Brazilians travelling, more Chinese travelling. There were some extremely positive growth years for the industry. It tends to follow a more exaggerated curve than global GDP growth – you get very strong years and negative years. It is more of a roller coaster in that sense.”

    The Nestle executive concedes this aspect of travel retail makes the business more difficult to manage. “If you have a crystal ball and you know what is coming you can do it very easily. But without one it is not so easy to call what is coming. It is one of the first discretionary spend items that goes. It is a challenging channel because of the peaks and troughs, but it is also part of the fun.”
  • UOB Indonesia Projects 5.2% Growth in 2017

    UOB Indonesia Projects 5.2% Growth in 2017

    Bank UOB Indonesia projects Indonesia’s economy to grow next year despite the global slowdown. UOB Indonesia president director Kevin Lam said Indonesia’s economy will grow steadily at around 5.2 percent in 2017, up from this year’s 5.0 percent.

    Kevin is certain that the government will maintain the country’s growth momentum through various economic policy packages aimed at boosting investments. Several infrastructure projects that are currently underway are also expected to help achieve economic equality and income growth.

    “The projects also create jobs, thus contributing to household consumption,” he said in a press conference after the UOB Indonesia Economic Outlook 2017 event in Jakarta.

    Kevin said the government’s effort to attract investors by releasing policy packages—comprised of relaxations and deregulations—is working. According to the UOB Asian Enterprise Survey 2016, nearly a quarter of the respondents, which were Asian companies, chose Indonesia as a destination for their expansions in the next three to five years.

    Last week, Finance Minister Sri Mulyani Indrawati projected that Indonesia’s economy in the fourth quarter will reach 5.0-5.1 percent, “due to fiscal expansions.”

    The minister said state institutions will have plenty of expenditures ahead of the year-end, and the state’s spending figure will reach 96 percent of the target.

  • Thai AirAsia has plans to expand its fleet in China

    Thai AirAsia has plans to expand its fleet in China

    Low-cost carrier (LCC) Thai AirAsia has plans to expand its fleet in China, revealing that it is planning to add five to six aircraft per year over the next few years.

    Thai AirAsia CEO Tassapon Bijleveld told that half of the additional aircrafts would be allocated to China, its largest international market.

    China has accounted for 26 percent of the carrier’s total international capacity to date. Thai AirAsia currently, has 38,880 weekly seats across 14 routes in the Thailand-China market.

    CAPA–Center For Aviation stated that China accounts for 13 of the combined 35 international destinations to which Thai AirAsia/Thai AirAsia X flies.

    Thai AirAsia currently serves 11 destinations in mainland China. Its sister medium/long haul LCC Thai AirAsia X serves another two Chinese destinations.

    The airline, a joint venture between the Malaysia’s AirAsia and Thailand’s Asia Aviation, is keen to grow its base at U-Tapao near the city of Pattaya, which opened in September 2015 and is linked to Macau.

    The expansion on the U-Tapao/Pattaya base would enable new routes to China.

    The low-cost airline has two A320s based at U-Tapao operating three domestic and four international routes – including the two mainland Chinese routes, Macau and Singapore.

    According to Bijleveld, all the U-Tapao routes “are doing very well”, and the Pattaya market is promising.

    The carrier is also considering launching routes from Hat Yai to Hong Kong, Macau and Singapore.

    Through the first three quarters of 2016, Thai AirAsia’s passenger numbers increased by 19 percent to 12.86 million.

    Thai AirAsia plans to add five A320 neos aircraft in 2017. Under its current five-year fleet plan it envisages a fleet of 71 aircraft by the end of 2020.

    Further, Thai AirAsia is also expanding in India, which it referred to as a logical growth market for Thailand.