Author: Mei Ling Tan

  • Turban Chopsticks Launches Eight Flavour Curry Paste Sachet Line

    Turban Chopsticks Launches Eight Flavour Curry Paste Sachet Line

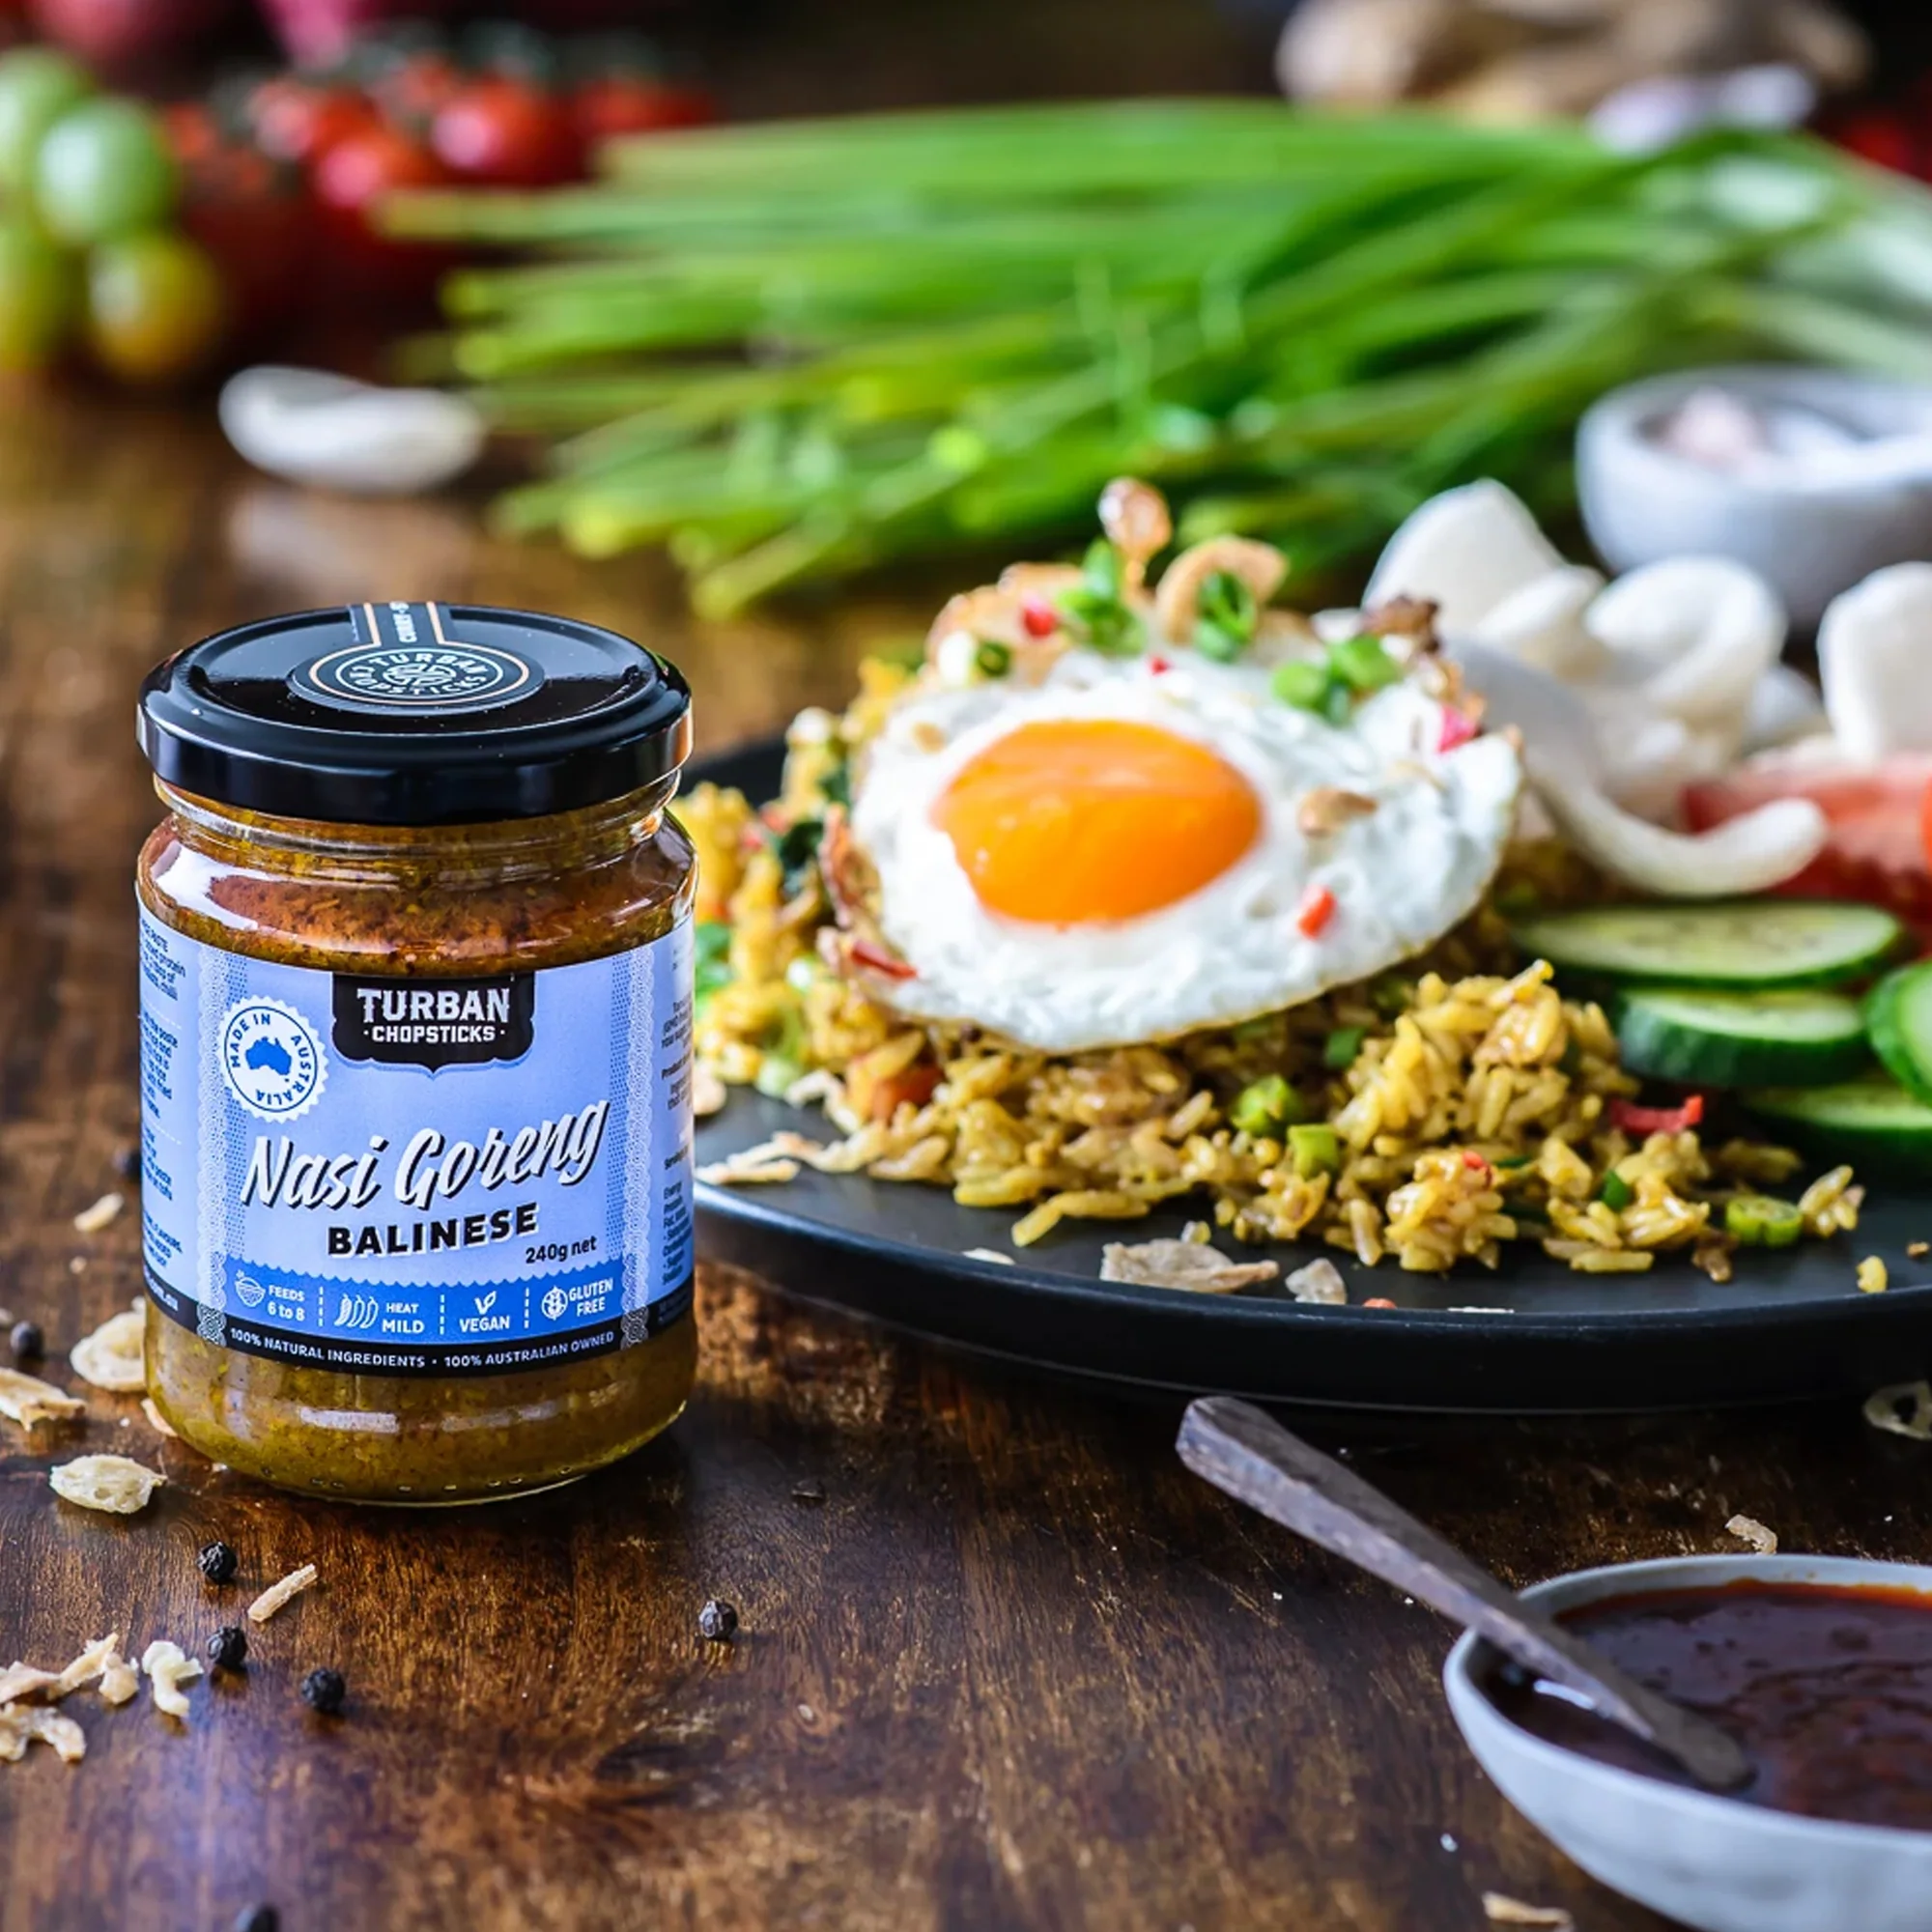
    Perth food producer Turban Chopsticks rolled out an eight-flavour range of curry paste sachets on October 5. The 80-gram packs yield three to four home-cooked servings.

    Shoppers wanting Asian meal bases can buy the smaller packs without committing to full-size glass jars.

    Sachet format and flavour lineup

    Flavours include Korean Gochujang, Japanese Curry, Tandoori, Massaman, Vindaloo, Thai Green Curry, Butter Chicken, and Nut-Free Satay. Every plant-based 80g recipe caters to single-meal household preparation.

    Single-use flexible sachets lower the entry price on retail shelves. They also cut down on pantry waste from half-used jars.

    Pantry shifts and portion control

    Smaller pack formats are gaining ground across supermarket condiment aisles as grocery bills climb. Buyers now look for exact-recipe portions instead of stocking multi-serve jars that spoil.

    For independent brands, the format encourages shoppers to sample different regional dishes. Retailers gain higher inventory turnover and tighter shelf density per square centimetre.

    Competition across supermarket aisles

    Condiment giants and private-label ranges continue to crowd cooking sauces onto middle and bottom shelves. Turban Chopsticks is leaning on allergen-friendly and plant-based recipes to hold shelf space in mainstream Asian grocers and independent supermarket networks.

    Success will hinge on repeat sales against cheaper mass-market pastes. Holding that shelf space demands steady volume across all eight recipes rather than reliance on a single standout dish.

    Distribution and retail targets

    Targeting metropolitan households that cook frequently at home, the brand is rolling out the sachets across Australian retail channels. Reorder rates over the next quarter will decide broader national ranging.
  • Bursa Malaysia Climbs to 1,635 as Financial Counters Lead Early Trade

    Bursa Malaysia Climbs to 1,635 as Financial Counters Lead Early Trade

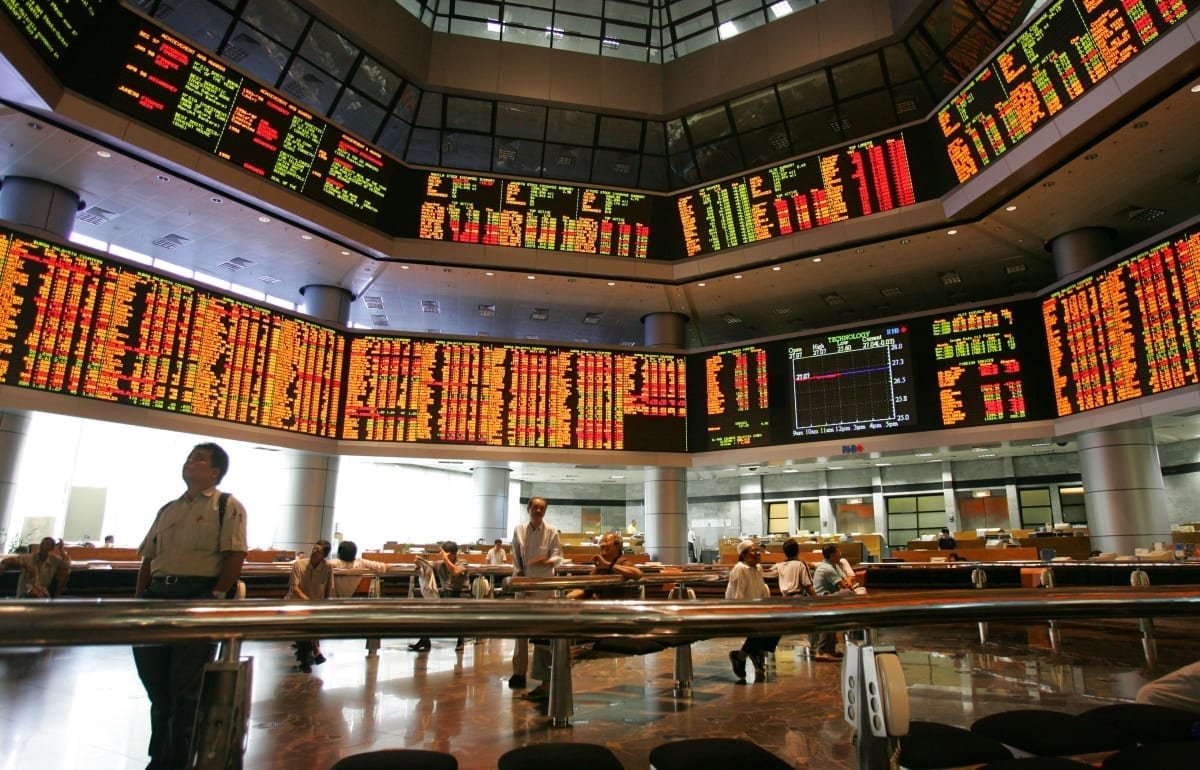
    Bursa Malaysia opened higher on Monday as the benchmark FTSE Bursa Malaysia KLCI gained 5.01 points to reach 1,635.88 within the first ten minutes of trade.

    The 0.31 per cent advance built on the previous Friday’s close of 1,630.87, aided by softer United States payroll figures that dampened expectations of immediate monetary tightening by the Federal Reserve.

    Trading across the Kuala Lumpur exchange showed broad participation in the opening hour. Advancing stocks outnumbered decliners 224 to 158, while 337 counters remained unchanged, 2,054 went untraded and 24 faced suspension.

    Banking and energy counters advance

    Lenders provided the primary push for the index. Malayan Banking, Public Bank, and CIMB each climbed four sen to RM10.06, RM4.70, and RM7.69 respectively, driving the Financial Services Index up 97.59 points to 19,138.10.

    Utility giant Tenaga Nasional also added four sen to trade at RM13.00. Energy stocks followed suit, pushing the sector index up 2.57 points to 835.60, while the Plantation Index gained 2.23 points to 9,058.78.

    Healthcare provider IHH Healthcare moved against the upward trend, shedding six sen to RM7.74.

    Trading volume and market breadth

    Total market turnover reached 206.30 million shares valued at RM98.78 million during early exchanges. Technology and manufacturing counters saw heavy volumes among retail and institutional accounts.

    VS Industry gained three sen to 32 sen, while Notion VTec added four sen to 74.5 sen. GB Bond rose half a sen to 23.5 sen, SFP Tech picked up one sen to 28.5 sen, and Dagang NeXchange traded unchanged at 51.5 sen.

    Renewable energy and industrial engineering names led percentage gains. Samaiden climbed 19 sen to RM3.03, UWC gained 16 sen to RM7.73, Critical Holdings rose 15 sen to RM2.61, Mi Technovation added nine sen to RM5.30, and Solarvest advanced eight sen to RM4.25.

    Regional pressures and bond yields

    External macroeconomic indicators continue to dictate capital flows across Southeast Asian bourses. Rakuten Trade equity research head Thong Pak Leng noted that elevated benchmark borrowing costs and commodities keep local sentiment selective.

    Brent crude traded at US$102.25 per barrel while the US 10-year Treasury yield held at 5.28 per cent, maintaining pressure on emerging market valuations. In Hong Kong, the Hang Seng Index slipped below the 24,000 threshold as selling hit technology and financial listings.

    For consumer brands and industrial suppliers across Malaysia, higher bond yields and fuel costs present direct friction against corporate margins and transport overheads. Investors are filtering allocations toward cash-generative banking and energy plays while trimming positions in high-multiple consumer staples.

    Consumer decliners and index levels

    Consumer bellwether Nestle recorded the sharpest decline of the morning, dropping 32 sen to RM89.20. Industrial and tech decliners included Vitrox, down 14 sen to RM10.32, Kobay Technology, losing 12 sen to RM2.18, and Kelington, shedding five sen to RM8.58.

    Secondary indices tracked the main board higher. The FBM Mid 70 Index rose 28.14 points to 17,510.07, the FBM Emas Index added 33.81 points to 12,204.38, and the FBM ACE Index climbed 31.41 points to 5,560.87.

    Rakuten Trade projects the FBM KLCI to fluctuate between 1,625 and 1,635 points through the remainder of the session as bargain hunters test resistance levels.

  • Vingroup and Alstom Agree on Deal for 200 Hanoi Metro Trainsets

    Vingroup and Alstom Agree on Deal for 200 Hanoi Metro Trainsets

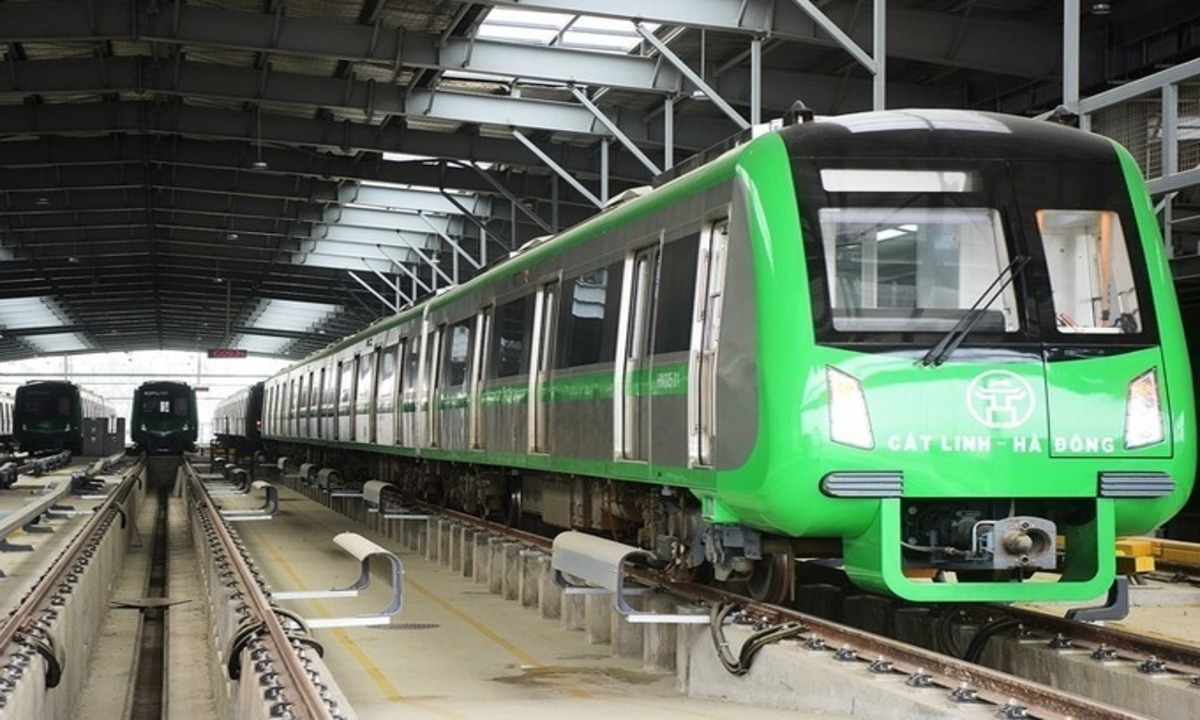
    Vietnam’s Vingroup and France’s Alstom announced a deal on Tuesday for 200 metro trainsets and an associated technology transfer to support Hanoi’s urban rail network. The partnership covers fully automated, driverless rolling stock for the capital city’s planned transit lines.

    Alstom will design and construct the initial batch of 83 five-car trainsets at its manufacturing plant in France. Vingroup will assemble the remaining 117 trainsets at its facilities in Vietnam. Alstom will supply engineering expertise, tooling systems, and critical components for the domestic build.

    Splitting production between France and Vietnam

    Work will shift industrial capacity to Vietnam in two phases. Alstom handles early engineering and fabrication in Europe to set technical baselines for the automated systems. Vingroup then assumes direct assembly operations to build out domestic rail manufacturing capability.

    Neither company disclosed delivery timelines or the total financial value of the contract. Alstom will stay tied to local assembly lines across the build program, providing specialized parts and technical supervision throughout.

    Industrial shift for Vietnam’s transit pipeline

    Securing domestic rolling-stock assembly alters the economics of future transit tenders. It reduces long-term dependence on fully imported fleet orders. However, Vingroup takes on the execution risk of mastering precision rail manufacturing alongside its existing industrial operations.

    Rail development is one of Vietnam’s most active transport sectors. Planners in Hanoi and Ho Chi Minh City have mapped out approximately a dozen lines between them. That pipeline creates continuous demand for standardized rolling stock and signalling hardware across both hubs.

    Scaling the capital city network

    Vietnam has accelerated procurement to relieve road congestion and support high-density commercial corridors. In the capital, Hanoi has outlined a blueprint to expand its urban rail footprint to 979 route kilometres across 18 separate lines by 2045.

    Fleet procurement will scale up as line construction advances toward those milestones. The next operational metric to watch will be the formal announcement of delivery schedules and line allocations for the first French-built trainsets.

  • Flexport Connects Freight Platform to AI Tools Claude, Gemini and OpenAI

    Flexport Connects Freight Platform to AI Tools Claude, Gemini and OpenAI

    Flexport has linked its freight forwarding, customs brokerage and fulfilment platform to commercial artificial intelligence tools including Claude, Gemini and OpenAI. Flexport CEO Ryan Petersen presented the integration, which uses an open API and the Model Context Protocol, during a technology release in September.

    The system allows Australian retailers importing goods or expanding into overseas markets to replace spreadsheets stitching together five vendors with a single system of record. Connecting live freight data directly into enterprise planning platforms helps supply chain teams automate forecasting without waiting 12 hours for manual updates across international time zones.

    How the Data Pipeline Operates

    Cross-border retail shipments frequently stall when tracking numbers fail to match purchase orders across disconnected third-party logistics portals. Customs paperwork, transit updates and carrier records arrive through separate emails and PDFs. Discrepancies between enterprise resource planning software and physical transit status often go unnoticed. Containers then miss scheduled delivery windows at regional distribution centres.

    Live transit status, container utilisation rates and customs filings now feed directly into forecasting software. Enterprise planning platforms can adjust safety stock thresholds automatically. They also update landed cost calculations without staff chasing forwarders across time zones.

    The Operational Shift for Asia-Pacific Retailers

    Regional operators face compounding logistics risks as product origins multiply across manufacturing corridors in Australia and Southeast Asia. A single delayed container in transhipment hubs like Singapore disrupts wholesale commitments when inventory systems rely on manual entry. Direct data piping gives supply chain teams early warning before transit delays turn into retail stockouts.

    Operational risk now shifts from manual data entry errors to data governance and integration reliability. Connecting logistics data to external large language models requires clean origin records and consistent carrier updates at the source. Automated forecasting tools still produce faulty delivery estimates if upstream freight partners fail to digitise customs milestones.

    September Product Rollout Sets the Foundation

    Flexport chief executive Ryan Petersen introduced the Model Context Protocol architecture during a corporate technology release in September. The deployment targeted chronic data disconnects between freight forwarders, domestic customs brokers and enterprise resource planning systems.

    Older freight software rollouts focused on internal tracking dashboards rather than machine-readable feeds for external analytical models. By exposing live shipping data to outside generative tools, the company aims to reduce manual reconciliation across multi-lane retail supply chains.

    Next Steps for Integration and Rollout

    Global forwarding lanes now run the technical deployment for commercial importers and exporters using the platform. Supply chain operators must next integrate their proprietary forecasting algorithms and enterprise resource planning software with the open protocol to automate real-time reordering schedules.

  • Global AI Data Centre Spending to Hit Thirty Trillion Dollars by 2050

    Global AI Data Centre Spending to Hit Thirty Trillion Dollars by 2050

    Cumulative global spending on artificial intelligence data centres will reach 30 trillion dollars by 2050, exceeding the capital poured into any previous technological transition in modern economic history.

    That outlay projection from PwC puts infrastructure commitments on par with the entire market value of outstanding United States Treasuries. The scale of investment eclipses the capital deployments seen during the nineteenth-century railroad expansion and the late-1990s internet boom, even after adjusting for historical inflation.

    The Capital Equation for Infrastructure

    Tech companies and sovereign funds are committing capital to server capacity, specialised chips, and power generation at a pace that demands rapid commercial returns. The sheer volume of hardware spending means enterprise software buyers now face pressure to prove that automation cuts operating costs faster than the infrastructure depreciates.

    Data centre developers are also running into physical bottlenecks across regional power grids. In major markets, server farms are competing directly with residential housing sectors for high-voltage electricians, base-load electricity contracts, and industrial water allocations required for cooling compute clusters.

    Cost Shifts Across Enterprise Operations

    Corporate adoption is altering cost structures across regional businesses, though initial savings frequently push expenses into other parts of the balance sheet. In retail and supply chain operations, automated inventory tracking and customer service systems reduce direct headcount while increasing technical compliance and software licensing overhead.

    The labour impact has hit external service providers first. Enterprise data compiled by fintech platform Ramp shows companies that spent heavily on freelance contractors cut those budgets by 97 per cent after switching task workflows to generative software. The transition eliminated costs for translation, graphic design, and basic coding without requiring formal corporate restructurings or severance payouts.

    Dispute Volume and Operational Frictions

    Lower barriers to generating technical and legal text are creating fresh operational strains for regulators and public tribunals across the Asia-Pacific region. Australian legal services provider Maurice Blackburn noted in regulatory filings that automated tools alter access costs across the market.

    “AI will let law firms deliver high-quality services at scale,”

    Cheap generative drafting has also driven an influx of poorly verified submissions into administrative bodies. Australia’s Fair Work Commission has recorded an increase in automated unfair dismissal filings, forcing public registries to allocate extra staff time to screening low-quality claims.

    Consumer Agents and Capital Allocation

    New consumer tools are targeting deposit inertia at traditional financial institutions. Meta has introduced its Muse personal assistant, designed to help retail users automatically identify higher-yielding non-bank deposit alternatives and shift balances out of standard accounts offering sub-one per cent returns.

    These consumer-facing agent deployments mark the next phase of enterprise software rollouts following two years of pure model training and server farm buildouts. The Australian Parliament’s Joint Select Committee on Artificial Intelligence is scheduled to deliver its final findings on regional economic impacts in November 2026.

  • Nike Merges Asia Operations and Cuts Outlook as Greater China Revenue Drops 22%

    Nike Merges Asia Operations and Cuts Outlook as Greater China Revenue Drops 22%

    Nike reported a 22 percent revenue decline in Greater China for its first quarter, forcing a regional restructuring that will merge its Asian operations and cut corporate jobs next year.

    Total group revenue fell 4 percent to $11.2 billion in the three months to August 31, weighed down by the steep slide across Chinese retail channels and a 28 percent drop at Converse.

    Chief executive Elliott Hill outlined an operational overhaul called Pace to combine Nike’s geographic footprint into three operating divisions. Under the plan, Asia Pacific and Greater China will merge into a single entity named APGC. The Americas will combine North America and Latin America, while Europe, the Middle East and Africa will continue operating as EMEA.

    The company is also establishing a corporate campus in Bengaluru, India, while reallocating capital toward product design, supply chain flexibility and core athletic categories. The restructuring will involve an unspecified number of layoffs across the business in 2027.

    Consolidation Across Asian Markets

    Folding Greater China into the broader Asia-Pacific division reflects a sharp change in how Nike manages its most lucrative growth engine of the past decade. Greater China previously ran as an autonomous reporting region with dedicated commercial teams in Shanghai.

    Lumping the market with Southeast Asia, Japan, South Korea and Australia reduces administrative overhead, but it also signals that standalone hyper-growth in China is over. Local Chinese sports brands have steadily captured domestic market share across lower-tier cities, leaving Western labels to fight over promotional retail space in tier-one malls.

    For retail landlords and franchise partners across Asia, the reorganization brings tighter product allocations and reduced exposure to lifestyle footwear. Department stores and mono-brand franchise operators in China and Southeast Asia face inventory adjustments as Nike curbs deliveries to clear excess stock.

    Inventory Backlog in Jordan and Lifestyle Lines

    Nike acknowledged that its Jordan brand suffers from severe market oversupply, requiring the company to pull back retro releases and clear wholesale pipelines. That overhang mirrors broader softness in fashion sneakers, where demand for retro basketball silhouettes has cooled sharply across Asian metropolitan centers.

    While North American sales rose 2 percent during the quarter, the rebound was not enough to offset declines in overseas territories. Nike’s core Air Force 1 franchise stabilized after several quarters of intentional volume cuts, but executives cautioned that sports apparel and lifestyle ranges remain under severe pressure.

    To fix the pipeline, Nike is shifting resources away from direct-to-consumer lifestyle channels and redirecting budget into performance running, basketball and training gear. The pivot requires rebuilding wholesale ties with multi-brand sports retailers across Asia who lost access to top-tier allocations during Nike’s direct-selling push.

    Restructuring Follows Repeated Timeline Shifts

    Pace represents Nike’s third corporate restructuring effort since fiscal 2024. Previous initiatives, including the Win Now framework, failed to generate operating use as consumer demand slowed across Asia and Europe.

    The group issued revised guidance warning that full-year revenues will fall in the high-single digits. Management conceded that corrective actions will depress wholesale shipments and retail margins through the remainder of the current fiscal year and into the next.

    Work will now focus on establishing the Bengaluru technical campus and completing regional management appointments across the newly formed APGC unit ahead of the next fiscal reporting cycle.

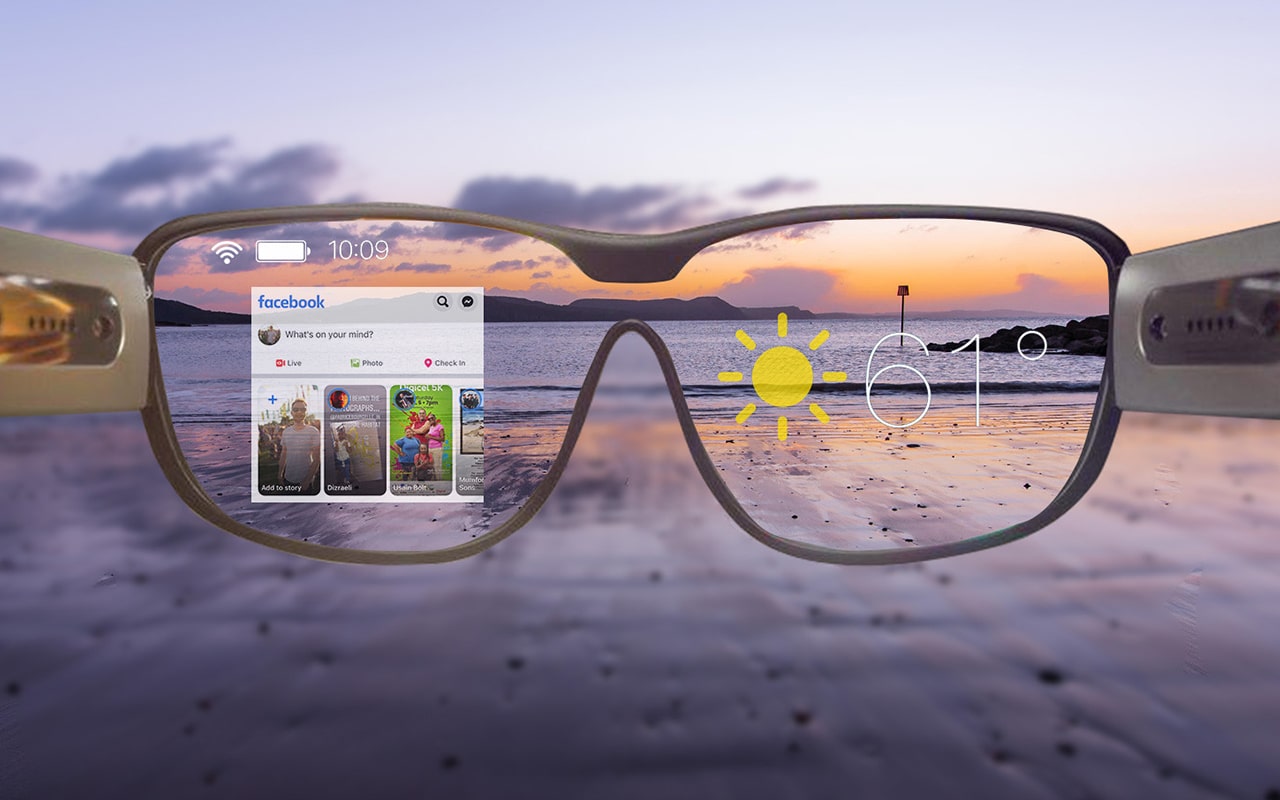
  • MemoMind Expands AI Glasses Translation to 53 Languages

    MemoMind Expands AI Glasses Translation to 53 Languages

    MemoMind rolled out a software update for its One AI glasses on September 30, 2026. The patch expands real-time translation to 53 languages and opens a second developer phase.

    Incubated by projector maker XGIMI, the company is selling the standard hardware for $399 on promotion against a $599 list price.

    Language Support and Audio Capture

    The firmware update extends live two-way translation across South Asian and Middle Eastern markets. It adds firmware-level support for Urdu, Tamil, Gujarati, Nepali, and Arabic. To improve speech intake in crowded environments, users can now toggle between front-facing directional audio capture and omnidirectional recording.

    Display capabilities received an upgrade as well. The internal heads-up display now renders up to four lines of notification text, reducing the need to check paired smartphones. Users can also pull custom RSS 2.0 and Atom 1.0 feeds directly into the display interface rather than relying on curated platform feeds.

    Input Protocols and Peripheral Support

    Bluetooth Low Energy now carries the standard Human Interface Device protocol on the frames, allowing third-party input hardware to connect directly. The protocol complements existing temple touch controls, voice prompts, and head-gesture tracking with peripheral ring inputs.

    Hardware startup Kiwear serves as the flagship partner for the peripheral integration, enabling ring-controlled inputs out of the box. Memo Labs also introduced Memo Agent. That tool lets users view and dispatch basic commands to an automated coding agent through the glasses.

    Ecosystem Strategy and Hardware Margins

    Wearable AI makers face steep customer churn once the initial novelty of audio playback and basic transcription fades. By adding standard peripheral input protocols and open RSS syndication, MemoMind is attempting to anchor the hardware into everyday productivity routines before larger consumer electronics rivals dominate the category.

    A $200 promotional discount reflects a familiar hardware playbook. MemoMind needs active units on faces to attract third-party developers. Subsidising hardware margins creates financial drag if software-driven retention fails to materialise. Competing display-enabled frames from regional consumer brands have struggled with battery constraints and thermal limits during continuous ambient workloads.

    Software Cadence and Workspace Beta

    Customer orders opened on June 29 as part of a structured commercial rollout. On September 1, the company published its open SDK on GitHub with two development tracks: native C plugins for on-lens rendering and sensor access, and web plugins for phone-side data processing.

    In October, MemoMind will launch a closed beta for its App Workspace through a community whitelist. That trial will allow selected developers to build, install, and execute local applications directly on retail devices ahead of a broader public application storefront.

  • AIA Urges Shift from Fee-for-Service as Asia Medical Inflation Hits 21%

    AIA Urges Shift from Fee-for-Service as Asia Medical Inflation Hits 21%

    Medical costs across Southeast Asia will surge by up to 21 per cent in 2025, forcing insurers and healthcare operators to replace traditional fee-for-service billing models with bundled pricing and tighter network controls.

    Forecasts compiled by Mercer Marsh Benefits show medical trend rates hitting 21 per cent in the Philippines, 19 per cent in Indonesia, and 15 per cent in both Malaysia and Vietnam. These double-digit increases run well ahead of headline consumer price inflation across the region, putting immediate strain on corporate benefits budgets and personal household finances.

    Waste Drives a Quarter of Regional Healthcare Spending

    An estimated 25 per cent of all healthcare expenditure across Asian markets stems directly from administrative and clinical waste. This inefficiency includes unnecessary surgical interventions, prolonged hospital stays, inappropriate antibiotic prescriptions, and inadequate preventive screenings.

    Payor-provider alignment could help eliminate redundant treatment cycles by linking compensation to clinical outcomes rather than the volume of procedures billed. Under the traditional fee-for-service structure, private hospitals and clinics face financial incentives to run additional diagnostic tests and extend inpatient admissions regardless of clinical necessity.

    Addressing these inefficiencies requires insurers and medical providers to standardise diagnostic and clinical data at the line item level. Sharing harmonised laboratory results, procedure codes, and diagnostic files across private networks reduces duplicate testing and accelerates claims adjudication.

    Out-of-Pocket Spending Surges Across Key Markets

    Rising medical costs are shifting directly onto consumers across developed and emerging economies alike. World Health Organisation figures cited by AIA show personal out-of-pocket healthcare expenditure jumped 13 per cent in both Singapore and Australia between 2022 and 2023.

    Emerging markets saw similar spikes over the same twelve-month window. Patients in India and Indonesia experienced a 10 per cent increase in direct out-of-pocket spending, eroding discretionary consumer purchasing power as basic medical treatments absorb larger portions of family income.

    Price opacity in private hospital networks worsens the burden. Transparent fee schedules for standard procedures allow policyholders to compare facilities effectively while enabling insurers to steer patients toward cost-effective treatment pathways.

    Alternative Payment Models and Preferred Panels

    Insurers are pushing private healthcare operators toward alternative commercial agreements, including episode-based bundled payments and risk-adjusted provider networks. Bundled rates establish a single, fixed fee for an entire course of treatment, eliminating unexpected add-on charges for routine post-operative care.

    Payors are also constructing preferred provider panels using verified clinical outcome metrics. Facilities that demonstrate lower complication rates and strict adherence to treatment protocols receive higher patient volumes and predictable fee schedules in exchange for discounted service tariffs.

    This structured collaboration replaces transactional claims processing with multi-year commercial partnerships. Hospitals secure stable patient flows across competitive metropolitan markets, while insurers contain underlying claims volatility.

    Corporate Benefit Pressures in 2025

    Medical trend rates remaining in double digits across Southeast Asia present an operational challenge for corporate employers competing for talent. Companies face the choice of absorbing premium hikes, reducing policy coverage limits, or passing higher deductibles to staff.

    The pressure is acute in markets like the Philippines and Indonesia, where private medical insurance serves as a primary tool for corporate staff retention. Retail operators, commercial landlords, and regional service conglomerates operating across multiple Asian jurisdictions must renegotiate group policy structures to keep benefit plans solvent.

    Attention now turns to the rollout of standardised digital health records and published procedure tariffs across major private hospital operators in Malaysia, Vietnam, and Indonesia ahead of the 2025 contract renewal cycle.

  • Japan Convenience Stores Boost Apparel as Footfall Drops for 14 Months

    Japan Convenience Stores Boost Apparel as Footfall Drops for 14 Months

    Japan’s major convenience store operators, including Seven-Eleven Japan, FamilyMart, and Lawson, are expanding dedicated fashion ranges to pull younger shoppers through their doors as same-store customer footfall has fallen for 14 straight months.

    Shoppers aged 50 and older accounted for roughly 40 percent of visitors to Seven-Eleven Japan outlets last fiscal year, while customers aged 20 and younger represented just 17 percent.

    That demographic squeeze is forcing the country’s dominant chains to treat clothing as an everyday destination rather than an emergency purchase for stranded commuters. Instead of stocking items strictly for bad weather or travel, merchandisers are allocating shelf space to designed casualwear, branded collaborations, and street accessories.

    Seven-Eleven Targets Younger Demographics

    Seven-Eleven Japan introduced 28 limited-edition apparel items on Sept. 25 through a partnership with fashion group And ST. The rollout features merchandise from youth brands nico and… And Lowrys Farm, focusing on T-shirts, scarves, and hair accessories across domestic outlets. The chain wants to double total apparel sales compared with fiscal 2025 levels.

    “Attracting younger customers is essential for us to continue growing over the long term,” Junko Watanabe of Seven-Eleven Japan’s merchandising division said.

    Merchandise buyers are using lower price points and impulse gift items to draw young women. That demographic has drifted toward specialist drugstores and online platforms.

    FamilyMart Targets ¥30 Billion in Sales

    FamilyMart began the sector’s clothing push in 2021 by hiring an external designer and rolling out its Convenience Wear line nationwide. It built early sales with brightly striped socks and packaged handkerchiefs before expanding into outerwear and daily essentials.

    A flagship Tokyo store opened in July with fitting rooms and roughly 300 apparel stock-keeping units. Management targets a 50 percent year-on-year increase in apparel revenue, aiming for ¥30 billion in fiscal 2026.

    Clothing floor space brings higher basket values and wider gross margins than packaged drinks or boxed meals. Non-refrigerated displays also cut electricity overheads for franchise operators.

    Lawson Expands Partnership Lines

    Lawson took a partner-led approach by expanding shelf space for Ryohin Keikaku’s Muji apparel range in April. It supplemented those basics by adding winter accessories, including gloves, through a tie-up with lifestyle brand Bruno.

    Brand partnerships shield operators from the inventory risks of full private-label production. Sourcing branded lines passes design and markdown liabilities back to partners while giving store managers steady replenishment cycles.

    Convenience networks across East Asia face similar demographic and basket-size pressures. Japan’s apparel strategy offers a template for franchise operators in South Korea and Taiwan.

    Footfall Headwinds Across Franchise Networks

    Data from the Japan Franchise Association shows sector-wide same-store customer traffic down year-on-year for 14 consecutive months. Inflation and a shrinking population have squeezed visits, forcing operators to lift revenue per transaction.

    Upcoming fiscal 2026 winter quarterly results will deliver the verdict on whether higher-priced apparel can lift total store receipts without cannibalising traditional convenience sales.

  • Nespresso and Swarovski Launch Festive Coffee and Accessories Range

    Nespresso and Swarovski Launch Festive Coffee and Accessories Range

    Nespresso rolled out a festive collaboration with Swarovski in October 2026, launching co-branded coffee blends, machines, and accessories ahead of the holiday season. The seasonal lineup includes Festive Crystal Spark Espresso for Original machines and Festive Crystal Spark Double Espresso for the Vertuo system.

    Packaging across the range adopts Swarovski’s octagonal motif and colour scheme, targeting premium gift buyers during the fourth-quarter retail rush.

    Dual formats and crystal merchandise

    The product release spans coffee capsules, drinkware and seasonal collectables. Both Original and Vertuo systems receive dedicated advent calendars, engineered to reveal two capsules on selected countdown dates rather than the standard single pod.

    Hardware and accessories extend into standalone display pieces. A crystal ornament shaped like the classic Nespresso capsule carries 62 facets with a shimmer effect, finished with a brushed chrome-tone top and pink satin ribbon. The merchandise roster also adds branded travel mugs, mug holders and Pixie Lungo cups designed for the festive sales window.

    Premium positioning in holiday gifting

    Seasonal capsule drops have become standard across the single-serve coffee sector, but tie-ups with luxury jewellers push price points higher. For Nestle, pairing single-portion coffee with crystal glassware helps lift average basket values when discretionary consumer spending faces margin pressure across regional retail networks.

    Department stores and branded boutiques rely heavily on limited-edition packaging to drive footfall in November and December. Swarovski gains direct placement in kitchen counters and home pantries, extending its brand presence beyond traditional jewellery counters into everyday consumer goods.

    Earlier retail collaborations

    Nespresso previously anchored its holiday campaigns around high-profile fashion designers and pastry chefs to generate seasonal momentum. Integrating crystal design elements represents a pivot toward collectible lifestyle items that outlast the consumable coffee supply inside the box.

    Inventory across the Swarovski range rolls out through Nespresso boutiques, online channels and selected retail partners ahead of peak holiday trading.

  • Lark Master Distiller Chris Thomson to Step Down After 20 Years

    Lark Master Distiller Chris Thomson to Step Down After 20 Years

    Lark Distilling Co master distiller Chris Thomson will leave the Tasmanian whisky maker at the end of 2026 after nearly two decades. He plans to launch his own spirits venture.

    His exit follows a financial year in which the Pontville-based distiller lifted international export sales 69 per cent to AU$1.8 million. Global travel retail revenue rose 43 per cent to AU$2.2 million.

    Thomson joined Lark in February 2007 and became master blender and distiller in 2010 after training under founder Bill Lark. He finishes his tenure in late December. He will take several months off with family before launching the new whisky project.

    Export expansion and production scale

    Net sales grew 15.1 per cent for the financial year ending June 30, 2026. Gains came from expanding beyond domestic bottle shops into regional duty-free hubs and offshore export channels across Asia-Pacific.

    Primary distillation and cask storage shifted to the expanded Pontville site north of Hobart, building an inventory reserve for larger commercial runs. Thomson oversaw the formulation and rollout of the luxury single malt range earlier this year. He established standard production recipes to maintain barrel consistency as volume expands.

    Leadership changes at Pontville

    Former Four Pillars gin co-founder Stuart Gregor took over as Lark chief executive and managing director in late 2025. He praised Thomson’s contribution across the past two decades.

    “Chris has been much more than an integral member of our team; he has been our beating heart and soul for more than half of our existence and one of the world’s great distillers,” Gregor said.

    This leadership handover tests whether a craft spirits label can maintain its liquid profile without its longtime blender. For liquor retailers and regional distributors, the challenge is whether brand equity survives the exit of the personality behind the product.

    Industry recognition and market shifts

    Thomson collected the Rest of the World title for Master Distiller and Master Blender of the Year at the 2026 World Whiskies Awards Icons of Whisky. The Spirits Business Awards also named him runner-up Blender of the Year in 2025.

    Tasmanian single malts face tougher shelf competition in Asian travel retail corridors from Japanese, Taiwanese and Scottish distillers. Lark has relied on limited-cask releases and luxury pricing to protect margins against higher local excise rates and rising logistics overheads.

    Operational handover ahead of 2027

    Production staff at Pontville will handle distillation and blending once Thomson departs at year-end. Lark has not named an external successor for the master distiller post.

    Investors and retail buyers will watch the distillery’s half-year trading update in early 2027 to see whether export momentum across Asian duty-free accounts holds under Gregor.

  • Thailand Targets 25,000 Megawatts of Clean Power for Industrial and Data Demands

    Thailand Targets 25,000 Megawatts of Clean Power for Industrial and Data Demands

    Thailand must boost renewable electricity generation to between 65 percent and 80 percent by 2050 as expanding industrial operations and data centres demand roughly 25,000 megawatts of clean power.

    Green Investment Hub Chairman Kulit Sombatsiri delivered the capacity forecast at the ESG Symposium 2026 in Bangkok, warning that heavy reliance on imported energy leaves regional supply chains vulnerable to price shocks.

    The investment roadmap requires capital deployment across modernised power grids, virtual power plants, carbon capture utilisation and storage, and small modular nuclear reactors. Meeting the target demands public-private partnerships across energy producers, industrial consumers, and regulatory agencies to maintain grid stability without driving power tariffs higher for commercial users.

    Powering Industrial Expansion

    Thailand’s industrial base faces rising pressure from export markets to prove low-carbon production credentials. Heavy manufacturers and emerging data centre operators require dedicated green power contracts to fulfill global corporate net-zero pledges.

    SCG President and Chief Executive Officer Thammasak Sethaudom said Southeast Asian economies cannot afford to view decarbonisation as a trade-off against economic expansion. Regional operators must link green investments directly to cost reductions and factory floor efficiency rather than treating sustainability as a regulatory compliance burden.

    Supply Chain Pressures and Market Realities

    Large multinational brands and retailers sourcing out of Southeast Asia are tightening Scope 3 emissions reporting, shifting procurement orders toward suppliers that run on certified clean grids. Thai manufacturers that delay equipment upgrades risk exclusion from regional export networks.

    Payong Srivanich, co-chairman of the Joint Standing Committee on Commerce, Industry and Banking, said structural reform must address the informal economy and assist small and medium-sized suppliers. Without targeted financing, smaller vendors cannot afford the capital expenditure required to comply with international carbon standards, threatening supply continuity for major consumer goods producers.

    Industrial Execution at the Factory Level

    Dr. Ilham Kadri, chair of the executive committee of the World Business Council for Sustainable Development, pointed to the Saraburi Sandbox project in central Thailand as an operating model for industrial clusters. The platform links industrial plants, local farms, and logistics operators to turn agricultural waste into alternative industrial fuels and create revenue from carbon credits.

    “The AND matters because the old either-or framing has constrained too many decisions for too long and sometimes led to making big industrial mistakes.”

    Kadri stated that green transition projects must pass strict internal hurdle rates at investment committees before scaling across factory operations and regional retail distribution channels.

    Infrastructure Milestones Ahead

    Southeast Asian governments are coordinating regional investment frameworks to share cross-border power transmission and build integrated supply chains for solar photovoltaic systems, smart grids, and low-carbon construction materials.

    Thai energy authorities are scheduled to review regulatory structures for direct power purchase agreements and carbon accounting frameworks, establishing the commercial terms under which industrial operators and data centre developers can procure green electricity directly from private renewable generators.

  • Singapore Ranks 6Th Globally in Savills Next-Gen Wealth Index

    Singapore Ranks 6Th Globally in Savills Next-Gen Wealth Index

    Singapore took sixth place globally and first across Asia-Pacific on Savills’ Next Generation Wealth Hubs Index released last Thursday, beating seventh-placed Hong Kong for young high-net-worth individuals.

    The benchmark tracks capital destinations for individuals under 40 with a net worth of at least US$5 million as an estimated US$84 trillion transfers between generations over the next 20 years.

    Savills evaluated more than 100 destinations across four core pillars: business, governance and connectivity; wealth clusters and local environment; wealth management and taxation; and lifestyle. Singapore gained ground through its concentration of private capital, tech networks and family office structures.

    “Singapore’s combination of regional connectivity, established financial infrastructure and access to opportunities across Asia gives it an important role in these capital flows,” says Rayson Yeong, Savills Singapore’s head of private wealth, investment sales and capital markets.

    The Global Benchmark and Asian Standings

    United States cities dominated the upper tiers of the global ranking. New York took the top spot, followed by Miami, London, San Francisco and Los Angeles before Singapore broke into the sixth position.

    Hong Kong placed immediately behind Singapore at seventh. The city continues to attract mainland Chinese capital through its low-tax environment, family office ecosystem and direct access to cross-border financial channels.

    Other Asian commercial centers secured positions in the global top 30. Tokyo ranked 12th, Shanghai took 18th, Bangkok placed 25th, and Kuala Lumpur claimed 29th position.

    Shifting Priorities Among Under-40 Millionaires

    Younger wealth holders are reallocating capital based on different criteria than previous generations. Inheritors and tech founders below 40 prioritize education, wellness, lifestyle amenities and personal values alongside pure capital preservation.

    This shift alters demand for luxury real estate and commercial investments. Established wealth management hubs must now offer cultural infrastructure and urban livability to retain international capital.

    Singapore and Hong Kong serve primarily as structuring centers. Both territories handle private banking, cross-border investment platforms and corporate holding entities for assets distributed across Southeast Asia and mainland China.

    Emerging Hubs and Manufacturing Wealth Creation

    Wealth creation across the wider region is moving outward from traditional financial centers. Industrial growth in Vietnam and India is producing a new pool of entrepreneurs across technology, manufacturing, financial services and real estate development.

    Secondary destinations across Southeast Asia are capturing lifestyle and residential demand. Phuket, Bali, Hoi An and Ho Chi Minh City recorded growing interest from mobile high-net-worth residents.

    Rising consumer spending in urban centers like Bangkok and Ho Chi Minh City is pulling luxury retail operators and commercial landlords into faster expansion plans. Upgraded transport links and modern residential developments continue to back that inflow.

    Capital Structuring Against Global Competition

    Competition between Singapore and Hong Kong centers on family office registrations and fund management incentives. Both jurisdictions offer tax exemptions and residency pathways tailored to high-net-worth families.

    Western hubs like Miami and London maintain strong pull through deep capital markets and established lifestyle assets. Asian hubs rely instead on proximity to fast-growing regional supply chains and regional wealth creation.

    Private banks and property developers are tracking how the US$84 trillion intergenerational wealth transfer spreads across Asia over the coming decade.

  • China Third-Quarter Economic Growth Estimated at 4.4%

    China Third-Quarter Economic Growth Estimated at 4.4%

    China expanded by an estimated 4.4 per cent year on year in the third quarter, falling short of official targets despite sustained momentum across artificial intelligence.

    The July to September result edged up only marginally from the previous quarter, held back by protracted weakness in domestic consumption and real estate.

    Tech gains trail real estate losses

    Surging investment in artificial intelligence and related hardware provided a lift to industrial output during the quarter. Overseas shipments also held firm, providing critical support for factory floors across the mainland.

    Those industrial gains failed to counterbalance the wider property slump. Housing market contraction continues to depress household balance sheets, limiting the broader economic impact of high-tech manufacturing.

    Consumer spending holds back recovery

    Domestic retail demand remained subdued throughout the three-month period. Shoppers kept spending tight, muting turnover across merchant networks and consumer brands operating in tier-one and regional markets.

    Sluggish consumer spending poses direct challenges for retail operators, landlords and supply chain networks that rely on strong mainland foot traffic. Without sustained consumer demand, gains in factory output cannot flow into the service sector.

    Export strength faces domestic drag

    Strong export numbers kept trade balances positive through September, but external demand cannot carry the entire expansion. Domestic store operators and commercial landlords continue to absorb the impact of cautious household budgets.

    Manufacturers focused on artificial intelligence hardware and export goods outperformed domestic consumer suppliers by a wide margin. That divergence leaves consumer-facing businesses exposed to prolonged margin pressure.

    Pressure builds on growth targets

    The slight quarter-on-quarter uptick leaves the full-year economic trajectory under pressure. Earlier quarters delivered steady factory output, yet household consumption failed to accelerate alongside industrial capacity.

    Official full-year gross domestic product targets require stronger domestic demand in the final quarter. The focal point shifts to upcoming retail sales figures and property transaction volumes across major metropolitan markets.

  • Thai Headline Inflation Rises to 2.82% in September Below Market Forecasts

    Thai Headline Inflation Rises to 2.82% in September Below Market Forecasts

    Thailand’s headline consumer price index rose 2.82 per cent in September from a year earlier, driven by higher fuel and food costs across the country.

    The annual increase stepped up from 2.53 per cent in August but fell short of the 3.06 per cent rise projected in a Reuters market poll.

    Data released by the Ministry of Commerce on Tuesday showed the headline print remained within the Bank of Thailand’s official target range of 1.00 per cent to 3.00 per cent. Core consumer prices, which strip out volatile fresh food and energy expenses, climbed 1.50 per cent year on year against a forecast of 1.54 per cent.

    Ministry adjusts full-year price band

    Nantapong Chiralerspong, head of the ministry’s Trade Policy and Strategy Office, told a briefing that headline inflation will accelerate further in the fourth quarter. Officials expect the pace of price gains in October to exceed the September reading as seasonal patterns and distribution costs take effect.

    Recent regional flooding will have only a minor effect on consumer pricing across agricultural supply chains, Nantapong said. Taking flood damage into account, the ministry narrowed its full-year 2026 inflation forecast to a range between 1.80 per cent and 2.20 per cent, compared with an earlier projection of 1.50 per cent to 2.50 per cent.

    Margin pressure across consumer retail

    For supermarket chains, convenience operators and food service groups in Thailand, the pickup in food and energy expenses tests gross margin buffers. Retailers face higher transport overheads while consumer demand remains sensitive to basket price increases at fresh markets and grocery aisles.

    Store operators that rely on imported staples or high-turnover packaged foods must absorb cost variations or risk losing volume to discount channels. The moderate core inflation rate indicates that underlying demand across discretionary categories is not overheating, limiting the pricing power of consumer brands.

    Central bank interest rate posture

    Subdued underlying price pressure gives monetary authorities room to support broader commercial activity without tightening borrowing costs abruptly. Higher retail lending rates would pinch consumer credit balances and stall store expansion plans for regional mall developers.

    The policy stance remains focused on stability as commercial lenders track household debt levels. Stable borrowing costs help mid-sized retail operators finance working capital and inventory requirements ahead of the peak year-end holiday shopping cycle.

    Monetary policy timeline

    Between January and September, headline consumer price inflation averaged 1.54 per cent across the Thai economy. That average sits in the lower half of the central bank’s target corridor, reflecting moderate price pressures over the first nine months of the year.

    Don Nakornthab, assistant governor at the Bank of Thailand, said last month that monetary policy is “very, very accommodative”. The central bank left its benchmark interest rate unchanged at 1.00 per cent during its monetary policy review in August.

    Rate setters at the central bank hold their next scheduled monetary policy review on October 28.