Category: E-Tailing

Retail News Asia is committed to providing both local and global retailers with the latest E-Commerce & Etail news throughout the Asian market. This on a daily base.

  • TikTok Shop Singapore Seller Base Reaches 80,000 as Video Sales Double

    TikTok Shop Singapore Seller Base Reaches 80,000 as Video Sales Double

    TikTok Shop nearly doubled its short video gross merchandise value in Singapore as its merchant roster expanded over 125 percent year on year to approximately 80,000 sellers.

    Live commerce sales on the platform climbed more than 70 percent year on year, supported by a 150 percent surge in live stream viewership, a 60 percent rise in monthly buyers, and a 30 percent increase in overall transaction volumes.

    Shifting from Search to Feed Purchases

    Speaking at the Retail Asia Summit 2026 in Singapore, Leon Koh, Fashion Lead and Seller Management Lead at TikTok Shop Singapore, said consumers are shifting from search-driven shopping to discovery-led purchases inside content feeds.

    Koh outlined how discovery commerce has taken root across retail verticals, bringing content and commerce together so shoppers discover, explore, and purchase products within the same experience.

    Sales gains spanned fashion and accessories, beauty and personal care, phones and electronics, everyday supplies, and food and beverage categories. The platform positions video feeds as an additional touchpoint to complement, rather than displace, brands’ established distribution channels.

    Live Commerce Gains Ground Across Categories

    Live broadcasting has emerged as the main vehicle for larger sales conversions on the app. Real-time product demonstrations let sellers answer questions instantly and verify sizes. Hosts can also offer short-lived pricing incentives during broadcasts.

    For merchant support, TikTok Shop introduced the Go Live Academy for businesses without broadcasting experience, alongside the Merchant Self Live programme for retailers running internal studios. The platform advocates a three-pillar framework of exposure, experience, and enablement to turn viewers into regular buyers.

    Discovery feeds create fresh operational hurdles for established multi-brand retailers. Marketplaces like Shopee and Lazada rely on catalog depth and search bidding. Feed-driven platforms demand continuous video output, live presenters, and creator partnerships to maintain sales volume.

    Merchant Training Targets for 2026 and 2027

    This shift requires physical retailers and consumer brands to allocate capital to hosting teams and video production. Brands that treat social commerce as an occasional stunt lose ground quickly to digital native merchants who broadcast daily.

    Maintaining buyer momentum requires steady production schedules and rigorous post-broadcast tracking. Inventory management also becomes volatile when creator broadcasts trigger abrupt order spikes that strain warehouse packing and parcel delivery networks.

    “Content commerce is an ongoing cycle, not a one-off campaign,”

    Koh said.

    Singapore E-Commerce Growth Trajectory

    Singapore’s broader digital economy provides an expanding baseline for video shopping. The country’s total e-commerce market value grew from $8 billion in 2023 to $9 billion in 2025, according to the e-Conomy SEA 2025: Singapore Country Report. Projections indicate the domestic online market will reach $15 billion by 2030.

    Competition across the island is intensifying. International e-commerce platforms are investing heavily in creator tools and local logistics infrastructure to lock in shopper loyalty.

    TikTok Shop is tracking seller adoption benchmarks over the next two years. The platform has committed to training more than 3,000 local creators by the end of 2026 and at least 1,000 local sellers through formal merchant programmes by the end of 2027.
  • Shein Net Revenue Rose 1 per Cent in First Report as Public Company

    Shein Net Revenue Rose 1 per Cent in First Report as Public Company

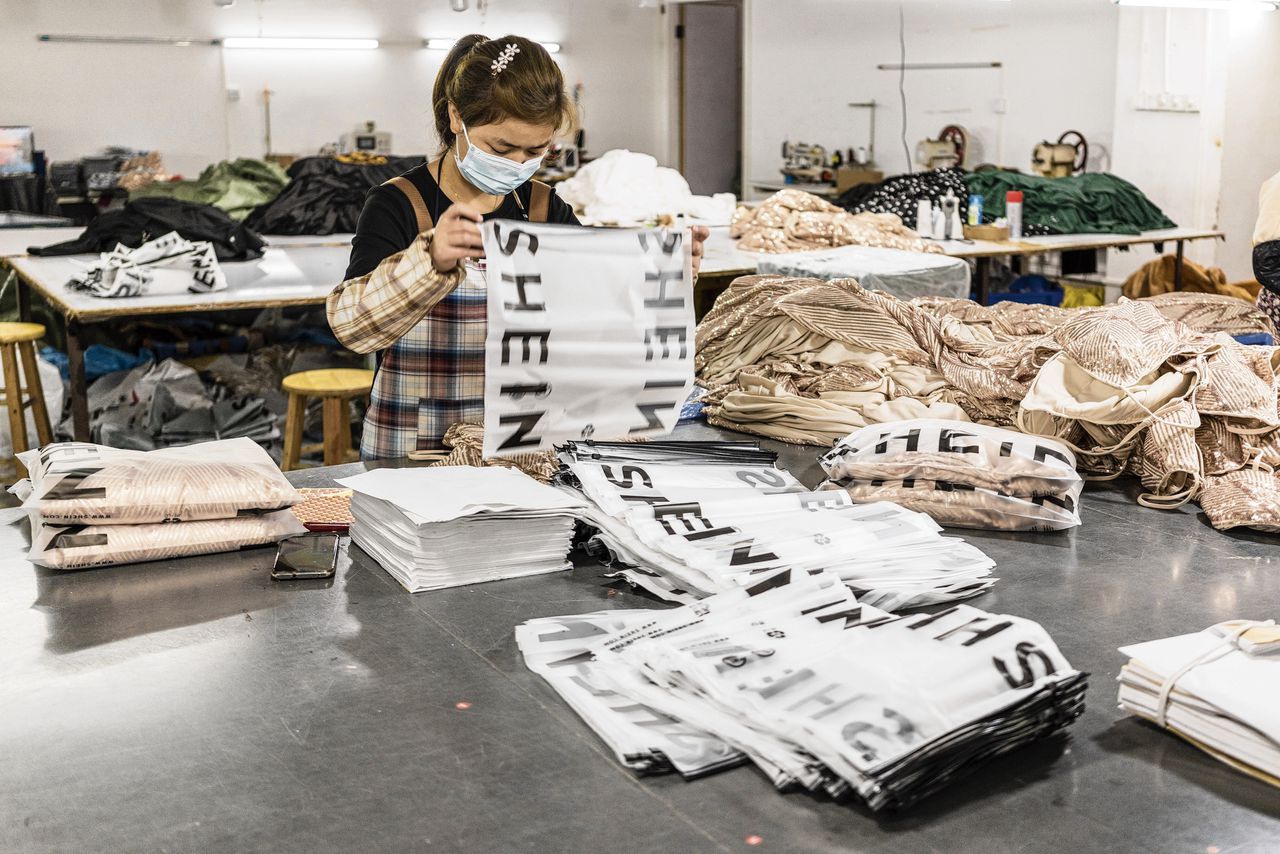
    Shein reported that its net revenue rose just 1 per cent year on year in its first earnings report as a public company, as rising shipping costs and changing customs rules squeezed profits.

    The fast-fashion retailer built its business on delivering cheap clothing to shoppers quickly, but the economics behind that promise have become harder to sustain while attempting to broaden its appeal without losing low prices.

    While orders and active customer numbers grew, retail advisor Deanna Andersen noted on October 1, 2026, that rules changed faster than Shein’s model could.

    Regional Sales Slump in Western Markets

    Western consumers pulled back sharply during the quarter as import rules tightened. Revenue across European markets dropped 13.9 per cent to $3.77 billion. In the United States, sales contracted 6 per cent to $2.5 billion. Growth across Latin America offset the Western downturn just enough to keep overall group revenue marginally above the prior year.

    Cross-border direct dispatch from Chinese factories made Shein a global retail power, but that direct-to-consumer logistics network is facing regulatory resistance. Customs authorities in North America, Europe and South Africa have tightened de minimis duty exemptions on small postal parcels. The introduction of handling fees and import duties immediately chips away at low-ticket transactions, forcing the company to decide between absorbing extra fees or hiking list prices.

    “The rules changed faster than Shein’s model could,” said advisor Deanna Andersen.

    The Limits of Centralised Air Freight

    For Asia-Pacific supply chains, the squeeze on Shein signals a forced restructuring of cross-border e-commerce. Chinese manufacturing networks configured solely for fast-turnaround, air-shipped parcels are losing their cost edge when border duties apply. Domestic apparel brands and established department store chains in regional markets are holding their ground against offshore competitors as price parity narrows.

    Rival platform Temu has also stepped up pressure by broadening its product catalogue beyond apparel into general merchandise and home goods. That rivalry has inflated digital advertising acquisition costs across search and social channels, compounding the margin decline for pure-play fashion sellers.

    Inventory Risk Shifts to Local Warehouses

    To bypass package-level border scrutiny and lower delivery times, cross-border sellers must move bulk inventory into regional warehouses closer to target consumers. Doing so breaks the core mechanism that made Shein profitable: producing tiny batches on demand with zero local inventory carrying cost.

    Bulk sea shipping and local distribution centres demand working capital and introduce markdown risk on unsold inventory. Passing higher freight and warehousing expenses onto shoppers risks alienating the core demographic that uses the app strictly for bargain pricing.

    Losses in Early 2026 Followed by Weak Rebound

    The margin contraction follows a difficult start to the financial year. Shein posted a net loss of $99 million in the first quarter of 2026, reversing a $395 million net profit recorded in the corresponding period of 2025. Although the business returned to positive net income in the second quarter, profitability remains far below historic performance.

    Investors now await third-quarter trade volume data and customs clearance metrics ahead of the peak year-end holiday shopping quarter.

  • Target Lists 25,000 Items on Uber Eats for 60-Minute Delivery

    Target Lists 25,000 Items on Uber Eats for 60-Minute Delivery

    Target has expanded its fast-delivery options by offering more than 25,000 products on Uber Eats ahead of the holiday shopping period.

    As the first fashion retailer in Australia to partner with Uber Eats, Target expects orders to arrive within 60 minutes. The service will initially launch at 20 Target store locations in high-demand areas before expanding nationally.

    Store Shelf Pricing and Rapid Fulfilment

    Shoppers can order apparel, beauty products, homewares, toys, baby gear, and everyday staples directly via the Uber Eats app. Prices match in-store shelf tags, with standard Uber Eats service and delivery fees applied at checkout.

    Local stores will act as urban fulfilment hubs to support the service. Bypassing central warehouses lets the retailer turn existing shelf inventory into immediate digital supply.

    Bernard Wilson, chief commercial officer for Kmart and Target, said shoppers increasingly want flexible fulfilment that fits shifting daily schedules without advance planning.

    Expanding Department Store Reach

    Traditional department store operators face heavy competition from pure-play e-commerce platforms offering same-day parcel drop-offs. Using on-demand couriers cuts transit times from days to minutes. It also saves retailers from investing in dedicated last-mile transport fleets.

    This arrangement puts products directly in front of millions of active app users. Still, platform commission costs and service fees push final basket prices higher for consumers.

    Hardware and Discount Precedents

    Bunnings set an earlier precedent this year after adding more than 30,000 hardware products to the Uber Eats catalogue. Target has also integrated its clothing line into Kmart digital channels to capture cross-brand online traffic.

    Lucas Groeneveld, managing director of Uber Eats for Australia and New Zealand, noted that fast delivery is moving well beyond food into general merchandise. “Bringing Target onto Uber Eats means more of those everyday needs can arrive at their door in under an hour, making on-demand delivery useful for even more moments in their day,” said Groeneveld.

    Next Steps for National Expansion

    Service is now live across the initial 20 retail locations in metropolitan centres. Target plans to expand the delivery service to additional regional and suburban stores across Australia over the coming quarters.

  • Seoul High Court Clears Coupang Probe Amid $350 Billion US Talks

    Seoul High Court Clears Coupang Probe Amid $350 Billion US Talks

    The Seoul High Court on Wednesday rejected Coupang’s bid to suspend an on-site antitrust inspection, allowing South Korea’s Fair Trade Commission to proceed with its investigation.

    The ruling complicates talks between Seoul and Washington over the next stages of a planned $350 billion South Korean investment in the United States.

    Coupang had refused to cooperate with the probe, arguing that the regulator failed to provide advance notice. Following the court’s decision, FTC Chairman Ju Biung-ghi vowed to review internal agency rules to prevent companies from using court injunctions to evade or delay investigations.

    Court Clears On-Site Fair Trade Probe

    Ju rejected claims from Washington that Korean regulators are singling out American businesses. He affirmed that the watchdog enforces competition rules equally across domestic and foreign firms. The regulator opened its on-site probe in September following months of tension over platform compliance and supplier relationships. In June, Coupang secured FTC approval for a voluntary co-prosperity scheme tied to private brand supplier contracts. Broader compliance inquiries continued anyway.

    For digital platform operators across South Korea, the ruling establishes that procedural objections will not derail regulatory sweeps. Domestic rivals such as Naver and Shinsegae-backed SSG.com, alongside foreign entrants targeting the Korean market, face strictly enforced spot checks. Suppliers and merchants gain use against platform gatekeepers as regulators examine contract terms and distribution dominance.

    Scrutiny Strains Bilateral Investment Package

    Regulatory friction is now spilling into broader trade diplomacy between Seoul and Washington. Under a bilateral framework, South Korean conglomerates agreed to commit 350 billion dollars to US industrial projects in exchange for lower US tariffs on Korean exports. The two sides have already selected a 200 billion dollar gas-fired power facility in Texas. It will power data centres and semiconductor fabrication plants.

    Subsequent tranches of the investment deal remain subject to negotiations over financing, returns and government approvals. Those talks involve capital commitments in nuclear energy, Westinghouse technology partnerships and the Alaska LNG development. Heightened scrutiny on Coupang gives American trade officials use to demand protective carve-outs for US-domiciled technology companies operating in South Korea.

    Pressure Builds in Washington

    Political pushback in the United States has mounted steadily over the summer. A US House committee accused South Korean authorities in July of discriminating against Coupang. A US lawmaker also introduced draft legislation to sanction foreign regulators deemed to be targeting American corporations. Seoul maintains that all enforcement actions adhere strictly to domestic competition statutes, targeting business conduct rather than corporate nationality.

    South Korean President Lee Jae Myung met US President Donald Trump in New York on the sidelines of the UN General Assembly to review bilateral economic cooperation.

    The platform dispute remains a persistent flashpoint as both governments work to finalize the bilateral investment framework.

    What Lies Ahead for Platform Rules

    Attention now shifts to the FTC’s findings at Coupang headquarters and the pending rewrite of procedural inspection rules. RetailNews Asia will track whether the regulator levels formal financial penalties against the platform and how Washington incorporates tech sector protections into upcoming project rounds of the 350 billion dollar pact.

  • Buy&Ship Joins Tokyo Stock Exchange Hub as First Hong Kong Scale-Up

    Buy&Ship Joins Tokyo Stock Exchange Hub as First Hong Kong Scale-Up

    Hong Kong cross-border e-commerce platform Buy&Ship has joined the TSE Asia Startup Hub, becoming the first scale-up from the city to enter the Tokyo Stock Exchange program.

    The initiative gives the logistics and shopping platform institutional backing in Japan. That support comes as Buy&Ship builds retail partnerships, deploys artificial intelligence tools and evaluates a potential Tokyo initial public offering after recently securing a 12 million US dollar first closing in Series C funding.

    Expanding Japanese Logistics and Retail Routes

    Buy&Ship runs parcel-forwarding and cross-border shopping services across Asia. The service lets consumers buy directly from overseas merchants. Japan is one of its central sourcing corridors, driven by consumer demand in Hong Kong and Southeast Asia for Japanese goods.

    To support that volume, the company recently relocated its Japanese processing warehouse to Chiba. Joining the exchange hub gives the operator direct access to Japanese consumer brands seeking export channels without building their own international distribution networks.

    The Exchange Strategy for Asian Tech

    Tokyo Stock Exchange created the Asia Startup Hub to attract growth-stage companies with existing commercial ties to Japan. It connects regional tech firms with domestic underwriters, commercial partners and institutional capital. Through the program, the exchange aims to position Tokyo as a primary listing venue for Asian tech scale-ups.

    For Buy&Ship, the relationship provides corporate introductions and regulatory guidance foreign operators rarely secure alone. Cross-border platforms often face customs clearance hurdles, carrier contract limits and seller recruitment bottlenecks in Japan without domestic partners.

    Funding and Regional Scaling

    Cross-border commerce across Asia has shifted away from basic freight forwarding. Platforms now handle payment, customs, localization and return logistics under one roof. Those securing direct tie-ups with domestic brand owners capture higher margins than pure parcel consolidators.

    Regional logistics networks and domestic marketplaces are battling hard for parcel volumes across East Asian freight corridors. Direct integration with Japanese merchants gives specialized platforms a defensible product inventory that general freight forwarders cannot match.

    Earlier Capital and US Market Expansion

    Buy&Ship entered the exchange hub after securing a first closing of 12 million US dollars in Series C funding. That capital is financing its international expansion, including its entry into the United States market and upgrades to its software stack.

    Next, the platform will expand merchant onboarding programs in Tokyo while working through the exchange hub’s advisory track ahead of a planned public listing.

  • Amazon Rolls Out Agentic AI Service for Third-Party Sellers

    Amazon Rolls Out Agentic AI Service for Third-Party Sellers

    Amazon on Wednesday, September 25, 2026, introduced a new agentic artificial intelligence service for third-party sellers on its main e-commerce site, expanding automation for listing and inventory management.

    The service performs multiple actions with little to no human intervention and is free and optional for any seller to use, according to Amazon vice president Mary Beth Westmoreland.

    How the autonomous workflows operate

    Known as “workflows,” the system runs continuously through the Seller Assistant platform to carry out prompts such as alerting sellers if ratings drop, monitoring product pricing, and connecting to Anthropic’s Claude and Amazon’s Quick.

    Amazon built the capability into its Seller Assistant platform. The system stores merchant profiles to generate recommendations for discount schedules, promotions, and reorders.

    Integration with external models

    Plug-ins connect the service directly to third-party artificial intelligence platforms. The initial rollout supports connections to Amazon Quick and Anthropic’s Claude models.

    Mary Beth Westmoreland, vice president of worldwide selling experience at Amazon, said the agentic tool is free and optional for registered merchants. Sellers also control the volume of operational and personal account data shared with the system.

    Shift toward autonomous seller operations

    Platforms across Asia and Western markets already use generative tools for copywriting. Agentic systems shift the focus to operational execution. Cross-border sellers managing thousands of stock keeping units across multiple time zones can modify listings without waiting for staff review.

    Risks center on algorithmic errors and sudden price wars. Margin compression can accelerate across crowded product categories when thousands of automated agents adjust pricing at the same time.

    Platform automation timeline

    Over the past two years, platform automation has expanded from listing summaries to predictive warehouse inventory placement. Multi-step software agents represent the next stage in reducing support overhead.

    Adoption rates across North America, Europe, and Asia-Pacific regional hubs will determine whether Amazon expands plug-in access to more external AI models later this year.

  • Amazon Blocks Meta Shopping Bot as Agentic E-Commerce Hits $7.7 Billion

    Amazon Blocks Meta Shopping Bot as Agentic E-Commerce Hits $7.7 Billion

    Amazon has blocked Meta’s artificial intelligence agent Muse from its storefront. A platform battle is brewing as agentic e-commerce transactions reach 7.7 billion dollars globally in 2026.

    The dispute centers on unauthorized bot browsing, privacy safeguards, and proprietary customer access. Autonomous tools are starting to execute purchases without direct human navigation.

    Bot Access Battles at the Storefront

    Amazon stated that Muse entered its retail site without clearance, triggering security and privacy protocols. Meta disputed parts of the claim. It wants open access so Muse can compare listings and complete purchases directly for users.

    This conflict extends beyond simple web scraping. Retailers must now deal with autonomous agents that parse catalog data, evaluate pricing, and place binding orders within milliseconds. The shift turns digital storefronts from consumer destinations into backend suppliers for third-party software.

    To protect its ecosystem, Amazon deployed AgentCore Web Bot Auth. The system uses cryptographic verification to evaluate incoming bots and enforce merchant access rules. Simultaneously, the Fast Identity Online alliance began drafting authentication standards to govern automated purchasing agents across retail domains.

    India Prepares Infrastructure for Automated Orders

    In India, the operator of the Unified Payments Interface is developing protocols to clear AI agents for independent payment execution. This blueprint will govern automated consumer spending across domestic retail networks.

    Domestic platforms including Flipkart, Reliance, Meesho, and Myntra face immediate commercial exposure. When autonomous agents replace human shoppers, traditional revenue drivers lose impact. Search ads, sponsored placements, and banner promotions suddenly carry less weight.

    Market power shifts toward the entities controlling the primary agent interface. If a few dominant models decide which merchants surface during an automated query, regional sellers risk losing direct relationships with shoppers. Their only defense may be launching proprietary purchasing bots of their own.

    Legal Precedents and Security Thresholds

    Cyber boundaries around retail data access remain contested in court. In August, a United States appeals court lifted a preliminary injunction that had restricted search startup Perplexity from deploying agentic browsing across Amazon’s catalog. The broader legal dispute remains unresolved.

    Platform operators now face a dual risk. Allowing unrestricted bots creates cybersecurity vulnerabilities and inventory distortion. Conversely, erecting restrictive technical firewalls reduces merchant visibility across emerging consumer search platforms.

    Attention now shifts to whether the UPI automated payment framework establishes workable compliance benchmarks before major marketplaces implement universal bot blocks across South Asia.

  • Lazada Maps Carbon Footprint and Claims 1.1 Million Ecosystem Roles

    Lazada Maps Carbon Footprint and Claims 1.1 Million Ecosystem Roles

    Lazada Group logged 1.1 million economic roles across its Southeast Asian e-commerce network. The tally appeared in its inaugural sustainability report alongside its first operational greenhouse gas baseline.

    This benchmark inventory covers operations in Indonesia, Malaysia, the Philippines, Singapore, Thailand and Vietnam. It forms the foundation for a wider decarbonization plan.

    Carbon accounting and logistics operations

    Prepared against the Global Reporting Initiative Standards 2021, the FY2022 review details the group’s first group-wide carbon inventory. The baseline identifies primary emission sources across fulfillment hubs and transport networks. That data will help steer fleet contracts toward third-party logistics operators using electric vehicles.

    Packaging reduction programs ran alongside the emissions audit. In the Philippines, the LazGoGreen initiative recorded sales of 70,000 alternative material pouches in March 2020. Thirty-five sellers switched entirely away from conventional plastics. By the end of that year, 18 national plastic collection hubs were operational.

    Merchant enforcement and counterfeit screening

    On compliance, a dedicated Intellectual Property Rights team introduced automated detection tools in March 2020. That system removed 98 percent of flagged counterfeit listings in 2021 before shoppers completed a transaction.

    Information security across the six regional markets secured certification under the ISO 27001:2013 standard. Local business units also ran joint consumer data protection campaigns with state agencies. Partners included the Department of Trade and Industry and the National Privacy Commission in Manila.

    Workforce programs and regional read-across

    Merchant training ran through Lazada University alongside the Lazada Learning Festival 2022 for small businesses. Separately, a specialized technical scholarship with For The Women placed 70 percent of its female data science graduates into formal technology positions.

    Emissions tracking gives institutional investors standard data points, but implementation across independent fleets remains uneven. Company-owned sorting centers can enforce strict packing rules. Even so, tens of thousands of third-party merchants still use standard plastic mailers because sustainable alternatives cost more per unit.

    Rival platforms face identical packaging friction across Southeast Asia. Low average order values make merchants resistant to packaging surcharges. Marketplaces that mandate compliance without absorbing packaging overhead risk driving small vendors toward competing platforms.

    Corporate footprint across Southeast Asia

    Founded in 2012, Lazada became the Southeast Asian flagship platform for Alibaba Group in 2016. Over the following decade, the marketplace built proprietary logistics and payments infrastructure across six core territories. It now runs localized operations in each market.

    Operations across the region are geared toward a target of serving 300 million consumers by 2030.

  • Shein Net Profit Drops 67 Percent to 228 Million Dollars as Air Freight Squeezes Margins

    Shein Net Profit Drops 67 Percent to 228 Million Dollars as Air Freight Squeezes Margins

    Shein reported a 66.6 per cent slump in second-quarter adjusted net profit to $228 million, hit by surging air cargo rates and falling revenue in Western markets.

    Net profit margins narrowed to 2.1 per cent from 6.2 per cent a year earlier, even as the platform fulfilled 298 million orders between April and June.

    Group revenue inched up 0.9 per cent year-on-year to $11.08 billion during the period. Active customers climbed to 291 million over the 12 months to June, up from 254 million, but shoppers spent less per order while overhead surged.

    Higher shipping costs hit the bottom line

    Fulfillment costs surged 18.1 per cent during the three-month period. Shein relies on direct air shipments from contract factories in southern China to consumers worldwide, leaving operating margins exposed to sudden swings in aviation fuel and commercial cargo pricing caused by Middle East route disruptions.

    Growth in Latin America compensated for contractions in primary markets, preventing top-line sales from shrinking outright. Total order volume increased by 21 million transactions compared with the second quarter of last year.

    Tariffs and parcel fees bite in the West

    Revenue from Europe fell 13.9 per cent to $3.77 billion as Shein pulled back on digital marketing spend and lifted retail prices ahead of regional regulatory changes. The European Union introduced a flat 3-euro customs fee on low-value e-commerce packages on July 1.

    United States revenue declined 6 per cent to $2.5 billion. Price adjustments followed the removal of de minimis duty exemptions by US authorities, which had previously allowed parcels valued under $800 to enter the country free of import tariffs.

    Warehouses and premium labels

    Cross-border operators in Asia now face the end of the frictionless air-freight model that built ultra-fast fashion. Temu and AliExpress face identical regulatory scrutiny in Brussels and Washington, but Shein carries heavier direct inventory risk as it attempts to reposition itself toward higher-priced apparel categories.

    Shifting higher up the price ladder creates direct competition with established European apparel chains such as Inditex and H&M without guaranteeing the same local store network or brand equity. Shein must absorb heavy fixed property costs across Europe while defending its low-cost apparel base against newer discount apps.

    Hong Kong stock slides

    The company listed in Hong Kong on September 1 at an offer price of HK$48.56 per share. Trading has dropped 27.3 per cent since the debut, reflecting investor concern over margin erosion and sluggish Western revenue.

    To reduce dependence on individual air parcels, the group is expanding land-based logistics hubs inside the European Union. Shein opened a 740,000-square-metre distribution facility in Wroclaw, Poland, in December and leased an additional 66,000 square metres of warehouse space from industrial developer CTP earlier this year.

    Investors now await third-quarter earnings figures in November, which will show the full impact of the European Union’s 3-euro parcel surcharge during the peak autumn trading period.

  • Shein Second Quarter Profit Plunges 67 per Cent to US$228 Million

    Shein Second Quarter Profit Plunges 67 per Cent to US$228 Million

    Shein posted an adjusted net profit of US$228 million for the second quarter, down 67 per cent from a year earlier. Freight costs surged while sales across Europe fell.

    Net margin shrank to 2.1 per cent from 6.2 per cent a year ago. Flying low-cost parcels directly from Asian factories to consumers worldwide became far more expensive. Total revenue edged up 0.9 per cent to US$11.08 billion for the three months to June 30. Gains in Latin America counterbalanced declining receipts in Western markets.

    European sales dropped 13.9 per cent to US$3.77 billion during the quarter. The retailer raised prices and trimmed marketing budgets across the region ahead of July 1, when the European Union introduced a 3-euro customs charge on low-value parcels. United States revenue declined 6 per cent to US$2.5 billion. That drop continued a slide that began after American authorities ended duty-free treatment under de minimis rules last year.

    Air Freight and Customs Squeeze Margins

    Conflict in the Middle East disrupted aviation routes and pushed up jet fuel prices. That drove an 18.1 per cent increase in quarterly fulfillment costs. Shein’s direct-to-consumer model depends entirely on affordable air cargo capacity out of southern China. When air freight rates spike, the margin on five-dollar apparel vanishes.

    Shares in Hong Kong have fallen 27.3 per cent below their HK$48.56 offer price since the company went public on September 1. Institutional investors had already priced in regulatory scrutiny. Even so, the rapid deterioration in core operating earnings caught market analysts off guard.

    European Warehouses and On-the-Ground Logistics

    Shein is shifting inventory onto European soil to insulate operations from cross-border customs fees and volatile air cargo rates. The group opened a 740,000-square-metre logistics hub in Wroclaw, Poland, in December. It secured an additional 66,000 square metres of Polish warehouse space through developer CTP earlier this year.

    Holding stock locally cuts delivery transit times and skirts per-parcel import tariffs. Yet it also creates lease liabilities and inventory holding risks the platform once avoided. For suppliers in Guangdong province, bulk sea shipments to European distribution centres require longer production planning cycles. That slows down the ultra-fast test-and-reorder batches that built the brand.

    Pivot to Higher Price Points and Brand Acquisitions

    Executive leadership plans to adjust the product catalogue toward higher price tiers to rebuild profitability. Moving beyond ultra-cheap garments requires winning market share from established mid-market apparel groups. It also means managing higher marketing and acquisition costs.

    “As the product mix shifts towards brands at higher price points, the platform’s overall average selling price will rise accordingly,” Shein chief executive and chair Yangtian Xu said in a statement.

    Potential fast-fashion acquisition targets are under review as the company seeks to build a portfolio of distinct labels across different price tiers. Buying regional brands gives the group immediate recognition in overseas territories. It avoids relying purely on paid online advertising to acquire customers.

    Next Steps on Customs and Third Quarter Results

    Second-quarter figures reflect business conditions before the European Union’s 3-euro parcel levy took effect in July. Shein cautioned that the full financial hit could exceed the disruption caused by the end of American de minimis exemptions.

    Investors will watch third-quarter trading updates to see whether European warehouse operations can restore gross margins before the peak year-end holiday shopping rush.

  • JD.com Pushes Past 700 Million Active Shoppers on Repeat Buying

    JD.com Pushes Past 700 Million Active Shoppers on Repeat Buying

    JD.com has passed 700 million annual active customers in China. It is expanding offline stores and after-sales networks to generate repeat business beyond discount promotions.

    During the 2025 11.11 shopping festival, the Beijing-based group lifted shopper numbers by 40 per cent year on year. Order volumes climbed nearly 60 per cent across digital and physical channels.

    Building Out Physical Malls and Services

    Customer retention now relies on in-house procurement, fulfilment, and post-purchase service rather than livestream discounts alone. That operational backbone gave JD.com an edge in high-consideration categories like smartphones, personal computing, and home appliances. In these segments, punctual delivery and installation support drive buyer choices.

    Store expansion through JD Mall sites and electronics outlets now runs alongside new service categories. The group added food delivery, travel bookings, and home repair services to generate daily touchpoints that funnel transactions into core retail channels.

    Targeting High-Value Brand Alliances

    Pitching cross-border trade to international suppliers, the platform is targeting high-retention consumer tiers. Marcia Mao of JingDong Cross-Border spoke at the 2026 UK-China Brand Excellence Summit. She told overseas merchants that sustainable entry requires targeting specific buyer profiles instead of chasing raw traffic.

    This strategy contrasts with rivals using heavy subsidies and flash sales to inflate gross merchandise volume. JD.com gives foreign brands direct control over inventory authenticity and customer service. That protects brand equity while domestic consumer spending stays cautious.

    Running owned warehouses, installation crews, and shopping centres in lower-tier cities carries steep capital costs. Competing discount platforms run asset-light marketplaces with lower take-rates. Those setups give sellers cheaper entry points when consumer demand for general merchandise softens.

    From Scale to Shopping Frequency

    JD.com built its scale by investing billions of yuan in nationwide logistics hubs, promising next-day delivery across hundreds of mainland cities. The network proved essential when domestic e-commerce competition escalated in 2024. The group defended market share by turning reliable service into repeat purchases.

    Chief executive Sandy Xu pointed to user engagement as the main driver for the company’s next stage of growth.

    “We are also seeing encouraging signs from new initiatives, and we believe these emerging opportunities will further position us for long-term, high-quality growth,” Xu said.

    The Next Test for Everyday Consumption

    Management now faces the challenge of converting foot traffic from regional JD Malls into daily online orders across tier-two and tier-three cities.

  • Marketplaces Surpass Specialist Beauty Retailers in Australia as Online Market Nears $2.2B

    Marketplaces Surpass Specialist Beauty Retailers in Australia as Online Market Nears $2.2B

    Marketplaces outpaced Australia’s leading beauty chains online for the first time in late 2025, taking e-commerce sales past the combined total of Mecca, Sephora, Adore Beauty and Chemist Warehouse.

    The shift comes as Australia’s online beauty and personal care market heads toward 47 per cent growth to reach $2.2 billion by 2030, according to Pattern’s State of Beauty & Personal Care in Australian Ecommerce report.

    Amazon Expands Category Grip

    Online marketplaces generated roughly $200 million in Australian beauty sales during the fourth quarter of last year. That total cleared the $199.3 million recorded by Mecca, Sephora, Adore Beauty and Chemist Warehouse combined.

    Amazon drove much of the advance. Its local beauty and personal care turnover rose by $66.7 million year on year, lifting the marketplace operator to a 19.9 per cent share of Australia’s total online beauty spend.

    Shopper intent points to further gains. Pattern found 71 per cent of Australian digital beauty shoppers plan to purchase products on Amazon over the next twelve months, while 43 per cent say they will switch to an alternative brand if their first choice is out of stock.

    Consumers aren’t thinking about a brand’s distribution strategy. They simply expect beauty products to be available through the channels they use, and they’re willing to switch brands for that convenience.

    Fragmented Social Discovery Funnels

    Discovery patterns are pulling shoppers away from traditional storefront browsing. Nearly half of surveyed beauty shoppers reported buying items based on creator recommendations, compared to just 15 per cent across non-beauty retail sectors.

    Instagram and Facebook each shaped purchase intent for 47 per cent of beauty shoppers, followed closely by YouTube and TikTok. Yet discovering an item on social networks rarely results in a direct in-app checkout.

    Instead, 39 per cent of buyers who spot products on social feeds complete their transactions on standalone retailer or brand websites. Another 32 per cent head directly to Amazon to finish the order.

    Algorithmic Search and AI Assistants

    Artificial intelligence assistants are now actively routing consumer purchase paths. The data shows 38 per cent of Australian beauty shoppers use AI tools more frequently than they did last year to search for products online.

    Roughly 27 per cent of consumers have relied on ChatGPT or comparable conversational tools to research or buy cosmetics, and 55 per cent express confidence in AI-generated product advice. Global beauty conglomerates are taking notice: Estée Lauder Companies recently partnered with marketing startup Profound to optimize brand visibility across generative platforms including ChatGPT and Google Gemini.

    What the Shift Means for Specialty Retail

    For dedicated beauty retailers, the loss of market share to general merchandise marketplaces threatens the high-margin basket sizes that have long supported domestic store networks. Department stores and specialty chains can no longer rely on exclusive supplier arrangements to protect digital footfall when marketplace logistics offer faster shipping and lower barriers to checkout.

    Brand owners face an equally sharp operational trade-off. Direct-to-consumer storefronts carry heavier customer-acquisition costs as search engines and social platforms shift toward algorithmic discovery, forcing brands to list on Amazon or risk losing sales to competing formulations.

    The critical metric for retailers heading into 2027 will be whether specialist chains can defend their remaining 80 per cent market share as marketplace volume accelerates toward the $2.2 billion category ceiling.

  • Southeast Asia Savvy Online Shoppers Spend 31% More at $11.5 Billion

    Southeast Asia Savvy Online Shoppers Spend 31% More at $11.5 Billion

    Discerning online buyers in Southeast Asia spend 31 per cent more each month than general consumers. Across six regional economies, they will generate 11.5 billion dollars in annual marketplace sales in 2026.

    A joint study from Lazada and commerce analytics group Cube defines roughly 24 per cent of regional consumers as savvy shoppers. Another 18 per cent sit immediately below that threshold. These buyers demonstrate distinct commercial habits. They cross-check merchandise across channels, inspect merchant credentials, and routinely pay premiums for guaranteed authenticity and transaction safeguards.

    How purchasing behavior splits across markets

    Penetration of these higher-spending consumers varies widely by country. The Philippines leads Southeast Asia with 36 per cent of its online buyers qualifying as savvy. Indonesia follows at 28 per cent and Vietnam at 25 per cent. Thailand registers 22 per cent, while Malaysia records 20 per cent. Singapore sits at the bottom of the regional ranking at 9 per cent.

    Friction points also differ across borders. Shoppers in Malaysia and Vietnam report product verification as their primary hurdle during online purchases. Buyers in Singapore, Indonesia, and the Philippines cite buyer protection and seller confidence as their main challenges. Thai consumers report an even split between verification and security concerns.

    Value replaces pure price discounts

    Shoppers across Southeast Asia show an increased willingness to invest time to secure better transactions. About 43 per cent of surveyed consumers spend extra time searching for improved offers. Another 41 per cent delay purchases to find better timing. Meanwhile, 36 per cent conduct detailed price comparisons before checking out.

    Price concessions lose traction when they compromise trust. Only 14 per cent of consumers say they would sacrifice authenticity indicators for a lower price. Just 13 per cent would forfeit purchase protections to obtain a steeper discount. Among savvy buyers, 47 per cent state they will pay extra fees for certified order protection, compared to 30 per cent among general consumers.

    Discovery moves outside marketplace walls

    Transaction journeys now start well before buyers enter marketplace apps. The study finds that 83 per cent of savvy consumers discover products outside primary marketplace catalogs, compared to 42 per cent of general buyers. 86 per cent consult third-party information channels during purchase evaluation. A full 91 per cent verify seller track records across external web sources.

    Savvy consumers also buy more frequently and spread their spending across competing channels. Some 58 per cent shop online several times each week, compared to 35 per cent of baseline consumers. Mall environments capture 53 per cent of this cohort, compared to 40 per cent for general shoppers. Multi-homing is standard practice. About 82 per cent of savvy shoppers actively use all three major marketplace platforms across the region, against 61 per cent among the general shopper base.

    Commercial demands on digital merchants

    For marketplace merchants and brand principals, the findings demand a recalibration of promotional spending. Pure discounting drives immediate volume. However, higher-value shoppers demand verified supply chains, fast dispute resolution, and consistent branding across external touchpoints before committing their baskets.

    “Southeast Asia’s eCommerce market is no longer defined by whether consumers shop online, but by how confidently and effectively they do so,” said Simon Torring, Co-Founder of Cube.

    Platform operators now face the operational task of retaining these multi-homing consumers as growth shifts from user acquisition to basket optimization. Marketplaces that fail to guarantee authenticity will see the most profitable quartile of regional demand migrate to rival platforms offering tighter brand verification standards.

  • Coupang Reaches 34.5 Billion Dollars in Sales as Margin Squeeze Drags Valuation

    Coupang Reaches 34.5 Billion Dollars in Sales as Margin Squeeze Drags Valuation

    Coupang generated 34.5 billion dollars in revenue across South Korea and regional markets in fiscal 2025. Growth followed expansion in Taiwan and luxury retail.

    Sales climbed 14.1 percent year on year. Net income finished at roughly 208 million dollars, leaving the group operating on a net margin of 0.6 percent.

    The Seoul-based e-commerce operator relies heavily on its WOW subscription program. It pairs proprietary logistics with midnight-to-morning dawn delivery across densely populated South Korean metro districts. The company also runs its own fintech payment rail and operates luxury marketplace Farfetch, acquired to seed a cross-border fashion offensive.

    Cash flow and margin pressure

    Balance sheet disclosures for December 2025 show a current ratio of 1.0x, leaving short-term assets equal to short-term obligations. Debt-to-equity stood at roughly 1.0x at year-end. Free cash flow reached 522 million dollars for the fiscal period. Stock-based compensation accounted for 26.8 percent of operating cash flow, reflecting non-cash add-backs rather than cash conversion from retail sales.

    Gross margin held at 28.35 percent. Logistics expenditures, customer acquisition costs, and Farfetch integration costs continue to compress bottom-line profit. The stock dropped to 13.88 dollars, sitting at the bottom of its 52-week trading band between 13.88 dollars and 32.96 dollars. Market capitalisation now stands at 26 billion dollars.

    Regulatory exposure and security fallout

    Domestic operating risk escalated after a November 2025 data breach affected 33 million user accounts. The incident triggered regulatory reviews in Seoul. The Fair Trade Commission and labor authorities already maintain scrutiny over marketplace practices and courier working conditions.

    Legal exposure for corporate leadership remains an active concern under South Korean commercial codes. Foreign exchange fluctuations also shaved earnings value as the South Korean won weakened against the dollar. That compounded price competition from domestic rivals and global platforms such as Amazon.

    The Taiwan expansion and luxury play

    South Korea’s high digital retail penetration leaves limited runway for volume expansion at home. Geographic diversification has become essential for Coupang’s capital spending. Management has directed fulfillment investment into Taiwan, deploying its automated logistics blueprint in Taipei to test whether delivery speed can outmuscle incumbent Southeast Asian platforms.

    Buying Farfetch gave the group direct access to European luxury supply channels. Turning around the loss-making fashion portal while funding warehouse construction in Taiwan absorbs capital that could otherwise bolster operating cash.

    Valuation gap against regional peers

    Investors price Coupang at a forward price-to-earnings multiple of 71.4x. This reflects high expectations for earnings recovery despite a trailing price-to-sales multiple of 0.7x. By comparison, Latin American peer MercadoLibre trades at a forward price-to-earnings multiple of 32.8x. It generated 2.0 billion dollars in net income on 39.1 percent revenue growth to 28.9 billion dollars.

    Public equity markets place a clear premium on embedded fintech profitability over asset-heavy logistics networks that operate with sub-one-percent net margins. Coupang’s revenue expanded from 24.4 billion dollars in 2023 to nearly 34.5 billion dollars in 2025. Its next filing must demonstrate that overseas volume in Taiwan can generate operating use without further diluting returns.

  • Amazon Commits $3 Billion to India Quick Commerce Expansion by 2030

    Amazon Commits $3 Billion to India Quick Commerce Expansion by 2030

    Amazon will invest $3 billion to expand its Indian quick commerce operations through 2030. The outlay funds a direct push into instant urban delivery. Currently, the company holds a 6.2 percent share of India’s $19 billion instant delivery market. It trails domestic operators who pioneered sub-hour fulfillment.

    Under the spending plan, $1 billion will roll out by the end of 2027, followed by another $2 billion through 2030. Capital flows straight to the Amazon Now network. The platform will grow its neighborhood distribution footprint from roughly 750 hubs to 1,300 locations by April next year. Funds will also back automated store-level inventory management, artificial intelligence forecasting tools, and wider selection across fast-moving consumer lines.

    Internal sales data shows Amazon Now generated over $1 billion in annualized gross merchandise value during the past three months. The platform still faces entrenched competition. Eternal’s Blinkit, Swiggy, and Zepto command a combined 77 percent market share across more than 4,500 dark stores. Walmart-backed Flipkart controls 11 percent through a network exceeding 1,000 facilities.

    Dark Store Economics and Inventory Strategy

    Hub designs center on repeat grocery orders rather than high-ticket goods. Domestic rivals stock smartphones and appliances for delivery within minutes. Amazon Now focuses strictly on household essentials, dairy, and fresh produce. Each site uses dedicated cold storage rooms instead of commercial refrigerators to limit spoilage.

    That product mix brings real financial trade-offs. Brokerage Bernstein noted in July that grocery-only models struggle to cover fulfillment expenses because average order values stay low. Non-grocery merchandise provides the margins needed to offset courier wages. By skipping high-value electronics, Amazon avoids inventory depreciation, but it sacrifices basket size.

    Suppliers must navigate a fractured distribution channel. Staple brands gain access to automated replenishment systems. Yet rapid fulfillment forces vendors to split inventory across hundreds of localized micro-warehouses instead of central regional hubs. This dispersion drives up working capital requirements for packaged food makers and distributors across tier-one cities.

    Regulatory Pressure and Platform Conversion

    Indian regulators are tightening scrutiny across the quick commerce sector. In January, authorities ordered platforms to pull marketing campaigns touting 10-minute delivery guarantees following traffic safety concerns for two-wheeler couriers. Platforms must now compete on product range and pricing instead of raw speed.

    Foreign ownership rules create another hurdle. Marketplace regulations bar foreign-funded platforms from holding direct inventory. At the same time, Amazon is contesting a 2024 antitrust finding from the Competition Commission of India over alleged preferential treatment given to select sellers.

    Price cuts are the opening weapon against entrenched domestic rivals. Amazon is running discounts directly inside its main smartphone app. The platform offers 20 percent cashback on first orders above 499 rupees ($5.20), alongside free delivery on purchases over 99 rupees ($1) for select customer cohorts.

    “It took some time for Amazon to commit. There appears to be a realization that this is a model they have to invest in,” said Satish Meena, founder of Datum Intelligence. “They are doing discounts, which can help lure current Amazon customers to quick commerce.”

    Market Projections and Operational Milestones

    Growth in India’s instant delivery sector took off from localized grocery networks in 2022. Datum Intelligence projects the market will expand from $19 billion to $41 billion by 2030. The shift has transformed consumer habits across Mumbai, New Delhi, Bengaluru, and secondary metros. It continues to pull transaction volume away from traditional neighborhood kirana stores and scheduled e-commerce routes.

    Flipkart launched its own counter-offensive earlier this year, expanding sub-hour delivery into suburban clusters ahead of a planned public listing. Amazon arrived late. It is banking on its core Prime subscriber base converting to Amazon Now once local fulfillment hubs are in place.

    April next year brings the first major operational deadline, when Amazon targets completing its 1,300-store footprint across Indian metros. Hitting that network target will decide how much market share the Seattle retailer captures before the $41 billion sector structure hardens.