Category: Finance

Retail News Asia is committed to providing both local and global retailers with the latest Finance news throughout the Asian market. This on a daily base.

  • Gold Prices Remain Resilient Amid Declining Global Market Trends

    Gold Prices Remain Resilient Amid Declining Global Market Trends

    Vietnamese gold prices maintained stability on Friday, even as global bullion rates experienced a slight dip.

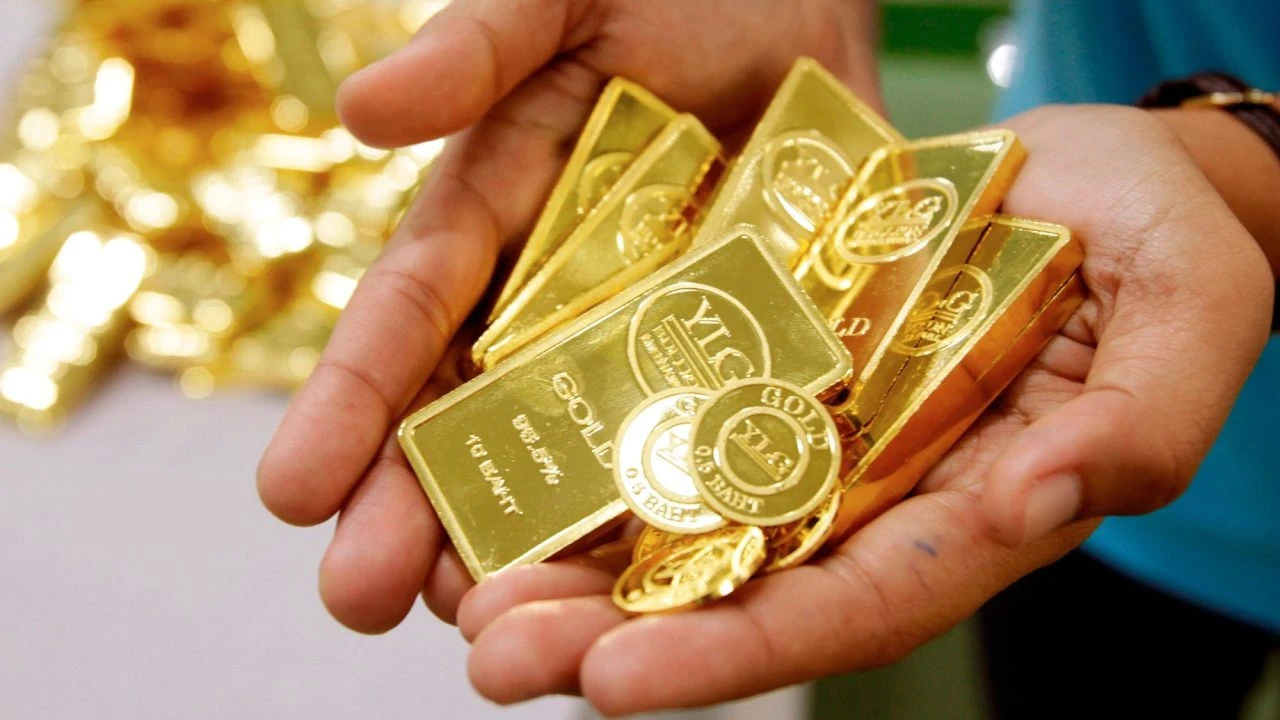
    In the bustling streets of Ho Chi Minh City, the Saigon Jewelry Company reported its gold bar price at VND121.7 million (approximately US$4,655.79) per tael. Meanwhile, the price for gold rings held steady at VND117.5 million per tael—a tael being 37.5 grams or 1.2 ounces. The local market stood strong despite global fluctuations, demonstrating the resilient appetite for gold among Vietnamese consumers.

    Globally, gold prices edged lower due to positive developments in trade discussions between the U.S. and its partners, which dampened demand for safe-haven assets. As optimism surged over trade negotiations, the price of spot gold slipped 0.3% to $3,356.75 per ounce, while U.S. gold futures fell slightly by 0.4%, settling at $3,358.60.

    Kelvin Wong, a senior market analyst at OANDA, noted that profit-taking by short-term bullish speculators was helping to drive these changes. “We’re seeing some profit-taking in the context of growing trade-deal optimism,” Wong explained. Nevertheless, he emphasized that the dollar’s weakening trend and ongoing Federal Reserve rate cuts are bolstering gold prices near the $3,360 mark.

    As investors navigate these shifting waters, curiosity lingers over if gold will truly glimmer brighter once the trade dust settles—after all, in retail, the unexpected can often be just around the corner.

    Questions & Answers

    What were the gold prices reported by the Saigon Jewelry Company?
    The Saigon Jewelry Company reported its gold bar price at VND121.7 million (around US$4,655.79) per tael, while gold rings remained at VND117.5 million per tael.

    What influenced the recent decline in global gold prices?
    Global gold prices dipped due to signs of progress in trade negotiations between the U.S. and other trading partners, which reduced the demand for safe-haven assets.

    How are Federal Reserve rate cuts affecting gold prices?
    The ongoing Federal Reserve rate cuts are providing support for gold prices, keeping them near the $3,360 level despite the recent downward trend.

  • ECB Adopts Flexible Stance, Exploring All Avenues for Future Monetary Policy

    ECB Adopts Flexible Stance, Exploring All Avenues for Future Monetary Policy

    ECB Holds Steady Amid Economic Whirlwinds

    The European Central Bank (ECB) has decided to maintain its current interest rates, a move that many analysts anticipated given the prevailing uncertainties clouding the economic forecast. In a statement released Thursday, the ECB outlined its intentions to adopt a data-driven approach when making future rate adjustments.

    The most recent data has largely reaffirmed the ECB’s previous outlook on inflation, indicating a gradual easing of domestic price pressures alongside a slowdown in wage growth. Inflation now hovers around the ECB’s medium-term target of 2 percent.

    Navigating Through Uncertainty

    Despite a cautious stance, the ECB highlights a landscape fraught with unpredictability, particularly related to ongoing trade tensions. Nevertheless, the eurozone economy has demonstrated resilience—thanks in part to earlier interest rate reductions that the Governing Council views as a hallmark of its monetary policy success.

    Commitment to Inflation Stability

    The ECB remains steadfast in its goal to stabilize inflation at the target level in the medium term but is careful not to pin itself down to any predetermined course of action. Decisions regarding future rates will be guided by incoming economic data, allowing for flexibility in its approach.

    As it stands, the interest rates in the euro area remain unchanged as follows:
    › Deposit facility rate: 2.00 percent
    › Main refinancing operations rate: 2.15 percent
    › Marginal lending facility rate: 2.40 percent

    Looking ahead, the ECB’s next monetary policy meeting is slated for September, right after the summer break. Economists are already buzzing with debates about whether another rate cut will be on the table. The outcome remains murky, with compelling arguments both supporting and contesting the notion.

    For one, inflation could drop further thanks to base effects from energy prices, while a strengthening euro against the dollar might give a leg up to cheaper imports—delivering a double whammy of influence on price levels.

    The Ripple Effect of EU-US Trade Talks

    The broader economic outlook is closely tied to the ongoing trade negotiations between the EU and the United States. The uncertainty surrounding these discussions could stifle economic growth, hinder corporate investment, and dampen consumer sentiment across the eurozone. A sluggish demand could further complicate the economic picture.

    Whether this current pause in the easing cycle marks a temporary break or the conclusion of a longstanding trend hinges on macroeconomic data as we head into autumn. For the time being, the ECB is keen to keep its options open—a methodical game of chess in the complex world of monetary policy.

    Questions & Answers

    What factors influenced the ECB’s decision to keep interest rates unchanged?
    The ECB’s decision was primarily influenced by ongoing uncertainties surrounding the economic outlook, inflation levels, and trade tensions, along with recent data confirming its previous assessments of inflation.

    What are the current interest rates set by the ECB?
    The ECB has maintained the following rates: Deposit facility rate at 2.00 percent, main refinancing operations rate at 2.15 percent, and marginal lending facility rate at 2.40 percent.

    How might EU-US trade negotiations impact the eurozone economy?
    Uncertainty in trade negotiations could hinder economic growth and affect corporate investment and consumer sentiment, potentially leading to weaker demand throughout the eurozone.

  • Swiss Banks Face Growing Concerns: A New Challenge on the Horizon

    Swiss Banks Face Growing Concerns: A New Challenge on the Horizon

    The New Challenge Facing Swiss Banks: Operational Resilience

    Swiss banks are currently grappling with a pressing issue: operational resilience. This concern has intensified, not only due to tightening regulations emanating from the EU but also because of real-world events that have shaken confidence in banking infrastructure. A recent blackout in Spain and Portugal highlighted vulnerabilities in modern banking systems, shifting the conversation from hypothetical scenarios to stark realities.

    Operational resilience, while a cumbersome term, has become a focal point in the IT departments of Swiss financial institutions. These banks are now tasked with shielding themselves from an array of technical risks, such as cyberattacks—think DDoS attacks targeting e-banking—outdated legacy systems, and a growing reliance on cloud providers. As new regulatory requirements for data protection and overall resilience come into effect, the pressure is mounting.

    Blackout: A Wake-Up Call for Banks

    The implications of power outages have taken on new significance. Historically viewed as an unlikely disaster, the blackout that struck Spain and Portugal on April 28 changed the game. “This is no longer a theoretical risk; banks have finally realized such an event could very well occur in our region,” says Henning Gebert, a digitalization expert at Capco, a management and technology consulting firm that assists financial institutions in their digital transformation efforts.

    Since the blackout, numerous Swiss banks have sought Gebert’s expertise. They urgently require stress tests to assess their vulnerabilities. The incident underscored several critical shortcomings:

    Firstly, many branches either lacked adequate uninterruptible power supplies (UPS) or were not prepared for short outages, leading to significant disruptions. With cash availability being a crucial backup during severe crises, it’s vital that contingency plans for cash logistics are established ahead of time. Secondly, during the blackout, redundancy systems seemed to be the privilege of larger institutions; many branch offices were left paralyzed when mobile and internet connections failed, crippling point-of-sale systems. Finally, while banks’ core payment infrastructure remained intact, customer access was gravely limited, effectively nullifying cash withdrawal capabilities at ATMs and branches.

    “In such situations, it’s critical that systems can autonomously restart without relying on external authentication, which typically falters during a blackout,” Gebert explains, emphasizing the need for robust internal systems.

    New Regulations Adding Pressure

    The stakes are high for banks that fail to bolster their IT security measures. Not only do they risk operational outages, but they also face the potential of hefty fines and substantial reputational damage. The Digital Operational Resilience Act (DORA) implemented in January, has brought forth stricter regulations for banks, insurers, and asset managers across the EU. It mandates rigorous ICT risk management, standardized incident reporting, resilience testing, and stringent guidelines for outsourcing IT services.

    Swiss Banks Caught in the Crossfire

    Though Swiss banks are not directly bound by DORA, they are nevertheless affected. They must adapt their governance frameworks, IT contracts, and processes to comply with these evolving standards or risk exclusion as third-party providers in the future. DORA’s cross-border implications are undeniable, even without a direct EU mandate.

    Gebert notes a marked increase in awareness among banks post-blackout. The clarion call for action has become too loud to ignore, and it appears Swiss institutions are finally ready to plot a more resilient path forward. After all, in the world of finance, it’s always wise to be prepared for the unexpected—even if that means wrestling with the jargon of operational resilience.

    Questions & Answers

    Why is operational resilience becoming a critical issue for Swiss banks?
    Operational resilience is under scrutiny due to increasing regulatory pressures, highlighted by recent power outages that exposed vulnerabilities in banking infrastructure.

    What were some key challenges faced by banks during the recent blackout?
    Banks struggled with inadequate uninterruptible power supplies, reliance on outdated systems, and failed connectivity that left many customers unable to access cash or banking services.

    How are new EU regulations impacting Swiss financial institutions?
    The Digital Operational Resilience Act (DORA) compels Swiss banks to adapt governance and IT protocols to avoid exclusion as third-party providers, even though they are not directly mandated to follow it.

  • Just 4% of Insurers Fully Trust AI Agents Amid Rising Enthusiasm for Technology

    Just 4% of Insurers Fully Trust AI Agents Amid Rising Enthusiasm for Technology

    In a revealing new report from the Capgemini Research Institute, the insurance industry finds itself at a crossroads regarding the adoption of AI technology. While the potential for transformation remains vast, with a $450 billion opportunity on the horizon, the current implementation is far from robust. Shockingly, only 10% of insurance organizations have partially or fully deployed AI agents, and a further 20% are merely dipping their toes into pilot projects.

    AI Adoption Left in the Dust

    A significant portion of the industry—42% of insurers—has yet to define a formal strategy for integrating AI agents into their operations. As excitement brews within the sector for what is termed Agentic AI, many firms still grapple with the early stages of adoption, revealing a pressing need for clear implementation roadmaps.

    Where Insurers Expect AI to Shine

    Despite the rocky terrain, there is optimism about the role AI could play in daily operations. Sales and customer service emerge as frontrunners, with 52% and 57% of insurers, respectively, anticipating that AI agents will manage at least one process daily in these areas. Yet, despite these lofty expectations, trust in AI technology remains disturbingly low. Only 4% of organizations report full confidence in AI agents, and overall trust has dipped from an average of 54% in 2024 to 47% in 2025.

    Concerns Rising Among Insurers

    Chief concerns identified by insurers highlight critical issues surrounding privacy, bias, and transparency, each garnering concern from half of the surveyed firms. As these risks loom large, the path forward for AI integration remains fraught with caution.

    The Future of AI in Insurance

    Looking ahead, 26% of insurers believe that AI agents will begin augmenting human work within the next one to three years, while 35% foresee these agents operating independently under human oversight. The demand for skilled personnel also rises sharply; 67% of employers indicate that programming and software development skills will be crucial, while 60% emphasize the importance of decision-making as a key soft skill.

    Yet, the ethical landscape appears murky; only a mere 8% of insurance organizations have successfully embedded ethical AI principles into their operations, significantly trailing the global average of 14%. As the financial sector increasingly embraces digital transformation, one can’t help but wonder: will insurers be quick enough to catch up, or will they find themselves left in a behind-the-times conundrum?

    Questions & Answers

    What does the Capgemini report reveal about the current state of AI adoption in the insurance industry?
    The report indicates that only 10% of insurance organizations have fully implemented AI agents, with another 20% in pilot stages, while 42% have no formal strategy for deployment.

    Which areas within insurance are most expected to benefit from AI agents?
    Sales and customer service are identified as the primary areas, with a significant number of insurers believing AI will manage daily processes in these functions.

    What are the main concerns regarding the implementation of AI agents among insurers?
    Insurers are particularly worried about privacy, bias, and transparency, with half of respondents expressing concern over these risks.

  • UBS Launches Review of Client Advisors Amidst Rising Standards in Wealth Management

    UBS Launches Review of Client Advisors Amidst Rising Standards in Wealth Management

    The Ripple Effect of Risky Currency Derivatives

    The fallout from the sale of high-risk currency derivatives is prompting UBS to scrutinize the actions of several of its client advisors. Reports from Bloomberg reveal that the bank is investigating six relationship managers who allegedly sold these complex financial products to Swiss clients, many of whom may not have grasped the risks involved.

    Sources indicate that the advisors are under the microscope due to concerns they did not ensure clients fully understood the intricacies and potential consequences of their investments. While some of the advisors have already departed from the institution, the fates of those remaining hang in suspense as the review unfolds.

    UBS previously communicated its proactive stance on this issue, confirming that it conducted a thorough examination of each individual case. “We have completed a review of this matter and found that a very small number of clients at a few locations in Switzerland experienced unexpected effects due to tariff-related market volatility in the U.S. in April 2025,” a spokesperson for UBS stated. The bank emphasized its commitment to addressing the situation seriously.

    In response to the concerns, UBS has reportedly settled with some clients, offering “goodwill payments” in approximately 100 cases, according to the Financial Times. It seems the only thing winding tighter than financial markets these days is the internal oversight at UBS.

    Questions & Answers

    What prompted UBS to review the actions of its client advisors?
    The review is a response to the sale of high-risk currency derivatives to Swiss clients, whom the advisors allegedly did not adequately inform about the risks involved.

    How many client advisors are under investigation?
    UBS is currently examining the activities of six relationship managers linked to the sale of these complex financial products.

    What measures has UBS taken regarding client settlements?
    The bank has reached settlements with some clients, making “goodwill payments” in around 100 cases as part of its efforts to address concerns stemming from the situation.

  • Gold Prices Soar to Three-Month High, Spark Excitement in the Retail Market

    Gold Prices Soar to Three-Month High, Spark Excitement in the Retail Market

    Vietnam gold prices surged to a three-month high on Wednesday morning, coinciding with a global retreat in bullion rates.

    Record Highs for Local Gold Prices

    In the heart of Ho Chi Minh City, gold prices at Saigon Jewelry Company climbed by 0.57% to reach VND122.7 million (US$4,694.85) per tael. This marks the highest rate observed since April 22, when gold prices peaked at a historic VND124 million.

    The Global Context

    Gold rings also saw an uptick, priced at VND118 million per tael, reflecting a 0.43% increase. Interestingly, while Vietnam experienced a gold rush, international prices were easing. As reported by Reuters, spot gold dipped by 0.2% to $3,423.44 per ounce, after initially reaching its highest level since mid-June earlier that day. Similarly, U.S. gold futures followed suit, sliding 0.2% to $3,437.70.

    Market Dynamics at Play

    The fluctuations can be traced back to a surge in risk appetite, sparked by U.S. President Donald Trump’s announcement of a trade agreement with Japan just ahead of a looming tariff deadline. A weaker dollar, coupled with declining U.S. Treasury yields, cushioned the blow for bullion prices. As the dollar index hovered around a two-week low, gold became more affordable for international investors—talk about a golden opportunity!

    Looking Ahead

    Market analysts are divided on future trends. Tim Waterer, Chief Market Analyst at CM Trade, noted that the signing of further trade agreements before August 1 could boost risk appetite, potentially diminishing gold’s allure. However, if the U.S. dollar continues to face pressure, a resurgence to $3,500 per ounce could remain within reach for this precious metal.

    Questions & Answers

    What has driven the recent increase in gold prices in Vietnam?
    Gold prices in Vietnam have increased due to a combination of local demand and international market dynamics, including positive trade news from the U.S. which has momentarily eased demand for gold.

    How did global gold prices react during the same period?
    Globally, gold prices dipped slightly as risk appetite was bolstered by U.S. trade news, indicating a fluctuating relationship between domestic and international market sentiments.

    What could affect gold prices in the near future?
    Future gold prices may be influenced by any new trade agreements and the strength of the U.S. dollar, with a weaker dollar potentially pushing prices higher.

  • Morgan Stanley MD Invests $18.8M in Two Luxurious Hong Kong Apartments

    Morgan Stanley MD Invests $18.8M in Two Luxurious Hong Kong Apartments

    In a striking display of resilience in Hong Kong’s luxury real estate market, two units within the Deep Water Pavilia development, nestled in the Wong Chuk Hang neighborhood, recently changed hands for a remarkable average of HK$45,440 per square foot (US$62,300 per square meter). According to data from the Land Registry, the combined saleable area of the units totals 3,242 square feet, further highlighting the pent-up demand in a city known for its sky-high property prices.

    A Snapshot of Luxury Real Estate Deals

    One of the prime properties, spanning 1,706 square feet, features four bedrooms with two en-suites and sold for HK$81.89 million. The second unit, a slightly smaller four-bedroom flat at 1,536 square feet, fetches HK$65.43 million. Such transactions depict a vivid picture of high-end demand even as the city grapples with an ongoing market downturn.

    Developer’s Strong Showing Amid Market Fluctuations

    Deep Water Pavilia, developed by a consortium led by New World Development—one of the so-called “big four” developers in the city—has been a powerhouse in attracting buyer interest ever since the launch of its first phase last month. The initial batch of 138 units, featuring a mix of two- to four-bedroom flats, sold out within hours, with an average launch price that set a record low for new homes in the area at approximately HK$21,000 per square foot (US$28,800 per square meter), as noted by Bloomberg.

    Looking Ahead: More Units on the Horizon

    Following this strong debut, New World Development is now collecting expressions of interest for the second phase of sales, poised to hit the market possibly as early as next week. Many speculate that these new offerings may command higher prices, stoking further excitement among would-be buyers.

    Market Dynamics: Navigating the Downturn

    Despite this buzz, the broader market remains in a challenging position, with home prices having plummeted nearly 30% since their peak in 2021. Factors contributing to this downturn include escalating mortgage rates, a dwindling number of professionals living in the city, and an overall weak economic outlook, according to Reuters.

    Heroic Investments in Luxury

    Investor sentiment may be shifting, however; notable figures like Wraight are seizing opportunities presented by discounted luxury prices. Following a research note from Morgan Stanley in June predicting a four-to-five-year upward cycle for the market, expectations for a rebound are creeping back, particularly in the latter half of the year.

    In a poignant example of bold investing, Jeremy Wong, the son of Peter Wong, chairman of HSBC’s Asia subsidiary, recently purchased two connected units for a staggering HK$121.5 million at Hong Kong Parkview, a sought-after apartment complex in the Southern District. This brings his total investment in luxury flats this year to at least HK$231 million, underscoring a trend among wealthy investors eager to capitalize on the current climate.

    Questions & Answers

    What notable property transactions have taken place recently in Hong Kong?
    Two luxury units at the Deep Water Pavilia development sold for an average of HK$45,440 per square foot, with one fetching HK$81.89 million and another at HK$65.43 million.

    Who developed the Deep Water Pavilia project?
    The project was developed by a consortium led by New World Development, part of Hong Kong’s “big four” property developers.

    How are current market trends affecting luxury property sales in Hong Kong?
    While home prices have dropped nearly 30% since peak levels in 2021, there is a renewed interest among investors, spurred by lower prices and forecasts of an impending market rebound.

  • Bangkok Bank Set to Fall Short of 2025 Net Interest Margin Goals: What This Means for Investors

    Bangkok Bank Set to Fall Short of 2025 Net Interest Margin Goals: What This Means for Investors

    Bangkok Bank is bracing for a challenging financial landscape as it navigates potential interest rate cuts in the latter half of 2025. According to a recent report by UOB Kay Hian, the esteemed Thai bank is expected to fall short of its target net interest margin (NIM) as it faces the prospect of two rate reductions: a 25 basis point cut in October and another in December.

    A Daring Forecast Amid Rate Cuts

    While Bangkok Bank is forecasting that the December cut will hold its NIM steady above 2.8%, UOBKH analysts predict a dip, projecting the ratio to settle at approximately 2.7% by year-end. For context, the NIM reflects the net interest income from loans after accounting for interest paid to depositors, a crucial metric for banks in assessing profitability.

    A Mixed Bag of Earnings Results

    In its latest financial report, the bank announced a flat year-on-year earnings result for Q2 2025, logging THB11.8 billion—a figure that was also down by 6% compared to the previous quarter. Surprisingly, this outcome beat UOBKH’s estimates, offering a glimmer of hope amid the forecasted challenges. Corporate loans stood as the sole bright spot in an otherwise stagnant loan growth landscape, revealing a complex interplay of sectors within Bangkok Bank’s operations.

    Non-Interest Income Shows Resilience

    On a more upbeat note, the bank’s non-interest income surged by 22% year-on-year to THB12.7 billion. However, it did experience an 8% decline quarter-on-quarter, illustrating the pressure on various income streams. Adding to the caution, credit costs and the nonperforming loan (NPL) ratio registered an uptick in the second quarter, compelling Bangkok Bank to set aside THB10.7 billion in provisions.

    Looking Ahead With Caution

    UOBKH analyst Thanawat Thangchadakorn expressed a cautious outlook on the rising NPL trend, suggesting it might mirror last year’s patterns. Although Bangkok Bank maintains its credit cost target at 1% for 2025, it acknowledges the possibility of exceeding this level, estimating a year-end credit cost of approximately 137 basis points. As the bank charts its course through an uncertain financial environment, all eyes will be on its ability to adapt and navigate these impending challenges.

    Questions & Answers

    What interest rate cuts is Bangkok Bank anticipating for late 2025?
    Bangkok Bank is expecting two rate cuts in the final months of 2025, specifically a 25 basis point cut in October and another in December.

    How did Bangkok Bank’s earnings perform in Q2 2025 compared to expectations?
    The bank reported a flat earnings outcome of THB11.8 billion for Q2 2025, surpassing UOBKH’s estimates despite being 6% lower than the previous quarter.

    What challenges is Bangkok Bank facing regarding its nonperforming loans?
    Bangkok Bank is experiencing an increase in nonperforming loans, prompting it to set aside THB10.7 billion in provisions to address this issue, aligning with a trend seen in the previous year.

  • HSBC Global Private Banking Expands Teams to Elevate Services in Southeast Asia and Australia

    HSBC Global Private Banking Expands Teams to Elevate Services in Southeast Asia and Australia

    HSBC Global Private Banking (GPB) is making waves in Southeast Asia and Australia with exciting leadership changes designed to strengthen its client services. The firm has appointed Joanne Ng as the new desk head for its Singapore operations, a strategic move that signals its commitment to the region.

    A Dynamic Trio Takes the Helm

    Joanne Ng, a seasoned professional with 22 years of experience, transitions from OCBC Premier Private Client to lead a dedicated team of relationship managers focused on high-net-worth clients in Singapore. Her extensive background in the financial sector positions her well to elevate HSBC’s private banking offerings.

    Joining Ng in this leadership expansion is Tim Morse, who steps in as senior business development manager for HSBC GPB in Australia, set to begin in August 2025. With a wealth of experience from top-tier financial institutions like Citi, J.P. Morgan, and Deutsche Bank, Morse will be pivotal in fostering collaboration between HSBC’s onshore services and offshore private banking teams.

    New Faces in Private Banking

    Completing this dynamic trio is Tom Kinnear, appointed as a relationship manager to oversee operations in Australia and international markets. Kinnear will report directly to Kapil Khanna, contributing his expertise to enhance client relations across the board.

    Moreover, HSBC is not just focused on leadership in Singapore and Australia—there are also significant additions in Indonesia and Malaysia. Le Hong Sie joins as a senior relationship manager in Indonesia, bringing more than three decades of experience at HSBC. Her transition from Corporate and Institutional Banking to private banking coverage promises to enrich the firm’s offerings in the region.

    Leonard Eggert also steps into the Indonesia team as a relationship manager, having previously worked at KfW, while in Malaysia, Rayner Wong joins from Julius Baer and Samuel Chi Hao Kee makes the move from HSBC Premier, both taking on the role of relationship managers.

    With these strategic appointments, HSBC is clearly positioning itself to not only meet but anticipate the needs of its affluent clientele in a rapidly evolving market landscape. After all, who wouldn’t want a financial institution that knows you better than your favorite barista?

    Questions & Answers

    What experience does Joanne Ng bring to HSBC?
    Joanne Ng has 22 years of experience in the financial sector, most recently serving at OCBC Premier Private Client, and will lead a team focused on high-net-worth clients in Singapore.

    What role will Tim Morse play at HSBC GPB in Australia?
    Tim Morse is appointed as senior business development manager, responsible for fostering collaboration between HSBC’s onshore franchises and offshore private banking teams, starting in August 2025.

    Who are the new relationship managers joining HSBC in Indonesia?
    Le Hong Sie, with over 30 years of experience at HSBC, and Leonard Eggert, formerly of KfW, are the new additions to the relationship management team in Indonesia.

  • Switzerland’s Shocking $900,000 Bitcoin Bank Loss: What Happened?

    Switzerland’s Shocking $900,000 Bitcoin Bank Loss: What Happened?

    How Switzerland Lost a 900,000 Bitcoin Bank

    Once on track to be Switzerland’s first Bitcoin bank, Xapo, founded in Silicon Valley, has found a new home in Gibraltar after confronting regulatory challenges in the Swiss market. Now, as a fully licensed digital private bank, Xapo serves clients across the globe, with CEO Seamus Rocca shedding light on its journey during an exclusive interview with finews.com. Today, the only remnant of Xapo in Switzerland is a high-security vault nestled deep within the Gotthard Massif.

    Xapo began its journey in 2013, founded by Argentinian entrepreneur Wences Casares as a secure vault service for Bitcoin. Fueled by a vision that Bitcoin could stabilize global economies, Casares established ultra-secure cold storage solutions, including a vault set within a former army fortress high in the Swiss Alps.

    In 2015, the company moved its headquarters to Zug, Switzerland’s Crypto Valley, aiming to secure a banking license and bringing in former UBS and Barclays executive Olga Feldmeier to bolster its efforts.

    Regulatory Hurdles Derail the Swiss Dream

    However, the optimism surrounding a Swiss domicile quickly evaporated as the harsh reality of regulation set in. “Switzerland was promoting itself as crypto-friendly, but the reality was different when dealing with regulators,” remarked Rocca. Swiss authorities required servers to be located within the country and enforced a board structure that Rocca described as “going back in time,” highlighting how outdated these requirements felt amid a tech revolution reliant on global cloud setups.

    Simultaneously, regulatory tensions in the U.S. prompted Xapo to reassess its global aspirations. After selling its institutional custody segment to Coinbase in 2019, Rocca noted, “We decided to simplify our operational, regulatory, legal infrastructure.” This strategic retreat from both Switzerland and the U.S. was aimed at shielding clients from prohibitive regulatory costs. Rocca wryly mused that perhaps they should have kept that custody business given Coinbase’s subsequent fee hikes.

    Finding Solid Ground in Gibraltar

    In 2021, Xapo set its sights on Gibraltar, a jurisdiction that embraced blockchain businesses. Rocca characterized this pivot as establishing Gibraltar as “the new Switzerland—private banking in the realm of crypto.” Unlike its Swiss counterpart, Gibraltar’s regulatory environment allowed Xapo to maintain a global, remote-first structure—a necessity for a fintech-driven bank. “We’re more tech than fin,” Rocca declared, reinforcing the need for a more supportive jurisdiction.

    Today, Xapo boasts a full banking license and a distributed ledger technology license as a virtual asset service provider in Gibraltar. With a workforce of approximately 200 employees, it stands among the largest crypto-focused banks worldwide, paralleling Swiss entities Sygnum and Amina Bank, both granted banking licenses in 2019.

    Retail Focus: A Unique Approach

    What sets Xapo apart, however, is its distinct business strategy. Aimed entirely at retail clients, it operates much like a traditional private bank but with a focus on cryptocurrency holders. New members are charged a $1,000 onboarding fee—a conscious decision to attract serious investors. “If that fee feels expensive, you probably don’t have enough bitcoin,” Rocca quipped, setting a tone for their exclusive clientele.

    Clients enjoy a suite of banking products including deposit accounts, payment cards, savings, loans, and investment options—all incorporated under Bitcoin’s umbrella. Imagine holding a U.S. dollar account with an IBAN for wire transfers, while simultaneously storing bitcoins securely within Xapo’s vault and earning interest. Rocca emphasizes that clients can engage with Bitcoin just as they would with traditional currencies.

    Innovative Offerings: Bridging the Old and New

    Clients of Xapo can use a debit card linked to USD accounts, creating a seamless experience that converts Bitcoin into dollars at the point of sale. Rocca explains, “Every time you use your card on Bitcoin, we buy the Bitcoin off you, sell it into dollars, and settle with the merchant.” So, while merchants may see dollars only, clients are utilizing their Bitcoin balance.

    Looking Ahead: New Financial Products on the Horizon

    Xapo’s Bitcoin savings account allows users to earn interest by depositing BTC, functioning as a fund generating yield, all while providing users with a straightforward interest-bearing experience. The bank also offers bitcoin-backed loans, letting clients leverage their BTC as collateral while ensuring it remains securely housed within its vault. Rocca noted that this approach secures clients’ assets, invoking images of the Swiss mountains where they are stored.

    Excitingly, Xapo is integrating the Bitcoin Lightning Network for expedited transactions, with plans to introduce new features—one being the capability for clients to invest in stock indices using Bitcoin. “We’re going to allow you to buy stocks in the S&P 500 with Bitcoin,” Rocca revealed.

    Exclusive Clientele: A Strategy for Stability

    All of these products come via a user-friendly app that merges the elegance of private banking with the convenience of fintech. Rocca explains their mission of recreating traditional banking functions for Bitcoin users, emphasizing that “we’re not in the mass market; we’re in the premium banking business, pretty much like a Swiss private bank.”

    Assets Under Management: An Impressive Track Record

    Xapo’s assets have reportedly peaked at around 900,000 bitcoins, nearing 90 billion francs at current valuations, before the company chose to reshape its business strategy. Rocca noted an intention to sustain profitability, sharing that the bank experienced its first profit in 2023. Unlike Sygnum and Amina, focusing on institutional clients, Xapo’s gamble lies in appealing to high-net-worth individuals, particularly in regions where local banking systems may inspire distrust.

    The Future: Navigating Regulatory Waters

    The evolution of Xapo illustrates the importance of regulatory arbitrage within the crypto finance sector. Gibraltar’s adaptive regulations stand in stark contrast to the stifling environment Xapo left behind in both Switzerland and the U.S. Rocca observes an emerging trend where the U.S. appears more crypto-friendly as European markets become increasingly cautious, “We never quite seem to strike that balance where the main economic superpowers are all aligned.”

    Revisiting the U.S. Market

    This uneven landscape explains why Xapo still abstains from onboarding U.S. clients but remains open to reconsideration. Rocca has hinted at potential plans for a U.S. presence, gauging the viability of re-entering the market if conditions become favorable.

    Security Meets Innovation: A Unique Proposition

    While Xapo has shifted its headquarters, it retains its Swiss vault—an impenetrable fortress shielded by thick granite and biometric security. By fusing legendary Swiss security with the flexibility of modern fintech, Xapo offers clients both safety and cutting-edge banking functionalities. As the crypto industry experiences another wave of optimism, fueled by rising Bitcoin prices, Rocca remains vigilant, aware that “winter will come again.”

    Forecasting the Future: Cycles of Change

    “If you’re in the Bitcoin space, we’re riding high,” Rocca reflects. However, acknowledging the cyclical nature of Bitcoin, he speculates that the current bullish market might carry through to 2025 before potentially facing a downturn. The eventual “crypto winter” may arrive, and his insight encourages investors to stay informed. In the meantime, Xapo continues to ride this wave, navigating the ever-shifting sands of the crypto landscape.

    Questions & Answers

    What prompted Xapo to move its operations from Switzerland to Gibraltar?
    Xapo faced stringent regulatory requirements in Switzerland that stifled its growth and operational flexibility, whereas Gibraltar offered a more accommodating environment.

    How does Xapo differentiate itself in the competitive crypto banking market?
    Xapo focuses entirely on retail clients, providing traditional private banking services tailored for Bitcoin holders, unlike many peers targeting institutional clients.

    What future plans does Xapo have regarding its operations in the U.S.?
    Xapo is currently assessing the possibility of re-entering the U.S. market, evaluating regulatory conditions to determine if it makes sense to onboard American clients again.
  • Techcombank Reports 1.48% Drop in H1 2025 Profit, Reaching $472.75 Million

    Techcombank Reports 1.48% Drop in H1 2025 Profit, Reaching $472.75 Million

    In a financial landscape marked by challenges, Vietnam Technological and Commercial Joint Stock Bank (Techcombank) has unveiled a profit after tax of $472.75 million (VND12.36 trillion) for the first half of 2025. This figure represents a modest decline of 1.48% compared to the approximately $480 million (VND12.55 trillion) reported during the same timeframe last year.

    Operating Income Experiences a Dip

    Techcombank’s total operating income took a downturn in H1 2025, amounting to $931.34 million (VND24.35 trillion), down from VND25.68 trillion in H1 2024. Despite the overall income decline, the bank observed a small silver lining as net interest margin (NIM) edged upward to 3.8% by the end of Q2 2025, compared to 3.7% in Q1, even as net interest income (NII) fell to $665.51 million (VND17.4 trillion), a 3% year-on-year decrease.

    Net fee income also slipped, totaling $210.37 million (VND5.5 trillion), a 5.4% decline from last year, primarily due to lower earnings from letters of credit, remittances, and card fees. However, a standout performer was the investment banking sector, where fees surged by 30.2% year-on-year to reach $89.11 million (VND2.33 trillion), bolstered by a strong issuance in previous quarters.

    The second quarter of 2025 painted a more vibrant picture for Techcombank. Investment banking fees alone rose to $53.93 million (VND1.41 trillion), marking a remarkable 35.5% year-on-year increase and a 53.3% surge compared to Q1. This uptick was spurred by robust activity across multiple business lines, including brokerage and agency management, margin lending, and bond underwriting.

    Teetering Trade Activities

    In contrast, earnings from letters of credit, remittances, and cash settlements plummeted by 40.6% year-on-year to $49.72 million (VND1.3 trillion), attributed to changes in accounting treatment and subdued customer demand. Nonetheless, these figures saw an 11.4% improvement from Q1, thanks to a newly adopted trade financing solution known as ‘LC purchase without recourse.’

    Card Income Declines, But QR Code Dominance Shines

    Card-related income fell sharply by 24.7% year-on-year to $29.43 million (VND769.4 billion). Techcombank noted this decline aligns with a broader industry trend toward alternative payment methods like QR codes. Indeed, the bank proudly claims the top market position for QR code transactions in H1 2025, as reported by VietQR.

    A Flourishing FX Segment

    On a brighter note, foreign exchange sales skyrocketed by 57.7% year-on-year, reaching $22.34 million (VND584 billion). This growth indicates a notable shift in consumer and business behavior towards FX trading.

    Questions & Answers

    What contributed to Techcombank’s profit decline in H1 2025?
    The bank reported a 1.48% decrease in profit mainly due to lower total operating income and a decline in net fee income, particularly from letters of credit and card fees.

    How did investment banking perform for Techcombank in this period?
    Investment banking fees saw significant growth, rising by 30.2% year-on-year to $89.11 million, driven by increased activity in several business lines.

    What payment trend is Techcombank capitalizing on?
    The bank is leading the market in QR code transactions, reflecting a broader industry shift away from traditional debit cards towards modern payment methods.

  • E-commerce Surge Fuels Expansion in Taiwan’s Credit Card Payments Market

    E-commerce Surge Fuels Expansion in Taiwan’s Credit Card Payments Market

    Taiwan’s credit card payments sector is on the brink of substantial growth, projected to see an impressive 7% increase by 2025, reaching a staggering $156.2 billion (TWD 5 trillion), as evidenced by findings from GlobalData. This upward trajectory is propelled by an insatiable appetite for cashless transactions, a booming e-commerce landscape, and the rising adoption of contactless technology.

    The trend is already apparent, with credit card transaction values surging by 19.9% in 2023, followed by a robust 11.9% increase in 2024, pushing the total to $145.9 billion (TWD 4.7 trillion). Surprisingly, despite global economic instability and the looming specter of U.S. tariffs, credit card popularity shows no signs of waning.

    “While debit cards dominate in terms of sheer numbers, consumers still prefer credit cards for payments,” noted Ravi Sharma, Lead Banking and Payments Analyst at GlobalData. “In 2025, the average number of transactions per card will hit 66.1, while debit cards lag behind with only 5.2.”

    This dramatic shift is attributed to several factors: a burgeoning middle class, a dynamic young workforce, enhancing payment infrastructure, and the escalating trend of e-commerce and contactless payments.

    Remarkably, credit cards accounted for 93.1% of total payment card transaction values in 2024. Major financial institutions are cashing in on this trend, with banks like Taipei Fubon Bank offering enticing installment plans, including a six-month interest-free option on select purchases. The digital marketplace plays a pivotal role here, with online transactions representing a noteworthy one-third of all credit card activity.

    Innovative partnerships are also making their mark; for instance, Cathay United Bank has teamed up with the online platform Shopee to create a co-branded credit card that rewards purchases with Shopee’s Shrimp Coins—who knew shopping could come with its own little treasure hunt?

    Public transport initiatives are aligning with this growth momentum too. In November 2023, Metro Taipei collaborated with Thales Group and MiTAC to roll out contactless payment options leveraging both cards and digital wallets, making travel smoother for the cashless commuter.

    Looking ahead, GlobalData anticipates continued expansion in this market, projecting a reach of $211.3 billion (TWD 6.8 trillion) by 2029, achieving a remarkable CAGR of 7.8% amid evolving consumer preferences and technological advancements.

    Questions & Answers

    What factors are driving the growth of credit card transactions in Taiwan?
    The growth is fueled by rising consumer demand for cashless payments, a burgeoning middle class, enhanced payment infrastructure, and the boom in e-commerce and contactless technology.

    How significant are online transactions within the credit card market?
    Online transactions now account for one-third of total credit card transaction value, underscoring the vital role of e-commerce in driving credit card usage.

    What innovative partnerships have emerged in Taiwan’s credit card market?
    A notable collaboration is between Cathay United Bank and Shopee, which has introduced a co-branded credit card that rewards consumers with Shrimp Coins for purchases, adding an engaging twist to the shopping experience.

  • F&F Engages Goldman Sachs For Potential Acquisition Of Taylormade Amid Legal Tensions

    F&F Engages Goldman Sachs For Potential Acquisition Of Taylormade Amid Legal Tensions

    South Korean apparel company F&F Co announced on Monday that it had engaged Goldman Sachs as its advisor on the prospective purchase of TaylorMade. The company also stated that it would pursue legal action if the current owner of TaylorMade proceeds with an independent sale process.

    The Context of the Acquisition

    Earlier this year, Centroid Investment Partners, a private equity firm headquartered in Seoul, initiated a sales process for TaylorMade, which it had acquired in 2021. The company, based in Carlsbad, California, could potentially be sold for as much as $3.5 billion, according to those familiar with the transaction.

    F&F Co was a pivotal player in the 2021 acquisition of TaylorMade, participating as a strategic investor. As the most significant investor, F&F secured written Consent Rights over major business decisions, which included borrowing, key management decisions, and sales of equity. However, F&F has not approved Centroid’s current attempt to sell TaylorMade, and it views this action as a considerable violation of its contractual consent rights.

    Despite the potential acquisition, F&F stated that it is fully prepared to use all available legal and contractual measures to hold Centroid accountable for any violations. The company is carefully preparing to exercise its Right of First Refusal (ROFR) if necessary, to ensure alignment with its original investment thesis.

    Investment Breakdown

    F&F’s investment in the acquisition of TaylorMade by Centroid was substantial, contributing 358 billion won ($258 million) of a total subordinated equity investment of 619.2 billion won. This made F&F the primary equity investor as a limited partner (LP).

    Additionally, F&F contributed 195.7 billion won to a mezzanine investment of 471.5 billion won. The fashion company had already expressed its intent to acquire TaylorMade last month, explaining that its significant investment in TaylorMade in 2021 was made with the ultimate aim of acquiring the company.

    Centroid’s Sale Process

    According to insiders, Centroid’s advisors have sent confidential memoranda and process letters concerning the sale of TaylorMade to potential buyers. However, no official process has been initiated yet. Responding to a request for comment, Centroid confirmed it was in the process of selling TaylorMade to maximize its LPs’ return on investment.

    In the private equity sector, a GP, or General Partner, refers to the manager of a fund who is responsible for making investment and operational decisions. In contrast, LPs, or Limited Partners, are investors in the fund who usually have a passive role in individual deals. F&F is an LP investor in a fund managed by Centroid as the GP.

    Centroid confirmed that F&F holds the right of first refusal, which it guarantees. However, it pointed out that this right does not preclude a sale process from occurring.

    TaylorMade Overview

    Established in 1979, TaylorMade produces golf clubs, balls, and other golf-related accessories. The company has offices in Canada, China, Japan, South Korea, and Australia, in addition to its U.S. base.

    Questions & Answers

    What is F&F Co’s role in TaylorMade’s acquisition?
    F&F Co participated as a strategic investor in the 2021 acquisition of TaylorMade and is the largest equity investor as a limited partner (LP).

    What are the potential legal actions that F&F Co might take?
    F&F Co stated that it is fully prepared to use all available legal and contractual measures to hold Centroid accountable for any violations of its contractual consent rights.

    What is the right of first refusal that F&F Co holds?
    The right of first refusal allows F&F Co to decide whether or not to match the terms of a sale determined through the auction process.

  • China Everbright Bank Faces Rising Threat from New Bad Loan Formation

    China Everbright Bank Faces Rising Threat from New Bad Loan Formation

    China Everbright Bank (CEB) is navigating a complex landscape, facing the challenge of potential new nonperforming loans (NPLs), but recent assessments indicate that its financial health remains robust. According to Moody’s Ratings, the bank has built adequate buffers, with reserves covering a formidable 174.4% of its NPLs, ensuring a steady foundation as it maneuvers through changing economic tides.

    As the country transitions economically, CEB grapples with unseasoned risks, particularly in financing that shift along with evolving nonlending credit challenges stemming from its investment portfolio. Despite these hurdles, Moody’s analysis suggests that CEB can maintain its asset quality, capitalisation, profitability, and liquidity in the upcoming 12 to 18 months.

    Shifts in Loan Growth Trends

    In recent months, overall loan growth has experienced a slowdown, dropping to 3.9% in 2024 from 6% the previous year. However, the bank has seen a notable surge in specific areas, with green loans skyrocketing by 41% and inclusive financing loans rising by 15%. This shift highlights a pivot towards sustainable and responsible banking, setting the stage for a future where eco-conscious lending becomes a norm—perhaps enough to make even Mother Nature smile.

    Moody’s forecast remains optimistic regarding the bank’s asset quality over the next year and a half. Their analysis attributes this stability to CEB’s measured growth strategy and the significant buffers it has established in anticipation of market fluctuations. As of March 31, 2025, the NPL ratio has held steady at 1.25%, marking four consecutive years of stability.

    Robust Capitalisation Prospects

    Looking ahead, CEB’s capitalisation is projected to remain sufficient through 2026, bolstered by subdued asset growth. With profitability, gauged by return on average assets (ROAA), anticipated to stabilize around 0.6% over the next 12 to 18 months, the bank appears to be on solid ground. While a narrowing net interest margin (NIM) could pose challenges, the decline in deposit costs is likely to alleviate some pressure, supporting net interest income, which currently constitutes 71.3% of total revenues.

    Questions & Answers

    What is the current status of China Everbright Bank’s nonperforming loans?
    China Everbright Bank has reserves that cover 174.4% of its nonperforming loans, and the NPL ratio has remained stable at 1.25% for the past four years.

    How has loan growth changed at CEB recently?
    Overall loan growth has slowed to 3.9% in 2024 from 6% in 2023, but green loans and inclusive financing loans have seen significant increases of 41% and 15%, respectively.

    What does Moody’s predict for CEB’s financial stability moving forward?
    Moody’s expects that CEB will maintain adequate asset quality, capitalisation, profitability, and liquidity over the next 12 to 18 months, aided by a careful growth strategy and existing financial buffers.

  • Indonesia’s Consumer Loan Growth Faces Headwinds as Banks Reinforce Risk Management Strategies

    Indonesia’s Consumer Loan Growth Faces Headwinds as Banks Reinforce Risk Management Strategies

    As Indonesia moves into the second half of 2025, the outlook for consumer loan growth appears to be weakening. A recent report from CGS International emphasizes that banks are tightening their lending practices, which could spell trouble for borrowers seeking loans. Stakeholders are taking note as rejection rates for applications rise and down payment requirements for auto loans increase.

    Banking Sector Tightens Lending Practices

    According to CGS International, raw data from their on-the-ground checks reveals a noticeable tightening in risk parameters across banks. “We have also seen consecutive increases in mortgage rates from Bank Central Asia (BBCA), the market leader in consumer loans, over the past few months since end-FY2024,” noted analysts Handy Noverdanius, Owen Tjandra, and Elizabeth Noviana. When a bank as influential as BBCA adjusts its rates, it’s usually a signal that something larger is at play in the economy.

    Non-Performing Loans on the Rise

    The issue of non-performing loans (NPLs) is becoming increasingly pressing. CGS International reports that NPLs for consumer loans have crept up since 2024, with Q1 2025 figures showing an increase to 2.08%. This marks a rise of 28 basis points compared to Q1 2024 and a 19 basis points uptick year-to-date. Disturbingly, mortgage NPLs are experiencing an even sharp uptick, reaching their highest levels since October 2020, which calls into question the stability of this segment.

    In the broader banking landscape, a similar trend is evident among major banks, albeit at a lower magnitude, with an increase of 22 basis points year-on-year and 14 basis points year-to-date as of Q1 2025. CGS International attributes this to soft macroeconomic conditions, fueling fears of a knock-on effect within the consumer loan sector.

    Future Implications for Consumer Loans

    The analysts forecast a lag of 6 to 12 months for the repercussions of rising NPLs to fully express themselves, potentially constraining growth in consumer loan segments significantly. As the landscape evolves, growth in consumer loans was recorded at 1.9% year-to-date and 8.7% year-on-year as of May 2025. However, as lending conditions tighten, these figures could soon morph from optimistic to fraught with caution, making the future of consumer spending on borrowed money in Indonesia uncertain.

    Questions & Answers

    What key changes in lending practices have been observed by CGS International?
    CGS International has noted a tightening of risk parameters among banks, leading to increased rejection rates for loan applications and higher down payment requirements for auto loans.

    How are non-performing loans affecting the consumer loan market in Indonesia?
    Non-performing loans in the consumer segment have risen to 2.08% as of Q1 2025, with mortgage NPLs experiencing significant increases, reaching levels not seen since October 2020.

    What are the projections for consumer loan growth moving forward?
    Analysts estimate that the impact of rising NPLs will cause a slowdown in consumer loan growth over the next 6 to 12 months, with current growth rates at 1.9% year-to-date and 8.7% year-on-year as of May 2025.