Category: Finance

Retail News Asia is committed to providing both local and global retailers with the latest Finance news throughout the Asian market. This on a daily base.

  • Gold Prices Surge Close to All-Time Highs: What This Means for Retail Investors

    Gold Prices Surge Close to All-Time Highs: What This Means for Retail Investors

    The rally in Vietnam’s gold prices shows no signs of slowing down as values edge closer to their all-time high from earlier this year. On Tuesday afternoon, the Saigon Jewelry Company reported its gold bar price climbing 0.41% to reach VND123.8 million, or approximately US$4,726.91, per tael. This marks a mere 0.16% away from the previous peak of VND124 million recorded on April 22.

    Meanwhile, the price of gold rings also saw an uptick, rising 0.42% to VND119.3 million per tael. For context, a tael is equivalent to 37.5 grams or 1.2 ounces.

    The surge in gold prices in Vietnam has been impressive, escalating by 47% since the year’s start.

    On the global stage, gold prices stabilized on Tuesday, maintaining a position near a one-week high following a slowdown in U.S. job growth, which fueled speculation of a potential Federal Reserve rate cut in September. This shift has influenced both the dollar and Treasury yields, according to reports from Reuters.

    Spot gold remained steady at $3,371.40 per ounce, with bullion recently reaching its highest point since July 24. U.S. gold futures also held firm at $3,425.30.

    “Short-term momentum has improved for the bullish side of the story… the fundamental narrative supporting gold prices is that the Fed is still in a position to actually cut rates in September,” noted Kelvin Wong, a senior market analyst at OANDA.

    Questions & Answers

    What recent trends are influencing gold prices in Vietnam?
    Vietnam’s gold prices have surged 47% this year, with recent price increases attributed to expectations of a Federal Reserve rate cut, after slower job growth in the U.S.

    How close are Vietnam’s gold prices to breaking previous records?
    Gold prices in Vietnam are currently just 0.16% away from the previous peak of VND124 million per tael set in April, highlighting a potential upcoming record.

    What are some global factors affecting gold prices?
    Globally, gold prices have been influenced by recent U.S. economic data, particularly concerning job growth, which has led to speculation of a Federal Reserve rate cut, affecting the dollar and Treasury yields.

  • Fintech Innovations Steal the Spotlight in APAC’s Thriving Card Payment Landscape

    Fintech Innovations Steal the Spotlight in APAC’s Thriving Card Payment Landscape

    In the fast-paced arena of Asia-Pacific’s bustling $24.7 trillion card payment market, fintech firms are carving out a competitive edge with their tech-savvy agility. Unlike traditional banks and platform giants who command significant portions of the landscape, these nimble fintech players are redefining digital payments and accelerating innovation across both mature and emerging markets.

    Fintechs Outpace Traditional Banks

    Sean Fu, Senior Vice President for Greater China at Global Payments, provides insight into this evolving competition, observing that fintech firms excel due to their scalability and technological leverage. “Among these three, I see the FinTech players as more competitive in the market,” he remarked, citing their ability to expand rapidly across borders.

    While banks continue to hold sway with their established reputation and control over card issuance, Fu notes that their outdated infrastructure can hinder their efficiency. “Their disadvantages are obvious—slow processing and higher operational costs,” he added. In essence, while banks can subsidize acquiring costs to attract major merchants, they often grapple with cumbersome legacy systems that stifle speed and innovation.

    Platform Giants Navigate Their Own Challenges

    On the other hand, platform companies enjoy high levels of user engagement and app stickiness. However, they are not immune to challenges, facing significant technology costs along with regulatory and security hurdles similar to those encountered by fintechs. Even so, it’s the fintechs that are driving the game forward with pioneering solutions in buy-now-pay-later schemes, contactless payments, and integrated wallets—attributes that make them remarkably agile and expansive in scope.

    A Competitive Landscape Unfolds

    Assistant Professor Ruan TienYue from the Department of Finance at NUS Business School highlights the distinct lanes of competition arising from these dynamics. “Banks are fiercely competing on card issuance as well as acquiring merchants, while fintechs are leading different innovations. Meanwhile, platform companies are integrating card payments into their own digital ecosystems,” Ruan explained.

    This seismic shift in competitive strategies is particularly evident in emerging markets like the Philippines and Malaysia, where fintechs are gaining traction. For instance, in the Philippines, where a staggering 99% of the market consists of small and medium-sized businesses, the government is promoting an alternative payment method known as QR PH, fueling fintech growth. Similarly, Malaysian fintechs are zeroing in on the tourist-driven hospitality sector with tailored digital solutions.

    While mature markets like China and Australia currently dominate in terms of card penetration, Ruan notes that emerging economies are catching up with impressive growth rates in digital payments. “Emerging economies are following very fast growth in terms of these digital payments,” he observed.

    The Road Ahead: Collaboration Is Key

    To boost card payment adoption, especially in rural areas, both experts advocate for public-private collaborations. “First of all is education—then infrastructure—then customized solutions,” Fu stated, listing mobile banking and alternative payments as vital tools for expanding reach. Ruan echoed this sentiment, suggesting that governments should spearhead investment in infrastructure and launch campaigns aimed at promoting the usage of bank accounts and cards.

    Questions & Answers

    How are fintechs gaining an edge in the card payment market?
    Fintechs leverage their technology-driven agility, allowing for faster scalability and the ability to innovate in ways traditional banks cannot, particularly in areas like buy-now-pay-later and integrated wallets.

    What challenges do platform companies face in this competitive landscape?
    Platform companies benefit from user engagement but struggle with high technological costs and face regulatory hurdles similar to those encountered by fintechs.

    Why is public-private collaboration important for expanding card payment adoption?
    Collaboration is crucial for improving education, infrastructure, and customized solutions, particularly in reaching rural areas where traditional banking services may be limited.

  • DBS and UOB Earnings Reveal How SORA and Rising Credit Costs Shape the Banking Landscape

    DBS and UOB Earnings Reveal How SORA and Rising Credit Costs Shape the Banking Landscape

    As the financial world eagerly anticipates this week’s earnings reports from major banks, all eyes are on DBS and UOB, particularly regarding their net interest margins and credit costs tied to Hong Kong property exposure. Michael Makdad, a senior equity analyst at Morningstar, shared insights that shed light on what investors can expect.

    DBS Earnings Could Shine Amid Challenges

    Makdad remains optimistic about DBS, forecasting positive earnings that he believes will emerge without significant spikes in credit costs or major drops in net interest margins. However, one pivotal query lingers: will DBS face increased credit costs stemming from its Hong Kong property operations, a concern that has raised eyebrows, especially in comparison to HSBC and its subsidiary, Hang Seng Bank?

    “OCBC has thus far escaped these pressures, and DBS’ operations in Hong Kong have yielded impressive returns without encountering similar issues,” Makdad noted. “Yet, it’s prudent to keep an eye on this factor.” The analyst hinted that while DBS appears well-positioned, tracking these credit costs remains essential as the full impact of Hong Kong’s real estate market unfolds.

    UOB’s Hefty ASEAN Exposure Sparks Questions

    For UOB, the stakes are equally intriguing. Makdad is particularly interested in the impact of the declining Singapore Overnight Rate Average (SORA) on UOB’s net interest margins. With UOB having a more substantial footprint in some ASEAN countries compared to DBS and OCBC, he speculated, “It will be telling to see if economic slowdowns in regions like Thailand influence their overall performance.”

    As the week progresses, the financial sector waits with bated breath. Will the results reflect the resilience of these banks or expose vulnerabilities in a shifting economic landscape? One thing’s for sure: the market’s pulse beats in sync with these earnings disclosures.

    Questions & Answers

    What factors are influencing the upcoming earnings reports for DBS and UOB?
    Key variables include credit costs related to Hong Kong property exposure and the impact of declining net interest margins, particularly with the recent drop in SORA.

    What is the outlook for DBS’s earnings according to Michael Makdad?
    Makdad expresses optimism about DBS’s earnings, expecting them to be positive without significant credit cost flare-ups or drastic reductions in net interest margins.

    Why is UOB’s situation particularly noteworthy during this earnings season?
    UOB has greater exposure to ASEAN markets compared to its peers, raising questions about the potential impact of economic slowdowns in those regions, particularly in Thailand.

  • Morgan Stanley Sees Potential in Pop Mart’s Labubu Amid Recent Stock Decline

    Morgan Stanley Sees Potential in Pop Mart’s Labubu Amid Recent Stock Decline

    Morgan Stanley maintains a bullish outlook on Pop Mart International Group, even as the company experiences a 10% dip in its stock price. The U.S. investment bank sees this slump as a potential buying opportunity, driven by Pop Mart’s robust growth trajectory fueled by exciting new product launches.

    Understanding Demand Amidst Market Fluctuations

    Despite a reduction in store lines and resale prices, Morgan Stanley asserts that this doesn’t reflect a drop in consumer interest. According to a recent report, most of Pop Mart’s offerings are mass-market items rather than scarce collectibles, which the Singapore-based investment platform Moomoo highlighted.

    This year has seen the LaBubu line—a collection designed by Dutch-Hong Kong artist Kasing Lung—continue to captivate children and collectors alike, while emerging toy lines such as Crybaby and Twinkle Twinkle are also generating buzz and showing promising sales.

    Power of Direct Sales

    Pop Mart’s direct-to-consumer model, which accounts for 90 to 95% of sales, enables the company to gather valuable real-time data. This agility allows them to adjust supply effectively, ensuring that inventory levels align closely with consumer demand.

    Impressive Projections Amid Challenges

    Morgan Stanley has ambitious forecasts for Pop Mart’s future, projecting sales to reach an impressive US$4.3 billion by 2025, escalating to US$6 billion in 2026. Notably, overseas operations could contribute as much as 60% of the company’s profit this year. Despite this optimistic outlook, the stock has suffered, dropping from a peak of HK$269.60 since July 8, largely due to a scarcity of near-term growth catalysts.

    “Market sentiment towards the company has yet to fully recover in the short term, given the high base last year,” noted Richard Lin, chief consumer analyst at SPDB International. “For the stock to rebound, the company will need to provide greater visibility on potential earnings drivers.”

    The Allure of the Labubu Toy

    The Labubu toys, featuring adorable yet cheeky creatures with a mix of soft fur and sharp teeth, have ignited a collector’s frenzy, prompting fans to queue for hours to snag the latest releases. Sold in blind boxes, these toys add an element of surprise, heightening the thrill of the collectable culture and motivating collectors to seek rare models, often marking them up for resale at enticing prices.

    This phenomenon has sent Pop Mart’s valuation soaring beyond US$40 billion, with its Hong Kong-listed shares skyrocketing an astonishing 588% in the past year, according to Bloomberg.

    Questions & Answers

    How is Morgan Stanley viewing Pop Mart’s recent stock price drop?
    Morgan Stanley views the 10% decline as a buying opportunity, emphasizing the company’s strong growth potential driven by new product launches.

    What factors contribute to Pop Mart’s success in the toy market?
    Pop Mart’s success stems from its popular toy lines, particularly Labubu, and its direct-to-consumer sales model that allows for real-time inventory management.

    What challenges does Pop Mart face in the near term?
    The company faces challenges such as a need for clearer visibility on earnings drivers to boost market sentiment and share price recovery after a significant peak loss.

  • VN-Index Soars to Its Largest Gain in Four Months: Retail Market Celebrates Strong Recovery!

    VN-Index Soars to Its Largest Gain in Four Months: Retail Market Celebrates Strong Recovery!

    The index closed 32.98 points higher, rebounding from a prior drop of 7.31 points. This encouraging shift reflects a resurgence of investor confidence in the Vietnamese stock market.

    Trading volume on the Ho Chi Minh Stock Exchange surged by approximately 9.2%, reaching VND42.6 trillion (US$1.63 billion), a clear sign of renewed activity.

    Most stocks in the VN-30 basket, representing the 30 largest companies, ended the day on a high note. Four notable stocks—VJC from budget airline Vietjet, VIC from conglomerate Vingroup, SHB of Saigon Hanoi Commercial Bank, and TPB from TPBank—hit their ceiling prices, illuminating a robust market sentiment.

    However, not every blue chip could bask in the glow; FPT of tech giant FPT Corporation slid slightly, closing down by 0.4%. It’s almost as if FPT was the lone wolf at a party of jubilant investors.

    Foreign investors took a different stance, emerging as net sellers with VND10.26 trillion in sales, predominantly offloading stocks like VIC and SSI of SSI Securities Corporation.

    Meanwhile, the HNX-Index on the Hanoi Stock Exchange, which tracks mid and small-cap stocks, climbed 1.29%, while the UPCoM-Index for unlisted public companies advanced by 0.66%, demonstrating that the upward momentum was widespread.

    Questions & Answers

    What was the performance of the VN-Index on August 4, 2025?
    On August 4, 2025, the VN-Index saw a significant increase of 2.21%, closing at 1,528.19 points—its most substantial gain in nearly four months.

    Which stocks hit their ceiling prices during this trading session?
    Four stocks achieved ceiling prices: VJC of Vietjet, VIC of Vingroup, SHB of Saigon Hanoi Commercial Bank, and TPB of TPBank, highlighting a thriving market environment.

    How did foreign investors react during this trading session?
    Foreign investors were net sellers, offloading VND10.26 trillion, primarily selling shares of VIC and SSI Securities Corporation, indicating a cautious approach amidst the market’s rising trend.

  • Islamic Finance Market Set to Reach $7.7 Trillion by 2033: A Future of Growth and Opportunity

    Islamic Finance Market Set to Reach $7.7 Trillion by 2033: A Future of Growth and Opportunity

    The Islamic finance market is poised for remarkable growth, projected to reach an astonishing $7.7 trillion by 2033, according to a report by Allied Market Research. This translates to a compound annual growth rate (CAGR) of 12% over the next decade, scaling from a valuation of $2.5 trillion in 2023.

    The surge in cashless transactions and the rise of digital banking are key drivers behind this expansion. Innovations such as real-time payment systems and AI-enhanced fraud detection are not just buzzwords; they are pivotal in shaping consumer preferences and ensuring secure financial interactions. “By emphasizing risk-sharing models and providing alternatives to interest-based lending, Islamic financial institutions have been successful in reaching underserved populations, particularly in developing economies,” the report emphasizes.

    Rooted in Shariah law, Islamic finance has distinctive principles that prohibit interest (riba) and speculative practices (maysir), favoring instead profit-sharing and asset-backed financing. These concepts resonate particularly well in regions where conventional banking systems may not adequately serve the community. Governments in many Muslim-majority countries and prominent financial hubs are stepping up their support for Islamic finance, leveraging favorable policies and regulatory reforms to foster growth.

    Clear legal frameworks that align with Sharia principles are being established, creating a safe and secure landscape for Islamic banking, investment, and insurance products. “This not only enhances trust but also attracts a growing base of consumers who are seeking ethical investment options,” the report notes. It seems that Islamic finance is not just about numbers; it’s crafting a narrative where ethics meets commerce.

    However, the journey is not without its hurdles. The lack of standardization and regulatory consistency can shadow market players, while complex product structuring poses additional challenges. To navigate these waters, institutions are increasingly turning to AI-driven solutions for fraud prevention and blockchain technologies to secure transactions, ensuring smoother operations and increased consumer confidence.

    Questions & Answers

    What is the projected growth of the Islamic finance market over the next decade?
    The Islamic finance market is projected to grow to $7.7 trillion by 2033, achieving a compound annual growth rate of 12%.

    What are some key factors driving the growth of Islamic finance?
    The shift towards cashless transactions, advancements in digital banking, real-time payment systems, and AI-driven fraud detection are significant factors propelling the market.

    What challenges does the Islamic finance market face?
    Challenges include a lack of standardization, regulatory harmonization, and the complexity of product structuring. Institutions are seeking to address these issues through AI technology and blockchain for secure transactions.

  • UBS Settles Legacy Credit Suisse RMBS Case with U.S. DOJ: A New Chapter Unfolds

    UBS Settles Legacy Credit Suisse RMBS Case with U.S. DOJ: A New Chapter Unfolds

    In a significant move, UBS has put another Credit Suisse legacy issue behind it by reaching a settlement with the U.S. Department of Justice (DOJ). This agreement pertains to outstanding obligations linked to a 2017 settlement concerning Credit Suisse’s former Residential Mortgage-Backed Securities (RMBS) business, as detailed in a press release from UBS.

    The pivotal moment came on August 1, 2025, when Credit Suisse Securities (USA) LLC signed a definitive agreement with the DOJ, committing to fulfill all remaining consumer relief obligations established in the original 2017 settlement. As part of this resolution, UBS will disburse a substantial payment of USD 300 million.

    Looking ahead, UBS anticipates registering a credit in its Non-core and Legacy segment during the third quarter of 2025. This credit will stem from the release of a contingent liability recognized during the acquisition of Credit Suisse and is expected to contribute positively to the financial narrative the bank is crafting.

    This settlement aligns perfectly with UBS’s broader strategy aimed at addressing lingering legacy issues quickly and equitably, reinforcing their commitment to serve the interests of all stakeholders involved. For UBS, it’s not just about closing old chapters; it’s about paving the way for a more resilient future—after all, who doesn’t love a good comeback story?

    Questions & Answers

    Why did UBS reach a settlement with the U.S. DOJ?
    UBS settled with the U.S. DOJ to resolve outstanding obligations tied to a 2017 agreement related to Credit Suisse’s former RMBS business, demonstrating their commitment to addressing legacy issues swiftly.

    What is the financial impact of the settlement for UBS?
    The settlement entails a payment of USD 300 million, and UBS expects to register a credit in its Non-core and Legacy segment, contributing positively to its financial standing in the third quarter of 2025.

    How does this settlement fit into UBS’s overall strategy?
    This resolution is part of UBS’s broader strategy to address remaining legacy matters efficiently and equitably, enhancing transparency and trust among stakeholders while moving towards a stronger financial future.

  • Dollar Dips as Vietnamese Dong Gains Strength in Currency Exchange Dynamics

    Dollar Dips as Vietnamese Dong Gains Strength in Currency Exchange Dynamics

    The U.S. dollar fell against the Vietnamese dong Monday morning as it inched up against major peers.

    In a notable shift, Vietcombank set the dollar at VND26,370, reflecting a 0.08% decline compared to the previous weekend’s rate. Meanwhile, in the black market, the dollar maintained a robust position at around VND26,480.

    The State Bank of Vietnam also adjusted its reference rate, lowering it by 0.04% to VND25,240, marking another chapter in the ongoing currency fluctuations.

    On the global front, the dollar experienced a slight uptick on Monday, recovering marginally after a staggering U.S. jobs report and the surprising firing of a high-ranking labor official by President Donald Trump rattled investors. The developments fueled expectations for imminent rate cuts by the Federal Reserve, according to Reuters.

    Against a basket of major currencies, the dollar climbed by 0.2%, reaching 98.86, following a significant drop of over 1% last Friday. In the currency exchange market, the dollar made a modest recovery against the Japanese yen, trading 0.14% higher at 147.60 yen, albeit still down around 3 yen from its peak on Friday. The euro slipped by 0.2% to $1.1560, while sterling eased slightly, down 0.1% to $1.3263, demonstrating the ongoing volatility in currency markets.

    Questions & Answers

    What caused the U.S. dollar to fall against the Vietnamese dong?
    The dollar’s decline against the dong mainly resulted from Vietcombank’s adjusted selling rate and a global market response to disappointing U.S. job figures and the surprising removal of a labor official by President Trump.

    How did the State Bank of Vietnam respond to the shifting currency landscape?
    The State Bank of Vietnam lowered its reference rate by 0.04% to VND25,240, which plays a role in guiding the overall value of the dong amid international fluctuations.

    Is the dollar likely to show more volatility in the near future?
    Given the current economic environment, including rate cut expectations from the Federal Reserve and geopolitical uncertainties, the dollar is expected to experience continued volatility against multiple currencies.

  • Citi Unveils Enhanced Tokenisation and Real-Time Solutions for Corporate Treasuries

    Citi Unveils Enhanced Tokenisation and Real-Time Solutions for Corporate Treasuries

    Citigroup, Inc. is ratcheting up its foray into tokenization and automation, responding to the growing demand from corporate treasuries for real-time access to liquidity and global cash visibility. The bank’s latest suite of digital services is designed specifically to dismantle operational challenges linked to traditional banking cut-off times, public holidays, and regional time zones.

    “The absence of real-time visibility into cash positions across multiple accounts often leads to myriad challenges, such as ineffective cash forecasting and inefficient allocation,” explained Stephen Randall, global head of liquidity management services at Citi, in a recent interview with Asian Banking & Finance. “These issues can increase operational costs, elevate risk levels, and hamper strategic decision-making.”

    According to Citi’s November 2023 research, top-tier treasury operations are characterized by advanced forecasting capabilities and a centralized liquidity pool. This growing expectation from clients has compelled banks to innovate continuously to keep pace. “There is a pressing demand for enhanced speed and greater volumes in cash flows,” Randall added, mentioning clients’ desire for improved visibility and easier reconciliation processes.

    In response, Citi has launched several groundbreaking initiatives, including Citi Token Services (CTS), Real-Time Funding (RTF), and 7-Day Sweeps, all geared towards optimizing cash positioning while reducing operational friction. CTS enables clients to transfer cash instantaneously across borders, free from the typical constraints of holidays or banking hours. “Asia is a focal point for CTS; two of the four markets currently operational are Singapore and Hong Kong,” said Randall.

    Meanwhile, Real-Time Funding stands out as a game changer, allowing clients to transfer funds globally among their Citi accounts in real time. “Imagine a client needing to make an urgent payment from their Citi Hong Kong account today, but their money is stuck in a Citi London account,” Randall said. “With RTF, that funds transfer becomes instantaneous, enabling timely payments without cumbersome manual processes.” Presently, RTF is available in Australia, Hong Kong, and the UK, with plans for expansion into Singapore, Thailand, China, and Taiwan on the horizon.

    Additionally, Citi’s 7-Day Sweeps service automates liquidity management round-the-clock and is now operational in the US, South Korea, and Thailand. Randall pointed out that these sweeps are processed even on holidays, significantly reducing reconciliation challenges and providing a robust liquidity buffer over weekends and public holidays.

    The dynamic landscape of treasury management is shifting, with treasurers moving away from static liquidity structures—often evaluated annually—to more adaptable frameworks that can respond swiftly to cash flow volatility. “Treasurers are looking for liquidity structures that can handle abrupt cash flow changes, especially in light of the market uncertainties imposed by geopolitical shifts and tariff-related disruptions,” said Randall.

    Moreover, as clients confront risks associated with fluctuating interest rates and foreign exchange, they increasingly seek digital solutions and advisory support from Citi. Automation and digitalization offer crucial advantages, providing timely access to vital data on global cash positions—information that is instrumental for informed decision-making.

    Citi Treasury Diagnostics, the bank’s global benchmarking tool, serves to highlight how clients’ treasury operations measure up against best practices. The bank provides advanced programming interfaces such as Balance Inquiry and Payment Status, along with integration support, to enable clients to enhance their treasury systems.

    Randall emphasized that tools like Citi Treasury Diagnostics can assist clients in benchmarking their practices, revealing opportunities for further improvements through automation. He encouraged clients to leverage technology-driven services to minimize dependency on manual processes while refining and automating their operations.

    Questions & Answers

    How is Citigroup addressing the needs of corporate treasuries?
    Citigroup is introducing innovative solutions like Citi Token Services, Real-Time Funding, and 7-Day Sweeps to enhance cash visibility and streamline operations for corporate treasuries.

    What are the benefits of Real-Time Funding?
    Real-Time Funding enables clients to make global fund transfers instantaneously, allowing immediate access to cash for urgent payments without manual intervention.

    How is Citi’s 7-Day Sweeps service beneficial for liquidity management?
    The 7-Day Sweeps service automates liquidity management around the clock, processes transactions on holidays, and helps maintain a healthy liquidity buffer, reducing reconciliation difficulties.

  • AEON Bank and foodpanda Partner to Boost Digital Banking Adoption for Riders and Merchants

    AEON Bank and foodpanda Partner to Boost Digital Banking Adoption for Riders and Merchants

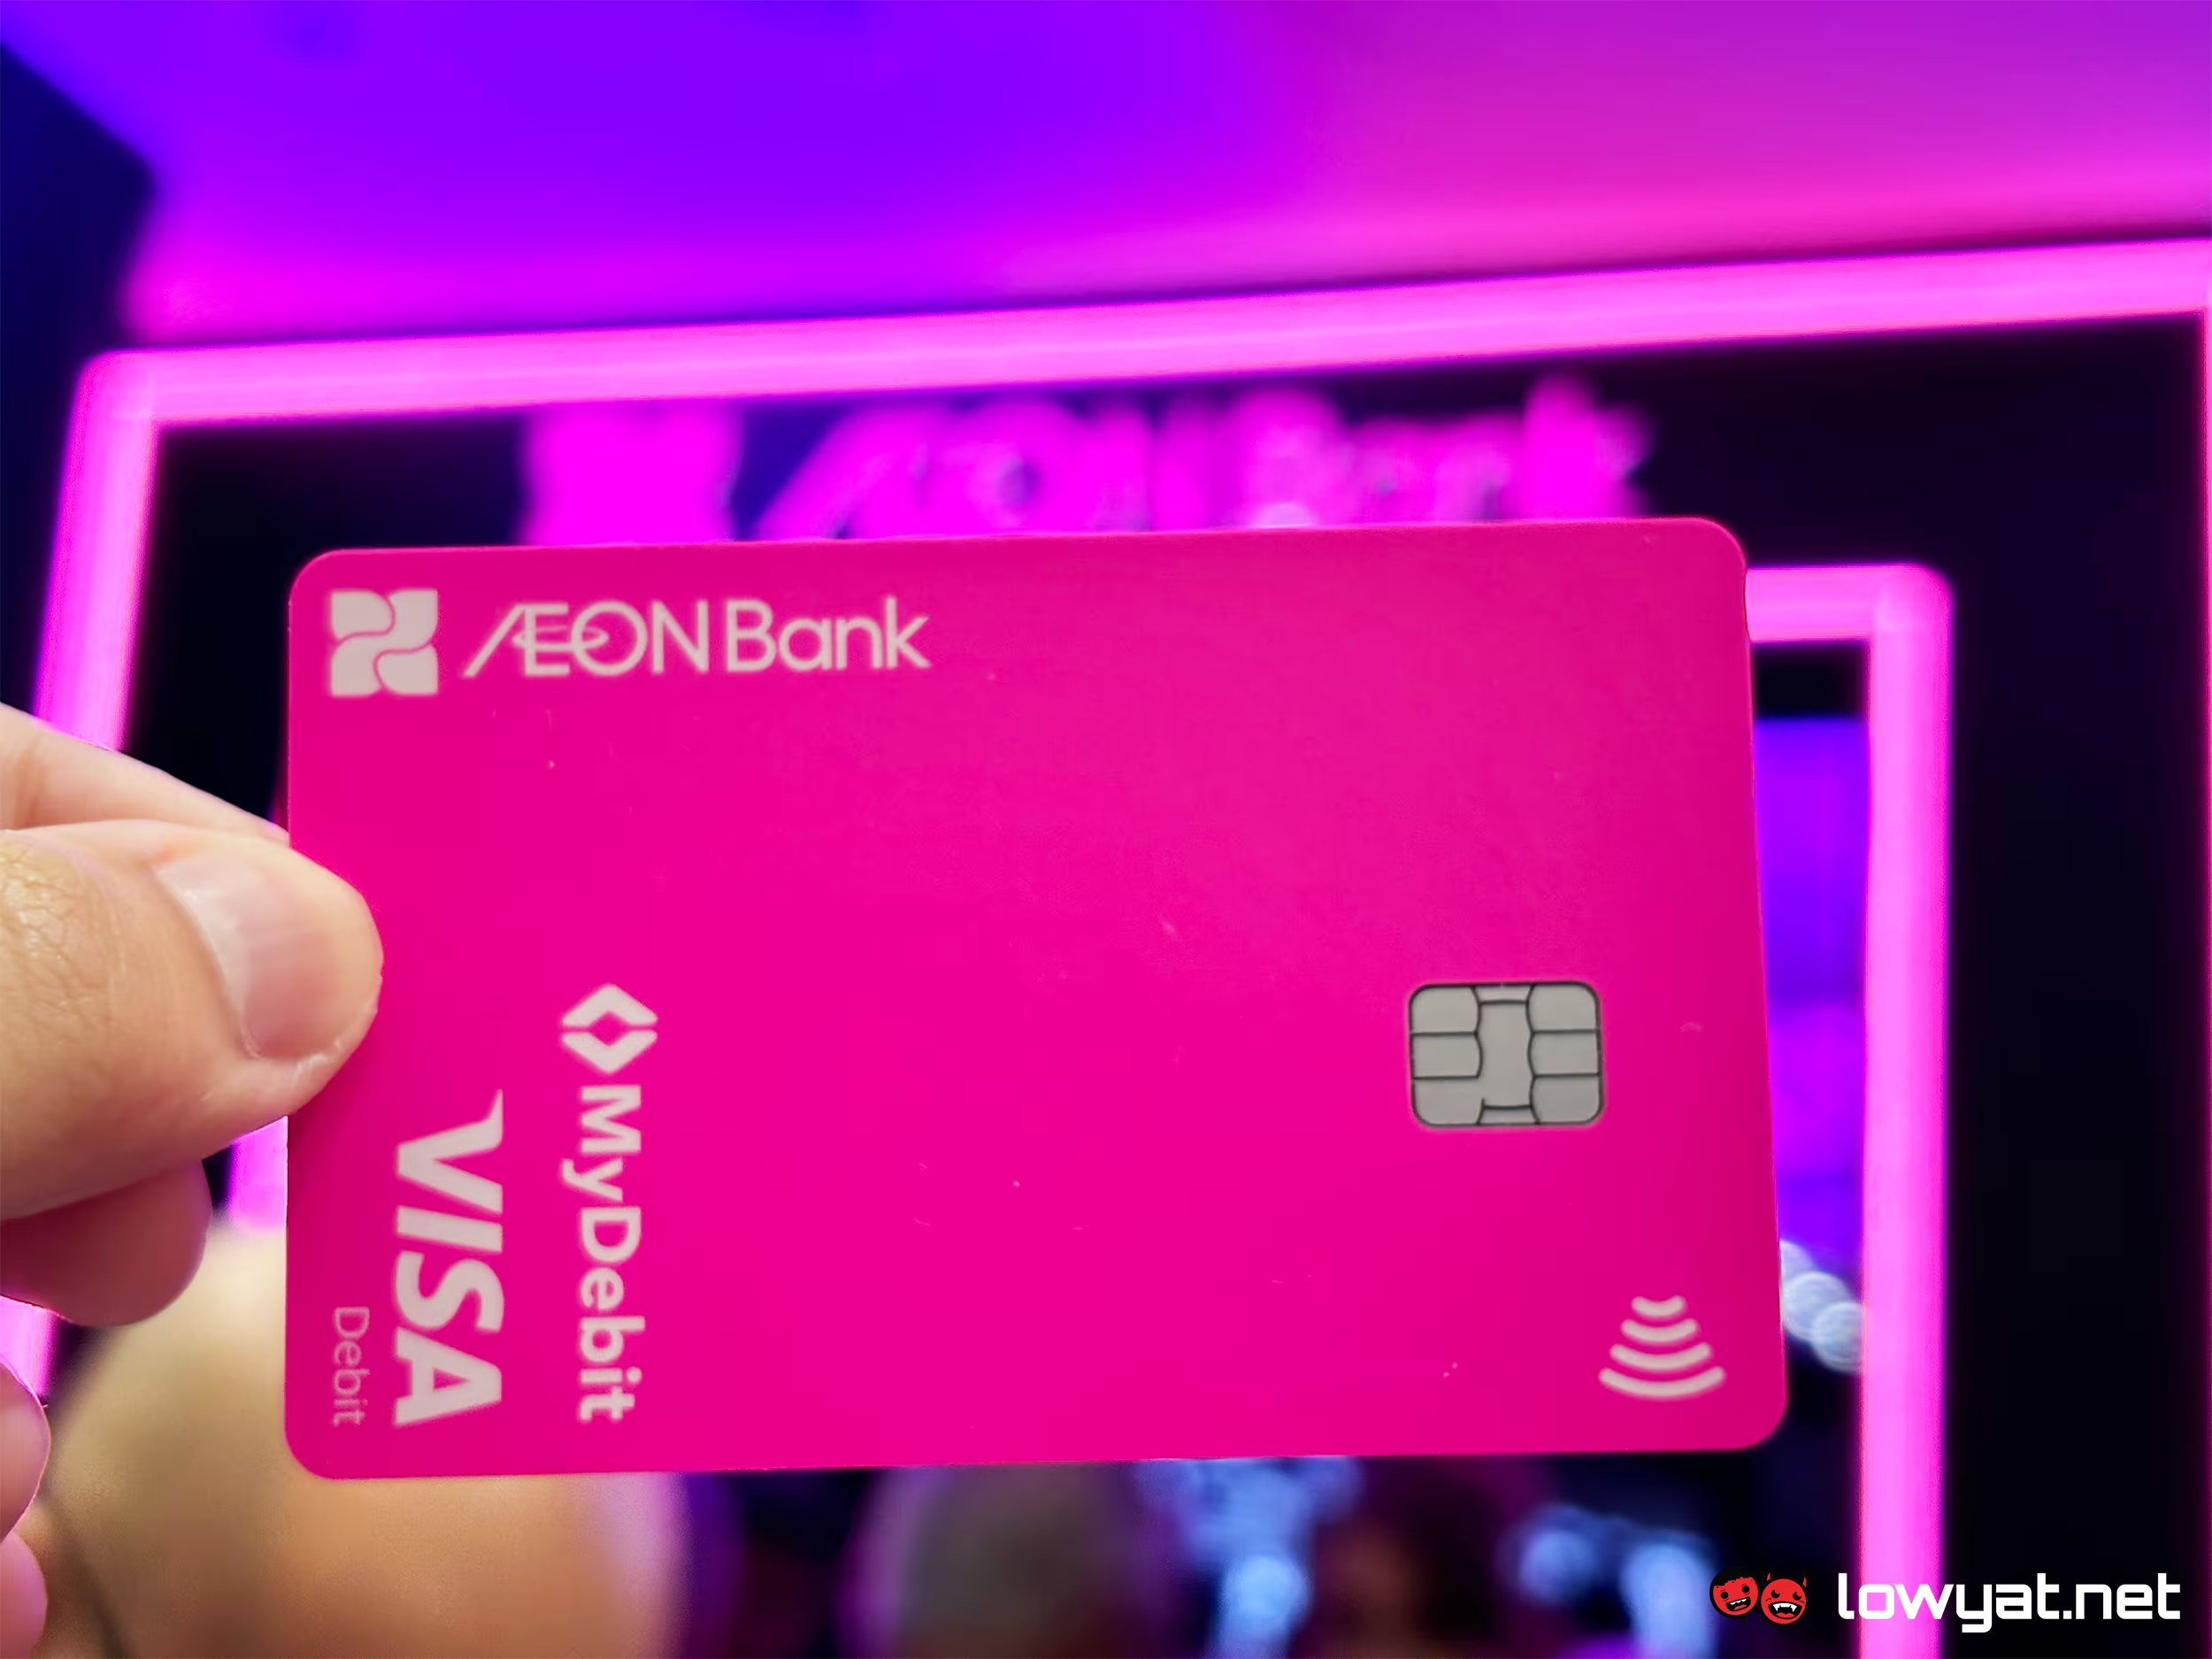
    In a significant move to enhance digital banking access, AEON Bank has announced a partnership with foodpanda Malaysia aimed at boosting financial services among the platform’s extensive user base, which includes customers, delivery riders, merchants, and business partners. This collaboration, formalized under a memorandum of understanding, seeks to combine their strengths in customer acquisition, digital financing, and joint promotional campaigns.

    A Bold Step for Islamic Digital Banking

    As Malaysia’s first Islamic digital bank, AEON Bank stands at the forefront of innovation in finance. “We are excited to bring added value to foodpanda’s riders and merchants by providing them access to digital banking, rewards programs, and services that will enhance their overall experience,” stated YM Raja Datin Paduka Teh Maimunah Raja Abdul Aziz, the bank’s CEO.

    Linking Platforms for Greater Impact

    The partnership aims to utilize foodpanda’s vast network in conjunction with AEON Bank’s Shariah-compliant financial products and AEON Points loyalty program. Teh Maimunah emphasized that this integration will significantly impact target segments, particularly gig workers and micro, small, and medium enterprises (MSMEs). “Our goal is to drive growth and engagement within these communities,” she added, hinting at a future where digital banking and food delivery intersect seamlessly.

    The Future of Food Delivery and Online Grocery Shopping

    Both companies are optimistic about contributing to Malaysia’s burgeoning food delivery and online grocery sector. Projections suggest that user penetration in this market could climb to 34.2% by 2025, translating to over 14.5 million users by 2030. Who knew that a simple meal delivery service could serve as a gateway to financial empowerment?

    Signing the memorandum of understanding were Teh Maimunah and Tan Ming Luk, the Managing Director of foodpanda Malaysia, marking the beginning of a partnership that promises to reshape the digital finance landscape for many in Malaysia.

    Questions & Answers

    What is the main goal of the partnership between AEON Bank and foodpanda Malaysia?
    The partnership aims to enhance digital banking access and services for foodpanda’s wide array of users, including customers, riders, and merchants, while fostering customer acquisition and growth for both companies.

    How does AEON Bank intend to support gig workers and MSMEs through this collaboration?
    AEON Bank plans to provide Shariah-compliant financial products and integrate its AEON Points loyalty program to offer meaningful services that cater to the specific needs of gig workers and micro, small, and medium enterprises.

    What are the projected figures for Malaysia’s food delivery and online grocery sector?
    User penetration in this sector is expected to reach 34.2% by 2025, with forecasts indicating over 14.5 million users by the year 2030.

  • Vietnam Sets Ambitious Goal to Launch International Financial Center by Year-End

    Vietnam Sets Ambitious Goal to Launch International Financial Center by Year-End

    Vietnam is embarking on an ambitious initiative to establish an International Financial Center (IFC), a move poised to attract medium and long-term financial investments that will serve as a cornerstone for the nation’s socio-economic development. In tandem with this effort, the Vietnamese government is committed to finalizing a legal framework for the IFC, promoting a transparent and coordinated environment that will appeal to capital, cutting-edge technologies, modern management practices, and high-caliber talent from around the globe.

    Building Infrastructure for Financial Success

    To power the IFC’s ambitious goals, essential infrastructure and services—including transportation, telecommunications, and logistics—will see significant upgrades in Ho Chi Minh City and Da Nang. With a target of finalizing key infrastructure projects by late 2025, the government aims to create a web of seamless connectivity that supports the IFC’s operations.

    A Vision for a Modern Financial Ecosystem

    The overarching plan includes the development of a sophisticated financial ecosystem—think carbon and commodity exchanges—while championing innovative financial services like fintech and digital banking. The initiative also underscores the importance of establishing international-standard support services in legal, auditing, and technology domains.

    Key Locations Take Center Stage

    Ho Chi Minh City is prioritized for the development of the IFC facility, which will extend across 793 hectares in the Saigon, Ben Thanh, and Thu Thiem wards. The city is also tasked with deploying a 5G network, laying the groundwork for flawless digital transactions that will underpin fintech and digital banking initiatives.

    Conversely, Da Nang is directed to enhance its technological capabilities, focusing on investing in computing server systems and intelligent operational infrastructure at Software Park No. 2. The city will promote the rollout of 5G coverage while also exploring blockchain technologies to pilot digital asset products, all the while establishing national standards for IoT, Big Data, and data management.

    Leadership Driving Change

    Prime Minister Chinh formalized this significant strategy with a decision on August 1, launching the Steering Committee dedicated to shaping Vietnam’s IFC vision. Featuring notable leaders like Permanent Deputy Prime Minister Nguyen Hoa Binh and key figures from the finance and banking sectors, the committee will guide the government’s strategic direction and ensure the IFC operates smoothly amidst Vietnam’s burgeoning financial landscape.

    Who knew a country could be both a tech playground and a financial powerhouse? As Vietnam builds its international financial center, the risk is high but the potential gains are tantalizingly close on the horizon.

    Questions & Answers

    What is the primary goal of Vietnam’s International Financial Center initiative?
    The initiative aims to attract medium and long-term financial investments, laying a foundation for Vietnam’s socio-economic growth while creating a robust legal framework for the financial center.

    Which cities are at the forefront of this financial movement?
    Ho Chi Minh City and Da Nang are the primary locations for the International Financial Center, with each city focusing on enhancing essential infrastructure and technological capabilities.

    Who is overseeing the development of Vietnam’s IFC?
    The effort is being guided by a Steering Committee headed by Permanent Deputy Prime Minister Nguyen Hoa Binh, alongside key leaders from various sectors of government and finance.

  • Singaporeans Boost Gold Investments by 37%, Signaling Strong Market Confidence

    Singaporeans Boost Gold Investments by 37%, Signaling Strong Market Confidence

    Singapore’s investment in gold bars and coins surged by 37% year-on-year, reaching 2.2 tonnes in the second quarter. Although this figure falls short of the record high of 2.5 tonnes observed in the first quarter, the World Gold Council indicates a strong upward trend in gold investments. Meanwhile, in Southeast Asia, gold investment also flourished, with notable double-digit growth reported in Indonesia, Malaysia, and Thailand. In contrast, Vietnam saw a 20% decline in gold investment, a discrepancy that raises eyebrows.

    On the jewelry front, Singaporeans are growing cautious. Gold jewelry demand fell by 8%, totaling 1.5 tonnes, largely influenced by soaring gold prices that restricted consumer purchasing power. This trend mirrors a broader global decline in jewelry consumption, which has dropped to levels reminiscent of the pandemic.

    Globally, investment in gold bars and coins witnessed an 11% uptick, amounting to 306.8 tonnes. Chinese investors led the charge with 115 tonnes, complemented by Indian investors contributing 46 tonnes. Interestingly, European net investment doubled to 28 tonnes, while the U.S. found itself on a different trajectory—demand for gold bars and coins plummeted by half to just 9 tonnes in the second quarter.

    Looking ahead, the World Gold Council cites geopolitical tensions, market volatility, and macroeconomic uncertainty as factors that will continue to fuel investment demand for gold. It also notes that the performance of the U.S. dollar will be crucial for institutional investors moving into the second half of the year. With many analysts predicting a structurally weaker dollar, the stage is set for intriguing shifts in the gold market.

    Questions & Answers

    What percentage increase did Singapore experience in gold investment in the second quarter?
    Singapore’s gold investment rose by 37% year-on-year in the second quarter, totaling 2.2 tonnes.

    How did the demand for gold jewelry in Singapore change recently?
    Gold jewelry demand in Singapore declined by 8%, reaching 1.5 tonnes, largely due to record-high gold prices.

    Which regions showed notable growth in gold investment during the second quarter?
    In Southeast Asia, gold investments increased significantly in Indonesia, Malaysia, and Thailand, all reporting double-digit growth compared to the previous year.

  • Vietnam Gold Prices Approach Historic Highs: What This Means for Investors and the Market

    Vietnam Gold Prices Approach Historic Highs: What This Means for Investors and the Market

    On Saturday, the price for gold bars from Saigon Jewelry Company surged by 1.73%, hitting VND123.5 million (approximately US$4,710.14) per tael, tantalizingly close to the historic peak of VND124 million set on April 22. Gold rings also saw a bump, climbing 1.62% to VND119 million per tael, with a tael equaling 37.5 grams or 1.2 ounces.

    Since January, the price of gold in Vietnam has skyrocketed by 47%, reflecting a broader pattern of investment interest amid evolving economic conditions.

    On the global stage, gold prices surged nearly 2% to reach a one-week high on Friday, driven by disappointing U.S. payroll data that heightened expectations for rate cuts from the Federal Reserve, as well as new tariff announcements that increased demand for safe-haven assets. In fact, spot gold, which peaked at its highest since July 25, saw an impressive rise, adding 1.8% to $3,347.66 per ounce after flirting with a 2% increase earlier in the day. Over the past week, bullion notched a 0.4% gain.

    “Although payroll figures came in below forecasts, they were slightly higher than the market anticipated. This enhances the likelihood that the Federal Reserve will consider rate cuts later this year,” remarked Bart Melek, head of commodity strategies at TD Securities, to Reuters. Indeed, gold, often regarded as a non-yielding asset, tends to thrive in a low-interest-rate environment, leaving investors on the edge of their seats to see how this plays out.

    Questions & Answers

    How much have gold prices in Vietnam increased since the beginning of the year?
    Gold prices in Vietnam have jumped 47% since the start of the year.

    What recent economic data influenced the rise in gold prices globally?
    Weaker-than-expected U.S. payroll data played a crucial role in boosting expectations for Federal Reserve rate cuts, which in turn heightened demand for gold as a safe-haven asset.

    What were the recent price movements for gold bars and rings in Vietnam?
    Gold bars increased by 1.73% to VND123.5 million per tael, while gold rings rose by 1.62% to VND119 million per tael.

  • Hong Kong’s Stablecoin Legislation: A New Era for Wealth Management and Payment Innovations!

    Hong Kong’s Stablecoin Legislation: A New Era for Wealth Management and Payment Innovations!

    Hong Kong’s recently enacted stablecoins ordinance is poised to shake up the local banking landscape, particularly in the realm of digital payments. As these digital currencies emerge, they may create fresh competition for banks while simultaneously providing new opportunities in wealth management. “Stablecoins issued in Hong Kong could increase competition for banks, particularly in wholesale payments, due to potential advantages in cost and speed,” stated Phyllis Liu, a credit analyst at S&P Global Ratings.

    Facing this evolving environment, local banks are expected to proactively participate in the market to mitigate the risk of disintermediation. Liu notes, “Hong Kong banks will seek to participate in the market to avoid disintermediation threats.” The new landscape could also bolster their wealth management services, drawing in more clients from mainland China and beyond.

    Michael Huang, another credit analyst for S&P, elaborates on this potential shift, suggesting that by offering stablecoin-linked products or digital assets, Hong Kong banks may appeal to both local and international customers eager for offshore crypto investments. It’s like a retail revival for the financial sector, where traditional banking meets the digital frontier.

    The interest in Hong Kong’s stablecoin market is described as “very strong,” with the Hong Kong Monetary Authority indicating that it plans to issue a limited number of stablecoin licenses. “We anticipate first movers will likely be big tech companies and large banks that have deep resources and technological skills,” remarked S&P, hinting at an exciting intersection of technology and finance in the city’s future.

    Questions & Answers

    How might stablecoins affect traditional banking in Hong Kong?
    Stablecoins could introduce significant competition for banks, particularly in wholesale payments, by offering advantages in cost and speed, prompting banks to adapt to avoid losing their market share.

    What opportunities do stablecoins present for Hong Kong banks?
    Aside from facing competition, banks could enhance their wealth management services and attract mainland Chinese customers by offering stablecoin-linked products and digital assets.

    Who are likely to be the first movers in the stablecoin market?
    Big tech companies and well-established banks with extensive resources and technological prowess are expected to be the early adopters in Hong Kong’s stablecoin landscape.

  • Malaysia Imposes MYR3.44 Million Fine on Bank Islam for Service Disruptions and Compliance Failures

    Malaysia Imposes MYR3.44 Million Fine on Bank Islam for Service Disruptions and Compliance Failures

    Amidst evolving regulatory landscapes, Bank Islam Malaysia Berhad (BIMB) finds itself in hot water as Malaysia’s central bank, Bank Negara Malaysia (BNM), imposes a financial penalty due to service disruptions and compliance failures. The bank has been penalized a total of MYR3.44 million for a series of unfortunate events that impacted its banking services and risk management practices.

    Unplanned Downtimes Shake Customer Trust

    BIMB drew the central bank’s ire with a fine of MYR1.74 million after experiencing multiple unplanned downtimes between June 1, 2023, and December 31, 2024. These outages severely affected its e-banking channels, debit card services, and online payment transactions. BNM disclosed that these disruptions resulted from BIMB’s delayed response and lack of a robust recovery process, ultimately causing turmoil for customers relying on essential banking services.

    Compliance Breaches Compound Troubles

    In addition to service lapses, BIMB faced a separate penalty of MYR1.7 million for failing to comply with anti-money laundering and combating the financing of terrorism (AML/CFT) regulations. According to BNM, an on-site examination revealed alarmingly inadequate sanctions screening processes within BIMB’s systems.

    The bank’s noncompliance was further exacerbated by its failure to timely screen its entire customer database against the Domestic List following updates published in the Federal Gazette in 2022 and 2023. This oversight delayed the identification of matches for three specified entities, raising significant concerns regarding the bank’s anti-financial crime measures.

    A Wake-Up Call for Financial Institutions

    The penalties imposed on BIMB highlight the critical need for financial institutions to maintain rigorous compliance protocols and ensure their systems are equipped to handle unexpected challenges. While BIMB may have caught a few unfortunate breaks, the overarching lesson remains: in the fast-paced world of banking, a blip in service can ripple out to many unsuspecting customers, making swift mitigation a must. Warning bells ringing, BIMB now has a stern reminder that effective risk management is as essential as delivering seamless service.

    Questions & Answers

    What prompted Bank Negara Malaysia to impose penalties on BIMB?
    The penalties stemmed from a series of unplanned downtimes affecting services and shortcomings in compliance with AML/CFT regulations.

    How much total financial penalty was levied against BIMB?
    BIMB faced a total penalty of MYR3.44 million, which includes MYR1.74 million for service disruptions and MYR1.7 million for compliance failures.

    What were some specific compliance failures identified by Bank Negara Malaysia?
    BIMB failed to conduct timely sanctions screening for its customer database, which led to delays in identifying matches for three specified entities.