Category: Finance

Retail News Asia is committed to providing both local and global retailers with the latest Finance news throughout the Asian market. This on a daily base.

  • UBS Subsidiary Faces Setback with Loss of Esteemed Banking Mandate

    UBS Subsidiary Faces Setback with Loss of Esteemed Banking Mandate

    Revamping Leasing: Porsche Shifts Focus to Internal Management

    Porsche Switzerland is making a significant pivot in its leasing strategy. In a recent announcement, the iconic sports car manufacturer revealed that it will no longer rely on Bank-now—a subsidiary integrated into UBS following its acquisition of Credit Suisse—for its leasing operations. Instead, Porsche Financial Services Schweiz (PFSCH) will take the reins and manage leasing directly, aided by the operational support of Amag Leasing as an outsourcing partner.

    The End of an Era: Goodbye to Bank-now for Leasing

    For over a decade, Bank-now has held the reins of Porsche’s leasing activities in Switzerland. The specialist in consumer credit and leasing joined UBS after the historic takeover of Credit Suisse, marking a notable partnership since 2008. This recent restructuring reflects a strategic decision by Porsche to bring leasing operations in-house, allowing the company to have more control over key aspects of the value chain. The goal is to enhance flexibility in addressing customer demands and the needs of its dealers amid a rapidly changing automotive landscape.

    Embracing the Future with New Offerings

    The shift allows Porsche to respond more dynamically to evolving market trends driven by the rise of electric vehicles and the increasing importance of digital solutions. “With this strategic realignment, we are strengthening our resilience in an increasingly demanding market environment,” stated Dino Minutolo, Managing Director of PFSCH, underscoring the proactive approach to meet the challenges ahead. Expect a fresh array of tailored financing models to hit the market soon—imagine financing your dream Porsche with a swipe on an app!

    Gaining Independence: A New Chapter

    This newfound autonomy paves the way for Porsche to engage in independent product design while ensuring a closer relationship with its dealers. To facilitate the transition, Porsche will count on Amag Leasing’s expertise for back-office functions and contract processing, allowing them to focus on strategic development and customer service enhancement.

    Bank-now Faces New Challenges

    As Porsche moves forward with PFSCH, Bank-now experiences a notable loss of a high-profile client. The bank chose not to comment on how this change might impact its financial metrics. “Beyond our annual report, Bank-now does not provide information on current business developments,” a representative shared, suggesting that all is not lost as the bank continues working with various strategic partners in vehicle financing.

    The Bigger Picture: Bank-now’s Stability

    While Porsche has opted for a new direction, Bank-now reassured stakeholders regarding its collaborative ties with brand-independent garages and extensive dealer networks. The volume of Porsche’s previous leasing business remains a well-guarded secret, as both parties are tight-lipped about the specifics of their financial dealings.

    On a more positive note for UBS Switzerland, Porsche Financial Services’ credit card business, which underwent restructuring last year, still maintains ties with the bank. So, while one door closes, another remains open.

    Financial Health: Bank-now’s Robust Position

    Looking ahead, Bank-now displayed commendable health in its financial reports for the 2024 fiscal year, boasting total assets exceeding CHF 5 billion, equity of CHF 416.3 million, and an operating profit of CHF 39.5 million. With a CHF 73 million dividend distribution to UBS Switzerland, the bank appears to be on steady ground, even as it navigates this noteworthy client transition.

    Questions & Answers

    What prompted Porsche to transition its leasing operations away from Bank-now?
    Porsche decided to take control of its leasing operations to enhance flexibility and better respond to changing customer needs and market dynamics, particularly in the wake of electric mobility and digitalization.

    How does this restructuring affect Bank-now?
    Losing Porsche as a client represents a significant shift for Bank-now. However, the bank continues to collaborate with various strategic partners in vehicle financing, aiming to offset this loss.

    What financial condition is Bank-now currently in?
    Bank-now has reported strong financial health, with more than CHF 5 billion in total assets and a dividend distribution of CHF 73 million to UBS Switzerland, demonstrating its resilience despite recent changes.
  • Raiffeisen Reports: Immigration Key to Sustaining GDP Growth Momentum

    Raiffeisen Reports: Immigration Key to Sustaining GDP Growth Momentum

    Swiss Economy’s Growth Weighed Down by Global Concerns

    The Swiss economy’s growth appears to be buoyed more by immigration trends than by domestic productivity, according to Raiffeisen’s latest semi-annual economic forecast. The report highlights that challenges in the global economy, particularly from the U.S. and EU, are casting a shadow over Switzerland’s economic outlook.

    As trade relations with the U.S.—Switzerland’s second-largest trading partner—remain precarious, Raiffeisen’s economists caution that the impact of potential tariffs looms large. Negotiations have been sluggish, with possible tariffs on the Swiss pharmaceutical industry still on the table. “The market underestimates that Trump is focused on increasing tariff revenues, not on reciprocal tariffs,” warned Chief Economist Fredy Hasenmaile, during a web call.

    Hasenmaile projected that regardless of the severity of any final tariff measures, the pervasive uncertainty is stifling the industry, predicting a loss of momentum in the latter half of the year.

    Economic Activity Dips Following Early Surge

    Switzerland experienced a paradoxical first half of the year, driven initially by pre-emptive purchases but ultimately leading to a significant downturn. After a robust boost in the first quarter, economic activity fell to its lowest level in over 15 months.

    Raiffeisen now forecasts GDP growth of 1.1 percent for the current year and 1.0 percent for the next, a considerable drop from earlier projections made in December 2024, which had assessed a 1.3 percent growth for 2025. “The return to potential growth of around 1.5 percent is further delayed,” Hasenmaile noted, positioning Raiffeisen on the conservative end of economic forecasts.

    Mixed Signals in Industrial Performance

    The outlook for Swiss industry is bleak, with purchasing manager indices indicating poor business conditions. Domestically focused small and medium enterprises (SMEs) are faring better, continuing on a growth trajectory. Conversely, export-driven firms are witnessing dwindling demand, particularly from Germany, with only 20 percent anticipating any improvement.

    The service sector, which had seen sustained positive momentum for nearly a year, has now dipped below the growth threshold in the purchasing managers’ index, indicating rising concerns.

    Real Wage Growth Fuels Consumer Spending

    Despite the uncertain industrial backdrop, Swiss consumer spending remains robust, bolstered by wage increases and low inflation contributing to real wage growth. Yet, signs of a cooling labor market are increasingly evident.

    Employment Landscape Slows

    The labor market mirrors the economy’s mixed expectations, with the KOF employment indicator showing signs of weakness. Surveys reflect a dip in hiring intentions, hinting at slower employment growth and a seasonally adjusted uptick in unemployment. “So far, the industrial downturn has hardly affected the service sector,” Hasenmaile pointed out, “but even the previously resilient domestic market could encounter challenges as the year progresses.”

    Negative Interest Rates Unlikely in Switzerland

    As uncertainties around tariffs persist, they have become a significant hindrance to Switzerland’s return to potential growth, raising the proverbial elephant in the room. Hasenmaile commented on the Swiss National Bank’s (SNB) interest rates, stating, “Zero is not negative,” and he does not foresee the SNB pushing rates back into negative territory soon.

    Global Influence on Interest Rate Policy

    The robust Swiss franc plays a critical role in shaping interest rate policy conditions. The current strength of the dollar has also lent a hand to the eurozone. While further rate cuts are anticipated in the eurozone and the U.S., where more flexibility exists, Hasenmaile believes the European Central Bank is likely to keep rates steady in July.

    Population Growth Fuels Economic Activity

    Two consecutive years of moderate economic growth could potentially lead to a decline in per capita economic output in Switzerland. With the economy largely expanding due to population growth rather than productivity, maintaining pace with demographic changes remains a crucial factor. Hasenmaile predicts a population growth rate of 0.9 percent for 2025, falling slightly to 0.8 percent the following year. “Net immigration depends heavily on the domestic labor market and developments in the EU,” he concluded.

    Regional Disparities in Growth

    Raiffeisen’s analysis reveals significant regional disparities within Switzerland. While sectors driven by population growth—such as retail, education, and healthcare—are thriving, autonomous sectors like industry and IT services are either stagnating or contracting in many regions. Zurich stands out, accounting for over 40 percent of autonomous growth, particularly in IT and consulting services. Central Switzerland and parts of western Switzerland, like Nyon and Rolle–Saint-Prex, are resisting the tide of deindustrialization and showing dynamic growth, although the overall contribution to growth from autonomous sectors has diminished.

    Questions & Answers

    What factors are currently impacting Swiss economic growth?
    Key factors include global economic uncertainties, particularly concerning trade relations with the U.S., and substantial net immigration which has bolstered growth.

    How is the industrial sector performing in Switzerland?
    The industrial sector faces challenges, with many companies reporting poor business conditions and declining demand, especially from export markets like Germany.

    What is the outlook for interest rates in Switzerland?
    The Swiss National Bank is not expected to move interest rates into negative territory, as existing economic conditions do not warrant such a drastic measure.

  • Malaysia’s Private Sector Loans Surge 5.4% in May, Boosting Economic Confidence

    Malaysia’s Private Sector Loans Surge 5.4% in May, Boosting Economic Confidence

    Asia’s retail landscape is brimming with innovation, and nowhere is this more evident than in the rise of omnichannel strategies among major players. As consumers in the region demand seamless shopping experiences that integrate both online and physical interactions, retailers are stepping up to meet these expectations with creativity and precision.

    Transforming Customer Experience

    Leading the charge is JD.com, which is redefining the shopping experience through cutting-edge technology. In a recent initiative, the e-commerce giant has begun experimenting with augmented reality (AR), allowing customers to visualize products in their own space before making a purchase. This playful and immersive approach not only enhances engagement but also boosts buyer confidence—a win-win in today’s competitive market.

    Revamping Traditional Outlets

    Meanwhile, traditional retailers aren’t sitting on the sidelines. With the pandemic having propelled a shift towards digital shopping, brands like 7-Eleven are redesigning their brick-and-mortar stores to cater to a hybrid shopping model. These new outlets emphasize convenience, featuring smart kiosks and dedicated pickup areas for online orders, making the in-store experience just as appealing as e-commerce. It’s not just a store; it’s an experience!

    Personalization at the Forefront

    In a world awash with choices, personalization has emerged as a powerful driver of customer loyalty. Retailers like Sephora have leaned into this trend by harnessing data analytics to offer tailored product recommendations. This level of customization not only enhances the shopping experience but also cultivates a connection between the customer and the brand, ensuring that shoppers feel seen and valued.

    Innovative Strategies in Payment Solutions

    Asia’s retail sector is also witnessing a revolution in payment solutions. The proliferation of mobile wallets, particularly in markets like China and Southeast Asia, is reshaping the way transactions are conducted. Companies such as Alibaba and Grab are leading the charge, enabling seamless transactions that often bypass traditional banking systems altogether. It’s as if cash is making a quiet exit, and digital currencies are gleefully taking center stage.

    Looking Ahead: Sustainability Matters

    As the spotlight on sustainability grows ever brighter, retailers are taking action. Brands are investing in eco-friendly practices and products to appeal to a more environmentally conscious consumer base. The challenge lies not only in meeting these expectations but also in communicating their sustainability efforts effectively. Retailers that navigate this tricky terrain will likely lead the pack in the years to come, as consumers increasingly prioritize ethics in their purchasing decisions.

    Questions & Answers

    How is JD.com using technology to enhance customer experience?
    JD.com is integrating augmented reality into its shopping platform, allowing customers to visualize products in their own environments before purchasing, thereby boosting engagement and buyer confidence.

    What changes are traditional retailers making to adapt to the rise of e-commerce?
    Traditional retailers like 7-Eleven are redesigning their stores to support hybrid shopping models, featuring smart kiosks and dedicated pickup areas for online orders to enhance convenience for customers.

    Why is personalization important in retail today?
    Personalization is crucial as it helps forge a deeper connection between the customer and the brand. Retailers like Sephora leverage data analytics to provide tailored product recommendations, enhancing customer loyalty.

  • Bank Australia’s Merger with Qudos: A Strategic Move to Enhance Competitive Edge in Retail Banking

    Bank Australia’s Merger with Qudos: A Strategic Move to Enhance Competitive Edge in Retail Banking

    Bank Australia (BAL) has strengthened its foothold in the competitive banking landscape with its recent merger with Qudos Bank. The two entities joined forces on 1 July 2025, with Qudos transferring all its assets and liabilities to BAL, which will now operate under both the Bank Australia and Qudos Bank brands. This merger is seen as a significant step toward enhancing BAL’s capital position, which is projected to remain robust.

    Upcoming Australian Unity Bank Acquisition

    In an additional strategic move, BAL is set to acquire the assets and liabilities of Australian Unity Bank in fiscal 2026. Overall, these ventures are estimated to impact BAL’s risk-adjusted capital (RAC) ratio, which S&P Global Ratings predicts will decline to between 16.2% and 16.7% in fiscal years 2026 and 2027.

    Healthy Growth Amid Challenges

    S&P has expressed confidence in BAL’s stability, indicating the newly merged entity is unlikely to experience disruptions to its core activities. The agency believes that underlying loan growth will remain slightly above the average for the Australian banking sector. The RAC ratio serves as a critical metric for assessing a bank’s resilience against economic volatility.

    Navigating Integration Risks

    Of course, with growth comes challenges, particularly in the form of integration risks associated with the Qudos merger. S&P points out that as BAL works to consolidate systems, it must also contend with the financial strain posed by merger-related costs. The bank is anticipated to act as a price taker in the competitive Australian lending and deposit markets, facing pressure from larger regional and major banks.

    Following the merger, BAL will carve out a modest market presence, holding around 0.4% of Australia’s residential lending market. However, S&P remains optimistic, stating that the merger is unlikely to significantly raise the underlying risk in BAL’s consolidated lending and funding portfolios. The agency forecasts the bank’s credit losses to remain impressively low at approximately 0.05% of customer loans, which is below the systemwide average. This indicates a well-capitalized future for BAL, with expectations that its RAC ratio will stabilize between 16.2% and 16.7% until 2027.

    A Bright Future Ahead

    In a landscape marked by change, Bank Australia is poised to navigate its mergers while maintaining stability, a feat that may surprise even the most seasoned industry watchers.

    Questions & Answers

    What impact will the merger with Qudos Bank have on BAL’s capital position?
    The merger is expected to boost BAL’s competitive standing while maintaining a strong capital position, estimated to remain between 16.2% and 16.7% in the coming fiscal years.

    What challenges does BAL face post-merger?
    BAL must address integration risks associated with consolidating systems and manage costs related to the merger while remaining competitive in the Australian lending market.

    How does BAL’s market share compare after the merger?
    After the merger, BAL will hold about 0.4% of Australia’s residential lending market, a modest share that suggests it remains a small player amidst larger regional banks.

  • Gold Bar Prices Surge as Global Market Rates Rebound – What It Means for Investors

    Gold Bar Prices Surge as Global Market Rates Rebound – What It Means for Investors

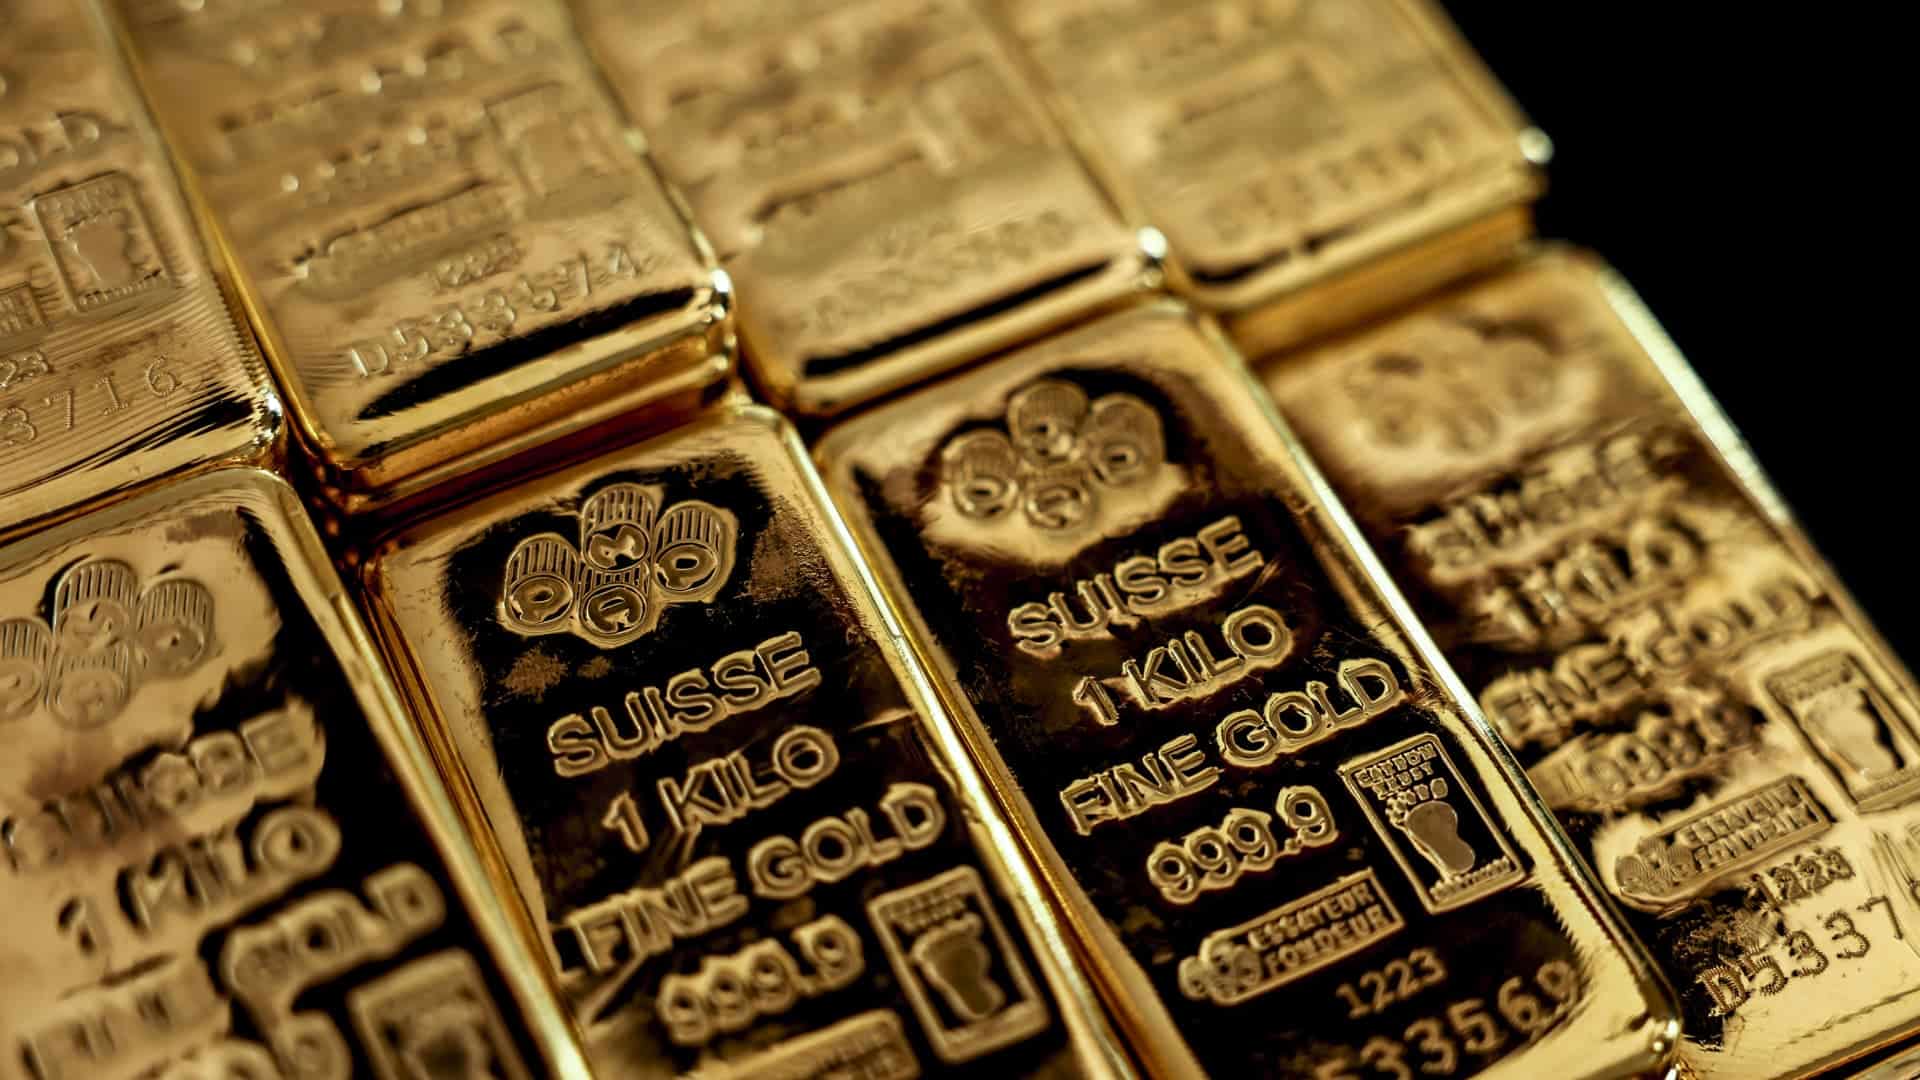
    Vietnam gold bar prices rose on Monday afternoon as global bullion rates recovered from a one-month low. On Monday, the price of gold bars from the Saigon Jewelry Company increased by 0.25%, reaching VND119.5 million (approximately US$4,578.98) per tael, while the gold ring price held steady at VND115.7 million. For reference, a tael weighs about 37.5 grams or 1.2 ounces.

    A Global Recovery in Sight

    Internationally, gold prices made a comeback, buoyed by a weakening dollar. Earlier in the day, gold had dipped to its lowest point since May 29, prompted by easing tensions in U.S.-China trade relations that reduced the demand for safe-haven assets while heightening risk appetites, according to Reuters.

    Market Insights and Investor Sentiment

    Spot gold climbed by 0.5% to reach $3,290 per ounce after its earlier dip, with U.S. gold futures also rising by 0.4% to $3,301. Tim Waterer, Chief Market Analyst at KCM Trade, highlighted that the market sentiment has shifted away from a “doom and gloom” perspective regarding tariff discussions and geopolitical tensions in the Middle East, resulting in a decline in gold’s safe-haven appeal.

    Key Price Levels to Watch

    “The dollar continues to be under pressure, which is preventing a steep decline in gold prices,” Waterer noted. “The $3,250 threshold is pivotal for gold, as a breach of this level could lead to a swift plunge toward $3,200.” It seems the gold market is not ready to don its “doom and gloom” costume just yet, but the balance is precarious.

    Questions & Answers

    What was the price increase for gold bars in Vietnam on Monday?
    The price of gold bars from the Saigon Jewelry Company rose by 0.25% to VND119.5 million (approximately US$4,578.98) per tael.

    What contributed to the rise in global gold prices?
    Global gold prices increased due to a weaker dollar and improved investor sentiment following easing U.S.-China trade tensions, which dampened the demand for safe-haven assets.

    What key price level should investors watch for gold?
    Investors should monitor the $3,250 level, as a breach of this threshold could trigger a more significant decline toward the $3,200 mark.

  • AEON Credit Service Reports Impressive 31.3% Profit Surge to US$13.9 Million in Q1!

    AEON Credit Service Reports Impressive 31.3% Profit Surge to US$13.9 Million in Q1!

    AEON Credit Service (Asia) Company Limited has announced promising financial results for the three-month period ending May 31, 2025, showcasing its resilience and strategic focus in a competitive market. The company recorded a revenue of HK$442.2 million (approximately US$56.33 million), reflecting a 3.7% increase year-on-year. This growth was primarily fueled by enhanced interest income and a steady rise in revolving credit card and personal loan receivables, underscoring the firm’s robust lending framework.

    Moreover, AEON Credit’s after-tax profit reached HK$109.3 million (US$13.92 million), marking a 31.3% surge compared to the same period last year. With earnings per share climbing to 26.11 HK cents, up from 19.88 HK cents, the company is clearly on a bullish trajectory, toasting to a fruitful quarter.

    Operational Profits and Strategic Enhancements

    Operating profit before impairment losses saw an impressive increase of 8.7%, rising to HK$229.7 million. Concurrently, the company’s cost-to-income ratio improved, dropping to 44.6% from 47.3% the previous year, signaling efficient management and cost control.

    To navigate the intricacies of credit exposure, AEON Credit has bolstered its credit assessment model. This strategic move allows the company to better manage higher-risk advances and receivables, ensuring that growth is sustainable and backed by robust risk management.

    Marketing Innovation and Customer Engagement

    The financial institution is also reaping the rewards of its focused marketing efforts. By employing targeted marketing and innovative digital advertising campaigns, AEON Credit has stimulated spending and maintained momentum in its credit card segment, even as personal loan sales faced a decline.

    Looking towards the future, AEON Credit is betting on its “AEON HK” mobile app as a cornerstone for acquiring new customers for both credit card and personal loan services. Moreover, the company is in the process of developing a new rewards platform tailored to its customers in Hong Kong, promising a more convenient way to redeem premium points and e-coupons. It seems the customer experience is set to take flight, with rewards that will surely keep clients engaged and coming back for more — because who doesn’t love a little extra something on their shopping spree?

    Questions & Answers

    How did AEON Credit perform financially in Q1 FY2024/25?
    AEON Credit reported a revenue of HK$442.2 million, a 3.7% YoY increase, while profit after tax surged by 31.3% to HK$109.3 million.

    What factors contributed to AEON Credit’s revenue growth?
    The growth was primarily driven by higher interest income and an increase in revolving credit card and personal loan receivables.

    What future initiatives is AEON Credit undertaking to enhance customer engagement?
    AEON Credit plans to leverage its “AEON HK” mobile app for new customer acquisitions and is developing a rewards platform for easier premium point and e-coupon redemptions.

  • Report: Thailand’s Emerging Virtual Banks Face Steep Challenges Against Established Players

    Report: Thailand’s Emerging Virtual Banks Face Steep Challenges Against Established Players

    Despite the buzz surrounding the rise of virtual banks, Thailand’s existing financial institutions appear to retain a safe buffer against potential disruption, at least in the near term. Moody’s Ratings recently indicated that the new entrants, set to launch in 2026, will navigate a landscape defined by regulatory restrictions that could curtail their growth over the next three to five years.

    Regulatory Framework Shapes Future Operations

    The Bank of Thailand’s (BOT) licensing framework will require these virtual banks to gradually increase their capital from THB5 billion ($153 million) to at least THB10 billion ($306 million) during their formative years. This regulatory structure aims to foster stability in the financial sector as these banks target segments that traditional institutions often overlook.

    Filling the Gaps in Financial Services

    These digital newcomers will primarily focus on lending to underserved populations, including lower-income retail clients, self-employed individuals, and small businesses. By catering to these niche customer groups, they may actually act as a shield for incumbent banks, delaying any immediate threats and allowing these traditional players time to adapt.

    Meet the New Players in Thailand’s Banking Scene

    Thailand’s Ministry of Finance has officially green-lighted three applicants to establish virtual banks, following rigorous evaluations alongside the BOT. The selected players include ACM Holding Company, part of the Charoen Pokphand Group, a consortium of Krung Thai Bank, PTT Oil, and Advanced Info Service, and another consortium including SCB X, KakaoBank, and WeTechnology, backed by WeBank.

    Leveraging Partnerships for Competitive Edge

    What these virtual banks lack in physical branches, they more than make up for in strategic partnerships. As Moody’s points out, the SCBX consortium stands to gain significantly from the operational experiences of KakaoBank and WeBank in South Korea and China, respectively. Simultaneously, the KTB consortium could leverage the market dominance of AIS and PTT Oil, major players in telecommunications and energy.

    A Competitive Arena Awaits

    Competition in this space is expected to be fierce, with incumbent banks not resting on their laurels. Many have stepped up their digital offerings, diversifying into areas like micro-financing and wealth management, though these segments currently contribute modestly to their overall revenue. “It’s not just about getting on the digital bandwagon; it’s about driving the innovation that sets new entrants apart,” Moody’s asserted.

    Challenges on the Horizon

    The launch of PromptPay, Thailand’s real-time retail payment system, has already transformed the speed of fund transfers and payments, adding further pressure on these new virtual banks to innovate. Compounding the challenge is Thailand’s high household debt and stagnant economic growth, a tougher landscape compared to the more favorable conditions faced by virtual banks in other Southeast Asian markets.

    As Thailand readies for an evolution in its banking system, both incumbents and new players will need to navigate a rapidly shifting terrain filled with opportunities and obstacles alike. One thing is certain: the quest for customer loyalty is about to get more exciting.

    Questions & Answers

    What regulatory hurdles will virtual banks face in Thailand?
    Virtual banks in Thailand will be required to increase their capital from THB5 billion to at least THB10 billion and will operate under certain restrictions for 3-5 years.

    Who are the major players in the new virtual banking landscape?
    The three approved virtual banks are ACM Holding Company (part of CP Group), a consortium including Krung Thai Bank and PTT Oil, and another consortium featuring SCB X, KakaoBank, and WeTechnology.

    How will existing banks respond to the rise of virtual banks?
    Incumbent banks are enhancing their digital offerings and expanding into micro-financing and wealth management to maintain their competitive edge against new entrants.

  • Krungsri and Schneider Electric Unite to Boost Energy Efficiency for Small and Medium Enterprises

    Krungsri and Schneider Electric Unite to Boost Energy Efficiency for Small and Medium Enterprises

    Driving Sustainable Energy Solutions in Thailand

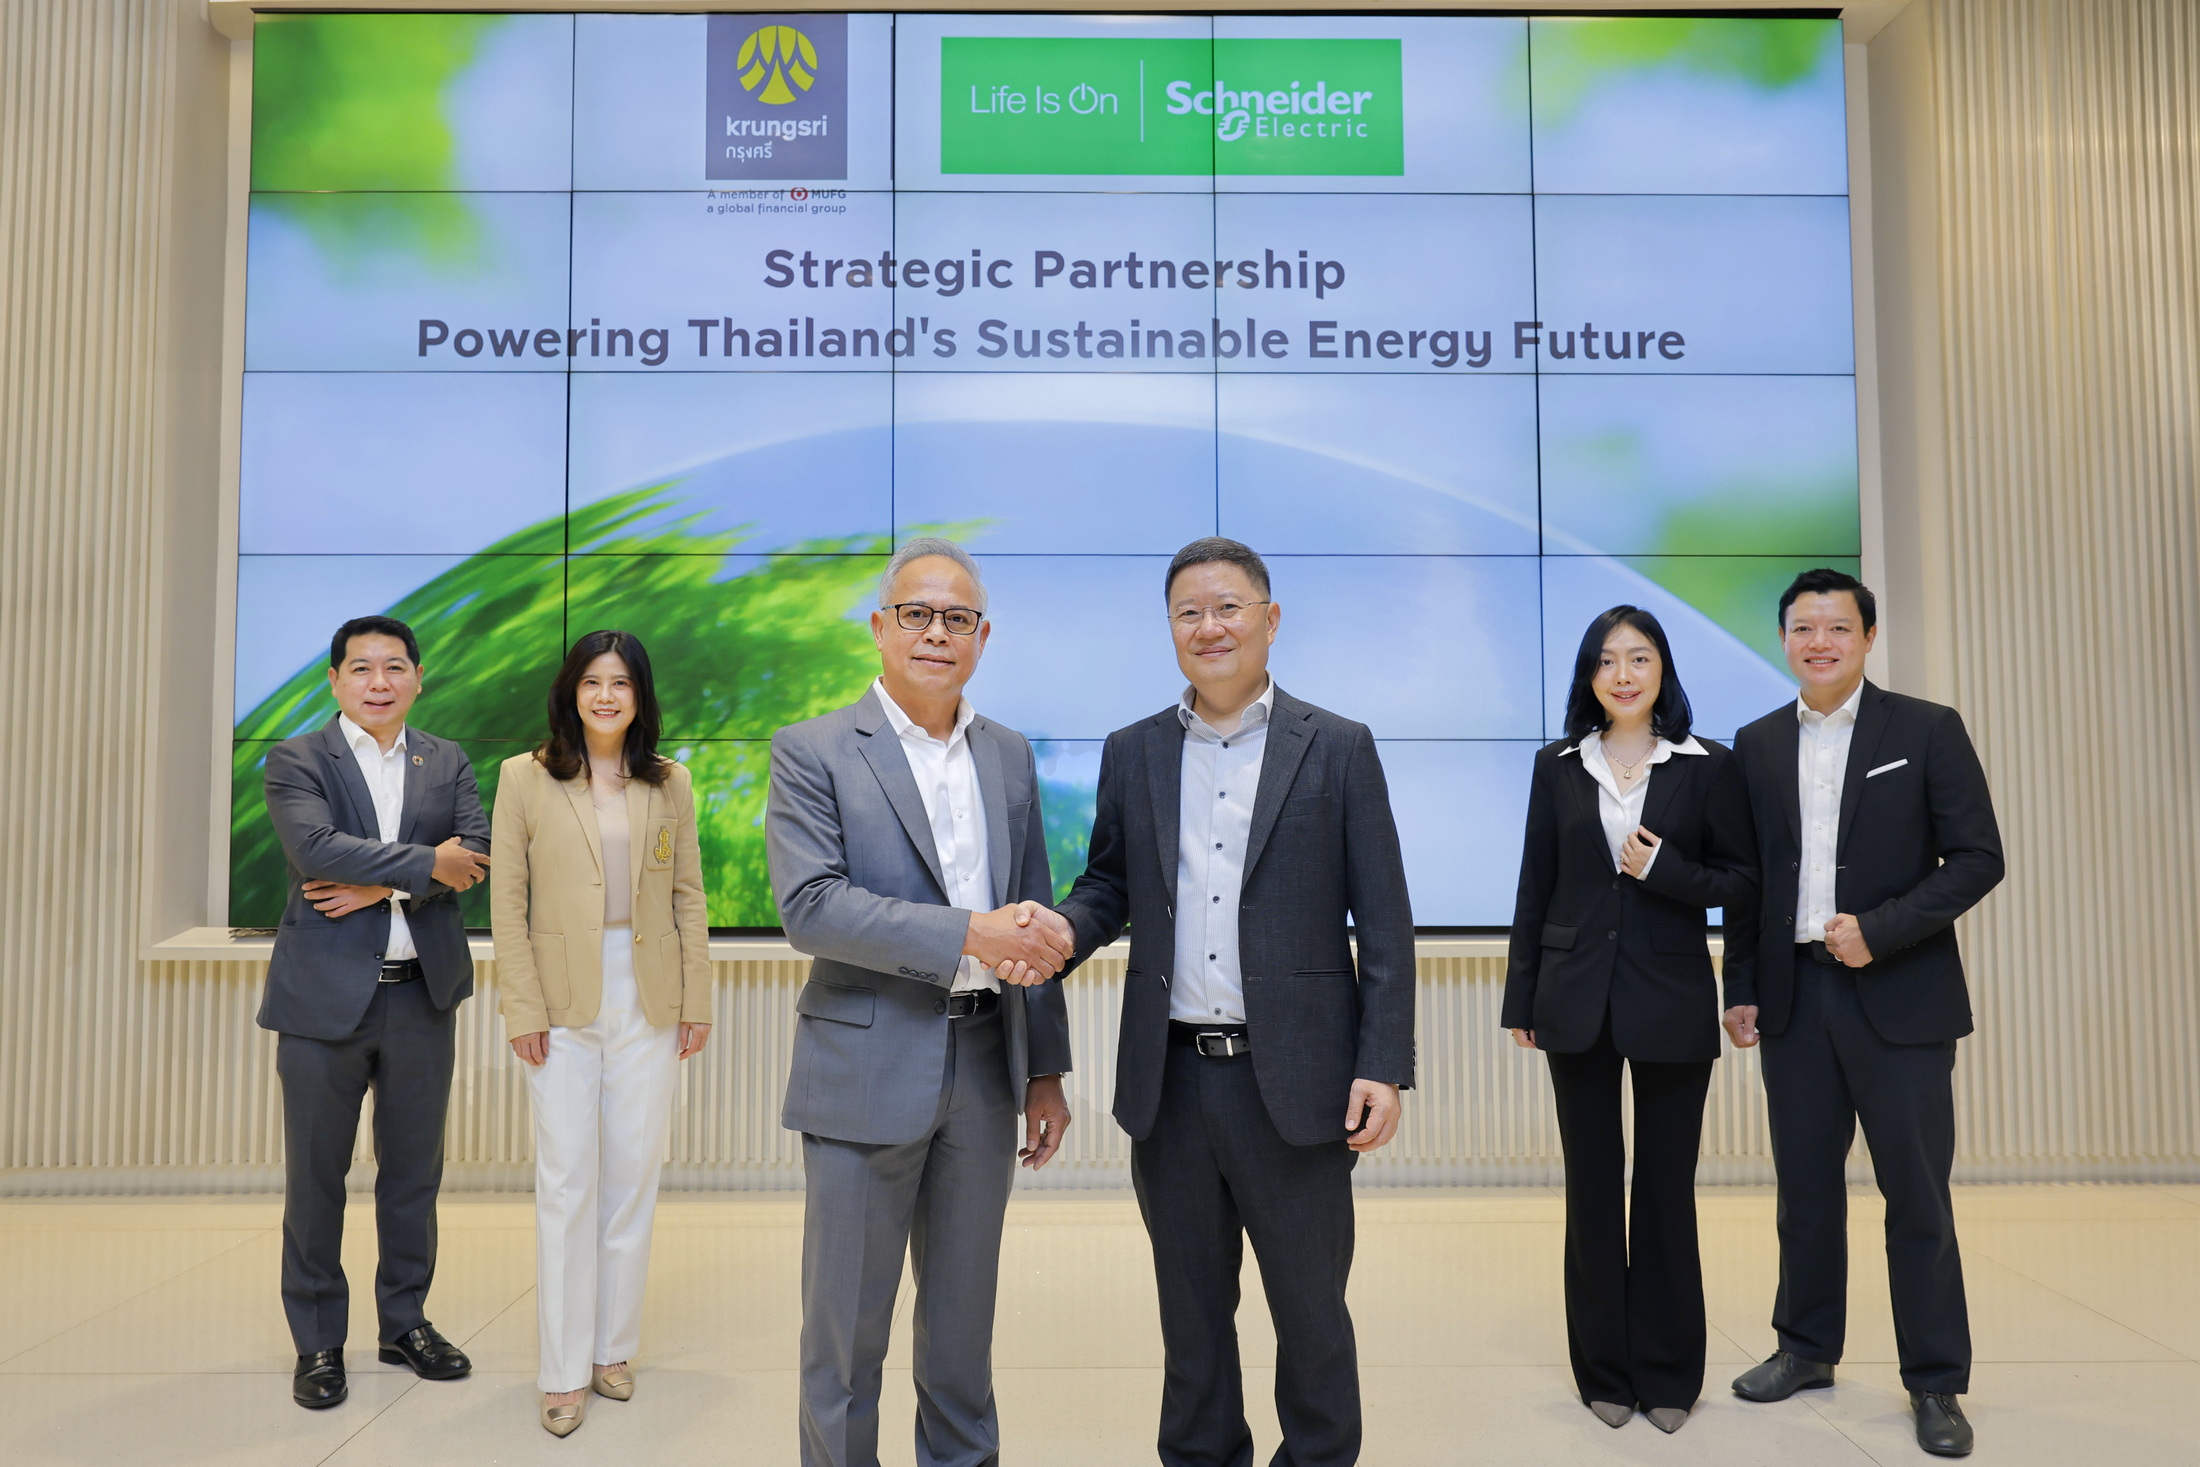
    In a progressive move to enhance energy efficiency in Thailand, Krungsri (Bank of Ayudhya) has joined forces with Schneider Electric. This partnership aims to empower the nation’s entrepreneurs, particularly small and medium enterprises (SMEs), to embrace cutting-edge energy technologies.

    By blending Schneider Electric’s renowned expertise in energy management and automation with Krungsri’s prowess in sustainable finance, the two organizations are set to tackle pressing energy and environmental challenges facing Thailand. “In our pursuit of becoming The Leading Sustainable and Regional Bank, we are committed to promoting ESG practices among Thai businesses,” stated Pairote Cheunkrut, Krungsri’s Chief Strategy Officer, in a press release.

    Focusing on the unique needs of SMEs, which can face electricity costs ranging from 10% to 30% based on their industry, Krungsri is determined to facilitate their transition to more sustainable operations. “We understand how crucial these shifts are for SMEs struggling with high energy expenses, and our initiative is designed to support them through these evolving energy landscapes,” added Cheunkrut.

    Collaboration will center around two vital areas: decarbonization and ecosystem development, as well as sustainable finance solutions. Notably, Krungsri plans to provide financial assistance that enables SMEs to invest in energy-efficient technologies. As a result, businesses can expect not only a reduction in carbon emissions but also improved long-term sustainability. After all, who wouldn’t want to turn their energy bills into a business opportunity?

    Questions & Answers

    How will Krungsri and Schneider Electric support SMEs in Thailand?
    They will combine their strengths to provide access to advanced energy technologies and financial solutions, helping SMEs transition to energy-efficient operations.

    What is the significance of decarbonization in this partnership?
    Decarbonization is a central focus as it addresses the urgent need to reduce carbon emissions, offering a pathway for businesses to operate more sustainably.

    What are the expected benefits for SMEs adapting to these energy solutions?
    SMEs can expect to reduce their electricity costs significantly, enhance their sustainability, and improve their business resilience through the adoption of energy-efficient technologies.

  • ANZ’s Technology and Group Services Executive Announces Retirement, Marking a New Era for the Bank

    ANZ’s Technology and Group Services Executive Announces Retirement, Marking a New Era for the Bank

    In a rapidly evolving retail landscape, Asia continues to be a hotspot for innovation and consumer engagement. With burgeoning economies and a tech-savvy population, retailers are increasingly focused on strategies that captivate the modern shopper. Amidst this backdrop, a fresh wave of creativity is emerging, allowing brands to connect with consumers in unexpected ways that resonate deeply with their lifestyles.

    Changing Consumer Behavior and Retail Adaptation

    As shopping habits shift due to factors like digital transformation and changing demographics, retailers are adapting their approaches to meet evolving consumer needs. The rise of e-commerce has not only revolutionized how products are sold but has also challenged traditional brick-and-mortar strategies. Here, the importance of integrating technology into the shopping experience cannot be overstated. Retailers are leveraging data and analytics to personalize experiences, creating a seamless transition between online and offline worlds.

    The Power of Localized Strategies

    Asia’s diverse markets require retailers to adopt localized strategies to truly resonate with consumers. Companies are honing in on cultural nuances and preferences, whether it’s a brand that launches a limited-edition product reflecting local festivals or one that embraces regional tastes and traditions in its offerings. Such strategies not only enhance brand loyalty but also foster a sense of community, proving that sometimes thinking small is the key to large-scale success.

    Experiential Retail: The Leap Beyond Transactions

    As the retail experience evolves, many brands are realizing that it’s not just about the sale anymore—it’s about the experience. Retailers are crafting environments that go beyond transactions, turning stores into lifestyle hubs that encourage customer engagement and interaction. Imagine shopping in a space that feels more like a trendy cafe than a conventional store, where events and social gatherings thrive. This movement toward experiential retail is drawing in consumers, turning casual visitors into dedicated brand enthusiasts.

    Sustainability Takes Center Stage

    Environmental consciousness is no longer a mere add-on; it is now pivotal in shaping retail strategies across Asia. From sustainable sourcing to eco-friendly packaging, consumers increasingly seek brands that align with their values. Retailers are embracing sustainability not just as a responsibility but as a unique selling proposition, showcasing their commitment to the planet. It’s a refreshing shift in the industry, proving that being good to the Earth can also be good for business.

    Looking Ahead: The Future of Retail in Asia

    As we look towards the future, the Asian retail sector stands at a crossroads of tradition and innovation. With challenges come opportunities, and the ability to pivot and adapt will determine success in this dynamic market. Retailers who navigate these waters with agility and creativity are poised to thrive, continually engaging consumers in ways that surprise and delight. It’s a thrilling time to be part of the retail scene—after all, you never know when a shopping spree might turn into an unforgettable experience!

    Questions & Answers

    What strategies are retailers in Asia adopting to adapt to changing consumer behaviors?
    Retailers are increasingly utilizing data and analytics to personalize experiences and create seamless integration between online and offline shopping.

    How important is localization for brands operating in diverse Asian markets?
    Localization is critical, as brands that tailor their strategies to fit cultural nuances and preferences are more likely to foster brand loyalty and community engagement.

    What role does sustainability play in the future of retail in Asia?
    Sustainability has become a central focus for many brands as consumers actively seek out products and practices that align with their environmental values, making it a key competitive advantage.

  • Gold Hits Two-Week Low: What This Means for Investors and Retail Buyers

    Gold Hits Two-Week Low: What This Means for Investors and Retail Buyers

    A person holds gold bars in a jewelry shop in Hanoi. Photo by VnExpress/Ngoc Thanh

    In a noteworthy turn of events, Vietnam’s gold prices dropped sharply on Saturday, marking their lowest point since June 12 as the global gold market experienced a significant pullback.Saigon Jewelry Company reported a 0.42% decline in the price of gold bars, now valued at VND119.2 million (approximately US$4,567.92) per tael. Likewise, gold rings saw a 0.43% reduction, now priced at VND116 million per tael.

    Despite this recent dip, gold prices have soared by 42% since the start of the year. However, last Friday marked a crucial shift as gold fell by 2% globally, reaching a near one-month low. The decline followed a U.S.-China trade agreement that renewed risk appetite among investors, thus diminishing gold’s status as a safe haven.

    Spot gold prices eased by 1.5% to $3,277.17 per ounce, after an earlier drop of 2% that marked its lowest level since May 29. This decline represents a continued downturn for bullion, which has experienced a 2.8% drop over the past two weeks.

    “The waning geopolitical tensions have encouraged investors to take profits, driven by the increasingly optimistic outlook regarding relations with China and the evolving situation in the Middle East,” said Daniel Pavilonis, a senior market strategist at RJO Futures.

    The recent U.S.-China trade agreement, aimed at speeding up the shipment of rare earth metals to the United States, has been positively received by markets, leading to a rally in global shares.

    In the Middle East, the ceasefire agreement between Iran and Israel appears to be holding steady, despite a few minor incidents earlier on.

    Questions & Answers

    How much have gold prices fallen in Vietnam recently?
    Vietnam’s gold prices dropped to their lowest level since June 12, with gold bars declining by 0.42% to VND119.2 million per tael.

    What factors contributed to the global decline in gold prices?
    A new trade agreement between the U.S. and China, which has increased investor risk appetite, along with easing geopolitical tensions, has decreased gold’s appeal as a safe-haven asset.

    What is the overall trend for gold prices this year?
    Despite the recent drop, gold prices have surged by 42% since the beginning of the year, reflecting a strong performance before recent market shifts.

  • Krungsri Launches Exciting Corporate Banking Initiatives Across ASEAN Markets

    Krungsri Launches Exciting Corporate Banking Initiatives Across ASEAN Markets

    Bank of Ayudhya, known as Krungsri, is set to enhance its partnerships and consulting services geared towards high-potential industries, as it seeks to expand its corporate banking operations throughout ASEAN. With its eyes firmly on the future, the Thailand-based institution is prioritizing engagement with sectors that promise significant growth, including bio green technology, semiconductors, food innovation, and smart agriculture — all of which are pivotal for Thailand’s economic landscape in 2025.

    A Spotlight on Innovation and Collaboration

    The recent Japan-ASEAN Startup Business Matching Fair stands out as a key initiative underlining Krungsri’s strategic roadmap. This event saw participation from over 54 startups and showcased cutting-edge Japanese technologies focused on disaster prevention, culminating in an impressive 400 business connections made in just one day. Such endeavors reflect the bank’s commitment to bridging gaps and fostering collaboration within the region.

    Paving the Way for Tailored Financial Solutions

    As part of its ambition to deepen ties across ASEAN, Krungsri intends to roll out customized financial solutions for businesses, positioning itself as a valuable partner in their growth journeys. Moreover, the bank is unwavering in its dedication to achieving net-zero greenhouse gas emissions, emphasizing the importance of collaboration with public entities to facilitate knowledge sharing and elevate awareness around sustainable practices.

    Empowering Japanese Corporations

    Krusgri is particularly focused on supporting Japanese firms operating in Thailand, a community it serves robustly, covering over 70% of these businesses. The bank’s commitment is evident in its mission to empower these companies and help them realize sustainable growth metrics.

    Bunsei Okubo, head of Japanese corporate banking at Krungsri, echoed this ambition, stating, “Krungsri will remain a key driving force for Japanese corporations and support for the growth of the Thai economy, advancing innovation, nurturing growth, and fostering regional partnerships to support customer success. We are committed to being the first call business partner and Platformer for Society and Environment.”

    With plans for continuous development and collaboration, Krungsri stands ready to build the retail landscape of tomorrow, one innovative solution at a time. After all, in the fast-paced world of banking and retail, adaptability is as essential as a strong foundation.

    Questions & Answers

    What sectors is Krungsri focusing on for its expansion in ASEAN?
    Krungsri is concentrating on emerging sectors like bio green technology, semiconductors, food innovation, and smart agriculture as part of its strategy for growth in ASEAN by 2025.

    How does Krungsri plan to support Japanese companies in Thailand?
    The bank aims to empower Japanese firms by providing tailored financial solutions and helping them achieve sustainable growth, covering over 70% of Japanese businesses operating in Thailand.

    What commitment has Krungsri made regarding environmental sustainability?
    Krungsri is dedicated to achieving net-zero greenhouse gas emissions, focusing on collaboration with public sectors to enhance knowledge exchange and promote sustainable operational practices.

  • J.P. Morgan Expands Its Footprint in Switzerland, Enhancing Global Retail Opportunities

    J.P. Morgan Expands Its Footprint in Switzerland, Enhancing Global Retail Opportunities

    J.P. Morgan Reshapes Corporate Banking Landscape in Switzerland

    In a bold move that underscores its ambitions in Europe, J.P. Morgan is repositioning its Corporate Banking operations within the DACH region. Effective July 1, Lutz Karl, who has been at the helm of serving large corporate clients across the region, will make his way to Zurich. There, he will spearhead coverage for both Large and Mid Caps in Switzerland.

    This strategic shift was disclosed in an internal memo co-signed by Marcus Hiseman and Stefan Povaly, Co-Heads of Global Corporate Banking (GCB) for Europe, the Middle East, and Africa (EMEA). The details were later confirmed by J.P. Morgan, signaling a clear intent to strengthen its foothold in the Swiss financial landscape.

    Ambitious Growth Endeavors in Investment Banking

    The creation of this new leadership role in Switzerland emphasizes J.P. Morgan’s determination to bolster its corporate and investment banking capabilities—a narrative that has been echoed in previous reports by finews.com. With the goal of attracting an array of clients, from multinational giants to burgeoning mid-tier firms, the bank is clearly casting a wider net.

    Meanwhile, Bernhard Brinker, who has successfully navigated the Mid Cap segment in Germany and Austria, will expand his purview to also include oversight of the Large Cap segment along with other GCB functions. It seems that J.P. Morgan is ready to shake things up in a market ripe for competition.

    As the financial landscape evolves, echoes of opportunity ripple through banks such as J.P. Morgan, reminding industry players that change is often just the first step in a game that blends strategy with good fortune.

    Questions & Answers

    What is the significance of Lutz Karl’s relocation to Zurich?
    Lutz Karl’s move to Zurich reflects J.P. Morgan’s strategic shift to reinforce its Corporate Banking operations in Switzerland, aiming to enhance its presence in the region’s financial landscape.

    How does this repositioning align with J.P. Morgan’s broader goals?
    This reorganization aligns with J.P. Morgan’s aspirations to grow its corporate and investment banking sectors, allowing it to cater to a wider range of clients, from large corporations to mid-sized firms.

    Who will oversee the Large Cap segment in Germany and Austria?
    Bernhard Brinker, who has been leading the Mid Cap segment, will now expand his responsibilities to include the Large Cap segment and additional GCB business areas, further solidifying the bank’s leadership in the region.

  • Gold Prices Experience Slight Uptick, Signaling Market Resilience

    Gold Prices Experience Slight Uptick, Signaling Market Resilience

    Gold prices in Vietnam experienced a modest uptick Thursday morning, influenced by a slight rise in global gold rates amidst a weakening dollar. The Saigon Jewelry Company reported a 0.25% increase in gold bar prices, bringing them to VND119.8 million (approximately US$4,584.94) per tael. Meanwhile, gold rings climbed 0.34% to reach VND116.7 million per tael, contributing to a remarkable 42.3% surge in gold values since the year’s onset.

    Globally, gold prices edged upward on Thursday, buoyed by the declining dollar and increasing uncertainty following reports that U.S. President Donald Trump may have mulled replacing Federal Reserve Chair Jerome Powell as soon as September or October, according to Reuters.

    Spot gold rose by 0.2% to $3,339.20 per ounce, while U.S. gold futures increased 0.3% to $3,353.10. With the dollar slipping to its lowest level since March 2022, gold priced in dollars became more affordable for international investors, adding to its appeal.

    Typically, gold thrives during uncertain times and low-interest-rate conditions. Market analysts suggest that the prospect of a dovish Fed Chairman under Trump’s potential influence may further suppress the dollar’s strength. Tim Waterer, Chief Market Analyst at KCM Trade, noted, “Trump clearly wants a dovish Fed Chairman next time around, so the increased likelihood of an aggressive rate-cutting cycle is pinning down the USD.”

    For now, gold markets are in a holding pattern, awaiting fresh insights from upcoming U.S. macroeconomic data, including GDP and core PCE figures. Gold seems to be taking a breather, but that doesn’t mean investors are taking a nap — they are wide awake, scanning for the next clue!

    Questions & Answers

    What drove the recent increase in gold prices in Vietnam?
    The rise in gold prices in Vietnam can be attributed to a modest increase in global gold rates and a weakening dollar, which made gold more affordable for international buyers.

    How much have gold prices increased since the beginning of the year?
    Gold prices in Vietnam have surged by an impressive 42.3% since the start of the year, reflecting strong market demand and global economic conditions.

    What factors are influencing the current gold market trends?
    The gold market is currently influenced by uncertainties surrounding U.S. economic policies and potential changes within the Federal Reserve, alongside the typical behavior of bullion during low-interest-rate environments.

  • Bank Negara Indonesia Faces Ongoing NIM Challenges in Second Quarter: What Lies Ahead?

    Bank Negara Indonesia Faces Ongoing NIM Challenges in Second Quarter: What Lies Ahead?

    Over the past few years, the retail industry has endured a whirlwind of transformation, especially in Asia, where adaptation and resilience have been put to the test. Amid the ongoing evolution shaped by technological advancements and shifting consumer behaviors, companies are redefining their strategies to stay ahead in this dynamic sector.

    Embracing Technology: The Retail Revolution

    From mobile payments to virtual fitting rooms, technology is not just an addition to retail; it’s reshaping its very foundation. Asian consumers, known for their swift adoption of new digital tools, are now more empowered than ever. Retailers are responding with innovative solutions that enhance in-store and online experiences, appealing to an increasingly tech-savvy audience. Even traditional markets have found ways to digitize their operations, proving that innovation knows no bounds.

    Interestingly, amidst all this digital transformation, a few retailers are choosing to go old school—think cash transactions and handwritten receipts. It’s a reminder that sometimes, simplicity holds its own charm.

    The Luxury Segment’s New Frontier

    The luxury retail sector is experiencing rejuvenation as well, particularly in markets like China and Japan. High-end brands are tapping into the growing affluent middle class, curating exclusive experiences that blend both tradition and modernity. Events are no longer just about showcasing products; they’re immersive experiences that engage customers on an emotional level. Whether it’s a pop-up shop in a trendy Shanghai district or an exclusive virtual tasting in Tokyo, luxury retail is all about creating memorable moments.

    Sustainability Takes the Spotlight

    As environmentally conscious consumers on the rise, retailers are scrambling to adopt sustainable practices. Many are integrating eco-friendly materials into their products and adopting more transparent supply chains. In a climate where shoppers want to know the story behind their purchases, brands that prioritize sustainability aren’t just making a “greener” choice—they’re also amplifying their appeal. Embracing sustainability could spell the difference between staying relevant or fading into oblivion.

    The Future of Shopping: Omnichannel Strategies

    As the lines blur between online and offline shopping, retailers are leaning into omnichannel strategies more than ever. The seamless integration of physical and digital platforms is no longer a luxury but a necessity. Consumers expect a consistent experience whether they shop via mobile apps, websites, or brick-and-mortar stores. Retailers that fail to meet these expectations face the risk of losing their customer base to more agile competitors.

    While it’s easy to get caught up in forecasts and projections, the heart of retail is still about fostering connections. Whether it’s a brief chat with a store associate or classic customer service, businesses that understand this human element will stand the test of time.

    Questions & Answers

    What role does technology play in the transformation of retail in Asia?
    Technology is fundamentally reshaping retail by enhancing customer experiences through innovations such as mobile payments and virtual fitting rooms, reflecting the swift digital adoption among Asian consumers.

    How is the luxury retail sector adapting to modern consumer demands?
    Luxury retail is focusing on creating exclusive and immersive experiences that engage customers emotionally, appealing to a growing affluent middle class in markets like China and Japan.

    Why is sustainability becoming increasingly important for retailers?
    With the rise of environmentally conscious consumers, retailers are prioritizing sustainable practices and transparent supply chains, as these factors significantly enhance brand appeal and relevance in today’s market.

  • Metrobank Appoints Renato De Borja, Jr. as New Leader of Financial and Control Sector

    Metrobank Appoints Renato De Borja, Jr. as New Leader of Financial and Control Sector

    Riding the wave of digital transformation, retailers across Asia are navigating a sea of change as they adapt to evolving consumer behaviors and market dynamics. The rise of e-commerce continues to reshape the retail landscape, compelling businesses to rethink their strategies and embrace innovative technologies.

    Asian Retailers Embrace E-commerce Evolution

    In recent years, e-commerce has surged in popularity, driven largely by the pandemic, which forced consumers to rely on online shopping for their everyday needs. According to a report from eMarketer, Asia-Pacific is expected to account for over 60% of global e-commerce sales by 2023, with giants like China leading the charge. This unparalleled growth has prompted traditional retailers to pivot and enhance their digital offerings or risk being swept away by agile competitors.

    Omni-channel Strategies Take Center Stage

    Retailers are increasingly adopting omni-channel retailing, integrating online and offline channels to create seamless shopping experiences. This shift not only caters to consumers’ preferences for convenience but also allows retailers to gather valuable data about customer behavior. Brands like Alibaba and Shopee are setting benchmarks for personalization, employing advanced algorithms to tailor recommendations, making shoppers feel as if they’ve struck gold with every purchase.

    Technological Adoption Fuels Retail Innovation

    Emerging technologies are at the heart of the retail revolution, with artificial intelligence, augmented reality, and blockchain becoming critical tools for growth. AI chatbots are now commonplace, providing 24/7 customer service that rivals even the most attentive sales associates. Meanwhile, augmented reality is enhancing the online shopping experience, allowing consumers to virtually try on clothes and accessories from the comfort of their own homes—a fitting measure of convenience in a fast-paced world.

    Local Heroes Emerge Amid Global Giants

    As much as multinational corporations like Amazon and Walmart dominate headlines, local players are carving out niches by catering to regional tastes and preferences. For instance, South Korea’s Coupang has gained immense popularity through its lightning-fast delivery service, while India’s Flipkart continues to adapt its offerings to resonate with the local populace. This nimbleness not only fosters loyalty but also emphasizes the importance of understanding local markets in a globalized economy.

    Environmental Concerns Reshape Consumer Choices

    Today’s consumers are not just focused on convenience; sustainability has emerged as a significant driving force behind purchasing decisions. Retailers in Asia are increasingly conscious of their environmental footprint and are responding with eco-friendly practices, from sustainable sourcing to reduced packaging. Companies that embrace green initiatives are not only attracting eco-conscious shoppers but also setting trends that challenge the traditional notions of retail.

    The Future is Bright, Yet Challenging

    As Asia’s retail arena evolves at breakneck speed, the future holds both promise and challenges. Companies must navigate the complexities of supply chain disruptions and the rapidly changing regulatory landscape. However, the potential to connect with consumers in innovative and meaningful ways has never been greater. For retailers, the key lies in being adaptable, understanding their audience, and not being afraid to pivot in a landscape where change is the only constant. And as the old saying goes, “If you can’t beat them, join them”—though in this case, one might add, “and then outsmart them.”

    Questions & Answers

    How is e-commerce expected to shape the future of retail in Asia?
    E-commerce is projected to dominate retail sales in Asia, accounting for over 60% of global online transactions by 2023, pushing traditional retailers to innovate or risk obsolescence.

    What role do local retailers play in the competitive landscape?
    Local retailers are uniquely positioned to cater to regional preferences, often outshining global giants by offering tailored experiences and understanding customer needs better.

    How are sustainability practices changing consumer behavior?
    Today’s consumers are increasingly prioritizing sustainability, driving retailers to adopt eco-friendly practices that not only appeal to this demographic but also set new standards in the market.