Category: Research

Retail News Asia is committed to providing both local and global retailers with the latest Research throughout the Asian market. This on a daily base.

  • How To Prevent Shoplifting

    How To Prevent Shoplifting

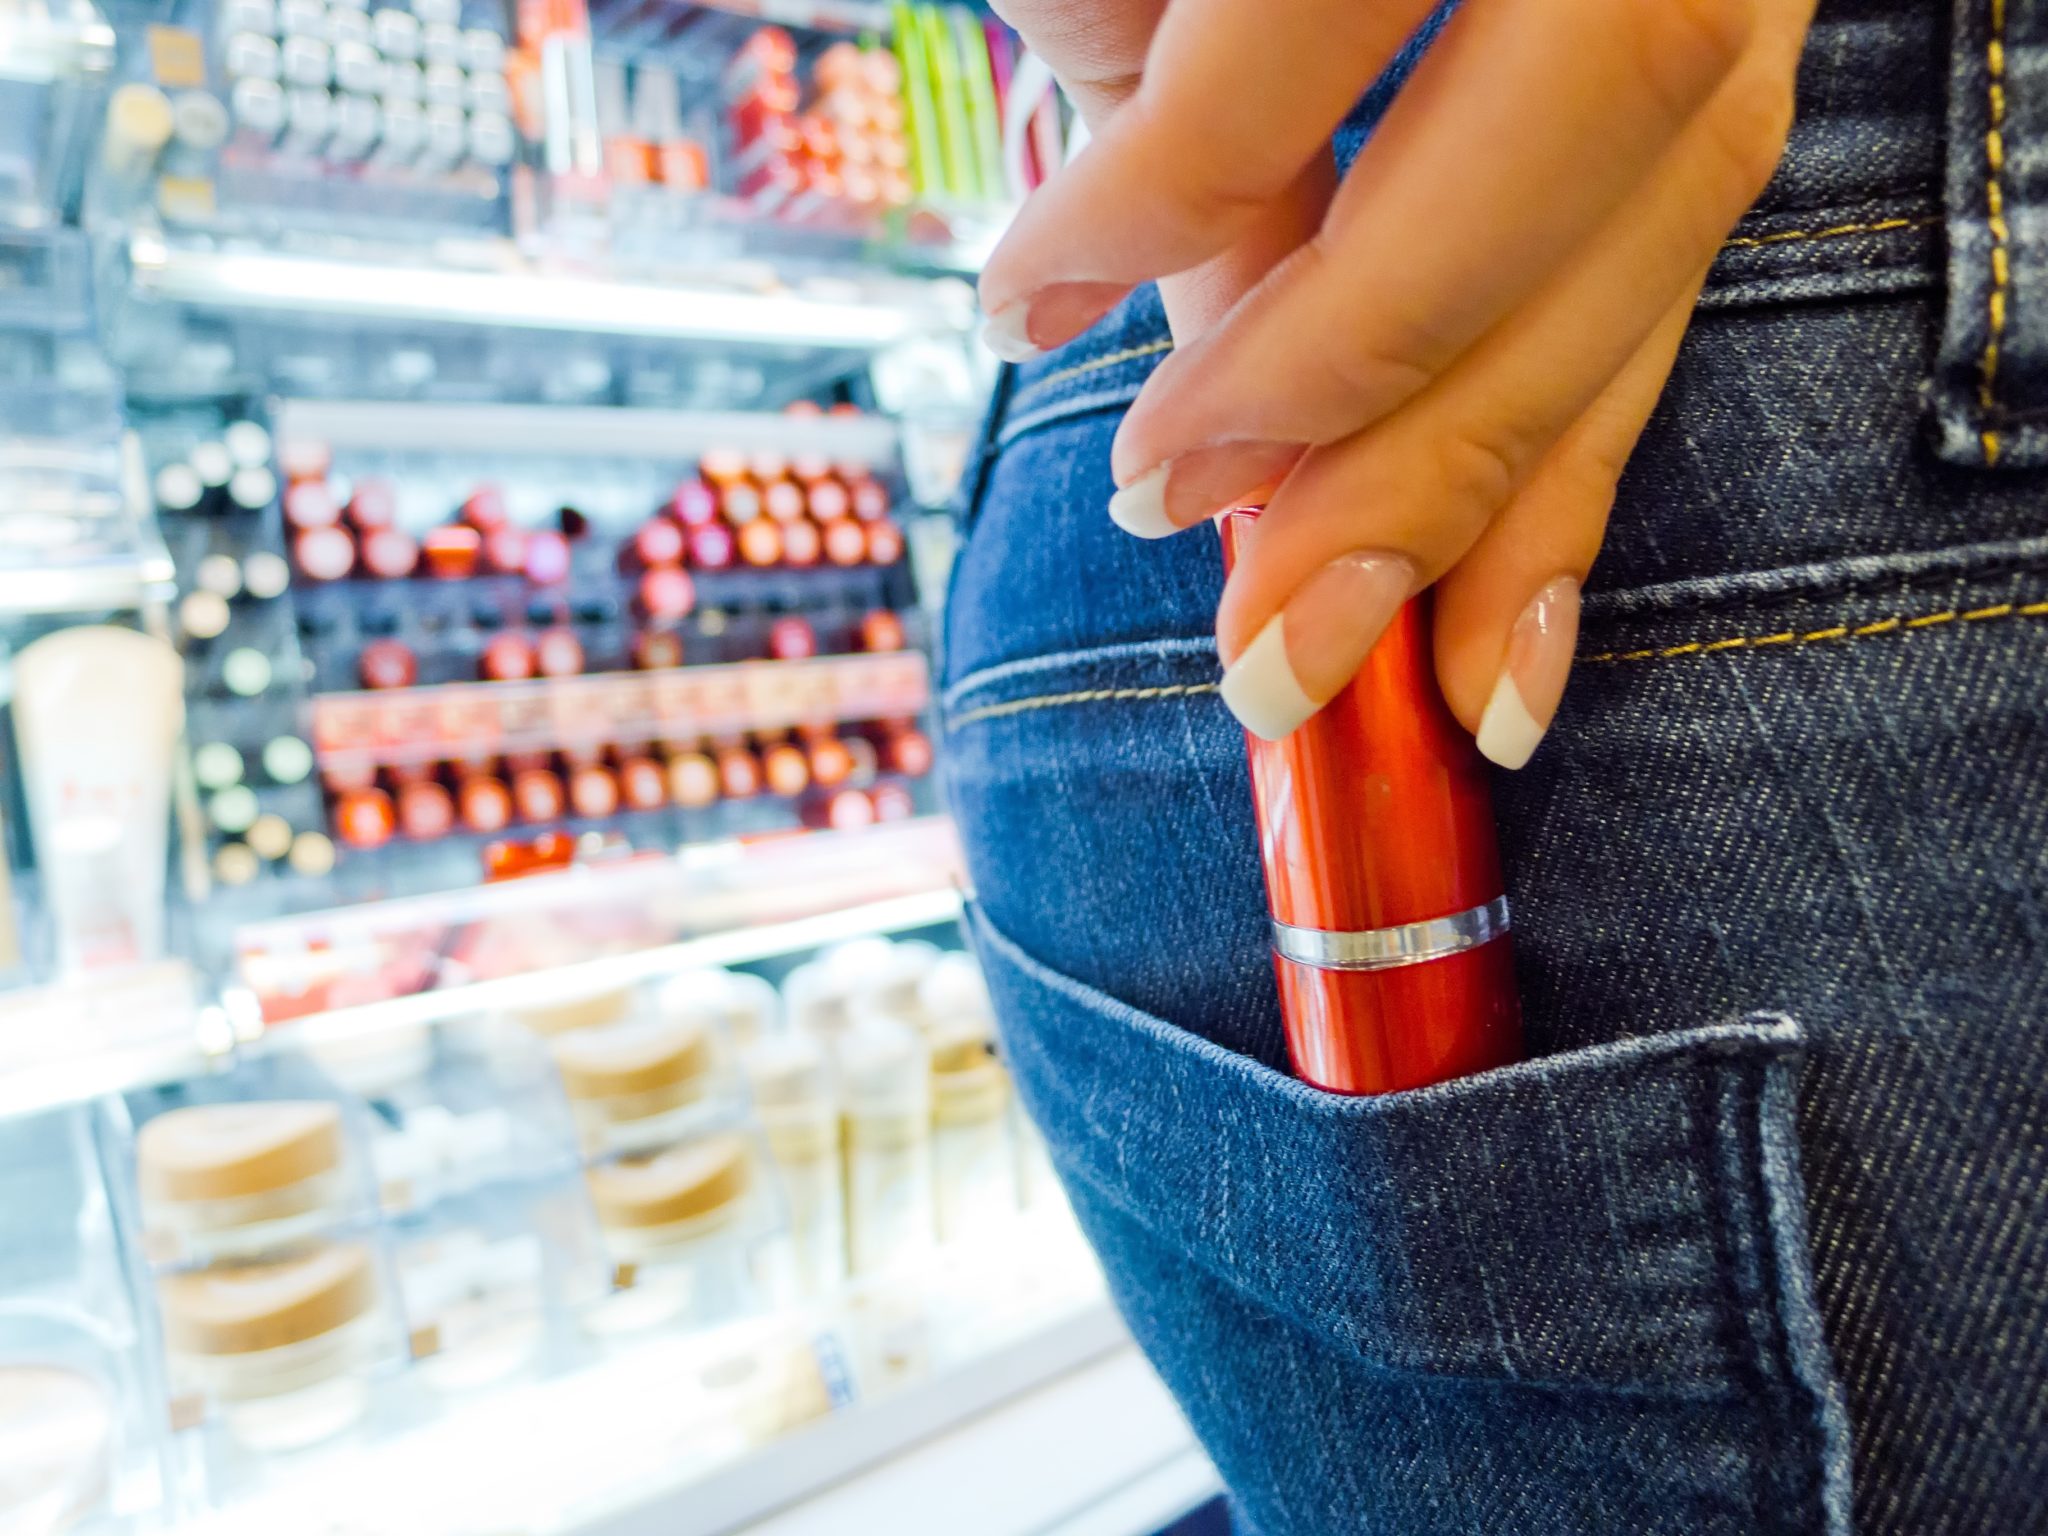
    The definition of shoplifting is the taking of merchandise offered for sale without paying for it.  Shoplifting, according to the National Association for Shoplifting Prevention, has resulted in more than $25 million worth of merchandise being stolen from retailers every day.  This is one of the big causes of retail shrinkage.

    Regardless of the size of the retail store, all types of retailers will be susceptible to the growing issue of shoplifting.  This is why retailers need to determine how to identify shoplifters and common shoplifting methods.  They will also need to create an environment that is less attractive to shoplifters through implementing policies and procedures which protect their stores.

    Knowing What To Look For

    If you want to stop a shoplifter, you first need to be familiar with the different types of shoplifters, the commonly used methods and what you should be looking for when customers exhibit strange behavior.  The main thing that you will need to consider is the visual cues that you get.

    According to this NYC shoplifting lawyer, most shoplifters use other items to conceal their theft.  Grab and run shoplifting is actually rare and will generally not be what you have to worry about.  Most shoplifters will have a plan for how they are going to remove the merchandise from the store.  An example of this will be a long coat which provides a great place to conceal merchandise or a female shoplifter who carries more than one purse or handbag.

    The use of a handbag or purse is common because it is an item that will generally not cause additional attention.  However, the presence of more than one should be noted.  Other places that are commonly used by thieves will be strollers, umbrellas and inside bags with items that they have paid for.  An example of this will be a shoplifter who buys a pair of shoes and then returns to stuff the bag full of socks and belts.

    There are other sides of a shoplifter that you need to be aware of.  Shoplifters will often pay more attention to the employees in the store than the merchandise.  They will also pick up random items and pretend to be looking at them.  Walking in the opposite direction of employees is another sign particularly when they move when the employee moves.

    If you run a clothing store, you need to take note of the number of items they take into the dressing room.  You should then do a quick count when they exit to ensure the number is the same.

    Use Preventative Measures

    Good store management is one of the most effective tools when you want to prevent shoplifting.  You should look at using the store layout, common security practices, and inventory controls to fight shoplifting.  You should look around your store and try to find some of the hidden places that shoplifters will use.  These locations will generally be where an employee will not see what the customer is doing.  This will not only make it easier for shoplifters, you will also impact your ability to provide a service.

    Thinking about service, another way to prevent theft will be to offer a proactive service.  If there is an employee actively engaging the customer, they will have a hard time stealing something.  They will know that they are being watched and this type of customer service will be the best weapon you have.

    Keeping your store shelves organized is also important. Disorganized shelves will make it harder for you to determine if something has been stolen.  However, an empty space on the shelf or display table will be a sign that something is wrong.  However, this will only help when you are focused on your merchandise.

    Stopping Shoplifters

    It is important that you have policies and procedures for shoplifting set up early in the business planning process.  While you hope this will never happen in your store, the truth is that it is going to happen.  When it does, you and your staff will need to be prepared to handle the situation.  When you create your shoplifting procedures, you should take some of these points into consideration.

    How are you going to approach a customer you suspect of shoplifting?

    Will you confront the suspect or will your policy be to not confront them?

    Who will you be calling or contacting?

    What documentation are you going to need?

    You should take some time to role-play the proper procedure with your employees.  This is not something that they should try to complete at the time.  Train them correctly and everything will go smoothly.

    Retailers are being struck by outside influences every day.  The truth is that most shoplifters are not professionals and only 3% are estimated to be professional thieves.  However, it is possible to control your losses through shoplifting prevention.
     

  • The AI moment: preparing for the revolution

    The AI moment: preparing for the revolution

    Artificial intelligence, AI, is the next big technology to have entered mainstream consciousness. From eerie androids such as Sophia to the silent efficiency of automated delivery systems in modern Amazon warehouses, the growth of autonomous driving and the popularity of smart speaker systems such as Alexa or Google Home – AI is everywhere. And it’s coming for our jobs, white collar and blue, threatening massive social and economic upheaval.

    But what is AI really? Why has it suddenly become so popular? Why is everyone so excited about its tremendous potential? Will it really replace humans – and should we welcome it with open arms, or fear for its impact?

    Far from being an omnipotent, autonomous robot, AI is at heart simply a machine programmed to make sense of data on a scale humans can’t deal with. It is the king of the algorithm, a machine learning from its own experiences, objective-oriented and highly intelligent, producing logical conclusions based on input. As part of the digital technology connecting people, things and machines on a big data platform, it has the potential to enable solutions saving time, energy and lives, opening up opportunities as yet undreamt of. And it is still in its infancy in its real world deployment.

    The use of AI is growing dramatically right now in response to extraordinary increases in the amount of data produced daily, as powerful computing has become available at lower costs. Humans alone simply cannot process the complexity and ongoing volume of data from people, devices, sensors and machines.  In parallel, there is a growing awareness of the tremendous potential of AI technologies to solve problems across all industry sectors and the entire spectrum of human life.

    AI can unlock scale and opportunity to deal with the grand challenges facing the world today, from ageing populations to sustainable urban living, access to food, healthcare, water and education, reducing poverty and increasing gender equality. Physical AI will be able to free humans from mundane, routine tasks, allowing them to concentrate on more important, higher-end work, releasing creative potential.

    In emerging markets and smart cities alike, AI can help overcome natural limitations to growth such as geographic size or lack of natural resources, creating new markets and new value, rather than merely improving on existing models.

    Improvements on current models will, however, be where the power of AI is first felt, in its promise of enormous cost savings, increased productivity, lower production cycles and improved back end or internal processes. Within the telco industry itself, AI will accelerate the evolution of network operator infrastructure into intelligent networks able to offer smarter, faster and more scalable services. Using the engine of big data, AI will enable multiple, diverse and often sector-specific demands to be met through highly-tailored network slices managed in real time.

    In the financial services sector, for example, AI can reduce the hundreds of thousands of hours needed to carry out regulatory compliance to a matter of seconds; or the time, effort and investment necessary for a mortgage to a few minutes. New financial services may include mass market personalised services, opening an enormous market of lower earners, or microfinancing for the unbanked. In call centres across a range of industries, AI can work either alongside humans analysing complex data sets in parallel to the human customer-facing contact, or take calls as a co-worker as far as possible before passing on to human expertise.

    In all cases, AI is a tool to augment human abilities rather than replace them. And it is only as good as the person inputting information and parameters into its system.

    This is one of the principal challenges: ensuring that AI is provided with initial information in a way that does not reflect and perpetuate inherent bias, unconscious or not. It is critical to be aware of, and work to avoid, replication of existing divides and inequalities: on gender, race, geography, the urban/rural split, access to education, investment in infrastructure, the availability of talent, the provision of adequate cyber security. Without action, AI will prolong or deepen these divides. There is a very real danger that the powerful impact of algorithms actuated by AI will remain limited to the developed world due to a lack of infrastructure, advanced networks, open data or data scientists.

    Providing open public data and open APIs to allow private companies and individual developers to create solutions for public and commercial services is key to democratising AI – and fast-tracking its deployment. Accessing large data sets in the ecosystem to improve quality of life must be balanced against data protection, privacy and security issues.

    Preparation in general – and education – is critical. The international community, government, businesses and individuals should be as ready as possible for the seismic changes that the widespread adoption and deployment of AI will bring with it.

    The big one, of course, is the transformation of the existing labour market. It is estimated that up to 75% of all jobs will be impacted by AI over the next ten years – and these will not just be routine, low-skilled jobs, but also traditional blue collar sectors such as journalism, law or financial services. Productivity and revenue should rise as costs are cut, but the societal disruption will be enormous.

    AI is often invisible, raising issues of transparency and accountability. It is itself a neutral tool, without morality, but the ethics of its use are complex. Establishing codes of conduct and social norms as the first step to any regulation is urgently necessary at intergovernmental, international level. Regulation – as well as the standardisation necessary for it to function in a multi-vendor ecosystem environment – is further complicated by AI’s inherent structure as an active machine, learning in real time with real data.

    AI is here – and growing fast. There is an increasingly urgent need to bring together key stakeholders from government, industry and academia to debate its impact on a neutral platform such as ITU Telecom World 2018, the leading tech event organised by ITU, the UN lead agency for ICTs. Making AI democratic, fair and equitable is a challenge that cannot be met by any one single stakeholder.

    Experts at ITU Telecom World 2017 last year felt that its first use cases and greatest impact would be economic rather than social: AI will go where the money is, or can be made.  In some sectors, if you are not yet using AI, you are two years behind the curve. But the size of the opportunity is so great, the potential so huge, that it is far from too late.

    The potential negative effects of AI include social and economic disruption, in particular in the job market; the deepening of inequality; the danger of inherent bias; major issues of transparency, security and accountability; the lack of an internationally-agreed ethical code. Now is the time for contingency plans, for preparation and education throughout governments, industries and societies.

    There is downside, after all, to both deploying AI and not deploying it.

    AI will be a key component of discussions at ITU Telecom World 2018 in Durban, South Africa, 10 -13 September, providing the diverse perspectives of international experts from government, industry, SMEs and academia. Find out more at https://telecomworld.itu.int/

  • Omnichannel Retail is Coming to Hong Kong

    Omnichannel Retail is Coming to Hong Kong

    The future of retail is about to be delivered to Hong Kong’s commercial developers, and it’s coming via the Internet, according to a report released today by property consultancy JLL.

    The company’s report on the city’s shopping scene, “Reimagining Retail – Bricks, Mortar and the Evolution of E-Commerce in Hong Kong,” forecasts that the value of Internet retail sales in the Asian financial hub will reach US$3.7 billion by 2021, nearly double the US$1.8 billion transacted in 2016.

    However, although government statistics forecast that e-commerce in Hong Kong will have grown at an average of more than 16 percent per year from 2016 through 2021, the burgeoning online sector will become a component in retailer strategies, rather than a replacement for in-store sales, according to the company’s analysts.

    Ecommerce Growth May Not Lead to Lower Rents

    “As the US and mainland China markets have seen an increasing number of vacant shops, together with the continuous growth in online sales, some of our clients start to worry that the demand for brick and mortar stores will diminish once Hong Kong’s online retail takes off,” said Denis Ma, Head of Research at JLL in a press conference held in Hong Kong.

    According to the report, some 90 percent of the city’s landlords believe online sales will grow over the next five years. However, despite a spate of cut-rate lease deals in a number of the city’s top retail locations, that may not translate into lower rents at Hong Kong’s malls.

    “We don’t see the growth in online retail to be a significant factor in influencing rents in the short term. Factors like the number of tourists coming to Hong Kong and unemployment rate are more relevant to the rental level,” said Eric Cheng, Local Director of Retail at JLL.

    Some of Hong Kong’s busiest shopping districts have witnessed sharp rent cuts during the past few months. In March, fashion brand Twist leased a two-storey shop at 24-26 East Point Road in prime shopping district Causeway Bay for 56 percent less than the HK$1.1 million monthly rent that the previous tenant had been paying.

    On Russell Street in the same district, which formerly ranked as the most expensive retail strip in the world, Swatch Group last month secured a 33 percent cut in it’s HK$1 milliion per month rent when it renewed a lease originally signed in 2015.

    HK Retail Goes Omnichannel

    While online retail may not mean an end to traditional shopping, landlords will have to be ready to accommodate retailers that are selling to consumers who use smartphones and desktops for their shopping as much as they rely on strolls through the mall.

    “The future of the retail market of Hong Kong lies in its evolution into omni-channel retailing,” Ma said at a media briefing on the report. “From our perspective, the growing popularity of mobile payments and wider adoption of big data analytics will move us in this direction, as well as enhancing the overall shopping experience of consumers. This certainly requires retailers and landlords, such as mall operators, to invest more heavily in technology.”

    Ma predicts that online retailers will look into establishing brick and mortar stores while existing physical retailers will open up online platforms in the future. “As the rental market is expected to bottom out within this year, our advice to retailers looking to move into bricks and mortar is that they should act fast. Because in a few months’ time, there will be fewer vacant shops available,” said Ma.

    Last year, Chinese phone maker Xiaomi opened two physical showrooms in Hong Kong after the tech unicorns sales had grown 40 percent in the city as of October last year. The Chinese firm originally adopted an online-only strategy by selling its products directly to customers online before it started opening brick and mortar stores in mainland China in 2015.

    Small Living Space Drives People to Malls

    Hong Kong’s Internet retail grew at a compound annual growth rate of 15 percent from 2011 to 2016, and is expected to grow by 16.1 percent in the next five years, data from the Hong Kong Trade Development Council shows. While the growth rate seems steady, the online retail market in the city remains underdeveloped. Online shopping will account for just 6.1 percent of the city’s total retail sales in 2021, well below the 17.3 percent average in Asia.

    The relatively slow expansion of the Hong Kong’s online retail industry is attributed in part to the city’s famously tight living quarters. With 80 percent of the existing private homes below 70 square metres (753 square feet) in area, people tend to spend their leisure time outside of their homes, often in malls, according to Ma.

    A high density of retail shops, poorly designed online platforms and an ageing population also hindered the development of online retail in the city, Ma added.

  • Shiqi Metro Mall golden egg for Dasin

    Shiqi Metro Mall golden egg for Dasin

    Acquired on June 19 last year, Shiqi Metro Mall has proved a profit booster for Dasin Retail Trust, according to its financial results for the three months to the end of March.

    Dasin is the only China retail property trust providing direct exposure to the growth of the Guangdong/Hong Kong/Macau Bay Area, and has an initial focus on retail malls. Its four present malls each had 100 per cent occupancy at the end of March.

    Largely because of the contribution of the Shiqi mall in Zhongshan, net property income year on year increased by 85 per cent. This was 3 per cent higher than forecast.

    Opened 10 years ago, the regional mall’s anchor tenants include Gome Electronics, Jane Eyre Furniture Mall, Jinyi Cinemas, KFC, RT Mart, Starbucks, Superior City Department Store, Watsons and Xin Xuan Hotel Restaurant.

    Other Dasin malls include Xiaolan Metro Mall, with tenants including Bank of China, Chow Tai Fook, KFC, McDonald’s, Pizza Hut and Sunning.

  • How updating Privacy Settings will affect Businesses

    How updating Privacy Settings will affect Businesses

    You may have suddenly started receiving privacy updates from all the internet sites, apps and services you use. That’s because the European Union’s General Data Protection Regulation becomes law on May 25, 2018. It’s the clearest statement yet from any regulator on what consequences companies could face in dealing with their customers’ personal data.

    The regulation has been introduced to counter the power and prevalence of data collection and online surveillance techniques. It contains strict new rules of data protection, and severe penalties for breaches.

    The regulations apply to the data processing activities of any business that is a data processor (like US-based Amazon Web Services or India-based Habiledata) or data controller (like Ebay and Facebook) with an establishment in the EU.

    It also applies to any processor or controller, wherever they are located, that is processing the personal data of EU residents. This is regardless of where that data is processed and is irrespective of whether payment is required.

    By forcing non-EU companies to comply, the EU is ensuring that EU and non-EU businesses compete on the same terms.

    How it will affect businesses

    Australian businesses will not be forced to comply with or fall foul of the new data regulation merely because they maintain websites accessible in the EU. However, those with an office in the EU, or whose website is aimed at or tracks the data of EU residents, will be affected.

    These include businesses with an EU footprint, for example retailer Harvey Norman operates in Ireland, Croatia and Slovenia. It also covers data processors in Australia whose business includes EU or EU based clients, and startups which trade globally.

    Australian businesses may benefit from the fact that the new rules are consistent with the Australian Privacy Principles. Both promote transparency and accountability in information handling and require businesses to notify of any privacy breaches.

    By contrast, businesses in countries where data handling requirements are less comprehensive (notably the US) will have to make changes to become compliant.

    Nevertheless, the new EU law will impose new burdens on Australian businesses. For example, the EU laws specify encryption and pseudonymisation – where personally identifiable information is replaced by one or more pseudonyms – to ensure data is not identifiable.

    The new EU law will also change the standard practices of online businesses by outlawing pre-ticked boxes, required consent and bundled consent. Businesses must now seek (in clear and plain language), and individuals must give, active, specific, free and informed consent to each purpose for which their data is collected.

    The data law also require all businesses to demonstrate that they have procedures for notifying regulators and customers of data compromises: within 72 hours in the case of high risk breaches and without undue delay in all cases.

    How it will affect consumers

    The EU law includes new or enhanced rights for individuals. Many have no equivalents in other jurisdictions, including Australia.

    People have a right to demand that businesses erase and cease disseminating personal information, and to halt its processing. However, this “right to be forgotten” is balanced against the public interest in the information remaining available.

    The right to data portability in the legislation enables individuals to obtain personal information they have given by consent to one controller in a “structured, commonly used, machine-readable format” and transfer it to another. This will make it easier for customers to switch between businesses.

    However these rights impose regulatory burdens on businesses. It may be technically and organisationally difficult without sophisticated and expensive data handling processes.

    For businesses that rely on things like cloud backup and third party customer support, deleting or making copies of transferable data will be difficult.

    The commercial value of data is such that some companies may simply try to avoid the consequences of the new EU laws by processing information outside the EU, and applying different standards of data protection to customers depending on their location. Facebook has done this.

    On the other hand, given how complex double standards can be to apply in practice, they may simply make the EU rules the new normal of global privacy. In that case businesses should be using it as an opportunity to build more sustainable business models in the emerging era of respect for privacy.

  • Online Giants Carve Out Twin Empires in China’s Age of New Retail

    Online Giants Carve Out Twin Empires in China’s Age of New Retail

    The largest e-commerce players in China have rapidly expanded their scope and reach in recent years through a wave of investments and acquisitions. Alibaba owns two of China’s largest e-commerce platforms, Taobao and TMall, as well as an electronic payments system, AliPay. JD has allied with Tencent, which owns WeChat. Now, a report released by Oliver Wyman, a global consulting firm, analyses how the two players’ ubiquity in mobile payments, deep consumer data and sophisticated logistics capabilities has resulted in a new ‘age of empires’ in China’s retail sector where incumbents must quickly adapt to survive.

    The report, Chinese Grocery’s Age of Empires, reveals the e-commerce giants’ efforts to drive further growth by introducing new shopping formats – dubbed O2O, or online-to-offline. These blend online shopping’s convenience and wealth of information with the social experience and physical contact with products that people enjoy in traditional, brick-and-mortar stores. This is most immediately visible in the online grocery sector, where Alibaba and Tencent/JD are actively pursuing three strategic plays that could together increase their share of grocery shopping from around 10 percent today to around 30 percent over the next five years, by when it could be worth approximately 400 billion renminbi in gross merchandise value.

    “With the grocery sector seeing mobile payment penetration of 35%, the two giants are seeking to maximize their critical advantage of dominance in covering 97% of the overall mobile payment market,” says Richard McKenzie, Partner, Greater China at Oliver Wyman. “Now their investments are rapidly building a wider ecosystem of alliances that will make them ubiquitous through online-to-offline tools and features.”

    Over 460 million people in China regularly shop online, where densely populated cities facilitate home delivery. As a result, China has leapfrogged other markets to take the lead with nearly 10 percent of the population shopping for groceries online, compared to just 3 percent in the United States and 6 percent in the United Kingdom, Europe’s highest rate.

    This rapid change favors the two giant empires, which could make it hard for independent retailers to survive outside of them, evidenced by declining like-for-like sales and margins among China’s traditional supermarkets and convenience stores over the past few years. However, they may yet survive in some form with help from the online giants themselves, leveraging the empires’ logistics networks, rapid delivery services and new software solutions.

    Both empires are building their O2O power through three plays, each of which blends their online capabilities with offline stores in new ways:

    1. Experimentation with own retail formats

    Unlike supermarkets elsewhere that offer online shopping in parallel with a traditional in-store experience, China’s players integrate elements of the two. For example, Alibaba’s Hema stores offer smartphone payment and home delivery within 30 minutes. . Though expensive to set up and with high initial running costs, these stores are only marginally loss making. With further maturity and ramp up, breaking even is within reach. Oliver Wyman believes there is potential for at least 1,000 stores in major cities with total revenues of RMB 200 billion.

    1. Strategic Partnership with Big Box Retailers

    Big-box retailers have tried and failed to launch their own O2O and online shopping services in the past. Amid pressure from the online giants, a flurry of partnerships has seen large retailers aligning themselves with the two tech empires. These show early signs of success as parties combine their different strengths. Examples include Alibaba installing Tmall Supermarket shelves in RT-mart branches, with one-hour home delivery for products on these shelves, while Walmart, which has a strategic partnership with JD, is using its O2O unit JD Daojia as the service platform for over 150 stores to attract online traffic.

    1. Reinvention of the traditional world of “mom and pop” shops

    Traditional stores still account for half the sales of fast-moving consumer goods in China, much of them through the more than 7 million family-run stores that dominate retail outside big cities. Since early 2017, JD and Alibaba have been converting these into franchises, helping them optimize their stock through data-based curation tailored to their neighborhoods. Smartphone-based ordering systems and rapid delivery have also revolutionized procurement. Tmall planned to open 10,000 such franchises in 2017, while JD is aiming for one million by 2021. Alibaba and JD are further likely to dominate the growing market for their ordering systems, a market that could be worth up to RMB 400 billion over the next five years.

    Wai-Chan Chan, Partner, Greater China at Oliver Wyman notes, “China has not only surpassed the US in terms of online grocery penetration but also in terms of the pace of innovation and introduction of value-added services. Customers at a Hema store can pay seamlessly via their mobile phone, have fresh crayfish cooked in-store and delivered to their home within 30 minutes. Players in other markets are still some way behind in matching that offering.”

    As O2O becomes the new normal in retail, the two alliances will act as both players and facilitators of these models. While retailers and brands need to plan the best way to function in a retail world dominated by the two tech empires, identifying opportunities for synergy, it will pose a more serious challenge for some incumbents.

    The new environment will pose serious challenges to independent supermarkets and hypermarkets. Survival will require drastic changes, but this is unlikely under their current set-up. Some leading convenience stores should be able to survive outside these empires in the short term, but they too will come under threat in time from the revival of family-run stores under the franchise networks run by the two giants.

    The tech empires will inevitably influence the shape and future of the supermarket and hypermarket industry. It is crucial for incumbents to find ways to partner or co-exist with them if they are to survive and thrive.

  • Robots the future of customer service?

    Robots the future of customer service?

    When consumers walk through physical aisles of a supermarket or browse online catalogues these days, it is easy to overlook a vital and emerging trend – robots in retail.

    Robotics play a crucial role in cultivating a holistic retail experience for consumers in ways that have not been seen or thought of before. In warehouses, robots boost productivity and speed up the shipping of goods to stores and customers. Robots have also been drafted in stores, ready to serve customers with efficient inventory management. As the role of robotics in retail advances, we will see the same increase in speed and efficiency apply to the shopping experience as it has for industrial applications.

    Robots are making a timely appearance in the retail landscape as businesses today face pressure from multiple angles. Besides facing intense competition, they are also having to cater to a business environment that is being turned topsy-turvy as e-commerce grows.

    Consumer preference is also going through rapid transformation as shoppers become accustomed to e-commerce experiences that allow for cross-site comparisons, competitive prices and the convenience of shopping anytime, anywhere as they are connected via a computer or mobile device.

    The retail industry stands to gain as a whole with the entrance of robotics technology. Robots are being deployed, both in e-commerce businesses and brick-and-mortar establishments, to enhance efficiency and strengthen logistical and operational functions. Indirectly, this should translate to improved service levels and shopping experiences, and perhaps even lower costs.

    Workers in the retail industry too stand to benefit as robots can take on menial, mundane or dangerous tasks, freeing them up for knowledge-driven work.

    “Can.I.Help.You.Mdm?… Beep”

    Robots in retail can take on frontline, customer-facing roles too. As artificial intelligence capabilities grow, robots are emerging from beyond behind-the-scenes operations. Retailers have started to accommodate in-store robot assistants, able to direct traffic and perform important roles such as inventory management, freeing staff to handle more complex tasks.

    One such retailer is Walmart, which has installed robots into 50 of its stores across the US. These robots cruise along supermarket aisles checking shelves for items that need to be restocked, as well as merchandise that is misplaced or incorrectly priced. This vital information is then communicated to store staff who take necessary action. Equipped with cameras, these robots scan shelves three times faster than humans and are more accurate in picking irregularities. The engagement of robots is a pivotal component of Walmart’s plan to boost efficiency and accessibility of shoppers.

    Warehouses and delivery: hardwired for efficiency

    To satisfy today’s customer expectations of receiving goods faster, and with low or no delivery charges, retailers must develop an effective logistics system. Robots can help ease the pressure on retailers by improving logistical functions that are otherwise time-consuming. One example is how automation and robotics are used in smart warehouses to move large volumes of items through storage systems in a quick and reliable fashion, while still monitoring the exact location of each item at all times.

    Global retail stalwart Amazon built its success on automating its warehouse operations while maintaining its top-10 status in the ranks of the biggest employers. Fuelled by the support of the 55,000 robots employed last year, Amazon offered quicker deliveries at lower costs and led the retail industry in sales growth.

    Closer to home, robots have progressively proven themselves at Alibaba. The company recently introduced ‘Steel Soldiers’, a film about human and robots fighting shoulder-to-shoulder together. Its renowned smart warehouse is laden with sensor-charged robots who perform 70 per cent of tasks and can each carry up to 500kg of goods.

    Its competitor JD.com has also started using robots for the transportation of goods within 20km. Using robots has reduced JD’s unit delivery cost by 80 per cent and it’s fully automated sorting centre handles 9000 online shopping orders per hour – an operation previously performed by 180 human sorters.

    Alibaba and JD are testament to the idea that robotics can add value to shoppers by reducing delivery costs and speeding up logistical processes, even if they never meet them.

  • How to action data from your business

    How to action data from your business

    E-commerce websites have the ability to collect a ridiculous amount of information.

    With access to such large data sets it’s no wonder so many e-commerce businesses are touting about how “big data” and “business intelligence” (“BI”) sets them apart from the pack.

    We certainly agree that the insights that can be generated from data represent a significant opportunity for a business of any size, but for all the focus on the systems, tools, and resources, the other side of BI needs just as much consideration – that is, what are you doing with the information?

    The ability to answer this question is what turns the data from numbers into actionable insights. While there is no shortage to the questions and solutions that data can provide, BI gets discussed in such general terms that it’s not always clear how one takes data and uses it to make actionable recommendations. So, how do you turn data into actionable insights?

    First you need to find patterns in your data.

    A year has a lot of data points, so start with peak sales period(s). Look at your data, including the age and gender shopping on your website during that key period, it can offer meaningful insights that can be actioned to improve performance over that period. We’ve found that there are patterns to indicate when certain customers tend to shop over others.

    For instance, we found that on certain key dates male customers aged 18-24 were more likely to go online and shop than other days. We also found that during other key dates in the period, woman aged above 35 years were shopping on certain dates but what they were purchasing on those dates were largely for younger males, suggesting that they were purchasing on behalf of their children.

    With this data in hand, we then determined what our key objectives were for this period to best identify how to tailor a marketing plan to achieve them; looking to grow revenue so we used the data to launch specific marketing campaigns aimed at increasing conversion rates, capturing new customers and recovering customers who had not purchased for over 360 days. With these goals in hand, we identified specific products that were likely to resonate by customer type before creating multiple creative assets with the product, tone of voice, message/visuals all geared towards each specific customer type. Using these assets to place them in emails and media where each of these customer sets were most likely to view it in order to maximise the exposure, click through rate and conversion. And finally, we launched look-a-like campaigns across social media to capture new customers.

    While this data was used to find ways to enhance key sales periods from a marketing perspective, the insights can be used to make decisions from as early on as setting the season’s buying plan. Setting a buying plan that considers what cross-sell opportunities exist to the shopper at hand – without compromising the brand proposition – would provide an even stronger opportunity to maximise sales. Simply knowing who you are buying for and what dates they are likely to buy let you both target your messaging and curate what you’re selling to meet that customers’ needs.

    The specific implementation is an important component – what, when and where you are advertising needs to be aligned with the insights you’ve found and the assortment aligned to your customer, but these serve as examples into how you can use your data to action meaningful change to your marketing and buying initiatives.

  • Shift to New Retail ‘imperative’

    Shift to New Retail ‘imperative’

    A shift by brands to a New Retail model is imperative to remain relevant and competitive in China, according to a joint report from AliResearch and Bain & Co.

    The report, the most complete to date, offers a look at the blueprint for how companies and brands can seamlessly meld their online and offline channels, providing a better customer experience and making their own operations more efficient.

    It notes the challenge laid out by Alibaba Group CEO Daniel Zhang in a letter to investors, whereby companies need to tap big data analytics to redefine the core of retail – consumers, merchandise and stores – as well as the ties among them, to upgrade formats and create new retail occasions. And it cites a list of brands, including Mondelez, Friso, Estee Lauder and Bestseller, as “leading the charge to shape tomorrow’s retailing.”

    A fundamental change in thinking by companies and brands needs to happen with respect to the customer, viewing them “in the role of co-producers,” the report said. More than just identifying target consumers and their needs, more-comprehensive and dynamic profiles allow brands to find “ways to stimulate consumer needs, identifying look-alike consumers and turning consumers into brand ambassadors who effectively co-create the brand.”

    At the same time, products morph from mere commodities to becoming part of the consumption process and consumer experience. In the world of New Retail, products and delivery are inspired by consumer data and they’re highly personalized. Moreover, with a fully integrated, omnichannel experience, it’s no longer about simply spending time in an online or offline store. It’s about consumers shopping while enjoying content or spending time on social networks, the report said.

    “The best brands are determining how to integrate products with the overall experience of not only shopping, but learning about a product, using it and recommending it,” the report said.

    In all, the report highlights six steps “winning brands” are taking “to reshape the future and make the most of New Retail.” They are:

    • Identifying new governance principals for a customer-centric model
    • Developing new flexibility and efficiency in R&D and supply chains
    • Reimagining marketing and consumer management
    • Modernising route-to-market and retail formats
    • Transforming the organisation and operating model for digital
    • Investing in new technology development.

    The 24-page report covers each step in detail and offers case studies of the above-mentioned and other brands in their quest to reimagine and redefine their business through New Retail.

    While the report’s focus is on China, it telescopes outward and concludes that the changes Jack Ma predicted when he coined the “New Retail” term in 2016 “are arriving so swiftly and dramatically that each month seems to bring with it a big, new preview of what retailing will look like everywhere, as China sets a pace for the rest of the world.”

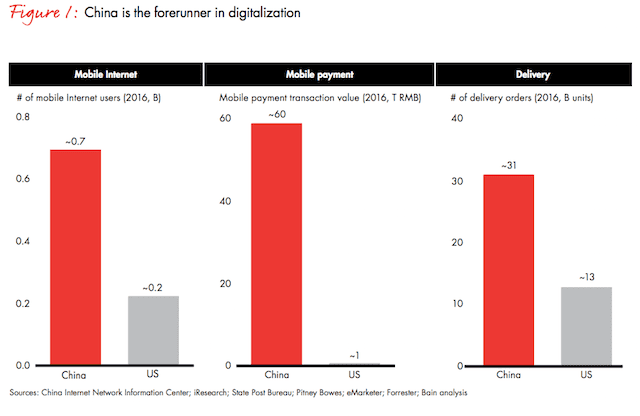
    New Retail in China has already taken hold in numerous sectors, transforming small, disparate shops and businesses into “order-and-delivery stations for e-commerce.” Food-delivery platform Meituan, for example, fulfills more than 18 million orders a day. And China is well ahead of other countries, such as the US, with 60 times more mobile payments.

    “Wherever retailing is headed, China is already there,” the report said. “For brands hoping to sell in China, survival means moving equally fast to capture this future ahead of competitors, both incumbents and digitally savvy upstarts. It will not be enough merely to keep up. Brands will be required to get ahead and help shape the vast changes, even as they completely overhaul the rules of engagement.”

    That means adopting a big-data-based approach to business, along with a new type of customer-centric experience that involves much-higher levels of engagement and personalisation than ever before. Businesses, themselves, need to erase any existing cross-unit barriers, investing in the technology and process redesign to make that happen, as well as changing their mindset.

    The results for brands that get it right are both clear and gratifying. Citing a case study from Mondelez, the report delves into what happened when the cookie company focused on customisation for Tmall’s Super Brand Day 2017. Its goal was to make Oreos more popular among teenagers.

    To do so, Mondelez partnered with third-party vendors and Tmall to create, launch and market a music box that played tunes when an Oreo cookie was placed on a turntable-like device. Taking a bite of the cookie and putting it back on the turntable changed the tune. Consumers could record their own voices on the music box and decorate it, customising it by scanning a QR code. Relying on a flexible supply chain, Mondelez brought the music box to market in just seven days, rather than a more-traditional two to three months.

    “It has been a New Retail success story,” the report said. “The singing biscuits generated 80 times more sales on Mondelez’s site than normal, with 90 per cent of the purchases made by new consumers.”

    Brands need to act now to adapt to a New Retail reality, though the changes they make to their operating models and the introduction of new capabilities won’t necessarily bear fruit right away.

    “New Retail is a work in progress that will require brands to constantly refine and reinvent themselves for new occasions, new formats and the steady flow of new ideas that will define retailing tomorrow,” the report concluded.

    You can read the full AliResearch/Bain report here.

  • Retailer spending on AI to rise, says Juniper Research

    Retailer spending on AI to rise, says Juniper Research

    Juniper Research predicts global retailer spending on AI will reach US$7.3 billion a year by 2022, up from an estimated $2 billion for this year.

    Its report AI in Retail: Disruption, Analysis and Opportunities: 2018-2022 says retailers will heavily invest in AI tools that let them differentiate and improve customer services. These range from automated marketing platforms that generate tailored, timely offers to chatbots that provide instant responses to customers.

    Juniper found that spending will be strongest in customer service and sentiment analytics, where AI can be applied to understand reactions to purchased products and service received.

    It predicts retailer spending share in 2022 as:

    1. Customer service/sentiment analytics, 54 per cent
    2. AI-based automated marketing, 30 per cent
    3. Demand forecasting, 16 per cent.

    Juniper predicts retailers will use AI insights to design product ranges as well as create targeted promotional offers.

    “Retailers are looking to replicate the success of Amazon in making AI a core part of their business,” says research author Nick Maynard.

    He says retailers will increasingly turn to tactics such as AI-optimised pricing and discounting, as well as demand forecasting.

    With the advent of specific days for shopping, such as the Black Friday phenomena, understanding customer demand and planning appropriately is more important than ever, says the report.

    Juniper says retailers need to invest in this area in order to stay competitive, particularly in low-margin retail segments. Also, the cost of AI tools, now uneconomical for many players, will drop by 8 per cent over the next four years, helping realise 300 per cent growth in software spend.

  • 8 best cities on this side of the world to live

    8 best cities on this side of the world to live

    Time Out’s City Life Index, a survey of 15,000 people in 32 global cities, has been released, and it shows which ones promise the most fun and excitement in 2018. Eight of them are on this side of the world.

    The survey, conducted by Tapestry Research, questioned residents on a variety of aspects of city life.

    It ranked cities in categories across food, drink, culture, friendliness, affordability, happiness, and liveability.

    It also “found the key factors that make residents find their city exciting,” from dining out often to feeling proud of where they are from.

    Here, their ranking in ascending order along with their overall scores:

    31. Singapore (98.7) — Those from Singapore may not rate its culture scene highly, but they do value the city’s safety and are perfectly comfortable walking around at night.

    28. Sydney (106.1) — While they may think the city is lacking in things to do and good restaurants, Sydney residents live a healthy life, with 66% having exercised in the past week and 38% never having taken drugs. They know how to party, though, and are the world’s No. 1 vodka drinkers.

    26. Hong Kong (109.6) — Seventy-five percent of residents said the public transport in Hong Kong was great, contributing to the city’s overall score. They’re also among the biggest restaurant-goers in the world.

    24. Bangkok (111.0) — The survey revealed Bangkok as the world’s street-food capital, with more people eating on their feet than anywhere else — 42 times a year, on average. They’re also the biggest restaurant-goers, with 94% of respondents having visited a restaurant in the past week.

    22. Beijing (113.0) — The city may be exciting, but the commute is long, with 6% of Beijing residents even commuting for two to three hours a day.

    19. Tokyo (117.7) — Tokyo residents love their food — they visit restaurants more than most other cities on the list.

    16. Shanghai (119.5) — It may not come cheap, but there’s plenty to do in Shanghai, where residents say that while it is tough to find love, 79% believe it is easy to find a more casual encounter.

    4. Melbourne (132.3) — This Australian city came out above all others in terms of happiness, with nine in 10 residents saying they felt happy within the past 24 hours. They also find it easy to make friends and think the food-and-drink scene is one of the city’s best features.

  • McKinsey predict Online luxury to leap

    McKinsey predict Online luxury to leap

    Online sales are projected to more than triple to US$74 billion by 2025, involving about one in every five luxury sales, according to management consulting firm McKinsey & Company.

    Its report The Age of Digital Darwinism says there is a growing need for luxury brands to have digital competency, with McKinsey expecting the bricks-and-mortar environment to become dependent on digital.
    It says luxury goods e-commerce sales are growing rapidly. Online sales of personal luxury goods are presently $20 billion, making up 8 per cent of total luxury sales.

    Monobrand online stores are currently dominating, but multibrand platforms are growing their sales more rapidly. These e-tailers or marketplaces were born digitally, giving them an advantage over brands having to adapt legacy systems, says the report.

    Consumers have become more active in the luxury online sector, whether it is sharing content about brands on social media or participating as a secondhand seller or curator.

    In an increasingly digital ecosystem, those poised for success are adopting what McKinsey dubs a “Luxury 4.0” model. Based on Industry 4.0, which integrates customer data with production mechanisms and design, it aims to create a seamless process from concept to consumer.

    While luxury is centred on tradition and craftsmanship, 60 per cent of luxury managers see their brand selling 3D-printed goods within in the next decade, says the report.

    Data is also going to be key in customer engagement. As personalisation becomes the norm, marketers will need to focus on delivering a customised and individual experience.

    Digital is changing consumer expectations – consumers expect to be entertained and engaged offline as well. “Reverse-omnichannel” means that rather than digital needing to live up to the store, the store now has to live up to digital.

    Luxury brands are also facing competition from outside the industry, the report says. Amazon is changing customer behaviour, turning consumers into online buyers and making pushes into categories such as beauty and fashion. Amazon also accounts for 55 per cent of consumer product searches, with shoppers starting their journeys on the platform.

    Converging thriftiness and desire for sustainability is creating new models for consumption, such as rentals and secondhand marketplaces, the report notes.

  • Retailer spending on AI to rise

    Retailer spending on AI to rise


    Juniper Research predicts global retailer spending on AI will reach US$7.3 billion a year by 2022, up from an estimated $2 billion for this year.

    Its report AI in Retail: Disruption, Analysis and Opportunities: 2018-2022 says retailers will heavily invest in AI tools that let them differentiate and improve customer services. These range from automated marketing platforms that generate tailored, timely offers to chatbots that provide instant responses to customers.

    Juniper found that spending will be strongest in customer service and sentiment analytics, where AI can be applied to understand reactions to purchased products and service received.

    It predicts retailer spending share in 2022 as:

    1. Customer service/sentiment analytics, 54 per cent
    2. AI-based automated marketing, 30 per cent
    3. Demand forecasting, 16 per cent.

    Juniper predicts retailers will use AI insights to design product ranges as well as create targeted promotional offers.

    “Retailers are looking to replicate the success of Amazon in making AI a core part of their business,” says research author Nick Maynard.

    He says retailers will increasingly turn to tactics such as AI-optimised pricing and discounting, as well as demand forecasting.

    With the advent of specific days for shopping, such as the Black Friday phenomena, understanding customer demand and planning appropriately is more important than ever, says the report.

    Juniper says retailers need to invest in this area in order to stay competitive, particularly in low-margin retail segments. Also, the cost of AI tools, now uneconomical for many players, will drop by 8 per cent over the next four years, helping realise 300 per cent growth in software spend.

  • Top 10 Global Consumer Trends for 2018

    Top 10 Global Consumer Trends for 2018

    Genetic make-up and extended augmented reality are among the top 10 consumer trends for 2018, according to a new Euromonitor International report.

    People’s growing curiosity about their genetic make-up and a rising interest in personalised health and beauty are fuelling a global market expected to soar by 2022, says the Top 10 Consumer Trends for 2018 report.

    A new wave of companies aims to provide consumers with genetic findings related to their general health, fitness and nutrition, with the market growth being global and competition in the largely unregulated Chinese market particularly intense.

    “Although the consumer market still faces hurdles, such as country-specific regulations, things are improving on the regulatory front, and with the market continuing to evolve, it is likely that further innovative start-ups will invest in new technologies,” says report author Alison Angus, Euromonitor International’s head of lifestyles.

    With augmented reality (AR) having a wide range of applications in various industries, the potential in the mainstream consumer space is vast, bringing the benefits of in-store shopping into the home, says the report.

    Convenient shopping

    It forecasts that global internet retail sales will increase in value by a further 3 per cent this year.

    “Online captures consumers’ interest with the convenience of the hassle-free, anytime, anywhere shopping they crave. The ability to see and touch products before buying is a bonus.

    This is in part why the in-store shopping experience remains appealing, with 88 per cent of global sales in value terms still being made in-store last year,” says Angus.

    “This year consumer expenditure is expected to grow at its strongest rate since 2011. Overall, we will see consumers continuing to question their values, priorities and purchasing decisions; deepening their engagement in the brands and issues that matter to them.”

    The top 10 global consumer trends for this year are:

    • Clean lifers: Consumers adopting clean-living, more minimalist lifestyles, where moderation and integrity are key. Clustering around educated 20 to 29-year-olds, a new generation of “straight edge” consumers has grown up knowing deep recession, terrorism and troubled politics, and has a wider worldview than previous generations.

    • The borrowers: A new generation of community-minded sharers, renters and subscribers is reshaping the economy, making conspicuous consumption a thing of the past. Rejecting material goods in favour of experiences and a freer lifestyle, which has characterised the buying habits of millennials for the past few years, is a trend that continues to evolve and spread.

    • Call-out culture: Whether it is airing a grievance on Twitter, sharing a viral message or signing an e-petition, consumers are having their say. “Hashtag activism”, while not new, is rapidly gaining momentum as internet use explodes and more people have access to social media.

    • It’s in the DNA – I’m so special: People’s growing curiosity about their genetic make-up – what makes them so special – and a rising interest in personalised health and beauty are fuelling demand for home DNA kits. Target consumers range from the “worried well” and those curious about their origins to hardcore fitness and nutrition fanatics.

    • Adaptive entrepreneurs are increasingly seeking flexibility in their lifestyles, and are prepared to take risks. Millennials especially have an entrepreneurial nature, shifting away from the “traditional” nine-to-five career toward one that affords more freedom.

    • View in my roomers will be connecting perception and reality this year, merging digital images with physical space. Consumers will be able to visualise products before they try or buy, both in-store and online. The advent of even more sophisticated smartphones has given this demographic access to greater functionality, including AR technology.

    • Sleuthy shoppers: With further political upheaval last year, the consumer trust crisis is deepening and leading to greater emotional involvement and action. Shoppers are still sceptical of mass-produced products and the motivations of the companies that create them, and are tired of hearing empty rhetoric and soothing words of assurance.

    • Co-living: This trend has blossomed among millennials and the over-65s in the residential space. It is a form of housing where residents share living space and a set of interests and values. The trend stems from hyper-urban hubs that have embraced the sharing economy as a lifestyle choice.

    • I-designers: The lingering impact of the global financial crisis has encouraged prime, working-age older millennials and gen X-ers to re-evaluate their spending habits.

    Simultaneously, the rise of the sharing economy, with pioneers such as AirBNB and Uber, is eroding their desire to own goods (see The Borrowers trend).

    • The survivors: Ten years on from the credit crunch that heralded the start of the Great Recession, the frugal mindset of consumers remains entrenched. Despite improving economies, rising incomes and falling unemployment, the gap between rich and poor is highly visible, and those caught between low pay/meagre state benefits and high living costs are still struggling to cope with austerity.

  • Indonesia Logistics Market is Expected to Reach USD 240 Billion by 2021

    Indonesia Logistics Market is Expected to Reach USD 240 Billion by 2021

    3PL market in Indonesia is expected to increase at a five year CAGR of 14.0% in the near future. Jakarta contributed highest revenue share of 38.0% in Indonesia warehousing market in 2016 owing to the industrial parks situated in the largest city Jakarta.

    Indonesia Logistics Market is currently in the growth stage with presence of various organized and unorganized players consisting of a combination of shipping and international freight forwarders, courier providers which are mainly engaged in land transportation and total logistics services providers that operate a multimodal transport model. Players are taking up and diversifying into 3PL segment to enhance their market share. Presently, there are more than 155 logistics and warehouse service providers in Indonesia.

    The freight forwarding market size has increased with the boost in air freight and sea freight, the development of transportation infrastructure and increase in number of freight forwarders, increasing industrial activities, growing FMCG market and rising e-commerce industry. Road freight has the highest share owing to the high number of deliveries that take place through road network. Air freight had the second largest share in the country freight forwarding market. Asian Countries flow corridor is the largest contributor in terms of revenue in the freight forwarding market owing to free trade agreement. The leading players in the industry are DHL, CEVA Logistics, Yusen Logistics, Agility Logistics and others. The freight forwarding market is forecasted to dominate the Indonesia logistics market in future

    Air express logistics has dominated the Indonesia express logistics with 61.0% revenue market share during 2016 owing to major international shipments falling in this category. B2B segment has dominated the express logistics market in Indonesia during 2016. The major players of Express logistic in Indonesia include DHL, FEDEX, First Logistics and JNE Express. High growth rate can be advocated from the growth expected in the e-commerce industry, rise in the demand of perishable goods and the increased use of express delivery by people in case of personal and corporate documents and last mile delivery.

    According to the report by Ken Research, a noteworthy CAGR of 7.9% in revenue in Indonesia Logistics Market is expected in next 5 years till 2021. Freight Forwarding is expected to be the fastest growing segment in future with an expected CAGR of 9.2% from 2016-2021.