Tag: Australia

  • Australian Functional Drinks Market Generates over $2 Billion

    Australian Functional Drinks Market Generates over $2 Billion

    In September 2026, Australian innovation is helping drive a new phase in functional beverages, targeting a domestic market that generates more than $2 billion a year.

    The shift toward what industry observers call 4th Gen Drinks moves past adding electrolytes, caffeine, vitamins, protein or probiotics to instead use naturally occurring compounds from food and food-production streams.

    Chris Plazzer, founder of Olive Mill Water, has developed a functional drink made from polyphenol-rich liquid released during olive oil production, without added sugar, caffeine, flavourings or artificial sweeteners.

    Extracting Value From Agricultural Waste

    Olive processors have historically discarded wastewater despite high concentrations of active phenolic compounds. Pre-clinical research currently links olive-derived phenolics to metabolic, cardiovascular and gut microbiome function, drawing commercial interest from functional food formulators.

    Rather than dosing purified extracts into standard liquid bases, upcycling systems capture active compounds directly from existing farmgate processing lines. The method reduces waste management costs for agricultural millers while generating raw inputs for consumer-packaged drinks.

    The next generation of functional drinks won’t be built by adding more to the formula. It’ll be built by discovering what’s already there; in ingredients the industry has spent decades overlooking, or throwing away entirely.

    Shifting Formulations in Regional Beverage Retail

    Australian beverage brands face changing consumer patterns as younger demographics reduce alcohol intake and demand clean-label alternatives. Convenience retailers and supermarket chains across the region are reallocating refrigerated shelf space away from high-sugar soft drinks toward functional hydrators and natural extracts.

    The main commercial bottleneck for upcycled functional beverages sits in taste profile regulation and supply stability. Olive wastewater carries natural bitterness that requires precise filtration without thermal degradation of target polyphenols, limiting initial batch yields.

    Export Pathways and Science Backing

    Functional drink makers previously relied on imported vitamin premixes and synthetic electrolytes to build label claims. Upcycled domestic ingredients allow manufacturers to shorten ingredient supply chains while tapping into Asian retail demand for clean Australian agricultural provenance.

    Clinical trials on olive phenolic bioavailability in beverage formats continue across independent laboratories, with initial commercial retail distributions scheduled for review in late 2026.
  • Dove Expands Advanced Care Deodorant Range to Six Scents in Australia

    Dove Expands Advanced Care Deodorant Range to Six Scents in Australia

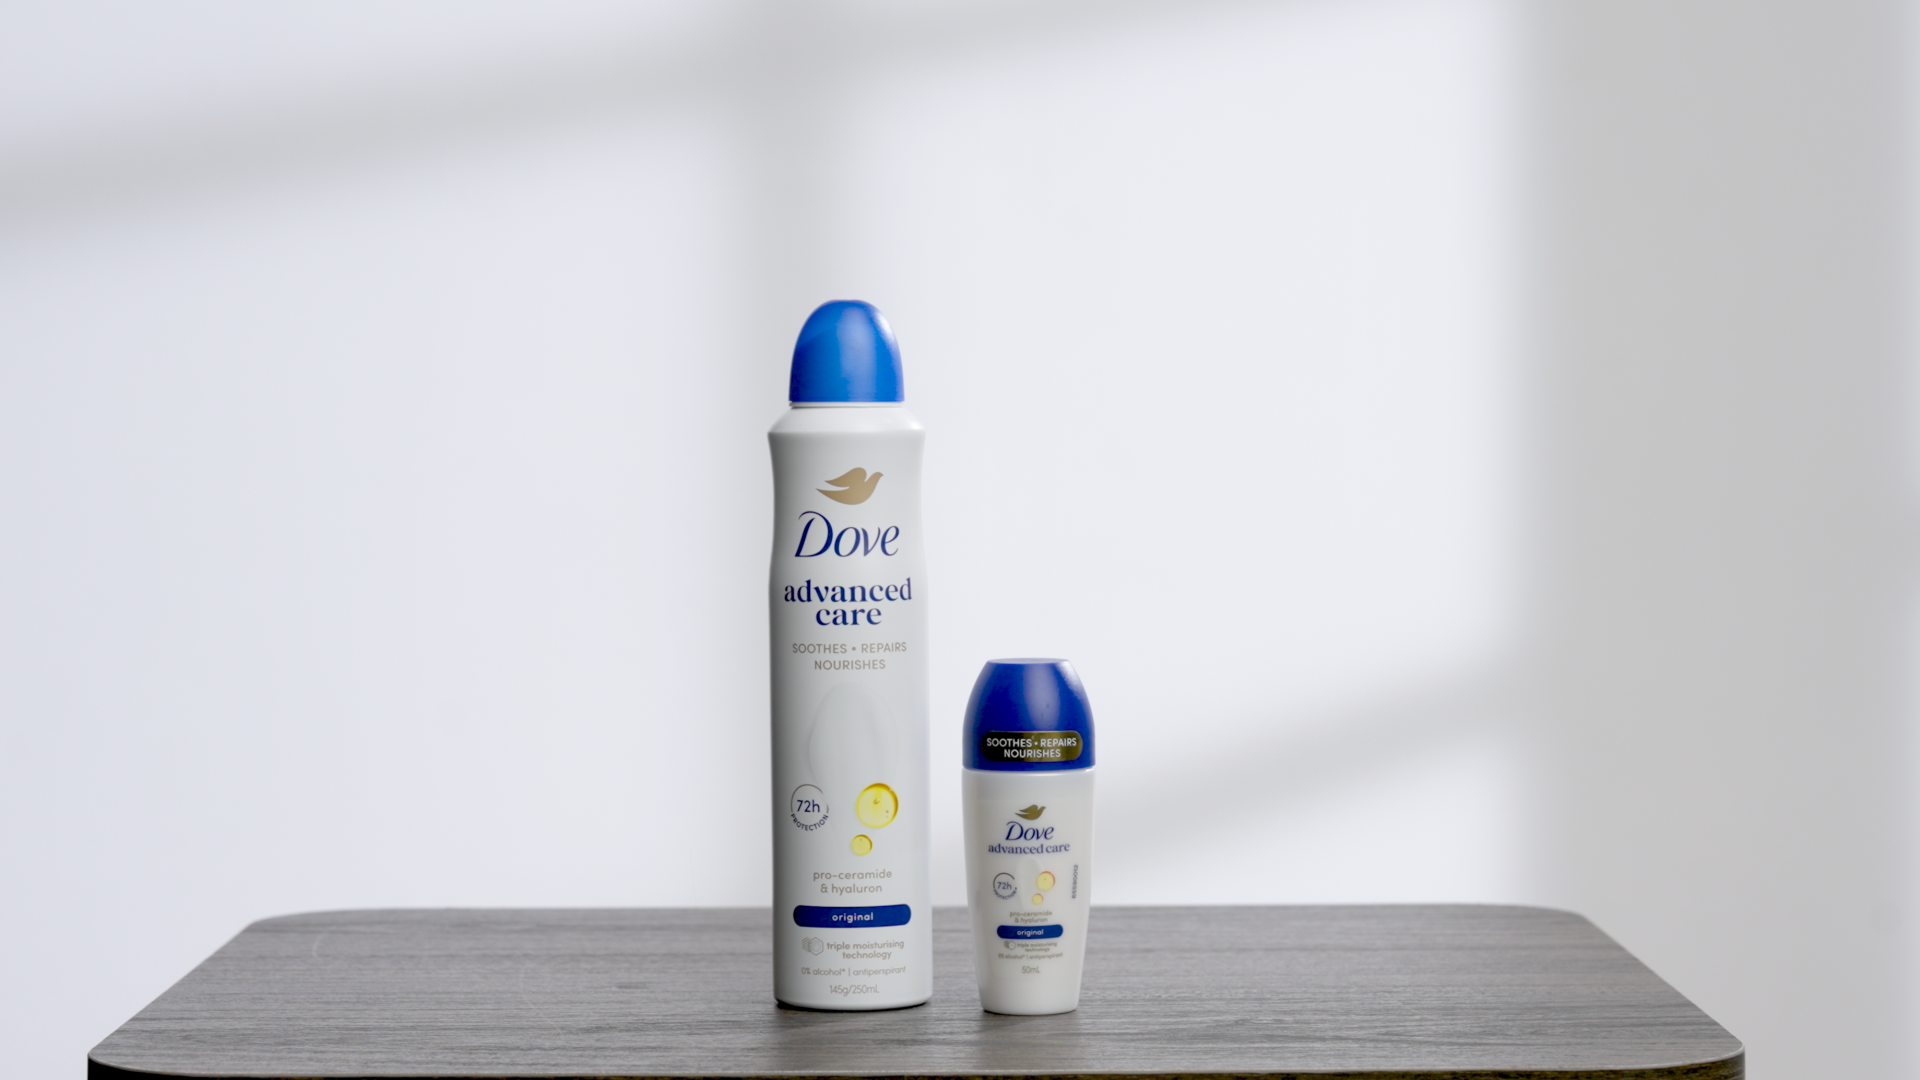
    Dove upgraded its Advanced Care deodorant lineup in Australia in September 2026, adding active skincare ingredients across six distinct fragrance varieties.

    The revamp introduces pro-ceramide serum and hyaluronic acid directly into the brand’s mass-market underarm portfolio, featuring an exclusive scent for independent retailer IGA.

    Skincare Ingredients Enter Daily Deodorants

    Formulations across the refreshed line now blend barrier-repair ingredients typically reserved for facial serums. Pro-ceramide serum works alongside hyaluronic acid to hydrate skin, targeting irritation caused by daily shaving and friction.

    The range spans six fragrances: Original, Pomegranate & Lemon Verbena, Acai Berry & Waterlily, Coconut & Jasmine Flower, Passionfruit & Lemongrass, and Apple & White Tea.

    Retail Distribution and Exclusive Variants

    Supermarket distribution splits the lineup across major national grocers and independent operators. The Apple & White Tea variant sells exclusively through independent IGA stores across the country.

    Channel-exclusive scents give independent operators a defensive shield against major supermarket chains. Tier-one grocers take the core five variants, while IGA uses the exclusive fragrance to drive foot traffic into its personal care aisles.

    Shifting Formulations on Supermarket Shelves

    Personal care manufacturers across the region continue migrating premium skincare ingredients down into high-volume grocery categories. Adding active hydrators allows everyday consumer brands to protect shelf space against specialty pharmacy competitors.

    Retail buyers are watching whether functional skincare claims can lift basket values in basic grocery aisles as shoppers manage everyday household budgets.

  • Over 60 per Cent of Black Friday Shoppers Pre-Plan Holiday Purchases

    Over 60 per Cent of Black Friday Shoppers Pre-Plan Holiday Purchases

    Australian retailers face a structural shift in holiday spending as 57 per cent of shoppers concentrate gift purchases in November after pre-selecting brands in October.

    Data compiled by market research agency Retail Safari and consultancy PwC shows 64 per cent of holiday budgets remain unspent entering November, even as buyers finalise purchase shortlists weeks earlier. Black Friday alone now captures 55 per cent of holiday shoppers, turning the discount window into an execution phase rather than a discovery channel.

    The Split Between Early Planning and Peak Spending

    Consumer research from Mintel indicates more than six in ten Black Friday shoppers choose their target products before promotional events begin. Shoppers use September and October to compare specifications, check customer reviews and track merchant pricing before committing funds. In Australia, research from the Australian Retailers Association and Roy Morgan showed 29 per cent of consumers started browsing earlier in 2025 than the previous year, while only 8 per cent started later.

    The US-based National Retail Federation recorded an identical baseline, with roughly 40 per cent of consumers starting holiday research before November. Shoppers cite three main drivers: managing household budgets over time, avoiding store congestion, and eliminating late delivery risks.

    Big-Ticket Sales Diverge From Headline Retail Growth

    Official figures mask underlying pressure across discretionary categories. Australian Bureau of Statistics data analyzed by investment research firm MST Marquee placed July retail turnover growth at 6.6 per cent year on year, running above the 4.9 per cent historical average. Food services rose 9.3 per cent and clothing gained 7.1 per cent, but major durable goods operators failed to capture that momentum.

    First-quarter trading updates reflect the divide. Online furniture seller Temple & Webster reported sales down 13 per cent across its first seven weeks, department store operator Myer posted a 4 per cent decline, and Accent Group recorded a 2 per cent like-for-like drop. Electronics chain JB Hi-Fi saw comparable sales slip 1.4 per cent, while its home appliance unit The Good Guys declined 1.7 per cent and furniture retailer Nick Scali tracked flat from July 1.

    Household Wealth Pressures Shorten Brand Lists

    For store operators and suppliers, the divergence means consumers are buying smaller items frequently while delaying expensive, considered purchases until deep discounting begins. Retailers that spend their marketing budgets solely on late November discounts risk losing shoppers who eliminated unfamiliar brands during the October evaluation window. Merchant margins face compounding pressure if price cuts merely settle competition among pre-selected names rather than bringing in new foot traffic.

    The shift follows a broader contraction in gift-buying participation. ARA and Roy Morgan figures showed 68 per cent of Australian adults planned holiday gift purchases last year, down 9 per cent from 2024, while average spend per remaining buyer climbed 7.1 per cent to A$757.

    MST Marquee projects household goods demand will soften further through the fourth quarter as property price weakness and potential interest rate hikes from the Reserve Bank of Australia curb discretionary outlays.

  • 91 Per Cent of Australian Consumers Switch Brands for Better Offers

    91 Per Cent of Australian Consumers Switch Brands for Better Offers

    A report by retail industry association Shop ANZ and consumer insights platform Vypr reveals that 91 per cent of Australian consumers have switched brands for a better offer.

    The study found that 79 per cent of shoppers have visited a different retailer to secure an offer, putting sustained pressure on retailers to continue promotional activity.

    According to the findings, 81 per cent of respondents said price has become a more important factor when purchasing a product than it was a year ago, making customer retention increasingly difficult.

    Promotional Cycles Drain Brand Value

    Heavier promotional spending generates short-term transaction spikes, but it fails to secure lasting customer retention once items return to full shelf price. Suppliers that fund continuous price reductions face falling margins without gaining repeat foot traffic.

    Vypr chief revenue officer Sam Gilding noted the structural weakness of relying on perpetual markdowns. “If a brand is recruiting shoppers heavily and then losing them to the next offer on shelf, it’s funding a cycle rather than building a base,” Gilding said.

    Middle-Aged Buyers Drive Shift

    Demographic data reveals acute pressure among mid-career shoppers, with 42 per cent of consumers aged 35 to 44 frequently switching brands because of a promotion. This demographic carries higher mortgage commitments and household expenses, making them faster to trade down than younger or older cohorts.

    Retailers across the Asia-Pacific region have expanded loyalty apps to protect basket sizes, yet Australian consumer behaviour suggests shoppers treat these programs as discount search engines rather than commitments to a banner. When every rival matches the discount, the retailer funding the deepest markdown simply buys temporary volume at the expense of profit.

    Shelf Pricing Faces Margin Test

    Shop ANZ general manager Carla Bridge explained that while shoppers discover promotions across apps, email catalogues, and social media feeds, purchasing decisions are still confirmed directly at the physical shelf.

    The findings follow two years of compounding inflation across Australian consumer staples, which reshaped grocery shopping habits and made weekly catalogue specials the primary driver of household spending routes.

    Packaged goods suppliers negotiating trade terms for the upcoming trading quarters now face demands from major supermarket chains to co-fund deeper price cuts to protect category volume.

  • Australian Retailers Overhaul Content Models to Curb Omnichannel Delays

    Australian Retailers Overhaul Content Models to Curb Omnichannel Delays

    Australian retailers have spent years adding digital touchpoints, but many are now getting slower at producing the experiences those platforms require as teams contend with cautious consumers and margin pressure. The operational challenge has mounted as websites, apps, marketplaces, loyalty programs, social commerce, and digital signage expand alongside physical stores.

    In many retail businesses, marketing teams and developers repeat work by building one version of a product launch for the website, another for the app, and separate material for email, social channels, and in-store displays. This fragmented production process leaves campaigns reaching one channel days after another while increasing the likelihood of inconsistent pricing and outdated product details.

    Ending Repetitive Channel Production

    When turning a single campaign into live assets requires weeks of handovers and developer queues, retail teams lose the capacity to personalize experiences or adapt to local trading conditions. To eliminate duplicated effort and lower costs, businesses are shifting toward composable models where product benefits, imagery, and promotional messages are created once and governed centrally.

    The alternative infrastructure treats product details, pricing banners, promotional terms, and media files as reusable modular components. Central governance teams control core brand messaging and product claims, while regional managers assemble approved components into distinct channel formats without writing custom code or rebuilding entire digital pages.

    Regional Adaptation and Guardrails

    For retail networks spanning diverse state territories and multiple brand banners, modular architectures protect brand standards while allowing localized commercial flexibility. Store managers can adapt pre-approved digital assets to reflect local inventory levels, regional weather events, and suburban community promotions without violating national brand guidelines.

    Across the wider Asia-Pacific retail sector, similar pressures have forced department store operators and convenience chains in Singapore, Tokyo, and Hong Kong to adopt composable technology architectures. Retailers that maintain monolithic content management systems risk falling behind agile pure-play operators who test, deploy, and retire promotional campaigns in hours rather than weeks. The primary operational risk sits in execution, as marketing teams often resist structural changes to publishing workflows without clear internal compliance mandates.

    The Operational Drag of Artificial Intelligence

    The operational shift follows several years of capital expenditure directed toward customer-facing channels, including social commerce integrations, automated locker networks, and mobile loyalty applications. While these investments widened customer reach, they divided digital production resources across disconnected content management software platforms.

    Recent deployments of generative artificial intelligence have highlighted these structural limitations. Retail operations that feed unstructured, fragmented catalogue data into automated generative tools produce inconsistent pricing and conflicting marketing claims at high speed, reinforcing the requirement for structured component databases.

    Merchandising and technology teams are now tracking campaign turnaround metrics and content reuse rates as key performance indicators ahead of the high-volume holiday trading period.

  • Barambah Organics Founder Ian Campbell and Daughter Die in Plane Crash

    Barambah Organics Founder Ian Campbell and Daughter Die in Plane Crash

    Barambah Organics founder Ian Campbell, 56, and his daughter Hannah, 23, died in a light plane crash south of Brisbane on Monday.

    Campbell founded the dairy business alongside his wife Jane in 2002.

    The Tamara Capital Buyout and Brand Growth

    Private equity firm Tamara Capital bought a majority stake in the business in 2020 in a deal valuing it at $50 million, while the Campbell family kept a minority stake and continued to influence operations.

    Following the buyout, the business expanded distribution across Australian retail channels to supply independent grocers, organic specialists and national supermarket shelves. It established a dedicated processing network and direct farm supply model across regional Queensland and northern New South Wales.

    Dairy Sector Pressures and Market Position

    Australian premium dairy producers face cost inflation across cold chain freight, feed and energy. Premium organic labels rely on tight supply agreements and consistent volume to protect margins against conventional private-label milk pricing.

    Customer retention was built on single-source farm provenance and organic certification standards. Preserving brand equity and operational continuity now falls to the institutional investors and executive management installed following the 2020 acquisition.

    Operational History and Next Steps

    The Campbell family ran the business as an independent operation for 18 years. Outside capital was brought in to fund factory upgrades and broader national distribution.

    Aviation safety authorities continue to examine the site south of Brisbane to determine the mechanical factors and flight conditions surrounding the crash.

  • Metcash Boosts Sales 2.8 per Cent but Warns of Food Margin Pressures

    Metcash Boosts Sales 2.8 per Cent but Warns of Food Margin Pressures

    Wholesaling giant Metcash lifted sales by 2.8 per cent in the first 18 weeks of the financial year, excluding tobacco, but warned investors that elevated food inflation could dent profit margins.

    Hardware and tools led the gains with a 6 per cent rise, while wholesale liquor climbed 5.1 per cent over the same period.

    Hardware and Drinks Outpace Core Food

    Core food expanded 2.6 per cent against the previous year, with group chair Peter Birtles noting that cost inflation continues to challenge the company’s bottom line.

    Logistics and retail expenses stayed elevated. Supply lines held stable, however, with no material disruption from Middle East shipping conflicts.

    Birtles told investors that Metcash’s “diversified portfolio, disciplined execution” and independent retail model have supported resilience despite external challenges.

    Cost Pressures Squeeze Independent Grocers

    For independent supermarkets, rising wholesale prices present a direct dilemma. Passing costs to shoppers risks losing market share to dominant chains. Absorbing them erodes thin retail margins.

    Margin pressure shifts the burden onto wholesale inventory. Distributors must lean on categories like trade hardware and commercial tools, where pricing flexibility beats daily grocery staples, to protect profits.

    New Zealand Liquor Exit Nears Completion

    Trading updates follow fiscal 2026 results of higher sales revenue but lower net profit. Warehousing and freight costs weighed on full-year earnings despite steady turnover.

    Metcash is now closing its New Zealand liquor distribution business to simplify operations and protect returns. The wind-down wraps up before the second half of fiscal 2027, reducing total earnings by approximately $2 million.

  • Sydney Fashion Label Asta Resort Opens Permanent Flagship in New York

    Sydney Fashion Label Asta Resort Opens Permanent Flagship in New York

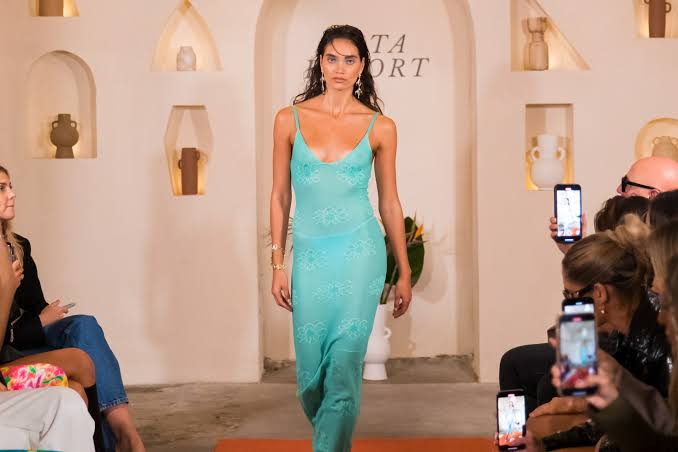
    Sydney luxury label Asta Resort opened its first permanent US flagship in Manhattan’s SoHo. Helena and Jasmine Ammitzboell founded the brand in 2021. The permanent boutique converts an earlier New York pop-up trial into a long-term presence.

    The retail launch coincides with a back-office buildout in Williamsburg, designated as the operational base for North American distribution.

    From Sydney Harbour to Manhattan

    Designers Joel Harding and Yuria Kailich of Studio of Enso planned the SoHo space around a Mediterranean resort aesthetic. The boutique features a quartz-clad champagne bar and a dedicated bridal podium. Ceramic plates hand-painted by the founders line one wall.

    Sydney is where Asta Resort began. New York is where we are laying down roots for our North American home.

    Wholesale Bypass and Direct Retail

    High digital customer acquisition costs push Australian resortwear labels toward physical flagships in global hubs. Securing permanent SoHo space lets independent brands bypass wholesale intermediaries. It also captures higher direct margins from affluent shoppers who first discovered the label online.

    Operating in New York brings steep lease commitments in a commercial market far costlier than Sydney. Operators expanding abroad also face inventory exposure across two hemispheres with opposing seasonal apparel demands.

    Building the US Operations Base

    Asta Resort opened its first permanent flagship boutique in Sydney in December. That domestic store served as the testbed for translating its online catalogue into an experiential physical space.

    Centralising regional management in Brooklyn gives the label direct control over inventory dispatches, styling appointments and client services across North American time zones.

    RetailNews Asia will track whether the label follows Manhattan with dedicated resort outposts in Florida or California retail corridors.

  • Coles Drops Palantir AI Software Across 840 Australian Supermarkets

    Coles Drops Palantir AI Software Across 840 Australian Supermarkets

    Coles will terminate its software partnership with US technology firm Palantir. The platform will leave more than 840 Australian supermarkets when the three-year contract expires.

    The system processed more than 10 billion rows of operational data. That load covered employee shifts, bakery production schedules and store-level inventory allocations.

    Operational Data and Customer Backlash

    Signed in February 2024, the agreement deployed Palantir’s Foundry operating system and artificial intelligence tools for workforce planning and supply-chain logistics. The supermarket chain confirmed the platform will exit its stores beyond 2027. Public pushback over Palantir’s government surveillance and defence contracts drove the decision.

    Advocacy group GetUp mounted a billboard campaign near hundreds of stores in July, mimicking Coles branding to challenge its privacy practices. Coles rejected claims that shopper data was exposed to external access.

    “The software is deployed within Coles’ own environment and is operated and isolated under Coles controls,” a Coles spokesperson said.

    Supplier Scrutiny and Reputational Risk

    Retailers across the Asia-Pacific region face swift commercial fallout when back-end software vendors carry political or military profiles. Enterprise procurement once rested on technical capability and cost alone. That calculation has changed. Boards must now weigh vendor reputation alongside data isolation protocols.

    Ripping out an enterprise planning platform creates operational friction and heavy switching costs. Replacing tools that coordinate thousands of store rosters and perishable stock orders takes months of procurement, technical integration and staff retraining.

    The Shift in Retail Procurement

    Work began as a standard productivity initiative while grocery chains accelerated automation to curb operating costs. Palantir’s historical ties to intelligence agencies, US immigration enforcement and foreign defence contracts turned routine back-office optimization into an active brand problem.

    A replacement tender and full system migration across the 840 supermarkets must now wrap up before the contract concludes at the end of 2027.

  • Danone Launches YoPro High-Protein Yoghurt in New Zealand

    Danone Launches YoPro High-Protein Yoghurt in New Zealand

    Danone launched its high-protein yoghurt brand YoPro in New Zealand in September 2026. The rollout includes 15g and 20g protein formats manufactured at its Victorian processing site.

    An exclusive distribution deal with Foodstuffs North Island places the brand directly into the cooperative’s supermarket network.

    Protein formats and supply lines

    Standard YoPro pots and pouches contain 15g of protein per serve. The concentrated YoPro Perform line offers 20g per serve. Danone formulated both product tiers without added sugar or artificial sweeteners, targeting gym-goers and convenience shoppers seeking functional dairy.

    Supply ships across the Tasman from Danone’s manufacturing facility in Victoria’s Kiewa Valley. Using this established Australian base allows the dairy group to test New Zealand consumer demand without committing capital expenditure to local processing infrastructure.

    The exclusive grocery route

    The arrangement gives Danone immediate shelf space across high-volume banners including Pak’nSave and New World. For Foodstuffs, exclusive rights to an established Australian brand create a temporary point of difference against rival Woolworths New Zealand.

    Exclusivity deals carry operational trade-offs. Danone cuts its addressable market in half by bypassing Woolworths and South Island stores. That places the entire burden of brand adoption on a single cooperative’s promotional schedule.

    Battle for dairy shelf space

    This launch pits Danone against domestic dairy giants where Fonterra and boutique local processors dominate chilled cabinets. High-protein and low-sugar yoghurt has developed into a reliable growth pocket across Asia-Pacific dairy. It pulls consumers away from standard flavoured yoghurts that carry higher sugar loads.

    Danone spent several years building YoPro into a category leader in Australia before expanding the supply chain eastward. That playbook relies on heavy athletic marketing and high protein-to-calorie ratios to defend premium shelf pricing against private-label alternatives.

    Distribution now shifts to in-store execution across North Island supermarket chillers as Foodstuffs completes category resets for the spring retail cycle.

  • Nearly 200 Coles Shareholders Urge Retailer to Act on Plastics

    Nearly 200 Coles Shareholders Urge Retailer to Act on Plastics

    Nearly 200 Coles shareholders urged the company to break its silence over plastic use in September 2026. The demand follows the supermarket chain’s decision to stop selling Antarctic krill oil supplements.

    Rival Woolworths followed suit days later, ending the sale of krill-derived products across its supermarkets.

    Supermarket Giants Drop Antarctic Krill Lines

    Coles confirmed the product exit after conservation group Sea Shepherd spotted several unavailable krill oil items on the grocer’s website. Woolworths then ended all krill supplement sales in its own stores.

    The simultaneous delisting strips high-margin marine dietary lines from both chains. Environmental groups have long scrutinised Antarctic krill harvesting for disrupting Southern Ocean food webs.

    Shareholders Target Packaging Policies

    Investors are now pressing Coles management to address packaging waste and match Woolworths’ commitments. The shareholder group wants firm disclosures on plastic volume metrics alongside specific reduction milestones.

    Coordinated pressure on both supermarket operators accelerates packaging redesign deadlines for regional brand and private-label suppliers. Those unable to cut secondary plastics or adopt circular materials face delisting risks.

    Sourcing Audits Across Australian Aisles

    The sudden krill exit shows how quickly activist campaigns alter Australian retail range planning. RetailNews Asia has tracked similar rapid category exits across fresh produce, seafood and packaging formats in recent trading periods.

    Coles faces its next test when investors look for binding packaging targets and plastic reduction timelines at the upcoming formal shareholder meeting.

  • Funday Natural Sweets and Cotton on Kids Partner on Apparel Range

    Funday Natural Sweets and Cotton on Kids Partner on Apparel Range

    Confectionery brand Funday Natural Sweets has partnered with Australian childrenswear retailer Cotton On Kids in September 2026 to launch a limited-edition apparel collection based on its core product range.

    The apparel run is designed for children aged two to 10 years and sells exclusively through the Cotton On website. Graphic designs across the garments replicate four confectionery variants: Strawberry & Cream, Sour Peach Hearts, Sour Cola, and Fruity Koalas.

    Candy Graphics for Digital Shelves

    Cotton On is keeping the release confined to its online channels rather than distributing inventory across its physical store fleet. Digital exclusivity lowers supply chain overhead for short-run collaborative merchandise while testing customer demand before committing floor space in suburban shopping centres.

    For Funday, the partnership puts grocery-aisle branding into everyday childrenswear. Apparel licensing gives fast-moving consumer goods makers repeated household visibility without requiring an increase in trade marketing expenditure inside supermarkets.

    Brand Collaborations in Childrenswear

    Fashion retailers across Asia-Pacific continue to use branded novelty drops to drive direct web traffic. Cross-category partnerships between food brands and apparel chains have expanded rapidly as fast-fashion operators look for distinctive graphic intellectual property that appeals directly to parents buying for young children.

    The operational risk in food-to-fashion licensing sits squarely on inventory velocity. Themed capsule collections lose consumer appeal quickly once seasonal promotional cycles end, making web-only fulfillment a calculated choice to prevent discounted stock overhang in physical stores.

    Licensing Growth in Apparel

    Cotton On has built a steady business model around limited licensing deals across its adult and youth divisions, drawing on entertainment properties, beverage brands, and food labels to refresh basic garment blanks.

    Online performance data from this initial confectionery run will determine whether Cotton On expands the licensed grocery range into retail stores across Australia and its broader Asia-Pacific store network.

  • Australian Retail Health Index Drops to Negative 1.07 as Insolvencies Rise

    Australian Retail Health Index Drops to Negative 1.07 as Insolvencies Rise

    Australian retail conditions worsened sharply in the three months ending June 2026, dragging KPMG’s Retail Health Index down to negative 1.07 from negative 0.37 in the previous quarter.

    A steep 11.4 per cent drop in consumer sentiment drove the decline, even as total household spending and producer prices recorded modest gains.

    Pressures on cash flow and demand led to 254 retail insolvencies during the three-month period. Employers pulled back hiring across store networks, cutting job vacancies by 15.3 per cent to leave 26,000 open roles across the country. The index measures spending, sentiment, turnover, pricing and underlying business performance to gauge sector viability.

    Value Hunting Alters Store Economics

    Shoppers across Australia have shifted their habits toward planned, price-sensitive purchases rather than halting expenditure entirely. Foot traffic and checkout totals increasingly concentrate around major promotional windows such as End of Financial Year sales, thinning margins for operators between events.

    For regional retail groups and brand distributors, this concentration creates sharp operational volatility. Inventory holding costs rise between discount periods, while staffing models must flex quickly to handle brief spikes in transaction volume without blowing out payroll costs.

    Digital Channels and Labour Adjustments

    Suppliers face renegotiations on wholesale terms as storefront operators fight to protect gross margins against higher input costs. Landlords in secondary shopping centres risk longer lease negotiations, particularly where specialty fashion and discretionary merchants struggle to sustain standard rent-to-sales ratios.

    The contraction follows a prolonged period of cautious buying that started when higher borrowing costs began constraining disposable income across major metropolitan centres. Earlier quarters had managed to absorb rising operational overheads through modest price adjustments, but consumer pushback against shelf prices has now limited further retail pass-through.

    Promotional Execution Takes Centre Stage

    Relief for the sector depends heavily on whether lower supply chain disruptions and sustained population growth can offset cautious household budgets. Retailers are directing investment into automated personalisation and inventory tracking systems to lift conversion rates ahead of high-volume seasonal trading.

    Merchant performance across the market now hinges on order execution during the upcoming Black Friday and Cyber Monday discounting calendar.

  • Virtue Mirage Launches 17-Tool Fashion Personalisation Platform

    Virtue Mirage Launches 17-Tool Fashion Personalisation Platform

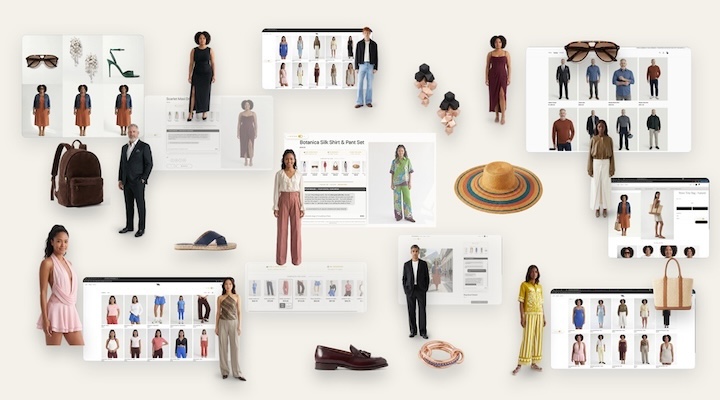
    Australian entrepreneur Lukas Cervenan launched Virtue Mirage in September 2026, introducing a hyper-personalisation platform designed to reshape the online fashion shopping experience.

    The system offers 17 tools that create a digital twin of a shopper using photos or exact measurements, extending personalisation across entire online stores rather than limiting it to individual products.

    By replacing traditional model imagery across every product gallery, the platform allows shoppers to see garments on their real body sizes across participating stores running on services such as Shopify and BigCommerce.

    How the Network Functions

    Shoppers manage their profiles through a central dashboard that stores saved outfits, real-time stock availability, and tailored size advisories for specific garments. A semantic search engine pairs items across a merchant’s inventory directly onto the user’s avatar, rather than displaying isolated product grids. New inventory drops can be pre-rendered for registered customer profiles before users land on the store page.

    To our knowledge, we are the only platform in the world that is transforming entire websites. So a size-16 shopper is never looking at a professional size-6 model; she sees her real size, on her real body, in every image across a brand’s entire store.

    The Return Problem Across Regional Fashion

    Retail margins across Asia-Pacific e-commerce continue to erode under the weight of reverse logistics. Fit failures drive the bulk of fashion returns, worsened by bracket-buying habits where shoppers purchase several sizes of a single item with the intention of returning most of them. Eliminating the disconnect between model proportions and real customer bodies attacks reverse logistics costs at the point of discovery.

    Standalone virtual fitting widgets rarely alter overall conversion because they sit isolated on individual product detail pages. By transforming whole catalogues into personalised galleries, operators attempt to lift checkout completion while defending independent web stores against dominant regional marketplaces like Shein and Zalora. The primary technical hurdle remains rendering fidelity, as artificial intelligence tools frequently struggle with drape and textile weight across edge sizes.

    Decade of Commercial Imaging Preceded Launch

    The platform builds directly on Cervenan’s commercial imaging business, Virtue Creative Studios, which produced e-commerce and campaign photo shoots for more than 500 apparel brands over the past ten years. That production background informed the platform’s visual architecture, which formats store catalogs to allow external AI shopping agents and semantic web scrapers to parse inventory data directly.

    Participating merchants on Shopify and BigCommerce are now integrating the software into their live storefronts ahead of peak year-end trading cycles.

  • GetUp Targets Hundreds of Coles Stores over Palantir AI Deal

    GetUp Targets Hundreds of Coles Stores over Palantir AI Deal

    Community advocacy group GetUp targeted hundreds of Coles stores across Australia with spoof digital billboards, challenging the supermarket operator over its enterprise partnership with US analytics vendor Palantir. The advertisements ran outside store entrances in July, mimicking the retailer’s signature red and white branding with the slogan: “Here at Coles, we’re always watching you.”

    The pushback followed Coles deploying software from the controversial US technology company to sharpen artificial intelligence and operational efficiency across its supermarket network. While the digital billboards were taken down quickly, the campaign triggered public debate over how large grocery chains handle customer data and explain tracking tools to shoppers.

    Public Scrutiny Over Store Analytics

    Supermarket operators across the Asia-Pacific region have accelerated investments in predictive analytics, automated inventory forecasting, and computer vision systems. Enterprise partnerships with overseas defence and intelligence contractors carry brand risks that standard retail IT upgrades do not. Consumer groups increasingly scrutinise the boundary between back-end supply chain optimisation and customer-facing surveillance.

    For grocery chains operating in concentrated retail markets, transparency around data architecture has become an operational necessity rather than an investor relations footnote. When retailers fail to define where data processing stops, third-party advocacy groups easily fill the information vacuum with negative messaging right at the store entrance.

    Retail AI Strategy Under Pressure

    The dispute reflects broader friction across Australian retail as grocers test advanced algorithmic tools to cut shrink and streamline operations. Coles had framed its AI rollout as an efficiency play, intended to modernise store workflows and stock management across its national footprint. Linking store-level operations to specialised analytics vendors has instead tested customer goodwill at a time of heightened consumer sensitivity around commercial data collection.

    Grocers managing similar automation rollouts across regional markets now face tighter questions regarding data sovereignty, third-party software governance, and in-store customer communications. Retailers will need to clarify operational boundaries as advocacy campaigns continue tracking corporate technology procurements.