Tag: E-Commerce

  • Ant International Deploys AI Agents Across 1.5 Billion-Account Network

    Ant International Deploys AI Agents Across 1.5 Billion-Account Network

    Ant International is deploying artificial intelligence agents across its global merchant acquiring network this quarter to automate cross-border payments and digital commerce workflows.

    Based in Singapore, the fintech arm of Ant Group processes transactions across dozens of partner e-wallets. Together, those wallets serve over 1.5 billion consumer accounts worldwide.

    Automating Cross-Border Commerce

    Autonomous AI systems are being integrated directly into merchant settlement channels and checkout interfaces. These software agents handle currency conversions, fraud monitoring and automated order reconciliation without manual intervention. Ant International is embedding the technology into its Alipay+ cross-border payment platform and WorldFirst business account solutions.

    Engineering teams in Singapore and Hangzhou designed the architecture. It allows software agents to execute transactions autonomously based on predetermined consumer and merchant parameters.

    The Regional Shift to Agentic Commerce

    Competition is heating up. Ant International is racing regional rivals to capture merchant transaction fees as generative artificial intelligence moves from text prompts to autonomous execution. Competing operators including Grab, Tencent and regional banking groups are testing similar machine-to-machine checkout models across Southeast Asia. The shift aims to lower settlement dispute rates and cut conversion friction for cross-border retailers selling to outbound travelers and digital buyers.

    For independent merchants, autonomous agent integration lowers payment handling overheads across multi-currency checkouts. Verification protocols remain the primary operational risk. Unauthorized autonomous agent decisions can trigger false approvals or dispute liabilities across fragmented regulatory jurisdictions.

    Building Beyond Traditional QR Networks

    Merchant acceptance under Alipay+ recently passed 90 million points of sale across travel hubs in Japan, South Korea, Europe and Southeast Asia. That network previously relied on consumer-initiated QR code scans to route local e-wallet transactions across national borders.

    Commercial deployment across enterprise merchant accounts begins later this quarter. Cross-border clearing metrics are due in the group’s next operational update.
  • Herbalgy Launches 27-Year Campaign in Hong Kong with Keung To

    Herbalgy Launches 27-Year Campaign in Hong Kong with Keung To

    Hong Kong topical pain relief maker Herbalgy Pharmaceutical launched an anniversary retail push on September 16. The promotion features 27 per cent discounts and tiered basket incentives on its direct-to-consumer online store.

    The campaign pairs the brand’s 27th year in business with Hong Kong pop idol Keung To. The singer turns 27 this year.

    Discounts and High-Ticket Spend Tiers

    Shoppers face three volume incentives on the brand’s website. A one-day flash sale cut prices by 27 per cent across the catalogue on September 16. A month-long gift promotion runs through October 15. That offer gives customers an exclusive Keung To merchandise gift on net purchases of HK$430 or more.

    To lift order values among regular buyers, the company added an upper tier requiring a single net spend of HK$2,700. Reaching that threshold yields 27 units of 5 ml portable pain relief products.

    The Direct-to-Consumer Push for Traditional Formulations

    Traditional Chinese medicine makers across Hong Kong face steady pressure to turn pharmacy foot traffic into direct digital accounts. Medicated oils and plasters rely heavily on neighborhood dispensaries. In those physical shops, distributor fees and shelf rental costs squeeze profit margins.

    By partnering with a celebrity ambassador, Herbalgy aims to bypass retail intermediaries and secure higher gross margins. Retaining those buyers after discounts expire remains the central commercial risk. That challenge grows when asking shoppers to spend HK$2,700 on everyday topical remedies.

    Roots in Hong Kong Manufacturing

    Chinese medicine practitioner Professor Wong Tin Chee founded Herbalgy in 1999. He built the business on formulas created by his father, medicated oil producer Wong To Yick. Wong set up a Good Manufacturing Practice facility in Hong Kong to make registered proprietary Chinese medicines, later adding brands such as Touch Cool and Tibet Red.

    Digital sales and the Keung To gift promotion continue on Herbalgy’s official storefront through October 15, 2026.

  • Vevor Plans First European Store in France for 2027 Following Berlin Debut

    Vevor Plans First European Store in France for 2027 Following Berlin Debut

    Cross-border hardware brand VEVOR will open its first European brick-and-mortar store in France in 2027. A regional network of 22 distribution warehouses will support the site.

    That launch follows the brand’s five-day show at the IFA trade show in Berlin. There, the company presented 20 product lines spanning tools, kitchen equipment and outdoor gear.

    VEVOR currently distributes roughly 15,000 stock keeping units to European buyers through direct storefront sales and third-party marketplaces. The planned French site is its second physical retail location globally. Its first was a 32,000-square-foot flagship store in Houston, Texas, opened in March 2026.

    Shifting from Pure Marketplace to Physical Aisles

    Asian export brands are shifting strategies across European real estate. Pure digital distribution on Amazon and domestic marketplaces delivers fast volume. However, it exposes merchants to rising ad costs, platform commissions and counterfeit disputes. Dedicated storefronts give hardware sellers direct control over their branding. These sites also double as service centers, lowering the high return rates typical of heavy workshop machinery.

    Established European tool retailers now face tighter margins. Direct-to-consumer suppliers from China previously competed only on price through parcel delivery. Now, factory-direct brands pair local inventory with walk-in repair desks and showroom displays. That approach eats into the after-sales edge long held by traditional DIY chains.

    Building Out the Western Logistics Footprint

    Warehouse expansion across Western consumer markets underpins the European store rollout. VEVOR operates more than 200 fulfillment hubs worldwide. In total, the business supplies equipment to roughly 30 million households across 50 countries.

    “Our first European store in France opening next year will be an important next step in our long-term growth in the region,” said Shirley Liu, Head of E-commerce at VEVOR Europe.

    Company officials are finalizing site selection and store dimensions in France ahead of the 2027 opening.

  • NFL Australia Fixture Drives 400 per Cent Surge in Online Merchandise Traffic

    NFL Australia Fixture Drives 400 per Cent Surge in Online Merchandise Traffic

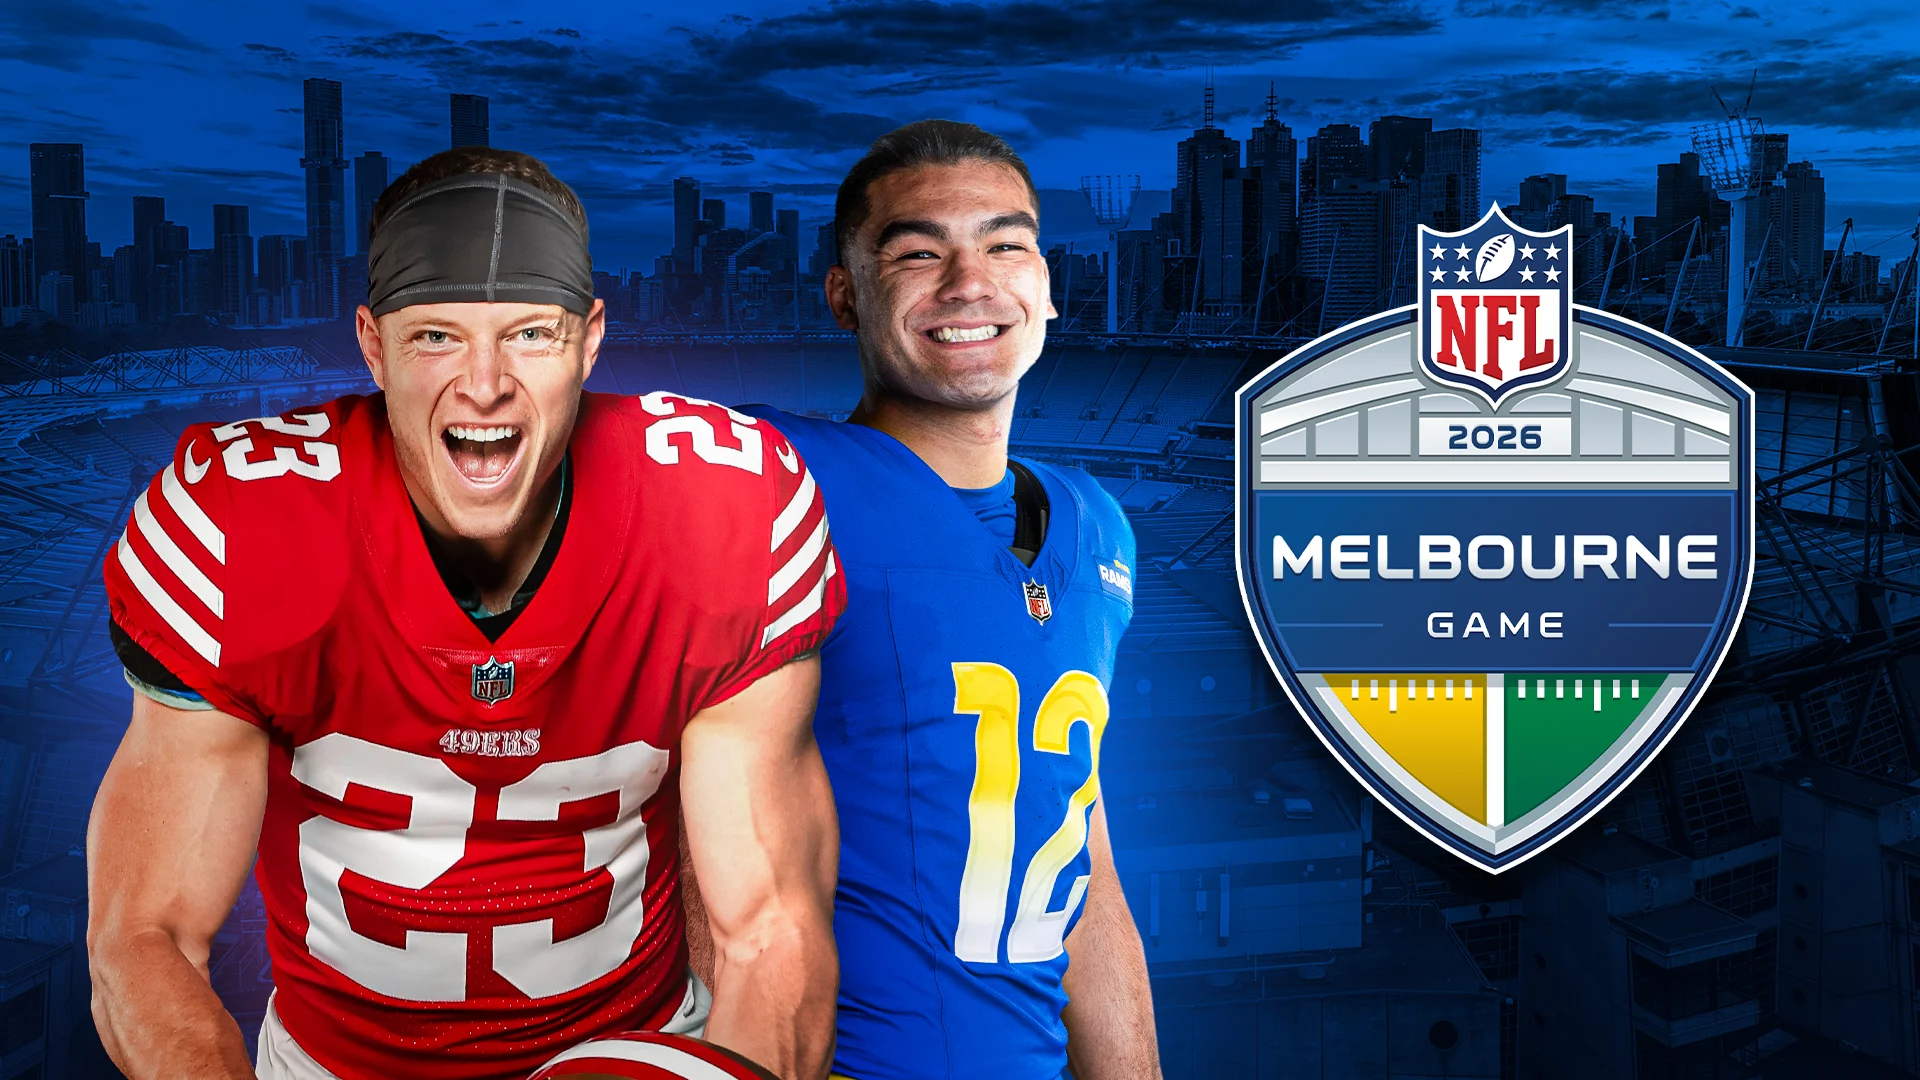
    Online traffic for National Football League merchandise surged roughly 400 per cent in Australia during the month before Melbourne’s inaugural regular-season game.

    More than 100,000 spectators attended the fixture between the Los Angeles Rams and the San Francisco 49ers at the Melbourne Cricket Ground. That capped a week of commercial activations across the city.

    Merchandise demand and consumer spending spikes

    Digital traffic for NFL gear was already running 310 per cent above baseline levels across the twelve months ending in August, according to data from Adobe. Sponsors hold high expectations. Adobe found 72 per cent of brands investing in the Melbourne fixture anticipate a 1.5-times return on spend. Another 30 per cent expect to double their outlay.

    Local spending patterns mirrored established habits. Carly Lynch, principal strategist of retail, media and travel at Adobe’s digital strategy group for Asia-Pacific, noted that 79 per cent of Australian households buy goods tied to major Australian Football League finals. During similar sporting windows, spending on streaming hardware jumps 74 per cent as consumers upgrade home setups.

    The commercial stakes for regional retailers

    For electronics retailers and licensed apparel distributors, foreign sports codes create a revenue window outside the traditional domestic footy calendar. Department stores and specialty chains face sharp demand spikes. These require precise inventory timing rather than prolonged shelf space. The immediate payoff sits with official merchandise and home viewing tech, leaving general retailers with minimal spillover.

    Buying teams face real risks if they overcommit stock beyond headline event weeks. Domestic leagues offer six months of consistent weekend matches. In contrast, overseas touring properties generate intense, narrow purchasing bursts that drop quickly once teams leave.

    A four-year runway in Victoria

    The Melbourne match is the first stage of an agreement between the league and the Victorian Government to host three games across four years. It follows a sustained effort by NFL Australia to build fan engagement and retail tie-ins before bringing full-scale games to the region.

    Charlotte Offord, general manager of NFL Australia and New Zealand, now targets a permanent annual fixture at the MCG under future scheduling arrangements.

  • TikTok Shop U.S. Gross Merchandise Value Hits $15.1B

    TikTok Shop U.S. Gross Merchandise Value Hits $15.1B

    TikTok Shop generated US$15.1 billion in gross merchandise value across the United States in 2025, up 68 per cent from the previous year, according to data from Momentum Works.

    The expansion established the platform as a major cross-border sales channel for Chinese manufacturers and domestic sellers, defying regulatory pressure and intense competition from Amazon and Temu. ByteDance built the platform by merging creator live streams and algorithmic product discovery into a direct checkout experience that bypasses traditional search-based retail.

    Expanding Across Core Retail Categories

    Fashion, beauty, and consumer electronics drove the bulk of U.S. Order volumes through short-form video links and creator storefronts. Lower take rates and subsidized shipping helped recruit thousands of merchants who previously depended solely on Amazon Seller Central.

    Supply chain infrastructure handled larger fulfillment runs through partnered logistics networks in California and Texas. The platform shortened delivery windows for local inventory while maintaining discounted direct air-freight routes from hubs in Shenzhen and Yiwu.

    The Content Commerce Blueprint in Asia

    ByteDance perfected this shopping model across Southeast Asia before scaling it westward. Regional content commerce across Southeast Asian markets is on track to reach US$77.9 billion in 2026 as Shopee and Lazada roll out competing live video formats.

    In Indonesia, Vietnam, and Thailand, social video transactions now account for a double-digit share of total online retail spending. Regional logistics networks adjusted their sorting hubs to manage high-volume, low-ticket parcels generated during evening live stream flash sales.

    Competition and Regulatory Targets

    Temu, operated by PDD Holdings, continues to fight for identical budget-conscious consumer dollars with aggressive discount coupons and gamified referrals. Meanwhile, Sea Limited’s Shopee invested heavily in creator incentives across Southeast Asia to defend its core market leadership against ByteDance.

    Merchants face rising advertising costs on the platform as competition for feed placement stiffens. RetailNews Asia tracks whether TikTok Shop can maintain its merchant retention rates through the 2026 holiday shopping cycle while targeting US$20 billion in North American sales.

  • China Aims for $8.94 Trillion in Retail Sales as Price Wars Persist

    China Aims for $8.94 Trillion in Retail Sales as Price Wars Persist

    China’s physical retailers are retooling floor space into leisure and entertainment hubs to counter entrenched price competition as Beijing targets $8.94 trillion in annual consumer sales by 2030.

    First-half retail sales reached $3.7 trillion, but Bain & Company partner Weiwen Han warns the market will stay muted over the next three years as discounting continues to squeeze operating margins across shopping centres and supermarket chains.

    Experience Costs and Margin Pressures

    Official policy guidelines urge store operators to blend standard shopping with immersive dining, social spaces, and entertainment. The strategy shifts the industry away from chasing raw foot traffic toward extracting higher margins from shoppers who do enter. Transforming selling space into experience zones raises the fixed cost per square metre, penalising operators whose foot traffic fails to convert at the cash register.

    The policy combines experience-led flagships in commercial districts and transit hubs with neighbourhood infrastructure upgrades dubbed 15-minute life circles. These local clusters focus on daily essentials through convenience stores, supermarkets, and wet markets.

    Digital Convergence and Supply Chains

    Pure physical retail has ceased to exist in the Chinese market. With online sales of physical goods rising 4.8 per cent year to date compared to 1.3 per cent growth for total retail sales, shoppers routinely compare shelf prices against live e-commerce listings on their phones within seconds.

    Instead of trying to defeat digital platforms on pricing, operators are adopting automated inventory systems, drone delivery, and private-label merchandise. Developing proprietary private-label lines allows chains to offer price value directly without slashing headline gross margins on national brands.

    “They are asking stores to be worth visiting for reasons beyond price,” said Jotham Lim, head of global marketing at Beijing Taomi Technology Co. Ltd.

    Winners and Structural Consolidation

    Mid-sized domestic grocery, convenience, and food and beverage operators stand to gain the most from planned regional deregulation, which removes long-standing barriers preventing chain retailers from expanding across provincial borders. Independent single-store merchants face steep hurdles absorbing the capital expenditure required for digital traceability and store fit-outs, accelerating industry consolidation into regional chains.

    Financing rules now allow qualifying retail operators to raise capital through asset-backed securities and commercial real estate investment trusts, alongside interest subsidies from commercial banks. Landlords and property-owning retailers can tap these vehicles to fund store refits without burning operating cash flow.

    The retail sector entered this transition carrying heavy overcapacity in commercial floor space following decades of rapid mall construction across second- and third-tier cities. Moojing Market Intelligence recorded a steady increase in consumer discussions regarding in-store price checking against e-commerce platforms between the first half of 2024 and the first half of 2026.

    Market operators now face the rollout of regional licensing reforms and the government target to lift retail sales from ¥24.87 trillion to ¥60 trillion over the next four years.

  • Oksana Stakhovych Launches Mia Coosh in Australia’s $22 Billion Pet Market

    Oksana Stakhovych Launches Mia Coosh in Australia’s $22 Billion Pet Market

    Melbourne founder Oksana Stakhovych launched Mia Coosh in October 2025, targeting Australia’s $22 billion pet industry with vegan microfibre leather accessories.

    Stakhovych created the brand to challenge mass-market pet accessories that typically rely on standard nylon webbing, plastic buckles, and bovine leather.

    Designing for Premium Pet Owners

    Stakhovych spent more than a year prototyping the range before going live, testing hardware weight, strap placement, and fit on small and medium dog breeds across parks, beaches, and varied weather conditions.

    Her background spans e-commerce, online retail operations, and business administration. That operational experience shaped the fulfilment setup, customer service protocols, and digital storefront ahead of launch.

    Animals should not wear animals. At the same time, I did not want to compromise on quality.

    Microfibre leather replaced animal hides to keep the gear lightweight, water-resistant, and durable for everyday urban use.

    The Direct-to-Consumer Model in Australia

    Australia ranks among the highest pet-ownership markets in the Asia-Pacific region. High ownership rates drive premium spending across food, healthcare, and lifestyle accessories. Specialty pet chains and supermarkets dominate staple goods, but higher-margin accessories increasingly sell through independent digital channels.

    Mia Coosh bypasses wholesale middlemen to capture full retail margins on its smaller initial production runs. Competing against established global pet lifestyle brands requires tight control over unit economics and paid customer acquisition costs.

    Embedded Charity Allocations

    A permanent revenue share is built directly into transaction processing. A fixed portion of every customer purchase goes to registered Australian animal rescue organisations to fund rehabilitation and rehoming work.

    Setting up the donation mechanism at checkout replaces periodic promotional campaigns. The structure integrates charitable allocations into baseline cost of goods sold from the initial operating date.

    Expanding the Sizing Line

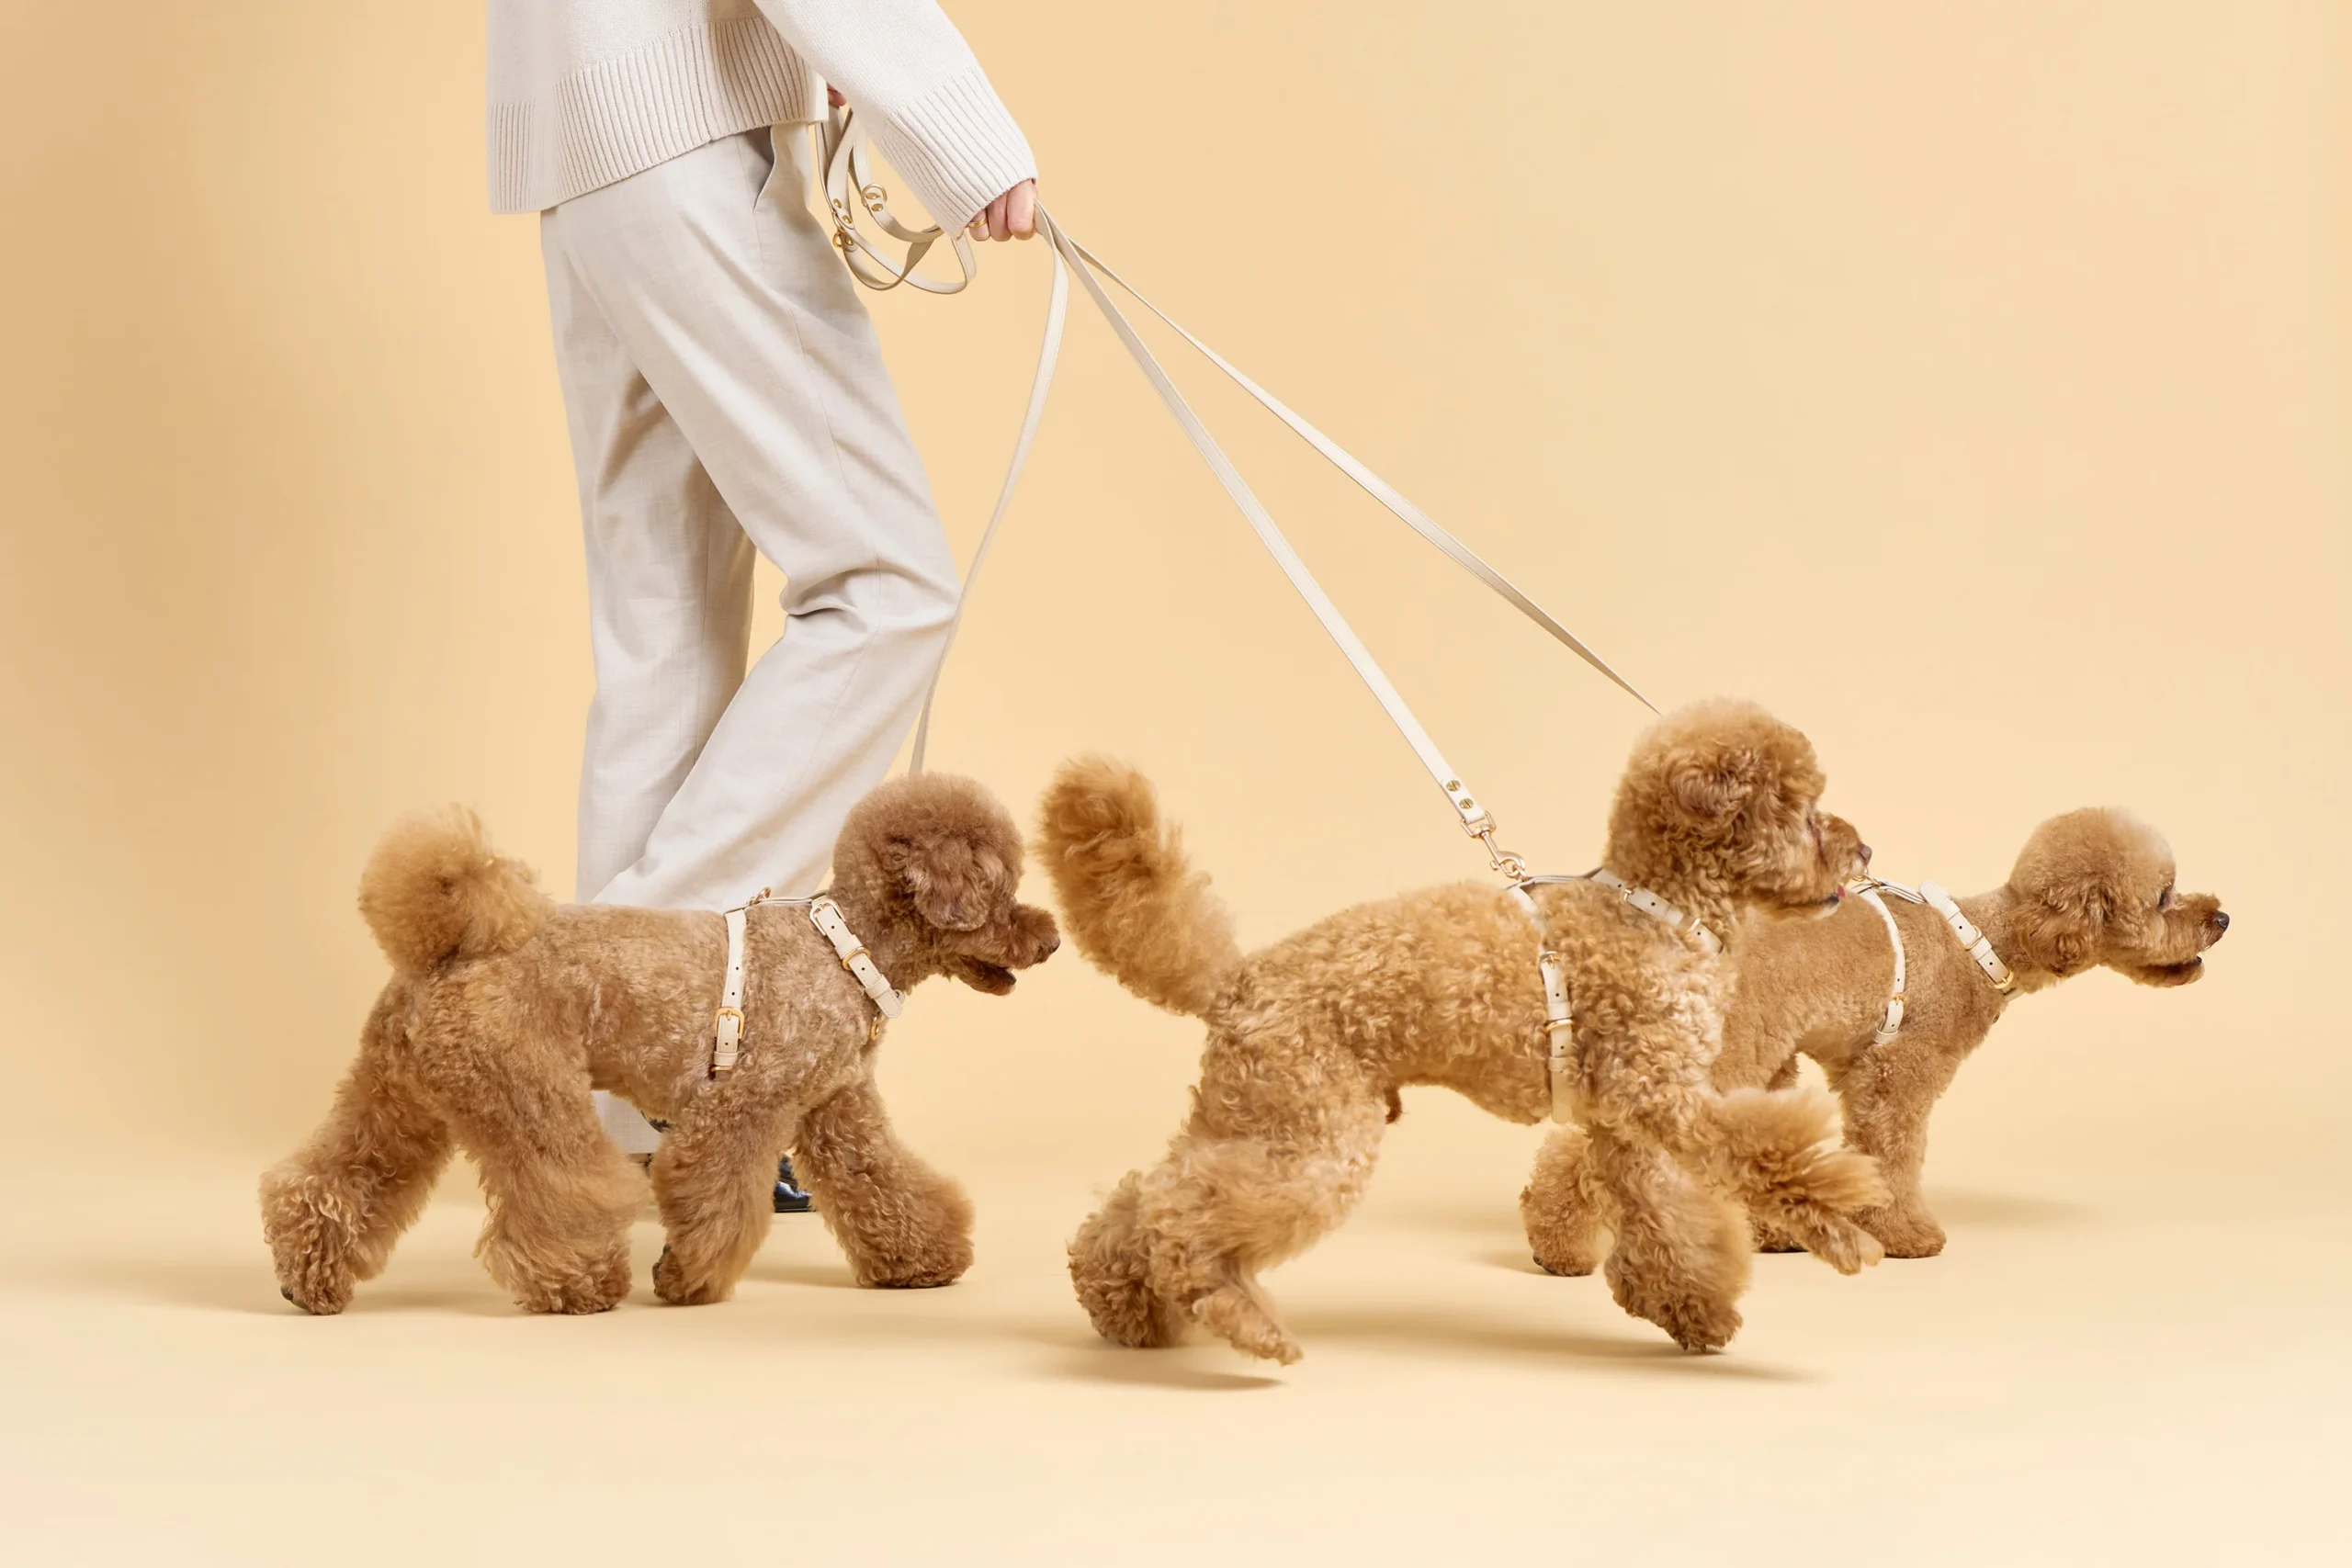
    The venture originated in October 2025 after trials on Stakhovych’s toy poodle revealed a lack of ergonomic, lightweight harnesses for smaller dogs. Development work throughout 2024 centered on refining buckle hardware and strap proportions before committing to manufacturing runs.

    Mia Coosh is monitoring order volume across Australian capital cities while evaluating broader accessory lines and additional dog sizing tiers for subsequent inventory cycles.

  • Tara McKeon Regains Control of Proud Poppy Across 3 Remaining Stores

    Tara McKeon Regains Control of Proud Poppy Across 3 Remaining Stores

    Proud Poppy founder Tara McKeon has regained control of the womenswear brand after creditors voted this week to approve a Deed of Company Arrangement.

    Creditors from Hall Chadwick voted to allow McKeon to continue owning and operating the business, following an initial creditors’ meeting held on August 17.

    Founded in 2019, Proud Poppy once operated seven standalone stores and will now trade online alongside three remaining retail locations.

    Downsizing The Store Network

    The approved arrangement formalises a sharp reduction in physical retail overhead. Proud Poppy built its initial scale around inclusive sizing ranging from Australian sizes six to 30, expanding quickly into standalone shopping locations before rising operational costs and softened apparel spending squeezed cash flow.

    By trimming four locations prior to and during the statutory process, management reduced fixed lease liabilities to protect inventory purchases. The remaining three doors now serve as localized collection points and brand touchpoints rather than a high-cost national footprint.

    “It feels very meaningful that each creditor voted to return the business to me. I want to especially acknowledge our staff and our suppliers. I know the level of support we have been shown is rare, and we do not take it for granted,” McKeon said.

    Pressure Across Mid-Market Apparel

    Australian independent fashion labels face persistent margin compression as commercial rents, freight charges, and digital customer acquisition costs stay high. For operators in the mid-market segment, maintaining extensive store networks without institutional equity backing has proven unsustainable under volatile consumer demand.

    Passing a deed of company arrangement offers a rare path back to solvency without an outright trade sale or asset liquidation. The risk shifts directly to working capital management, where trimmed product ranges must generate enough cash to settle legacy claims under the agreed deed timetable.

    Earlier Footprint And Next Milestones

    Established in 2019, Proud Poppy expanded its inclusive-size model over five years before cash strain forced management to close multiple locations and trim its garment range in mid-2026. McKeon placed the company into voluntary administration in early August to halt creditor actions and assemble a compromise package.

    Trading continues uninterrupted across the digital store and the three surviving physical doors as administrators finalize the formal execution of the deed.

  • India’s Fraud Agency Recommends Detailed Probe into Xiaomi

    India’s Fraud Agency Recommends Detailed Probe into Xiaomi

    India’s Serious Fraud Investigation Office has recommended a full probe into Xiaomi over alleged foreign investment breaches and fund transfers. The inquiry intensifies pressure on the Chinese phone maker.

    The Beijing-based company has seen its local market share fall from 19 per cent to 13 per cent. Its India revenue dropped 40 per cent over three years to $2.52 billion in 2025.

    A draft memorandum prepared by the SFIO in May recommends examining fund movements. It asks investigators to verify whether Xiaomi Technology India Private Limited and its affiliated entities secured mandatory government approvals. The document also calls for a review of foreign investor and parent group beneficial ownership to confirm whether changes in corporate control were declared.

    Investigators also proposed testing financial statements and auditor reports filed with the Indian government for material misstatement. They seek authority to record formal statements from current and former directors, chief financial officers, and compliance leads under a 21-point investigative framework.

    The Squeeze on Online Distribution

    This proposed probe places Xiaomi’s core sales model under fresh scrutiny. The brand built its early dominance in India on flash sales hosted on Amazon and Walmart-owned Flipkart. Offline shopkeepers have long argued that those arrangements violate foreign direct investment rules by giving preferential terms to selected online merchants.

    Under the proposal, the SFIO instructs investigators to determine whether Xiaomi exercised de facto control over Indian retail sellers and launch partners while presenting them as independent businesses. Any formal finding against these distribution structures would force hardware vendors across the region to rework online retail partnerships, raising distribution costs and limiting promotional pricing flexibility.

    Rivals Gain Ground as Legal Pressure Mounts

    Regulatory scrutiny is accelerating a commercial shift across India’s handset market. Samsung and Apple have captured premium and mid-tier demand as legal battles occupy management attention. Xiaomi has now dropped to fourth place in national shipments.

    Suppliers and channel partners face uncertainty around contract terms and inventory financing. For cross-border consumer brands operating in India, the agency’s focus on ultimate beneficial ownership signals that holding company layers and offshore licensing pacts face direct exposure.

    Unresolved Assets and Stalled Clearances

    Tensions between New Delhi and Chinese consumer brands have built since 2020 border clashes prompted tighter screening of Chinese capital. Xiaomi has already failed to overturn a separate 55.51 billion rupee ($584 million) bank asset freeze imposed by India’s financial crime agency in 2022 over contested royalty transfers.

    The corporate affairs ministry must now decide whether to authorise the probe, reject it, or refer specific points to other enforcement agencies. The ministerial review carries no statutory deadline, leaving the 21-point inquiry pending as officials assess the file.

  • Unresolved Scams Hit 45% Across Southeast Asia as Losses Mount

    Unresolved Scams Hit 45% Across Southeast Asia as Losses Mount

    Nearly half of all reported scam cases across Southeast Asia remain unresolved, leaving consumers without financial recovery and triggering account churn for digital service providers. Research from the GSMA released in Kuala Lumpur shows 82 per cent of victims who lost money recouped nothing, while only 10 per cent recovered their funds in full.

    The findings, drawn from the GSMA ASEAN Consumer Scam Report 2026, cover Indonesia, Malaysia, the Philippines, Singapore, Thailand and Vietnam. Across these six economies, eight per cent of surveyed consumers fell victim to scams during the previous 12 months. When fraud occurred, 68 per cent of targets suffered direct monetary losses.

    Financial Losses and Platform Churn

    Unresolved fraud is creating direct commercial consequences for digital operators. Consumers who suffered a scam incident were more than twice as likely to switch accounts or abandon service providers compared to unaffected users. The research revealed that 96 per cent of consumers in the region actively worry about fraud and unauthorized account breaches.

    For consumer brands, e-commerce marketplaces and digital banks, this churn represents an unbudgeted retention cost. When fraud dispute mechanisms fail, the merchant or carrier bears the brand damage, regardless of where the vulnerability originated. Retailers relying on app-based checkouts and instant digital payments face the immediate threat of shoppers retreating to cash on delivery or narrowing their transaction volumes.

    Network operators face a parallel squeeze on connectivity revenue. As subscribers associate incoming communications with financial danger, answer rates collapse and push marketing loses value. The commercial risk sits with consumer-facing platforms that fail to isolate malicious actors before transactions clear.

    Access alone is no longer enough. As ASEAN’s digital economies become more sophisticated, people must have confidence that digital services are secure, reliable and accountable.

    Messaging Apps Drive Fraud Encounters

    Messaging applications now serve as the primary channel for fraudulent outreach in Southeast Asia, accounting for 41 per cent of all recorded scam interactions. Fraud patterns have shifted away from crude automated calls toward targeted investment schemes, cryptocurrency pitches, bogus job offers and fake online shopping storefronts where victims transfer funds voluntarily.

    Artificial intelligence tools are accelerating these schemes. Nearly nine in ten surveyed consumers recognized at least one form of AI deployed in fraudulent attempts, ranging from deepfake media and voice cloning to automated phishing scripts. While 69 per cent of affected individuals reported the incidents to authorities or service providers, 45 per cent of those complaints concluded without resolution.

    A companion report, Digital Nations 2026: Building Trusted Digital Ecosystems in ASEAN, identifies four structural requirements to counter the surge: identity verification, authenticated communications, resilient network infrastructure and shared fraud intelligence across commercial borders.

    Cross-Border Identity Enforcement

    The spike in digital deception follows five years of rapid mobile wallet adoption and instant payment integration across ASEAN member states. National real-time payment links between Singapore, Malaysia, Thailand and Indonesia lowered transaction frictions for commerce, but also allowed illicit funds to move faster across jurisdictions before local compliance teams could freeze beneficiary accounts.

    Industry discussions on unified digital identity frameworks and mandatory scam reimbursement guidelines continue on September 10 at the M360 ASEAN summit. Delegates will review regional enforcement strategies during sessions with Malaysian Minister of Communications Fahmi Fadzil, ASEAN Secretary-General Kao Kim Hourn, and GSMA Director General Vivek Badrinath.

  • Over 60 per Cent of Black Friday Shoppers Pre-Plan Holiday Purchases

    Over 60 per Cent of Black Friday Shoppers Pre-Plan Holiday Purchases

    Australian retailers face a structural shift in holiday spending as 57 per cent of shoppers concentrate gift purchases in November after pre-selecting brands in October.

    Data compiled by market research agency Retail Safari and consultancy PwC shows 64 per cent of holiday budgets remain unspent entering November, even as buyers finalise purchase shortlists weeks earlier. Black Friday alone now captures 55 per cent of holiday shoppers, turning the discount window into an execution phase rather than a discovery channel.

    The Split Between Early Planning and Peak Spending

    Consumer research from Mintel indicates more than six in ten Black Friday shoppers choose their target products before promotional events begin. Shoppers use September and October to compare specifications, check customer reviews and track merchant pricing before committing funds. In Australia, research from the Australian Retailers Association and Roy Morgan showed 29 per cent of consumers started browsing earlier in 2025 than the previous year, while only 8 per cent started later.

    The US-based National Retail Federation recorded an identical baseline, with roughly 40 per cent of consumers starting holiday research before November. Shoppers cite three main drivers: managing household budgets over time, avoiding store congestion, and eliminating late delivery risks.

    Big-Ticket Sales Diverge From Headline Retail Growth

    Official figures mask underlying pressure across discretionary categories. Australian Bureau of Statistics data analyzed by investment research firm MST Marquee placed July retail turnover growth at 6.6 per cent year on year, running above the 4.9 per cent historical average. Food services rose 9.3 per cent and clothing gained 7.1 per cent, but major durable goods operators failed to capture that momentum.

    First-quarter trading updates reflect the divide. Online furniture seller Temple & Webster reported sales down 13 per cent across its first seven weeks, department store operator Myer posted a 4 per cent decline, and Accent Group recorded a 2 per cent like-for-like drop. Electronics chain JB Hi-Fi saw comparable sales slip 1.4 per cent, while its home appliance unit The Good Guys declined 1.7 per cent and furniture retailer Nick Scali tracked flat from July 1.

    Household Wealth Pressures Shorten Brand Lists

    For store operators and suppliers, the divergence means consumers are buying smaller items frequently while delaying expensive, considered purchases until deep discounting begins. Retailers that spend their marketing budgets solely on late November discounts risk losing shoppers who eliminated unfamiliar brands during the October evaluation window. Merchant margins face compounding pressure if price cuts merely settle competition among pre-selected names rather than bringing in new foot traffic.

    The shift follows a broader contraction in gift-buying participation. ARA and Roy Morgan figures showed 68 per cent of Australian adults planned holiday gift purchases last year, down 9 per cent from 2024, while average spend per remaining buyer climbed 7.1 per cent to A$757.

    MST Marquee projects household goods demand will soften further through the fourth quarter as property price weakness and potential interest rate hikes from the Reserve Bank of Australia curb discretionary outlays.

  • Australian Retailers Overhaul Content Models to Curb Omnichannel Delays

    Australian Retailers Overhaul Content Models to Curb Omnichannel Delays

    Australian retailers have spent years adding digital touchpoints, but many are now getting slower at producing the experiences those platforms require as teams contend with cautious consumers and margin pressure. The operational challenge has mounted as websites, apps, marketplaces, loyalty programs, social commerce, and digital signage expand alongside physical stores.

    In many retail businesses, marketing teams and developers repeat work by building one version of a product launch for the website, another for the app, and separate material for email, social channels, and in-store displays. This fragmented production process leaves campaigns reaching one channel days after another while increasing the likelihood of inconsistent pricing and outdated product details.

    Ending Repetitive Channel Production

    When turning a single campaign into live assets requires weeks of handovers and developer queues, retail teams lose the capacity to personalize experiences or adapt to local trading conditions. To eliminate duplicated effort and lower costs, businesses are shifting toward composable models where product benefits, imagery, and promotional messages are created once and governed centrally.

    The alternative infrastructure treats product details, pricing banners, promotional terms, and media files as reusable modular components. Central governance teams control core brand messaging and product claims, while regional managers assemble approved components into distinct channel formats without writing custom code or rebuilding entire digital pages.

    Regional Adaptation and Guardrails

    For retail networks spanning diverse state territories and multiple brand banners, modular architectures protect brand standards while allowing localized commercial flexibility. Store managers can adapt pre-approved digital assets to reflect local inventory levels, regional weather events, and suburban community promotions without violating national brand guidelines.

    Across the wider Asia-Pacific retail sector, similar pressures have forced department store operators and convenience chains in Singapore, Tokyo, and Hong Kong to adopt composable technology architectures. Retailers that maintain monolithic content management systems risk falling behind agile pure-play operators who test, deploy, and retire promotional campaigns in hours rather than weeks. The primary operational risk sits in execution, as marketing teams often resist structural changes to publishing workflows without clear internal compliance mandates.

    The Operational Drag of Artificial Intelligence

    The operational shift follows several years of capital expenditure directed toward customer-facing channels, including social commerce integrations, automated locker networks, and mobile loyalty applications. While these investments widened customer reach, they divided digital production resources across disconnected content management software platforms.

    Recent deployments of generative artificial intelligence have highlighted these structural limitations. Retail operations that feed unstructured, fragmented catalogue data into automated generative tools produce inconsistent pricing and conflicting marketing claims at high speed, reinforcing the requirement for structured component databases.

    Merchandising and technology teams are now tracking campaign turnaround metrics and content reuse rates as key performance indicators ahead of the high-volume holiday trading period.

  • Starbucks Expands in East Asia as Walmart Unwinds Suburban Hypermarkets

    Starbucks Expands in East Asia as Walmart Unwinds Suburban Hypermarkets

    Starbucks continues to scale its store footprint across East Asian metros while Western big-box operators like Walmart have spent years unwinding their suburban hypermarket networks.

    The divergence reveals how high-density Asian urban layouts reward high-frequency beverage retail while penalizing large-format car-dependent grocery models.

    Western retail expansion into East Asia split along structural lines over the past two decades. Big-box hypermarkets required expansive floor plates, suburban road infrastructure, and weekly bulk purchasing routines that never fully aligned with daily fresh food shopping habits in cities across China, Japan, and South Korea. Coffee chains, by contrast, secured small-footprint real estate embedded directly into transit nodes, office towers, and dense residential clusters.

    Urban Density And Real Estate Economics

    Hypermarket operators faced escalating commercial rents on massive suburban plots that could not generate the sales density required to offset real estate overhead. Local convenience store chains and neighborhood wet markets retained daily foot traffic, while domestic e-commerce platforms quickly captured non-perishable consumer goods.

    Starbucks structured its expansion around rapid footfall and premium beverage margins. Store units occupy high-traffic ground-floor positions in office complexes and transit hubs, turning compact footprints into reliable daily transactions. The company positioned its locations as functional meeting spaces for urban workers living and working in tight quarters.

    Localization Of The Consumer Experience

    Walmart relied heavily on centralized global procurement systems and standard supply chains designed to lower unit costs through sheer volume. That formula failed to dislodge regional grocery competitors who maintained direct, daily ties with domestic produce distributors and localized supply channels.

    Beverage operators adapted their product menus and store concepts far more quickly. Seasonal product launches, integration with regional digital payment apps, and localized delivery partnerships allowed coffee chains to embed themselves into daily consumer routines across tier-one and tier-two cities.

    Supply Chains And Digital Delivery Channels

    The rise of on-demand quick-commerce platforms in East Asia further eroded the traditional hypermarket advantage of wide product selections under one roof. When consumers can order household staples on mobile apps for delivery within thirty minutes, the incentive to drive to an out-of-town warehouse store disappears.

    Coffee retail adapted directly to this shift by integrating order-and-pay apps and motorcycle courier fleets into store operations. Compact urban kitchens double as mini-fulfillment nodes for instant delivery without adding significant real estate overhead.

    Western multi-brand retailers entering East Asia now structure their market entries around small-format, experience-driven spaces rather than sprawling suburban warehouses. The next operational test centers on maintaining beverage gross margins as domestic discount coffee brands add thousands of low-cost kiosks across the region.

  • Funday Natural Sweets and Cotton on Kids Partner on Apparel Range

    Funday Natural Sweets and Cotton on Kids Partner on Apparel Range

    Confectionery brand Funday Natural Sweets has partnered with Australian childrenswear retailer Cotton On Kids in September 2026 to launch a limited-edition apparel collection based on its core product range.

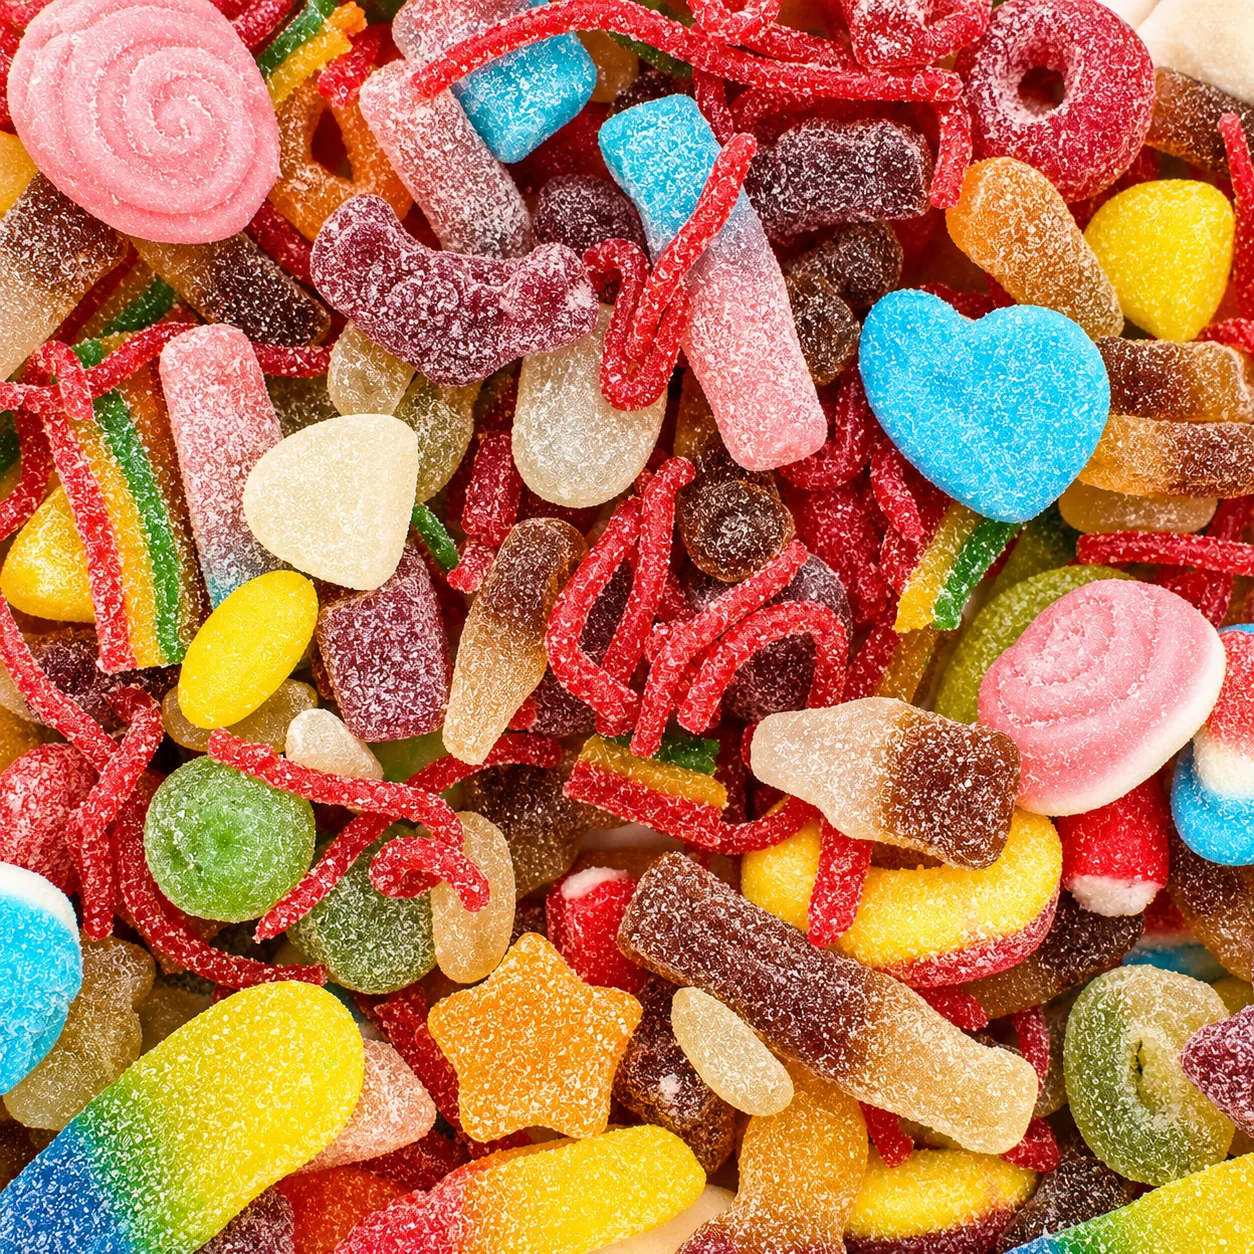
    The apparel run is designed for children aged two to 10 years and sells exclusively through the Cotton On website. Graphic designs across the garments replicate four confectionery variants: Strawberry & Cream, Sour Peach Hearts, Sour Cola, and Fruity Koalas.

    Candy Graphics for Digital Shelves

    Cotton On is keeping the release confined to its online channels rather than distributing inventory across its physical store fleet. Digital exclusivity lowers supply chain overhead for short-run collaborative merchandise while testing customer demand before committing floor space in suburban shopping centres.

    For Funday, the partnership puts grocery-aisle branding into everyday childrenswear. Apparel licensing gives fast-moving consumer goods makers repeated household visibility without requiring an increase in trade marketing expenditure inside supermarkets.

    Brand Collaborations in Childrenswear

    Fashion retailers across Asia-Pacific continue to use branded novelty drops to drive direct web traffic. Cross-category partnerships between food brands and apparel chains have expanded rapidly as fast-fashion operators look for distinctive graphic intellectual property that appeals directly to parents buying for young children.

    The operational risk in food-to-fashion licensing sits squarely on inventory velocity. Themed capsule collections lose consumer appeal quickly once seasonal promotional cycles end, making web-only fulfillment a calculated choice to prevent discounted stock overhang in physical stores.

    Licensing Growth in Apparel

    Cotton On has built a steady business model around limited licensing deals across its adult and youth divisions, drawing on entertainment properties, beverage brands, and food labels to refresh basic garment blanks.

    Online performance data from this initial confectionery run will determine whether Cotton On expands the licensed grocery range into retail stores across Australia and its broader Asia-Pacific store network.

  • Virtue Mirage Launches 17-Tool Fashion Personalisation Platform

    Virtue Mirage Launches 17-Tool Fashion Personalisation Platform

    Australian entrepreneur Lukas Cervenan launched Virtue Mirage in September 2026, introducing a hyper-personalisation platform designed to reshape the online fashion shopping experience.

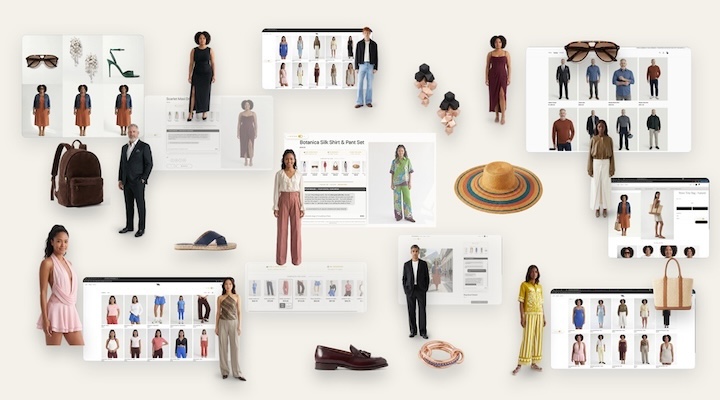
    The system offers 17 tools that create a digital twin of a shopper using photos or exact measurements, extending personalisation across entire online stores rather than limiting it to individual products.

    By replacing traditional model imagery across every product gallery, the platform allows shoppers to see garments on their real body sizes across participating stores running on services such as Shopify and BigCommerce.

    How the Network Functions

    Shoppers manage their profiles through a central dashboard that stores saved outfits, real-time stock availability, and tailored size advisories for specific garments. A semantic search engine pairs items across a merchant’s inventory directly onto the user’s avatar, rather than displaying isolated product grids. New inventory drops can be pre-rendered for registered customer profiles before users land on the store page.

    To our knowledge, we are the only platform in the world that is transforming entire websites. So a size-16 shopper is never looking at a professional size-6 model; she sees her real size, on her real body, in every image across a brand’s entire store.

    The Return Problem Across Regional Fashion

    Retail margins across Asia-Pacific e-commerce continue to erode under the weight of reverse logistics. Fit failures drive the bulk of fashion returns, worsened by bracket-buying habits where shoppers purchase several sizes of a single item with the intention of returning most of them. Eliminating the disconnect between model proportions and real customer bodies attacks reverse logistics costs at the point of discovery.

    Standalone virtual fitting widgets rarely alter overall conversion because they sit isolated on individual product detail pages. By transforming whole catalogues into personalised galleries, operators attempt to lift checkout completion while defending independent web stores against dominant regional marketplaces like Shein and Zalora. The primary technical hurdle remains rendering fidelity, as artificial intelligence tools frequently struggle with drape and textile weight across edge sizes.

    Decade of Commercial Imaging Preceded Launch

    The platform builds directly on Cervenan’s commercial imaging business, Virtue Creative Studios, which produced e-commerce and campaign photo shoots for more than 500 apparel brands over the past ten years. That production background informed the platform’s visual architecture, which formats store catalogs to allow external AI shopping agents and semantic web scrapers to parse inventory data directly.

    Participating merchants on Shopify and BigCommerce are now integrating the software into their live storefronts ahead of peak year-end trading cycles.