Tag: Finance

  • Standard Chartered Looks at Strategic Options for its Indonesia Business

    Standard Chartered Looks at Strategic Options for its Indonesia Business

    Standard Chartered said its troubled principal finance unit toted up a $650 million loss last year, weighing on the bank’s efforts to improve returns. Standard Chartered’s net loss for 2016 narrowed to $478 million from $2.36 billion in 2015, but revenue and profit figures fell short of analysts’ expectations and the stock fell 5%.

    The emerging-markets focused bank said it sharply marked down its private equity stakes in companies in Africa, Asia and India, as it prepares to exit from the principal finance business in the next couple of years. It said its risk committee reviewed processes and controls in the unit last year, amid the losses and probes by U.S. and other authorities into alleged bribery at a portfolio company, power plant builder Maxpower Group Pte. Ltd.

    Standard Chartered said the unit will be stripped out of its underlying results going forward, with any gains or losses treated as restructuring costs. The principal finance unit manages around $5 billion for Standard Chartered and external investors. The bank’s exposure is around $2 billion.

    Standard Chartered’s smaller full-year loss was the result of a near-halving in bad loans across its businesses. But revenue dropped by 11% to $13.8 billion from $15.4 billion. Standard Chartered blamed the fall on a range of factors including negative revenue in principal finance, dollar strength against emerging market currencies and lower client activity.

    Fourth-quarter revenue was $3.53 billion, up from $3.26 billion in the fourth quarter of 2015. The bank said significant further improvement is needed.

    Chief Executive Bill Winters said the bank is on a stronger foundation after cutting costs and selling around a dozen businesses since he started as CEO in June 2015. He said the bank will look at strategic options this year for its Indonesia business, currently run through two banks.

    Standard Chartered operates under its own name in the country and holds a 44.6% stake in PT Bank Permata. Mr. Winters said the bank is fully committed to Indonesia but wants to operate through a single entity there.

    He said shifts in global trade and potential U.S. protectionist policies posed a threat to the bank, but also opportunity as trade flows realign. “If the U.S. for whatever reasons or through whatever political process makes itself a less desirable trading partner, there are other countries that will want to fill that gap,” Mr. Winters told reporters.

  • Krungsri gears up for return of investors from Japan

    Krungsri gears up for return of investors from Japan

    Bank of Ayudhya, commonly known as Krungsri, is reinforcing its commercial banking after seeing a return by Japanese companies considering investment in the Kingdom in light of the government’s “Thailand 4.0” industrial goals.

    Pornsanong Tuchinda, head of commercial banking, said yesterday that healthcare and wellness and real estate were currently the priority focus of Japanese businesses looking to invest in Thailand again since the government announced the Thailand 4.0 industrial-development policy.

    The actual level of new Japanese investment will be seen when these companies have a clear picture of development plans under the policy, he added.

    Japanese companies invested in Thailand have been a crucial part of the customer base for Krungsri’s commercial-banking operations since 2015, reflecting the successful integration between the Thai bank and BTMU (Bank of Tokyo-Mitsubishi UFJ) Bangkok Branch, which is part of Japan’s MUFG (Mitsubishi UFJ Financial Group), he said.

    Pornsanong said Japanese investors were currently eyeing healthcare and wellness business in Thailand because of this country’s increasingly “greying” population.

    Japan has expertise in healthcare and wellness in light of its own ageing population, while real estate is another business that investors are keen on because of its being tourism-related.

    The bank will offer investors total financial solutions, catering to corporate customers that may not only require financing but also financial advice and business-matching services, he said, adding that Krungsri would therefore focus more on how to deliver a package of solutions to such clients.

    A number of medium-sized Thai hospitals also are interested in expanding their healthcare and wellness business, presenting a further opportunity for the bank’s commercial-banking arm, he said.

    Last year, the unit enjoyed loan growth of 11 per cent, with outstanding lending rising to Bt642 billion thanks to the financing of major deals involving Siam City Cement, which acquired a cement business in Sri Lanka; Central Group, which purchased a retail business in Vietnam; and Thai Union Group, which acquired a business in the European Union, Pornsanong said.

    Excluding those large deals, loan growth was 7-8 per cent.

    This year, while the bank’s commercial-banking arm targets 5-per-cent growth due to fewer big deals on the horizon, it should still outpace its peers thanks to the recovering Thai economy and Thailand 4.0-related business activity, he predicted.

    Moreover, with the unit’s customer base sufficiently large for the provision of improved total solutions, it wants to give more importance to the quality of customers and offer value-added solutions to its current clients, he explained.

    Commercial banking at Krungsri covers corporate customers with annual sales revenue of more than Bt1 billion, and small and medium-sized enterprises with annual revenue below that level.

    Based on the loan-growth target of 5 per cent, most lending this year will be contributed by medium-sized enterprises, a segment in which the bank has witnessed lending demand, he said.

    “These firms [mid-sized enterprises] are more confident in the Thai economy, and many of them are in retail, where there is purchasing power but consumer sentiment |has not yet returned. If sentiment improves, purchasing power will be released and SMEs will benefit.

    “On the other hand, most corporate customers are not requiring new lending at present, as they first want to see how the global trade situation settles,” the commercial-banking head said.

  • Mobile banking to have nearly 3b users by 2021

    Mobile banking to have nearly 3b users by 2021

    Juniper Research predicts that by 2021, nearly 3 billion users will be using retail banking services on smartphones, tablets, PCs and smartwatches, up 53% from 2017.

    The new research titled “Retail Banking: Digital Transformation & Disruptor Opportunities 2017-2021” also predicts that usage will continue to rise as consumers increasingly opt for banks offering the convenience of rapid, multi-channel digital services. This means that banks will need to focus on providing a more frictionless digital experience to their customers, especially if they are to remain market leaders.

    According to Juniper while traditional banks have so far remained a step behind in delivering innovation and maintaining their competitive edge against new Fintech players, the situation is gradually changing.

    “Technology is currently the big differentiator for all types of banks; including traditional banks and the so-called challenger banks. Investments in banking technology reached record levels in 2016 and traditional banks are expected to focus on digital transformation initiatives”, added research author Nitin Bhas.

    Juniper predicts that in 2017, big banks will acquire challenger players including tech-startups and digital-only banks, and this will further accelerate the rollout of traditional players’ digital strategy.

    Juniper’s Digital Transformation in Banking Readiness Index analyzed leading global tier-1 banks to evaluate their digital transformation readiness scores and highlight their respective positioning within the digital innovation roadmap.

    Its list of leading banks for digital transformation include Banco Santander, Bank of America, Barclays, BBVA, BNP Paribas, Citi, HSBC, JP Morgan Chase, RBS, Société Générale, UniCredit and Wells Fargo.

    Juniper says these banks are progressing rapidly towards the final stages of digital transformation with heavy investments, have excellent digital portfolios, and are already witnessing significant cost savings.

  • Bank Rakyat to enter Indonesia mart in Q2 this year

    Bank Rakyat to enter Indonesia mart in Q2 this year

    Bank Rakyat will enter the Indonesian market in the second quarter (Q2) of this year after getting approval from the authorities, including Bank Negara Malaysia.

    To this end, the bank said, it had signed a memorandum of understanding with Indonesia’s largest bank, Bank Rakyat Indonesia (BRI), today.

    In a statement, the bank said, the collaboration would enable both banks to provide money order services to over 700,000 Indonesians in Malaysia.

    Its Chief Retail Banking Officer, Mohd Shahril Isa, said Malaysia has the highest number of money order transactions worth US$1.9 bilion (US$1 = RM4.44) to Indonesia in 2016.

    “This is one of the main factors for Bank Rakyat to expand its banking services to the country,” he said.

    BRI was set up in 1895 and has 50 million retail clients, with over 10,612 business and services branches all over Indonesia, while Bank Rakyat is the largest Islamic cooperative bank in Malaysia with 147 branches.

  • KBank unveils capital branch

    KBank unveils capital branch

    Kasikornbank (KBank), one of the largest banks in Thailand, officially unveiled its first branch in Phnom Penh with the aim of offering financial services to local businesses as well as corporate and retail customers.

    KBank entered the Cambodian financial market in November and initially, the branch’s objective was to facilitate Thai businesses in Cambodia in the area of corporate finance and fund mobilization for investment in infrastructure projects towards the production of garments and processed food.

    KBank services are available in Thai baht, US dollars and Cambodian riel for bilateral trade activities and other transaction services.

    KBank president Predee Daochai said the bank’s first injection of investment capital into Cambodia was $50 million and it will increase, based on bank performance and demand.

    Mr. Predee said recently that KBank’s loan portfolio was $2 million with a small amount of deposits. However, the bank expects to expand its loan portfolio to about 1.5 billion baht ($43 million) to corporate customers, local businesses and retail customers, both Thai and Cambodian, in the next three to five years.

    “We have to grow in terms of loans and deposits. Our loan portfolio is $2 million, but we have targeted that within the next three to five years, it should rise to two billion baht [$57 million] and we aim to have 800 million baht [$22.8 million] in deposits,” he said.

    “We can grow faster than that because there are many big Thai customers here since they came here many years ago. Most of them use our services in Bangkok so they are pleased to use our services here.”

    Mr. Predee said that KBank is not only looking to serve the financial sector in Cambodia, but also wants to help boost investment and trade between Cambodia and Thailand.

    He said if the first branch performs well, the bank will look to open a second branch in the country.

    Nattavudh Photisaro, Thai ambassador to Cambodia, said that KBank opened its representative office in Cambodia in February 2015, and had a soft opening of its Phnom Penh branch in November.

    He added that although KBank just officially unveiled its branch, it was no stranger to the Thai embassy in Phnom Penh as the bank had worked closely and has strong ties with the Thai diplomatic staff in Cambodia for the past couple years.

    “With KBank, Thailand has a total of four banks in Cambodia including Bangkok Bank, Krungthai Bank and Cambodian Commercial Bank. Now KBank has brought another Thai business to Cambodia,” he said.

    Mr. Nattavudh added that bilateral trade between Thailand and Cambodia reached $5.6 billion last year. He said several Thai companies have expanded their operations in Cambodia and more will follow.

    “I have always encouraged Thai businesses here to operate on three principles: mutual trust, mutual respect and mutual benefit. I think that Kasikornbank has taken these principles to implement here,” he said.

  • Retail offers banks a lifeline

    Retail offers banks a lifeline

    Retail customers offer a silver lining for banks amid tepid demand in corporate lending and the fragile state of small and medium-sized enterprises (SMEs), says Kasikorn Research Center (KResearch).

    Lending to individual customers in 2017 is expected to continue to outshine overall loan growth and the traditional mainstay of Thai lenders — commercial loans — said the research unit of Kasikornbank (KBank) in a report.

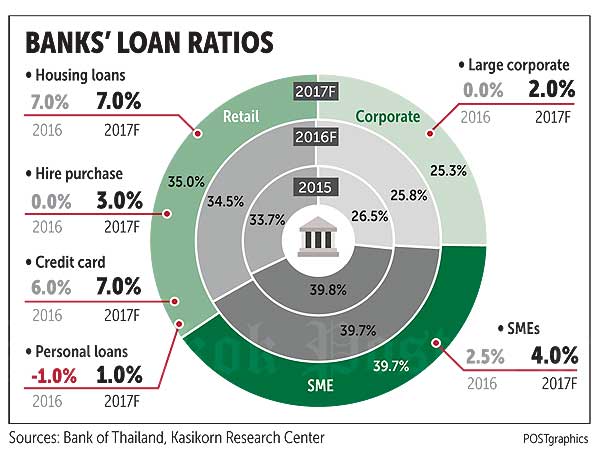
    KResearch forecasts 5.5% growth in retail loans this year, compared with 3% in commercial loans and 4% in overall lending.

    Over the past few years, retail lending also grew at a faster pace than overall and commercial loans. Retail loans rose by 6.2% in 2015 and 4.5% in 2016, well above 2.9% and 1.5%, respectively, for commercial loans those two years and 4.0% and 2.5% for overall lending, according to KResearch data.

    Thai banks’ exposure to retail loans is expected to climb to 35% this year from 34.5% last year, with SME loans steady at 39.7%, said the report. The share of large corporate loans or so-called wholesale banking is projected to fall to 25.3% from 25.8%.

    As Thailand’s economy has struggled with subpar growth since 2013, it is not a surprise banks have pushed into the retail banking business — mortgages, credit cards and personal loans in particular — as companies’ investment projects have stalled. Companies have also turned to debt instruments to raise capital because of low interest rates.

    Retail banking business offers a better profit margin than corporate loans, but carries lower default risks than loans to SMEs struggling with the uneven economic turnaround.

    Moreover, retail borrowers, white-collar workers in particular, on average have seen their income continue to grow slowly, while the unemployment rate remains low at less than 1%.

    “We expect retail lending will deliver the strongest growth in that segment this year as large corporates move toward the capital market for fund mobilisation, while only a handful of banks, especially large lenders, have expertise in SMEs lending,” said Thanyalak Vacharachaisurapol, deputy managing director of KResearch.

    “Even though retail loan growth is expected to increase at a fast clip, overall lending will only record single-digit growth as banks remains cautious amid high household leverage. However, the end of the lock-up period for the first-time car buyer scheme will add to consumer purchasing power this year.”

    The lock-up period is five years for most cars bought under the excise tax rebate scheme. KResearch estimates some 320,000 car owners, representing 30% of those in the first-time car buyer scheme, will have their lock-up period end this year, and some may consider replacing their cars.

    Auto-hire purchase is expected drive retail lending growth this year, said the report.

    KResearch predicts auto loans will expand 3% this year, up from zero last year, while housing loans — accounting for more than half of retail lending — are expected to grow steadily at 7%.

    Although banks will likely focus on retail banking business this year, lenders’ focus areas will be diverse, said the report.

    Krungthai Bank (KTB) and Siam Commercial Bank plan to pay more attention to the wealth customer segment to offset fee-based income expected to be hit by PromptPay, electronic money transfer under the government’s national e-payment scheme.

    KTB, the country’s second-largest lender by total assets, aims to increase assets under management (AUM) for wealthy clients by 25% this year from 600 billion baht. Its provincial customer base is the bank’s strength for expanding both its wealthy client numbers and its AUM.

    KBank, the country’s fourth-largest lender by assets, set a total loan growth target of 4-6% and retail loan growth of 5-7%, with mortgages contributing the highest growth among other retail lending.

    Bank of Ayudhya (BAY) targets double-digit growth for its retail banking business this year compared with total loan growth of 6-8%. The bank recorded the highest loan growth among its industry peers last year at 11.2%, with retail blazing the trail, increasing 15.9%.

  • BRI posts net profit of Rp25.8 trillion

    BRI posts net profit of Rp25.8 trillion

    State-owned lender Bank Rakyat Indonesia (BRI) last year posted a net profit of Rp25.8 trillion, up 2.18 percent from a year earlier.

    The profit growth was attributable to the banks prudential efforts as indicated by a rise in the ratio of reserves to non-performing loans to 170.53 percent in 2016 from 151 percent in 2015.

    The 2016 income was mostly contributed by fee-based income which grew 25.2 percent to Rp9.2 trillion, BRI President Director Asmawi Syam said in a press conference here on Tuesday.

    Meanwhile, net interest income increased 16.2 percent to Rp65.7 trillion, he added.

    “The interest income was fueled by credit growth which reached 13.8 percent or Rp635.3 trillion,” he said.

    BRI Vice President Director Sunarso said the banks net profit grew only 2.18 percent as it adopted prudential principles amidst economic downturn and an upward trend of the banking industrys non-performing loans.

    “The profit did not fall short of target. It continued to grow positively,” he said.

    By adopting the prudential principles, the bank managed to keep down its non-performing loan ratio in 2016 to 2.03 percent from 2.02 percent (gross), while its reserve ratio rose to 170 percent from 151.5 percent.

    He said the banks loan-to-deposit (LDR) ratio reached 87.7 percent and its capital adequacy ratio (CAR) stood at 22.9 percent.

  • Asian shares rattled by Trump policy worries, dollar soft

    Asian shares rattled by Trump policy worries, dollar soft

    Asian shares slipped on Tuesday as stringent curbs on travel to the United States ordered by President Donald Trump brought home to investors that he is serious about carrying out his controversial campaign pledges.

    Global stocks posted their biggest loss in six weeks on Monday after Trump signed an executive order to bar Syrian refugees indefinitely and suspend travel to the United States from seven Muslim-majority countries, sparking widespread protests.

    European bourse are expected to remain fragile after big losses on Monday, with spread-betters seeing opening losses of as much as 0.1 per cent in major indexes, including Britain’s FTSE, Germany’s DAX and France’s CAC.

    “Investors are becoming worried as it appears as if he was setting fire to geopolitical risks that already exist,” said Yoshinori Shigemi, global market strategist at JPMorgan Asset Management.

    Trump’s move drew criticism from some US policymakers, and business leaders, with technology companies, which depend on talent from around the world, planning to discuss a legal challenge.

    “His stance is really inward-looking, making investors nervous about his ’moderateness’,” said Masahiro Ichikawa, senior strategist at Sumitomo Mitsui Asset Management.

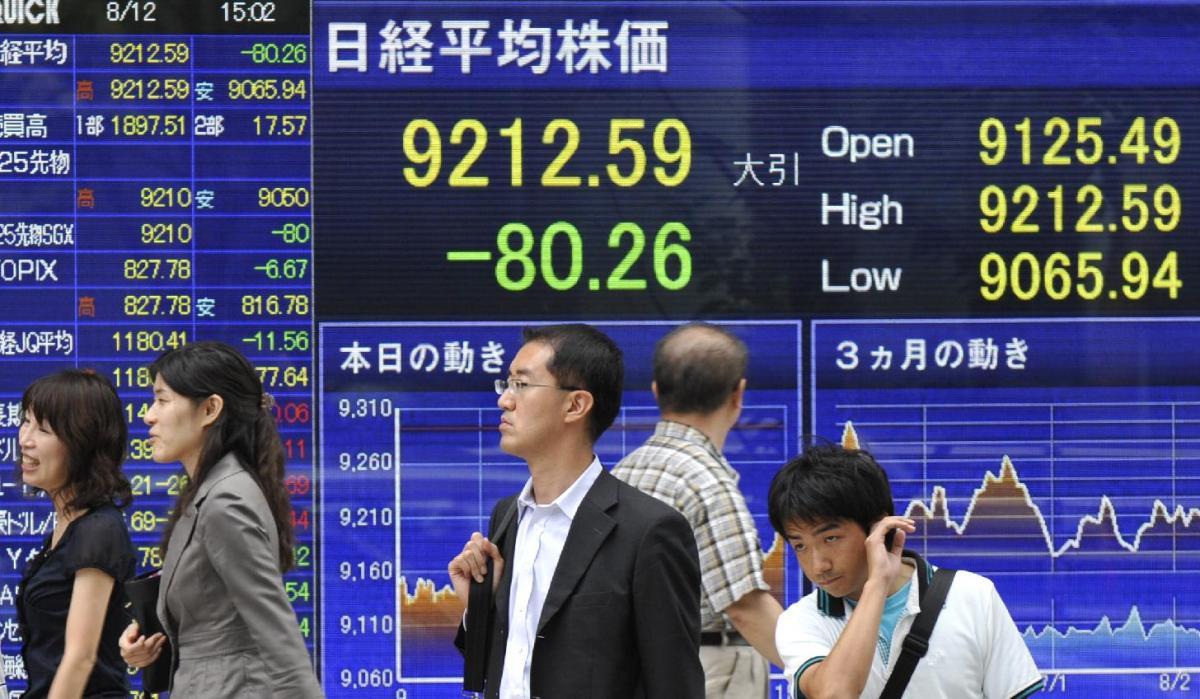
    MSCI’s broadest index of Asia-Pacific shares outside Japan fell 0.5 per cent while Japan’s Nikkei dropped 1.7 per cent, its biggest fall in almost three months.

    On Monday, the US S&P 500 Index fell 0.6 per cent, its biggest fall in a month, though it remained well above levels seen before the November 8 presidential election.

    MSCI’s gauge of the world’s 46 stock markets shed 0.6 per cent, its largest loss in a month and a half.

    The mood soured further when Trump fired the federal government’s top lawyer after she took the extraordinarily rare step of defying the White House.

    US stock futures ESc1 shed 0.3 per cent on Tuesday and the dollar extended losses against the yen.

    Still, most share prices were up on the month, supported by signs of accelerating momentum in the global economy and hopes of large fiscal stimulus from Trump.

    MSCI’s ex-Japan Asian shares index was up 5.7 per cent this month while its index of world markets was up 2.5 per cent. They were also higher than their levels before the US elections.

    In the currency market, the dollar was broadly weak and fell 0.3 per cent against the yen to 113.49 yen. It was down 3.1 per cent so far this month, after three straight months of sizable gains.

    The Japanese currency showed no reaction after the Bank of Japan kept its policy on hold, as expected. A string of recent data has suggested the economy is slowly regaining traction.

    The euro edged up to US$1.0710, consolidating after its rebound this month from its 14-year low of $1.0340 set on January 3.

    In a possible sign of increased anxiety among investors, the safe-haven Swiss franc strengthened to a seven-month high of 1.0637 franc per euro on Monday.

    Worries are also growing about a political shift to populist leaders in Europe.

    French bond yields rose to the highest level since September 2015, on rising uncertainty over the Presidential election later this year.

    Conservative leader Francois Fillon, seen as the front-runner, is now battling to contain a scandal over allegedly unlawful payments to his wife while the Socialists on Sunday picked a hard-left candidate, possibly helping popular far-right leader Marine Le Pen.

    Italian debt yields climbed to 1 1/2-year highs partly as early elections could be called following a ruling from the country’s constitutional court last week.

    Italian assets have also been hit by worries over its banking sector after UniCredit, the country’s biggest bank, revealed on Monday it expects to book a net loss of around 11.8 billion euros ($12.6 billion) for 2016 and fall short of European Central Bank capital requirements.

    By contrast, the yield on German debt fell on Monday even as data showed inflation in Germany hit a 3 1/2-year high in January.

    News that Germany posted a national inflation rate of 1.9 per cent stoked talk of an unwinding of monetary stimulus by the ECB, even though the inflation outcome was below expectations.

    Elevated uncertainty about Trump’s policies, including a lack of detail so far on his plans for tax cuts and fiscal spending, offset optimism on the US economy.

    Data on Monday showed US consumer spending accelerated in December while inflation showed some signs of picking up last month.

    The core PCE price index, the Federal Reserve’s preferred inflation measure, rose 1.7 per cent on a year-on-year basis after a similar gain in November.

    “We’ve seen a jump in US economic sentiment after Trump’s victory. But the improvement in hard economic data remains moderate,” said Haruka Kazama, senior economist at Mizuho Research Institute.

    “And if Trump takes more steps to limit permits for immigrants, that would surely boost inflation as the US is now near a full employment,” she added.

    The Federal Reserve, which will start its two-day policy meeting today, is widely expected to keep interest rates unchanged as it awaits greater clarity on Trump’s economic policies.

    Oil prices dipped as rising US drilling activity offset efforts by OPEC and other producers to cut output in a move to prop up the market.

    Brent crude futures LCOc1, the international benchmark for oil prices, were trading at $55.14 per barrel, down 0.2 per cent from Monday’s settlement price.

  • International Commercial Bank Lao Wins GBO 2016 Awards

    International Commercial Bank Lao Wins GBO 2016 Awards

    International Commercial Bank Lao Limited provides banking and related financial services in the Lao People’s Democratic Republic. It offers various deposit products, including current, savings, education fund savings, and senior citizen savings accounts; and fixed deposits, fixed deposits with advanced interest, demand deposits, and term deposits.

    The company also provides loans, such as vehicle/auto express loans, housing/shoplot/mortgage loans, and educational loan schemes; and other services comprising bills discounting and bank guarantees. In addition, it offers international banking services, such as inward and outward remittances, import/export collections, documentary letters of credit, and foreign currency operations. The company provides its products and services through head office and two branches located in Vientiane; and one branch located in Pakse.

    The company is headquartered in Vientiane, the Lao People’s Democratic Republic. International Commercial Bank Lao Limited is as a subsidiary of Asia Investment and Financial Services Co., Ltd.

    Mr. Zulkiflee Kuan Shun Abdullah, Chief Executive Officer of International Commercial Bank Lao Ltd. Upon receiving this award said “We are indeed honoured to win the “Best Retail Bank – Laos 2016″ award by Global Business Outlook. This would not be possible without the dedication, hard work and commitment from all the staff and the support from the stakeholders. It has been a great achievement for the Bank in 2016. The Bank has been accorded awards in the same category by 2 other international publications. These awards are recognition of their invaluable contribution to the Bank. The stakeholders share this award with all the staff and together we will continue to strive to provide Value Banking to our customers. ”

  • Diversification is driving Brunei’s banking sector forwards

    Diversification is driving Brunei’s banking sector forwards

    As a result of a wider economic expansion and diversification strategy, Brunei’s banking sector is growing at a rapid rate and attracting a new wave of international players

    Despite its small size, Brunei, a southeast Asian nation on the island of Borneo, is a formidable economic power in the region. A thriving oil sector has ensured a very high standard of living for the population. However, similar to many oil-producing nations in the present climate of plummeting prices and global oversupply, the economy’s reliance on the energy industry has become problematic. In response, the Brunei Government is taking comprehensive steps to reduce the economy’s reliance on oil and gas revenue and instead focus on the growth and development of local businesses.

    In 2015, ASEAN – of which Brunei has been a member since 1984 – established the ASEAN Economic Community, achieving a major milestone in regional economic integration. “The integration of ASEAN members can potentially represent a huge opportunity for growth”, said Pierre Imhof, CEO of Baiduri Bank. As such, the possible increase in trade and investment flows, which will result from a single market for goods, services, capital and labour, can open the doors to a far broader customer base for Bruneian banks, while also enabling local SMEs to venture outside of the country.

    National interests
    With the recent implementation of Darussalam Enterprise (DARe), a statutory body established by the government earlier in the year to monitor and nurture the development of local enterprises in Brunei, diversifying the economy and supporting SMEs has become a major priority for a nation that is heavily dependent on revenue from the oil and gas sector. “We have always had a strong focus on SMEs, which has consistently been one of our major customer groups from the very beginning”, Imhof told World Finance. “With the establishment of DARe and its assistance in the development of SMEs, I hope to see the SME market develop to become even more competitive locally, and to eventually become competitive internationally as well. In line with our commitment to develop local businesses and SMEs, Baiduri provides a wide range of financial products to businesses in order to ease their cash flow management and support their growth.”

    Baiduri Bank recently rolled out enhancements to its online banking platforms to coincide with the growing demand for flexibility

    The bank also offers Business i-Banking, Baiduri’s internet banking facility catering specifically for businesses. “Our aim is to provide customers with a modern, user-friendly and secure channel for businesses to manage their banking more efficiently”, Imhof said.

    In April of last year, Baiduri introduced Business Banking – a new unit as part of its retail banking division – that was designed to target the growing number of SMEs in Brunei. According to Imhof, the unit serves to complement the bank’s corporate banking department by tapping into non-borrowing and small-borrowing accounts. Services provided by Business Banking include card merchant services for local retailers and setting up the Baiduri Internet Gateway System, which allows retailers to accept payment from their online customers. The Business Banking unit also helps SMEs apply for credit facilities.

    Moreover, Baiduri Bank is launching a new online payment solution with affordability at its core – again with local SMEs in mind. According to Imhof: “Our latest product, known as MerchantSuite, aims to provide a very accessible and user-friendly method of facilitating online payment without the merchant needing to create their own website. This way, our SMEs are able to conduct business efficiently with minimum difficulty. With over 90 percent of our corporate clients being SMEs, Baiduri Bank clearly recognises their ability to generate revenue in the country and the vital contribution they make to the long-term economic stability of Brunei.”

    Race to expansion
    Another vital aspect to consider when trying to stay competitive in a rapidly changing society is keeping up with the latest technological innovations. In response to this necessity, Baiduri Bank recently rolled out enhancements to its online banking platforms to coincide with the growing demand for greater flexibility, in order to meet various business needs.

    This transition towards the modern digital economy also required the bank to provide a safe and secure digital environment for its customers. According to Imhof: “We continue to invest heavily in our systems to ensure a high level of service delivery along with the highest level of security in the industry.” In fact, Baiduri Bank is at present the first and only bank in Brunei to receive the PCI-DSS certification, a payment card industry standard for the secure processing, transmitting and storing of cardholder data. In line with this trailblazing approach, Baiduri Bank has implemented hi-tech security features for its online banking platforms, such as authentication via mobile or tokens, dual-factor authentication and SMS notification for logins and transactions.

    In response to a shifting customer trend towards diversified investment portfolios, Baiduri Bank launched Baiduri Capital, a wholly owned subsidiary that offers a range of global investment products and services. Baiduri Capital was also the first business in the country to launch an online securities trading platform, thereby leveraging technological developments in the global market.

    “We feel that this is the right time for the Baiduri Bank Group to go into securities trading, as there is a growing number of Bruneians looking for opportunities to build their wealth by investing in stocks and shares, in addition to deposits”, said Imhof. “Therefore, the establishment of Baiduri Capital is very much in line with the bank’s long-term strategy of playing a leading role in the development of Brunei’s financial sector and in serving the people of Brunei.”

    The timing of this strategic move was crucial. “Through our online trading platform, our customers can already trade online in various international stock exchanges, such as those in Malaysia, Singapore, Hong Kong and the US”, said Imhof. As indicated by a statement made by Brunei’s financial regulator, there is more and more talk about a stock exchange being established in Brunei Darussalam in the near future. Baiduri Capital has the capacity to play an important role in educating Bruneians and building their experience of stock trading in light of this potential and significant development.

    This commitment to Brunei’s economic development is further indicated by the bank’s acquisition of the retail banking business of United Overseas Bank’s Brunei branch at the end of 2015. “We look at strengthening and developing our retail business in line with our long-term strategy”, Imhof said.

    In fact, the retail business is now a pillar of the bank’s business activities. With this acquisition, Baiduri has significantly increased its customer base in a bid to get ahead in Brunei’s challenging economic environment. “The acquisition of United Overseas Bank’s Brunei retail business was made possible thanks to Baiduri’s high level of excess liquidity and strong capital base, as evident from its credit rating of BBB/A-2 with a ‘stable’ outlook from Standard & Poor’s, which we believe reflects the bank’s excellent performance.”

    Tackling challenges
    Being rooted in the domestic market, Baiduri Bank has the competitive advantage of an in-depth knowledge of its customers and cultural preferences, in addition to having strong brand name recognition. Imhof explained: “Some of the main benefits of being a local bank are that the decision process is done internally. This allows us to tailor our products and services to specifically suit our clients’ needs. From a business banking perspective, it also means that we are able to be more flexible and faster in making decisions to grant facilities or in structuring financing options.”

    When asked about the recent arrival of the Bank of China in the Bruneian market, Imhof spoke of the move being demonstrative of the strong interest in Brunei from overseas. “Brunei’s local banks are perfectly equipped to cater to the needs of clients, just as well as, if not better than, other international banks. They can offer those clients a wide, if not wider, range of products and services. In terms of the Bank of China specifically, I believe that its presence will have a positive impact on the image of the country and that, as with any newcomer, there will be a learning curve to understanding Brunei’s unique market culture.”

    Amid the current international financial landscape, the global banking industry is operating in an increasingly regulated environment – and Brunei is no exception. “Though it is expected that the business environment will continue to face challenges, the opportunities for businesses and for the Baiduri Bank Group to grow are very promising, throughout the process of Brunei promoting economic diversification and development”, Imhof said. Moreover, the prospect of a stock exchange coming into fruition in the coming years is expected to firmly cement Brunei’s place on the map, which may encourage a surge in both local and foreign investment.

  • Vietnam’s bank CEOs receive sky-high salaries

    Vietnam’s bank CEOs receive sky-high salaries

    Meanwhile, the managers at VP Bank receive twice as much as Vietcombank’s managers, about VND3.6 billion if the bank can fulfill the business plan. At ACB, the average level for key personnel is VND530 million a year.

    Vietnamese banks are more generous, accepting to pay billions of dong a year to their key personnel.

    VP Bank is believed to lead the banks in pay to members of the board of directors and supervisory board. Shareholders agreed to pay one percent of pretax profit, or VND32 billion to the members if the bank can make the pretax profit of VND3.2 trillion in 2016.

    There are nine members on the boards, which means that if the business plan can be fulfilled, each of the members can receive VND3.6 billion a year.

    Techcombank also promises attractive awards to the managers. Its shareholders approved the pay of VND29.54 billion in 2016 to the board of directors and supervisory board. With 11 members, each of them expects to receive VND2.6 billion this year.

    With satisfactory business result, Vietcombank’s shareholders approved the pay of VND1.9 billion for every member of the boards in 2015.

    The bank has consulted with shareholders about the pay equivalent to 0.35 percent of post-tax profit to the members of the boards in 2016, while the bank plans the pretax profit of VND7.5 trillion. This means that if the business plan is fulfilled, the pay would be VND2.3 billion.

    Meanwhile, Maritime Bank plans a little bit lower pay for the members of the boards, at VND16 billion. Every of nine members expects to get VND1.7 billion in 2016.

    Orient Bank plans a relatively modest pay to its key personnel with the budget of VND8.2 billion only for the members of the board. However, the figure is still higher by VND1.2 billion than the last year.

    Nam A Bank plans to pay VND18 billion to 18 members of the boards in 2016, the level which some shareholders think is too high icompared with the dividend of 5 percent paid to shareholders in 2015.

    Banking is the business field which offers high pay to staff.

    A report of Navigos Search showed that the two positions which received the highest pay in the first three months of the year were the senior executive of a joint stock bank and a service company. Each of them got over VND200 million a month.

    The following positions were ones in the fields of healthcare, service, trade and bank.

    Meanwhile, the managers of state-owned conglomerates, keep complaining that the pay is unreasonably low which cannot reflect the effective business performance of the enterprises.

  • Small banks avoid being merged or acquired

    Small banks avoid being merged or acquired

    Small-sized banks are making great efforts to grow and avoid being merged or acquired, however, it is not easy, according to the Đầu tư chứng khoán (Securities Investment) newspaper.

    VietA Bank, for example, plans to promote retail sales and focus on individual customers and small- and medium-sized enterprises (SMEs).

    Although VietA Bank’s non-performing loan ratio in late September 2016 reduced to 1.17 per cent from 2.25 per cent in early 2016, its provisions for risky loans rose by 82 per cent to VNĐ71 billion (US$3.12 million), strongly affecting the profit result. Following the first three quarters of 2016, VietA Bank posted pre-tax profit of only VNĐ101 billion.

    Another case is Kienlongbank, which was transformed from a rural bank to an urban bank. The bank aims to become a retail bank targeting SMEs operating in agriculture and rural areas. However, Kienlongbank is also facing difficulties like other small banks in the banking system.

    The bank failed to complete its 2016 profit plan, with pre-tax profit of only VNĐ19.8 billion recorded in the first nine months of 2016, a decline of 90 per cent compared with the same period of 2015. Kienlongbank’s bad debts increased from 1.12 per cent in the beginning of 2016 to 1.46 per cent by late September 2016.

    Financial expert Trần Du Lịch said the more important task for small banks, at present, is to find solutions to successfully carry out restructuring and improve financial capacity, thereby avoiding being merged or acquired.

    In an attempt to avoid M&As, small banks also plan to raise capital and have conducted self-restructuring in recent years through internal resources, however, many have repeatedly been unsuccessful.

    Saigonbank, for example, has not fulfilled its plan to increase charter capital to VNĐ4 trillion following its refusal to merge with Vietcombank.

    VietA Bank also managed to raise its capital to just VNĐ3.5 trillion in early 2016 and no further progress has been recorded since then.

    Following the failure of the merger deal with Export Import Commercial Joint Stock Bank (Eximbank), according to insiders, NamA Bank has also been unable to increase capital as expected. The current charter capital of the bank is just more than VNĐ3 trillion.

    The central bank recently also allowed VietBank to increase charter capital from VNĐ3 trillion to VNĐ3.249 trillion. With this level of charter capital, VietBank remains at the top of banks with the lowest charter capital in the market, along with other banks whose legal capital has reached only VNĐ3 trillion, such as Kienlongbank, VietCapital Bank, NCB and Saigonbank.

    Experts said small banks which wanted to survive without conducting M&As, must raise their financial capacity.

    However, foreign investors are not interested in weak domestic banks if the controlling regulations are not relaxed. As long as the ownership limit of foreign investors is still less than 51 per cent, foreign shareholders cannot take control of the bank.

    According to economist Lê Xuân Nghĩa, since weak and small banks are finding it difficult to increase financial capacity to accelerate the settlement of bad debts and restructuring, it is in their interests to find potential partners to conduct M&As.

  • HSBC closes 62 more UK branches, but all Hong Kong outlets to stay open

    HSBC closes 62 more UK branches, but all Hong Kong outlets to stay open

    HSBC is shutting 62 more British branches this year, meaning the bank will have closed 340 outlets across the country within the past two years.

    But in a divergence of strategies between two of its most significant retail banking markets, the bank said it had no such plans in Hong Kong.

    “While individual branches relocate from time-to-time, there is no programme of closures in Hong Kong,” insisted HSBC spokesperson Gareth Hewett.

    The bank has about 100 branches and more than 300 standalone express bank centres in Hong Kong. It blamed the UK closures on the changing habits of its customers, adding HSBC will still have 625 branches in the country by 2018.

    “More customers are using mobile and internet banking than ever before … and fewer people are using branches. More than 90 per cent of our interactions with customers are now through our digital channels – an increase from 80 per cent last year,” said Francesca McDonagh, HSBC’s head of retail banking and wealth management for UK and Europe.

    Last year HSBC halved its branch network in India, again citing the move to digital as an important factor in the decision.

    While the lender is pursuing a digital strategy in Hong Kong, which includes digital peer-to-peer payments systems and virtual assistants for its corporate clients, these new initiatives have not led to a need to reduce its branch network here.

    More customers are using mobile and internet banking than ever before … and fewer people are using branches. More than 90 per cent of our interactions with customers are now through our digital channels – an increase from 80 per cent last year

    Francesca McDonagh, HSBC’s head of retail banking and wealth management, UK and Europe

    Across the board, branch networks in Hong Kong have remained broadly solid, though last June Bank of East Asia said that its brokerage business, East Asia Securities, would close its 22 retail outlets.

    As has become standard practise, BEA too noted the vast the majority of its transactions were now being conducted via the internet or over the phone.

    The new closures mean HSBC has shut more branches than any other major UK high street lender, but the closures are by no means unique.

    Last week, the Yorkshire and Clydesdale bank group said that it would close 79 UK branches, and, in 2015 and 2016, more than 1,000 banks were closed across Britain according to consumer group Which?

    Dominic Hook, national officer at UK’s largest trade union Unite said in a statement: “Unite is again calling on the banking industry to rethink such branch culling exercises, which do nothing to reassure customers or staff that banking is accessible and open to all.

    “Without doubt customer service in financial services will suffer if our high streets are left with no local branches.”

  • BNI prepares Indonesia-Hong Kong worker card

    BNI prepares Indonesia-Hong Kong worker card

    State-owned PT Bank Negara Indonesia (BNI) will be launching Indonesia-Hong Kong Worker Card (KPIH), a multi-function card for Indonesian employees in Hong Kong.

    The Bank had previously launched Indonesia-Singapore Worker Card (KPIS) in November 2016.

    The dissemination and soft launching event of the card was carried out in the presence of 500 Indonesian migrant workers in the Banks Hong Kong branch on Jan 22, and was attended by BNIs Vice President Suprajarto.

    “There are savings acquisition potentials, which reached 25 thousand Indonesian migrant workers in Hong Kong. This card has many functions. Apart from being a debit card, it can also act as a Worker Identity Card,” Suprajarto said in an official statement received by Antara here on Monday.

    The cards functions include Internet/Mobile/SMS banking facilities that ease transaction processes, access to the Banks programs information and remittance and/or bill settlement to Indonesia through BNIs Hong Kong branch or ATM machines.

    The card can also be used as a shopping card in stores with a MasterCard logo in their EDC s.

    Card holders also get a chance to join an entrepreneurship training program called “KAMI bersama BNI” (We are with BNI), as well get home credit facilities for new residential purchases or renovations through BNIs Hong Kong branch.

    As an appreciation to the Banks consumers, BNI is having a remittance fee discount program for money wiring services through the Hong Kong branch, in which transfer costs are being exempted for transactions among BNI accounts, he continued.

    Customers can also move their savings balance into a deposit account once the amount is considerably high, and they can also propose for the Worker Retirement account and auto-debit system for health and work insurances.

    For migrant workers who wish to start their own business in Indonesia, BNI also offers financial support through their Peoples Business Credit (KUR) program.

    They can simply contact the Banks small credit centers across Indonesia to submit their proposal.

    One of the programs selling points lies in its low interest rate, which is noted to be at 9 percent annually as per 2016.

    Until the end of 2016, BNI had given out credits to 386 migrant workers in Hong Kong through seven credit centers, with the loan reaching Rp5.3 billion.

    The loan is also being disposed to migrant workers who had been employed in Singapore, Japan and Taiwan.

    As of December 2016, there are 2,463 debtors, with the total amount reaching Rp38.9 billion.

  • CB Bank pursues self-service banking in Myanmar

    CB Bank pursues self-service banking in Myanmar

    Cash remains the primary payment method in many parts of Southeast Asia. In Myanmar, competition to provide cash services is intense.

    Vikram Kumar, country manager for Myanmar at the International Finance Corporation, the private arm of the World Bank Group, recently told that domestic banks in Myanmar are under pressure “to prepare themselves to cope with the demands placed on them by the expected pace of economic growth. As a consequence, most banks have upgraded or are in the process of upgrading their technology capacity.”

    Myanmar’s Co-Operative Bank Limited (CB Bank) is the latest to upgrade its banking infrastructure. Sometime earlier the bank upgraded all its existing ATMs to more secure EMV chip card technology and obtain EMV certification with both VISA and MasterCard.

    More recently, the bank ordered 500 new ATMs and cash recyclers as part of a more extensive contract for systems, software and services to expand its self-service cash offerings beyond the country’s main commercial hub Yangon.

    Diebold Nixdorf is also assisting CB Bank with the implementation of cardless cash withdrawals at ATMs. Bank customers will be able to use their mobile devices to generate a one-time PIN to activate a withdrawal at an ATM either for themselves or for a third party without requiring a bankcard.

    The technology provides an innovative person-to-person payment service to consumers especially in developing markets, and underscores Diebold Nixdorf’s commitment to drive connected commerce and help bridge the digital and physical worlds.

    CB Bank has grander ambitions beyond just upgrading its infrastructure. According to U Kyaw Lynn, CEO and Executive Vice Chairman, at CB Bank, the bank aims to become one of Myanmar’s top banks offering secure, innovative and convenient cash services across our branch, online and mobile channels.

    The rollout will mean a total of 1,000 advanced cash systems across a network of 180 CB Bank branches. Completion is expected to be by the end of 2017.