Tag: Finance

  • Standard Chartered Banks on Chinese Fintechs

    Standard Chartered Banks on Chinese Fintechs

    Standard Chartered has launched a Shanghai-based innovation lab to tap China’s tech market and improve its own capabilities.

    The eXellerator innovation lab in China alongside others in Singapore Hong Kong, London, Kenya, and San Francisco are part of the bank’s SC Ventures unit, a research and development arm focused on innovation and fintech.

    With the launch of the eXellerator, Standard Chartered aims to deepen its contribution and participation in China’s vibrant technology and innovation ecosystem, the bank said, highlighting various tech competencies including artificial intelligence, biometrics and mobile payments that could improve its client products and experiences.

    In addition, the bank also highlights the opportunity for such fintechs startups to scale their solutions across the bank’s global business and leverage the opportunity to co-create new businesses and operating models in the process.

    Rapid changes in financial technology are reshaping the future of the global banking industry, especially here in China which is home to some of the world’s most established companies leading the way in areas like artificial intelligence and Big Data, said Jerry Zhang, CEO of Standard Chartered Bank (China), stressing the Chinese market’s strategic importance to the group.

    Alex Manson, global head of SC Ventures echoed the sentiments emphasizing that a mere online banking app will not be enough to rewire the DNA. To truly rewire the DNA in banking, we need to go beyond just offering a digital interface, he said. Our eXellerators create an environment which combines innovation from both in and outside the Bank.

    The rewiring is well underway in Asia with various milestones recently achieved. In Hong Kong, it established a strategic joint venture with major local telecoms PCCW and HKT, alongside travel service provider Ctrip to build a standalone digital bank. And in India, it will be launching an open digital platform targeting SME clients with various financial and business solutions.
  • Strong Wealth Management Flows Drive Q2 Growth at UOB

    Strong Wealth Management Flows Drive Q2 Growth at UOB

    The bank’s strong second quarter was driven by strong wealth management flows, higher credit card volume and higher trading income. UOB’s net earnings grew in the second quarter to S$1.17 billion ($850 million) – 11 percent higher year-on-year and 8 percent higher than the previous quarter, due to improvements in both interest and non-interest income, the bank reported in a filing to Singapore Exchange before the market opened on Friday.

    UOB’s net interest income grew 7 percent to S$1.65 billion, while net fee and commission income increased 6 percent to S$527 million, with strong wealth management flows and higher volume in credit cards and loan-related fees.

    Non-interest income rose 33 percent to S$403 million, driven by higher trading income and gains from investment securities.

    UOB’s net earnings for the first half of 2019 grew 8 percent year-on-year to reach a record S$2.22 billion ($1.61 billion), while total income rose 9 percent to reach S$4.99 billion on the back of strong loan growth and higher trading and investment income. Net interest income grew 8 percent to S$3.24 billion, net fee and commission income stayed flat, and non-interest income rose 36 percent to S$743 million, with stronger gains in trading income and investments.

    The bank reported «healthy income growth» across all business segments compared to 2018 – Group Retail saw 7 percent income growth to S$2.07 billion, led by income growth from high affluent customers, while Group Wholesale Banking saw a 9 percent income growth to S$2.06 billion, led by volume growth and stronger contribution from the investment banking and treasury businesses.

    UOB cited higher staff, revenue-related and IT-related expenses as behind a 10-percent growth in total expenses, reaching S$2.2 billion. Its cost-to-income ratio saw a marginal increase to 44.1 percent.

    Our results reflect the relevance of our strategies in connecting our customers to opportunities across the region, deepening their engagement through our omnichannel approach and offering them the right solutions through our ecosystem partnerships, Wee Ee Cheong, UOB deputy chairman and chief executive officer, said in a statement.

    UOB declared an interim dividend of 55 cents per ordinary share, up from 50 cents the year before.

  • OCBC Q2 Profit Growth Purely From Consumer And Private Banking

    OCBC Q2 Profit Growth Purely From Consumer And Private Banking

    Strong performance from OCBC’s consumer and private banking segment helped bump up quarterly profits by 1 percent and offset all of the group’s other segments which posted negative year-on-year profit growth.

    The Singaporean financial group posted second-quarter profits of 1.22 billion Singapore dollars ($890 million), up 1 percent from last year’s ($880 million) and first-half profits of $1.78 billion, up 6 percent year-on-year.

    While economic growth in our key markets is slowing, our healthy capital, funding, and liquidity position will allow us to comfortably navigate the challenging operating environment and pursue our long-term growth strategy, said OCBC CEO Samuel Tsien. This also gives us the flexibility to capitalize on market expansion opportunities as they arise.

    OCBC registered year-on-year operating profit drops across all business segments but closed the quarter higher due to a 20 percent surge in its consumer and private banking segment. The segment posted profits of $273 million due to higher net interest income and lower allowances. Its private wealth arm, Bank of Singapore also reached a new high in assets under management with $111 billion.

    Despite a 33 percent drop in profits from its insurance segment, attributed to weaker performance from its subsidiary Greater Eastern Holdings, non-interest income still rose 1 percent driven by various business lines including wealth management fees which posted a five-quarter high and 8 percent increase. Net interest income climbed 10 percent year-on-year to reach $1.16 billion, attributed to increased customer loans and higher net interest margins (12 basis points).

  • Nomura Shares China Brokerage JV Strategy

    Nomura Shares China Brokerage JV Strategy

    Following the relaxation of foreign ownership limits in China, Nomura will seek to launch its joint venture operation in China within 2019 and shares its strategy and view on the market.

    According to Nomura Securities, its new 51 percent-owned joint venture will initially focus on the wealth management business before gradually expanding into other areas such as IPO underwriting, equity and fixed income, M&A and asset management.

    Although we start with wealth management first, that is not our goal. Our goal is to provide wider financial services, said Iiyama Toshiyasu, executive vice-president of Nomura Securities and chairman of its China committee, in a recent report.

    We understand that one business model is not sustainable. We have to combine different areas of business.

    We will start everything from the scratch, Iiyama said, referencing the recent loosening of ownership caps in domestic financial institutions. «China’s opening of the financial sector makes us more confident about what we can do in China and what we can contribute to this market.»

    Iiyama reiterates the importance for foreign financial institutions to focus on importing their unique strengths. In addition to the brokerage JV, Nomura has also gained license as a wholly foreign-owned private fund manager to raise onshore funds and invest in A-shares.

    I believe many international banks will follow suit, Iiyama said. They have their own strength and they will bring that into the Chinese market, which will further broaden and deepen the Chinese market and benefit the Chinese investors and corporations.

  • Nearly 5,000 HSBC Banking Jobs Face Ax

    Nearly 5,000 HSBC Banking Jobs Face Ax

    HSBC reiterates continuity in its business strategy, despite the recent CEO exit, underlining a potential axing of more than 4,700 jobs as part of its ongoing cost-cutting measures.

    HSBC’s finance director Ewen Stevenson noted that up to 2 percent of jobs (currently 237,865 employees globally), or 4,754, could but slashed as part of the overall group strategy to cut 4 percent of the bank’s wage costs. It anticipating cost savings from targeting senior roles, attrition, as well as $650 to $700 million in severance costs, saved moving forward, according to a report.

    This is in addition to cuts announced in June 2018 by former CEO John Flint that covered areas such as digital banking and productivity improvement, which is expected to save an additional $0.5 to $2.5 billion from then to 2020.

    The new announcements follow the recent unexpected exit of former CEO Flint who was at the helm for a mere 18 months. Pundits are expecting even more strategic changes to come including a potential reduction to its global footprint.

    HSBC Chairman Mark Tucker had then noted that the bank needed to respond to «an increasingly complex and challenging global environment» with a shift in leadership. Circumstances change and we need to adapt, he said.

  • Apple Card terms specify that iPhone holders can’t jailbreak their phone

    Apple Card terms specify that iPhone holders can’t jailbreak their phone

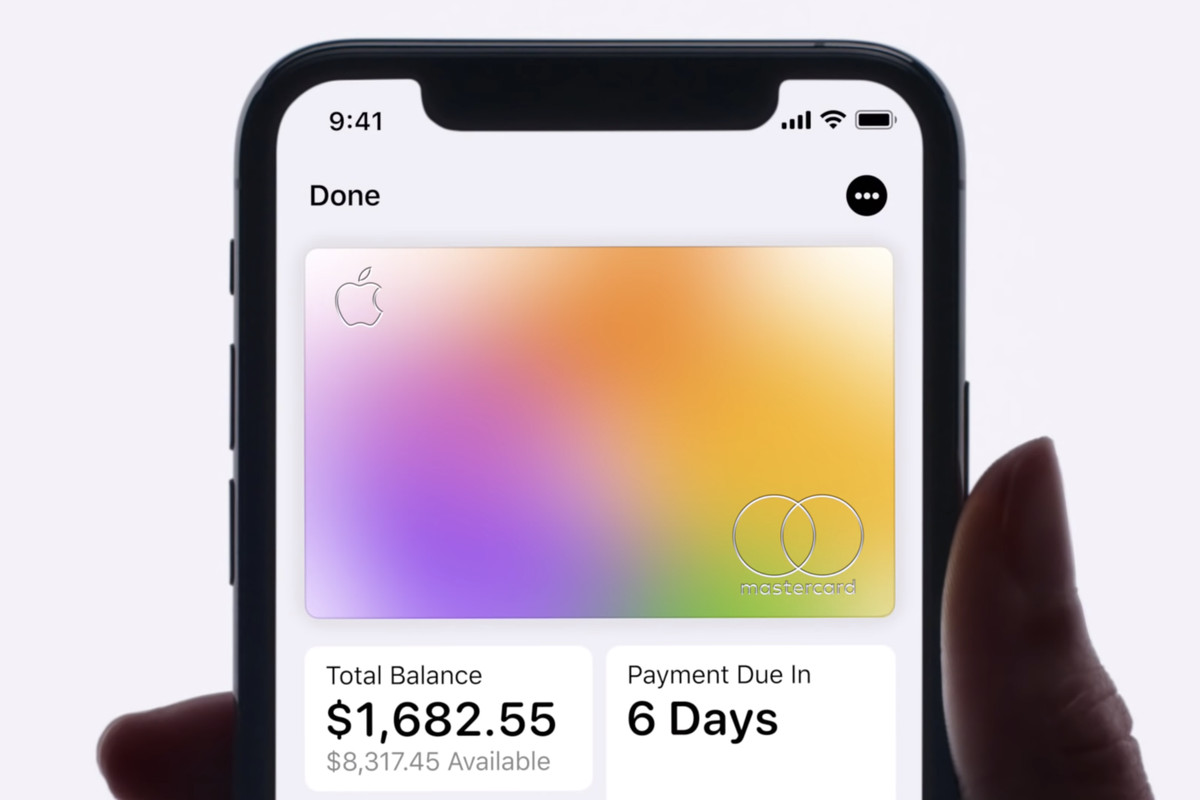
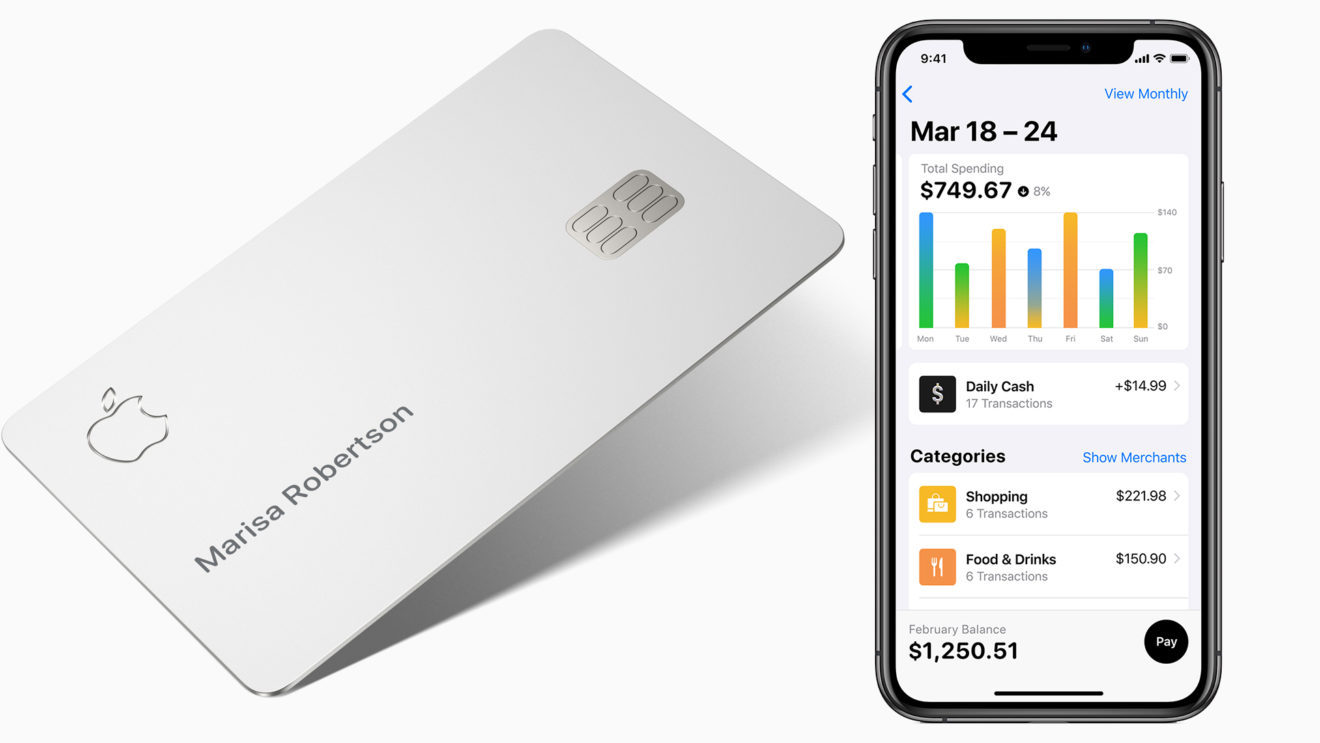
    Back in March, Apple introduced the Apple Card. The virtual card sits in the iOS Wallet app, although an actual physical card can be ordered. For privacy reasons that card will not include the account number, but will have the user’s name on the card. Apple Card users will face no fees. That’s right, say goodbye to Late fees, Annual fees, International fees, and Over-limit fees. Card users will get back 2% of the value of transactions made outside of the Apple ecosystem and 3% of those purchases made from the App Store, Apple Store, and other Apple properties. Transactions paid for with the physical card will get 1% back. These rebates will be computed daily and made available each day.

    The card is expected to launch sometime this month and investment banking firm Goldman Sachs is Apple’s partner for this project. Goldman Sachs has posted the Apple Card Customer Agreement and this reveals some interesting things. First of all, depending on the card user’s credit ratings, the annual interest on the card will range from 13.24% to 24.24%. Future changes will be based on any rate hike or cut made to the Prime Rate. This is the rate that banks charge their best customers for loans.

    To be eligible for an Apple Card, you must have an Apple ID that is associated with a valid iCloud account. There must be an active email address connected to the Apple ID, with Apple’s two-factor authentication turned on. And those iPhone users who “jailbreak” their phone to remove iOS software restrictions are at risk of having the account closed. In addition, the Apple Card cannot be used to buy casino chips, lottery tickets, and cryptocurrencies. In other words, you can’t use the Apple Card to buy Bitcoins. This is probably not devastating news for the majority of consumers looking to open an Apple Card account.

    “If you make unauthorized modifications to your Eligible Device, such as by disabling hardware or software controls (for example, through a process sometimes referred to as “jailbreaking”), your Eligible Device may no longer be eligible to access or manage your account. You acknowledge that use of a modified Eligible Device in connection with your Account is expressly prohibited, constitutes a violation of this Agreement, and could result in ours denying or limiting your access to or closing your Account as well as any other remedies available to us under this Agreement”-Apple Card user agreement.

    So if you own a jailbroken iOS device, you’re not allowed to use it to apply for the card. And if you have an iPhone that you used to obtain a card, you cannot jailbreak it. Pretty simple rules. In fact, all of the terms and conditions of the Apple Card can be found on the Goldman Sachs website.

    The Apple Card will be another business in Apple’s Services unit. After the iPhone, this segment is the second-largest in terms of revenue for the company, and it is the tech giant’s second most profitable division. Apple is aiming to hit $50 billion in annual revenue by next year for the Services group, double the $25 billion the unit grossed in 2016. For Apple’s fiscal third-quarter covering April through June, the company reported record Services revenue of $11.5 billion. The reason why this business is so important to Apple is that it is less dependent on iPhone shipments and is more dependent on the global active number of iPhones. At the beginning of this year, that number was approximately 900 million. Other businesses under the Services umbrella include the App Store, iCloud, Apple Music, Apple TV+, Apple News+, Apple Arcade (once it launches), AppleCare, Apple Pay and more.

  • DBS 2Q Net Profit Rises On Sustained Business Momentum

    DBS 2Q Net Profit Rises On Sustained Business Momentum

    DBS Group’s second-quarter net profit rose 17 percent from a year ago as the lender’s total income reached new highs.DBS’ recorded net profit of S$1.60 billion, 17 percent higher than a year ago due to sustained business momentum.

    The results reflect the strengths of an entrenched broad-based franchise that is well placed to nimbly navigate market volatility and capture opportunities as they arise, said DBS Chief Executive Piyush Gupta in a media statement.

    Net interest income, the difference between interest collected versus interest paid to depositors, increased by 9 percent to S$2.43 billion due to loan growth of 5 percent, while net interest margin improved six basis points to 1.91 percent.

    Net fee income rose 9 percent to a new high of S$767 million, on the back of investment banking, wealth management and cards.

  • Citi To Cut Hundreds Of Trading Jobs

    Citi To Cut Hundreds Of Trading Jobs

    Global banks continue to feel the pinch from slowed trading with Citi joining its peers to lighten their trading operations with hundreds of related jobs expected to be axed in 2019.

    The American lender is expected to slash jobs according to multiple media reports. A Bloomberg report noted that the job cuts will occur over the course of the year and will be focused on its fixed income and equity trading business, including 100 jobs in the latter—nearly 10 percent of the whole division.

    Excluding a one-off sales of a stake in a trading venture, combined revenue from fixed income and equity trading fell 5 percent at Citigroup in the second quarter.

    A drop in trading revenue has affected the banking sector as a whole, especially American banks which have a heavy reliance on the business. The five largest American Wall Street banks reported an 8% decrease in trading revenues in the second quarter after a 14 percent decrease in Q1.

    In addition to weaker sentiments and market uncertainty, numerous longer-term structural drivers have been in play to pressure bank’s trading businesses. Hedge funds, traditionally the major revenue source for bank trading, has failed to recover from its heydays and faces outflows due to competitive low-cost funds. Online trading has not only taken significant market share from banks but continues to pressure margins.

    Citi joins Deutsche Bank as the latest heavyweight to headline job cuts in trading. Earlier this month, the German lender announced plans to exit equity trading and cut 18,000 jobs globally.

  • Apple Pay is gaining popularity

    Apple Pay is gaining popularity

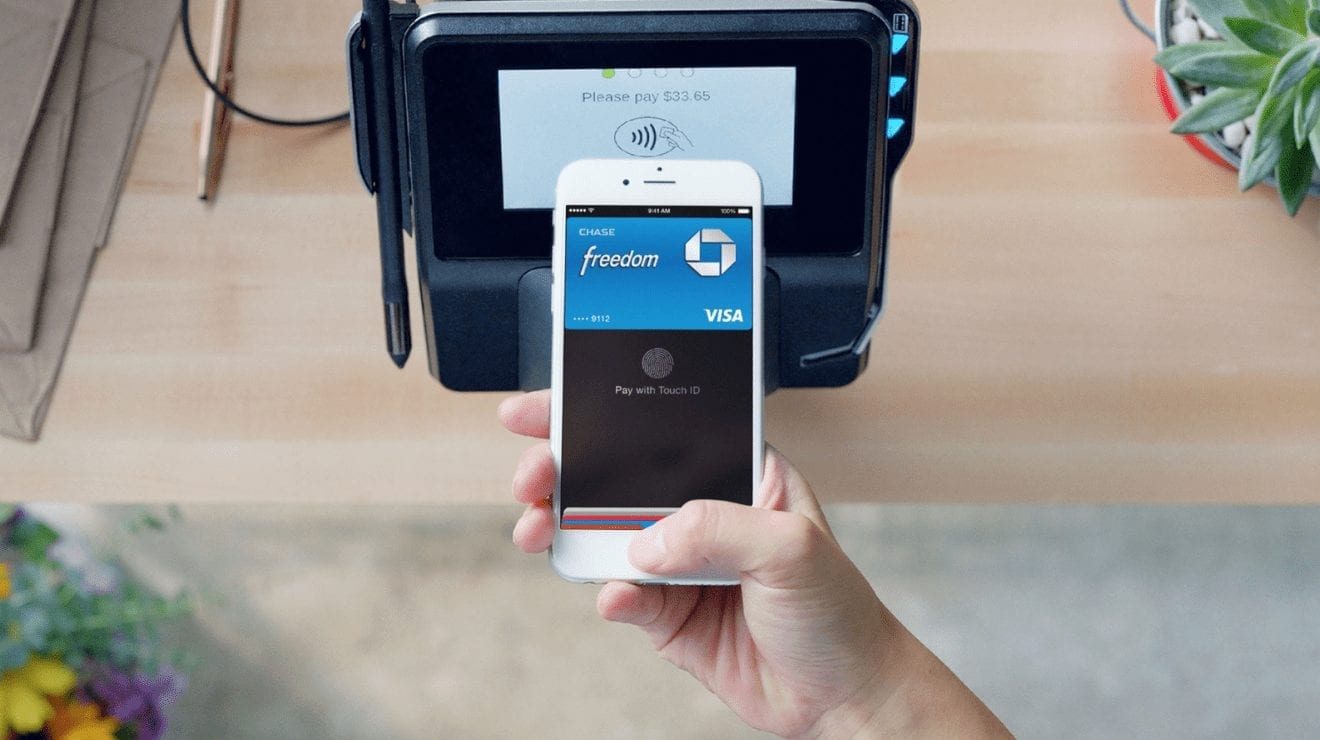
    Apple’s Services business generated record revenue of $11.5 billion during its fiscal third quarter. This is Apple’s second-largest unit and its most profitable. And one of the businesses in this segment is Apple Pay. This is Apple’s mobile payment system and the company takes .15% of the value of each transaction rung up on the platform. For example, if someone with a compatible device (iPhone 6 and later, iPad Air and later, Macs sporting Touch ID and all Apple Watches) uses the system to make a $100 purchase, the company takes 15 cents. That might not sound like a lot of money, but multiply that by the number of transactions a month that use Apple Pay and you can see how this can be a lucrative business for Apple.

    So how many transactions a month involve Apple Pay? The tech titan said during today’s earnings call that its payment platform is used on nearly 1 billion purchases each month. And that is close to doubling the number of monthly transactions that Apple Pay was involved in last year. According to CEO Tim Cook, “Based on June quarter performance, Apple Pay is now adding more new users than PayPal and monthly transaction volume is growing four times as fast.” During the quarter, Apple Pay was rolled out to 17 new countries and is now available throughout the European Union. Cook says that the service can be found in 47 markets.

    Apple also is expanding the number of transit systems that use Apple Pay. It has already added support for TriMet, Portland’s mass transit system, and has started rolling out support for the massive New York City transit system. Later this year, Chicagoans will be able to use the system to cover fares when commuting.

    “In the United States, in addition to successful integration into Portland’s transit system in May, we’re beginning the rollout of New York City transit, and will launch in Chicago later this year. In China, Apple Pay launched the payment card for Didi, the world’s largest ride-hailing provider. As I’ve said before, transit integration is a major driver of a broader digital wallet adoption, and we’re going to keep up this push to help users leave their wallet at home in more and more instances.”-Tim Cook, CEO, Apple

    After Apple iPhone shipments worldwide peaked at 231.22 million units in 2015, the manufacturer decided the next year to focus on its Services unit. This was a good idea because much of the revenue in this segment is recurring such as subscriptions for Apple Music and Apple News+ (and soon, Apple Arcade). Also in this category is AppleCare, iCloud, the App Store and more. The company set a goal of $50 billion in Services revenue for 2020, double the amount it garnered in 2016. This part of Apple’s business is dependent on the number of active iPhone units (900 million at the beginning of this year). As a result, growth in shipments is nice to have but is not nearly as important.

    Based on the firm’s fiscal third-quarter report, the Services unit is currently generating revenue at a rate of $46 billion on an annual basis. But $50 billion in gross next year can be achieved if Apple Pay and Apple Music continue to grow and if Apple Arcade captures the imagination of mobile game players.

    Overall, Apple reported fiscal third-quarter revenue of $53.81 billion up from $53.27 billion. Net profits decreased from $11.52 billion during the same period last year to $10.04 billion. Earnings per share decreased to $2.18 from $2.34 during the 2018 quarter.

  • Apple Card expected to be launched in August

    Apple Card expected to be launched in August

    When Apple announced its card back in March, the company said it will be available at some point this “summer,” but didn’t commit to a certain date. Now that Apple added support for Apple Card in the latest iOS 12.4 update, we can expect the card to be made available very soon.

    Apple and Goldman Sachs Group have reached an agreement for the launch of the Apple Card in the first half of August, a person familiar with both companies claims.

    According to people familiar with the matter, the Apple Card was a complex project that “involved the mixing of two very different corporate cultures as the companies split up responsibilities for the project and worked together on the new technology.”

    To use the new Apple Card, iPhone users will have to sign up for the card using the Wallet app, which has been recently added support for this specific feature.

    It’s worth mentioning that the Apple Card uses a cash-back rewards structure instead of points, which means users will get 1% on purchases made with the physical card, 2% for Apple Pay transactions and 3% for purchases of Apple products and services.

    Keep in mind that while the Apple Card has been designed to be used mainly via Apple Pay, the Cupertino-based company said users will be offered physical cards for merchants that don’t accept Apple Pay.

  • Citi Asia Execution Services Head Joins From JPMAM

    Citi Asia Execution Services Head Joins From JPMAM

    Citi hires J.P. Morgan Asset Management’s former Americas head of trading to run its Asia Pacific execution business. Curt Engler has been named as Citi’s Asia Pacific (APAC) Head of Execution Services. A key focus under his leadership will be to ensure Citi’s franchise continues to embrace the latest technology to meet the changing needs of clients.

    Curt’s market knowledge of operating in the world’s largest equity market and the market infrastructure changes he has worked through will be invaluable for Citi and our clients as Asian markets continue to evolve rapidly, said Richard Heyes, Head of Equities, Asia Pacific, in a media statement on Thursday.

    Curt, who has worked in financial markets for over 20 years – joins from J.P. Morgan Asset Management (JPAM) in New York, where he was Head of Trading for the Americas. Prior to JP Morgan Asset Management Curt was a trader and analyst at Blackrock, in the Quantitative Equity Group.

    At J.P. Morgan Asset Management since 2010, Curt was responsible for the daily activity of the trading desk and oversaw the trading operations of over $250 billion in assets under management. He also led the build-out of trading technology to support significantly increased levels of automation and the usage of analytics to improve execution performance.

    Based in Hong Kong, Curt will be responsible for Citi’s regional execution business. where he will be responsible for Citi’s cash execution business that spans 12 markets across the region.

    «Asia-Pacific is a key market for our global equities business and I am confident this addition to the strong bench will support further growth with clients across the region,» said Dan Keegan, Global co-head of Equities.

  • DBS Inks Sustainability-Linked Loan in Indonesia

    DBS Inks Sustainability-Linked Loan in Indonesia

    The export financing sustainability-linked loan is the first of its kind in Indonesia. DBS Bank Indonesia has signed a sustainability-linked export financing loan with wooden door manufacturer PT Sumatera Timberindo Industry (STI), the bank said in a press release on Wednesday.

    DBS said the loan is evaluated based on a target of obtaining timber and raw materials from sources certified by the Forest Stewardship Council (FSC). Its interest rate will be reduced for each shipment of raw material that has an FSC certification that the raw material is responsibly sourced.

    STI is a FSC-certified company focused on responsible sourcing, manufacturing and exporting of sustainable-certified products. According to director Hidayat Ang, STI’s synergies with DBS in advancing sustainability support the company’s long-term growth and empower the local community to do good for the environment.

  • APAC Banks Face More Competition From Disruptors

    APAC Banks Face More Competition From Disruptors

    Technology and e-commerce disruptors such as Google, Alibaba and Apple are considered the biggest threat to banks, followed by payment players and Neo-banks, says Asia’s bankers.

    In markets where mobile payments have already taken root, banks and payment processors are battling tech companies on two fronts. They are working to retain their own retail card and current-account customers and attract new users to their apps and e-wallets. They also need to get and keep merchants on their side if they are to reap the economies of scale from a high-volume, low-margin sector, according to a study by The Economist Intelligence Unit commissioned by Swiss software firm Temenos.

    The survey, entitled «A Whole New World: How technology is driving the evolution of intelligent banking in Asia-Pacific», found that competition is intensifying between established retail banks and the technology and e-commerce disruptors that threaten to carve up the payment solutions market. Big tech giants Google, Alibaba and Apple are considered the biggest threat to banks (32 percent), followed by payment players such as PayPal, Ripple, and Alipay (28 percent) and Neo-banks such as Volt Bank, Varo Money and Monzo (25 percent).

    With these threats top of mind, 37 percent of Asia-Pacific bankers see mastering digital marketing and engagement as their top strategic priority by 2020.

    Asia-Pacific bankers are acutely aware of the race they find themselves in against technology giants that have the capital and scale to take market share from established players. Neo-banks are not far behind and have the flexibility to outmaneuver major banks on the margins. To remain relevant, retain customers and appeal to the evolving demands of younger generations, banks must master digital engagement, and quickly, said  Martin Frick, Managing Director of APAC at Temenos, in a media statement on Tuesday.

    To counter the possibility of losing customers to non-traditional banking competitors, some banks are following a “2 app” approach in order to counter non-traditional banking competitors. For example, Singapore’s DBS bank has its traditional banking phone app and PayLah!, an app that is used for transactions and lifestyle services. With over 1 million users for its PayLah! app, DBS DBS believes more users would come on board for its trusted data privacy and security measures.

    In contrast, big tech competition could struggle to ensure the trust of traditional bank users because of the high possibility of data leaks that have occurred in the past in the tech industry.

    One of the main issues being brought forward from the survey is how to regulate banking effectively across the APAC region. The survey highlighted the dangers of a deregulated banking environment with the dominance of the WeChat Pay and AliPay duopoly in China. Sopnendu Mohanty of the Monetary Authority of Singapore argues that a common data policy would be beneficial for the APAC region.

    A regional regulatory banking policy would be effective in creating a balanced and transparent intelligent banking industry, the survey highlights. The European Union’s General Data Protection Regulation could be an inspiration for how to push forward such regulatory oversight in the APAC region. These standards would be easier to implement in the digital economy than in the physical economy.

    Regulation across the region has developed disparately. In Australia, open banking is being driven by the government to increase competition within established regulatory frameworks. In other parts of Asia-Pacific, such as Singapore, open banking is primarily being driven by the players themselves propelled by their desire to remain competitive and resulting in a need for retrospective regulation. In China, tighter licensing and data protection rules are set to diminish Alipay and WeChat Pay’s duopoly across the broader region.

  • The popularity of online loans has not increased in Singapore

    The popularity of online loans has not increased in Singapore

    Analyzing statistics of search requests, analysts of the company compared trends of demand for online loans in Singapore, Indonesia, Vietnam and the Philippines. The findings show that the situation in Singapore differs from other countries  significantly. The demand in Indonesia, Vietnam and the Philippines demonstrates a clear ascending trend and fast development. However, in Singapore, with low development of online loans issued by alternative lending companies, there is no significant growth of their demand recorded by the systems for search analytics. At the same time, looking at the frequency of the search request of “online credit”, the increase is observed from late 2007 to 2015 and stops afterwards.
    The reason is the faster economic development and dense area of Singapore, as opposed to its multi-island neighbours. Consequently, the country has an advanced financial sector, which is accessible for all residents. Taking into account the general maturity of the digital sphere, it’s obvious that the fintech services started developing here earlier, but within the traditional banking sector.
    The legislative regulation of lending in Singapore also makes an impact. Limited interest rates make it more profitable for alternative lenders to work with the business community. According to the University of Cambridge, in 2017, 99% of issued alternative loans there fell under the business segment. In the Philippines and Vietnam, the situation is opposite: only 7% and 10% of loans respectively accounted for business sector. In Indonesia, the distribution is more balanced: 72% were business loans and 28% – consumer loans.
    Moreover, the demand for online loans is affected by the age of the population. According to the United Nations, the average age of Singaporeans is 40, Filipinos – 24, Indonesians – 28 and Vietnamese  – 30. The young age and lack of access to banking products are the main driver for the development of alternative lending in Indonesia, Vietnam and in the Philippines. This is confirmed by the statistics on 200,000 online loans issued by the companies of Robocash Group in Southeast Asia (the Philippines, Vietnam, Indonesia), where 49.9% of borrowers are under 30.
  • Consumer Fintech Use Goes Mainstream

    Consumer Fintech Use Goes Mainstream

    The use of fintech products and services in Singapore has grown substantially in the past two years, though the country still lags China and India by a large margin.

    The fintech adoption rate among Singapore consumers has almost tripled to 67 percent in 2019 from just 23 percent in 2017, according to the «Global FinTech Adoption Index 2019» published by professional services firm EY.

    The report, its third edition, was based data gathered from an online survey of over 27,000 consumers in 27 markets. Leading the index were mainland China and India, which both recorded 87 percent consumer fintech adoption, followed closely by Russia and South Africa (both 82 percent).

    Singapore has enjoyed significantly increased rates of consumer fintech adoption and we expect even higher rates in the future, due to the supportive regulatory environment. Singapore may be a relatively small business-to-consumer (B2C) market by size, but it is a hotbed for innovation and a great launchpad for startups and businesses to build their technology, test it, and then scale across Southeast Asia, Varun Mittal, EY Global Emerging Markets FinTech Leader, said.

    The report credited fintech’s phenomenal rise to the increasing consumer and SME awareness and engagement with fintech products and services. When the report was first published in 2015, the average global adoption rate stood at 16 percent. It is now 64 percent, with money transfers and payment services driving awareness globally.

    Crucially, EY noted that maturing fintech challengers are having a growing influence on the market, actively driving legacy and non-financial organizations to develop their own fintech products and services.

    Among other findings, the report said that consolidated platforms have an edge, with 6o percent of consumers preferring to access services through a single platform, and that non-financial players are on the rise, with 68 percent of respondents saying they are willing to consider a financial proposition by a non-financial company.