Tag: Finance

  • Bapcor refinances debt, gains access to $520m

    Bapcor refinances debt, gains access to $520m

    Autobarn-owner Bapcor has successfully entered into a new $520 million debt package with existing lenders and new financier Metropolitan Life Insurance Company (MetLife) to establish an improved debt platform.

    One of the largest institutional investors in the world, MetLife is joined in the financing by ANZ, Westpac, MUFG Bank and HSBC.

    According to the business, the new package provides increased headroom, improved terms and pricing, as well as a new tranche of long-term debt.

    “The new debt facility has improved terms and pricing and provides significant flexibility for Bapcor going forward,” Bapcor chief financial officer Greg Fox said in a statement to investors.

    “We are pleased to have the ongoing support of our existing relationship banks and the addition of MetLife provides Bapcor with added diversification and an extended debt maturity profile.”

    The package includes funding in three-, five- and seven-year tranches: with a three-year $70 million tranche available for working capital requirements, as well as a three-year $200 million tranche, $150 million five-year tranche, and a $100 million seven-year tranche, all available for general corporate purposes.

    Bapcor said its net debt had reached $350.9 million as of the end of 2018, having increased $61 million compared to June 2018.

  • UOB and Zilingo tie up to drive the growth of ASEAN’s fashion industry

    UOB and Zilingo tie up to drive the growth of ASEAN’s fashion industry

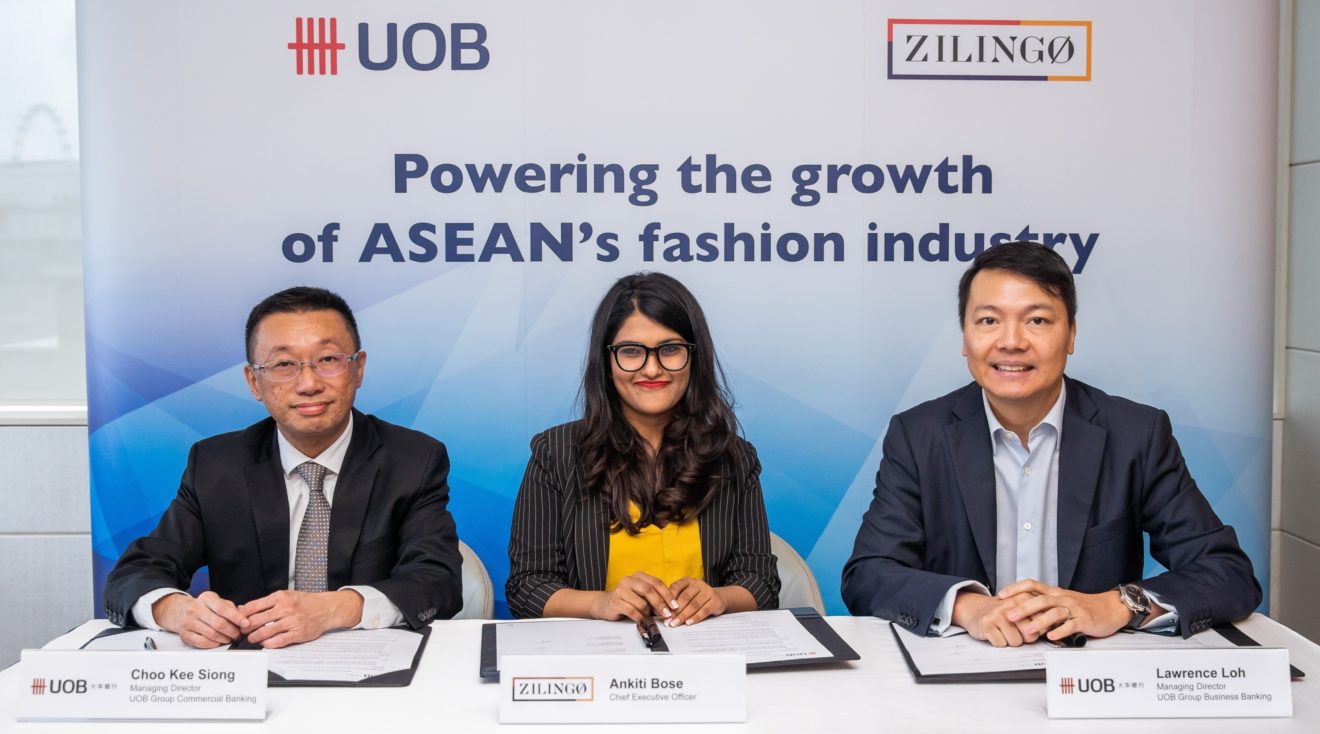
    United Overseas Bank Limited (UOB) and Zilingo, a fashion and lifestyle e-commerce platform, today announced that they have signed a Memorandum of Understanding (MOU) to support the growth of ASEAN’s fashion industry. Under the MOU, businesses on Zilingo’s platform, which are mostly small- and medium-sized enterprises (SMEs), will be able to access UOB’s banking solutions through the e-commerce platform. The greater access to banking solutions will enable Zilingo’s merchants and manufacturers across the region to manage their cash flow better and to grow their businesses more efficiently and easily.

    Ms Ankiti Bose, CEO and Co-founder, Zilingo, said, “Through this collaboration with UOB, we want to reaffirm our commitment towards empowering merchants and manufacturers with everything they need to run their business. Where businesses may find difficulty in accessing capital due to insufficient financial records, Zilingo’s unique position as a connector of the fashion supply chain will allow us to leverage a bird’s eye view of the supply chain to make a comprehensive assessment of the business’ capabilities and value proposition”.

    Mr Choo Kee Siong, Head of Industry Groups, Group Commercial Banking, UOB, said, “At UOB, we have been working with various ecosystem partners to offer our banking products and services to companies across entire supply chains, helping them pursue growth strategies and seize business opportunities. Through our MOU with Zilingo, fashion businesses across ASEAN will be able to access our comprehensive range of banking solutions seamlessly to meet their operational and financial needs.” In addition to supporting Zilingo’s merchants, UOB will also explore support for the e-commerce platform in a number of other areas, from cash management and foreign exchange services to workplace banking services

  • IMF head warns fintech could disrupt world’s financial system

    IMF head warns fintech could disrupt world’s financial system

    International Monetary Fund (IMF) Managing Director Christine Lagarde warned on Saturday that the increasing presence of technology giants using big data and artificial intelligence could cause a significant disruption to the world’s financial system.

    The rapid development of financial technology (fintech) has increased access to cheap payment and settlement systems for low-income households in emerging countries where traditional banking networks are scarce.

    But it has raised concern about the increasing dominance of big technology firms in mobile payments, which could force global policymakers to rethink the way they regulate the banking system and ensure financial settlements are executed safely.

    “A significant disruption to the financial landscape is likely to come from the big tech firms, who will use their enormous customer bases and deep pockets to offer financial products based on big data and artificial intelligence,” Lagarde told a symposium on financial technology held on the sidelines of the G20 finance leaders’ meeting in Fukuoka, southern Japan.

    While such innovation may help modernize financial markets, they could make the financial system vulnerable such by putting payment and settlement systems under the control of a handful of technology giants, she added.

    “This presents a unique systemic challenge to financial stability and efficiency, and one I hope we can touch on during the G20, and address in a cooperative and consistent fashion.”

    Lagarde said China presents an example of the trade-off between benefits and challenges posed by financial technology.

    “Over the last five years, technology growth in China has been extremely successful and allowed millions of new entrants to benefit from access to financial products and the creation of high-quality jobs,” she said. “But it has also led to two firms controlling more than 90% of the mobile payments market.”

    Addressing the pros and cons of financial innovation is among topics of debate at the two-day meeting of Group of 20 finance ministers and central bank heads that began on Saturday.

  • Battle for HK Retail Customers Begins as HSBC Scraps Fee

    Battle for HK Retail Customers Begins as HSBC Scraps Fee

    As banks in Hong Kong brace for fierce competition from virtual banks, HSBC on Wednesday said it is scrapping minimum balance fees and associated charges.

    HSBC announced on Wednesday that it will scrap the minimum balance fee that applies to its 3 million customers in Hong Kong. From August 1, it will be the first bank in Hong Kong to go back to providing free basic banking services to retail customers who hold its passbook accounts, statement accounts, personal and advance integrated accounts and super ease accounts.

    To reinforce HSBC’s commitment as Hong Kong’s leading bank, it will also waive off associated charges faced by small depositors, like counter transaction fees.

    «More than 3 million retail banking customers will benefit from the removal of our below-balance fees, counter transaction fees and annual fees for most our personal savings accounts,» said Greg Hingston, HSBC’s head of retail banking and wealth management in Hong Kong, who was quoted in «South China Morning Post».

    Introduced 18 years ago, the monthly charge of HK$50 for small depositors with a passbook savings account and other basic accounts with a balance below HK$5,000 (US$640), is seen as a penalty on some of the bank’s most loyal customers.

    The move comes as the Hong Kong Monetary Authority (HKMA) issued eight virtual bank licenses since March. The virtual bank licensees, who operate solely online, are not allowed to charge a minimum balance fee to small depositors. Such zero-cost bank accounts would likely lure millions of customers away from banks who are still charging small depositors.

    The move is likely to be followed by other big lenders as they brace for the intense competition from the virtual banks due to come online later this year. Hang Seng Bank, a unit of HSBC, is also considering a plan to scrap its minimum-balance fee, according to a spokesperson.

    «Banks should draw up their fees structures in accordance with their own corporate strategies, service models and costs,» an HKMA spokesperson said. «However, the HKMA has constantly reminded banks to keep in mind the public’s expectations and needs in basic banking even while they run their banks based on business principles.»

  • Grab explores digital-only banking licence in Singapore

    Grab explores digital-only banking licence in Singapore

    Grab, Southeast Asia’s most valuable start-up, is exploring a move into Singapore banking as regulators in the Southeast Asian city-state consider allowing online-only banks, four people with knowledge of the process said.

    Grab is close to hiring a consultancy to advise it on its banking potential and is gearing up to apply for a digital-only bank licence in Singapore if the banking regulator decides to open up the sector, said the people, who declined to be identified as they were not authorised to speak to the media.

    Singapore-headquartered Grab’s interest in what would be its first foray into banking has not been reported before.

    When asked for a response, the Monetary Authority of Singapore (MAS) referred Reuters to its comments issued last month when it said it was studying the potential for allowing “digital-only banks with non-bank parentage” into its market.

    Hong Kong, Singapore’s fierce financial centre rival, began issuing licences earlier this year.

    A potential entry by Grab – backed by Japan’s SoftBank Group Corp – and others would mark the biggest shake-up in years for a market dominated by DBS Group Holdings Ltd, Oversea-Chinese Banking Corp and United Overseas Bank Ltd.

    The MAS could make a decision in the next couple of months on whether to admit digital-only banks with non-bank parentage, as well as the eligibility applicants, the people said.

    The city-state’s banking regulator is likely to issue only two to three licences in the first phase, two of the people said.

    The interest from Grab underscores how Asia’s non-banking firms are keen to challenge traditional banks by leveraging their technology and their user databases to offer banking services to retail customers and small businesses.

    Securing a digital banking licence in Singapore could help seven-year-old Grab to benefit from its existing data on transport movements, payment transactions and consumer behaviour, the people said.

    Last year, Grab teamed up with Japan’s Credit Saison Co Ltd to provide loans in Southeast Asia.

    Global fintech players are among other groups expected to seek licences in Singapore, with some of them looking to form joint ventures, said two of the people.

    Consultants said a digital banking licence could also appeal to Singapore Telecommunications Ltd (Singtel), which is expanding beyond its traditional carrier services into areas such as mobile payments and cybersecurity.

    “It is too premature to comment but having ventured into mobile financial services, we are open to exploring the feasibility of such an opportunity should it arise,” a Singtel spokeswoman said in an emailed response.

    In Hong Kong, affiliates of Alibaba Group Holding Ltd and Xiaomi Corp, and consortia led by Standard Chartered PLC and BOC Hong Kong Holdings Ltd were among those who won the digital-only banking licences.

    “In Hong Kong, the guidelines were quite precise in terms of what applicants had to prove in order to get a virtual banking licence, more so than in Europe,” said Dan Jones, APAC partner at consultancy Capco Digital.

    “It will be interesting to see whether MAS goes down a similar route to Hong Kong … so that the only people who can apply are established companies, rather than literal start ups.”

    As in Hong Kong, online-only banks in Singapore are also expected to launch by offering services such as savings accounts, personal loans and travel insurance, two of the people said.
  • Citi’s Retail Business Grows Despite Branch Cuts

    Citi’s Retail Business Grows Despite Branch Cuts

    Citi has closed hundreds of branches in Asia in recent years, shrinking its network from 600 to roughly 250, according to «Reuters.» Despite downsizing its physical network, Citi is benefitting from the increasing shift towards digital banking among retail banking customers.

    This (digital banking) has kind of evened the playing field for us because today, customers are online. We are no longer relying on having the number of branches to reach out to them, especially in a market like Singapore, said Charles Wong, Citibank Singapore’s head of retail banking.

    Last October, Citi rolled out a virtual remote engagement feature for Singapore clients to speak with relationship managers on demand using screen sharing and video capabilities. The following month, it revamped its Citi Mobile app to offer a cleaner user interface and new features such as a multi-currency wallet.

    The bank is also targeting to enable customers to open accounts with the bank digitally in the third quarter of this year. The aim is to enable all branch transactions to be carried out on the mobile app within the next two to three years.

    Citi’s bets to serve retail banking clients via its mobile app and online services in Singapore appear to be paying off – its first-quarter revenue this year was up about 10 percent from a year ago, even as its physical branches have been cut back from 18 to 15 last year.

    Digital acquisitions of retail banking customers grew 20 percent in Q1 from the year-ago quarter, said Wong. «In terms of how we generate interest and leads in the digital world through digital partners, versus generating leads through the traditional marketing channels, that has come up significantly as well,» he added.

  • Facebook reveals its new digital currency called Libra

    Facebook reveals its new digital currency called Libra

    As expected, Facebook announced a brand new cryptocurrency coming in 2020 – Libra. Described as a new digital wallet for new digital currency, the new financial service will allow consumers to keep their cryptocurrency safe, as well as make various transactions.

    When it launches in 2020, the digital wallet will be available in Messenger, WhatsApp, but also as a standalone app. The decision to launch such a service is based on the people’s need to save, send or spend money even if they don’t have a bank account.

    Apparently, many people around the world still don’t benefit from even basic financial services, especially in developing countries. Calibra, the company behind the financial service, is meant to address this problem since it will allow those who don’t have a bank account to save, send and spend Libra.

    Most importantly, Calibra will allow users to send Libra to almost anyone with a smartphone just like sending a text message. Additional services will be provided to those using Libra later on, including the option to pay their bills.

    Facebook says that Calibra will not share account information or financial data with its servers or any third party without customer consent. Furthermore, the social network company mentions that Calibra will use Facebook data to comply with the law, secure customers’ accounts and prevent criminal activity.

    It remains to be seen what merchants will accept Facebook’s new crypto currency and how companies in developing countries will be convinced to pay their workers in Libra if they so choose.

  • HSBC Bolsters Asia Technology M&A Team

    HSBC Bolsters Asia Technology M&A Team

    HSBC Holdings has hired Jeremy Choy to head its Asia Technology Mergers & Acquisitions (M&A) team, a Hong-Kong based role that will also see him work with technology companies in areas such as initial public offerings and financing, Bloomberg reported, citing unnamed sources close to the matter.

    Choy, who is expected to start in his new role as early as next week, joins HSBC from boutique investment bank China Renaissance, where he worked for 4 years, most recently as managing director and head of M&A. He will report to Rajeev Sahney, the bank’s head of Asia-Pacific advisory and corporate, Bloomberg said.

    According to his LinkedIn profile, Choy also worked for J.P. Morgan’s North Asia M&A team for 4 years, was an M&A advisor at PacBridge Capital Partners for 2 years, and worked for Goldman Sachs for 5 years.

    Bloomberg reported that the volume of technology, telecommunications and media deals in Asia-Pacific is down 47 percent from the year before.

    However, it noted several large deals on the horizon, including the sale of a major stake in gaming company Nexon Co. and a potential share sale in Hong Kong by Chinese internet giant Alibaba Group.

  • Naver’s Latest Move and the Rise of New Payment Methods in Japan

    Naver’s Latest Move and the Rise of New Payment Methods in Japan

    Trends come and go in the retail world, but one which undoubtedly appears to be here to stay is the shift in how consumers now choose to pay for goods and services.

    Physical cash has played an important part in retail for decades, but a recent announcement involving South Korean internet firm Naver has put a spotlight on how new payment methods are becoming increasingly common in Japan.

    Mobile payments system

    Earlier this month it was confirmed that the company has launched a mobile payments system which can be used in Japanese stores. According to the Korea Herald, the Naver Pay service now features a tool known as Cross-Border, which allows people to make payments via a QR code on their smartphone or tablet.

    Naver Pay chief Choi Jin-woo told the media outlet that the move was the company’s “first step” into Japan and was based around providing a “convenient service” to customers wherever they are.

    While it is thought that the move will help Koreans travelling to the country, the announcement is also arguably another sign of the major changes being seen in how people pay for different items across the world.

    Going cashless

    A huge number of countries have embraced the idea of going cashless by using new payment methods, with the likes of Canada, Sweden and the UK thought to be among those leading the way.

    The types of services which have made the move possible include Google Pay, Apple Pay and, of course, the likes of PayPal. The latter is thought to have a total user base of 277 million accounts, with 255 million of those being consumers.

    Many businesses have worked hard to keep up with the consumer appetite for new payment options, and evidence of this can be seen in a range of sectors. For example, Amazon Pay allows people to use payment methods linked to their Amazon account to pay for services on other sites. In addition, this site offering Japanese NetBet casino games gives users a chance to make deposits via a range of means including Neteller, Skrill, Entropay and Trustly. Companies like Subway and Expedia have even flirted with cryptocurrency in the past too.

    Set for growth

    According to payment technology provider InComm, it is thought that around 20 per cent of all payments in Japan are currently made with methods other than cash, and it is thought that the government is keen to boost this further in the next six years. When did the organization reveal this? In an announcement that it had partnered with DFS to launch barcode payment solutions in the country.

    The world of payments is undoubtedly changing, and it will be fascinating to see whether all of the innovations emerging in Japan will ultimately mean the country rises up the rankings when it comes to going cashless. In addition, it will be vital that retailers can stay on top of these trends to ensure they can continue to meet consumer demand.

  • SHB Finance issues certificates of deposit worth millions

    SHB Finance issues certificates of deposit worth millions

    SHB Finance has issued its fourth tranche certificates of deposits worth a total of VND300 billion ($12.88 million). These were 12-month deposits with an annual interest rate of 10.3 percent and no transfer fees.

    The SHBank Finance Company Limited (SHB Finance) issued the certificates of deposits for its fourth tranche as part of its book-building process. This issuance attracted prestigious institutional investors, including one domestic investment fund and one securities company.

    On April 25, SHB Finance had successfully issued its third tranche certificates of deposit with the same interest rate.

    Explaining the factors that make SHB Finance’s certificates of deposits attractive to investors, CEO Dinh Quang Huy said that although the company was a new player in the consumer finance market (official launch in August 2018), it has gained the attention of many institutional investors, thanks to its efficient and speedy operating system.

    “We always try to be transparent to investors at all time, not just when we need to raise funds. Therefore, our certificates of deposits are always welcomed by investors, even though timing of tranches are quite close,” Dinh said.

    The company announced positive business results in the first four months of 2019, very soon after it commenced operations. SHB Finance ended April 2019 with outstanding loans of VND1.44 trillion ($61.84 million), up 103 percent compared to 2018, fulfilling 39 percent of the plan for 2019. With the fourth tranche, SHB Finance has successfully raised VND900 billion ($38.65 million), VND810 billion from certificates of deposit and VND90 billion from deposits. The funds will help SHB Finance serve immediate consumer finance demands of low to medium income customers across the country, contribute to the development of a healthy consumer finance market and eliminate rampant shadow banking activities.

    Its profit before tax as of April 2019 had reached VND71.6 billion ($3.08 million).

    The company has served over 150,000 customers.

  • VinID acquires MonPay e-wallet in Vietnam

    VinID acquires MonPay e-wallet in Vietnam

    Vingroup’s loyalty program VinID has acquired digital wallet app MonPay, a central bank source says.  The takeover procedures have been completed but did not disclose its form and value.

    Earlier this week, a new feature called “My Wallet” has appeared on the VinID app where customers can accumulate points from goods and services bought from Vingroup’s ecosystem, which includes real estate, education and shopping.

    From this feature, customers can deposit and withdraw money as with any electronic wallet, and all transactions go through MonPay. MonPay is a product created and run by local firm People Care JSC.

    Previously, at the end of 2018, People Care completely replaced its management board with three key executives from VinID, including Nguyen Thi Diu, deputy general director of Vingroup and general director of VinID; and Nguyen Minh Hong, one of three founding shareholders of VinID.

    VinID JSC was established in July 2018. It has a chartered capital of VND3 trillion ($128.81 million) and is 80 percent owned by Vingroup, Vietnam’s biggest private conglomerate.

    People Care JSC is one of 29 enterprises that have been granted the payment intermediary license from the State Bank of Vietnam. The company doubled its charter capital from VND68 billion ($2.92 million) to VND138 billion ($5.93 million) at the end of 2018, after it had reappointed its board of directors.

    The government is working to accelerate the use of cashless transactions. In a resolution released January, it tasked the central bank to come up with solutions that would promote the use of e-wallets, which allow users to deposit cash into their e-wallets without the need for a bank account.

    However, Vietnam is still far away from becoming a cashless society, given low financial literacy and the lack of an ecosystem, experts say.

    The use of cash in Vietnam remains high. World Bank’s statistics released last year showed that the country had the lowest percentage of cashless transactions in the region with only 4.9 percent, while this value for China and Thailand were 26.1 percent and 59.7 percent respectively.

  • HSBC Plans To Scale Up SME Business in Singapore

    HSBC Plans To Scale Up SME Business in Singapore

    HSBC, which has been present in Singapore since 1877, said it intends to increase its share in its target small-medium-enterprise (SME) market from the current 10 percent to 15 percent by 2021. HSBC classifies SME clients as those with a turnover of $5-$100 million.

    At a high level, we see Singapore as a de facto financial capital for Southeast Asia (ASEAN), as well as an attractive destination for our customers around the world,» said Alex Turner, managing director and head of commercial banking in HSBC.

    To support the growth in SME lending, the bank increased its headcount in business banking by 30 last year. As the SME lending space is highly competitive, HSBC country head of business banking Ng Li Lian said that the bank will tap on its advantages, such as having a dedicated relationship manager for each SME client.

    It also launched the Pioneer program in August last year to target fast-growing SMEs with minimum topline growth of 15 percent, especially those who wish to internationalize. Besides access to skills and capabilities, this 12-month program lets SME leaders have conversations with different teams within HSBC, such as speaking with its alternative finance team on how to raise capital other than through debt.

    For ASEAN to benefit from a wide-scale migration of supply chains into the region, the countries need to first improve on technology, capacity, and regional integration said HSBC Singapore CEO Tony Cripps.

    There has been a widespread sentiment that the supply chains of businesses are starting to shift to Southeast Asia (SEA) en masse, on the back of the trade war and the region’s vitality, but there has been little evidence of that happening, wrote Cripps in a report.

    ASEAN needs to build more visibility and credibility amongst international firms, particularly in their ability to handle and deliver production orders, he added.

  • DBS Chief Information Officer Retires

    DBS Chief Information Officer Retires

    DBS’ Chief Information Officer and Head Of Group Technology and Operations, is leaving the bank.  DBS has confirmed that its group head of technology and operations David Gledhill is departing effective from 1 August. He will return to the United Kingdom, according to his announcement on LinkedIn. The 57-year-old is a British citizen calls his departure a soft Glexit.

    After 29 years in Asia and 11 years at DBS, we decided it’s finally time to move on and replant our roots back in the U.K. So, after almost two years of planning, today we announced my retirement from DBS, and the Packers moved in at home,» Gledhill said in a LinkedIn post.

    Gledhill said he will stay connected with DBS in a part-time advisory role. Also an independent director with Singapore Airlines, Gledhill said he will also be back in Singapore every three months. Before joining DBS in 2008, Gledhill worked at J.P. Morgan for 20 years, holding senior regional positions in technology and operations.

    A DBS spokesperson said that Gledhill has been a leading figure in the bank’s transformation. He has been responsible for standardizing the bank’s systems, creating reliability and resilience, and most recently, taking DBS down the path of agile and cloud.

    Gledhill will be succeeded by Jimmy Ng, who has been deputy group head of technology and operations at DBS since January 2018. Having joined DBS in 2009, Ng started his career briefly as a system analyst in Singtel before joining the technology audit function in J.P. Morgan.

    He subsequently worked in various functions including operations, risk management and product control at ABN Amro.

  • UOB Outlines Growth Priorities

    UOB Outlines Growth Priorities

    Amid rising global trade tensions and concerns over a synchronized global slowdown, UOB wants to focus on three areas for growth. UOB wants to focus on regional connectivity, ecosystem partnerships, and strong balance sheet/quality earnings to harness growth, the bank said at its Corporate Day held in Singapore on Wednesday.

    In such an environment, it is even more important that we focus on the fundamentals and not lose sight of our main objectives, UOB’s chief executive Wee Ee Cheong underlined.

    In his keynote address, he added that with rising global trade tensions and concerns over a synchronized global slowdown, it was essential that the bank focused on its key priorities.

    At UOB, this rests on our consistent approach of putting our customers at the center, he said. The Corporate Day covered how UOB will continue to build on its regional operating model, to invest at scale in digital and new technology, to equip its people for the future and to drive productivity and performance.

    Currently, the bank has more than 40 percent of group operating profit derived outside of Singapore. Of this, close to 80 percent comes from operations in Southeast Asia and Greater China. «We expect these numbers to go up as we strengthen our regional connectivity, collaborate in win-win partnerships to tap intra-regional flows and the region’s rising affluence for growth,» Wee added.

    Southeast Asia has the third largest population globally, after China and India. The region also has a young population, with 384 million people below 35 years old.

    Given Southeast Asia’s prospects, the bank will continue to make significant investments in developing its digital capabilities to make banking simpler, smarter and safer across all its network. «Throughout the region, we have invested in an omnichannel approach: engaging our customers across a range of touchpoints that best suit them – offline or online, physical or digital or a combination. This is because we know that digital is not the only way that our customers want to be served,» Wee said.

    The impact of UOB’s omnichannel approach is enhanced by the ecosystems which the bank has forged with like-minded partners for the customer’s benefit.

  • Apple Pay focussing on wider NFC adoption

    Apple Pay focussing on wider NFC adoption

    Apple has been trying to replace your wallet with your iPhone for years now. Despite the relatively wide adoption of Apple Pay (at least in the States), however, it’s still not abundant enough to make you think twice about leaving your wallet at home. One of the main reasons for that is that Apple, in its typical fashion, has restrained the things developers can use the available hardware and software for. But it seems that might be changing very soon.

    Apple recently announced changes coming to the way NFC can be used on its iPhones in combination with Apple Pay during a conference for electronic transactions. Called Transact, the conference was held in Las Vegas in late April and was host to a rare Apple presentation that’s not during one of the company’s own events.

    Apple is looking to make it easier for businesses to integrate NFC payments into the Apple Pay ecosystem. To do that, it is going to allow its Core NFC framework to work with multiple NFC formats. Currently, Apple only supports one format called NFC Data Exchange Format. Three new formats are expected to be added with the release of iOS 13. These changes, among many others, will likely become official during Apple’s Worldwide Developers Conference 2019 that starts on June 3.

    But NFC formats don’t matter to users, they care about what that means for the way they use their devices. There will be some noticeable improvements in that area if Apple’s plans come to fruition. The company’s goal is to make paying for almost everything as easy and convenient as possible. Let’s take a look at what’s its vision.One example given at the presentation was the so-called micro-mobility, which is a fancy term for all the scooter-renting services like Bird and Lime. Right now, each of those comes with its own app that you can use not only to locate a scooter but mostly to pay for your time using it. Needing an app and an account adds friction, as experts call it, which reduces the number of people that use the service. Apple is working in cooperation with some of these companies to remove that extra step. In the future, tapping on the NFC chip of the scooter will allow you to rent it straight from Apple Pay. This will not only make it easier for non-frequent users to rent scooters but will also improve security, as you’re not sharing payment information with yet another entity.

    And then there are parking meters. The ones that allow mobile payments come with their own app as well. Similar to the scooter approach, Apple aims to cut out the unnecessary step of installing and logging into various apps (companies still get their money, after all) by handling everything within Apple Pay. The same technology can be applied to almost anything, from vending machines to public transport and all sorts of venues that you need to pay to get into.

    But NFC is not only useful for payments, but it can also carry all sorts of information. A few companies are already partnering with Apple to streamline the sign-up process for their loyalty programs by using NFC instead of paper forms people need to fill out.

    Once the ball starts rolling, we’ll likely see more and more businesses joining Apple’s initiative. This move will strengthen its ecosystem and tie down iPhone users to the brand even more than they already are. Hopefully, it will also nudge Google to put more effort into its own Google Pay.