Tag: Finance

  • Techcombank targets US$504.3 million in pre-tax profit

    Techcombank targets US$504.3 million in pre-tax profit

    Techcombank has targeted a pre-tax profit of more than VNĐ11.7 trillion (US$504.3 million) in 2019, representing a 10 per cent year-on-year increase.

    The target was approved at its annual shareholders’ meeting held in Hà Nội last week.

    It also planned to increase its total assets by 17 per cent to VNĐ375.8 trillion this year while holding outstanding loans at VNĐ245.4 trillion, up 32 per cent from last year. Its bad debts would be limited to less than 2.5 per cent in 2019.

    In 2018, Techcombank achieved high business results. Its pre-tax profit was up 32.7 per cent from the previous year at more than VNĐ10.6 trillion.

    These helped the bank achieve return on average assets (ROAA) of 2.9 per cent and return on average equity (RAE) of 21.5 per cent.

    Nguyễn Lê Quốc Anh, Techcombank’s CEO, said the two criteria had not only been among the highest among banks in Việt Nam but also surpassed big scale banks in India and Thailand.

    In addition, Techcombank successfully mobilised capital to raise its capital adequacy ratio (CAR) to 14.3 per cent, much higher than the level stipulated by the State Bank of Vietnam as well as the minimum level according to Basel II.

    Techcombank was among the few commercial banks last year which were assigned higher credit growth limits of 18 per cent with priority given to those who met Basel II’s capital safety and risk management standards ahead of schedule.

    “The bank plans to grow revenue by 20-30 per cent a year and retain 20 per cent of profit. In order to increase revenue, instead of growing debt balance, the bank would focus on raising fees (expected to account for 50 per cent of the total revenue),” Anh said.

    He added that Techcombank always focused on controlling credit growth from the central bank to ensure sustainable growth of the economy.

    Anh said Techcombank was among the banks to have successfully resolved bad debt. All of its debts were sold to VAMC and totally resolved two years ago. It had also well controlled credit quality by its strict risk warning and management system.

    With its profits listed in the top three banks in the country’s banking system in 2018, Techcombank’s shareholders agreed to continue to retain earnings to invest in creating growth momentum in the future.
    Hồ Hùng Anh, the bank’s chairman, said the bank wanted to retain profit to strengthen its equity and ensure the requirements of the central bank and Basel II are met.

    At the meeting, shareholders also approved a plan to issue 10 million shares under the Employee Stock Ownership Plan (ESOP) programme at a price of VNĐ10,000 to increase its charter capital to more than VNĐ35 trillion.
    The bank said it would focus on growth contributed by service fees thank to implementing a modern banking transaction system for corporate customers and improving their experiences through online payments and life insurance products.

    In addition, it would develop new solutions in house lending, car lending, credit and payments to meet increasing demands of customers.

    Anh added the bank would start construction of two new buildings on Lý Thường Kiệt Street (Hà Nội) and Lê Duẩn (HCM City) this year. The two buildings are expected to become operational in 2021.

    Hồ Hùng Anh was re-elected to the position of chairman of Techcombank’s board of directors for the third consecutive term.

    Other members include Nguyễn Đăng Quang, Nguyễn Thiều Quang Nguyễn Cảnh Sơn, Đỗ Tuấn Anh, Lee Boon Huat, Saurabh Narayan Agarwal and Nguyễn Nhân Nghĩa.

    The new management board would continue to implement its customer-centric strategy, invest in technology to develop a digital foundation and big data while improving risk management to reach high ratings with prestigious ratings organisations.

  • UOB Partners Local E-commerce Platform To Mine Opportunities

    UOB Partners Local E-commerce Platform To Mine Opportunities

    United Overseas Bank has partnered with a popular e-commerce platform to build ecosystem partnerships. This follows a string of partnerships announced with other high profile online platforms.  United Overseas Bank (UOB) announced a regional alliance with local e-commerce platform Qoo10 on Monday, complementing the bank’s efforts to help small businesses seize opportunities in the digital economy. Qoo10, with more than three million buyers, is the top e-commerce platform in Singapore.

    «Our alliance with Qoo10 enables us to extend our touchpoints to provide small businesses with the financing they need directly on the e-commerce site, helping them to take advantage of opportunities quickly as they arise,» said Lawrence Loh, Head of Group Business Banking at UOB.

    In January this year, Qoo10 launched QuuBe, a blockchain-based e-commerce platform which already has more than two million products on the marketplace. Through the alliance, Qoo10 will be able to tap UOB’s holistic suite of financial solutions to help consumers and merchants buy and sell products more easily on both the Qoo10 and QuuBe platforms.

    «Partnering established and trusted allies such as UOB enables us to empower our merchants and customers with readily accessible solutions that provide greater financial flexibility in running a business or making purchases,» says Ku Young Bae, CEO of Qoo10.

  • Investor Groups Attack UBS

    Investor Groups Attack UBS

    UBS faces pressure from shareholders ahead of an investor meeting next month. The opposition centers around a nearly $12 million windfall for CEO Sergio Ermotti and a prolonged French legal tussle.

    UBS’ investor meeting on May 2 promises to be a heated one: U.S. investor group ISS is recommending shareholders deny UBS’ management and board for 2018 a so-called dispensation, which is a peculiarity of Swiss securities law which exempts managers from liability for their actions.
    The move adds to opposition to UBS’ pay practices from Glass Lewis, which last week said it will oppose the Swiss bank’s compensation report. Geneva-based Ethos views the 73.3 million Swiss franc ($73.1 million) bonus pool for UBS’ top 13 executives as inappropriate given the poor performance of the Swiss bank’s stock last year.

    CEO Sergio Ermotti is taking home 11.9 million francs in so-called realized compensation after contingent capital instruments that UBS gave him in 2012 matured. At the helm since 2011, Ermotti is Europe’s best-paid banking CEO. His bonus for 2018 is 4.5 times his salary (the metric is capped at 5 times his yearly salary). In contrast to Glass Lewis and Ethos, ISS said UBS’ pay practices by and large reflect those of the wider financial industry.

    The wealth manager has justified the pay with the fact that UBS’ net profit rose 12 percent on the year, its capital is solid, and it bought back 750 million francs worth of its own shares last year. Ethos criticized that shareholders suffered a nearly one-third drop in the value of their shares during that time.

    From 2016 until last year, shareholders sucked up a more than 28 percent tumble, far more dramatic than the 1.8 percent fall in the wider banking sector, Ethos said. «Ethos believes that UBS must introduce a performance target taking into account the relative performance of the bank’s share price», said the group, which holds sway with many of Switzerland’s weighty pension fund voters.

    The «nay» from ISS on releasing board and management for 2018 is purely pre-emptive, the shareholder advocate said – it is the first time since the financial crisis that shareholders have mounted opposition against top executives.

    ISS issued the recommendation in view of UBS’ long-running French criminal troubles, where the bank was recently hit with a 4.5 billion euro ($5 billion) fine (the bank shredded the decision and faces at least another two years of appeals process). The shareholder group said the move would simplify any potential legal steps against members of the C-suite later. Ermotti and chief lawyer Markus Diethelm are the architects of a pugnacious legal strategy in France.

  • Australian dollar slightly up again

    Australian dollar slightly up again

    The Australian dollar has dipped slightly, buying 71.70 US cents from 71.69 US cents on Monday.

    On Monday morning, the dollar was buying 71.71 US cents from 71.61 US cents on Friday.

    Last Friday morning, the local currency has fallen, buying 71.25 US cents from 71.61 US cents on Thursday.

    It had flatlined near a six-week peak as losses on Asian share markets chilled risk sentiment somewhat.

  • South Korean bank launches hand palm recognition verification

    South Korean bank launches hand palm recognition verification

    A South Korean bank has launched a service allowing customers to use palm recognition to withdraw cash – a likely precursor to similar technology becoming available in retail stores.

    KB Kookmin Bank says by using palm prints, customers no longer have to use a bankbook, stamp or password.

    The bank explained that palm vein recognition is safer and more precise than other biometric identification methods such as fingerprint or iris recognition. It believes the service will appeal to older customers who often have difficulty recalling passwords.

    According to a report, using palm recognition is also quicker than current means. Palm vein patterns differ by individual, allowing the scanner to correctly identify the customer.

    Similar palm-vein scanners are already being used at automated teller machines (ATM) from major banks worldwide, including Barclays in the UK and Ogaki Kyoritsu Bank in Japan.

    To prevent biometric information from leaking, the bank will encrypt the vein pattern database and work with the Korea Financial Telecommunications and Clearings Institute to store the information. The data will be disassembled into multiple blocks when stored, and reassembled when used for transactions.

    KB Kookmin Bank expects that the new palm-recognition service will particularly benefit senior customers who often have a hard time remembering passwords.

  • Vietnamese banks find out car loans not low-hanging fruit

    Vietnamese banks find out car loans not low-hanging fruit

    Vietnamese banks are struggling to recover overdue car loans since many customers mortgage vehicles bought using bank loans. Dao Minh Tuan, manager of the debt recovery department at private lender Vietnam International Bank (VIB), said 50 percent of non-performing car loans are because of this.

    Borrowers are supposed to get the bank’s permission before pawning a car, but most don’t, which makes it difficult for the bank to repossess the car, he said.

    “Pawn shop owners decline to meet our staff while our customers are unreachable. As the banks do not technically own the car, we have trouble recovering the debt.”

    Since banks normally lend 80-100 percent of the cost of a car, getting the cars back by paying off pawnbrokers would cost too much, he said.

    “The last resort would be to sue the customer, but this will take a long time and cause damage to both sides.”

    Banks also have to pay a commission to car dealers of 0.7-1 percent and offer competitive interest rates of 7-9 percent in the first year. All this means, in a competitive, crowded segment, banks are unable to earn much.

    A banking expert who asked not to be named said: “Banks which want to maintain high credit growth often focus on increasing the amount of car loans, not quality.”

    Those focused on this segment are usually banks which are not competitive in other areas with higher interest rates, such as real estate, the expert said.

    The auto loans segment has seen average growth of 38 percent in 2012-2016, according to data from Viet Capital Securities VCSC.

  • Vietnamese stocks slide as lack of information hits large-caps

    Vietnamese stocks slide as lack of information hits large-caps

    Vietnamese shares slid yesterday as large-cap companies faced strong selling amidst a lack of supportive information while investors awaited discussions on the amended securities law. The benchmark VN-Index on the Hồ Chí Minh Stock Exchange fell 0.91 per cent to end at 988.48 points.

    The southern market index climbed 0.84 per cent on Monday.

    More than 165 million shares were traded on the southern bourse, worth VNĐ4.24 trillion (US$182 million).

    Market breadth was negative with 207 declining stocks, while 111 stocks advanced and 45 ended flat.

    Fifteen of the 20 sector indices ended Tuesday on a negative note, dragged by real estate, energy and petroleum, rubber and plastics and consumer staples.

    Those sector indices lost between 1.1 per cent and 3.1 per cent, data on vietstock.vn showed.

    The energy and petroleum sector was the worst-performing one on the stock market.

    Petro stocks such as PetroVietnam Gas (GAS) and PetroVietnam Drilling and Well Services (PVD) reversed after oil prices encountered volatility on Tuesday.

    GAS shed 1.9 per cent while PVD slipped 3 per cent.

    Real estate firms also dragged the market down, with the industry index falling 2 per cent.

    Among the worst-performing property developers were Vincom Retail (VRE), Vingroup (VIC) and Hòa Bình Construction Group (HBC).

    According to MB Securities Co (MBS), the VN-Index slid as leading stocks moved in different directions and pressured market sentiment.

    Foreign selling also caused negative movement for the stock market, which ended at a net VNĐ277.4 billion, MBS said in its daily report.

    In addition, gloomy earnings forecasts for 2019 for listed companies weighed on investors’ confidence ahead of the National Assembly Standing Committee meeting on April 10-18, in which the draft on amended Law of Securities will be discussed, MBS noted.

    “The stock market is clearly in its instability stage as large-cap stocks are still heavyweights. It is likely the VN-Index will fall whenever large-cap stocks are hit by strong selling,” Thành Công Securities Co (TCSC) said in a note.

    In addition, listed firms are experiencing a lack of supportive information, making investors unwilling to buy their stocks and reducing market liquidity, TCSC said.

    Therefore, the VN-Index may struggle at the current level of 990 points in the next trading days with focus shifted to companies with positive first quarter earnings, the company said.

    On the Ha Noi Stock Exchange, the HNX-Index slid 1.12 per cent to end at 107.71 points.

    The northern market index climbed nearly 1 per cent in the first trading day of the week.

    Nearly 48 million shares were traded on the northern bourse, worth VNĐ669 billion.

  • Argomall partners with CoinGate to adopt Bitcoin and cryptocurrency payments

    Argomall partners with CoinGate to adopt Bitcoin and cryptocurrency payments

    Online shopping website Argomall.com now takes payment in cryptocurrencies and is the first Filipino online retailer in Southeast Asia to accept Bitcoin and around 50 other cryptocurrencies as payment.

    In line with Argomall’s value proposition of personalized convenience, it has added cryptocurrencies, also called Altcoins, to its already wide list of payment options, which include cash on delivery (COD), credit/debit cards, online installment via Home Credit, online banking, over-the-counter payments in banks and non-bank institutions, G-cash and PayPal.

    This option became available on April 1 and is only available for straight payments.

    Argomall partnered with CoinGate to make this project possible. CoinGate is an online trading platform for Bitcoin, Ethereum, Litecoin, XRP and other coins like: Bitcoin Cash (BCH), Sirin Labs (SRN), Telcoin (TEL), Nano (NANO), TRON (TRX), Dai (DAI), Bitcoin SV (BSV), Zcash (ZEC), Ethereum Classic (ETC), Augur (REP), Dogecoin (DOGE), Golem (GNT), DigixDAO (DGD), Wings DAO (WINGS), iEx.ec (RLC), Decred (DCR), Stellar (XLM), Basic Attention Token (BAT), Aragon (ANT), Bancor Network Token (BNT), Civic (CVC), EOS (EOS), TenXPay (PAY), OmiseGo (OMG), Monaco (MCO), 0x Protocol Token (ZRX), Qtum Ignition (QTUM), Storj (STORJ), FunFair (FUN), Salt (SALT), Bitcoin Gold (BTG), DigiByte (DGB), district0x (DNT), Power Ledger (POWR), Populous (PPT), Bread (BRD), Noah (NOAH), Binance token (BNB), Polymath (POLY), Kyber Network (KNC), TrueUSD (TUSD), Mithril (MITH).

    In a report by Entrepreneur magazine: “Compared to its Southeast Asian neighbors, the Philippines has been relatively more open to using Bitcoin and other cryptocurrencies, according to a report in FT.com, the Financial Times newspaper’s online site.” It will be recalled that the Bangko Sentral ng Pilipinas (BSP) released a circular in February with regulations for businesses that want to sign up as a virtual currency exchange. It is the only central bank in five countries cited in the FT.com report to do this.

    Some 2.9 percent of Filipinos are adopting Bitcoin, according to a survey conducted by FT.com, second only to the 3.3 percent of Indonesians doing the same. Overall, Southeast Asia’s cryptocurrency adoption rate is 2.5 percent.

    According to a report written by Financial Times’ Confidential Research analysts Prinz Magtulis and Andi Haswidi: “Among the five ASEAN countries we survey, the Philippines has made the most regulatory progress. Since February, its central bank has required all exchanges to obtain a permit for trading cryptocurrencies and to register with the country’s Anti-Money Laundering Council. They are also subject to annual fees. We expect the rest of Asean-5 to follow, in response to concerns that Bitcoin is being used to fund terrorism and other crimes.”

    Prominent global companies that accept Bitcoin include Microsoft, British Airways, McDonald’s and Shopify.

    Established in November of 2015, Argomall grew out of a creative dream by the Filipino-owned conglomerate Transnational Diversified Group to deliver trustworthy and efficient solutions to the discerning Filipino tech shopper.

    “These solutions,” Argomall Chief Argonaut Karel Holub said, “now include the opportunity to pay in Bitcoin and around 50 more Altcoins, because it is part of our mission and vision at Argomall to make the discovery, selection and purchase of smartphones—or any other related gadget—in the Philippines easy, while providing the best service on the internet to our consumers.”

    “Enabling online shoppers in the Philippines to pay with Bitcoin and around 50 more Altcoins is our way of providing good service, as well as opening up another means by which to earn,” Holub said. “This, to us, is a win-win situation where everyone gets good benefits. After all, our vision is that anyone in the Philippines will be able to easily upgrade their smartphone from anywhere, anytime—and that includes giving our customers all the ease and convenience they need to do just that. We aim to make their new device shopping journey as easy and comfortable as possible.”

    CoinGate Marketing Manager Veronika Mishura said this partnership with Argomall is a large step for cryptocurrency adoption, adding that this is CoinGate’s first such integration in Southeast Asia. Moreover, Mishura said, using cryptocurrencies as payment for online purchases present a cheaper and faster alternative to traditional payment methods.

    “Crypto-adoption among retailers is definitely what we need to strive for,” Mishura said. “When more stores accept digital currencies, more users are prompted to buy all types of goods with cryptocurrency. This is exactly what crypto-industry needs for recognition that would lead to it becoming a standard payment method along with credit cards.”

    “Technologies like Lightning Network have already made it more convenient and profitable for businesses to accept cryptocurrency rather than fiat,” she added. “We are thrilled to have Argomall on board. Hopefully, Philippine crypto enthusiasts won’t stay aside, and will start using this new payment method!’

    While Argomall does not endorse the purchase of Bitcoin or any of the other 50 or so Altcoins, the company provides opportunities for those who do have these cryptocurrencies to pay with them at argomall.com in a safe way.

  • Millennials in Singapore eshew power and famefor self-fulfillment and caring for the community

    Millennials in Singapore eshew power and famefor self-fulfillment and caring for the community

    The majority of Singapore millennials are extremely passionate about social causes such as human rights, poverty and helping the elderly, and prefer to gain life experiences when they have the financial means, rather than physical possessions.

    These key insights of millennials were revealed in the inaugural annual FRANK by OCBC survey, the FRANKly Asked Questions, which aims to understand and track four psychographic variables – values, attitudes, interests and desired experiences – of millennials over time. Conducted between January and February 2019, 866 students and young working adults aged 16 to 29 years old were asked a total of 50 questions in an online survey. Forty-five per cent of the respondents were students from all Singapore universities and polytechnics.¹

    An integrated banking programme for millennials in Singapore

    OCBC Bank created the FRANK by OCBC banking programme in 2011. It remains the only programme which provides millennials with banking products and solutions designed for them as they go through milestones in life as tertiary students, to entering the workforce as young professionals. FRANK by OCBC offers millennials deposit accounts, credit and debit cards, insurance, investment products and study loans. The other programme activities in place today include:

    • Financial literacy seminars organised regularly for FRANK by OCBC customers to learn how to invest and manage their finances
    • Helping youths give back to the community

    o   Organising youth dives to clean up the reefs of plastic waste

    o   Supporting campus programmes such as at Prinsep Street Residences, where SMU students organise overseas Community Involvement Programmes and programmes to support the elderly in the Bras Basah area

    • Helping youths prepare for future careers

    o   FRANKpreneurship – learning human-centred design and start-up business principles as they are mentored by The Open Vault at OCBC and different teams in OCBC Bank to tackle real banking challenges

    Insights from the FRANKly Asked Questions survey will help FRANK by OCBC develop more comprehensive programmes on financial literacy and beyond to meet millennials’ holistic needs. They will include:

    • Helping youths to build their wealth

    o   Looking to introduce new investment and insurance products which will be affordable for youths

    o   Organising financial seminars with partners such as SGX to learn the basics of investing

    • Helping youths to raise awareness of environmental issues

    o   Supporting #noplastics initiatives by distributing reusable tote bags at the NUS FRANK store and Cheers and FairPrice outlets at NUS

    Mr Dennis Tan, OCBC Bank’s Head of Consumer Financial Services Singapore, said: “The ‘FRANKly Asked Questions’ is the first FRANK by OCBC survey that we will be conducting annually. The survey has revealed insights into the psyche of millennials today and the values and attitudes they hold dear. In addition to the deep and rich insights that we already have from banking with one in two youths in Singapore, this enables us to tailor products and services that they will find useful at every stage of their lives and help achieve their aspirations.”

    Key Insights from FRANKly Asked Questions (see attached slides)

    Youths are motivated to discover their inner selves, care for their family and society, and are less likely to be materialistic in nature

    o   86% of millennials are motivated to understand their inner selves, compared to being famous (32%)

    o   3 in 4 millennials are concerned about their parents’ finances for retirement, and find it important to help others

    o   Less than half of millennials want to gain physical possessions when they have the money

    They understand the importance of a well-rounded education, value work-life balance at the workplace, and are practical

    o   82% of millennials feel that internships and working experience is crucial; 73% agree that getting a degree is a necessity

    o   Work-life balance is their top consideration for an ideal job

    o   83% of millennials want to secure a job with regular income, rather than start a family (46%) or start a business (37%)

    o   70% of millennials will only consider marriage once their career is stable

    They are generally positive in their financial attitudes, but more could be done to keep them informed and educated about investments and insurance

    o   41% of millennials struggle to stick to their saving plan

    o   While 69% of millennials want to start buying insurance policies and 71% want to start investing, less than half of millennials consider themselves knowledgeable about insurance and investments

    They are interested in bigger societal issues and new technologies, but are less interested in entrepreneurship and freelancing

    o   The top 5 most important social causes millennials care about are human rights (82%), poverty (81%), the environment (79%), helping the elderly (79%) and mental health awareness (79%)

    o   Millennials are more excited about the Internet of Things (73%) and Artificial Intelligence (62%) than going cashless (59%) or self-driving cars (57%)

    o   Less than half of millennials are interested in starting a business in the next five years, or being a freelancer

    They value gaining life experiences to value-add to themselves, and are constantly seeking to broaden their horizons and skillsets

    o   82% of millennials say gaining life experiences will be a priority when they have the financial means

    o   82% want to maintain relevant skillsets, which is their top motivation for pursuing higher education

    o   76% like to try new and different things, and half of them often try out new and trendy restaurants

    New ‘borderless’ FRANK Store at NUS

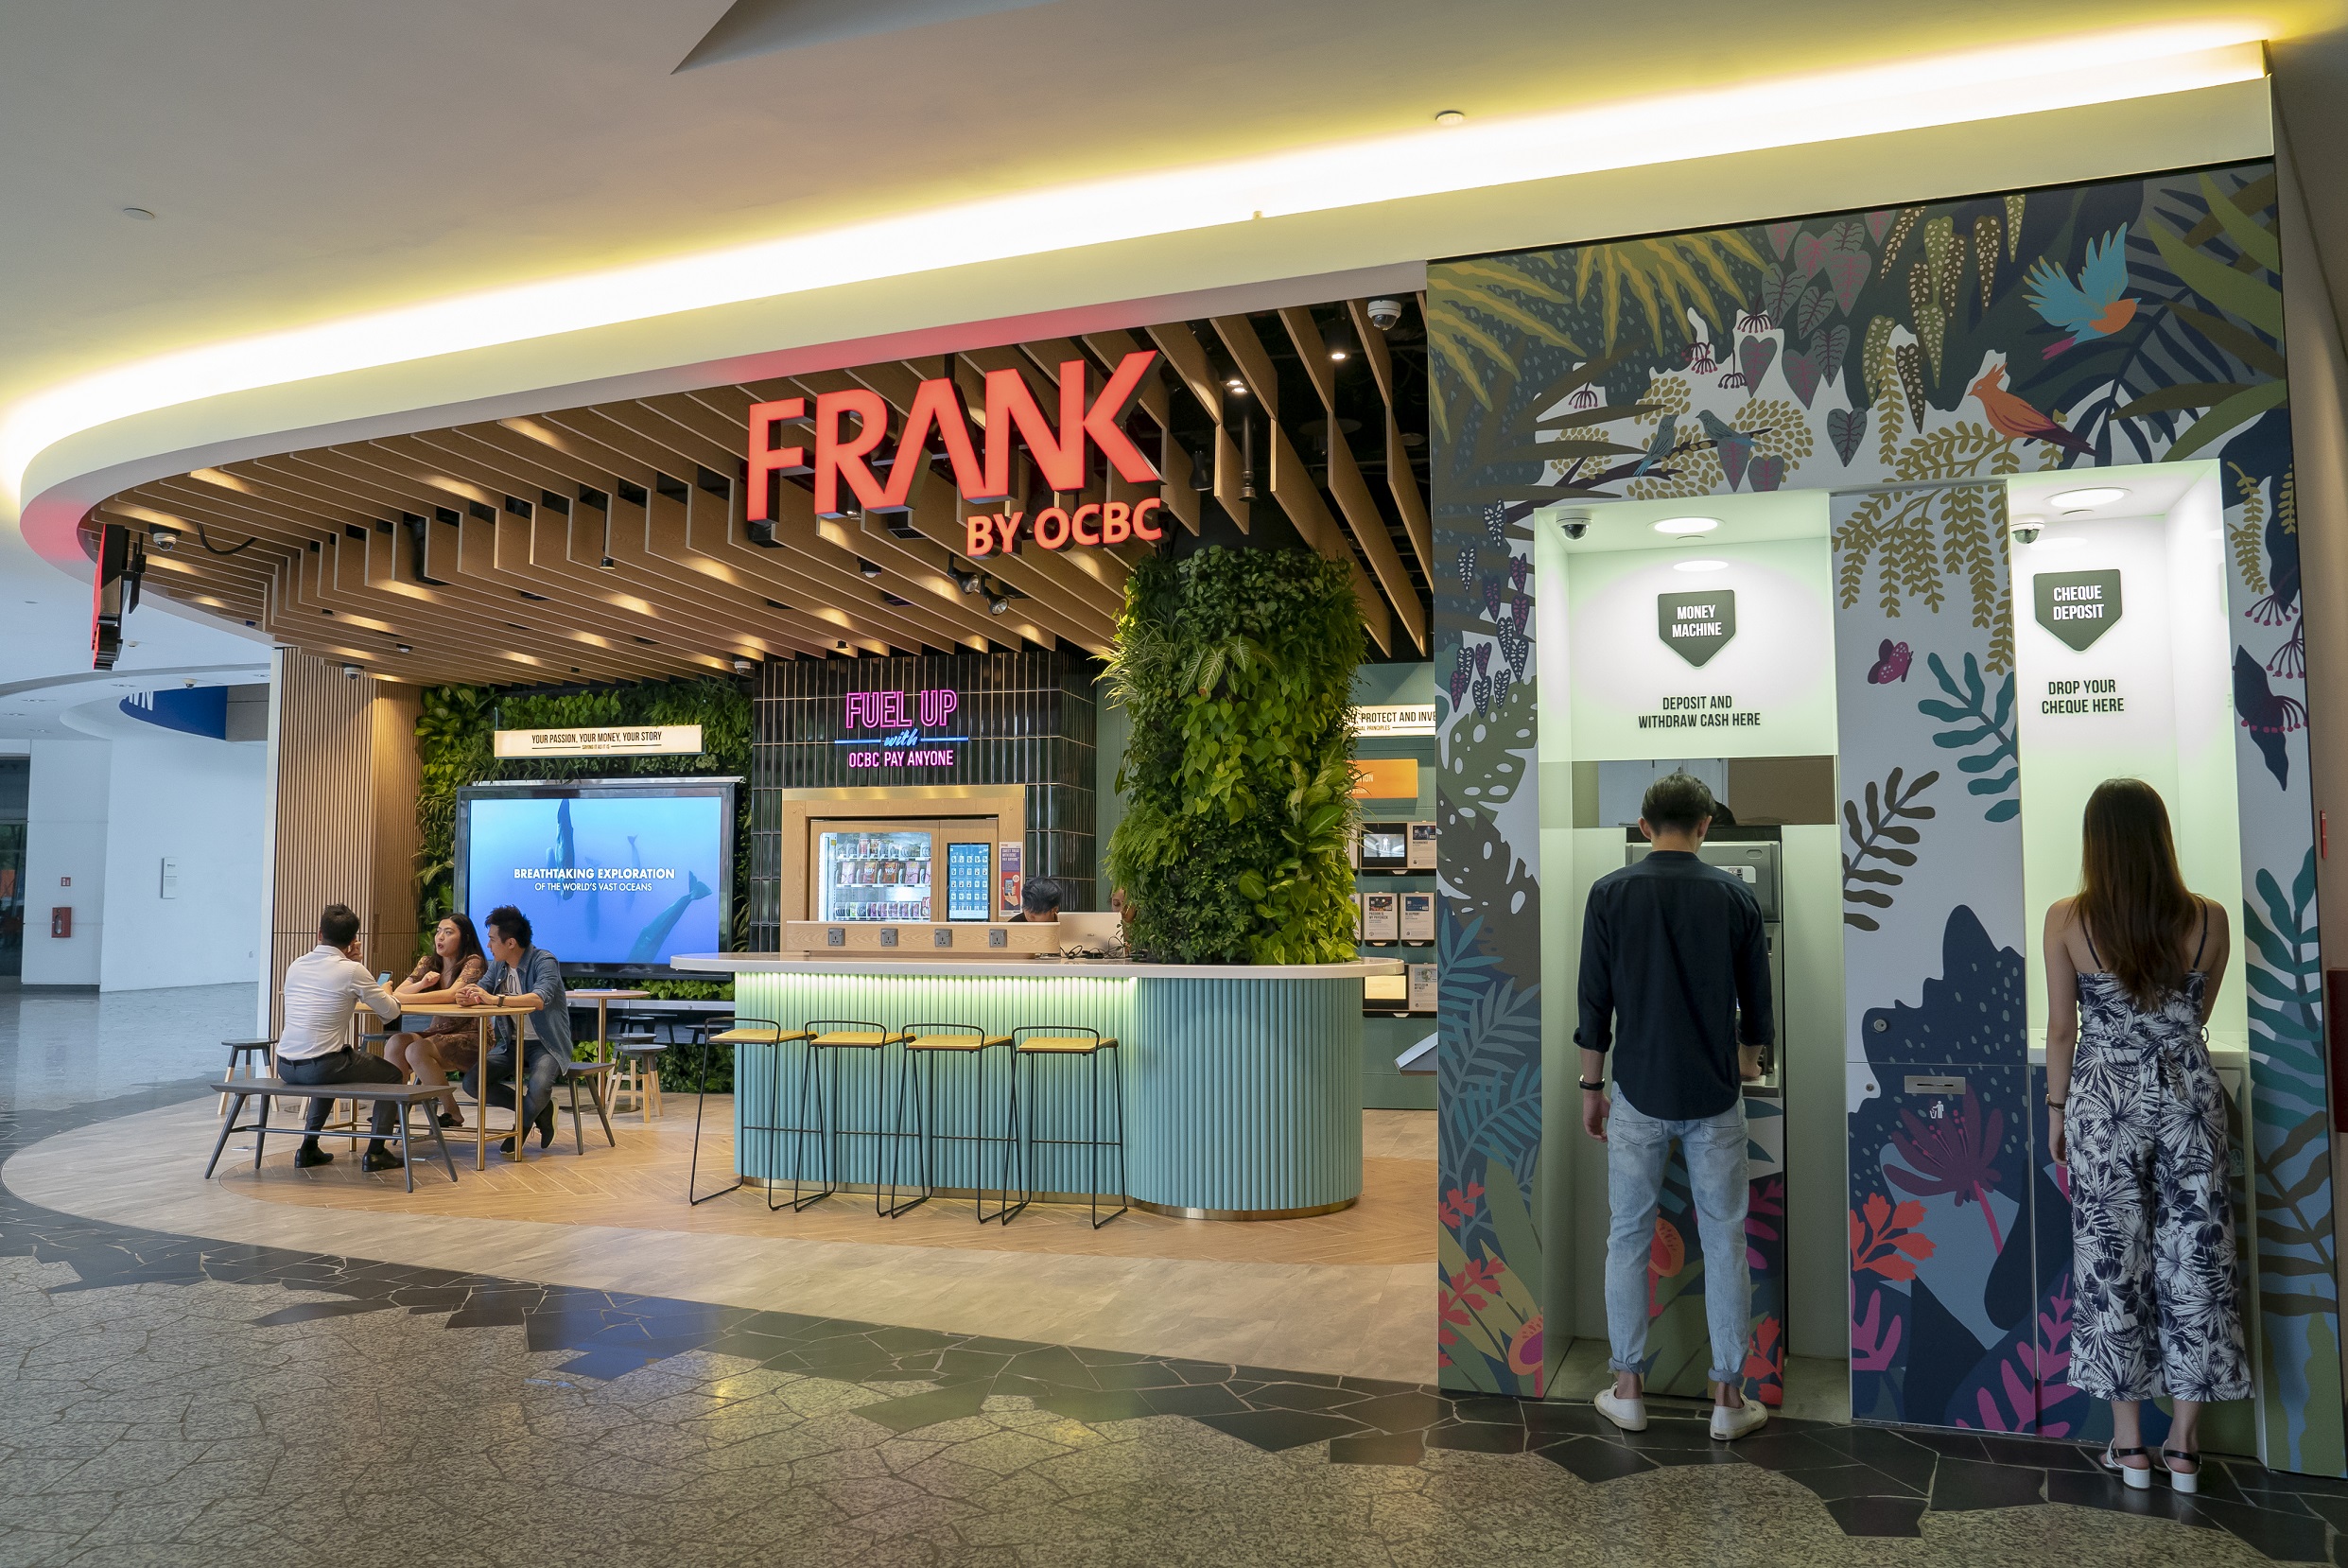
    The survey comes on the heels of the opening of the fourth and newest FRANK by OCBC Store at the National University of Singapore (NUS) last month. Taking over the space at the Stephen Riady Centre at University Town (UTown), which was previously a sports shop, OCBC Bank won a public tender for the space by offering to build a bank branch to offer students an essential service, and at the same time, add vibrancy to UTown through the creative design and use of the space. Occupying an area of 947 square feet, the FRANK by OCBC Store at NUS is a testament to the deep knowledge and insights FRANK by OCBC boasts in understanding the interests of millennials and integrating banking and financial literacy into their lives to make it accessible and relatable. The new FRANK by OCBC Store integrates features that are desired by millennials – borderless and digital interactions, environmental sustainability and a casual setting for banking.

    Like all other FRANK by OCBC Stores, the Store at NUS is designed differently from a traditional bank branch, making it attractive for students to come into the Store to take their time to browse and ask questions about banking products and services, play games or catch up with their friends over coffee.

    The new Store at NUS is Singapore’s first borderless and open-concept bank branch that does not utilise shutters or barriers after operating hours, and has no teller counters.

    Students interact with banking staff – known as FRANK Ambassadors – at the store’s collaboration areas, and can access the store round-the-clock to study or to get snacks at the cashless vending machine using the OCBC Pay Anyone mobile payments app. A ‘Future of Banking Zone’ highlights new mobile and Internet banking features on the latest iPads and iPhones, and enables students to try out digital banking services, including interacting with chatbot ‘Emma’ about study loans.

    The other FRANK by OCBC stores are located at Singapore Management University, Nanyang Technological University and orchardgateway mall.
  • Legacy Banks Must Become Agile, Says Citi

    Legacy Banks Must Become Agile, Says Citi

    New entrants and increased competition brought about by challenger banks could result in revenue losses of up to 30 percent among legacy banks over the next 10 years. While digitalization can lower costs for incumbent banks by 30 to 50 percent, new competition and greater transparency in the banking market, prompted by the emergence of challenger banks driven by fintech startups, are likely to lower revenues by 10 to 30 percent in the next decade, according to the report “Bank X: The New New Banks” published by Citi on Thursday.

    As legacy banks recognize the threat that new entrants into banking are posing to revenue and customers, they need to reinvent themselves and reimagine banking. This involves legacy banks partnering with technology companies to create effective joint ventures as well as moving into more disruptive technology and business models to transform themselves into digital competitors, the report said.

    If banks successfully transform digitally, their ROEs will rise from 8 percent in Europe and 16 percent in the U.S. to 15 percent and 24 percent respectively in a bullish scenario, and 5 percent and 10 percent respectively in a bearish scenario, the report noted.

    Bank X

    Built by new entrants, challenger banks designed around new digital technologies, leveraging data insights via agile technology stacks to offer customers better personalization and fully digital banking experiences. As they offer their services remotely via online or mobile banking, challenger banks tend to be quicker at incorporating new products or processes into their platforms and help easily connect with third-party products, ultimately offering more choices to the end-user.

    By creating their own Bank X, we believe legacy banks can transform themselves from slow-moving caterpillars to agile butterflies, Ronit Ghose, Citi Global Head of Bank Research, said.

    The report noted that while creating a new digital-only bank can help incumbent banks meet an evolving set of customer expectations quickly and effectively, setting up an independent challenger bank needs to be differentiated from digital transformations and core banking overhauls that they undertake. This is because creating their own Bank X requires independent application programming interfaces (APIs) and technology stacks, which is a significant departure from the operating model of incumbent banks.

    Need for Regulation in Asia

    Apart from the lower number of challenger banks in Asia compared to the U.K. and U.S., Citi noted that challenger banks in Asia are largely offshoots of big tech, telcoms, and banks. For example, WeBank, MYbank, and Kakao Bank are all backed by tech firms, KBank and Jibun Bank are backed by telcoms, while DBS has made progress in Indonesia and India with digibank, its own challenger bank.

    While Asia has several challenger banks originating from startups aiming to disrupt the financial system, Neat in Hong Kong or Paytm in India, they are exceptions. This is a result of the limited regulatory framework for challengers in Asia, with the emerging exception of Hong Kong, and the presence of large tech companies, particularly in China.

    Conversely, challenger bank activity is vibrant in the U.K. and Europe as a result of progressive regulations enacted to promote competition and break up the banking monopoly, the report said.

  • OCBC Forms Committee to Ensure Responsible Banking

    OCBC Forms Committee to Ensure Responsible Banking

    The bank’s new ethics and conduct board committee wants to ensure that the group’s core values of trust and integrity continue to anchor the way it conducts its business.

    OCBC Bank has formed an ethics and conduct board committee, which is chaired by OCBC chairman Ooi Sang Kuang and includes directors Lee Tih Shih and Christina Ong, according to a news release on Thursday.

    While the industry is seeing ethics and compliance as an area of greater concern, the committee, which provides oversight of the group’s policies, guidelines, and programmes, is a first among Singapore banks.

    Laying Out Standards

    It held its first meeting on Wednesday, laying out expectations and standards for the group’s 29,000 employees as it aims to «sustain and grow a strong culture of responsible banking and fair dealing» and ensure that responsible banking is rigorously enforced across the whole OCBC group, the bank said.

    In the last decade, there have been several high-profile examples of questionable conduct by financial institutions. These examples span the globe and the misconduct ranges from extreme over-leveraging to violating international sanctions, tax fraud, and money laundering. The misconduct stems mostly from an imbalance between the pursuit of financial goals and responsible banking, Ooi said.

    Transforming Rapidly

    The banking industry is transforming rapidly due to technological advancements, and customers’ expectations have also changed. However, what has not changed is that our customers still expect us to be utterly worthy of their trust. That is why amid so much change in the banking industry, our underlying values of integrity and honesty must never change, Ooi added.

    The ethics committee also oversees a new culture and conduct committee, chaired by group chief executive Samuel Tsien. The committee will implement initiatives to enhance existing policies and programmes on ethics and conduct, as well as roll out new ones to strengthen these values among all the group’s employees.

  • Deutsche Bank Appoints Head of Thailand

    Deutsche Bank Appoints Head of Thailand

    The German lender hires a new head from Siam Commercial Bank to fill the position left vacant since 2018. Deutsche Bank (DB) will get a new head for its Thailand operations in May, with the appointment of Pimolpa Suntichok as chief country officer and head of the financing and solutions group for Thailand, according to people close to the matter.

    Suntichok fills a position left by Phumchai Kambhato, who left the bank in 2018. She will report to Werner Steinmueller in her country management capacity and to Sreenivasan Iyer for her FSG responsibilities.

    Suntichok was previously the Senior Executive Vice President serving as the Head of Commercial Banking Solutions at Siam Commericial Bank, Thailand’s largest commercial bank. She brings over 20 years of experience in banking, having worked at Bangkok Bank, Jardine Fleming Thanakom Securities, Fitch Ratings (Thailand), and Standard Chartered Bank (Thailand). She joined SCB in 2008 to lead the structured finance practice for the Capital Markets Division and became the Head of Corporate Segment in 2015 and the Head of MultiCorporate Segment in 2016, according to SCB’s website.

    Future Uncertainty 

    Deutsche Bank in recent months has seen a raft of departures in Asia, including Southeast Asia Vice Chairman Philip Lee, Jakarta-based managing director Kunardy Lie, and North Asia COO

    Katherine Lai.

    DB, on its third CEO in four years, has in recent years scaled down its Asian operations as its focus has shifted towards Europe amid difficulties in the region. However, Thailand remains an important market for DB in Asia-Pacific, with the bank having a 40-year history in the country.

    The bank is currently in the midst of merger discussions with Commerzbank, which has cast uncertainty over Deutsche’s general strategy for the future.

  • New Milestone for Hong Kong as a Financial Center

    New Milestone for Hong Kong as a Financial Center

    The Hong Kong Monetary Authority has granted the first virtual banking licenses to three institutions. According to their business plans, these banks will launch their services within six to nine months.

    The three banks that received a license are Livi VB, SC Digital Solutions and ZhongAn Virtual Finance to operate in the form of a virtual bank. The granting of these banking licenses takes effect today, according to a media release on Wednesday.

    According to their business plans, these three newly licensed virtual banks intend to launch their services within 6 to 9 months. After the granting of the above banking licenses, the number of licensed banks in Hong Kong will be increased to 155.

    Reinforcing Hong Kong’s Position

    The Hong Kong Monetary Authority (HKMA) is making good progress in the processing of the remaining 5 virtual bank applications, according to further information.

    «It is a major milestone in reinforcing Hong Kong’s position as a premier international financial center. I believe that virtual banks will not only help drive fintech and innovation but also bring about brand new customer experiences and further promote financial inclusion in Hong Kong», Norman T.L. Chan, CEO of the HKMA, said.

    Targeting the Retail Public and SMEs

    I believe that virtual banks will have to offer innovative and customer-centric services in order to attract customers. Moreover, in targeting the retail public and SMEs as their main client base, virtual banks should help promote financial inclusion in Hong Kong, he added.

    The U.K. market, where neobanks and digital-only challengers have been around for a while, shows there’s a big chance new players will grab a significant chunk of new financial services revenue in the near future in Hong Kong, but that doesn’t mean all is lost for traditional banks here, Fergus Gordon, a managing director at Accenture who leads its Banking practice in Asia Pacific and Africa, said.

    Some Consolidation Expected

    Virtual banks will need some years to establish themselves, then there will likely be some consolidation among some of the players, and in the meantime, traditional players should continue to rapidly reconfigure their branch networks to become more focused on experiences and use technology to make the transition from digital to physical and back much more seamless, he added.

  • Sunways Malls Welcomes the Cashless Revolution

    Sunways Malls Welcomes the Cashless Revolution

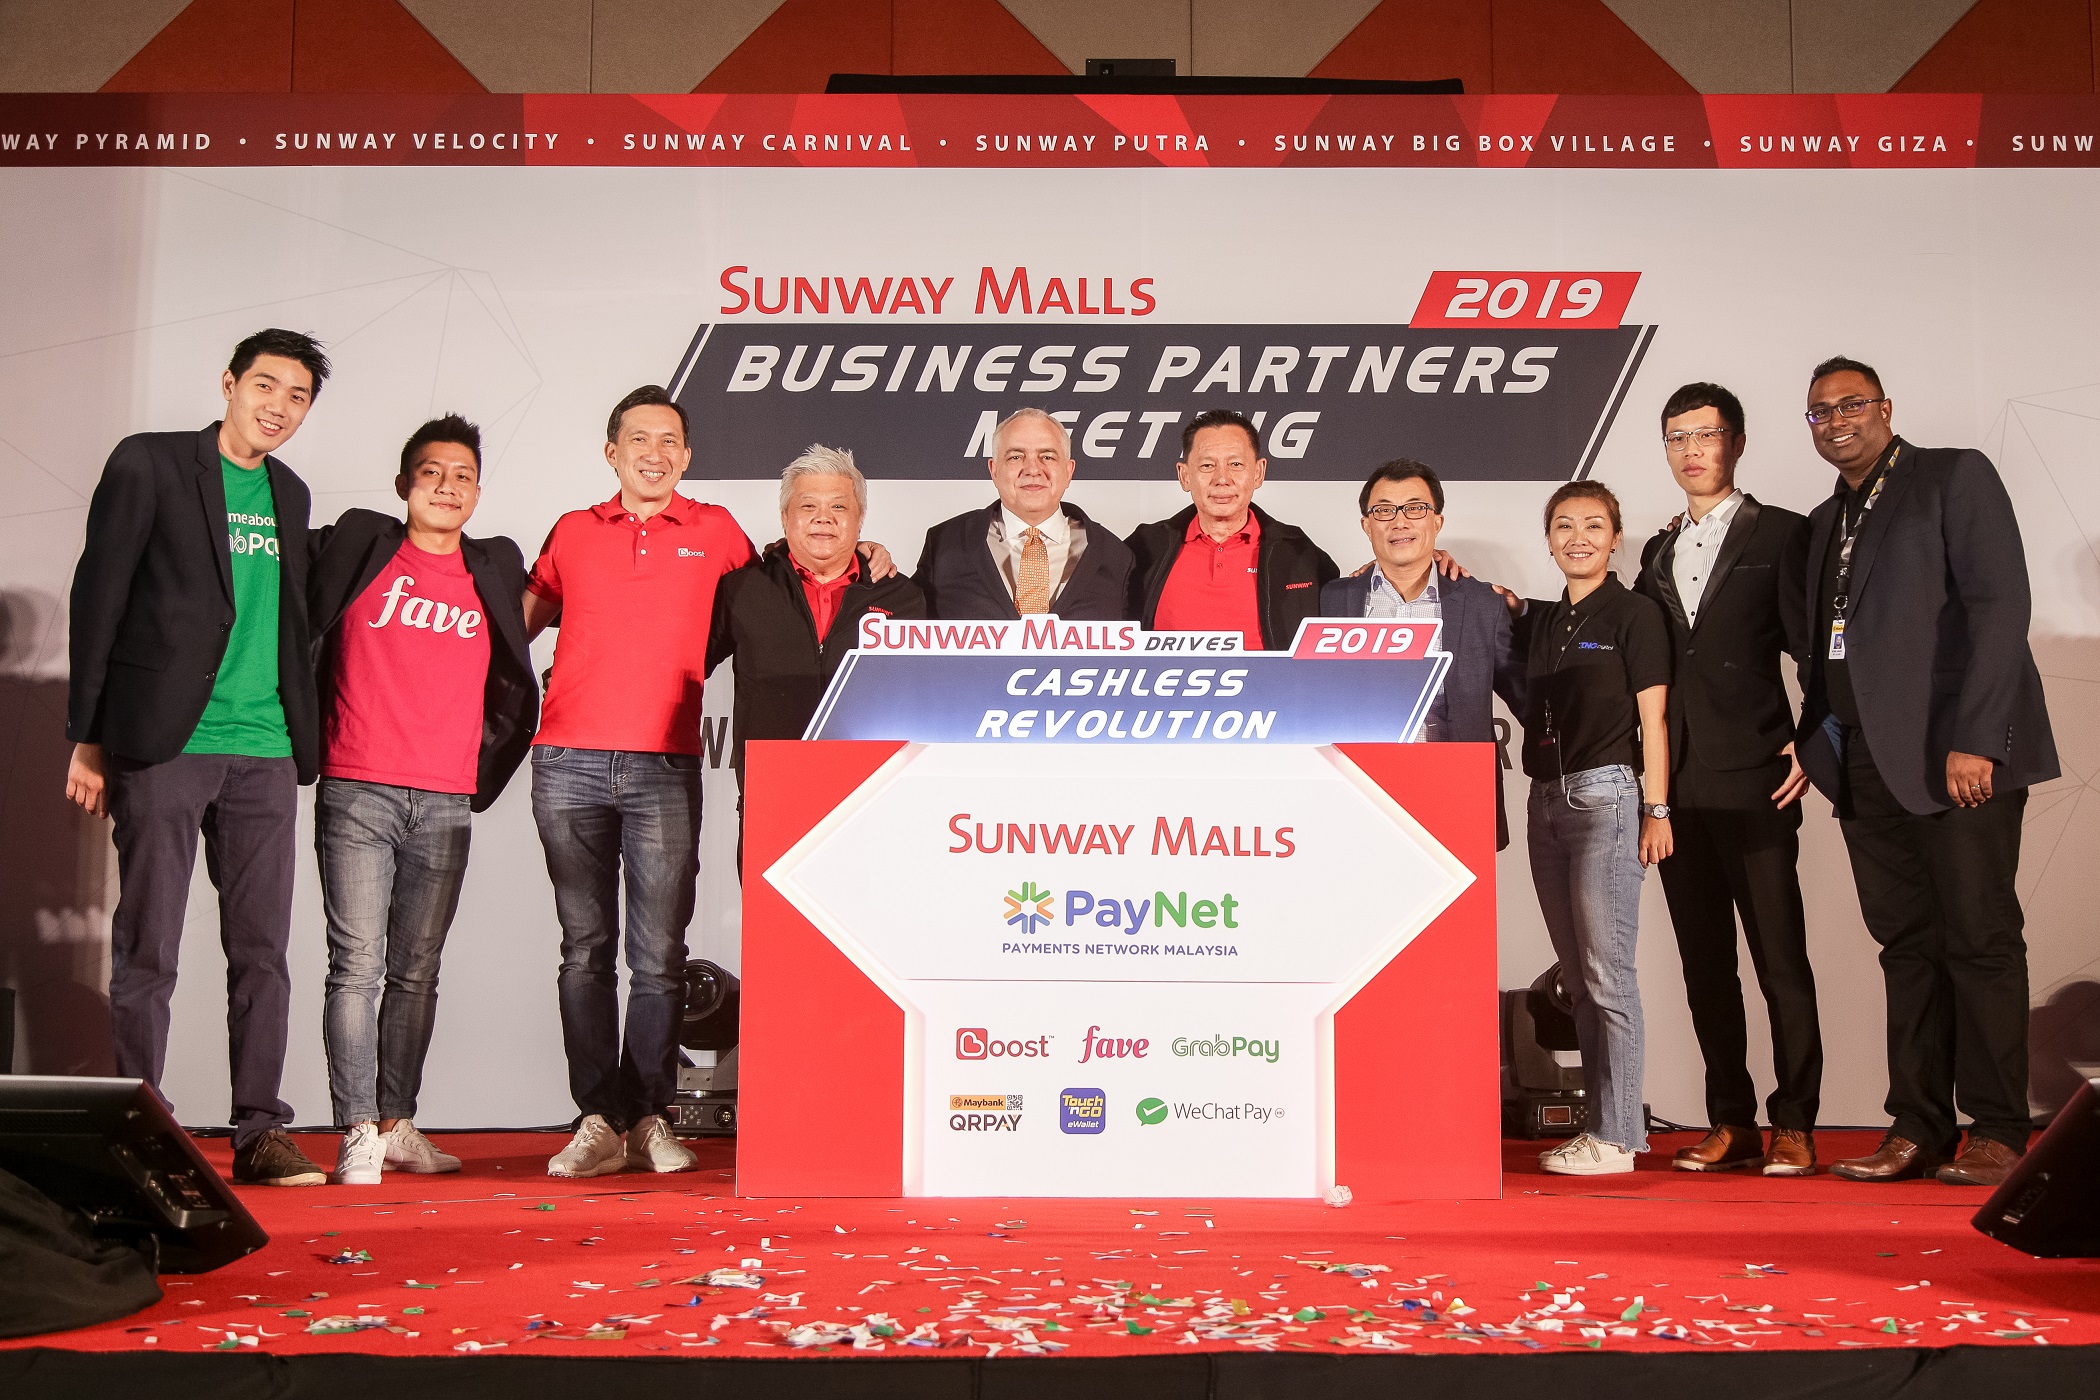
    Ever since Bank Negara embarked on a 10-year roadmap to move towards a cashless society, the ever growing trend of cashless transactions has been increasing and is popular amongst the Gen-Y and Millennial Generation. Sunway Malls took the initiative to bring in leading e-wallet companies such as Boost, FavePay, GrabPay, Maybank QRPay, Touch ‘n Go Pay, and WeChat Pay for exclusive face-to-face sessions with retailers at a closed door conference held at Sunway Pyramid Convention Centre.

    No longer do you need to carry around cash and credit cards as your mobile phone can do the paying! Numerous e-payment players in the market have emerged and is providing shoppers with better deals and convenience.

    Benefits of e-payment:

    • Enhances shopper experience
    • Increased sales
    • Quick and convenient

    “As the payment market continues to evolve, it is imperative that we stay abreast with development of cashless payment to cater to new consumer demands”, said H.C Chan, Chief Executive Officer of Sunway Malls & Theme Parks.

    Retailers who attended the conference were treated to a detailed and in-depth look at how cashless transactions would benefit their business and increase their sales through intimate small group discussions with the five e-wallet companies. To date, close to 35% of retailers across Sunway Malls are using some sort of e-wallet payment at their outlets and the malls hopes to increase this number to cater to the ever growing trend of cashless payments.

    The conference keynote was presented by Mr. Peter Schiesser, Group Chief Executive Officer of Payment Networks Malaysia (PayNet), Malaysia’s premier payments network and central infrastructure for financial markets. Mr. Deep Chowdhury, Client Service Director (Consumer Insights) from Nielsen Malaysia spoke on the topic of ‘Cash or Cashless? Malaysia’s Payment Landscape’ and shared insights on current Malaysian purchasing and spending behaviour in the retail industry and beyond.

    Over 350 brands attended the conference which was also Sunway Malls’ annual Business Partner Meeting to receive the latest updates on the current market outlook and upcoming plans for each mall.

    Sunway Malls is gearing to be amongst Malaysia’s largest mall owner-operator as existing projects and those in the pipeline now stand at 7.7 million sqft NLA and that figure is planned to be increased to 10.2 million sqft NLA by 2020.

    The malls are:-

    Sunway Pyramid, Bandar Sunway

    Sunway Velocity Mall, Cheras, Kuala Lumpur

    Sunway Big Box Village, Johor Bahru (opening 2019)

    Sunway Putra Mall, Kuala Lumpur

    Sunway Carnival Mall, Penang

    Sunway Citrine Hub, Johor Bahru

    Sunway Giza, Kota Damansara

  • Apple introduces Apple Card: Daily Cash, no fees

    Apple introduces Apple Card: Daily Cash, no fees

    Apple has announced a brand new service: Apple Card. Starting this summer in the US, users will be able to sign up for a real Apple credit card that’s going to reside within the Wallet app. Requesting a virtual Apple Card living in your iPhone will be very easy, as you’ll be able to do it straight from your device. Issuing a new Apple Card shouldn’t take more than a few minutes. Once issued, your Apple Card should be right there in your Wallet app.
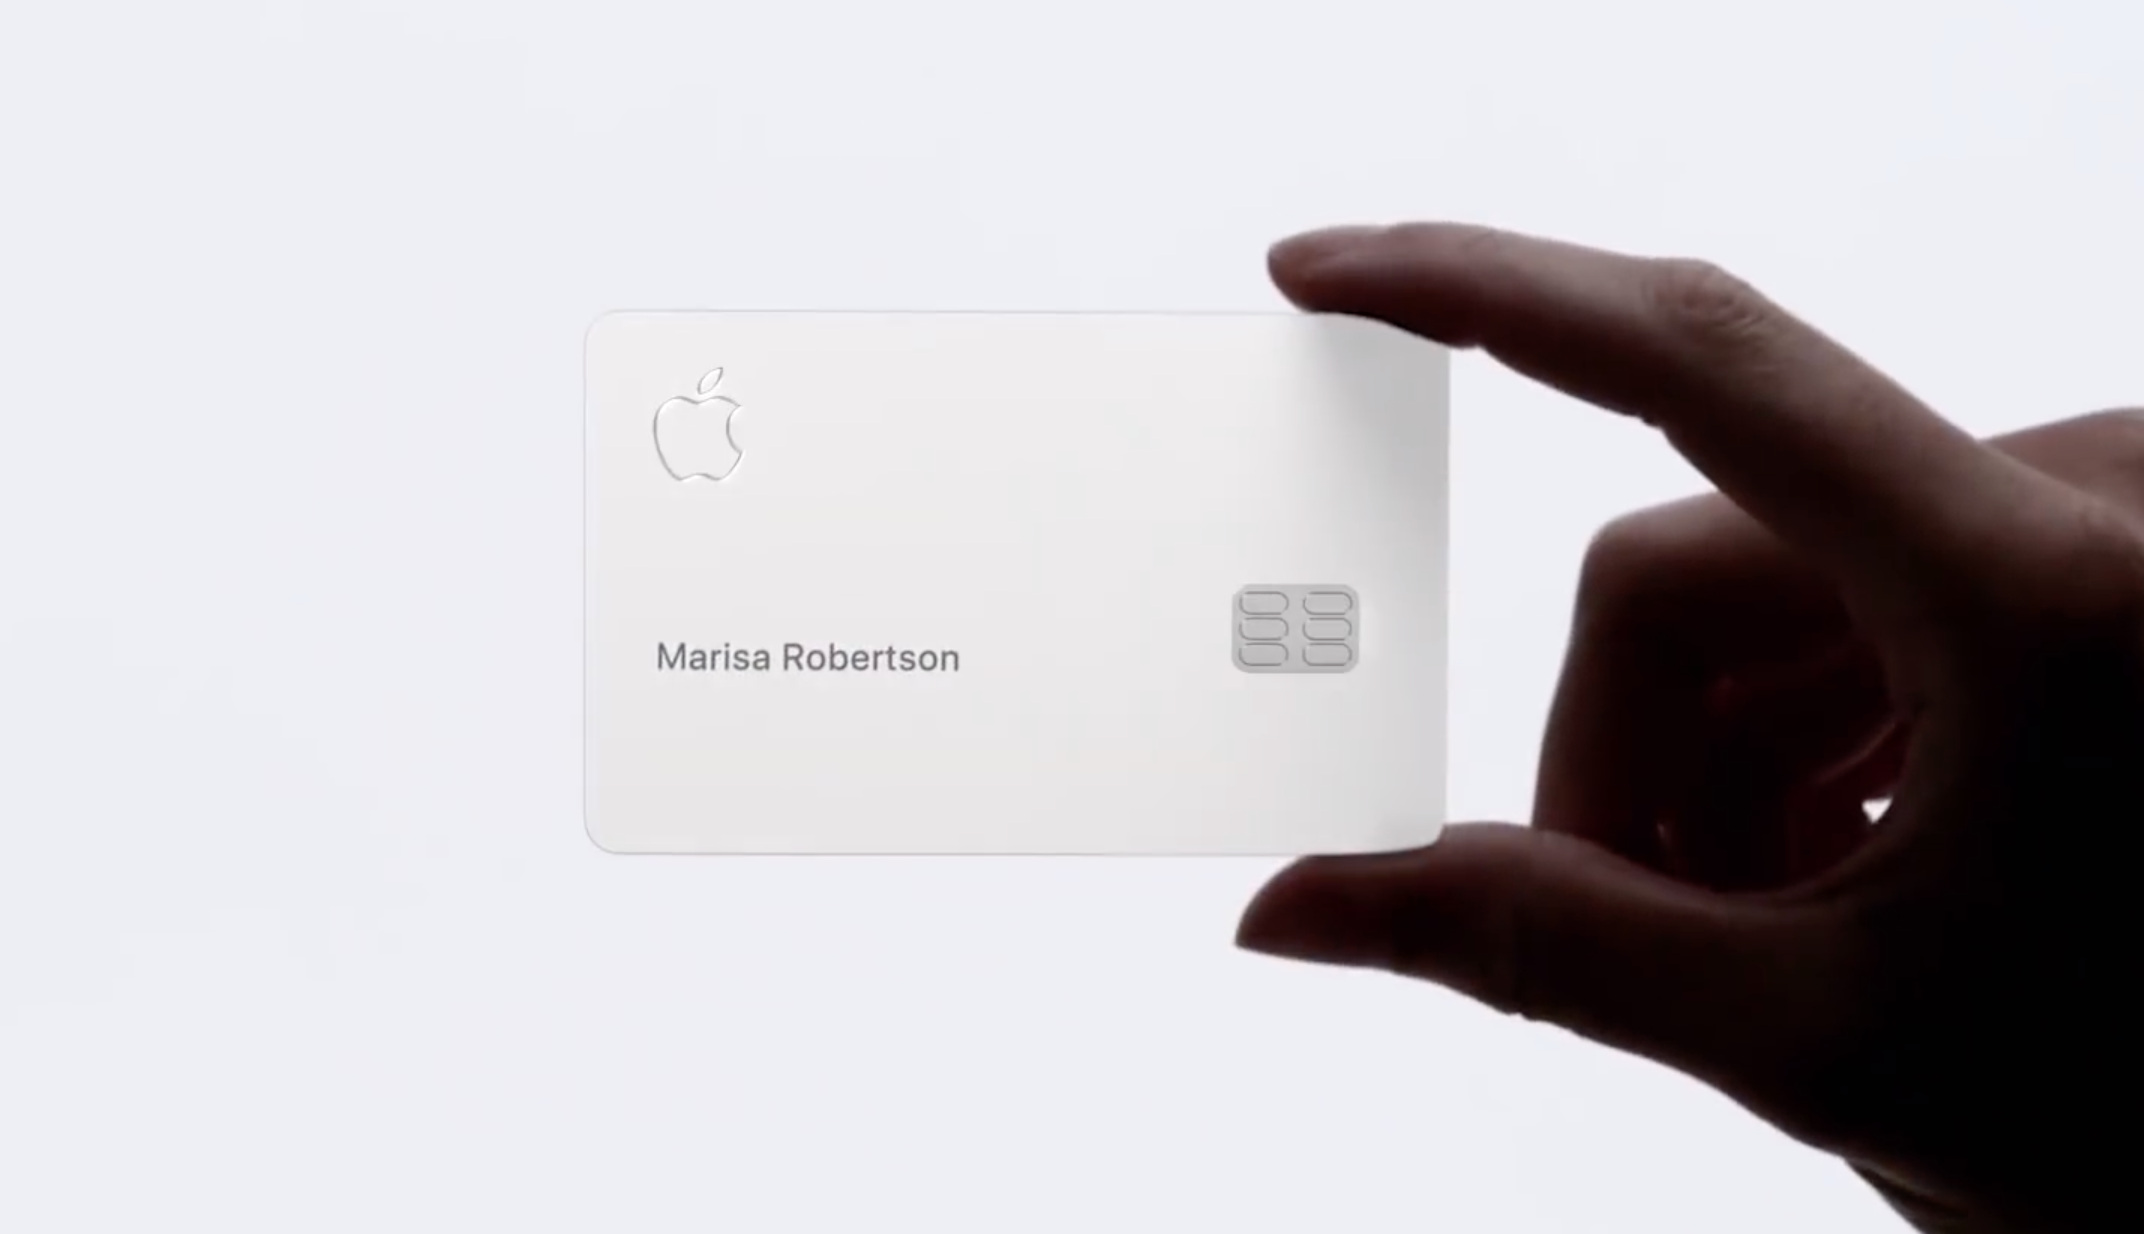
    What’s even cooler is that users will also be able to request a physical credit card, which will be made of titanium and have the user’s name laser-etched. No card numbers, CVV, or expiration dates will be printed on the card, making it that much more secure.
    Apple is creating Apple Card in partnership with Goldman Sachs. As it’ll be using the Mastercard payment network, the card will be accepted worldwide. Card support is going to be handled by Apple directly in a delightful new way: through Apple Messages. Just text Apple with your questions or requests, and the company will respond right there, in Messages. Apple Card will be available this summer in the US. Unfortunately, the company isn’t revealing any details regarding a future international rollout of the service.

    Daily Cash

    With Card, Apple is introducing a welcome new take on the cash back program. It’s called Daily Cash for a reason: you’ll be receiving your cash back amount daily, and you’ll be free to spend it again through Apple Pay, put it towards your Apple Card balance, or send it to family or friends through Apple Messages.
    Customers will be receiving Daily Cash to the tune of 2% on all of their Apple Card payments outside of Apple’s ecosystem. When it comes to Apple’s own stores, like Apple Stores, iTunes or the App Store, the Daily Cash amount will be 3%. And for purchases made using the physical Apple Card, the Daily Cash amount will be 1% of the purchase value.

    Apple helping you have a better financial culture

    Apple is building a number of new features around Apple Card, designed to help you have a better understanding of your spending. For starters, it’ll help you track your purchases more easily by using machine learning and Apple Maps in order to ‘translate’ the names of merchants in your purchases log. You are probably familiar with how merchant names often appear fairly cryptic when you view then through your bank’s web portal or mobile app; with Apple Card, Apple will make sure to have them all clearly labeled so that you’ll immediately know which transaction was made with whom.
    Color coding will also help with the organization of your transactions: products from distinct categories such as Food and Drinks or Shopping and Entertainment will be assigned a different color so that you can immediately find the ones you’re looking for. This, in tandem with the new weekly and monthly spending summaries, Apple hopes will give you a better vantage point over your overall expenditures.
    What’s more, Apple Card will include a tool to help users pay less interest by making their options more transparent. It’ll be suggesting a range of payment options and a handy calculator that estimates the interest cost on different amounts, so that each users can pick the option that suits their budget the best.

    Physical Apple credit card made of titanium

    Apple knows that for customers to fully embrace its payment service, it needs to be universally accepted. So, to let you deal with those merchants that don’t support Apple Pay yet, the company is creating a real, physical credit card with the signature Apple minimalist design. The company hasn’t released some of the technicalities, such as if it’s going to charge you for issuing such a card, but at least we know how it’s going to look like.
    No card numbers, expiration dates, or CVV numbers will be present on the card, making for an extremely clean look, with only the Apple logo and the holder’s name laser-etched onto the titanium piece. Your card’s numbers are, of course, still available: you’ll just have to look them up in the Wallet app on your iPhone.
    Thy physical Apple Card seems like a very appropriate product for international users, where Apple Pay support is still widely lacking, but the company seemingly has no immediate plans to launch Apple Card in markets other than the US at this time.