Tag: fmcg

  • Bodie’z Rolls Out Waterless Functional Sherbet Sachets Across Kmart

    Bodie’z Rolls Out Waterless Functional Sherbet Sachets Across Kmart

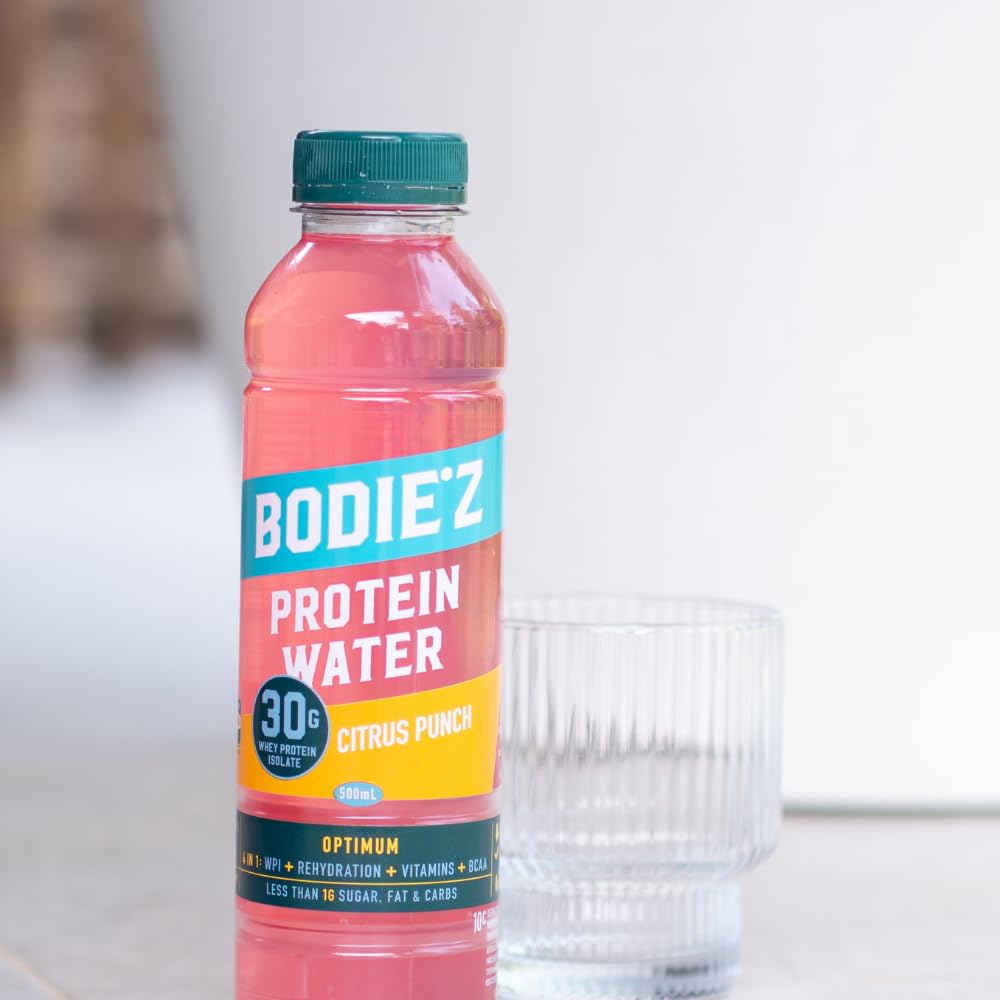
    Sydney sports nutrition brand Bodie’z has launched a waterless functional sherbet range called Fizzers across Australia, pricing single-serve sachets at $2.50. The rollout puts the direct-to-mouth powders into discount department store chain Kmart alongside Amazon and the company’s direct retail site this September.

    The launch shifts the company beyond its established ready-to-drink protein water products into portable dry formats. Each sachet delivers active nutritional compounds without requiring water or shaker bottles, targeting consumers seeking faster daily supplement habits.

    Three functional recipes

    Bodie’z built the Fizzers lineup around three specific formulations. Electrolyte Fizz focuses on hydration and mineral replenishment, while Creatine Fizz provides 3 grams of creatine monohydrate per serving. The third option, Lock In Fizz, combines L-tyrosine, matcha, and vitamin B6 for cognitive support.

    Every variant is low in sugar and uses natural flavouring. Founder Bodie Lazar designed the recipes to eliminate common points of friction in sports nutrition, including measuring scoops and swallowing large capsules.

    Waterless formats and retail reach

    Functional food manufacturers across the Asia-Pacific region are increasingly testing waterless and confectionery-inspired formats to capture shoppers who find standard powders and pills inconvenient. Moving into Kmart gives Bodie’z direct access to high-footfall general retail shelves, broadening its consumer base beyond specialist supplement channels.

    Distribution begins this month across Kmart’s national store network, Amazon Australia, and the brand’s e-commerce platform.
  • Who Gives A Crap Targets A$100 Million Annual Donations on Retail Push

    Who Gives A Crap Targets A$100 Million Annual Donations on Retail Push

    Melbourne consumer brand Who Gives A Crap has distributed more than A$50 million to global sanitation initiatives as it expands into mainstream supermarket chains worldwide.

    The company, which gives half of its profits to water and hygiene projects, is now mapping a growth path aimed at generating A$100 million in annual donations by 2050. That target requires building a commercial footprint large enough to challenge legacy paper giants such as Kimberly-Clark.

    From web stunt to supermarket shelves

    Co-founders Simon Griffiths, Danny Alexander and Jehan Ratnatunga launched the business in 2012 by raising A$50,000 through a 50-hour crowdfunding web feed. Bootstrapped for its first nine years, the company took outside institutional funding in 2021 and expanded its workforce to nearly 300 employees.

    While direct-to-consumer delivery drove early revenue across Australia, the United States, Britain, Canada, France and Germany, long-term growth now depends on physical grocery distribution. In the United States, placement with Whole Foods Market opened access to shoppers who do not buy paper goods online. Supermarket distribution across Australian chains followed a similar pattern, forcing the brand to compete directly against entrenched multinational FMCG lines on store shelves.

    Targeting global scale in paper goods

    Entering physical stores presents distinct margin and packaging challenges for direct-to-consumer challengers across the Asia-Pacific region. Brand visibility in high-traffic aisles requires heavy inventory commitments and immediate shelf recognition, especially in staple categories where consumers buy on autopilot.

    The company plans to use expanded supermarket listings in North America and Europe to fund its target of A$100 million in yearly charitable disbursements by 2050.

  • Nestlé Sells Holistic Health Supplement Business to Yellow Wood for $1.4 Billion

    Nestlé Sells Holistic Health Supplement Business to Yellow Wood for $1.4 Billion

    Nestlé has sold its mainstream vitamins, minerals and supplements unit, Holistic Health, to private equity firm Yellow Wood Partners for $1.4 billion. The transaction transfers brands including Nature’s Bounty to the consumer-focused buyout firm for US$1 billion in cash.

    The Swiss food and beverage group is pruning product lines that fall outside its core high-margin categories. Management described the divestment as a necessary step in realigning capital toward divisions where the company holds stronger global pricing power and manufacturing advantages.

    Portfolio refocus at Swiss food group

    Chief executive Philipp Navratil pointed to changing dynamics across consumer health channels as the rationale for exiting mainstream supplements. Dedicated specialist owners are better suited to run broad-market dietary brands as grocery and pharmacy retail channels fragment.

    Yellow Wood Partners focuses on corporate carve-outs in personal care, beauty, and consumer health. The private equity buyer plans to run the acquired supplement portfolio as an independent platform operating across global retail networks.

    Divestment strategy in global retail

    Consumer goods giants across the Asia-Pacific region and western markets have spent the past two years shedding slower-growth divisions to protect margins against inflation. Nestlé itself has pursued selective acquisitions in medical nutrition while trimming commoditised lines from its health science roster.

    Regulators will review the sale before formal closing, with transfer of manufacturing assets and brand distribution agreements expected in the coming quarters.

  • Australian Grocers Expand Private Labels as Coles Posts $1.09B Profit

    Australian Grocers Expand Private Labels as Coles Posts $1.09B Profit

    Coles Group posted a 1.09 billion Australian dollar net profit for the financial year ending June 28, as the country’s supermarket giants add thousands of private-label lines to store shelves.

    The expansion of store brands directly targets margin defence and customer retention across Australian grocery aisles.

    Private label pressure from Aldi

    Aldi entered the Australian market through Sydney in 2001, building its network on an inventory model where 90 per cent of products were private labels sold at lower price points. At that stage, Coles and Woolworths together controlled about 71 per cent of the national grocery market.

    The German discounter captured substantial market share by 2015. That persistent push forced both incumbent chains to rethink their merchandise mix and build out multi-tier house brands to compete across basic grocery categories.

    Margin defence and shelf allocation

    Supermarket operators use own-brand ranges to secure higher gross margins and gain greater use over suppliers. For grocery retailers across the Asia-Pacific region, allocating more shelf space to proprietary labels offers direct protection against wholesale price inflation.

    Both Coles and Woolworths face continued consumer demand for cheaper basket alternatives as shoppers swap branded packaged goods for supermarket-owned items.

  • Robusta Coffee Climate Resilience Is a Flawed Myth, Study Warns

    Robusta Coffee Climate Resilience Is a Flawed Myth, Study Warns

    A new research study has challenged the widely held assumption that robusta coffee will withstand global warming better than arabica varieties. The crop suffers from severe drought intolerance, undermining its reputation as a climate-resilient alternative for global beverage supply chains.

    Tens of millions of bags of robusta reach international markets every year, with the bulk originating from farms in Vietnam and Brazil. Beverage brands and roasters have increasingly relied on the bean as rising temperatures squeeze traditional arabica harvests across Latin America and Africa.

    Flawed Assumptions on Crop Tolerance

    Researchers found that prior assessments overlooked how sensitive robusta plants are to water shortages during key growing cycles. The lead author described claims of broad climate resilience as an internet myth built on incomplete data.

    “Robusta is more heat-tolerant than arabica, but it’s drought-intolerant,” the study noted. While the variety can endure higher ambient temperatures, dry spells drastically cut yields, leaving commercial growers exposed to sudden harvest declines.

    Pressure on Asian Beverage Supply Chains

    For Southeast Asian agricultural hubs and instant-coffee processors, the findings point to growing volatility in raw bean procurement. Vietnam supplies the vast majority of global robusta exports, meaning prolonged dry weather in the Central Highlands directly disrupts margins for consumer packaged goods groups and cafe operators across Asia.

    Food and beverage manufacturers now face higher hedging costs and the need for heavier capital investment in farm irrigation systems to secure future robusta volumes.

  • Australia Food Manufacturing Turnover Hits $182.6 Billion

    Australia Food Manufacturing Turnover Hits $182.6 Billion

    Australia’s food and grocery manufacturing turnover rose 5.5 per cent to $182.6 billion in the 2024-25 financial year. Steady consumer demand across supermarket aisles drove the increase.

    Total workforce numbers across processing plants and distribution hubs passed 301,000 people over the 12-month period. That headcount now represents 33 per cent of all manufacturing jobs in the country.

    Squeezed margins and factory payrolls

    The annual State of the Industry 2024-25 report from the Australian Food and Grocery Council shows steady top-line expansion across packaged goods, beverages and daily essentials. Yet the headline revenue growth conceals worsening operational headwinds inside processing facilities.

    Persistent cost pressures and compressed margins are reducing the capital available for factory upgrades, automation and long-term expansion, the council warned. While consumer spending on staples supported turnover, wholesale input prices and elevated running expenses continue to erode net profitability across supply chains.

    Regional production pressures

    Similar margin pressure affects food manufacturing hubs across the Asia-Pacific region. Processors face higher utility bills, freight volatility and stubborn ingredient costs. When consumer-facing brands cannot fully pass wholesale cost increases to supermarket buyers, capital spending plans are routinely deferred.

    Factory operators are now recalibrating capital expenditure budgets for the 2025-26 cycle. They continue to monitor wholesale input pricing ahead of supplier negotiations with national retail chains.

  • Australian Supermarkets Adapt to In-Between Shoppers Seeking Asian Groceries

    Australian Supermarkets Adapt to In-Between Shoppers Seeking Asian Groceries

    Australian mainstream grocers are restructuring their international food aisles as demand from second-generation shoppers erodes the traditional gap between independent Asian grocers and major supermarket chains.

    The shift challenges decades of split retailing, where consumers bought standard household staples at major chains and visited specialty Asian grocers for authentic ingredients.

    Breaking the Specialty Divide

    May Wong, who concluded her tenure as a category manager at Coles Group on August 31, 2026, after seven years managing an Asian grocery store, said the boundary between the two channels is disappearing. Shoppers from second-generation migrant backgrounds increasingly expect mainstream supermarkets to stock the authentic food items that match their cultural heritage.

    Specialty grocers long held a monopoly on authentic imported brands, while major supermarkets focused on westernised pantry staples. Younger shoppers now seek authentic taste profiles without making a separate trip to suburban ethnic markets.

    Shifting Demographics on Mainstream Aisles

    For supermarket operators across the Asia-Pacific region, tailoring shelf space to multicultural demographics has turned ethnic aisles into high-growth territory rather than niche perimeter displays. Major chains in markets with large diaspora populations are expanding direct sourcing relationships with Asian food exporters to meet tighter consumer standards on authenticity.

    Coles and competing Australian supermarket operators will test updated product assortments across metropolitan store networks through the coming retail quarters.

  • Twelve Chinese Food and Beverage Brands Reach $63.4 Billion Valuation

    Twelve Chinese Food and Beverage Brands Reach $63.4 Billion Valuation

    Twelve Chinese food and beverage brands expanded their collective brand valuation to $63.4 billion this year, according to valuation data from consultancy Brand Finance.

    The gain reflects steady domestic volume and pricing power across packaged food, dairy, and drinks makers in China. Brand valuation measures the net economic benefit that a brand owner achieves by licensing the name in the open market.

    Domestic Scale and Category Strength

    Consumer staples manufacturers across the country have focused on product differentiation and distribution depth in lower-tier cities. Brand Finance tracks consumer enterprises globally, applying royalty relief methodology to calculate future revenue attributable to brand equity.

    Chinese producers have converted local consumer familiarity into commercial resilience. Direct control over supply chains and rapid adaptation to retail trends helped the 12 brands maintain their valuation trajectory.

    Shifting Competition Across Asian Aisles

    For multinational food groups operating in East Asia, the strength of domestic Chinese labels presents a persistent competitive hurdle. Global conglomerates face rivals that command supermarket shelf space while dominating live-commerce channels and local delivery apps.

    Several Chinese packaged goods producers have also expanded distribution across Southeast Asia, placing products directly into supermarkets in Singapore, Malaysia, and Thailand.

    Investors and retail operators now look to upcoming quarterly financial filings from Chinese consumer staple producers to see whether higher brand value translates directly into operating margin expansion.

  • Comvita Swings to NZ$7.7 Million Annual Profit on Honey Reset

    Comvita Swings to NZ$7.7 Million Annual Profit on Honey Reset

    New Zealand Manuka honey producer Comvita swung to a net profit after tax of NZ$7.7 million for fiscal 2026, rebounding from a NZ$104.8 million loss a year earlier.

    Operating profit reached NZ$14 million for the twelve months ended June 30, reversing a NZ$29 million operating deficit booked during the previous financial year.

    Margin Recovery and Cost Discipline

    Gross profit climbed 38.8 per cent to NZ$114.8 million across the period. That performance expanded the group gross margin to 53.9 per cent as efficiency measures took hold across manufacturing and inventory handling.

    The return to the black follows an intensive reset programme that targeted operational costs after heavy inventory impairments and market softness damaged earnings in fiscal 2025.

    Asia Demand and Export Execution

    Comvita built its business on premium functional food demand across Greater China, Southeast Asia and North America. Premium specialty honey brands in the region spent the past two years battling cautious consumer spending, cross-border channel resets and distributor destocking across East Asian department stores and cross-border platforms.

    Market attention now turns to export volume trends in Asian retail channels over the first half of fiscal 2027 to verify whether the margin gains hold up in core consumer accounts.

  • Bubs Australia Revenue Reaches $111.9 Million as US Distribution Expands

    Bubs Australia Revenue Reaches $111.9 Million as US Distribution Expands

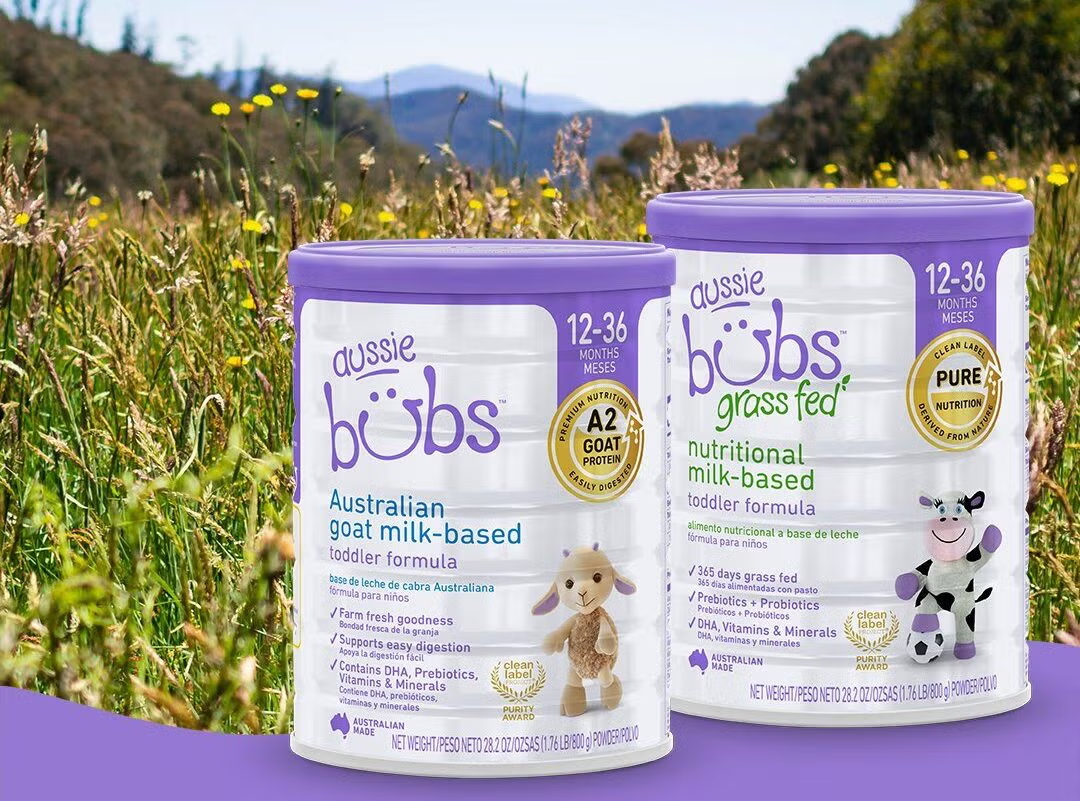
    Bubs Australia lifted group revenue 9.2 per cent to $111.9 million for the twelve months ended June 30, driven by rapid retail expansion in North America.

    Underlying earnings before interest, tax, depreciation and amortisation climbed 338 per cent to $5.3 million. The top-line gain masked tightening margins at the Australian infant formula maker, where gross profit dropped 9 per cent over the period.

    Expansion in the American market

    Sales growth centered on the United States, where revenue rose 24 per cent across the fiscal year. The company widened its physical retail presence to more than 10,000 American stores, turning the market into its primary growth engine outside Australasia.

    Higher distribution scale helped absorb overheads, but rising costs and shifting regional demand checked profitability across secondary territories.

    Margin pressures and regional divergence

    Results across regional markets outside the United States delivered mixed performances. While volume moved through larger overseas retail networks, gross margins contracted under higher cost pressures across the supply chain.

    For dairy and infant nutrition exporters across the Asia-Pacific region, rapid volume growth in Western supermarket aisles continues to balance uneven purchasing patterns across legacy Asian cross-border channels. Maintaining profitability now depends on turning trial into repeat shelf velocity.

    Attention turns to whether the brand can defend shelf space across its expanded 10,000-store US footprint while repairing gross margins in the next reporting cycle.

  • It’s Olio Reaches Seven Figures and Targets $2 Million in Online Sales

    It’s Olio Reaches Seven Figures and Targets $2 Million in Online Sales

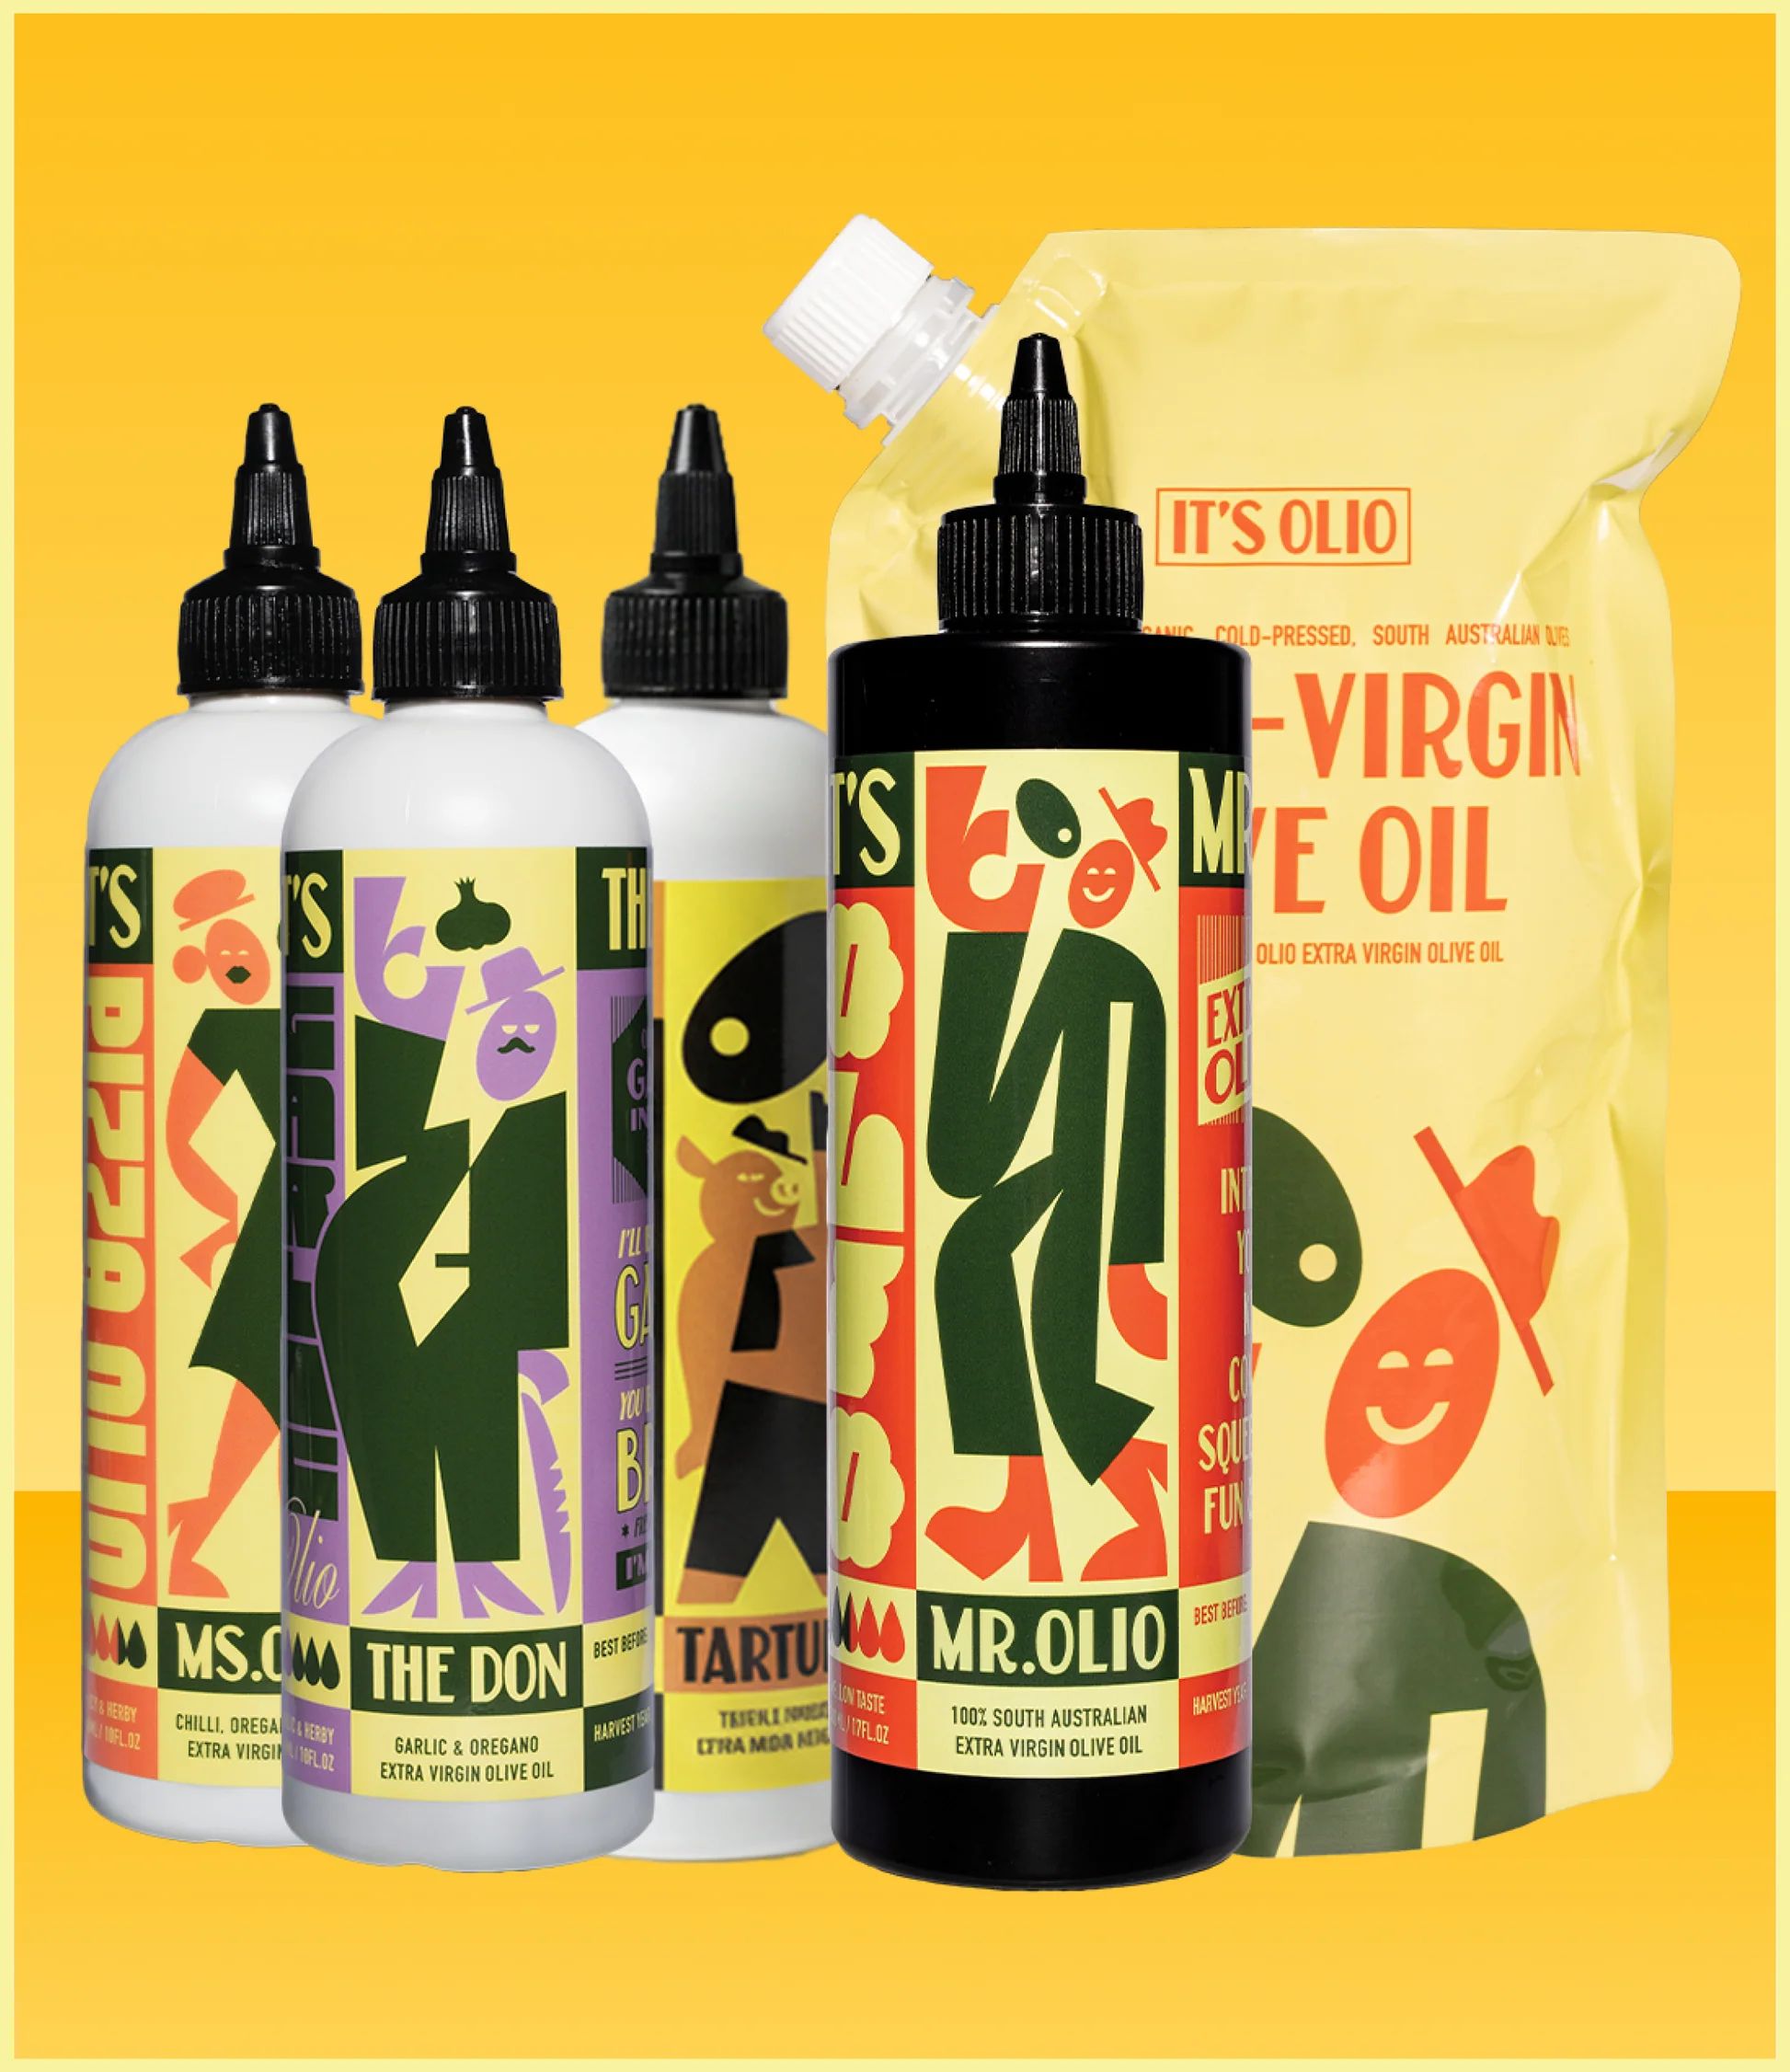
    South Australian olive oil brand It’s Olio has reached seven figures in revenue three years after launching on an initial budget of $10,000. The direct-to-consumer label now targets more than $2 million in online sales before the end of 2026.

    Founder Alec Randall conceived the business after travelling through Sicily in 2022 and attending local cooking classes. He started commercial operations the following year, focusing on premium olive oil marketing and digital direct sales.

    Cross-border digital distribution

    The business built its initial customer base in Australia before adding distribution across New Zealand and the United States. Online sales provide the core revenue engine, allowing the producer to handle fulfilment and marketing across three separate national markets.

    Self-funded pantry startups across the region increasingly bypass traditional supermarket contracts early in their lifecycles. High grocery shelf fees in major retail chains make pure-play e-commerce a leaner route to prove export demand before pursuing physical wholesale distribution.

    Targets for the current financial year

    Direct export logistics remain the main testing ground for boutique Australian food labels selling into North America and Australasia. Controlling fulfilment costs across multiple shipping zones will decide whether the brand maintains gross margins as volume scales.

    The company is now working to convert its offshore digital traffic into recurring subscriptions, with management targeting the $2 million online sales threshold before the close of the calendar year.

  • Supermom Raises S$18 Million to Expand AI Family Platform Across Southeast Asia

    Supermom Raises S$18 Million to Expand AI Family Platform Across Southeast Asia

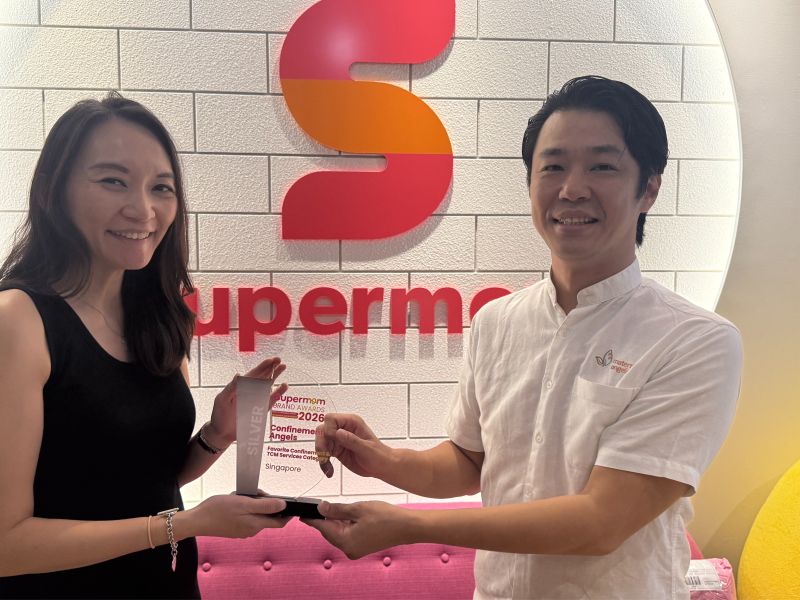
    Singapore-based parenting network and consumer data platform Supermom secured S$18 million in Series B funding to expand its artificial intelligence capabilities across Southeast Asia. The round provides fresh capital to build out data infrastructure that links consumer brands directly to parents and family shoppers.

    The company runs a network connecting mothers and families with consumer goods manufacturers, market researchers, and retail brands. Its platform uses machine-learning models to analyze parenting behavior, product sentiment, and household spending habits, allowing brands to gather consumer insights and run targeted community campaigns.

    Scaling AI Across Southeast Asia

    Proceeds from the fundraise will fund product development and cross-border expansion. Supermom is building automated matchmaking tools that pair fast-moving consumer goods companies with verified parent communities across key regional markets, including Indonesia, Malaysia, and Vietnam.

    Regional marketing spend in the family and babycare segment continues to migrate away from broad social ad channels. Brand managers face higher customer acquisition costs on open networks, pushing marketing budgets toward closed, high-trust community platforms where purchase recommendations carry more weight.

    Brand Spending Shifts to Family Networks

    RetailNews Asia has tracked how consumer packaged goods giants across the region are reallocating retail media budgets to first-party data ecosystems. By controlling the channel from parent survey to direct product trial, platforms like Supermom offer brand clients measurable conversion metrics that traditional digital display ads miss.

    The company will now focus on rolling out localized data analytics suites for multinational consumer brands before entering additional Southeast Asian markets over the next twelve months.

  • Suntory Oceania Expands Maximus Lineup with Pink Lemonade Sports Drink

    Suntory Oceania Expands Maximus Lineup with Pink Lemonade Sports Drink

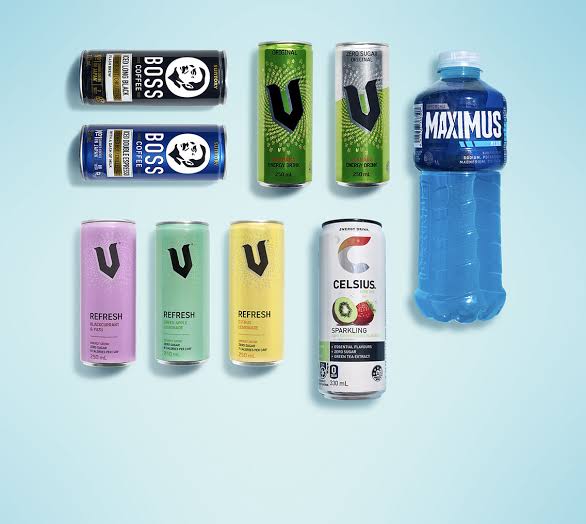
    Suntory Oceania launched a Pink Lemonade variant for its Maximus sports drink brand across Australia. The standard 1-litre bottle carries an RRP of $3.15.

    This addition expands the core beverage lineup. It follows reported incremental volume growth across the regional sports hydration category.

    Category Expansion and Flavor Lineup

    Shipments join existing Maximus varieties on retail shelves, including Blue, Mango Passionfruit, Grape, Red, and Lemonade Ice Block. Retailers are stocking the 1-litre single-serve bottle to capture commuter and athlete demand for high-volume functional drinks.

    Brand teams aimed the release at consumer demand for familiar citrus profiles in hydration. Maximus leans on its value-per-volume pitch against traditional 600ml rivals in convenience stores and supermarkets.

    Oceania Hydration Strategy

    Japanese parent firm Suntory Holdings consolidated its Australia and New Zealand commercial operations to speed up distribution across soft drinks, ready-to-drink options, and functional beverages. Maximus acts as the group’s primary volume driver against global incumbents in the regional isotonic category.

    Across Asia-Pacific, beverage makers face tighter shelf space as retailers cut underperforming SKUs for high-turnover line extensions. Suntory Oceania is pushing mainstream flavor profiles to secure fridge door share in independent petrol and grocery channels.

    Rollouts continue across major Australian retail chains and convenience networks this month. Sales velocity and inventory levels over the spring trading period will determine whether the flavor secures a permanent core ranking.

  • Moondarra Expands Dairy Line with Cranberry Vanilla Cream Cheese at Woolworths

    Moondarra Expands Dairy Line with Cranberry Vanilla Cream Cheese at Woolworths

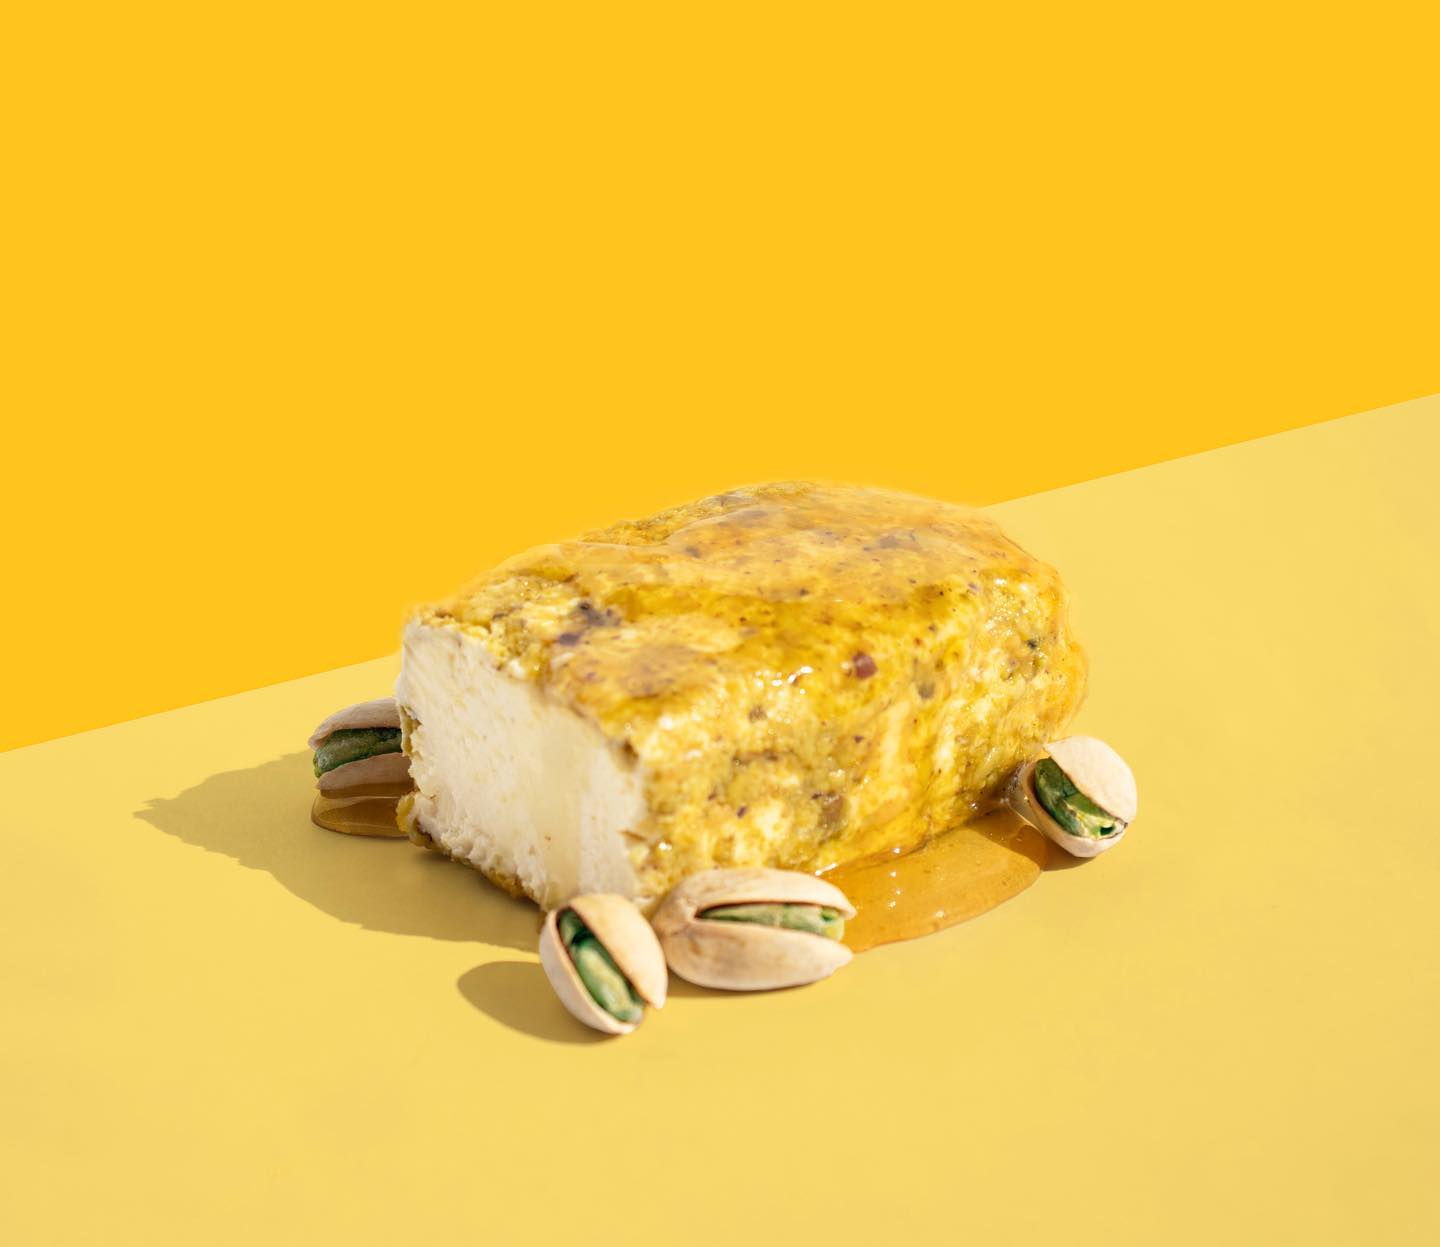
    Australian dairy brand Moondarra Cheese has rolled out a cranberry and vanilla soft cheese across selected Woolworths supermarkets nationwide, priced at $4.20 for a 120-gram tub.

    The product uses the manufacturer’s triple cream cheese base blended with cranberries and vanilla. Alongside the new SKU, Moondarra refreshed the packaging design across its broader line of marinated cheeses to improve shelf visibility in the specialty deli and dairy aisles.

    Supermarket Dairy Competition

    Sweet and savoury combination cheeses have gained shelf space in Australian grocers as producers target entertaining platters and snacking occasions. Woolworths and rival Coles have both reshuffled their specialty cheese sets over the past two years, replacing slower-moving European imports with local flavoured cheeses that offer higher margins and shorter supply chains.

    For Moondarra, the rollout secures valuable facings in Australia’s largest supermarket network. Supermarket dairy aisles remain tightly contested as private-label options squeeze mid-tier branded producers on everyday staples, pushing commercial cheese makers toward higher-value sweet and marinated segments.

    Distribution and Retail Presence

    The new cheese formulation is now available in selected Woolworths stores across the country. Moondarra will monitor sales performance across the network ahead of the key summer entertaining season.

  • New Zealand Children Food Brand Odi Launches Direct Sales in Australia

    New Zealand Children Food Brand Odi Launches Direct Sales in Australia

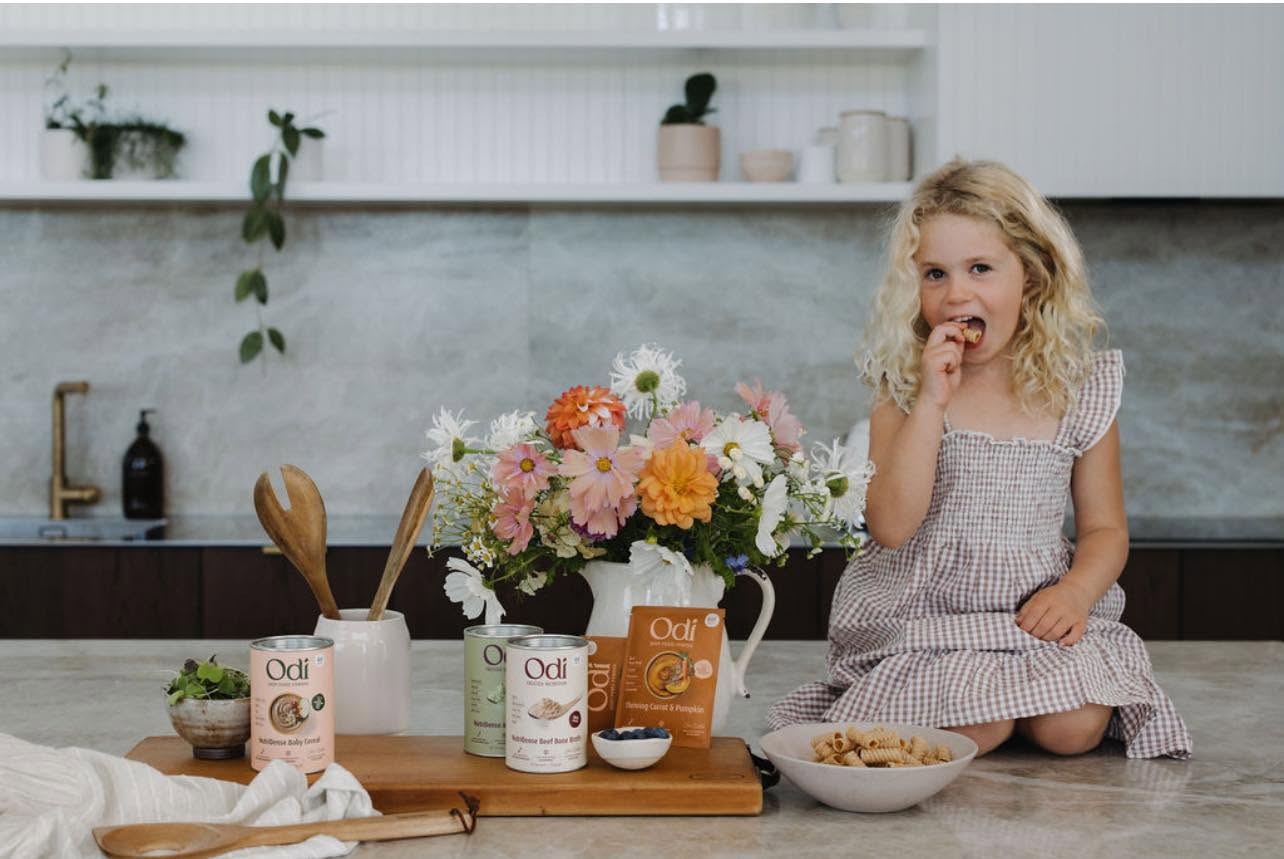
    New Zealand children’s food maker Odi entered Australia on August 28, 2026. The launch brings direct-to-consumer sales in the brand’s first international expansion outside its home market.

    Domestic retail distribution across New Zealand came first. Now, the company is targeting Australian shoppers through an online-first model.

    Direct Sales Before Supermarket Shelves

    Odi sells directly to households through its website during this initial launch. Later, it plans to secure distribution agreements with nationwide Australian grocery and food retailers.

    This export push tests whether New Zealand brand momentum translates across the Tasman without immediate supermarket placement. Direct shipping builds customer demand data first. That gives the brand use before it negotiates wholesale terms with major supermarket chains.

    Scrutiny on Infant Food Formulations

    Regulators in Australia are paying closer attention to packaged children’s food formulations. Government research found commercial infant and toddler products are major sources of dietary sugar. That finding puts pressure on established FMCG manufacturers to reformulate ranges.

    Retail buyers have responded by reviewing children’s food ranges, opening shelf space for newer independent labels. Direct sales offer New Zealand brands a fast entry point while buyers evaluate these category shifts.

    Odi will run direct fulfillment in Australia while it finalizes retail supply partnerships for a planned nationwide physical store rollout.