Tag: report

  • Airport Authority Hong Kong creates new tender structure for anchor concessions

    Airport Authority Hong Kong creates new tender structure for anchor concessions

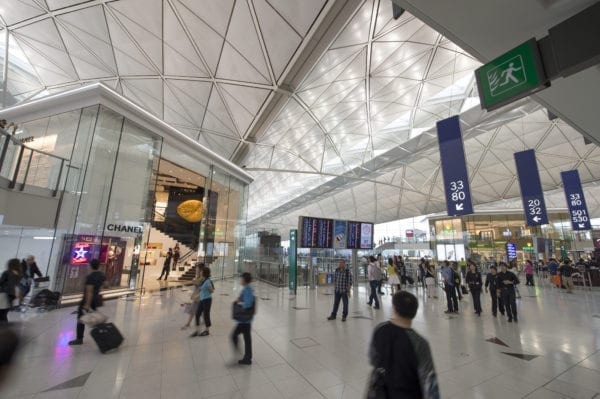
    Airport Authority Hong Kong (AAHK) will restructure its core category airside retail concessions in advance of a series of major tenders beginning late October or early November, The Moodie Davitt Report can reveal.

    There are currently three anchor concessions – liquor & tobacco, airside general merchandise, and perfumes & cosmetics, all held by DFS.

    As detailed by The Moodie Davitt Report in July, AAHK pledged earlier this year to refine the category and contract mix, promising “significant changes” to the concession structure to drive spending and improve the consumer experience at Hong Kong International Airport (HKIA).

    Since July, AAHK has been talking to potential retailers and conducting intensive consumer research with its passengers regarding the anchor licences. As a result, it has fine-tuned the contract packages.

    LIQUOR & TOBACCO AND PERFUMES & COSMETICS EXTENDED – BUT NO AIRSIDE GENERAL MERCHANDISE CONCESSION

    The core liquor & tobacco and perfumes & cosmetics concessions will be continued – but with important refinements. To spice up the traditional liquor & tobacco offering, AAHK plans to allow the new concessionaire flexibility to include other products. These include liquor & tobacco-related accessories, such as wineglasses and decanters, as well as upmarket gourmet items, for example fine teas and coffees. That concept proved highly popular with passengers during AAHK’s qualitative surveys.

    HKIA L and T

    The liquor & tobacco concession will be increased substantially both in terms of space and range, with the addition of liquor-related accessories and gourmet items

    To make the perfumes & cosmetics offer more attractive, AAHK plans to create a beauty and accessories “one-stop shopping destination”. That will involve combining perfumes & cosmetics with fashion accessories – the latter including sunglasses, fashion watches, small leathergoods, handbags and others. Those categories are currently sold through the airside general merchandise concession.

    HK P & C

    The perfumes & cosmetics concession will be extended to become a “beauty and accessories one-stop shopping destination”

    AAHK believes that the high penetration rate driven by beauty products can enhance the cross-selling potential of the two categories combined. Consumer feedback also strongly suggested that the categories are complementary.

    Critically, AAHK has decided to discontinue the airside general merchandise concession. The authority believes that given the airport’s extremely strong line-up of speciality stores and mono-brand boutiques, there is no need for the airside general merchandise concession. Instead it will allocate the best-selling general merchandise categories to the other packages.

    DEDICATED CONFECTIONERY CONCESSION

    In another key change, AAHK has opted to create a dedicated confectionery licence. Confectionery is a high-demand item at HKIA and the authority believes this justifies a separate concession covering multiple units across the terminal.

    hkia conf

    Confectionery, a big in-demand category, will enjoy its own dedicated concession

    The distribution and location of the stores will also see some important changes. For example, AAHK plans to remove the current small gate store units near the boarding gates. Because of the size constraints, the liquor & tobacco and perfumes & cosmetics assortments in them is limited. The units will be turned over to other retail purposes, deemed as better serving passengers’ needs.

    Simultaneously AAHK will increase the retail space in the East Hall – the shopping epicentre of the airport. Liquor & tobacco space there will increase by around +40%, while the addition of the fashion accessory categories will result in a huge +70% increase in the area dedicated to the extended beauty concession. More importantly, AAHK hopes that the additional floor space will allow the chosen retailers to introduce a wider product assortment.

    MORE DIVERSITY OF PRODUCTS; GREATER CONSUMER ENGAGEMENT

    In its consumer surveys, AAHK was told by many passengers that besides the big, upmarket European and US beauty brands they also wanted to see more variety – including the upcoming Korean and Japanese skincare names, most of them mid-price to premium price-points. In liquor & tobacco, consumers told AAHK they wanted to see more new and rare products.

    With the enhanced store sizes, AAHK will be asking its retailers to create greater customer engagement (for example, more wine tastings), which it deems as increasingly important to bricks and mortar stores. The enhanced space will also encourage greater flexibility, experimentation, rarity and excitement, it believes.

    TIME-LINE COUNTDOWN

    AAHK will begin the tender process with the liquor & tobacco and perfumes & cosmetics bids in late October or early November, with results being announced in March or April next year. Confectionery will be tendered in late 2016 or early 2017.

    The targeted changeover of concessions is set for the fourth quarter of 2017.

    NOTE TO AIRPORT OPERATORS: The Moodie Davitt Report is the industry’s most popular channel for launching commercial proposals and for publishing the results. If you wish to promote an Expression of Interest, Request for Proposals or full tender process for any sector of airport revenues, simply e-mail Martin Moodie at Martin@MoodieDavittReport.com.

    We have a variety of options that will ensure you reach the widest, most high-quality concessionaire/retailer/operator base in the industry – globally and immediately.

    Similarly The Moodie Davitt Report is the only international business intelligence service and industry media to cover all airport consumer services, revenue generating and otherwise. We embrace all airport non-aeronautical revenues, including property, passenger lounges, car parking, hotels, hospital and other medical facilities, the Internet, advertising and related revenue streams.
  • Hong Kong retail sales plunge for 17th month in a row

    Hong Kong retail sales plunge for 17th month in a row

    HK retail sales 07 16

    Things are not exactly looking up.

    The bad news continues for Hong Kong’s downtown duty free and travel retailers such as DFS as the latest retail sales statistics show another month-on-month decline.

    July government data provisionally indicate that the value of total retail sales in July fell by -7.7% to $34.6bn/$4.46bn, compared with July 2015. This means that for the first seven months of 2016, the value of total retail sales decreased by -10.1% compared with the same period in 2015.

    The trend in department stores was slightly better: in July they fell by -6.9% and by -8.7% in the first seven months of the year.

    The graph above shows the rate of change on a monthly basis for all retail sales in Hong Kong and it suggests that since the second quarter of 2015 there has been continuous downward, negative pressure on sales [the spikes reflect the timings of Chinese New Year].

    HIGH-VALUE ITEMS HAMMERED

    By those product categories most relevant to duty free, the figures showed a very mixed performance in July. Value sales of jewellery, watches and clocks, and ‘valuable gifts’ took a beating, decreasing by -26.2% as did electrical goods and photographic equipment (-21.8%), while footwear, allied products and other clothing accessories held their ground at (-1.1%).

    The tourism trend this year looks worse than in 2015 which is a worry.

    The overall negative trend has been attributed to the depressed tourist traffic coming to Hong Kong, particularly from China. While the July figures are not yet available, in the half-year to June visitor arrivals fell by -7.4% to 27.16m, with mainland Chinese traffic falling by over -10%.

    This follows an inbound decline of -2.9% to 59.3m in 2015, but a spending decline of -7.5% to HK$332.3bn. Of the 59.3m, Mainland China continued to be the largest visitor source market accounting for 77% of total arrivals.

  • Pos Malaysia Q1 net profit jumps 40% to RM32mil

    Pos Malaysia Q1 net profit jumps 40% to RM32mil

    Pos Malaysia Bhd’s net profit for its first quarter ended June 30, 2016 grew 40% to RM31.84mil, from RM22.74mil a year ago, despite operating in the current challenging environment, said group chief executive officer Datuk Mohd Shukrie Mohd Salleh.

    The increase was due to higher profits generated from its courier segment that was driven by demand from its e-commerce and online businesses. First quarter revenue rose to RM415.87mil from RM390.37mil a year earlier.

    Shukrie said Pos Malaysia is focussing to transform itself into a one-stop fully integrated logistics services provider through the recently approved and soon-to-be-completed corporate exercise of acquiring Kuala Lumpur Airport Services Sdn Bhd (KLAS) group of companies.

    The company will also introduce more new 24/7 e-commerce convenient touch points when it unveils a slew of new services. The company will also enhance facilities at all Pos Laju Centres and post offices nationwide. It is planning a total of 110 more touch points from the current total of 1,030 throughout Malaysia by end of 2016, Shukrie said.

    In a separate Bursa filing yesterday, the company said its courier segment registered higher revenue of RM162.8mil in the first quarter of this year compared with RM148.1mil a year ago.

    The upward performance was driven by increase in demand from e-commerce, the company said. Its postal services segment registered lower revenue of RM206.7mil in the first quarter of 2016 compared with RM230.6mil a year ago.

    “This is due to lower revenue for direct mail for mail segment and decrease of transactions from bill payment for retail segment,” Pos Malaysia said.

    Its international segment registered lower revenue by RM16.4mil as compared to RM36.1mil a year earlier due to lower transactions from transhipment business segment.

    Meanwhile, Pos Malaysia’s other segments which consist of digital certificates, printing and insertion registered higher revenue by RM7.8mil in the first quarter of this year due to higher business volume attributed to sales of digital certificates, as well as printing and insertion.

    Going forward, the company said its longer term prospects remain closely tied to the growth in the fulfilment and delivery of merchandise arising from the growth of e-commerce.

    “Investments by global e-commerce giants into the South-East Asia’s e-commerce players, for example the acquisition of Lazada by Alibaba, support the growth and development of the industry in the region.”

  • Jimmy Choo sales outperform Burberry and Mulberry

    Jimmy Choo sales outperform Burberry and Mulberry

    British footwear brand Jimmy Choo has outperformed luxury peers such as Burberry and Mulberry to post a strong set of growth figures for the first half of 2016.

    While competitors struggle with declining luxury demand in Asian markets, Jimmy Choo has bucked the trend and reported an impressive 22.1 per cent growth in Asia (ex-Japan) with China leading the way with double digit like-for-like growth; proving its measured approach to store expansion and brand building is successful without over exposing the brand.

    Europe, Middle East and Asia revenue grew by 12.2 per cent – commendable given it is one of Jimmy Choo’s most mature markets – with the UK performing well as domestic demand remained robust, supported by a renovated store portfolio.

    The recent uptick in luxury goods demand in the UK, as international travellers take advantage of the weaker pound, will further benefit Jimmy Choo’s UK performance in the second half.  The Americas, however, is proving a tougher nut to crack though, as sales declined 3.4 per cent; affected no doubt by the continuing volatility in the US department store market which has led wholesale orders to decline.

    Creative director Sandra Choi has led a strong half year of product design, building upon Jimmy Choo’s British identity to produce ranges which continue to resonate with consumers across the globe. The brand’s recent decision to focus on expanding men’s footwear is proving fruitful, as it’s now its fastest growing category, representing 8 per cent of total revenue. That will continue to grow as the brand opens dual gender stores and invests in the product and marketing of men’s collections.

    Globally, Jimmy Choo sales grew 9.2 per cent at reported currency and 3.8 per cent at constant currency. Improved gross margins and cost controls drove adjusted EBITDA growth of 13.7 per cent. Reported operating profit rose 42.6 per cent to £25.3 million.

    Jimmy Choo is in prime position to continue its growth momentum with its multi-pronged focus on eCommerce (bolstered by growing social media engagement and a robust distribution network) and conversion of retail outlets to new concept stores – all supported by a stellar product offer that is effective in both design and range.

    *Nivindya Sharma

  • Analytics shift to predictive, prescriptive

    Analytics shift to predictive, prescriptive

    While the value of historical and descriptive analytics persists, the balance has been tipped towards more predictive and prescriptive analytics, according to a new report from Machina Research.

    For many decades, enterprises have solidly built their knowledge, strategic insights and processes around well-established approaches to data management and analytics.

    Terms such as ETL (extract-transform-load), data warehouses, data-marts and business intelligence became solid ground on which to build strategic and business approaches and decisions.

    With millions of connected devices providing real-time data about the physical world as it is, data management and analytics processes have been inundated with new requirements and opportunities.

    Machina Research said business and strategic decisions are being augmented with highly operational and predictive/prescriptive analytics, shifting the ground from “look at what happened” to “what may happen” and how best to address those potential scenarios.

    “One of the more significant developments as part of, and in parallel to, developments in IoT, is the approach of two different ‘waves’ in data management—Big Data and Fast Data,” said Emil Berthelsen, principal analyst at Machina Research.

    “Both are characterized by scale and speed, and the combination or aggregation of these two waves have led to significant changes and new requirements on data management technologies,” said Berthelsen.

    He said the landscape of IoT data and analytics is certainly evolving and will include a new age of machine learning, augmented insights and managed autonomy, as well as a new set of enabling technologies and data governance tools.

  • Singapore REITs’ performance falls flat in 2Q

    Singapore REITs’ performance falls flat in 2Q

    Overall DPU growth sits at -0.1%.

    While its retail sector remained resilient, other sectors such as hospitality and industrial have continued to impede Singapore real estate investment trust (REITs)’s growth, registering a flat -0.1% improvement in 2Q16.

    Even with the dismal performance, OCBC Investment Research said the REITs’ performance in 2Q is in line with the expectations.

    OCBC noted that the strong performances of OUE Commercial Trust, Lippo Malls Indonesia Retail trust and Mapletree Greater China Commercial Trust have offset the underwhelming performance of their peers in the hospitality and industrial sector.

    The three registered DPU growths of 34.7%, 16.4%, and 9.1%, respectively.

    Overall, the flat REIT DPU growth was amid the decent uptick in net property income at 8.2% and distributable income 5.2%.

    “This can be attributed to the regular issuance of new units as partial/full payment of management fees, coupled with REITs which have recently carried out equity fund raising exercises,” OCBC explained.

    Meanwhile, it explained how hospitality sector have remained the main drag during 2Q, pointing out to the weakness in revenue per available room for Singapore hotels and revenue for available unite in serviced residences.

    “Most industry players highlighted that June was a particularly poor month. We believe this could be attributed largely to the absence of the SEA Games which took place in June last year. Another key factor for the muted performance was due to weaker demand from the corporate sector,” OCBC said.

    For the industrial sector, its poor performance came from small-mid cap REITs.

    Looking forward, OCBC said the operational performance of the REITs would continue to be be pressured by the macroeconomic uncertainties and supply concerns.

    More so, it explained that some REIT managers are making use of the soft environment to carry out asset enhancement initiatives to reposition their assets in the future.

    These projects, the report warned, would result in a fall or loss of income contribution in the near future and will eventually mute DPU growth.

  • Estee Lauder’s quarterly sales miss on lower retail traffic

    Cosmetics maker Estee Lauder Cos. reported a smaller-than-expected rise in quarterly sales, hurt by a slowdown in sales in the Americas as fewer customers visited department stores and tourist spending declined.

    Shares of the company were down about 4 percent at $91.34 before the bell on Friday. Up to Thursday’s close, the stock had risen 13.5 percent in the past year.

    Sales in the Americas, its biggest market, rose 1.4 pct to $1.1 billion on a reported basis, its slowest growth in four quarters.

    Lower retail traffic mainly affected the company’s “heritage” brands Estee Lauder and Clinique, and a few M.A.C freestanding stores.

    Demand for its skin care products continued to weaken, as the company cited overall global slowdown in the category. Sales from its namesake brand and Clinique were also hurt by lower sales in some Asia-Pacific countries, mainly Hong Kong.

    “Social and political issues, currency volatility and economic challenges are affecting consumer behavior in certain countries, such as Hong Kong, France and some emerging markets,” the company said.

    Rival L’Oreal SA earlier reported second-quarter sales growth marginally below forecast as the company said Western Europe was being held back due to a “very difficult market in France.”

    Net income attributable to the company fell to $93.5 million, or 25 cents per share, in the quarter, from $153 million, or 40 cents per share, a year earlier.

    Net income was hurt by restructuring and other charges. Excluding items, the company earned 43 cents per share. Net sales rose to $2.65 billion from $2.52 billion. Analysts on average had expected a profit of 40 cents per share and revenue of $2.66 billion.

    New York City-based Estee Lauder said its expects fiscal 2017 adjusted profit to be between $3.38-$3.44 per share, missing analysts’ estimates of $3.53.

    The company also said it expects to incur restructuring charges of about $80 million-$100 million in fiscal 2017, related to its Leading Beauty Forward strategy.

    As part of its Leading Beauty Forward strategy, the company had earlier approved restructuring initiatives to exit businesses in certain markets and channels of distribution while also reducing its workforce globally.


  • Modern Trade back for Growth for 2nd quarter of 2016

    Modern Trade back for Growth for 2nd quarter of 2016

    Kantar Worldpanel, the global market leader in consumer panels, reports the spending in fast moving consumer goods (FMCG) in 2nd quarter of 2016 grew by 4.6% year on year, faster than the 2.0% growth rate reported in 1st quarter of 2016.

    Modern trade (including hypermarkets, supermarkets, and convenience stores) showed a similar trend of improving growth, 1.4% positive growth in the second quarter in comparison to a decline of -0.5% in the 1st quarter. Modern trade’s growth was most prominent in county level cities and their surrounding urbanized counties – growth rates of 2.0% and 3.9% respectively. From a regional perspective, modern trade in the East and West performed much better than South and North regions. The East region grew at 2.8% – helped by strong performance of Sun-Art Group and Wal-Mart Group – while the West region grew at 3.6% driven by Wal-Mart Group and Yonghui Group.

    International retailers suffer from continuous share drop

    Wal-Mart Group has seen relatively stable performance in 2016, gaining 0.3 share points year on year in the latest quarter. Other international retailers such as Carrefour, Tesco and Lotus suffered from continued share erosion resulting in the overall poor performance of international retailers. Sun-Art Group and Yonghui lead the growth of Chinese players. Sun-Art group managed to grow its shopper base through both the continued development of existing stores and incremental opening of new one. Their growth was most marked in the competitive East region market; share increased from 13.5% of 2nd quarter of 2015 to 16.0% in the latest quarter – widening their leadership over competitors.

    Yonghui consolidates position as a top 5 national retailer: Yonghui continues to perform well in 2016, a fast pace of growth in penetration and basket size enabling its share to continue to exceed Lianhua Groups in Q2 after first overtaking it in Q1. Despite this strong performance – Yonghui still faces challenges in the East region. Strong growth of Sun-Art Group and Wal-Mart’s gradually recovery have meant that Yonghui’s acquisition of Lianhua has yet to see any sustained effects.

    Brick and Mortar and eCommerce retailers looking for cooperation: Continuous FMCG slow down combined with the impact from eCommerce growth in China, has pressured physical retailers into finding new solutions to drive growth. Kantar Worldpanel latest data show, 52 week end June.17th, show total FMCG eCommerce penetration% reached 49%, growing 10% from last year. The growth of online is leading by Tmall and JD, both with spend growth rate over 80%. While continuing to experiment with their own e-tailing platforms; the major retail chains are now seeking to bolster performance through strategic partnerships with existing digital players. Wal-Mart’s corporation with JD.com enables Wal-Mart to reach new online shoppers while allowing JD.com to utilize YHD’s broad footprint in East region. Vanguard’s strategic investment in the XinMeiDa (previously Meituan & Dianping) and Feiniu’s corporation with Shihui, both show brick-and-mortar chains’ new efforts to better realize their O2O strategy.

  • Retail sales up 0.9% on-year in June, boosted by vehicle sales

    Retail sales up 0.9% on-year in June, boosted by vehicle sales

    Retail sales in Singapore rose 0.9 per cent in June compared with the previous year, mainly due to a jump in sales of motor vehicles, the Department of Statistics (SingStat) said on Monday (Aug 15).

    However, excluding motor vehicles, retail sales dipped 3.0 per cent compared with the same period a year ago.

    On a month-on-month basis, retail sales were down 1.5 per cent in June. Excluding motor vehicles, retail sales dropped 3.7 per cent.

    The total retail sales value in Juune was estimated at S$3.6 billion, similar to a year ago.

    Retailers of motor vehicles recorded a sales increase of 17.1 per cent compared to the previous year, the highest increase of all sectors. The next best performing sector was furniture and household equipment, which saw a 5.8 per cent increase. The medical goods and toiletries sector also recorded an increase of 3.0 per cent.

    Other than the mini-marts and convenience stores section, which was unchanged, all other sectors were in the red.

    According to SingStat, the telecommunications apparatus and computers sector fell the most at 25.1 per cent, compared with the previous year. This was followed by petrol service stations, which fell 14.1 per cent, and recreational goods, which saw a 11.8 per cent dip.

    Sales of food and beverage services rose 0.4 per cent from the previous year. The total sales value of food and beverage services in June was estimated at S$649 million, higher than the S$646 million in June 2015.

    The Retail Sales Index and the Food and Beverage Services Index measure the short-term performance of retail and F&B service industries based on their sales records. The sales figures exclude taxes such as GST and COE.

  • Mainland China retail sales growth slows in July

    Mainland China retail sales growth slows in July

    Mainland China’s retail sales growth slowed sharply in July, statistics showed Friday, missing expectations in a disappointing sign for the world’s second-largest economy as the mainland China authorities look to consumer demand to push growth.

    Retail sales rose 10.2 percent in the month, the National Bureau of Statistics (NBS) said, a marked slowdown from June’s 10.6 percent increase and below the median forecast of 10.5 percent in a Bloomberg News poll of economists.

    Beijing is looking to retool the economy from a reliance on investment spending and exports to one driven more by consumer demand, but the transition is proving bumpy and gross domestic product growth is slowing.

    China is a key driver of the world economy but grew at its slowest rate in a quarter of a century last year, and has decelerated further since then.

    Industrial output in the Asian giant rose 6.0 percent in July over the year before, the NBS said, while fixed asset investment (FAI), a gauge of infrastructure spending, rose 8.1 percent in the first seven months of the year.

    Those figures also missed expectations of 6.2 percent and 8.9 percent respectively.

    Analysts were disappointed. Zhao Yang of Nomura called the figures an “across-the-board slowdown” that showed more weakness than expected. The investment figures were consistent with a deep contraction in imports that “points to sluggish domestic investment demand.”

    Looking ahead, factory output will face further downward pressures due to efforts to cut overcapacity, analysts with ANZ Research said in a note.

    Industrial production “may further dampen” this quarter, they added, as a result of flooding around the Yangtze River and suspended factory production in Zhejiang province, one of China’s most developed areas, due to a forthcoming G-20 summit in Hangzhou.

    Unswervingly Advance

    The NBS said in a statement China’s economy was “basically steady” in July but said that “serious disasters” from flooding and high temperatures in some parts of the country caused some indicators to slow.

    “However, overall economic development kept performing in a proper range with steady pace, as a result of stable employment and prices, deepened supply-side structural reform and accumulated new impetus,” it said.

    China should “unswervingly advance” supply-side structural reform and expand aggregate demand, it added.

    NBS spokesman Sheng Laiyun said it was “reasonable” for FAI growth to fall long-term as the economy shifts away from traditional heavy industries toward the service sector, which does not require as intensive investment.

    “The trend is good,” Sheng told a news conference. “Even though economic growth dropped slightly, the economy is stable and making steady progress, and the steady trend toward improvement has not changed.”

    Sheng acknowledged, however, that China faces “downward pressure” from weak global demand as Beijing carries out a marathon effort to nurture consumer-driven growth and reduce reliance on trade and investment.

  • Security on cloud still a major challenge for global firms, says study

    Security on cloud still a major challenge for global firms, says study

    Despite the continued importance of cloud computing resources to organizations, companies are not adopting appropriate governance and security measures to protect sensitive data in the cloud.

    This is just one of the findings of a Ponemon Institute study titled “The 2016 Global Cloud Data Security Study,” commissioned by digital security firm Gemalto.

    The study surveyed more than 3,400 IT and IT security practitioners worldwide to gain a better understanding of key trends in data governance and security practices for cloud-based services.

    According to 73% of respondents, cloud-based services and platforms are considered important to their organization’s operations and 81% said they will be more so over the next two years. In fact, 36% of respondents said their companies’ total IT and data processing needs were met using cloud resources today and that they expected this to increase to 45% over the next two years.

    Although cloud-based resources are becoming more important to companies’ IT operations and business strategies, 54% of respondents did not agree their companies have a proactive approach to managing security and complying with privacy and data protection regulations in cloud environments. This is despite the fact that 65% of respondents said their organizations are committed to protecting confidential or sensitive information in the cloud. Furthermore, 56% did not agree their organization is careful about sharing sensitive information in the cloud with third parties such as business partners, contractors and vendors.
    Larry Ponemon, chairman and founder of Ponemon Institute, said, “Cloud security continues to be a challenge for companies, especially in dealing with the complexity of privacy and data protection regulations.”

    “To ensure compliance, it is important for companies to consider deploying such technologies as encryption, tokenization or other cryptographic solutions to secure sensitive data transferred and stored in the cloud,” Ponemon said.

    Jason Hart, VP and CTO for Data Protection at Gemalto, said, “Organizations have embraced the cloud with its benefits of cost and flexibility but they are still struggling with maintaining control of their data and compliance in virtual environments.”

    “It’s quite obvious security measures are not keeping pace because the cloud challenges traditional approaches of protecting data when it was just stored on the network. It is an issue that can only be solved with a data-centric approach in which IT organizations can uniformly protect customer and corporate information across the dozens of cloud-based services their employees and internal departments rely every day,” Hart said.
    More customer information is being stored in the cloud and is considered the data most at risk.
    According to the survey, customer information, emails, consumer data, employee records and payment information are the types of data most often stored in the cloud. Since 2014, the storage of customer information in the cloud has increased the most, from 53% in 2014 to 62% of respondents saying their company was doing this today.

  • More than half the world is still offline

    More than half the world is still offline

    Despite falling prices for ICT services, more than half of the world’s population is still not connected to the internet, the latest ITU figures show.

    The UN agency estimates that 3.9 billion people remain cut-off from the vast resources available on the internet.

    The newly released report ICT Facts & Figures 2016 shows that developing countries now account for the vast majority of internet users with 2.5 billion users compared with one billion in developed countries. Internet penetration rates, however, tell a different story.

    In developed countries, internet penetration is pegged at 81% of the population, compared with 40% in developing countries and 15% in the least developed countries. It is also higher for men than for women in all regions of the world.

    The report noted that the global internet user gender gap actually grew from 11% in 2013 to 12% in 2016. The regional gender gap is largest in Africa, at 23%, and smallest in the Americas, at 2%.

    By early 2016, international internet bandwidth had reached 185,000 gigabits per second, up from a low of 30,000 gigabits in 2008. However, bandwidth is also unequally distributed globally, and lack of bandwidth remains a major bottleneck to improved Internet connectivity in many developing and least developed countries.

    ITU Secretary-General Houlin Zhao said more needs to be done to bridge the digital divide and bring the more than half of the global population not using the internet into the digital economy.

    “ITU, given the tremendous development of ICTs, has a key role to play in facilitating their attainment,” affirmed Brahima Sanou, the Director of the ITU’s Telecommunication Development Bureau.

  • Real Singapore retail sales continue to decline

    Real Singapore retail sales continue to decline

    Real Singapore retail sales in May rose on April’s figures – but remain down year-on-year.

    According to Statistics Singapore, total retail sales (seasonally adjusted) increased 1.4 per cent in May 2016 over April. Excluding motor vehicles, retail sales increased an even better 2.3 per cent.

    But compared to May 2015, retail sales decreased 3.3 per cent after removing motor vehicle sales from the data. Including vehicles, total sales rose 3 per cent year-on-year.

    After seasonal adjustment, retail sales of watches & jewellery, furniture & household equipment, food & beverages, optical goods & books, department stores, apparel & footwear, medical goods & toiletries and petrol stations increased between 0.8 per cent and 6.5 per cent in May 2016 compared to April.

    Retail sale SG May 16

    In contrast, retail sales of recreational goods, mini-marts & convenience stores, phones & computers and supermarkets decreased by between 0.4 per cent and 6.3 per cent in May over April 2016.

    Year-on-year, retail sales of furniture & household equipment and medical goods & toiletries grew by 3.1 per cent and 1.9 per cent respectively.

    Conversely, retail sales of phones & computers and petrol service stations declined 17.3 per cent and 14.9 per cent respectively. Sales of recreational goods, optical goods & books, watches & jewellery, food & beverages, supermarkets, mini-marts & convenience stores, apparel & footwear and department stores also fee, by between 1.9 per cent and 8.7 per cent. .

    The total retail sales value in May 2016 was estimated at $3.7 billion, higher than the $3.6 billion in May 2015.

    Food & beverage service sales

    Retail sale SG FnB May 16

    Sales of food & beverage services (seasonally adjusted) increased 0.9 per cent in May over April.

    Compared to May last year, sales of food & beverage services increased 0.7 per cent.

    The total sales value of food & beverage services in May 2016 was estimated at $690 million, higher than the $685 million in May 2015.

    Year-on-year, sales by ‘other’ eating places grew by 6.7 per cent and by fast food outlets by 1 per cent.

    However, turnover of food caterers decreased 3.7, and of restaurants by 3.6 per cent.

  • Singapore economy grows 2.2% in Q2, beating expectations

    Singapore economy grows 2.2% in Q2, beating expectations

    The Singapore economy grew 2.2 per cent on a year-on-year basis in the second quarter, marginally higher than the 2.1 per cent expansion in the previous quarter and in line with analysts’ expectations, according to advance estimates from the Ministry of Trade and Industry (MTI) on Thursday (Jul 14).

    On a quarter-on-quarter, seasonally adjusted and annualised basis, the economy expanded 0.8 per cent, an improvement from the 0.2 per cent growth in the first quarter.

    The figures were in line with analysts’ forecasts, with economists in a Reuters poll predicting a 2.2 per cent year-on-year growth and a 0.9 per cent growth on a quarterly basis.

    The manufacturing sector expanded by 0.8 per cent on a year-on-year basis, a reversal from the 0.5 per cent decline in the previous quarter. Growth was supported by an increase in the output of the biomedical manufacturing and electronics clusters, MTI said. On a quarter-on-quarter basis, the sector grew at an annualised rate of 0.3 per cent, following the 18.4 per cent growth in the preceding quarter.

    The construction sector grew by 2.7 per cent, easing from the 4.5 per cent growth recorded in the previous quarter. The moderation in growth was largely due to a slowdown in private sector construction activities, the ministry said. On a quarter-on-quarter basis, the sector expanded at an annualised rate of 0.6 per cent, lower than the 3.5 per cent expansion in the preceding quarter.

    Growth in the services-producing industries came in at 1.7 per cent, the same pace of growth as in the previous quarter. Growth was driven mainly by wholesale and retail trade, and the transportation and storage sector. Within the retail trade sector, growth was supported by strong motor vehicle sales. On a quarterly basis, the industry grew by 0.5 per cent, reversing the 4.8 per cent contraction in the preceding quarter.

    The advance GDP estimates were computed largely from data in the first two months of the quarter – in this case, April and May. They are intended as an early indication of the GDP growth in the quarter, and are subject to revision when more comprehensive data become available, said MTI.

    The preliminary GDP estimates for the second quarter, including performance by sectors, sources of growth, inflation, employment and productivity, will be released next month.

    GROWTH IN LINE WITH EXPECTATIONS, BUT LIKELY TO DETERIORATE: ANALYSTS

    Mizuho senior economist Vishnu Varathan said manufacturing primarily drove the improvement for the second quarter.

    “Manufacturing snapped six consecutive quarters of year-on-year contraction, to come into an expansion. It’s a modest expansion, but nonetheless a poignant one,” he said.

    The improvement of the economy in the second quarter, after the numbers for the first quarter were upwardly revised from 1.8 per cent to 2.1 per cent, probably framed a “stabilisation story” in Singapore’s growth, if not a slight improvement, added Mr Varathan.

    However, economists told us the recovery is likely to be tentative, with the volatile pharmaceuticals unlikely to sustain the lift in industrial production, while sectors like transport engineering and petrochemicals continue to show signs of weakness.

    On the external front, the impact from UK’s vote to leave the European Union is likely to be felt in the coming months, said Mr Brian Tan, Nomura Singapore’s Southeast Asia economist.

    “The Singapore economy is so open, not just to trade, but also from the financial market channels because we’re an international financial centre, so both these channels could have a very negative impact on the Singapore economy once Brexit has happened,” Mr Tan said.

    He added the impact may possibly be apparent in the July and August trade data, saying that “because of this, we worry that the growth outlook for Singapore will deteriorate over the coming quarters, especially when we get into the third quarter when the impact of Brexit might be a bit more visible.” 

    Amid ongoing macroeconomic risks and currency market volatility, observers also said the Monetary Authority of Singapore is likely to actively review the need to weaken the Singapore dollar.

    For the full year, the Government’s forecast is for Singapore’s economy to grow by between 1 and 3 per cent.

  • Hong Kong retail sales fall further

    Hong Kong retail sales fall further

    The latest Hong Kong retail sales data shows the rate of decline is continuing to slow this year.

    In May, according to information from the Census and Statistics Department released on the eve of Friday’s holiday, there was a year-on-year decline of 8.4 per cent to a provisionally estimated $35.7 billion. While that is a full percentage point higher than April’s decline, it is lower than the 10.8 per cent decline recorded for the first five months of the year, and the 11.4 per cent for the first four months.

    Based on the seasonally adjusted data, the value of total retail sales increased by 1.1 per cent in the three months ending May 2016 compared to the preceding quarter, while the volume of total retail sales increased by 0.3 per cent.

    Once again, falling jewellery and luxury goods sales brought the overall figures down, plunging nearly 20 per cent in May.

    A government spokesman said retail sales stayed weak in May, with many types of retail outlet still registering year-on-year declines in sales. “This was due partly to the drag from the slowdown in inbound tourism and partly to the more cautious local consumer sentiment amid the subpar economic conditions.”

    He said the near-term outlook for retail sales is still subject to a large degree of uncertainty, depending on the performance of inbound tourism as well as the extent to which local consumption sentiment will be affected by the increased external headwinds and heightened financial market volatility.”

    After netting out the effect of price changes over the same period, the volume of total retail sales in May 2016 decreased by 9 per cent compared with a year earlier. The revised estimate of the volume of total retail sales in April 2016 decreased by 7.7 per cent year-on-year and for the first five months of the year by 10.2 per cent.

    By broad retail category – in descending order of value – sales of jewellery, watches and clocks, and valuable gifts decreased by 18.7 per cent. This was followed by sales of commodities in department stores (down 5.9 per cent); apparel (down 5.7 per cent); electrical goods and photographic equipment (down 25.2 per cent); miscellaneous consumer durable goods (down 34.6 per cent); footwear and accessories (down 6.3 per cent); books, newspapers, stationery and gifts (down 6 per cent); furniture and fixtures (down 6 per cent); Chinese drugs and herbs (down 7.2 per cent); and optical shops (down 8.8 per cent).

    Sales of commodities in supermarkets increased by 1.5 per cent, medicines and cosmetics by 0.3 per cent; and food, alcoholic drinks and tobacco by 3.1 per cent.