Tag: Retailers

  • Macau retailers still cautious, despite better sales

    Macau retailers still cautious, despite better sales

    While retail outlets and dining establishments had better year-on-year sales in May, Macau retailers are still cautious about their business prospects, says the Macau Statistics and Census Service (DSEC).

    For its monthly business climate survey, the DSEC interviewed 167 dining enterprises that account for 53 per cent of the industry’s receipts, and 135 retailers that account for 70 per cent of trade.

    Despite their caution, 26 per cent of retailers expect a year-on-year increase in sales, up three points from May, while 38 per cent are less optimistic. During May, 36 per cent of the retail respondents indicated a year-on-year sales decline, a drop of two points.

    Experiencing better-than-expected results were adults’ clothing retailers and supermarkets, which exceeded forecasts by 40 and 33 points respectively.

    For June, 80 per cent of the respondents in the leather-goods area expect improved sales with all respondents having year-on-year increases in May.

    Watches, clocks and jewellery retailers had a 24-point rise in expectations for June, hitting 50 per cent, while department stores predict a 22-point increase to 56 per cent.

    Restaurants had a six-point drop from the previous month in the percentage of respondents reporting year-on-year growth, while those who had a year-on-year decline rose 10 points to 33 per cent.

    DSEC says the results were better than expected, as the April survey indicated only 18 per cent of respondents expected better sales figures.

    Expectations for last month are mainly pessimistic with 41 per cent of respondents expecting receipts to dip while while only 22 per cent expect a rise. Predicting increases are 27 per cent of Chinese restaurants, 25 per cent of Western restaurants and 18.8 per cent of Japanese and Korean restaurants.

    On the other hand, 60 per cent of Western restaurants foresee a drop.

  • 3,000 stores to open in India, world’s most promising retail market

    3,000 stores to open in India, world’s most promising retail market

    The recent implementation of the GST along with the rise of e-commerce has caused over 50 brands to announce that they will launch in India in the next six months.

    Data compiled by Franchise India states that a large number of brands, including 14 from the US and 11 from Singapore, are set to start business in India. The main sectors they will be doing business in are the food and beverage industry where 18 new brands will be launching and the apparel and lifestyle industry where 13 brands will be launching.

    Just some of these international fashion, cosmetic, and lifestyle brands launching at present in India are Greece’s bag manufacturer Migato and Lush Addiction, a jewellery company from Singapore using Swarovski crystals in its designs. Others include Korres, Monnalisa, Evisu, and Melting Pot. Education-focused brands will also be coming to India from abroad.

    An AT Kearney report stated that this month India overtook China as the most promising retail market in the world. Many international companies are experiencing troubles in their home countries due to the economic downturn and so are hoping that launching in India will help to boost their finances.

    India is currently an attractive market to launch in due to its growing middle class as well as increasing urbanisation. Moreover, e-commerce is blossoming as more and more labels are experiencing success through online retail portals.

    The government has now allowed 100% foreign ownership in business to business e-commerce ventures and has made efforts to boost cashless payments which is making the online market easier to break into for foreign firms.

  • Philippines convenience-store market among the least mature in Asia

    Philippines convenience-store market among the least mature in Asia

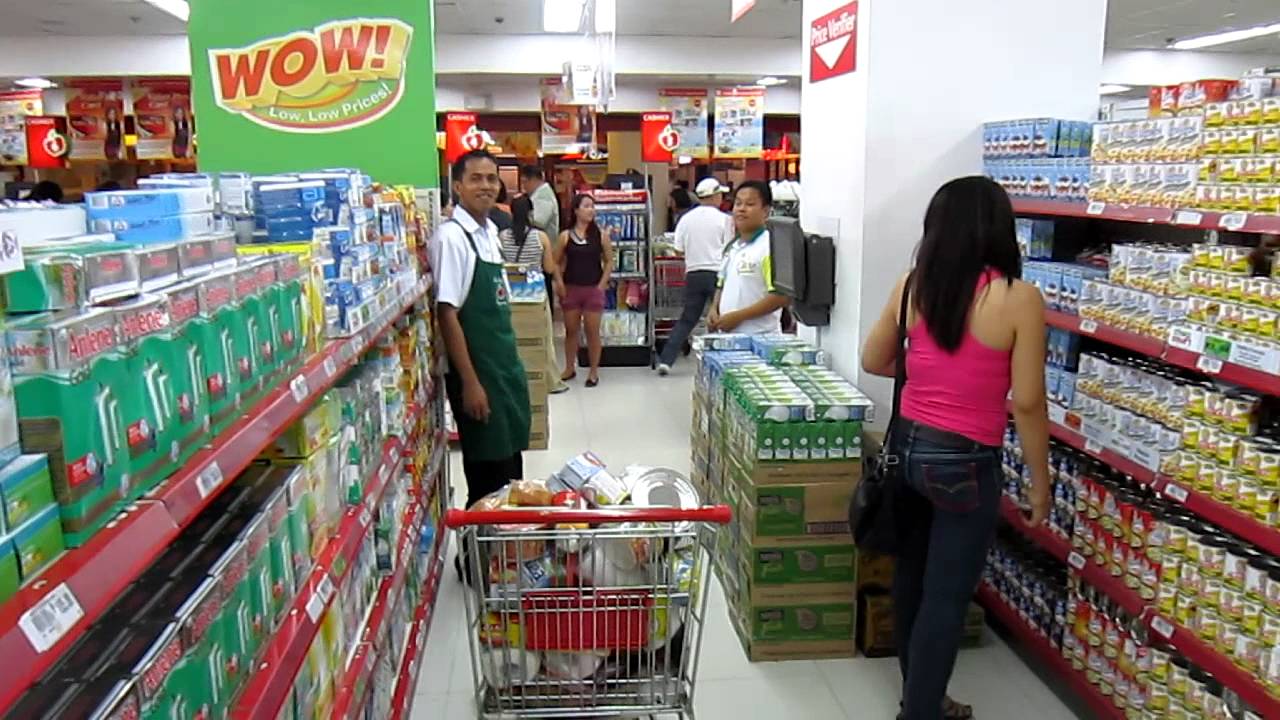
    The Philippines convenience-store market is one of the most unsaturated in Asia.

    The country had one store for every 35,000 people last year – a ratio similar to China – whereas in Indonesia, Malaysia and Thailand that figure ranges between 5500 and 10,000 people. In developed Asia, Japan and South Korea have around 1700 people to each store.

    With per-capita income growing about 5 per cent a year in the Philippines, the number of convenience stores has risen by 21.5 per cent a year over the past five years.

    Convenience-store sales have risen 20 per cent each of the past five years, double the rate of normal retail sales.

    With the nation’s historic ties to the US, 7-Eleven leads the way in the Philippines. The chain is licensed by Philippine Seven, which owns 45 per cent of the 1995 stores and franchises out the rest.

    Japan’s Nomura works through Robinsons Retail Holdings, which has exclusive rights to the Ministop chain for the Philippines.

    Only 7-Eleven has anything of an e-commerce presence in the Philippines, says the report, delivering goods from the country’s largest online-sales platform, Zalora Philippines.

  • China’s retail sales grow 10.4 per cent

    China’s retail sales grow 10.4 per cent

    China’s retail sales of consumer goods grew 10.4 per cent year-on-year in the first half of this year to RMB17.24 trillion (US$2.55 trillion), new official data shows.

    The pace was slightly faster than the 10 per cent for the first quarter, the National Bureau of Statistics (NBS) says.

    Retail sales last month grew by 11 per cent year-on-year, the fastest rate since December 2015.

    The NBS attributes the pick-up in growth partly to online sales, which surged 33.4 per cent year-on-year in the first half, 1.3 points higher than in the first quarter.

    Online sales of goods rose 28.6 per cent to RMB2.37 trillion, accounting for 13.8 per cent of China’s total retail sales, up from a share of 11.6 per cent for the first half of last year.

    NBS spokesman Xing Zhihong says the larger share proves new growth sources in the economy are rising.

    Retail sales in rural areas rose 12.3 per cent in the first half, outpacing the 10.1 per cent expansion for urban areas.

    Booming retail sales are behind China’s stabilising economy, which grew 6.9 per cent in the first half.

    The contribution of final consumption to GDP growth stood at 63.4 per cent, slightly down from last year’s 64.6 per cent.

    “Consumption demand is the most important engine of our economic growth,” says Xing.

  • Queenstown retail centre’s first stage complete

    Queenstown retail centre’s first stage complete

    The first stage of the NZ$130 million Five Mile Retail Centre development at the gateway to Queenstown has opened, after the site’s conversion from an abandoned construction project into a state-of-the-art shopping precinct.

    The 14,000sqm site is now home to retailers including Countdown, Briscoes Homeware, Rebel Sport, Warehouse Stationery, Number One Shoes, Supercheap Auto, and ANZ Bank.

    The complex will also eventually accommodate 800 carparks (including 250 underground) food operators, offices, serviced apartments and a child care centre.

    Australasian design firm The Buchan Group was appointed by Queenstown Gateway Ltd in 2012 to complete architecture, master planning, interior and graphics works for the project, located beside Queenstown Airport.

    The site had been home to a 2.4ha hole created from a construction project that was abandoned when the previous developer was placed into receivership in 2008.

    The Buchan Group Principal David Thornton said the first stage of the Five Mile Retail Centre had finally created an inviting gateway to Queenstown from the eastern approach through to Frankton.

    “Our vision was to design a development befitting the region that reflected the unique characteristics of the stunning surrounding vistas,” he said.

    “This meant not only designing a modern retail centre that was appealing to locals and visitors, but also one that was suitably striking for one of the best locations in the Frankton and Shotover region.

    “The buildings also frame view shafts to Double Cone, Peninsula Hill, Cecil peak and Walter Peak, ensuring the development highlights these natural assets.”

  • Supply of Bangkok retail space keeps growing

    Supply of Bangkok retail space keeps growing

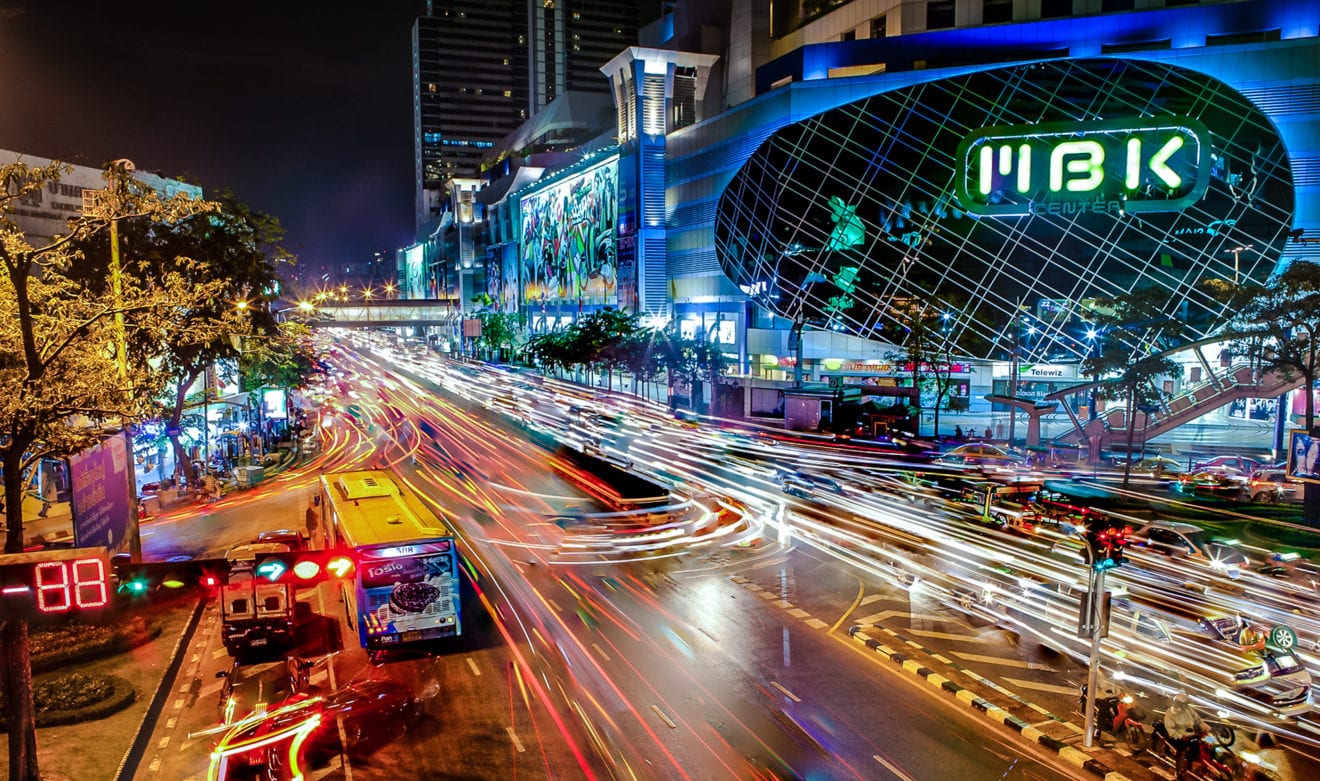
    Despite the challenges of low consumer purchasing power and the growth of online shopping, the supply of Bangkok retail space is continuing to grow.

    Colliers International Research expects about 300,000 sqm of new retail space to enter the Thai market this year.

    “Shopping malls have multiplied in numbers over the past few years, currently occupying the highest share in retail supply,” says Colliers International associate director Surachat Kongcheep.

    Around 114,350 sqm of new retail space opened in the first half of this year, pushing the total retail area in Bangkok to more than 7.6 million sqm. The new space mostly involves malls and office buildings in outer Bangkok, which comprises more than 60 per cent of total retail supply.

    Although Thailand’s economy has not fully recovered, many developers are still launching retail projects as long-term investments.

    Show DC shopping complex is the only large retail project to have opened so far this year.

    A source at IconSiam says the developer has postponed this year’s opening of the IconSiam Project, a 750,000 sqm retail space by the Chao Phraya River. Luxury Japanese department store Takashimaya is one of the project’s main anchors.

    Surachat says the growth of community malls, which boomed in Bangkok’s retail sector three years ago, started to slow down last year because of the developers’ lack of expertise in the retail business.

    As of the second quarter of this year, shopping malls in Bangkok and surrounding areas covered 4.4 million sqm, or 58 per cent of the capital’s total retail supply, which is about 7.6 million sqm.

    Even more malls

    Colliers’ research shows the major players in the retail sector will continue to increase the number of shopping malls in Thailand, especially in major cities, while other retailers will focus on expanding their portfolios internationally.

    Despite weak spending power, most hypermarkets, speciality stores and large shopping malls in Bangkok’s suburban areas are at 100 per cent occupancy level, says Surachat. Occupancy rates in all retail categories in the second quarter were nearly the same as those in the previous quarter, at rates above 96 per cent. Most of these areas are occupied by hypermarkets and surrounded by speciality stores and entertainment complexes.

    Meanwhile, shopping malls also show high occupancy rates as they are popular for local and international brands.
    “Bangkok’s total retail area has quickly risen within the past quarter through the addition of many new office buildings,” says Surachat. Office buildings have added retail space for tour and travel services, convenience stores and dessert cafes.

    Average rental rates of all locations in Bangkok in the first half of the year have risen by 5 to 10 per cent. Large shopping malls have the highest rents, says Colliers.

    Rental space in Bangkok’s city area can add up to more than THB3000 (US$88) a sqm per month, especially in central malls with direct access to BTS stations. Meanwhile, monthly rents in community malls beyond the main roads start at around THB800 a sqm.

    Despite the increasing average rental rate, Bangkok’s suburban community malls are not likely to raise their rents in the next two quarters because of their decreasing popularity, says Colliers.

  • Hong Kong retail expansion ahead

    Hong Kong retail expansion ahead

    Many Hong Kong retailers plan to open more stores next year, a new JLL survey shows.

    The realty consultancy firm found that 62 per cent of overseas and local retailers in its survey plan new stores despite predicting a recovery in retail rents in core shopping precincts like Causeway Bay, Central and Tsim Sha Tsui.

    Rates have plummeted more than 40 per cent from the market peak in 2014, says the survey, but half of the 50 retailers surveyed last month believe Hong Kong’s retail market will bottom out and recover next year.

    While all respondents believe high-street rentals are overvalued, there is an equal balance between retailers who prefer to open a store in a shopping mall and those who favour a street-level outlet.

    “Hong Kong’s retail market is still challenging, but the mood among retailers has changed from pessimistic last year to believing the worst is over and there are now opportunities,” says JLL Asia Pacific director James Assersohn.

    He says the city’s prominence in the global map of retail and luxury goods has not been diminished amid a strong domestic consumer market and its exposure to the Mainland Chinese market.

    More tourists

    Statistics from the Hong Kong Tourism Board offer more reasons for optimism: total tourist arrivals in the first five months this year rebounded 3.2 per cent year-on-year to 23.6 million. Moreover, visits by overnight tourists, who spend double on shopping than same-day tourists, rose 5.7 per cent to 11 million.

    “Tourist numbers are bouncing back. Hong Kong’s rentals have come down and still need a small amount of correction to create an equilibrium. However, business is booming for many retailers and the reduced rentals have left a great opportunity to obtain prime retail space,” says Assersohn.

    “Retailers are seeing this as a great time to take advantage of the market conditions and acquire more space.”

    Meanwhile, Hong Kong is lagging in online shopping. Of the surveyed retailers, 22 per cent believe consumers still prefer brick-and-mortar shops, though almost all key retailers and chains have been running online platforms for sales and promotion for years.

    “Hongkongers believe it’s still more convenient and more enjoyable to just pop into a mall,”  Assersohn said.

    Malls are transforming into community hubs by offering more entertainment and improving dining options, he says.

    JLL Hong Kong head of retail Terence Chan says landlords are now willing to offer flexible leasing terms to the retailers with a good brand image.

    Also, the rental correction allows more retailers to enter the market and for landlords to diversify their tenant mix. “It has also helped many retailers to open crossover stores to create a new shopping experience.”

  • RIP high street retailers, faced by the relentless onslaught of mobile

    RIP high street retailers, faced by the relentless onslaught of mobile

    I overheard a young Hongkonger say recently, “I rarely buy anything at shops anymore. I only shop online.” It is not hard to notice the profound effect that e-commerce has had around the world and especially in an emerging and fast-growing market like China.

    But this phenomenon has yet to fully hit Hong Kong’s major luxury malls and department stores that are crammed with overpriced purses and overwrought window displays.

    Despite a restructuring of Hong Kong retail outlets by major luxury brands, the city still hosts more flagship stores than any other place. The lucrative wave of mainland shoppers has long receded and on any given day the luxury stores in Landmark and Pacific Place and other high-profile malls appear awfully sleepy.

    The fate of Hong Kong’s luxury malls against the online shopping onslaught has not yet unfolded.

    I don’t expect them to become ghost towns, but even they cannot avoid downward trends.

    But they are like the fixed fortifications on Frances’s doomed Maginot Line that were bypassed by the German army on the second world war – intimidating and monolithic, but easily made irrelevant by technological disintermediation.

    E-commerce has radically changed shopping habits in the US. Hudson’s Bay department store posted a US$152 million quarterly loss. Ralph Lauren is closing its fabulous and iconic Fifth Avenue flagship store. What is occurring goes beyond an economic cycle, but rather it represents technology enabling generational change. Millennials are conducting their entire lifestyle on smartphones.

    Will Hong Kong’s malls become obsolete or changed so much they will not mean the same thing.

    Sites like deadmalls.com chronicle the slow, but sure death and irreversible evolution of shopping malls in the US.

    Although not all of them are dying, certain segments in urban and suburban areas are empty, hastened by the rise of online. Changing consumer habits and online shopping is decimating the mall as a central retailing concept or necessary gathering place for the community.

    JD.com’s recent acquisition of a US$397 million stake in Farfetch, the London-based luxury fashion and boutique e-commerce service provider, marks a major milestone in the development of luxury retailing. The company, which reported gross sales of US$800 million last year, runs nine local language e-commerce sites, which include the mainland, South Korea and Japan.

    The two companies described their strategic partnership as a means to dominate market share in the estimated US$80 billion market in domestic and travel-related purchases of luxury goods by mainland consumers.

    “We’re just scratching the surface of China’s US$80 billion luxury market,” said Jose Neves, Farfetch’s CEO and founder after the announcement.

    “In China, there’s a huge movement from offline to online [shopping] and there are millions of new millennial luxury shoppers who live their lives digitally.”

    I met its Portuguese founder Jose Neves in 2012 after he raised US$23 million from venture capitalists. Four years into its start-up he expected to close the year with over US$100 million annual sales growth rate of 204 per cent and 56,000 customers in over 100 countries. Today, its online marketplace sells to about 1 million customers in more than 190 countries and territories.

    Farfetch demonstrates the irreversible momentum of change that is possible in shopping habits when shoppers are technologically enabled.

    Furthermore, disintermediation – the reduction in the use of intermediaries between producers and consumers – is an almost imperceptible event when it takes hold.
    What looks like an insignificant catalyst is like observing a distant car in your car’s rear-view mirror. Suddenly, it sling shots past you at great speed and is never seen again as it no longer competes directly with you. Rather it has redefined and recreated a new industry.

    Hong Kong retailers and shoppers have been slow to adopt e-commerce. During internet 1.0, department store owner tycoons woefully misinterpreted the idea by spawning “Dickson CyberExpress”, a misguided attempt to cross a website with a physical mall.

    It only showed how our retail tycoons cannot visualise retailing beyond renting floor space, seeking profits per square foot and abusing “cyber” and “e”.

    By waiting for the trend to materialise and prove itself rather than adapting, leading and innovating Hong Kong mall owners only ensure their extinction.

    The best malls will probably survive as every major city has a high street, but tenant mix and rent levels may not remain the same. But then again, if technology has taught us anything, it is that you still have to worry about some obscure person toiling away in a garage or flat somewhere, inventing the new killer platform.
  • Hong Kong retailers fail to harness the power of data to improve customer engagement

    Hong Kong retailers fail to harness the power of data to improve customer engagement

    Brands are caught in a vicious cycle when it comes to building a relationship with their customers. According to a recent study conducted by global loyalty marketing agency ICLP, a majority of Hong Kong consumers do not expect to get anything in return for sharing their personal details with only 9% reporting that their shopping, payment and delivery preferences are recalled and used by retailers.

    “The reason for this is either because retailers might not be able to collect enough personal data or they don’t harness the data they have to improve customer engagement. Collecting data is one thing, but drawing insights to create a meaningful dialogue with customers is critical to trigger action,” comments Mary English, Executive Vice President-APAC at ICLP.

    Brands fail to harness the power of data

    Customers currently do not believe that retailers will deliver much when it comes to personalisation, whether it is providing product recommendations or remembering their favourite way to pay, according to the ICLP study.

    · Only 9% of Hong Kong shoppers say that brands remember their shopping, payment and delivery preferences

    · Only 9% say that brands remember their past purchase

    · Just 10% are given personalised shopping recommendations

    · Only 10% are given offers relevant to them

    · As few as 12% find that retailers remember their birthday (perhaps the most basic level of customer recognition)

    The study revealed that 88% of Hong Kong shoppers say that they do not think that they will get anything in return for sharing their personal details with retailers – this is the highest percentage of the Asia-Pacific markets surveyed compared with 78% of shoppers in Singapore and 67% in China. The conclusion, based on this feedback, is Hong Kong consumers lack passion and excitement for receiving a brand’s information. The risk for a brand is that these consumers will ignore its communications, considering them irrelevant, and seek excitement elsewhere. Without that passion and the personalised dialogue, there is limited opportunity for the brand to improve its relationship with its customers or to surprise and delight them, and thus inspire them to shop more often or make impulse purchases.

    To create an intimate relationship with customers, brands have to make sure they capture data across all channels. The data collected should not be limited to personal details, but also include social activities, and payment and delivery preferences. Customers realise the importance of their personal information and expect to benefit from providing it. Brands should therefore respect the data consumers provide, and reward them for sharing their information by offering discounts, offers or other rewards, and use the data collected in an effective way that actually delivers real benefits to the customer.

    Mary commented: “These findings reveal that Hong Kong customers don’t expect much from retailers by sharing their personal details. These particularly notable figures compared to the APAC territories and countries surveyed are certainly an action signal for brands to review their customer engagement strategy. Retailers need to respect the customers’ personal data by providing relevant, real-time experiences based on their shopping behaviour and incorporate elements of surprise and delight to drive customer devotion.

    Brands should have a cohesive engagement strategy with data architecture for a single view of their customer to continually gather insights to strengthen their relationship with their customers. Harnessing personal, transactional and social data gathered at point of sale and from social platforms enables brands to understand customers’ shopping, payment and delivery preferences. With these data analytics, brands are then able to provide personalised experiences, build emotional connections with their customers as well as identify demand trends for use in product development.

    In order to build stronger relationships with customers, brands need to be smarter in the way that they use and reward personal data. A devoted relationship requires intimacy, passion and commitment according to Sternberg’s Triangular Theory of Love. Delivering unique and tailored experiences helps build both passion, by delivering something customers will really value, and intimacy, by communicating when they expect it and through their choice of channel.”

  • Malaysian retailers urged to go digital

    Malaysian retailers urged to go digital

    The Malaysia Retail Chain Association (MRCA) wants to drive the retail industry to go into the online arena, in line with the government’s aspirations, for better opportunities and to compete better.

    President Datuk Garry Chua said online adoption among Malaysian retailers is still relatively low, but the initiative to start thinking and adopting digital strategies is there. He said members are putting their products for sale online and gauging feedback from online channels.

    “Some of our members have started adopting online initiatives but it takes time to pick up. But it’s a good start. Since the government is bringing in Alibaba, we have to rely on that wave to benefit the retailers and SMEs to the maximum,” he told reporters after opening the MRCA Retail Conference 2017 yesterday.

    He said online sales contribution is growing, but on a gradual mode.

    “This depends on the Digital Free Trade Zone (DFTZ). If it kicks off faster, the process (online sales) will be faster. We’re looking at the next three years (for a pick-up in online sales). Definitely a double-digit growth for online after this,” said Chua.

    Despite the growing importance of e-commerce, he said brick-and-mortar stores will not totally lose its presence.

    “You have to fine tune the balancing game. Countries like the US, Singapore and Malaysia always have a supply of malls, so some have to be wiped out. It’s like a rationalisation process. You can’t have too many, so there’s a balancing of online and offline,” he said.

    He reiterated MRCA’s expectation of a 4.5% growth in retail sales this year, driven by tourism.

    Themed “Retail Innovation: The Future is Now”, the MRCA Retail Conference 2017 discussed shifting retail landscapes, disruptive technology, digital economy, DFTZ and understanding Gen Y, in line with the government’s aspirations of spurring Malaysia’s economic growth by providing cross-border e-trade facilities for SMEs.

    The conference was officiated by International Trade and Industry Minister Datuk Seri Mustapa Mohamed.

    In his speech, Mustapa said the government launched the Productivity Blueprint a couple of months ago and has set up three groups of Productivity Nexus, in which one is a Productivity Nexus for retail and food & beverage (F&B) to be led by the private sector. The Nexus also comprises of organisations such as MRCA, Bumiputra Retail Organisation, Malaysia Franchise Association among others, in partnership with the government.

    “We recognise the importance of the retail and F&B sectors, which employ no less than 2.5 billion people and contribute 8.3% to GDP. Having said that, labour productivity in many of the sectors in the country is one of the lowest, therefore we formed the Productivity Nexus, which is about sharing of best practices,” Mustapa said.

    He added that innovation is important for retailers to move with the times and to be ahead of the curve, with digital being the way forward.

    The MRCA Retail Conference 2017 was held in conjunction with MRCA’s Malaysia International Retail Franchise & Licensing Fair 2017, which starts today.

  • Japan retailers’ profit growth slows to 0.6% in March-May

    Japan retailers’ profit growth slows to 0.6% in March-May

    Japan’s retail sector has seen earnings growth slow notably from a year earlier in the March-May quarter due to lackluster increases in sales combined with greater labor and other costs.

    The aggregate pretax profit of 61 retailers that announced their March-May results by Tuesday increased 0.6% on the year, according to a compilation. The figure, which translates to a nearly 3 percentage point drop from a year earlier, was the smallest over the past two years. About 40%, or 26 companies, booked profit increases.

    Are winners losing their grip?

    Convenience stores, which had been the winners in retail, are perhaps at a turning point. FamilyMart Uny Holdings, which was created through the merger between UNY Group Holdings and FamilyMart last September, said Tuesday its operating profit was 12.5 billion yen ($109 million), down 31% from the combined profits of its two predecessors a year before. Renovation costs were a major factor behind the profit drop, as the company turned some 750 Circle K and Sunkus convenience stores into FamilyMarts in the quarter.

    Lawson’s pretax profit declined even with a sales increase, partly due to the costs it shoulders for its store operators for the disposal of unsold packaged meals.

    Industry leader Seven-Eleven Japan was the only one among the top three players that booked profit growth. Its operating profit climbed 2% to 59.5 billion yen.

    Meanwhile, even within the same Seven & i Holdings group, general merchandise store operator Ito-Yokado struggled, with its existing-store sales shrinking 3.2%.

    “We will reform food operations by setting up a dedicated team,” said Yuji Kaneko, an executive officer of Seven & i.

    Aeon Retail, a general merchandise unit of Aeon group, sustained an operating loss for the quarter despite slashing advertising and other costs. The company cut prices of as many as 254 food and household items in April. President Soichi Okazaki says “sales would have slid even deeper were it not for the price cuts.” To spur sales, the company plans to lower prices again as early as August.

  • Bad news for Japan’s retailers as Chinese tourists cut back on buying

    Bad news for Japan’s retailers as Chinese tourists cut back on buying

    They’re still coming in droves — but no longer buying in spades. After propping up sales for overseas retailers over the past decade with a shopping-driven tourism agenda, Chinese visitors are no longer returning home with suitcases bulging like before.

    A new survey by consultancy Oliver Wyman shows Chinese tourist numbers and holiday expenditure continuing to rise last year, even as shopping during overseas travel dropped 17 percent from a year earlier.

    The average Chinese tourist spent about 6,705 yuan ($986) on shopping when traveling, down from 8,050 yuan in 2015. But overall holiday spending — including on hotels and sightseeing — rose 3.5 percent to 20,317 yuan from 19,635 yuan, according to the survey of 2,000 travelers from the mainland.

    The sea change in spending habits is dealing a blow to retailers from Parisian department stores to Japanese duty-free operators and Hong Kong jewelers, but bigger numbers of wealthier Chinese may create other opportunities for leisure and entertainment operators in popular overseas destinations.

    “Businesses globally have to adjust their strategy to think about how to capture the new Chinese tourist dollar,” said Oliver Wyman’s Shanghai-based partner, Hunter Williams. “It’s less about the outlet mall now and more about the national park.”

    One reason for the change is the easier access to foreign goods in mainland China due to a booming $60 billion cross-border e-commerce market.

    Imported items can now be ordered online and delivered in as quickly as a day, often exempt from taxes levied on goods from store shelves.

    That’s damped the practice of buying overseas for the purpose of reselling locally, and the survey showed such resales falling to 3 percent of shopping expenditures from 8 percent in 2015.

    Chinese outbound spending still ranks highest in the world. In 2016, travelers from the country spent $261 billion, a fifth of the global total, up from $249.8 billion in 2015, according to the World Tourism Organization.

    But the portion contributed by shopping has fallen to 33 percent of overall travel expenditure, from 41 percent in 2015, the Oliver Wyman survey showed.

    Chinese consumers no longer need to travel overseas to stock up on items from Playtex bras to Christian Dior lipsticks and Blue Nile diamond rings, which are now available on online portals run by firms like Alibaba Group Holding Ltd. and JD.com Inc. With foreign brands increasingly using the internet to reach Chinese buyers, foot traffic to malls and outlet stores in popular overseas destinations is slumping.

    Duty-free retailer Laox Co. reported a 33 percent fall in revenue for 2016 as Chinese tourists spent less, while U.S retailer Macy’s Inc. is shutting 14 percent of its stores to stem sales declines.

    Luxury houses like LVMH Moet Hennessy Louis Vuitton SE and Cie Financiere Richemont SA and brewer Kirin Holdings Co. have pointed to sales pressures from fewer Chinese shoppers visiting stores globally, said Bloomberg Intelligence retail analyst Catherine Lim.

    The survey also showed that more Chinese tourists are traveling with children and spouses rather than going alone or with friends. That could benefit destinations that offer unique leisure experiences or entertainment options, said Oliver Wyman’s Williams.

    “The number of Chinese tourists is still rising rapidly and at quicker pace than their overall spending,” he said. “This should give industry players some pause to think about how to make up for the loss of shopping-related spending through volume.”

  • Japan’s retail sales growth slows in May, June looks more positive

    Japan’s retail sales growth slows in May, June looks more positive

    Retail sales in Japan lifted 2% for the month of May, as shopping revenue growth slowed in the archipelago nation, compared to April’s increase of 3.2%.

    The May result came in below a median forecast of 2.6% compiled by Reuters.

    The biggest contributors to the rise were sales of motor vehicles, followed by fuel, medicine and toiletries, according to the Economy Ministry.

    Offsetting the gains, sales at supermarkets and department stores dipped 0.6% in May, after growing for the first time in nine months in April at a pace of 1.1%

    Month-on-month, sales fell 1.6% from April, when they rose 1.4% on March.

    However, June looks to be more positive on the retail front for major apparel and accessories players.

    A report by WWD said big-name fashion retailers in Japan recorded a positive sales month in June, on the back of early clearance sales and an increase in shopping tourists to the nation.

    Fast Retailing said Tuesday that same-store sales at its Uniqlo stores in Japan were up 4.1% on the year last month, while Isetan Mitsukoshi Holdings, the country’s largest department store operator, said same-store sales among its Tokyo metropolitan area gained 1.1% year-over-year in June.

    After releasing a soaring first-quarter profit result last week, Takashimaya said June sales at its 17 department stores in Japan grew 4.6% compared with the same month last year, while H2O Retailing Corp, which operates the Hankyu and Hanshin chains of department stores, said sales at those stores were up 4.6% on the year last month.

    Finally, the 18 Daimaru and Matsuzakaya department stores in Japan, operated by J. Front Retailing, posted a 4.8% sales rise on the year in June.

  • Australia’s retail sales lift more-than-expected in May

    Australia’s retail sales lift more-than-expected in May

    Australian retail sales increased 0.6 per cent, on seasonally adjusted basis, surpassing expert expectations of just a 0.2 per cent gain, according to data released this week.

    While the May results were down on the 1 per cent growth recorded in April, economists were pleased with the May increase, saying it signaled a solid second quarter for Australia after a poor start to year. Year-on-year, sales increased 3.2 per cent.

    With the majority of categories strengthening, department stores continued to have problems with turnover falling 0.7 per cent.

    Clothing, footwear and personal accessories rebounded from a recent weakness, largely held up by the demand for personal accessories and shoes, as apparel sales fell.

    Supermarket sales rose 0.5 per cent, while liquor sales dwindled, down 2.1 per cent.

    Finally, there were strong gains in electronic goods, furnishings and garden supplies.

    By state, shoppers in New South Wales and Victoria were the biggest spenders, while retail sales in Queensland fell for the sixth time out the last seven months.

    Analysts said the much stronger-than-expected rise in retail sales in May, coupled with the leap in sales over April, suggests Australia’s consumption growth surged in the second quarter. However, it may not be sustained.

    “With consumer confidence continuing to trend downwards, households’ incomes facing an additional squeeze from rising energy bills and household indebtedness at a record high we expect that real consumption growth will slow from around 2.6 per cent year-on-year in the second quarter to 2.0 per cent by the end of the year,” Capital Economics analyst, Kate Hickie, told The Australian.

  • e-retail brands out of the social media loop in SE Asia

    e-retail brands out of the social media loop in SE Asia

    Over 85% of consumers in Singapore, Malaysia and Indonesia, who mention e-retailer brand names in their social media posts don’t tag brand handles, according to Digimind.

    This means brands need to be vigilant in monitoring their brand reputation in the wider social media space to ensure they aren’t missing out on key conversations and trends, and are able to act upon any customer service concerns quickly.

    With the rise of empowered consumers and an increasing adoption of online shopping, e-retailers need to adopt customer-centric strategies in order to thrive. With so much of our daily conversations happening online, data from social media can provide key insights for e-retailers wishing to optimize customer experiences.

    Digimind’s study, Social Shopping in 2017, assessed the state of the e-retail industry in the three countries by monitoring 15 local and regional e-retailers, including Lazada, Zalora, and Berrybenka.

    “It’s no secret that brands who implement customer-centric strategies are excelling. With 2.8 billion active social media users in Southeast Asia, it is crucial for e-retailers to listen to what is being said about their brand, competitors and the industry online,” said Stephen Dale, general manager of APAC at Digimind.

    “Understanding what consumers are saying on social media can provide companies with an arsenal of insights that can be used to develop content strategies, improve customer service, build brand advocacy, and increase sales,” said Dale.

    He added that when analyzed in conjunction with other data such as web page visits and browsing behavior, this can further inform marketing plans and Voice of the Customer programs.

    The study also revealed that while the majority of e-retailer’s followers in the countries studied were on Facebook, consumers were most actively publicly posting their opinions and experiences on e-retailers on Instagram and Twitter.

    This means while Facebook is the ideal channel for brands to communicate with followers, Instagram and Twitter are key channels for community engagement.