Tag: retailing

  • Indian mall space to grow by 65 million sqft by 2022

    Indian mall space to grow by 65 million sqft by 2022

    India will take on more than 65 million sqft of new mall space by the end of 2022, according to a new report from real estate services firm Anarock.

    The report shows the region’s top seven cities will account for 72 percent of the new mall space, while tier 2 and tier 3 cities will see 18.2 million sqft of new supply. Nearly two-thirds of the planned space (40 million sqft) will hit the market by next year.

    “This new supply is also driven by the increasing interest of institutional investors – including private-equity players – who invested almost US$1.9 billion into Indian retail between 2015 and the first quarter of this year,” said Anarock Retail MD & CEO Anuj Kejriwal. “In fact, more than 60 percent of this investment was infused in the last two years alone, making these the best years for the Indian mall sector in recent times.

    Notwithstanding the decline in deal activity in the second half of last year following the liquidity crisis, the retail segment attracted investments of almost $115 million in just the first quarter of this year.”

    The report also maintains that real estate investment trusts (REITs) can be a viable tool for mall developers to raise funds, but this fund-raising instrument still needs to mature sufficiently. Also, the retail REIT structure and performance may not be directly comparable with the commercial office sector.

    The report also showed the Indian retail industry has moved from long-term leasing to short-term leasing tenures (three to five years) to enable constant updating of the brand mix within the mall. Globally, the standard lease term is still above five years.

  • Global Brands Group posts another loss

    Global Brands Group posts another loss

    Trimmed-down Global Brands Group has reported another loss but says its restructuring is on track to be completed next year.

    “Global Brands has entered into a new chapter as a nimble and more focused organization,” said CEO Rick Darling. “The changes we are implementing have put Global Brands in a strong position. We are already beginning to see the benefits, with the results in the second half of the fiscal year significantly improved from the first half.”

    For the year to March 31, revenue from continuing operations fell by 4.6 percent year on year,  which the company said was primarily due to eliminating unprofitable businesses. While net loss of the continuing operations increased to US$250 million, net loss attributable to shareholders improved by 55.7 percent to $400 million.

    However, as we reported in November, sales fell by 4.1 percent in the first half year to $699 million, largely due to lower revenue in Mainland China and the disposal of the homewares business. That figure excluded any impact from the $1.2 billion sale of the North American business which led to an extraordinary dividend of around $305 million in cash and scrip last April, as well as reducing debt.

    Since the restructure, Global Brands Group is now concentrated on core businesses of men’s and women’s fashion apparel, footwear and brand management.

    Darling said the company remains focused on flattening its structure and building a more responsive organization.

    “We are now making significant strides towards achieving our target of reducing $100 million in operating expenses and are well on our way to exceeding this initial target. Our goal is to complete the restructuring program by the end of the 2020 fiscal year.”

    The program involves a number of initiatives, including simplifying processes from design to product development to sourcing, and moving those functions offshore, “closer to the needlepoint, where production is located”.

  • Black forecast for Hong Kong retail sales

    Black forecast for Hong Kong retail sales

    Hong Kong retail sales will shrink by 5 per cent this year according to projections by PWC.

    Citing uncertainty clouding consumer markets across Mainland China and Hong Kong, PWC also says macroeconomic uncertainty has prompted Chinese retailers to refocus on customer experience.

    “Hong Kong retail sales is estimated to fall by 5 per cent to approximately HK$460 billion this year, as the ongoing Sino-US trade dispute, equity market turbulence and volatility of Renminbi continue to cast a long shadow on consumers sentiment and actual spending”, says Michael Cheng, PWC’s Asia Pacific and Hong Kong/China consumer markets leader.

    PWC had earlier forecast a 3-per-cent decline in Hong Kong retail sales and says its downgrade reflects a weaker outlook for the second half of the year, due to a combination of factors including external headwinds, economic instability, as well as the projected decrease in tourist arrivals and spending.

    The projections are included in the consultancy’s report Back to the Core: Reinvigorate Experience-driven Retail at a Time of Uncertainty.

    Government data shows Hong Kong retail sales for the first four months of this year fell by 2 per cent, with electrical and luxury goods among the sectors suffering the biggest decline, against the backdrop of a weak Renminbi and waning consumer confidence. On the back of the completion of major infrastructures such as the Hong Kong–Zhuhai–Macau Bridge and the Guangzhou–Shenzhen–Hong Kong Express Rail Link, mainland tourist arrivals grew steadily in the last quarter of last year, reaching a record high in January, aided by the Chinese New Year holiday-shopping season. However, mainland tourist arrivals started to drop from the peak three months in a row since February.

    “Local retail sales and mainland tourist arrivals are expected to continue on a downward trend through the rest of this year, indicating a slowing consumer market in Hong Kong,” says Cheng.

    “Electrical and luxury goods are set to shrink further, while consumer goods like health-and-beauty products will hold well with a modest growth. The recent political and social unrest, temporary closure of the Peak Tram due to renovations, coupled with a lack of new tourist attractions might lower mainland tourists’ appetite to visit Hong Kong in the short term. Meanwhile, a weakening economy as well as uncertainty surrounding the trade dispute present risks to the outlook in the medium to longer run,” he says.

    Adapt or suffer

    Cheng says this year’s tough Hong Kong retail climate underlines the importance for retailers to adapt to changing consumer preferences and spending patterns in order to maintain competitiveness and profitability.

    “As shoppers nowadays have put a bigger focus on consumer experience, more and more retailers are moving to create a more engaging and experience-driven shopping journey with innovative and unconventional retail strategies such as ‘retailtainment’ and ‘coopetition’. Moreover, brands are increasingly tapping the power of emerging technologies like AR and VR to appeal to a new generation of tech-savvy shoppers who value personalised experience.”

    The report, which builds on the survey findings of PWC’s Global Consumer Insights Survey 2019, also points to an increasing emphasis on customer experience among retailers in China, who are refocusing on business fundamentals such as profitability and cost management in the light of growing economic headwinds.

    He says this year continues to be challenging for mainland Chinese retailers amid uncertain outcome of trade negotiations with the US and a slowdown in the economy. Mainland retail sales growth fell to a 15-year low at 9 per cent last year, signalling sluggish demand among Chinese consumers. As part of its wider efforts to transition towards a consumption-driven economy, the Chinese government has rolled out a range of stimulus policies including tax cuts, reduction in social insurance costs and incentives for high-tech consumption, with a view to building a more resilient domestic economy to mitigate external risks.

    “In the face of a slowing economy and consumer market, retailers are going back to basics by pursuing a more defensive strategy, characterised by profitability focus, consumer-centricity and operational excellence,” says Phil Lai, PWC China consulting partner. “The story of New Retail continues, as retailers strengthen digitisation along the retail value chain through smart supply chain management enabled by technology and big data, with a laser focus on experience.”

    Thanks to extensive mobile connectivity and established technology infrastructure, digital-savvy Chinese consumers tend to accept and embrace emerging technologies to a greater extent than their global counterparts. Sixty-eight per cent of Chinese consumers surveyed purchase products online at least once a week.

    Technology enablement consequently fuels the hunt for new experiences that integrate digital into the offline environment. Close to 40 per cent of Chinese respondents said their in-store experience would be enhanced by the use of technology including IoT scanners, tablet and mobile checkout, and self-service kiosks.

    As Chinese shoppers seek to redefine their experience with a frictionless purchase journey and a blend of both physical and digital interactions, retailers are thinking beyond the traditional return on investment (ROI) metrics to adopt a consumer-centred return on experience (ROX) strategy.

    “Specifically, retailers need to map out their consumers’ purchase journey, isolate key customer touch points and factors that drive experiential moments, and invest more in aspects which directly impact those interactions and yield measurable results,” said the report.

    Lai concludes: “From end-to-end digitisation to the rise of experience-based business models, the New Retail evolution in China has come a long way. To thrive in the world’s largest consumer market, we see retailers and brands becoming more digitally-agile and data-driven, using new technologies to fuse customer experience across the entire value chain, while monetising discrete moments and building communities with a purpose to ensure long term profitability and sustainability.”
  • Tokopedia enters wedding industry, buying Bridestory

    Tokopedia enters wedding industry, buying Bridestory

    Indonesian e-commerce platform Tokopedia has acquired local wedding-service marketplace Bridestory, which allows users to plan their big day on their smartphones.

    Bridestory targets the Southeast Asian wedding market, connecting couples with venues, organizers and vendors/service providers in the wedding industry. It has reportedly connected more than 3.5 million customers with at least 27,000 wedding vendors annually.

    “It all started with a web application,” said Bridestory CEO Kevin Mintaraga, “then we slowly saw the change in behavior as people became more mobile-centric. We also wanted to help brides to plan their wedding anywhere and anytime with their smartphone”.

    The Tokopedia acquisition includes Bridestory’s new service, Parent story, which help parents and expecting parents connect with age-specific activity providers for their kids.

    Tokopedia has stated that the site will continue to operate independently, while Kevin Mintaraga will join Tokopedia’s management in a VP role.

  • Alibaba management shakeup not Ended yet

    Alibaba management shakeup not Ended yet

    The most significant Alibaba management shakeup since founder Jack Ma revealed he would step aside next September 10 sees high-profile CFO Maggie Wu take on a new role.

    Wu will take over responsibility for strategic investments by the group, charged with finding new growth streams for the technology and retail giant as its growth in the e-commerce sector begins to slow. She will oversee a team focused on investment, taking over that responsibility from executive vice-chairman Joe Tsai.

    The Alibaba management changes were revealed via the company’s official WeChat account by CEO Daniel Zhang.

    “To guarantee innovation, invest in our future, Alibaba is undertaking an organisational upgrade,” he said.

    Wu has been Alibaba’s CFO for six years.

    In other changes, Alibaba said its supermarket chain Freshippo – also known as Hema and now numbering 160 stores – will become a standalone business. DingTalk, the group’s enterprise software business unit, will be merged into the Alibaba Cloud business unit.

    These changes come ahead of a planned IPO in Hong Kong later this year which could raise as much as US$20 billion in fresh capital for expansion via investment.

  • The Great Singapore Sale renewed this year

    The Great Singapore Sale renewed this year

    The annual Great Singapore Sale is back this month, with the theme ‘GSS: Experience Singapore’.

    Taking place between June 21 and July 28, the sale will include Shopping Sprees such as ‘TGIF!’ (held every Friday) where retailers and food-and-beverage operators will run day-long specials and discounts.

    On July 7 (7.7), there will be an additional 7 percent off all goods – a marketing initiative based on retailers paying shoppers’ goods-and-services tax.

    Beyond the mega sales and discount programs, the event will boast a host of interactive activities and experiences at Orchard Road and Kampong Gelam.

    The first, the Orchard Road Fashion Scramble on June 21, will center around a fashion show curated by the Singapore Retailers Association and TAFF. Orchard Road will be transformed into a performing arena and an interactive runway for 300 dancers and models – showcasing an array of clothing designs and trends from local and foreign designers.

    The opening segment will feature designs by popular, up and coming local designers, followed by leading international fashion houses, before closing off with award-winning creations by Singapore students.

    The Great Singapore Street Pop Up will coincide with the Orchard Road Fashion Scramble, running from Ion Orchard to Mandarin Gallery, and at Robinsons The Heeren and the Grange Road carpark. The pop up will offer retail experiences and food for 10 days from the June 21-30.

  • Global personal luxury goods market growth endures

    Global personal luxury goods market growth endures

    Global personal luxury goods market growth has reached a “new normal” pattern, following back-to-back years of strong performance in 2017 and 2018, according to the luxury goods industry advisory service Bain & Company.

    Last year, 6 per cent global growth* led to €260 billion (US$292 billion) in sales, which is expected to balloon to €271–276 billion ($304.3–310 billion) this year, registering an expected 4-per-cent to 6-per-cent growth at constant exchange rates.

    According to Bain, the growth has been driven primarily by the acceleration in domestic spending of mainland Chinese consumers and an increase in European tourism, which, despite socio-political turmoil in countries like the UK and France, fuelled positive growth in the region through last year’s holiday season.

    Meanwhile a temporary weakening of consumer confidence in North America, as well as a decrease in traffic to malls and department stores, negatively impacted personal luxury spending during last year’s holidays stateside.

    The findings were part of the Bain Luxury Goods Worldwide Market Study, Spring 2019 presented this week in collaboration with Fondazione Altagamma, the Italian luxury goods manufacturers’ industry foundation.

    “This year looks to be on par with our new normal of growth in the market,” said Bain & Company partner and lead author of the study Claudia D’Arpizio. “China continues to dominate the luxury scene. Elsewhere we are continuing to see geopolitical uncertainty shape and reshape tourism spending patterns, with Chinese consumers choosing to spend domestically with more frequency. Overall we are seeing moderate growth in most markets.”

    The report showed that mainland Chinese consumers are demonstrating a strong preference for purchasing luxury goods at home thanks to price harmonisation, consumer-centered strategies, and governmental initiatives. Solid consumer confidence and willingness to buy, especially among young generations, are expected to drive year-over-year growth of 18–20 per cent* in the region.

    Japan remains an exclusive and attractive market for luxury brands, with forecasted growth of 2–4 percent* in 2019. Tourist spending is expected to rise ahead of the Tokyo Olympics in 2020, with Chinese consumers already confirming their interest in the area.

    Across the rest of Asia the outlook is positive, apart from Hong Kong and Macau, which continue to lose out to Mainland China. Bain & Company asserts that the luxury market in the region is set to grow by 10–12 percent*. An expanding middle class with increasing disposable income is fueling growth in Indonesia, Philippines and Vietnam, while sustained growth in South Korea is the result of local consumers and a mild rebound of tourism.

    The rest of the world is expected to be flat or see a slight decrease of 2 per cent*, with the Middle East remaining stagnant as domestic consumer spending begins to flow outside of the region.

    “We expect stable growth in 2019,” said D’Arpizio.  “But under the surface of this new normal, the future of luxury is taking shape with a number of key characteristics, including Chinese Generation Z, access, ownership, sustainability and social responsibility, the impact of digital across the entire value chain, preference for luxury experiences over products, and consumer networks as a new measure of value.”

  • AI-powered retail store We9go opens

    AI-powered retail store We9go opens

    Accrelist-owned AI retail store We9go has fully launched after an eight-month trial.

    The Geylang Road shop uses AI, facial recognition and radio frequency identification to track inventory, collect data on shopper preferences, facilitate payment processes and recognise product movements.

    When it soft launched last October it was open only to invited customers, so as to test and demonstrate its features.

    Accrelist says it will now focus on strengthening AI solutions and facial-verification services.

    “The company intends to move beyond smart retail-technology solutions,” said Terence Tea Yeok Kian, Accrelist’s executive chairman and MD.

    “We aim to offer a wider range of smart-and-secure cloud-based solutions as a systems integrator through its collaboration with technology companies to broaden the group’s revenue stream.”

    After its full launch, the 24/7 We9go store has an AI-powered robot that greets shoppers and assists them with product information and availability.

  • Waterstones parent to buy Barnes & Noble

    Waterstones parent to buy Barnes & Noble

    The parent of British bookseller Waterstones, Elliott Management, will purchase Barnes & Noble – the last remaining big-box bookseller left in the US following the departure of rival Borders – for about US$683 million.

    Once the deal is finalised in Q3 of this year, Waterstones CEO James Daunt will also assume control of all Barnes & Noble operations, although the two firms will remain independent.

    Dive Insight says: “The deal with Elliott could mark the closing of a turbulent chapter in Barnes & Noble’s story, one that included a failed merger, a legal battle with a former executive and agitation by activist investors. And prior to that there were years of management turnover, strategic misfires and lost sales as the last box book seller tried to hold off Amazon.”

    “As it happens, I know James Daunt fairly well,” said Barnes & Noble chairman Leonard Riggio in a letter to employees, “and I am delighted to have him as our new leader.

    “Like me, James believes our culture has to be more store-centric, which means more localisation of assortments and operations. It follows that he believes local managers must have more authority to get the job done.”

    A press release from Barnes & Noble read that Waterstones “has successfully restored itself to sales growth and sustainable profitability, based on a strategy of investment in their store estate and the empowerment of local bookselling teams.”

    Elliott, which has owned Waterstones for about a year, has US$825 million in debt financing available banks to fund the Barnes & Noble acquisition.

  • Topshop future in stretch as crucial vote delayed

    Topshop future in stretch as crucial vote delayed

    The future of fashion label Topshop is in limbo after a crucial vote on a Company Voluntary Arrangement for parent Arcadia Group was delayed last week.

    Arcadia’s chairman Sir Philip Green is trying to gather approval from creditors for a scheme which would see them convert debt to future equity and rents reduced on UK stores in return for sa further investment by Green’s family of £50 million (US$63.8 million). The scheme would also see 23 stores shuttered in the UK and the closure or sale of all 11 of Topshop’s US stores – on top of 25 UK store closures already planned.

    “Against a backdrop of challenging retail headwinds, changing consumer habits and ever-increasing online competition, we have seriously considered all possible strategic options to return the group to a stable financial platform,” Arcadia CEO Ian Grabiner said when unveiling the CVA last month.

    “This has been a tough but necessary decision for the business.”

    But a meeting of creditors – who include suppliers landlords and pension funds – was postponed last week when it became clear support would fall short of the 75 per cent required for it to be approved. That vote will now likely be held this week. However if it fails, creditors may call in administrators opening the possibility of a sale of Arcadia’s brands, which also include Miss Selfridge, Dorothy Perkins, Evans and Topman.

    UK retail industry sources say landlords are especially cynical to the CVA, casting doubts on whether Green can revive the troubled business in an era of dwindling high-street retail sales and growing e-commerce.

    One major retail landlord told The Business of Fashion that cutting rents to Arcadia to help its survival would be “quite a tough message to communicate to other tenants paying full rent”.

    Arcadia’s like-for-like sales reportedly fell 7.5 per cent in the year to August 2018, with total sales down 10.5 per cent to £1.7 billion. That decline was largely due to a 20 per cent slump in Topshop sales.

    The chances of Green’s plan did receive a boost last week after The Pensions Regulator and Pensions Protection Fund indicated their support. That followed a commitment by Sir Philip’s wife Lady Tina Green to invest a further £100 million in the fund to protect staff.

    Lady Green has also promised landlords who accept the deal a 20 per cent share of the proceeds should Arcadia be sold.

  • Amazon Fashion drops first influencer collection

    Amazon Fashion drops first influencer collection

    Amazon Fashion has just released the first collection from an influencer as part of its new shopping experience, The Drop.

    For the next 30 hours, customers will be able to purchase pieces made on-demand from the collection designed by influencer Paola Alberdi via the Amazon app or mobile browser. The Drop collections are available in more than 100 countries and regions.

    Fashionistas are encouraged to sign up for Amazon text alerts, as the next Drop influencer collaboration could be released at any time. Other influencers slated to design future collections include Emi Suzuki, Sierra Furtado, Leonie Hanne and Patricia Bright.

    “Influencers are able to turn their creativity and style into beautifully designed collections that capture the latest street style trends from around the world,” said a statement from Amazon.

    “Amazon Fashion is excited to enable influencers to be designers and bring fresh Fashion assortments directly to customers via The Drop.”

    Amazon Fashion is also offering Staples By The Drop, wardrobe staple pieces to complement the influencer collections.

    “I am beyond grateful to Amazon for entrusting me to be the first influencer to launch The Drop, their innovative new shopping experience. I have worked hard for many years to create a brand that is true to myself and did the same with this collection,” said Alberdi.

    “Fashion can be so expensive but my belief is that it should not have to be expensive to feel beautiful. The primary goal of my collection is simply to help women feel good about themselves. I’m so excited to share these pieces with the world!”

    Other retail brands have been tapping into the power of influencers and collaborating with them on collections for some time, such as Nordstrom, which is currently selling the Cupcakes and Cashmere range from fashion blogger and designer, Emily Schuman.

    When the department store engaged with influencer Arielle Charna in 2017, her collection reportedly brought in $1 million in sales in less than 24 hours, according to an article from Fashionista.

  • Versace to expand Asian store network

    Versace to expand Asian store network

    More stores, broader range, fewer brands as fashion icon tries to double sales. Versace will open its largest store yet in China this week, part of a concerted plan by the fashion label’s new owners to expand its footprint globally.

    Capri Holdings, which also owns Michael Kors and Jimmy Choo, bought Versace from Donatella Versace late last year for US$2.2 billion. It is now implementing a plan to double the label’s worldwide sales with at least 112 new stores scheduled by 2022 along with a refurbishment program for the existing network. The new Beijing store – details of which are scant at present – is a key step in that plan.

    Worldwide, Versace has 188 stores currently and wants to reach 300 within three years. Asia will be a big benefactor from the plan, already accounting for more than half the network. China alone has 40.

    Along with new openings and revamps of existing stores, Versace will boost its product offer, adding more handbags, footwear and leather goods to its high-end clothing range. Accessories currently account for just 35 per cent of Versace’s sales and the company wants to lift that to 60 per cent.

    “It’s very clear: The productivity in our stores is not what it should be,” CEO Jonathan Akeroyd told an investors briefing this week. He plans to double the sales per square foot across the network.

    “We need to rapidly increase productivity and this will really be the real driver to take us to our US$2 billion revenue target.”

    Versace’s marketing strategy will be revised, with less focus on fashion shows in favour of a stronger social media presence.

    The company has quietly dropped its diffusion brands Versace Collection and Versace Versus and new stores will all bear the core Versace brand name alone.

  • Kiehl’s pop up opens at Sha Tin, using AR to engage

    Kiehl’s pop up opens at Sha Tin, using AR to engage

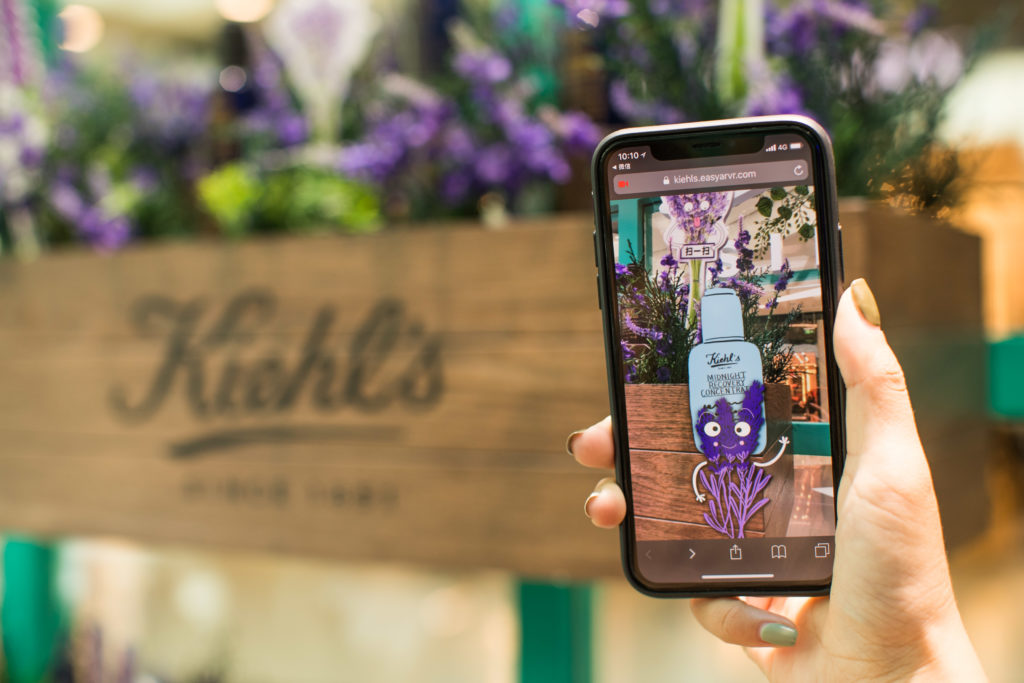
    A Kiehl’s pop up at Sha Tin features an AR gaming app to engage with shoppers.

    The beauty products retailer’s short-term store at the New Town Plaza in Sha Tin has been launched to promote Kiehl’s Calendula Serum-Infused Water Cream, and displays a giant 3D Calendula flower in the centre of the atrium that is only visible through visitors’ mobile phones.

    Visitors who upload images from the pop-up to their social media can redeem a special cosmetics product. Other product samples and a skin analysis are available for customers browsing the store.

    Kiehl’s has also designed an AR game that can be used at its regular stores after the pop-up closes, which will be playable until June 30. The game has collected 8000 registrations over the course of the campaign.

  • The space where purchasing decisions are made, Fitting Rooms

    The space where purchasing decisions are made, Fitting Rooms

    Why do customers walk into a fitting room when they are in a retail space? The answer is logical: because they have found a piece of clothing they like – and it should be considered a sure sign of purchase intent, even if the customer does not buy what they try.

    This small but mighty area of a retail store is actually the room where purchase decisions are made.

    Yet, far too many retailers still tend to overlook the importance of fitting room design. So here are some fresh ideas to help retailers boost sales through intelligent fitting-room design…

    How fitting rooms affect sales

    Let‘s start with some numbers and hard facts. First and foremost, the fitting room area is one of the most significant advantages brick-and-mortar retailers have over online retailers. Whereas online, one in five shoppers return their purchased items, in brick-and-mortar stores, fewer than one in 10 customers return purchases. Returns usually result in costs for any retailer – online or offline, so it is important for retailers to minimise the potential for returns. Here’s where an effective fitting-room design can play a part.

    Research shows that shoppers who use fitting rooms are seven times more likely to make a purchase than browsers who do not. Not only that, but if the customer has a good experience with a sales assistant in the fitting rooms, they can buy up to three times as many items in one transaction. Combine those figures and you can estimate that 70 per cent of all purchasing decisions in your store are made in the fitting room.

    Design can influence the buying decision

    Most retailers already recognise the importance of size, colour and lighting in fitting rooms. So let’s take a closer look at other design features.

    A fitting room represents the most intimate area of your store. This is a place where your customers take off their clothes, hoping to try on a new piece of clothing which makes them look and feel good. Here is where design can play a part in that feel-good factor – after all, it is not just about the clothes.

    Take one simple example: remember how uncomfortable you feel when you think you are over- or under-dressed for an occasion. Similarly, if a fitting room design fails to provide the shopper with a character and flare that matches the clothes, the customer can experience the same uncomfortable feeling. An uncomfortable environment can lead the customer to feel something ‘does not look right’. The result: the customer decides against making a purchase and the retailer loses a sale.

    How to create the perfect fit

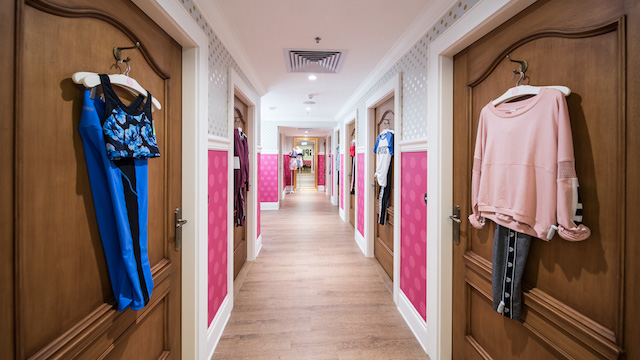
    We found some great examples of fitting rooms in Mainland China.

    INXX represents a forward-thinking, boundary-shattering exploration of how the genres of streetwear, sportswear and high-end fashion can be reconstructed, reinterpreted and recombined. Through this cool and futuristic fitting room design, the Chinese street-fashion brand not only encourages shoppers to try on their clothes but had also created an atmosphere which is towards their target market.

    With design concepts such as these, it is no surprise the brand has enjoyed continued success over the years. INXX was founded in Guangzhou in 2013 and in less than five years opened 54 stores in 17 Chinese cities. This is a brand we can all learn from.

    Lululemon is a Canadian brand that sells fashionable and high-quality yoga clothing and athleisure wear. One of the brand’s core values is mindfulness.

    Lululemon describes its mission as: “Our manifesto is one way we share our culture with the community. It’s an evolving collection of bold thoughts that allow for some real conversations to take place.”

    Lululemon cleverly uses the fitting room area as a platform to express some of these bold thoughts through its design. Positive affirmation statements frequently used in yoga are integrated in the fitting room design, illustrating how fitting-room spaces can also reflect fundamental brand values.

    So, when adopting slogans and other statements within the design of your fitting rooms, be sure to choose the “perfect fit” for your brand.

    Fitting rooms are a significant advantage for brick-and-mortar stores over online alternatives. Some brands which sell mainly online have begun to recognise this and are finding effective ways to deliver an offline customer experience.

    One of these brands is Jooos, which has combined offline and online experiences by providing the Top 100-selling fashion brands on Tmall with a retail space to showcase their products.

    The design of the fitting-room space here is interesting, because it is located in the centre of the store. Additionally, the exclusivity of the products is highlighted by a small staircase: customers literally have to walk upstairs to reach the fitting room, leaving them feeling “special” when they arrive there.

    Remember, in any fashion store, the fitting room marks the final barrier retailers need to draw a customer beyond in order to achieve a sale. So make that space count.

  • Hong Kong retail sales felt Last Month

    Hong Kong retail sales felt Last Month

    Hong Kong retail sales fell by 4.5 per cent in April, contributing to a 2 per cent decrease in year to date.

    Worse, the Census and Statistics Department said that after netting out the effect of price changes year on year, Hong Kong retail sales fell 5 per cent year on year, following a 0.8 per cent fall in March and contributing to a 2.3 per cent decline year to date.

    “The larger year-on-year decrease recorded in April reflected the still-cautious consumption sentiment amid external uncertainties, but was also partly due to the late arrival of the Labour Day holidays in the Mainland (which fell in early May this year but straddled between April and May last year), which has led to a notable deceleration in the growth rate of visitor arrivals,” a government spokesman said, commenting on the data.

    He said that in the near term, consumption sentiment will continue to be affected by various external uncertainties, though the sustained expansion in inbound tourism and the largely stable local labour market should provide support to retail sales business. In other words: it may be too soon to start panicking.

    Predictably, the jewellery, watches and luxury goods sector performed the worst, sales down 11.4 per cent in April. Apparel, the second greatest contributor to the figures, slipped by a more modest 2.2 per cent, with cosmetics down 6 per cent, department-store sales down 4.3 per cent and electrical goods by 13.7 per cent. Sales of footwear and accessories fell 5.4 per cent, furniture by 0.4 per cent; books, newspapers, stationery and gifts by 7.5 per cent; Chinese drugs and herbs by 5.7 per cent, and optical shops by 7.8 per cent.

    On the positive side, supermarket sales rose by 1.1 per cent; food, alcohol and tobacco by 0.8 per cent and fuels by 3.3 per cent.