Tag: Singapore

  • Reits: An attractive alternative form of property investment

    Reits: An attractive alternative form of property investment

    In just 14 years, the real estate investment trust (Reit) industry in Singapore has drastically transformed the country’s investment property landscape, making it one of the most admired in the Asia Pacific.

    The Singapore Reit industry now ranks third in size in the region, behind Japan and Australia. S-Reits have been actively contributing to the improvement of properties in Singapore, practically in all sectors of the rental market: retail, office, and industrial.

    As landlords, Reits are committed to maintaining and improving their properties and have consistently demonstrated this commitment by investing in extensive asset enhancement initiatives to refurbish and upgrade older properties in their portfolios, including introducing eco- technology into their properties.

    Such improvements have led to improved offerings for tenants and raised the quality of real estate in Singapore as a whole.

    The motive for Reits to continually upgrade their investment assets is driven by commercial interest doubtlessly, to generate return on investment for unitholders.

    But the resultant benefit is not confined to Reits, or else the progress could not be sustained.

    The other three key players in the game are tenants, consumers, and the Singapore economy at large.

    Unfortunately, this aspect of the impact of Reits has tended to be overlooked; instead, fingers have been pointed at Reits as the culprit causing the plight of tenants, especially the smaller enterprises, who bow out of the business citing rising high rent as a key reason.

    This has in fact caused the resurgence of the classic landlord/ peasant conflict.

    There will continue to be murmurings, especially from the quarter that has been ousted from their comfortable rented nests of many years until rentals made it untenable for them to continue with their business.

    Their lamentation is that Reits which appear to have taken over “most” of the rental properties in the country, have been regularly raising rental rates to maximise their yields and keep up with their distribution per unit (DPU) growth.

    Look at the big picture

    To be objective, one needs to look at the big picture.

    Many rental buildings here (both office and retail) have remained in the same state for 20-30 years and maybe even longer.

    Fortunately, many of the tired-looking buildings have also been rejuvenated and given a new lease of life after they were acquired by Reits.

    Someone once told me Singapore needs Reits to transform the investment property market the way the Urban Redevelopment Authority (URA) did the Singapore landscape over the last few decades; the difference is that Reits will have to do it on a fully commercial basis.

    The benefits of developing the Reit industry to the economy is perhaps more obvious in that it enables developers to recycle their capital for other investments, creates specialist professional jobs, generates high-value supporting services, etc.

    The best evidence of this are the aggressive measures many of our neighbours are taking to develop their own Reit industry.

    S-Reits are here to stay. S-Reits are celebrating their 14th anniversary since the first Reit, CMT, was listed in Singapore in 2002. Today, Singapore has succeeded in having 38 Reits listed on our stock exchange, with a total market capitalisation of S$74 billion.

    What is interesting is that, according to estimates, about 25 per cent of the shares of Reits are in the hands of retail investors. (The sponsor groups and controlling shareholders are estimated to hold some 35 per cent, while institutional investors own 40 per cent.)

    Assuming most of these retail investors are Singaporeans, the 25 per cent translates to a whopping S$18 billion in investment money.

    The government has put in measures to regularly improve the operating and regulatory environment for Reits, so that they can continue to grow, and at the same time operate under good corporate governance, and embrace best industry practices.

    We are fortunate that the listed Reits here are under the prudent supervision of the regulatory authorities, which should instil confidence among investors, both here and overseas.

    A stable and transparent tax infrastructure to support S-Reits helps to advance the goal of establishing Singapore as a fund management and asset management hub, and continue to fuel demand for expertise in these high-value financial areas.

    Specifically, it will allow S-Reits to maintain their competitive advantage over other regional markets and allow the Republic to position itself as the pre-eminent global hub for the listing of S-Reits.

    It will also allow Singapore to attract foreign capital and investment in S-Reits.

    Many Singaporeans are eager to find investment alternatives that give higher returns than banks’ fixed deposits or their CPF ordinary accounts. Reits are perhaps one such alternative.

    Some investors may have discovered that it is possible to turn Reits into personal ATMs that they can “withdraw” money from regularly.

    This is what Reits are in a nutshell: giving the investors a stable income on a regular basis (every three or six months), with potential upside that their price will go up over time.

    The ability to enter and exit Reits easily is another big contrast to direct investment in physical assets. Another benefit is the affordability of Reits, with outlay as low as a few hundred dollars.

    Perhaps the next exciting phase in Reit development here is brewing.

    This is the rising use of CPF and Supplementary Retirement Scheme (SRS) money for Reit investments – something that may significantly affect the growth of the Reits industry over the next few years.

    Looking at CPF statistics, as at March 31, 2016, Singaporeans had about S$308 billion in their CPF.

    This is after deducting the S$190 billion drawn down for housing purchases.

    Of the S$308 billion, S$113 billion is in the Ordinary Account, S$78 billion in the Special Account, and the rest is in Medisave and Retirement accounts.

    If we focus just on the Ordinary Account which CPF rules currently allow to be used for investments after setting aside S$20,000, the investible amount is estimated to be about S$73 billion. Since the rules allow up to 35 per cent of the investible money for share investment, this means a potential pool of S$25 billion available for investing in shares, including Reits.

    This is an enormous sum of money which is looking for higher returns than the 2.5 per cent that CPF gives.

    Over time, as people become more aware of the relative attractiveness of Reits, more of such CPF monies will flow into Reits.

    And that will be interesting because it will mean that more Singaporeans will be owners of investment properties both here and overseas.

    Even investing abroad

    Singaporeans, like most Asians, traditionally prefer to invest in brick-and-mortar assets.

    Some even venture to buy overseas properties.

    Reits present a new form of investment tool to meet such aspirations of Singaporeans to own investment properties with regular rental income, without having to deal with all the problems associated with investing directly in a property, especially in unfamiliar overseas markets.

    It is interesting that, currently, CPF rules do not allow Singaporeans to use their CPF money to buy overseas properties directly.

    But with Reits, one can effectively do that.

    For example, one can invest in German office buildings by buying IReit Global shares.

    One can own a stake in shopping malls or hospitals in Indonesia through Lippo Mall Trust and First Reit respectively.

    For exposure to China and Hong Kong properties, there are Mapletree Greater China Commercial Trust, EC World Reit, CapitaLand Retail China Trust and BHG Retail Trust to choose from.

    One can also access the US, India and Japan markets through Reits listed here.

    Today, some 30 per cent of the Reits’ assets are outside Singapore.

    Effectively, this means that the Reits are bringing properties from all over the world to the doorstep of Singaporeans for them to pick and invest in, with the added comfort that these overseas assets are owned and managed by Reits which are under the regulatory oversight of our government authorities.

    We may therefore see a stronger trend of Singaporeans sinking more of their excess investment money (including CPF and SRS money) into Reits, instead of pursuing the traditional approach of buying a physical property asset for investment.

    Best of all, one gets to keep 100 per cent of the dividends received from Reits without having to worry about the taxman’s share.
     

  • Shopping patterns in Singapore shift amid slowdown

    Shopping patterns in Singapore shift amid slowdown

    And yet, amid this gloom, consumers continue to spend – though there is a shift in the pattern and quantum of their spending.

    In June, the first month of the Great Singapore Sale, retailer sales were down 3 per cent compared with the same month last year. It is not just tourists who are staying away, but local consumers are also looking more closely at price tags.

    The mood has not been helped by the fact that about 4,800 people were laid off in the second quarter, 48 per cent more than in the same period last year.

    Landlords are feeling the pinch as well. Average monthly gross rents for prime first-storey speciality retail shops dipped 1.2 per cent in the three months to September from the previous quarter, said property consultancy Edmund Tie & Company recently.

    Vacancies in the Orchard planning area rose again in the second quarter to 9.2 per cent, after reaching what was then a five-year high of 8.8 per cent in the first quarter.

    ANZ economist Ng Weiwen pointed out that home prices have fallen for 12 consecutive quarters, while bank lending has shrunk for 11 straight months. This has translated into weaker spending.

    However, the decline has been gentle across the board and there have been some bright spots. Those who find this surprising should look at the unemployment rate. While it rose from 1.9 per cent in March to 2.1 per cent in June, it remains quite low. Said OCBC economist Selena Ling: “When unemployment rate is anything below 3 per cent, it is effectively at full employment.”

    It could be one reason why consumers continue spending on mid-range goods and services, such as travel and at cafes, even as they cut back on luxury items and seek better deals for necessities.

    ANZ’s Mr Ng said: “For the different tiers of consumer spending, the high-end consumer segment will be more sensitive to changes in consumer income, so it’s not surprising.

    “The mid-range segment will still hold up in the near term as wages are still holding up.”

    In fact, more are paying their credit card bills on time. Only 32.25 per cent of card holders did not pay their bills in full for the second quarter, down from 33.91 per cent in the first quarter. Ms Ling said: “People have been turning slightly more cautious with spending.”

    They may spend less on fashion. And malls could take a hit if their offerings are the same as the ones available on Taobao and the like, she added.

    But cheaper options like house brands at supermarket chain FairPrice are seeing stronger demand.

    This is what a slowing economy looks like – in Singapore.


  • Singapore banks missing the boat in booming SE Asia

    Singapore banks missing the boat in booming SE Asia

    The three local banks are not having a good year, mostly due to forces beyond their control, but they seem to be also scoring own goals – missing opportunities right on their doorstep, our South-east Asian neighbours.

    The past two decades have been a waste in terms of what they should have done, formulating and working out a thoughtful strategy of expansion in ASEAN countries but efforts have been half-hearted and sometimes marred by ineptitude.

    Singapore contributes the bulk or the lion’s share of profits to DBS Group Holdings, OCBC Bank and United Overseas Bank (UOB) but domestic sluggish growth, a slump in the property market and a prolonged period of weak interest rates are translating to poorer earnings.

    What could have helped is if the banks have a larger presence in the region which is booming; some countries this year and the next are projected to grow more than 6 per cent against 1-2 per cent for Singapore.

    Year to date, the stockmarkets of Indonesia and Vietnam are posting double-digit gains while it’s in the high single digit for Thailand and the Philippines. Singapore equities by contrast is a minus 2 per cent.

    For various reasons, the banks have pretty much neglected the Philippines, Thailand and Vietnam, concentrating on expanding in Greater China.

    All three have Indonesian subsidiaries but progress in getting meaningful traction in ASEAN’s largest economy has been slow. And payback for their Greater China strategy is taking a very long time.

    In Q2, DBS said China recorded a net loss of S$15 million compared with a net profit of S$79 million a year ago and S$23 million in the previous quarter.

    Net profit for Hong Kong halved to S$161 million from S$320 million a year ago.

    OCBC’s Greater China pre-tax profit was unchanged at S$253 million in Q2; UOB posted a pre-tax profit of S$66 million for Greater China, down almost 30 per cent.

    From Malaysia, where OCBC and UOB are among the largest foreign banks, contributions there are somewhat underwhelming.

    In Q2, OCBC’s Malaysia pre-tax profit was up 11 per cent at S$214 million making up 19 per cent of total group earnings.

    UOB’s Q2 pre-tax profit from Malaysia fell almost 9 per cent to S$125 million, and contributed 13 per cent to group total.

    The banks had a golden opportunity to acquire banks in the debt-strapped ASEAN countries following the 1998 Asian financial crisis but they let that slip after some missteps.

    DBS tried with forays in Thailand and the Philippines but quit after huge losses.

    Today, it has some activities in Indonesia which are so small that the bank lumps it under South and South-east Asia. Still, Q2 net profit of South and South-east Asia of S$46 million from breakeven a year ago shows the potential.

    OCBC’s Indonesian business posted Q2 pre-tax profit of S$76 million, or 7 per cent of group total, and up from S$47 million a year ago.

    UOB, which has the most extensive operations in South-east Asia including 157 branches in Thailand and 190 in Indonesia, tried to buy a bank in the Philippines in 1999.

    But stymied by minorities, the bank pulled back in 2005, efforts which left its then chairman and chief executive “allergic” to the Philippines.

    UOB’s Q2 pre-tax profit from Thailand and Indonesia came to a combined S$78 million or 8 per cent of group earnings.

    For sure, it will never be smooth sailing to venture into these countries given that their sometimes chaotic domestic politics, frequent changes in policy, and weak adherence to rules, factors which deter all but the most stout-hearted foreign investors.

    Venturing out of Singapore will always be tough but our deep-pocket banks have the resources.

    The potential of South-east Asia is well documented: the 10 South-east Asian countries with a US$2.4 trillion (S$3.3 trillion) economy and population of 626 million forms one of the largest markets in the world which remains under-banked. It also has a burgeoning educated middle class that is receptive to financial services and products.

    What our banks need is staying power and agility to navigate these unwieldy markets, before they entirely miss the boat.

  • India and Singapore to collaborate on innovation

    India and Singapore to collaborate on innovation

    India and Singapore have signed an agreement to promote innovation, creativity and technological advancement in both markets.

    According to the official statement released, “The MoU will enhance bilateral cooperation activities in the arena of industrial property rights of patents, trademarks and industrial designs. It is intended to give a boost to innovation, creativity and technological advancement in both regions.”

    The agreement covers intellectual property cooperation between DIPP and the Intellectual Property Office of Singapore. The MoU was signed during the visit of Singapore’s Prime Minister to India last week.

    The key initiatives under the pact will be exchange of best practices, experiences and knowledge on intellectual property awareness among the public, businesses and educational institutions of both countries.

    Both the countries will also exchange experts in the field of intellectual property; dissemination of best practices, experiences and knowledge on IP with the industry and universities.

    The MoU will enable India to find out about best practices in the innovation and IP ecosystems that will substantially benefit entrepreneurs, investors and businesses on both sides.

    “The exchange of best practices between the two countries will lead to improved protection and awareness about India’s range of intellectual creations,” the release mentioned.

    It adds that the collaboration is a step forward in India’s journey towards becoming a major player in global innovation and will further the objectives of the National IPR Policy.

  • Korea and Singapore’s broadband lead narrows

    Korea and Singapore’s broadband lead narrows

    South Korea continued to have the highest average connection speed in the world at 27 Mbps while Singapore maintained its position as the country with the highest average peak connection speed at 157.3 Mbps.

    These were among the findings of the Akamai Technologies’ Second Quarter, 2016 State of the Internet Report.

    Both countries, however, registered declines in average connection speed and average peak connection speed, respectively, at 7.2% (South Korea) and 7.1% (Singapore) compared to the first quarter.

    Meanwhile, the global average connection speed decreased 2.3% quarter over quarter to 6.1 Mbps, while the global average peak connection speed increased 3.7% to 36 Mbps. The 10 Mbps broadband adoption rate grew 0.7% quarter over quarter, but 15 Mbps and 25 Mbps broadband adoption rates fell 0.8% and 2.1%, respectively.

    In Asia-Pacific, the report noted that 14 of the 15 surveyed countries had average connection speeds above the 4 Mbps broadband threshold. Indonesia registered a 148% gain in average connection speed in the second quarter and the only country to see its speed double compared to the previous year.

    In the mobile space, Akamai reported that average mobile connection speeds ranged from a high of 23.1 Mbps in the United Kingdom to a low of 2.2 Mbps in Venezuela. The report noted that in the upcoming quarters, it expects to see mobile speeds continue to climb as 4G LTE becomes deployed more broadly worldwide.

    In Asia-Pacific, South Korea (11.1 Mbps) also led the world in average mobile connection in the second quarter of 2016, followed by New Zealand (9.8 Mbps), Japan (9.5 Mbps), Taiwan (9.3 Mbps), Australia (8.9 Mbps), and the Philippines (8.5 Mbps).

  • Singapore Website Shutdown After Selling Fake Calvin Klein Products from Taobao

    Singapore Website Shutdown After Selling Fake Calvin Klein Products from Taobao

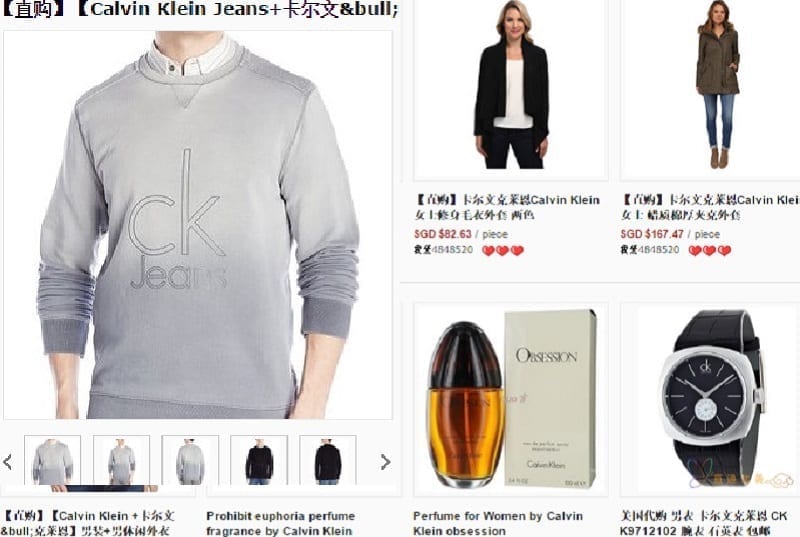
    Website SGbuy4u was found selling fake Calvin Klein goods after investigators successfully purchased imitation wallets and underwear from the website.

    Calvin Klein’s case against Singapore-based Global PSM marked the first reported suit that involved a summary judgment against a firm selling fake goods online in Singapore.

    Global PSM however, claimed that their business model was customer-to-customer service.

    2

    Users can search for and buy a variety of goods on the website and after a payment for an item has been made, Global PSM then passes on the order to Chinese shopping website Taobao. After the company has transferred payment, and the item has been delivered in China, it will then be shipped to the customer in Singapore.

    Calvin Klein filed cases and asked for summary judgment against Global PSM, freight forwarding company HS International and a Mr. Jeffrey Tan, the owner of the two firms, after two successful purchases.

    “The crux of the dispute lies in the proper characterization of the business and the involvement of each of the defendants in those business activities,” said Justice Chan Seng Onn was quoted as saying.

    Global PSM’s argument claimed that the company merely served as a courier, pointing the blame for the trademark breaches to original sellers on Taobao.

    Prosecution lawyers, however, countered that the SGbuy4u business does more than courier services as it collects payments, buys the fake goods on Taobao and has them delivered to their warehouse.

    While Justice Chan had expressed willingness to hold Global PSM accountable for trademark infringement, he ruled that some issues were needed to be clarified in relation to the involvement of the other defendants.

    “There is a pressing need for intellectual property law to keep up with technological advances in order to ensure that the law continues to protect intellectual property and rights owners in real and relevant ways,”the judge said.

  • Fortis Healthcare to take loan of Rs 77.6 cr from Singapore bank

    Fortis Healthcare to take loan of Rs 77.6 cr from Singapore bank

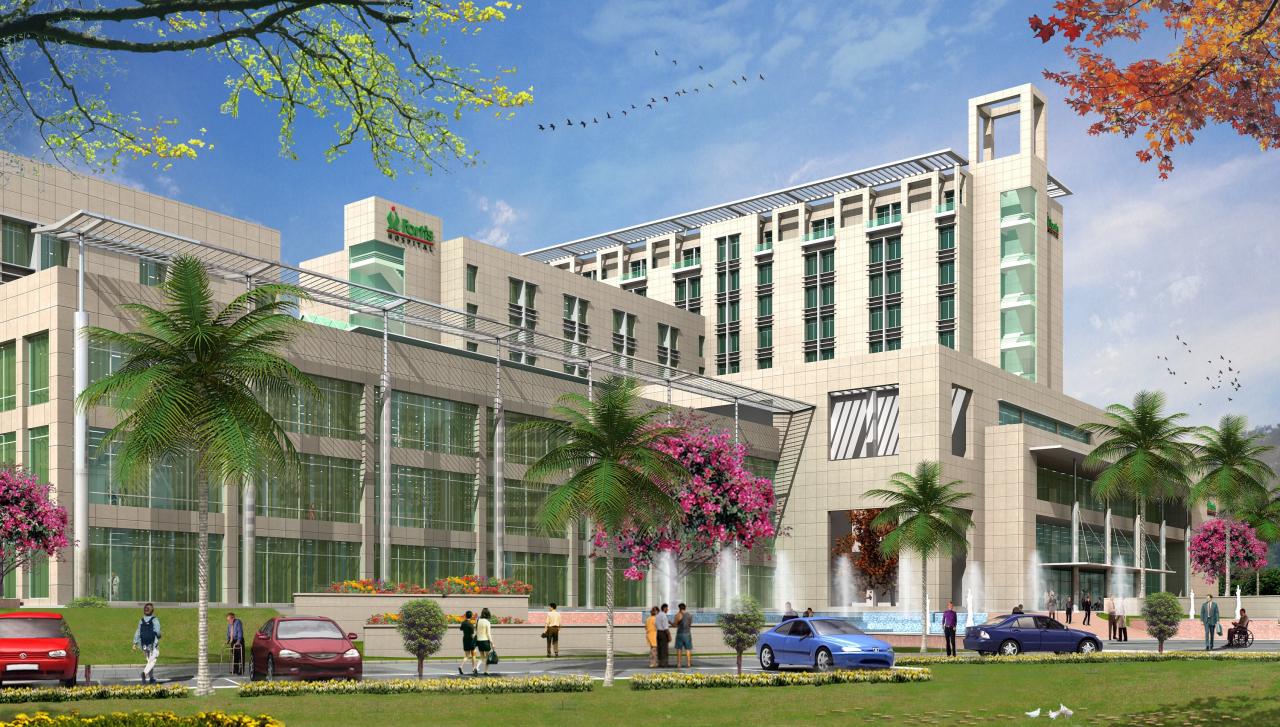
    Fortis Healthcare said it´s Mauritius subsidiary Fortis Healthcare international Ltd, has will take a loan of SGD 165 mln (Rs 77.6 crore) from Singapore-based Consortium of Bankers.

    “Fortis Healthcare Ltd has being holding the company, is giving guarantee on behalf of FHIL securing the payment of principle and interest thereon.,” said the Indian company.

    Fortis Healthcare Limited is a chain of super speciality hospitals in India.

    Currently, the company operates its healthcare delivery services in India, Dubai, Mauritius and Sri Lanka with 54 healthcare facilities (including projects under development), approximately 10,000 potential beds and 314 diagnostic centres.


  • Xiaomi opens its first store outside greater China

    Xiaomi opens its first store outside greater China

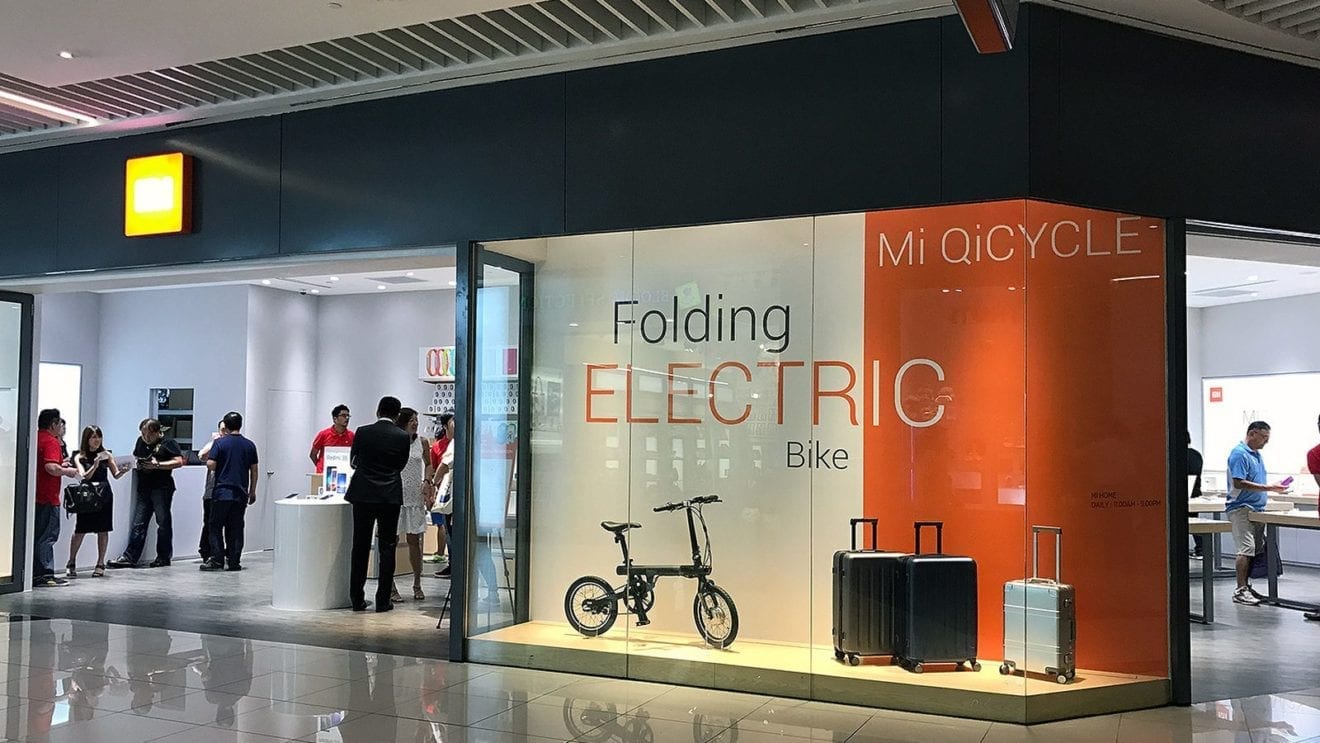
    Xiaomi phones are finally available offline in southeast Asia as the company has opened a shop outside greater China for the first time ever.

    The sunny island state of Singapore hosts the first Mi Home store to open outside of China, Hong Kong and Taiwan. The Singapore Mi Home store, located at popular shopping mall Suntec City, sells Xiaomi’s line of phones and accessories. But unlike other stores, it doesn’t stock the company’s other Mi ecosystem products such as the Mi TV or the Mi Rice Cooker.

    Xiaomi says that it plans to bring in more of its product lineup in time. But for now, customers will have to make do with the Mi Max, Mi 5, Redmi 3S, Redmi Note 3, Mi Band 2 and other accessories such as portable speakers and power banks.

    The Chinese manufacturer is using a local partner to run the store — unlike the ones in China, Hong Kong and Taiwan, which are run by Xiaomi itself.

    The company is also turning to regional online retailer Lazada to manage its online sales, an area it’s managed by itself in Singapore up to now.

    These moves to divest itself of retail responsibilities in Singapore could point towards a shift in Xiaomi’s current strategy. It’s possible the Chinese giant will focus on its home market to make up for ground lost to rivals Huawei, Oppo and Vivo.

    While the company continues to battle it out for India — the second largest smartphone market in the world after China — it’s likely Xiaomi will use the same retail strategy from Singapore across the Southeast Asian region as the company shifts its focus towards India, China and a possible US launch next year.

  • McDonald’s Malaysia, Singapore ‘buyer found’

    McDonald’s Malaysia, Singapore ‘buyer found’

    Twenty-year franchise rights for McDonald’s Malaysia and Singapore outlets have been conditionally sold to a Saudi Arabian group for up to US$400 million.

    Reza Food Services, which owns McDonald’s restaurants in Saudi Arabia, is seeking finance from Malaysian bank CIMB to finance the transaction, insiders say.

    McDonald’s is moving to bring in partners as it switches to a less capital-intensive franchise model in Asia, and has said it wants regional family-owned groups and local tycoons as long-term partners.

    Insiders say the basic terms of the agreement with Reza have been finalised, with the deal expected to be completed by the end of the year.

    McDonald’s, which has about 260 restaurants in Malaysia and about 120 in Singapore, is also selling its China and Hong Kong outlets, and has received final bids from at least three groups.

  • TravelersBox rolling out in Asia

    TravelersBox rolling out in Asia

    TravelersBox kiosks are being launched in Asian airports allowing travellers to deposit their leftover foreign coins into their preferred online accounts.

    More than 40 are expected to be service by the end of the year.

    TravelersBox is the first service allowing travellers to convert foreign currency into usable digital currency at airports. First rolled out at Manila airport in the Philippines, the latest kiosks have just come online in Narita International Airport in Japan.

    In parallel to the expansion, the company is also launching additional products and services in the kiosks tailored to the Asian market.

    Baidu wallet is the first offering, specifically aimed at the Chinese market, the largest travelling population in the world.

    “For the Asian market we’ve given specific attention to each traveller’s nationality,” says TravelersBox co-founder/CEO Tomer Zussman. “Services such as Nets FlashPlay Card for Singaporeans, Lazada for Southeast Asian travellers and more will soon be available in the TravelersBox around the world.”

    TravelersBox has more than 75 kiosks internationally where travellers can convert their leftover foreign change into digital money with options including iTunes, PayPal, Skype and gift cards such as Gap or Starbucks. There is also a donation button.

  • Singapore retail rents slip over latest quarter

    Singapore retail rents slip over latest quarter

    Singapore retail rents slipped during the last quarter – but experts say the outlook is not too grim.

    According to Edmund Tie & Company Research, average monthly retail gross rents across the island eased by 1.2 per cent quarter-on-quarter to about $29.30 per sqft in the three months to September 30. This was 9.6 per cent lower than its peak in the first quarter of 2015, when the average monthly gross rent was about $32.40 per sqft.

    “The decline was primarily due to a subdued economic growth forecast, as well as job cuts across various industries that led to weaker consumer sentiments,” the company said.

    According to the Ministry of Manpower in September, the total number of workers made redundant in the second quarter of 2016 rose by 2 per cent quarter-on-quarter and 48 per cent year-on-year to 4800 workers.

    Rents in the other city areas led the overall rental decline in the latest quarter, falling by 3 per cent to about $20.10 per sqft per month. This was followed by the suburban areas, with average monthly gross rents declining by 1.5 per cent to $30.60.

    Orchard Rd holds firm

    Retail rents in Orchard and Scotts Rd precinct, however, stayed unchanged at $37.20 per sqft,

    notwithstanding the slower economy and fears over the impact on tourism of the spread of the Zika virus.

    “The resilience of this district was supported by the lack of new retail developments. While retailers in Orchard/Scotts Rd face strong competition for tourist dollars from regional countries, renowned global brands and local retailers are still attracted to set up shops there. The recent opening of several high-profile flagship stores in the area has further enhanced Orchard/Scotts Rd’s position as one of the top shopping attractions in South East Asia,” said Edmund Tie.

    “Overall, we anticipate the decline in rents to moderate in 2017, barring any external shocks. Landlords and retailers are adapting to the challenges by integrating technology with their physical stores to manage manpower constraints and tap on the growing eCommerce market.” The company cited the upcoming OUE Downtown Gallery along Shenton Way which will introduce a 11,000 sqft “trend gallery” comprising pop-up stores and retail counters on the first-storey, and a 4000 sq ft “social kitchen” fitted with 10 cooking stations available for bookings on the third-storey.

    A new F&B concept will also be introduced, whereby diners place their food orders via a mobile app. The food is prepared in a central kitchen and is subsequently placed in an assigned locker for diners to collect at a specified time. This significantly reduces the amount of leasable space required by the food establishment, as well as its reliance on manpower.

    In addition, the upcoming Singapore Post Centre in 2017 and the newly revamped Funan mall in 2019 will be introducing hands-free shopping. Shoppers will be able to browse through the products in-store, purchase the product and arrange for the product to be delivered directly to their homes. Not only does this provide greater convenience for shoppers, it also allows retailers to save on storage space in their physical stores, as logistic arrangements are done in the warehouse.

    “Separately, there is also a trend towards Click-to-Brick, where the shopping is done online and the merchandise is collected in the shops. Retailers that allow consumers to click-and-collect include Harvey Norman, Courts, NTUC, Decathlon, and Tangs.”

    Too early to write off brick-and-mortar

    Despite eCommerce gaining traction, Dr Lee Nai Jia, Edmund Tie & Company’s Southeast Asia head of research, believes it is too premature to write off the brick-and-mortar retail sector.

    “In order to remain competitive, landlords and retailers are continuously looking for ways to improve their business models and remain adaptable to challenges. Many landlords and retailers are making use of big data analytics to understand the underlying purchasing psychology, which helps them to redefine their marketing strategies to better cater to their customers’ needs.

    “Additionally, retailers are introducing experiential shopping and new retail concepts to increase footfall and encourage in-store sales. They offer hands-on activities for customers to experience at their physical stores. For example, Uniqlo’s SEA flagship store at Orchard Central will be reeling in Singaporean creatives and talents to hold a wide range of workshops in its three-storey flagship store. Similarly, K+ at Scotts Square and Naiise outlets at The Cathay, Orchard Gateway and Clarke Quay Central also provide dedicated spaces for workshops within their stores,” said Jia.

    “While it is still too early to judge the effectiveness of experiential retail in increasing footfall and in-store sales in Singapore, the concept has worked well for some brick and mortar retailers in the US, which saw eCommerce gaining an increasing foothold in the retail industry. A case in point was the success of Whole Foods in the US, which built on its success by creating personalised rewards and in-store experiences, including cooking classes, juice and coffee bars and consultations with nutritionists.”

  • CapitaLand Mall Asia plans expansion

    CapitaLand Mall Asia plans expansion

    CapitaLand Mall Asia is stepping up its investment in India.

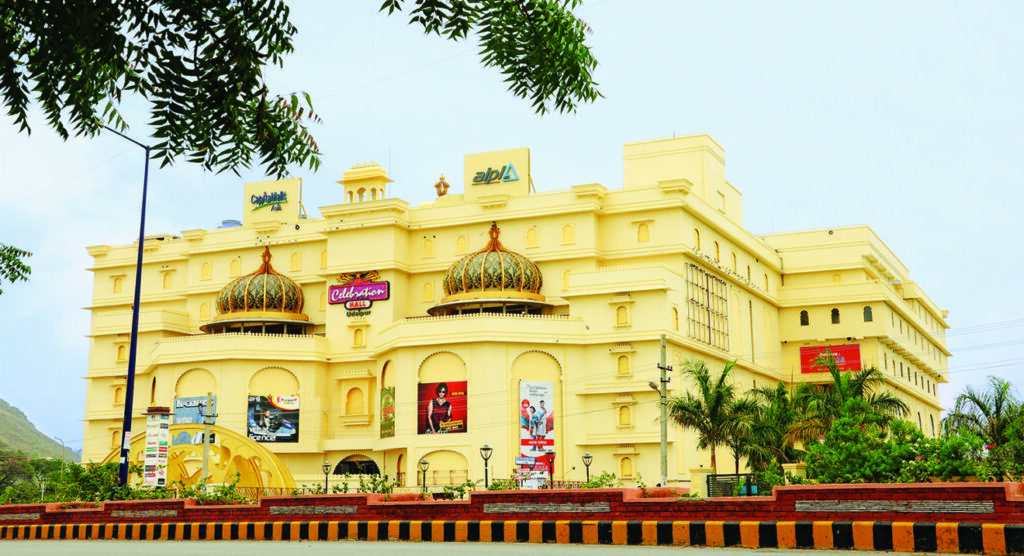
    During a visit by Singapore’s Prime Minister Lee Hsien Loong to The Celebration Mall in Udaipur (pictured) , wholly owned by CapitaLand Mall India Development Fund, CapitaLand Mall Asia announced plans to open two more malls in India over the next three years.

    The group already has four malls in the country.

    CapitaLand president/group CEO Lim Ming Yan says India has been looking to tap Singapore’s experience in urban planning as it plans to upgrade and build 100 cities.

    capitaland-mall-india

    “India thus presents opportunities for CapitaLand to share our expertise in real-estate development and management, particularly in integrated developments where we have established a strategic advantage, as well as in the shopping mall and serviced residence sectors where we have already gained a foothold in the country.

    “With more liberal rules on foreign direct investment in real estate, CapitaLand has been presented with a number of opportunities. We are also in discussion with several parties on management contracts for shopping malls and serviced residences.”

    Partnership

    CapitaLand’s two upcoming malls are opening next year and in 2019 respectively, Forum Mysore, and Forum Cochin.

    Both are being developed in partnership with real-estate developer Prestige, with whom CapitaLand also partners for three other malls, The Forum Neighbourhood Mall, Bangalore, The Forum Sujana Mall, Hyderabad and The Forum Fiza Mall, Mangalore. Including two other malls being developed in Jalandhar and Nagpur, CapitaLand is Singapore’s largest shopping-mall developer and manager in India with a total of eight malls.

    “In Asia, India is the next big retail prize after China,” says CapitaLand Mall Asia CEO Jason Leow.

    “India has a large and growing middle class with aspirations for a better life, and more than 400 million consumers between 15 and 34 years of age who are driving purchases in categories such as mobile phones, fashion, accessories and F&B.

    “Such favourable demographics are drawing retailers’ interest to India’s fast-growing consumer market, which is expected to be worth US$1.3 trillion by 2020.

    “As one of Asia’s leading mall developers, owners and managers, we are able to leverage our retail expertise and industry-leading network of about 15,000 leases to support local and international retailers who are keen to do business in India.”

  • Batam to facilitate SMEs export products to Singapore

    Batam to facilitate SMEs export products to Singapore

    The administration of Riau Islands city of Batam will facilitate the export of products manufactured by the Indonesian Micro, Small and Medium Enterprises (SMEs) to Singapore, an official has stated.

    “We are trying to facilitate (the export of products), because the products manufactured by the Micro, Small and Medium Enterprises are being exported to some neighboring countries, including Malaysia and Singapore,” head of the Batam office of the Community Empowerment, Cooperatives and Micro, Small and Medium Enterprises (SMEs), Pebrialin, said here on Monday.

    This October, the Batams administration will consult the Indonesian Embassy in Singapore to explore the market in order to facilitate the export of the SMEs products to Singapore, he added.

    As per a research undertaken by the local administration, many SMEs have shipped their products to Singapore. Unfortunately, the volumes are limited.

    According to Pebrialin, Singapore’s decision to replace the trademarks was detrimental to the Indonesian producers, because they cannot control the market directly.

    In addition, the manufacturers also face difficulty in developing their business, because they become dependent on the trademark of Singapore.

    The Community Empowerment, Cooperatives and Micro, Small and Medium Enterprises (SMEs) will also help the SMEs meet the norms applicable in Singapore and Malaysia, so that their products can be freely distributed in the market, Pebrialin added.

  • McDonald’s Malaysia ‘not in hurry’ to sell

    McDonald’s Malaysia ‘not in hurry’ to sell

    Despite shortlisting several bidders for the McDonald’s Singapore and McDonald’s Malaysia franchise rights, Malaysian subsidiary Golden Arches Restaurants says it is not in a hurry to sell.

    MD Azmir Jaafar says the deal is being discussed with the shortlisted bidders, but no time frame has been set to complete the transaction.

    “We want to find the right partner who understands the local market and can ensure continuity of McDonald’s value and tradition, as well as be backed by strong capital.”

    He says it has always been the group’s idea to sell the franchise rights to a local partner, which would be more efficient than management by a corporate entity.

    McDonald’s Corp announced a revamp of its ownership models throughout Asia in July, including plans to offload its China, Hong Kong, Malaysia, Singapore and South Korea master franchises.

    CEO Steve Easterbrook’s plan covers about 4000 restaurants with an ultimate goal of having at least 95 per cent of the group’s restaurants franchised.

    Meanwhile, Azmir says that as the Malaysian deal is a business transaction “we will ensure the valuation is done properly”.

    “Still potential”

    There are 260 McDonald’s restaurants in Malaysia, with Golden Arches managing 200 and the rest in the hands of a third party. Though Malaysia has a population of only about 30 million people, which is relatively smaller than China and Indonesia, Azmir still sees huge potential in the market.

    “There are still many underserved areas,” he says. “As the government is improving the infrastructure in Sabah and Sarawak, I think we can expand our footprint into Kota Kinabalu and Kuching and other cities.”

    Azmir says the company intends to open 30 stores in the Klang Valley, Johor, Melaka and Penang as well as Sabah and Sarawak in the next three years. Five to seven new stores are targeted for this year, with one in Presint 2, Putrajaya, and another in Chukai, Terengganu, already open.

    “Our expansion plan is focussed on stand-alone stores as this model works very well, especially in terms of accessibility and convenience. Our ultimate goal is to have 500 stores in the country.”

    Azmir says the company also intends to renovate and remodel up to 30 outlets, each to cost about RM1 million (US$241,700). They have been open for nearly 30 years and will also have their technology upgraded.

    Combined, McDonald’s Singapore and McDonald’s Malaysia have enjoyed record sales in the past few months and is still targeting higher double-digit growth this year.

    Even following the introduction of the goods and services tax in Malaysia in April last year, Azmir says the company raised its selling prices by only about 1 per cent to offset the higher raw-material cost.
    He believes McDonald’s has captured up to 42 per cent market share in the Malaysian fast-food market.

  • Fast Retailing rolling out GU shops overseas

    Fast Retailing rolling out GU shops overseas

    Japanese retail holding company Fast Retailing intends to have 1000 shops for its low-cost GU brand overseas in 10 years, up from about 10 foreign stores now.

    GU sells clothing often priced at about half that of stablemate Uniqlo.

    Fast Retailing will expand GU first in Asia, where Uniqlo has been successful, says chairman/president Tadashi Yanai.

    After increasing its GU outlets in Taiwan and China, Fast Retailing will turn its attention to South Korea, Hong Kong, Thailand and Singapore for growth in the next five years.

    GU’s first overseas store opened in 2013. In Japan, the brand’s low prices and sensitivity to fashion trends have helped store numbers grow to around 350.

    Meanwhile, Uniqlo now has more stores overseas than in Japan, with plans to set up around 100 shops a year in China.

    Other brands under Fast Retailing’s wing include Comptoir des Cotonniers, J Brand and Princesse Tam-Tam.