Tag: supply chain

  • DHL Global Forwarding Establishes Six Air Cold Chain Corridors to Asia

    DHL Global Forwarding Establishes Six Air Cold Chain Corridors to Asia

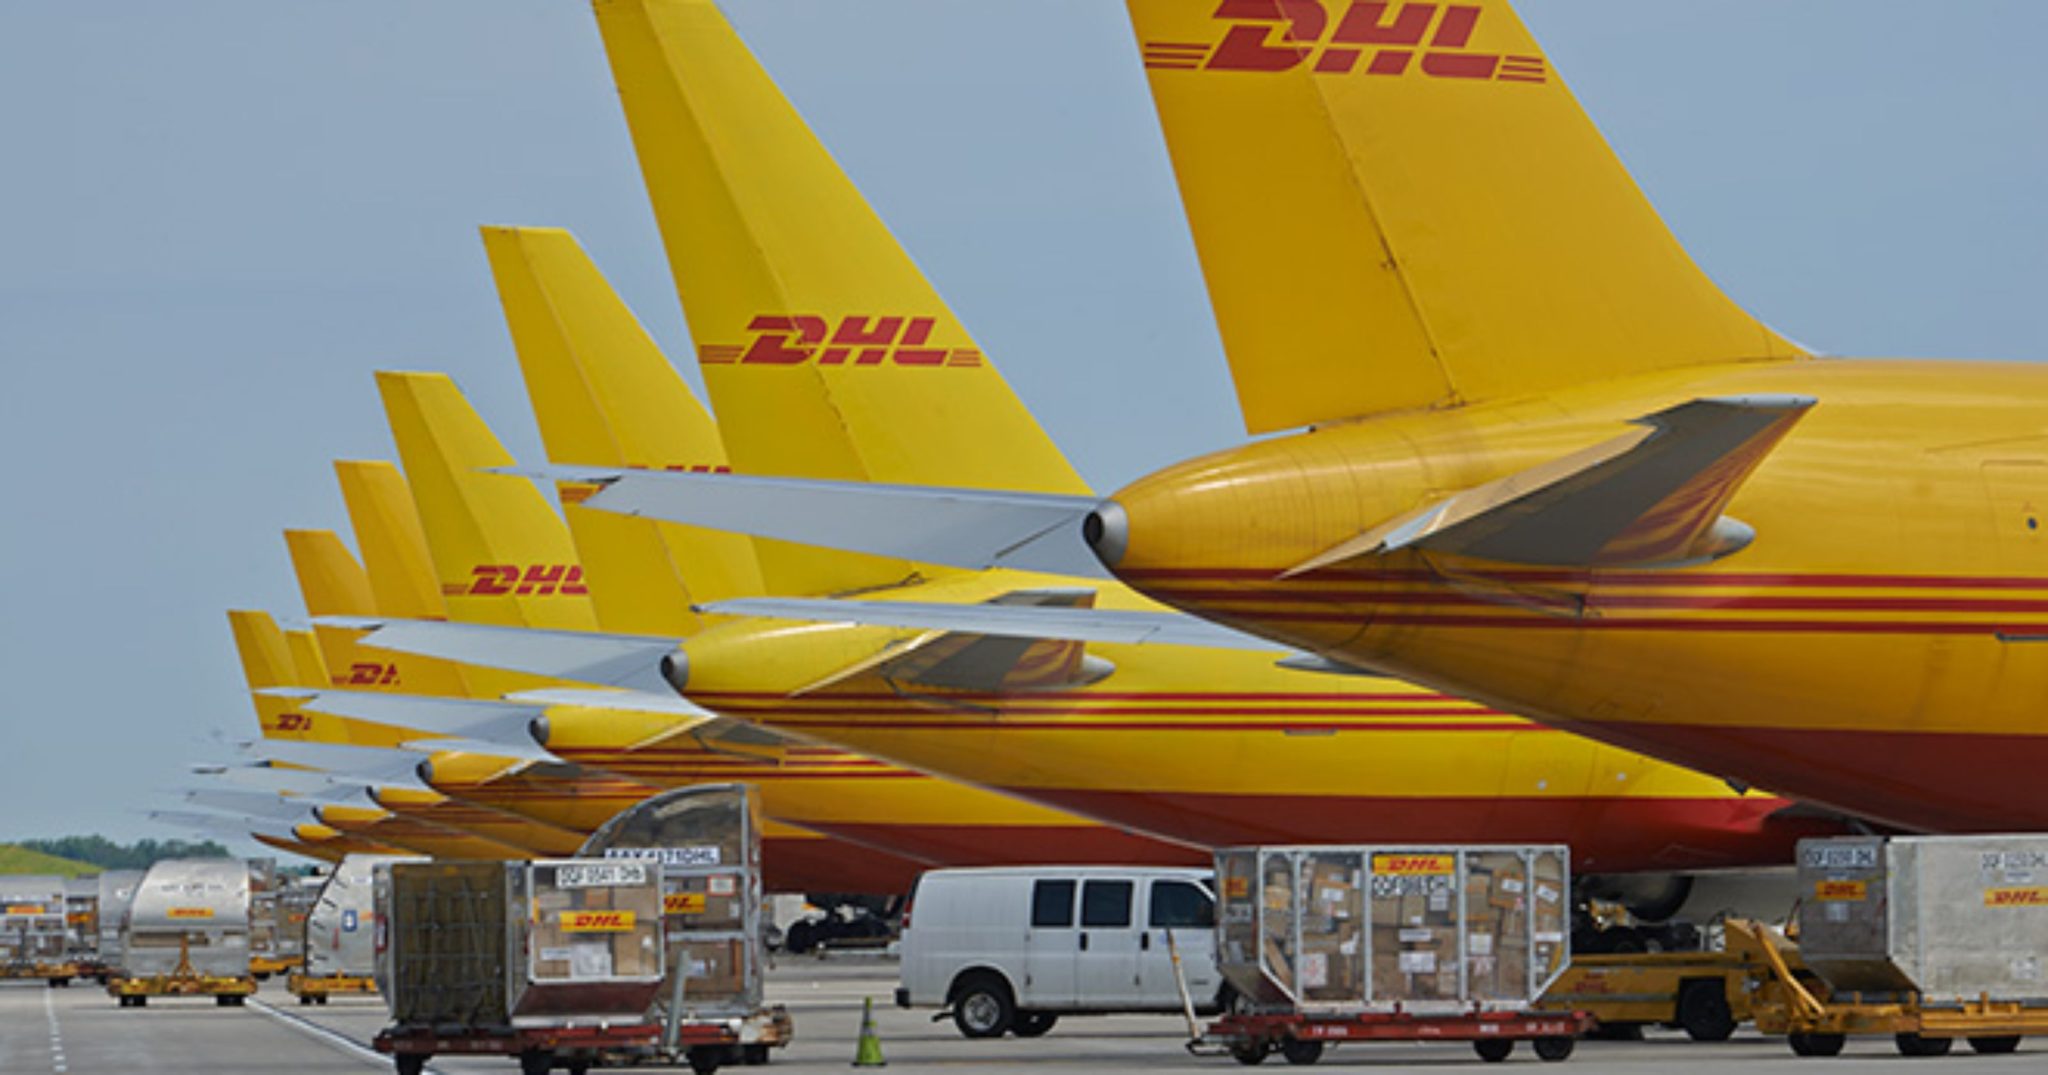
    DHL Global Forwarding expanded its cold chain network in October 2026 by launching six dedicated life sciences and healthcare air corridors connecting Europe and North America with Asia.

    The newly established routes connect Liège and Brussels in Europe, along with Cincinnati in the United States, directly to Shanghai, Singapore, Tokyo Narita, and Seoul Incheon.

    Operated primarily on DHL Express-branded Boeing 777 freighters, the flights offer three different temperature-controlled compartments to reduce handovers and safeguard temperature-sensitive healthcare shipments.

    The Six Strategic Transcontinental Trade Lanes

    Three corridors run directly from Europe, and three run from the United States. European departures connect Liège to Shanghai, Brussels to Shanghai and Brussels to Singapore. Transatlantic flights leave DHL’s Cincinnati hub for Singapore, Tokyo Narita and Seoul Incheon.

    Each aircraft combines active temperature control with passive packing protections, including thermal blanket systems and phase-change materials. These systems maintain strict limits: 2 to 8 degrees Celsius for refrigerated biologicals, and 15 to 25 degrees Celsius for controlled room-temperature medicines.

    These new corridors further expand our Cold Chain Network into strategically important healthcare markets across Asia. They respond to customer demand for reliable connectivity between major healthcare markets while giving us greater control over critical quality parameters throughout the transportation process. This enables our customers to move critical healthcare products with greater confidence and reliability.

    Control Across Healthcare Supply Chains

    Transfer points create the biggest operational bottleneck in long-haul pharma airfreight. Commercial passenger bellyhold space exposes sensitive cargo to tarmac temperature spikes during layovers or unexpected delays.

    Operating dedicated Boeing 777 freighters across proprietary hubs gives drug makers predictable schedules and uniform standard operating procedures from loading to customs clearance. It also limits reliance on third-party ground handlers who may lack good distribution practice validation.

    Competition is intensifying against rival global integrators and forwarders fighting for high-margin life sciences contracts across Asia-Pacific. Drug manufacturers in Japan, South Korea, China and Southeast Asia demand direct, auditable cold chain links into Western consumer and clinical trial markets.

    Expanding the Global Cold Chain Footprint

    This Asian expansion builds on DHL Group’s February initiative to create an integrated international cold chain network. That rollout started with transatlantic flights between Brussels and Cincinnati before extending into secondary healthcare routes.

    North American drug producers gain direct export lanes from Cincinnati into North Asia and Southeast Asia without routing through intermediate commercial air hubs. European plants around Belgium’s biopharma cluster gain matching outbound capacity into China and distribution nodes in Singapore.

    Changi Logistics Hub Anchors Regional Growth

    Adding the Brussels-Singapore and Cincinnati-Singapore routes fits DHL Global Forwarding’s wider infrastructure spend in Southeast Asia. In September, the group confirmed plans for its upcoming DHL Singapore Cold Chain Hub at Changi Airport.

    The airport facility will provide dedicated 2 to 8 degrees Celsius and 15 to 25 degrees Celsius handling zones linked directly to the airside tarmac. It will process inbound cargo from the new Boeing 777 flights and transfer shipments into regional distribution channels across Southeast Asia.

    Looking ahead, DHL plans to commission the Changi cold store facility and add further network routes across the Middle East and Latin America.
  • Broekman Logistics Highlights Middle Corridor for Europe-Asia Project Cargo

    Broekman Logistics Highlights Middle Corridor for Europe-Asia Project Cargo

    On 13 October 2026, Broekman Logistics highlighted the growing strategic importance of the Middle Corridor as European and Asian shippers seek alternative transport routes for project cargo, industrial equipment and high-value freight.

    The Netherlands-based logistics company said continued investment in rail infrastructure, ports and terminals along the Trans Caspian route is improving connectivity and creating new options to reduce dependence on established maritime corridors.

    Multimodal Links Across the Caspian Sea

    Running through Turkey, Georgia and Azerbaijan, the corridor crosses the Caspian Sea to reach Kazakhstan, Turkmenistan and Uzbekistan. Shippers combine short-sea shipping, rail freight and road haulage to bypass maritime bottlenecks and geopolitical flashpoints.

    Moving breakbulk cargo across the route requires coordination across multiple rail gauges, seaports and customs jurisdictions. Broekman Logistics focuses on synchronised route surveys, transit permits and heavy-lift transfers at Caspian terminal interchanges.

    Transit Coordination and Gateway Roles

    Turkey serves as the western anchor for the corridor, feeding European traffic through rail and highway links toward the South Caucasus. Turkish ports handle transshipment for landlocked Central Asian destinations that lack direct maritime access.

    Route selection depends on physical constraints along the way. Axle-load limits, bridge clearances, rail tunnel dimensions and Caspian port crane capacities dictate whether oversized equipment can move intact or requires disassembly before crossing inland borders.

    Operational Bottlenecks for Project Cargo

    Terminal upgrades along the Trans-Caspian line have expanded container handling, yet breakbulk cargo faces different operating realities. Transporting industrial machinery requires dedicated roll-on/roll-off vessel capacity and heavy-lift handling gear, which remain limited across Caspian Sea crossings.

    Customs alignment across five transit countries is the primary variable for schedule reliability. For equipment suppliers and engineering contractors, single-point delays at rail-to-ship transfer points can disrupt installation timelines at Central Asian mining and energy developments.

    Border Clearances and Caspian Vessel Capacity

    Infrastructure authorities along the corridor have invested in rail sidings and port berths across Baku, Aktau and Kuryk to improve transfer speeds. These terminal projects aim to establish predictable transit intervals for industrial shippers evaluating overland options against long-haul sea routes.

    Commercial viability for heavy freight now rests on the delivery of scheduled Caspian ferry slots and standardised customs transit documentation across Kazakh and Azerbaijani border points.

  • Beximco Plans British and Chinese Deal to Reopen Shuttered Bangladesh Garment Plants

    Beximco Plans British and Chinese Deal to Reopen Shuttered Bangladesh Garment Plants

    Beximco Group is seeking government approval for a foreign leasing deal to reopen its shuttered apparel plants in Gazipur, backed by British and Chinese investors.

    The five-year agreement brings British investment firm Charter HCP and Chinese operator Besting into the industrial park. Factory restarts are targeted for April 2027.

    How the factory leasing structure works

    Under the proposed plan, foreign backers will run Prefix Fashions, a specialized garment unit inside Beximco Industrial Park. Production will focus on outer garments, with export jackets accounting for roughly 90 percent of output. The first phase will restore approximately 2,500 manufacturing jobs.

    Revival Global, the asset manager for the investor group, designed a mechanism to ringfence cash flows and shield operations from Beximco’s domestic liabilities. Export proceeds will flow directly into bank accounts held by secured creditors. This prevents Beximco management from touching operational funds before paying debt obligations and working capital expenses, according to company executives.

    Phased expansion across Gazipur industrial park

    Prefix Fashions is the initial test case for a broader revival strategy. If operations and finances hold up, the consortium plans to reopen the remaining 15 shuttered apparel units in stages.

    A full rollout could rehire more than 30,000 garment workers across the complex. Beximco previously ranked among the largest private sector employers in Bangladesh. It operated vertically integrated facilities spanning spinning, weaving, denim washing and garment assembly before operations stopped.

    Supply chain shifts across South Asia

    Regional apparel sourcing faces severe turbulence. International fashion brands have spent recent months shifting purchase orders across South Asia to avoid production bottlenecks and delivery delays.

    Neighboring production hubs face their own bottlenecks. In India’s knitwear center of Tiruppur, roughly 460 dyeing facilities halted operations in October to protest raw material shortages and dye price spikes of up to 100 percent. The closures disrupted fabric supplies for export houses. Large-scale capacity in Bangladesh offers global buyers a hedge against regional limits, but confidence hinges on whether foreign management can insulate factory floors from political disruption.

    The collapse following political upheaval

    Beximco’s factory network shut down after the political collapse of the Awami League administration in Dhaka. The arrest of Beximco co-founder Salman F. Rahman, private industry adviser to former Prime Minister Sheikh Hasina, froze bank credit lines. That cut off working capital across the conglomerate’s textile, pharmaceutical and ceramics divisions.

    Plant closures in Gazipur displaced roughly 40,000 garment workers, triggering protests over unpaid wages and leaving multi-million-dollar export contracts unfulfilled. Local lenders took possession of assets. Foreign partnership leases remain the only viable route to restart production without direct government bailouts.

    Government regulators and creditor banks are reviewing the lease documentation for Prefix Fashions. State approval will determine whether maintenance teams can enter the Gazipur facility ahead of the planned April 2027 commercial restart.

  • ASML Warns AI Chip Tool Demand Will Outstrip Capacity Through 2028

    ASML Warns AI Chip Tool Demand Will Outstrip Capacity Through 2028

    ASML will fail to satisfy customer demand for its chipmaking machinery in 2027 and 2028 as orders for artificial intelligence hardware exceed manufacturing capacity.

    The Dutch equipment maker projected fourth-quarter sales between €14.2 billion and €15.2 billion, beating average market forecasts of €14.19 billion compiled by LSEG.

    Gross margins for the final quarter are projected at around 57 per cent. Extreme demand for advanced lithography systems has stretched delivery schedules well past normal lead times, pushing commercial negotiations into the next decade.

    Delivery Bottlenecks Hit Advanced Fabs

    Chief executive Christophe Fouquet confirmed that order discussions with key chipmakers now routinely bypass near-term delivery slots. Demand has outpaced every planned production adjustment across the company’s assembly facilities.

    “A lot of our discussions with our customers now are shifting in fact beyond 2027,” CEO Christophe Fouquet said in a statement.

    Fouquet noted that tool buyers are placing firm bookings for 2028 delivery while opening formal negotiations for 2029 and 2030 production slots. Foundries across Asia building capacity for artificial intelligence processors face extended wait times for critical extreme ultraviolet scanners.

    Asian Foundry Expansion Pressures

    For semiconductor manufacturers in Taiwan, South Korea and Japan, machinery shortfalls limit how fast new wafer fabrication plants can ramp output. Tool allocations dictate foundry expansion schedules, consumer hardware production runs and memory delivery timelines.

    The equipment shortage concentrates operational risk among contract chipmakers competing for identical production slots. Commercial foundries that secured earlier delivery positions will hold output advantages over rivals waiting on delayed tool shipments.

    Capacity Expansions Fall Short

    Production limits persist despite aggressive factory investments announced earlier this year. In July, the toolmaker outlined plans to raise equipment output by 30 per cent in 2027 and add another 30 per cent capacity increase in 2028.

    Those production increases will still leave the manufacturer short of customer requirements. Management is reviewing additional manufacturing options to widen assembly bottlenecks before 2028 delivery commitments close.

    Production Timelines to Watch

    Tool buyers now face strict ordering windows to secure production slots for 2029. Equipment allocations and any revision to the planned 30 per cent annual capacity increases will determine delivery timelines for global semiconductor plants.

  • Piramal Pharma Opens Microbiology Lab in 85 Million Dollar US Expansion

    Piramal Pharma Opens Microbiology Lab in 85 Million Dollar US Expansion

    Piramal Pharma Solutions has opened a microbiology laboratory at its sterile injectable plant in Lexington, Kentucky. The project advances an 85 million dollar expansion.

    The new space triples testing floor area. It targets a 50 per cent cut in product release turnaround times.

    Regulators cleared routine Good Manufacturing Practice work on September 11, 2026. Conditional approval for the adjoining sterility suite followed soon after. The lab unit forms the first operational phase of the multi-year capital program.

    Boosting Sterility and Cleanroom Capacity

    Engineers reconfigured the Lexington site to handle higher volumes of sterile drug products for clinical and commercial use. The upgrade adds three biosafety cabinets for concurrent testing. It also consolidates all incubation equipment into a single footprint.

    A dedicated Grade C cleanroom suite houses a Grade A sterility testing isolator. That setup replaces a non-classified zone. It doubles testing throughput by running open and closed filtration on multiple batches at once. Built-in sample pass-throughs connect manufacturing suites directly to analytical benches.

    Cutting Release Bottlenecks for Injectables

    Global sterile injectable manufacturing faces capacity crunches, particularly for antibody-drug conjugates, peptides and high-potency small molecules. Bringing microbiology and sterility testing in-house cuts sample transport delays. It also lowers contamination risks.

    Faster batch clearance gives the company an edge over Asian contract development and manufacturing rivals tied strictly to domestic facilities. Shorter release cycles also help pharmaceutical clients. They trim inventory holding costs and speed market access.

    Indian CDMOs Expanding Global Footprints

    Indian contract manufacturers continue to buy and upgrade assets in North America and Europe to stay close to clinical sponsors. Piramal Pharma Limited trades in Mumbai on both the BSE and the National Stock Exchange of India. It runs 17 development and manufacturing sites across India, North America and Europe, alongside hospital generics and consumer healthcare units.

    Through its subsidiary Yapan Bio, the parent company entered complex biologics manufacturing while keeping fill-finish work in Western jurisdictions. Cleanroom and testing capacity in the United States protects contract volume from overseas trade barriers and inspection backlogs.

    Timeline for Full Commercial Operations

    Nathan Richardson, vice president and site head at the Lexington facility, said: “By enhancing sterility testing and microbiological quality capabilities, we are further strengthening our ability to support clients with high quality, reliable, and responsive services throughout the product life cycle.”

    Crews are now installing commercial-scale fill and finish equipment across the remaining space. Piramal expects the full Lexington plant to reach commercial readiness in late 2027.

  • Oeko-Tex Records 13 Percent Rise in Made in Green Demand

    Oeko-Tex Records 13 Percent Rise in Made in Green Demand

    Oeko-Tex launched its Trust in Every Thread consumer campaign on Oct. 12 after the European Union introduced regulations restricting unverified sustainability claims across apparel and textiles.

    Demand for the group’s Made in Green standard rose 13 percent during its 2025-26 fiscal year.

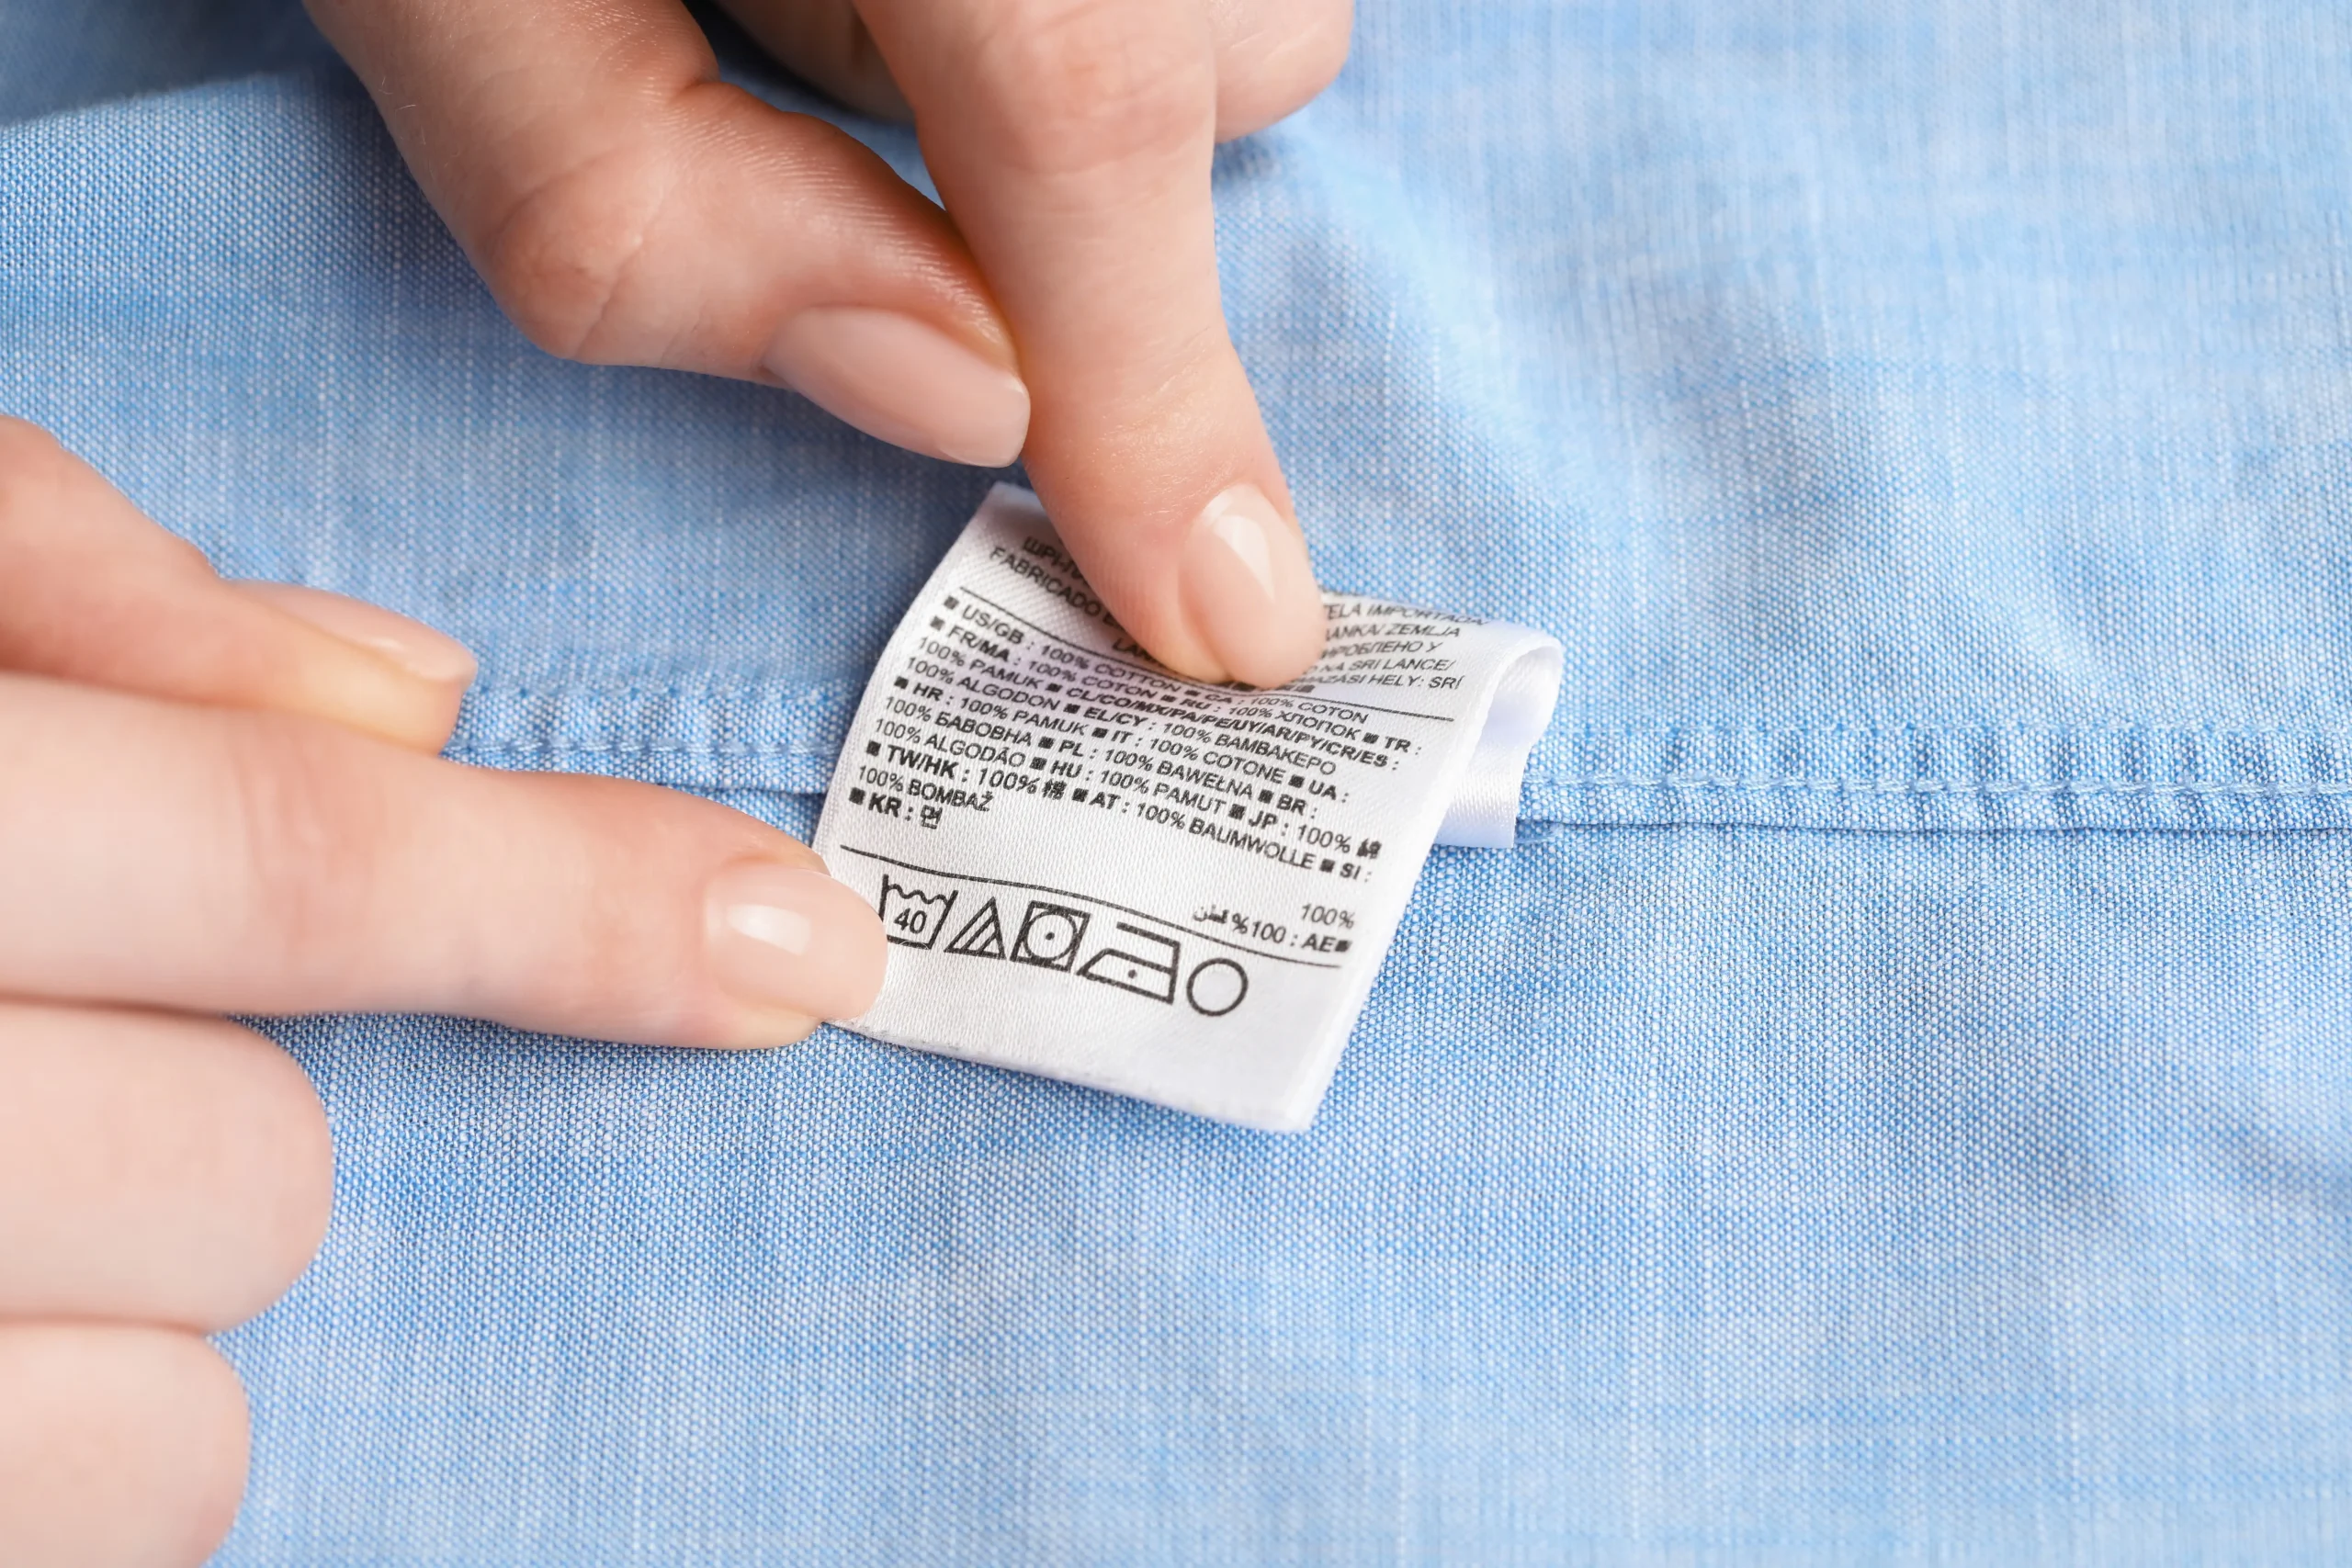
    At the centre of the campaign is a 35-second film and consumer education drive. It directs shoppers to inspect garment tags and verify claims through digital traceability tools. The European Union’s Empowering Consumers for the Green Transition Directive took effect on Sept. 27. It outlaws sustainability labels lacking backing from public authorities or accredited third-party certification bodies. Private schemes must now maintain publicly accessible criteria, enforce third-party monitoring, and provide mechanisms to suspend non-compliant users.

    Stricter verification rules for textile certification

    Generic environmental buzzwords face outright bans under the new European framework unless backed by verified data. Brands can no longer present a single product characteristic as proof of whole-garment sustainability. Verification systems must also operate independently from scheme owners and commercial clients.

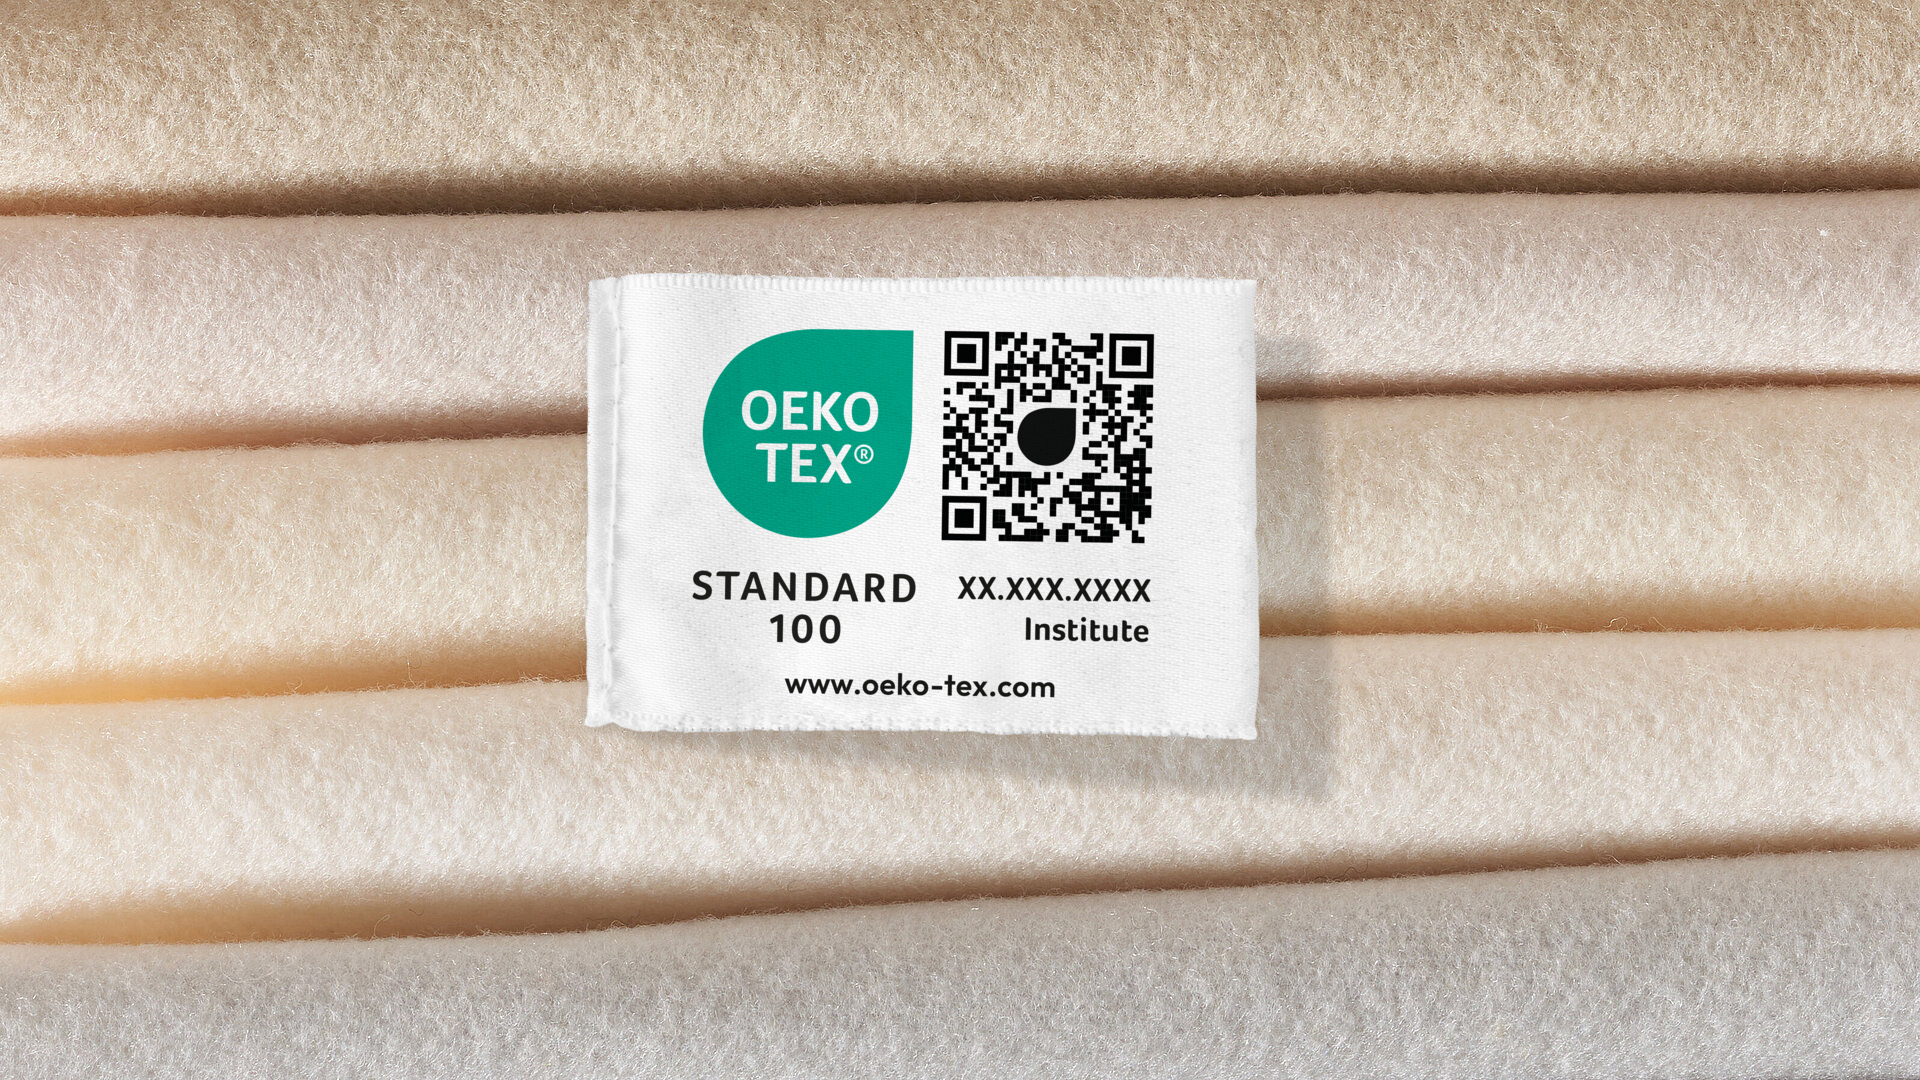
    Standard 100, the core certification from Oeko-Tex, tests raw materials, intermediate goods, and finished items for more than 1,000 harmful chemicals. Criteria cover every component of a finished product, including sewing threads, zippers, and buttons. Limit values undergo mandatory annual reviews. The tightest thresholds apply to baby and toddler clothing up to three years of age.

    Quality control procedures require retesting for 25 percent of all issued certificates each year. The group enforces compliance through unannounced site inspections and factory audits across its global network.

    Supply chain transparency and chemical screening

    The broader Made in Green certification links Standard 100 product testing with facility-level audits under the STeP program. That framework evaluates chemical management, working conditions, and environmental performance inside processing mills and cut-and-sew units. Each certified item carries a dedicated product ID and QR code. Shoppers can use them to track production stages back through the manufacturing chain.

    Rival standards take different approaches. The Global Organic Textile Standard requires a minimum of 70 percent organic fibres, while Bluesign focuses on facility chemical management and specific inputs. Oeko-Tex designed its dual-track testing and facility tracking system to satisfy European regulators demanding end-to-end evidence.

    Garment suppliers and global brands sourcing from manufacturing hubs across Asia face immediate compliance pressure. Exporters operating without accredited third-party verification risk regulatory fines and product suspensions at European ports of entry.

    Governance overhaul and structural separation

    Oeko-Tex revamped its operating structure ahead of the European directive to protect its certification status. In an announcement on Aug. 19, the organization separated standard-setting operations from conformity assessments. The restructuring introduced an independent oversight council and an anonymous whistleblowing platform for reporting compliance breaches.

    Inga Bleyer, head of marketing and communication at Oeko-Tex, outlined the rationale behind the verification drive in an official statement:

    “Trust is not a word you can put on a label. It is built in the places nobody looks: in the button, the zipper, the thread, in the limits we revise every year because the science moves, in a quarter of our certificates we go back and retest.”

    What buyers and suppliers face next

    Chief executive Alfred J. Beerli stated that independent verification remains the only mechanism to safeguard consumer trust under the new regulatory climate. The group’s digital Label Check portal lets retailers and shoppers enter certificate numbers to verify validity in real time.

    European member states must now transpose and enforce national penalties under the directive as customs authorities inspect incoming shipments. Brand compliance audits across autumn and winter retail collections will test how strictly European regulators apply the documentation standards.

  • EU Supply Chain Rules Target 37 Percent of Inaccurate Clothing Labels

    EU Supply Chain Rules Target 37 Percent of Inaccurate Clothing Labels

    European Union sustainability and forced-labour laws will penalise apparel brands and their global suppliers, with new packaging rules rolling out in August. Companies must track materials down to individual farms and component mills. Regulators in Brussels are introducing strict enforcement rules, empowering border authorities to seize non-compliant garments and name offending companies publicly.

    A European Commission testing campaign found that 37 percent of clothing labels failed to reflect material composition accurately. That finding has accelerated regulatory scrutiny across Asian textile export hubs supplying European fashion groups, prompting brands like Tod’s to partner with sustainability-data management firm Renoon.

    Forced Labour Import Bans Target Factory Floors

    The EU Forced Labour Regulation gives European investigators direct authority to inspect supply chains. Officials can ban non-compliant goods from entering the single market. Older disclosure laws required only annual corporate reports. The new framework mandates product-level proof of compliance before shipments clear customs.

    Marissa Brock, senior director of policy and government affairs at supply chain software firm Sourcemap, said: The EU has already indicated that it will target large brands and retailers for forced labor enforcement.

    For manufacturers in China, Vietnam, Bangladesh and India, documentation is now a strict condition for export. Ignorance of subcontracting practices or raw material origins no longer shields buyers or vendors from penalties.

    Digital Passports Shift Burden to Component Makers

    Compliance pressure will mount as the Ecodesign for Sustainable Products Regulation introduces mandatory Digital Product Passports. These digital records attach directly to physical goods. They log raw material extraction, chemical treatments and repairability standards.

    Upstream suppliers carry the operational burden. European fashion houses hold legal liability under EU law. Yet Asian tier-two and tier-three vendors must produce and standardize the operational data required for every production batch.

    Fast Fashion Faces Inspection Bottlenecks

    Standard fast-fashion retailers benefit from agile, digitized supply networks when integrating digital passport systems. Ultra-fast-fashion businesses face acute exposure. Compressed production schedules and minimal chemical auditing create immediate risks for their low-cost models.

    Luxury brands face separate hurdles. Milan courts placed Italian operating subsidiaries of major fashion houses under judicial administration after investigations uncovered illegal subcontracting. High price points do not guarantee upstream transparency.

    Tight Timelines for Single Market Access

    Brussels began applying its Packaging and Packaging Waste Regulation in August. Full enforcement of the Empowering Consumers for the Green Transition Directive takes effect in September. Farm-level traceability mandates under the Deforestation Regulation follow by the end of next year.

    Broader requirements arrive next, with full implementation of the Corporate Sustainability Due Diligence Directive and digital product passport mandates taking effect across 2028 and 2029.

  • Pakistan Textile Exporters Seek 6% to 8% Support Amid Export Slump

    Pakistan Textile Exporters Seek 6% to 8% Support Amid Export Slump

    Pakistani textile makers face a steep decline in goods exports during the second quarter from October to December, driven by weakening Western demand, surging shipping costs, and escalating production expenses.

    According to Pakistan Textile Exporters Association (PTEA) Patron-in-Chief Khurram Mukhtar, ocean freight charges have climbed by 1.5 to 2.5 times, severely squeezing profit margins.

    The downturn is affecting the country’s entire textile value chain, from ginning and spinning to weaving, knitting, and processing, compounded by weak domestic demand amid high inflation.

    Squeezed margins and export rebate demands

    PTEA Patron-in-Chief Khurram Mukhtar said inflation in major Western consumer markets has depressed wholesale orders from international retail brands. Rising input costs and higher transport expenses have also hurt competitiveness. Pakistani apparel and textile goods now struggle against goods from regional manufacturing hubs across South and Southeast Asia.

    To stop factory shutdowns and protect export volumes, the association wants an immediate temporary Duty Drawback of Local Taxes and Levies rebate of 6 per cent to 8 per cent. Exporters are also demanding the quick release of delayed tax refunds across government heads to resolve working capital shortages.

    Mill operators also want authorities to eliminate cross-subsidies embedded in industrial electricity and gas tariffs. They say these surcharges push local production costs above regional rivals.

    Financing bottlenecks hit textile supply chain

    Credit access remains another friction point for garment suppliers. The federal government set a fixed 4.5 per cent financing rate under the Export Finance Scheme in the FY27 Finance Bill. Commercial lenders have not implemented the concessionary rate.

    Banks continue to charge exporters borrowing costs ranging from 5.5 per cent to as high as 8.5 per cent. Mukhtar said approximately Rs200 billion in concessionary financing went to yarn exporters, even though yarn is on the scheme’s negative list. Sugar exporters also received allocations despite operating in a regulated sector.

    Value-added garment producers that beat State Bank of Pakistan mandatory export volume targets by five to six times have been denied loans under the facility.

    Allocations miss export volume reality

    State planners increased credit allocations for small and medium enterprises by Rs300 billion, but industry groups say the qualification rules make the money unusable. Accessing that pool requires incremental export performance of Rs600 billion. Under current global demand patterns, that hurdle is unachievable.

    A previous SME export allocation of Rs100 billion lapsed unused during the prior fiscal year for the same reason. Mukhtar urged the central bank to rebalance credit distribution to match actual trade performance. The country’s top 100 exporters account for up to 60 per cent of total export volume.

    The decline in export trade volume is unprecedented,

    Mukhtar warned that only the most resilient operators will survive current conditions. Lost international retail accounts will prove difficult to recover once global apparel sourcing desks shift contracts elsewhere.

    Modernisation funding and ten-year strategy

    Seeking to prevent broader factory closures, the association proposed a targeted modernisation financing package of Rs140 billion for technological upgrades across four production segments. The plan allocates Rs20 billion each for cotton ginning and sizing, alongside Rs50 billion each for weaving and fabric processing.

    The funds would pay to balance, modernise, and replace aged machinery, deploy automation, and meet international buyers’ sustainability and resource-efficiency standards. Mill groups want the State Bank of Pakistan and the federal government to build this lending framework directly with trade bodies.

    Beyond emergency relief, the association called for a 10-year strategic export blueprint focused on industrial surplus capacity and structural competitiveness reforms. The immediate test is whether the central bank enforces the 4.5 per cent lending cap before second-quarter export data registers the projected downturn.

  • Nine in 10 APAC Consumers to Reconsider Buying from Unsustainable Brands

    Nine in 10 APAC Consumers to Reconsider Buying from Unsustainable Brands

    Around nine in ten consumers across Asia-Pacific plan to stop or reconsider buying from retail brands that fail to prioritise sustainability, Retail Asia reported this week. The regional consumer shift places immediate pressure on consumer goods makers and store operators across major regional markets.

    Shoppers across key Asian metropolitan centres increasingly treat environmental performance as a basic buying criterion rather than an optional marketing feature. Brands that delay operational changes face direct volume losses as regional consumers switch to competitors with transparent practices.

    Shifting Consumer Spending Priorities

    Consumer sentiment across Asia-Pacific retail channels demonstrates a sharp reduction in patience for businesses without visible sustainability targets. Retailers that treat environmental initiatives as secondary risk losing significant portions of their regular customer base.

    The shift affects everyday grocery, apparel, personal care and packaged food categories where substitution is straightforward. In these segments, switching costs remain low and shoppers actively look for clear evidence of responsible sourcing.

    Commercial Risk for Retail Operators

    For store operators and brand owners, customer churn driven by environmental practices creates a direct revenue threat. Retailers operating in competitive urban centres cannot afford to alienate large shares of their shoppers when customer acquisition costs remain elevated.

    Suppliers across regional retail ecosystems must adapt packaging, raw material sourcing and logistics networks to retain shelf placement. Retail chains are increasingly aligning their merchandise assortments with consumer demand for verifiable sustainability credentials.

    Supply Chain and Sourcing Demands

    Consumer pressure now travels directly up the retail supply chain to manufacturers, packaging suppliers and distribution partners. Operators that fail to audit their supply lines face reputational pushback from shoppers who demand accountability across product lifecycles.

    Regional manufacturers that modernise factory operations and reduce waste gain an immediate commercial advantage with retail category buyers. Suppliers slow to provide sustainability disclosures risk removal from mainstream store networks.

    What Retailers Face Next

    Retail networks across the region must balance the capital expense of operational overhauls against the clear cost of customer attrition. Brands that integrate environmental measures directly into product development and store operations will protect market share as consumer criteria tighten across Asia-Pacific.

  • Indonesia Seeks Bigger Role in Asia-Pacific Retail Industry

    Indonesia Seeks Bigger Role in Asia-Pacific Retail Industry

    Indonesia is pushing to expand its footprint and secure a bigger role in the Asia-Pacific retail sector through deeper regional trade ties and cross-border commercial partnerships, ANTARA News reported. The domestic market of over 275 million people remains Southeast Asia’s largest consumer base, giving local operators use as they seek wider influence across regional supply networks.

    Indonesian retailers face direct competition from established operators in Thailand, Malaysia, and Singapore that expanded regional store footprints years ago. Building outward reach requires Indonesian brands to match international standards in supply chain management, inventory systems, and omnichannel fulfillment.

    Cross-border retail expansion across Southeast Asia depends heavily on bilateral trade arrangements and synchronized customs protocols ahead of planned rollouts over the coming fiscal quarters. Indonesian commercial groups want local consumer brands to gain wider shelf space in neighboring shopping centers and digital platforms.

    Regional Trade Integration

    Regional retail groups operate with sophisticated logistics hubs in places like Singapore and Bangkok. Indonesian operators must upgrade warehouse automation and freight links to compete effectively on delivery speed and product freshness.

    Digital Commerce and Store Networks

    Modern trade in Jakarta and secondary Indonesian cities combines physical hypermarkets, convenience store chains, and online commerce. Expanding that model into regional markets requires significant capital commitments from Indonesian conglomerates.

    Foreign retail brands continue to enter Indonesia, attracted by the country’s population of over 275 million people. Local retail groups now aim to reverse that dynamic by exporting homegrown retail concepts, packaged food brands, and lifestyle chains across Southeast Asia.

    Capital Allocation and Expansion Risks

    Entering overseas markets exposes Indonesian retail companies to foreign exchange volatility, varying labor regulations, and shifting local consumer preferences. Capital that goes toward foreign expansion could otherwise fund domestic store rollouts in underserved Indonesian provinces outside Java.

    Landlords and mall developers across Southeast Asia demand proven sales records before offering prime retail space to foreign newcomers. Indonesian brands will need to prove strong unit economics before securing competitive lease terms in prime shopping districts.

    Monitoring the Next Regional Steps

    Indonesian industry associations plan to increase participation in regional retail forums and trade delegations to establish partnerships with overseas distributors. Bilateral retail partnerships and franchise agreements will serve as the primary vehicle for initial store rollouts outside the home market.

    The pace of cross-border expansion depends on regulatory approvals, brand registration timelines, and formal franchise agreements signed over the coming fiscal quarters.

  • Vietnam and Cambodia Trade Hits $8.7B as Both Nations Eye $20B Target

    Vietnam and Cambodia Trade Hits $8.7B as Both Nations Eye $20B Target

    Bilateral trade between Vietnam and Cambodia reached 8.7 billion dollars in the first eight months of 2026. That represents an 8.3 percent increase year on year.

    The pace keeps both governments on track toward their target of 20 billion dollars in annual trade. Last year, bilateral trade reached a record 11.3 billion dollars.

    Vietnamese Customs figures show exports to Cambodia rose 13.8 percent to 4.3 billion dollars between January and August. Imports from Cambodia reached 4.4 billion dollars, up 3.4 percent over the same period. Vietnam currently ranks as Cambodia’s third-largest trading partner, its second-largest supplier of imported goods, and its second-largest export destination.

    Supply Chains and Commodity Flows

    Factories in Vietnam supply Cambodia with industrial inputs and finished goods, including textiles, garments, steel, footwear components, fertilizer, animal feed, paper products, plastics, and industrial machinery. Cambodia sends agricultural commodities and raw inputs back across the border. Shipments to Vietnam concentrate in 14 primary product categories, led by cashew nuts, natural rubber, cassava, rice, timber, fresh produce, and textile materials.

    The flow reflects an integrated supply chain rather than simple merchant trade. Cambodian farms provide raw commodities. Vietnamese processors then package and distribute those goods through domestic retail networks or export them overseas. Linking Cambodia’s agricultural base with Vietnam’s processing capacity and transport network yields higher margins than raw trade alone.

    Investment Capital and Manufacturing Footprint

    Companies from Vietnam hold 223 registered investment projects in Cambodia, representing nearly 3.4 billion dollars in committed capital. These ventures span agriculture, manufacturing, and telecommunications. Together, they employ tens of thousands of workers in Cambodian border provinces and industrial hubs.

    Cross-border manufacturing helps firms diversify production risks while keeping freight costs below distant East Asian supply routes. However, regulatory differences remain a hurdle. Customs procedures, technical standards, and clearance speeds still differ across the frontier.

    Transport Links and Border Infrastructure

    Border infrastructure has expanded to handle heavier commercial freight. Officials opened the Khanh Binh-Chrey Thom international border gate on October 3, 2026, linking Vietnam’s An Giang province directly with Cambodia’s Kandal province. That followed the late 2025 opening of the Meun Chey-Tan Nam crossing between Tay Ninh and Prey Veng.

    Planners now focus on connecting the Ho Chi Minh City-Moc Bai expressway to the Bavet-Phnom Penh expressway corridor. The highway link will cut transit times between southern Vietnamese ports and the Cambodian capital. It will also reduce freight rates and support industrial park development along the route.

    Policy Alignment at the Executive Level

    Government leaders reviewed economic ties at the Vietnam-Cambodia Business Forum in Phnom Penh on October 9, 2026. Vietnamese Prime Minister Le Minh Hung and Cambodian Prime Minister Hun Manet agreed to review trade pacts and eliminate border clearance bottlenecks.

    Negotiators will meet again before year-end to review cross-border trucking permits and customs data exchange protocols.

  • 85 Percent of Indian Shoppers Will Pay More for Natural Fibers

    85 Percent of Indian Shoppers Will Pay More for Natural Fibers

    Eighty-five percent of consumers in India will pay more for apparel made from natural fibers like cotton. The finding comes from research by Cotton Council International and Cotton Incorporated.

    Data from the 2025 Global Lifestyle Monitor survey of 13,026 respondents clashes with factory reality. Synthetic petroleum-based materials account for nearly 70 percent of global textile fiber production today.

    Across the globe, 75 percent of shoppers prefer garments made from cotton, cotton blends or denim over synthetics. Only 7 percent prefer polyester, followed by spandex at 5 percent and rayon at 4 percent. Willingness to pay a premium for natural fibers reached 59 percent globally and 66 percent in Mexico. India recorded the highest willingness worldwide.

    Asian garment manufacturers, spinning mills and retail brand buyers now face a sharp split between cost control and shopper sentiment. Sourcing teams across regional hubs have bought cheaper polyester and synthetic blends to protect margins against price swings. Yet consumer demand in major regional retail markets tilts toward breathability, durability and lower environmental impact.

    Brands that rely primarily on synthetic inputs risk alienating shoppers who distrust petroleum-based fabrics. The survey showed that 83 percent of respondents view cotton and other natural fibers as safe for the environment. Fewer than half held that view for rayon at 48 percent, polyester at 46 percent and Tencel at 41 percent.

    Emissions and Farm-Level Efficiencies

    Jesse Daystar, vice president and chief sustainability officer at Cotton Incorporated, presented field data tracking operational shifts among American growers who supply raw fiber to Asian textile mills. A cradle-to-gate life cycle assessment by WSP USA Inc. Calculated net negative field-to-gin emissions of -0.264 kilograms of carbon dioxide equivalent per kilogram of cotton fiber when factoring in temporary biogenic carbon storage.

    Efficiency gains over the past forty years have reduced the environmental footprint of fiber production at the farm gate. Growers now use precision agriculture, satellite monitoring, soil moisture tracking, flow meters and automated irrigation scheduling across operations.

    “Over the past four decades, U.S. Cotton has reduced soil loss by 45 percent, improved irrigation water-use efficiency by 58 percent, reduced greenhouse gas emissions by 25 percent and improved land-use efficiency by 30 percent,” Daystar said.

    Regenerative farming methods have expanded alongside technological investment. Data from Cotton Incorporated’s 2023 Natural Resource Survey revealed that cover crop usage rose from 20 percent of surveyed growers in 2015 to 48 percent in 2023. No-till and strip-till practices have steadily replaced conventional tillage systems.

    The Synthetic Cost Calculation

    Polyester remains significantly cheaper to produce and procure at scale, keeping synthetic fibers dominant across the market. That cost gap has driven fast-fashion supply chains to increase synthetic volumes across activewear, sportswear and basic apparel lines. This expansion has amplified textile waste problems throughout global supply networks.

    Figures from the United States Environmental Protection Agency indicate that 85 percent of all post-consumer textiles in America end up in landfills each year. Synthetic fabrics shed non-biodegradable microplastics during regular wash and wear cycles. This residue takes centuries to decompose in soil and marine ecosystems.

    Shoppers pick natural fibers primarily for physical comfort and longevity. Among surveyed consumers who prefer cotton, 67 percent cited comfort and 66 percent cited softness. Another 59 percent pointed to product quality, 49 percent selected sustainability and 44 percent pointed to product durability.

    Traceability Across the Asian Value Chain

    Cotton USA executive director Liz Hershfield pointed out that brand procurement decisions directly dictate the financial viability of farming infrastructure. More than 15,000 cotton farms operate across 17 US states. Family-owned businesses run 98 percent of them, absorbing volatile market pricing over consecutive growing cycles.

    Transparency programs such as the U.S. Cotton Trust Protocol provide verified farm-level environmental metrics directly to downstream textile processors and retail brands. Mill operators in Vietnam, Bangladesh and India increasingly require verified field data to satisfy upcoming corporate disclosure rules in export destinations.

    Sourcing executives face a clear choice between short-term savings from synthetic polyester and verified natural fiber sourcing that matches shopper preferences in high-growth retail territories. Purchasing allocations for the upcoming spring 2027 collection cycles will show whether brands are ready to align fiber procurement with these consumer metrics.

  • BYD Builds 150,000Th Commercial NEV as Heavy Truck Output Ramps Up

    BYD Builds 150,000Th Commercial NEV as Heavy Truck Output Ramps Up

    BYD rolled out its 150,000th commercial new energy vehicle at its Huai’an factory in Jiangsu on October 9. The milestone vehicle was a Q3 electric semi-truck.

    Commercial vehicle sales climbed 28.46 per cent year-on-year to 53,032 units across the first nine months of the year. That growth accelerates an operational pivot toward long-haul freight.

    Power Specs and Heavy Freight Demand

    The Q3 tractor unit uses a Blade Battery setup with peak motor output of 600 kW and dual-gun fast charging. Downtime on intercity logistics routes is critical. Battery replenishment speeds determine whether zero-emission heavy haulage can compete on operating margins with diesel equivalents.

    Long-distance road freight demands sustained power output and dense charging support. These requirements create high technical barriers for battery-electric platforms. The company plans to allocate additional capital expenditure to its long-haul heavy truck lines to expand across primary arterial freight corridors.

    Diverging Growth in Vehicle Lines

    Commercial vehicle volumes are outpacing the rest of the manufacturer’s catalog. Deliveries reached 6,848 commercial units in September alone. That figure rose 113.33 per cent from a year earlier, despite easing 0.88 per cent from August.

    Total group deliveries, including passenger cars, slipped 3.94 per cent to 3,131,576 units through September. Institutional fleet replacement cycles and decarbonisation mandates are cushioning commercial transport. These fleet contracts shield heavy vehicles from retail price wars curbing broader consumer demand.

    Logistics Fleet Shifts Across Asia

    Fleet operators across Asia-Pacific face tightening emissions regulations in urban centres and regional shipping hubs. These rules compel logistics providers to electrify their middle-mile and port-drayage fleets. BYD is positioning its heavy-duty trucks against regional diesel incumbents, shifting electrification from municipal transit to private commercial transport.

    Infrastructure hurdles now outweigh vehicle availability constraints for suppliers and fleet managers. Operators adopting 600 kW dual-gun heavy haulers must secure dedicated grid allocations and depot charging hardware. This requirement concentrates operational risk around depot power supply rather than vehicle range alone.

    Global Expansion Beyond Bus Fleets

    Truck production builds on an eighteen-year commercial vehicle programme that started with municipal electric buses. Dedicated truck research began in 2012. The programme gradually broadened into urban parcel delivery vans, cold-chain trucks and heavy port hauliers with battery-electric and hybrid powertrains.

    Production of the T5 light-duty truck crossed the 10,000-unit threshold in 2025, while the smaller T4 platform debuted in export markets. Commercial operations now span more than 70 countries and territories. These global operations include bundled fleet management software, maintenance contracts and depot charging equipment.

    Factory lines at Huai’an are scaling Q3 output as regional logistics firms begin scheduled fourth-quarter fleet replacements across eastern China.

  • Thai Car Plants Prepare to Restart as Flood Delays Ease in Chon Buri

    Thai Car Plants Prepare to Restart as Flood Delays Ease in Chon Buri

    Automakers across eastern Thailand will resume assembly operations on October 14 as component suppliers restore factory lines following late September floods in Chon Buri province. Major vehicle assembly plants had enough buffer inventory to maintain output until October 12 before parts shortages forced brief schedule adjustments.

    The recovery clears a bottleneck across Tier 2 and Tier 3 parts suppliers based inside the Amata City Chonburi Industrial Estate, protecting Thailand’s national target to produce 1.5 million vehicles in 2026.

    Supply Lines Clear in Chon Buri

    Floodwaters have now receded from the industrial corridors in Chon Buri, allowing parts manufacturers to bring technicians back to factory floors. Operations have not returned to full capacity immediately. Teams at dozens of small and medium-sized parts makers are inspecting machinery, rewiring electrical circuits, and reconfiguring logistics routes to move metal stampings, wiring harnesses, and sub-assemblies to assembly plants.

    Disruptions to regional road links briefly cut off parts deliveries from unflooded workshops to vehicle assembly plants across Rayong and Samut Prakan. The supply bottleneck temporarily hit factory schedules for Toyota, Isuzu, Ford, Nissan, and Honda. Assembly lines for battery electric vehicles escaped the disruption because their component supply chains rely on separate battery and motor fabrication lines.

    Combustion Engines Bear the Impact

    Traditional combustion vehicles absorbed almost all the downtime because their manufacturing footprints involve broad networks of domestic subcontractors. Missing a single bracket or fastener stops a finished vehicle from clearing the end of the line.

    Surapong Paisitpattanapong, advisor and spokesman for the Automotive Industry Club at the Federation of Thai Industries, pointed to the structural vulnerability of conventional platforms: An ICE vehicle contains more than 30,000 parts. If even a single component is missing, the vehicle cannot be delivered to customers.

    Assembly operations are structured around tight delivery windows with minimal warehouse holding costs. When water cut road access across parts of Chon Buri in late September, suppliers lost the ability to deliver sequential parts batches directly to factory bays. Carmakers weighed sourcing substitute parts directly from Japan before water levels dropped inside the industrial parks.

    Industrial Landlords Roll Out Rebates

    Industrial park operator Amata Corporation Plc is rolling out financial relief to keep tenants on schedule. The company introduced a 50 per cent reduction or waiver on industrial estate maintenance fees for one year. Factory operators will also receive a 50 per cent discount on utility bills, including industrial tap water, starting in October.

    Amata is also lowering water levels across drainage canals, running continuous drainage pumps, and tracking storm fronts across the eastern seaboard to keep runoff away from factory gates. Total industrial damage across flooded zones reached an estimated 6 billion baht, equal to roughly 178 million dollars, following heavy rainfall across 28 provinces.

    Export Schedules Hold Steady

    Thailand’s automotive sector is defending its role as Southeast Asia’s primary light vehicle assembly hub. The country locked in a total production volume of 1.5 million units for 2026. That plan allocates 950,000 vehicles for overseas export markets and 550,000 units for domestic retail buyers.

    The eastern seaboard assembly belt faced historic flooding risks during previous monsoon seasons, prompting heavy infrastructure investments in industrial drainage dykes. The rapid clearing of water at Amata City demonstrates that localized runoff can be drained before finished vehicle export schedules suffer long-term delivery cancellations.

    Parts makers will spend the coming two weeks running extra weekend shifts to replenish buffer stocks at assembly plants. Factory managers will watch export loading numbers at Laem Chabang port through the end of October to confirm that assembly lines have matched their standard output quotas.

  • Honda to Sell Thai-Built Mitsubishi Pickups in Southeast Asia by 2028

    Honda to Sell Thai-Built Mitsubishi Pickups in Southeast Asia by 2028

    Honda Motor will sell Thai-built Mitsubishi Triton pickup trucks under its own brand across Southeast Asia starting as early as 2028.

    The agreement represents Honda’s first vehicle rebadging arrangement in approximately three decades, putting the company back into commercial utility segments where it lacks dedicated platform architecture.

    Reviving rebadged supply in Thailand

    Under the arrangement, Mitsubishi Motors will manufacture the Triton utility vehicle at its production hub in Thailand, supplying finished units to Honda. Honda will apply its own badging and retail the pickup through its established distribution network in Southeast Asian markets and selected export destinations.

    Sourcing fully built vehicles from Mitsubishi spares Honda the heavy capital expenditure required to engineer a body-on-frame commercial truck platform from scratch. Mitsubishi maintains deep manufacturing scale in Thailand, where its Laem Chabang plant serves as a global export base for one-tonne pickups.

    Defending share against Chinese entrants

    Japanese automakers face intensifying pressure across Southeast Asia, where Chinese original equipment manufacturers have captured rapid market share in passenger electric vehicles. Expanding commercial and passenger vehicle catalogues helps traditional brands protect dealership throughput and service revenues across key territories such as Thailand, Indonesia and the Philippines.

    The risk sits in showroom differentiation. Selling an identical mechanical platform under two competing Japanese badges risks cannibalising existing Triton sales unless Honda targets distinct commercial fleet buyers or alters cosmetic styling and interior specifications.

    Pickup demand across regional showrooms

    One-tonne pickup trucks represent the largest single vehicle category in Thailand, functioning as both work vehicles and primary family transport. While Japanese brands have long controlled more than 80 percent of the commercial truck market in the region, shifts in fleet procurement and new competitive entries have forced legacy manufacturers to consolidate their supply networks.

    Honda has built its regional dominance on passenger sedans, hatchbacks and compact sport utility vehicles. Adding a robust pickup line fills an enduring gap in its commercial retail lineup across suburban and rural dealer networks throughout ASEAN.

    Supply roadmap to 2028 rollout

    Car manufacturers in Japan previously shared passenger and commercial models through original equipment manufacturing arrangements during the 1990s, but Honda largely abandoned cross-badging passenger models to focus on proprietary global architectures. This partnership with Mitsubishi reverses that independent approach in light of shifting regional economics.

    Both companies now face the task of finalising supply volumes, regional homologation schedules and market-specific styling changes ahead of the scheduled 2028 commercial rollout.