Category: General

Retail News Asia is committed to providing both local and global retailers with the latest General Retail news throughout the Asian market. This on a daily base.

  • Transformation in the Thai Retail Market

    Transformation in the Thai Retail Market

    Retail property is one of the most complicated types of real estate development because of the constantly changing behaviours, tastes and needs of consumers. The Thai retail property market has changed enormously over the last 30 years since CBRE established an office in Bangkok and change continues at an even faster rate especially with the growth of E-commerce.

    30 years ago, the Bangkok retail property market was limited to a handful of department stores and a few typical shopping centres like Central Plaza Ladprao completed in 1982, Amarin Plaza completed in 1985 and the original Siam Centre completed in 1977.

    The rest of the retail sector was shophouses and wet markets.

    There are now almost 7.5 million square metres of modern retail property in Bangkok split between department stores, shopping centres, big box stores and other new formats.

    There has been rapid growth and change in the range of retail formats and types of tenant.

    The first 7-Eleven convenience store opened in Thailand in 1989 and there are now 10,268 stores in 2018.

    The first big box store was Makro Ladprao in Bangkapi district in 1989 and now Big C, Tesco Lotus and Makro have over 450 big box stores in Thailand.

    Over the last 30 years we have seen an increased move from traditional retail in wet markets and shophouses to modern retail formats ranging from convenience stores and community malls to giant regional shopping centres such as Central Westgate.

    The modern retail format has spread throughout Thailand with many provincial cities now having modern shopping centres.

    The Thai retail market is, like the rest of the world, facing the new challenge of E-commerce.

    In the UK, E-commerce sales are expected to account for 18% of total retail sales in 2018 and 9.5% in the USA.

    Currently E-commerce sales account for less than 1% of total retail sales in Thailand but this is expected to grow rapidly as E-commerce platforms and infrastructure, including payment systems and distribution have now been established.

    Big players are currently entering the Thai E-commerce market such as Alibaba investing $320 million as well as JD forming a $500 million joint venture with Central Group.

    Retailers will have to adapt to best serve customers in stores and online.

    Retail developers will have to improve the customer experience through design, decoration, events, tenant mix and customer service.

    Retail landlords will have to create a unique environment that focusses on customer experiences. Landlords can achieve this through placemaking in which transforms retail space into “destinations” and “lifestyle centres” to draw more consumers to the area. Landlords may also choose to shift towards greater food and beverage based tenants, such as restaurants, as they provide an experience which cannot be replicated online.

    “clicks” will not totally replace “bricks” but will mean that retailers and retail property developers will have to change.  “Simply building a nice glass box and filling it with brand names, won’t work anymore. “said Ms. Jariya Thumtrongkitkul, head of retail services at CBRE Thailand.“

    Many retailers are trying to pursue an omni-channel approach with both online and offline channels that are fully integrated whereby the digital and physical options complement each other.” Landlords will need to fully integrate the omni-channel approach in which to provide consumers with a frictionless experience across online and offline channels. AI will also have a big role to play in collecting data. Through using interactive apps or customer order history, businesses will also be able to form a more accurate customer profile in which they then can use to personalise their marketing campaigns as well as improving their operations and sales. The use of data can also help retailers better keep up and understand consumer trends and expectations.

    The continuous change in consumer behaviour means that retail property development is much more complicated than office development.  It requires hands on management and constant innovation and improvement.

    The level of commitment and expertise needed is very high and unlike hotels it is rare to subcontract management to a third party in Thailand.

    Even though the economy is improving retailers, retail landlords and developers face big challenges in adapting to the changing environment caused by E-commerce.

    The shopping centre is one of the most successful business models and will not fade away but the competition from E-commerce means that the model will have to evolve to survive.
  • Stocking up on Digitalization to Increase Share-of-Basket

    Stocking up on Digitalization to Increase Share-of-Basket

    With the rise of e-Commerce, Asian retailers are under tremendous pressure to continuously push traditional boundaries and embark on digital transformation to engage consumers. Keeping up with the latest trends in providing the best consumer experience have retailers looking to tech innovations, particularly digital technologies, to play a key role in capturing and keeping customers’ attention and loyalty.

    Technologies such as the cloud, Internet of Things (IoT), mobility solutions, and augmented reality (AR) are driving customer-facing innovations such as digital marketing, smart shopping carts, couponing, and mobile apps – that bring people into the store and keep them coming back. Cloud applications also make it easier for store associates and corporate staffers alike to collaborate and take care of back-office needs.

    The reality is that retailers need to embrace digital transformation and use technology in innovative ways to enhance the customer experience if they want to remain competitive.

    Technology Challenges

    However, rapid adoption of digital in retail not only improves outcomes but ignites new challenges for IT administrators in retail organizations. Among the challenges are how to:

    • Support increased customer engagement with in-store technologies that have high-bandwidth demands
    • Support increasing use of applications in the cloud with a resilient and secure network
    • Ensure connectivity and provide secure access for point-of-sale (POS) applications and electronic payment transactions
    • Ensure performance for real-time applications such as voice, video, and unified communications

    Taking on one of these efforts in the past may have required every resource, but now all of these must be accomplished by the same IT staff.  Also, these changes must be deployed across hundreds and even thousands of store locations spanning vast geographical regions.

    Yet the connective element that brings everything together for retailers –  existing networks are now too complex, too expensive, and frankly, too outdated to support the challenges and opportunities that come from digital transformation. A new approach to the retail network is required.

    With a Virtual Cloud Network, retailers can create an end-to-end software-based network architecture that delivers services to applications and data wherever they are located at global scale from edge to edge, with consistent, pervasive connectivity, and security.

    Faster service delivery on the cloud

    Alfamart in Indonesia is an example of a retailer that embarked on digital transformation by adopting cloud and mobility solutions, and reaped the benefits of a modernized, connected business network.

    Faced with a vast network of over 10,300 minimarts spread across the Indonesian archipelago and basic internet infrastructure in many far-flung areas, it was difficult for Alfamart to convey information in a timely manner across its network.

    The slow flow of information impeded the business’ ability to make critical decisions in a timely manner,  resulting in them not being able to react quickly enough to customer feedback or market trends, and affected overall competitiveness.

    Alfamart decided to connect all of its store employees and partners with a bring your own device (BYOD) strategy and an enterprise mobility management platform over the cloud.

    All store employees are now equipped with the most up-to-date product information, prices and stock level at their fingertips, enabling them to act quickly to meet market trends, and manage peaks in demand for the fast-moving perishable goods they provide.

    This has improved their speed-to-market, reduced training costs by 20 per cent, enhanced mobility across device and platforms, and improved internal communications between management and employees. Customer satisfaction levels have also gone up.

    Keeping systems up and goods in stock at all times

    City Mart in Myanmar is another retailer which benefited from modernizing its legacy IT infrastructure by adopting virtualization. Lengthy downtimes were a common occurrence under their old IT system, which affected their supply chain and resulted in unfulfilled customer orders, negatively impacting revenues.

    The supermarket network implemented a software-defined IT infrastructure and automated certain IT processes, which not only eliminated server downtime but also cut operational expenses by half. Predictive analytics and smart alerts also helped improve the system performance.

    With a new inventory management system, City Mart is now able to gain visibility of their stock across their entire network of 180 stores, whether on storeshelves or in the warehouse. This enabled them to better understand changing consumer demand patterns across different stores, ensure that goods are in stock at all times, and build stronger relations with suppliers.

    Ultimately, the virtualized IT infrastructure supports City Mart’s expanding business, enabling the retailer to meet the needs of Myanmar’s growing consumer class.

    Networking for Retail 2020

    The future of networking is software, and the network of the future is the Virtual Cloud Network. Virtual Cloud Networks allow retailers to create a digital business fabric for connecting and securing applications, data, and users across the entire network in a hyper-distributed world. In this way, retailers can simplify networking and wide area network management, optimize cloud access from all locations, assure high performance for even the most demanding applications, and enforce security and compliance across the network in every store location.


    – Sanjay K. Deshmukh, Vice President and Managing Director, South East Asia and Korea, VMware

  • Hong Kong Top 10 Most Visited Cities in Asia Pacific: Mastercard

    Hong Kong Top 10 Most Visited Cities in Asia Pacific: Mastercard

    Hong Kong is listed as one of Asia Pacific’s top 10 most visited destinations for the eighth consecutive year in the Mastercard Global Destination Cities Index 2018 released. Ranked 14th globally and seventh in Asia Pacific, Hong Kong welcomed 9.03 million international overnight visitors in 2017. Despite dropping a notch from ranking the sixth the previous year, the city saw a slight increase in international overnight visitors from 2016 which saw 8.86 million visitors. Overnight visitor arrivals to Hong Kong are forecast to grow by 0.9 percent in 2018.

    The city is currently at the tenth spot regionally, and is also expected to see 3.78 percent growth in international overnight visitor spending from US$5.92 billion in 2017.

    Ranking the world’s 162 top destination cities, the Index analyzes visitor volume and spending for the 2017 calendar year and provides a forecast for annual growth, insights on the fastest growing destination cities, and a deeper understanding of why people travel and how they spend around the world.

    Global & Asia Pacific Highlights:

     Bangkok remains to be the No. 1 destination city in the world with 20.05 million international overnight visitor arrivals, while London came in a close second with 19.83 million visitors. Paris and Dubai came at the third and fourth spots, with 17.44 million and 15.79 million visitors respectively. Singapore remains at the fifth spot with 13.91 million visitors.

     Forty-eight point five percent of travelers to the global destinations came from China, which ranks at number two among the top origin countries, next to the United States with 57.4 percent.

     Dubai continues to be the top ranking destination city in the world based on overnight visitor spend, having recorded an International Overnight Visitor Spend of US$29.70 billion, followed by Makkah and London with US$18.45 billion and US$17.45 billion each.

     The top three overnight international visitors in Hong Kong last year were from the Republic of Korea (12.9 percent), the U.S.A. (9.6 percent) and Taiwan (9.5 percent).


  • Yonghui, Parknshop and Tencent to jointly establish JV

    Yonghui, Parknshop and Tencent to jointly establish JV

    Tencent has teamed up with ParknShop and Yonghui Superstores to create a new combined grocery chain ParknShop Yonghui. The joint venture, valued at US$170 million, aims to help Shanghai-listed Yonghui expand its business outside of the southern province of Guangdong, as well as consolidating Yonghui and ParknShop’s businesses in the province.

    Yonghui gains half of the joint venture with $89.6 million while ParknShop will hold a 40 per cent stake with cash and equity contributions amounting to $72 million, and Tencent will pay $18 million yuan for a 10 per cent stake.

    Tencent spent $750 million to buy a 5 per cent stake in Yonghui last December, with ambitions to shake up the bricks-and-mortar shopping market and compete with rival Alibaba Group.

    Yonghui operates more than 830 supermarkets in 24 provinces, 21 of them in Guangdong.

    ParknShop, a member of the AS Watson Group, has more than 50 shops in the southern province.
    This is the first time companies within the group have formed a joint venture with mainland Chinese firms.

  • Vietnam to cut dependancy on crude oil

    Vietnam to cut dependancy on crude oil

    A prime ministerial advisory body has said the state budget is overly dependent on crude oil, an unsustainable income source. The National Financial Supervisory Commission (NFSC) recently said crude oil is not a sustainable income source, both in the short and long term.

    In the short term, crude oil revenue can be affected by global oil prices and mining output; and the state budget has been significantly impacted by such fluctuations over the years, the NFSC noted.

    In the long run, this source of income is also unsustainable as national reserves are limited, it added.

    Earlier, Deputy Prime Minister Vuong Dinh Hue had said at a meeting of the legislative National Assembly that Vietnam needs to stop relying on crude oil and focus on tourism to ensure its economic growth.

    “It is better to welcome one million tourists than trying to find one million tons of crude oil because tourism is more eco-friendly and safe for the economy,” he’d said.

    Vietnam’s September crude oil exports totaled 375,000 tons, down 21.1 percent year-on-year, according to the General Statistics Office. This brought crude oil exports in the first nine months of this year to 2.97 million tons, down 45.2 percent from a year earlier.

    From early this year to September 15, accumulated budget revenue is estimated to be at VND898.3 trillion ($39.06 billion), of which VND43.5 trillion ($1.89 billion) or about 5 percent comes from crude oil, according to the General Statistics Office.

    Vietnam’s domestic crude oil production reached its peak in 2004 with an output of more than 20 million tons, but has declined to an estimated 14.2 million tons in 2017.

    It is forecast that around 11 million tons will be produced in 2018. Crude oil exports have contributed 0.25 percent to the country’s GDP in recent years.

  • Vietnam’s authority no longer certain about 2020 GDP target

    Vietnam’s authority no longer certain about 2020 GDP target

    Vietnam’s GDP per capita is set to increase this year, but its 2020 target of $3,200-3,500 looks distant. Minister of Planning and Investment Nguyen Chi Dung said at a National Assembly meeting Monday that if Vietnam’s GDP increases by 6.7 percent this year, per capita GDP will reach $2,540, up $155, or 6.1 percent year-on-year, and 1.21 times that of 2015.

    However, the number is still far away from the country’s target of $3,200-3,500 by 2020, he conceded.

    According to World Bank Group statistics, Vietnam’s GDP per capita in 2017 is $2,343. The figure for Singapore is $57,714, Malaysia ($9,945), Thailand ($6,594), the Philippines ($2,989) and Myanmar ($1,298).

    Minister Dung estimated that Vietnam’s GDP would grow by 6.57 percent on average in the 2016-2018 period, meeting the National’s Assembly target of 6.5-6.7 percent growth.

    However, he expressed concerns about the increasing number of businesses that stopped operations in the first nine months of this year.

    While 96,610 new businesses opened, 73,100 closed, up 48 percent year-on-year.

    These figures worried government officials at the meeting. Vu Hong Thanh, Chairman of the National Assembly’s Economic Committee, said that the goal of having one million businesses by 2020 will be “difficult to achieve.”

    Last year Vietnam had over 560,000 active businesses, up 11 percent year-on-year, according to the General Statistics Office.

    But in another meeting last week, Deputy Prime Minster Vuong Dinh Hue said that the goal “is full of challenges, but achievable.”

    Hue said that how strong these businesses are and how much they can contribute to the economy is more important.

    “The government aims to practically improve the business environment by not imposing more conditions,” he said.

    In the first nine months this year, Vietnam’s GDP grew by 6.98 percent, the highest nine-month growth rate since 2011. The economy grew by 6.81 percent last year, the highest rate in a decade.

  • Vietnamese taxi firm to get support in lawsuit against Grab

    Vietnamese taxi firm to get support in lawsuit against Grab

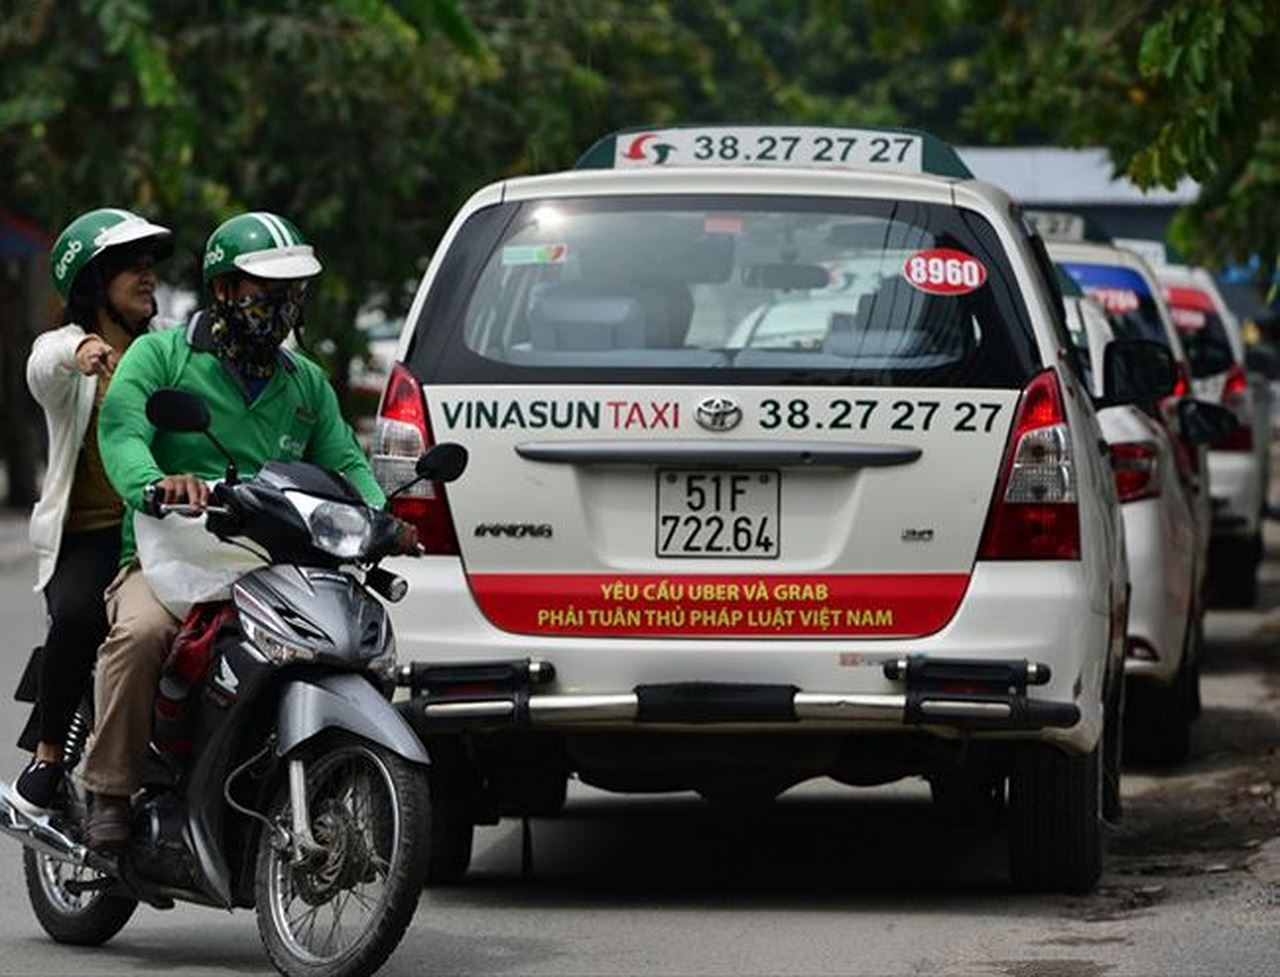
    Prosecutors have argued in a trial in HCMC that Grab must pay Vinasun compensation for losses it caused through “unhealthy competition.” At a hearing Tuesday the city People’s Procuracy rejected ride-hailing firm Grab’s argument that the court had no jurisdiction over the case, saying it does since it is a commercial dispute.

    Prosecutors also asked the judges to deny Grab’s request to summon representatives of Vietnam’s Ministry of Transport, other companies participating in the ministry’s pilot scheme for ride-hailing services and the company responsible for estimating Vinasun’s losses.

    As for Grab’s claim it is a tech firm and not a taxi company, they said since the firm directly assigns drivers, sets fares, sets regulations for drivers, and offers promotions, there is enough reason to dismiss this too.

    “Vinasun’s demand for compensation for reduced profits is well founded since Grab was dishonest in its business declaration and ran promotions in contravention of regulations, causing over 70 percent of Vinasun’s customers to switch to Grab due to lower fares.”

    Vinasun’s after-tax profit was nearly VND320 billion ($13.7 million) in 2015 and VND295 billion ($12.63 million) in 2016, but dropped to VND53 billion ($2.27 million) in the first half of 2017, by which time over 8,000 drivers had quit and hundreds of cars had stopped running due to a lack of drivers.

    Prosecutors asked the court to accept Vinasun’s petition for compensation of VND42 billion (nearly $1.8 million) in one payment.

    Grab continued to insist the case did not come under the court’s jurisdiction and that it is a tech firm.

    Dismissing the claim it had caused losses to Vinasun, Grab cited market research purporting Vinasun has been losing customers due to other reasons such as driver’s attitude, long waiting time and declining car quality.

    Vinasun filed the suit against Grab at the HCMC People’s Court in June last year accusing the Malaysia-based firm of abusing the Ministry of Transport’s pilot scheme and committing violations.

    Claiming Grab’s illegal activities had caused damages to it, Vinasun claimed to have suffered losses of nearly VND76 billion ($3.25 million) in 2016 and the first half of 2017, of which nearly VND42 billion (nearly $1.8 million) was caused by Grab.

    The trial began last February, but was first adjourned a month later due to the need for more evidence and again last month when Grab protested against the evaluation of Vinasun’s losses and refused to attend.

    The court is scheduled to hand down its verdict next Monday.

  • Lotte pledges 50 trillion won investment

    Lotte pledges 50 trillion won investment

    Lotte Group announced Tuesday a major investment plan to spend 50 trillion won ($43.9 billion) and hire 70,000 workers over the next five years. “The plan comes in order to normalize management activities, obtain a competitive edge for future growth and contribute to vitalizing the local economy,” Lotte said in a statement.

    The announcement comes on the heels of similar plans announced by other conglomerates like LG, Shinsegae and Samsung. Lotte couldn’t join that wave because Chairman Shin Dong-bin was sentenced to 30 months in prison last February for bribing former President Park Geun-hye. On Oct. 5, the Seoul High Court replaced the prison sentence with four years of probation, and Shin returned to work three days later.

    Lotte announced an investment plan of 40 trillion won in 2016. But most of the investments couldn’t be executed after the group was badly affected by the deployment of a U.S. antimissile system in Korea in 2017 on a golf course formerly owned by the group and a Chinese boycott against Lotte that followed. Shin’s imprisonment earlier this year also got in the way.

    Execution of the 50-trillion-won plan will start next year. A 12 trillion won budget is planned for 2019, a record for the conglomerate.

    The two sectors that will receive the greatest attention are chemicals and retail. Some 40 percent of the investments will be in chemicals and 25 percent in retail. Lotte grew to its current size thanks to food and retail, but in recent years, the company has been active in developing the chemical business.

    For chemicals, investments will focus on expanding local and overseas manufacturing facilities. The group currently has factories in three locations in Korea, which Lotte said will be expanded.

    Investments in overseas facilities will also be made to expand the company’s businesses abroad. Lotte Chemical has a $4-billion project in Indonesia that was put on hold when Shin was jailed. A source at Lotte said, with Shin back in the saddle, resuming the project won’t take long.

    The main goal for investments in retail is improving the infrastructure for e-commerce. Lotte said in a statement it plans to establish logistics and computing infrastructure to offer a more convenient experience for shoppers online and off.

    Tech development and enhancing the level of digitalization is a long-term goal across the conglomerate’s affiliates. For example, Lotte wants to apply tech to its food business: Artificial intelligence technology is underway to be used for trend analysis and to suggest new products.

    Indonesia and Vietnam will be two foreign markets Lotte’s affiliates will focus on. The company once had a huge footprint in China, but Beijing unofficially retaliated against Lotte after the deployment of the antimissile system in Korea. The company added in the statement that it would continue discovering new markets.

    The goal for new jobs in 2019 is 13,000, which is 10 percent higher than what Lotte plans to hire this year. Many hires will be in the e-commerce sector.

  • Two thirds of the company wrong in measuring customer loyalty

    Two thirds of the company wrong in measuring customer loyalty

    A commissioned study conducted by Forrester Consulting on behalf of Collinson, a global leader in loyalty and benefits, reveals that the majority of organisations do not understand what is driving customer loyalty, and are therefore putting customer relationships and profitability at risk.

    Surveying decision-makers in organisations with revenue exceeding US$300 million, respondents graded their programmes based on a series of measures and also shared their key goals and challenges. The study surveyed and compared the results for a multitude of countries and regions in Asia Pacific (APAC), including Hong Kong, mainland China, Singapore, Indonesia, Japan, Korea and Australia.

    The research found that two thirds (65 per cent) of those surveyed markets in APAC do not understand why their customers are loyal to their organisations. Almost 7 out of 10 (67 per cent) reported that they do not have a proper framework in place to measure loyalty in the context of overall business performance. Remarkably, the research also found a misalignment between the loyalty objectives and the measurement criteria used to determine the effectiveness of their loyalty success.

    Three reasons why organisations may be struggling with customer loyalty

    1. Loyalty strategy without clearly defined business objectives and appropriate metrics

    Loyalty success is led by a holistic loyalty strategy with clear defined goals and measurement framework which needs to be embedded consistently across an organisation.

    Less than half (49%) of the APAC respondents have clearly defined business goals and objectives to define their loyalty proposition, where Hong Kong and Japan have the highest percentage (55%) compared with 39% of respondents in Singapore. Only 40% have cohesive customer loyalty strategy that spans multiple functions and is a top strategic initiative with C-level support.

    From the research, we found there is a clear discrepancy between what people are trying to achieve through their loyalty programmes and the KPIs in places to measure the performance in relation to their objectives.

    The key loyalty objectives and performance metrics shared by our respondents for their customer loyalty programme in APAC are misaligned as shown below:

    Key loyalty objectives The metrics for measurement
    1 Acquiring new customers (53%) Customer satisfaction (62%)
    2 Retaining existing customer (47%) Customer engagement (59%)
    3 Enriching customer relationships (46%) Customer retention rate (57%)
    4 Improving the customer experience (37%) Loyalty programme enrolments (57%)
    5 Increase customer advocacy (35%) Sales & revenue (57%)

    Without appropriate metrics, it could be difficult to know which areas need improvement and understand the impact of customer loyalty on overall business performance.

    1. Without a single customer view to harness data potential

    To appeal to the modern, choice-rich consumers, it is important to engage them at an individual level which means collecting all appropriate data across the customer journey.

    The research found that three-fifths (60%) of respondents in APAC do not have centralised business rules to incorporate all sources of customer data into a single customer view. Less than a half (48%) collect a wide enough range of customer data to run deep analyses, where only 26% of them automate advanced data analytics to optimise their customer strategy, and 35% would use predictive modelling to identify the right existing dynamic content based on customer behaviour.

    Predictive modelling enables brands to make better decisions and run more effective programmes where China has the highest percentage (47%) compared with the rest of respondents in Asia Pacific to harness the value of data for providing personalized offers for each member. It is vital to recognise each customer preference and behaviour to provide a personalised experience that stands out from the competition. This can only be done when brands continuously collect the right information about their customers and using it effectively, to understand what makes them tick.

    1. Competitive differentiation

    Loyalty programmes with reward, point and VIP schemes have been pervasive for years. These tactics are still frequently employed, but the effectiveness is uncertain when they are deployed without a sound loyalty strategy. From the research, we found that brands continue to see competitive differentiation as being vital, with two thirds (66%) of loyalty practitioners in APAC reporting that is a critical or high priority.

    72% in Asia Pacific, 78% in Hong Kong, Indonesia and Korea respondents planned to increase funding for developing new loyalty programme benefits and rewards.  Embracing partnerships with like-minded brands, who can offer unique experiences and access to their customer base, will enhance and strengthen the member’s engagement. It enables partner brands to expand their knowledge of the customer through an integrated cross analysis of buyer behaviour and preferences for personalized, curated communications to increases sales leveraged through the partnership.

    Mary English, Executive Vice President, APAC of Collinson, says, “A clearly defined loyalty strategy provides the foundation to design a proposition for continuous engagement with your customers in a relevant and meaningful way. Data is the fuel for ongoing loyalty to a brand with heavy weighting on a well-structured single customer view to capture, measure, gain insights, and personalise the dialogue with their customers.  Organisations need to put loyalty back on track by becoming better aligned in terms of their objectives, what they measure, and how to differentiate their programmes. There is really no ‘one size fits all’ approach and each organisation must identify their brand’s unique, valuable assets in formulating a strategy that is regularly reviewed and updated to the changing behaviours of their customers.”

    “Creating formalised processes and employing dedicated resources can be a valuable investment and demonstrate your company’s commitment to loyalty. It is logical for companies to consider ‘connected loyalty’ as a goal of their strategy. Customers who feel connected to the organisation become fans, not just purchasers of their products and services. The latter may simply be shopping out of habit or convenience, whereas fans will go out of their way for the brands they love.”

  • Nok Air launches international direct flights from Phuket to Chengdu

    Nok Air launches international direct flights from Phuket to Chengdu

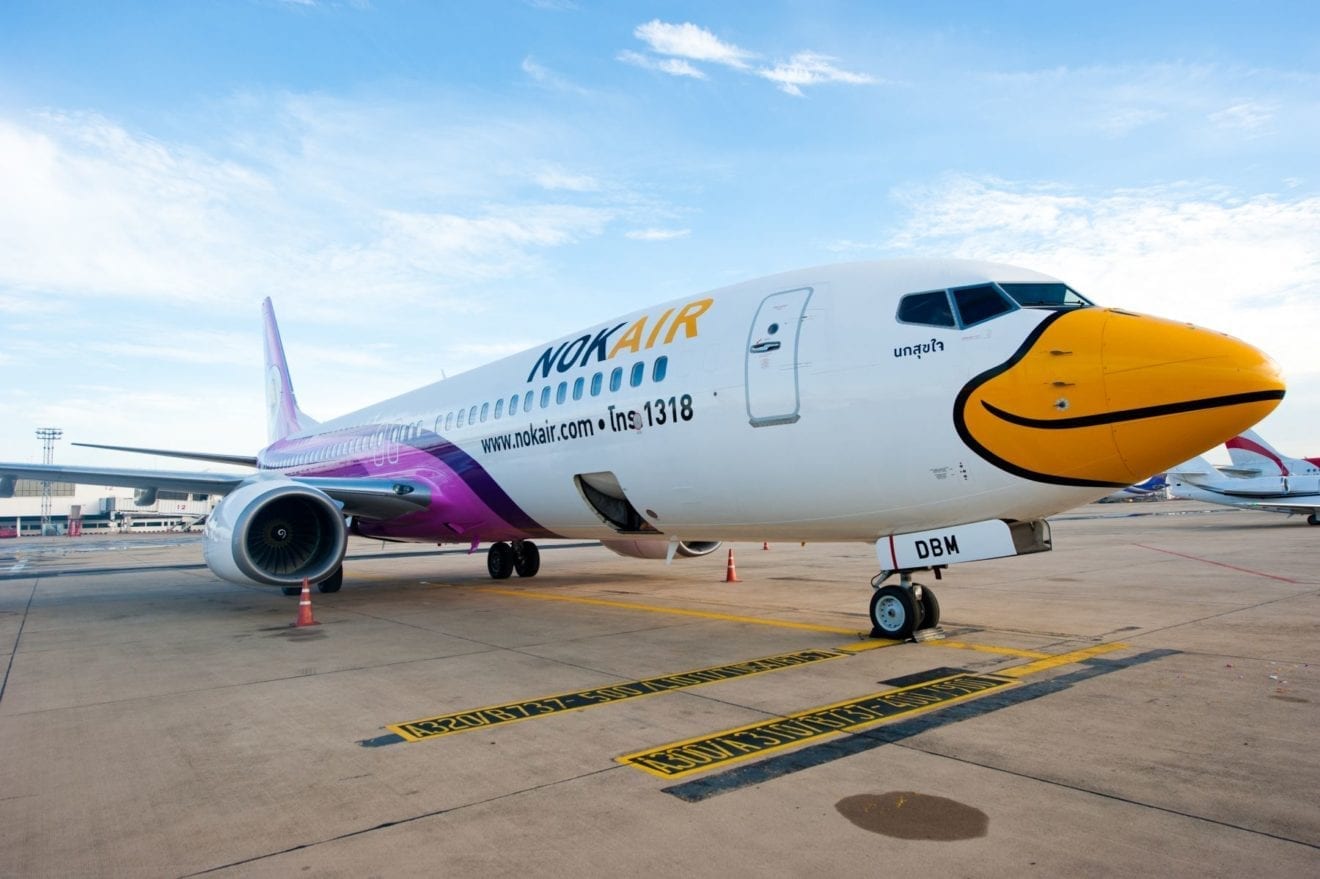
    Nok Air launches the daily international direct flight, Phuket-Chengdu, aiming to offer passengers the most impressive travel experience Nok Air always commits itself to impress all travelers lifestyle. To offer Chinese passengers the best experience, Nok Air has just launched the new daily direct flight from Phuket to Chengdu, China, 7 flights a week (1 round-trip flight/day) starting from 4,000 baht with free of charge baggage allowance of 20 kilograms and free Royal Orchid Plus (ROP) mileage earning from THAI Airways.

    Nok Air also provides various routes to China which include Zhengzhou, Nanning and ‘Phuket-Chengdu’ as the latest one with more than 500,000 Chinese passengers in the last year.Phuket-Chengdu and Chengdu-Phuket tickets are available on www.nokair.com from October 8th 2018.

  • Korean companies in China becoming less optimistic

    Korean companies in China becoming less optimistic

    Korean companies operating in China are less optimistic about business conditions in the fourth quarter of this year, as the Chinese economy is cooling amid a trade spat with the United States, a survey showed Sunday. According to the Korea Institute for Industrial Economics and Trade (KIET), its business survey index (BSI) stood at 103 for the October-December period, down 12 points from the previous quarter.

    A BSI reading above 100 means optimists outnumber pessimists. The BSI for the sales outlook was also still over 100, but came in at 117, down 8 from a quarter ago.

    By sector, electronics, electric and retail were more pessimistic about the fourth quarter, while automaking and textiles remained bullish over business conditions in China.

    Last week, China reported its weakest quarterly growth since the first quarter of 2009, during the global financial crisis.

  • Li & Fung to have new COO

    Li & Fung to have new COO

    Weizhong Zhu (“Wilson”) has joined Li & Fung as Chief Operating Officer (COO) and will lead operations across all Li & Fung’s 40+ production countries. As Li & Fung pushes ahead on its digital supply chain strategy to build the Supply Chain of the Future, Wilson will focus on strengthening the Company’s production platforms globally, ensuring consistent KPIs and driving operational excellence to improve customer service.

    A 31-year industry veteran, Wilson brings deep expertise in international trade relations and supply chain for retail and consumer products.

    His vast industry experience includes Chief Sourcing and Production Officer at Gymboree, EVP for Private Brand and Global Sourcing at Michaels Stores Inc, VP of Private Brand and Global Sourcing at Office Depot, and VP for Global Sourcing at Hudson’s Bay Company.

    Most recently, Wilson co-founded Cooper Aerobics Wellness Center in China, the first fitness and wellness center of its kind in China, and prior to that, he served as Chairman and CEO of inQbrands, where he led the transition of the US subsidiary of China-based Focus Technology into a full-service brand and product agency.

    “With the ongoing US-China trade war, Wilson’s leadership comes at a critical time as our customers rely on our scale and expertise to deliver alternative sourcing strategies and mitigate any potential risk in their supply chains” said Spencer Fung, CEO of Li & Fung.

    Wilson Zhu received his Master of Arts degree in Language and International Trade from Eastern Michigan University in 1987.

    Passionate about sharing knowledge and ideas, Zhu was a columnist for China’s New Fortune business magazine from 2013 to 2016 and regularly contributes to other media outlets on globalization, retail, management, branding and China-US trade relations.

  • Tigerair receives most complaints for sixth year in a row

    Tigerair receives most complaints for sixth year in a row

    For the sixth year, Tigerair has scored the dubious title of being the most complained about airline in Australia. The recent data by the Airline Customer Advocate, from January to December 2017, which has gone largely unreported, revealed the low-cost carrier had the highest rate of complaints in relation to flight cancellations or delays — with an average of two complaints for every 100,000 passengers.

    Overall, the most common complaints among Australian domestic carriers related to flight cancellations (28 per cent), refund requests (26 per cent), baggage services (11 per cent), loyalty and frequent flyer programs (10 per cent) and fees or charges (7 per cent).

    The annual report revealed a total of 1253 complaints out of more than 77 million passengers were received in 2017, which was up 17.15 per cent on the previous year. 

    Tigerair also received the highest complaints in relation to refund requests — with an average of 1.54 complaints for every 100,000 passengers.

    A Tigerair spokeswoman said the airline was committed to delivering a safe and reliable service to its customers.

    “In aviation there are times when things go wrong for reasons outside of our control and we recognise that the way we handle such disruptions is an important part of the customer experience,” the spokeswoman said.

    Virgin Australia was next with 0.42 complaints relating to refund requests, followed by Jetstar with 0.36, Qantas with 0.31 and Regional Express with 0.24.

    Virgin Australia fared the worst when it came to complaints about baggage services, receiving an average of 0.24 for every 100,000 customers, It was followed by Jetstar and Tigerair with 0.17, Qantas with 0.14 and Regional Express with 0.08.

    Of the three airlines that offer frequent flyer or loyalty programs, such as Qantas, Virgin Australia and Jetstar, the most complaints were lodged against Qantas. Airline Intelligence Research managing director and former Qantas chief economist Dr Tony Webber said he wasn’t surprised that cancellations and delays were the biggest gripes among passengers. 

    “Tigerair are on really strict turnaround times given that they’re a smaller and low-cost carrier,” Dr Webber told.

    “This means that they’re just as strict on refunds because the ability for passengers to buy a cheap fare means that they don’t get a refund.”

    Dr Peter Bruce, airline operations expert at Swinburne University, said some airlines outsource their baggage handling to third-party services. 

    “Areas of improvement could definitely include better engagement with these services to create more efficiency,” Dr Bruce told.

    Monash University’s Professor Greg Bamber, who has researched airline performance in Australia and overseas for more than 15 years, said complaints needed to be handled better by low-cost carriers. 

    “Passengers aren’t being dealt with appropriately as they’re usually put through to a call centre which is usually in another country,” Professor Bamber told.

    Passengers are usually left to wait on hold, in some cases more than an hour, he said.

    “Low-cost carriers need to step up and handle complaints more appropriately, especially when it comes to cancellations which can be extremely frustrating.”

    A Virgin Australia spokeswoman said the airline continually reviewed its complaint-handling practices to facilitate a responsive and positive experience for its customers and to ensure it was complying with its legal obligations.

    A Jetstar spokesman said the airline still had areas to work on, but was pleased to see a reduction in the number of complaints in a number of key areas including delays and cancellations, refund requests and fees or charges.

  • Airasia To Launch Colombo-Bangkok Direct Flights Soon

    Airasia To Launch Colombo-Bangkok Direct Flights Soon

    AirAsia will launch four-time weekly direct flights between Colombo and Bangkok from December 14, with a special promotional fare, an airline press release said. Operated by Thai AirAsia (flight code FD), this direct route to Bangkok in Thailand will be the airline group’s second connection from Colombo’s Bandaranaike International Airport which includes direct route to Kuala Lumpur, Malaysia (flight code AK).

    Santisuk Klongchaiya, Chief Executive Officer of Thai AirAsia said, “Sri Lanka has always been a promising destination for AirAsia as we have connected the country to a wider network via Kuala Lumpur for nearly a decade. To This time we are relaunching the flight from Colombo to Bangkok to provide the people of Sri Lanka with even greater connectivity that comes with attractive low fares to create more demand. We are strongly confident that our return to the market will stimulate travel appetite and demonstrate our commitment to generating more traffic to Sri Lanka to fuel tourism and economic growth for the country. Sri Lanka is such a hidden gem in South Asia with undiscovered potential. We therefore have high expectation for a healthy market reception for this new route.”

    Thai AirAsia operates the widest network in domestic Thailand and offers several international connections to other prominent cities in Asia. Travellers from Sri Lanka who wish to explore beyond Bangkok can enjoy a convenient Fly-Thru service with just a single-time baggage check-in from Colombo and make a brief transit in Bangkok to continue seamlessly to other destinations in Thailand and beyond. Sri Lankan travellers can take advantage of the convenient flight schedule that gives them more time to spend abroad by arriving in Bangkok in the early morning and depart in the evening.

  • AirAsia to launch start Manila-Shenzhen direct flights in December

    AirAsia to launch start Manila-Shenzhen direct flights in December

    AirAsia said Monday it would fly direct between Manila and the Chinese city of Shenzhen, dubbed Asia’s answer to Silicon Valley, starting December 1.

    The low cost carrier started its Cebu-Shenzhen flights last April. Without direct flights, travelers had to travel to Hong Kong or Beijing before reaching Shenzhen.

    “China is an important market for us and we are looking to expand our network further and connect Filipino travelers to new and exciting business and leisure cities,” said AirAsia Philippines CEO Dexter Comendador.

    Telecommunications companies Huawei and ZTE are headquartered in the southern Chinese city.

    AirAsia will fly direct to Shenzhen every Tuesday, Thursday, Friday and Saturday. Direct flights from Cebu to Shenzhen are also on Tuesday, Thursday, Friday and Saturday.