Category: Research

Retail News Asia is committed to providing both local and global retailers with the latest Research throughout the Asian market. This on a daily base.

  • Global ad revenue on pace to $590b in 2017

    Global ad revenue on pace to $590b in 2017

    Big brand budgets and quadrennial events such as the Olympics, European Football Championship and US presidential election will drive 2016’s global advertising revenue growth to $532 billion.

    The advertising industry is about to turn the corner thanks to the global economy getting back on track, according to a new report released by IHS Markit.

    Advertising revenue will grow 7.1% in 2016 to $532 billion. Strong growth in global real private consumption also buoyed advertising revenue as brands tried to take advantage of heightened consumer spending. Advertising revenue accounted for 0.69% of global GDP in 2016, up from 0.66% in 2015, the report said.

    Top 10 markets

    The top 10 markets make 75% of the global revenue figure. The top 10 markets still account for the lion’s share of global advertising revenue. However, their collective power has dropped due slowdowns in the Chinese and Brazilian economies, which were the rising stars in the top 10 in 2015.

    The top 10 accounted for 76% of global ad revenue in 2015; it dropped to 75% in 2016.

    Four out of the five fastest growing countries in 2016 were in Africa. Ghana and Kenya have been high on the list of many media companies’ expansion plans, and we are seeing growth above 20%. These markets are still growing from a low base, but the sheer size of their populations means they are becoming interesting targets for big brands.

    TV remains number one, but online will overtake by 2020

    TV was the number one medium globally for advertising revenue, accounting for $192 billion, or 36%, of global revenue. Despite the incredible growth of online giants like Facebook, Google and Snapchat, the TV market continues to benefit from big brand budgets. Quadrennial events such as the Olympics, the European Football Championship and the US elections helped keep TV on top.

    However, revenue from online advertising will overtake TV within the next five years. In some countries such as the UK, online already accounts for almost 50% of total advertising revenue and will only keep getting stronger.

  • Global device sales set to stay flat until 2018

    Global device sales set to stay flat until 2018

    Worldwide combined shipments of PCs, tablets, ultramobiles and mobile phones are projected to remain flat in 2017 with 2.3 billion units, according to Gartner.

    There were nearly 7 billion phones, tablets and PCs in use in the world by the end of 2016. However, Gartner does not expect any growth in shipments of traditional devices until 2018, when a small increase in ultramobiles and mobile phone shipments is expected.

    “The global devices market is stagnating,” said Ranjit Atwal, research director at Gartner. “Mobile phone shipments are only growing in emerging Asia-Pacific markets, and the PC market is just reaching the bottom of its decline.”

    Atwal said that aside from declining shipment growth for traditional devices, average selling prices are also beginning to stagnate because of market saturation and a slower rate of innovation.

    “Consumers have fewer reasons to upgrade or buy traditional devices,” he said. “They are seeking fresher experiences and applications in emerging categories such as head mounted displays (HMDs), virtual personal assistant (VPA) speakers and wearables.”

    Gartner sees the PC market benefiting from a replacement cycle toward the end of this forecast period, returning to growth in 2018. Increasingly, attractive premium ultramobile prices and functionality will entice buyers as traditional PC sales continue to decline.

    The mobile phone market will also benefit from replacements. There is, however, a difference in replacement activity between mature and emerging markets.

    “People in emerging markets still see smartphones as their main computing device and replace them more regularly than mature markets,” said Atwal.

    Device vendors are increasingly trying to move into faster-growing emerging device categories.

    “This requires a shift from a hardware-focused approach to a richer value-added service approach,” said Atwal.

    “As service-led approaches become even more crucial, hardware providers will have to partner with service providers, as they lack the expertise to deliver the service offerings themselves.”

  • Why omni-channel payments need to be the new norm in retail

    Why omni-channel payments need to be the new norm in retail

    Electronic payments account for 69%1 of consumer transactions in Singapore – just slightly higher than the global average of 65%. The country’s e-commerce market, valued at US$1.39b in 2015, is predicted to exceed S$7b in 2025 with 60% of consumers saying they bought products online at least once a month2 – some even showing a growing preference to shop online and pick up their purchases in-store.

    Consumer buying habits aren’t rooted solely at retail locations or online. They shift between retail stores at malls, smartphones, laptops, and transient, yet trendy, pop-ups. In other words, consumers are omni-channel shoppers. So why haven’t payment systems followed in the same direction?

    In Singapore, it’s a common sight to see retail counters with multiple terminals serving different modes of payment: one for credit cards, another for debit cards, yet another for contactless payments. On the back-end, business owners spend hours liaising with various vendors, different banks, grappling with multiple platforms and numerous devices.

    Businesses could instead integrate payments across multiple platforms – increasing efficiency and profits by adopting a seamless, omni-channel payments system. In doing so, they would be able to process payments with greater speed and efficiency saving time and resources in their back-offices, leverage integrated data for actionable insights, and offer customers a seamless, integrated experience.

    1. Greater efficiency
    70% of businesses surveyed in a KPMG report agreed that there are simply too many payment methods to deal with. Many retailers have multiple banking contracts and relationships across Singapore to manage, each of which provides part of the company’s in-store payment solution. This represents an enormous investment in managing reports and financial flows.

    By adopting omni-channel payments, businesses will be able to work across a single centralised platform that enables businesses to accept and process payments across multiple markets. In doing so, retailers can drastically simplify these processes, cut down on the human resource and financial investments needed to manage their payment acceptance.

    2. Leverage data for actionable insights
    The use of technology and data allows local retailers to gain business intelligence and insights into areas such as purchasing habits. Integrating payments from the point-of-sale (POS) system with accounting software or customer relationship management (CRM) systems to capture disparate pieces of information enables retailers to better serve their customers. Leveraging insights gleaned from payment information, retailers can decide when and who to offer discounts and deals to drive sales.

    Having access to cross-channel shopper data gives merchants a treasure trove of information that can be analysed for patterns online and offline. They can then mine this information for customer retention and loyalty marketing. Many merchants are already beginning to offer their customers an omni-channel shopping experience and in doing so significantly improve the shopper experience.

    An example: a shopper makes a number of purchases from an e-commerce site. Several months later, she goes shopping whilst on vacation. At the checkout, the terminal recognises the shopper’s card, and the staff member adds a discount and a personal thank you thus delighting the customer with an even more seamless, personalised experience.

    3. Seamless customer experience
    Businesses need to recognise that the customer journey today is fluid, accessible, and continuous. Shoppers can, and want, to purchase whatever they want, without restrictions on time, location, and across social, online, and mobile channels.

    Businesses too need to provide a seamless experience and allow customers to start a purchase in the channel of their choice and complete it in a potentially different channel of their choice.

    Here’s what a customer journey might look like: a shopper goes into a store and wants a shirt in a different colour than what’s currently available in-store. If a store has adopted an omni-channel approach, the shopper can go to the in-store tablet-assisted sales terminal that carries the entire web-based inventory, choose the colour they want, make the payment on the spot, and have it delivered to the address of their choice.

    Omni-channel payments enable retailers to service customers across multiple channels (in-store, online, or mobile); retail sectors, payment types (NETS or debit and credit cards), and payment methods (contactless, chip and PIN, magnetic and online) through mobile point-of-sales devices, payment gateway, or virtual terminal. In doing so, the store has gained a purchase rather than losing an opportunity.

    With discerning consumers becoming increasingly accustomed to omni-channel payment capabilities, it will transform “the next big trend” into “the new norm” for consumers in Singapore.

    1.https://newsroom.mastercard.com/asia-pacific/press-releases/singapore-among-top-markets-in-asiapacific-advancing-towards-a-cashless-society-new-mastercard-report/
    2.https://www.pwc.com/sg/en/publications/assets/total-retail-sea-2016.pdf

  • Affin Hwang Research retains Neutral on consumer sector

    Affin Hwang Capital Research is retaining its Neutral sector rating on the consumer sector and recommends stocks with solid track records and high yields, with Heineken as its top pick.

    It said on Monday while the Q3, 2016 earnings mainly disappointed,  it believes consumer spending will recover slowly in 2017 as the consumer sentiment index should pick up, backed by positive government initiatives.

    “Sector net profit fell by 26% YoY, with six of nine of our companies below expectations. We changed two ratings this round: we upgraded BAT to Hold on a share-price retraction which brought about more attractive dividend yields; and we downgraded MSM to Sell, as raw sugar prices have risen strongly, hurting margins.

    “We also recently upgraded Hai-O to Hold on better-than-expected growth in its multi-level marketing (MLM) division,” it said.

    Affin Hwang Research pointed out that while the Malaysian Institute for Economic Research (MIER) consumer sentiment remained low at 73.6 in 3Q16 – a slight pickup from an all-time low of 63.8 in 4Q15 since the global financial crisis – it was still below the 100-point threshold.

    According to Nielsen, Malaysian consumers are among the least confident in Asia Pacific. Given potentially higher transport costs and food prices partly due the removal of the cooking oil subsidy, it forecasts a higher full-year inflation rate of 2.7% in 2017 (vs. 2.2% in 2016E).

    Comparatively, MIER’s retail trade index improved to 111.6 in Q316, above the 100-point threshold, which seems to indicate that expected sales and business conditions will strengthen.

    Retail Group Malaysia forecasts 5% on-year growth in 2017 (vs 3% on-year  in 2016E and 1.4% on-year in 2015), expecting a boost on increased tourist arrivals. Budget 2017’s key initiative to increase government aid under the BR1M scheme by as much as 20% with an allocation of RM6.8bil and special assistance of RM500 to all public servants should also help boost consumer spending.

    “Nonetheless, the retail sector remains challenging, with earnings before interest and tax (EBIT) margins and same-store-sales growth in a downturn. The F&B segment will likely be hit by higher raw material prices moving forward.

    “While the tobacco segment lacks positive catalysts, BAT’s share price has come down and now offers dividend yields of 5% or more, on our estimates.

    “We are generally still positive on the brewery sector, which had done well in previous quarters, and we like our two stocks, Heineken and Carlsberg, for their dividend yields.

    “We expect domestic consumer spending to recover slowly in 2017, as consumer sentiment is expected to improve from its low base, supported by stable labor market conditions and a large young population. Maintain Neutral. We advise investors to focus on companies with defensive characteristics and attractive dividend yields,” said Affin Hwang Research.

  • Multivo – The all-in-one revolution in shelf management to boost your profit

    Multivo – The all-in-one revolution in shelf management to boost your profit

    After 2009 when the financial crisis hit most part of the world, labor productivity has fallen in many countries while minimum wages have increased steadily. As a consequence, many retailers and brands owners are experiencing pressure on already low margins, which put larger focus on improving retail store efficiency. Volumes are relatively flat, though in some studies have indicated that the basket size maintains itself but the number of visit per year decreases. Improving store traffic is high up on most retailer’s agenda.

    The questions now emerge, how to create differentiation between retailers and brands, how to increase the sales, and how to reduce the labor costs?

    This leads the retailers and brands owners need to continuously innovate, not for novelty but to bring about change for the better. With the extensive knowledge of retail environment and customers’ needs and challenges, HL Display Indonesia are now launching a new innovation within shelf management system named Multivo™.

    Multivo™ is the newest shelf management system that makes the daily work of refills, front facing and planogram changes easier and faster than ever. The system is especially suited for health and beauty category but can also be used for multiple products and pack types. The solution allows automatic fronting of more pack types than ever before.

    https://www.youtube.com/watch?v=Nrfb8iFAO8o

    Having a good visibility is proven to drive sales. Reducing time spent of fronting, refill and planogram changes is a key for today’s retailers and brands owners. Multivo™ maintains products faced up and ensures that shelves always look attractive and well-stocked without staff having need to invest too much of their time keeping the shelves in order.

    For further information, HL Display Indonesia is based in Jakarta office can be directly contacted during office hour at +622179186024 / +622179198613 with the attention to Ms. Sharania Pangalila, or e-mail to sharania.pangalila@hl-display.com or  info.asia@hl-display.com.  Visit the company website at www.hl-display.com/asia.

  • Mobile fuelling growth in Asia’s startup scene

    Mobile fuelling growth in Asia’s startup scene

    Mobile connectivity is fueling growth in Asia’s startup scene, a survey from Telenor Group shows.

    The survey covered technology buffs to better understand key startup trends for 2017 and the challenges and views of entrepreneurs in Asia.

    The survey was conducted over Facebook and LinkedIn with 215 respondents aged 15 to over 55 years old from Bangladesh, India, Malaysia, Myanmar, Pakistan, Singapore, Thailand and other Asian countries.

    To gauge the interests and personalities of the survey respondents, each person was assigned the type of startup they were most likely to create in 2017, based on pattern of their responses. 38% of respondents were found to be the most likely to create an IoT startup in 2017, significantly outnumbering the number who would establish medtech startups (22%), on-demand startups (14%), enterprise startups (11%) and fintech startups (10%).

    With a potential market of 34 billion devices expected to be connected to the internet by 2020, and nearly US$6 trillion to be spent over the next five years, it appears Asia’s entrepreneurs are well aware of the potential opportunities offered by the Internet of Things.

    In addition to these 2017 startup trend insights, the survey findings also hint at what Asian entrepreneurs think it takes to succeed in the tough startup world. More than a third of respondents (36%) believe that cybersecurity and data privacy is their number one priority, and keeping their customers’ data safe and secure is the biggest challenge facing Asian startups.

    One in 4 also admitted that the lack of business management skills and experience is another major obstacle, and having access to expert guidance would be an important growth factor. Another 16% say they are hampered by public policy frameworks and environments that are not conducive to startups, while 14% say that sustained funding across all stages of startup development would be important. Fewer than 1 in 10 were seen as were concerned with the challenge of expanding into other markets in the region.

  • Live Streaming, Gaming Apps And Chat Bots – Here Are 6 Trends We’re Excited For In 2017!

    Live Streaming, Gaming Apps And Chat Bots – Here Are 6 Trends We’re Excited For In 2017!

    As we enter into the new year, it seems only natural that we share all the Singapore technology trend in 2017 what we’re excited about, and what we foresee happening in the digital space this year.

    Here are our top 6 picks!

    1. The Rise Of Chat Bots

    Chat bots have been made popular especially since June 2016 – when Facebook launched them in Messenger.

    Over the past few months, developers have been experimenting with various chat bot use cases, and according to Facebook, while the early chat bot attempts by developers have been “really bad“, the quality of chat bots have generally improved over time.

    According to David Marcus, Facebook’s vice president of messaging products, the best use cases include driving people toward subscriptions, facilitating small transactions, and customer service.

    This year, we definitely expect companies in Singapore to come out with smart use cases for Chat Bots and integrate them into their product offerings. We also expect a rise of companies offering professional services around Chat Bots.

    2. Mega Apps

    One of the fastest growing regions in the world now is China – and if you have been following its development closely, the dominant platform now is undeniably WeChat.

    WeChat introduced the idea of “apps in apps” or “instant app”, and is literally the “one app to rule them all” in China.

    Its concept is very interesting, because with it, you can perform everything beyond just chatting with your contacts – from product purchases to payment, to joining interest clubs (WeChat has a fitness tracking feature called WeRun), to booking a cab and making restaurant reservations, there’s a high possibility of relying on the app for most everyday processes!

    If you are interested in finding out more, here are 10 WeChat travel industry case studies where companies integrating their business with WeChat’s platform – very fascinating.

    And who knows, we might just see a mega app in Singapore to rule them all this year.

    3. Breakout Gaming Apps

    The third thing we’re excited about this year is in the mobile gaming space.

    We’re expecting at least 2 or 3 mega breakout gaming apps this year. While we have no clue on what would pop up, we expect more gaming developers to take the cue from Pokemon GO’s brilliant use of augmented reality to create a real world interactive gaming experience. Pokemon GO was (still is) a game that transcends age, gender and race, and sets very high standards in the gaming community.

    We have yet to see a huge breakout gaming app from Singapore – and hopefully, 2017 is the year we will see one that will fly our Singapore flag high and proud in the global gaming arena.

    After all, there’s a dedicated area by the government called Pixel Studios dedicated to catalyse the creation of valuable gaming apps in Singapore.

    4. Smart Companies Taking Up Dead Retail Space

    One of the biggest trends is that retail vacancy is at its highest in decades. With recession (Singapore only reported an overall economic growth of 1% in 2016, and projects a growth of 1% this year) looming, as well as competition from e-commerce, it’s no wonder that retailers are unable to make ends meet, and some are even forced to move out from their physical locations.

    Of course, not all is doom and gloom though – we’re expecting resourceful and entrepreneurial individuals to negotiate contracts and/or deals with shopping mall operators which would be flexible and thus beneficial to the former.

    We expect smarter usage of spaces, with digital companies taking up physical locations around in Singapore as an extension of their business.

    Take Naiise for example. Originally a design centric e-commerce company, it has now expanded to 6 physical locations around in Singapore. Or take co-working space operator Spacemob for example, which raised almost S$8 Million in funding last year.

    Both Naiise and Spacemob are examples of smart innovators taking advantage of retail space in Singapore, and bringing the arrangement’s benefits to both space owners and consumers alike.

    5. Live Streaming

    Another space that we (ok, maybe just me) are personally very excited about is the live streaming space.

    At this moment, I think that we are still barely scratching the surface of the possibilities of live streaming. Live streaming is something different from usual platforms, and allows brands and personalities to appear more authentic and spontaneous. It also helps garner immediate interaction with the public – something which brands are all severely lacking nowadays, as they seem to chase quantity over quality.

    Another thing about live streaming is that it is completely powered by millennials, given how they often have FOMO (fear of missing out), and want to always be in-the-know of the latest trends and happenings. Where stock images and highly-edited content flood our social feed, live streamed content also offers experiences that are more ‘honest’.

    Live streaming has already exploded in China, but we have yet to see mainstream adoption in Singapore – but that’s something we’re expecting to change dramatically this year.

    6. Government Becoming Increasingly Digitised

    The last thing that we are excited about this year is that Singapore is becoming increasingly digitised.

    Taking the lead for digitising Singapore is GovTech, which sits under the newly-formed stat board IMDA. As the agency responsible for most of the digital applications used by the different government bodies, they are helping government services to move online and become mobile-friendly, all in the name of convenience for the average Singaporean.

    They also constantly monitor data from these e-Government services and get user feedback so as to keep improving what’s offered.

  • Retail trends for 2017: AI shopping, mini stores

    Retail trends for 2017: AI shopping, mini stores

    Today’s consumers are increasingly looking for specific and engaging experiences while shopping, according to an analysis from Lotte Department Store’s research team for retail trends. The team proposed a set of guidelines to help retailers prepare next year’s business strategies.

    “For modern customers, shopping is not only about buying products, but a complex experience,” said Na Hyun-jun, head of Lotte Department Store’s retail research team. “The key would be how successfully retailers provide new shopping experiences while catering to the increasingly segmented needs of consumers.”

    The first is the trend for smaller department stores that focus on catering to tastes of specific demographics. Mini department stores are frequent in Japan. Tokyo-based retail giant Isetan Mitsukoshi has more than 120 small and midsized stores nationwide near airports and train stations. Lotte Department Store opened three “el CUBE” stores in a similar concept this year, and their contents slightly differ according to visitors’ demographics.

    Personal curation for shoppers is another target selected by the team. Item choice is becoming more difficult for consumers as new products are constantly released. In the past retailers used personal shopping assistants, but recently shoppers have been using new technology like artificial intelligence and big data. In March, KT released the app Shodoc, which recommends products according to consumer demographics.

    Lotte also pointed out that consumers are more impulsive due to the development of technology related to shopping, like easy payment methods via apps. This has helped consumers purchase items immediately after seeing them online or via smartphones. The human-less supermarket Amazon Go launched this month, marked the start of a trend of moving offline.

    Retailers are providing virtual reality services at brick-and-mortar stores. Virtual reality is a field especially favorable in the fashion industry. In May, eBay and U.S. retail brand Myer launched a VR department store that is accessible by a VR headset and an app. For luxury or high-end brands, however, expanding contact with consumers and providing the chance to experience products will become a core task in establishing brand image. In the past, companies had the image of being too difficult to relate to due to their premium images. This year, high-end car brand Bentley set up a showcase “studio” in a London mall just for brand image rather than sales.

    In terms of product category, retailers are slowly expanding their reach outside industrial goods to products they have not carried in the past. This year, Harrods Department Store in London had a pop-up store to display Emaar Properties’ real estate in Dubai.

  • Mobile Research Starts The Purchase Cycle; 78% Buy Within The Day

    Mobile Research Starts The Purchase Cycle; 78% Buy Within The Day

    Once a consumer starts researching products on their smartphone, the actual purchase of a product is pretty close behind.

    In the U.S., the final purchase is most likely to occur in a physical store, which is not the case in some other countries.

    While different countries have varying degrees of penetration, the smartphone is considered the most important device for retail research by almost a third (30%) of all retail shoppers, according to a new report.

    The Global Mobile Path to Purchase study was conducted by xAD and Millward Brown and examined shopping behaviors in five countries (U.S., U.K., Germany, China and Japan).

    The importance of the smartphone as a research tool for retail purchase varies by country, with the device taking on more importance than desktops in China. Here’s the breakdown of where mobile is the most important device for shopping:

    • 50% — China
    • 44% — Japan
    • 32% — United Kingdom
    • 31% — United States
    • 29% — Germany

    There are a wide range of items that people are shopping for on phones. Consumers in Japan and China use phones for grocery shopping way ahead of other countries. In China, 88% of consumers use phones for grocery shopping, and 63% of consumers in Japan.

    By contrast, just over half (57%) of U.S. consumers use their phones for grocery shopping, with clothing and apparel talking the top spot. Here’s what consumers in the U.S. use their phones for when shopping:

    • 58% — Clothing and apparel
    • 57% — Grocery
    • 41% — Electronics
    • 39% — Home goods and improvement
    • 37% — Beauty and wellness
    • 31% — Games and entertainment
    • 23% — Sports and leisure

    While more consumers in Japan make purchases on their phones, U.S. shoppers head to the store for that final purchase. For example, 67% of consumers in the U.S. make a trip to the store to complement their mobile research compared to fewer than half (45%) in Japan.

    The real key in all of this is that once consumers start researching on their phones they are in the market to make a purchase relatively soon. Mobile research is the beginning of the intent to purchase cycle.

    Chinese and U.S. consumers are the quickest to convert, while Japanese consumers tend to take a bit more time. When shoppers start their mobile researching, here’s the breakdown of how many make a purchase within the day or sooner:

    • 86% — China
    • 78% — United States
    • 78% — United Kingdom
    • 73% — Germany
    • 49% — Japan

    After they begin their mobile research, more than half (54%) of U.S. consumers end up making the purchase in a physical store. In China and the U.K., more consumers make their final purchase via mobile rather than in person or via desktop.

    This may be a factor in the adoption of mobile payments, at least in stores.

    In the U.S., in-store mobile payments account for only 2% of all retail transactions, according to new research form GfK.  In China, it accounts for 24% of transactions.

    Shoppers in the U.S. may pass on mobile payments and prefer to make most of their purchases in a physical store, but that does not leave mobile out of the process.

    Smartphones are used all the way to the final purchase, for comparing products and checking prices of competitors. The consumer may end up buying at the store, but they likely used their smartphone to determine the product, the store and the timing of the buy.

  • Korea braces for next industrial trends in 2017

    Korea braces for next industrial trends in 2017

    Korean businesses’ quest to step closer to future industries is expected to accelerate in the New Year, regardless of the political scandal, the ongoing investigations into dubious business-political ties and the looming presidential election.

    The year 2016 was an opportunity for general consumers to familiarize themselves with the innovative concepts of technologies. And the year 2017 is likely to see some of these technologies become reality.

    The convergence of the automotive industry with technology will speed up along with a transition to green cars, amid the growing competition in the battery market and the rising price of oil.

    Devices including smartphones and home appliances operated by artificial intelligence will come to the fore, with virtual reality and augmented reality technologies becoming mainstream in the tech world.

    The shifting technologies are also expected to affect the retail market with consumers looking for products that offer experience and value beyond a simple price benefit.
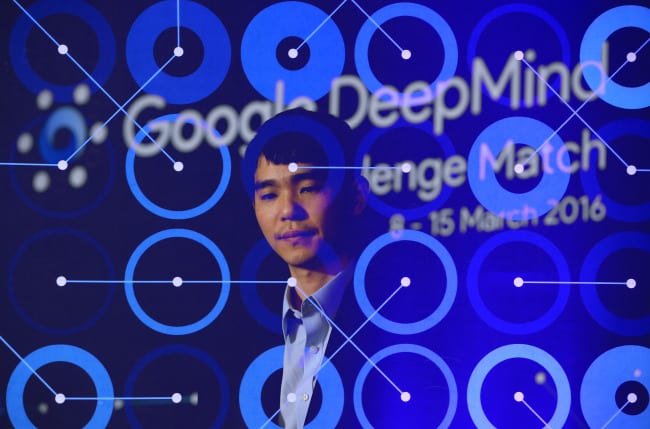
    Go player Lee Se-dol at a press conference at the Four Seasons in Seoul on March 12, 2016

    AI to be next big thing in the tech industry

    Artificial Intelligence, which astonished the world in a match with the top Go player Lee Se-dol, is expected to become the next big thing in the smart device and appliances industry in 2017.

    The nation’s largest tech company Samsung Electronics, which acquired the AI startup Viv Labs in October, seeks to recover from the note 7 debacle with its new AI-based smartphone Galaxy S8, which is set to be unveiled early this year. Viv Labs is the US tech firm set up by Apple’s Siri developers.

    Samsung Electronics’ Vice President Rhee In-jong said in October, “Galaxy S8 will be Samsung’s first platform, which adopts AI-based voice recognition technology,” adding that the technology has reached close to the level of the understanding humans.

    Korean tech firms — both smartphone makers and mobile carriers — are spurring AI development as the technology will ultimately be used to connect and control all home appliances and electronics.

    Samsung is set to unveil more advanced AI-based home appliances, which can be connected via Wi-Fi technology and controlled through smartphones, at the upcoming Consumer Electronics Show in January.

    LG Electronics is also slated to unveil AI-based home appliances, which adopt deep learning technology at the upcoming show. The deep learning technology enables products to provide customized services and functions by learning users’ habits and surroundings.

    The nation’s largest telecom carrier SK Telecom is also upgrading its AI-based speaker NUGU after first launching it in August. This device figures out users’ taste to recommend music, control home appliances and provides customized information such as weather and schedules based on their preferences.

    Market consulting firm IDC predicted that the global AI market would grow 55 percent on average annually from $8 billion in 2016 to $47 billion in 2020.
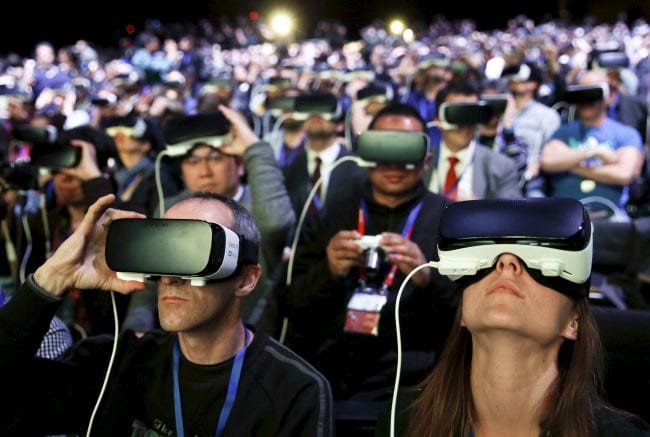
    Journalists and participants wear the Samsung Gear VR headset at the company‘s flagship Galaxy S7 launch event in Barcelona in February 2016.

    AR, VR to gain bigger presence

    Virtual reality and augmented reality technologies are geared to gain a bigger presence in the tech world in 2017, building upon the landmark developments made in 2016.

    VR is a technology that completely immerses users in computer-generated virtual worlds via a head-mounted display, while AR technology overlays, or augments, digital images onto a person’s view of the world.

    The year 2016 saw the release of next-generation VR headsets such as the HTC Vive, the Oculus Rift and Sony’s Playstation VR, which prompted the emergence of thousands of VR video games and mobile apps.

    The explosive popularity of AR-based mobile game Pokemon Go also highlighted AR’s potential to appeal to the masses on the mobile platform.

    The two cutting-edge technologies are geared to further advance and draw closer to the public in 2017 as the price of VR headsets further drop to boost the VR gaming sector, and as AR technologies are embraced by more industries.

    “After several years of hype, the operative reality behind virtual, augmented and mixed digital worlds is set to manifest more fully in 2017,” IHS Markit said in a recent outlook report.

    The firm expects AR and VR technologies will “advance significantly as Facebook, Google and Microsoft consolidate their existing technologies into more exhaustive strategies.”

    According to tech market intelligence company IDC, worldwide revenues generated by the AR and VR market will jump from just $5.2 billion in 2016 to more than $162 billion in 2020, as the two technologies expand their applications across diverse industries and services.

    IDC predicts that revenues generated by VR systems will surpass that of AR-related revenues until 2017, due to rising consumer uptake of VR-based video games and paid contents.

    After 2017, AR revenues will grow bigger as AR technology finds mass applications across areas such as healthcare delivery, product design and management tasks, it said.

    Just about every major tech company in the world has already entered the race to secure its place in the approaching era of VR and AR technologies. In the lead is Facebook-owned Oculus, Google and Microsoft, with Apple and Samsung Electronics working to catch up.
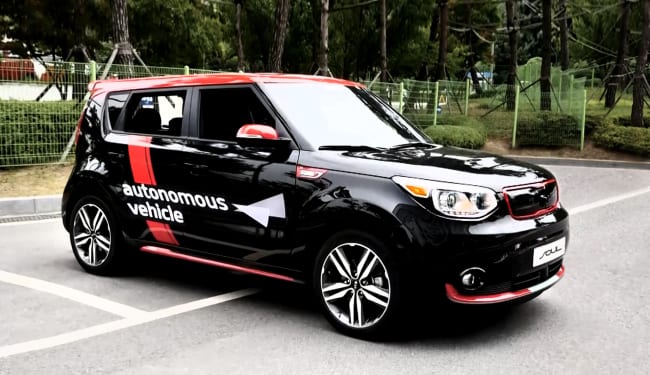
    Kia’s EV autonomous vehicle Soul

    Auto industry to face unprecedented race

    It was a tough year for the auto industry in Korea with an emissions scandal, strikes, low demand and negative growth.

    With the auto market expected to continue negative growth next year, carmakers will face unprecedented competition in the industry where automotive and technology are converging rapidly.

    South Korea’s largest automaker Hyundai Motor conducted a survey on the most anticipated technology next year. Almost 76,000 of 320,000 voters picked the autonomous driving technology. Although self-driving cars won‘t populate the road next year, most of the major carmakers and tech companies are putting all-out efforts to commercialize the self-driving technology.

    The debut of US electric automaker Tesla Motors and Chinese electric car maker BYD Auto will likely boost the EV market in South Korea, giving customers more choice in this growing segment. Tesla is set to open its flagship store in Korea and BYD officially launched its Korean office in Jeju Island in October.

    Backed by growing popularity, sport utility vehicles will remain as the silver lining for the sluggish auto market, which is expected to decline 1.2 percent on-year.

    Domestic carmakers, especially Hyundai Motor Co and Kia Motors Corp, will face fierce competition in 2017 in the Korean market as imported cars expand its market share. Currently, imported carmakers take up 13 percent of the total market.

    Outside Korea, South Korean automakers will struggle to thrive in mature markets, like the US and EU where analysts expect a zero growth next year, and in China where they saw disappointing sales figures in 2016. China’s auto market is expected to grow 4 or 5 percent in 2017 while other developing markets, like Russia and East Europe, will recover from the 2016 slump.

    China looms over Korean battery makers

    For Korea’s major battery makers — Samsung SDI and LG Chem — concerns over their performance in the Chinese market are likely to persist next year amid the neighboring country’s stricter rules on providing battery certification.

    The two companies have been dealt with a blow after the Chinese government suspended subsidies for electric vehicles using batteries produced by the two firms earlier this year. The two were excluded from the subsidy list as they failed to acquire the battery certification amid tightened regulations in China’s alleged protectionism moves.

    Unless China changes its policies, the Korean battery makers are unlikely to see improvement in their business there, the companies said.

    “While (the company) had anticipated the EV battery certification process will resume in the third quarter, (the Chinese government) did not carry it out. It is difficult to project an accurate timing,” a Samsung SDI official said in the third quarter’s conference call.

    LG Chem shared a similar view.

    “The biggest variable for the company’s sales growth for next year is China. If the status quo continues next year, the automotive battery business growth rate will be around 30 percent. If (the certification issue) is solved, the growth rate will possibly jump up to 60 percent.”

    Amid the higher threshold to the Chinese market, Korean battery makers are seeking to sustain their top position in the global ESS market next year.
    LG Chem topped the global ESS market share with 21 percent this year, standing at No.1 for two years straight, followed by Samsung SDI with 19 percent.

    “Amid the three-party competition of LG Chem, Samsung SDI and BYD Auto in the market, Tesla has risen as the new competitor. As the supply amount of the two Korean companies is projected to surpass 2 gigawatt hours next year, the two are likely to make up half of the market in total,” SNE Research forecasted.

    LG Chem has made aggressive ESS moves with supplying ESS for California’s largest power company SCE and other European companies.
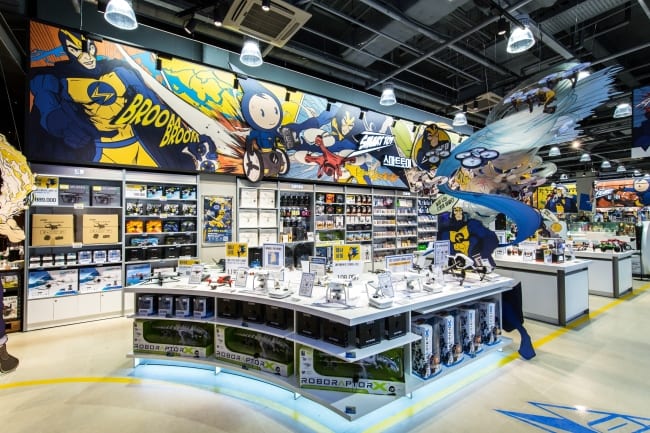
    Experience-focused electronics retailer Electromart at Starfield Hanam

    ‘YOLO’ trend to rule retail in 2017

    In 2016, the retail sector saw consumers shifting their focus to stores and products that offer value and experience, rather than simply low prices.

    Despite the stagnant economy, brands saw consumers reaching for premium and healthy products, packing newly opened malls offering experience-based stores.

    In “Trend Korea 2017,” Seoul National University consumer studies professor Kim Nan-do dubbed this the “YOLO,” or “you only live once,” trend.

    “Consumers who used to think of restraint as a virtue are now enjoying and challenging themselves each moment, and spending money on simple, clear value,” he said.

    The most notable examples of YOLO spending can be found in travel, with consumers facing record-low interest rates choosing to spend money on meaningful experiences rather than saving it away. All retail sectors, meanwhile, have seen consumers choosing to open their wallets and enjoy the “here and now.”

    For example, consumers are buying more decorative products for the home to create better surroundings for themselves. According to the online open market Auction, sales of products like sculptures and music boxes from January to November rose by over 200 percent on-year. Hobby-related products such as classical guitars and model buildings and model airplanes also nearly doubled on-year.

    The Samsung Fashion Research Institute saw “selfness,” or the importance of brands‘ personalities matching those of consumers, to be a major factor moving the fashion industry in 2017.

    Starfield Hanam, a shopping mall featuring stores that allow consumers to experience products as well as buy them, saw nearly 2 million shoppers each month since it opened in September. Starfield Hanam’s popularity during a year when department stores struggled to maintain sales indicated that consumers are visiting and spending money at places that have an element of entertainment, rather than simply shopping options.

    “In an ‘experience economy,’ it will become more important for brands to find new marketing strategies that can satisfy the now-focused experience consumption of the YOLO consumers,” Kim wrote.
  • An iPhone’s journey, from the factory floor to the retail store

    An iPhone’s journey, from the factory floor to the retail store

    Apple buys many of the components for iPhones — like the memory chip, the modem, the camera module, the microphone and the touch-screen controller — from more than 200 suppliers around the world. Foxconn, the Taiwanese company that runs the Zhengzhou facility, even produces some smaller parts, such as metal casings.

    Apple orders many of the components from global suppliers and then sells them, en masse, to one of its contract manufacturers in China. In Zhengzhou, that means Foxconn.

    Foxconn’s facilities in Zhengzhou cover 2.2 square miles and can employ up to 350,000 workers, many of whom earn about $1.90 an hour. The operation does final assembly, testing and packaging.

    There are 94 production lines at the Zhengzhou manufacturing site, and it takes about 400 steps to assemble the iPhone, including polishing, soldering, drilling and fitting screws. The facility can produce 500,000 iPhones a day, or roughly 350 a minute. After the iPhone rolls off the assembly line, it is placed in a sleek white fiberboard box, wrapped and put on a wooden pallet, and then wheeled out to waiting trucks.

    The newly assembled iPhone is transported a few hundred yards beyond the factory gate, where China built a large customs facility. The customs operation sits in a bonded zone, which allows Apple to sell the iPhones more easily to Chinese consumers.

    As the final point of assembly for the iPhone, China also serves as a starting point for Apple’s global tax strategy. In Zhengzhou, often in the customs facility, Foxconn sells the completed iPhones to Apple, which in turn resells them to Apple affiliates around the world.

    The process, most of which takes place electronically, allows Apple to assign a portion of its profits to an affiliate in Ireland, a tax-advantageous locale. The system is not unique to China.

    IPhones bound for the United States and other parts of the world leave customs by truck and are transported three miles to the Zhengzhou airport. The airport has been significantly expanded in recent years, as production of the iPhone has increased.

    Some years ago, personal computers that were made in China were transported to the United States by container ship, with a trip lasting about a month. Smartphones are small enough to be shipped by plane in huge quantities — and cost-effectively. A single wide-body Boeing 747 can easily carry 150,000 iPhones tucked into its aluminum canisters.

    From Zhengzhou, UPS, FedEx and other freight carriers typically fly U.S.-bound iPhones to Anchorage, Alaska. There, they refuel, before going on to Louisville, Ky., a major logistics hub, or other points.

    For an iPhone headed for the China market, customs officials use an electronic system to virtually stamp the goods as “exports” and then restamp them as “imports.” In Zhengzhou, the process happens in the same customs facility just outside the factory.

    Once the products are declared an import, customs can collect a 17 percent value-added tax, a kind of national tax, based on the import price. Afterward, the goods are approved for transport around China. Domestic-bound iPhones are typically loaded onto a large truck and taken on an 18-hour drive from Zhengzhou to Shanghai, in eastern China, where Apple has set up its national distribution center. A single tractor-trailer holds up to 36,000 iPhones. Because the vehicles have about $27 million worth of freight on board, they are equipped with cameras and sometimes accompanied by armed security guards.

    After the iPhone leaves the Foxconn factory in Zhengzhou, it takes two days, on average, to get to a store in Shanghai, a 590-mile trip. It takes three days, on average, to get to a store in San Francisco, some 6,300 miles away.

    IPhones can sell for nearly 20 percent more in China than in the United States.

    Chinese customers pay much higher prices, because of currency fluctuations and the country’s hefty value-added tax.

    A 32-gigabyte iPhone 7 sells for about $776 at the Apple Store in Shanghai. In New York, it goes for $649.

  • Rampant growth of DDoS attacks in 2016

    Rampant growth of DDoS attacks in 2016

    The threat of IoT botnets was realized in 2016 and popularized by Mirai, according to a study by Neustar.

    Mirai and similar types of malware compromise IoT device credentials to enrol them into botnets, which are activated by command and control servers.

    As these code assemblies are published, new developments continue to emerge, such as persistent device enrolment, which enables botnet operators to maintain control of a device even after it is rebooted.

    The study also reported that the frequency of DDoS attack mitigations by the company increased 40% in 2016 compared to the same period of time in 2015, according to a study released by the company.

    “With DDoS attacks predicted to become even more complex and ferocious in 2017, increasingly digital organizations within Asia-Pacific will be exposed to more frequent and severe cyber-attacks,” said Robin Schmitt, general manager for APAC at Neustar.

    Multi-vector attacks, which combine attack vectors to confuse defenders and supplement attack volume, also increased 322% and accounted for 52% of the attacks mitigated by Neustar. UDP, TCP and ICMP comprise the three most popular attack vectors, which were leveraged in more than 50% of attacks.

    The report also showed that DNS-based attacks increased 648% with many attackers leveraging DNSSEC amplification to generate massive volumetric pressure.

  • 83% of smartphone users in India shop online

    83% of smartphone users in India shop online

    Indian retail customers are taking strongly to mobile commerce, with nearly 83 percent of people owning a smartphone saying that they shop online on their mobile phones, new study reveals.

    As expected, customers in the younger age group – 25-34 years old – are using their mobile phones more (90 percent) to shop online.

    However, the State of M-Commerce 2016 survey, conducted by US-based global digital strategy and services firm Regalix Inc., also showed that while a large number of customers have used their mobiles to shop online, there is still much room for growth in terms of the frequency of online shopping.

    Only 53 percent of those surveyed said that they had shopped online within the last month. Moreover, only 25 percent of respondents said that they shopped on their phones at least once a week. There seems to be a gender divide also in the frequency of online shopping, with more men (63 percent) doing so at least once a month than women (40 percent).

    Overall, gadgets and electronics was the most popular product category at 60 percent, followed distantly by clothing and accessories at 20 percent. While 66 percent of men shopped for gadgets online, only 31 percent of women did so. On the other hand, more women (65 percent) shopped online for clothing, accessories and home products as compared to men (27 percent).

    The survey likewise showed that the lion’s share of online retail is divided between three platforms – Flipkart (44 percent), Amazon (32 percent), and Snapdeal (19 percent). Interestingly, preference between these platforms is segmented by age, with Flipkart the preferred retailer for 49 percent of respondents in the 18-24 age group, but only 35 percent in the 25-34 age group. Snapdeal received more support in the 25-34 age group (25 percent) than in the 18-24 group (only 13 percent).

    Another interesting finding is that the number of retail customers shopping online has grown, many still prefer to browse online and purchase offline. Around 42 percent off respondents said that they preferred to do so while purchasing gadgets and electronics, while 33 percent said that they bought clothing and accessories this way.

    Clothing and accessories were the one category in which offline purchasers outnumbered online shoppers across all age and gender groups.

    The two biggest factors influencing a customer’s decision to shop online are Cash-on-delivery (34 percent) and free delivery (34 percent). CoD was the preferred payment mode for the majority of customers, with 62 percent preferring this over net banking, credit/debit cards or mobile wallets.

    Mobile apps are also the preferred way for customers to shop on their phones, with an overwhelming 94 percent declaring they preferred apps to mobile websites. The study also found that while 81 percent of respondents said they were unaffected by mobile ads, a higher percentage of women (25 percent) said that ads influenced their shopping behavior than men (17 percent).

  • India’s internet population to reach 600m by 2020

    India’s internet population to reach 600m by 2020

    India’s rapidly expanding digital population is expected to double to approximately 600 million users by 2020 from 343 million users today, a new study reveals.

    The joint study, conducted The Associated Chambers of Commerce & Industry of India (ASSOCHAM) and Deloitte, also showed that of India’s over one billion mobile subscriptions, smartphone users account for approximately about a fourth or 240 million subscriptions. This is expected to grow to 520 million by 2020.

    While India is the second largest mobile phone market globally, the study noted that over 55,000 villages remain deprived of mobile connectivity, largely because providing mobile connectivity in these locations is not commercially viable for service providers.

    Spectrum availability in Indian metros is also just about a tenth of the same in cities in developed countries, which is a major roadblock to providing high-speed data services.

    The study noted that public Wi-Fi penetration remains low, with only about 31,000 hotspots available. For India to achieve the global average of one Wi-Fi hotspot for every 150 citizens, the country needs over eight million hotspots.

    Rural adoption of data-enabled devices, however, is expected to increase with the BharatNet initiative under the Digital India program, which itself has been hampered by many challenges including a lack of technical skills and capabilities or competent organizations to support the program.

    Other factors include lack of awareness of internet services among Indian consumers and non-availability of most of these digital services in local languages. Moreover, with the proliferation of cloud-based services like DigiLocker, data security has also emerged as a major challenge.

    The recent data breach in August 2016, in which debit card data for more than 3.2 million subscribers was stolen, highlights the importance of implementing foolproof security systems.

    The study recommends that the government should make efforts to make additional spectrum available to telecom service providers for deployment of high-speed data networks and must effectively collaborate with the private sector to develop the digital infrastructure.

    Moreover, it noted that in rural and remote areas, private sector players should be incentivized to provide last mile connectivity. Satellite communication solutions could also be used to speed up broadband access in rural and remote areas. For instance, banks can use VSAT technology to connect remote ATMs, remote branches which need instant access to customer data.

    “In order for the benefits of the Digital India program to reach all sections of the population, improving digital literacy is imperative. A strong skill base is required to support the initiatives and services that are envisaged under the Digital India umbrella,” the study concluded.

  • Digital video software market to exceed $9b by 2021

    Digital video software market to exceed $9b by 2021

    The video software market is expected to exceed $9 billion in revenue by 2021, according to a new report recently released by IHS Markit.

    The atomization of media distribution and the switch from hardware-based technology solutions to cloud implementations are key drivers for the $3 billion in revenue growth over the next five years, according to the new Video Software, Security, and Analytics Intelligence Service report from IHS Technology.

    “Taken together, these two forces have created a market where value is shifting towards the frontend,” said Cecilia Zhu, analyst at IHS Technology. “A superior user-experience has become fundamental to securing increased consumer spend.”

    Globally, content security accounts for 32% of the digital video software market. While demand for robust security solutions is unlikely to deteriorate,  particularly in the presence of high-value UHD and HDR content,  the segment is effectively saturated.

    North America is the key region for the video software market, and generates roughly $2.9 billion. The region’s value relates primarily to confluence of three factors — the presence of large media companies, their outright scale, and their sheer number.

    The region’s economic dominance should not, however, overshadow the existence of cutting-edge video services in Europe, Asia, and the Middle East, and the technology demand that these services generate.

    Cisco has a 15% share of the video software segment, the largest globally. The company has proven adept at transitioning into the video space, and in using its longstanding presence in core, metro, and access-network infrastructure to cross and upsell video-specific software.