Tag: apparel

  • Indian AC Volumes Surge over 25% Ahead of Festive Season

    Indian AC Volumes Surge over 25% Ahead of Festive Season

    Indian consumer demand accelerated during the July-September quarter, with air conditioner shipment volumes surging more than 25 per cent year-on-year, according to manufacturers.

    Sales of refrigerators and washing machines grew 13 to 14 per cent, while departmental store chain Lifestyle and market researcher Bizom tracked strong momentum across apparel and consumer goods.

    Volume gains outpace price rises

    Godrej Enterprises Group business head Kamal Nandi said festival demand expanded in double digits across Independence Day, Onam and Ganesh Chaturthi, noting that retail channels held over a month of stock at earlier prices to absorb recent hikes.

    Branded apparel revenue climbed more than 12 per cent during the three-month stretch. Early discount events, including Independence Day promotions in August along with regional festivals such as Onam and Ganesh Chaturthi, generated double-digit retail turnover across regional hubs.

    Department stores see tier-two traction

    Department store operators recorded steady foot traffic, led by non-metro locations where discretionary purchasing held up better than in the largest cities. Retailers cleared previous seasonal lines without heavy discounting, entering the festive calendar with lean inventory.

    “The July-September quarter was good with early double-digit sales growth and strong single-digit same-store growth,” said Devarajan Iyer, CEO at departmental store chain Lifestyle.

    Lifestyle reported that inventory levels of older lines remained restricted, allowing fresh merchandise to command full retail margins across department store networks.

    Grocery baskets show mixed momentum

    Fast-moving consumer goods recorded a value expansion of roughly 9 per cent through the quarter, according to data from retail analytics provider Bizom. Packaged food categories outpaced home care and personal hygiene products by a wide margin.

    Beverages, packaged groceries, confectionery, dairy products and commodities posted value gains between 10.8 per cent and 16.4 per cent from June through September. Personal care and household goods moved at a single-digit rate, showing that shoppers prioritized immediate food consumption over non-perishable refills.

    Macro tailwinds and monsoon risks

    Macroeconomic indicators provided support for consumption, with Indian gross domestic product expanding 7.8 per cent during the fiscal first quarter. Industrial output climbed 8 per cent year-on-year in August, improving on the 7.4 per cent recorded in July.

    A 13 per cent overall monsoon deficit across 15 states and union territories presents the primary risk factor for agricultural income and late-season rural demand. Consumer goods companies are now tracking whether rural sales channels match urban momentum as Diwali distribution cycles close out in October.
  • British Brand Hunter Opens First Thailand Flagship at IconSiam

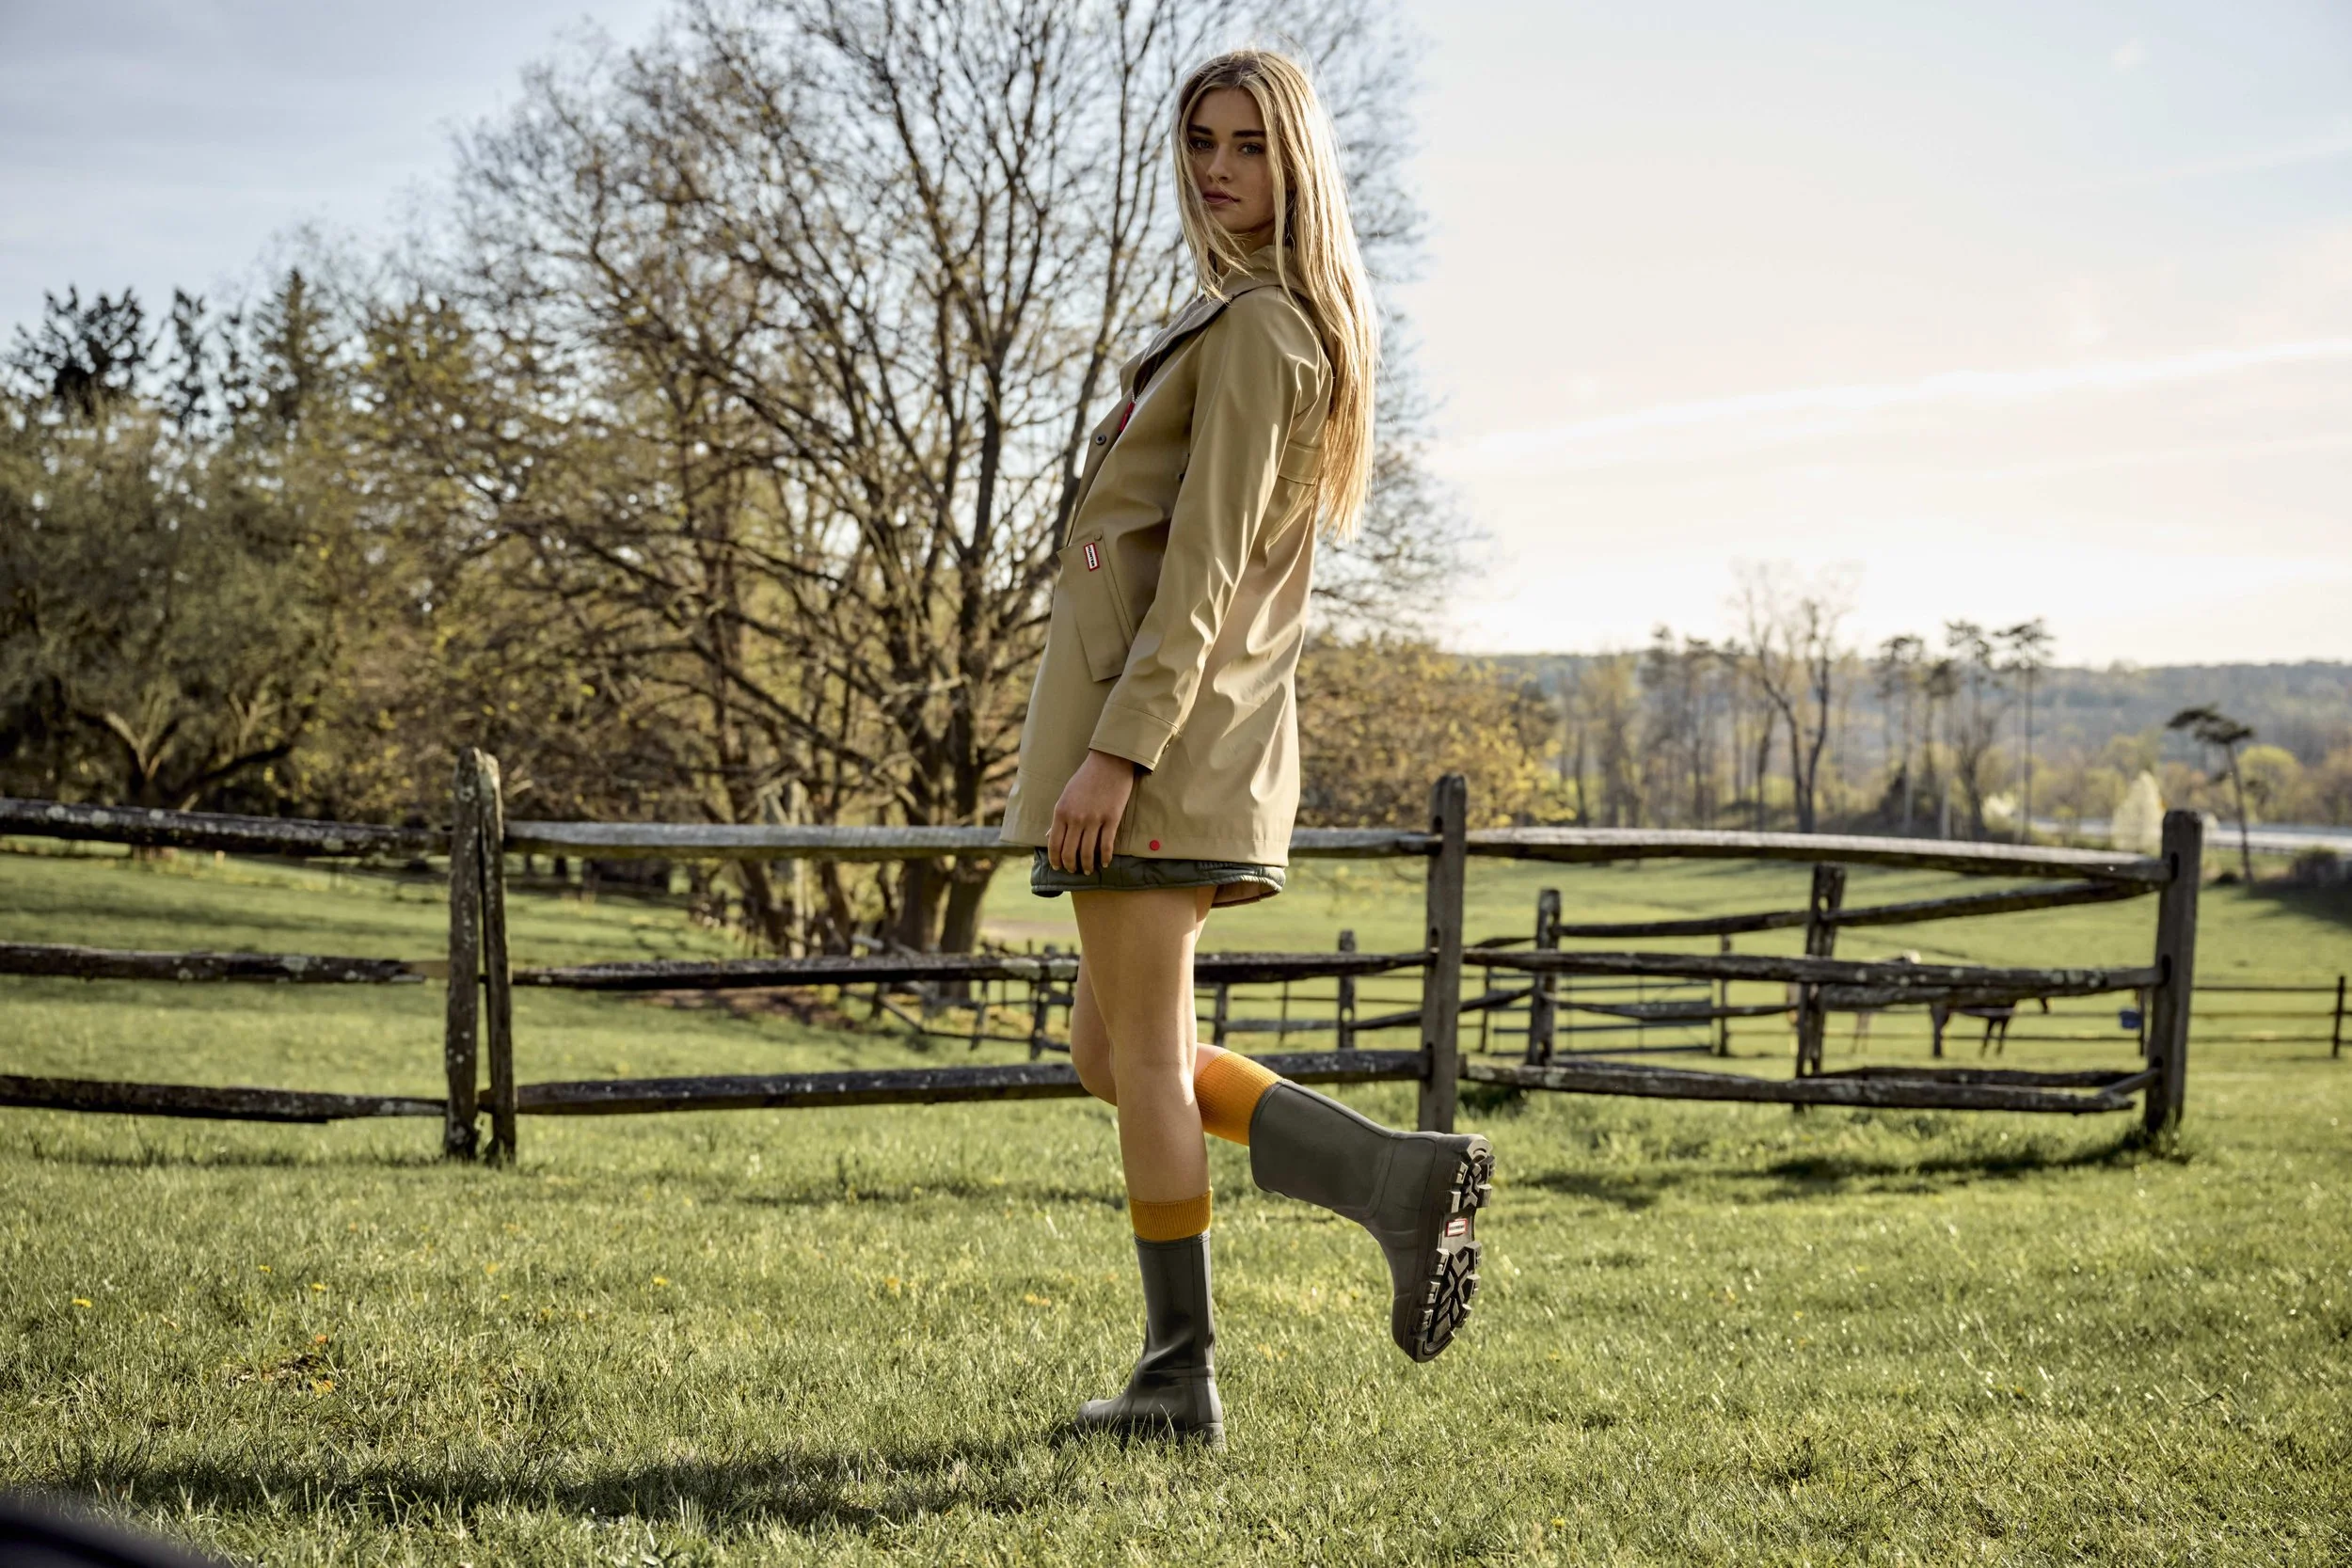
    British Brand Hunter Opens First Thailand Flagship at IconSiam

    British heritage brand Hunter opened its first flagship boutique in Thailand on September 25, 2026, setting up shop inside Bangkok’s riverside IconSiam shopping centre.

    The retail site features the Scottish company’s complete product line, spanning its classic rainwear range alongside seasonal apparel and accessories. Founded in Scotland in 1856, the label made its name on vulcanised rubber Wellington boots before building out a wider lifestyle catalogue.

    Flagship layout and aesthetic

    Hunter designed the Bangkok interior with oak-inspired timber finishes, mint accent tones and natural greenery. The layout uses the brand’s signature red palette across key fixtures, drawing visual references from rural British coastal and countryside scenery.

    Merchandise on the floor includes the core waterproof boots that established the brand, alongside bags, outerwear and travel gear. Carrying the full range in one dedicated space allows the company to present itself as a comprehensive lifestyle label rather than a seasonal rubber boot specialist.

    Prime placement at IconSiam

    Securing space inside IconSiam gives the label direct exposure to high-spending domestic shoppers and international tourists. The riverside complex remains one of Bangkok’s premier luxury and premium lifestyle destinations, attracting heavy foot traffic across its retail floors.

    For mall operator Siam Piwat, adding a legacy British name strengthens its outdoor and casual footwear mix against competing upscale developments along Sukhumvit. Premium lifestyle brands continue to bid for prime ground and lower-level floor plans across Bangkok’s top retail properties.

    Tropical market dynamics

    Selling heavy-duty rainwear in a tropical Southeast Asian climate comes with specific operational demands. Bangkok’s prolonged monsoon season drives practical consumer demand for durable waterproof footwear and water-resistant bags, but styling must suit humid weather rather than cold northern European winters.

    The store’s inventory mix must balance heritage rubber boots with lighter footwear, lightweight apparel and everyday commuter accessories. Retailers that adjust regional assortments to local weather patterns protect sell-through rates and limit inventory markdowns.

    Regional brand expansion

    Hunter’s Bangkok launch follows years of shifting distribution across Asia-Pacific markets, where brand operators have sought deeper direct-to-consumer relationships. Establishing standalone brick-and-mortar stores allows the company to control brand presentation and pricing discipline better than wholesale distribution channels.

    Retail watchers will monitor sales momentum at IconSiam through the final quarter of 2026 to see whether Hunter adds concession counters across Central Group and The Mall Group department store networks in Bangkok.

  • Skechers Scales Southeast Asia Network Past 1,000 Sales Points

    Skechers Scales Southeast Asia Network Past 1,000 Sales Points

    Skechers has pushed its Southeast Asian distribution network past 1,000 points of sale. That footprint started from fewer than 10 stores in 2009.

    Regional executive Zann Lee led the 17-year expansion across key regional markets. The push shifted the footwear brand from niche specialty distribution into major shopping centres, department store concessions, and standalone flagships.

    Scaling regional store networks

    Managing inventory across 1,000 regional locations brings operational headaches that smaller chains avoid. Operators must balance stock allocations against wide gaps in purchasing power. Singapore represents a mature market, while Thailand, Malaysia, and Vietnam offer high-growth retail environments.

    Larger store formats serve as testing grounds for broader category assortments. Floorspace has shifted away from walking shoes toward performance athletic lines and apparel. Maintaining sales productivity per square metre gets tougher as footprints expand in prime malls.

    The biggest change is that consumers today are much more sophisticated and demanding.

    Shifting consumer preferences

    Shoppers across Southeast Asia now favour technical features, comfort engineering, and visible brand differentiation over price discounts. That shift forces footwear retailers to shorten product update cycles. Floor staff in larger formats also need broader training.

    Rival athletic and lifestyle footwear operators are crowding metropolitan capitals. Brands compete directly for prime ground-floor mall units. This rivalry drives up occupancy costs and piles pressure on full-price sell-through rates.

    Channel diversification and store density

    Monobrand store rollouts run alongside wholesale partner doors, franchise outlets, and direct e-commerce channels. Keeping prices consistent across these touchpoints remains a constant operational challenge for multi-market distributors.

    Wholesale accounts deliver immediate volume across provincial cities. Direct flagships anchor brand equity in primary commercial hubs. At this scale, retailers must prune weak concessions while securing high-traffic mall corridors.

    Inventory control across borders

    Cross-border logistics across archipelagic markets like Indonesia and the Philippines add supply chain complexity to regional footprints. Lead times for seasonal footwear collections require precise forward purchasing and regional warehousing support.

    Looking ahead, the brand will focus on refining store productivity, optimising larger footprints, and aligning regional inventory across direct and franchised storefronts.

  • Penshoppe Expands to Indonesia Ahead of Summer 2013 Collection Rollout

    Penshoppe Expands to Indonesia Ahead of Summer 2013 Collection Rollout

    Philippine fashion brand Penshoppe will open its first retail store in Indonesia in December. The expansion takes its casual wear footprint into Southeast Asia’s largest consumer market.

    The overseas entry follows the debut of the retailer’s Summer 2013 collection during the closing day of Philippine Fashion Week on October 28.

    Four Lines for Summer

    Penshoppe structured its runway presentation across four product segments: Dressy: Glitter and Shine, Preppy Casual, Resort, and Active Wear. Each model wore a single assigned outfit during the show rather than cycling through multiple wardrobe changes. That allowed the brand to show a high volume of individual garments.

    Designs in the collection update basic casual apparel with elevated tailoring and evening styling. The pieces are built to transition from daywear to formal settings.

    Entering the Indonesian Market

    Expansion into Indonesia gives Penshoppe direct exposure to an urban middle class with growing discretionary spending on ready-to-wear apparel. Setting up physical shopfloors in Jakarta and surrounding retail hubs places the brand in direct competition with entrenched regional operators and international fast-fashion chains.

    Local retail landlords in Southeast Asia continue to allocate floor space to affordable fashion brands capable of generating consistent foot traffic. For Penshoppe, the commercial test lies in replicating its domestic brand recognition in a market where local tastes and supply chain overheads differ sharply from the Philippines.

    Regional Fast Fashion Pressures

    Apparel retailers across the Association of Southeast Asian Nations face increasing margin pressure from rising logistics expenses and quickening inventory turnover cycles. Competing against established global giants requires domestic brands to maintain sharp pricing. They must also shorten product lead times.

    To capture broader demographics across casual and professional settings, Penshoppe broadened its design categories, leaning on styling lines like preppy basics and activewear.

    What to Track Next

    Runway looks unveiled at the conclusion of the Manila fashion calendar on October 28 established the four-part summer templates scheduled to reach Philippine shop shelves ahead of the warm-weather shopping period.

    Attention now turns to the location and format of the first Indonesian store opening in December, alongside the commercial rollout schedule for Summer 2013 inventory across domestic outlets.

  • Levi Strauss Hires Skechers Veteran John Vandemore as Finance Chief

    Levi Strauss Hires Skechers Veteran John Vandemore as Finance Chief

    Levi Strauss & Co. Named John Vandemore as executive vice president and chief financial officer on Wednesday. He joins the apparel maker after a nine-year stint at footwear group Skechers.

    Vandemore assumes the post on November 1. The San Francisco-based apparel maker wants to hit $10 billion in annual revenue, up from $6.3 billion recorded in 2025.

    At Skechers, Vandemore helped build the business into the world’s third-largest footwear brand. Net sales there reached nearly $9 billion across more than 180 countries and 5,000 retail locations. In his new role, he will oversee global accounting, financial planning, investor relations, tax, treasury, digital operations, information technology and supply chain logistics. Harmit Singh announced his retirement in April after serving as chief financial and growth officer. Singh stays in office until Vandemore starts, then serves as a special advisor through November 30.

    Building Out Direct Retail Channels

    Levi Strauss currently operates roughly 3,300 retail stores and shop-in-shops across 120 countries. Chief executive Michelle Gass joined from Kohl’s Corp. And has pushed direct-to-consumer sales, mono-brand retail stores, and expansions into women’s tops and athleisure through the Beyond Yoga label. Footwear brands built direct consumer networks faster than traditional denim wholesalers did. Vandemore’s background in retail store expansion fits that jeans strategy directly.

    Mall operators and franchise partners across Asia-Pacific and Europe will see continued real estate spending on full-price flagship stores rather than wholesale distribution deals. Execution costs carry risk. Operating company-owned stores ties up working capital and lifts lease liabilities in volatile retail markets.

    Shifting Away from Pure Wholesale

    Over the last decade, the company pivoted from a wholesale men’s denim supplier into a broader multi-category retailer. Singh and former chief executive Chip Bergh led that transition. They took the company public on the New York Stock Exchange in 2019 and rebuilt profitability.

    Wholesale accounts now share shelf space with company-owned retail stores, digital platforms and regional franchise operations. Hiring a finance chief with direct operational oversight of logistics and store real estate aligns the balance sheet with Gass’s direct-selling push.

    Cross-Industry Executive Shifts

    Before Skechers, Vandemore served as executive vice president and CFO of global brands and commercial sales at Mattel Inc. He previously held finance leadership roles at International Game Technology and The Walt Disney Company, where he was chief financial officer of Walt Disney Imagineering. His early career began at PricewaterhouseCoopers, followed by finance positions at Deloitte & Touche, Goldman Sachs and AlixPartners.

    Gass noted that Vandemore’s operational track record equips him to expand the brand into a broader global lifestyle business. She added that he can deliver that growth while protecting operating margins.

    Targets and Next Filings

    Managing capital expenditure will be the first test as store rollouts continue across international markets. Investors will watch whether Levi Strauss can protect profit margins while moving inventory away from department store partners and into its own shops.

    Singh wraps up his advisory work on November 30. Vandemore then delivers his first full quarterly financial blueprint to Wall Street analysts in early 2027.

  • Canada Goose Opens 254-Square-Metre Chatswood Store in Sydney

    Canada Goose Opens 254-Square-Metre Chatswood Store in Sydney

    Canada Goose opened its third Australian store on September 30 at Sydney’s Chatswood Chase. The retailer secured 254 square metres on the centre’s new luxury level.

    That space sits inside a 625 million Australian dollar redevelopment targeting affluent shoppers across Sydney’s lower north shore.

    The location introduces the brand’s 2.0 Luxury Retail Concept to Australia. Norwegian architecture firm Snøhetta co-developed the design. It combines limestone, terrazzo, and local Australian timber with Canadian elements, including tactile walls depicting Canadian mountain ridges and river valleys.

    The Snøhetta Layout and Materials

    Interior finishes mix regional sourcing with brand heritage. Snøhetta avoided purely functional alpine aesthetics, choosing polished stone and textured surfaces common in high-end fashion boutiques.

    Flagship stores in Paris, Milan, Chicago, and Vancouver already use the layout. Sydney represents the concept’s first installation in the southern hemisphere.

    Adapting Product for Southern Seasons

    Chatswood stock spans womenswear, menswear, and kidswear, plus dedicated areas for footwear and eyewear. The floor carries the Fall/Winter 2026 collection designed by creative director Haider Ackermann.

    Merchandising heavy thermal parkas in a temperate coastal market demands adjustments. To draw shoppers outside peak winter, the store holds exclusive regional launch rights for the Loma Half Zip and Loma Fleece Jacket. Those garments anchor a wider lightweight fleece line built for transitional weather.

    Chatswood Chase Luxury Expansion

    Landlords across major Australian retail hubs are shifting lower floors toward luxury labels to protect foot traffic from e-commerce. Developer Vicinity Centres pointed its 625 million dollar capital expenditure directly at building this luxury precinct.

    For luxury brands, Chatswood captures wealthy suburban shoppers who skip trips to Sydney’s central business district. High rents per square metre present clear risks if demand for expensive performance wear drops during long warm spells.

    From Milan to Sydney Suburbs

    Canada Goose first entered Australia with shops in Melbourne and downtown Sydney. Opening in Chatswood shifts that focus from downtown flagships into dense suburban luxury enclaves.

    Ackermann’s upcoming seasonal collections will reveal whether the Toronto outerwear brand can sustain year-round apparel sales through the Australian calendar.

  • Musinsa Helps 15 Korean Fashion Brands Enter China via Shanghai Pop-Up

    Musinsa Helps 15 Korean Fashion Brands Enter China via Shanghai Pop-Up

    South Korean fashion platform Musinsa is helping 15 domestic apparel brands enter China through a dedicated pop-up store at Shanghai’s Jing An Kerry Centre. The temporary retail space drew more than 10,000 visitors between Aug. 21 and Sept. 21.

    Running through Nov. 30 on Nanjing West Road, the initiative covers product certification and in-store sales operations. Backed by South Korea’s Ministry of Trade, Industry and Energy alongside the Korea Trade-Investment Promotion Agency, the project aims to reduce costs and hurdles for small and midsize brands entering the market.

    State backing and regulatory clearance

    Participating labels include Lookast, Lebah, Tillaidie, and RSSC. Musinsa selected brands based on local demand and consumer preferences, assisting them with Chinese product standards required for local distribution and managing on-site sales.

    Small apparel exporters face steep barriers in mainland China, where localized testing, labeling rules, and import certifications routinely stall foreign market debuts. Handling store staffing and inventory management centrally removes upfront capital expenditure for the labels, letting them test mainland consumer appetite without signing long-term commercial leases.

    Testing demand on Nanjing West Road

    Securing prime frontage at Jing An Kerry Centre places these emerging Korean names beside established global luxury flagships. The high-traffic shopping corridor gives independent streetwear and contemporary labels immediate exposure to Shanghai’s core fashion demographic.

    Foot traffic numbers indicate solid curiosity, but footfall does not guarantee recurring wholesale orders. Chinese consumer spending across mid-tier fashion remains selective, and domestic Chinese streetwear brands have taken market share by responding to local trends faster than overseas competitors.

    The platform approach across Asian markets

    Musinsa’s export model shifts financial risk away from single designers and turns the platform into a consolidated distributor. The company is replicating this physical playbook across the region, pairing its domestic roster with localized retail partners, as seen in Southeast Asia where its Musinsa Standard private label partnered with ACx Retail to enter the Philippines.

    For commercial landlords, the arrangement provides a rotating roster of trending Korean brands without the lease default risks tied to single-label tenants. For the fashion brands, the structure caps downside exposure while testing whether Chinese shoppers will buy beyond short-term novelty.

    Anfu Road pipeline and next steps

    The Kerry Centre project builds on Musinsa’s permanent footprint in Shanghai. The company opened a flagship retail space on Anfu Road in December, which serves as a dedicated launchpad for Korean apparel labels seeking Chinese distribution.

    That location has already hosted individual pop-ups for brands including Ronron, Sculptor, and Stand Oil. Accessories label Find Kapoor starts a monthlong residency at the Anfu Road store on Oct. 30, while the Jing An Kerry Centre multi-brand show runs until Nov. 30.

  • SM Retail Keeps 15 Forever 21 Stores Open in the Philippines

    SM Retail Keeps 15 Forever 21 Stores Open in the Philippines

    SM Retail will keep all 15 Forever 21 stores open across the Philippines following a bankruptcy filing by the brand’s US parent company in October 2019.

    SM Retail, which holds the majority stake in the local joint venture, confirmed that domestic operations will remain unaffected by the overseas restructuring.

    Insulation From Global Closures

    The voluntary bankruptcy in the United States ensures the parent company retains control of its assets while restructuring, even as it is expected to close around 350 stores worldwide, primarily in its main US market.

    Ponciano Manalo, president and chief executive officer of SM Retail, confirmed that domestic sales diverge sharply from struggling Western markets.

    There is no effect on our Philippine operations. Forever 21 Philippines continues to be one of the stronger global operations.

    Joint Venture Structure Protects Footprint

    Local ownership shields the Philippine network from overseas insolvency fallout. SM Retail controls domestic operations and houses the stores inside its nationwide mall network. This structure spares the brand from the heavy standalone lease liabilities that broke its Western counterpart.

    Across flagship commercial centres, the steady 15-store footprint prevents sudden vacancies. North American landlords face empty retail space as hundreds of large-format units wind down. Philippine commercial tenancy under SM Retail remains fixed.

    Decade of Local Expansion

    Do Won and Jin Sook Chang founded Forever 21 in California in 1984. The chain expanded rapidly across international shopping centres on a fast-turnaround, budget apparel model.

    Its Philippine debut arrived in 2010 through the SM Retail partnership, opening at SM Megamall in Mandaluyong. The domestic footprint expanded steadily across metropolitan retail hubs over the following nine years.

    Marketing Push for Peak Quarter

    Fresh capital is now moving into inventory and promotional campaigns for the fourth-quarter shopping period. Year-end consumer spending in the Philippines represents the most lucrative sales window for apparel merchants.

    Regular merchandise shipments will reach retail floors throughout the final quarter as marketing campaigns roll out across all 15 branches.

  • Misto Group Opens 1St Taiwan Store for Korean Label Mucent

    Misto Group Opens 1St Taiwan Store for Korean Label Mucent

    Misto Group has partnered with Korean streetwear brand Mucent to open the label’s 1st store in Taiwan, launching in Taipei in September 2026.

    The contemporary casualwear label is recognised for its monochromatic aesthetic with black as a signature colour, blending streetwear influences with everyday wear targeted at younger female consumers.

    The Store Network Across Three Cities

    Following the Taipei debut, Misto Group plans to open additional Mucent stores in Taichung and Kaohsiung by the end of the year.

    Opening three prime urban locations within a single calendar quarter requires dedicated retail floor space in top-tier shopping districts. By targeting Taiwan’s three largest metropolitan centers at once, the distributor bypasses a slower test-and-learn strategy in favor of immediate national visibility.

    Targeting the Young Fashion Consumer

    Mucent built its domestic reputation in South Korea around everyday casualwear combined with functional streetwear accents. The brand focuses heavily on monochrome design palettes, using black textiles as its core visual identity to attract young female consumers.

    Taiwanese department stores and street-level shopping strips have steadily increased their allocation of floor space to independent Korean apparel labels. Streetwear concepts that emphasize affordable styling and daily wearability compete directly against Japanese fast-fashion operators and domestic boutique chains.

    Pressure on Regional Distributors

    Distributors managing imported fashion brands face compressed shelf-life cycles driven by social media trends. Physical retail commitments across three separate cities demand consistent replenishment logistics and strong sell-through rates to offset rising retail lease costs in central Taipei.

    Local retail landlords in Taichung and Kaohsiung continue to court imported lifestyle concepts to draw younger foot traffic into physical malls. Misto Group relies on Mucent’s existing online traction among regional shoppers to drive footfall into the new brick-and-mortar units.

    Expansion Timeline for Southern Doors

    South Korean apparel exporters have broadened their presence across East Asia by leaning on established local distribution partners to manage store buildouts and inventory risk.

    Work now shifts to site preparation in central and southern Taiwan. RetailNews Asia will track the opening schedules for the Taichung and Kaohsiung stores as Misto Group works toward its year-end target.

  • H&M Shrinks Asian Footprint to 886 Stores as Regional Sales Edge up 4 per Cent

    H&M Shrinks Asian Footprint to 886 Stores as Regional Sales Edge up 4 per Cent

    H&M Group closed 54 stores across Asia, Oceania and Africa over nine months to August. That trimmed its regional footprint to 886 locations. Regional sales for the quarter still rose 4 per cent.

    Group-wide revenue for the three months to August 31 reached SEK 57.2 billion ($5.8 billion). That was an increase of just 1 per cent in local currencies, as a stronger Swedish krona erased top-line gains.

    Operating profit climbed 23 per cent to SEK 6.04 billion, beating market forecasts of SEK 5.14 billion. The operating margin widened to 10.6 per cent from 8.6 per cent a year earlier. One-off refunds from US tariff payments accounted for 1.6 percentage points of that margin increase. The company confirmed those credits will not repeat in coming quarters.

    Pruning the Asian Store Network

    Physical retail space continues to shrink across Asia, Oceania and Africa. The regional network stood at 940 locations in November 2025 before net closures reduced the tally to 886 by the end of the third fiscal quarter.

    Management has paired store closures with selective rollouts for higher-margin labels. The group introduced COS to India in October 2025. It is betting affluent urban shoppers will back premium concepts as core H&M outlets leave marginal shopping centres.

    “We are able to get product from having a first rough idea to the customer in six weeks, and when we talk about shortening the lead times, it is about increasing the share that we buy in that way,” said chief executive Daniel Erver.

    Online transactions now generate more than 30 per cent of total sales. That growth has accelerated the push to refit existing flagships. The company has modernised a fifth of its 4,000 global stores rather than adding floor space.

    Rival Pace and Regional Margins

    H&M faces pressure from both ends of the fashion market in Asia. Zara owner Inditex reported a 9 per cent sales increase in constant currency in August, outpacing H&M through rapid stock turnover.

    Discount competitor Shein continues to capture budget market share across Southeast Asia and East Asia, squeezing the middle price bracket where H&M operates. Landlords in tier-two Asian malls face falling footfall. That drop leaves retailers with less bargaining power over fixed leases unless their sales density improves.

    Shifting logistics hubs has added further friction. A warehouse closure in Belgium disrupted stock flows into international distribution channels earlier this year. Transport bottlenecks in the Middle East compounded those freight delays.

    Decarbonising the Manufacturing Base

    Supply chain costs remain exposed to rising energy expenses across South Asia. Fuel price hikes in Bangladesh, a major manufacturing centre for the group, prompted H&M to push suppliers toward renewable power.

    Direct suppliers must complete the phaseout of coal-fired boilers by the end of 2026. This energy shift targets long-term operational resilience as regional fossil fuel tariffs fluctuate.

    European logistics operations are also expanding through 2027 with new facilities. These hubs aim to shorten shipping cycles and improve product availability across digital channels.

    The Next Trading Targets

    Recent store closures follow a difficult 2025 fiscal year. H&M shuttered a net 105 stores across Asia, Oceania and Africa during that period, driving a 7 per cent reported revenue drop in Swedish krona terms.

    Early autumn trading shows little acceleration. September sales are projected to grow 1 per cent in local currencies, matching the flat trajectory of the third quarter.

    Investors and retail partners are watching the fourth-quarter gross margin to see if shorter lead times can protect full-price sales without discounting once temporary tariff credits vanish.

  • Hermès Reopens Renovated Store at Taikoo Li in Chengdu

    Hermès Reopens Renovated Store at Taikoo Li in Chengdu

    Hermès reopened its retail store in Chengdu, located in China’s Sichuan province, on September 28, 2026, following a renovation.

    Situated in the Taikoo Li open-air mall, the store first opened in 2014.

    According to the company, the redesigned space reimagines the region’s architecture and cultural heritage through a contemporary lens, featuring dark timber, matte-finish metal, enamelled ceramic in amber tones, and tall windows veiled with bamboo screens and curtains.

    Architectural overhaul at Taikoo Li

    The redesign updates a flagship that anchors one of western China’s highest-grossing commercial developments. Luxury labels in Chengdu have steadily shifted focus toward expanding and retrofitting established premier doors rather than pursuing raw floorplate expansion across secondary properties.

    Regional textures and craft references align the boutique with a broader global strategy of giving individual flagships distinct local identities. For high-spending regional shoppers, tailored physical store environments remain the primary point of contact for leather goods, ready-to-wear lines and bespoke collections.

    Western China luxury demand

    Chengdu serves as the principal luxury capital for inland and southwestern China, drawing top-tier consumer spending from Sichuan, Yunnan and Guizhou provinces. Competition among European fashion houses for prime positioning at Taikoo Li remains intense as landlords curate tenant mixes to retain ultra-high-net-worth client traffic.

    Upgrading the 2014 location preserves Hermès’s standing against rival flagship boutiques from Chanel, Louis Vuitton and Dior. The investment protects market share in a provincial capital where retail footfall and high-ticket sales consistently rival levels recorded in Shanghai and Beijing.

    Network investment across China

    This completed renovation follows a three-year cycle of store expansions and refurbishments executed by Hermès across greater China. The Paris-based fashion house opened its initial mainland boutique in 1997 and spent the next three decades building a tightly controlled network of directly operated flagships in key commercial hubs.

    Hermès continues to review and modernise its legacy stores across mainland retail hubs, with further provincial flagship enhancements planned as commercial lease renewals approach across the national network.

  • Chanel Acquires France’s Oldest Shirtmaker Charvet

    Chanel Acquires France’s Oldest Shirtmaker Charvet

    French luxury fashion house Chanel acquired France’s oldest shirtmaker Charvet in July. Sibling co-directors Jean-Claude and Anne-Marie Colban continue to lead the heritage brand from its long-standing boutique on Place Vendôme in Paris, offering classic tailored shirts and ties.

    The move comes alongside milestone anniversaries and executive transitions across independent fashion labels. British brand YMC is celebrating 30 years since its first collection, with creative director Sage Toda-Nation directing design alongside co-founder Jimmy Collins after joining in 2024 following the death of co-founder Fraser Moss.

    Wholesale Networks and Direct Market Entry

    In retail, South London store Suntosons launched in 2025 under founder Keita Hiraoka, formerly of Beams Japan and Trunk, while in Southeast Asia, former Mall Group executives founded retail venue Friend Friend in summer 2025 inside Bangkok’s Emporium shopping mall.

    South Korean fashion exports have gained commercial traction across Tokyo and Shanghai, helped by consumer demand for unisex silhouettes and neutral palettes. Direct market entry allows brand owners to retain higher gross margins compared to pure wholesale distribution, which often discounts unsold seasonal inventory through third-party stockists.

    Mass Market Scale and Regional Supply Chains

    At the top of the market by volume, Fast Retailing’s Uniqlo is projecting annual sales of 3.9 trillion yen, equivalent to 20.8 billion euros, keeping pace with global fast-fashion operators Inditex and H&M Group. The Japanese retailer is using functional outerwear, including padded blousons with checked linings, to anchor seasonal volume across its Asian store network.

    Independent designers across the region are also integrating domestic textile manufacturing into global wholesale networks. Seoul-based designer Jiyong Kim, an LVMH Prize semi-finalist in 2024 who trained at Louis Vuitton and Lemaire, supplies Dover Street Market in Singapore and Paris, 10 Corso Como in Seoul, and GR8 in Tokyo with sun-weathered and light-responsive fabrics.

    Repurposing Mall Real Estate in Southeast Asia

    Retail formats in Southeast Asia are shifting space away from conventional department store layouts toward multi-use commercial hubs. In Bangkok, retail venture Friend Friend opened inside a converted car park at The Mall Group’s Emporium shopping complex at 622 Sukhumvit Road.

    Former Mall Group executives Suchada Peanpiriya, Worapun Sinakhom and Tanchanok Thitisaksakul established the venue in 2025, mixing workshops, food service and lifestyle merchandise. The floor plan stocks local ceramics from Bangkok’s Aoon Pottery alongside Sekisaka tableware from Japan and Kent hairbrushes from Britain, demonstrating how mall operators are converting underutilised square footage to drive foot traffic.

    Niche Manufacturing and Technical Commuter Lines

    Specialist Asian apparel makers are targeting functional categories to build export niches. In Japan’s Tokai region, Gifu-based commuter brand Ketta developed cycle-ready formalwear, adding cuff fasteners to suit trousers to prevent gear snags during urban commutes.

    Cross-border production partnerships are supporting this technical shift. Japanese label Comoli paired with Italian outerwear house Ten C, overseen by Federico Melchioli, to manufacture a nine-piece black collection blending Japanese flannel with humidity-responsive jersey textiles. In South London, former Beams Japan buyer Keita Hiraoka founded appointment-only showroom Suntosons in 2025, contracting garment factories in Japan to produce heavyweight denim fatigue jackets for European buyers.

    Commercial landlords and multi-brand buyers across Shanghai and Tokyo are now reviewing autumn order books as Recto finalises its opening retail locations in both territories.

  • Honda and Onitsuka Tiger Debut Concept Motorcycle and Apparel in Milan

    Honda and Onitsuka Tiger Debut Concept Motorcycle and Apparel in Milan

    Honda and Japanese fashion brand Onitsuka Tiger have launched a collaboration to bring together motorcycles and fashion, debuting a concept motorcycle and apparel line in Milan on September 23, 2026.

    The centerpiece is the Onitsuka Tiger Honda Mid Sports Concept motorcycle, which held its world premiere during Onitsuka Tiger’s Spring/Summer 2027 show at Milan Fashion Week. Based on a mid-displacement sports model, the bike features Tiger Yellow as its base color, bold black stripes on both sides, and black wheels with Tiger Yellow accents and both brands’ logos.

    Onitsuka Tiger also unveiled footwear and apparel incorporating Honda’s motorcycle Wing Mark emblem, with designs inspired by motorcycle culture.

    Translating Mobility Into Apparel Foot traffic

    For fashion labels in high-rent urban corridors across Asia and Europe, mobility collaborations offer an avenue to younger male consumers who shop apparel less frequently. Through the deal, Onitsuka Tiger gains access to Honda’s motoring heritage. It applies that industrial brand equity directly to footwear and street apparel.

    Honda is using European fashion runways to reach demographics outside traditional dealership networks. The automaker wants to broaden city rider adoption. Instead of relying solely on speed and engineering metrics, it is packaging two-wheelers as lifestyle design objects.

    Shared Industrial Roots in Postwar Japan

    Both enterprises trace their origins to postwar industrial expansion in Japan. Honda was founded in 1948, and Onitsuka Tiger started in Kobe in 1949. Each business expanded globally over seven decades by anchoring manufacturing in specialized product engineering.

    The Milan presentation linked those corporate histories through physical product design. Staging the bike during the September 22 to 28 fashion calendar put mechanical hardware directly before international department store buyers and fashion media.

    Commercial Pipeline and Product Rollout

    Retail distribution details, production timelines, and pricing brackets for the co-branded footwear and apparel collections align with the Spring/Summer 2027 commercial cycle. Neither manufacturer has disclosed dealership availability or road-homologation plans for the Mid Sports Concept motorcycle.

  • Alo Yoga Opens 7,000 Square Foot Flagship at K11 Musea in Hong Kong

    Alo Yoga Opens 7,000 Square Foot Flagship at K11 Musea in Hong Kong

    Alo Yoga opened its first Hong Kong flagship store at K11 Musea on September 25, taking over a 7,000-square-foot harbourfront unit across two retail levels.

    The two-storey outlet is the Los Angeles brand’s first physical store in Greater China, following an online launch on Alibaba’s Tmall platform.

    Located at Units 022 and 122 along Victoria Dockside at 18 Salisbury Road in Tsim Sha Tsui, the shop occupies the waterfront footprint previously leased by British grocer Fortnum & Mason. The layout stocks the brand’s full women’s and men’s sportswear collections, footwear and street-focused garments, including woven shirts and tailored trousers. Opening promotions and customer events run through October.

    The Greater China Physical Push

    Securing a prominent two-floor anchor unit in Tsim Sha Tsui positions Alo directly against Lululemon in Hong Kong’s premium activewear sector. Until now, local shoppers bought the label directly through cross-border web orders or through wholesale rails at department store Lane Crawford. Taking direct control of prime real estate gives the label the floorplate required to show broader lifestyle and streetwear ranges that struggle on multi-brand racks.

    The store sets the template for a rapid mainland rollout. The company has mapped physical openings across six additional cities: Beijing, Shanghai, Shenzhen, Hangzhou, Chengdu and Macau. Rollouts of this size require reliable local inventory pipelines and sustained store-level sales to offset high core retail rents across top-tier shopping malls.

    Tmall Launch Provided the Base

    Direct entry into Hong Kong physical retail follows digital testing on mainland e-commerce channels. Alo established its Tmall storefront to measure regional demand, size curves and category preferences before committing capital to long-term commercial leases. That digital data now informs the physical product mix across women’s studio sets and newer lifestyle categories.

    Physical store openings across Beijing, Shanghai, Shenzhen, Hangzhou, Chengdu and Macau follow this flagship debut as lease handovers conclude.

  • JD Sports Sales Dip Globally as Asia Pacific Delivers 10.7% Organic Growth

    JD Sports Sales Dip Globally as Asia Pacific Delivers 10.7% Organic Growth

    JD Sports lifted organic sales in Asia Pacific by 10.7 per cent in the six months to August 1. It was the retailer’s sole expanding region globally.

    Total group revenue dipped 0.7 per cent to $11.1 billion (£5.89 billion) during the half-year period. Weaker consumer spending across larger Western markets weighed on the top line.

    Asia Pacific Leads Organic Revenue

    North America generated the largest share of group receipts. However, regional demand slowed compared with previous reporting periods. Asia Pacific bucked that trend with double-digit organic expansion while other divisions contracted.

    Brick-and-mortar shopping drove the regional gain. The company opened six stores across Asia Pacific in the half-year, lifting same-store receipts through event-driven sports merchandise sales.

    “We remained focused on ‘controlling the controllables’ – progressing our strategy at pace while maintaining tight cost and capital discipline,” said Régis Schultz, chief executive of JD Sports.

    Store Expansion and Footfall Dynamics

    Stores remain central to the JD Sports operating model, generating 79 per cent of group turnover during the period. Organic e-commerce sales rose 5.2 per cent.

    For landlords across Asia, the numbers confirm steady footfall demand for multi-brand athletic anchors. Standalone mono-brand stores face margin volatility. In contrast, multi-brand formats draw wider traffic by consolidating footwear lines under one roof.

    Local wage pressure and fit-out inflation still threaten store expansion. Managing occupancy costs across prime retail hubs will determine whether new sites generate positive returns on capital over the next cycle.

    Product Mix Shifts to Apparel

    Category diversification provided extra sales insulation. Apparel and accessories climbed to 36 per cent of total group sales. Demand grew for technical running gear and newly introduced shoe silhouettes.

    A push into higher-margin apparel gives the retailer flexibility against footwear supply bottlenecks from major athletic brands. Regional rivals have also built up non-footwear inventory to defend transaction values against cautious discretionary spending.

    Earnings Rebound and Regional Headwinds

    Group pre-tax profit rose nearly 75 per cent to $454 million, up from $260 million a year earlier. The prior-year figure had absorbed a $307 million one-off charge that suppressed net earnings.

    World Cup demand lifted regional merchandise sales, helping offset softer retail sentiment in Australia and New Zealand. The next test comes in the second half, when tournament sales cycles fade and the retailer must sustain full-price sell-through rates across its Asia-Pacific stores.