Tag: China

  • K11 Musea First-Half Sales Jump 40 per Cent on Luxury Tenant Overhaul

    K11 Musea First-Half Sales Jump 40 per Cent on Luxury Tenant Overhaul

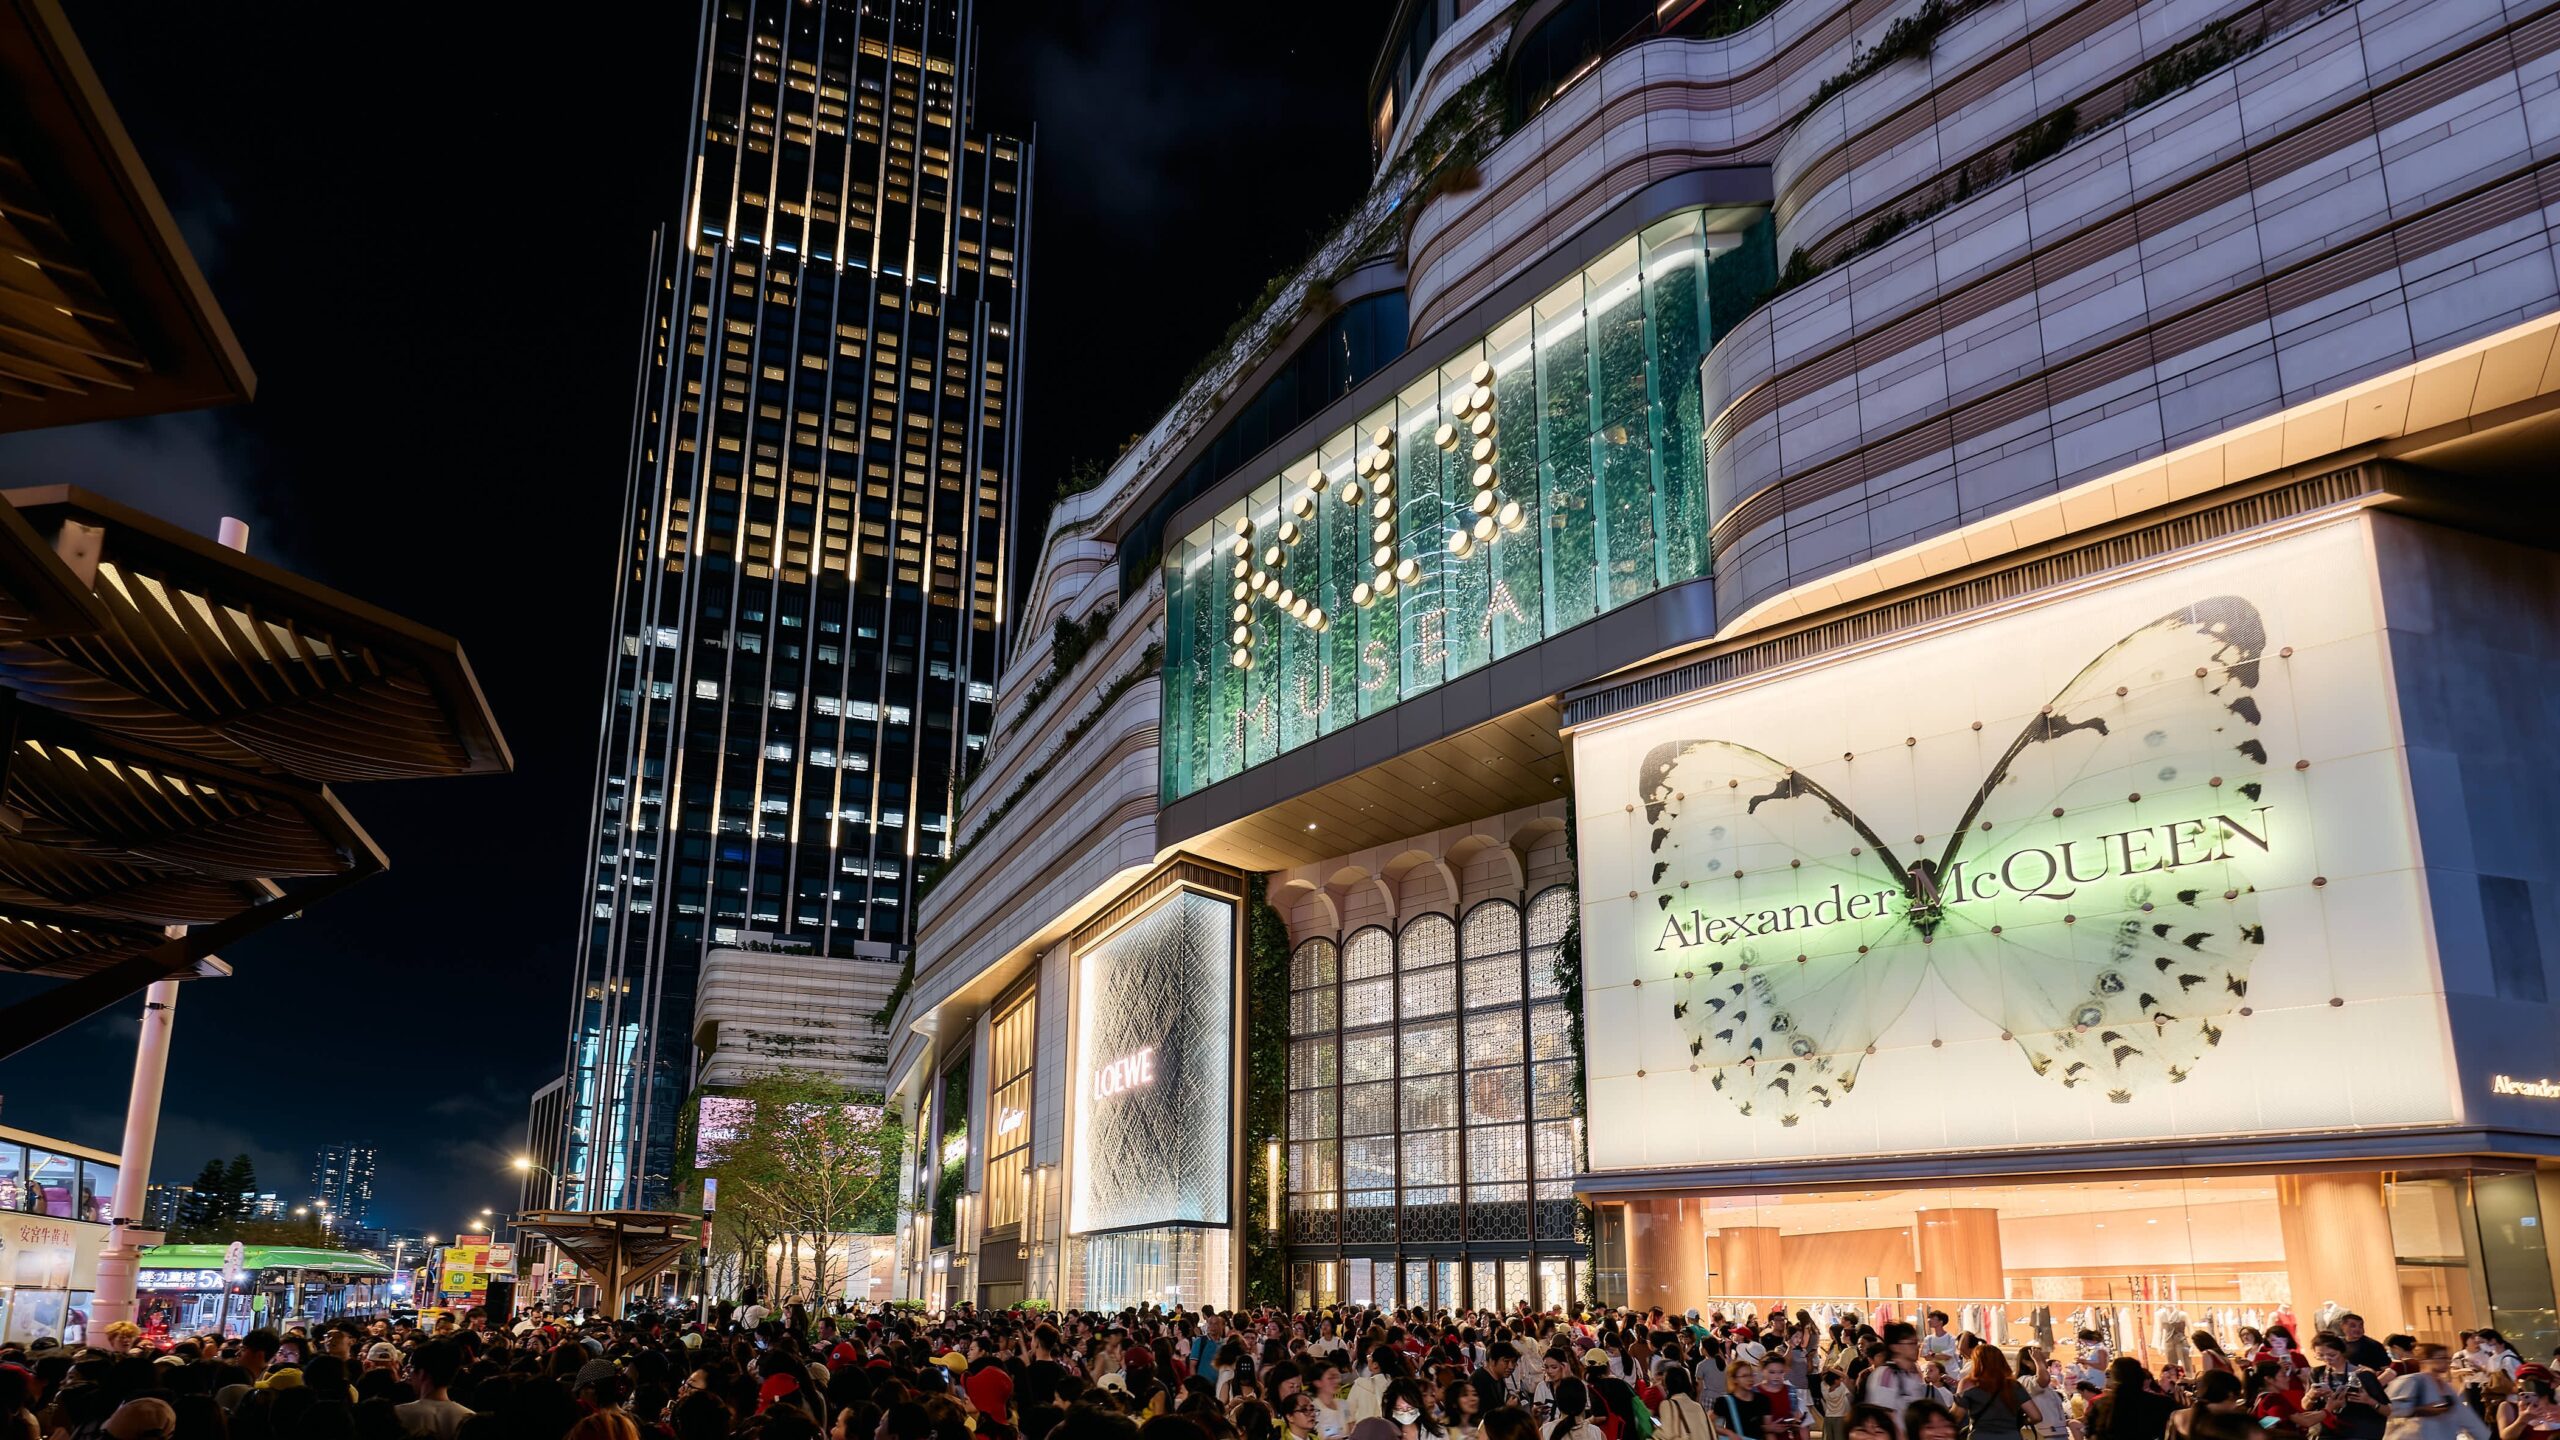
    Hong Kong retail complex K11 Musea increased first-half revenue by 40 per cent year-on-year, posting record sales for the period following a sweeping overhaul of its tenant roster.

    Newly introduced brands at the Tsim Sha Tsui waterfront destination averaged sales gains of more than 30 per cent, parent company New World Development said.

    The landlord initiated the first phase of its brand repositioning in the second half of 2024. That phase will wrap up by the end of this year, clearing space for flagship retail formats designed to generate higher revenue per square foot.

    Watches and Jewellery Drive Member Spending

    Hard luxury delivered the sharpest gains. Loyalty member spending on watches and jewellery climbed 80 per cent year-on-year during the first six months, while outlays on international luxury labels rose 20 per cent.

    Recent openings include boutiques from Miu Miu and IWC Schaffhausen, alongside a duplex flagship for Max Mara. Running label Hoka and Chinese outdoor brand Kailas also opened locations at the property over the summer.

    Tourist retail spend climbed 50 per cent year-on-year across the summer holiday period, supported by targeted arts and cultural exhibitions. Loyalty club spending continued that pace into August, rising 30 per cent.

    Landlords Shift Floor Plans to High-Yield Tenants

    Hong Kong shopping malls are aggressively reallocating square footage toward top-tier luxury labels and high-margin outdoor apparel to capture higher average basket sizes from mainland visitors. Rather than relying on volume foot traffic alone, operators are filtering tenants by direct sales productivity, a metric Horace Lam, chief executive of K11 Hong Kong, identified as the primary filter for new leases.

    Prada will open a new boutique at K11 Musea in the coming months, alongside an unannounced international yoga apparel brand scheduled to make its debut before the upgrade concludes.
  • BYD Adapts Japanese Kei Car Platform for European Electric Microcars

    BYD Adapts Japanese Kei Car Platform for European Electric Microcars

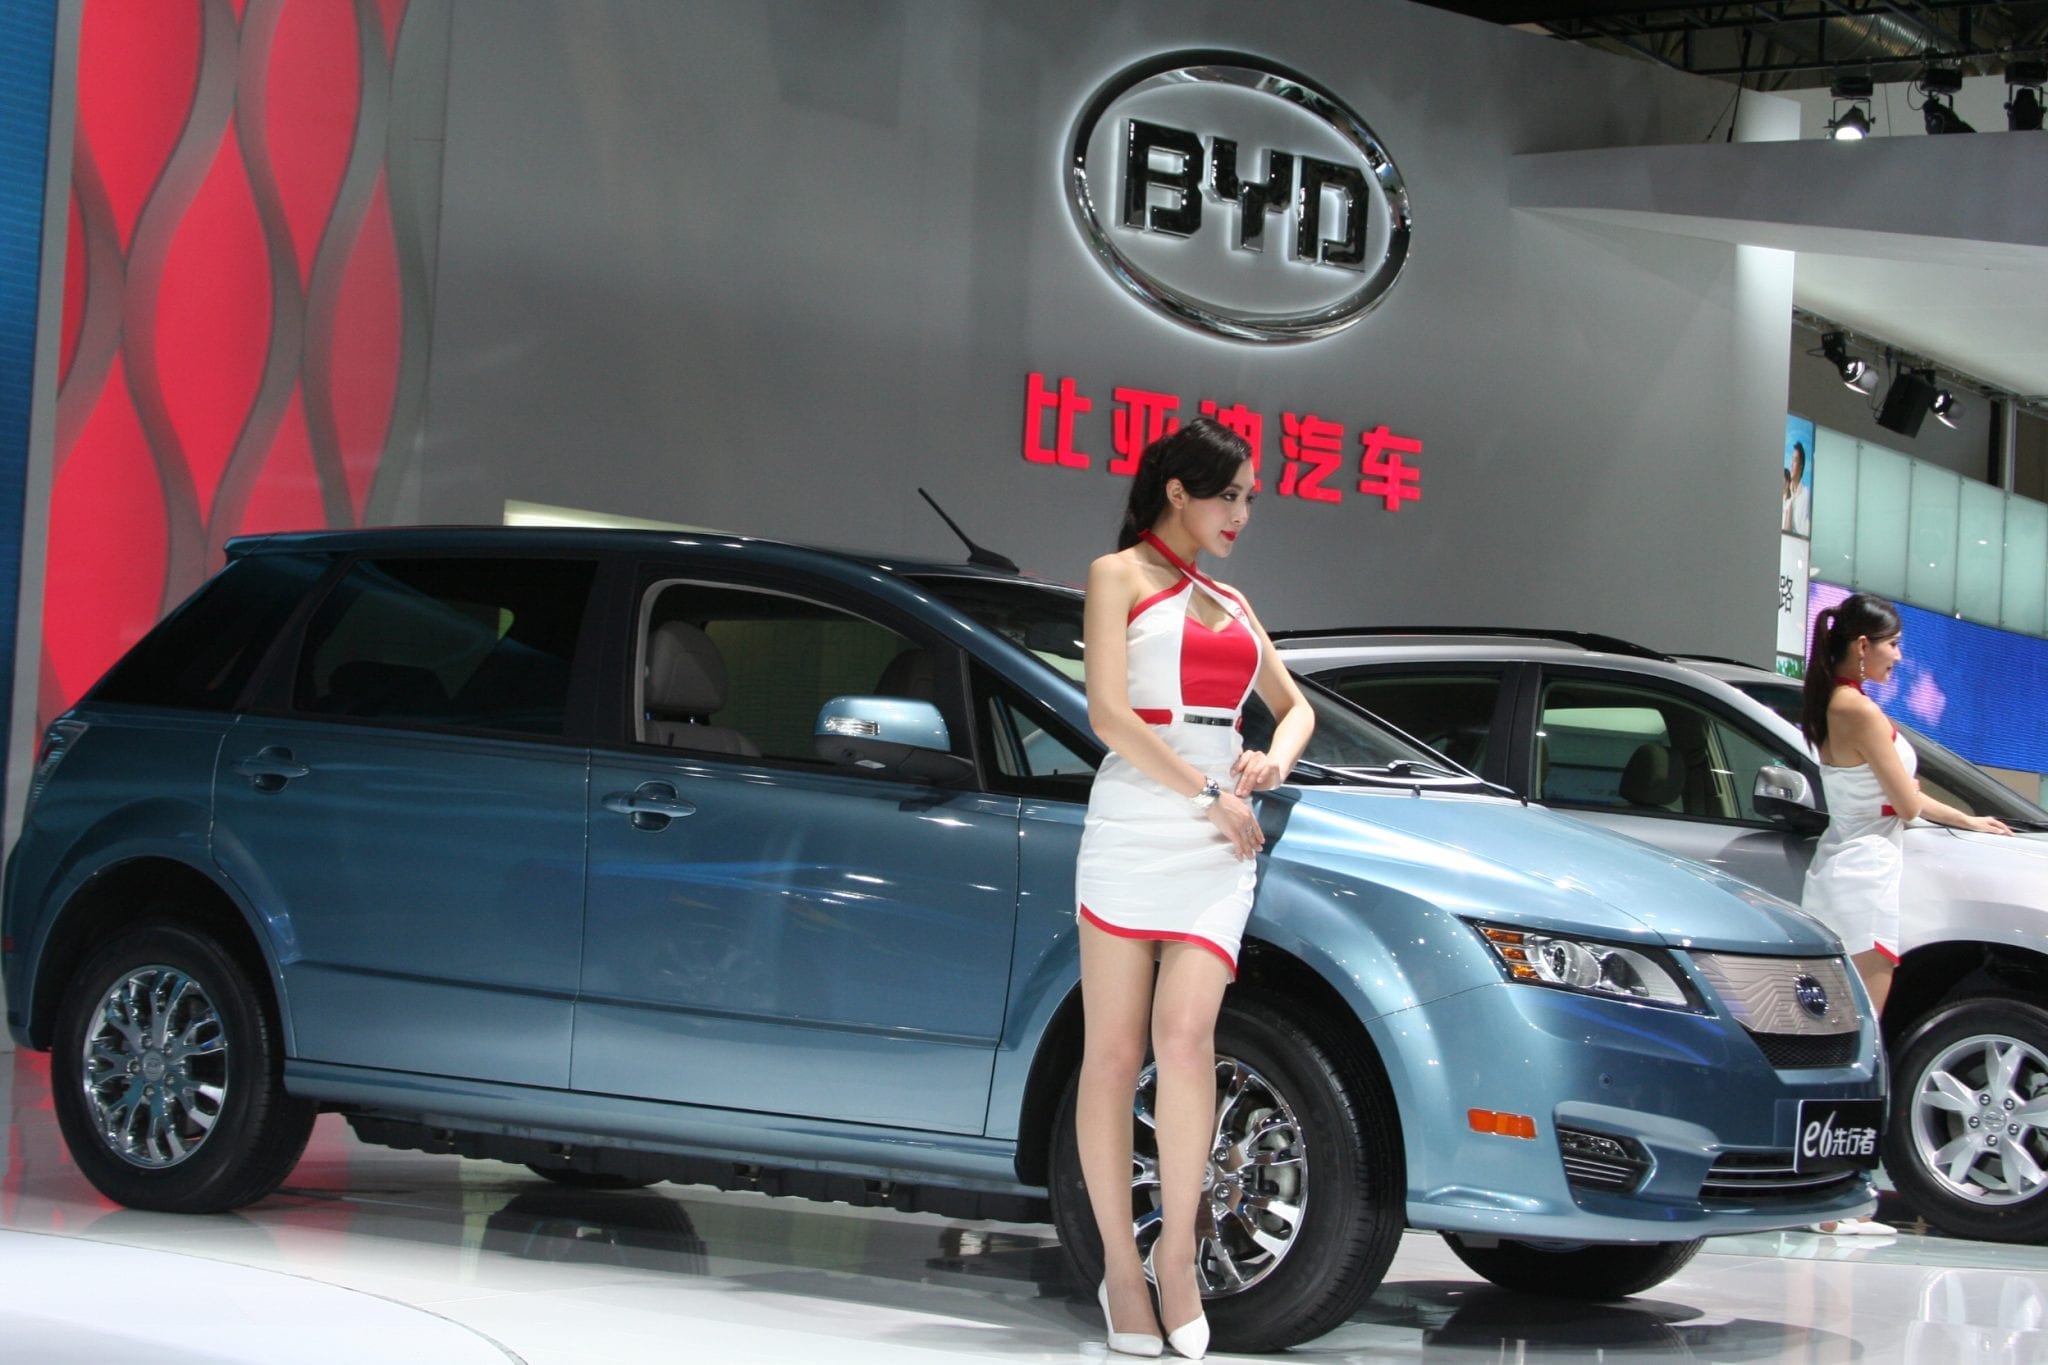
    BYD will develop compact electric cars for Europe using vehicle architecture and battery technology adapted from its Racco microcar sold in Japan for 2,145,000 yen.

    The plan uses the structural layout of the Japanese mini-vehicle to anchor a new line of small urban cars tailored to export markets. While the Japanese Racco measures 3.40 metres long and 1.48 metres wide, the export derivatives will be larger to match European consumer preferences and safety standards.

    Underfloor Battery Integration

    Central to the export project is the X-Pack battery format developed for the Racco. The design packs the motor inverter and primary control units directly inside the underfloor battery housing rather than mounting them separately in a traditional front motor bay.

    That unit combines with BYD’s lithium iron phosphate Blade cells in a cell-to-body structure where the pack functions as a load-bearing chassis component. By eliminating standalone control housings and shortening internal wiring runs, the company cuts manufacturing costs and frees up passenger space inside short-wheelbase bodies.

    In Japan, the Racco runs on a 36 kilowatt-hour pack and a 47-kilowatt front-axle motor, delivering a range of 320 kilometres. The European variants will use scaled versions of the same integrated platform to hit higher cruising speeds while keeping overall vehicle length under 4.20 metres.

    Positioning Below The Dolphin Surf

    Staying under the 4.20-metre threshold allows BYD to target the European Union’s proposed M1E small-vehicle classification, which is expected to carry regulatory incentives. The planned models will sit below BYD’s existing 3.99-metre Dolphin Surf hatchback.

    European legacy brands have struggled to build profitable electric city cars below the 20,000-euro mark because small battery packs carry high fixed component costs. BYD’s transfer of Japanese kei-car packaging gives the Shenzhen carmaker a direct shortcut into entry-level pricing in Western markets.

    Production of the new compact models could feed into BYD’s passenger car assembly plant in Szeged, Hungary, where trial production began earlier this year.

  • China Orders Automakers to Curb Overseas Price Cuts as Exports Surge

    China Orders Automakers to Curb Overseas Price Cuts as Exports Surge

    China ordered domestic automakers to halt volatile overseas price cuts and deceptive marketing across foreign markets on Tuesday, after passenger car exports reached 5.18 million units through July.

    Shipments of electric and plug-in hybrid vehicles jumped 129 per cent to roughly 2.77 million units over the same seven-month period.

    Jointly released by the Ministry of Commerce, the Ministry of Industry and Information Technology, and the State Administration for Market Regulation, the 20-article rulebook targets predatory pricing practices that damage brand reputations abroad. The agencies directed manufacturers to set export prices based on production costs and local supply, avoid abrupt discounts, and give foreign dealerships full autonomy over retail pricing. Sales incentives, customer gifts, and financing promotions must also comply transparently with host-market laws.

    Rules for Dealerships and Data

    Beyond showroom floors, the guidelines govern physical factory investments, which currently span more than 80 countries. Auto groups setting up regional assembly plants must adhere to local workplace safety, intellectual property protections, after-sales requirements, and labor standards.

    The policy also places strict limits on software and vehicle intelligence. Companies running connected-car or autonomous-driving systems abroad must handle consumer privacy and cross-border data transfers in accordance with local regulations.

    Exporting Domestic Competition

    Prolonged price wars inside China squeezed dealer margins and triggered aggressive showroom discounting over the past two years. By extending regulatory supervision overseas, Beijing is stepping in to prevent state-backed and private manufacturers from exporting those destructive discounting tactics into Southeast Asia, Europe, and Latin America.

    Passenger new energy vehicle shipments reached 540,000 units in July alone, capturing 58.8 per cent of total passenger exports, as manufacturers attempt to outpace the 8.32 million total vehicles China exported worldwide in 2025.

  • Kering Redirects up to €300 Million to Asia as Regional Sales Grow 12 per Cent

    Kering Redirects up to €300 Million to Asia as Regional Sales Grow 12 per Cent

    Kering has reallocated up to €300 million in capital toward Asia-Pacific markets as regional sales growth of 8 to 12 per cent outpaced softer Western demand across its fashion portfolio.

    Asian territories now generate nearly half of total group revenue, led by Greater China at 20 to 25 per cent, Japan at 8 to 10 per cent, and the rest of Asia-Pacific contributing 10 to 15 per cent.

    Where the Revenue Comes From

    Direct-to-consumer flagship boutiques in cities like Shanghai and Tokyo anchor the group’s regional retail network, capturing full-margin sales. Wholesale partnerships with upscale department stores account for 35 to 40 per cent of total volume, while digital commerce platforms generate 15 to 20 per cent. The standalone eyewear division adds between €1.5 billion and €2 billion annually across all licensed and owned lines.

    Yves Saint Laurent proved the strongest performer in the region. The label expanded at annual rates of 25 to 30 per cent in Asian markets between 2019 and 2023, lifting global house sales from €3.18 billion in 2022 to an estimated €3.7 billion by 2024.

    Brand Performance and Capital Shifts

    Gucci remains the conglomerate’s largest single cash generator, producing roughly €9.5 billion in 2024 revenue. Its share of group intake fell from 52 per cent in 2022 to 48 per cent, prompting management to divert capital toward faster-growing labels and regional retail upgrades.

    Bottega Veneta generated between €1.8 billion and €1.95 billion with gross margins reaching 68 per cent, driven by leather goods demand. Balenciaga showed signs of recovery with projected growth of 5 to 8 per cent after revenues contracted 15 per cent during 2023.

    European luxury groups spent the past two years reassessing their heavy reliance on flagship labels in Asia. While rivals like LVMH diversified early across jewellery and hospitality, Kering’s concentrated bets on fashion houses make regional retail productivity critical to its bottom line.

    Management continues to review smaller portfolio brands generating under €200 million annually, with further divestment decisions expected as capital shifts to primary retail hubs.

  • Star Leap Overhauls Beauty Sourcing as Global Markets Fragment

    Star Leap Overhauls Beauty Sourcing as Global Markets Fragment

    Hong Kong supply chain distributor Star Leap has revamped its cosmetics procurement model to target regional divergences across Southeast Asian, European, and American beauty retail markets.

    The company confirmed that global demand patterns no longer align across key consumer territories, forcing wholesalers to match stock directly to local channel mechanics rather than relying on global brand awareness.

    Shifting Channel Demands Across Regions

    Market dynamics are splitting along regional lines. In Vietnam and across wider Southeast Asia, multinational cosmetics labels face stiff competition from domestic brands, producing a price-sensitive consumer base with distinct SKU preferences.

    Western territories show different retail drivers. United States retailers are tying physical store sales directly to artificial intelligence tools and virtual testing setups, while European buyers are shifting purchasing budgets toward South Korean and Japanese beauty imports at the expense of traditional domestic lines.

    Matching Inventory to Local Channels

    Distributors must balance unit costs against shelf-life constraints and regional stock velocity. Star Leap tracks purchasing costs, batch codes, and SKU assortments against specific distribution channels to prevent unsold stock sitting in secondary markets.

    Cross-border beauty logistics across Asia Pacific historically relied on moving excess inventory between territories when domestic demand slowed. Rising import compliance standards and the rapid growth of domestic Southeast Asian brands have largely closed those secondary arbitrage routes.

    Procurement teams are now locking in smaller, localized batch orders as retailers prepare their mid-year stock allocations across Asian department stores and regional e-commerce platforms.

  • Chagee Same-Store Sales Fall 16.1% in China as Network Shifts Direct

    Chagee Same-Store Sales Fall 16.1% in China as Network Shifts Direct

    Chagee posted a 16.1 per cent drop in same-store gross merchandise value across Greater China for the second quarter, marking its fifth consecutive quarter of double-digit declines at home.

    Total revenue for the Nasdaq-listed tea chain edged up 2.5 per cent year on year to RMB3.4 billion (US$503.3 million) in the three months ended June 30, while operating income jumped 387.6 per cent to RMB524.7 million. Total gross merchandise value fell 5.5 per cent to RMB7.66 billion, weighed down by a 9 per cent contraction in Greater China to RMB7.16 billion.

    Network shifts to corporate stores

    Chagee is responding to cooling domestic demand by buying back franchised outlets and running them directly. In Greater China, company-operated stores jumped from 164 to 624 over the past twelve months, while franchised locations declined from a peak of 6,836 in September 2025 to 6,616.

    Those company-owned outlets made up 11.6 per cent of the total network at the end of June but generated 27.5 per cent of overall revenue. Direct-store revenue climbed to RMB940.6 million, offsetting an 18.1 per cent fall in franchise revenue to RMB2.47 billion. Meanwhile, active members fell from 50 million in the first quarter to 47.1 million.

    China’s beverage chains are grappling with the aftermath of an aggressive 2025 delivery platform price war that drove cup prices down to single digits. While rivals like Mixue and Heytea rely heavily on deep discounting and sheer store density, Chagee is attempting to lift unit margins by consolidating ownership of its best locations.

    Overseas footprint doubles

    Outside China, gross merchandise value rose 114.3 per cent to RMB504 million. Chagee expanded its international footprint to 399 stores from 208 a year earlier, with initial momentum in new territories including South Korea, where its first three Seoul locations sold more than 16,000 cups in three days.

    Yet existing international stores are feeling the same demand pressures as domestic sites. Overseas same-store GMV declined 15.1 per cent during the quarter, steepening from a 12 per cent drop in the first three months of the year.

    Investors will watch whether the pace of franchise buybacks can stabilize network revenue before international same-store sales deteriorate further in the third quarter.

  • Shein Targets US$1.7 Billion Hong Kong Listing After Shifting Focus to China

    Shein Targets US$1.7 Billion Hong Kong Listing After Shifting Focus to China

    Shein will debut on the Hong Kong stock exchange on Tuesday, seeking to raise US$1.7 billion after abandoning earlier plans to list in New York and London.

    The listing values the fast-fashion group at US$26.5 billion, down from its peak valuation of more than US$100 billion in 2022. That drop follows years of regulatory hurdles in the West and an extensive effort to secure approval from Chinese market authorities.

    Supply Chain Commitments and Regulatory Clearances

    Founded in Nanjing in 2012, Shein shifted its corporate headquarters to Singapore in late 2021 as part of an attempt to position itself as a global retail player. That strategy ran into resistance from Chinese regulators, including the China Securities Regulatory Commission, which reviews foreign-registered businesses with substantial domestic operations.

    Founder Sky Xu responded by taking direct charge of regulatory relations in China. Xu made a rare public appearance at a February business forum in Guangdong province, pledging a US$1.5 billion investment to expand the company’s supply chain network across the region.

    The company also opened a research and development centre in Nanjing. In its Hong Kong listing prospectus, Shein confirmed that mainland China remains the central anchor of its logistics network and accounts for nearly 80 per cent of its total workforce.

    Western Market Pressures Reshape Listing Strategy

    Attempts to secure listings in the United States and the United Kingdom unraveled under heightened political and regulatory scrutiny. US lawmakers pushed for supply chain audits under the Uyghur Forced Labor Prevention Act, while trade policy shifts eliminated the US$800 de minimis customs exemption that originally accelerated Shein’s cross-border parcel volumes. European authorities introduced comparable parcel handling charges.

    Former executive chairman Donald Tang stepped down ahead of the Hong Kong filing after his previous public remarks claiming American corporate values drew criticism from Chinese officials.

    For retailers across Asia, Shein’s pivot illustrates the limits of cross-border corporate restructuring when manufacturing remains concentrated in southern China. Regional e-commerce operators face a tighter compliance environment globally, leaving Hong Kong as the primary capital market for Chinese-rooted digital exporters.

    Trading begins on Tuesday on the Hong Kong exchange, where investors will test Shein’s revised pricing against slowing margins in overseas markets.

  • Shein Shares Drop 8 per Cent in Hong Kong Debut

    Shein Shares Drop 8 per Cent in Hong Kong Debut

    Shares in Shein fell 8 per cent on their first day of Hong Kong trade on Tuesday, valuing the online fast-fashion retailer at roughly US$24 billion.

    The morning price of HK$44.60 represents a steep reset from the company’s peak valuation of nearly $100 billion in 2022. Hong Kong’s benchmark Hang Seng Index slipped 0.6 per cent over the same session.

    Shein turned to Hong Kong after regulatory pushback from Chinese authorities blocked earlier listing attempts in New York and London. The public offer sold about 6.6 per cent of the company’s enlarged share capital. Cornerstone investors took roughly one-fifth of the shares on offer, leaving just 5 per cent freely tradeable under a six-month lockup agreement.

    Valuation gap with regional rivals

    Investor appetite remained muted throughout the sale. The retail portion was subscribed 5.63 times and the international tranche 2.59 times, trailing the hundreds-fold subscriptions common in Hong Kong’s technology and robotics listings.

    Saxo market data shows Shein listed at 15 times forward earnings. That multiple is more than double the valuation of PDD Holdings, the owner of Temu, giving Shein a premium price tag despite heightened geopolitical friction and slower earnings visibility across major Western markets.

    RetailNews Asia notes that the muted debut reflects how quickly cross-border e-commerce economics deteriorated once Western customs loopholes vanished. For years, Chinese discount retailers expanded into the US and Europe by relying on tax exemptions for low-value parcels. Now that both jurisdictions levy duties on direct-shipped goods, margins across the entire ultra-fast fashion export sector are compressing simultaneously.

    Tariffs squeeze operating margins

    Policy changes in Shein’s largest markets dismantled its core cost advantage. The US repealed its duty exemption for packages under $800 last year, and the European Union instituted collection fees on small consumer shipments.

    Higher customs duties, tariffs and logistics expenses across Europe and the Middle East dragged Shein’s net income down 39 per cent last year, pushing the business into an operating loss in the first quarter. To compensate earlier venture backers who bought in at higher price points, Shein agreed to disburse $3.5 billion in cash payments and execute share adjustments for select preferred stockholders.

    Management has turned to acquisitions and marketplace fees to diversify revenue. The company purchased American clothing label Everlane in May, adding to earlier takeovers of British brand Missguided and French fashion label Pimkie.

    Attention now turns to Shein’s upcoming first-half financial report, where the company projected operating profit margins will fall below first-quarter levels.

  • Asia Air Cargo Rates Diverge as Transpacific Prices Surge 30 Percent

    Asia Air Cargo Rates Diverge as Transpacific Prices Surge 30 Percent

    Air cargo rates from China to the United States climbed 30 per cent year-on-year ahead of the peak shipping rush, driven by steady semiconductor and e-commerce shipments.

    By contrast, rates on the China-to-Europe corridor rose 12 per cent over the same period, slowed by the European Union ending its de minimis tax exemption on July 1.

    The price split reflects an uneven recovery across Asian export corridors. While air space out of Taiwan remains tight on artificial intelligence hardware, and outbound demand from South Korea, Malaysia and Singapore holds firm, outbound volumes from mainland China and Hong Kong have cooled. Pricing data from the TAC Index shows transpacific air freight maintaining a sharp premium, supported by technology shipments alongside higher jet fuel expenses caused by Persian Gulf shipping disruptions.

    Ground Bottlenecks and Route Shifts

    Airlines and forwarders face wide gaps in aircraft fill rates across the region. Dedicated freighter aircraft operate at roughly 65 per cent average load factors, compared with only 36 per cent for passenger aircraft belly hold space, according to IATA figures cited in the Journal of the Air Transport Research Society.

    Freight forwarder Dimerco Express Group noted that cross-border shippers altered transport modes to bypass tight air lanes, diverting freight between China, Vietnam and Thailand onto road networks and utilizing rail corridors into Europe. Early tariff front-loading by retail importers also pulled seasonal volumes forward into earlier quarters.

    Capacity limits on the ground often matter more than available aircraft. At regional transshipment hubs such as the Maldives’ Velana International Airport, which handled nearly 89,000 tonnes of cargo in 2025, warehouse throughput and labor deployment govern holiday processing speeds rather than runway slots.

    Shifting Asian Supply Chain Flows

    For consumer brands and electronics manufacturers across Asia, these fragmented lane dynamics mean freight procurement can no longer rely on broad regional averages. Shippers managing supply chains out of Taipei or Penang face sustained space premiums that do not match the softer spot rates available out of southern Chinese export hubs.

    Carriers are adjusting winter flight schedules to manage the uneven demand. Velana International Airport expects flight movements to rise 12 per cent during the 2026/27 winter schedule, supported by new scheduled freighter operations including Raya Airways’ weekly service from Penang.

  • Louis Vuitton Exits Chinese Province After Sales Drop and Trademark Dispute

    Louis Vuitton Exits Chinese Province After Sales Drop and Trademark Dispute

    Louis Vuitton closed its retail footprint in a Chinese province after local store sales dropped and a trademark dispute sparked consumer backlash against the French luxury house.

    The pullout follows intense public scrutiny in China over the brand’s legal enforcement of its intellectual property, which prompted pushback from shoppers and weakened foot traffic across regional department stores.

    Reassessing Regional Footprints

    Luxury groups in mainland China are reviewing their exposure to lower-tier provincial markets where operating costs outpace store revenue. Falling retail demand across secondary cities has pushed European fashion houses to trim underperforming storefronts and redirect capital toward flagship flagships in tier-one hubs.

    Shopper sentiment in the affected province turned sharply against the brand during the legal dispute. Local consumers shifted spending away from the label, accelerating management’s decision to shut down operations in the territory entirely.

    Consolidation in Core Hubs

    European luxury labels previously expanded across provincial capitals to capture rising domestic wealth outside Beijing and Shanghai. That expansion model now faces pressure as consumer spending concentrates in top-tier commercial centres and duty-free zones such as Hainan.

    LVMH continues to review its retail network across Greater China, with future store renewal deadlines and regional lease expiries determining where the group will prune or retain square footage.

  • China Shifts Property Market to Completed Homes in Broad Policy Overhaul

    China Shifts Property Market to Completed Homes in Broad Policy Overhaul

    China ordered local governments on Friday to prioritise sales of completed homes over presales, overhauling the housing model to halt a property downturn that has dragged on domestic consumer spending.

    The joint directive from the housing ministry, the natural resources ministry and the National Financial Regulatory Administration targets newly transferred residential land alongside parcels sold without construction planning permits.

    Rules on land and developer financing

    Projects on newly transferred plots must adopt the finished-home sales structure, while sites with existing permits are encouraged to make the transition. Two accompanying notices from financial regulators cleared commercial banks to issue revised development loans and gave securities authorities room to back mergers and restructurings among listed property firms.

    The policy overhaul directly attacks the off-plan financing structure that left millions of buyers waiting for unfinished apartments and froze household balance sheets across mainland cities. “The policies announced today are stronger than what the market expected,” said Zhang Zhiwei, chief economist at Pinpoint Asset Management, noting that weak domestic demand stemmed largely from real estate distress.

    Impact on consumer confidence and household wealth

    Property accounts for the bulk of Chinese household wealth, making housing stability essential for any rebound in retail sales, automotive purchases and consumer services across second-tier and third-tier markets. For consumer brands operating in China, weak property valuations have consistently translated into cautious discretionary spending and higher promotional discounting over the past two years.

    Municipal governments must now issue local execution timetables for the finished-home rules, with developers waiting for commercial banks to publish specific loan quotas under the updated development guidelines.

  • Miniso First-Half Revenue Rises 22% to $1.7 Billion on China and US Gains

    Miniso First-Half Revenue Rises 22% to $1.7 Billion on China and US Gains

    Miniso lifted its first-half revenue 22.4 per cent to RMB11.5 billion (US$1.69 billion) as Chinese domestic demand rebounded and foreign store openings accelerated. Second-quarter revenue rose 17 per cent to RMB5.81 billion (US$856.4 million) in the three months to June 30.

    Domestic sales supplied the momentum. Mainland China revenue climbed 26.2 per cent during the six months, marking the company’s fastest first-half expansion rate in three years. North American operations posted a 37 per cent top-line increase over the same period, while the Top Toy pop-culture unit grew revenue 32.7 per cent.

    Global Store Count Nears 8,700

    Network growth continued across offshore territories. Miniso finished June with 8,674 stores worldwide, adding 769 doors in 12 months. International locations accounted for almost half of all net-new store openings during the year.

    New market entries pushed the retailer’s footprint to 113 countries and territories after opening its first store in Switzerland. Top Toy also moved past mainland borders, adding storefronts in Taiwan and the US. Domestic registered members reached 130 million, up 31 per cent year on year, while US loyalty members doubled to roughly 5.8 million.

    IP Formats and Capital Allocation

    Value retailers across East Asia face margin pressure from discount e-commerce platforms, pushing operators to rely on licensed intellectual property and larger destination shops to protect transaction values. Miniso has shifted toward branded character goods and blind-box toys to lift average basket spend rather than relying solely on cheap household consumables.

    Founder and chief executive Guofu Ye said the group will keep directing capital toward proprietary IP lines and large-format retail sites while pursuing regional localisation.

    Capital management plans remain active following the June rollout of a HK$2 billion (US$255 million) share buyback program, which runs alongside Ye’s personal commitment to increase his equity stake in the business.

  • Chagee Second Quarter Profit Jumps to $68.5 Million as Overseas Sales Surge

    Chagee Second Quarter Profit Jumps to $68.5 Million as Overseas Sales Surge

    Chagee posted a net income of RMB464.8 million ($68.5 million) for the second quarter, up from RMB77.2 million a year earlier as international expansion lifted returns.

    Net margin climbed to 13.6 per cent from 2.3 per cent in the prior-year period. Total revenue rose 2.5 per cent to RMB3.4 billion ($503.3 million) for the three months ended June 30, supported by an 8.5 per cent increase in store count to 7,639 locations worldwide.

    Overseas Momentum Offsets Domestic Softness

    Operating income surged 387.6 per cent to RMB524.7 million after the chain cut operating expenses by 10 per cent. While gross merchandise value dropped 9 per cent in Greater China, sales across eight international markets jumped 114.3 per cent.

    Seoul provided an early spark for that overseas push. Three teahouses in the South Korean capital sold over 16,000 drinks during their first three days, driven by more than 46,000 mobile app downloads recorded ahead of the launch.

    The divergence between domestic and overseas performance reflects the intense discounting battle among premium tea brands inside mainland China. Rivals such as Nayuki and Heytea have faced margin erosion at home, prompting operators to look abroad where pricing power remains intact and consumer demand for Chinese milk tea formats is expanding rapidly.

    Member Retention and Sales Outlook

    Loyalty membership reached 257 million registered users by the end of June. Repurchase rates among active loyalty users held above 43 per cent during the period.

    Management reported that same-store sales declines moderated in July, with comps projected to swing into positive territory in August.

  • China Sovereign Bond Yields Drop to 1.69 per Cent as US Gap Widens

    China Sovereign Bond Yields Drop to 1.69 per Cent as US Gap Widens

    China’s 10-year government bond yield fell to 1.692 per cent on Monday, widening the policy divergence with the United States as domestic economic growth slowed.

    The yield sits near a 12-month low after July retail sales, industrial output, and fixed-asset investment all missed analyst forecasts.

    Brokerages including Great Wall Securities project the 10-year yield will drop further to 1.65 per cent. The slide reflects rising domestic calls for borrowing cost cuts to counter deflation and a prolonged property slump.

    In contrast, long-term borrowing costs in the United States remain elevated. The US 30-year Treasury yield hovered near a two-decade high of 5.304 per cent. Federal Reserve Chairman Kevin Warsh indicated at the Jackson Hole symposium that inflation control remains the primary focus over employment, while eliminating forward policy guidance. US Treasury Secretary Scott Bessent pledged to double a bond buyback programme, yet investors continue demanding higher yields for long-dated American debt.

    Foreign Inflows and Diverging Policies

    Overseas investors purchased 9.5 billion yuan ($1.4 billion) in Chinese government bonds in July, logging their third consecutive month of net buying. Total foreign holdings in China’s nearly 200 trillion yuan debt market stand at approximately 4.3 trillion yuan, representing roughly 2 per cent of the market.

    A stronger yuan alongside lower local yields has helped attract offshore capital seeking insulation from volatile global equities. While the US central bank confronts energy price pressures and heavy fiscal debt issuance under the Trump administration, Beijing faces the opposite challenge of stimulating dormant consumer demand.

    Capital Flows Across Asian Markets

    For corporate borrowers and retailers across Asia, the widening interest-rate spread alters funding strategies. Chinese issuers are leaning harder into yuan-denominated debt to capture ultra-low domestic borrowing costs, while dollar-denominated debt servicing grows heavier.

    Markets now watch whether the People’s Bank of China will deliver an official policy rate cut before the third quarter ends, testing the projected 1.65 per cent floor on sovereign yields.

  • Hong Kong Retains Top Billionaire Spot in Asia with 106 Ultra Wealthy

    Hong Kong Retains Top Billionaire Spot in Asia with 106 Ultra Wealthy

    Hong Kong held its position as Asia’s top billionaire city with 106 ultra-wealthy residents last year, ranking second globally behind New York’s 164.

    The city lost two billionaires over the period even as its aggregate billionaire net worth rose, according to data from research firm Altrata.

    San Francisco, London, Singapore and Los Angeles took the third through sixth spots globally. Beijing placed seventh with 61 billionaires, while Shenzhen and Dubai tied for eighth place with 43 each.

    AI Gains Shift Wealth Creation

    New York added 12 billionaires during the year as the artificial intelligence investment boom propelled technology fortunes higher. Global billionaire numbers recorded their fastest pace of expansion since 2020, with the United States and mainland China remaining the only countries holding multiple cities in the top 15 rankings.

    Hong Kong and London were the only hubs in the top 15 to register declines in billionaire headcount. A prolonged downturn in Hong Kong’s real estate sector and relatively limited exposure to direct AI equity gains curbed new entries.

    Asian Hubs Draw Inbound Capital

    Banking and finance accounted for the largest share of global billionaire fortunes at 19.6 per cent, more than double the proportion held by business and consumer services. Across the worldwide cohort, the average age stood at 71, with men representing 86.9 per cent of the total.

    For luxury operators, private banks and commercial landlords across Asia, the shifting balance between property and technology fortunes alters where discretionary capital flows. Both Hong Kong and Singapore continue to draw high proportions of foreign-born billionaires, particularly from mainland China and India, supporting prime retail footfall and asset management inflows despite broader market volatility.

    Attention now turns to whether mainland China’s expanding tech sector can push Shenzhen and Beijing past European wealth centres in Altrata’s next census.