Tag: Japan

  • Mixed fortunes for online and offline retailers in Japan and Korea

    Mixed fortunes for online and offline retailers in Japan and Korea

    Brands in the tech sector are likely to record mixed fortunes as a result of the COVID-19 pandemic, with retail tech brands predicted to fare the best compared to leisure and tourism tech brands, which are expected to suffer considerably, according to the latest report by Brand Finance. The top 100 most valuable tech brands, on average, should see a slight decrease in brand value following the pandemic, falling 5%.

    The Brand Finance Tech 100 2020 ranking is split into sub sectors, with electronics, software, retail and media & games analysed separately as these brands make up more than 80% of the total brand value in the ranking. All brand values are correct as at 1st January 2020.

    Alex Haigh, Director, Brand Finance, commented:

    “The sheer size and diversification of the tech sector undoubtedly means that brands are going to be affected differently from COVID-19. On the one hand, e-commerce brands are likely to see a boost to their brand values following record high demand. In contrast, other tech brands’ journeys in the coming year could be more turbulent, with supply chains impacted, consumer spending shifting and slowing demand impacting brands’ bottom lines and, in turn, their brand values.”

    Electronics: Apple storms ahead despite losing brand value

    Making up 27% of the total brand value and with 30 brands featuring, electronics are the dominant sub sector in the Brand Finance Tech 100 2020 report. The electronics sub sector is likely to be moderately impacted by COVID-19, with a potential 10% loss of brand value at stake.

    Leading the way is Apple, recording a 9% drop in brand value to US$140.5 billion and simultaneously dropping to 3rd spot in the ranking, with Google (brand value up 12% to US$159.7 billion) overtaking in 2nd.

    Apple has struggled to grow in key emerging markets, showing little motivation to diversify its portfolio. Brand Finance’s analysis shows that Apple could lose up to 20% of its brand value following the pandemic with supply chains broken and consumer spending slowing – the brand will be hoping the return to normality in China could offset some of this damage.

    With an impressive brand value growth of 37%, ZTE is the fastest growing electronics brand – its surge in brand value bolstered by its increased adoption of 5G. Telco equipment brands should be in a solid position to experience good growth as the rise of 5G accelerates globally.

    Software: Google overtakes Apple

    The second most valuable sub sector, software, makes up 21% of the total brand value in the Brand Finance Tech 100 2020 ranking with 15 brands featuring. Brand Finance’s analysis shows that software brands could lose up to 10% of their brand value as a result of COVID-19.

    With a brand value of US$159.7 billion, Google is the most valuable software brand in the ranking and the 2nd most valuable in the overall ranking. Google’s sleek brand extension from software to hardware, is a direct threat to Apple, who have lost their streak of brilliance in recent years. COVID-19 is likely split Google’s fortunes down the middle with Google Cloud predicted to celebrate boosted demand, as remote working becomes widespread. The pandemic does pose a major threat to its advertising business, however, – where the majority of the brand’s revenue comes from – which is inevitably going to slow down.

    Chinese software giant Baidu recorded the largest drop in brand value in the ranking, down 54% to US$8.9 billion. The company reported its first quarterly loss since its initial public offering (IPO) back in 2005. Along with the intense market competition, the brand’s revenues were heavily impacted as regulators placed more attention on online advertising. Baidu is now focusing on other areas to drive long-term growth, such as its cloud division, smart speakers, and even driverless cars in an effort to secure better results for the future. The combination of the economic slowdown in China and COVID-19’s damage to ad sales will no doubt cause some damage to aid-dependent brands like Baudi.

    Retail: Amazon primed for more growth

    Retail brands contribute 19% of the total brand value in the ranking, largely as a result of the sheer dominance and size of the world’s most valuable brand Amazon. Bucking the trend of traditional bricks and mortar retail, e-commerce brands have the opportunity to thrive in the current climate as demand reaches record highs. Retail is, therefore, the only subsector in the Brand Finance Tech 100 2020 ranking, that could potentially see an increase in brand value as a result of COVID-19, up to 20%.

    Breaking the so far unattainable US$200 billion brand value mark, following 18% growth, Amazon remains a cut above the rest. While most brands are experiencing or expecting a slump in revenue during the pandemic, Amazon is set for continued growth. As with fellow e-commerce brands, Amazon has been benefitting from the unprecedented surge in demand as consumers turn online following store closures.

    Japan’s Rakuten is the fastest growing brand in the ranking, recording an impressive 66% brand value growth to US$5.2 billion. The Tokyo-headquartered brand has celebrated strong growth in its domestic e-commerce services and has its sights set on building upon and winning new customers with the aim of cross-use of services to further open up the brand’s ecosystem.

    Media & Games: limited damage from COVID-19

    The 14 media & games brands make up 18% of the total brand value in the Brand Finance Tech 100 2020 report. Eight of these brands hail from the US and have grown, on average, 12% in brand value year on year. Brand Finance’s calculations have found that this sub-sector is going to suffer limited impact from COVID-19, equating to a 0% change in brand value.

    Media & Games’ most valuable, Facebook (brand value down 4% to US$79.8 billion), has negotiated several high-profile reputational issues, most notoriously the Cambridge Analytica scandal, which resulted in a US$5 billion fine last year. The pandemic could, however, turn the tide on the tarnished brand, as people are forced to keep in touch with friends through social media. Facebook has also been developing a symptom survey, which is hoped to reveal a lot about COVID-19 and contribute to research.

    In contrast, Facebook-owned Instagram has enjoyed an explosion of growth, securing the second-highest brand value increase among all tech brands this year, up 58% to US$26.4 billion. The platform is successfully leveraging its position in the market as a genuine business tool – beyond its traditional influencer market – as more businesses move online during the lockdown.

    In line with positive trends in brand value among other video streaming services, last year also saw Netflix enjoy an 8% boost in brand value to US$22.9 billion. Netflix has been a pioneering force in changing consumers’ viewing habits. This success has only been spurred on by COVID-19, with the timely release of Tiger King raking in 34 million US viewers in the first 10 days alone.

    In addition to calculating overall brand value, Brand Finance also determines the relative strength of brands through a balanced scorecard of metrics evaluating marketing investment, stakeholder equity, and business performance. Alongside revenue forecasts, brand strength is a crucial driver of brand value. According to these criteria, WeChat is the world’s strongest tech brand with a Brand Strength Index (BSI) score of 92.9 out of 100 and a corresponding elite AAA+ brand strength rating.

    WeChat has significantly broadened its proposition since its inception, successfully leveraging its brand to develop an extraordinary level of vertical product integration. With WeChat Pay now being accepted in more than 60 countries and the platform opening to international travellers in China for the first time, the brand has set its sights on global markets.
  • Shiseido plans sale of consumer product lines for over $1.45 billion

    Shiseido plans sale of consumer product lines for over $1.45 billion

    Japanese cosmetics firm Shiseido Co Ltd said on Friday it was in talks to sell its lower-priced skincare and shampoo lines to private equity firm CVC Capital Partners in a deal reported to be valued at over $1.45 billion.

    Shiseido said it was in talks to sell its “personal care” business in the first half of the year to CVC but that no decision had been made.

    The business includes its Tsubaki shampoo and Sea Breeze deodorant brands which are sold at drugstores and convenience stores throughout Asia.

    The talks were first reported by Bloomberg News, which put the value of the deal at between 150 billion to 200 billion yen ($1.45 billion-$1.93 billion).

    Shiseido said it was considering taking a stake in the business and remaining involved in its development.

    The talks come as Shiseido has been eyeing possible asset sales to focus on premium cosmetics, including its namesake line and brands such as Cle de Peau and NARS sold at department store counters.

    Global private equity firms such as CVC and Carlyle Group have recently been looking to expand in Japan, taking advantage of large Japanese companies coming under pressure to sell non-core assets and improve returns to shareholders.

    CVC last year raised $4.5 billion for its fifth Asia Pacific fund.

    Like other companies in the luxury sector, Shiseido was hit hard by the coronavirus as people shopped less and wore less make-up. A halt in tourism has been particularly painful as the company depended heavily on Chinese visitors.

    The company said in November that it expects a net loss of 30 billion yen in 2020, worse than a previous forecast loss of 22 billion yen.

    Shiseido shares rose 4% in morning trade on the Tokyo Stock Exchange. A CVC representative declined to comment.

  • Laura Ashley rolls out new stores in Japan

    Laura Ashley rolls out new stores in Japan

    British lifestyle brand Laura Ashley has revealed an expansion plan in Japan with seven new outlets scheduled to open during the first three months of this year.

    New Laura Ashley Japan stores will include those in Tokyu Department Store Sapporo, Tobu Department Store Ikebukuro, Odakyu Department Store Machida and Keikyu Department Store.

    “We will deliver products that beautifully and richly colour your “home” and “living”, including original textiles that are naturally inspired,” the company said in a statement, translated from Japanese. “We will introduce more various items such as women’s wear and home miscellaneous goods.”

    The British retailer entered Japan after trading house Itochu acquired the master license rights. The brand was then sold to The World Group under a sublicense agreement. Besides Laura Ashley, The World Group is also managing other house goods and interiors brands, such as 212 Kitchen Store, One’s Terrance, and Timeless Comfort.

    Laura Ashley was one of the world’s first high-profile retailers to collapse due to the Covid-19 pandemic last year.

  • Nomura Hires More Than 20 Private Bankers

    Nomura Hires More Than 20 Private Bankers

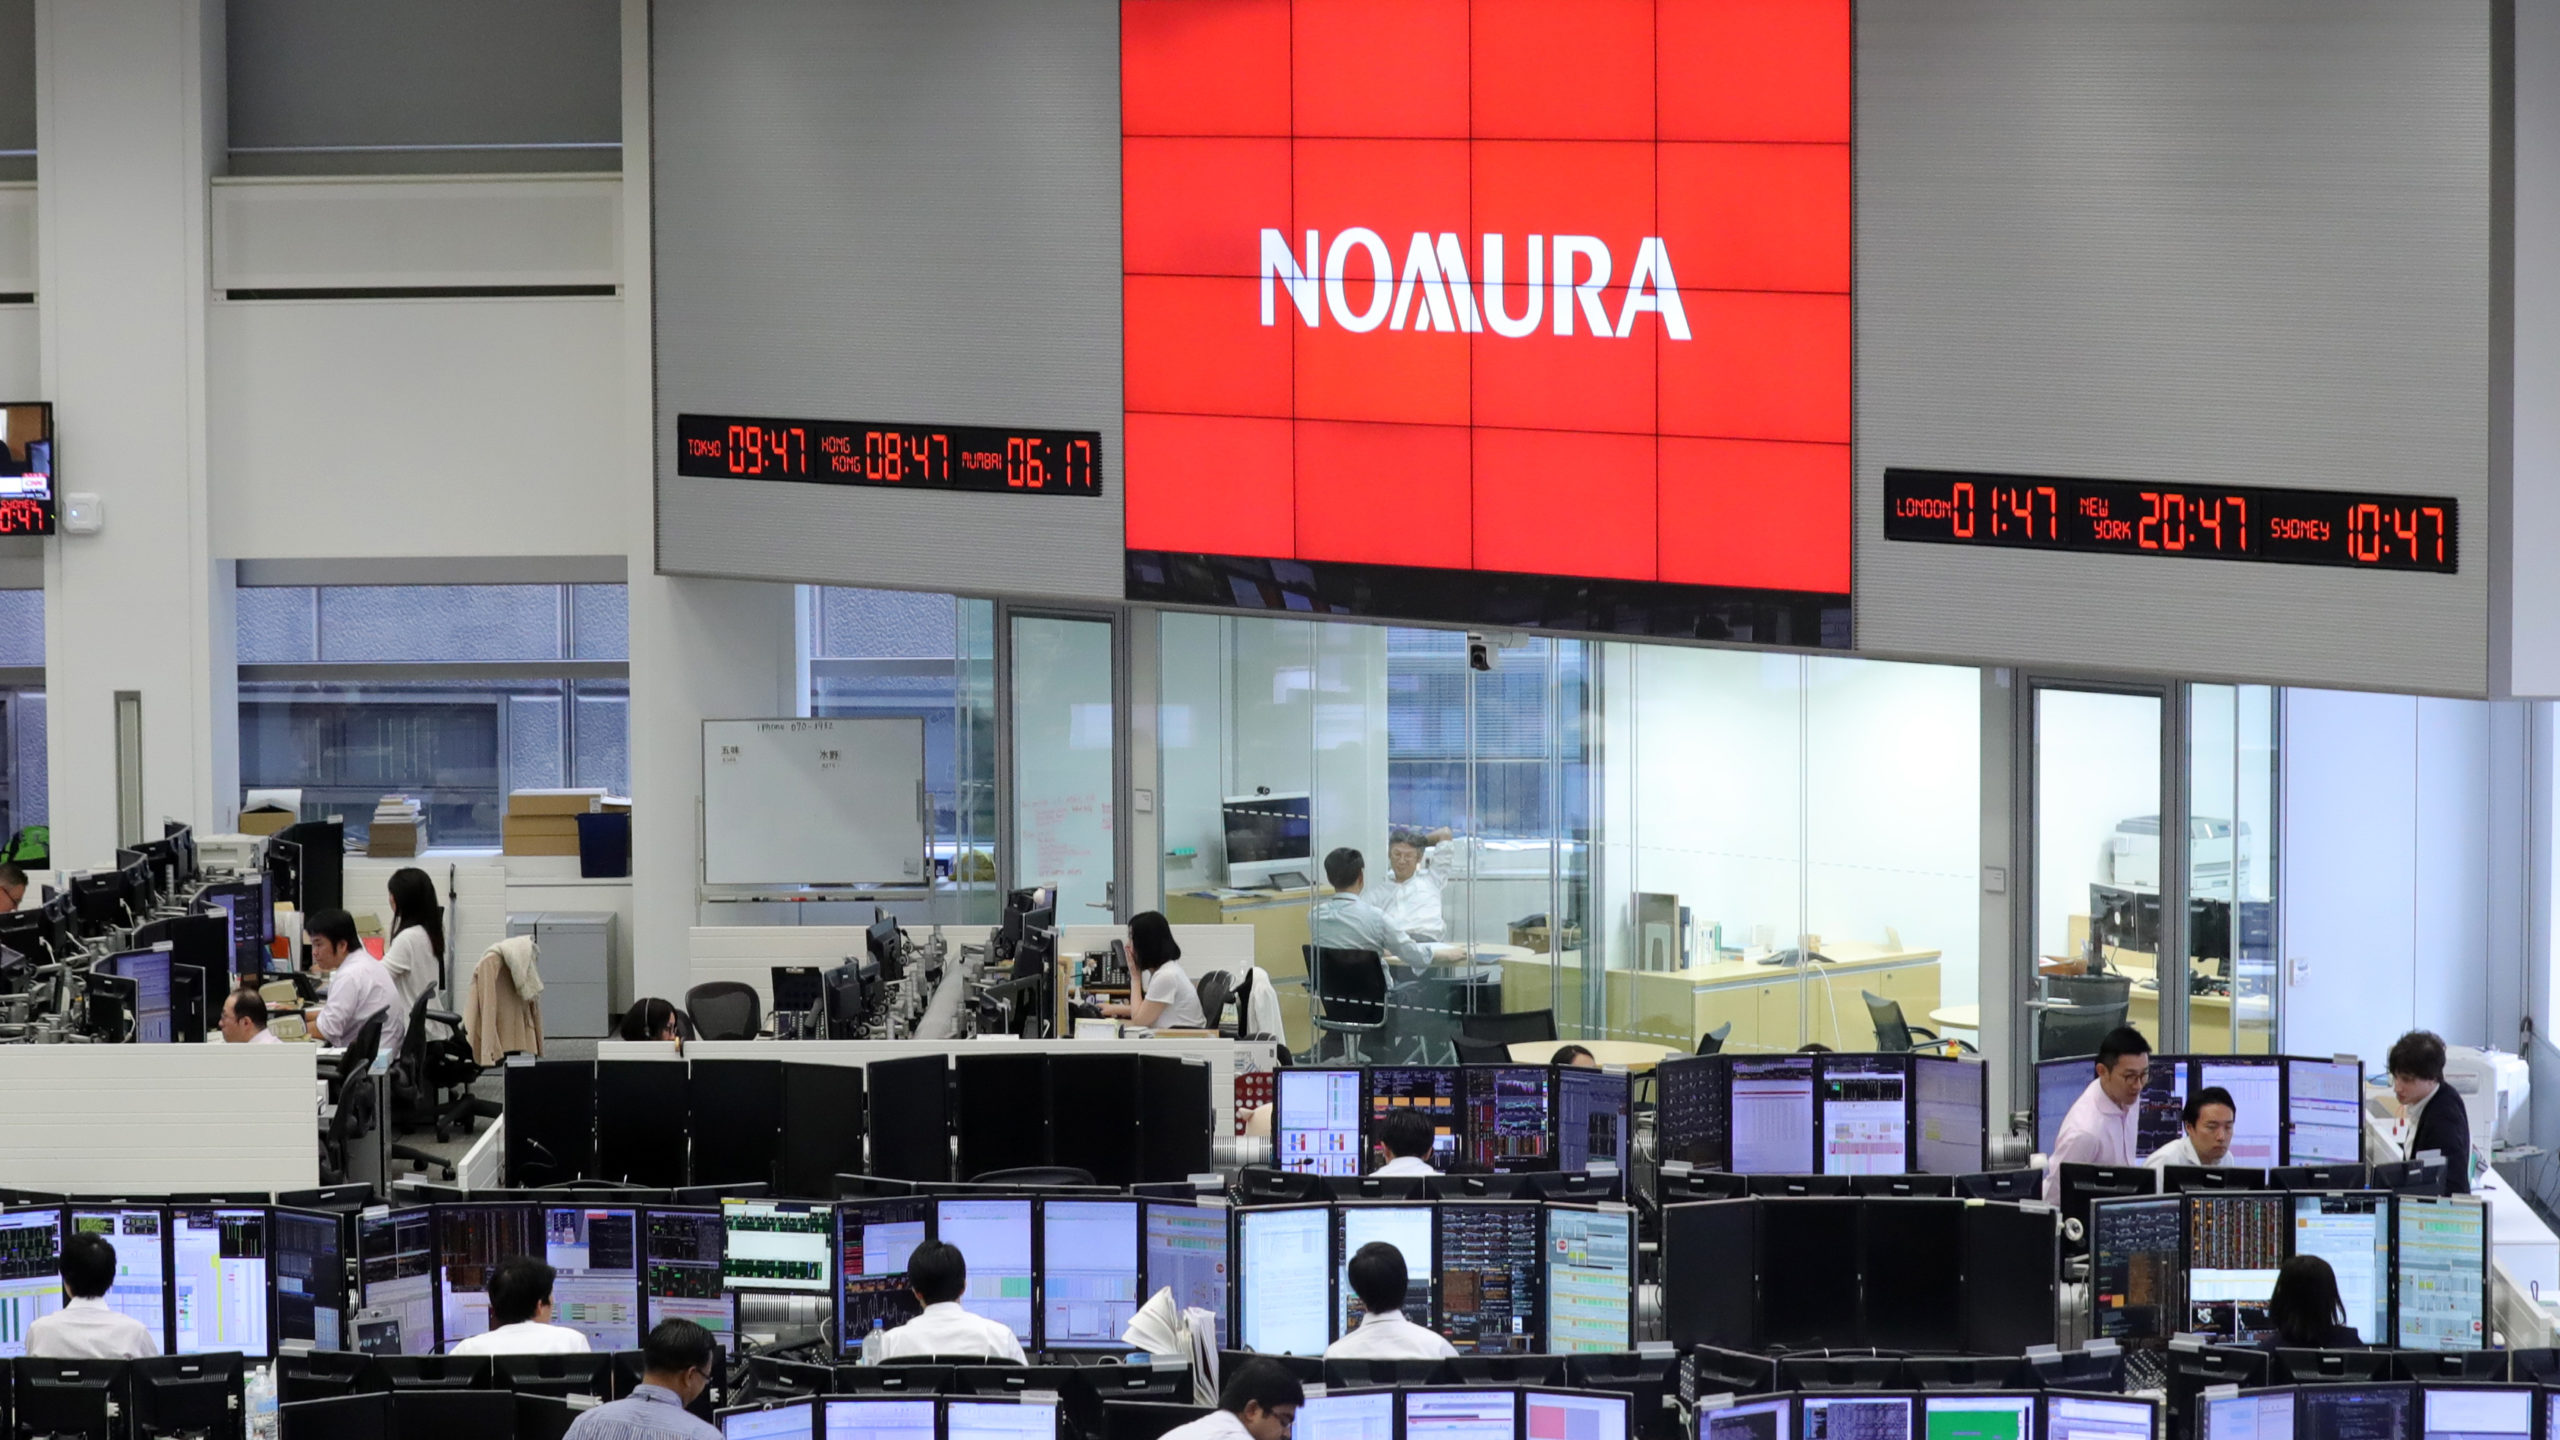
    Japanese bank Nomura aims to more than triple assets under management in its International Wealth Management business by March 2025, through an accelerated expansion of the client franchise and enhancement of the wealth management product and services platform.

    All these individuals have been hired in Hong Kong and Singapore following the integration of International Wealth Management into Nomura’s Wholesale business, and the appointment of Ravi Raju as Head of International Wealth Management in September 2020, the firm said in a media release on Tuesday.

    Our ability to attract top talent from the industry is an acknowledgment by the market that we are serious about our ambitions to build a leading wealth management business and are well-positioned as a platform of choice for aspiring relationship managers in the region. The initial focus of the recruitment drive has been to strengthen our presence across Greater China, Southeast Asia and the Global South Asia market,» he said. Some of the senior hires include:

    Client Coverage

    Wayne Yang has joined as Managing Director and Group Head, Greater China, from Baxian Private and Investment Bank, where he was CEO. He started his career more than 30 years ago and has held multiple senior-level positions at private banks including two stints spanning two decades at Citi’s private bank. He has also held leadership roles at the Asia Pacific private banking teams of Merrill Lynch and Deutsche Bank.

    Trevor Mak has been hired as Managing Director and Relationship Manager for Hong Kong. He joined from UOB Kay Hian where he was Managing Director, Private Wealth Management, since March 2020. Before that, he was a Managing Director at Citigroup’s private bank, covering Hong Kong HNW clients for over 12 years. He started his banking career with Standard Chartered in 1984 in Hong Kong, and has worked in private banking at UBS, Coutts, Standard Chartered and Julius Baer.

    Johnny Liu was appointed Managing Director focused on family office coverage for Greater China. He joined from Aldworth Management, a family office, where he was a partner. Before that he was Managing Director and Head of Global UHNW Advisors, Greater China, at UBS’s private bank. He has also worked at HSBC, Credit Suisse and Deutsche Bank in wealth management and investment banking roles.

    Kitty Chen joined as Managing Director and Team Lead for China. She moved after a short stint as Managing Director with Union Bancaire Privee in their Hong Kong office. Before that, she was an Executive Director at Credit Suisse’s private bank, where she spent eight years covering mainland China-based clients. She has also worked in the private banking divisions of Merrill Lynch, ING and HSBC.

    Adil Khan has been appointed Managing Director and Group Head, Southeast Asia, focusing on the NRI market in the Middle East and Southeast Asia as well as the Middle East market. He joined from Citi Private Bank where he was Managing Director and Team Head for the Global India business, and was responsible for the Middle East desk in Asia, working with bankers from the Middle East booking business into Asia. Prior to that, he was Middle East CEO for EFG Bank, based in Dubai.

    Brajesh Jha has been appointed Managing Director and Group Head, Southeast Asia. He joined from BNP Paribas Wealth Management where he was Managing Director and Head for Southeast Asia markets that included Thailand and Vietnam for three years. Prior to BNP, he spent over 10 years with UBS, both in wealth management and investment banking in multiple senior roles.

    Mohit Gupta has joined as Managing Director and Team Lead for Southeast Asia NRI from BNP Paribas Wealth Management where he was Managing Director and Team Head, Indian Markets, covering family offices and UHNW clients from Singapore. Prior to this, he was in various investment advisory roles with Credit Suisse and Standard Chartered for 12 years.

    Charly Madan has been appointed Managing Director and Team Lead, Southeast Asia, focusing on Thailand and Vietnam. He joined from BNP Paribas where he was also Managing Director and Team Leader responsible for UHNW clients in Thailand and Vietnam. He has over 30 years of experience in financial services and has held several senior roles in Thailand including Chairman of CNP REIT, CFO & CRO of Pruksa Real Estate, Country Executive, Thailand, and Asia Pacific Head of Capital and Portfolio Management at Royal Bank of Scotland, Head of Corporate Banking at Bank of Ayudhya and Country Officer at Citibank.

    Nini Rojanavanich has been appointed Executive Director and Relationship Manager, Southeast Asia, covering Thailand and Vietnam. She joined from BNP Paribas Wealth Management in Singapore where she was a Director in the UHNW client segment for Thailand. Prior to that, she was with Sumitomo Mitsui Banking Corporation in charge of its Financial Institutions Group in Thailand, and has held other leadership roles with institutions including Royal Bank of Scotland, Citibank, Bangkok Bank and ABN AMRO.

    Umesh Pandey has been appointed Executive Director and Relationship Manager, Southeast Asia, covering Thailand and Vietnam. He joined from BNP Paribas Wealth Management which he joined in October 2019. Prior to that, he was in the media industry, having spent 16 years over two stints at the Bangkok Post where his last role was as Editor-in-Chief. He has also worked as a Thailand correspondent for Reuters and The Wall Street Journal.

    Kripa Bathija has joined as Executive Director and Relationship Manager covering family offices and UHNW clients in Southeast Asia. She was at Bank of Singapore where she was a Director covering a similar demographic of clients for over seven years. She has also worked with Citibank across various geographies for seven years, with the majority of that time spent with the firm’s Singapore wealth management unit focused on the NRI business.

    Investment Products & Advisory Solutions

    Akshay Prasad has joined as Managing Director and Head of Investment Products & Advisory Solutions, Asia Pacific, from Deutsche Bank’s wealth unit where he worked for nearly 14 years. His last role there was as Managing Director and Head of Investment Advisory, Global South Asia, where he managed a sales team delivering cross-asset advisory and discretionary solutions for clients across Asia and Europe. He started his career with Citi’s wealth management unit.

    Sooraj Arur has joined as Executive Director and Head of Lending & Credit Solutions, Asia Pacific. He joined from Deutsche Bank where he was a Director in structured lending, originating financing deals, structuring credit solutions and negotiating bespoke loan documentation for Asia Pacific wealth management clients in markets including Singapore, Hong Kong, Indonesia, Thailand, India and the Middle East. Before Deutsche, he was a credit specialist at Citibank.

    Aditya Sehgal joined as Executive Director to help drive transformation and business development for Investment Products & Advisory Solutions. He came from Deutsche Bank Wealth Management, where he was a Director and cross-asset investment specialist. There, he provided bespoke multi-asset structured solutions for clients’ investment and hedging needs by partnering with coverage teams in Singapore, Hong Kong and Dubai. He worked at Deutsche for 11 years.

    Infrastructure and Platform

    Mohan Kuppuswamy joined as Executive Director and Head of Architecture & Technology, Asia Pacific, from HSBC where he was Program Head for Platform, implementing Avaloq for Singapore and Hong Kong. Prior to that, he worked for eight years in multiple roles at Deutsche Bank in Asia and Europe, and for over a decade at Citibank including at its private bank in treasury, operations and technology.

    TS Murali has been appointed Executive Director and Head of Front Office Risk and Supervision, Asia Pacific. He joins from Citi Private Bank where he was Business Unit Manager, South Asia, for seven years. In this role, he directly managed the sales support team, ensuring the business operated within applicable regulatory frameworks with appropriate operational and control infrastructure. He has worked at Citigroup and its affiliates since 1993 in various roles across business and operations.

  • Sony Starts Testing Vision-S Electric Car On Public Roads

    Sony Starts Testing Vision-S Electric Car On Public Roads

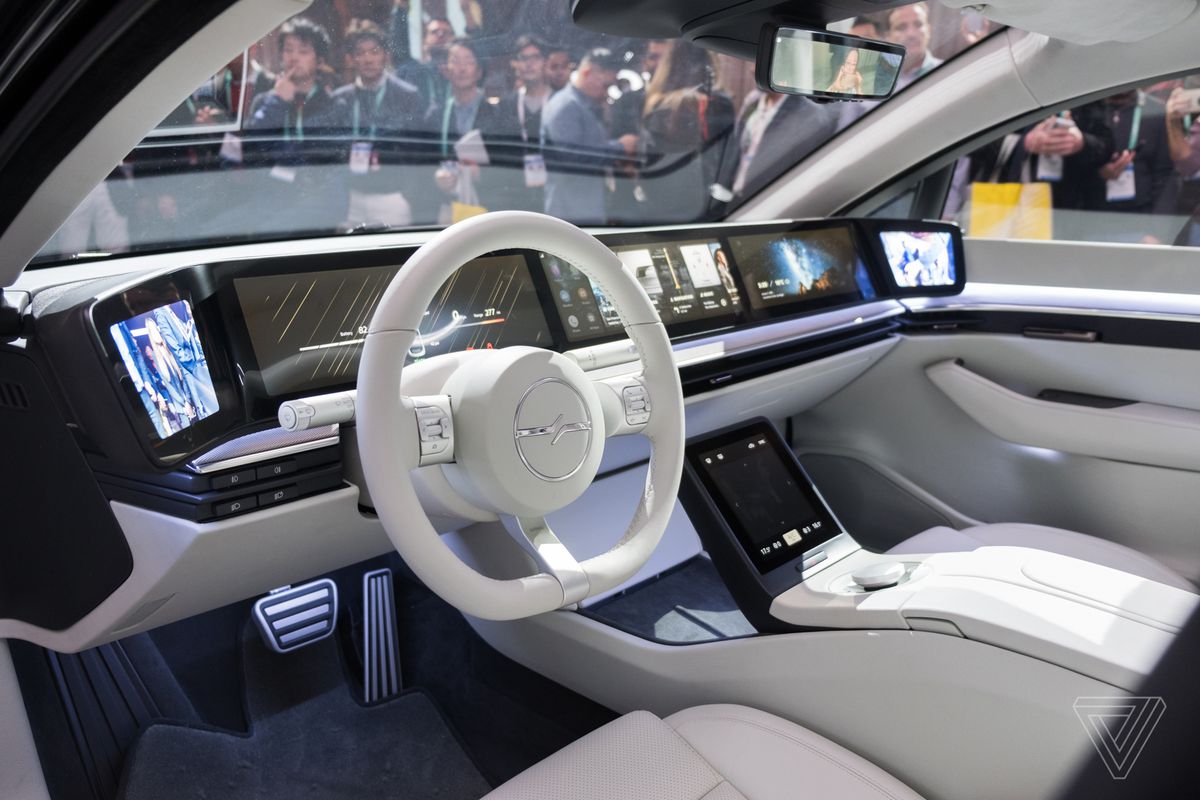
    It was last year at the 2020 Consumer Electronics Show (CES) in January when Sony Corporation surprised everyone by showcasing its fully electric car – Vision-S. The Japanese technology giant revealed the electric prototype which comes packed with high-end technologies including camera sensors, entertainment systems and much more. Sony’s Vision-S Prototype reached Tokyo in July 2020 for advancing its sensing and audio technologies. Though the car is not expected to go on sale anytime soon, the company seems to have started testing the electric car on public roads in Austria.

    Built by an in-house AI and robotics team, the Japanese company claims that it has been fully road-tested. This is just to ensure that the EV and its platform Vision-S will comply with applicable safety norms and regulations. Moreover, Sony is also working Magna-Steyr to ensure that the vehicle is well-equipped to hit the road in Europe.

    Sony’s driverless prototype comes embedded with 33 sensors which can easily sense people and other vehicles both inside and outside the car to provide driving support. It takes advantage of the brand’s expertise in the field of imaging, entertainment and sensors, which could be employed in the next-generation electric vehicles. The company is already supplying these technologies to Japanese automakers, however, it now wants to develop an individual product that can be supplied as an all-purpose solution.

    Sony hasn’t shared any details about what powers the vehicle. However, it has revealed some key specifications of the car. Dimensionally, this prototype vehicle from Sony measures 4,895 mm in length, 1,900 mm in width and 1,450 mm in height. The wheelbase and ground clearance of the car stands at 3,000 mm and 120mm (up to 135 mm) respectively. The company claims that the Vision-S can sprint from 0 to 100 kmph in just 4.8 seconds before hitting the top speed of 240 kmph.

    It is also equipped with Sony’s 360 Reality Audio offering ensuring an unprecedented and immersive audio experience. The company uses object-based spatial audio technology for recreating vivid realism. Every seat comes with built-in individual speakers so that every passenger can enjoy their music their seats with a personalised sound configuration option. Additionally, there’s a panoramic screen which offers a diverse array of content that can be accessed by driver and passengers.

  • Asics shutters New York flagship as Covid plagues business

    Asics shutters New York flagship as Covid plagues business

    Japanese sporting goods maker Asics closed down its New York flagship store in December amid the prolonged impact of the COVID-19 pandemic, the company announced on Monday.

    The store opened in December 2017 on Fifth Avenue, selling running shoes and sportswear. Asics’s decision comes as high rent bites the company, on top of uncertainties around when the pandemic will end.

    Due to the store’s closure, the sports brand is taking an extraordinary loss of about 2.3 billion yen ($22 million) for the fiscal year ended December 2020. The loss is already included in the latest earnings forecast.

    Asics’ sales in North America declined by 19% between January and September 2020, compared to the same period in 2019. The company is expected to take a net loss of 17 billion yen in fiscal 2020. Sales are forecast to decline by 15% to 320 billion yen.

  • More Japanese firms opt for Vietnam after China

    More Japanese firms opt for Vietnam after China

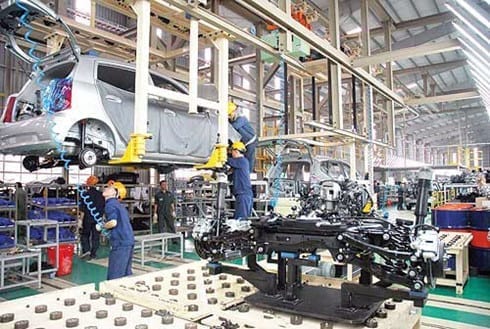
    Twenty-two more Japanese firms have registered Vietnam as their next investment destination under a scheme in which the Japanese government will fund a production shift from China.

    With the latest additions, 37 out of 81 Japanese firms receiving the government’s subsidies to move factories out of China and set them up in Southeast Asian markets have opted for Vietnam, Japanese ambassador to Vietnam Yamada Takio said at a conference between Japanese firms and the Vietnamese government Monday.

    In July, the Japan External Trade Organization (Jetro) released an official list of 15 Japanese firms that had chosen to move to Vietnam. Most of these firms make medical equipment while the rest produce semiconductors, phone components, air conditioners or power modules.

    “Vietnam currently tops the list of potential investment destinations among Japanese firms choosing to diversify their supply chains,” Yamada said, adding that Thailand came second with 19 firms.

    He said while many economies around the world were struggling to fight against the Covid-19 pandemic, Vietnam has successfully contained outbreaks and is one of the few economies posting positive growth in 2020, estimated at 2.48 percent.

    In the first 11 months of this year, Vietnam’s total export value reached $489 billion, up 3.5 percent year-on-year.

    “In the world, only Vietnam has achieved such great success,” Yamada said. As a result, Vietnam has become more attractive for foreign investors, including Japanese enterprises, he said.

    The Japanese government had earlier announced a 243.5-billion-yen ($2.3 billion) stimulus package to help Japanese companies move production out of China. Jetro said the Japanese government will give each company 0.1-5 billion yen for the move.

    Though Vietnam has emerged as an attractive destination for Japanese investors, there are investment environment problems that need to be resolved, it added.

    Many Japanese firms have complained to the Vietnamese government about complicated administrative procedures.

    Nakagawa Tetsuyuki, general director of Aeon Mall Vietnam, said their projects often take a long time to complete admin procedures. Some projects have to wait more than one year to receive the investment registration and land use right certificate.

    For projects that need approval under the Prime Minister’s licensing authority, it takes even longer, Tetsuyuki added.

    Therefore, Japanese businesses expected the government to shorten and speed up administrative procedures to improve business environment.

    Japanese firms are also concerned about tax incentives, equitization and entry and quarantine policies, infrastructure, and human resources.

    Japan was the fourth-largest foreign direct investor in Vietnam in the first eight months of this year with a total registered capital of $1.64 billion, behind Singapore, South Korea and mainland China.

  • A Japanese First: Japan Airlines to Offer Complimentary COVID-19 Coverage for International Passengers

    A Japanese First: Japan Airlines to Offer Complimentary COVID-19 Coverage for International Passengers

    Japan Airlines (JAL) today announced that the carrier will provide a new service called JAL Covid-19 Cover, as part of its JAL FlySafe program to provide reassurance and support to passengers with essential travel needs during the global pandemic. The new service provided by Allianz Travel—the first of its kind for a Japanese carrier—includes coverage of up to €150,000 in total medical costs resulting from the initial COVID-19 testing fee and subsequent medical treatment for those that test positive during their travels.

    Additional coverage for isolation costs and repatriation is also included for those requiring such after a positive diagnosis. A global 24-hour support line in English and Japanese will also be available to assist customers exhibiting symptoms, providing further peace of mind throughout their journey. Services related to the coverage will be offered from December 23, 2020.

    “As international flights gradually return to service, the JAL Group has implemented key measures against COVID-19 to provide customers a safe and secure travel experience. While it may take time to welcome back customers on a global scale, we hope this coverage with Allianz Travel will provide reassurance to those that need to travel today,” said Hideo Ninomiya, Managing Executive Officer of Passenger Sales, Japan Airlines.

    “AWP Japan is very proud to support JAL in this service. Our assistance teams will help provide peace of mind to JAL’s passengers in these challenging times. Allianz Travel is the specialized travel-related insurance and services brand from Allianz Partners, and we will leverage our vast experience in emergency assistance to travelers and our global medical network to support passengers affected by COVID-19,” said Patricia Moon, CEO of AWP Japan Co., Ltd., member of the Allianz Partners Group.

    The JAL Group has implemented key measures against COVID-19 at the airport and throughout the travel experience. For details on the JAL FlySafe initiative, click here.

  • Cole Haan opens new concept store in Tokyo

    Cole Haan opens new concept store in Tokyo

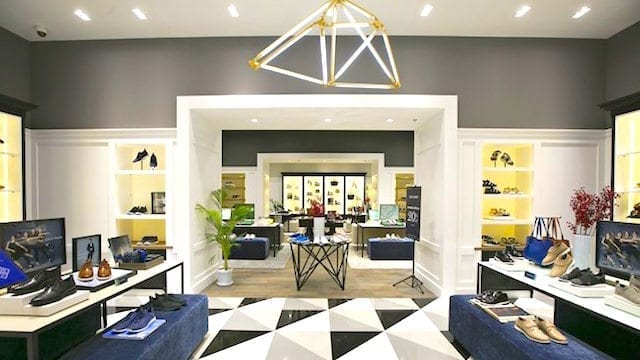
    American luxury fashion brand Cole Haan has launched its concept store in Tokyo at Grandshop – Cat Street, Harajuku. The flagship houses a selection of footwear and lifestyle products, including the exclusive GrandPro Rally Court Sneakers range in collaboration with Indian-American comedian Hasan Minhaj.

    “Japan holds a special place for the Cole Haan brand as we’ve been there for more than a quarter-century,” said  David Maddocks, brand president at Cole Haan. “It only made sense to bring our most innovative retail concept to one of the most iconic shopping destinations in the world — Harajuku district’s Cat Street.”

    The store facade includes a window integrated with a transparent LED screen showcasing Cole Haan’s product. Digital touchpoints such as QR codes and a selfie station are implemented inside the store.

    The Cole Haan Harajuku is also the brand’s third Grandshop. Founded in 1928, Cole Hann is now sold in more than 60 countries.

  • Japan May Ban Sale Of New Petrol-Powered Vehicles In Mid-2030s

    Japan May Ban Sale Of New Petrol-Powered Vehicles In Mid-2030s

    Japan may ban sales of new petrol-engine cars by the mid-2030s in favour of hybrid or electric vehicles, public broadcaster NHK reported on Thursday, aligning it with other countries and regions that are imposing curbs on fossil fuel vehicles.

    The move would follow Prime Minister Yoshihide Suga’s pledge in October for Japan to slash carbon emissions to zero on a net basis by 2050 and make the country the second G7 nation to set a deadline for phasing out petrol vehicles in a little over two weeks.

    Japan’s industry ministry will map out a plan by the year-end, chief government spokesman Katsunobu Kato told a news conference on Thursday.

    Japan’s Prime Minister Yoshihide Suga pledge in October for Japan to slash carbon emissions to zero on a net basis by 2050.

    The likelihood of state interventions to lower carbon emissions is fuelling a technological race among carmakers to build electric cars and hybrid petrol-electric vehicles that will lure drivers as they switch from petrol models, particularly in the world’s two biggest auto markets, China and the U.S.

    Measures already in place in Japan mean Japanese automakers, particularly big ones such as Toyota Motor Corp with greater research and development resources, could use electric vehicle technology they have already developed at home.

    Nissan Motor Co chief operating officer Ashwani Gupta last month told Reuters his company was ready to respond to Britain’s decision to hasten a phase-out date for new petrol and diesel powered cars and vans by five years to 2030 because it was part of a global trend.

    Japan’s industry ministry is considering requiring all new vehicles to be electric, including hybrid vehicles, NHK reported earlier, adding the ministry would finalise a formal target following expert-panel debates as early as the year-end.

    Nissan says it’s ready to respond to Britain’s decision to hasten a phase-out date for new petrol and diesel-powered cars and vans by five years to 2030

    Japanese automakers for now are keeping quiet on what impact those measures could have on their businesses.

    Toyota, Honda Motor, Nissan and its alliance partner Mitsubishi Motors Corp declined to comment.

    In Japan, the share of electric vehicles is expected to increase to 55% in 2030, Boston Consulting Group said in a report on prospects for battery-powered cars.

    Globally, “the speed of expansion of the share of electric vehicles will accelerate due to the fact that battery prices are falling more rapidly than previously expected,” Boston Consulting said in the report.

    Japan, China and South Korea recently announced firm targets to end net emissions of carbon, which has given momentum for companies and banks to push for cutbacks to keep global warming in check.

    Apart from Britain, parts of the United States and Canada, Norway and Germany, are or plan to imposed curbs on fossil fuel cars. The wider European Union is expected to decide on future restrictions as early as this month.

  • Tokyo pop-up mask store lures shoppers with festive face coverings

    Tokyo pop-up mask store lures shoppers with festive face coverings

    As a new wave of coronavirus infections sweeps Tokyo, a pop-up store near Japan’s capital is luring Christmas shoppers with 250 types of face mask, including festive versions with decorative lights.

    Tokyo Mask Land, which opened Tuesday for a month in an office building in Yokohama, also has a mask bar and is offering mask-making workshops to draw visitors.

    People often wore face mask in Japan before the pandemic, particularly during the winter flu season and in Spring when cedar and cypress pollen triggers hay fever.

    Although no law mandates wearing them, it is currently unusual to see someone without a mask in Tokyo, even outside.

    The store also plans an exhibit on the history of face coverings and a photo booth featuring Christmas trees and a mannequin dressed up as Santa Claus.

    “I don’t think you would come up with an idea like this if there had been no coronavirus outbreak,” 23-year-old Ryota Nabetani, who was shopping for masks with his mother, said of the photo spot.

    Although it has had far fewer cases than in the United States and Europe, a recent surge in coronavirus infections prompted authorities in Tokyo last week to request bars and restaurants to shorten opening hours.

    Japan’s capital on Tuesday reported 372 new cases, the seventh straight day above 300, according to public broadcaster NHK.

    A spokesman for the store said it had implemented measures to ensure that visitors didn’t catch the coronavirus while shopping for masks.

  • Japanese sushi chain Sushiro eyes cross-border expansion next year

    Japanese sushi chain Sushiro eyes cross-border expansion next year

    Sushiro Global Holdings, the Japan-based operator of sushi chain Sushiro, plans to boost its Asian presence with the opening of new restaurant units in Thailand and China.

    The company will be renamed to Food & Life in April 2020. It will launch its first Thailand location in Bangkok next spring, Nikkie Asia reported.

    Sushiro will establish its business unit in China by December this year and intends to open one restaurant by September 2021.

    Commenting on the entry into these Asian markets, Sushiro Global Holdings CEO Koichi Mizutome was quoted by the publication as saying: “Asia has rice culture, and Asian people have a higher tolerance for raw fish.”

    Sushiro expects to ramp up its overseas sales to approximately 10% of total sales in fiscal 2021 by next September with the establishment of new restaurants in China and Thailand.

    The Japanese firm plans to set up 24 to 28 restaurants abroad during fiscal 2021.

    Meanwhile, the chain will slow down its expansion in the home market.

    Several Japanese sushi chains have been under pressure to focus on their growth in foreign markets due to the country’s rapidly ageing population.

  • Nike Japan ad on bullying, racism sparks hot online response

    Nike Japan ad on bullying, racism sparks hot online response

    A video ad from Nike Japan against bullying and racism that features biracial athletes and other minorities, such as those of Korean descent, has prompted a sharp online response including calls to boycott the company.

    Japan has traditionally prided itself on being racially homogeneous, although successful mixed-race athletes such as tennis star Naomi Osaka are challenging that image.

    The commercial, “Keep Moving: Yourself, the Future,” released on Nov 30, shows several teen girls bullied in school over their race or other differences, but who ultimately find confidence through soccer prowess.

    One scene features a girl whose father is Black surrounded by fellow students, squealing and pulling her hair.

    The video, viewed 14.1 million times on Nike Japan’s Twitter feed by noon (0300 GMT) Wednesday, had racked up 63,000 likes but also a cascade of critical comments from many who vowed never to buy Nike products again.

    “Nowadays, you often see one or two people of different nationalities going to school perfectly peacefully. The one that’s prejudiced is Nike,” wrote one user named “hira1216”.

    Another asked, “Is it so much fun to blame Japan?”

    Although Japanese sports fans have celebrated Osaka, who counts Nike as a sponsor and makes a cameo appearance in the ad, she was once depicted as a cartoon character by another sponsor, Nissin, with pale hair and light brown hair, while a comedy duo said she “needed some bleach”.

    Nike Japan was not immediately able to comment on the response, but said on its website it believes in the transformative nature of sports.

    “We have long listened to minority voices, supported and spoken for causes that fit our values,” it added.

    “We believe sports have the power to show what a better world looks like, to bring people together and encourage action in their respective communities.”

  • CapitaLand sells three Japanese malls to invest in logistics

    CapitaLand sells three Japanese malls to invest in logistics

    Capitaland has divested three malls in Japan and an office building in South Korea for a total of S$448.7 million, as part of its ongoing portfolio reconstitution strategy, it said Tuesday morning in an exchange filing. It also announced that it has made its first foray into Japan’s logistics sector, entering into a joint venture with Mitsui & Co Real Estate, with CapitaLand as the majority partner, to develop and operate a logistics project in Greater Tokyo.

    The divested properties in Japan are La Park Mizue and Vivit Minami-Funabashi in Greater Tokyo, as well as CO-OP Kobe Nishinomiya Higashi in Greater Osaka, which were sold for a total of 21.99 billion yen (S$283.6 million).

    It also divested ICON Yeoksam in Seoul for 142.2 billion won (S$165.1 million) in August this year. The office building was held through a private fund, Ascendas Korea Office Private Real Estate Investment Trust (Reit) 5. CapitaLand remains the asset manager of ICON Yeoksam and will continue to receive fee income.

    CapitaLand said the divestments were done above valuation, and the buyers are unrelated third parties. Post divestment, CapitaLand will retain S$3.8 billion of assets under management (AUM) in Japan and S$2 billion of AUM in Korea.

    With the divestments, the total gross value of divestments by CapitaLand and its real estate investment trusts (Reits) would be S$3.02 billion, crossing its annual target of recycling S$3 billion of capital.

    CapitaLand and its Reits have invested more than S$3.3 billion into new assets as at end-November.

    “The divestment of these mature malls and office assets is part of CapitaLand’s capital recycling strategy to unlock value by reinvesting the capital into new growth opportunities such as the logistics sector in Japan,” said Jason Leow, president, Singapore & International, CapitaLand Group.

    “By paring down our exposure in Japan’s retail sector and leveraging our logistics experience in markets such as Singapore, Australia and the United Kingdom to expand into the new economy sector in Japan, we are responding swiftly to shifting market trends and consumer behaviors, positioning CapitaLand for future growth,” he added.

    CapitaLand’s new logistics venture in Japan is close to Central Tokyo, and is expected to be completed in Q4 2022. The four-story logistics facility will have a gross floor area of about 24,000 square metres.

    Gerald Yong, chief executive officer, CapitaLand International, said the logistics sector in Japan presents “significant opportunities” for CapitaLand.

    “The global pandemic has accelerated the growth of e-commerce and the logistics sector has been a prime beneficiary of this trend,” Mr Yong said. “We aim to achieve meaningful scale over time by leveraging Mitsui & Co Real Estate’s local knowledge and access to business opportunities to grow our logistics portfolio in Japan.”

  • AirAsia Japan files for bankruptcy in latest Covid casualty

    AirAsia Japan files for bankruptcy in latest Covid casualty

    AirAsia Japan Co has filed for bankruptcy with the Tokyo District Court after flagging last month it would cease operations in the country, as the coronavirus pandemic that’s wiped out travel globally took its toll.

    Flights between Japan and destinations such as Bangkok will continue to be operated by other AirAsia carriers.

    The Japanese arm of Malaysia’s AirAsia Group Bhd received a provisional administration order from the court Tuesday, it said in a statement.

    “Given AirAsia Japan’s current financial position, we regret to inform that AirAsia Japan is currently unable to settle the outstanding refunds,” the statement said. “We sincerely apologize for any inconvenience caused to customers who have used or booked AirAsia Japan flights.”

    AirAsia, which reported its largest loss on record in the second quarter ended June 30, has been under immense pressure this year as Covid-19 roils the aviation industry. Airlines globally have been plunged into crisis, with many cutting thousands of jobs and trying to secure funds for survival. Some, pushed to the brink, have gone out of business.

    The low-cost airline has also stopped funding its Indian affiliate, leaving the future of AirAsia India Ltd largely dependent on its majority shareholder, Indian conglomerate Tata Group. Long-haul budget arm, AirAsia X Bhd, isn’t faring much better, earlier this month submitting a new debt restructuring proposal to creditors.

    AirAsia Japan had already canceled all flights, including one between Nagoya and Taipei. Services operated to Japan by AirAsia’s other carriers in places like Thailand and the Philippines won’t be affected. International services to Japan from Malaysia, Thailand and the Philippines will resume as travel restrictions are eased and borders reopen, the airline said Tuesday.

    Customers who have booked AirAsia Japan flights can apply for a refund, which should be available from April next year, or they will receive a credit that can be used on any other AirAsia-operated flight.