Tag: Philippines

  • Hikiniku to Come Opens Second Manila Store at SM Megamall

    Hikiniku to Come Opens Second Manila Store at SM Megamall

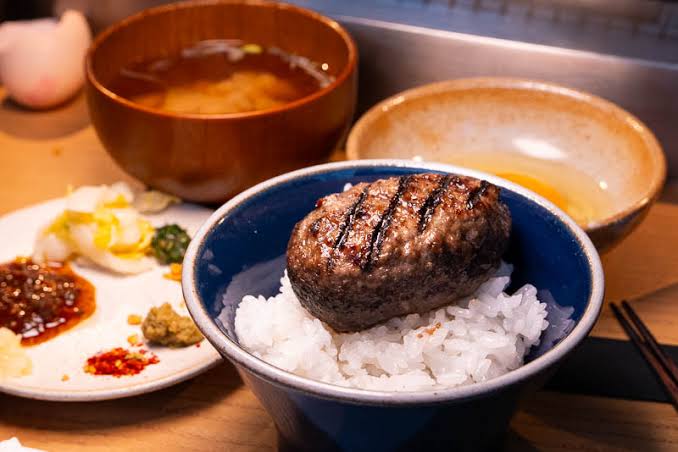
    Japan’s charcoal-grilled hamburg chain Hikiniku to Come opened its second Philippine outlet at SM Megamall, setting up a third location for 2027.

    The expansion adds prime mall retail space in Metro Manila to the Japanese concept, which entered the market under local operator The Standard Group. Diners receive freshly ground, charcoal-grilled beef patties served individually on bowls of rice rather than pre-cooked patties held in warmers.

    How the concept operates

    Founded in Tokyo in 2020, the brand built its format around single-item execution. Counter seating surrounds central charcoal grills where staff cook patties directly in front of customers.

    The format relies on high inventory turns and strict batch preparation. The Standard Group handles daily operations, sourcing, and retail site selection across the country.

    Mall landlords and format demand

    Japanese dining concepts continue to secure high-traffic anchor positions in Metro Manila shopping centres. Landlords favour specialty operators that generate queues and consistent ticket averages over standard food-court counters.

    For Philippine mall operators, bringing single-specialty Japanese brands into central retail clusters drives weekday footfall and boosts food and beverage revenue per square metre. The model carries operational discipline: tight menus minimise raw material waste, while the open-grill theatre speeds customer turnaround.

    The operational hurdles

    Replicating Tokyo counter dining across Southeast Asia carries supply chain pressure. Operators must maintain daily beef consistency and import Japanese short-grain rice while navigating local import tariffs and currency fluctuations.

    Labor training presents another operational bottleneck. Grilling fresh beef to precise specifications at a live counter leaves little room for service errors during peak meal rushes.

    What comes next

    Hikiniku to Come launched its initial Manila flagship earlier before expanding to the Mandaluyong retail corridor. The Standard Group is now scouting real estate for the brand’s third branch, with additional metropolitan sites under review for development over the coming year.

  • Korea’s Born to Stand Out Opens First Southeast Asia Store in Makati

    Korea’s Born to Stand Out Opens First Southeast Asia Store in Makati

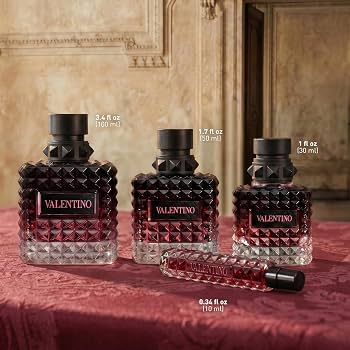
    South Korean luxury perfume label Born to Stand Out opened its first Southeast Asian boutique at Glorietta 4 in Makati City, entering the Philippine market through local distributor Scent & Beauté.

    Founded in Seoul by Jun Lim in 2022, the brand built its identity on high-concentration formulations and unconventional scent profiles, contrasting with the clean, minimalist branding common among East Asian beauty exports.

    Inside the Glorietta 4 Boutique

    The Makati boutique pairs bright crimson interiors with white ceramic-style flacons across the full catalog. Inventory spans four core collections: Dirty and Sticky, Dark and Drunk, Eau Intimité, and the flagship Extrait Extrême tier.

    Formulations in the Extrait Extrême series run between 55 and 62 per cent perfume oil concentration. The brand ages those blends for three months in traditional Korean earthenware jars known as onggi to round out volatile top notes before bottling. The store also stocks scented body lotions, washes, and home fragrances.

    The Play for Manila’s Niche Beauty Spend

    Distributor Scent & Beauté handles store operations, logistics, and retail management for the rollout. The company manages luxury and premium personal care portfolios across the Philippines and Singapore.

    Department store beauty counters in Metro Manila have long favored Western legacy houses, but independent Korean beauty and lifestyle brands are taking dedicated square footage in prime retail properties. Ayala Land continues to reconfigure Glorietta’s ground floors toward specialized retail and indie beauty concepts to capture younger foot traffic.

    What to Watch Next

    Niche fragrance carries high margin potential, yet price elasticity in Metro Manila will test whether consumers convert from entry-level K-beauty purchases into ultra-high-concentration extracts. Scent & Beauté has not disclosed expansion targets for additional locations across Metro Manila or second-tier Philippine retail hubs.

  • Robinsons Retail Opens First Panglao Supermarket in Island Push

    Robinsons Retail Opens First Panglao Supermarket in Island Push

    Robinsons Retail Holdings opened its first supermarket in Panglao, Bohol on September 4, targeting an island market where tourism operators and local households still lack modern grocery chains.

    Net sales in the food division reached 125.8 billion pesos in 2025, generating 59.8 per cent of company revenue. Same-store sales grew 3.2 per cent. That performance gave the Manila-listed group clear incentive to add square footage outside the capital.

    Located near Bohol’s international airport and beach strip, the Panglao store supplies commercial buyers such as resorts, restaurants, and hotels alongside residents and hospitality workers. In tandem with the supermarket opening, the company launched a Rose Pharmacy at Bellemar Lifestyle Center, bringing its provincial pharmacy network to nine sites.

    The Imbalance Outside Luzon

    Total food store count reached 799 across the group at the end of 2025, spanning Robinsons Supermarket, The Marketplace, Shopwise, Robinsons Easymart, and convenience brand Uncle John’s. The footprint remains concentrated in Luzon. Metro Manila held 410 locations, and outer Luzon accounted for 308.

    Southern regions hold only a fraction of that total. The company operated 56 food stores in the Visayas and 25 in Mindanao at the end of 2025. Together, those 81 outlets equal less than a fifth of the Metro Manila network. That gap leaves substantial room for modern formats to expand across central and southern provinces.

    Sari-Sari Dominance in Provincial Trade

    Island expansions shift operating risk toward tourism cycles and local supply logistics rather than standard household traffic. Cold-chain transport to island provinces costs more than urban replenishment. Turnover also depends partly on seasonal visitor arrivals. Securing supply contracts with hotels and restaurants helps smooth those volume swings, shielding stores from local spending constraints.

    Traditional retail continues to handle most grocery volume outside major cities. Government data from the 2023 National Nutrition Survey showed 66.9 per cent of households bought groceries regularly from neighborhood sari-sari stores and micro-retailers. Only 45.6 per cent shopped at supermarkets or modern outlets once or twice a month. Independent shops remain the chief competitor for formal chains entering provincial towns.

    Scaling Beyond Capital Malls

    Network consolidation in recent years helped RRHI sharpen its food stable across upscale, mass-market, and convenience formats. Revenue growth in 2025 paired store openings with like-for-like sales gains. Better integration across banners also improved regional supply lines.

    Future quarters will show whether provincial same-store sales outrun the 3.2 per cent baseline set in 2025 as resort hubs absorb modern supermarket formats.

  • Cellboy Deploys Anchanto Software Across More Than 200 Stores

    Cellboy Deploys Anchanto Software Across More Than 200 Stores

    In September 2026, Philippine mobile phone and gadget retailer Cellboy announced the deployment of Anchanto’s cloud-based Order Management System across its network of more than 200 stores nationwide. The 17-year-old retail brand previously faced operational challenges with manual store-level tracking that delayed inventory and financial reporting.

    The roll-out links Cellboy’s warehouse operations directly to its physical storefronts and online platforms. While the Quezon City-based retailer already utilized a warehouse management system for internal hub operations, the new integration automates transactions from purchase to delivery with real-time updates.

    Connecting Warehouses to Store Shelves

    Under the partnership, Singapore-based commerce technology provider Anchanto supplies a unified system architecture that synchronises online and offline data. The platform provides store teams with real-time inventory visibility across every sales touchpoint, eliminating after-the-fact processing and reducing manual reconciliation work.

    “One of our biggest challenges was the lack of real-time visibility,” said Alvin Teng, chief executive officer of Cellboy. “Transaction data was only updated after processing, making it hard to get an accurate view of inventory and act quickly.”

    The Omnichannel Hurdle for Philippine Retail

    Consumer electronics chains across the Philippines face margin pressure from both organised mall-based competitors and digital marketplaces like Shopee and Lazada. For multi-store operators, carrying excess stock in backrooms to prevent stockouts ties up working capital, while running lean without live data leads to missed sales when shoppers cross between physical counters and online listings.

    By removing batch processing at the branch counter, Cellboy reduces the labour hours spent on nightly reconciliations. The risk now shifts to store-level compliance, where cashiers and stock clerks must maintain disciplined system entry to keep the live data stream accurate across 200 locations.

    Software Consolidation Across Southeast Asia

    Anchanto has built its footprint by targeting regional merchants that outgrow disparate legacy software. The Singaporean software vendor currently operates across 12 countries in Southeast Asia, the Middle East and Europe, maintaining direct integration links with more than 200 third-party logistics firms and marketplace platforms.

    Cellboy started operations 17 years ago as a mobile phone and accessories seller before expanding into wider gadget retail across Philippine shopping malls. The operational test now turns to how fast the retailer cuts order fulfilment lag as holiday device buying ramps up across its nationwide store footprint.

  • SM Supermalls Shifts Tenant Mix to 30 Percent Dining as First-Half Revenue Reaches P41.8B

    SM Supermalls Shifts Tenant Mix to 30 Percent Dining as First-Half Revenue Reaches P41.8B

    SM Supermalls raised its food and beverage tenant share to 30 percent while lifting first-half revenue 8 percent to 41.8 billion Philippine pesos. The shift marks a fundamental redesign of floor plans across the country’s largest retail network.

    Dining accounted for less than 5 percent of the group’s leasable space when current president Steven Tan joined in 2004. The operator is now reallocating square meters from apparel and standard department store goods to dining, sports, and live events under a five-year platform called My SM.

    Retrofitting Floor Space for Food and Sports

    Expanding dining requires heavier investments in physical infrastructure than dry retail. Malls require upgraded water connections, higher-capacity electrical systems, grease traps, and expanded kitchen exhaust ducts to handle restaurant tenants at scale.

    Alongside dining, the landlord is adding non-retail recreation to fill communal areas. The group added 41 pickleball courts during the first six months of the year, taking its total to 102 courts across 32 properties. In June, its commercial complex cohosted the Galaxy Manila Marathon, bringing 25,000 runners onto the grounds.

    Internal merchandising direction now runs partly through an internal advisory unit. The operator created a Gen Z Council of junior staff to evaluate pop-culture trends, such as pop-up matcha fairs, before senior managers commit capital to physical rollouts.

    You have to constantly inject freshness to your centers so that you keep the interest in coming back.

    Regional Realignment from Shelves to Social Space

    Mall operators across Southeast Asia face identical pressures as e-commerce captures routine apparel and consumer electronics purchases. Landlords in Bangkok, Jakarta, and Manila are converting between 25 and 35 percent of gross leasable area to food and leisure to defend foot traffic. SM watched Chinese shopping centers retrofit for hospitality a decade ago and applied the template locally before domestic online shopping reached similar penetration levels.

    The operational risk sits in capital expenditure and lease yields. Restaurants and recreational concepts cost more to fit out, consume more utilities, and post higher tenant turnover rates than legacy fashion retailers. Operators must turn over pop-up concepts and specialty dining fast enough to sustain foot traffic without squeezing margins on rental collection.

    Expanding the Footprint Across South Luzon

    Revenue growth reflects solid consumer spending despite inflationary pressures across basic goods. The 41.8 billion pesos generated in the first half of 2026 improved on 38.6 billion pesos recorded during the same period in 2025, driven by steady leasing income and higher foot traffic across metropolitan centers.

    Construction is underway on SM Nuvali in Laguna, which will serve as the company’s 91st Philippine mall. The property will test an upscale store format aimed at higher-income residential enclaves across Cavite, Laguna, Batangas, Rizal, and Quezon.

  • Philippine Regulator Clears GCash Parent Mynt for $1.48 Billion IPO

    Philippine Regulator Clears GCash Parent Mynt for $1.48 Billion IPO

    The Philippine Securities and Exchange Commission has approved the initial public offering of Mynt, Inc, the parent company of GCash, for up to $1.48 billion (P92.32 billion).

    The company will list on the Philippine Stock Exchange with an expected initial market capitalization of $10.71 billion (P668.96 billion) under regulatory guidelines established in 2026 for large-scale issuers.

    Under the approved terms, Mynt will issue up to 1.61 billion primary common shares, while a selling shareholder will offer up to 6.42 billion shares, alongside an overallotment option of up to 1.20 billion shares priced at up to $0.16 (P10) each.

    Share structure and float relief

    Regulators granted Mynt permission to list with a 12 percent initial public float rather than the standard 15 percent requirement. SEC Memorandum Circular No. 11 allows this lower threshold for issuers valued above $3.2 billion at listing. With an anticipated market capitalisation of 668.96 billion pesos, Mynt easily surpassed that statutory mark.

    That regulatory waiver protects existing shareholders from heavy dilution while injecting fresh liquidity into the local bourse. The secondary share sale gives early backers a clean exit route. It also keeps excess cash off the operating balance sheet.

    Valuation and market impact

    A $10.71 billion listing immediately reshapes index weightings on the Philippine Stock Exchange, where conglomerates, real estate developers, and traditional lenders dominate trading. The float gives fund managers a direct, liquid proxy for domestic consumer spending and fintech transaction volumes. It also tests local capital depth by absorbing funds that might otherwise flow across regional equities.

    Across Southeast Asia, the float provides a pricing benchmark for consumer fintechs moving from venture capital to public markets. Digital payment operators in Indonesia, Vietnam, and Thailand face similar profitability pressures. Yet Mynt’s multibillion-dollar domestic valuation shows local exchanges can absorb large tech listings when profitability metrics line up.

    Path to the trading floor

    Clearance follows years of rapid expansion for GCash, which grew from a basic telco money transfer tool into an everyday payment utility for Philippine merchants, transit routes, and small businesses. Backed by Globe Telecom and Ant Group, the platform built a lead over domestic rivals by capturing both banked and unbanked retail transactions during the pandemic shift to digital settlement.

    Bookbuilding and domestic retail offer periods will set the final strike price within the approved 10-peso ceiling before trading begins in Manila.

  • Ice Cream and Food Drive 45 Percent Surge in Philippine Convenience Store Sales

    Ice Cream and Food Drive 45 Percent Surge in Philippine Convenience Store Sales

    Philippine convenience store sales jumped 45 percent year on year in January, propelled by heavy consumer spending on food and packaged goods, according to Kantar Worldpanel data.

    Food purchases accounted for 59.3 percent of all fast-moving consumer goods transactions across the format, up from 58.8 percent in the previous year.

    Ice cream retained the top spot among individual product categories, followed by milk, packaged snacks, and alcoholic beverages. Beverages accounted for 23.8 percent of overall basket value, dipping from 25.6 percent in 2014. Personal care items captured 13.5 percent of sales, marking the largest category share expansion with a 2.2 percentage point gain. Household care products took a 4.3 percent share, up from 3.5 percent.

    Shifting Baskets and Fast Growth

    Consumer baskets also showed new priorities during the tracking period. Diapers, bottled water, and fabric cleaners entered the top ten bestselling categories by sales value, while coffee and hair care products dropped out of the list. Diapers climbed straight into fifth place, sitting just behind alcoholic beverages and ahead of biscuits, soft drinks, bottled water, fabric cleaners, and fruit juice.

    The convenience channel outpaced every competing modern trade format in the country over the 12-month period. Convenience store sales growth reached 45 percent, compared with 31 percent for direct sales and 11 percent for drugstores.

    Regional Shopper Divergence

    Household penetration widened alongside value growth. Kantar tracked 3,000 urban and rural households and found that 18.5 percent bought goods from convenience stores, up from 16.1 percent a year earlier. That shift brought an estimated 566,991 new families into 24-hour retail chains such as 7-Eleven, Ministop, and FamilyMart.

    Shopper behaviour varies sharply by geography. The National Capital Region accounts for the highest shopper volume, with 34 percent of homes using convenience stores, but residents there visit only five times a year on average. Mindanao holds fewer total convenience shoppers, yet those households visit nine times annually, making them the most frequent spenders in the country.

    Format Expansion Pressures

    Operators face higher inventory management demands as convenience stores shift from late-night snack stops into daily grocery replenishment hubs. Stocking bulky items like diapers and laundry detergents requires tighter shelf space allocation in stores that average only one to two checkout counters. Chains that fail to optimize their stock mix risk losing margin to traditional sari-sari neighbourhood stores that hold lower overheads.

    Philippine operators are matching this shift by accelerating store expansion beyond Metro Manila into secondary cities in South Luzon and Mindanao. Kantar new business development head Lourdes Deocareza attributed the channel expansion to faster consumer lifestyle routines across urban centers.

    Store counts across the major three chains continue to rise toward regional footprint targets, with full-year channel penetration and repeat trip frequency serving as the key benchmarks to watch.

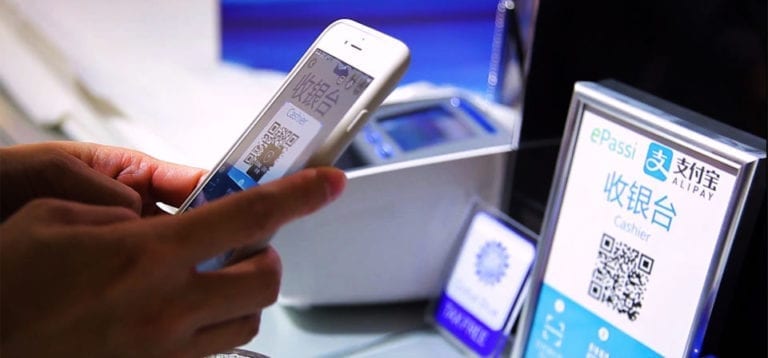
  • Alipay+ Links to QR Ph to Connect 2.5 Million Philippine Merchants to Global Wallets

    Alipay+ Links to QR Ph to Connect 2.5 Million Philippine Merchants to Global Wallets

    Philippine Payments Management Inc. And Ant International have integrated Alipay+ into QR Ph, opening the country’s standardized merchant network to international digital wallet users across 2.5 million businesses.

    The integration connects arriving tourists directly to local point-of-sale systems after QR Ph transaction volumes jumped more than thirteenfold in 2025.

    Under the rollout, overseas visitors pay by scanning existing merchant QR Ph counter stands with their home banking applications and digital wallets. Filipino merchants receive payments in Philippine pesos through their standard settlement accounts without installing separate point-of-sale hardware or signing individual foreign merchant contracts. Bangko Sentral ng Pilipinas figures show digital channels handled 64.69 percent of total retail transaction volume nationwide in 2025.

    How the Cross-Border Routing Works

    Ant International operates Alipay+ as an aggregation switch connecting more than 50 e-wallets, bank apps, and domestic clearing systems covering two billion accounts globally. The Philippine Payments Management Inc., established under the National Payment Systems Act to oversee retail clearing houses PESONet and InstaPay, acts as the local operational counterparty under central bank supervision.

    Transactions clear instantly over the domestic interbank infrastructure. By routing foreign user credentials through the standardized QR Ph matrix, independent grocers, transport operators, and shopping mall tenants process foreign spend through their existing merchant acquiring banks.

    Through our partnership with Alipay+, we are extending that connectivity beyond our borders, enabling Filipino merchants, particularly SMEs, to serve international customers.

    Carmelita Araneta, general manager of Philippine Payments Management Inc., confirmed the system enables local micro, small, and medium businesses to capture inbound tourist spending directly without upgrading terminal hardware.

    Regional QR Linkages Across Southeast Asia

    Central banks across the Association of Southeast Asian Nations spent five years connecting national QR systems through bilateral central bank arrangements, including links between Singapore, Thailand, Malaysia, and Indonesia. Ant International has taken a parallel commercial route by plugging its private wallet switch directly into ten national QR schemes across Asia, the Middle East, and Latin America.

    Retailers benefit immediately from broader payment acceptance, yet the shift consolidates settlement traffic onto private gateway protocols rather than public central-bank settlement rails. For merchant acquirers and payment processors in Manila, merchant acquisition margins face pressure as payment routing shifts toward high-volume, low-margin standard QR processing.

    Central Bank Mandates and the Next Phase

    The Bangko Sentral ng Pilipinas designated PPMI as the country’s official payment system management body under Circular 980 in 2018, mandating standardized QR codes to eliminate proprietary closed-loop merchant terminals. That policy push cleared the ground for interoperability between competing domestic mobile wallets before enabling cross-border integrations.

    Ant International is now rolling out artificial intelligence analytics and fraud screening modules across its regional merchant network to manage currency conversion risks and transaction disputes. The Philippine clearing body will monitor cross-border settlement volumes through InstaPay as inbound tourist arrivals ramp up across provincial retail corridors.

  • Jollibee to List 7,251-Store International Unit in Hong Kong

    Jollibee to List 7,251-Store International Unit in Hong Kong

    Jollibee Foods Corporation is preparing to separate and list its international business in Hong Kong instead of the United States, carving out an overseas network of 7,251 restaurants across 33 countries.

    Shares in the Manila-listed parent rose 1.87 per cent following the move, which replaces a plan announced on January 6 to float the international arm on an American exchange.

    Richard Chong Woo Shin, currently chief executive of Jollibee Foods Corporation International (JFCI), will lead the standalone entity full-time once the separation concludes. Shin previously held senior roles at William Grant & Sons, Ralph Lauren, Bacardi and Altria. Jollibee Foods Corporation said the international business will operate with a lean corporate structure focused on capital allocation, investment opportunities and portfolio priorities, subject to listing committee approval from the Hong Kong stock exchange.

    Portfolio Tilt Toward Asian Beverages

    JFCI functions largely as a multi-brand operator with heavy exposure to Asian beverage chains. The international business holds full ownership of Smashburger, Tim Ho Wan, Yonghe King and Hong Zhuang Yuan, alongside controlling stakes of 80 per cent in The Coffee Bean & Tea Leaf, 70 per cent in South Korea’s Compose Coffee, 60 per cent in Highlands Coffee operator SuperFoods Group and 51 per cent in Milksha.

    Jollibee Foods Corporation ended June with 10,767 outlets worldwide under 19 brands, with overseas locations accounting for nearly 70 per cent of the total network. International system-wide sales climbed 25.4 per cent in the second quarter, while overseas same-store sales rose 4.4 per cent.

    Regional momentum is heavily concentrated in Asian markets. In Vietnam, system-wide sales jumped 47.6 per cent in the second quarter on same-store sales growth of 17.9 per cent. South Korea’s Compose Coffee added 145 stores during the first half, opening roughly 30 outlets a month. In China, Yonghe King reached 537 restaurants, with 65 per cent operating under franchise agreements and a target to reach 70 per cent by the end of the year.

    Shifting Away From Capital-Heavy Expansion

    Listing in Hong Kong aligns JFCI’s capital structure with where its physical earnings actually compound. While the flagship Jollibee fried chicken brand commands strong name recognition in Western markets, its North American presence remains tiny and capital-intensive compared to its Asian coffee and fast-casual footprint. The group ended June with 340 North American outlets, down from 357 a year earlier. Of those, the Jollibee banner ran 108 stores, including 106 company-owned sites and just two franchised locations.

    That balance sheet model is changing slowly. Jollibee launched its US franchising programme in March 2025 and secured seven multi-unit development groups by July, aiming for 330 franchised American locations by 2030. In the second quarter, US Jollibee stores posted a 9.8 per cent gain in same-store sales, marking 66 consecutive months of growth. Smashburger increased same-store sales by 7 per cent, though its store count fell from 203 to 180 as underperforming units were shuttered.

    Since the announcement on January 6, 2026 to list our international business, we have been doing the detailed work required to establish two strong, independent companies. That work has reinforced our conviction in the listing and has led us to conclude that Hong Kong is the market best aligned with JFCI’s business, geographic footprint, and long-term ambitions.

    The Path to Hong Kong Trading

    The pivot to Hong Kong coincides with a sharp rebound in the city’s equity fundraising. Hong Kong Exchanges and Clearing chief executive Bonnie Chan stated that new listings in 2026 had raised more than US$40 billion, surpassing the roughly US$37 billion collected during all of 2025. Hong Kong has actively courted Southeast Asian consumer groups, with more than 150 regional issuers already listed, representing over US$4.3 billion in capital raised.

    Group president and chief executive Ernesto Tanmantiong has set a target to position the flagship Jollibee brand among the top five restaurant operators globally, up from its current 18th position on Brand Finance’s global ranking with a valuation of US$3.3 billion.

    Before JFCI begins trading in Hong Kong, Jollibee must resolve the composition of its portfolio assets. The parent group is currently evaluating a separate initial public offering in Vietnam for Highlands Coffee, which has grown from 56 outlets in 2012 to approximately 1,000 stores, with a target listing date in the first quarter of 2027 that could raise up to US$400 million.
  • Eastern Communications Targets Regional Enterprise Deals at BATIC 2026

    Eastern Communications Targets Regional Enterprise Deals at BATIC 2026

    Eastern Communications pitched its enterprise connectivity portfolio to regional partners at the Bali Annual Telkom International Conference in Nusa Dua, Indonesia, seeking cross-border deals across Southeast Asia. The four-day summit brought together regional operators and digital infrastructure providers to negotiate wholesale bandwidth, enterprise links, and cloud interconnects.

    The push comes as Philippine telecommunications operators prepare more than USD 2.2 billion in capital expenditures for 2026 network upgrades. Eastern Communications, which is approaching its 150th year of operations, wants to capture more corporate traffic flowing between Manila and regional hubs like Singapore and Jakarta.

    Enterprise Focus in Bali

    Company co-coordinators Atty. Aileen Regio and Jaeson Evangelista led discussions at the Bali International Convention Center from August 25 to 28. Management focused talks on international enterprise clients that require dedicated bandwidth and cross-border connectivity across the Philippine archipelago.

    “Technology may connect the world, but it is people who make those connections meaningful,” Regio said, pitching the company’s customer support and service model to international carriers looking for local landing partners.

    Regional Wholesale Traffic

    Competition for regional enterprise traffic has intensified across Southeast Asia as businesses digitize supply chains and shift workloads to distributed data centres. Philippine carriers are actively securing bilateral agreements with regional telcos to defend enterprise margins against domestic rivals and international network providers.

    Eastern Communications plans to roll out additional enterprise data products and international partner links before the end of the year.

  • Okada Manila and Dior Lead Philippine Customer Service Rankings

    Okada Manila and Dior Lead Philippine Customer Service Rankings

    Okada Manila topped a Philippine customer service study across 78 categories with a score of 96.87, leading a field led by luxury hospitality and global retail brands.

    Grand Hyatt Manila followed in second place at 95.57, while French fashion house Dior ranked third overall at 95.12. The benchmark, compiled by data portal Statista and the Philippine Daily Inquirer, evaluated both physical and digital operations using more than 90,000 customer reviews collected between February and April 2025.

    How the scores were calculated

    Researchers weighted the final scores equally between a respondent’s likelihood to recommend a brand and five direct performance metrics. Those five criteria, each carrying a 10 percent weighting, covered accessibility, customer focus, quality of communication, professional competence and range of services.

    Participants evaluated companies they had transacted with, visited or researched over the previous three years. The survey spanned five broad sectors: brick-and-mortar stores, online retailers, digital services, hospitality and general consumer services.

    Top performers across retail and hospitality

    Homegrown luxury furniture maker Philux placed fourth with a score of 94.88 in the home goods retail division. Shangri-La Hotels took fifth at 94.81, followed by serviced apartment operator Ascott at 94.41.

    Consumer technology and fast-moving retail also secured spots in the upper tier. LG Electronics Philippines led online home goods with 94.33, while bakery chain Red Ribbon scored 93.5 in the restaurant and leisure bracket. Japanese apparel giant Uniqlo took the final two spots in the top ten, scoring 93.38 for its physical stores and 93.30 for its Philippine e-commerce operation.

    The strong showing of physical flagships alongside digital channels mirrors a broader shift across Southeast Asian retail, where omnichannel consistency dictates customer loyalty. Premium hospitality operators and luxury apparel labels continue to command the highest marks because their operating models justify higher floor staffing and dedicated post-purchase support.

    Statista and local partners plan to track category shifts through the next evaluation cycle, where rising store automation and digital checkouts face direct consumer assessment.

  • Southeast Asia Targets USD 11 Billion Subsea Cable Expansion for Route Redundancy

    Southeast Asia Targets USD 11 Billion Subsea Cable Expansion for Route Redundancy

    Telecommunications operators and infrastructure investors are committing USD 11 billion between 2026 and 2035 to build new subsea cable systems across Southeast Asia. The spending will expand the number of active intra-Asian cable lines from 14 in 2025 to 19 by 2035, securing international data bandwidth for regional digital economies and hyperscale cloud providers.

    Submarine cables handle more than 99 per cent of international communications traffic in hubs such as Singapore. Under the city-state’s Digital Connectivity Blueprint, authorities plan to double the volume of subsea cable landings over the next decade, backed by an estimated SGD 10 billion (USD 7.4 billion) in predominantly private sector capital.

    Rerouting Around Maritime Chokepoints

    Engineering plans for newly announced trans-Pacific and regional cables increasingly avoid traditional, direct passages through the South China Sea. Systems including Apricot, Echo, and Bifrost run alternative paths through Indonesian and Philippine territorial waters to connect Southeast Asia directly with North America, Japan, and South Korea. Taking longer perimeter paths increases capital costs and latency, but operators accept the trade-off to shield data links from geopolitical exposure and congested straits.

    For enterprise users and cloud operators across Asia-Pacific, these southern corridors remove single-point failure risks that have historically disrupted regional supply chains. Financial platforms, retail marketplaces, and cloud providers gain lower downtime risks during localized outages, while secondary telecom operators in Jakarta and Manila secure direct wholesale access without routing entirely through Singapore.

    Equipment Supply and Infrastructure Competition

    The supply chain for physical infrastructure remains divided among a handful of global manufacturers. Japan’s NEC and France’s ASN maintain strong market positions in island networks across Indonesia and the wider archipelago, while Chinese suppliers have expanded cable contracts in Cambodia and selected Indonesian domestic systems.

    This supplier spread gives regional governments room to balance national security requirements against procurement costs. At the same time, physical reliability remains a constant operational bottleneck. International Telecommunication Union data indicates that human activity, mainly commercial fishing and vessel anchoring, causes 86 per cent of all subsea cable faults, requiring more than 200 offshore repair operations worldwide each year.

    Coordinated Regional Master Plans

    The push for network redundancy builds on policy commitments laid out in the ASEAN Digital Master Plan 2030, which directs member countries to coordinate subsea repair approvals and landing permits. Previous repair timelines often stretched for months due to overlapping maritime jurisdictions and strict cabotage restrictions in archipelagic waters.

    Attention now turns to the planned commissioning of major multi-terabit links, including the Apricot and Bifrost systems, which are scheduled to land initial capacity phases before 2027.

  • Philippine Telcos Commit over USD 2.2 Billion in 2026 Capital Spending

    Philippine Telcos Commit over USD 2.2 Billion in 2026 Capital Spending

    Philippine telecommunications operators have budgeted more than USD 2.2 billion in capital expenditure for 2026 to expand mobile networks, fiber connectivity and digital infrastructure across the country.

    Filings and guidance compiled by the Department of Information and Communications Technology put the combined baseline for the three largest networks at USD 2.21 billion. Total industry spending will rise to between USD 2.4 billion and USD 2.45 billion once DITO Telecommunity figures are added.

    Carrier Budgets and Network Expansion

    Globe Telecom leads the spending group with a guidance ceiling set below PHP 59.4 billion for 2026. PLDT has committed approximately PHP 55 billion to fund its mobile and fixed-line networks, while Converge ICT Solutions plans to deploy between PHP 17 billion and PHP 20 billion for fiber rollout.

    DITO Telecommunity plans to scale back outlays from its 2025 level of PHP 15 billion to PHP 18 billion. DICT did not release a specific 2026 allocation for the third major mobile operator, but department officials confirmed the group will maintain active network expansion.

    “Crossing the USD 2 billion mark sends a clear message: the telecommunications industry believes in the Philippines,” said DICT Secretary Henry Aguda. He noted that the capital programmes will direct resources toward data centers, cloud platforms, e-commerce support and artificial intelligence capacity.

    Policy Shifts and Network Competition

    For consumer brands and retailers across Southeast Asia, sustained telecommunications spending underpins the shift toward digital payments, omnichannel commerce and last-mile logistics. Carriers in Manila spent heavily over the past five years to establish basic 5G footprints, and the 2026 budgets shift capital toward data density, subsea links and enterprise connections rather than speculative coverage builds.

    The investment cycle aligns with market reforms under the Konektadong Pinoy Act alongside public investment in the National Fiber Backbone. The next milestone for the sector comes with third-quarter company earnings reports in November, when operators will release finalized 2026 project timelines and vendor procurement contracts.

  • Philippine Airlines Adds Cats to Domestic In-Cabin Flights for 2,500 Pesos

    Philippine Airlines Adds Cats to Domestic In-Cabin Flights for 2,500 Pesos

    Philippine Airlines opened its domestic passenger cabins to cats on September 5, charging 2,500 pesos per one-way flight under its expanded FurPAL pet scheme. The service allows passengers to bring one small dog or cat inside the cabin, provided the animal and its carrier weigh no more than 10 kilograms combined.

    Pets must be at least 12 weeks old and fully weaned. The airline requires animals to travel in soft-sided carriers measuring no more than 45 by 25 by 28 centimetres, sized to slide underneath the seat while allowing the animal space to stand, turn, and lie down.

    Carrier Rules and Paperwork

    Passengers cannot buy an extra seat for a pet or remove the animal from its carrier during flight. Dogs must wear diapers throughout the journey, while cats require absorbent pads inside their carriers. Feeding during the flight is barred, though water is permitted.

    Boarding requires four distinct documents presented at check-in: a signed declaration and waiver, a veterinary health certificate dated within five days of departure, an anti-rabies vaccination certificate, and a local shipping permit issued by the Bureau of Animal Industry.

    Fleet Restrictions and Capacity

    Capacity limits remain tight across the network. Most eligible aircraft can accommodate a maximum of three pets per flight, requiring passengers to book and pay at least 48 hours prior to scheduled departure.

    The service applies only to select aircraft types, including PAL’s De Havilland Dash 8-Q400 turboprops, Airbus A320s, A321ceos, specific A330s, Boeing 777s, and Airbus A350s.

    Southeast Asian carriers have long restricted live animals to cargo holds due to cabin cleanliness standards and biosecurity regulations. By expanding cabin access to cats alongside dogs, PAL is testing revenue potential in a domestic consumer market where pet spending and companion travel continue to gain traction.

    Bookings remain governed by the 48-hour advance cut-off, leaving seat inventory and carrier approvals strictly capped on high-frequency provincial routes.

  • Lumio Solar Raises US$900,000 for Plug-and-Play Solar Appliances

    Lumio Solar Raises US$900,000 for Plug-and-Play Solar Appliances

    Lumio Solar raised US$900,000 in pre-seed funding in August 2026 to build a distribution and service network for solar-powered appliances across the Philippines.

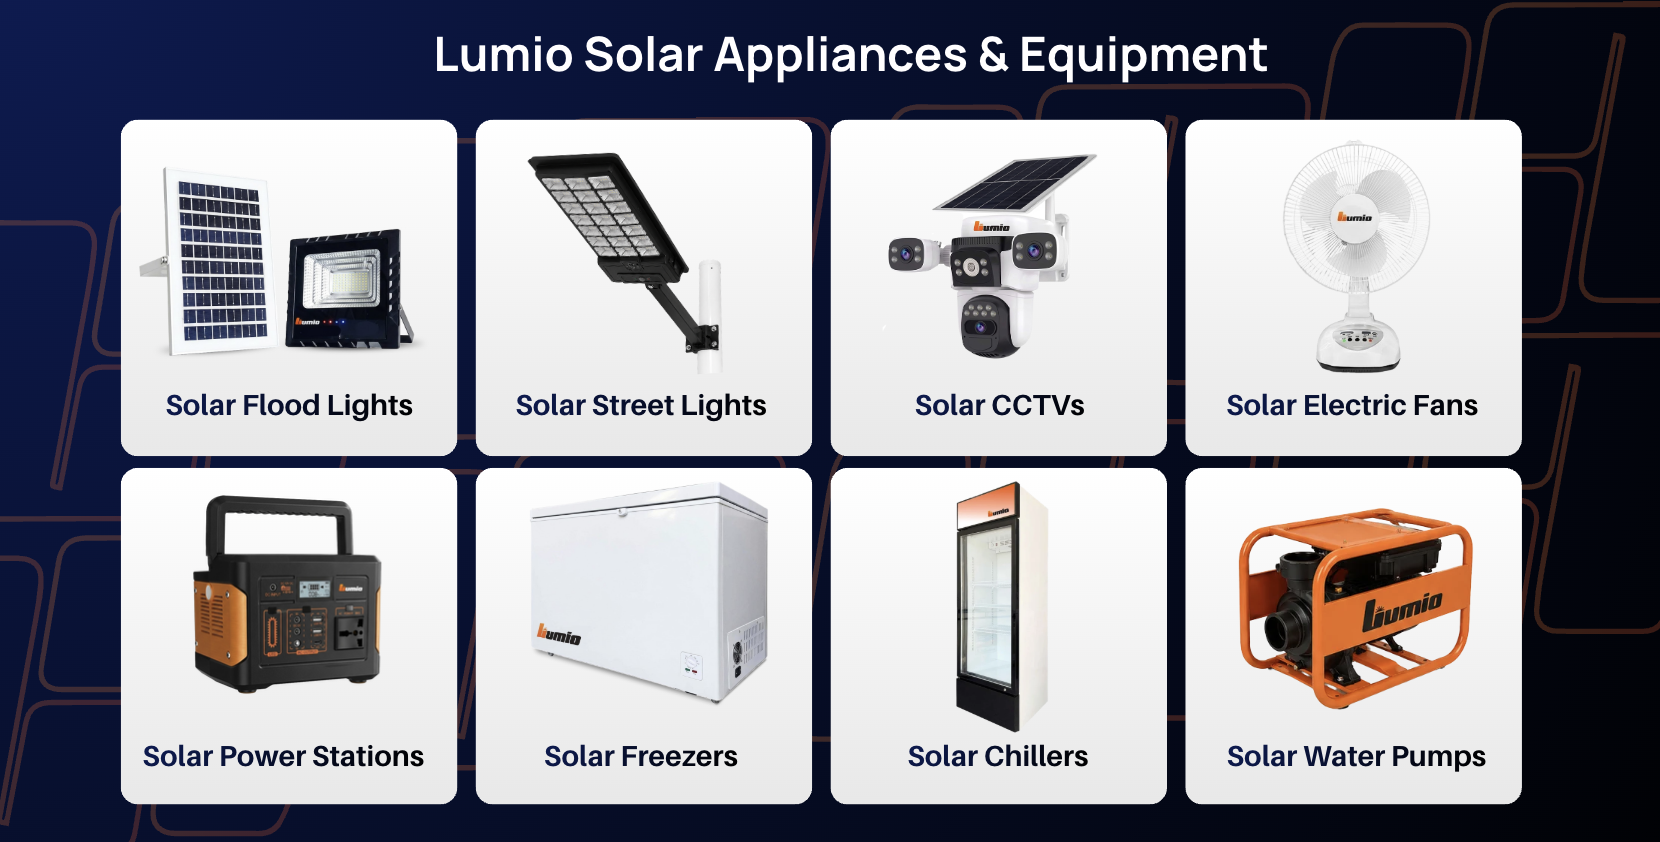
    The investment round was led by 100×100, the Southeast Asia climate venture builder formerly known as Wavemaker Impact, to back the Pampanga-based startup’s rollout of solar fans, lights, freezers, and portable power stations.

    Replacing Rooftop Panels with Standalone Units

    Lumio sells appliances that generate and store their own electricity without requiring roof installation, property ownership, or utility permits. The company targets households, micro, small and medium enterprises, and agribusinesses that are often priced out of rooftop solar. According to Lumio, its equipment cuts operating costs between 10 per cent and 90 per cent compared to standard alternatives while reducing electricity-related emissions by at least 50 per cent.

    Rey Sunglao, founder and chief executive officer of Lumio Solar, leads the venture after more than two decades in Philippine retail and commercial operations, including senior roles at SM Malls Online. Capital from the funding round will go toward widening the startup’s product range, strengthening regional hubs, and establishing localized after-sales repair points.

    The Retail Distribution Hurdle

    The operational test for Lumio lies in logistics and servicing rather than basic hardware manufacturing. Portable power stations from global brands like EcoFlow, Bluetti, and Jackery already sell across Southeast Asia, but they target affluent consumers and outdoor enthusiasts through digital storefronts. Lumio is attempting a traditional retail route, placing inventory and technician support into secondary cities and agricultural areas where power grids remain unstable and diesel generators drive up overhead.

    For independent shopkeepers and food vendors in provincial markets, energy costs represent a daily margin calculation. Commercial rooftop installers such as Solar Philippines, Buskowitz Energy, and Solaric focus heavily on large commercial roofs, industrial compounds, and high-income residential properties. By shrinking the hardware transaction to the size of a single chest freezer or shop fan, Lumio avoids long financing approvals, though it assumes the operational burden of warranty claims and replacement parts across an archipelago.

    Expanding from Central Luzon

    High retail power tariffs in the Philippines have accelerated private generation projects, with national solar capacity projected to expand 17.4 per cent annually through 2050. Lead investor 100×100 launched a US$100 million second fund in 2026 to back 50 climate enterprises across Southeast Asia and India, targeting scalable businesses in high-emission sectors.

    Initial commercial rollouts will concentrate on Central Luzon and Metro Manila before expanding into provincial hubs in the Visayas and Mindanao, where Lumio plans to deploy its first batch of regional service centers.